Small Cap Value Report (Fri 5 March 2021) - SAGA, New floats, Hill Report, HOTC

Good morning, it's Paul here, with the SCVR for Friday.
Many thanks to Jack for covering yesterday.
Timing - you have my full, undivided attention today, so I'll be working all day. Finish time about 16:00. Am hoping to catch up on HOTC & a few other backlog items. Update at 16:36 - I'm just finishing off HOTC, it should be up by 5pm. Update at 17:19 - today's report is now finished.
Agenda -
Saga (LON:SAGA) (I hold) - successful refinancing of borrowings
New floats - regulatory developments, and a quick look at InTheStyle
Hill Report - a few comments
Hotel Chocolat (LON:HOTC) - Interim results from earlier this week. Interesting company, but very expensive.
.
Saga (LON:SAGA)
400p (pre market open) - mkt cap £560m
Corporate and cruise ship finance facilities
Preamble - Renegotiation of the group’s borrowings was the last remaining significant question mark hanging over this share. That’s now sorted with today’s announcement.
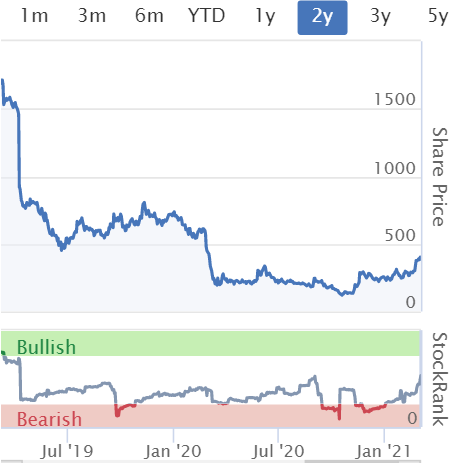
I’m going to keep reporting on SAGA here, despite the market cap being £560m now, it having tripled in price from the lows in Oct 2020. This is because SAGA is a big holding for me personally, and lots of Stockopedia subscribers too. So far the bull case is playing out exactly as I’d hoped. All we now need to see, is the 2 cruise ships, plus the rest of the travel division, resume operations. Given the target over-50s market have now mostly been vaccinated, then it shouldn’t be long.
I note that Carnival announced this week that its P&O division will soon be doing some cruises in UK coastal waters, instead of going further afield. The idea being that a lot of people would be happy just to go cruising, and right now don’t really care where the ship actually goes! Given that Europe is lagging so far behind the UK in vaccinations, that sounds sensible as a stop-gap.
A few years ago I went on short (3 and 5 day) cruises in UK waters, and we loved it - just being on the ship, enjoying all the facilities, lovely food & wine, shows, gym, etc, was really relaxing. Not suitable for everyone I know, but in my view there would probably be plenty of demand given current circumstances.
Today’s update -
Ship loans - this is by far the largest element of the group’s borrowings, and provided the bulk of the financing for its 2 owned mid-size cruise ships, which have barely been used since construction, due to covid lockdown.
- Agreement has been reached for a one-year extension of the existing deferral of debt repayments on the ship loans.
- Repayments of principal due £51.8m, are deferred until 31 March 2022, then repaid over 5 years
- Covenants are waived until March 2022
- Dividends restricted - that’s fine, as the group had already stated it has no intention of paying divis for several years, because debt reduction is the priority
- Minimum liquidity requirement of £40m (cash and undrawn facilities) - an increasingly popular condition that banks are requiring, I’ve seen this at other companies too.
Bank borrowings - are small, given that the equity refinancing last year paid off a lot of the bank debt.
The Group has reached agreement to amend covenants on the term loan and revolving credit facilities ….
The table in the appendix shows only a minor amendment to the leverage ratio covenant in Jan 2022. The main changes being relaxation of the interest cover covenant. Both covenants return to normal on 31 July 2022.
Given the backdrop of continued disruption to the Travel business, the actions taken provide sufficient headroom should the period of Travel suspension, which is subject to government guidance, continue well into the second half of the year.
£250m Bond - nothing mentioned about this, because it didn't need any attention.
Outlook -
We continue to see strong pent-up demand for travel among our customers and remain well placed to deliver on this opportunity when the guidance on international travel changes."
Diary date - 7 April 2021 for preliminary results for FY 01/2021.
My opinion - this announcement today reduces risk significantly, so it’s good news. Although I personally never had any particular worries about the group getting a further relaxation on the borrowing facilities.
Remember the key point with SAGA is that its insurance division is a cash cow, and has been trading resiliently. Thus providing cash flows to subsidise the fairly modest £6-8m per month outflows in the mothballed travel division. Therefore this share provided a nice, lower risk, way of backing the resumption of travel. As opposed to shares in airlines & pure play holiday companies, which typically have had to keep coming back for more equity.
So far, so good! I’m treating SAGA as a long term position, so remain of the view that the longer term price could be a multiple of say 50-100p future EPS? I really like the turnaround story here, with the founder’s son, himself a successful former CEO of SAGA, Sir Roger de Haan, having returned to run the company last autumn, and take it back to its core values, after years of mismanagement.
I know many punters are short-term focused, so might want to bank profits along the way at some stage, but personally that doesn’t interest me. There’s a bigger prize longer-term, if the turnaround is successfully executed, and there’s not actually a great deal to be fixed here. Also, I think cruise ship operators are likely to be on the cusp of a boom, from the pent-up demand mentioned in today's update.
I thought I was going mad last autumn, when the share price hit ridiculous, irrational lows, so it's good to see things recover so strongly, as inevitably you do question whether you've got it right, when the market is so wildly out of tune with my own analysis. It's difficult to swim against the tide, but sometimes lucrative, as in this case! Anyway, let's not jinx things by doing a victory lap at this early stage.
.
.
New Floats
Recent newspaper articles have flagged that there is a strong pipeline of companies intending to float their shares on the London market. Deliveroo has apparently chosen the London market for its mooted £8bn float. That follows Dr Martens (LON:DOCS) and Moonpig (LON:MOON) having successfully floated this year, at substantial valuations.
I very much welcome this, as the London market generally feels stale, and dominated by stagnant companies in traditional, declining sectors. We don't have enough growth companies to chose from.
ThomsonReuters seem to be a bit slow in updating the information here for some new floats, so I've just flagged the issue to Stockopedia HQ and Alex is on the case. So there's no need to raise a green blob to alert them, as I've already done it.
UK Listing Review
Chaired by Lord Hill, former UK EU Commissioner for financial services. This project was commissioned by the Treasury in Nov 2020, and has reported this week. The quick summary is here.
I'm surprised at some of the key recommendations (e.g. reducing the free float minimum from 25% to just 15%). For smaller caps, I would say the opposite should have been done - we need larger free floats, to improve liquidity, and that can help prevent fraud too. A lot of previous frauds (e.g. all those Chinese frauds like Naibu & Camkids) I think might have had dominant shareholders. They just used a London listing to blatantly fleece gullible London investors, and nothing ever happens to the perpetrators. I roared with laughter when reading the Hill Report, and it talking of maintaining London's high standards!
The full Hill Report is here, 88 pages. I'll read it over the weekend, but have jumped to Section 5 - Empowering retail investors, and there's some really good stuff in there, e.g. considering how technology can be used to give shareholders more power in company votes. I also like section 5.2, which suggests using technology to make it quicker & more efficient for existing listed companies to raise capital, and more easily involve retail investors. Hallelujah! This is also about 20 years overdue, but a positive intention. I would like to see fundraisings done quickly, electronically, with the minimum of paperwork & costs, and shares suspended for (say) 7 days whilst fundraisings are one. And pre-emption rights should be respected in every case - i.e. give existing shareholders first refusal, then allow other investors to participate. Price new offerings through an online auction process. It's so simple, and we've had the tech to do this for at least 20 years, or longer. There are too many vested interests, earning fat fees, getting in the way of reform.
This information is quite interesting from the report, and shows how effective London was at refinancing many existing companies, which we should be proud of. Although the system could be improved in future -
The speed at which the various bodies were able to move and the
amount of capital raised quickly is a testament to the agility of
the London ecosystem when it puts its mind to it.
In total, capitalof £11.7bn and £42.7bn respectively was raised through IPOs and
secondary issuances respectively on the LSE from March 2020
to December 2020, representing 36.1% of capital raised in
Europe over the same period
The need to publish cumbersome, expensive prospectuses, is also under review. Again, very welcome, but long overdue. I think a prospectus should only be necessary when companies originally list. Subsequent fundraisings should be possible with just a short document explaining what the money is for. Nothing more than that is needed. The Australian system is noted as being worthy of investigation, to copy elements of it maybe. Sounds good. I don't know anything about Australian markets, but do recall some readers commenting here that their systems are much better than the UK's. I'd be interested in hearing any views on this from our Australian friends, I'm told we have quite a few subscribers & readers here from Australasia.
Different classes of shares are also being considered, to attract tech floats, where the founders are left in control, despite dilution. Why not? If that's a key advantage for US markets, then let's embrace it. After all, nobody is forced to buy any shares, so if you don't like it, don't buy the shares.
My opinion - too soon to judge, I need to read the full report. In principle though, I really like the idea of freeing up London from unnecessary restrictions, in order to attract more business. That's a key opportunity from leaving the EU, and hopefully offset some of the lost business that the EU is (understandably) trying to claw back from London - e.g. Amsterdam has apparently overtaken London recently for stock market activity. Nothing wrong with a bit of healthy competition!
.
In The Style (“ITS”)
Intention to Float on AIM - issued on 1 March
This caught my eye because it’s a “fast growing e-commerce womenswear fashion brand” - very much a sector that interests me.
Key points -
- Founded in 2013 by Adam Frisby (quite young, doesn’t seem to have a rag trade background)
- Product looks a little more middle-of-the-road compared with BOO or PLT, but similar young demographic targeted
- Prices seem higher than fast fashion competitors
- Promotes female empowerment, and uses influencers, just like all their competitors!
- “Unbroken revenue growth” since inception in 2013
- Revenue of £41.0m in Y/E 12/2020 - so still small compared with the main BOO brands
- Active customers 0.7m, up 61% on LY
- Very good performance since covid/lockdown started - £35.4m revenues (up 159% vs LY), and £3.6m adj EBITDA for the nine months to 31 Dec 2020 - small, but very fast growth & an impressive EBITDA margin
- Admission date on AIM expected to be 17 March 2021
- Liberum is running the placing, and will be NOMAD
- Causeway Capital bought 49% of the company in early 2018
- ITS featured in a TV documentary called “Breaking Fashion” on the BBC, I must see if it’s on iPlayer or YouTube and have a watch
- Recently started selling via third parties, including Asos, Lipsy, and Shop Direct (importance of marketplace platforms)
.
Historic financial information - intention to float announcements typically just cherry-pick a few positive financial bits of info, as in this case, so I tend to visit Companies House website to look at the historic accounts. It can sometimes be difficult to find the correct limited company, but this seems to be the one here, company number 08792519.
The most recently filed accounts are for FY 03/2020, and they look poor, e.g. revenue of £19.3m (up 13% on LY), and a loss before tax of £(2.2)m (LY: loss of £(1.9)m).
The balance sheet is also weak, with negative NAV of £(2.9)m.
ITS capitalises intangible assets, probably IT development spend, which was £616k in FY 03/2020. Therefore caution is needed with EBITDA, which would overstate real world cashflows due to this effect, and IFRS 16 might have further distorted it. Hence I’m treating the £3.6m positive EBITDA mentioned in the RNS with scepticism.
The losses were funded with a £2.5m issue of preference shares in 2019 - probably injected by the PR backer, I imagine.
My opinion - this looks potentially interesting. The historic financial information at Companies House shows a slowly growing, loss-making business - not impressive at all. However, it seems to have had a stellar year in 2020, which looks far too good to be just boosted by lockdown. Therefore it looks like there must be some other reason for the tremendous growth in 2020 as well.
The big question is whether the 2020 growth is a one-off, that might ebb away as physical shops re-open, or whether this company is a star in the making?
We also don’t yet know what the valuation is going to be, which is all-important. If it’s £20m I’d have a punt on it. If it’s £200m then I’d walk away laughing.
I’ve asked my broker to keep me in the loop on this one, as anything eCommerce-related is potentially interesting. Once we have more information, I’ll pass it on here.
.
Hotel Chocolat (LON:HOTC)
405p - mkt cap £509m
Hotel Chocolat Group plc, a direct-to-consumer premium chocolate brand, today announces its interim results for the 26 weeks ended 27 December 2020. All numbers are shown post-IFRS16 unless otherwise stated.
At first glance these numbers look really good, considering that the period concerned was disrupted by intermittent and partial lockdowns, and reduced footfall to its shops & cafes.
H1 trading update on 19 Jan 2021, which in summary said -
- H1 revenues up 11% vs LY
- Accelerating revenues trend, with Q2 +19% vs LY Q2
- Online growth more than offset closure of retail outlet - this is highly significant I think, and the only other multi-site retailer in my universe of stocks which I can remember saying the same thing, was Joules (LON:JOUL) (I hold)
- Good growth in USA and Japan, with more expected
- Outlook - continues to be in line with expectations, despite higher costs due to increased digital marketing, and covid
So a decent update in January 2021, which it looks like I didn’t get round to covering here at the time. Moving on to the…
Interim results for the same period, H1, published earlier this week, on 2 March 2021.
- Revenues in line, at +11% to £101.9m
- NB - ignore the £24.9m EBITDA number, it’s not real! It’s badly distorted by IFRS 16, which strips out a £5.1m notional depreciation charge on property leases. It’s nonsensical to effectively exclude property rents from EBITDA, so the £24.9m underlying EBITDA figure shown in the financial highlights is bogus, ignore it!
- Profit before tax is however a reliable number, at £15.5m, up 3% on LY H1
- EPS is 9.7p (ot 9.6p diluted, not much difference), down from 11.5p in H1 LY - note there was dilution from a £22m equity fundraising in March 2020. The other factor affecting EPS is that the tax charge was more normal this year, after being low last year
- NB - Seasonality - H1 (containing Christamas) makes all the profit, so you can’t double profit to get to a full year figure, that would be far too high. In fact Liberum is forecasting a whacking great loss of £(12.0)m in H2, similar to the H2 loss of £(12.6)m generated LY. That puts a very different perspective on things. I wonder what the H1/H2 profit/loss split would be in a non-covid time? It would be worth checking back to pre-2020 results. Hence likely future seasonality is a big issue to follow up on
- Online - comprised 51% of sales in H1, very impressive - HOTC seems to be successful at moving physical customers online, making it very resilient during covid
- Gross margin - is high at 61.0%, but down from 65.0% in H1 LY, due to discounting driven by lockdown, which is understandable. I see upside here, in that future gross margin could recover to or nearer to 65.0%
- No dividends - fair enough, growth companies should be investing in growth, although it does remind us that HOTC is quite capex hungry - expansion requires big investment in stores & other facilities
- Leases - 13% saw rent reductions, and 56% have a lease event (i.e. expiry or break clause) in the next 2 years - good news, as rents should continue reducing overall
- Interesting aside - HOTC says sites in Japan (a key market expanding via a JV) are typically turnover rents. We really do need to the see the UK move in that direction too
- Brexit - no disruption to supplies, and few sales are made into the EU, so this sounds OK
- Broker forecasts are now rising, but from a low base
Balance Sheet - quite capex heavy. Note the £9.7m loan to Japanese JV. Big lease liabilities. Current ratio not that great, possible creditor stretch as trade creditors looks high. Freeholds of £14.1m is good - hidden value. Overall the balance sheet looks OK, but not as good as high cash figure initially suggests.
Liquidity looks fine, with most recent net cash of £26.3m at 28 Feb 2021.
Owner/Managers - Christopher Mayer’s book, "100 Baggers" (highly recommended), has had a big influence on me recently, so I’m now prioritising investments in companies with entrepreneurial management (preferably the founders) who still have large shareholdings. HOTC gets a big tick in that box, with the founders being the two largest shareholders. They’re spent 28 years building up this business - serious commitment, so imagine how motivated they must be, this is their life’s work, something I see as very positive -
.

.
My opinion - I’ve got mixed feelings about HOTC.
Bull points -
- Owner/managers with big shareholdings, which is exactly what I’m looking for
- Impressive H1 results, moving lost physical sales online very successfully, and repeat online business through subscriptions, VIP club, etc
- High gross margins with scope to increase further
- International expansion in USA and Japan could transform long-term scale of the business
- Sailed through the covid crisis, showing resilience of the business model, despite temporary closures
- If you see HOTC more as a stylish/aspirational international brand, than a retailer - seen this way, the £500m market cap may not be so outrageous
Bear points -
- Hideously expensive on a PER basis, for years to come, unless it greatly exceeds broker forecasts
- Expansion requires heavy capex, although less so with online sales, so maybe that’s less of a worry given how well online is doing
- Priced aggressively as a growth company, but growth has actually been quite modest - 28 years from formation to where we are today, reinforces that. Revenue took about 7 years to double more recently. Growth would need to greatly accelerate to justify a £500m+ valuation, in my view.
On balance then, whilst I see an attractive business here, the valuation seems way too high to me, given the relatively pedestrian growth rate, and limited profitability to date.
One final point, I just didn’t like the product when I tried it. It tasted unpleasant to me and was wildly over-priced. That's only one person's view of course. Therefore, my worry is that fancy branding and packaging might only take it so far, before sales peak, and customers drift away. It would be interesting to drill down into customer churn rates - how long do subscribers remain subscribers on average, I wonder?
I think I’ve talked myself out of wanting to buy this share, but good luck with it to holders, I do understand the upside case, but it's much too expensive for me.
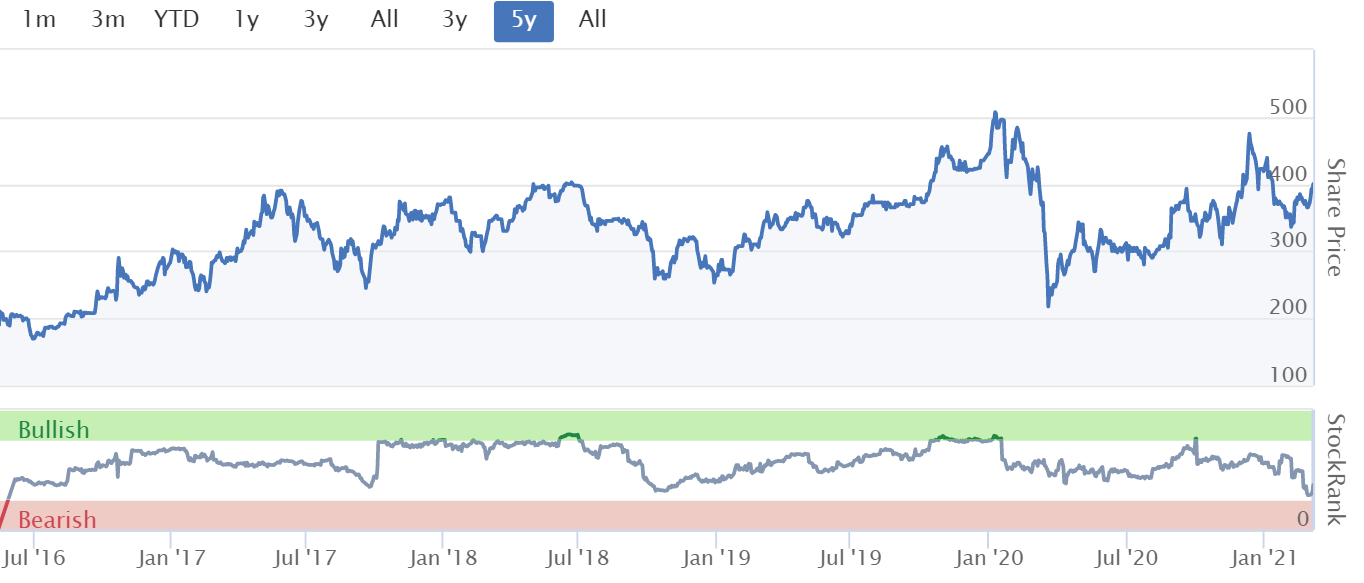
Surprisingly, the chart has gone sideways for the last 3 years, which I wasn't expecting to see.
.
.
Right, that's me done for today. I hope you have a lovely weekend, we might even get some sunshine apparently!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Rumour has it that Saga (LON:SAGA) goes on general sale for "UK" staycation cruises on Monday.
Great British Isles Tour - 11th July - 14 nights. Spirit of Discovery - from Tilbury
Northern Isles to the Fjords - 8 nights - 25th July - Spirit of Discovery - from Tilbury.
Northern Isles to the Fjords - 3rd July - 8 nights - Spirit of Discovery from Tilbury.
Scottish Highlands and Islands - 27th June - 6 nights - Spirit of Discovery from Tilbury
The Inaugural Cruise - 26th July - 15 nights - Spirit of Adventure from Tilbury.
The Inaugural Cruise Spirit of Adventure • July 26, 2021 • 15 nightsSail from Tilbury • Cruise code: SU064Newcastle, England • Newhaven (for Edinburgh), Scotland • Dundee, Scotland • Kirkwall, Orkney Islands • Ullapool, Scotland • Cruise St Kilda • Greenock, Scotland • Belfast, Northern Ireland • Douglas, Isle of Man • Holyhead, Anglesey, Wales • Bristol, England • Falmouth, England. Disembark in Dover.
Above picked up from another site - could of course be from a ramper so no guarantees but I guess Monday will tell.
Discl. I hold (a lot).
Thanks for sharing, that would be great news if so (I hold) - although I'm happy with my position so wouldn't be taking any action either way. It seems like a good move following P&O's announcements. Looking at the Saga website these dates don't seem to conflict with anything that these ships are currently available for bookings. I know they were in Tilbury over the winter, is this a new departure point?
I posted here the other day on Hotel Chocolat (LON:HOTC) but can't find it.
1) Pros: the only pure-play chocolate retail play, impressive online business, exposure to US and Japan
2) Cons: product and financials are horrible. I know about chocolate and get paid to taste it by big brands when they develop new ones. HOTC uses undifferentiated bulk cocoa, but puts a clever marketing spin on it which makes you think you're buying superior chocolate; far too many SKUs (product ranges); poor ethical and sustainable practices again despite clever marketing; stable margins but they never seem to flow to the bottom line; all valuation metrics are poor: sales, EBITDA, PER, PEG; illiquid and wide bidoffer.
It was ok for a punt with a 2-handle but not here.
Can recommend an ice cream from Hotel Chocolate. Very tasty!
Re HOTC the owners will be shocked regarding may of the comments about taste, they have won a lot of awards and are positioning themselves as a more upmarket chocolate company. I accidentally met the one of the owners ( Mr Harris) many years ago. He came across and a very astute businessman and I think will be heavily invested in the business from a long-term goal which is probably at least partly why the shares have moved sideways a fair bit. He ( and I am guessing) is not so focussed on the share price, more of the long-term for the business overall. I agree it's positioning itself as a stylish brand, and is probably why it may be trading at a high multiple?
I am not invested in the company.
I agree with Paul about the taste of HOTC chocolate. We threw it away because it tasted revolting! It seems many like it but I can’t fathom why. The chocolate offering in Lidl and Aldi is way better and a fraction of the price too.
e.g Moser Roth chocolate in Aldi is delicious and if any is still available their Christmas chocolate box “Just Dark” is exceptional and though £5 a box for just 13 chocolates might seem pricy, similar quality in specialist chocolate shops would be at least double that price. And that includes far worse quality (for our taste buds) in Hot Chocolate shops.
The Just Dark selection consists of Lemon Caramel. Blood Orange gin, Gianduja, Almond Millionaire, Coconut, Spiced Apple, Amoretti and Gingerbread. And if that’s sold out just try their standard bars of chocolate and then compare with HTOC in a blind tasting!
So I’m not remotely tempted to buy HOTC and they seem overvalued even if their chocolate was exceptional.
I agree with Paul that the actual HOTC product is distinctly unappetising and believe that is a fundamental problem.
I brought some discounted products just after Christmas and did not like the taste at all! Am surprised there are repeat buyers of the products.
Holy smoke, what a week.
International Personal Finance (LON:IPF) closes @ 99.99 on 781,401 volume following a balanced and encouraging FY results on Wednesday. A stonking week for IPF gaining about 18%.
UK_Investor has on paper my largest ever single gain in the above... but I think I'm holding long. Let one's shares mature and grow.
+46.71% on my foray.
XLMedia (LON:XLM) closes @43.7p on 402,076 volume. The surge is over for this round. Hopefully more to come as results approach.
Across the board 2 to 6% gains today. What happened? Did Jesus come back or E.T. land?
+15% in 3 months. A bit of a change from where we all were this time last year.
Sounds like you need to start your own blog, for people (1, at the latest count) who might be interested.
I heartily agree and am sad to see that your post is "under review". On Wednesday in reply to a similar post from she/he Racer70 said "This isn't advfn " to which the reply was https://www.stockopedia.com/content/small-cap-value-report-wed-3-march-2021-budget-day-nxr-getb-snws-773334/?comment=64#64 Oh dear, that's where she/he belongs. The problem is that Stocko have abolished the 'thumbs down' (and I appreciate why having spent time wondering why I had received them on factual posts where I had not expressed an opinion) but not given us an alternative. At least ADVFN has the "filtered" facility and I would love to use it here on this particular poster!
Here to Invest wisely, not for ego strokes.
So I've invested in company's you and your cohorts don't like.
I would love to hit reset, unwind all my positions, have the perfect Paul Scott portfolio, but, as I've been finding out, its not that simple.
Really don't care if you gang up on me. Only the numbers are of consequence to anyone.
Congratulations, I am down 3% this month...oucharoony, but at the same point, looking long term, controlling the emotion, I hold the companies I want to hold and have a larger portion of cash right now, as posting on Saturday night shows how much time I have to be active right now...
Tommy
I see that Simon Thompson repeated his tip for £SLP (which I hold) in the Investors' Chronicle today, rating it a "strong buy" and raising his target price from 145p to 180p. He says this rates SLP on a "2022 cash-adjusted PE ratio of 4.5".
I know that Palladium and Platinum’s prices have come down in the recent Treasury Bond wobbles, but it’s principle profit driver Rhodium is now well over $29k..
Hello Paul, did you look into Dr Martens (LON:DOCS) at all?
I did. If you just search on a company name, then scroll down, it shows any articles which tagged the name in them. Here we are: https://www.stockopedia.com/co...
OK thanks Paul, this feature does seem seem to work anymore on the old site.
As both a shareholder in Mobeus Income & Growth 2 VCT (LON:MIG)4 (which was an early stage investor) and a very satisfied customer of Parsley Box I welcome the news of the IPO very much and have registered to be informed of how to apply when it happens.
If any subscribers want to try Parsley Box's excellent meals you can get 50% off your first order by quoting discount code 7ZVXR9V. The 10 Meal Express Delivery Selection is not a bad place to start.
For disclosure, I will also get loyalty points if you use this code.
Gostevie
Fantastic work by Paul on Saga. I’m sorry I bailed too early.
The Finncap (LON:FCAP) share price has jumped quite a lot over the past week - very pleasant to see as I hold. I am guessing this is down to read across from results from larger brokers. Anyone else have any insight on this?
I think the positive run on the Finncap (LON:FCAP) shares has been driven by the very positive trading statement issued by the company on Wednesday. I’ve also seen it pop up on a couple of bulletin boards as well as “confidential” blog from a popular market trader/commentator. As an aside, it also looks pretty good value at the moment! (No position).
Thank you for this - I shou8ld have seen the update!
Not just this, but Director buy-ins at finnCap reported this morning via RNS too. I hold Numis (LON:NUM) and believe there is excellent read-across. The last 3 months particularly have seen Cenkos Securities (LON:CNKS) and Finncap (LON:FCAP) race ahead but I think there is potential for Numis (LON:NUM) to catch up with their trading update expected before the end of March. (Cenkos 37%, finnCap 29% compared to Numis at 7%)
Edison research recently upgraded the estimates but by their own admission - conservatively so - especially with the number and scale of IPOs Numis have recently completed/yet still to come.
I also bought some Numis (LON:NUM) recently, seems like these brokers were printing money for old rope last year on the back of easy fundraisings and the UK IPO/M&A scene seems to be ramping up. I don’t understand the dual-CEO thing but they seem to have a great reputation and have their mitts on a lot of deals. The proposed relaxation of market regs are designed to benefit them.
Paul, I really do appreciate your insights and look forward to the morrow. Now here is something which is topical today yet may be reminiscent of your days as a moonlighting DJ?
Saga (LON:SAGA) website updated today regarding start of cruising in light of "road out of lockdown" (apologies if that's not what it's called, I can't keep up) announced by Boris:-
Update March 5, 2021
A message to all guests booked on cruises aboard Spirit of Discovery in June 2021, and cruises aboard Spirit of Adventure from May 2021 to July 2021.
I hope that you have continued to keep safe and well since I last wrote to you in January and that you have started to receive your COVID-19 vaccinations.
The Government’s recent announcement of the roadmap out of lockdown and the timelines contained within it have enabled us to further review our plans to return to service.
As you will know, we had planned our first cruise in May with Spirit of Adventure’s inaugural sailing and June for Spirit of Discovery. Whilst the Government’s announcement indicated that the earliest date international travel could restart was May 17th, it is unclear exactly what this means for the cruising industry. What is clear is that after June 21st social distancing rules will be relaxed, which will in turn allow us to offer an onboard experience as close as possible to what you would have previously experienced.
With this in mind, having carefully considered our options, we have taken the decision to delay our return to service once more and will commence our cruising programme from June 27th with Spirit of Discovery, and the inaugural cruise of Spirit of Adventure will now take place on July 26th.
Here are my SCVR heat maps for today (prices as at ~10:15am).
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
RE: the Hill Report.
It's a utter waste of space for private investors. Every single important issue has been kicked down the road. Lots of fine words but no action.
We can see this by looking at the list of proposed actions. In the section on retail investors the two actions both start with the weasel word "Consider". No recommended action, just an invitation for another set of reviews. Just another grandee ensuring that the rich get richer with barely a sop for the likes of us.
There's absolutely no need for pre-emption rights to be ignored or for private investors to be shut out of IPOs - we already have the technology to address this, it doesn't need another review (which will presumably take another few years). Nor is there any need to wait to reverse the ridiculous MiFID rules that block private investor access to broker information.
The Hill Report's main focus is changing listing rules so that the UK isn't disadvantaged in global competition - less than 5% of global IPOs (i.e. those that aren't purely local) are now coming to London. Which is fine as far as it goes - but as far as we're concerned we remain second class citizens.
timarr
I believe that the reason that the report says "Consider" so much was that the report was to the Chancellor - it's up to the Government to decide how it is to be implemented.
I believe that the reason that the report says "Consider" so much was that the report was to the Chancellor - it's up to the Government to decide how it is to be implemented.
No it doesn't say "Consider" so much. It says it only twice - on the two recommendations on retail investor market access.
While it's true it's down to the government about how it's implemented the vast majority of the other recommendations are just that - recommendations about the actions to take. The retail investor actions are recommendations to have another long think about it.
It may be OK on the wider market issues but it doesn't do a damn thing for private investors.
timarr
Private Investors have been a low priority for as many years as I can remember. I don't see this changing with the Hill Report. ShareSoc have been banging the drum for many years now, but recognition and appreciation of the PI in the UK investment landscape is painfully slow.
Part of the problem could be fairly low numbers of PI s in the UK. Hence not much incentive to make changes.
Maybe the 'fairly low numbers of PIs in the UK' is *caused* by the way we are treated!
Could well be a factor. It might well discourage new PIs who then go down the route of collectives using HL etc. There are probably a number of other factors involved as well.
A new generation of active investors would no doubt help - though the industry probably doesn’t see that happening. The consolidation and withdrawal of online brokers from the UK market suggests that they see limited growth.
When investing in the 1960’s my broker would phone me and ask if I wanted my name put down for a new issue which I was pleased to do, almost always with a good result. Why was that changed?
Paul,
Thanks for your brief summary of the Hill report. I will read it in full myself. Just to say that you (and behind you Stockopedia) now have a substantial, engaged readership of probably quite influential readership ie a good base for some campaigning. Having recently got into local politics myself, I know how influential well structured letter writing campaigns / petitions can be. I think you ought to talk to Ed and for this to be a small part of Stockopedia's remit and an opportunity to give back.
I know you are super busy but you have built a position where your voice counts. Pick a few key issues, draft a letter we can all get behind and let us all send/share it to our MP (+ some of the great & the good - your readership will know who!).
Politically, I would not have voted for Brexit but that ship has sailed. We need to embrace where we are. This is exactly the type of thing where we should truly be able to move faster alone and thus secure advantages.
FWIW - electronic auctions (with pre-emption rights enforced) to raise funds seems a good focus. Ensuring fair access for small shareholders seems an easy, fast & meaningful win - except for all but those who feed off it. (Not necessarily the same price as big purchasers deserve a slightly lower price just like if I place a larger order for boxes I get a better price. In an electronic auction, this is easily managed) . I could easily see this approach attracting interest and capital from continental investors as well.
If we want an entreprenurial Britain, getting finance simply and cheaply will be a key part.
Re the Hill Report (new listings, and easier secondary offers), any relaxation of rules should be accompanied by stiffening the resolve (one could use less polite terms!) of the FCA, and other regulatory bodies, to prosecute fraudulent behaviour, and hand out heavier sentences. The length of time sagas such as Pat Val drag on for is unacceptable.
Hi Paul, I would like to say a big thank you for all your coverage of £SAGA. After reading your stockopedia reports and doing my own research I decided to buy some at around 13p/14p. As you said after the 15 to 1 share consolidation it crashed further to around 120p/130p. I took the opportunity to add again and have been adding right up to 300p. It is now my largest holding and by far my most profitable share ever. Your reports highlighted Saga (LON:SAGA) to me and provided reassurance of my own thoughts on the down days. I will continue you to hold as I am also of the opinion this could reach 1000p+ in the next 24 months. So again a big thank you, I definitely owe you a good bottle of wine for this one! On that note I probably owe you a bottle for Revolution Bars (LON:RBG) as well, again highlighted by you and a purchase was made at 9.9p!
Tom
Very kind, thanks Tommy!
Although to be fair, I don't think I can claim any credit for Revolution Bars (LON:RBG) since I held it all the way down from over 100p to less than 10p at one point, not exactly a glittering success! Thought I'd get that in first, before one of the usual suspects who like making snide comments against me, points it out! (comes with the territory, and the internet, unfortunately).
Sounds like you made some very shrewd buy decisions at the right time & price, so the credit very much goes to you :-)
Regards, Paul.
No one could of predicted the covid affect Paul! However I think you will find your comments on Revolution Bars (LON:RBG) on the 27th October 2020 with the share price at 9.65p were:
'What would this business be worth, once trading conditions have returned to normal? I reckon 3-5 times the current valuation is about right. It would be able to repay debt fairly quickly, because in normal circumstances, this is a highly cash generative business. Even more so in restructured form, with all the loss-making sites gone. Plus it might have opportunities to snap up bust competitor sites for a song.
At this stage, I think risk:reward is good. Obviously it’s been a disastrous investment so far, because of covid, but that’s irrelevant in terms of making an investment decision to buy/hold/sell today. All that matters is what the future holds. I see favourable risk:reward, because I think the group can get through to a covid recovery world before it runs out of cash, especially given that the rents are now coming down for problem sites with this CVA. This business should be making £15m+ p.a. EBITDA once it can trade normally, in my view. That’s what makes it so interesting. Its customers are young, and want to party. Therefore demand is like a coiled spring, that’s going to be released at some point, we just don’t know when.'
You definitely deserve some credit for that analysis in my opinion!
Thanks again
I'd second that. SCVR has highlighted some very good opportunities to me and likewise Saga (LON:SAGA) my single biggest holding and a very nice 5-figure profit hopefully well into 6-figures if these estimates play through. And this is one of just several in my SIPP doing well, the daily write-ups and this bulletin board are excellent at identifying good value small-mid cap companies .
Paul,
I, too, would be interested in your take on (LON:RBGP). I am a holder.
I like Nocola Foulston, she made a storming success of the Brands Hatch story after her father's tragic death. I knew John slightly and admired his fine buccaneering spirit. It seems to me that the apple has fallen close to the tree, but maybe without some of the thrill seeking approach that made John what he was.
RBGP seems to be on a roll as we come out of the trough.
Jasper.
I for one hope you carry on providing updates on Saga (LON:SAGA) Paul, and a big thanks from me for drawing this one to our attention last year.
I Agree I have been a long time backer of cruise ships being the first to break out of the holiday gloom. with the main bulk of cruisers being over 50 with cash to burn. and in general child friendly ships its a no brain teaser.
did Hotel Chocolat (LON:HOTC) end up getting covered? I know it was intended to be written up yesterday.
Hi smig78,
Sorry about the delay on HOTC. I'll do that one next, should be up by lunchtime.
Regards, Paul,
Morning Paul,
As it's a quiet day on the news front, I'd be interested to know your thoughts on RBGP. They seem to be on the turnaround (SP and fundamentals), and the news flow is continuously positive. So if you're feeling bored I'd be keen to get your opinion on them.
Hi rich,
OK, I'll try to take a look at Rbg Holdings (LON:RBGP) (I hold) after lunch.
I did pick up a few myself, because a friend whose investing prowess is considerable, told me it was cheap & had good prospects.
I was listening to their latest InvestorMeetCompany presentation yesterday, but can't say it floated my boat.
Regards, Paul.
Oh dear, sorry I ran out of time before getting to look at Rbg Holdings (LON:RBGP) my apologies. We'll circle back to it at some point in the future I'm sure.
Just to add in SAGA that Numis the house brokers have 62p of earnings for 2023. 67p for 2024. Their target price is £5.85.
I think if travel resumes "normally " and they start paying down debt , I'd expect it to trade at a lot more than pe 6.5x.
Genuinely curious about SAGA. The data doesn't show any institutional inflows which makes me a little wary.
Looking at SAGA's price history before COVID doesn't fill me with confidence either. The biggest price drop shown in Pauls graph started well before COVID (early 2019)! Does anyone know what the differences are between the SAGA of 2021 and the SAGA of 2019 (if COVID bounceback were removed as a factor)?
Re Saga (LON:SAGA) whilst instis may be lukewarm, even reducing, if you take a look at the directors’ holdings then you can see where the difference is! (I hold)
The data shows that none of the purchases are at market price. They are all exercising options. So it begs the question as to whether its worth it at this price for the average PI on the street.
shamusj,
You're not an Australian DJ are you? I started jogging about 10 years ago, listening to megamixes from SeamusJay, an Australian dJ!
As regards Saga (LON:SAGA) (I hold) - the key Director buy is from Sir Roger de Haan. He put in £100m of his own money in the recent £150m placing. From memory, of his £100m, about two thirds of it was priced at a substantial premium to the share price.
So the big money is what matters, and it went in at a big premium.
Also SAGA had a bid approach last year, which I think was priced at c.450p in new money? Or maybe 415p? Can't remember exactly, but it was a big premium at the time also.
So there were very clear signs that this stock was massively under-priced last year, as I flagged up here.
Regards, Paul.
From Paul's Small Cap report of 16/11/2020
"The former CEO (founder’s son) has injected £100m of his own cash in recent £150m fundraising, most of it put in at 405p per share! The balance was put in at 180p per share, which was also the open offer price. A takeover bid of 495p was recently rejected. Yet we can buy now at c.190p - it’s crazily cheap IMO."
I hold, having purchased my first tranche on 20/10/2020 at 132p.
Pual, many thanks for your hard work and insights.
Hi Paul
Pretty sure the bid was £4.80
Hah no although I did own a small indie record label at one point in my past.
Thanks for responding, that’s just the historical context I needed. Thanks Paul! I have recently started enjoying your daily blog very much, I just wish there was also a parallel US one!
Further to my comment earlier today on Angle (LON:AGL) I also posted a reply to someone late yesterday which may be of interest to those reading today. Hope so.
'Hello Zoiberg. Thanks for your comment on Angle (LON:AGL) which as you may have guessed I have followed and been an investor for around 7 years. If you are minded to, there are a couple of recent presentations (Jan 21) on YouTube which you may find interesting. Take your pick. The first is where the CEO is making a presentation which would normally be live in the US. The other contains similar material but which is targetted at US investors. You will find them at :
https://www.youtube.com/watch?v=dmihuELlhDM
Biotech Showcase – normally live Jan 21
https://www.youtube.com/watch?v=5gx3zy9iJes
Similar presentation, but targeted at new investors particularly in US.
Two really key points that I have taken out of a range of presentations he has made in the last year is that there is a compelling financial case for the introduction AND this patented and superior technology is available at a really critical time - when there is a huge backlog AFTER Covid 19 of cancer cases in particular where this can help speed up the process of finding the right treatment to save lives. As investors we are naturally interested in the former, financial, case; as human beings, we should perhaps feel that we should be even more interested in the latter, urgent medical case.'
interesting news at Saga (LON:SAGA)
Re Saga (LON:SAGA) what particular news are you talking about?
https://www.stockopedia.com/sh...
My morning smallcap tweet:
K3 Business Technology (LON:KBT) Xeros Technology (LON:XSG) RBG Holdings (LON:RBGP) GSTechnologies (LON:GST)
K3 Business Technology (KBT) CEO scarpers because things are so good: "having managed the recent successful disposal of Starcom Technologies Limited, which has substantially strengthened the Company's financial position, and with the Company moving into a new phase of development," He is thanked. [SP=176.5 Cap=76m]
Xeros Technology (XSG) £8m placing and £1m OO at 240p, a 1% discount, for development. [SP=246.47 Cap=49m]
RBG Holdings (RBGP) Convex wins £1.5m deal and is working on a further eight transactions which have the potential to complete in the short to medium term. [SP=96 Cap=82m]. I hold.
GSTechnologies (GST) to address "new higher growth synergistic business areas focussed on blockchain technology...pioneering next-generation digital money solutions based on blockchain technology will ...enable it to offer differentiated cutting edge technology solutions to a bigger client base." Digital sick bag please. Will apply to become an Authorised Payment Institution. [SP=2.72 Cap=32m]
Hi Paul, quick Saga update would be appreciated. TIA:)
xricx, I appreciate you weren't seeking my council on Saga (LON:SAGA) However, in my opinion the market is waking up to the opportunity. The announcement from Boris showed a clear return to travel. The vaccine news is exceptionally good. Up 35% in a month.
It will remain volatile in my opinion. Any bad news such as an infected passenger will cause short term drops. However, travel will undoubtedly return to near normality. I appreciate this is reliant on the global roll out and not just ours. This will generate profits which will fuel the share price.
The new ships generate £40m EBITDA each. They replace ships that generated £3m each. This is due to efficiencies in fuel consumption mostly. What may impact on this is if they have reduced passenger numbers for the sake of safety. This will likely reduce the profit rather than create losses.
Over and above the return to travel is the turnaround of the insurance division. I expect that will continue to improve.
I expect good growth over the next 2 years and would no be surprised to see a share price of £8 - £10.
It has been muted that 100p EPS is possible and at a PER of 12 that would be £12 a share.
Hang in would be my opinion and don't be spooked by sudden sell offs.
Thanks Camraid, really appreciate view and I am likely to hold now. Sold 50% holding not long back on impulse, as a novice, and lost out.... reassessed and bought back in (pride eaten..) and can see a possible very rosy future, but, as you note, not without a possible rocky road. Trying to find my feet in investing.... diversifying but then possibly greed says 'stick a load it on a big winner". Never dull!
Some good points on Saga (LON:SAGA) Camraid, all IMHO of course. It took me a little time to wake up to the points that Paul has been banging on about but I did finally do it and now have a significant part of my portfolio here.
I would like to add one further point. These ships operate UK back to UK. Maybe it shows my age but I am finding flight travel becoming ever more tiresome, but on the other hand I am very much in the Saga (LON:SAGA) target audience!!! 'No flight cruising' becomes ever more appealing. At a time when although we have the power of vaccinations and we are going to have to live with Covid going forward, airports are going to be places to be avoided for a very long time, if ever.
I think back to our last holiday in Feb 2020 on a Viking cruise in the Caribbean, inconveniently operating from Puerto Rico. Two flights each way, via Philadelphia to avoid the hell hole that is Miami. We flew business class and the time on the plane was very comfortable indeed (and of course very expensive), but the whole palaver of air travel is for the young now Im afraid. So, just making the case even more strongly for Saga cruising in future. I hope for the benefit of my shareholding value that I am not alone!
For my friends here with an interest in Angle (LON:AGL), I posted a comment late yesterday, following the company's RNS yesterday and the subsequent sharp fall in SP. Comments appreciated.
Hi ridavies
The fall was actually less than I had feared. It seems the market has taken on board the fact that FDA approval, if granted, has been deferred until the second half of this year and not rejected. Also, the additional information required by the FDA is statistical/analytical rather than requiring further human samples/trials, which would be much more time-consuming.
@ridavies
I agree with rogerh. The delay due to the Covid priorities at the FDA is annoying if entirely understandable and a fall in the share price was to be expected. It doesn't really change anything for me and I continue to hold. But I'm a relative newcomer to the stock so my patience hasn't yet been tested as much as that of longer term holders.
I agree with the previous posts – the delay is an annoyance but the FDA queries are at a level £AGL expected – there is no hint of the proverbial brick wall. I also at times think ‘US conspiracy’ but balance the views of medical companies with those of insurers who will benefit from the reduction Parsortix will bring to their costs.
A large part of the SP fall will have been manufactures by MMs who have been ‘shaking the tree’ for weeks in an effort to acquire stock. There was a significant reversal and I read elsewhere that some PIs were adding to their holdings at 73p. The start of the ISA season should also boost the price. I will continue to hold.
Just for info, I’ve read the University Hospital of Basel is recruiting cancer patients into a 9 year study to track CTCs throughout the life of the disease. We know they already use Parsortix.
another Boohoo (LON:BOO) report:- http://news.sky.com/story/booh...
That Parliamentary Committee is really working to keep itself in the news. As I recall it was £BOO who asked to come late last year and brief them.
Interesting, thanks for flagging.
I don't see it as price sensitive, as it's only a suggestion by the parliamentary committee. They can suggest anything they want. I would argue that we've seen how sensitive (in the short term anyway) the share price is to ESG concerns. Therefore the existing bonus scheme, which is linked to the share price, will be strongly influenced by the success or failure of BOO to clean up its supply chain.
I remain perplexed as to why the press have it in for BOO to such an extraordinary extent, when these problems are industry-wide?
The company is dealing with the problems, and ultimately it's the financial results that influence the share price the most. The growth here should be spectacular over the next couple of years, as the relaunched Debenhams marketplace (already doing something like £300m pa sales) comes on stream under new, more commercial management. Plus all the other new brands. There's hardly anything in the existing forecasts for this.
Meanwhile, the ESG lobbying is likely forcing BOO to source more from much cheaper overseas producers, helped by the weakening of the dollar against sterling, which should improve margins.
It's not the easiest share to hold, given the volatility, but there we go. Personally I'm in for the duration, as this should be a huge business in a few years' time. Everything else is just background noise.
Regards, Paul.
Boo. Its an easy clickbait headline for any news outlet, the fact its not time sensitive allows any news channel to use the story as a sub headline filler around the main stories of the day (if they have any), plus any individual news outlet can give traction to the story by simply re-telling over various days giving the impression that there is a mounting head of steam.
Agreed.
I'd suggest that anyone interested in Boohoo (LON:BOO) ASOS (LON:ASC) Next (LON:NXT) Associated British Foods (LON:ABF) Frasers (LON:FRAS) read today's article about Philip Green in the Telegraph (if they can get access). I learned a few things I didn't know - some relevant (Shein) and some just interesting.
I've reflected further on the stream of stories about Boohoo (LON:BOO)
One explanation is someone (or group) with a grudge.
Another is a competitor - either a retailer competing with Boohoo or a manufacturer competing with Leicester. I'd not considered this before because all the competitors I could think of could easily be discounted. But Shein looks a genuine worldwide competitor in the same space and, as a Chinese company, presumably has close links with Chinese manufacturers. Though I'd've thought they'd be vulnerable to the Uigher publicity - I'm not sure how accessible their supply chain is. I'm sure there will be others I don't know about, especially in the US.
I've reflected further on the stream of stories about Boohoo (LON:BOO)
One explanation is someone (or group) with a grudge.
The more likely reason is what it appears to be - there are serious problems with modern slavery in textiles in Leicester, Boohoo are the biggest user of the factories connected to them and it's an interesting - and easy - story for media outlets to run. There are a range of NGOs that have been raising concerns over conditions in Leicester for years, this is not new, but the failure to contain CV-19 in Leicester factories has given the campaign new impetus.
For instance - Stop the Traffik have been campaigning about conditions in Leicester since 2017:
Our research and intelligence have shown that Leicester is a hotspot for exploitation. In 2017, we launched a campaign to raise awareness that reached 175,000 people, which yielded results, but unfortunately, the problem has not gone away.
https://www.stopthetraffik.org...
Or you could look at the Behind The Label report on the same topic:
https://labourbehindthelabel.o...
It's trivially easy to find lots of similar examples. As Next have noted, they can't use most factories in Leicester because they don't meet their standards.
And, of course, also there's still an ongoing National Crime Agency investigation into modern slavery in Leicester. As I've said before, if there's no smoking gun then Boohoo will be fine but if there is all bets are off. If the Liberty Shared petition to the CBP gets granted that will have other repercussions.
timarr
Having had a look at stopthetraffick website you suggested, it appears that the fundamental problem, according to them, is illegal immigrants and others who are here legally, but with no right to work. As both groups of individuals are operating illegally, it is then not surprising that local employers who act illegally by employing these people do not pay legal minimums. It would be a bit like expecting bootleggers to keep to price controls or Mafia to be model employers.
Given that these are voluntary, albeit illegal, associations between illegal workers and illegal employers, why this is all given the moniker Modern Day Slavery I just don’t know...unless there also illegal slave markets now going on in Leicester as well!
Why it’s not the role of police, Home Office and Council to sort these issues, is beyond me, but I suspect that Boohoo (LON:BOO) will be working very hard to have nothing to do with these illegal employers and their illegal staff...queue more stories about how people are losing jobs because of £BOO...which would be funny, if it wasn’t tragic.
Why it’s not the role of police, Home Office and Council to sort these issues, is beyond me.
It is, but they've not been doing it. That's part of the Liberty Shared complaint. Some of the explanation is that HSE funding was cut by a third under austerity and they were told that the textiles industry wasn't a priority. The problems in Leicester have been known about for years - this report goes back to 2015:
https://www2.le.ac.uk/offices/press/for-journalists/media-resources/Leicester%20Report%20-%20Final%20-to%20publish.pdf/
It's clear, if you read around the topic, that the issues of working conditions and pay are endemic, it's not just illegal immigrants. It's a structural problem in Leicester linked to high levels of poverty, a big immigrant community, language issues and range of other factors. It's been known about for years, but it was only the persistant level of CV-19 in the community that forced it onto the government's agenda.
The problem for Boohoo (LON:BOO) is that, if this was widely known do they really have plausible deniability when it comes to distancing themselves from the problems? It's not like this was happening on the other side of the world. Arguing that it was the authorities responsibility to deal with this is one thing, but knowing about it and continuing to use these facilities is another.
However, the issue of people in Leicester losing the jobs is a non-issue. We can't seriously countenance modern slavery in the middle of one of the UK's cities in full view of the authorities. If these jobs and employers are lost then good. Hopefully they'll be replaced but either way they add no value to our society or to our economy. No one's paying taxes and most of the employees are having to claim benefits anyway.
But with all this being the case it's no surprise that the media keep on circling back to Boohoo. The arguement is circular - if the problem is Leicester then Boohoo are the problem.
If there's no smoking gun, if the NCA finds that there's no case to answer and if the CBP petition is rejected then Boohoo is very cheap indeed. But I don't think investors should delude themselves that this is all the big, bad press being egged on by people or people unknown. There's a real underlying issue, and the threat is not customers going elsewhere, it's criminal charges or sanctions.
timarr
I too do not understand the constant blaming of 'the press' for the travails of £Boo . If the US has opened an investigation into modern slavery then it doesn't matter if the press report it, the investigation is still opened.
I sold out my Boohoo holdings over the last couple of weeks. My reverse DCF indicates that they have to maintain 30% growth for next 5-6 years to justify price at this p/e. I feel that the pivot from US growth to a UK-centric online marketplace of brands is not without execution risk and puts this into question, and it is becoming harder and harder to deny (to myself) that Boohoo's fantastic success wasn't knowingly built on the problems in Leicester.
I'll happily return to the fold once all issues prove to be little more than a grudge by 'the press', but 30% growth is hard to pull off in the best of times.