Small Cap Value Report (Mon 11 Dec 2017) - SOS, OnTheMarket, PHTM, BOWL, MRL

Good morning,
Thanks for the comments, I'm planning to cover at least the following:
- Sosandar (LON:SOS)
- On The Market (new float)
- Photo-Me International (LON:PHTM)
- Hollywood Bowl (LON:BOWL)
Will then assess what to cover after that, possibly Marlowe (LON:MRL).
Best,
Graham
Sosandar (LON:SOS)
- Share price: 18.4p (-3%)
- No. of shares: 107 million
- Market cap: £20 million
This is an online womenswear brand which recently (last month) reversed into a shell on AIM. Adam Reynolds, who has been involved in similar deals to bring shells back to life, was Chair of the shell prior to the deal.
There are some great comments on this in the thread below, including one by Paul. So on the basis that Stockopedia is a "hive mind" of sorts, producing far more intelligence than any one individual could ever produce, I strongly recommend that you check out the comment thread!
Today's update is brief:
Sosandar plc (AIM: SOS.L), the online women's fashion retailer, is pleased to announce that trading since 31 August 2017 to the end of November has exceeded management expectations. The new funds raised at the time of the reverse takeover on 2 November 2017 are enabling the business to acquire larger and wider ranges of product and has also enabled the business to accelerate its media and marketing activities. Investment in new marketing channels has yielded strong results and will be further expanded in order to drive new customer acquisition.
I've taken a quick look at the Admission Document on the company's website. Sales for the five months ended August 2017 were c. £240k with cost of sales £123k.
Given how early-stage it is, this is almost purely a bet on the management team. The joint-CEOs are the founder and former editor of Look magazine. You can imagine how their experiences at Look might be very helpful and give them a fresh approach to online retail.
It's a bit too early-stage for my portfolio, but it's probably worth taking a look at this for anyone interested in ASOS (LON:ASC), Boohoo.Com (LON:BOO), etc, as another competitor in the space.
The strategy in the admission document is as follows:
Sosandar is an online womenswear brand specifically targeted at a generation of women who have graduated from younger online and high street brands, and are looking for affordable clothing with a premium, trend-led aesthetic.
So it isn't competing head on with "price-led" retailers, but it still wants to be affordable. Fair enough.
Since it's only selling its own-brand product, and not competing on price, the most important thing is that the brand itself is unique and memorable.
I'm certainly not the person who would be able to figure that out on my own, so I'll leave this for now and defer to those who might have keener insights.
-----------------------
Paul writes in the comments (please note that he owns shares in this company):
Sosandar (LON:SOS) - "Trading update makes generally positive noises, but gives no figures. Since the share price already has considerable expectations built into it, I think today's news won't necessarily move the share price up. It should however give holders comfort that things are going to plan (or rather, better than plan), hence preventing the share price from going down.
The only forecasts I have are a detailed note from Turner Pope from Aug 2017, which is the broker that floated Sosandar. This shows forecast revs of £1.0m this year 03/2018, rising to £3.3m 03/2019, and £9.4m 03/2020.
PBT is forecast at -£1.9m this year, followed by -£1.4m 03/2019, and a small maiden profit of £0.1m in 03/2020. Whilst these figures may look unexciting in terms of profitability, they look very exciting in terms of revenue growth. The market would extrapolate out the rapid growth rate, and value the shares on a racy multiple. I can foresee a £50-100m valuation within a year or two, if growth is strong. That may sound crazy, but we're in a bull market, where online fashion businesses that are demonstrating strong growth are given hefty valuations. Just look at the bonkers valuation given to hapless Koovs (LON:KOOV) a while ago, even though it was generating tiny revenues and huge losses.
SOS is well-funded for now, and exited the IPO process with net cash of about £7m, I believe. So it shouldn't need to come back to the market for more cash for the foreseeable future.
SOS is now one of my largest personal holdings, because I'm backing the experienced, and capable management. If you look at what they achieved in 1 year from startup, it's astonishing. Hence why I think the premium valuation is justified.
Note that there is about 18% potential dilution from share options for the founder management, as they had been diluted down to only 5% each from previous funding rounds, and the key people need to be incentivised. Not ideal, but I can live with it. Critics have said that there's something wrong with Sosandar, because management got diluted so much in the early stages, compared with say Boohoo.Com (LON:BOO) founders who retained almost 100% control before floating. What these critics overlook is that BOO was funded by an existing, highly profitable wholesale business (called Jogo/Pinstripe). So the BOO founders already had pots of money, so were able to fund BOO from scratch without dilution. Founders of Sosandar just weren't in a financial position to do that.
Anyway, time will tell whether this is an inspired stock pick, or bull market froth!"
END.
On The Market
I'm not sure why this has taken quite so long, but OnTheMarket today reminds us that it intends to raise £50 million and float. I first covered it in August, when it made the initial announcement.
As previously announced on 4 August 2017, OnTheMarket plc will seek to offer a minority stake to investors as part of the IPO with OnTheMarket's entire issued and to be issued share capital being admitted to trading on AIM. The objective is to raise approximately £50 million of new equity capital which will be used to fund the growth of OnTheMarket, already the third biggest UK residential property portal provider in terms of traffic.
This is the property portal owned by agents, who want to take control away from Rightmove (LON:RMV) and ZPG (LON:ZPG).
I can understand why they would want to do that, but I continue to lean toward the view that there is only space for at most two highly profitable companies in this space. Due to the network effects of this kind of website, smaller portals are of much lower value. Think Google or Facebook versus their nearest competitors in search or social networking! OnTheMarket is still much smaller than both Rightmove (LON:RMV) and ZPG (LON:ZPG).
Also, the expertise to run a web portal is very different to the expertise required to run a property agency, so I don't see why OnTheMarket would be any better than its larger competitors.
The only way I could see it working would be if the agents acted in unison to keep their listings off of both of the big portals. It tried that initially, and is still trying to incentivise agents to focus on their OTM listing and to hold on to their OTM shares:
A key part of the Group's growth strategy involves implementing appropriate incentives for agents to make a long term commitment to list their properties on the portal and the rapid building of its agency branch base. This will be achieved in part through offering equity participation following Admission to selected new agents alongside long term listing agreements, with arrangements in place to restrict agents from the short term sale of any such shares and to align their interests as shareholders with the success of the Group.
There is logic to this, but won't agents be highly tempted to sell their shareholdings, whenever they need some extra cash? Convincing large numbers of estate agents to be far-sighted and to hold on to valuable shares for the long-term, rather than liquidating them in the short-term, sounds very difficult to me.
It's a fascinating question but I'd be much more comfortable holding shares in Rightmove (LON:RMV), which has a unique position in the domestic market and has excellent economic characteristics (albeit that it is not cheap):
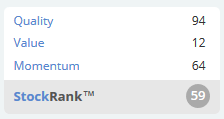
Photo-Me International (LON:PHTM)
- Share price: 180.75p (-3%)
- No. of shares: 376.5 million
- Market cap: £680 million
This vending machine operator (photo-booths and laundry units) issues results for the six months to October 2017. The results are in line with expectations.
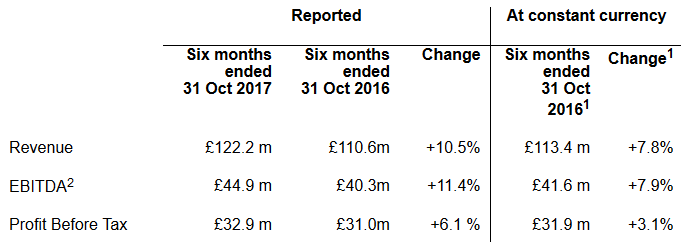
The constant-currency movements are very important since Photo-Me earns only 27% of its revenue from the UK & ROI segment. Most sales are from Continental Europe, particularly France. So I would focus on the percentage changes on the far-right hand side of this table.
I've written positively about this company in the past, on the basis that it was being managed well, was shareholder-oriented with heavy dividend payments from very healthy cash generation, and earned impressive margins.
There has been a worry about people taking selfies for passport photos and driving licenses instead of using a photo-booth. The response has been positive, as the company works with various European governments to encourage the use of photo-booths rather than self-taken pictures.
E.g. today's report informs us of the following:
In the UK, positive conclusion of discussions with Her Majesty's Passport Office and of the testing of the new online passport service; E-passport photobooths being rolled out across the UK, from mid December 2017.
With the photo-booth sector being mature and low-growth, emphasis for growth is now firmly on the laundry side of the business. The number of laundry units is up almost 50% over the past year, and revenues per mature unit are rising, too.
While the company offers full-services launderettes and B2B laundry services, the main growth element here is the self-service unit where small business and individuals can wash larger bundles than domestic washing machines can handle.
The company defines its "segments" as its different geographical regions, which makes it a bit trickier to get detailed financial info on how the laundry service alone is performing. "The Group is not managed around product lines", but instead around geography. We do know that laundry revenues for the period were £17 million, now material in the context of the group as a whole.
The outlook statement is good. No big surprises, as the growth strategy is executed:
In the medium term, it is anticipated that laundry revenue will grow significantly as a proportion of the total Group revenues and satisfactory progress is being made towards our target of 6,000 total laundry units (owned and sold) deployed by the end 2020.
Banking? One interesting little section concerns a potential new growth opportunity in retail banking, turning the photo-booths into ATMs. It would be fantastic if that evolved into something commercial. ATMs and photo-booths are both a little bit old-fashioned now. Putting them together in the same physical space, especially since photo-booths should already be enabled to read banks card, sounds good.
My opinion
Things are pretty much "as you were". This remains a healthy cash generator in rude financial health and generating strong returns on its capital for shareholders.
The PBT growth is a little bit weak, at 3% on a constant-currency basis, and I think this reflects the fact that laundry service margins are perhaps not so high as the photo-booth margins, and the photo-booth business remains under some pressure despite the company's best efforts.
The very helpful Risk section in today's report underlines again the threat of various governments taking regulatory action which would change the way people take passport photos.
Today's results also include £2.3 million in one-off profit on a property sale which was valued in the books at almost nothing prior to sale. So the results given are, if anything, an overstatement of the underlying profit prior to the sale.
Overall, therefore, I can understand why some shareholders might have lightened their holdings here today.
I've been positive about this share at slightly lower levels. At current levels, given today's results, it looks fairly valued to me.
Hollywood Bowl (LON:BOWL)
- Share price: 204.9p (+8%)
- No. of shares: 150 million
- Market cap: £307 million
This is a ten-pin bowling operator which we've covered twice so far this year - check the archives to see the previous articles. It's the largest bowling company in the UK with 58 sites.
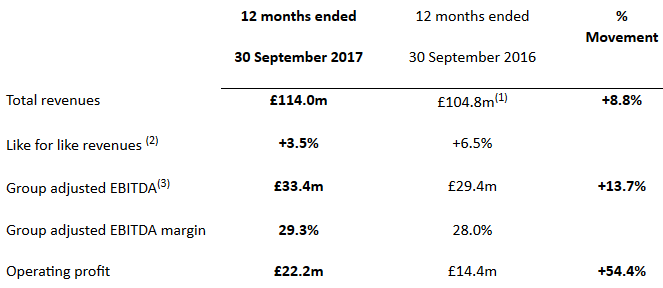
We already had a trading update for the full-year, where we learned that LFL revenue growth for the full-year was 3.5%, while total revenue growth was 8.9%, after a strong H2. H1 had been held back by dry weather (nobody wants to bowl when it's nice outside!)
The stock has been listed for just over a year and so far at least, it hasn't disappointed. The PE outfit which floated it is now fully divested.
These results are encouraging. Note however that the prior year saw £5.2 million in exceptional costs, which artificially depressed last year's operating profit. Excluding them, the underlying operating profit of £22 million in 2017 is 14% better than 2016.
Net debt falls to £8 million, insignificant compared to the company's profitability. Net debt/adjusted EBITDA is just 0.24x.
Indeed, the company had hinted at making a capital return due to the robust cash generation here. There will be a final dividend of 3.95p and a special of 3.33p, so total payouts this year of more than 9p per shares. The Board is happy with a debt/EBITDA ratio around 1x on average, so I can see generous payouts continuing for the considerable future.
CEO comment includes:
"We expect to continue this positive momentum as we intensively manage the portfolio for growth and deliver a high-quality customer experience, which continues to be great value for money.
It does sound like value for customers, at an average of £8.70 per game.
I've remarked before that this company has excellent clarity in its financial reporting, breaking out maintenance and expansion capex.
The text in this report is also very clear. The company's strategy includes being co-located with the top cinema in each new town that it enters. And when it rebrands or refurbishes a property, it demands at least 33% return on investment. Simple and good.
Being careful with its roll-out, it only opened 3 new stores in the most recent financial year.
My opinion
I like this company. It's executing plans well, it's another example of a market leader (and there are some benefits of scale in supplier negotiations), it's well-capitalised, and there are no obvious red flags.
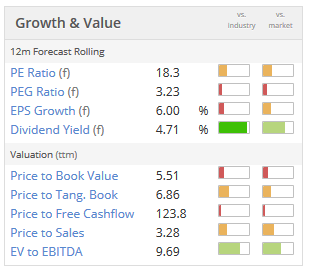
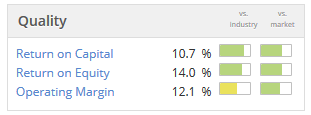
The only change that I might recommend is that perhaps the company is slightly too conservative on the balance sheet side of the equation? It's quite capital-intensive but the returns seem predictable enough that perhaps it could safely use a higher debt load. That would help to give the ROE a bit of a boost:
Marlowe (LON:MRL)
- Share price: 347.5p (+2%)
- No. of shares: 34 million
- Market cap: £120 million
This is an investor in support services businesses, specifically in fire, air ventilation and water services. It was a cash shell up until c. 2015, when it raised funds and began to take on its present form.
It wants to be "the UK's leading group of critical asset maintenance businesses", with cross-selling opportunities between its various services.
These results are on the back of four acquisitions, so the headline revenue gains are meaningless. Two further acquisitions have taken place since period-end. It had £18 million in debt facilities at period-end, so plenty more ammunition for purchases.
Outlook for the full year is in line with expectations:
The second half of the year has started well and we remain confident of delivering a full year performance in line with market expectations.
My opinion
Treating this as an investment company, and assuming that the prices paid for its subsidiaries have been approximately fair, I'd treat this first and foremost on an NAV basis. Book value is £48.6 million (September 2017), of which £37 million is intangible assets which were acquired with the purchase subsidiaries: goodwill and customer relationships.
This market cap implies that the combined entity has a value more than double the value of the funds which have been ploughed into it by shareholders so far. That's a lot of synergies from cross-selling and scale, and to be blunt is just a bit too high for me to be believable.
It is profitable, and if the deals have been shrewd and if management is high-quality, then some premium would certainly be reasonable. But I will leave this one alone for now.
That's it from me today.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
PS.
In addition to the investments mentioned, there have been the purchase of 1/2 commercial laundry operations + the retirement of 800 amusement rides. Thus although the number of machines is similar, there are no ugly ducklings in terms of ROE.This investment leads to a heavy D+A charge, depressing the P+L. Cashflow is the relevant measure here IMV.
Re:PHTM
I have to say that I am a little surprised by the general press comments.
What I see, is a solid business built around 3 core products/services, which trades on a pe of 18. But within these figures are the purchasing, re-equiping and the restructuring the ASDA franchises. The upgrading of the French,Irish and now UK photobooths and the roll out of the laundry business.
Their Japanese business has been criticised.
My number in Japan will come about, but there was a delay due to an initial rush of applications and then a data breach. For Japanese people, having a my number card, cuts the paperwork to negotiate the govt system, so demand will increase, the only questions for me are when and whether other operators will undercut the price.
The company has improved the products in each and their market positions, thus making them more valuable.
Apart from the current offering, the company has developed a number of new products/services which are hit or miss in nature, but crucially, these have not stopped the the significant cash generation finding its way back to shareholders.
Yes the car wash, figurine and wall paper business looked a bit odd, but they are a by product of the ant like industriousness.
At some point they may [or may have] develop[ed] a really useful product.
What is reassuring for me, is that the management have a measured approach to allocating cash to each idea.
I look on it a a 4.5% index linked bond with a venture capital arm thrown in for free. ie inexpensive to my mind. Personally, having seen the fingerprint scanners in Singapore at work and knowing how easy it is to photo shop 2d ID pictures for passports, I think the 3d photo idea could well be a winner.
Just wish Sosander had a different ticker!
Evidently some companies do actually need some help with their PR!
Re Hollywood Bowl (LON:BOWL), note that, if pricing is along the same, or similar, lines as its rival Ten Entertainment (LON:TEG) (I don't actually know, but I assume it is) then the quoted game price is PER PLAYER. I recently played 2 games at a Ten Entertainment (LON:TEG) bowling alley in a provincial city (Derby) on a Saturday late afternoon (so peak time - I understand Hollywood Bowl (LON:BOWL) use dynamic pricing? I think Ten Entertainment (LON:TEG) does too) as a group of three players. Our 2 games cost us £12-90 each (drinks extra; anything else extra) and provided entertainment for 40 to 45 minutes or so. Granted, I'm not used to crazy London prices, but it didn't strike me as good value, especially for small groups, for which the games are done in a jiffy. I can understand why both Hollywood Bowl (LON:BOWL) and Ten Entertainment (LON:TEG) are so cash-generative though. I have no position in either, though that might change in the future.
Regards,
Ed Miller
Marlowe (LON:MRL) I hold. Not sure you can treat a trading company as an investment company simply because it is executing a buy and biuld strategy. Put simply if you buy at say a PE of five or six and live in a stock market world where a PE of say ten was not considered toppy then every acquisition adds value. Now of course you need to trade them profitably and synergies are clearly an added benefit but assuming you do this then you also throw off cash and pay down the debt provide yield return to shareholders. Look at victoria ( which I have held for a number of years) classic and very well executed buy and biuld in a very untrendy "dull" market space. I think graham calling it and valuing as an investment company misses its point and its execution plan. Anyway, time will as ever tell! Great write up as ever. Just completed the survey and your section key reason for me being here.
Mixed views regarding Photo-Me International (LON:PHTM) as the way things stand the company pays a good dividend and even special dividends over their £50m Threshold (not sure if this still stands).
The recognised growth through the laundry side is clearly very good, and I am sure they will continue to invest in this as they see fit.
Cautious about the photo booth side, considering this has traditionally been their bread and butter source of income.It would seem there are other competitors eager to capitalise on Japans 'My Number' inititive scheme. Also they have commented about a softening demand in the UK.
However I feel very bullish about their efforts going into the Photo Identification technology. I personally have never been sold on the fact that a 'selfie photo' would be adequate for the future, when security levels have been at their highest for a while. So now the HM Passport service has rolled this out I see this as very positive.
This technology seems to be rubbing off into the banking sector. With recent news about RBS potentially closing around 250 of its high street banks, this would be a great benefit for them as they could open more smaller automated branches utilising their technology, if it works of course.
It leaves me questioning how easy will it be for someone else to emulate their technology In this sector, anyone have any thoughts on this?
So as a holder I am prepared to sit tight for now and tuck this one away for the long term.
Thanks
Sean
I'm confused, I'm reading you can do passport photos just with your ipad or mobile phone? Apple have 100 different country templates set up. Also in UK "Applicants can now renew their passports online by uploading a head-and-shoulders shot from digital devices, such as phones, tablets and cameras, in a move that will do away with the need to physically post a photo printout to the passport office."
Passport is usually only every 10 years but visa could be yearly but quite a few countries are going over to evisas which don't need a photo printed out, so I think the market is declining.
The CEO holds over 22% of the shares, I can see the dividend being maintained.
Re Photo-Me International (LON:PHTM), I'm just one case, but I'm not particularly good at taking selfies. However, I paid attention to the stated requirements for digital photos for a very recent passport renewal. My selfie, taken at home, by me, and without any help, and submitted online, was accepted, no problem. Advice was to get a friend to take the photo. Either way, if you follow the advice on how to take the shot and what the photo must, and must not include, it's a lot easier than making a special trip to a venue with a photo-booth to pay for the inconvenience of taking a photo away from home, when a photo conveniently taken at home is free. Worth bearing in mind perhaps, given PHTM's reliance on their photo-booths for revenue and profit? I have no position in Photo-Me International (LON:PHTM).
Regards,
Ed Miller
Yes I certainly agree that the way things stand at the minute doesn't really promise alot of future value from their booths, why would travel to one if you don't have to. I guess this is a play on if governments change the rules/restrictions in a few years from now. France Ireland and the UK are certainly making all the right noises.
Sean
Agreed (re £PHTM). That 'play' though seems to me a bit of a gamble rather than an investment, given that my convenient selfie-at-home was accepted by the UK passport office because it met their stated requirements. Given that they have already approved self-taken digital photos, I could only see them changing the rules and disallowing them if failure rate was over say, 50%. It does require paying attention to their requirements and perhaps to their advice on how to take the shot, but nothing else really. And given that the UK government have already allowed self-taken digital photos, it has to be a distinct possibility that many other governments - perhaps those of France &/or Ireland - will follow suite. Shame really - there's a lot to like about Photo-Me International (LON:PHTM), but the laundry-machines business is, for the moment, too small and too low-margin to make good for any unwelcome news affecting their photo-booth business.
Regards,
Ed
Re Sosandar (LON:SOS) I highlighted this to my better half after reading about it on here. I think she is about the target market (45), and she loved the look and ordered quite a few items. Unfortunately for my credit card bill, kept most of them.....
I saw this and thought it worth posting ... https://www.standard.co.uk/business/jim-armitage-a-very-fishy-minnow-shows-that-aim-is-way-off-target-a3715791.html
Another case of flagrant abuse on AIM and authorities seemingly not caring.
Does the Company ring any bells ? Maybe Stockopedia sleuths can work it out ...certainly if it sounds like one of your investments, could be time to ditch !
Thanks Nicobos
A fascinating Evening Standard article. Sounds just about par for the course. There are some great companies on AIM. But the poor regulation and lack of enforcement have turned AIM into a treasure trove for crooks and charlatans. And sorry, I don't know the name of the company.
Thanks for posting. Only partly related, there was an FT article on Zeus today, mentioning a number of Zeus's AIM flops (Accrol, DX, Entu) and that the LSE is studying whether to tighten up rules on the due diligence required to be done by NOMADs on AIM. The catalyst for the FT printing the article was not clear, as there was no recent news in the article - other than a tangential reference to the recently announced P/L of Zeus
https://www.ft.com/content/282f2cdc-ca23-11e7-ab18-7a9fb7d6163e
Photo-Me has achieved their longest period of earnings expansion (9 yrs), and due a decline https://i.imgur.com/F7MSpyf.jpg
But management reiterating growth in their laundry division could lessen this probability.
I feel they are paying a rather high dividend and should conversing cash due to unknown uncertainties surrounding Brexit.
Re Sosandar (LON:SOS) i know Paul is keen on it but I can see neither the appeal in their product range nor the demonstrated expertise in the management team to execute their chosen strategy. The website does not inspire confidence and the lack of numbers in the RNS is also worrying. They may well have sufficient funds in the short term but I would have to see more evidence of results before I would consider buying in here.
I think it's a little harsh to criticize the range... I'd be happy if my girlfriend came home in some of those dresses, as I'm sure many others would be, so I picked up a position this morning on the drop! Solid growth, not a ridiculous valuation, time will tell on this one!
Vote from me for Headlam (LON:HEAD) Sosandar (LON:SOS) and Photo-Me International (LON:PHTM) please!
Two out of three! Thanks for the suggestions. G
I wouldn't mind hearing your thoughts on Photo-Me International (LON:PHTM). They've successfully diversified into the launderette business, funded by cash flow from the photo side, and are simultaneously incrementally improving the photobooth arm. I think that management have played their hand well so far.
I also would welcome thoughts on the trading statement from Headlam (LON:HEAD) last week. It got passed over (MIA?) but would reward examination I believe as they also announced a significant acquisition.
Hi Damian, thanks for the suggestions. I hope 1 out of 2 is acceptable! Yes, I tend to agree with you on Photo-Me International (LON:PHTM).
Best wishes,
Graham
Please could posters put a £sign before the ticker symbol as it helps everyone.
So for example, photo me, with a £ sign before it, reads Photo-Me International (LON:PHTM).
cheers,
Francis
Interested in your view of Sosandar (no position) . Stockopedia seems to have the directors listed wrongly. I was interested to see that none listed on the company website seems to have experience of running a clothing company before. Hmmm.
Hi Fegger,
No, that's out-of-date information.
Sosandar reversed into Oregon Gold (ORE). So the business has completely changed.
Here is the up-to-date position;
http://www.sosandar-ir.com/
Regards, Paul.
Hi thats exactly where I was looking which is different to Stocko. If you look at those directors yes they have fashion magazine experience, they have media experience but I don't see any clothing retail operations experience. You've probaly got a handle on whether that's ok or not
Re Sosandar (LON:SOS) the comments in the trading update about being able to source more product now they have some money from the IPO rang alarm bells for me. I wonder what supply chain or operations experience they have on board. I fear this company has been brought to market too soon in its development.
For me Stockopedia is right to have this down as a sucker stock.
Out of interest, why does that comment ring alarm bells for you?
I have no experience of the retail clothing sector so would be interested to hear your comments?
@Zarathustra
Re Sosandar (LON:SOS) I would be aiming to get paid by my customers before I had to pay the suppliers so being cashflow positive. The comment implies that they aren't there yet which to me says they have immature supplier relationships where the suppliers are not yet willing to extend credit terms. That may change with more trading history and establishing a record of paying their bills on time etc.
It reinforces for me what an early stage business it is - too soon for a flotation in my view.
Hi Fegger, re Sosandar (LON:SOS)
Hi thats exactly where I was looking which is different to Stocko. If you look at those directors yes they have fashion magazine experience, they have media experience but I don't see any clothing retail operations experience. You've probaly got a handle on whether that's ok or not
Ah, sorry, I see what you mean now!
I think the joint CEOs are so immersed in fashion that they're highly credible. That they haven't done fashion retail before doesn't seem to be a problem, as the team around them fills in any gaps - e.g. the sourcing person at Sosandar is a former sourcing Director of Matalan, so has all the contacts needed with suppliers, and knows how to handle the detail of importing garments, quality control, etc.
As part of their fashion magazine experience, the joint CEOs had experience of designing clothing ranges for big brands. So their experience looks quite broad, and is very much the draw for me, in wanting to own this share.
The business model is great - all outsourced, so they don't have a warehouse, they use Clippper Logistics for handling the physical goods & dispatching them, handling returns, etc. The IT is outsourced too, to a big platform that is widely used by other eCommerce companies.
I think it's potentially very exciting. However, the current valuation is up with events, so I see this one as more of a long-term growth stock. For me, the slightly different fashion sector experience of the joint CEOs is actually a positive thing - as they've been immersed in the fashion itself, and what customers want, rather than the detail of retail. To be honest, online fashion retailing isn't that difficult these days. What really matters is offering unique & appealing products, and getting the marketing side of things right. Everything else should be manageable fairly easily using outsourced partners. I'm tremendously impressed with the product, it fills a big gap in the market for 35-55 women who want fashionable product, but don't want to look like mutton dressed as lamb.
Cheers, Paul.
I had shares in ORE so quite happy with this reverse. I mentioned this deal on here some months ago. I like the fact that some of the top daytime presenters are fans.
I bought shares in ASOS (ASC) at 4p and they of course went to £80 ....that stock was seen as far too risky by most as is Sos. ASOS was also hopeless too at the start...the receptionist told me on the phone that everyone was in the warehouse packing the big orders ...which was sort of inside info I suppose. Indeed they were....Victoria Beckham's pearl jeans copies were a big hit.
So I expect Sos to be all over the place at the moment. Their main role is to sell and get stuff out of the warehouse fast. So long as the margin is fine, there will be plenty of time to count the cash after Xmas.
Add me to the +1's kindly asking if you could please cast your eye over Photo-Me Graham.
It's been somewhat stuck in a channel for the past few years (I think the SP got well ahead of itself when re-rating from the lows), but it broke out recently, likely in anticipation of today's results (which look good). So wondering if the SP is finally going to make it to (the shores of France and) 200p+, backed up by the figures, or suffer fatigue and fall back into the (English) channel. (as figures have looked good in the past on results day, only to be met with falls and continued water treading in the channel).
Sosandar (LON:SOS). Thought this was a fairly pathetic announcement which told the market very little in reality, and was so circumspect about the period involved, that it is possible to think it may not be that good as it looks superficially.
The market reaction seems to be 'so what!'
Sosandar (LON:SOS) - trading update makes generally positive noises, but gives no figures. Since the share price already has considerable expectations built into it, I think today's news won't necessarily move the share price up. It should however give holders comfort that things are going to plan (or rather, better than plan), hence preventing the share price from going down.
The only forecasts I have are a detailed note from Turner Pope from Aug 2017, which is the broker that floated Sosandar. This shows forecast revs of £1.0m this year 03/2018, rising to £3.3m 03/2019, and £9.4m 03/2020.
PBT is forecast at -£1.9m this year, followed by -£1.4m 03/2019, and a small maiden profit of £0.1m in 03/2020. Whilst these figures may look unexciting in terms of profitability, they look very exciting in terms of revenue growth. The market would extrapolate out the rapid growth rate, and value the shares on a racy multiple. I can foresee a £50-100m valuation within a year or two, if growth is strong. That may sound crazy, but we're in a bull market, where online fashion businesses that are demonstrating strong growth are given hefty valuations. Just look at the bonkers valuation given to hapless Koovs (LON:KOOV) a while ago, even though it was generating tiny revenues and huge losses.
SOS is well-funded for now, and exited the IPO process with net cash of about £7m, I believe. So it shouldn't need to come back to the market for more cash for the foreseeable future.
SOS is now one of my largest personal holdings, because I'm backing the experienced, and capable management. If you look at what they achieved in 1 year from startup, it's astonishing. Hence why I think the premium valuation is justified.
Note that there is about 18% potential dilution from share options for the founder management, as they had been diluted down to only 5% each from previous funding rounds, and the key people need to be incentivised. Not ideal, but I can live with it. Critics have said that there's something wrong with Sosandar, because management got diluted so much in the early stages, compared with say Boohoo.Com (LON:BOO) founders who retained almost 100% control before floating. What these critics overlook is that BOO was funded by an existing, highly profitable wholesale business (called Jogo/Pinstripe). So the BOO founders already had pots of money, so were able to fund BOO from scratch without dilution. Founders of Sosandar just weren't in a financial position to do that.
Anyway, time will tell whether this is an inspired stock pick, or bull market froth!
Regards, Paul.
Any interest in £PHTM? Results this morning with laundry revenue +75% and dividend +20.1%
Morning Gents. Ive there is a chance you could look at Vela,VELA I would be grateful. It has some interesting investments in blockchain and the like and looks to be rising with the price of crypto currencies in general. It could be described as an investor in disruptive technology firms.
Appreciate its a tiddler but I think it looks like a proxy play for those that have not jumped on the bitcoin train.
Another request for Marlowe (LON:MRL) please and Spectra Systems (LON:SPSY). Thank you
Thanks for the suggestions, appreciate it. Not sure what to conclude from the Spectra Systems (LON:SPSY) postponement today.
G
Forgot to mention late news from Friday for Boohoo.Com (LON:BOO) holders-
Announced after market close on Friday. BOO CFO and NED increase holdings. CFO insignificant 1/2% but NED 6% increase.
Dave
That is interesting re Boohoo.Com (LON:BOO), particularly as the Kamani 6 month lock-up following the sale in June must be on the point of expiring.
Hi Graham,
Not sure if they're "your bag" as I don't think you've covered them before but would love your view on the following if suitable...
Marlowe – 340p – £116.9m – PER 23.4
Interim Results For The 6 Months To End September 2017 – Revenue up 104% to £36.0m, PBT up90% to £2.4m (£1.3m last time) and EPS up 23% from 5.1p to 6.2p. “The second half of the year has started well and we remain confident of delivering a full year performance in line with market expectations”.
Having looked into this a little more I like the forecasts (they’re massively greater than any historic performance) and the fact it’s got Cash in the bank (albeit a small amount). IF the forecasts are met (and it looks like they may be based on this update) this is looking quite attractive here.
K3 Capital ( £K3C ) – 149p – £62.9m – PER 13.7
Trading Update – Expects “Interim Results will demonstrate a continuation of the Group's strongperformance across all three divisions with significant uplifts from the comparable prior year period”. Expecting to report record revenue of approximately £7.5m, a LFL increase of 34 per cent and EBITDA of approximately £3.3m, a LFL increase of 27 per cent - Comfortably in line with market expectations for the full year ending 31 May 2018.
Quite like the look of this, it looks good value here. It's going on my Watchlist (but I hate EBITDA, why can't the tell us the real PBT - Arggghhhhh!) until I see the actual results.
Thanks in advance.
A vote for Polar Capital Holdings (LON:POLR) H1 results - Have others noticed that most of the Investment management companies are doing well at the moment?
I echo a vote for Polar Capital Holdings (LON:POLR) to have Graham’s considered view on a company in one of his focus sectors.
Although no longer a small cap at £1bn, the short announcement from Plus500 (LON:PLUS) of a licence to operate in Singapore, their first in South East Asia, where I believe there may be one or two "gamblers" is significant.
Agree unquantifiable good news from Sosandar (LON:SOS). Management expectations plus X%, where X could be a very large or very small number! Not sure Graham can produce an analysis on this announcement?
A most unusual announcement from Spectra Systems (LON:SPSY) in that they say they have had to postpone the AGM for lack of a quorum! With a float of 73% there should surely be enough to gather a quorum amongst the Directors and inside investors, but it appears not.
This is another aspect of the ridiculous situation that most private investors find themselves in as nominee holders prevent us from directly participating. It requires effort (which I admit to not often putting in) to get the nominee to provide an authorization for the holder to attend meetings (and I am not sure that attendance on such terms would count towards a quorum anyway)
Agreed Aislabie. Surely there is a good opportunity here for a broker willing to go the extra mile and offer CREST membership to its clients. Lots of downtrodden private investors would, probably, go for that even at a slightly higher cost. I have a CREST account which, sadly is no longer available to new clients. But this does not extend to my SIPP or ISA so it only covers a small portion of my portfolio.
I have been trying to get my SIPP broker to get me the covering letter so that I can attend the Bioventix (LON:BVXP) AGM on Thursday. I have called twice over the last month. So far all I have had is promises.
And there must be a question about what is going on at Spectra. It is quite a strange situation anyway - a company that doesn't know who its clients are. Could be a genuine situation or should we exSpectra something strange?
Aislabie re Spectra Systems (LON:SPSY);
They have postponed the AGM in both '15 &'16 ; after the latter, prices rose by 50% in the next two weeks , so in that case was not a forecast of bad news. Unlikely to be so in this current case either, as there was a jubilant trade update only on 16.1017
Thank you for the note on Spectra Systems (LON:SPSY)
I have been trying to figure out why getting a quorum is so hard; it appears to require over 50% of voting shareholders to register/attend. This would seem high but "broker non-votes" are included in any count which seems to refer to shares held in nominee accounts. Since the company has 52% held privately you would think that this could be rounded up fairly easily. Hargreave Hale has 5%, a former NED has 8% , a single company In Guildford, Worsley Associates, has 15% and the CEO has 4%.
But it may be that in a company with only 29 people (re Stockopedia) that nobody has got round to organizing this.
My morning smallcap tweet:
Sosandar (LON:SOS), Ukrproduct (LON:UKR), Aquatic Foods (LON:AFG)
Sosandar (SOS) trading since 31 August 2017 has exceeded management expectations.
Ukrproduct Group (UKR) OTP Bank loan extended again to March 2018. Bank has agreed in principle to a 3 year extension to the OTP Loan, needs extra time to ut the 3 year extension into place. What, months?
Aquatic Foods Group (AFG) NED Mircle Yap Ching Chai resigns.
PS Also voting for Hollywood Bowl (LON:BOWL) where profits are up 50% and £YU to which Ofwat has just granted the licence to sell water services to businesses, both of which I seem to have missed the boat on. Is Yu (LON:YU.) still a momentum trap?
Love the Hollywood Bowl (LON:BOWL) suggestion - been keeping an eye on that one. Cheers RTJ.
G
photo me please
photo me please
Click!
Happy Monday all: Sosandar (LON:SOS) = 'Sosandar plc, the online women's fashion retailer, is pleased to announce that trading since 31 August 2017 to the end of November has exceeded management expectations. The new funds raised at the time of the reverse takeover on 2 November 2017 are enabling the business to acquire larger and wider ranges of product and has also enabled the business to accelerate its media and marketing activities. Investment in new marketing channels has yielded strong results and will be further expanded in order to drive new customer acquisition.
Julie Lavington and Ali Hall, Joint CEO's, commented: "We are delighted with the progress we have made to date and the additional funds we have recently raised has allowed us to drive significant momentum into the business. Our depth of product is expanding, we are now able to buy larger lines of product, thus reducing lead times and increasing margin."
I know what Paul would say: but what *are* management expectations? Wondering what you think Graham, thanks! I hold a smidgeon.