Small Cap Value Report (Mon 11 March 2019) - SCVR Grim Tales, Mello, TSLA, NTBR, XAR, QRT, ORCH, DRV

Morning!
How are we all doing? From a financial point of view, the FTSE All-Share is up well over 7% year-to-date (including today's gains). But I get the sense that those of us in the small-cap space aren't doing quite so well.
The AIM All-Share Index was up 5.4% as of last night (excluding dividends, which don't make much of an impact anyway).
Within AIM, however, there have been many individual casualties and sadly many of them were favourites of the private investor.
I enjoyed this article by timarr: When Stocks Go Bad: Grim Tales from the SCVR. He goes into a great level of detail into popular stocks whose valuations have suffered to one degree or another:
- Revolution Bars (LON:RBG)
- Keywords Studios (LON:KWS)
- Purplebricks (LON:PURP)
- IQE (LON:IQE)
- accesso Technology (LON:ACSO)
- Amino Technologies (LON:AMO)
- Flowtech Fluidpower (LON:FLO)
- Gear4music (LON:G4M)
- Fevertree Drinks (LON:FEVR)
- Restaurant (LON:RTN)
- Plus500 (LON:PLUS)
- XLMedia (LON:XLM)
- Taptica International (LON:TAP)
- XP Power (LON:XPP)
- Air Partner (LON:AIR)
It's a fine list, worthy of dissection.
It turns out that I've never had a position in any of these shares, but perhaps I should have: long-term holders in Fevertree Drinks (LON:FEVR), for example, have done terrifically. A period of share price weakness is inevitable for any company. Fevertree Drinks (LON:FEVR) remains on my watchlist for a potential purchase.
On the other hand, there are some members of the above list which I've written cautiously about: the first four of them in particular and also the three Israeli shares. While acknowledging that I could be unduly cautious, my stance on these seven companies is unchanged.
As a general principle, there is a lot to be said for avoiding "popular" shares, as they do tend to be higher risk and priced unattractively. Like any rule, there are exceptions. But the best investment is probably the one where you are the first, or at least early, to discover it. If it subsequently becomes "popular", I guess that's beyond your control.
This community is special because those shares which become popular here tend to at least have good arguments in their favour. There are other venues, which I won't name, where their popular shares tend to be the most speculative and poorest-quality companies with the fewest redeeming characteristics.
As the Mello slogan goes, "Invest in Good Company".
Mello Trusts & Funds - 15th May
Speaking of Mello, I hope to see many of you at Mello London this year. On 15th May, the companies event will be preceeded by a Trusts & Funds event, the first of its kind. Keynote speakers will include a range of leading experts in the trusts and funds space.
So whether you invest directly in trusts and funds, or are merely a keen watcher of the investment sector, this should be a fantastic occasion.
I have been informed by the organisers that those who wish to attend Trusts and Funds on its own, rather than the full 3-day extravaganza, can enjoy a £20 discount if you use the code Stocko20. You're welcome!
Tesla ($TSLA)
Apologies for mentioning something that is neither UK-listed nor a small-cap, but this is currently my key research focus.
Tesla is the only company I have shorted since Slater & Gordon back in 2015. I have been carefully analysing its financials, trying to understand the likely progression of its cash pile.
Unfortunately, this is a crowded trade on the short side with about 15% of shares currently sold short (25.5 million out of 173 million).
At least this is a material reduction from the short interest around April and May of 2018, when 39 million shares were sold short. That would have taken more than 7 trading days to cover based on volumes at the time.
In hindsight, that short interest looks like it was justified to me. Elon Musk admitted that the company was "within single-digit weeks of death" during the cash burn in early 2018.
Many levers have been pulled to accelerate cash flow since then, and no doubt more levers will be pulled to coincide with the unveiling of the new Model Y.
To avoid any damage from a short squeeze, I have been investigating long-term put options as a means of expressing my view on the situation.
While it's true that the short trade is painfully crowded, what maintains my interest in this opportunity is the company's financial data, specific risks related to Tesla's governance, and the strength of the arguments from the longs (who will be my counterparty, if I execute the trade).
Now let's get down to business and look at some of today's updates:
- Northern Bear (LON:NTBR)
- Xaar (LON:XAR)
- Quarto Inc (LON:QRT)
- Orchard Funding (LON:ORCH)
- Driver (LON:DRV)
Northern Bear (LON:NTBR)
- Share price: 66.34p (-12%)
- No. of shares: 18.5 million
- Market cap: £12 million
It's a short update from this Newcastle-based group of building services companies, so I'll try to keep this brief.
- The group continues to trade well.
- For ten months to January 2019: ahead of expectations, in line with the outstanding prior year.
- Current expectation is that adjusted operating profit for FY March 2019 will be broadly in line with the prior year (GN: this probably means a bit less than the prior year).
There are no numbers given in the update, and no consensus forecasts in the market, either. So we are driving blind as far as market expectations.
For what it's worth, adjusted operating profit was £3.1 million last year. This translated to net income of £2 million.
I retain my positive impression of the management team here. If you are happy to invest in building services, then this seems like one of the better options, albeit at a very small scale.
Valuation reduces to c. 6x net income after this slight disappointment, with no further progress made in FY 2019 as far as profitability is concerned.
Investors are right to price this at a cheap multiple, in my view, given the inherent risks. I would view it as fairly priced, offering nice upside if the company gets another fair wind behind it.
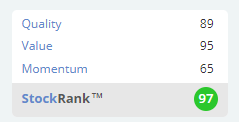
The StockRanks, looking at things purely from a quantitative point of view, adore it:
Xaar (LON:XAR)
- Share price: 125.4p (-7%)
- No. of shares: 78 million
- Market cap: £98 million
Another brief update. Xaar makes industrial printheads and other inkjet technology.
It's amazing how far this share has fallen since its glory years. It was worth about £750 million at the peak. Hopefully it reaches a point where it is fundamentally good value soon!
My suspicion is that competitors in China, where many of Xaar's customers were based, have stolen its thunder. Demand from China was always very unstable. See this story from 2014.
Today's update:
- underlying results for FY 2018 in line with expectations. Revenues £63.5 million, net cash £27.9 million.
- provisions of £7 million relating to inventory and debtors. There is an "unfavourable working capital aging profile".
My view
The company will argue that this £7 million hit does not relate to the current period. To the extent that is true, it means that previous periods were in aggregate £7 million worse than reported.
Looking at the forecasts in the market, I see that Xaar is forecast to make a loss this year and next year, adding to the pain of an expected loss for 2018.
It is looking for "more extensive partnering in the Printhead business unit". Perhaps going one step further and getting a trade sale to one of the big boys is how this will eventually play out? It would seem to be the logical outcome of several years of disappointment, with more losses lined up despite the company's cost-cutting efforts.
To me, the shares are definitely worth something. Xaar has always made sure that it has a big cash pile, and has managed its costs lower in line with falling demand, and I expect it to remain prudent in that regard. And the digital printing technology it offers, while difficult to assess from outside the industry, appears to offer something unique to customers. The company has nearly 300 patents registered or pending.
According to Xaar's interim results for June 2018, it had balance sheet strength as follows:
- net assets of £142 million
- net tangible assets of £104 million
- net current asset value (NCAV) of £75 million
I suppose we need to knock at least £7 million off all of these numbers for the latest provisions.
That leaves NTAV of £97 million and NCAV of £68 million.
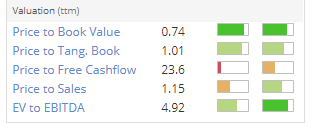
This could be completely wrong, but I would have thought that a large competitor would be happy to snap up Xaar (e.g. Konica Minolta?), with tangible balance sheet value providing a floor to the valuation.
Quarto Inc (LON:QRT)
- Share price: 53.5p (-2%)
- No. of shares: 20 million
- Market cap: £11 million ($14 million)
Final Results for the Year Ended 31 December 2018
Another major faller, these shares are now trading like options on the company's $60 million debt pile.
Results are USD-denominated, as more than half of revenues are derived from the US.
Quarto is a global book publisher whose results have been seriously disappointing since 2017.
Let's summarise the latest news:
- revenues down 2% to $149 million
- adjusted PBT $5.9 million, up from $3.9 million
- exceptional costs $5.2 million. After those costs, plus amortisation of intangibles, there is a statutory pre-tax loss of $0.1 million.
The company's ambitions are unbowed: it wants to be "the dominant publisher of illustrated books worldwide".
The Board has been shaken up, costs have been cut, and banking facilities are renewed to 2020.
The CEO (also a major shareholder) acknowledges the priority being given to debt management:
Net debt is still sizeable and remains an immediate focus for the Board.
Outlook - not much change expected in the short-term. "Ongoing soft market conditions" to continue, mostly impacting foreign language markets and Adults books.
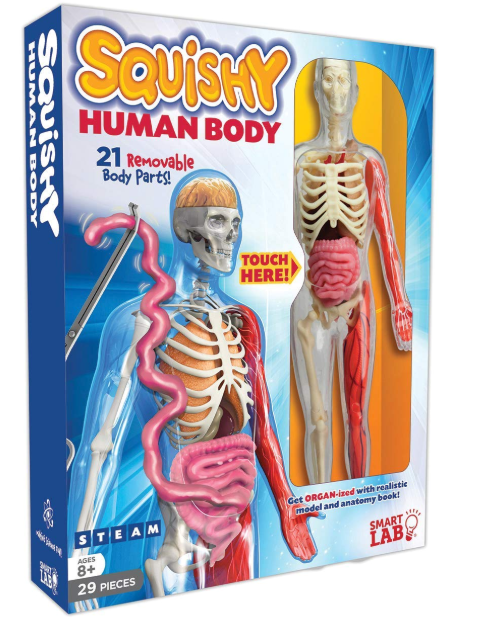
(Quarto's top selling product in 2018 was a weird toy, not a book. Source: Amazon)
Exceptional items - reorganisation costs, board changes and refinancing costs. While individually they are one-off in nature, I would expect similar "one-off" costs to occur in many years.
Cash flow: there is some funny accounting, with large "pre-publication costs" of books being capitalised and then amortised or written off.
Quarto enjoyed operating cash flow before movements in working capital of $38 million in 2018, up from $37.3 million the year before.
It then spent about $30 million of cash preparing books, with $32 million in total spent on investing activities. After all was said and done, there was roughly $6 million left over for interest payments and debt reduction.
My view: the enterprise value is c. $74 million. If the company could continue doing what it has just achieved in 2018, earning about $6 million in cash flow after investing activities, then I would think that it is attractively valued.
However, recent events have shown that there is a great deal of uncertainty surrounding the value of the company's investing activities, as huge amounts needed to be written off.
I don't feel qualified to judge its prospects at this point but it does strike me as interesting and worthy of additional research.
Orchard Funding (LON:ORCH)
- Share price: 84.5p (+3%)
- No. of shares: 21 million
- Market cap: £18 million
Half-year Results - six months ended 31.1.19
This specialist lender to professionals reports good results, with the loan book up by almost 10% and PBT up 18% on a like-for-like basis.
Pricing has weakened a little. Average gross rate on loans made is 6.2%, down from 6.5%.
The exciting bit about this company is that it's applying for a banking license, so it could end up being a similar type of story to PCF (LON:PCF) (in which I have a long position).
There is a link with another financial stock I'm involved with: Orchard's CEO and major shareholder is a director of Honeycomb Investment Trust (LON:HONY), the provider of a debt facility to Duke Royalty (LON:DUKE) (in which I have a long position).
Outlook - momentum has "continued to build" in Q3.
My view - I am leaning toward the view that this is undervalued, as it has equity of £14.6 million and seems to be earning a good return on that, even at its current small scale and before any conclusion to the banking license process. So I believe it should be trading at a range of 1.5x - 2x book value.
What's holding me back from getting involved with a starter position is the 6p spread. The free float is less than 10 million shares, so it is probably very illiquid. Apart from that, I quite like this one.
Driver (LON:DRV)
- Share price: 52.1p (-23%)
- No. of shares: 54 million
- Market cap: £28 million
Comment by drvodkaquickstep, who has a long position in DRV. Huge thanks for his input:
------------------------------------------------------------------
As any readers of this investment forum and others such as ADVFN will be aware, I have been a firm supporter of Driver (LON:DRV) since early / mid 2017 when they refinanced and brought new management in. From the 40p placing in Feb 2017 the valuation of the business more than doubled within 18 months; topping out at circa 85p last October.
This morning's Trading Statement noting some deferred and delayed commissions in their Middle East and Asian operations has therefore, not been well received by the market with the valuation down 26% as I write.
Frustratingly, the Trading Update was in mid-February last year and investors can only assume that some of the delayed contracts were hoped by management to be secured prior to the Trading Update but sadly not.
The valuation of the business has in fact been under pressure since the Year End (Sep 2018) and some questions marks have been raised this morning on social media concerning share sales by Directors (or their wives) in November 2018 and earlier this month along with a circa 1% share sale that was printed last Friday.
The weakness in the share price, a reduced cash position and the above noted transactions pre-TS do raise some questions and I have written to management this morning to express my concerns.
All of this said, Driver (LON:DRV) remain a leading expert in their field, are profitable, now pay a divi and have a solid order book.
The market reaction this morning seems unwarranted but current macro issues and perceived nervous investor sentiment means such news will be punished accordingly. Driver are a Top 3 holding for me so not a good start to the week.
And more:
Further to my initial comment above re: Driver (LON:DRV) I have since spoken to Gordon Wilkinson (CEO) and he confirmed his agreement to me relaying the content of our discussion here:
1) Trading Statement date. Gordon noted that whilst the trading statement was in February last year the Board did not want to release an update without the full facts on some of their delayed/deferred contracts and the necessary information to update the market was only recently made fully available to the Board. See 2) below...
2) Cash Collection. I quizzed Gordon re: the narrative in the statement concerning cash collection and he noted that a couple of staff members had had their "knuckles wrapped" re: timeliness of reporting both with respect to timely cash collection and the status of contract awards/delays. From my own professional experience in this sector I am fully aware of the challenges of contract award dates when a client will update you each week saying "yes the paperwork is on its way to you" only to get the same story for the next few weeks and sometime months making it very difficult when trying to forecast. Always better to err on the side of caution.
3) Recent Director / PMDR share sales. Personally I have a fairly relaxed attitude to Director share sales as everyone has their own reasons for selling although clearly it's not a sign of confidence. I questioned the sale (200k shares) in November 2018 by the Regional Director of the MEA business and Gordon noted it was off the back of the positive October trading statement (pre FY) and hence there was no reason for the Board to object to the sale. Equally Gordon was made aware of the intention by the wife of the UK MD to sell 25k shares in early February at which time again the Board had no reason to object to the sale. By the time the transaction was reported it was 1st March 2019 and he noted the timing could have been better.
It should be highlighted that Gordon personally owns and/or has options over circa 2m shares and hence he has some alignment with other shareholders.
4) Cash position. The £5m cash position noted in the TS is net cash (actually £5.1m) and compares to £6.9m net cash at the year end. The reason for the difference (reduction) pertains to the Group's contracts in Oman where the finance ministry are very slow to pay between Nov-Feb each year. The Group hence has to fund its Omani projects until payments are released from March onwards and Gordon noted that a six figure payment had recently been received with further payments due imminently.
5) Share price weakness in 2019. Gordon noted that the Board was made aware in November 2018 of one of their major shareholders wanting to reduce their holdings hence there has been some downward pressure on the share price. This may also possibly account for the large trade on Friday last week although the timing of this specific trade is still questionable.
6) Middle East staff. Some staff have been released in the Middle East due to a slowing workload. Having worked in the Middle East myself for 6 years I know how boom and bust it can be although its hard a strong run since 2010. Things will pick up again as sure as the sun sets and rises. The cost of these redundancies will not be treated as exceptional.
Summary
Gordon summarised our phone call by noting his own frustration given the turnaround of the business since 2017, the order book being at a record level and the core UK business (30% of sales) etc which is doing "very well". It would appear there is scope for the noted contract delays to fall into H2 although clearly nothing is certain.
With 10p a share in cash and assuming diluted EPS of circa 5p puts the Group, which is still on a growth trajectory, on a cash adjusted PE of less than 9.
Whilst this news is disappointing I plan to retain my holding and perceive the Group as increasingly likely to be the subject of future M&A should current prices persist.
END
That's it for today, cheers everyone!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Obviously, I'm a day late...a few observations re Quarto Inc (LON:QRT)
1) Despite $6m fall in gross debt from $77m to $71m and $13m of it switching from bank to directors and associated cos the interest expense is up from $2.9m to $3.7m plus there is $0.4m of 'other interest' too. I'd have liked some further disclosure around this (Nov RNS doesn't say much either). Looks like banks have demanded immediate reduction to extend credit facility and new CEO CK Lau has had to stump up the cash.
2) CEO owns near 30% of company. He's out of pocket on his stock purchase and now he's had to find nearly the equivalent of market cap for loans
3) Increase in payables last couple of years to help cash flow - $4.6m 2018 and $6.8m 2017 (2018 offset by $2.3m increase in receivables).
4) There are a businesses and initiatives that are not core (eg Q Partners, some of their publishing teams). Its unclear whether these will flourish or become exceptionals...and whether this is good for profit.
5) What's the duration of backlist? At 2/3rd of revenue and requiring low investment there would seem potential to cut investment and overhead and generate high cash flow. However, in recent years part of the problem seems to be that some old publishing units were a bit dead on their knees and that acquisitions and heavy investment in recent years in new publishers and publishing (that partially responsible for sinking old management) was needed to replace dead wood.
So, where is the company at?
Why doesn't Lau just take private? One more significant negative surprise and is he effectively forced to take private?
Who has the answers? :)
Always interested to hear your thoughts on $tsla Graham as im long, though the constant negativity does keep me second guessing myself -probably a good thing. I still believe the product they offer for the price isn't going to be matched by their competitors anytime soon, even if it is claimed they will be. Though I feel better about it over 10 years than over the next 1-2, falling margins on the model 3 and the ramp up in production for the model y might mean a repeat in the up and down share price of the last few years.
According to various news sources, the Financial Reporting Council is to be abolished and replaced by a new regulator, the Audit, Reporting and Governance Authority. The BBC claims that for the first time, the new regulator will be able to:
Colour me cynical, but I'm not holding my breath.
deleted
Record (LON:REC)
Is there any excuse for releasing a RNS at 16:29?
No. Outrageous and I'm not even a holder.
Why not first thing tomorrow.
No, an RNS at 16:29 is inexcusable. I would argue 16:35 is fine, as it gives everyone time to digest the news.
I'm not sure about the precise timing of this RNS, but the first sell trades were at 16:29:13 and Shareview shows 8 trades over the next 4 seconds, although all very modest trade sizes. Compared with no trades at all from 12:59 to 16:29.
Hi Graham
Thanks for your write up on Orchard Funding (LON:ORCH) as it's a company which is also on my watchlist.
Although I agree with your sentiment of potential value following the weakening of the share price, my only concern is the company's constant reference to obtaining a banking licence over the last 12 months which consistently fails to materialize.
I'm not surprised investors have moved away to more fertile investment territory and the share price is where it is when one of the main prospects for growth of the business resembles can-kicking down the road....
Considering how long it took PCF (LON:PCF) to get a banking licence (and it was already majority owned by a bank) I do not see any concern about a banking licence for Orchard Funding (LON:ORCH) which was only applied for in July 2018
Another point raised recently in SCVR was that City Financial was a significant holder and the recent price drop may have reflected a liquidation of their holdings
Further to my initial comment above re: Driver (LON:DRV) I have since spoken to Gordon Wilkinson (CEO) and he confirmed his agreement to me relaying the content of our discussion here:
1) Trading Statement date. Gordon noted that whilst the trading statement was in February last year the Board did not want to release an update without the full facts on some of their delayed/deferred contracts and the necessary information to update the market was only recently made fully available to the Board. See 2) below...
2) Cash Collection. I quizzed Gordon re: the narrative in the statement concerning cash collection and he noted that a couple of staff members had had their "knuckles wrapped" re: timeliness of reporting both with respect to timely cash collection and the status of contract awards/delays. From my own professional experience in this sector I am fully aware of the challenges of contract award dates when a client will update you each week saying "yes the paperwork is on its way to you" only to get the same story for the next few weeks and sometime months making it very difficult when trying to forecast. Always better to err on the side of caution.
3) Recent Director / PMDR share sales. Personally I have a fairly relaxed attitude to Director share sales as everyone has their own reasons for selling although clearly it's not a sign of confidence. I questioned the sale (200k shares) in November 2018 by the Regional Director of the MEA business and Gordon noted it was off the back of the positive October trading statement (pre FY) and hence there was no reason for the Board to object to the sale. Equally Gordon was made aware of the intention by the wife of the UK MD to sell 25k shares in early February at which time again the Board had no reason to object to the sale. By the time the transaction was reported it was 1st March 2019 and he noted the timing could have been better.
It should be highlighted that Gordon personally owns and/or has options over circa 2m shares and hence he has some alignment with other shareholders. He has not sold any shares since joining the business.
4) Cash position. The £5m cash position noted in the TS is net cash (actually £5.1m) and compares to £6.9m net cash at the year end. The reason for the difference (reduction) pertains to the Group's contracts in Oman where the finance ministry are very slow to pay between Nov-Feb each year. The Group hence has to fund its Omani projects until payments are released from March onwards and Gordon noted that a six figure payment had recently been received with further payments due imminently.
5) Share price weakness in 2019. Gordon noted that the Board was made aware in November 2018 of one of their major shareholders wanting to reduce their holdings hence there has been some downward pressure on the share price. This may also possibly account for the large trade on Friday last week although the timing of this specific trade is still questionable.
6) Middle East staff. Some staff have been released in the Middle East due to a slowing workload. Having worked in the Middle East myself for 6 years I know how boom and bust it can be although its hard a strong run since 2010. Things will pick up again as sure as the sun sets and rises. The cost of these redundancies will not be treated as exceptional.
Summary
Gordon summarised our phone call by noting his own frustration given the turnaround of the business since 2017, the order book being at a record level and the core UK business (30% of sales) etc which is doing "very well". It would appear there is scope for the noted contract delays to fall into H2 although clearly nothing is certain.
With 10p a share in cash and assuming diluted EPS of circa 5p puts the Group, which is still on a growth trajectory, on a cash adjusted PE of less than 9.
Whilst this news is disappointing I plan to retain my holding and perceive the Group as increasingly likely to be the subject of future M&A should current prices persist.
Hi Graham,
I enjoyed your introduction today.
I think nearly all the stocks you list have suffered bad trading news with the exception of Air Partner.
Air Partner had an accounting issue which has now been thoroughly investigated and appears contained.
Trading at Air Partner was going very well before this issue and it has been ok since. The shares now seem very good value to me with a large dividend in the promising sector of private aviation. They have cash in the bank, a PE of 9 and a forward div of 7%. Stockopedia likes it Q 92, V 80 and it qualifies for Greenblatt's magic formula!
I would buy more but already have a large stake.
Michael
drvodkaquickstep - you are not alone - Keith Ashworth-Lord, for whom I have some respect, holds over 19% of Driver (LON:DRV) in his Buffetology fund.
rmillaree - IMHO this is one of Stocko's big failings. They make their own adjustments to eps which often means that they are not comparable with the forecasts in the next column. This in turn gives false eps growth and peg figures in the top right box, in turn affecting screen results. WebFG/Sharecast show eps 6.10 to 9/18 with forecasts of 6.33 then 7.22. The warning that eps will be 'slightly below' last year suggests a 5% drop from forecast making the sp drop of 26% this morning looking like an over-reaction.
(The 6.1p figure is from the company where 'underlying' is defined as stated before the share-based payment costs, exceptional items and amortisation of intangible assets).
sharw
You commented...
" IMHO this is one of Stocko's big failings. They make their own adjustments to eps which often means that they are not comparable with the forecasts in the next column. This in turn gives false eps growth and peg figures in the top right box, in turn affecting screen results. "
It seems like its comparing apples amd pears.
Can I ask - do you have a workaround for this?
Regards
Driver (LON:DRV)
The stokopedia forecast numbers arent complete for current year (no profit figure available) - but they did show an expected increase in EPS from 3.84p per share 2018 to 6.3p per share 2019 and 7.2p 2020.
are they now advising EPS will be below last years 3.84p? - if this is the case is this not a huge miss ? in which case the shareprice reduction seems more than justified?
per RNS
the Board now anticipates full year underlying profits before taxation to be slightly below the 2017/18 result at approximately £3.5
As any readers of this investment forum and others such as ADVFN will be aware, I have been a firm supporter of Driver (LON:DRV) since early / mid 2017 when they refinanced and brought new management in. From the 40p placing in Feb 2017 the valuation of the business more than doubled within 18 months; topping out at circa 85p last October.
This morning's Trading Statement noting some deferred and delayed commissions in their Middle East and Asian operations has therefore, not been well received by the market with the valuation down 26% as I write.
Frustratingly, the Trading Update was in mid-February last year and investors can only assume that some of the delayed contracts were hoped by management to be secured prior to the Trading Update but sadly not.
The valuation of the business has in fact been under pressure since the Year End (Sep 2018) and some questions marks have been raised this morning on social media concerning share sales by Directors (or their wives) in November 2018 and earlier this month along with a circa 1% share sale that was printed last Friday.
The weakness in the share price, a reduced cash position and the above noted transactions pre-TS do raise some questions and I have written to management this morning to express my concerns.
All of this said, Driver (LON:DRV) remain a leading expert in their field, are profitable, now pay a divi and have a solid order book.
The market reaction this morning seems unwarranted but current macro issues and perceived nervous investor sentiment means such news will be punished accordingly. Driver are a Top 3 holding for me so not a good start to the week.
Just to mention that any of you attending the Mello2019 event on Thursday 16th and Friday 17th May can add a ticket to the Mello Trusts and Funds day on Wednesday 15th May for just a tenner Links for both are here...
http://melloevents.com/upcoming-event/
If buying a ticket for Mello2019 use the discount code Stocko40 to get 40% off and simply add your Investment Trusts one day for £10 (normal price £49) so a huge money saving tip.If just attending on the Wednesday then apply the discount Graham provided in his intro.
See you all there.
David
Northern Bear (LON:NTBR)
BIACS
Also, I'm not sure if we are supposed to read something into the fact that they specifically refer to "operating profit (prior to the impact of non-cash amortisation and transaction costs)" being in line with last year - i.e. are they hinting that there will be a different result in terms of other costs/amortisation/depreciation that will bring this below last year on a net basis? If so, why not tell us and explain this now rather than making indirect veiled noises. If not, why not say something less cryptic?!
I am 100% fine with regard to the ignoring of the amortisation / transaction costs when doing LFL comparison - practicably speaking the board aren't accountants so ignoring those adjustments makes sense and this treatment is 100% consistent with the previous years similar update when they said the following.
Per rns 2/2/19
The Board is delighted to announce that the Group's turnover and adjusted profit before income tax from continuing operations (stated prior to the impact of transaction costs and the amortisation of acquired intangibles, both associated with the acquisition of H Peel & Sons (Holdings) Limited announced in July 2017) are currently ahead of both management expectations and excellent prior year results.
Note it could be that there could be a material adjustment to the carrying value of the goodwill at some stage we simply do not know in that regard, i wouldn't expect the board to monitor that too closely in year - if there is a goodwill adjustments its kind of irrelevant from my perspective now as its simply the earnings of the group that matter - any goodwill adjustments shouldn't have any adverse cashflow impact.
Thanks for all the comments on Northern Bear (LON:NTBR). Agree with your POV on adjusted profits, rmillaree.
Cheers
G
Good morning Graham. As you follow the sector, I would be interested in your analysis on Ramsdens Holdings (LON:RFX), following their announcement about acquiring 18 shops last week. I have a small (1%) position in this and something in H & T (LON:HAT), but do not particularly like the growth in unsecured lending in at H & T (LON:HAT). Both look to be good value
Hi jonesj, thanks for the message. A quick note on Ramsdens Holdings (LON:RFX). I'm not a big fan of acquisitions in this arena except when stores are bought out of administration.
The deal by RFX was small so that reduces the overall risk. But if I was an RFX holder, I would have preferred an increase in the dividend.
I agree that RFX looks like good value here. I have a slight preference for HAT which has been extraordinarily disciplined when it comes to acquisitions.
Disc: long HAT
I'm interested in your thoughts on Quarto Inc (LON:QRT). Market cap £11m v net debt $60m.
Still think there's a decent business "60% annual recurring revenue through the Group's enduring backlist and innovative use of its rich IP catalogue" so hopefully they can pull through?
I'm long and wrong, but don't want to average down because of the leverage / distressed situation.
On the positive side, at least management don't claim that they have a "strong balance sheet" !!!
Hi Bruce. Quarto Inc (LON:QRT) looks nice at current levels - if they carry on doing what they are doing, without any more mess-ups! I don't know if they can do that but the risk:reward looks nice on my initial inspection ..... good luck!
Thanks Graham, particularly for highlighting the cashflow statement movements, net debt is reducing, but driven by less upfront spend on new books. Possibly that will impact revenue in future years.
In 3 years time it almost certainly won't be the same price... if things go right, but also if anything else goes wrong.
That said, I'm optimistic, the group is well within it's banking covenants, but I just can't average down into a situation like this.
Morning Graham!
Confident and positive TA this morning from Mountfield (LON:MOGP), You previously commented "I imagine that these shares could easily re-rate higher when people have digested the earnings that are likely to be achieved in full-year 2018 and possibly in 2019. On current trends, it's probably going to look very cheap in comparison to a £5 million market cap.While it may have individual merits, it's not for me simply because this is not a sector I want to get involved with".
The TA itself is not heavy with firm figures. Note that this comes after the recent announcement that it had secured £7m of orders "with the work on all to be undertaken during 2019.
So a good 2018 and a potentially very good 2019 - assuming they can deliver of course.
I for one will be topping up after an starter purchase after the 25 Jan £7m order announcement.
What's particularly pleasing is the comment stating that "Whilst much of the construction industry has been impacted by the unresolved Brexit negotiations, the Group has continued to experience buoyant demand for its services".
EDIT - looks like me and gregatr0n crossed on £MGOP!
I don't hold Mountfield (LON:MOGP) or pretend to know lots about them, but I wonder if the commentary is getting slightly ahead of itself...? If one eliminates all the glowing froth from the trading update then all that they are essentially saying is that they are confident (though not certain) that the full year numbers will be somewhat better than last year's. Considering that last year full year profit was up 95% and revenue up 35% then this year seems rather unexciting. Considering that at the halfway stage pretax profit was up 128% and revenue was up 56% then I am similarly unimpressed with the statement - in theory, it implies that H2 profit could be up a more moderate 24% and in fact H2 revenue could be flat!!! Perhaps that is enough to get excited about when the current PER is in single digits, I don't know. But it doesn't personally tempt me into investing... :-/
Statements exuding frothy words and few numbers increasingly don't wash with me... and perhaps Northern Bear (LON:NTBR) are a case in point - the group has traded "ahead of management expectations and in line with the prior year outstanding results"?!?!? I am a disappointed holder and in my mind the directors have very low expectations. Perhaps that is why the PER is so low :-(
Northern Bear (LON:NTBR)
Yes - todays wording is beyond confusing and explains the sharp drop this am. To be honest this company would be better placed giving a range of expectation at the start of the year and updating on that band in year rather than trying to use a range of superlatives that simply confuse. I guess the exceptional h1 and outstanding prior year means that we should not have expected a decent h2 even though they advised h2 outlook was "very good" - presumably very good is is not as good as the previous years "outstanding" - or the more recent "trading well" is really the clue that they have lost the edge they had in the first half. Scratches head.
The saving grace here is that the pe of under 6.5 means that close to in line with last year isn't a disaster.
Agreed. sounds like we may end up with a slightly lower than last year result based on this announcement (which, as you say, provided its a near miss is not a disaster given the lowly rating here), but it's hard to tell with certainty.
Also, I'm not sure if we are supposed to read something into the fact that they specifically refer to "operating profit (prior to the impact of non-cash amortisation and transaction costs)" being in line with last year - i.e. are they hinting that there will be a different result in terms of other costs/amortisation/depreciation that will bring this below last year on a net basis? If so, why not tell us and explain this now rather than making indirect veiled noises. If not, why not say something less cryptic?!
I hold and was hoping for something a little better but will hang on in there for next year.
good trading update today from Mountfield (LON:MOGP) . Record revenue and order book. A pity no update on cash position. Graham you have looked at this one before - any thoughts?
My morning smallcap tweet: ME & Asia screws Driver
Charter Court Financial Services (LON:CCFS), Northern Bear (LON:NTBR), Quarto Inc (LON:QRT), IDE Group (LON:IDE), Driver (LON:DRV)
Charter Court Financial Services (CCFS) in advanced merger discussions with OneSavings Bank with 0.8253 new OSB shares for each Charter Court share. Charter Court shareholders would hold ~45% of the combined group.
Northern Bear (NTBR) first 10 months of FY ahead of mgmt expectations. Guides op profit broadly flat YoY. No forecasts. Says previous year was 'outstanding'. I hoped very mild winter would have boosted H2 YoY but no. I hold.
Quarto (QRT) mixed language in FY results. Rev down 2%, adj EPS 23.0c (17.8c). Has cut no of imprints and cut overheads, expects the ongoing soft market conditions to continue. CEO is "very passionate about returning the Group to full health". But is he 110% passionate?
IDE Group (IDE) H2 trading performance improved after previously announced cost cuts. Has settled outsourced service dispute, saving c.£3m over 3 years. Group now expects significantly reduced adj EBITDA loss compared to H1.
Driver Group (DRV) Guides U/L FY pretax ~£3.5m which is below previous year. Blames weak Middle East and south-east Asian markets.