Small Cap Value Report (Mon 15 Jan 2018) - CLLN, SPSY, CAR, CMCL, JDG, WJG, SAL

Good morning folks,
Looks like it has been another interesting morning for updates.
I'm looking at the following:
- Carillion (LON:CLLN) (won't spend too long on this, as it's game over)
- Spectra Systems (LON:SPSY)
- Carclo (LON:CAR)
- Caledonia Mining (LON:CMCL)
- Judges Scientific (LON:JDG)
- Watkin Jones (LON:WJG)
- Spaceandpeople (LON:SAL)
This list is provisional. I'll see how things are going as the morning/afternoon progresses!
Also, Paul has written an article discussing how MiFID II has affected him. It's available here:
Cheers!
Graham
Carillion (LON:CLLN)
- Share price: Suspended.
Compulsory Liquidation of Carillion
Putting this here as a full stop for the story, which has reached its conclusion as far as shareholders in the construction support services group are concerned. It had about £900 million in financial debt through 2017, plus a £700 million pension deficit.
Late on Friday evening, an RNS informed us that the company was "in constructive dialogue in relation to additional short term financing while the longer term discussions are continuing".
It was completely out of cash, and needed new funds just to keep the lights on.
The lenders weren't willing to provide such funds, and the gap was too large to be plugged by fresh equity. So as of this morning, the shares are suspended.
Honestly, I'm a little surprised that the end came as abruptly as it did. It looked like there was going to be a conversion from debt to equity, along with a fundraising, so that existing shareholders were reduced to a token percentage holding.
Instead, existing shareholders will be reduced to zero, and the company will cease to exist in its current form. Employees, creditors and customers (including the Government) will need to figure out what happens next for them. The Construction Enquirer (external link) reports that work has temporarily stopped on "scores" of Carillion's former projects.
Pensioners will move to the Pension Protection Fund, meanwhile, which looks like it will be able to take care of most of their entitlements, particularly for those who have already retired.
From an investment point of view, maybe we should take note of the perils of investing in the support services sector, where other high-profile companies have also run into difficulties in recent years (Capita (LON:CPI) and Serco (LON:SRP) spring to mind). On a smaller scale, most SCVR readers will be aware of Lakehouse (LON:LAKE).
The economics of these companies are increasingly unappealing to me: long, uncertain B2B contracts with extremely price-sensitive customers and few sources of long-term competitive advantage. Maybe we are better off avoiding them altogether?
For those who are still interested in the sector, Carillion's joint venture partner Kier (LON:KIE) has seen its shares nudge higher this morning, and trades on less than 9x earnings.
Spectra Systems (LON:SPSY)
- Share price: 97p (+19%)
- No. of share: 45.3 million
- Market cap: £44 million
Licensing Agreement and Supply Agreement
This is a mysterious (to me), US-based security company, with expertise in banknotes.
Today's news concerns the extension of a licensing agreement to one of Spectra's technologies in perpetuity. $11.2 million in royalty payments will be received over the next five years. There is also a new material supply agreement with this licensee.
Royalty payments for intellectual property are the best source of cash - no further investment is required to generate them!
The next paragraph helps to explain today's share price increase:
It is estimated... that the combined licence and supplied material sales will generate a contribution per annum from this product through 2023 which is approximately 2.7 times that of the current agreement, based on the minimum purchase requirements in that agreement and experienced in certain recent years.
If I'm reading this correctly, the new agreement does not have minimum purchase requirements. But based on the minimum purchase requirements in the previous agreement, and trading in recent years, Spectra is expecting that revenues are set to increase 2.7x versus the previous agreement.
As such, results for the current year will significantly exceed market expectations.
This share has come to life in the past few months. Last October, it told us that 2017 would significantly exceed market expectations. And now we find that 2018 is going to do the same.
The company had $9.5 million in cash as of last June, so the balance sheet is super-healthy and the shares are cheaper on an enterprise value basis than they first appear.
Note that the license-related income will only last for the next five years, and then the customer will have the perpetual right to use Spectra's technology. This means we can't attach an earnings multiple to this source of income. We can only value it at $11 million, discounted for the time delay in receiving it.
The high-margin supply of materials to the customer, on the other hand, should hopefully continue. Note that 2017's superb result was due to one of the underlying central bank customers redesigning its notes, producing exceptional demand for Spectra's materials for the period.
The market cap in dollars is $60 million. If I cut a few corners and simply deduct last June's cash balance along with the anticipated royalty income, we are left with a $39 million valuation for the rest of the company.
It's an intriguing situation. The company earned $2.5 million in operating profit in H1 last year, which ordinarily would make a sub-$40 million valuation look rather cheap. It's entirely possible that the shares are still a bargain at this level.
Personally, I'm not entirely sold on the sustainability of earnings yet, so I'll have to put this in the "too difficult" basket for now. Central bank demand, and the banknote industry in generally, is highly unpredictable (just ask De La Rue (LON:DLAR) ).
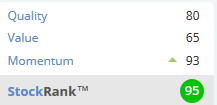
It's still one of the more interesting stocks to have popped up over the last few months. The StockRank is excellent, which is another good reason to investigate it. I don't think any software will be able to differentiate between Spectra's temporary royalty income, versus ongoing material-related sales, so do watch out for that.
Carclo (LON:CAR)
- Share price: 79p (-37%)
- No. of shares: 73 million
- Market cap: £58 million
Trading Update and Board Changes
This is a supplier of technical plastics products and specialist LED lights. Paul briefly covered it in November.
Checking its historic results, it had a great track record of profitability until 2015, when the results were ruined by £31 million in exceptional items, related to the closure of certain activities ("conductive inkjet technology") which it described as non-core.
Today's results are an example of a H2 results weighting failing to materialise in full, and as such performance for the current year will be significantly lower than planned. Profit expectations for 2018/2019 are also affected.
In both the Technical Plastics and the LED divisions, large contracts were delayed. Additionally, an important customer hasn't increased its orders yet despite previously indicating that it would have "a strong second half".
Board Changes - the FD will leave in March after 14 years. As I said with Quartix Holdings (LON:QTX), it's not a red flag for me when somebody leaves after a long stint such as this. The Chairman is also leaving, in July, after 12 years as an NED.
Some people like to keep an eye out for FD movements, and it's worth mentioning that Carclo (LON:CAR) has significant debts: £30 million in net debt as of September, which is forecast to rise by another few million through to this March. The bank requires Net Debt/EBITDA of no more than 2.75x. Carclo reiterates today that it "continues to operate well within its banking covenants".
While the FD leaving is not a red flag on its own, the timing is perhaps unfortunate. It would be a bit more reassuring for shareholders if he had left when news was benign.
Conclusion - the risk is somewhat elevated here, given the debt load which is now more than 50% of the market cap. The enterprise value is in the region of £90 million.
That said, the underlying businesses sound highly investable. The plastics business produces moulded components for medical/electronics products, and the LED business makes exterior lights for supercars.
I'd like to spend some more time understanding exactly how niche these businesses are. Performance over the past few years suggests that the company does enjoy strong pricing power.
Brokers have reduced adjusted PBT forecasts to £9 million (2018) and £11 million (2019). If a multiple of say 11x-12x PBT was justified, then the shares could be worth a purchase. Given the apparent concentration of the company's customer base. I probably couldn't justify an above-average earnings multiple here. 10x PBT might be about right.
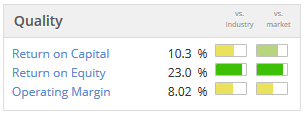
The quality stats are ok. I'm guessing the shares are priced about right for now.
Caledonia Mining (LON:CMCL)
- Share price: 555p (+3%)
- No. of shares: 10.6 million
- Market cap: £59 million
Record Quarterly and Annual Gold Production
We don't typically cover resources here. I just keep a few of them on my watchlist, and Caledonia is one of them.
The important features of Caledonia are:
- 49% ownership of a gold mine in Zimbabwe, which has a new business-friendly government.
- Virtually no share issuance for 10 years.
- Dividends since 2012, now paid quarterly.
- Good track record of meeting forecasts.
Today's update shows 16,400 ounces produced in Q4, a new quarterly record helping to make 2017 a record year. Total 2017 production was marginally above the forecast production range of 54k-56k ounces. The 2018 forecast range is 55k-59k ounces. The plan is to reach 80k ounces by 2021.
I use balance sheets to anchor my valuation of resources stocks; Caledonia had shareholders' equity of $58 million (£42 million) as of last June. Given the company's track record of profitability, the favourable gold price environment, and political developments in Zimbabwe, I would guess that the recent share price increase, and the current valuation, still leave an opportunity for new investors here.
Judges Scientific (LON:JDG)
- Share price: 2200p (+6%)
- No. of shares: 6.1 million
- Market cap: £134 million
Trading Update and Notice of Results
This is a scientific instruments group. It buys and builds small, niche businesses, and then lets them run independently of each other and the parent.
Management must be very disciplined, as the strategy has been executed with only moderate dilution to shareholders over the years.
Today's update is ahead of market expectations, thanks to strong orders and an FX tailwind. According to Stockopedia, the expectations were for normalised 2017 EPS of 110p, rising to 124p in 2018. Those are a few percentage points lower compared to forecasts I can see elsewhere. Assuming that 2018 will be at the higher end of expectations, the 2018 PE ratio now appears around 16.5x.
Business is order-driven and can be a bit lumpy, so the order book is a good leading indicator of performance. It finished 2017 at 14.9 weeks of sales, an improvement on last year.
It's a short, neat update which has pushed the shares up in the direction of their all-time highs around £24, originally achieved in 2013 before some of the subsidiaries ran into difficulties.
I've been aware of Judges Scientific (LON:JDG) since it was covered on expectingvalue.com (external link) in 2015. If the management team do continue to compound value for many years, then your initial entry point doesn't matter so much - it will be virtually impossible to do badly with this share.
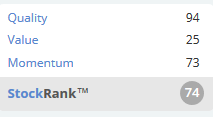
Stockopedia computers agree that it's a high-quality outfit. Value isn't quite so compelling at this point. As Ive hinted at, though, it's probably more worthwhile to think about the position in five or ten years, rather than the exact multiple where you buy in.
Watkin Jones (LON:WJG)
- Share price: 197p (-13%)
- No. of shares: 255 million
- Market cap: £504 million
This is a developer with a particular focus on student accommodation.
I've been urging caution with respect to its shares, and thus far haven't called it particularly well. I reckoned the shares were fairly valued at c. 120p, and overvalued in excess of 180p.
Today's results are in line with expectations.
3,300 beds were delivered on time for the 2017/2018 academic year, as planned.
9,000 student beds are in the pipeline, with 3,400 next year (2018/2019), and 2,700 the year after that (2019/2020). That's an 800-bed reduction for 2019/2020, compared to the estimate which I had previously noted.
The company is also involved with "build-to-rent" residential accommodation, and the management of student accommodation, and these activities appear to be doing well. It has five development sites in the build to rent sector, and is in negotiations with respect to other sites.
CEO Succession - the CEO is the ninth generation of the founding family to manage the company, and he will be moving on in due course. A formal search process begins to find his successor.
The reason given is as follows:
For personal reasons, Mark is not able to undertake a full time executive role over the longer term and he and the Board believe that it is in the Group's best interests to recruit a successor.
The Board will hope to keep him on as an NED. But as with any CEO change, it will be a distraction and a threat to continuity.
From a technical point of view, I wonder how much appetite the family still has to hold on to the shares? There was a very significant share sale at 145p last year, following the 2016 IPO, and it looks to me as if the company still hold 25-30% of the shares. This doesn't change the value of the business, but it potentially means that there will be further supply of shares to the market as a whole.
Having scanned through the results, it looks like the CEO news is responsible for the share price decline today. The outlook statement is entirely confident.
My opinion - I'm happy to admit that I may be unduly sceptical, but I'm still cautious on valuation here.
In student beds, Watkin Jones (LON:WJG) has forward-sold all ten of its developments for completion in the current financial year.
That gives it great visibility and reduces the capital which the company itself (i.e. its shareholders) needs to deploy. On the other hand, we need to remember that there are only ten developments in play this year. The company has executed very well in the past, but the risk of just a handful of projects going wrong is a major risk for shareholders.
And the annual output of beds doesn't look like its going to grow very much from here. So we can't rely on risk reduction via diversification and increased output.
While Watkin Jones (LON:WJG) sees growth opportunities "across all parts of the Group", it sees "greatest upside potential" in build to rent. As I mentioned above, it currently has five development sites in this space.
My concern around the valuation is not because I think the company is likely to execute badly. The track record says that the company is likely to execute very well.
My concern is that the stock market is attaching a significant earnings multiple to earnings which have arisen from success in a very modest number of transactions, and will only be repeated if the limited range of transactions which are in the works over the next few years also turn out to be successful.
Spaceandpeople (LON:SAL)
- Share price: 36.5p (+9%)
- No. of shares: 19.5 million
- Market cap: £7 million
Pre-Close Trading Update and Notice of Results
This is a media company which commercialises high-footfall locations. We regularly covered it before it fell below our £10 million threshold. I'm mentioning it here for completeness.
Revenue is line with expectations. Thanks to a favourable mix, profit before tax will be ahead of expectations at £1.2 million.
The company is now debt-free, wants to pay dividends again, and finished the year with adjusted net cash of £1.9 million. It's a great recovery story, albeit one which is not yet reflected in the share price.
On an ex-cash basis, the valuation is now about 5x PBT. That's after the shares approximately doubled from their lows last year.
Is it still good value here? Probably, yes. But we have to balance that against the company's small size and the illiquidity of the stock. It is cheap because of the extra risk you take when you buy a very small company which has disappointed investors in recent memory.
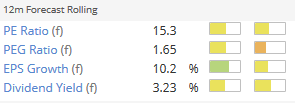
The StockRank is huge, thanks to a perfect ValueRank. If you just want old-fashioned value, and don't care about liquidity, this is worth a look.
I'm out of time for today, thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Re. Taptica International (LON:TAP) At the time of this note, you can pick up TAP shares @450 , the placing price for institutions, roughly 10% discount.
Yes, I agree that the placing looks as if it was primarily for the directors to cash in. But Tal's total holding comes down from 11m to 9.4m shares, and Smart & Simple 's total holding comes down from 11m to 5m shares. So Tal still has significant skin in the game.
The extra cash could also be earmarked for further acquisitions.
IMO the risk/ reward ratio @450 a share is favourable. I picked up a good chunk this morning.
I had a small holding, sold out this morning. I'm not happy the directors are selling loads, if they are selling then so am I. Will watch from the sidelines.
Yes the ceo of Carclo has to be on notice. The context of the Carclo warning is appalling and quite frankly amateurish.Get bad news out ASAP is the best policy.
Re : Carclo (LON:CAR)
Sorry Graham, but I think that rather misses the point - the timing is very appropriate imho. The management team's credibility is badly damaged as far as I am concerned.
The November statement seemed 'optimistic' - we badly missed H1 but we will do so well in H2 that we'll still be on track. Oh wait what they actually said was "Solid first half trading overall with, as previously highlighted, an outperformance by LED Technologies offsetting a weaker performance by Technical Plastics" - except that the outperformance patently did not offset the weakness, resulting in the H1 miss.
Two months later the super H2 has proven to be a mirage. I really think there is a good business in here, but they just seem to "accident prone", so perhaps a refresh of the entire management team would be no bad thing.
Hi Paul & Graham, Late RNS out this evening from Taptica Taptica International (LON:TAP) - I hate those out of hours late RNS's, especially the Friday night ones.
http://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/TAP/13497042.html
Would you care to give your thoughts - it seems like more dilution and an SP fall to me?
I hold a little Taptica International (LON:TAP) and don't have a particular issue with the RNS - in the end it will depend how wisely they use the funds raised for further acquisitions, but I agree it likely won't help the SP short term depending on the price they get in the book build.
Regards the timing, I would prefer all RNS's like this were issued after 16.30 rather than 7.00 the next morning as it gives us more time to absorb them, but perhaps not on Fridays. Maybe the book build will be done by the morning.
Re Taptica International (LON:TAP). Raise/ book builds are announced after hours if it is expected to be completed overnight. this prevents the need to suspend the share which would most likely happened if it had been announced in the morning.
RNS that Taptica International (LON:TAP) have completed their placement at £450p (vs. Share price at close of 495p) per share overnight. Seems they placed all the shares being sold by existing shareholders and just under (4.85m) of the 5,000,000 new shares being offered.
This company was on my watch list to buy but I think I’ll hold off for now. Seems the directors are taking a fair amount of cash out of the company and not buying into the placement; demand for the new shares was at quite a big discount and even then insufficient to fully clear the market for the new shares to be issued that they had indicated in last night’s RNS. I’m slightly sceptical the placement was more about the directors creating a smokescreen to take cash out than raise funds for investment/debt pay down that the company needs.
Gus.
———————
Taptica International Ltd
("Taptica" or the "Company")
Closing of conditional Placing to raise £38.2 million
Taptica (AIM: TAP), a global end-to-end mobile advertising platform, today announces that further to the announcement made on 15 January 2018 regarding the proposed placing of new shares of NIS 0.01 each in the capital of the Company ("Ordinary Shares"), the Company has conditionally placed 4,850,000 new Ordinary Shares ("Issue Shares") at a price of 450 pence per Ordinary Share, raising gross proceeds of approximately £21.8 million ($30 million) through an oversubscribed placing (the "Placing"). The Issue Shares represent approximately 7.73% of the Company's current issued Ordinary Share capital (excluding dormant shares).
In addition, MTD PTE Ltd, a company controlled by Hagai Tal, CEO and Director of Taptica, and held in trust (the "Selling Shareholder"), and Smart and Simple Ltd, a company controlled by Ehud Levy and held in trust ("Smart & Simple"), have informed the Company that they have successfully placed 1,650,000 and 2,000,000 existing ordinary shares in Taptica respectively (together, the "Sale Shares") at a price of 450 pence per share. The Company will not receive any proceeds from the sale of the Sale Shares by the Selling Shareholder or by Smart & Simple.
Completion of the Placing and sales is expected to occur on 22 January 2018, subject to admission of the Issue Shares to trading on AIM ("Admission").
finnCap Ltd ("finnCap") and Joh. Berenberg, Gossler & Co KG London Branch ("Berenberg") acted as joint bookrunners to the Company and the Selling Shareholder. Berenberg acted as sole bookrunner to Smart & Simple.
Following completion of the Placing and the sales, the Selling Shareholder will hold 8,903,125 shares in the Company. Mr Tal, through his direct and indirect holdings, will be the beneficial owner of 9,375,509 ordinary shares representing 13.88% of the enlarged issued share capital of the Company. Mr Tal has agreed not to sell any further ordinary shares for a period of one year after completion of the Placing.
Following completion of the Placing and the sales, Smart & Simple will hold 4,517,625 shares in the Company. Mr Levy, the ultimate beneficial owner of Smart & Simple, will be the beneficial owner of 4,990,009 ordinary shares representing 7.39% of the enlarged issued share capital of the Company. Smart & Simple has agreed not to sell any further ordinary shares for a period of 90 days after completion of the Placing.
Hagai Tal, CEO of Taptica, commented:
"With a broader footprint across the globe and consumer mobile usage and adoption rising, we anticipate our strategy of on-boarding local advertisers onto global platforms to result in continued growth. The funds raised will reduce the level of debt under the Company's existing debt facility, which we believe will better position the Company to capitalise on near-term M&A opportunities. We thank our existing shareholders and welcome new investors to our share register and look forward to updating them on our progress."
Another Great British invention/technology.......going......going........gone!
Manchester University was the place where graphene technology was developed, a world leader, Cambridge University has also moved graphene development forward , now Versarian are "giving it away" to the Chinese.
Versarien plc - Planned Chinese graphene manufacturing facility
" Versarien will provide its intellectual property (IP) on a licensed basis together with production know how"
"It is the Company's intention to form a wholly owned Hong Kong company which will become one of the joint venture partners, whilst ensuring the strongest protection of its IP"
Anyone believe the Chinese won't nick the technology?
Re Carillion (LON:CLLN)
Hopefully the current activity will save the individual parts of this important but poorly run company , the UK cannot afford to lose the skills existing throughout the firm. Fortunately I was alerted to the dire situation 18 months ago via a financial magazine report; which raises the question ' why, as it was so obvious, was it allowed to blunder on for so long' ; as It played such an important role in our infrastructure.
Thanks guys - appreciate your replies on Attraqt.
I have some thoughts regarding ATTRAQT (LON:ATQT), unfortunately they are not positive.
After the company took over Fredhopper, it gave guidance of £14.7M in combined revenue for the full year of 2017. Today's top line number for the period is in line with the previous warning of a ~10% decline in that revised guidance (i.e. £13.5M). Given that the Attraqt core business did £3.6M in revenue for 2016, and Fredhopper did £11.1M (remember that Attraqt have only owned this business for 10 months of that year, so recognised revenue is more like £9.3M for the same period). Combining those two numbers gives us £12.9M that the combined Attraqt entity would have done in 2016 on a pro forma basis. If these numbers are correct, then the revenue number for 2017 grew by less than 5%, which is much less than 22% growth that the company did in 2016.
Paul has suggested that there is a problem with competition here, and going by the numbers and the resignation of the founder, that is my thought as well. When you look at the 2017 interim which states the company had an exit run-rate of £16.5M (based on June revenues of £1.375M) and H1 revenue of £5.5M, and you consider FY revenue is £13.5M, you can extrapolate that the month-on-month growth in the run rate has stopped, and actually looks like it's in decline. June run rate for revenue was £1.375M - if the company had 0% growth since June, they should have done H2 revenue of £8.25M. Instead revenue was only £8M, which says to me that the revenue run rate provided in ther interim was nonsense. Indeed, my extrapolated H2 numbers would back up Paul's point that the business might actually be shrinking at this stage, or at very least not growing.
Now that the founder Andre Brown is down to a 3% stake in the business and given the challenges here, it's not at all surprising that Nick Habgood with his 18% stake in the business has taken the reigns here. The only positive I can think of here is that Habgood is savvy in the tech sphere, so with him in charge, he might have contacts in the industry that can buy out Attraqt. It's clear they have a good product, but I am wondering would it be more useful as a bolt on acquisition to a larger player in the e-commerce world than as an independent player?
While I am at it, one more point. At the last interim (June 30th 2017), cash was at £2.7M. As of September 30th, the company reported £2.3M of cash. As of January 12th, the cash position was described as being over £2M. This isn't good for a company that is no longer growing, or even worse, showing negative growth.
The ATTRAQT (LON:ATQT) RNS today is an interesting non-statement. Avoided saying much except indicating revenue. My interpretation is that AB was pushed; the October update was with a new FD & my guess is that a long hard look has been taken at future profitability and decisions have been taken about change. Small number of very large holders now who will be looking to salvage what they can - mostly bought in much higher. Probably no bad thing that management will change, just as it was no bad thing that Wagner lost his effective control. Can't say it looks like a good investment though, unless you know what the prospects actually are.
Hi Graham,
Thanks for your thoughts on Carclo (LON:CAR) . I've also checked it out, and jotted down the following brief notes, taken mainly from the last results, interims to 09/2017, and of course from today's statement, plus a broker note that I got hold of this morning;
So on this basis, I declined to catch the falling knife this morning - mainly as I don't like the combination of heavy debt/pension deficit, and declining performance. That's a pity actually, as it's bounced very strongly from earlier lows this morning of 67p, to 83p now. That would have been a nice little trade, but never mind - these things are impossible to predict, because it's down to decision-making of existing shareholders. It would only take one big holder to get cold feet & dump aggressively in the market, and the price would have carried on falling.
Margins in the supercar lights business look excellent - maybe this business would be worth more on a standalone basis?
Best wishes, Paul.
Attraqt anyone (LON:ATQT) Founder and CEO stepping and trading in line with expectations.
I think it was called "uninvestable" by Graham or Paul when it warned last October.
Hmmm, I hold and they could be right. But, maybe, just maybe, it is now simply too cheap, particularly bearing in mind it is focused on site search for online retail websites.....
Hi deltrotter,
There is a problem with ATTRAQT (LON:ATQT) . Its original software is a plugin which helps improve eCommerce websites. It improves the customer search results, and hence increases the conversion rate of people browsing to actually buying.
However, the problem now is that a lot of eCommerce companies which have built up their own bespoke systems are now moving to third party software with all-singing-and-dancing features. Thus making ATQT's plugin redundant.
So the risk is that ATQT could now almost be seen as being in run-off, with customers gradually melting away as they upgrade their systems to newer ones which don't need ATQT any more.
For that reason, and that ATQT has never achieved profitability, I think it looks a very weak investing proposition.
Regards, Paul.
For those who are still interested in the sector, Carillion's joint venture partner Kier (LON:KIE) has seen its shares nudge higher this morning, and trades on less than 9x earnings.
Hi Graham,
ON Kier (LON:KIE) I'd say that rating is about right for a low quality company with margins < 2%. I'm with you on ignoring this sector completely - it often looks very cheap if you only look at the PER but the operational gearing and nature of the business means the risks of a blow up are higher than may be perceived by the valuation alone. Someone else mentioned Amey but it was Balfour Beatty's near death experience a couple of years ago that first came to my mind.
I think the main thing to look for now is collateral damage from Carillion (LON:CLLN). I see that Galliford Try (LON:GFRD) and Balfour Beatty (LON:BBY) are both lower and have admitted they will have to complete the work and provide extra funding for a joint venture road project in Aberdeen. Also it seems Speedy Hire (LON:SDY) has been effected as it has an ongoing equipment supply contract with Carillion.
All the best, Si
Fellow Burford Capital (LON:BUR) holders will be interested in today’s Times report that litigation funder Vannin Capital intends to launch an IPO in London.
Competition for Burford Capital (LON:BUR) and a sign of the growing maturity of the sector they have created.
https://www.thetimes.co.uk/article/lawsuit-funder-vannin-capital-seeks-public-backing-9xrbn97sx
Good luck to them. Burford are still the big hitters by a long way with lots of ongoing cases and growing like crazy. Burford were flat for 6 years from 2010 -2016.
With the cloak and dagger nature of law theres no way to know what your investing in with Vannin Capital or BUR.
It could go up and then flatline for years like BUR, who knows. I wish legislation would allow the full disclosure of litigation funders name in cases at least you could work out the win ratio.
http://www.leadersleague.com/en/rankings/2017-global-ranking-of-the-top-litigation-funders
Burford results in March , expect another bumper year for 2016 and hopefully same of the same..
@Redrichmond
Bear in mind that the majority of disputes are settled before they get to court, so even with disclosure at the court stage a lot of the data would remain confidential.
Regarding Spaceandpeople (LON:SAL)
I seem to remember from a previous results statement from last year that their Germany contracts are expiring end of January, and that if they were unable to reach a renewal, then that is the bulk of the Germany business gone and they were planning to shut down in Germany.
I haven't seen any updates as to those German contract negotiations yet, and end of January is coming up.
It seems it could be both good and bad news. Good news because the German contracts were not very profitable. Bad news because I think it was a big share of revenues (and overheads). So if there is a wind down, could be further temporary losses and maybe some impairments? Who knows.
For that reason I'm sitting on the sidelines till this issue becomes clear.
Joint Venture with Carillion plc
Galliford Try (LON:GFRD) Galliford Try plc (the "Group") notes the announcement by Carillion plc this morning. The Group is in joint venture with Carillion and Balfour Beatty on the £550 million Aberdeen Western Peripheral Route contract. The terms of the contract are such that the remaining joint venture members, Balfour Beatty and Galliford Try, are obliged to complete the contract. Our current estimate of the additional cash contribution outstanding from Carillion to complete the project is £60-80 million, of which any shortfall will be funded equally between the joint venture members.
Re Carillion (LON:CLLN), this question may have been covered before but I can't remember.
What is the position with a short sell when the company folds.
Thanks
Hi there, re: Carillion (LON:CLLN).
I think if you are short when shares are suspended, the position is marked to full value and you have to hold it until your broker deems that the shares are proven worthless. So you have to wait until the long positions are deemed worthless, too. This can take several months, it depends on your broker and the specifics of the company you are short. Sometimes there is a payout to shareholders, after all.
At least, this is how my broker is supposed to deal with it.
In the case of Carillion (LON:CLLN), PWC have already stated that there is no prospect of any return to shareholders, so that should simplify things.
https://www.pwc.co.uk/services/business-recovery/administrations/carillion.html
Anybody have any thoughts on WEY (I have a very small holding ) seems to be falling since the presentation last week the general feedback is that people were not convinced with the market strategy ?
I'm wondering if Wey Education (LON:WEY) (and Sosandar (LON:SOS) a little bit too) are suffering due to market makers having recently artificially inflated the share prices on small buying after "tipping" (either here - even though this is a DYOR commentary-only site - or elsewhere).
Re Carillion (LON:CLLN), this in my mind is exactly like AMEY all over again... which I lost all of my small investment on; happy to have not made the same mistake again.
tony,
Re: Wey Education (LON:WEY) , there has been a lot of positive newsflow and a large share price rise in the past few months, all culminating last week's presentation. This will have attracted momentum investors and, as you say, reports back from the presentation weren't particularly positive.
What is there to drive the share price now / look forward to in the short term? Based on last year the next news will be interims in May. Although we can hope for a update on acquisition integration and new enquiries before then, the timing of the academic year may mean there isn't much to say.
Negative factors in my mind are:
* Relatively new to AIM - some kind of hiccup seems quite likely.
* Recently raised lots of money at 22p
* Management sitting on large profits and may wish to diversify financially
* Forecast PE of 40 assuming a massive rise in profits.
* Likely considerable uncertainty over forecast profits (this is also a positive)
Overall, this is a share I want to own much more of, but at this time it looks too expensive and risky even after the falls.
Further RE: Carillion from PwC:
https://www.pwc.co.uk/services/business-recovery/administrations/project-rome.html
A brief explanation of a compulsory liquidation and the roles of the Official Receiver and special managers will appear here shortly. In particular, it explains that a special manager is an officer of the court with his/her powers and functions defined by the court.
This website will be regularly updated to provide more information as it becomes available.
The Official Receiver’s priority is to ensure the continuity of public services while securing the best outcome for creditors. Unless told otherwise, all employees, agents and subcontractors are being asked to continue to work as normal and they will be paid for the work they do during the liquidations.
Shareholders
Unfortunately, as a result of the liquidation appointments, there is no prospect of any return to shareholders.
Graham - Camtab has requested Carclo (LON:CAR). Perhaps you could link that with Coral Products (LON:CRU) who issued a warning on Friday afternoon - discussed at the end of your Friday thread. In both cases the previous outlook was quite upbeat. What lessons can be learned from these?
Another Spectra Systems (LON:SPSY) please. Accouncements seem transformational, but very little public info. Have any of the Stocko community done any research that goes beyond a Goggle search? Ian
Graham, I would be interested in your thoughts on Carclo. They have become a serial underperformer despite having an interesting range of products. Op Margin isn't great which is a measure I use a lot, suggesting not much defence against the dark arts. But price has fallen to such an extent I wonder if it isn't one to put away in ones back pocket for the longer term. Balance Sheet doesn't seem too bad so doesn't appear to be going bust? Any thoughts appreciated.
Just a thought (that I had a while ago) about Spectra systems - it seems to me that their technology would be ideal for marking disposable packaging, including plastic bottles, coffee cups, fast food containers etc in order to operate a deposit system. It is very secure [1] and cheap to produce / scan so you could have quite high deposits (maybe £1 for a bottle or cup) without fear of fraud.
[1] Or is it? It is impossible to completely trust something where the details are secret.
Spectra Systems (LON:SPSY) issued a rns in October I think regarding if I recall correctly licensing their technology for
K-cup coffee type portions to be used in machines.
Happy holder at present but the shares are extremely illiquid so waiting for the 2017 preliminaries which should push the price up again. Be interesting to see the actual profits made as all the talk is of revenues.
Does anyone know a source of FY17 and FY18 forecasts
Steve’s Cups, re Spectra Systems (LON:SPSY), I understand from hearing the views of one of the larger investors in the company that what most excites them is the commercialisation of “Trubrand” technology as first highlighted in an RNS in July 2017. A couple of extracts:
“...approval for the use of Spectra's TruBrand(TM) materials on tobacco products sold in China has been granted. The approval was issued by The Tobacco Standardization Research Center (CTSRC) in Beijing to one of Spectra System's potential customers. This potential customer had applied for the approval, and remains interested in using TruBrand(TM) materials on their products....”
“...This approval of Spectra System's TruBrand(TM) materials should open the way for production testing and commercialization of this breakthrough smartphone technology....”
“...Assuming this approval is granted to other applicants, which the directors believe is highly likely, then other manufacturers of tobacco products in the People's Republic of China will also be able to test and potentially commercialize the technology. Further updates will be provided, as appropriate...”
Clearly nothing has emerged since then but I assume getting deals done of this nature takes time.
Together with the coffee lids technology it seems there are several strands to SPSY technology apart from banknotes.
In addition, the company has committed to a substantial dividend annually so there is good yield (subject to USA withholding tax).
It does seem that the CEO, Dr Nabil Lawandy, is the brains of the outfit and much depends on this man. That is often true of small tech outfits though.
Disclosure, I hold a good few of these in my ISA.
Graham,
Any comment on Non-Standard Finance (LON:NSF) - Pre-closing trading update. Non-Standard Finance (LON:NSF) confirmed that the business continued to grow rapidly through key Christmas lending period with impairment under control and falling. Reads very well to me and I cannot understand why it is not better rated vs peers like Morses Club (LON:MCL) on Stockopedia. Rapid growth AND good margin to be expected.
Surely the discount in rating vs other non-standard lenders should disappear now all 3 of NSF businesses are established in house and delivering rapid organic, profitable growth with impairment falling and process improvements coming through !!
* Expansion of EverydayLoans branch network appears to be accelerating (towards profitable maturity in 2020 ?) with loans +21% and 12 new branches in 2017; plus now 12 new branches promised in 2018 as well.
* Guarantor loans up +35% with integration of George Banco with TrustTwo clearly going well - record ever lending in both Nov & Dec
* Loans@Home (Home Credit Collection) up +53% vs LY with quality (ie not in arrears customers up to 64% of total as 442 agents (mostly ex Provident Financial (LON:PFG) ie Provident) added
I think maybe some extra short term investment costs to support growth in 2018 but once these mature, medium term should be very profitable. I now expect 2019 forecasts will be a huge step up and of course the group moving into profit this year
A very happy holder, considering buying more ahead of main March statement. What am I missing?
I agree and as a holder of Non-Standard Finance (LON:NSF) was somewhat surprised at the shares falling 4% this morning.
This company was set up by the chap who ran Provident Financial (LON:PFG) for 20 years and under him their share's went up 1400%. All Provy's woes set in well after he had departed.
Peel Hunt and Liberum have just issued buy recs at 84 and 95p and at 73p I am considering topping up.
Surprised no interest in VRS.
tads,
Do tell, why should we be interested in Versarien (LON:VRS) ? Some kind of announcement? If so, perhaps you could summarise it and maybe give us your analysis? Do you think that the share price has under / overreacted / it is a buy / it is a sell, and more importantly: why?
RNS this am. NR....”second industrial revolution “ on Twitter. I hold and will add on any weakness.
Morning All!
Carillion (LON:CLLN) has gone bust - forced liquidation into the hands of the Official Receiver, the RNS says. I'm not sure why it was done this way, instead of the more usual Administration route. Perhaps so that the Govt has more control over what happens next, with important public sector contracts?
A tiddler from the past - Spaceandpeople (LON:SAL) - has put out an OK trading update. Too small for the SCVRs probably. After years of disappointments, I sold mine at/near the all-time lows, some time ago.
Judges Scientific (LON:JDG) - positive trading update.
Watkin Jones (LON:WJG) - strikingly good results, very good profit margin. I like their build to rent idea - we need much, much more of this in the UK, to solve the housing crisis & bring down exorbitant rents from increased supply.
Best wishes, Paul.
P.S. Sorry, I crossed in the post with MrContrarian!
https://www.wilsonfield.co.uk/...
The difference between administration and liquidation and their relevancy to the task at hand is governed by the desired fate of the company. Liquidation is the route to take to wind up and finish the company entirely. If all/some of the business needs rescuing, administration is the mechanism to go for. If the business is large with several sub organisations, it may be a mixture of both.
Suggests the situation with Carillion was more serious or perhaps they felt there was more value to be had for remaining stakeholders by trying to sell off parts quickly - a fire sale will almost certainly ensure there is very little left after pension deficit, HMRC and employees are paid.
Maybe it's the best way to structure a government bail-out without the negative press of nationalising the thing? With a quick reset of the pension question, at taxpayer expense (through the pension guarantee thing), and possibly some short term working capital support (notionally for essential public sector projects) they may be able to sell or refinance the operating businesses more efficiently than through other routes.
Good morning Graham
Another request for Spectra Systems (LON:SPSY) please.. I opened a position a couple of months ago believing more good news was to come, so I'm very happy to read their RNS this morning.
Francis
My morning smallcap tweet:
Spaceandpeople (LON:SAL), Spectra Systems (LON:SPSY), Carclo (LON:CAR), Judges Scientific (LON:JDG), Directa Plus (LON:DCTA), GAN (LON:GAN), Carillion (LON:CLLN)
SpaceandPeople (SAL) Guides FY rev in line and pretax £100k higher than anticipated at around £1.2m. Will restart dividends with 1.5p final.
Spectra Systems (SPSY) FY 2018 revenue and particularly pretax will significantly exceed market expectations. New deal with existing licencee - guides licence and supplied material sales about 2.7 times PA that of the current agreement, to 2023. Exp $14m in rev during 2018-2028.
Carclo (CAR) Curse of second half weighting - now expects FY performance significantly lower than previously planned. Profit will still show ' healthy' growth. The medium term outlook for the Group remains positive. FD resigns, going in March. Chmn resigns, going in May.
Judges Scientific (JDG) guides FY EPS ahead of current market expectations. Organic order intake (not rev) up 16%. Order book 14.9 weeks (13.9).
Directa Plus (DCTA) H2 sales of graphene-based products over 2x H1. Guides FY rev €0.9m. No profit guidance. F/C pretax -£4.1m.
GAN (GAN) SBTECH as a Strategic Partner for US Sports Betting. Well that sounds great. No rev unless Federal US prohibition on sports betting is reversed. Oh.
Carillion (CLLN) goes bust as widely expected.
ive opened a small position up in Spectra Systems (LON:SPSY) - a little bit secretive but company seems to be going places. - more of a punt but I expect the shares to rise.
Carclo (LON:CAR) - a profit warning by the looks of things. the results issued in November are not now looking to be achieved. Also the groups finance director is leaving.
Morning Graham, if you have time I'd be interested in your comments on the trading statement from Judges Scientific (LON:JDG) and acquisition by XLMedia (LON:XLM). Many thanks
ppdrs
Hi Graham - Watkin Jones (LON:WJG) has released its results for Y/E 30/9/17. Appreciate it's marginal higher than £500m but any insight would be appreciated as it appears to have have done well. Also note CEO will be departing but appears to be on amicable terms.
Thanks
Interesting announcements this morning for your consideration if possible:
1. Spectra Systems (LON:SPSY) - a significant contract win and upgrade to forecasts from this opaque and difficult to read company
2. Watkin Jones (LON:WJG) - Annual results beating EPS forecast for this specialist property developer
3. More on the Melrose Industries (LON:MRO) bid for GKN (LON:GKN). Outside the small cap arena but interesting nonetheless. Melrose Industries (LON:MRO) has generated excellent shareholder returns over the years
I wanted to flag an RNS from Spectra Systems (LON:SPSY) titled licensing agreement and supply agreement which states "based on the execution of these agreements, Spectra is expecting that both its revenue and particularly its profit before taxes for the year ending 31 December 2018 will significantly exceed market expectations."
I know Graham has written positively about Spectra Systems (LON:SPSY) previously.
Another vote for Spectra Systems (LON:SPSY) and a reminder that there is a second listing as Spectra Systems (LON:SPSC) .