Small Cap Value Report (Mon 15 March 2021) - HEAD, ITS

Good morning, it's Paul here with the SCVR for Monday.
Timing - update at 12:52 - I'm downing tools here for a while, as there's a webinar from Somero Enterprises Inc (LON:SOM) (I hold) about to start at 13:00 on PIWorld, that I want to watch, having recently opened a starter size position again in this share (I've held it on & off for years). There's hardly anything else of interest going on today, with very few results or trading updates from decent companies published today.
Agenda -
My latest market thoughts
Headlam (LON:HEAD) (I hold) - a few points from the webinar last week
InTheStyle (ITS) - an interesting new float on AIM, of another eCommerce fast fashion brand. The next BooHoo (I hold), or an opportunistic float after 1 profitable year?
.
Paul's Market Thoughts
So many shares in our small caps universe (and mid caps too) seem to have soared in price in the last 6 months. I can understand why - massive Govt stimulus has kept the economy mostly afloat, and we’re about to see lockdown phased out due to a successful vaccination programme.
Will this lead to a coiled spring of spending, as bulls reckon (and to be fair, that includes Andy Haldane, the respected Chief Economist at the Bank of England)? Or will it just lead to people shifting their spending from lockdown type things (revamping the home, buying a Pelaton), to returning to more normal spending patterns (holidays and eating out)? Answers on a postcard please (that’s my code for saying I don’t know!)
All I would say is this - I find there’s lots of scope to do your own forecasts, and work out that some current broker forecasts could be wrong on the downside - in some cases brokers could be too cautious, because businesses have stripped out a lot of costs. Therefore the leaner, more efficient businesses that emerge from lockdown, maybe could surprise on the upside? Especially if some competitors have fallen by the wayside giving them more market share.
We’ll see, but severe economic downturns are often the times when the best management shine.
Over-paying - lots of smaller growth companies are now looking very expensive. So I think it’s time to be really careful. We all feel great when something goes up in price by 50-100%, but that’s happening too much at the moment I think. I took a hard look at my portfolio this weekend, and made sure I’m totally happy with the valuations on everything. I keep a spreadsheet, where I colour-code the company names, with a simple traffic light system. If I’m happy with everything, it gets a green. If it’s a “coffee can” (100 Baggers book) share, then I colour code it very dark green - that means never sell.
If I’m not sure, or think it might be too expensive, then I colour it amber.
At the moment, I’m green or dark green on almost everything in my top 20 positions. That’s essential. Nothing amber should ever be in the top holdings.
The trouble is, we all feel confident and happy, when markets are great. Is that the time we should be banking some profits, and building up a cash pile to pounce, when the next market panic sell-off occurs? Who knows. It’s impossible to time these things, but I'm feeling uncomfortable with the seemingly indiscriminate share price rises in recent months.
Headlam (LON:HEAD)
(I hold)
This is an enthusiastic holding in the value section of my personal portfolio.
I reviewed the latest results here (add link) last week.
Many thanks to Headlam, and PIWorld, for a very useful results webinar last week.
Management here strike me as what we used to call in the 1990s “steady eddies” - i.e. hands-on managers that work hard, and are prudent in how they manage the finances.
This webinar very much reinforced my view on that front, so I feel very comfortable with them looking after my money, as regards to my small shareholding.
A few points stood out for me -
CEO - “incredibly resilient & cash generative business” - as proven in 2020. I agree. Headlam quickly rebounded from lockdown 1, and never showed any financial stress, due to its conservative balance sheet with a ton of freehold property in particular (a major plus to me).
CEO - the business can be “much more efficient” in particular with changes being made to deliveries from its many depots, to match supply to local demand. I was a bit surprised this wasn’t already being done, but never mind, it’s upside on future profits, so it’s good.
Operating margin - target increase to 7.5% by 2023. That’s a 200bps improvement, so should be a material increase in group profits.
Supply issues - have been resolved, but N.Ireland border is only current problem.
Products have a long life cycle, little change in fashionability of floor coverings, so should be simple to match supply & demand
Grey & beige dominate the colour palette, not sure if this was for domestic carpets, or commercial, or both. Depressing, but I know personally what a b*@#h cream carpets are to keep clean, so won’t be making that same mistake again! Beige all the way for me, next time!
Q&A - I complained about the lack of liquidity in the shares. Directors acknowledged the problem, but said about ⅔ are held by institutions, who aren’t going anywhere. Did consider share buybacks, but that would only make liquidity problem worse.
My opinion - if we take pre-covid revenues of c.£700m, and put a 7.5% (aspiration) operating margin, that’s OP of £52m. Finance costs should be little, and 25% corporation tax by 2023, then I make that £40m earnings. Put that on a PER of 15-20 times, and we have £600-800m market cap target.
Divide that by 85.1m shares, with little risk of dilution, and it’s 705-940p per share, with a 2 year view. That’s usefully above the current price of 434p. I’ve not been particularly aggressive with the PER either. And we should get divis along the way. Still looks cheap to me. But as always, please DYOR, my sums could turn out to be wrong, because we’re trying to predict the future.
Another angle here is that it could be a takeover target. Victoria (LON:VCP) did very well targeting conservatively financed carpet businesses that had too much stock, and owned freeholds. Hence acquiring them was semi-self-financing, as excess assets were sold down. Therefore, with over £100m in freeholds sitting on its balance sheet, HEAD could be seen as a sitting duck for a takeover bid. Also, what better way to increase your sales if you’re a carpet manufacturer like Victoria (LON:VCP) than to buy a distributor like HEAD, and then push your own group products? Seems an obvious fit to me.
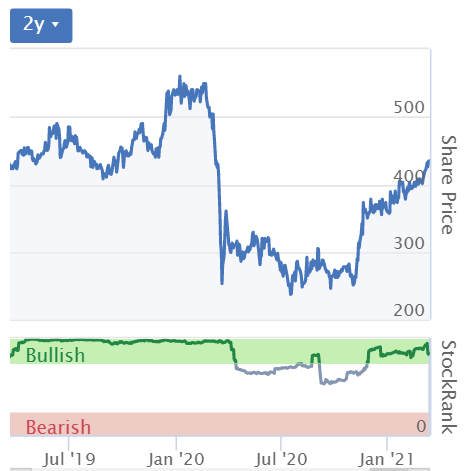
As you can see below, HEAD shares have been recovering well from the irrational market sell-off last summer/autumn. As mentioned here at the time, it just didn't make any sense at all that HEAD shares fell back down in the summer/autumn of 2020, to re-test the March lows, when trading was recovering well. Markets are strangely irrational at times, especially in less liquid shares.
Note also the StockRank is high most of the time, which gives me additional comfort.
.
.
InTheStyle (ITS)
Floats on AIM today. It’s another fast fashion eCommerce business, based on the North West, where so many similar businesses are based.
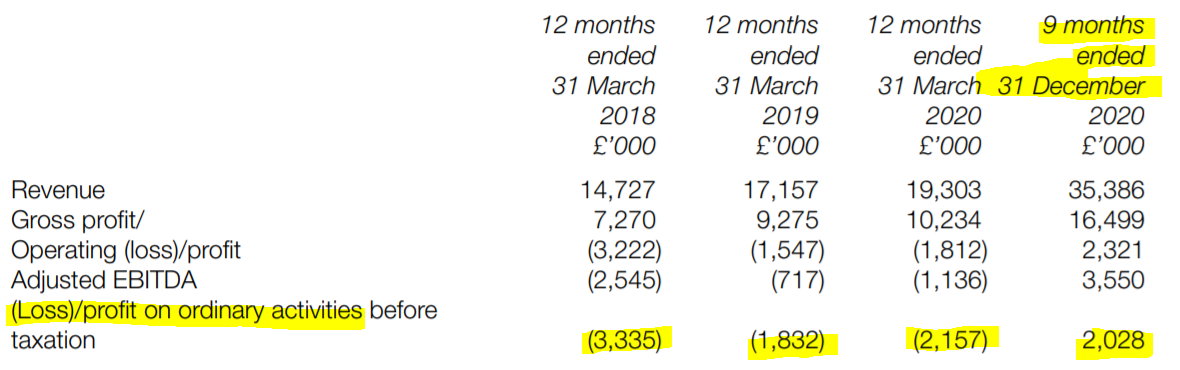
I gave my initial views here on 5 March 2021, on the “intention to float” (on AIM) announcement. These tend to be rather sparse on financial details. So I did a search at Companies House online, and found historic financials that are poor. However, ITS seems to have had a very good year in 2020. Therefore the key question is whether ITS has had one bumper year from lockdown, or if this is the start of something that could become the next BooHoo (I hold)?
Personally I need to see more than just one year of decent figures, so I’m watching this one from the sidelines.
Breaking Fashion - this was the name of a BBC series, a fly on the wall documentary about ITS, following the dramas & chaos at their Head Office, and on fashion shoots, etc. It was very entertaining actually, so well worth watching on catchup. This was first aired in Sept 2019, so I’m wondering if it helped boost strong sales/profits in 2020? A similar programme about competitor Missguided helped it bounce back from disastrous losses, into a small profit. So these TV shows do seem to stimulate interest amongst customers, and the more chaotic & foul-mouthed the participants, the bigger the boost to sales, it seems to me!
It struck me that the company is so similar to competitors (BooHoo, PrettyLittleThing, Missguided, ISawItFirst, and lots of others), that it’s in a very crowded space. ITS has little to nothing to distinguish it from the others, in my view. Its announcements make a big deal about relationships with “influencers” (reality TV stars, youtube vloggers, etc), but that’s exactly what BOO did to grow originally. Promoting ranges with influencers is nothing unique at all.
Admission to AIM - first day of dealings is today, so I’m looking forward to monitoring the progress of this interesting company.
The fundraising, which was significantly oversubscribed and priced at the top of the valuation range, included the placing of 5,500,000 new ordinary shares of 0.25 pence each ("Ordinary Shares") and the placing of 24,500,000 existing Ordinary Shares, both at a price of 200 pence per share (the "Placing Price"), raising gross proceeds of £11.0 million for the Company and £49.0 million for selling shareholders. At the Placing Price, the Company's market capitalisation is approximately £105 million.
Note that most of the money raised is for selling shareholder, selling 46.7% of the company. Would they be selling if the future was tremendously exciting?
The price seems to have gone to a premium, with a quote at 11:10 of 230p Bid, 240p Offer. Well done to everyone for a successful float on AIM. The Admission Document (“AD”) can be downloaded here. I’ll have a rummage through that this afternoon, and report back if there’s anything of interest in it.
As you can see from section 11 in the AD, the financial track record is poor, apart from a big surge in sales & profits in 2020 -
.
With the market cap already up to £123m (based on 235p per share current market price, and 52.5m total shares in issue), then continued strong growth & profitability are already priced-in.
My opinion - sceptical, until the company can prove growth is sustainable, and not just a flash in the pan.
.
Deliveroo also confirms its intention to float on the London stock market.
Not a small cap though, as it's raising c.£1bn in fresh money, plus more from selling shareholders.
Interesting structure, with A & B shares, giving additional rights to founders for the first 3 years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

106 comments
On the subject of upcoming IPO‘s, Parsley Box have just announced that there will be a retail leg to the offer available through Primary Bid. Already open for subscription to registered PB users. Issuing docs on the PB site. Minimum subscription amount £500. I believe the deadline is next Monday, 22/3.
https://primarybid.com/home/pa...
Gus.
Neat idea on colour coding your holdings Paul. I have always used my own spreadsheets and will give it a try.
Just to say there is a very interesting article on Next NXT in The Times today which amplifies on this move for the larger 'part' online retail apparel companies to include more third party brands in their offering. This ties in with the recent news on Sosandar products becoming available on M&S, adding to their agreements already in place with NXT and John Lewis. NXT has taken also recently announced a stake in Reiss. The key take in the articl for me is that the company - which already has more online sales than in the slightly shrinking traditional retail - is trying to beome a kind of Shopify or Ocado for the apparel sector in the UK. And one imagines that the smaller online seller will also benefit not only directly but also if clients decide to go straight to their own website. You can tell by my ignorance that I have been out of this sector for years but it did tempt me to take a small position in NXT for the long-term.
https://www.thetimes.co.uk/art...
Bitcoin nearly hit $62,000 over the weekend. An all time high by some way. It started 2020 at just $7,200. Could it go higher this year? Perhaps to $90,000 or even higher? I think so. The largest UK brokers say that crypto miner Argo Blockchain (LON:ARB) is the stock most in demand by smaller investors. No surprise bearing in mind it is a 100 bagger plus from the lows this 52 week year. I think there is no doubt that some of the $1.9 trillion being sent to US citizens will end up in stocks and crypto. It may well all be a bubble but this bubble could have some way to go yet!
I wish I had a dislike button.
FT Alphaville has a long running series "This is nuts, when's the crash"
As Stocko is (sort of) a rationalist, fact based place it might be interesting if Stocko could run an experiment on the wisdom of crowds
- and ask us for a group opinion on when we think the bubble will pop / the crash will be.
"FT Alphaville has a long running series "This is nuts, when's the crash""
Its a headache to predict.
As I recounted, I sold some big winners 3 weeks ago, and missed out on perhaps 5% more.
We are damned if we do, damned if we don't.
I think Edward Croft in his Stockopedia articles has indicated that higher SR shares tend to be more resilient in times of drama, and recover more quickly. That worked for me 11 months ago.
Things I am watching for:-
Bitcoin correction
US correction
Russia silly games (poisonings / "mutual aid" to neighbouring countries such as The Crimea / cyber attack)
China resurgence / cyber attack
North Korea getting one off (Nukes)
India-Pakistan border (Nukes)
India-China (Nukes)
Autumn/Winter - new "bug" strain / wave / "lockdown" / economic sabotage
Biden death, succeeded by a US Marxist
Incompetence of The Con-socialist party making Starmer seem competent, Capitalism left undefended, more lefter wing socialists to gain more power.
Asteroid / Kessler syndrome / Coronal Mass Ejection (systemic power and network failures)
And lastly... God Save The Queen... because the instability that might occur were we to lose HMTQ after nearly 70 years, spanning most of our lifetimes, may leave The UK and Commonwealth worse off constitutionally and within The Establishment.
and ask us for a group opinion on when we think the bubble will pop / the crash will be.
The problem is all the really smart people will just say 'don't know'
"and ask us for a group opinion on when we think the bubble will pop / the crash will be.
The problem is all the really smart people will just say 'don't know'"
And then the really smart people like Mr Scott hedge both ways!
Surely if you hedge then you are simply pressing the pause button - losing any further growth but knowing if it all pops you minimise your losses. Obviously there are degrees of hedging.
Sounds great, but what if we have another 5%, 10%, 15% or 20% to go. You will potentially miss out on that growth.
If you are in quality companies then you might drop the same 20% (or whatever the crash brings us) but hopefully these will be the first to recover and possibly the strongest and therefore you can hopefully pull a lot of it back over a period of time.
I may move a little towards cash (5-10%) in the short-term in case there are bargains to be had. BUT....to date, every week I have done this, by cutting my least conviction shares, I always find either new opportunities or want to top up my highest conviction shares eg. Headlam (LON:HEAD) today.
Currently less than 1% in cash, but will try again on a couple of low conviction shares later this week.
It all depends how you hedge.
Ideally you want to look for a hedge that will underperform your portfolio when the markets are going up and do significantly worse in the event of any downturn.
The best I personally have got to so far is a short portfolio that tends to actually go down when my longs are going up but unexpectedly (to me at least) falls slightly less than my longs in a downturn. It's quite hard work (and IG Group (LON:IGG) made it harder recently) but it (so far) works for me.
A lot of people seem to use index hedges (eg short the FTSE 100) , this has a similar failing to my approach - because the indexes are dominated by the mega caps they are generally more resilient in a downturn than a portfolio of small/mid-caps.
For me, dear Gromley, holding Plus500 (LON:PLUS) and IG Group (LON:IGG) shares has been very lucrative, being two of the meltdown winners last year.
Hedge early, hedge often.
a poll feature here would be very interesting / worthwhile
What bubble? The FT100 hasn't gone anywhere for years!
"The trouble is, we all feel confident and happy, when markets are great. Is that the time we should be banking some profits, and building up a cash pile to pounce, when the next market panic sell-off occurs? Who knows. It’s impossible to time these things, but I'm feeling uncomfortable with the seemingly indiscriminate share price rises in recent months."
New personal wealth record reached every day it seems.
The Great Turkey shoot for share bargains is nearly at an end... and it gets harder here on!
Don't forget, we've got tax bills to pay in the next 10 months!
Raven Property (LON:RAV) had figures today. A warehouse property company in Russia (or logistics if you prefer ) though there are some offices in St Petersburg. Good figures : 94% occupancy and 99% of rents collected . They estimate that the cost of new warehouses has increased by 15% since the start of the Covid crisis , due to labour shortage and increase in the cost of steel, which will enhance their valuations . NAV reduced to 40p due to fall of Rouble versus Sterling. Still have Euro debt though moving to Rouble debt . Overall cost of debt 5.5% approximately. The Russian economy in relatively good shape.
The huge Invesco overhang has been removed now. NAV would rise if the Rouble appreciates against the Pound.
Isn't it strange how not that long ago most portfolios would have been down 10% or more but in a period when you would have thought the worst scenario of Covid a lot of portfolios are performing well, to the extent that Paul is considering taking some profits.
At the same time in various strategies set out in 100 baggers, mirrored and emphasised by the likes of Fundsmith, say, 'buy good companies, don't overpay, do nothing'
Leaving a decent period for them to perform is key. I guess therefore, if we think this strategy works, we ought to sort our holdings into short/mid term/long term as well as other criteria.
One of my stocks was originally a short term punt on a takeover Best Of The Best (LON:BOTB), and leaving this alone has paid dividends in more ways than one. However having planned to get out I was so impressed by its recent growth announcements that I have stayed in for the ride. So some degree of flexible thinking is required.
Or does the world of small caps require another philosophy.
"Or will it just lead to people shifting their spending from lockdown type things (revamping the home, buying a Pelaton), to returning to more normal spending patterns (holidays and eating out)?"
I think Aston Girl reads this - perhaps she would like to give us the answer??
Absolutely, though I suspect that I’ll need my Peloton even more now if I’m to get back into lunches & holidays
In today's Telegraph! Effective as of March 15, 2021, the titles of Elon Musk and Zach Kirkhorn have changed to Technoking of Tesla and Master of Coin, respectively
Perfectly timed to capitalise on the $1.9tn stimulus checks hitting US millennial's bank accounts as we speak. Meme stocks on the march.
Any serious investor still long Tesla (beyond the inevitable stonk bounce) needs their head examining.
The Biden stimulus will be an awesome liquidity opportunity for the smart money to exit all the recent bubble trades.
"At the moment, I’m green or dark green on almost everything in my top 20 positions."
Paul, would love to know what your top 20 positions are if you are able to share.
Well, Turbo, I guess that we can make up a list of a few of those from Paul's comments in the past few months. Would you like to start it off?
ridavis, I'm pretty sure Paul holds
BOO, IGP, SAGA, SHOE, HEAD
Not sure if they are in his top 20 though
And Volex, FCCN, Redde Northgate, Revolution Bars, G4M, RNO. Off the top of my head. Not sure if he still has BOTB.
True in both instances!
Quiz (LON:QUIZ) and £RBGP too I think
and Gattaca - and no Paul - I don't have a written list - just from recall.
Good idea, it's been a while since I've done a portfolio review. Will put that on my to do list.
When was the last one Paul please? It's not that easy to find specific SCVR's if you don't know the date.
It may e this : https://www.stockopedia.com/content/small-cap-value-report-mon-16-nov-2020-pauls-recent-buys-ncyt-702158/
would also be good to understand what the amber (less confident) smaller positions are? thanks
Paul, re Headlam (LON:HEAD), thank you for your review today. I hold and have increased my holding this morning. Two thoughts which may be holding it back, or opportunities to take it further forward. Whilst its improvement programme is valuable, it is a little slow in implementation. On the other hand, they operate in a lot of locations and employee consultation can be tricky. The two thoughts I would mention are making more of the freehold property on the balance sheet, and secondly there seems little appetite in the plans to grow market share, particularly by takeovers. Re the freeholds, other companies have made a step change in SP by sale and leaseback. Perhaps the lease costs wouldnt be worth the candle, unless they were able to use the freed up cash to expand and become a significantly more profitable business. One company in a totally unrelated market that appliedthis sale/leaseback is Caretech Holdings (LON:CTH) which implemented this very successfully though Caretech Holdings (LON:CTH) does have a somewhat higher operating margin even than Headlam (LON:HEAD) with its 2023 target of 7.5%. I wonder if you have any comments to make on their plans in light of these two thoughts/suggestions. PS The takeover idea is a very tasty thought.
Here are my SCVR heat maps for today (prices as at ~10:10am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
My thoughts on the market ... the FTSE All Share reached 3440 in June 2007, some 14 years later and it's 3866. I think it's time to get going and catch up! In the last 5 years we've be weighed down with the election - now out of the way, banking crisis - that's passed, Brexit - we are 80% there and then Covid - we are again 80% through that one. The world stock markets have had a very cautious view when investing in the UK for years due to these potential pitfalls. But with America being overvalued and the UK having come through the all of the above, I think we could have a good recovery run ... but I thought that in January 2020, just before Covid. Let's see.
That's because there is little growth in our largest companies, we have no large tech. companies. If america crashes then so will we. If you look at the FTSE250 you will see it has performed a lot better than the FTSE100. Although dividends are higher.
I recall thinking that the FTSE looked cheap relative to the US 20 years ago, then 10 years ago. It is always going to be relatively cheap unless more growth companies list in the UK.
I was surprised to see my holding in Morses Club (LON:MCL) down 6% first thing, I then later found that Provident Financial (LON:PFG) was down 26% on news that it is likely to have its home collect business close or go into administration due to the high level of customer complaints that may cost it £50m in compensation plus a further £15m in costs, ouch! Interesting for Morses Club (LON:MCL), although they see Home Credit as a legacy low growth business, albeit one they have brought up to modern standards of technology, compared to their online banking and larger loans products, this must surely be an opportunity, one way or another, to acquire customers from what is currently by far the largest player in the market.
The thing that finalised my interest in Morses Club (LON:MCL) was their Trustpilot reviews, scoring 4.6 from over 2000 reviews (reading the one star reviews some are, bizarrely, from people happy with the service, and others from people who were refused credit). This appears to be another case where customer satisfaction is the difference between success and failure.
Hi Martin, can you clarify that £PFL please, I hold Morses Club (LON:MCL) so have an interest in the proceedings.
Sorry, I corrected in the comment. It should be Provident Financial (LON:PFG)
Would surely be positive for Morses if PFG pulled the plug on the home collection market. Would remove biggest competitor in one go.
From my reading of the announcement that sounds likely to be the outcome.
Provident announcement likely to have +ve impact for £MCl anyway - their agents were already unsettled and morale is always low in operations being 'downsized'. This might get some more agents to jump without MCL paying! A lot of the loyalty is to the agent and Morses have good claim to having the best reputation amongst agents. (The 3rd player NSF - I hold - has also had issues and I expect the smaller players will have struggled)
Morses have not given any indication of issue with FCA so (I hope as an MCL holder!!) the issue is Provident specific.
MCL are also reaching the end of their rebuild of the Digital bank and online loans companies they bought cheaply a couple of years. Just about to go for growth. Timing is great. I think it is the failures/issues at all their major competitors that is leading to a negative view on the complete sector - whereas MCL have been relatively unscathed and thus in a good position now. I have been adding MCL steadily in P6M and will likely buy some more. It wasn't long ago they were above 150p. I think they can get there again in 1-2 years.
The big question is, do you trust that Morses Club (LON:MCL) have an airtight, above water process. And will FCA stop moving the goalposts on what is acceptable or unacceptable lending behavior.
At the end of the day, agents, area managers, and middle management are tempted to fudge and do hard sells, to get their numbers up and hence their commissions. Regardless of which organisation they work for.
If I had spare funds to invest (bet on), I'd consider Morses Club (LON:MCL).
I'm in super-big in market leader competitor International Personal Finance (LON:IPF) who IMHO are doing OK with a credible business plan, diversification in two continents and multiple states, doorstep and digital businesses.
Interesting comparison:-
https://www.stockopedia.com/compare/?tickers=LON:IPF,LON:MCL
International Personal Finance (LON:IPF) have shed their under-performing business units, hence an Accounting H1 loss, but H2 cash positive, and refinanced their corporate bonds showing that The Management is trusted by the big banks/lenders/bond holders.
I think the recovery path for both is along a parallel road.
For Morses Club (LON:MCL) , Baroness Finn's involvement as a NED for nearly 2 yrs (she is stepping down soon BTW due to another imminent appointment) also provides a certain degree of re-assurance that Morses Club (LON:MCL) 's procedures, policies and practices have been professional. She must have carried out a DD prior to her appointment.
I think the question should be viewed in regards of risks to rewards. Given
- Provident Financial (LON:PFG) 's unfortunate current situation the consequential potential additional market share for £MCL
- Morses Club (LON:MCL) 's shift towards higher credit quality during 2020
- £ MCL 's SP
- Most recent Morses Club (LON:MCL) 's TU
- CFO 's recent purchase of Morses Club (LON:MCL) 's shares at 65.XXp
I have made an investment in Morses Club (LON:MCL) which justifies the risks.
Obviously one must balance out the risk - e.g FOS , FCA , claim contingency companies drumming up biz by looking for potential MCL complainants.
Thanks Martin, I also hold Provident Financial (LON:PFG) , perhaps one will balance out the other in my portfolio.
I see that N Brown (LON:BWNG) (I hold) has announced that it will sell more third-party brands on it's websites. It will be interesting to see how this plays out .....
https://www.retailgazette.co.u...
There were similar announcements last week of M&S and I think someone else (can't remember who) selling others products on their website. It will be interesting in the longer term to see whose websites will be the winners. At the moment it seem everyone thinks theirs will be the 'go to' site
Whatever the success of any individual clothing website platform, it does surely mean that the number of physical clothes shops operating in Jan 2025 will be vastly fewer than those operating in Jan 2020. And yes there are plenty of these websites proliferating, but then again there are huge numbers of clothes shops in any decent sized town...online is where I prefer my investments to go for this segment.
Hi Martin - Retail Gazette reported yesterday a net deficit of 9877 permanent shops in 2020 UK (https://www.retailgazette.co.u...) ..
Yes that’s a net loss of 5% of the 205k stores surveyed. And of course some store segments are still doing well in physical retail, eg sofas, tiles, hardware, garden centres, supermarkets. But it seems reasonable to expect that many clothes shops will close down over the next 12 months. Personally I can’t remember when I last bought clothes in a store. It was certainly well before Covid arrived.
£BOO. In case people have not seen this:
“Boohoo submits plans for new Leicester factory.”
https://www.ecotextile.com/202...
I see this as positive for Boohoo, garment manufacturing in the UK (long term) and the stock price.
Will it squeeze margins a tad I don’t care. If the pie is redistributed a little more towards the work force and or people pay a few pennies extra on the cost of a skirt I see this as a good thing.
I hold.
I came across this because of a Google Alert, which I have set up for all my holdings. Not yet for my watch list but I should get around to it.
Regards
Michael.
Anyone here make a case for or against Diaceutics (LON:DXRX) ? Its a niche potential platform company.
It does sound like a nice niche but the company does a terrible job on it's video on the home page - cheap 80's video voice over man talks shite for 50 seconds before summarising badly! BUT they have a nice cash pile and a high margin (cash pile added to via placing)
They got hit really badly in sept (overdone?) by a profit warning of a 1m loss which was reported as a 700k loss today. They obviously got clobbered by covid as most of their testing network seems to be oncology based and so you'd hope that as we move to a new normal then they should be in a position to profit - especially if their new platform pays off.
If I summarise correctly it seems that there is many a missed opportunity for cancer patients to be diagnosed correctly and swiftly and these guys work for pharma companies to improve testing in labs and their new platform will hopefully help here by linking all the labs and the pharma companies to get testing working better using the right drugs to do so. They have a massive dataset and the new systems will hopefully grow that and if it's working properly drive better testing for the brands they are onboarding.
Recover out of covid is key - a warning for me is that despite saying they added 7 new customers this year they must have lost 4 as the net gain is only 3.
I need to dig a bit deeper but I'm interested in the potential - I watched a Sharesoc video from Feb last year (first thought was jesus look at those people in a room together) which showed a big potential market which you would hope would start coming to fruition this year.
Okay - having watched it drop a further 5% today I bought some for recovery (pre covid it was around 180p).
Hi labbey1, they are presenting in next couple of days on InvestorMeetCompany.
I too find how they report clients a bit confusing. 'Therapy brands' seem to be the core measure of customer....and a clients can have more than one therapy brand operating with them. So they are not employed by Merck on a retained ongoing basis but rather specific drug launch and development teams within Merck. So this could explain the loss of 4 clients. They may not be truly lost but more dormant/unengaged as they await another therapy brand project.
As they move to the SaaS based product it seems they also reduced more consultative lines of business (partly this would have faded due to covid too?)...so some client loss may come from that.
I haven't seen their crap video...I do note that their written reports can be a bit poorly articulated....like sentences that are not quite finished.
Will this lead to a coiled spring of spending, as bulls reckon (and to be fair, that includes Andy Haldane, the respected Chief Economist at the Bank of England)? Or will it just lead to people shifting their spending from lockdown-type things (revamping the home, buying a Pelaton), to returning to more normal spending patterns (holidays and eating out)? Answers on a postcard please (that’s my code for saying I don’t know!)
Hi Paul
Your too clever for me, I had to look up that word (in bold) as I have never heard of it before.
Keep up the good work and stay safe
Can I assume you dont watch much TV ? The very annoying Ads are on a lot !
I think the answer is BOTH. We will have a K shaped recovery, many have built up savings they want to spend this Summer. When the furlough scheme ends many will lose their job and cut spending.
I would guess the net is still positive since Rishi Sunak is the most spendthrift Chancellor in the last 50 years.
Our spending will be both indoors and outdoors. We have refrained from having workmen in our house over the past year and put off decorating and other jobs so hopefully this year they will get done but we have also very much missed our meals out and holidays and can't wait to get out again.
I think that employment will pick up dramatically as we reopen. In fact in certain businesses finding employees could become a problem bearing in mind that many have returned to their own countries and with the new regulations in place they will find it difficult to return, e.g. having to have the equivalent of an A level qualification and be sponsored for a job with a salary of just over £26,000 p.a. will rule out a lot of those previously working here on low wages.
Which, along with Chancellor’s new hyper generous capital allowances against Corporation Tax, may lead at last to improved productivity due to raised capital investment.
The "hyper generous allowances against CT" are just a defensive move, as otherwise companies would put off investing until the new, higher rate of CT comes in. The relief will then be pretty much the same.
Civil engineers are desperately short and I was told they can’t be found for love or money, but have they tried more money?
The Civil Engineer in my family was just told no pay rise for the year because he is saving so much money on commuting! He replied that he is spending a lot more on providing his home office.
So that doesn't really show much love or money. I did comment that market forces would prevail.
Hi Tony
How much money are you offering???
Tommy
Fellow of the Institution of Civil Engineers (I Hold)
Sorry if this is too esoteric, but after my earlier comment re the only comparison with now that I could think of was WW2, I looked up the Dow and FT30 (FTSE as was). Both recovered strongly from about a third of the way through the war. The Dow then peaked in 1946, had three off years and then started rising again. The FT30 recovered strongly until 1945 but then went sideways for about 8 years, until the end of post war austerity (which really was austere...food rationing!).
So I guess one lesson from that is with our Government, and the US, being expansionary (who knows what the EU thinks it’s doing?) and the impact of Covid not over, the positive stock market may well continue until there is at least a declared ‘victory’ in what our politicians refer to as ‘war’ with Covid. Whilst things on that front will improve this year, I doubt any ‘victory’ will be declared this year.
Interesting release re. CAP -XX supercapacitor use in Portal Instruments needle free drug delivery air injection system. Portal Instruments is a Series B company so too early to assume large numbers but stills is another endorsement.
Thanks as always Paul for your thoughts on markets and individual companies .
All of my top 20 positions are up at least 20% YOY except my largest Boohoo (LON:BOO) which is ironic considering it is the stock I value more than any other in my portfolio and the one I expect to hold the longest.
It just shows how it takes two views to make a market! I don't think there is anything worthwhile about Boohoo (LON:BOO) that will give it any longevity. The original business is a fashion brand (which means it can go out of fashion) and from what I have heard from former customers it provides goods of very poor quality. There is nothing iconic or aspirational about the brand and with regard to the latest acquisitions I fail to see how putting together a collection of out of date brands can create a good brand. However, best of luck and I am glad the down tick facility has been removed or this would have created a record!
I agree on this point. Not a timeless brand by any stretch and poor quality/plastic clothes. I suspect in a few years it may have gone completely out of fashion and replaced by something else. I hear many youngsters are turning against the throw away culture and getting more into recycling/charity shops becoming trendy.
Boohoo (LON:BOO) - It's interesting to hear people's views, but for me, it's the numbers that matter! How can anyone possibly be sceptical about a business that produces figures like these?!
It's a phenomenal growth business. ROCE of 26%, and ploughing back profits into ever-faster expansion.
Bear in mind also that the broker forecasts barely include anything for the new brands recently acquired, yet they were already doing hundreds of millions in online sales. Therefore, with a bit of patience, broker upgrades on BOO are likely to be significant.
Every brand that BOO acquires, it breaths new life into.
BOO has probably the hardest working, and most ambitious management I've ever come across. They're relentless, and that very much filters down to all the staff too. I remember visiting their Manchester HQ a few years ago, and it was an absolute hive of activity, in a large old mill building, with open plan offices on several floors. They're on a mission to build a global fashion behemoth. I remember at the time when BOO's valuation was c.£1bn, Mahmud Kamani said to me, "There's no reason this can't be a £5bn business". It's not far off that already, with the mkt cap currently £4bn, and depressed (temporarily) by all the supply chain kerfuffle.
For investors, I think it's just a question of being patient, and not being knocked off course by the loud volume of background noise.
Yes when you look at those numbers it's hard to disagree!
I have noticed though that visits to the web pages of Boohoo, PrettyLitteThing and NastyGal have fallen in each of the last three months. Assuming the tracking site I used is accurate.
Boohoo (LON:BOO)
It just shows how it takes two views to make a market! I don't think there is anything worthwhile about Boohoo (LON:BOO) that will give it any longevity. The original business is a fashion brand (which means it can go out of fashion) and from what I have heard from former customers it provides goods of very poor quality. There is nothing iconic or aspirational about the brand and with regard to the latest acquisitions I fail to see how putting together a collection of out of date brands can create a good brand.
I would agree fashion can be fickle but i think you are ignoring the amazing operational delivery that Boohoo have shown for a long period of time - i would guess that alongside ASOS they are probably 1 of the top 3 only "internet only" retailers in the at present in the uk - this being the case i have always found that the fact that once you are one of the main players in a segment this means that they will be less likely to fail going forward as they have the opportunity to muscle in aggressively against anyone who dares to take market share from them - to me the branding is irrelevant in this regard - somewhat evidenced by the PLT brand name providing more growth than thje boohoo brand recently (i have presumed this is the case). I dout anyone is going to try to blow them out of the water on price - perhaps amazon could try but other than that personally they have enough strings to their bow now to make none of their brands now be material to long term success. If we take the next best retailer as being next - do they have anything standout about their brand now ? probably not - what they do have alongside boohoo is operational excellence - something something somehwat lacking if we look at companies like Ted Baker (cant count their stock) - Superdry - cant deliver basics or right product at the right time in the right place at the right margin and to a lesser degree ASOs who have had theire own issues on the way. Note i think boohoo has being going 15 years now is that not enough to kind of prove that they do have some winning formula aside from just branding? - i suspect its more providing something fit for purpose (including price) with the younger generation than any specific brand name.
I did for sometime worry (to my cost buying back in recently for way more than i sold up last time i exited the share) that they may hit a brickwall ref future growth peaking and then subsiding but i have now i think they are fimly establised themselves as a big boy that they are going to be that much harder to muscle out of the equation when it comes to being on of the first ports of call to but cheap tat clothing online - hopefully something more than cheap tat being available too!
I guess time will tell as to how this pans out though - the fact i am positive ref boohoo does mean my judment will definately be biased in this regard - although until recently i have been non holder for some time so i have only recently gone back into fanboy (holder) mode - so i like to think the business progress has suitably impressed me recently to ease some of the concerns i had had
Boohoo (LON:BOO)
Speaking as someone who knows bugger all about fashion and has never bought anything from Boohoo , I very tentatively suggest that Boohoo's competitive advantage does not come from the 'Boohoo' brand of clothing, but from
(a) its ability to nurture clothing brands to be fashionable, so it can replace dying clothes brands.
(b) the Boohoo website where people can go to order any of its multiple brands
(c) the distribution & collection network both in terms of technology and economies of scale
(d) the ability to source 'fast fashion' which is in line with clothing brand image - see (a) - quickly and cheaply; put it on its website - see (b); for onward distribution - see (c).
Neither of these factors are unique, but the integration and execution might be.
PS I don't own any Boohoo shares but might do after more research !
my 16 year old spends exclusively on ASOS and BooHoo - even got himself a watch from BooHoo. I've heard bad things about clothes quality but from what I've seen, it seems fine. Put my mind at rest anyway. (He probably spends more on ASOS than BooHoo) - that's my survey of 1 person.
I generally hate rebranding as expensive marketing speak. But in the case of Boohoo (LON:BOO) I do wonder now if there is a case for a new name for what has become an extensive group, which will have boohoo the brand diminishing as a % of group activity. Probably not, but potentially a better case than many.
Primark produce goods of very poor quality ( but cheaply !) IMHO but they are normally doing just fine !
Paul re ‘indiscriminate rises’, I guess the issue is that either businesses have done well during Lockdown and most will continue to do so, or have had sudden, extreme and very challenging and disruptive times, across most of the World, which most companies appear to have adapted to amazingly well. The market is now looking forward to a rising economic tide across the board as Lockdown is lifted and the threat, over time, of further disruption is reduced by the vaccine rollout. Not unprecedented, but the only historical occasion that I can think of that compares is following WW2. And yet it’s not a good comparison because in many ways little damage has been done, and lots of excellent work has gone in companies to adapt to the circumstances.
As you say, who knows? But this is quite an amazing time, and it will be fascinating to see how it works out for markets, small caps and in particular all of our investments!
It must be noted that many a Covid victim has had their assets recycled however distasteful the thought.
Chesnara (LON:CSN) I mentioned them in SCVR on the 12th Feb re the final results being a potential catalyst...confirmed today for Tuesday 30th March.
Thanks I remember your earlier post and did take a quick look. They seem to have lagged the big recovery in peers (Phoenix, Aviva, etc) so maybe scope to catch up. They are quite exposed to euro/sek so recent sterling strength could be slight headwind.
The trouble with Headlam (LON:HEAD) has been that the market didn’t seem to recognise the value in the past. Perhaps the market is right and although it is a good business it’s not going to grow fast enough to make a significant change to its attractiveness. I sold out 2.5 years ago because of this and the share price is now all of 3.3% above where it was back then. There’s bound to be some bounce in trade as we come out of lockdown. But that’s really just a catch up on deferred sales. The WFH bounce may well have finished.
I think it needs a compelling event to create a step change in performance. Perhaps that compelling event will be the Paul Scott effect - especially if it is relatively illiquid.
PE peak pre-Covid in 2017 was around 17 according to stocko; can’t see it going much beyond that for a steady eddy under normal trading conditions, but perhaps a short term leap driven by end of lockdown enthusiasm makes it a viable short term holding.
But perhaps we’re all off on holiday instead of buying a new carpet. I think that’s what makes the current market difficult to call. The rotation from discretionary spending in one area to another area is hard to judge. Listening to Terry Smith we should not be trying to call this at all. Is Headlam (LON:HEAD) his type of stock? I would think not, ROCE too low. James Halstead (LON:JHD) would appear to be the better business on that score but rather richly priced.
Hi GrahamF,
Fair points, but I think the appeal with Headlam (LON:HEAD) is mainly for income seekers. Management have stated they want to pay out half future earnings in divis, so if my estimate of 47p EPS by 2023 is accurate, then c.23p divi gives a yield of 5.2%, and a PER of only 9.5 (at 444p per share currently). Those seem attractive numbers to me, for a business with a good business model, and products that will always be in demand.
Over £100m freehold property thrown in for free, is rather attractive too, and could attract a bidder.
So I see it in a much more positive way than you.
Also note that if you add divis, then your total return if you'd not sold out, would have been much more than 3.3%
I appreciate that value shares are out of favour at the moment, as people are chasing growth shares to sky high valuations, but investing fashions change. A lot of UK investors want income, so anything paying a sustainable divi of 5%+ looks very appealing to me. You've got inflation protection with the business model too, which would just raise prices in line with cost inflation. It's hugely more attractive than fixed income investments, in my view, and that could lead to PER expansion over time. 10x seems absurdly cheap to me, in a zero interest rates world.
I agree on the attractions of income at the moment. In my SIPP I dumped the US growth stuff a few weeks back and I am gradually locking in some dividend earners, mostly UK, including Headlam (LON:HEAD)
I too agree on the appeal of value shares at the moment Paul.
What's not to like about investing in companies that look very cheap compared to the rest of the market. I certainly sleep better at night being mainly invested in value.
In Headlam (LON:HEAD), we have a company that have successfully navigated themselves through a global pandemic with a healthy balance sheet also making changes to become a more efficient streamlined operation. At the same time we have what looks to be a consistent dividend return and the prospect of a possible rerating or takeover over time. I would also include Somero Enterprises Inc (LON:SOM), Redde Northgate (LON:REDD), Macfarlane (LON:MACF), H & T (LON:HAT) in the same category.
There are many other companies around ticking similar boxes. Begbies Traynor (LON:BEG) looks like good value to me but also with huge growth potential as does Spectra Systems (LON:SPSY). Some of the tech valuations in the US make me very nervous but the 'boring' value shares still look exciting to me!
H & T (LON:HAT) gets a thumbs up from me too (I hold) , although I'm at a loss to explain why the SP hasn't moved much despite resilient trading numbers. The pawnbroker has good prospects this year IMO, high gold price is holding up, retail jewelery should pick up now that people are out to spend their lockdown savings, also sad to say but there will be many who have not benefitted from COVID handouts who will need access to alternative finance.
I regret not jumping into Somero Enterprises Inc (LON:SOM) last year but I think it's no longer a bargain after strong gains.
I held Begbies Traynor (LON:BEG) briefly last year. I think the generous and ongoing govt support to business has and will continue to limit business insolvencies. Insolvency is not a very scalable business, each case takes hours and hours of expensive labour (whose rates have no doubt increased) and profit margins do not benefit much from economies of scale. Begbies Traynor (LON:BEG) has expanded through acquisitions but ultimately the long term growth prospects are limited.
Are you my long lost twin by any chance? Just kidding!
But super scary that I have Begbies Traynor (LON:BEG) and Spectra Systems (LON:SPSY) in my portfolio and Headlam (LON:HEAD) Somero Enterprises Inc (LON:SOM) H & T (LON:HAT) on my watchlist, having owned all of them in the past at some point or other.
I love bargains, so a part of my pf comprises of cashed up value plays. I hold £PGH , £CAPD (seller holding back SP) , Tharisa (LON:THS) (seller holding back SP) , £RST (return to office trend, a bit geared tho) , Morses Club (LON:MCL) , £EQLS (change of biz model) , and snap H & T (LON:HAT) .
I've also noticed that also in my pf - I have a lot of former Woodford stocks - no idea why!
My morning smallcap tweet:
Omega Diagnostics (LON:ODX) Arix Bioscience (LON:ARIX) IXICO (LON:IXI) in Style (LON:ITS) Hardide (LON:HDD) £ATC Induction Healthcare (LON:INHC) SThree (LON:STEM)
Omega Diagnostics (ODX) Govt to buy £374m max rapid covid tests but "care should be taken not to use this number as an estimate or forecast of the actual likely value of purchase orders." Also co's test the necessary performance evaluation. [SP=98.5 Cap=179m]
Arix Bioscience (ARIX) share buyback up to £25m. [SP=190 Cap=258m]
IXICO (IXI) collaboration with Microsoft to develop its AI data analytics platform for the global pharmaceutical industry. Plan to "deliver XICO's AI solutions into global clinical trials for neurological diseases such as Alzheimer's disease and Huntington's disease by enhancing IXICO's large-scale data processing capabilities." [SP=91.01 Cap=44m]
In The Style (ITS) first day of dealings for this "womenswear fashion brand with an innovative influencer collaboration model". Sound familiar? And 'collaborated'? Why the euphemism? [SP=0 Cap=NA]
Hardide (HDD) AGM stmt. Sales stable, same level as H2 but "expects recovery in demand, particularly from the oil and gas sector, to accelerate in H2 2021." [SP=29.9 Cap=17m]
Actual Experience (ATC) initial order its new Human Experience Management Business Impact Assessment and Continuous Improvement ('CI') offering, [SP=NA Cap=NA]
Induction Healthcare (INHC) signs multiple NHS contracts for appointment booking app for covid vaccinations. No £££. [SP=98 Cap=40m]
SThree (STEM) Q1 performance ahead of management expectations, with net fees flat YoY. [SP=348 Cap=464m]
Strong sell signal!
Ha!
FOMO versus the LOGICAL...... Who will win ?
it's logical to have FOMO!
BTC outlawed by India hence the big drop this morning.
I was actually under the impression that it was already banned. The Indian government has always been very anti crypto currencies although there was talk of them at one time establishing their own digital currency. It could certainly have a short term effect as it is held by many people in that country.
yes, it seems to me that with any wave of buying the price jumps and then more and more people jump on board, and then there's a wave of selling and it drops right back, this happened a few years ago, just before Christmas coin base started trading bitcoin easily, suddenly you didn't need to have a standalone account you could invest in a on line account, so if you lost your details, you could recover it. lots of people bought in the price doubled in a few weeks, and then promptly dropped right back. I am not into crypto, but I did buy a fraction of a bitcoin back then at 10k, sold half recently at 35k, and held the last bit, if it's ever enough to buy a tesla with, that's what I plan to do. the last bit is free. I underestimated how far it would go this time, and indeed had it not been for elon musk buying it might not have gone nearly so far. However this Musk thing has given an air of acceptability to bit coin that perhaps this time it might not drop right back, 50-90% as it has done so many times in the past. You read about bitcoin being possibly banned or restricted in the US, but it's hard to imagine that happening while tesla holds a couple of billion in bitcoin. Now if tesla were to announce that it's sold it's bitcoin, and cashed in it's billion plus profit, well that could well lead to a crash in the share price of 50% or more. I certainly wish I'd been brave enough to punt some more back then given whats happened since !!
My worry is that with this blockchain bubble already at something like $1trn, there must be people borrowing money to buy bitcoin. So when the inevitable happens, and it crashes in price again, then where will all the bad debts end up? I wonder how many bounceback loans ended up funding bitcoin speculation?
Blockchain technology sounds interesting, and it may or may not have some practical use, but at the moment it ticks all the boxes for an absolutely classic financial bubble. Which always end in a crash.
A lot of my friends, family, and neighbours have asked me about Bitcoin. I always say the same thing - it's a financial bubble, which inevitably will burst, like all other financial bubbles have. Therefore if you want to punt on it, only risk money you can afford to lose. I've heard of quite ordinary people punting £10-30k on Bitcoin, and it seems to be evenly split, between people who have made money (on paper), and those that have lost money.
It's glaringly obvious how this is all going to end!
Yes, the unfortunate hook appears to be that information/knowledge technology people really rate blockchain as an important innovation that may have all sorts of positive uses and implications in the future.
Regardless of that I have no doubt that Bitcoin is the black tulip of its age.
.....the fact that Tesla has, on paper, made more profit from Bitcoin than from 10 years of producing cars just says it all really!
The question I ask is "can blockchain do X cheaper / better than any alternative"
If Yes, then it has a future.
Most of the time, if this is like a bank account, i think there is no cost / trust / functionality advantage over a boring old relational db.
If it is something like a land ownership record or a voting record where the govt is not trusted and _every_ _owner_ is it literate, then, maybe, but would an untrustworthy govt allow such a thing to be put in place in the first place?
So not really.
Disclaimer : I am one of the people who heard about BTC ~2009 when it was ~$10 and decided it was going to go nowhere.
..............and talking of Bitcoin:-
"Elon Musk changes his job title to “Technoking of Tesla” in official US filing" (no, this is not April 1)
St noking ly good job title !
Although the blockchain bubble may be valued at $1trn or so (I don't know, just taking your figure), I would assume that nowhere near that amount of net real fiat money has actually been put into crypto. My understanding is that a huge part of the bitcoin ecosystem is essentially untraded, probably much of it in accounts that have been lost for one reason or another, and a lot more has probably been mined much more cheaply in the early days and simply never exchanged for cash. Therefore the $1trn total valuation is probably set by real crypto<-->fiat transactions of a fraction of that amount, only touching a fraction of the total possible coins out there. And just as I assume that far less than $1trn fiat has ever been put into crypto, I assume that far less than $1trn could ever be taken out - the price would collapse as soon as significant redemptions were attempted IMO.
I agree wholeheartedly with what you say about a bubble and how it's going to end.