Small Cap Value Report (Mon 17 Sep 2018) - W7L, FIF, CTG

Good morning,
Today's report is taking ages to get going, so timing will be a bit later than usual, but I'm on the case.
StockSlam
These events are great fun. Please note that the next StockSlam is scheduled for Wed 24 October, evening, in central London.
At this stage, 15 presenters are needed, to do quickfire 3 minute pitches on your favourite shares. Then pizza & beer afterwards, networking & shares chat. Why not have a go, and apply to do a quick spiel about your favourite share? Click on the header above for more details.
Warpaint London (LON: W7L)
Share price: 250p (up 5.3% today, at 12:04)
No. shares: 76.7m
Market cap: £191.8m
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to announce its unaudited interim results for the six months ended 30 June 2018.
- Revenues have grown strongly, up 38.7% to £18.4m
- This growth has mainly come from an acquisition on 30 Nov 2017, of "Retra"
- Today's statement is admirably clear, also showing the organic revenue growth of 7.3%
- Adjusted profit is down though, which is not good;
Adjusted Profit from Operations of £2.8 million* in the half year (before exceptional Items, depreciation and amortisation costs) (H1 2017 £3.1 million)
Outlook - this is the key bit, which reassures;
"The additional revenues in the second half, particularly from Christmas gifting, are expected to result in overall revenue being two thirds weighted to the second half of this financial year and with a fixed cost base that is evenly spread over the full year, we expect to deliver overall Group earnings in line with management's expectations.
It's good to have the seasonality clearly explained. Let's hope the company does manage to double H2 revenues over H1 - a steep increase.
Valuation on a PER basis looks about right to me;
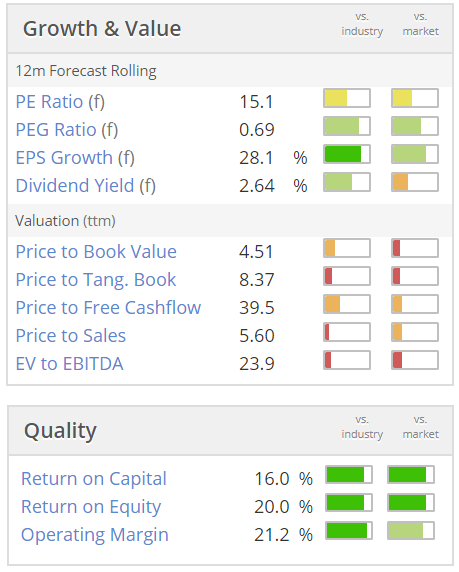
Note that the quality scores are high.
Balance sheet - looks excellent, with a very strong working capital position.
Although both inventories & receivables strike me as a little high - perhaps there are not tight enough controls over working capital?
Net cash of £4.6m is healthy.
My opinion - it looks quite interesting. It would be worth finding out more about the brands, how they are perceived by customers, their longevity, etc.
The figures strike me as a fairly good company, at a valuation that doesn't look stretched. So it could be worth a closer look perhaps?
Finsbury Food (LON:FIF)
Share price: 122p (down 1.6% today, at11:34)
No. shares: 130.4m
Market cap: £159.1m
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for the retail and foodservice channels, is pleased to announce its preliminary results for the financial year ended 30 June 2018.
The key headline numbers look OK;
- Adjusted PBT up 4% to £17.2m
- Adjusted basic EPS up 4.1% to 10.2p (for a PER of 12)
However, I always check what the adjustments are, and how big they are. In this case, note 3 shows us some large adjustments, relating to site closures. This brings statutory PBT down to only £4.5m (down 66% year-on-year).
This scale of closure costs also reinforces that this is quite a capital-intensive business - generally something that I try to avoid.
Outlook comments flag up steady organic growth, and more acquisitions.
Balance sheet - looks OK, not strong. NTAV is only £21.3m
Net debt is £15.6m, ample headroom within a £45m facility. There is also scope to double the facility size (presumably for acquisitions, if needed). This looks a satisfactory gearing position, quite low actually versus EBITDA. The company points out that it owns 3 freehold sites, and has a blue chip receivables book. So no issues here to worry about.
My opinion - this seems a decent, well-managed group.
The track record is solid, as you can see;
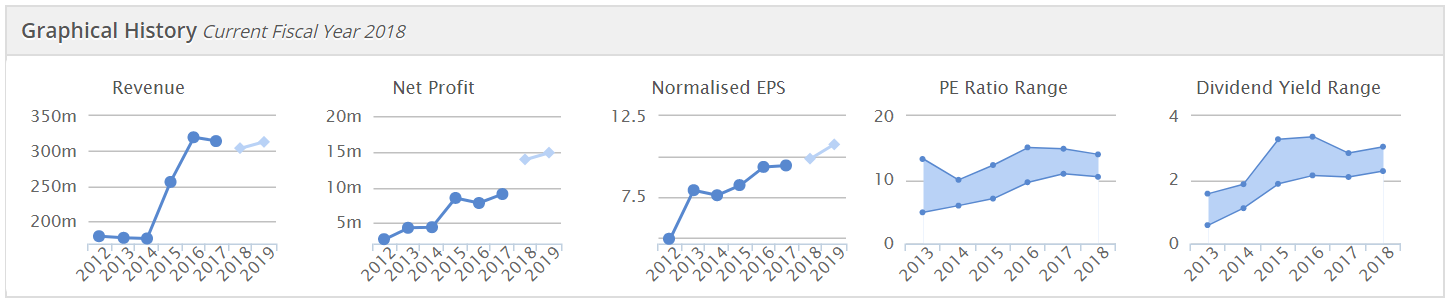
So if I wanted to park some money in an investment that gives a 2.9% dividend yield, and might go up in price a little bit, if I'm lucky, then this one could be worth considering.
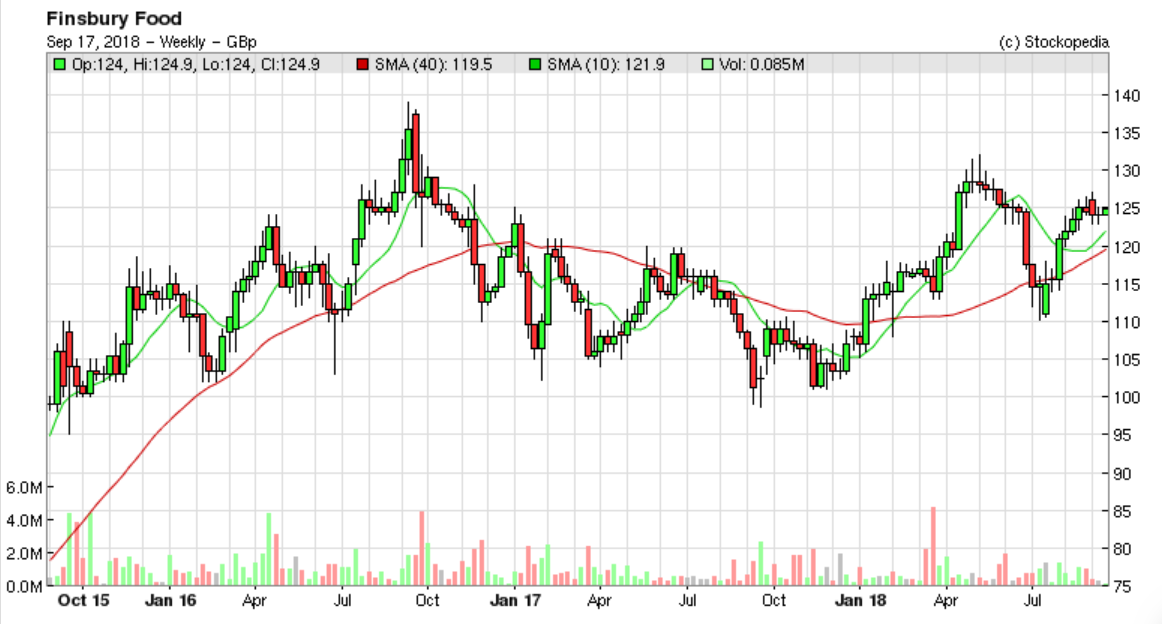
The 3-year chart below highlights the issue here - it's all a bit dull. The share price has just gone sideways, at a time when the stock market has presented numerous opportunities to make 100%+ gains on other shares. So that is an opportunity cost.
It seems a decent enough company, but personally I'm looking for shares which are a bit more exciting, and have more upside potential.
Christie (LON:CTG)
Share price: 136p (up 3.8% today, at 12:59)
No. shares: 26.5m
Market cap: £36.0m
Christie Group plc ('Christie' or the 'Group'), the leading provider of Professional Business Services and Stock & Inventory Systems & Services to the leisure, retail and care markets, is pleased to announce its Interim Results for the six months ended 30 June 2018.
I last reported on the impressive (big growth in profits) full year results from Christie here on 17 Apr 2018.
Interims published today show;
Outlook - the narrative mentions a solid pipeline, and;
In conclusion, the first half saw progress in performance while our services remain in demand from sophisticated commercial audiences. Looking at the second half we anticipate a more balanced year than 2017. With an increased pipeline of both current and ongoing projects we intend to deliver a solid set of results for the year.
I can't find any detailed forecasts, although Stockopedia has a figure of 13.3p EPS for 2018 - assuming that's correct, then the PER is 10.2, which strikes me as reasonable value.
Balance sheet - not great, which should be factored into the valuation.
NAV: £2,289k. Removing £1,843k in goodwill, and £1,370 other intangibles, gives;
NTAV: negative -£924k
Cash of £3,977k is more than offset by £692k + £6365k in borrowings, giving net debt of £3,080k
There's quite a large pension deficit of £12.0m
My opinion - it looks an OK company, although historically, results have been quite erratic. It seems to be humming along nicely now. Shareholders receive a modest dividend stream.
It's not clear to me why this share is listed on the stock market? It's very illiquid. Some time ago I tried to buy some, but there wasn't anything significant available.
I wonder if the stock-taking division might be affected by retailers moving to RFID tags in future?
There's nothing else of interest today, so I'll leave it there.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Tern, MJ Gleeson, and CLIG, are not the sort of things that I usually follow or report on. Sorry about that.
Hi Paul and welcome back (belatedly). OT is your twitter account OK? I cant access, though I have no trouble with others.
Hi cojode,
My Twitter account is set up so that all Tweets spontaneously combust within 24 hours.
It's much easier that way!
Regards, Paul.
Zzzzzzzz!?
Paul,
I know its not your area, so won't request it but thought I'd mention that I can't help but be impressed by the clarity of the results from City of London Investment (LON:CLIG) It's balance sheet looks fantastic and whilst it is obviously a geared play on both EM and general markets, I feel this update presents a very good excuse to continue holding. The likelihood of a special dividend has to grow over time, especially as I can't see such a well groomed CEO changing his approach to acquisitions. Furthermore, with the CEO moving to Chairman means I just can't believe that their general strategy will change too much with new leadership.
The natural concerns have to be continued weakness in inflows, sub benchmark performance and a possible further strengthening of GBP, along with fee income pressure. However, what's to stop a consolidator seeing value in the current operation, especially the cash rich balance sheet and relative 'cheapness' to other asset managers eg Ashmore along with the potential to extract significant cost savings. Their cost base could easily be reduced substantially by a bigger player.
If anyone has any thoughts on it, I would especially be most grateful to hear the bear case as I wonder if I am risk from falling a little in love.
Regards
Paul
City of London Investment (LON:CLIG) is a great company. I particularly love how transparent it is with regular updates outside of RNS announcements about its funds under management on its website. See here: https://www.citlon.com/investor-relations/funds-under-management.php
I guess the bear case at the moment is about the negative sentiment towards emerging markets. As they say today, only 18% of funds are for non-emerging market assets. But I see the July & August funds are holding up.
I've tended to buy into this share on dips and I've been wary of going back in recently due to emerging market sentiment plus it feels like the wrong part of the financial cycle to be buying investment management companies. It's trading around a p/e of 10 and a very good dividend so maybe a good time to buy back in? I don't hold currently.
I also quite like the company. I hold a small amount having bought in recently at 380p. The management team are well aligned with shareholders and they seem to communicate without any bluster or bravado. They are investors themselves, communicating to investors. Quite refreshing.
Another request for MJ Gleeson (LON:GLE) and Tern (LON:TERN) please. I hold both and at first look both sets of results seem more positive than I had expected.
Not a request for analysis, as £10m Mkt Cap is a bit too low(?) for SCVR, but any comments from holders/watchers would be appreciated. July 18 IPO, so nothing much to go on yet.
BigDish (LON:DISH) RNS - UK Launch and Fourth Quarter Strategy - "the company which operates a yield management platform for restaurants, is delighted to announce its beta launch in the UK today"
They're trialing 70 restaurants in Bath/Bristol to ensure App etc. works properly.
Migration of Table Pouncer to BigDish platform (seated 126,122 diners in Bournemouth in 2017)
Fourth quarter sets the stage for aggressive rollout across the UK in 2019, targeting up to 6,000 restaurants
This is on my watchlist, not so much as an investment (although a punt is possible), but to learn from - e.g. "I didn't think it would succeed - saved some cash.", or "Multi-bagged as I thought - retirement time! lol".
One concern is that one of the more established 'eating'-related companies muscle in, and with their larger presence, push BigDish into terminal decline. The other side of this is that they may view BigDish as a viable add-on and buy once more established/working.
This strikes me a another thing like purplebricks / justeat / airbnb / rightmove
This is introducing intermediation in the internet age when the idea was to disintermediate.
There will always be someone else who can do it (whatever that is cheaper)
The only defense is to
(a) get so much of the market you become the market (rightmove)
(b) create a new market (airbnb sort of )
(c) add value that is not easily replicated (stocko!)
'book via app' is easily replicated (as is purplebricks / justeat)
...so if it was my money it would stay in my pocket.
And yet you fail to mention that Just Eat (LON:JE.) which is just an intermediary platform, by your definition, has a market cap of £4.8bn now.
Can BigDish (LON:DISH) succeed? There are still many obstacles to a billion pound valuation, but potentially if the execution is right.
Based on my limited exposure to friends who are restaurant owners.
The problem with Just Eat (LON:JE.) and similar companies (intermediaries) is that the restaurants just don't want to use them because they make so little after the intermediary takes their "bite" (so to speak).
In fact, the owners I know, ask the driver to mention - Next time call us direct for 10% off instead of using (insert intermediary name). This has happened to me when ordering from a restaurant not associated with a friend. I just don't see this as good long term business sense.
As an addition, same said friends involved in the industry hate Groupon and always tell people to just come and ask for a discount next time (hows 25%). They use Groupon as a "marketing ploy" and actually usually make only a small return on the not included wet sales.
Limited experience, just sharing.
Another request for Christie (LON:CTG) please Paul. Great reading HY report under new Chairman. Refreshed website and it seems the various business segments are firing on all cylinders including International. Thanks!
Good morning Paul,
I wonder if you might have a look over Christie (LON:CTG) half-year report? An interesting transformation is afoot!
Thanks,
IG
Disclosure: I hold shares in Christie (LON:CTG)
Another vote for Gleeson....although i would be even happier if you looked at Inland Homes (results out Thursday) and did a comparison....similar sort of companies (strategic land specialists etc)....GLE focused on Midlands and North and INL south / south east.
@rbf post #7
I've got a comparison spreadsheet set up for Inland Homes (LON:INL) v MJ Gleeson (LON:GLE) and although it still needs some work, as it only compares P&L, Balance Sheet and Cashflow figures, but would be better comparing ratios. If I remember I'll see if I can put Inland Homes (LON:INL) figures in on Thursday and see if it's of any interest (don't mind a nudge if I forget ! lol).
Looking at last year Inland Homes (LON:INL) v this year MJ Gleeson (LON:GLE) on the P&L throws these margins up:
INL - 21.5% Gross - 29.0% Operating - 21.6% PBT
GLE - 33.2% Gross - 18.7% Operating - 18.7% PBT
So, although wild swings in the first two, the Profit Before Tax margins are quite close.
I do wish ALL companies adhered to EXACTLY the same wording and format/layout of their results. It would make life SO much easier ! lol
Morning Paul
I would appreciate your comments on MJ Gleeson (LON:GLE), time permitting please. Another good set of results, slightly ahead of forecast as far as I can tell. MJ Gleeson (LON:GLE) is a differentiated house builder, building low cost homes, primarily for first time buyers on brown field sites in the north of England. Average price £125,000. Very different from Berkeley Group (LON:BKG). The one obvious downside perhaps is that it is currently trading at a considerable premium to book value.
Cheers
Jonno
Morning Paul? Graham? everyone, Boohoo (LON:BOO) comment would be appreciated,
also £W7L half-year, Gross profit up 30.0% to £6.7 million* BUT Adjusted Profit from Operations of £2.8 million* in the half year (before exceptional Items, depreciation and amortisation costs - they made an acquisition) (H1 2017 £3.1 million) Net cash of £4.6 million at 30 June 2018 (30 June 2017: £2.5 million), Interim Dividend increased by 7% to 1.5p, international going well it would seem, but just 'in line' with mgt expectations.
Tern (LON:TERN) would be fun too (no position in either)
Good morning Paul!
Request for City of London Investment (LON:CLIG) if you have the time and interest.
Mark
My morning smallcap tweet:
Mirada (LON:MIRA), Imaginatik (LON:IMTK), Infrastructure India (LON:IIP), Realm Therapeutics (LON:RLM), Redt Energy (LON:RED)
Mirada (MIRA) will convert £3m loan into shares at 1p a 47% premium. 200% dilution. Ernesto Tinajero will become 87% owner.
Imaginatik (IMTK) Vin Murria grinds down possible offer to take control to 2p. Started at 2.5-5p in July.
Infrastructure India (IIP) tells buyer of subsidiary Indian Energy Limited for £4m to get lost after "an unduly protracted process and attempts by ReNew to seek to amend the agreed contractual terms."
Realm Therapeutics (RLM) will discontinue all drug development following poor trial results announced a month ago. Will "seek to maximize the value of our assets including the growing Vashe Wound care royalty stream and our FDA 510(k)-cleared anti-itch hydrogel." Co now in formal sale process. Cash, cash equivalents and short-term investments $21.3m. Cost cutting.
RedT Energy (RED) Conditional funding of €37m secured for the 700MWh portfolio of grid-scale energy storage projects in Germany (previously announced on 26 July 2018).
Re Mirada, with a magician’s wand Ernesto Tinajero is set to completely reverse the Free Float. Now 77%, soon to be 13%.
Paul,
Any chance you could please look at the H1 interims from warpaint £W7L?
Nice looking cosmetics company. International reach with large increase in exports to the EU and smaller to USA.
Nice dividend as well and net-cash,.
Nice comments about visibility of earnings as well.
This seems a well managed company overall with nice growth prospects and safe in terms of balance sheet.
You have owned swallowfield in the past, so interested in your comments.
Thanks!
By no means a small cap any more, but often discussed in these parts. Quite a big top level reorganisation at Boohoo (LON:BOO) board level with a new CEO being brought in from Primark and current CEO’s taking on different roles.
https://www.investegate.co.uk/boohoo-group-plc--boo-/rns/appointment-of-ceo-and-board-re-alignment/201809170700088962A/
Glass half full says it’s a good move bringing in experience to take the company onto the next stage, allowing founders to focus on being “creative”. Glass half empty suggests a major upheaval and disruption to stellar growth of recent years.
Gus.
Boohoo (LON:BOO) - Interesting. The pay package appears to be providing guidance that, given the current valuation and growth prospects, they expect future share price growth will be somewhere between 10 and 23%pa compound.
The incoming CEO will have a huge headwind achieving such share price growth in a prolonged bear market.
Incentive Plans should be relative, not absolute.
Not sure plans should be relative rather than absolute Howard, surely absolute payment plans are there to ensure the company doesn't pay out money it isn't earning, as much as anything else? Am in favour of longer plans though, 5-10 years to smooth out cyclical effects.
I sold out of Boohoo (LON:BOO) after the FT expose of conditions in the factories in Leicester. I seem to remember Paul doing the same.
My suspicion is that they have had to pay more to their suppliers resulting in a squeeze on their own margins, and will now be looking to increase foreign sourcing.
Disposable fashion has it's price.