Small Cap Value Report (Mon 18 Feb 2019) - Mello Trusts and Funds, MCLS, VCP, CLIG, ANG, CSSG

Good morning!
Mello Trusts & Funds
The first thing I wanted to do this morning was bring your attention to a new Mello event, to be held this year on the day before the main event in London. Mello Investment Trusts & Funds will be of interest not just to those of you who invest in funds, but also perhaps to those of you who invest in the fund management companies themselves. For example, I will be there to hear speakers from Polar Capital Holdings (LON:POLR) and Impax Asset Management (LON:IPX).
It's on Wednesday May 15th at the Clayton Hotel in Chiswick - convenient for Mello 2019 attendees, who only need to arrive one day early to attend.
PI World Interview
I was recently interviewed by Tamzin Freeman at PI World. We started out by discussing the initial steps that people take on the road to being experienced/professional investors, before moving on to discuss some of the things I've learned along the way and how my own strategy has evolved.
The video was published this morning - here's the link.
Right, let's take a look at today's news:
- McColl's Retail (LON:MCLS) - final results
- Victoria (LON:VCP) - trading update
- City of London Investment (LON:CLIG) - final results
- Angling Direct (LON:ANG) -trading update
- Croma Security Solutions (LON:CSSG) - trading update
McColl's Retail (LON:MCLS)
- Share price: 56.8p (+12%)
- No. of shares: 115 million
- Market cap: £65 million
McColl's Retail Group plc, the UK convenience retailer, ("McColl's" or "the Group") today announces its preliminary results for the 52 week period ended 25 November 2018, and a trading update for the 11 week period to 10 February 2019.
Strong share price reaction at McColl's today but we must remember that it's from a very low base - in the good times, it almost reached 300p (see my view when the share price was 280p).
The 2014 IPO was at 191p, so IPO investors are sitting on a 70% loss over 5 years, before we account for dividends.
Paul and I have provided mostly negative coverage, with Paul most recently saying: "I see nothing attractive about this share at all".
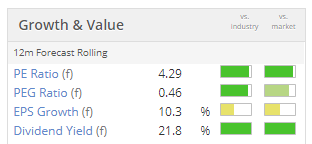
The Value numbers on Stocko (as of last night) signalled that the previous profit and dividend forecasts were unsustainable, with unrealistic metrics:
Let's take the key points from these results:
- Like-for-like sales still falling in FY 2018 but gradually improving throughout the year.
LfLs down 1.4% for the whole year, but had been down 2.7% in H1. Q4 was flat and Q1 FY 2019 LfLs are up 1.2% so far.
- Gross margin down by 80 basis points due to the "supply chain challenges" (supplier Palmer & Harvey going bust) and strong tobacco sales in the mix.
The reduction in gross margin comes despite the company's deliberate efforts to raise it by focusing on food and alcohol.
- Net debt down by over £40 million to £99 million.
- Final dividend is almost cancelled, as Paul predicted and as the unrealistic dividend yield suggested. Reduced to 0.6p from 6.9p last year. A sensible move to preserve the balance sheet.
Some reasons to think the future might be brighter and safer:
- 66 under-performing sites disposed (total portfolio is 1,550 stores).
- Increased comfort with new supplier Morrisons for 1,300 stores.
- banking terms revised.
- New CFO in position as of last month. He was previously CEO at Welcome Break (chain of motorway service stations).
Outlook: adjusted EBITDA for FY 2019 to be a "modest improvement" on FY 2018. Adjusted EBITDA for FY 2018 is £35 million, translating to PBT of £8 million.
My view
As I've said before, I continue to view this as a "no-moat business". Or in Paul's words, it gets pressure from all sides: from suppliers (who have to protect their own margin or else go bust, like P&H), from employee costs (National Living Wage, etc.) and from intense competition in grocery retail.
The company acknowledges that costs aren't going in any direction except up and that grocery will remain "intensely competitive".
Cost pressures are expected to intensify in 2019, with a further increase in wage rates, energy inflation and an increase in our annual rent following our sale and leaseback activity.
Besides the lack of a moat to protect it from all these pricing and competitive pressures, there is also the debt load to consider.
Net debt to EBITDA was 2.8x at the end of FY 2018, not far off the banking covenant of 3.0x.
The bank has agreed to raise the covenant to 3.25x for the test at the end of Q1. It will then reduce to 3x again for the rest of the year.
While McColl's should be able to pass these tests, it shows how strained the balance sheet has become that changing the covenants became necessary.
Situation vs suppliers: over the last two years, the company has generated a total of £125 million cash (pre-tax) from operations. This sounds impressive, but £89 million of this amount has come from its suppliers. Trade payable are now an enormous £213 million.
From the cash flow statement:
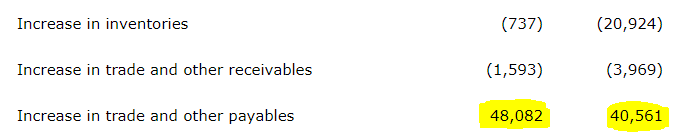
This is not a sustainable form of cash flow, so I would be cautious that operating cash flow over the past two years has been artificially influenced by this factor.
And while this is perhaps normal for a company in this sector, it creates a financial dependence on its suppliers. The latest current ratio for McColl's is only 0.67 (down from 0.75 last year), and trade and other payables are financing over 40% of the company's entire asset base (up from 35% last year).
The interest bill at the bank has also increased, and the coverage ratio (operating profit divided by finance costs) is now only 2x (down from 4x last year). This means that about half of operating profit was paid out in interest costs.
In conclusion, the company is walking a financial and operating tightrope with winds being blown at it by its bank, its suppliers, employees and competitors. It might pull through but I wouldn't be tempted to bet on it. I just don't think I'd ever be able to sleep soundly if this was in my portfolio.
Victoria (LON:VCP)
- Share price: 373.5p (-13.5%)
- No. of shares: 125 million
- Market cap: £468 million
This flooring company continues its return from the stratosphere, back to the small-cap territory where it arguably belongs.
Today's report confirms that it is continuing to pursue market share in difficult market conditions and at the expense of margins, despite this having unsettled some shareholders.
Financial outlook:
...the Group expects that the current-year to March 2019 EBITDA is likely to be £95m-£97 million (2018: £64.7m), with the Group's 2019 underlying pre-tax profits being around 35-39% higher than 2018 (2018: £40.8m).
For FY 2020, Victoria explains its plans to grow profits in each segment:
- UK & Europe hard flooring: integrating production facilities, administrative functions and procurement in Spain to add €5 - €5.5 million in pre-tax earnings. Another €6 million from owning a recent acquisition for the entire financial year.
- UK & Europe soft flooring: an additional £10 million boost from a new production line, logisitics efficiencies and eliminating >100 full-time employees.
- Australia: AUD $1.5 million in benefits from consolidation.
Cash generation: rather like the company discussed in the previous section, Victoria promises to reduce debt over the next 12 months. Stock levels at the latest acquisition will be reduced, so that it will tie up less capital and enable debt to be paid down (bringing efficiencies like this to its new companies has always been an important part of the investment thesis).
My view
I don't buy anything related to floor coverings any more, having seen too many disasters and having lost good money myself trying to participate in the sector.
There are also some company-specific reasons to be cautious about VCP, namely the massive debt load and the acquisition strategy which has worked out so far but which makes it somethng of a high-risk play.
Late last year, it attempted to issue €450 million in BB bonds, but had to abandon this attempt as the yield demanded by bond investors was too high. This helped to collapse the equity market's confidence in the shares, resulting in the following share price chart:
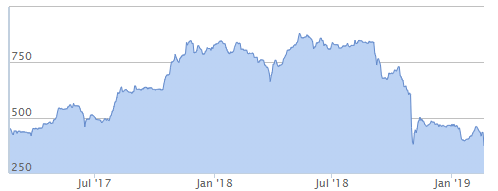
If bond investors weren't willing to finance the company at a reasonable price, it's a good sign to me that prospective equity investors should demand keen pricing, too (i.e. a lower share price).
The company's enterprise value based on the September 2018 debt load is in excess of £800 million, which represents a significant premium to its tangible assets (£520 million) but a discount to its entire asset base (tangible and intangible) of £1 billion.
This is very much a bet on the integrity and the ability of the Executive Chairman, who has been the singular driving force behind the company's strategy. Has he bitten off more than he can chew? Is the relentless pursuit of growth eventually going to come back and bite it? This is what we need to ask.
I can't predict how it's going to work out, but the company goes against several of my rules of thumb, i.e. to avoid:
- floor covering companies
- buy-and-build strategies
- debt-fueled strategies
- companies in non-financial industries being managed by former investment bankers
I'd be very pleased for shareholders if it does work out, but it's not something that I personally would want to own. If it ever issued high yield bonds, they would suit my risk tolerance much more than the equity!
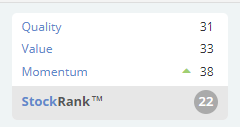
The StockRanks and I are in agreement in this instance, with Victoria being classified as a Sucker Stock:
The Altman Z-Score is also worth noting - according to Stockopedia:
Victoria has an Altman Z1 of 1.34 indicating a serious risk of financial distress within the next 2 years.
If you can believe the story and expect to see the creation of a sustainably profitable group of integrated business, I can see why it might be worth a small punt. Pricing is now much more attractive than it was a year ago, when the share price was around 850p. But betting big on this company seems to me like it would be asking for trouble.
City of London Investment (LON:CLIG)
- Share price: 396p (+3%)
- No. of shares: 27 million
- Market cap: £106 million
Half-year results and dividend declaration
City of London (LSE:CLIG) announces half year results for the six months to 31st December 2018.
This is a fund manger with a niche in emerging-market investment trusts (edit: thanks for the correction - it has nothing to do with City of London Investment Trust (LON:CTY) ).
Key points from today's update:
- Funds under management boosted in January 2019 back up to $5.1 billion, the same level as at the beginning of July 2018. The overall trend in calendar year 2018 was negative.
- H1 PBT is down 21% to £5.2 million.
Note that the broader markets were down 15%-16% in 2018. As such, most of the reduction in fund size and profits is due to market movements. There were also "marginal net outflows" and a reduction in fee margin contributing to the fall in profitability.
- Fund relative returns are mixed, with a small outperformance from CLIG's core strategy, but underperformance from other strategies.
- Interim dividend unchanged, special dividend of 13.5p declared on top. A nice explanation is given that the company agrees it should have a "use it or lose it" attitude to its cash pile!
Outlook statement - nothing too specific, but CLIG is confident that it will battle through the challenging conditions at present.
KPIs - the company is changing its key performance indicators. I wouldn't be a big fan of the previous or the new KPIs, as they are all based on CLIG's share price performance. But at least they do have a good long-term view: they want to compound their share price at 7.5% - 12.5% on a rolling 5-year basis.
Stock overhang - the retiring CEO, who has a 7.5% stake in the business, intends to sell 500,000 shares at each of 450p, 475p and 500p. This might depress the share price in the short and medium term until his share sales are cleared, but I wouldn't let it put me off investing in CLIG. Something similar (but in much larger size) is happening at Ashmore (LON:ASHM).
My view
I am interested in this share. As readers will know, I follow the fund manager stocks and like to keep an eye out for ones which have a niche and are well-managed.
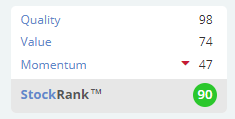
CLIG seems to fit the bill with an attractive long-term track record of profitability and high returns (ROCE is generally extremely high). It also has a StockRank of 90, with a forecast dividend yield of 7% and EB/EBITDA muliple of only 6.4x. Will keep reading about it.
From a timing point of view, sentiment is rather muted at the moment given the sell-offs in various equity indices, so it could also be a good way to bet on a rebound in global equity markets.
I've considered opening a starter position in it this morning. Unfortunately, the bid-offer spread is rather wide (>4%). This means I can't really open a starter position until I have enough conviction to make it a long-term hold. So I'll just keep an eye on it for now.
Angling Direct (LON:ANG)
- Share price: 72p (-1%)
- No. of shares: 64.6 million
- Market cap: £47 million
This is a pre-close update for the financial year ending January 2019.
Key points:
- like-for-like store sales are up 6.2%
- 3 new fishing stores opened
- online sales up 30%
- sales at its international websites almost doubled (from a low base).
Outlook - in line to meet its targets for the year.
My view - Good to see a company using its listing to raise money and expand. That is what the stock market is for, after all! It raised £20 million back in October, with the intention to nearly double its store portfolio and develop the roll-out of its international websites.
The October placing was at 92.5p. That makes for a nice discount at the current level, if you want to get involved.
But consensus forecasts suggest that the company will be loss-making this year. There is going to be some patience required to see it through to profitability.
Personally, while I don't hate the business by any means, I would have to be convinced that it is going to create a valuable customer franchise in order to seriously consider investing in it. It does talk today about positive signs in terms of customer loyalty and repeat business, which is encouraging. I will wish it good luck from the sidelines.
Croma Security Solutions (LON:CSSG)
- Share price: 97p (+9.5%)
- No. of shares: 16 million
- Market cap: £16 million
I mention this as a small but curious security play, that seems to be doing well for its clients.
Croma Vigilant, a security services division with over 1,200 security professionals on its books, is still trading at record levels despite the previous year benefiting from large one-off contracts which were not expected to repeat.
Croma Systems (CCTV, alarms and locks) is also experiencing "good demand".
The Strategy section stands out to me. I won't quote it in full here; essentially, Croma wants to become "the British homeland security brand". It will achieve this through:
- its differentiated, premium guarding services with an ex-military ethos.
- a national network of security centres to retail its products.
I don't normally get involved in support services, but I'd be open to the idea of backing a company that is doing things in a new way and is set to grow.This is a profitable dividend payer which I think deserves additional research.
Going to call it a day there, cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Graham, I am interested in how your positive view of fund managers contrasts with your view of other services businesses e.g. legal. Are these not people businesses too, where key individuals can walk away (like Neil Woodford). You like the high ROCE but the reason for the high ROCE is that the business model is capital light. It's the people that are the real assets.
Why invest in these companies when you regard other people businesses as uninvestable? I'm not saying that you're wrong, I would just like to know the answer.
Hi, good question - exposure to key man risk can be a significant risk at fund managers, so I would avoid (or pay less for) those which suffer that risk.
But the difference between fund managers are other "people" businesses is that fund managers are immensely scalable. The same number of personnel can manage £5 billion as £1 billion, depending on how it is structured. Once the platform has been built, you get incredible operational leverage.
This doesn't typically hold true for solicitors, accountants, etc. If you want revenues to increase 5x, you probably have to hire five times as many solicitors or accountants.
Graham, thanks, that's a good answer.
I would add though that there is a fair amount of evidence that these businesses are not scalable in the way that, say, a software platform is. You will no doubt be aware of the reasons, including the difficulty of deploying larger amounts of money in the small cap (or EM?) sectors and the difficulty in moving it quickly. I have often heard and read successful fund managers discussing the difficulties that success has brought. If performance deteriorates with scale then ultimately the business isn't scalable.
Hi Graham, would love to hear your views on @LON:SLP
They put out their half year report today and it was very good
re: Sylvania Platinum (LON:SLP)
I'm sorry but I don't cover resources. Hopefully there will be others who can provide you with insights on that front. G
Understand concerns over heavily indebted VCP, Graham - but there are good floor covering businesses, in particular in my view James Halstead. Lots of cash in the bank, excellent cash generation and straightforward accounting. Dividends increased every year for over 40 years!
re: James Halstead (LON:JHD)
Point taken, thank you!
Hi Graham,
Off today's topics, but I wanted to thank you again for your consistent commentary on Plus500 (LON:PLUS) which has been proven to be very insightful.
I had been in and out of this in the past, doing reasonably well, and admit to being sort of permanently tempted to buy back in again. But each time I nearly pushed the buy button, I would re-read your analysis and not bother. There's just no need to buy shares in a business which has (and always had) this much suspicion around it.
So thanks again; just in money saved on this one share, I owe you a beverage or two of your choice.
Chris
You're very welcome, Chris.
City of London Investment (LON:CLIG)
Thanks for the corrections, I have fixed it to say there is no link with City of London Investment Trust (LON:CTY).
Fantastic Video Graham.
I'm someone else who believes in Financials and insurance. Boring quality companies with no debt, grow slowly and pay good dividends. Never lose any sleep and when the price drops I just buy more.
GLA
I am a big fan of City of London Investment (LON:CLIG) so thanks for the writeup Graham. They are very transparent with their reporting and seem to be conservatively managed as a company. Anyone new to this share should take a look at this website page which highlights their monthly funds under management https://www.citlon.com/investor-relations/funds-under-management.php
This webpage indicates how their dividend is safe: https://www.citlon.com/investor-relations/dividend-cover.php They have so much cash in the bank that they can cover their dividend in any years where performance doesn't cover the dividend.
I don't hold at the moment as I would prefer to buy this share at a tiny bit lower than the current market price to factor in the risk of pound strengthening with a probable Brexit deal (I personally think MPs will back May's deal eventually so make my investment decisions on this basis) and nervousness about emerging markets.
I believe that City of London Investment Trust is managed by Janus Henderson. I looked into investing in City of London Investment briefly but was put off by this fact.
Note that City of London Investment Group (CLIG) has nothing to do with City of London Investment Trust (CTY).
City of London Investment (LON:CLIG) spread is always wide in morning and narrows by afternoon
I thought CLIT was managed by Janus Henderson?
Re PI World interview
Many thanks Graham for doing the interview with PI World. It was very interesting and insightful. In addition to learning about your investment criteria I found your no-sell (under normal circumstances) policy reassuring for my own situation. Whilst I don't actually have a no-sell policy myself, I am a reluctant and infrequent seller, and as such have felt a little out of sync with the apparent private investment community sentiment on this issue for some time.
If you are interested, my maximum market draw down on a single holding is 100%, which I think beats your 50% :)
fantastic look at the cash-flow and balance sheet for McColl's Retail (LON:MCLS)
so clear the dissection of the leverage and financing issues facing the company. Thanks for all the work on that, makes the company uninvestible IMHO, more importantly is the lesson in how to assess leverage, financing for other companies having similar difficulties
I agree an excellent review of the McColl's Retail (LON:MCLS) numbers, thanks Graham.
I take a slightly more optimistic view (although am not ready to be buying just yet).
Firstly, as I’ve mentioned before, I think there is a bit more of ‘moat’ than Graham recognises – in the form of the location of many of the stores and the extent to which they are embedded in their local community. (Although as has also been mentioned before this effectively mean that the landlords own the moat!)
Secondly, I think it’s important to understand just how disruptive the failure of P&H (their former wholesale supplier was) so I think there is a definite turnaround potential here.
However, the guidance that “we continue to expect adjusted EBITDA for FY19 to be a modest improvement on FY18.” Suggests to me that turnaround is a relatively long road.
Prior to this announcement the consensus view for 2019 (as per the stock report) was for a 15% improvement over 2018 – so ‘modest’ sounds like a downgrade on that expectation to me.
That said I am puzzled by the EPS forecasts shown :
Today’s results seem to me to be pretty much inline with what we were told at the last trading update. But based on the company’s numbers adjusted EPS came in at 6.7p however the forecast as per stock was 10.7p (and had been updated after the trading update in December).
Does anyone understand the mismatch in these numbers?
Profitability and Cashflow
Operating margins were a paltry 1.3%, but again recalling that this was a very disrupted year I would be looking for this to at least improve to nearer the 2.2% seen in 2017. I fully understand that such low operating margins, would immediately disqualify this as an investment for many people – however it is largely in the nature of the business (Op. margins for the big three supermarkets are in the range 2-3%)
It’s also certainly true that the impressive reduction in net debt is largely (in fact arguably more than all) down to one off factors.
The £46m improvement in working capital is all down to more generous payment terms from Morrisons compared with the previous supply deal with P&H and I would not expect any repeat of this.
There is also a c. £27m inflow from sale and leasebacks (with a smaller amount to come in 2019).
Cash flow from Ops before working capital movements was £21m (down on £41m the previous year)
The key “non-exceptional” items to come out of this were :
Tax : £5m
Interest : £8m
Dividends : £12m (but c. £4m pa going forwards at the revised payout rate)
Capex : £21m
With 59 store refreshes in 2018 and 20-30 expected for 2019 - capex will reduce somewhat. Guidance is for £15-18m pa with c. 45% of this being maintenance capex and c. 55% acquisitions, refreshes etc.
Overall therefore, they are cashflow negative (or at best close to breakeven) at this level of trading. However as per the view above that operating margins should improve in an un-disrupted year, I would also hope for the same from cashflow.
So at this stage I agree with the conclusion that it’s quite precarious financially and quite a high risk investment at this stage, but I will be watching for signs of improving underlying performance in a “clean” year.
I don’t believe that they routinely give a trading update before the half year results so I suspect the HY report in July will be the next material news (barring exceptionals)
EDIT : The results presentation is now online at https://www.mccollsplc.co.uk/media/1588/2018-preliminary-results-presentation.pdf
This does indeed give more guidance on the capex which I've added in above.
thanks for the detailed post
- I'm still concerned about profitability, there are a very large amount of adjustments. I'm keen to know how they expect a modest improvement in adjusted EBITDA when they acknowledge the expense headwinds (living wage, energy, new lease expenses) - with a smaller estate, D+A would also reduce, i believe that would also have a reductive impact on EBITDA if they are currently adding back a larger amount for D+A, perhaps it would only have a minor impact (say £2-3m)
- do you expect an undisrupted year? if brexit impacts the supply of fresh goods, alcohol and tobacco then this could be a major issue.
TNAV is c.(£100m) , does that concern you?
there is a half decent business in there somewhere, but my opinion is it is one that will struggle to grow and i'm not sure how they plan on improving the operating margin (i can see they want to do it, i'm just not convinced how)
Some very good points there mrosbiston re McColl's Retail (LON:MCLS) – one of the benefits of posting here is to get some intelligent “kicking of the tyres”. So I’ll return the compliment and give you my view on each point you raise.
Yes, although the net adjustment is quite modest (£0.8m), there some large negatives excluded that offset the £12m exceptional profit on sale and leasebacks.
Largely the adjustments look reasonable to me (relating to the supply disruption and transition and a couple of smaller historic issues) but there is one (actually two) that I would call out : £5.8m of cost for store closures and impairment. There will be an extent to which these costs (which amount to the lion’s share of adjusted profits in 2018) will be ongoing. This should be at a very much lower level but certainly something to keep an eye on in the next interims. In the short term there is also still some sale and leaseback to come in to offset these closure costs.
The first thing I think is that they will hopefully not see a primary supplier go belly up over a weekend again. You mention Brexit as a forward risk and I agree (although tend to be unconvinced by the most negative views) ; but even the worst possible Brexit outcome is surely a walk in the park compared to what they have just been through?
Nevertheless I’ll be happy to see the Brexit outcome before making any buy decision.
From a more helicopter view I would argue that the McColls business model is significantly less price elastic than the big supermarkets – so going back to my OP I would expect (unless management are useless) that Operating Margins above the 2-3% achieved by the supermarkets should be achievable rather than the recent impacted results that were below this level. Incidentally, you go on to talk about “the reduced estate” but actually my sense was that they are pruning unprofitable stores rather than downsizing, so I’m not sure I agree with the relevance of your further (otherwise valid) observations on the subject.
I don’t rule out an undisrupted year. However, I accept further disruption as a significant risk – one of the reasons that I am watching rather than buying at this time. Brexit is of course the great unknown for many businesses. But as I said above even a terrible Brexit outcome would imho be much less harmful than the events of 2018.
Not especially TBH. I differ from many (probably wiser heads) on the subject of balance sheets. Whilst I fully understand that ‘goodwill’ is entirely an accounting construct (based on the overpayment vs tangible assets on acquired companies) I don’t think it is entirely without meaning. There is a reason (good or bad) that acquisitions are made at above tangible book value – in the case of McColls acquisitions I would loosely characterise this as “location, location, location”. Those ‘intangibles’ have real value if they enable sustained ongoing earnings.
I would draw the comparison with PPE entries on balance sheets – which most balance sheet investors regard as more “real” – these assets most often can only justify their book value if they can be used to generated sustained earnings (their ‘scrap’ value is normally a small fraction of ‘book’).
I do however have a concern on the balance sheet and that would be the level of debt – they have had to relax the covenants in the short term to accommodate this which tells us they are walking a tightrope. As I indicated based on 2018 trading they are slightly cashflow negative which is highly risky for a highly indebted company, My two upsides against this are : 2018 was truly an exceptionally bad year (but I want to see that proved by better 2019 H1 numbers) and secondly that they have c. £10m of ‘discretionary’ capex that they can reign back on if debt coverage looks problematic.
If and when I invest , I won’t initially be relying on growth it will purely be a value/recovery play – which by itself could easily give a 100% upside imho. I don’t think the margin improvement is as challenging as you suggest if they can spend some time on refocusing on the strategy rather than firefighting supplier problems, but I’ll be looking for signs of this bearing fruit.
In terms of growth I tend to agree that they don’t look likely to shoot the lights out, but once they have overcome the current challenges there is an interesting potential prospect : they point out how much of the convenience market remains in private hands and IF they can acquire businesses and add value (which looks credible to me) then there could be a credible multi-year growth story – it’s not my focus at the moment but if I invest and the ‘reversion’ part of the investment case plays out I might start to look at this further.
Interestingly the forecasts on the stock report have been updated now and give a consensus view of 7.9p for 2019. That’s an 18% uplift on the 6.7p adjusted figure (as per the company) for 2018, this strikes me as a little ahead of the ‘modest’ improvement cited by the company.
As far as the stock report goes this is shown as a significant downgrade (against the 11.8p previously) which contributes to the momentum rank of ZERO. However, I think there is an anomaly here; as I mentioned in my OP prior to the results 2018 forecast EPS was shown as 10.7p (2019 was for 10% growth to 11.8) I don’t know what the anomaly was (although I note that Stocko shows normalised 2018 EPS of 9.4p which is too high.) Potentially therefore the forecasts have actually been upgraded (although it could just be that one of the forecasts contributing to consensus has not yet been corrected). So just to be clear, whilst I see reasons to be optimistic here, it’s much too early to call imho, so for me this is a watch and wait.
thanks for the comprehensive reply. will definitely keep an eye on the situation. i actually regard the extension of the covenants as a vote of confidence from senior creditors, they must also have faith in the turn-around plan.
one thing i would be interested in would be if management significantly increase their holdings and/or institutions start buying.
Thanks mr o,
Yes a fair point that the covenant change is a vote of confidence, but the need to do it is indicative of the tightrope they are walking.
Good point also about management or institutional buying, I'd been thinking more about wanting to see earnings momentum, but any such buying could indicate early optimism on that front and that could be a useful flag as we may not get a formal update prior to the HY results.
Although I would imagine that if director buying was going to happen it would have been immediately after the results - any buying later in the half year without a public trading update would be questionable imho.
Graham,
Superb dissection of McColls Retail - thank you.
Bonitabeach
Thanks bonita! G
Comprehensive half year report from Sylvania Platinum (LON:SLP) today. Looks positive but it needs an expert to comment usefully.
By co-incidence, I have decided to choose Sylvania Platinum (LON:SLP) for my presentation at the Stockslam on Wednesday night so will have done some further research by then.
I thinks notes of the presentation are put on this site after a few days.
And I'd be happy to post on this thread when I've completed as well.
Foot! Handy....easy to buy at just below 30 pence and now easy to sell at over 50p. JD Sports to the rescue again. Disclosure; sold half of mine for a nice profit so will see where we go.
Makes a number of these bombed out retailers of interest. Quiz next perhaps? Maybe....added some more today with the Foot cash.
Hope Paul S will look in on this news.
Hi Graham,
Would appreciate your thoughts following your meeting with Duke Royalty (LON:DUKE) last week.
Thanks in advance
Hi barney, I was hoping to have talked to DUKE by now but they rearranged the appointment for 28 Feb.
interesting announcement from Avingtrans (LON:AVG). £10M plus contract for its subsidiary Hayward Tyler to supply of critical components for nuclear reactor pumps in Sweden. Avingtrans (LON:AVG) seems to be gaining traction. I hold.
Interesting development today at Footasylum (LON:FOOT) this morning with JD Sports (LON:JD.) buying a sizeable chunk. This looks like it could be a very decent turnaround play now.
Thanks for the requests - I am planning to look at McColl's Retail (LON:MCLS), Victoria (LON:VCP) and City of London Investment (LON:CLIG), the others if time permits. G
Interesting results from Victoria (LON:VCP).
Change of strategy, but market doesn't like it - down 10%.
McColl's Retail (LON:MCLS) results are bang on from the profit warning they gave last time. The market cap seems really cheap, from experience some of the Co-op shops they have enjoy a bit of a local monopoly. I might have got involved but for the debts.
Interesting if small acquisition in France of Florin by specialist brick manufacturer Michelmersh Brick Holdings (LON:MBH) announced this morning.
https://www.investegate.co.uk/michelmersh-brick--mbh-/rns/acquisition-of-floren---cie/201902180700072891Q/
Only €9.9m against a market cap of £78m but gives them diversification into Europe and also comes with quite a substantial land bank underpinning the asset value. The acquisition they did of Carlton in 2017 was a success so there is form for picking up and integrating deals well. Also a non-underwritten placement of £5m at a negligible discount (0.6%) announced to fund part of the deal suggesting a pretty high level of confidence/respect for existing retail shareholder interests.
Gus.
Hi Graham - please could you look at City of London Investment (LON:CLIG) ? With US interest rates likely to remain stable or even fall in 2019 (and the dollar, therefore, likely to be weak) and with the potential for the trade war with China to be settled, does this represent an attractive entry point. The other unknown is how the company will fare after Barry Oliff's departure in December.
How about McColls (MCLS) Market Cap less than 60m. Dividend 4p. (was 10.3p last year)
Xpediator, (AIM: £XPD), a leading provider of freight management services across the UK and Europe, is pleased to confirm the Group has achieved its growth objectives and recorded significant increases in sales and profits for the twelve months to 31 December 2018 ("FY 2018") in line with market expectations.
· 54% increase in total revenues (unaudited) to approximately £179 million (2017: £116 million) generated by over 14,000 customers with no one customer accounting for more than 2% of revenues.
Acquisition led-growth, in 2018 Xpediator acquired two companies and Organic growth has been positive.
My morning smallcap tweet: Back from holiday
NB Distressed Debt Investment Fund (LON:NBDD), Realm Therapeutics (LON:RLM), Angling Direct (LON:ANG)
NB Distressed Debt (NBDD) sale of largest holding for $34m, may make a distribution.
Realm Therapeutics (RLM) Proposed disposal of hypochlorous acid assets for $10m or $9.6m net. Expect completion 28 March. Proposed adoption of an Investing Policy and delisting from AIM but retain Nasdaq listing. Realm had $18.8m cash and near cash at 31 Dec.
Angling Direct (ANG) Guides FY rev £42m up 39%. F/C £44m. Confident.