Small Cap Value Report (Mon 21 May 2018) - SEE, GTLY, GAN, SRC, ASY

Morning!
It's a little quiet on the newswires today. I shouldn't complain, as I'm just back from a very busy few days in London! Yesterday, I did some secret shopping at about half a dozen companies whose shares are of interest to me. A very interesting and worthwhile exercise, which I'll write about over the next couple of weeks.
Today's news includes:
- Seeing Machines (LON:SEE) - warning on sales. Share price -9%.
- Gateley Holdings (LON:GTLY) - trading update and proposed acquisition. Share price +5%.
- RM2 - annual results & open offer at 1p. Share price -14% at 1.375p.
- GAN (LON:GAN) - fundraising at 50p. Share price +5% (at nearly 70p!)
Seeing Machines (LON:SEE)
- Share price: 7.75p (-9%)
- No. of shares: 2240 million
- Market cap: £174 million
An unusual title for an RNS. Is this because of the company's Australian origins, I wonder?
Seeing Machines develops technology that can monitor humans, having particular applications in driver and pilot safety.
This is a warning on sales:
The Company has been informed by its manufacturer partner that, owing to a global shortage in traditionally short lead-time parts (capacitors and power supply) which are used in the Company's second-generation fleet product, Guardian Gen 2, production of a number of units that were due to be shipped shortly, will now be delayed by approximately six weeks.
Seeing Machines can't recognise the revenue for these units until they've been shipped to customers, so this revenue will now fall outside FY 2018 (ending in June).
Sales will be A$30 - A$35 million, instead of A$38 - A$43 million.
There has indeed been a general shortage in capacitors, so I'm inclined to think we can give Seeing Machines the benefit of the doubt as far as this particular profit warning is concerned - based on the information in front of me, I don't suspect that there is some other reason for the delay in revenue, other than the parts shortage.
Despite today's gap lower, the shares still sit at a premium compared to a week ago, thanks to the European Commission:
"Europe on the Move" will see all new cars, vans, trucks and buses sold in Europe fitted, as standard, with drowsiness and distraction monitoring, among 11 key safety features.
Seeing Machines' platform technology has the know-how to deliver real-time understanding of drivers and operators through tracking of heads, faces and eyes for DMS across multiple transport sectors to enhance safety.
Excellent news for Seeing Machines, since drowsiness and distraction monitoring is what it does!
The existing sales pipeline in the Fleet division remains large, at $200 million (this represents the value of contracts to be delivered over several years, it's not an annual sales figure).
I had a stab at valuing SEE in March. Drilling into the numbers, I reckoned that the underlying operating loss was much more modest than the reported losses. R&D and marketing costs, for the purpose of driving growth, were the major drag on results.
Having said that, the valuation is highly aggressive even if you ignore the company's losses and think only about its sales. Price to sales is perhaps about 9x (depends on which time period you use), for a serial diluter which has a track record of failing to hit forecasts:
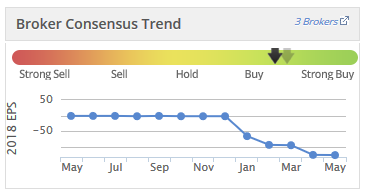
Stocko algorithms think it's a Momentum Trap and it's not something I'd want to own shares in, except perhaps with gambling money.
Gateley Holdings (LON:GTLY)
- Share price: 170p (+5.6%)
- No. of shares: 107 million
- Market cap: £182 million
Proposed Acquisition of GCL Solicitors
This was the UK's first publicly-listed commercial law firm.
The listing might seem to be a major achievement - and it is, in some sense - but why did commercial law firms never list before?
The most straightforward answer is that the public markets would never previously have been willing to pay more for the shares of a law firm, than those shares were worth in the hands of its partners.
It strikes me that a law firm should be owned by its partners and employees, not by outsiders. Can it really compete in the long-run if it has to pay dividends to public shareholders, in addition to salaries and bonuses, while its rivals only have to pay salaries and bonuses?
This is my simple reasoning as to why law firms, and people businesses in general, are best-suited for private ownership. For law firms, there might also have been a reluctance to face the scrutiny of the public which comes with a stock market listing.
Gateley listed in 2015 and IPO investors have done well so far, so what do I know? Maybe this will be the exception that proves the rule.
Today's trading update for the full year says that performance is in line with expectations. 70% of net income will be distributed as dividend, so shareholders are incentivised to continue holding.
Separately, the company's third acquisition has been agreed - a £4 million deal to buy a firm of solicitors which offers advice on land and property. This is line with the strategy given at IPO, to build a collection of legal and related professional services businesses.
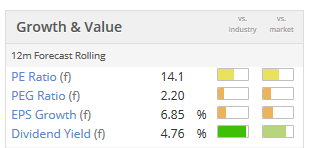
All of the metrics look reasonable and the StockRank is average. It's possible that I'm missing something, but I'm just not comfortable with the notion that firms of this type should be able to capitalise their value by selling to the public. As I was reminded by an astute comment this weekend, they fail an important investment test: scalability.
GAN (LON:GAN)
- Share price: 70.5p (+7%)
- No. of shares: 70 million
- Market cap: £49 million
I'm not familiar with this company but it struck me as an interesting piece of news after the recent bombshell announcement by the US Supreme Court, which means that US states are now free to make their own rules on sports betting.
Apparently, the black market in US sports betting is about 10x larger than the legal market, and much of this could be about to go legal.
Shares in the tiddler Webis Holding (LON:WEB) have been powering higher, and so have shares in GAN (LON:GAN). GAN ("Gameaccountnetwork") is a provider of technologies, platforms and games to online casinos.
Demand for GAN shares from traders is so high that the shares are up at 70p, even as the company raises £7.5 million at 50p.
GAN will be debt-free as a result, and:
The Company plans to use the net proceeds of the Subscription to substantially increase GAN's software engineering resources to better serve existing major US clients' services such as the WinStar.com Overseas Internet Casino, launch new US clients and new services in the US in anticipation of Internet sports betting following the US Supreme Court's decision to lift the Federal Ban on sports betting delivered on May 14, 2018.
The company has been unprofitable in recent years but perhaps it is going to turn the corner soon, with so much new opportunity? Worth investigating.
I have to go out now but will look at one or two other stocks when I get back - cheers.
EDIT: Back now, taking a look at Sigmaroc (LON:SRC) and Andrews Sykes (LON:ASY).
Sigmaroc (LON:SRC)
- Share price: 39p (+2%)
- No. of shares: 137 million
- Market cap: £53 million
This is a new one for me:
The principal activity of the Company is to make investments and/or acquire businesses and assets in the construction materials sector. The principal activity of the Group is production of high quality aggregates and supply of value-added construction materials.
It only arrived on AIM with its current strategy in August 2016, so perhaps that goes some way toward explaining why I haven't seen it before. We have never covered it in the SCVR.
It raised £50 million, most of it via a placing at 40p, and then made a large acquisition in the Channel Islands, in January 2017. Before that, it was just some sort of shell. Nearly all of 2017 revenues are from operations in the Channel Islands:
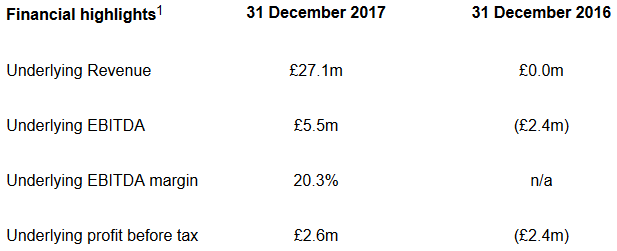
It made two acquisitions in the UK mainland concrete sector in H2, with the help of a further placing at 41p.
The CEO says: "...significant value creation at SigmaRoc lies with further consolidation of the fundamentally fragmented market of construction materials".
As I've said before in different contexts, investors shouldn't necessarily view a fragmented market as an opportunity - we have to ask ourselves why a market is fragmented in the first place, and then why should it change? What competitive advantage will allow this particular stock to grow market share, where everyone else has failed?
Pre-tax profit for SigmaRoc falls out at a modest £850k, after £1.7 million of non-underlying costs.
Here are the non-underlying costs:

Reasonable adjustments? Except for the share option expense, arguably yes. But the buy-and-build strategy is expensive, and I wager that we will see a lot more acquisition and restructuring expenses in the years ahead, as the strategy is pursued.
I'm not getting involved in any growth-by-acquisition strategies these days, so this one is not for me.
For those who would be willing to give this a second look, there is potential value emerging over the next year or two. The shares are trading at or below the level where money has been raised to fund the strategy, so you don't have to pay any premium to get involved at this level:

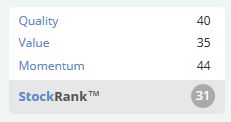
I'm neutral on this stock for now. The algorithms are more cautious:
Andrews Sykes (LON:ASY)
- Share price: 517.5p (+0.5%)
- No. of shares: 42.3 million
- Market cap: £219 million
I see that Andrews Sykes reported last year on 11 May. This year, it left it until 18 May.
It's not the only offender (not by a long shot), but this does introduce another risk element, for me, when a company is slow to report its results. Unless I have access to some other really good sources, it means that I'm almost certainly going to be at a big informational disadvantage, compared to others who might be trading the share.
This particular company issues on average about four RNS statements per annum. The last time it informed shareholders about how the company was doing was back in September. Nearly eight months without any sort of update!
To its credit, Andrews Sykes (LON:ASY) has been a super investment if you've been in it for at least a couple of years, so perhaps we can look past its relaxed reporting style?
It's a rental company, providing air control equipment: ventilation, pumping, heating, cooling etc. It's active in the UK, Western Europe and the Middle East.
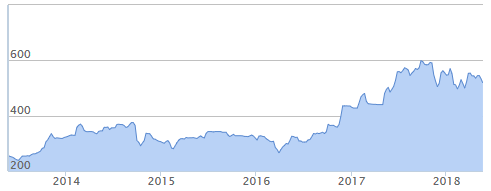
Companies which generate cash can often be very quiet in terms of RNS statements. Without any need to raise cash, they don't have any particular need for publicity:
Our policy of returning affordable dividends to shareholders continues and, over the last five financial years, the group has paid £47.8 million in cash to shareholders. This has not been at the expense of our other obligations; the group pays its external creditors in accordance with their agreed credit terms, it operates well within its banking covenants and has paid nearly £1 million into the defined benefit pension scheme during 2017 to eliminate the funding deficit of £0.7 million as at 31 December 2016.
The outlook is "cautiously optimistic":
The group continues to face both challenges and opportunities in all of its geographical markets but our business remains strong, cash generative and well developed, with positive net funds. The Board is therefore cautiously optimistic for further success in 2018, always being mindful of the favourable or adverse impact that the weather can have on our business.
Balance sheet is strong with equity of £53 million. You can even deduct all non-current assets (mostly PPE) and you are still left with NCAV (net current asset value) of £28 million.
This has several of the characteristics I like:
- Long history of operation (>150 years)
- Family business
- High returns on capital and cash generation
- Strong balance sheet
- "Boring" industry
The main drawbacks so far are:
- Slow reporting, as mentioned above.
- Tiny free float.
Only about 14% of the shares aren't owned by the family investment vehicle, leaving about £30 million of shares to trade amongst the general public.
The number of shares has gradually reduced, and Friday's statement mentioned the possibility of further buybacks. The Board is seeking the authority "to make market purchases of up to 12.5% of the ordinary share capital in issue" - that's nearly all of the free float, if the family isn't selling.
So I wonder if the shares will remain listed, or if the family would prefer to buy them all back?
My interest has been piqued. It's only the cancellation risk which would dissuade me from buying too many of this.
All done for today! Thanks for your suggestions.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
There was a lady Radio 4 Today the other morning (last week? I can't remember which day) talking about listed Law firms - she made the point that Partnered law firms don't provide good customer service and are expensive. For everyday legal matters listed firms, in her view, provide better service as they need to attract and retain everyday customers. Most people can't afford "Mr Fixit" hot shot lawyers kept on retainers, these people are the market for listed firms. Plenty of scope for perfectly good legal professionals to earn good money, the very best in demand ones will still be able to name their price as they have always done.
I might be using this term incorrectly as I am an idiot, but I think of it as commodification of access to legal services.
Yes, Nicola Foulston, CEO of Rosenblatt (unless there was another one!). A key feature of their offering will be Litigation Funding which they can manage in-house rather than through third party funders.
"Commodification of access" - the holy grail being sought is using AI to control the legal process, but I understand it's still at a very crude stage.
Re GTLY: Paul I think you are on the nail. The simple Maths is that law firms owned by partners pay all their profits to partners whilst those who are listed pay less profits to partners because they have to pay their shareholders. Why should good partners work for the latter when they can make more money at the former? Why did Gateley list? So the founding partners who are all 60ish could cash out. Good business but for me not a long term investment. KEYS is a much more interesting investment in my view and much more scalable - a platform for freelance lawyers to service clients and cross refer. That may be the law firm of the future.
re Gateley - "Why would a law firm float?" In this particular case ... to reward staff more equitably than is usually done in LLPs, and recruit and retain newcomers. How? via share options. Also, to allow expansion into related areas (ie. not other law firms) and get a more flexible balance sheet. (LLPs can't borrow except secured against property.)
So GTLY was an pretty good investment for me, but on balance I sold recently because of a couple of niggles. First, I'm scared of the existinging economic situation which will lead to recession; GTLY is particularly focussed on the construction industry so, second, because its level of receivables is a bit scary, and some are, I think, distressed. Maybe the flipside of a flexible balance sheet?
There are now three other law firms quoted on AIM. Each has its own USP and they are all interesting.
Having run into capacitor shortages two cycles ago, it is not a sign of bad planning but a serious global issue which may limit global growth esp.in phone technology.
Seeing Machines (LON:SEE) - just seen a demo of a generic technology that can monitor driver behavior using a well known cloud provider's tooling.
I personally don't see a competitive wall being built here and would recommend potential investors do a lot of research about the possibilities of iot for anything that relies on sensors. I know little about driver monitoring and it may be the case the generic doesn't meet regulatory requirements or may have other technical issues.
Happy to hear contrarian views :)
Disclosure, no position in Seeing Machines (LON:SEE) but I work for and hold stock of a well known cloud provider.
Spot on, IGotPoesJacket. OK, Seeing Machines (LON:SEE) may have a first mover advantage but the technological risk is that someone builds a better, cheaper mousetrap. A bright app developer with a true-depth vcsel enabled phone should be able to build a functional DMS system for the mass market. Obviously Seeing Machines (LON:SEE) have a head start in analysing head and eye movements to predict dozing off but AI should enable others to catch up. I may be mistaken but seem to remember Seeing Machine's original offering being a clunky head-worn hearing aid type device, so there's been considerable progress in just a few years and probably more to come.
Not related to any of today's stocks but I know a lot of you are interested in UK retail. I see there is an episode of "The trouble with" covering M&S this Thursday on Channel 5 at 9pm.
http://www.channel5.com/show/the-trouble-with/
Hi Graham, last Friday Paul said he would cover Andrews Sykes (LON:ASY) but then seemed to run out of time. If you have chance could you please circle round and provide your view on their results?
Taking a quick look at Andrews Sykes (LON:ASY) now, cheers. G
Many thanks for covering Andrews Sykes (LON:ASY) Graham, it has been very profitable for me in recent times although the free float is an area of concern, but for a small part of my portfolio it is a risk I'm prepared to take.
Also thanks for covering Sigmaroc (LON:SRC), I added it to my watch list a few months ago to see how their story develops.
Hello Wildshot,
Like you I have been a long term holder of Andrews Sykes and I have been pondering the effect of the recent blisteringly hot weather on the company's air conditioning business. Of course Andrews Sykes provides precious few updates on RNS but I just came across this on their blog dated 26.7.18.
"Despite unprecedented levels of enquiries and orders, Andrews Air Conditioning have taken steps to ensure supply continues to outstrip the incredible demand by ordering additional units – and these are now ready for immediate hire."
I like the "unprecedented levels of orders and enquiries bit" and I must admit that sounds almost share price sensistive info to me, although it refers to only part of their business. I have topped up my holding as I reckon the next lot of results are going to be excellent but the spread is awfully large so I would not encourage anyone else unless they are prepared to hold for the long term. Let's hope I am right.
I think that's the lowest free float I've seen.
Does that worry you?
Phil
I notice that the Carluccio's CVA statement shows that there has been minimal refurbishment of their sites and that this will be addressed (up to £250k per site) only if the CVA is approved. Demonstrates that all previously announced 'profits' were overstated.
Would like to see comments on the gambling industry after the USA Supreme Court decision which in effect allows each state to consider internet and sports betting.
Micro cap WEB, which I have held for yonks, today hit an 8 fold since the above news was released. Note that well known billionaire investor Jim Mellon owns 63% of the equity.
GAN today placed at 50p ...I had to pay 68p today to add......and that really has strengthened the balance sheet.
This is a potential huge market...50 billion dollars to 400 billion dollars per year has been suggested ....and every time a US state passes legislation that allows sports betting etc. affected stocks are likely to rise.
I don't understand much about the implications.....will spread betting on shares and bonds and currency be allowed? I just know I have to be in this sector.
Seeing Machines (LON:SEE) Looking at previous outlook statement the revenue expected seems to be quite a bit more than 6 weeks Fleet revenue loss. hey are suggesting A8m less, but 6 weeks Fleet loss would be about A3.4m.
So it seems to me that on top of this manufacturing issue, they are hiding some addition revenue shortfall.
I sold out this morning as despite the massive potential here, it's had a good run without the fundamentals fully justifying that.
Very hard to judge timing with these type of stocks, but can see results giving this a knock, and the price falling back.
Also Fleet is the part of the business which is supposed to help them get through to the auto cash cow element.
This news isn't great in that regard, and difficult to catch up, due to the slow nature Fleet is rolled out.
Whilst they can win big Fleet contracts they take an average of 18 months to 2years to roll out and see the full benefit. They don't need further delays.
I suspect there is now a risk for a further funding round down the line
Lee
Good morning Graham.
Please can you comment on this mornings full year results from Sigmaroc ?
Hi, I might get around to Sigmaroc (LON:SRC) a bit later, cheers. G
I think it is essential that Seeing Machines (LON:SEE) get their supply chain and in particular component reliability sorted out. I recall Sprue Aegis (LON:SPRP) had issues with faulty batteries (from an external supplier) a couple of years back, leading to the first leg down in their continuing share price fall. It wasn’t so much the value of the warranty contingent liability claims that seemed to do the damage but the hit to their reputation for reliability. You don’t really appreciate something like a smoke alarm day to day until it decides not to work and there’s a fire. I think getting it right will be more important in the long term then trying for a quick but potentially unreliable fix just to protect one accounting periods revenues.
Gus.
Gus,
Not sure why you are painting Seeing Machines (LON:SEE) with the Sprue Aegis (LON:SPRP) brush.
Seeing Machines having a six week delay in shipping an order is hardly in the same ball park as the Sprue issues. Why do you refer to their component reliability?
Component availability is very tight across the industry so I see no reason to disbelieve their explanation.
I'm not a holder of either.
Hi John.
I was picking up on the comment in leoleo’s post #4 first * bullet point about the delay being attributed to the delay in sourcing relatively low value component parts which can be subject to varying quality. In both cases with Sprue Aegis (LON:SPRP) and Seeing Machines (LON:SEE) there is the potential risk of the more complex composite whole being undermined by the weakness of a particular component. No position in either company either.
Gus.
Graham,
I would appreciate a quick look at Seeing Machines (LON:SEE) who made RNS statements both on Friday and again today. I realise it is rather early stage, but even a quick numbers sanity check would be welcome.
I've already commented on their Friday statement. Today we have a FY to 30 June 2018 revenue warning which will presumably also translate into larger losses.
I have researched and the claimed component shortage does appear to have some basis in reality - here is a fairly definitive-looking article specifically mentioning automotive: https://epsnews.com/2017/10/19/component-shortages-to-last-longer-than-expected/ , and another more recent speculating shortages to 2020: https://www.ttiinc.com/content/ttiinc/en/resources/marketeye/categories/passives/me-zogbi-20180302.html . As you can see this is far from a new situation.
My knowledge in this area is fairly limited, however my understanding is that:
* These are generally cheap commodity parts where the price could multiply in price and still make a small contribution to costs and will never run out. However quality can vary enormously and that for embedded automotive systems in particular cannot be compromised. For add-on systems like their fleet product there is perhaps more scope to let a certain proportion fail and be replaced under warranty, but this may cause reputational issues in an industry where high reliability is expected.
* Some specialist parts can indeed have limited supply that can be quickly exhausted and then have long lead times. However I'm not sure they are talking about such things.
* Designs can generally be made (or changed) to avoid specialist parts and to work with cheaper (wider tolerance) parts, perhaps at the expense of cost and/or size and/or power consumption. However changing designs may be harder in automotive as validation requirements may be higher and even more so if EU type-approval is concerned - this is a flip side of their "moat".
On balance I would say that the issue is due to a combination of low prioritisation, bad planning and poor designs from their manufacturers more than an unavoidable externality. It will cause some reputational damage as well as financial impact, but not as severe as if reliability was affected by substituting inferior components (although there is some danger they are doing that too). Most of all it is concerning that they are reporting the issue so late in their financial year when the industry shortage has been going on too long. I think they need to find an alternative / second manufacturer sooner rather than later which will reduce benefits of scale and increase costs.
(As DMS becomes more common and certainly if it becomes mandatory OEMs will require second-sourcing of product and if Seeing Machines (LON:SEE) don't do it for them then the OEMs will be looking for a second SEE-level supplier turning them into a commodity supplier. This screw-up can only bring that day forward.
There may be read-across to XP Power (LON:XPP) (not necessarily net-negative), and if this doesn't materialise it would underline that this is an issue that Seeing Machines (LON:SEE) and their manufacturer could have avoided.)
Edit: I hold, but a very small amount.
re: Seeing Machines (LON:SEE)
Excellent comment Leo, cheers. Yes, I researched that issue this morning too and founds lots of commentary on a general capacitor shortage. So I trust that this is the real issue facing SEE. But could they have avoided it? Good point. G
Good morning Graham. Seeing Machines (LON:SEE) have reported a large order being pushed back 6 weeks from one financial year into the other due to manufacturer constraints. I am unconcerned by this and will continue to hold, which means the price will probably be down 90% by lunchtime. I know you'll hate it as a blue-sky penny stock but Paul used to hold and yours or any reader thoughts are welcome (given the EU's commitment to DMS in new autos, I hold).
Hi RTJ, Seeing Machines (LON:SEE) is now included... thank you for the good suggestion. G
My morning smallcap tweet:
Toople (LON:TOOP), £RM2, Omega Diagnostics (LON:ODX), Cyanconnode Holdings (LON:CYAN), Seeing Machines (LON:SEE)
Toople (TOOP) Tiny telecoms tinpot Toople wins contract worth at least £360k over 2 yrs.
RM2 International (RM2) FY and 1.15 to 1 open offer at 1p, a 37% disc. Unusually the key investors who participated in the March placing and the Directors will not be allowed to participate in the Open Offer. FY rev $6.6m ($8.9m). Huge loss.
Omega Diagnostics (ODX) VISITECT CD4 development update - "results from feasibility testing show acceptable performance against design goals and accordingly, the Company has progressed into a formal optimisation phase within its design control programme." 'Acceptable performance'? Sounds like an old banger scraping through an MoT.
Cyanconnode (CYAN) FY and $3.2m order from India. FY highlights begins with "Order book increases during the period, Board and management team streamlined and strengthened etc etc". Poor financials coming! Rev £1.17m (£1.82m) due to delay in deployment of a large customer contract (as previously RNSed). Pretax -£11.1m (-£7.9m). "We continue to work on securing additional funding that will be required during 2018...We remain passionate about our ability to turn opportunities into revenue." Passionate! Desperate is more on the mark to stem the huge losses.
Seeing Machines Ltd (SEE) Warns FY rev A$8 less than guided due to mfr delay of Guardian Gen 2. Blames global shortage in traditionally short lead-time parts (capacitors and power supply) ie their subcontractor didn't order them early enough.
Morning Graham.
You’ve previously commented on the troubled RM2 pallets specialist. Details of the expected open offer published this morning.
https://www.investegate.co.uk/rm2-international-sa--rm2-/rns/launch-of-open-offer/201805210700206485O/
Looks a complete basket case heading lemming like for the edge of the cliff.
Gus.
Hi Gus,
Yes, I'm unlikely to write in any detail about RM again. Bargepole stock for me.
Hi Graham,
I appreciate your words on £RM2 will be brief, but I was surprised by the following sentence in today's RNS:
"Furthermore, in order to maximise the number of Open Offer Shares available under the Open Offer for qualifying shareholders, the key investors who participated in the Placing, and the Directors, will not be allowed to participate in the Open Offer."
Unless there is a better reason, I see this as providing the directors a prime excuse for not taking part in this further fund-raising.
Hi Graham,
One of those occasions where name confusion is a risk. I was relieved to discover on working my way back to the top of the thread that your reference to "RM" was to £RM2 and not to RM (LON:RM.), which I hold.
Stopped me in my tracks at first.
David.
Whoops -sorry.