Small Cap Value Report (Mon 26 Sept 2022) - PDG, MMAG, DEVO, SAAS, CNC

Good morning from Paul & Graham.
The big news continues to be sterling's rapid descent, with it having been given another kicking overnight, now down to £1 = $1.057 (at 07:01) . It will certainly be interesting to see how this pans out - no predictions from me, I'll leave that to others! Oh well apart from the obvious - that more takeover bids from the USA, for UK companies, are now looking likely, and UK companies with dollar earnings should hold up OK. That's all I can come up with at this time of the day. Let's have a coffee first.
Podcast - I'm relentlessly pressing on with my weekly audio recaps and macro commentary, no matter how bad things get. Episode 13 went up on Sunday lunchtime. It's available on podcast platforms (search for "Paul Scott small caps"), or using the link at the start of this paragraph. I've introduced a new mystery shares section, with a bespoke jingle, to hold back each week's best ideas just for Stockopedia subscribers, following some complaints about me giving away too much free content to the internet, that you lovely people are paying for, so point taken on that. About 500 people are tuning in each week, so it's well worth doing, I feel.
Mello is back! 5pm tonight, plus another show on Thursday looking at company results. Good news, as long as we have wifi, we can watch from our bunkers or under the kitchen table! More details here. We need to support things like this in the tough times, otherwise they may not be around when the good times return.
Agenda -
Paul's Section:
Pendragon (LON:PDG) - its largest shareholder has revived a previous bid approach, slightly higher, at 29p this time. The board are considering it. With huge property assets, sector consolidation looks highly likely.
Musicmagpie (LON:MMAG) - another profit warning. I've reported negatively on this recycler of mobile phones before. It now looks uninvestable to me, given profits have evaporated, and bank debt is set to increase. Definitely one to avoid, in my view.
Graham's Section:
Devolver Digital (LON:DEVO) (£354m) - this is an independent video game designer and publisher that floated on AIM back in November 2021. The game titles it released in H1 2022 have performed badly and today’s H1 results are financially very poor. On the more positive side, game titles being released in H2 have received good reviews and this should be a much better six-month period for the company. Overall, I’m not too impressed with this stock as a potential investment, although it does at least have a large cash balance, giving it plenty of runway ($74m), and the price to sales multiple is now sitting at a very modest level.
Microlise (LON:SAAS) (£178m) - another float from 2021, this company provides hardware, software and professional services related to transportation management. Unfortunately, I’m struggling to find reasons that might justify the current market cap. Growth is very modest and profit margins have deteriorated, suggesting to me that its professional services work is low-margin and the hardware/software solutions are replicable by competitors. Therefore, to me, this stock looks ripe for a de-rating.
Concurrent Technologies (LON:CNC) (£54m) (-12%) [no section below] - this is “a world leading specialist in high-end embedded computer products for critical applications”. Unfortunately, the ongoing supply chain issues have delayed shipments, and in turn delayed the company’s revenues that would otherwise have fallen in H1. Paul noted this overhanging problem affecting Concurrent’s prospects for the current year back in May. It has come to fruition with H1 revenues down 20%, a reduced gross margin (again due to problems acquiring components) and a fall down to breakeven in terms of profitability. Unusually for the company, it will not pay an interim dividend.
The company still has zero debt and a cash balance of £9.3m, and it states that the delayed shipping “is a short-term issue and in no way relates to the quality of the underlying business”. They are “well positioned for material growth as the situation resolves”. Valuation here looks reasonable: if the company recovers as it promises it will, there could be some medium-term upside. I’m neutral.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Pendragon (LON:PDG)
22.7p (pre market open)
Market cap £317m
Receipt of Unsolicited Proposal
The Board of Pendragon announces that, on 21 September 2022, it received an unsolicited, preliminary and highly conditional proposal from Hedin Mobility Group AB ("Hedin Group") regarding a possible cash offer for the entire issued and to be issued share capital of Pendragon at 29 pence per share (the "Proposal").
The Board of Pendragon is currently considering the Proposal together with its financial and legal advisers. Shareholders are urged to take no action at this time.
Auto Retail Agenda magazine says this morning that Hedin previously offered 28p for Pendragon, and then blocked a 29p approach from another bidder.
This sector is ripe for consolidation, as we’ve been saying here for ages. It would be a pity to see these companies taken out for a pittance, in a downturn. But ultimately, if the stock market undervalues companies in the short term, then bidders spot the opportunity.
This approach at 29p is a 28% premium to Friday's closing price - not madly exciting, but maybe in a bear market, shareholders might be happy to grab the cash and reinvest it in something cheaper without a bid premium in the price?
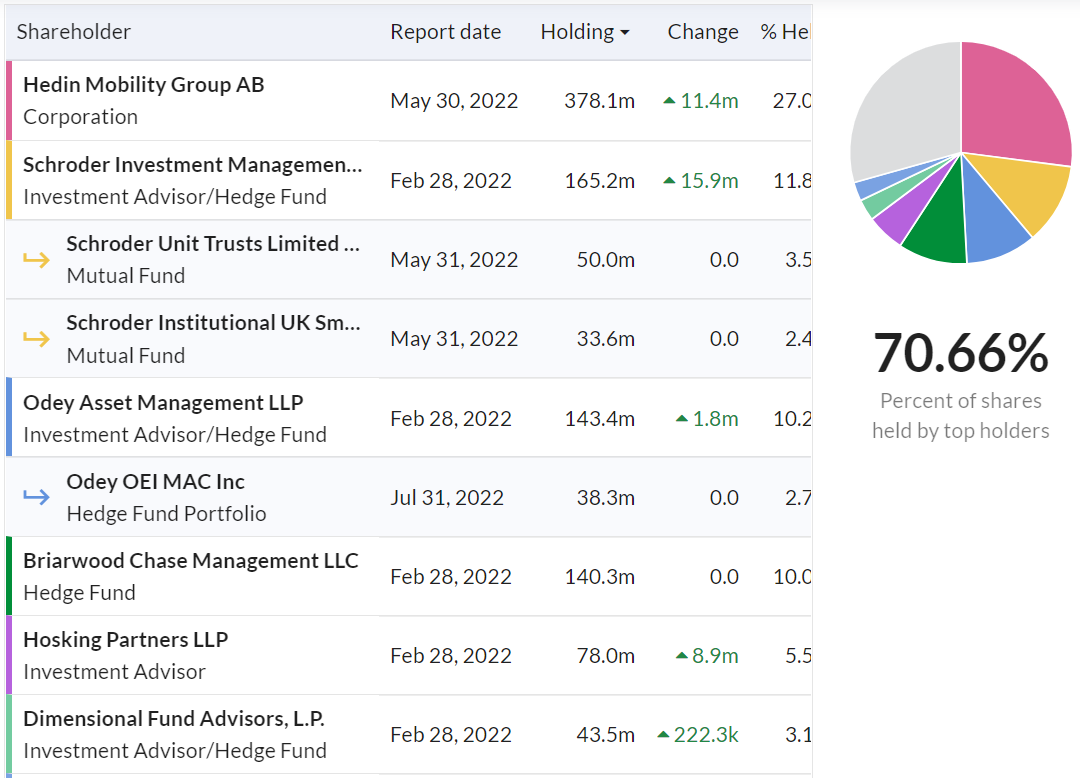
The shareholder register at Pendragon is concentrated, with Hedin already owning 27%. So it only needs to convince 3 or 4 fund managers, to make this deal likely to go ahead. Let's see what happens.
.
Musicmagpie (LON:MMAG)
15p (down 45% at 08:15)
Market cap £16m
musicMagpie, a circular economy pioneer specialising in refurbished consumer technology in both the UK and US, announces an update on current trading and outlook.
The outlook has worsened, as a result -
Whilst it still expects that second half profitability will be a substantial improvement on the first half, the performance of Consumer Technology (which represents around two thirds of Group revenue) has been weaker than anticipated and margin pressures have persisted…
Accordingly, the Group now expects that revenue generated in the second half will show lower growth over the first half than previously expected and that profitability for the year to 30 November 2022 will be below its previous expectations and those of the market.
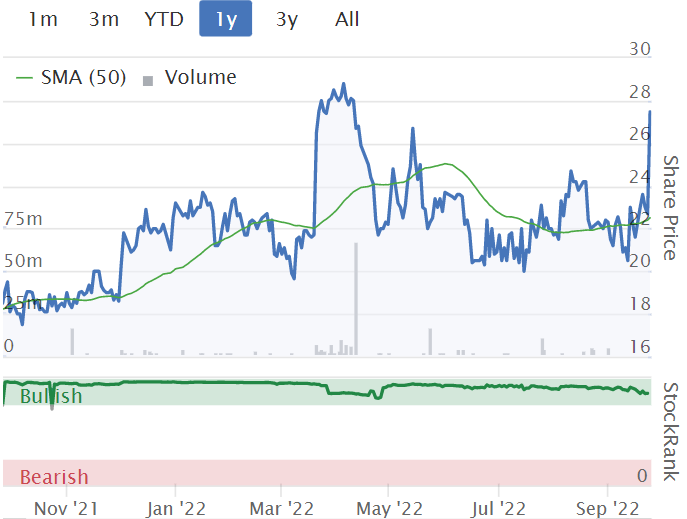
Revised forecasts - the above leaves us in the dark, but Shore Capital helps out considerably with updated numbers. It’s grim - FY 11/2022 was expected to make an adj PBT of £3.4m. That’s now gone, and replaced with a small loss of £(0.3)m. Continued losses are expected for the next 2 years after that.
Forecasts also seem to show increasing net debt, fuelling a big rise in fixed assets, which looks to be related to this -
A new £30m committed revolving credit facility was entered into on 26 July 2022 to allow the Group to continue to invest in the rental offering and the SMARTdrop kiosk roll-out with ASDA, which remains on track to complete by the end of the financial year.
My opinion - this is now the third time I’ve looked at this disastrous recent float. Here on 2 Mar 2022, I covered its profit warning, and thought it looked expensive at 119p. Then on 29 July 2022 I thought it needed to halve from the then price of 44p.
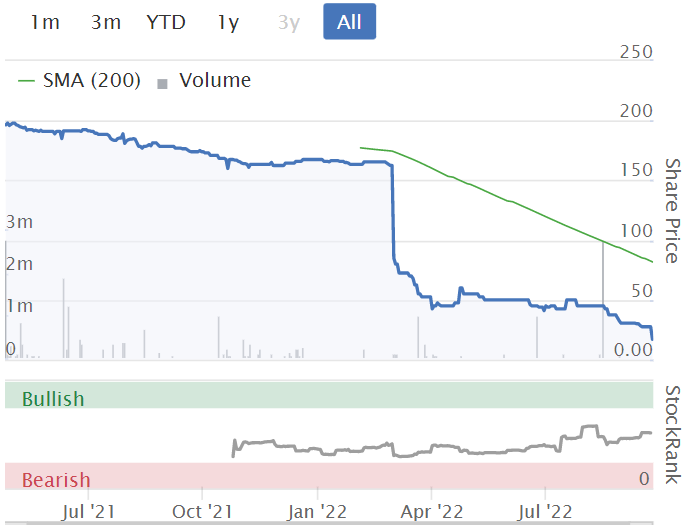
So is it cheap now at 15p? Given that profitability has gone, then I question whether the equity is actually worth anything?
With debt expected to spiral, as it rolls out some kiosks in ASDA, and seems to be up-front funding rental phones for its clients, this looks a really bad business model. It looks to me as if the IPO was selling a pup to the fund managers.
So it’s uninvestable now, I feel.
Graham’s Section:
Devolver Digital (LON:DEVO)
Share price: 80p (-2.4%)
Market cap: £354m ($382m)
We’ve never covered this one before in the SCVR: it’s an independent (“indie”) video game publisher and developer.
Described as “the biggest US firm to trade on AIM”, the Texas-based company joined the market in November of last year at an IPO price of 157p. The admission RNS is here.
Key facts about the IPO:
- Managed by Zeus Capital.
- £191m was raised but this was mostly (£154m) for the purposes of letting existing shareholders out, not raising funds for the company.
- The IPO was said to be “oversubscribed” but the initial valuation (just shy of £700m) was much lower than the £1bn that the company was originally thinking about.
So it’s fair to say that the IPO was not particularly promising for potential shareholders.
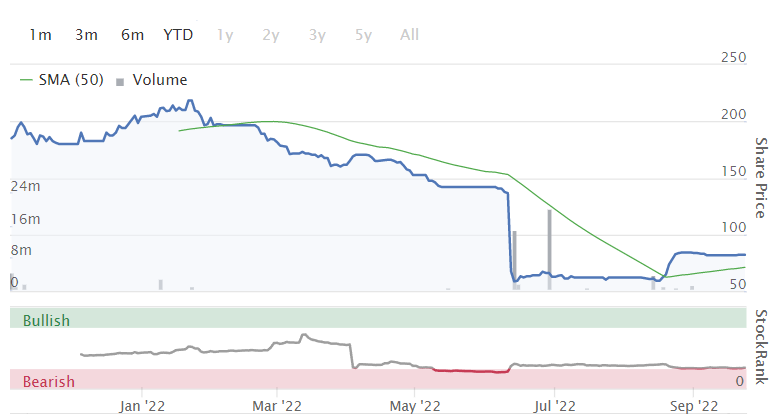
And sure enough, the share price has collapsed by almost 50% in less than a year, and the market cap is now only around £350m:
People might find it strange that I am able to so confidently assert that IPOs - in general - are bad investments. Aside from the logic behind the statement, I also have firsthand experience of this from when I worked for an institutional investor. An IPO causes Wall Street (or the City) to bring out all of its marketing machinery, to apply maximum pressure, and to make whatever promises are necessary to get people to invest. It’s one of the biggest paydays for bankers, and they will do whatever it takes to get people to take part.
Shares on the receiving end of such immense marketing efforts are almost inevitably overpriced. How could they not be? There are exceptions, of course!
Anyway, let’s dig into these interim results for H1 2022, and see if the company might now offer some value at this level:
- H1 revenues +14% to $53m.
- “Normalised adjusted EBITDA” (yuk!) down 46% to $6.8m, “reflecting underperformance of 1H releases, and increased administrative and headcount costs”.
- Net loss of $16.6m.
- Cash balance $74m.
Let’s skip ahead to the outlook:
- Guidance maintained for 2022
- Full-year revenues $130m - $140m, adjusted EBITDA $27m - $32m
- 12 new titles this year, of which five are being published in H2. I note that good feedback has already been posted for two of them on the review website IGN (here and here).
- Over 30 titles in the pipeline for the next three years (i.e. ten per year, on average).
In addition to all the new titles, there is a back catalogue of 97 games which “continue to perform strongly”. It’s sometimes easy to forget about the long tail of income received by video games publishers, for titles that were released several years ago. Devolver says that some games released in 2021 “continue to perform like newly-released titles in 2022”.
Covid: I figured that the Covid situation was good for the video game industry, for obvious reasons (people spending more time at home). But strangely, Devolver suggests that the end of Covid restrictions is positive for it:
The second quarter of 2022 saw the relaxation of Covid controls and a normalisation in travel, meaning we were able to meet again with our colleagues, partners and game-developers, gamers, influencers, and everyone involved in the complex game-production ecosystem. This has made an enormous difference in terms of ensuring the quality and positioning of our games.
This resumption of normal activities has released great pent-up enthusiasm for Devolver's games. At Pax East held in Boston in April there was a two-hour queue for gamers to try out the demo of Cult of the Lamb, our recent new game release.
My view
I have mixed feelings about this one. I want indie games publishers to do well, in the same way that I want independent film studios to do well. But I’m unclear as to the investment merits of this one.
For H1 2022, its first six-month period as a listed company, Devolver has made a gross profit of $18m and incurred administrative expenses of $30m. So there’s a pretty wide gap to catch up on, to recover to profitability.
The new titles released in H1 performed poorly, which the company attributed to “a competitive release window and specific factors for each title which are being actively addressed for future titles”. The H2 games, judging off their reviews, should do better.
One thing that does bother me is the company’s focus on EBITDA. By emphasising this metric, they are asking investors to look past the cost of making games, as development costs are capitalised and then amortised over time (the “A” in EBITDA).
Devolver’s cash balance fell by $12m in H1, despite positive adjusted EBITDA, for this reason. As the saying goes, “you can’t eat EBITDA”.
I’m happy to keep this on my radar and monitor its progress, but for now I agree with the StockRanks, which suggest that this is one to avoid:
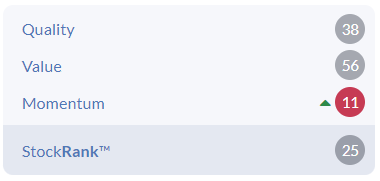
After stripping out the large cash balance from the company’s market cap, the price to sales multiple for the current year is only around 2.2x - 2.4x. At least the stock is not too expensive by this metric, giving it some speculative merit. But it still has a lot to prove.
Microlise (LON:SAAS)
Share price: 153.5p (unch.)
Market cap: £178m
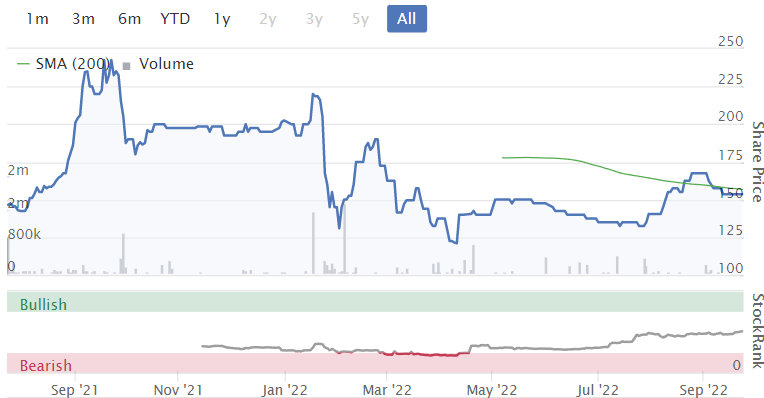
This is another stock with a short history on AIM: it joined the market in July 2021, at 135p per share. Paul gave it an initial once-over in January.
It has done ok: no collapse below 135p yet.
Based in Nottingham, it is “a leading provider of transport management software to fleet operators”.
Here is its website, where you’ll get a more detailed explanation of how it “automates and optimises critical processes such as scheduling, routing, driver performance monitoring and resource allocation, while providing valuable, actionable real-time data”.
And here are the H1 financial highlights:
- Revenue +5% to £30.7m (of which recurring revenue is about £20m)
- Gross profit £18.4m - gross profit margin of 60%
- Operating profit down 6% to £1.7m - operating profit margin much more modest at 5.5%.
- Cash balance £15.8m
Operationally, the company sounds like it had a busy six months. 60 new customers were signed up, and there were renewals and extensions to contracts with major supermarket chains including Tesco and Asda. Overall, however, the growth rate in subscriptions was nothing to write home about, at just 3%.
One interesting and positive feature at Microlise is the lack of any customer churn. It is reported today at just 0.1%.
Outlook - in line with expectations.
Balance sheet - the company has balance sheet equity of £73m, but this includes intangible assets of £75m, mostly allocated to goodwill. Tangible equity is therefore negative.
My view - like Paul, I’m reluctant to spend excessive amounts of time on this one, as I’m not seeing much to like. Given the lack of current profitability (relative to the market cap), and the empty balance sheet, I want to see high revenue growth, or at least fat profit margins. Something.
I wonder if the company has any unique, proprietary IP that potential competitors can’t match? Or is the software and hardware easily replicable, and this is the reason its profit margins are so limited? I’m looking for an investment thesis and unfortunately I can’t find one here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Good evening all ,
It seems that the boys are back in town:
PS. To those who haven’t realised , I am talking about Hostmore plc.
Still confused, Yiannos. What exactly is going on at Hostmore (LON:MORE) that you think we should already be aware of? ... Haven't a clue.
Afternoon all,
Anyone want to talk about Gulf Marine Services (LON:GMS) ? It's a bit of a special situation / value share. It rents out specialised vessels to oil companies in the Middle East on day rates, for varying charter lengths. They are coming out of longer-term charters on cheap rates, with new management, hoping to obtain higher rates (possibly of shorter duration), in a more positive business environment (for them).
Today's market cap is £60.5m, but has USD341m of debt, at the half year. Sales of USD115m last full year, hopefully about USD120m-USD150m this year, going on the half year revenue increase announced today.
They have profit after tax for H1 of USD13.1m. Not sure how that annualises as last year is marred by losses. They are forecasting USD70m-80m of EBITDA for the full year, and are intent on using it to deleverage. Assuming significant deleveraging, the rating on the shares (currently PER of less than 3), should raise significantly, although it's unlikely to happen for the next year or two (or just until the next bull market).
There is a lot of history, and the above is a very brief snapshot. The fly in the ointment, caused by the massive historic debt, is that a condition of their bank facilities is by the end of 2022 they are likely to have to do one of either:
They say it is more likely than not at the minute that it would be option 2, but won't commit. Presumably no one wants to try and raise that much equity in the current markets.
I am trying to work out the precise effects of the equity/warrants issue, and can't really, but on balance it still looks like good risk/reward to me, unless client demand collapses and they'll pretty much certainly go bust. I think that looks unlikely.
Anyone have any better opinions?
Thanks
Chris
Yes I have.
A plc with a market cap of £50m loaded with a debt of $350m is just a silly gamble for any serious investor. Sooner or later the creditors will take control of the company , and when they do you will be left with almost nothing.
Thanks Berksbee and Yiannos. As Yiannos points out, I'm clearly not a serious investor :)
The debt was loaded up by a previous board, who have since departed, so the mistakes are being rectified by new management and major shareholders.
Like I said, a special situation, and I realise the risks. There's a clear route to major deleveraging, at which point it could be worth a lot more (although there's the one minor point as to what has happened to the world economy at that point).
Cheers
Chris
I believe Paul Scott is an investor. Always assumed he was serious!
Chris, for my sins I hold, but not much and am in the black. I cant see the demand for Middle Eastern Oil collapsing anytime soon, even with a quick resolution to the Ukraine situation. I agree its a good risk reward but still something of a gamble if that makes sense.
I hold. Key for me is if day rates increase significantly cos operational leverage should see most drop to bottom line. Slightly disappointing that not increasing much so far so looks like slow burn but today's update still in line. Customer concentration is high. ADNOC (Abu Dhabi National Oil Co) are their biggest client & they recently bought their biggest competitor in Middle East (Zakheer Marine) to take offshore vessel services in house. I'm bit worried that ADNOC may use GMS alot less going forward. Basic investment thesis is this is classic cyclical play - years of underinvestment in upstream O & G and cycle is now turning. Fingers crossed but recession would throw major spanner in works as oil demand would likely reduce. Only smallish position for me cos risk of wipe out is high. Quite complicated set up : debt mountain, potential dilution, banks in driving seat & role of one of major shareholders - Seafox International. They tried to buy out company on cheap last year and failed but still have big say at board level, current CEO is their man, and who knows what they might do - let fall into admin and do a Mike Ashley ? I can't say that I fully understand what's going on with this co or is likely to happen in future bit I invested partly cos I'm quite intrigued by the story and how it will play out.
Here is the full programme for the Mello show tonight...
5.00 pm Company presentation by The Property Franchise Group
5.30 pm Karin Schulte presents investing educational content
5.45 pm Company presentation by DSW Capital
6.25 pm Steve Clapham goes Behind the Balance Sheet
6.45 pm Company presentation by RBG
7.15 pm Company presentation by Plant Health Care
7.55 pm Mello BASH with Kevin Taylor and Mark Simpson
If you would like a half price ticket, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/753448
Afternoon Paul,
The podcast is great so please keep it up! :)
I don't think you're giving too much info away. I'd personally prefer it if you just said the companies and details. Otherwise, I find myself having to take notes to go back into the reports (I usually listen on the tube or while walking where it's not easy to read the SCVR).
Your reports on Stockopedia are far more detailed than what you can provide on the podcast, so we're getting fantastic value here already. Ignore the complaints and do what you feel is best :).
Cheers,
Kieran
Timing of results.
Hi Paul, Graham, I know you guys talk to lots of small cap CEOs who understandably want to promote their story to investors and I have a suggestion for them. Why not release your results on a quiet news day? All too often they all turn up like the proverbial buses.
An example is LON:BYOT - I hold. They put a ton of effort into a results webinar last week , which I thought was excellent btw. The trouble is it was on a very busy day. Didn't get a mention of Stocko.
I am happy to do a quick write up on BYOT should anyone so desire just don't expect P&G standards!
It's a good idea, but humans pack animals and tend to come to similar decisions based on common factors. So, the results days are aligned based on things like, holidays, disinclination to have a heavy day on a Monday or Friday, even random stuff like, is there a big football match on. Means everyone tends to be busy at the same time, is also why things like almanacs and data science (how Tesco already know when next year's busy barbecue days will be).
Hi Paul,
I know others have commented on your podcast but I just wanted to say how useful I am finding it. I found this weeks macro economic commentary especially useful. I also like the fact that you let the time fit the topic rather than the topic fit the time.
Remember "fortunes are made in bear markets"
Obviously doesn't seem to be the case as everything is getting dragged down but I think with ongoing portfolio maintenance it is best to pretty much stay in the market ,
Ive just gone through my holdings and dumped several, especially the ones that Im just not passionate about or don't fully understand and various minor historic positions that are just "noise"
Saga - sold out just doesn't float my boat, big polluter and you need a big brain like Pauls to work through their numbers. I like simple and that I can understand ,
Hostmore - sold the last dregs clearly a basket case now .
Also reduced on a few winners especially Bank of Georgia / BP / Gulf keystone as they aren't offering any IHT cover and I was out of cash so wanted a buffer to move into the ones I like ,
Have rotated that into a big chunk of Equals which is getting hammered today, probably Crystal Amber dumping their last 2% so increased significantly.
I recently opened an account with them to check functionality and performance and it works well though interestingly we get better rates from our existing currency brokers moneycorp so we haven't yet traded with Equals.
Also topped up one Hargreaves which is a no brainer at these levels and Vertu which just slides and slides. Has to get taken over at these prices .
Gresham house energy storage looks good and has sold off, just waiting to hear if it gives IHT cover though dont think it does.
Also building a speculative position in Titon holdings which is very illiquid with a big spread but those clever guys at Rockwood are backing it, its pretty much fully backed up by assets and is the leading UK manufacture of some window ventilation that is about to become required as law to fit to all UK doors so thats the upside story . Still got to fully understand all this at Titon but it made sense at the time and that Richard Staveley of Rockwood is sharp as a blade .
Other than that Avingtrans , Crestchic, Holders, Bloomsbury, Somero, Belvoir, Croma, Hargreaves, Sureserve, Wynnstay are all happy holds and if any capitulate will increase unless the story changes .
I no longer get stressed by the down days (weeks) but took a long time to get to this mentality
PS - I would be avoiding at all costs any companies importing from Far East as GBP v USD is going to obliterate margins except in the ones that can pass on.
Hi Planetx
When you say Hargreaves do you mean "Services" or Lansdown?
---
There probably isn't much read across to Belvoir (LON:BLV) (which we both hold), but if it's of interest I listened to this podcast episode from the MD of Foxtons (from August 17th, 2022.)
https://open.spotify.com/episo...
He commented that they had just had 3 record lettings weeks in a row. I thought the market might be cooling down by now, but clearly not.
There was also a worrying comment that completions were taking so long that some mortgage deals were expiring.
Of course many will not be able to get mortgage deals at the same rates as 6 months ago, so I wonder if this will be another driver behind a fall in transaction levels?
---
On Somero Enterprises (LON:SOM) (which we also both hold) I listened to the recent piworld interview and noted that whilst demand for their equipment was still very high in the States, there was a big problem sourcing concrete, which was delaying projects - a possible short term concern.
---
Thank you for taking the time to share your thoughts.
A
Agree, the use of the ticker is most apprpriate.
There is a shortage of rental property as many landlords are leaving the market due to Osborn's Clause 24 tax. Hence shortage of properties = too many people chasing the same product = higher prices.
Belvoir (LON:BLV) Foxtons (LON:FOXT)
Hi Marigold
Yes, I understand that prices are higher, but I thought volumes would be lower, and therefore overall lettings revenues might drop.
The comment by Peter Cowgill (Foxtons MD) in the podcast episode implied that there were either record volumes or record revenues in August 2022 (he wasn't clear which).
Because of my expectations for low volumes, this comment surprised me.
A
Gilts yields keep surging this morning. 5yr at 4.54% and 10yr at 4.12%.
This is getting to scary territory now. The bar for investing in shares is now much higher when you can get a guaranteed 4.5% with a 5-year no-risk (well, maybe low-risk) bond.
And even if you don't want the faff of bonds, I presume soon, 2-year fixed savings accounts will be yielding 4.5%+. You can already get some 4% at the moment, but many providers are yet to catch up and release their new rates following last week.
Is it "no risk" though Boon? Sterling seems to be saying there is considerable risk in the UK.
Exactly. It is no longer considered by the market to be risk-free.
IMO over a 5 year horizon, we should still get full debt servicing by the UK Govt. But of course, getting the interest and principal in sterling while the currency devalues massively doesn't help...
But unfortunately, I've set my investment universe for my ISA and SIPP to be UK shares (I have another pot of money/investments for overseas), so somewhat the alternative is either keeping it in GBP cash, or GBP bonds.
So if the decision is between UK shares, gilts, or cash... I'm now not as convinced that the former is the preferred option for me anymore, as it has been over the last few years.
The risk for bonds of course is inflation. 4.5% may sound appealing but still well below inflation, so negative real return. At least equities should provide inflation protection over the long term (apart from those with very little pricing power).
Yes but inflation is unlikely to persist at current levels for 5 years or more - if it does we are in deep trouble!
Paul I would be very interested in your comments about the Results today from Next Fifteen Communications (LON:NFC) in the light of your comments on M&C Saatchi (LON:SAA) on 20th May.
It now looks as if Next Fifteen Communications (LON:NFC) are confident the deal will go through.
The numbers from NFC do look very good. I know the Market Cap is above your limit but it is the Take Over situation which is so intriguing.
On the topic of podcasts, the Moneyweek podcast is well worth a listen this week, has an excellent conversation about the macro situation.
"An AA survey of 12,500 drivers showed that rising domestic energy prices are putting many people off from switching to an electric car."
eParo - Big surprise and so what – this is close to the anti-EV PR spam that conspiracy lovers put out to create fear, uncertainty and doubt.
Mostly non-EV users who are not really in the market for EVs at the moment, hear that a fuel source they don’t use for their existing car has gone up and are less inclined to make a major investment in switching formats to it in a cost-of-living crisis. Shock, horror.
I think we will see ALL new car switching go down at the moment, irrespective of fuel type. Also, given where we are on the innovation curve for EVs (still only a few % of total vehicle fleet), there is little point in asking the mass market their view – especially as small, cheap EVs that they will buy are only just coming on the market.
And Trio “I suspect my 17 year old diesel van will be far cheaper to run than a new EV.”
Of course your 17yr old vehicle may be cheaper for now if (as I hope) it is fully depreciated and running well. That’s why I keep my old petrol car. However, a better apples-to-apples comparison would be : if I buy/lease an electric van including all costs (depreciation, maintenance, fuel, financing etc) which is cheaper – in yr 1 and over a full capital cycle.
On that basis, I think electric vans will already be cheaper and falling in cost – that why Amazon, the Royal Mail and all the big fleets are going electric not ESG. Many 1 van (& car) owners who thought broadly and added the cost of solar+ battery set up to their “van purchase” cost calculation are doing the same if they can. EV adoption is increasingly a cash upfront CAPEX and education issue.
But secondly, rather than debate EV’s, let’s ask what has this to do with small cap investing blog?
On a day Paul has written a post about an offer for Pendragon and sector consolidation is this a related view. If so, what? Are you suggesting this is evidence we should be less excited about EV supply chain companies promoting their exposure to chargers like Volex?
EVs always derail us - as COVID did before - from sharing investment comments or if we do we should try to to link them back to the purpose of this SCVR. With the pound tanking and lots happening economically, we should be leveraging the collective wisdom on that.
Disc - 8yr old petrol car/pedal bike user, who is pro electrification incl EVs but who has added little value to the SCVR by this post today.
I did not get a driving license until I was 22. Very impressed by your maturity :)
Sooner or later Road Tax (or will it be Road Toll?) is bound to make an appearance on the EV stage which will change everything,
Why will it "change everything"?
Petrol and diesel cars already pay per mile through fuel duty. Like everything, personal transportation has a cost which people will bear, if it becomes too great, they'll seek the next best alternative. The govt, through tax and spend, can move the balance however it wants. It can price people off the road, or price people onto it. Pricing people off the road comes with electoral consequences, so is unlikely to happen.
I was talking about EV.
Right, my comment is about EVs. Paying per mile is nothing new - if you look at car reviews you'll often see "cost per mile" figure. Nothing changes, people are prepared to pay a discrete amount for personal transportation. Nothing changes in that equation just because the fuel source changes.
Hi Zipmanpeter
This is a good post, as it is getting us to think beyond the headlines.
Obviously there are a percentage of the population who see a new iPhone has been released and have to buy it, and there feels to be a larger percentage who are now coming to the end of their 2 or 3 year deals at £30-50/month and starting to think do I want to do that or do I get a deal for SIM only with Tesco for £10 for 12 months and see what happens? For example.
My wife and I, are thinking that we are likely to go for an electric on our next car, currently we have a 64 plate petrol and 15 plate diesel both at about 70k and seem to be doing ok. But we will make the final choice when we get there (e.g. breaks down and is "how much???" to repair) on both what we feel is ethically the right thing to do, as well as a full financial assessment. We are not at the point where we can say yes lets spend £50k on ethical grounds alone. We know we are unusual in that, or rather I am.
We are similarly looking at solar panels currently, waiting for a second quotation to come through. We had thought for a long time, but a 15+ year payback it was not at the top of our priorities, now this is coming down towards 10 years and I am assuming now that there will be partial recovery on sale now, whereas talking to the local agent previously people saw them as a liability not an asset in our area.
So I do hold Volex (LON:VLX) (starter position not quite broken checkpoint sell down but close), I do not currently own any car dealerships.
There is a debate about the energy source, we all assume EV is green, as I talked through with my girls, before it ended we paid for a 100% renewable deal, but I pointed out our supply was just as likely to come from the local nuclear power station, as the localish offshore wind farm, or somewhere else entirely. We were paying more to encourage investment and use of renewable sources, and felt that price differential was something we could and should afford ethically. Similar what is the energy consumption and rare earth metal requirements just for building the car, the politics on the sources and ownership but that is more complex debate again.
Overall what we really need is a reduction in consumption by the entire planet, not what an investor would normally say, but that is where my personal lifestyle choices have been heading in the last 10 years.
Cheers
Tommy
ps. I cycle too, that is a 10 year old Giant Hybrid.
Good post Tommy. Have to say though I wish people would just get on and embrace renewables. Best investment I have made was Solar Panels in 2009, coupled with a ground heat pump. Bit of a kerfuffle putting it in but getting over 55p index linked per kw/hr and regular payments for GHP offset price ages ago. Appreciate this is because Govt were trying to attract people in but I remember reading utter crud from Papers telling me do no good whatsoever towards environment. Actually makes hell of a difference. For 6 months a year I am totally carbon neutral. Anyway got that off my chest!!
Number of companies with slightly negative outcomes this morning Gulf Marine, Musicmagpie and Concurrent Technologies appearing on my screens immediately. I suppose the one which interests me most is Concurrent Technologies. They are placing the blame almost entirely on problems with getting supplies in, arguing it is a short term issue and they are stacked with orders. As I like the company this should be an opportunity to buy and yet something is holding me back. Sure Macro isn't great, I would like to know a bit more about what supplies in particular and whether these are going to improve. Should do but it was an issue they were having at last report so sounds like they can only get them from a limited supplier(s). Anyway be interested to hear your thoughts Paul. Loved the podcast!!
I agree with you ref Concurrent Technologies (LON:CNC) as semi conductor shortages have supposed to have been improving over the last few months.
Lost confidence in this one over the short to medium term. Will see what the next RNS is saying.
Hopefully this is a capitulation low in the pound this morning. It can only be hope though and I don’t really have a view. The currency has essentially been a release valve for poor economic governance of late. From $1.40 last year to skirting with parity now… that’s a big move.
The BOE (and ECB) are hiking rates far more slowly than the Fed, despite UK (and Eurozone) inflation being higher than US inflation. The central bank isn’t being strong enough on the monetary side, while the government is adding huge fiscal stimulus to the fire. I’m told that is a classic mistake which has been repeated in decades past…
The currency has no choice but to decline. Hopefully this move is a one-off step-change, rather than a continuing trend. As for inflation, we are clearly now relying wholly on good luck and external factors to bring it down. Needless to say, currency devaluation is itself inflationary, especially for a net importer on the scale of the UK. This decade may indeed be very different to the last.
Thanks for the podcast Paul, its good stuff and much appreciated. Its highly recommended if anybody here hasn't listened.
Finsbury Food (LON:FIF) put a fascinating set of results out this morning, managing to pass on cost's and improve profit before tax - up 12.1% and EPS up 17%.
Food services up 38% (under threat perhaps?), retail up 7.1% and overseas up 27% helped by the 85% share in Lightbody-Stretz.
Under the circumstances of high energy costs, this Bakery has struck me as a very well run business.
Very low P/E and SP and with additional Government help on energy I'm in with this one.
Be interested to see what Paul makes of the numbers for £FIF. There are a lot of adjustments in there, moving from a statutory decline to an adjusted growth. Can't help but feel they should have taken more costs to the market earlier on. Agree it looks well run, but they have to get costs past the retailers and the commodity / energy concerns are far from over.
Morning Paul/Graham,
Either of you fancy a maiden look at Likewise (LON:LIKE) - Looks like there's a decent amount to like there - Interim's show Rev +108% (27% organic), PBT up 77% - There's a Zeus note out on RT for this quite recent IPO headed up by, mostly, ex-HEAD management so they've plenty to aim for via their old relationships. The f/c's on Zeus look like Rev's 10%+ p.a. and Profit & EPS 20%+ p.a. with a 2%+ yield thrown in too.
Thanks in advance.
ps - Paul the Podcasts are excellent and much appreciated
They are also on IMC in 25 mins (10:30)
I attended the Getbusy (LON:GETB) Capital Markets Day last week, and have shared an up to date write-up here: https://www.upsidedownsidecapi...
I think at this point it's an attractive SaaS business at 1.5x ARR, with strong downside protection, & new products providing substantial potential upside as “free” options.
Welcome thoughts or questions.
I have looked at Getbusy (LON:GETB) in the past and thought it looked cheap with good prospects. I did not buy however due to my uncertainty about the quality of the CEO, Daniel Rabie. I have nothing concrete to go on - but I don’t think he presents very confidently and I note that Paul Scott has also made a comment along the lines of the CFO being a better presenter than the CEO.
I don’t know how Daniel Rabie was appointed CEO but given his age and links with Reckon, I presumed (haven’t verified) that he has a close family link with Clive Rabie. With so many stocks out there - this was enough to stop me doing further work.
I am not necessarily against young people with wealthy family links, running companies and I have invested in such companies. But it does raise the question of how good the CEO really is.
Do you know by what process Daniel Rabie was appointed CEO and do you have a view on his strengths as a CEO ?
Hope the below is helpful on Getbusy (LON:GETB) but let me know if further questions.
In 2017 GetBusy was formed by the demerger of the document management software business from Australian company Reckon Ltd, who provide software for areas such as accounting, payroll, and practice management. CEO Daniel Rabie worked for Reckon since 2010, and Director Clive Rabie worked for Reckon for many years, including being CEO from 2006 to 2018 and then Managing Director. Daniel is Clive's son. At the point of demerger and listing of GetBusy on LSE AIM, £3m was raised to fund GetBusy by a rights issue underwritten by Daniel Rabie, Clive Rabie, and Greg Wilkinson at AUD 0.48 (£0.28) per share.
There is significant insider alignment: CEO Daniel Rabie owns 3.2%, Director Clive Rabie owns 18.6%, Greg Wilkinson founder of Reckon Ltd whom the company demerged from owns 7.4%, significant incentive plan for CEO & CFO. I suppose there can be positive and negatives with "family businesses", I'm not sure I'd quite describe GetBusy as a family business, but clearly Clive & Daniel are family and Greg has worked closely with Clive for many years. These 3 own c. 30% of the company, and given my impression that management will act responsibly, and they know the value of the business, then this could help protect other shareholders from a low ball bid for the company.
I think Daniel came across well at the CMD, he spent a lot of time on the culture of the company which may sound wishy-washy, but I think it was legitimate, and is actually important. I think he is switched on with regard to strategy. My personal interaction has been more with the CFO, and the management do share presentations, but I would say having a strong CFO as well is a positive. I rate management highly, and think they are steering the company in a very thoughtful way. They are conservative in approach and have only ever upgraded market expectations.
£STCM (Steppe Cement) - great 1/2 year results, YoY improvements abound:
cash as 16% reserved for dividend or capital return tbc
Gemfields (LON:GEM) - great H1 results 6 months profit after tax $56.7m. Worth a look.
"An AA survey of 12,500 drivers showed that rising domestic energy prices are putting many people off from switching to an electric car."
https://news.sky.com/story/cost-of-charging-an-electric-car-surges-by-42-caused-by-rise-in-energy-costs-12705528
I wonder what proportion of electric car owners charge at home versus on the road. I do but I guess tat I may well be atypical. I appreciate that going forward if electric cars are to make big strides then the service station price becomes more important.
I haven't calculated my charging cost at home overnight at a preferred rate where I live (around half price) but its a helluva lot less than I am paying for our other, older, diesel car.
I suspect my 17 year old diesel van will be far cheaper to run than a new EV.
Trio, I bet you're right. Love it!
Most drivers are not in a position to charge at home so the better cost comparison is public charger versus petrol fill up. Sky news today quoted 19p per mile for electric, 20p per mile for petrol and 21p per mile for diesel.
A more imprortant consideration when considering going electric is the convenience / time taken to fill up. I drive a 6 year old diesel. It does up to 600 miles on a full tank (long journeys and 450 (short journeys). It currently takes me 10 minutes to leave home, fill up and return home.
If I want to go electric I would have an average car range of, say, 250 miles per full charge. If I was easily able to access a rapid charge outlet (some chance!) then at best it would take me 30 minutes door to door to get an 80% charge. I would need to do this 3 times as often as I currently do to fill up my diesel and therefore spend approx an hour and a half longer per fill up. The time spent is likely to be much longer given local chargers be be out of order or already in use.
Until it becomes as easy and as time efficient to re-charge an electric car as to fill up at a petrol station then for me the electric option is a non starter.
I think the answer to the question is - it depends. For me, our next car will be electric. Along side this I will be installing a solar power array combined with a battery array. This will give me very, very low cost motoring as I will effectively be getting it for free - until I also convert to an air source heat pump, which means I will have to import electricity in the winter - but I will utilizing the full window of low cost electricity in the off peak times to keep costs to a minimum which when I add up everything for my specific case, means very, very cheap energy costs overall. For those who cannot charge at home, I see different membership solutions popping up to bring down the costs. I think this is a paradigm shift and will take time to implement, much in the same way that wind energy is starting to be the largest provider of electricity and is cheap, although when it originally was being implemented, the short sighted could only see the current costs. Our human race has time and time again met the challenges and succeeded, albeit with some short term suffering. I see no change to that here.
Lucky to have a garage, but I have never used a public charger on our EV. AND, when we moved house and realised we wouldn't get another free fast charger, we used the 13A socket for a week. That was enough to make us realise we didn't need a fast charger. Just put it in, charges at 10mph. Battery at 32,000 miles @ 98% State of Health. Seems simple.
From the same article - "However, the reality is that even with the hike in domestic electricity costs, running an EV is considerably cheaper than a petrol or diesel car.”
Edit - we will pay 7.5p per kWh for 4 hours at night from 01/10/22 on our tariff (Octopus Go July 2022 v1), enough for 100 miles. We rarely do more than 100 miles per day, but if we regularly did, there are other tariffs offering 6 hours at a reduced rate. We only occasionally use the roadside chargers, perhaps once or twice a month on a longer trip and only put as much in as needed.
Fox Marble Holdings (LON:FOX) announced plans to day to pay £30m in a reverse takeover of Eco Buildings Group Limited, a newly incorporated business with £1k capital!
Well, it's not really £30m, however, since the purchase is being paid for with FOX shares, which are pretty much worthless. So it's one worthless company acquiring another worthless company but dressing it up to look like a £30m transaction.
The big question is, will they find enough fools to support the associated £10m placing, which involves real money?
Fox Marble Holdings (LON:FOX)
That's a blast from the past! Thought they were dead and buried.
One last throw of the dice with the promise of jam tomorrow!?
Phil
Really enjoy the podcast Paul. Thanks for doing it.
Me to! Although the bespoke jingle could be used to help scare Putins troops out of Ukraine.
Morning Paul,
Thanks as always for the weekend podcast, it certainly made my drive home feel a little shorter on Sunday evening! In the unlikely case of a slow day at the SCVR this week, any chance you could post your thoughts on stocks that will be in the spotlight for potential takeovers from US takeover bids? I know certain stocks have been mentioned at times over the past weeks and months but to get an overview from yourself or other posters would be much appreciated.
Lets all hope things don't turn too bleak this week.
Would definitely be interested in thoughts around Somero Enterprises (LON:SOM) Somero being a potential takeover target.
Facilities being expanded, earnings in dollars whilst listed in London, well known in the industry and sure the owners are well into their 70’s.
Short term may pose some headwinds but got to wonder if they could be a recipient of US infrastructure spending and possible stimulus in China if announced at next party meeting.
Been looking for "winners" and losers from a sinking pound and the current cost-of-living crisis resulting in so many UK small cap retail investors selling and/or not buying. (These may also be takeover targets).
Winners presumably will be those with large $ exports or growing $ sales, businesses with long term valuable brands and currently high, even excess inventory stocks.
In the spirit of starting to share ideas for DYOR, I am trying to resist buying more £PMP (60% sales in US/Korea, stock made for H2 weighted year) and looking at buying back into £G4m (big inventory & hated) and £SDG (already shifting focus to US, selling to 'banker bonus rich' in the UK ) although I am nervous about becoming overweight in cheap, contrarian retail orientated stocks!
Following a different logic, I am also thinking about GYM (LON:GYM) - huge gross margin that will be helped if it can follow even close to headline inflation and keep its net customer base/gym as it rolls out (some drop down from mid/high price & rival gym closures, some existing customers drop out) . It could also extend CAPEX replacement by a year to offset relatively small utility cost price increases. (I also think gyms are cheap entertainment for its mostly young users for whom there is also a lot of casual work available: a gym cost 20-25/month; a typical "night out" (food, drinks, taxi) might be 50-70/night - more in late night clubs).
However, what I don't know is the detail of how property leases work. Will these normally be fixed in absolute terms between break period/renewals or have an inflation-linked rise ? If ficed, they will get relatively cheaper fast and be quite an offset in real terms.
Any property experts to enlighten me?
(FWIW I am typically looking to buy and hold for a few years, not trade, hold £PMP )