Small Cap Value Report (Mon 28 Feb 2022) - MCLS, TSTL, OTMP, CNIC, MTEC, SFE

Good morning, it's Paul & Jack here with Monday's SCVR.
Agenda -
Paul's Section:
Tristel (LON:TSTL) - I reviewed interim results from a week ago, over the weekend. Despite halving in share price, I still don't see this share as a bargain.
Mccoll's Retail (LON:MCLS) - Ominous press coverage over the weekend suggests to me that this share is probably worth zero, with insolvency looming. Too much debt, and supply chain problems look set to overwhelm equity, leaving debt holders in the driving seat, and equity holders probably wiped out in an imminent administration. I would get out while you still can, at any price that's high enough to cover the stockbroker's selling fees.
Onthemarket (LON:OTMP) (I hold) - a reassuring (in line) trading update for FY 1/2022. It's profitable, and has cash in the bank. It remains to be seen if the updated strategy of CEO Jason Tebb will work.
Made Tech (LON:MTEC) - my first look at this IT company addressing the public sector. Stellar growth, but I wonder if it might be expanding too fast, and struggling to control its staffing costs? Today's interim results come with a profit warning due to increased costs, shares down by a third. Overall, I don't know enough about it, so will sit on the fence.
Jack's section:
Centralnic (LON:CNIC) - I hold - final results and another acquisition announced. Organic momentum is strong and this has continued into the new financial year. The group remains loss-making on a reported basis though and, while revenue and profits are up impressively, the per share improvement is more muted. The rate of acquisition activity here suggests an ambitious company, but one that remains tricky for investors to pin down.
Safestyle Uk (LON:SFE) - trading update and cyber attack. H1 earnings are expected to materially reduce as a result. The group retains its second half guidance though, and says that the operational recovery is underway. Momentum had been promising here, but this remains a turnaround and sentiment has taken a knock, with increased short term uncertainty.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Mccoll's Retail (LON:MCLS)
7p (pre market open) - mkt cap £20m
Weekend press
Very ominous press reports over the weekend, suggesting that this convenience store chain is on the edge of going bust, with equity now probably worth nothing.
Sky says that some of McColls bank debt has been sold to hedge funds. It also says Morrisons is monitoring the situation closely, with a view to possibly acquiring some Morrison branded stores out of insolvency.
An excerpt from the Sky article says -
Retail industry sources said that McColl's shares were now effectively "worthless" and that a pre-pack administration or other forms of insolvency increasingly looked like the most likely outcome.
People close to the company expressed hope this weekend that a solvent solution could yet be found.
An article from ThisIsMoney says that Morrisons might bid for McColls.
My opinion - we’ve been long term negative on McColls shares here, due to the excessive bank debt, poor performance, and wafer thin margins.
However, the refinancing last August did look as if there might be a speculative chance of a turnaround, with the CEO putting in £3m of his own money looking a strong move.
The newsflow deteriorated later last year though, with supply chain problems worsening.
These latest press reports suggest that equity is probably now worth nothing. The creditors look to be in control, and that suggests a very high likelihood of equity holders being wiped out.
Hence for shareholders, selling quickly looks the most sensible move, to salvage anything you can.
With more difficult economic conditions at the moment, and the likelihood of interest rate rises, and withdrawal of Govt support, then I think highly indebted companies are looking a lot more risky. Investors who ignore balance sheet risk look set to get a rude awakening this year. It’s so difficult to predict these things though, because some highly indebted companies seem to sail through, whilst others collapse.
It’s worth remembering that, as outside shareholders, none of us really know for sure what’s going on at any company we invest in.
MCLS as just issued a statement this morning -
Ongoing discussions with banks.
Note the use of the words "stakeholders" and "partners" - often a warning sign that shareholders are now irrelevant -
The Group continues to believe that a financing solution will be found that involves its existing partners and stakeholders.
Working capital headroom has now gone, due to planned capex, and a poor H2 for FY 11/2021.
Guidance for FY 11/2021 results: in line with expectations (£1.11bn revenues, and £20m pre-IFRS 16 adj EBITDA)
Omicron impacted Xmas trading
Recent trading - improved gross margin, and improved product availability
Morrisons Daily store conversions delivering >20% LFL sales growth.
FY 11/2022 guidance - slightly behind expectations.
Net debt expected to remain flat, at £100m at end of this year.
Outlook -
As previously stated, the Group continues to believe that a financing solution will be found that involves its existing partners and stakeholders. However, there are also other options available to it. The Group confirms that it recently received an approach for the whole business, which has subsequently been withdrawn and there are no further discussions with that party or any other party in relation to an offer for the whole business. In addition, the Group has also received indications of interest for parts of the business. The Board will consider all options with the aim of maximising value for all stakeholders.
My opinion - ominous use of "stakeholders" suggests to me they're fighting to keep the business trading, rather than necessarily being able to salvage any value in the equity.
There's a glimmer of hope in the above, but I'd say it's looking >90% likely (my guess) that existing shares end up worth zero, or very close to zero if there's a debt for equity swap, as one possibility.
Tristel (LON:TSTL)
325p - mkt cap £153m
The share price of this seller of infection prevention products, has been hit hard in the current small caps bear market. We’ve been flagging here for a long time, that the valuation of Tristel shares was looking stretched in the big bull run from 2019 to 2021.
So I’m interested to see if, having halved in price, the shares might now look attractively valued as a possible purchase?
.

.
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products utilising proprietary chlorine dioxide technology, announces unaudited interim results for the six months to 31 December 2021.
Company’s PR summary -
Product rationalisation to deliver faster top-line growth and higher profitability
Continued progress towards commercial launch in North America
These interim results are tricky to interpret. It all depends what emphasis you put on the company’s adjustments.
The statutory numbers show a 7% fall in H1 revenues to £13.6m, and a big fall in reported PBT from £2.4m last year H1, to £1.0m in H1 this time.
How much of this poor performance is due to the continued impact of covid? As Tristel says in the commentary, we see on the news constantly how much elective surgery has been delayed by the pandemic, which suggests an upturn in business could be imminent, as elective surgery comes back. That’s a bull point for Tristel shares. Also the long awaited US approval could boost sales.
Throughout the first half, COVID-19 has put enormous pressure on healthcare provision in all our markets. However, there are signs that hospitals are returning to pre-pandemic levels of service, although this improvement is neither uniform nor consistent. Whilst we expect this "start-stop-start" pattern to continue through the second half, the number of diagnostic procedures that generate demand for our products is reviving globally.
We anticipate that second half revenue from Continuing operations will be higher than first half revenue.
Adjustments - there are three layers to this -
Firstly, some lower margin products are being discontinued. So the company presents these (falling) sales separately, which makes continuing business look more positive.
Secondly, one table moves £0.9m of sales related to Brexit stocking-up, from H1 last year into H1 this year, which is stretching things a bit, in order to turn a negative trend into a positive adjusted trend!
Thirdly, there’s a £2.4m write-off related to intangibles for discontinued operations. Taking that into account, the total loss after tax for H1 is £(982)k.
Note that share based payments look excessive (not for the first time at Tristel) of £884k in H1.
Also note H1 this year benefits from a negative tax charge.
Pricing power - a key issue at the moment, with higher input costs and pay rises.
This sounds reassuring -
We are experiencing labour cost increases and component and raw material price increases across the Group and are increasing prices this year to match them.
Balance sheet - absolutely fine, very strong, with plenty of working capital, including £8.8m net cash.
Cashflow statement - is still good, despite profits falling. So the dividend paying capacity of the company still looks good. The forecast yield doesn’t excite me, at 2.0%.
The interim divi is held at 2.62p.
Outlook - talks about recovery potential after covid -
As the impact of the pandemic recedes and the number of endoscopies, ultrasound scans and other diagnostic procedures return to their pre-COVID-19 levels, we are confident that we will return to the growth trajectory we were on before 2020. The backlog for these procedures is front page news in all countries.
We have simplified the business and sharpened our focus on the hospital and our proprietary chlorine dioxide chemistry. We are better placed than before COVID-19 to capitalise upon a return to normal service in global healthcare. We look forward to growing our two core brands - Tristel and Cache - and expanding our global reach.
Valuation - forecast EPS has been falling, quite a lot -

.
Accordingly, even though the share price has halved, earnings forecasts have fallen a similar amount. So the PER still looks high - Stockopedia shows the forward PER of 42.5.
My opinion - it still doesn’t look cheap to me.
I wouldn’t pay a PER of 42.5, for a company where the upside is still quite tricky to forecast.
As always, this is just a personal view, but to pay that kind of rating, in a bear market for small caps, I would want to see a much clearer upside case.
Tristel is quite a decent company, making solid profits at high gross margins. It’s got an excellent balance sheet. But it’s always struck me as a bit too niche, only generating small sales, in lots of countries. For a growth company rating, I much prefer to see exponential growth, with huge market potential. That’s not obviously the case with Tristel. So it’s not for me, but good luck to holders.
.
Onthemarket (LON:OTMP) (I hold)
92.5p (unchanged, at 08:56) - mkt cap £69m
Trading Update (post year-end)
OnTheMarket plc (AIM: OTMP), the majority agent-owned company which operates the OnTheMarket.com property portal, is pleased to announce an update on trading for the year to 31 January 2022 (FY22).
It’s another reassuring update -
the Group expects to report for FY22:
· Revenues of approximately £30.8m (FY21: £23.0m); and
· Adjusted operating profit for the year of approximately £2.6m (FY21: £2.4m).
Liquidity looks fine -
net cash at 31 January 2022 of £8.4m and no borrowings.
Outlook - no numbers, but upbeat commentary -
With the new website and brand launch in December 2021, and an increasing range of commercial partnerships successfully established, the transformation of OnTheMarket to create a tech-enabled property business across the broader property ecosystem is accelerating.
The new website, and initiatives such as 'Only With Us', continue to attract serious property-seekers and connect them with our advertisers.
The strategic steps the Group has taken, alongside the support of our agent customers and shareholders, provide the Group with the confidence that it has a platform from which to drive long-term profitable growth.
"We are delighted to have achieved a year of further financial and operational progress. But there is much more to come. We have received great feedback from our customers regarding our new strategy and enhanced suite of product and service offerings. We look forward to continuing to deliver greater value to both advertisers and consumers during the year ahead."
My opinion - it’s profitable, and has cash in the bank.
I don’t know if the added tech services strategy under newish CEO Jason Tebb will work or not, we’ll just have to wait and see.
.
.
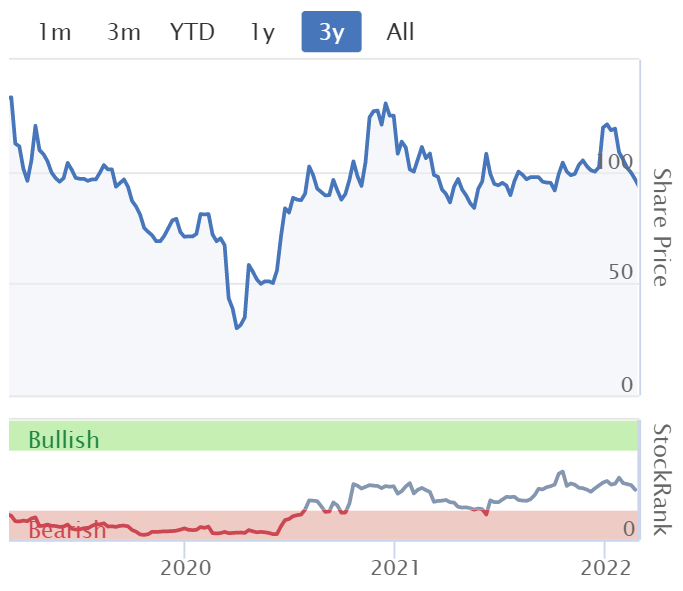
Made Tech (LON:MTEC)
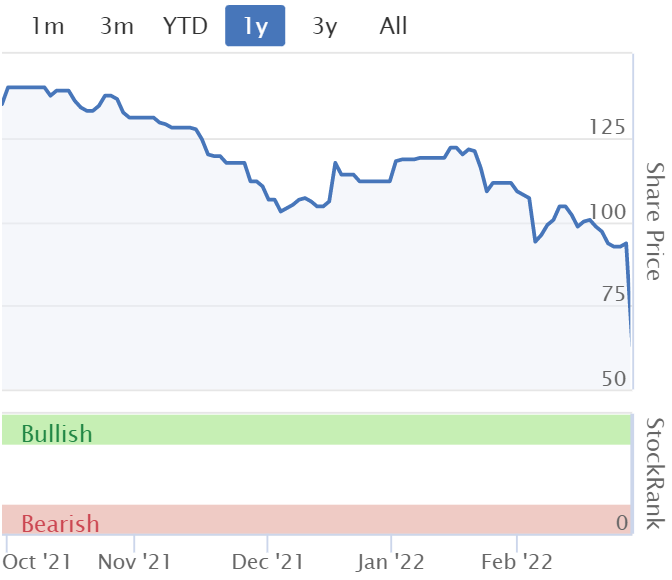
62.5p (down 33% at 09:37) - mkt cap £92m
Major new contract with NHS digital
Made Tech Group plc, a leading provider of digital, data and technology services to the UK public sector, is delighted to announce that a consortium including Made Tech has been awarded a two-year contract worth up to £37.5m with the Health and Social Care Information Centre ("NHS Digital").
MTEC’s share is about half, so c.£19m, and the contract has already started.
“Significantly enhances revenue visibility” for FY 5/2023 & FY 5/2024.
This announcement sounds positive, so it must be the interim results that has triggered the share price dropping by a third this morning. Let’s take a look.
Made Tech Group plc, a leading provider of digital, data and technology services to the UK public sector, is pleased to announce its interim results for the six month period ended 30 November 2021.
MTEC floated on AIM on 30 Sept 2021, it’s a new share to me, so this is just an initial review of the numbers.
Impressive growth here -

.
Skimming through the commentary, I’m struck by how fast the company is expanding, and that headcount is rising very fast - which is likely to be a challenge to control.
Profit warning - this seems to be the culprit for today’s 33% share price fall -
Despite some short-term challenges relating to IR35 and staffing of public sector contracts and increased overhead costs, which we expect to impact our trading performance in Q4 FY22 and into the first half of FY23, the Group's significant new contract bookings and robust pipeline underpin the Board's confidence in the medium term outlook. We look forward to continuing to deliver strong revenue growth in the second half of FY22 and beyond, and remain incredibly positive about the Group's long-term prospects."...
Wage inflation and the well-publicised challenges in the hiring market have made recruitment more difficult than anticipated. We've had to significantly increase our headcount within our internal Talent team and lean more heavily on external recruiters than we had originally planned. This is leading to an increase in both recruitment overheads and average staff costs, which we expect to have an impact on our full year performance. The increase in our billable staff costs has already been offset by delivering increased billable utilisation across our staff and an increase in our average billable day rate, so we're expecting our gross margin to remain broadly in-line with expectations. However, we expect it to be more challenging to offset overhead costs, though we will of course continue to look at this closely.
Rather a mixed bag there.
Is the company growing too fast? Is it winning contracts by under-pricing them? I don’t know, but am just asking the questions.
Balance sheet - looks fine. £11.1m cash, NAV £13.5m, and only £453k intangible assets, so this is a very capital-light business model, which appeals to me. Although as with any people business, the fixed assets walk out of the front door every night, and can be poached by competitors quite easily. In a time of rising salaries, that sounds like a challenge for MTEC. So rising staff costs is probably the main threat to the business.
My opinion - neutral at the moment, because this share is new to me.
Things I like -
- Extremely rapid growth in revenues, and a move into profit
- Sound balance sheet, with plenty of cash raised in the IPO late last year
- Public sector IT seems a lucrative area, as we’ve seen from Kainos (LON:KNOS) and Tpximpact Holdings (LON:TPX)
Things I’m not keen on -
- Staffing challenges & costs - is it expanding too fast?
- Profit warning today could put a cloud over the share price for a while
- Difficult to value, given it’s only just moved into profit
.
.
Centralnic (LON:CNIC)
Share price: 126.98p (-4.88%)
Shares in issue: 251,160,084
Market cap: £318.9m
(I hold)
Preliminary results for the year to 31 December 2021
- Revenue +71% to $410.5m (organic revenue +39%),
- Gross profit +58% to $118.5m,
- Operating profit up from loss of $2.1m to positive $12.4m,
- Profit before tax up from loss of $11.8m to positive $1.6m,
- Net debt down from $85m to $75m after $18.3m of acquisitions,
- Adjusted EPS +18% to 11.8c.
The shares are down this morning, possibly due to a more muted improvement in metrics at the per share level. And, stripping out adjustments, the company remains loss-making.
Adjusted EBITDA of $46.3m includes $18.3m of amortisation of intangibles, $8.7 of non-core operating expenses (primarily related to acquisitions), and $5m of share-based payments.
CentralNIC is an evolving company and some of the share value is in its growth prospects. That said, it is fair to be wary of companies that continually acquire via equity dilution.
The company purchased four businesses in the period: SafeBrands (online presence), Wando (online marketing), White & Case (online marketing), and NameAction (online presence). Deferred considerations were also paid out on Team Internet and SafeBrands (totalling $1.7m).
Operationally, management has said a few times that Big Tech’s increasing focus on privacy is suited to the group’s business lines. It continues that today, noting ‘very strong traction for the Group's privacy-safe online marketing technologies in the context of privacy-conscious policies of Big Tech’.
Meanwhile, it has invested in new management, staff and systems, which has helped to accelerate organic growth to record levels (of 39%). A new Data and AI group has also been set up to improve growth and profitability.
Online presence (essential tools for businesses to go online) - revenue grew 17% to $127.9m.
Online marketing - revenue up 133% and 65% organically.
Acquisition and placing
CentralNIC also announces a placing and open offer of £45m this morning, for the acquisition of online marketing business VLG. The transaction will value VLG at c$75m in exchange for a company that generated $55.3m in annual revenue and $10.9m in adjusted EBITDA for the year to 31 December 2021. There’s an additional earn out of up to $38m over three years ‘if the growth of VGL materially exceeds expectations’.
CentralNic expects to issue additional senior secured callable bonds for a nominal value of EUR 21 million under its existing senior secured bond. The proceeds of the bond Issue will be partly used to fund the acquisition.
It’s a sizeable transaction, but the companies CentralNIC goes for tend to be relatively easy to integrate and are quite scalable. The group has recurring revenues and cash conversion generally in excess of 100%, so it should be able to swallow this but the larger the acquisition, the higher the risk.
This will continue to be a feature for the group: 'The pipeline of future acquisition targets remains strong and we are confident in continuing our trajectory towards joining the ranks of the global leaders in our industry'.
Balance sheet - $254m of intangibles make up the bulk of the $271.8m fixed assets. The current ratio is less than 1x. All in all, I would like to see more here.
Cash flow - is better. Net CFO of $38.4m and free cash flow of $33.2m (or c$24.6m after interest) is some way above the reported statutory profit figure and may be a better indicator of where the group is at.
Conclusion
There’s a lot of news to digest today. The company has made quite a few acquisitions over the past few years and a lot of investors might understandably put CNIC in the ‘too difficult’ tray.
Management does make the effort to communicate with private investors, but ultimately I suspect people will want to see consistent positive reported earnings per share growth over a period of time. CentralNIC remains loss-making for now, although cash generation is stronger.
Repeated acquisitions can make investors wary, although management does have experience with this kind of strategy and is in an industry with suitable economics (predictable, recurring revenue, low churn, strong cash conversion). These are often just websites automatically billing credit cards, there’s no key person risk or anything like that.
And CNIC is well positioned higher up the supply chain, with great visibility over its acquisition pipeline. It can see who is growing, most targets know the company, and it is often seen as a preferred partner.
So this remains about where you think the company is heading. As the company scales up, the underlying qualities of high recurring revenues and strong cash conversion should become increasingly meaningful. The group has been through a phase of heavy investment as well, and it expects lower costs here in future.
CNIC does have to make sure it is adding sufficient value at the per share level though and, while cash generation is good, the balance sheet is not the strongest. That makes me slightly more cautious given the expectation of further acquisitions.
That said, organic momentum has been strong and this has continued into the new financial year. The new acquisition is expected to be double digits earnings enhancing and there is the ambition to build a materially larger business here in time.
Safestyle Uk (LON:SFE)
Share price: 43.21p (-9.03%)
Shares in issue: 138,615,378
Market cap: £59.9m
Trading update and cyber incident
An unfortunate update here, which sees the share price down c9% at the time of writing as a result of a cyber attack.
In terms of trading, Safestyle says:
Our sales momentum, supported by our return to TV advertising on 14 February, has remained strong and our order book has continued to build. Our balance sheet, liquidity and net cash positions remain healthy and are comparable to those levels previously communicated at the end of 2021 (net cash is currently over £12m).
However:
Order processing and customer services operations were… severely impacted by the attack and our On Time in Full ('OTIF') levels were increasingly disrupted until the relevant installations systems were successfully recovered. That recovery has now been achieved and we expect the level of disruption to markedly reduce as we return to normal business operations over the next month or so.
The incident is now mostly fixed but the resulting impact will be a c10% hit to H1 revenue and a ‘material impact’ on H1 earnings. Audited results for FY21 will also be pushed back to 21 April 2022, although guidance remains unchanged from the 26 January update.
After careful consideration, we have decided not to change our strategic investment plans in 2022, including our return to TV advertising, and we also expect, in light of the attack, to accelerate our existing multi-year IT investment plans. As a result, and in the absence of other external factors, cashflow is expected to be broadly neutral for the year.
Conclusion
Safestyle is still investigating the nature and extent of the incident. That uncertainty will be uncomfortable for shareholders, but the group is maintaining H2 guidance and is using this as an opportunity to accelerate IT investment.
The disruption should not impact second half figures, so for now it looks like a temporary setback. OTIF run rates are expected to quickly return to targeted levels and the group retains a strong order book.
Liberum has cut its H122 PBT estimate from £4.5m to £0.2m though, with gross margins for 2022 reduced due to the incident delaying planned price rises.
It’s a shame, as the turnaround here looked to be working out well with a return to profitability last September after four years of hard work. This update introduces much more uncertainty into the mix, with a material impact on H1 earnings. It may prove to be a temporary issue, but trust in a turnaround is a fragile thing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Hi,
Do you know any news about Renold (LON:RNO)? I have purchased it for 29p end of January and it has gone down to 23.50p since then? I have almost reached the stop loss and I am not sure if it is related to the Ukraine situation or there are other internal problems as well, just thinking if it is worth cancelling the stop loss and thinking more long term or moving away.
Hi Giuseppe.
I don't have news about Renold (LON:RNO) but your comment made me take a look. From a chart point of view the price is at a low point. Personally (now that the price is low) I'd use the strong support at 22.2p as my stop loss. If the price breaks below here then it could drop below 20p.
Note that the Relative strength is also at a low not seen for some time so the selling might become exhausted or buyers might appear.
Revs8, thanks a lot for spending your time looking at this. Yes, my stop loss is set to 22p (-25%). This company has good fundamentals but after I had big losses with Joules (-43%) and Studio Retail (-46%)I don't think that I can rely on fundamentals for Small Cap anymore and go over than 25% loss.
I like Renold (LON:RNO) as a potential turnaround and it has exposure to defence and mining. Very different to the retailers you mentioned. I have owned previously and I am tempted to dip back in on evidence that the heavy selling has stopped.
I also note that Ocorian Limited as trustee for the Renold plc Employee Benefit Trust we’re buying shares until 24th Jan which would have been supporting (inflating) the price. If they have now stopped buying it might explain the recent lack of support.
If this is why the share price has been week then the good news is that it has little to do with the health of the company.
Offer for Oxford Instruments (LON:OXIG) oxford instruments from Spectris (LON:SXS) - cash and shares, board minded to accept (I hold Oxford Instruments (LON:OXIG) )
another one for Lord Lee, first offer received 3 weeks ago
Another example of 'Catch-up' - just released statement from £OXIG. (I hold). and Spectris (LON:SXS) of a buyout - going back to 11th Feb. Maybe not as bad as examples last week - but still a time lag......
Associated British Foods (LON:ABF) (Not a small cap but plenty of read across)
Interesting commentary from the only clothes retailer that I can think of who is growing their store count at a decent clip.
Sales and adj operating profit up vs pre pandemic levels.
Like everyone they are suffering from the effects of inflation across their wide portfolio of businesses. Price increases lagging inflation but margin expected to normalise throughout the remainder of the year. Sugar well up after a few years of under performance. Margin seemingly under pressure though.
Primark. Total sales 4% lower than pre-covid same period. But includes 27 new stores representing 8% additional selling space. LFL 11% lower. Reasons for this include omnicron and destination city centre stores declining.
Us lfl 2% growth and total sales up 35%.
Encouraging signs as footfall is picking up again and they are on course to open 128 stores across the next 5 years. I hold but the story will become a lot more interesting when precovid lfls are beaten and price increases are successfully passed to the consumer.
Primark to me feels like a good part of the market to have exposure to in the current environment. Spending power is declining so more people will be forced to consider brands at the cheaper end of the market and if they are the cheapest I can't see how they won't be able to pass on increases as there shouldn't be a cheaper alternative.
The remaining businesses look fine to me with the exception of Allied Bakeries. It clearly has the ability to produce good products at competitive prices e.g. Allinsons bread but it seems that the remaining brands are a bit tired and in need of a refresh. Perhaps it would make sense to get rid of this segment altogether.
I think it's fine to talk about large caps from time to time. I agree that Associated British Foods (LON:ABF) looks quite compelling at the moment; its close to the very top of my watchlist. It's trading well below its historic valuation in a market environment that I think it will do well. It has said it will be able to pass on heightened costs in its grocery and food businesses (with a slight lag) and its retail arm is arguably quite well positioned in an environment where discretionary spending becomes more limited. There is also the increased likelihood of substantial returns of cash to shareholders via special dividends under the new capital allocation policy announced back in November. All the best, Will
Oncimmune Holdings (LON:ONC) this might be an interesting play that I think the market might be misunderstanding somewhat down about 10% after interims though in a poor market and on low volume.
Company is fast becoming the leader in autoantibody profiling with a product called ImmunoINSIGHTS. Market is growing at 27% per annum so plenty of market growth to accommodate them.
They are now signed with 5 of the top 10 global pharmas and contracts appear to be extending into multiple areas. ie when a client uses their services once it appears they subsequently use them for new studies too, which is clearly a strong endorsement.
But financials are all that really matter so...
H1 revenue was irrelevant at £1.4m and losses look bad at £4m. But here's what piqued my interest. H2 revenue is now expected to be £5m+ with visibility extending into next year and beyond. And this is the key......the company has the current capacity to do 10,000 samples per annum. These are all priced at €1080 per sample and have a gross margin of 85%! So that means capacity in H2 is already maxed. That £5m revenue gives a gross profit of £4.25m and should move them into profitability. Then in time for financial year 2023 they have increased capacity to 40,000 samples per year. With the market growth and sales/distribution network already expanded and in place I'd expect them to do circa 20,000 samples next year (plenty of room for upside but better to be conservative). That should mean revenues of around £20m for FY23 and gross profit of £15.5m less around £8m in admin expenses and R&D. So by my calcs we should be looking at a 1 year forward PBT of £7.5m vs a current market cap of £75m.
Then assuming they move to 30k samples the following year that doubles PBT to £15m so excellent operating leverage in evidence.
Looks like an interesting 2 year play to me. Heavily de-risked now they have master service agreements with 5 of the top 10 global pharmas and are maxing initial capacity whilst moving into profitability but with good upside based on the operating leverage kicking in.
Just noticed this interview for Oncimmune Holdings (LON:ONC) today on Vox Markets. Oncimmune Interview with CEO It seems the expansion to 40,000 capacity has been completed ahead of schedule, which looks to be excellent news as it means the ramp up of profitability into next year should be easier to manage. Also, noted that their market segment is currently £100m p/a and growing at 27% p/a so even at 15-20% market share that backs up revenue projections.
Importantly balance sheet doesn't need any funds so unless they find a good piece of M&A that is compelling there is no need for any raise. I might have to be patient for a year or so but risk/reward looks to be favourable.
Made Tech (LON:MTEC) - thanks for covering Paul. Here are my further thoughts:
Staffing issues: Paul, I think you've got the wrong end of the stick with the staffing issues. The problem is not (yet) with assimilating rapidly growing staff numbers, and the challenge with retaining hires is likely lower than it is for larger competitors, eg Kainos. Made Tech is the feisty little disrupter here, not the incumbent. The issue is with building permanent employee headcount at the same rate as the rampant order intake because hiring contractors, who are not in abundant supply either, is deleterious to margins. Here there is a shortfall in delivery and that accounts for lowered revenue targets in FY22 and FY23. However, there has been recent progress in ramping up hiring capability which might ease onboarding challenges moving forward.
Growth: The positive take here is that the RPO (order backlog) keeps growing at a rapid pace and the revenues are only constrained by supply (staff shortages). In time these will feed through as higher unit prices on the revenue line but they will lag input cost rises in the short term, bringing the challenges to margin that are acknowledged in the TU. Current challenges notwithstanding, the RPO gives a high level of visibility for the future. A backlog of £30m represents 75% of revised FY23 revenues. This company is growing fast!
Valuation: With the company around the inflection point for profitability, the operating leverage is so great that it is hard to value based on profits. However, I believe after today's adjustments it will be on a PER about 50x FY23 and 20x FY24. Looked at on an EV/revenue basis however, the shares get much more interesting on roughly 2x FY23 and 1.4x FY24. This is less than half the price of competitors for a business growing at a very significantly faster rate.
I have topped up this morning.
With the company around the inflection point for profitability, the operating leverage is so great that it is hard to value based on profits. However, I believe after today's adjustments it will be on a PER about 50x FY23 and 20x FY24. Looked at on an EV/revenue basis however, the shares get much more interesting on roughly 2x FY23 and 1.4x FY24. This is less than half the price of competitors for a business growing at a very significantly faster rate.
The continued sell-off is potentially creating a great opportunity here.
On an EV/revenue basis, Made Tech (LON:MTEC) is now valued at only a quarter of the multiple commanded by closest competitor £KNOS. This for a profitable business guided to grow at 5x the rate - Singer forecasts 50% from FY22 to FY23, much of which is already contracted.
My updated calculations deliver FY22 (May) PER of 27x and FY23 19x (Kainos 39x and 36x). EV/EBITDA 21x and 13x respectively (Kainos 30x and 27x).
Of course the market is in a punishing mood at the moment and has no tolerance for profit warnings, so a discount to the premium valued leader is entirely justified at the moment. But the secular drivers of growth in DX and government digital services are powerful and Made Tech (LON:MTEC) has a strong reputation for quality and delivery as well as strengthening order momentum.
Kitwave (LON:KITW) - Paul, may I jog your memory you wrote here : "Kitwave (LON:KITW) rings a vague bell, but I don't seem to have covered it here yet. Noted that a couple of readers are interested, so I'll make a mental note to review its next results here".
I had a look at the time and one thing I noted was the shareholder list: Liontrust, Harwood and Miton on board but largest shareholder with 15.7% is Paul Young co-founder and CEO of 30 years. Companies House gives birth Sept. 57 so 65 this year. Is he ripening it up to sell and retire? Shades of Stephen Marks at French Connection?
KITW distrubutes to retailers - mainly independents but I would want to ask about McColls- that may be difficult - looks as if they don't do presentations.
Looking at today's results I want to see how they match the forecast for underlying earnings - Stocko shows 6.36p. They don't show that before the a/cs where I find 0.08 - Oh! that is actually good - unlike most other companies they quote eps in £
All we need now is for Stocko to give them a rank.
YCA Yellow Cake
Anybody got any news on YCA, up 28.76% today, I hold.
Came up on my spreadsheet as a Pyramid Buy, can't find any news
Any help would be appreciated
Yellow Cake (LON:YCA) up 28%? Don’t you mean 28p?
Sorry, Rustbucket you are correct, The current price is up 10.53% and up 33.58p
My question still holds "as anybody got any news.
It's probably to do with Russia and possible shortages of uranium in the future. But I'm guessing. Some other commodities are up also today. I can't find any uranium prices for today. Geiger Counter (LON:GCL) is also up 4.8%.
YCA Yellow Cake
Rustbucket - Yes that makes sense, thanks for your comments I am now about to buy some more ( in accordance with my pyramid system.)
From another site but, I believe Kazakhstan has politely declined Putin's request for military assistance. Kazakhatom that have a deal to supply Yellow Cake (LON:YCA) are based there.
U3O8 trading spot at USD 46.65 / llb at 14:21 GMT. It has not moved much since September 21.
Probably related to Germany considering the extension of their nuclear plants life-span.
Perhaps newcomers to Stocko need reminding that Paul's note today is in response to an RNS issued by Mccoll's Retail (LON:MCLS) as is his standard practice for the SCVR. On a more personal level I sold out of this company months ago but not before suffering a sizeable loss when it became obvious that a recovery was a bridge too far. My guess is that I joined an exodus which Paul might have applauded.
Good morning Paul & Jack, not sure if you have Kitwave (LON:KITW) on your list today, but I understand if not, there is a lot of reporting.
First interims for Made Tech (LON:MTEC) today. Would you like to take a look guys? High uncertainty, with caution voiced over confusion wrought by IR35 changes and competition for staff, but upbeat in general and very attractively valued should forecasts be met, or even narrowly missed. Numbers look a bit short against forecasts for H1 ‘22, mainly due to a fall in margins, but huge growth nonetheless and no changes made to outlook in the TU.
I see a clear and large opportunity here in GDS, Government Digital Services - as did the Small Companies Sharewatch, calling it “son of Kainos”. I met the MD and FD last month and made an investment, just in time for markets to fall.
Made Tech (LON:MTEC) directors say they are ‘incredibly positive’ about the future, but if they find their own enthusiasm incredible, I can’t see any reason to be more confident than they are.
Mccoll's Retail (LON:MCLS)
No surprise here - facts are this company has been in hoc to its creditors for quite some time now and only exists in its current form due to their generosity of not pulling the plug . Ok it could have in theory traded its way out of the mire or been saved by morrisons paying shareholders reasonable price for the buisness at which time shares may have done ok but hopefully here it was clear to anyone who invested in last couple of years they could be completely wiped out in a heartbeat here.
Certainly a case here where the debit side of the balance sheet offers no protection unfortunately.
The Russian state is now a pariah and anything related plainly toxic. So lets use all those brains on Stockopedia in a positive and helpful manner to consider what stocks may benefit on a longer play, the world has changed for now.
One possibility to benefit from several Russian scenarios is cyber security. I could expect as long as Putin remains in power there to be more overt and more frequent cyber attacks against Western companies, governments and individuals.
One possibility to benefit from several Russian scenarios is cyber security.
Darktrace (LON:DARK) is up over 30% in the last week and still looks reasonably priced against analyst PTs and US competitors, which also had a boost last week. This theme is only gaining in significance and I hold a basket of leading names.
Hi BnB
This Tweet from Dan Ives a little while ago ref Cybersecurity US names might interest you.
Regards
Howard
Thanks Howard. Dan Ives is a big cyber bull so you have to take his announcements with a pinch of salt. That said, I have owned the first five on his list for some time!
Putin must be deranged if he thinks that attacking Strix (LON:KETL) (See rns today) will intimidate the West.
Putin must be deranged if he thinks that attacking Strix (LON:KETL) (See rns today) will intimidate the West.
Oh, I don't know. The Russians only need to attack Taylor's of Harrogate now, and I for one would be totally demoralised...
Seems I wasn't the only bright spark buying Concurrent Technologies (LON:CNC) first thing today.
All the best, Si
Chemring (LON:CHG) Bae Systems (LON:BA.) Avon Protection (LON:AVON) all up strongly this morning for obvious general reasons, Germany saying they will now up their spending on defence etc being a more specific reason.
Lockheed Martin and Northropp Grumman in the US will probably mirror these gains.
I am not sure if there is a 'defence' ETF out there but probably .
Richard
I hold all of these, bought Chemring , Avon & Thales this morning. Also rotated into SAAB & Rheinmetall last week. Previously bought BAE when the Aussies binned their French submarine deal. Given what is happening, it seems inevitable that European defence companies will be “ESG re-rated”. The tragic reality is that deadly advanced weapons are much needed insurance against tyranny. Germans have doubled their defence budget overnight and have declared that most of this is going on new kit. For too long now they’ve gamed the NATO 2% GDP target by including veterans pensions etc and even then were well short. Other Euro countries will be expected to follow their lead.
There are a couple of defence ETF's listed in the US. I hold Invesco Aerospace and defence (not a pure play).
Search for any O&G company that has no exposure to Russian assets. Most of the major British, French and Norwegian O&G plays have extensive exposure. Good bets are Baytex, Tourmaline, CNQ, Sandridge, Deveon Energy, Range Resources, or if you prefer UK assets, look at Serica and IOG. Avoid Kistos .... robbing bast*!ds. Look for gas tanker stocks as the German government have just approved financing for two new gas terminals (RWE will benefit). Look at the decent off shore drilling contractors like Diamond Offshore and Valaris. Valaris is out of bankruptcy and has a very clean balance sheet.
Serica has issued a RNS today. Production halted from Rhum for at least two weeks, faulty parts need replacing. Good hold otherwise.
Mccoll's Retail (LON:MCLS) The director who bought £3m shares had previously made £22m in the float, so not such a huge loss as it would be to the rest of us.
Hi Funnymoney,
Mccoll's Retail (LON:MCLS) The director who bought £3m shares had previously made £22m in the float, so not such a huge loss as it would be to the rest of us.
Thanks for flagging this, very interesting. I'm wondering if this might motivate the MCLS Director to back newco in a pre-pack administration, putting fresh money into newco, and writing off oldco? That would enable him to take a decent sized stake (say 10% for £5m [hypothetical figures]) of a £50m fundraise to buy oldco from the banks, minus the debt, and ditch all the loss-making sites and renegotiate rents down on everything else, leaving a much more attractive business going forwards, rather than pouring money down the drain in the old business.
It will be interesting to see who MCLS pans out but the existing equity now looks so high risk, it's highly likely to be worth nothing.
I note MCLS didn't say anything about the press reports saying some of the bank debt had been sold to hedge funds. That means the banks are already resigned to taking a haircut, and of course hedge funds tend to play hardball, so probably wouldn't be willing to waive covenants again.
At some point, the law on trading whilst insolvent kicks in, and forces Directors to place a company in administration. Otherwise they become personally liable for the company's debts, which tends to focus minds.
The upside case is that the store conversions to Morrisons Daily is delivering >20% improvement in store sales, which is very significant. So there could be a reasonable business that emerges from this, but the big question mark, is who will own it?
Regards, Paul.
Loved your opening title this morning Mr C. Gives me a chuckle to start the day
Blames reduced footfall due to covid. Mr C's 2nd paragraph caused a wry smile on my face, since Mccoll's Retail (LON:MCLS) outlets are basically cornershops I would have thought their convenience would have increased footfall. But there you go, as did my Mccoll's Retail (LON:MCLS) holding.
Mccoll's Retail (LON:MCLS)
Yes certainly seems slightly strange , presumably though they have justification for what they say as they have said it . Its probably factual more peeps have had omicron and been self isolating so perhaps other "shopping types" may have benefited - eg online ordering on sending someone else for bigger shop to stock up if they cant leave the house. I guess if loads of peeps are self isolating they may have resisted their xmas treats they would previously have gone to their local mccolls for so possibly peeps are simply living of the big xmas shop they would probably have done elsewhere - i think its a given the most peeps are normally overloaded with excess food and choccies come boxing day morning - personally i could probably quite easily do without food between day after boxing day and xams eve - would probably do me a good a nice 4 or 5 day fast.
Our local Mccol's has just become a Morrisons. Much more likely to pop in there now
Batm Advanced Communications (LON:BVC) has some results today - it would be interesting to get the SCVR view