Small Cap Value Report (Mon 28 Oct 2019) - SOS, CALL, WATR, CER, PHTM, IKA

Good morning, it's Paul here. I'll be writing all 5 reports this week.
Estimated time of completion - about 1pm.
Update at 12:28 - I'm running a bit late, as I spent so much time on Sosandar this morning. So with my apologies, am extending today's estimated completion time to 3pm.
Update at 14:33 - today's report is now finished.
Please see the header for the updates I've covered today.
.
.
Sosandar (LON:SOS)
Share price: 19.5p (up 23% today, at 08:19)
No. shares: 162.9m
Market cap: £31.8m
(at the time of writing, I have a long position in this share)
Sosandar PLC (AIM: SOS), the online women's fashion brand, is pleased to announce the following trading update covering the six month period ended 30 September 2019.
Today's update reads well, and is better than I expected.
The last update we had from Sosandar was on 23 Sept 2019, which I reported on here. I remember that day well, as I dashed around the London underground, mid-afternoon, trying to spot a Sosandar escalator panel digital advert, to no avail! Turns out that they only appear at peak commuter times. That update indicated that sales growth was strengthening, as promised, with sales in Sept roughly doubling on prior year. As I pointed out at the time, a good initial reaction to the autumn/winter range is usually a good omen for this peak season overall.
Sales growth - the LFL sales growth trend looks very positive;
Q1 (Apr-Jun) +23% - this was a big concern, and the share price sold off heavily when announced (understandably)
Q2 (Jul-Sep) +84% (including +112% for Sep)
H1 total +53% (£2.82m)
Oct >100% growth, over £1m (net of returns) revenues, for the first time.
Clearly we can see a very strong, improving sales trend.
Marketing spend - The strong sales growth trend has been driven by increased marketing spend, which is what the company said it would do, so no surprises there. That's why it raised £7m in a placing at 15p (heavily over-subscribed, which I know is true because my own allocation was scaled back considerably).
TV ads seem to be doing well;
These new marketing initiatives are significantly increasing brand recognition and awareness. September, the first month TV went live, saw a record number of email subscriber sign-ups with a 224% increase on August and the equivalent to approximately six months' performance in the prior year.
Incidentally, I was watching ITV last night, "Return of Alright on the Night", and nearly fell off my settee when a glitzy Sosandar advert appeared at the 9:30pm commercial break. It looked great, and is certainly very eye-catching, playing to Sosandar's strength in high quality imagery, from the joint CEOs background in fashion publishing.
Here is their TV ad. What amazes me is that they managed to find so many parts of Paris with hardly any people around, on a sunny day. From the angle of the sunlight, maybe it was filmed first thing in the morning? (Edit: yes it was, confirmed in my telecon). Anyway top marks here for some lovely shots;
Marketing spend is being further cranked up. This means extra costs & a higher loss this year & next.
Given the strong current trading and the very positive results achieved so far, the Board has taken the strategic decision to accelerate the growth of the business by investing further in TV advertising. Accordingly, marketing expenditure for the current financial year is expected to be higher than previously planned. This increased expenditure is expected to significantly enhance future growth through accelerated customer database growth and increasing frequency of purchase from a loyal and highly engaged following.
Repeat orders - the reason why it makes sense to spend heavily on marketing, is because the customer repeat order rate is high. In other words, once a customer has discovered Sosandar through its marketing, then many of them develop brand loyalty. This means that subsequent contact with that customer is either free (email), or low cost (brochures by post). This point is absolutely key to understanding the investment case for this share.
The numbers haven't been calculated yet, but the lifetime value of each customer could be very large, since Sosandar is turning out to have a very wide customer demographic. The core customer is aged 35-55 female, but the actual customer base is much wider than that. Therefore a new customer aged, say 25+ might still be buying Sosandar clothes 40 years later. That's not something that the fast fashion, youth brands can say, where the customer lifetime might be only 5-10 years.
Gross margin - no figures are given, but the company does say;
Entering Q3, the Company expects to continue with strong full price sales performance and expects some increase in AOV as the cold weather drives sales of higher price point items such as leather and outerwear.
That implies decent margins are being generated, from full price sales. I did wonder about this, as recently I received a 20% off everything email offer from Sosandar. I (wrongly) guessed that this must mean sales might be struggling. Querying it with the company this morning, they tell me that customers are segmented. I hadn't ordered anything for a year (when I bought a lovely velvet dress for my friend Gina, for her birthday - I still haven't got round to giving it to her, it's in a cupboard somewhere!). For that reason, I would have come up on a list of dormant previous customers, who were specifically targeted in a re-engagement email offer.
For this reason, it can be dangerous to draw general assumptions from Sosandar emails, which will be specifically targeted to different types of customer.
Returns rate - has improved from 52% last year, to 49% this year in H1. As the company has repeatedly said, this level of returns is just a cost of doing business. The strategy to grow the product mix into categories that have a lower returns rate (e.g. denim & accessories) appears to be working somewhat.
Active customer base - is only 75k, up 70% - clearly Sosandar is only scratching the surface of the potential market, which is massive, and international too of course. This is why I like this share. If it works, and reaches breakeven next year as planned, then the sky's the limit from then onward.
Of course, bears like to imagine that the company won't achieve that result, miserable sods! Mind you, I've not heard any bearish comments from sector experts.
Forecasts - note that whilst it's looking increasingly likely that Sosandar should meet the challenging growth forecast for this year at the top line & gross profit level, the operating loss for FY 03/2020 is now forecast to be £3.8m - a good bit worse than the previous forecast of £2.3m. Therefore bulls need to be clear that this is still a highly speculative share, and that it's burning cash in order to achieve the growth.
The reason why this is fine, in my view, is that marketing spend is a genuine investment - it's buying repeat, loyal customers, not one-off purchases. After the £7m fund raise there should be plenty of fuel in the tank to reach breakeven next year. No current cash figure is given, but the latest forecast assumes £4.7m net cash remaining at 03/2020, and £2.9m at 03/2021.
My opinion - this update considerably strengthens management credibility. The Q1 bombshell of only 23% growth did dent investor confidence. However, everything management said at the time, about growth accelerating in the key peak trading period of autumn, has turned out to be correct.
That's come at a cost though, in greatly increased marketing spend. That's why they raised more money in the £7m placing earlier this year, so shouldn't come as a surprise to anyone.
Overall, I'm a lot happier today, than I was yesterday.
This share is all about backing high quality management, who really know what they're doing. That's becoming increasingly evident, as the business achieves very ambitious growth targets. Once it's into profit, and self-funding further growth, then we could be onto something very exciting indeed.
Bear in mind also that Sosandar is planning to engage with online platforms, so there's more growth to come from that (effectively wholesaling) route.
Not for widows & orphans, this remains a speculative, loss-making company. But with exciting potential that seems to be working out reasonably well, albeit at higher cost than originally planned.
Call with management - this was a bit of a rush, but hopefully I got answers to some points people asked about;
Q1. Gross margin - no figures given. Narrative talked about high level of full price sales, so am I correct in assuming that gross margin is in line with expectations?
A1. Yes.
Q2. Why is cash figure not mentioned?
A2. I don't think we usually give the cash figure in trading updates. But you'll see all the numbers when the interim figures are published.
Q3. Repeat order statistic of 1.66 - please can you explain how you work this out?
A3. This is order frequency (per customer). It's worked out in the same way as Asos & BooHoo. Calculated as total orders, divided by active customer base. Because we're growing so fast, a lot of orders are from first time customers, which suppresses this metric. If we strip out new customers, the rate rises to about 2.0 times. i.e. an established customer orders from Sosandar about twice per year. This is rising, and customer churn is low.
Q4. TV ads look great, but must be very expensive?
A4. We've worked out a cost effective way of producing the video content. That can then be used in multiple ways, e.g. TV, social media, London underground digital panels by escalators, etc. We closely monitor the uplift in website visits & email sign-ups for every slot where the TV ad is played. So we calculate ROI for every play of the ad, enabling us to fine-tune which slots (times, and specific TV programmes) work best. Not as expensive as you might think. There's a longer tail with TV ads - i.e. immediate sales yes, but also subsequent sales once customers have signed up for email list prompted by a TV ad.
Q5. Are you feeling downward pricing pressure from competitors?
A5. No. Our price points are chosen very carefully, and things tend to sell at full price if we get the price right first time.
Q6. New factories working out?
A6. Yes, we've broadened the supplier base considerably and it's going well.
Management sound upbeat (they always do!), and said they're happy with the way things are progressing.
.
.
Water Intelligence (LON:WATR)
Share price: 287p (up 8% today, at 10:19)
No. shares: 16.9m
Market cap: £48.5m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence" or "Company"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide a trading update for year-to-date through the end of the third quarter.
I'm getting a sense of deja vu reading this announcement, and the reason is that it used the same wording with its interim results about a month ago, which I reported on here.
Today: Results for 2019 through Q3 are ahead of market expectations for revenue and comfortably in-line with expectations for profits before taxes (statutory and adjusted).
30 Sept 2019: Results are ahead of market expectations for annual revenue and comfortably in-line with expectations for profit before tax.
Outlook comments sound upbeat today;
"Moreover, we believe strongly that our technology investments will enable us to sustain our growth trajectory in 2020 and beyond. Given our installed base of service operations, especially across the US, and the strength of market demand for both potable and non-potable water infrastructure solutions, we have a considerable opportunity for realizing significant value for our shareholders...
My opinion - it looks quite good.
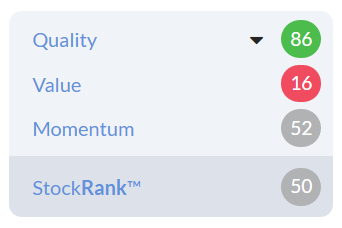
The rating looks full, for a fairly small company, on about 23 times 2019 forecast earnings.
Stockopedia reflects that - good quality, but expensive;
.
.
Cloudcall (LON:CALL)
Share price: 99p (up 2% today, at 11:29)
No. shares: 38.7m
Market cap: £38.3m
(at the time of writing, I hold a long position in this share)
I don't usually comment on "holding in company" announcements, unless there's something of wider interest. The reason for mentioning this one today, is that CloudCall appears to be attracting interest in the USA. Why does that matter? Because US investors value tech/growth companies very differently (i.e. much higher) than we do in the UK. They take a longer term view, generally value this type of company at multiples of the UK, and are much more relaxed about cash burn. They want growth above all else. This approach, combined with vast available funding, is why the USA leads the world in tech companies.
Today, Long Path Partners LP has popped up with a 7.75% (3m shares) stake in CloudCall. Its website describes Long Path like this;
Long Path Partners is a privately-owned investment firm that manages two concentrated equity Partnerships. The Firm employs an ‘ownership’ approach to public equity investing. We seek to compound capital by investing in high quality, predictable businesses that we intend to own for the long term.
It's based near New York, in Stamford. All of which makes me wonder how on earth they came across this tiny AIM-listed company? Looking at the major shareholders list, Long Path already had 2m shares (5.16%), so I'm wondering if perhaps they bought another 1m in the recent placing?
There's another American fund, called Kinderhook 2 LP, which has 11.2% of the company.
My opinion - this is getting interesting. CloudCall operates in both the UK, and USA. The USA is about 40% of its business, and there are obviously much greater growth opportunities there than in the UK, as its economy is something like 6-7 times the size of the UK's. I find it very interesting when a UK company succeeds in breaking into an American market, as its very difficult to do so.
CloudCall's recent big placing, means it has plenty of cash to deploy for faster expansion, which is the plan. Expansion into Australia is happening now, and it is bidding for some much bigger global accounts.
All of which makes me feel that, rather later than originally planned, CouldCall looks as if it could take off. The Yanks think it's cheap by the looks of it, so I wonder if the end game might be a takeover bid from across the pond? It's starting to look more interesting.
.
.
Cerillion (LON:CER)
Share price: 188.5p (unchanged today, at 12:39)
No. shares: 29.5m
Market cap: £55.6m
Cerillion, the billing, charging and customer relationship management ("CRM") software solutions provider, is pleased to provide a trading update for its financial year ended 30 September 2019.
I've been impressed with this company lately. It had some problems earlier this year, with large lumpy orders causing it to deliver a weakish H1. The outlook commentary at the time promised an improved H2. That old chestnut of an H2 weighting! However, kudos to the company, as it has delivered the stronger H2, and today indicates that its results for FY 09/2019 will be in line with expectations. Note that expectations have not been lowered either, so this is a bona fide in line outcome for the year just ended a month ago.
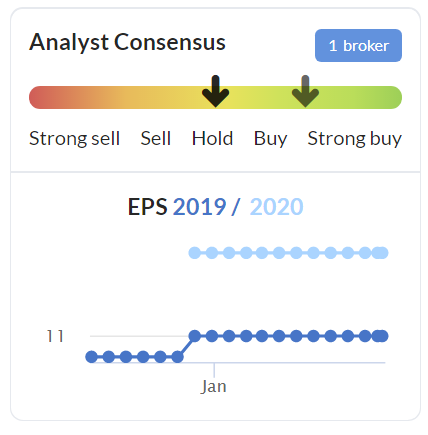
The y-axis hasn't worked properly there. The light blue blobs for 2020 forecast EPS are 11.8p.
.
Big contract wins - this is reiterating what previous announcements have said;
As anticipated in the Company's Interim Results in May, trading has been significantly second half weighted this year due to the timing of contract closures. The second half of the year saw Cerillion sign three major contracts, with these new wins continuing the trend towards larger deal sizes. Over the year, major new contracts were secured from all the Company's key international geographies, Europe, the Americas and Asia-Pacific.
My opinion - I like this share. Management has a lot of credibility, as it has steered investors accurately through a year with lumpy contract wins.
The forward PER of 16.0 looks about right to me for now. Although with some large contracts under its belt, that looks a good reason to expect further growth in FY 09/2020 maybe.
Worthy of a closer look, I'd say. I imagine contracts in this sector would be quite sticky. Therefore there could be nice, operationally geared upside, if it continues winning big contracts. Shareholders also get a 2.8% dividend yield.
.
.
Photo-me International (LON:PHTM)
Share price: 86p (down c.4% today, at 13:32)
No. shares: 378.0m
Market cap: £325.1m
Photo-Me (PHTM.L), the instant-service equipment group, announces the following trading update covering the period from 1 May 2019 to 30 September 2019.
I'm not sure why it's providing a 5-month update, instead of waiting until H1 was finished?
In the period to 30 September 2019, overall Group trading has been in line with expectations, underpinned by continued growth in Continental Europe and Asia, led by the Laundry business, despite trading in the Identification division in the UK remaining challenging. This has been due to continued uncertainty around the UK's European Union exit negotiations, leading to lower consumer activity, and the UK Government's decision to allow for photos taken on a smart device or camera at home to be used for passport photo identification.
That last bit is the major concern about this business. Its photo booths, mostly used for passport & other ID photos, look very much like a legacy business that maybe won't exist at all in a few years' time, if smartphone photos become generally accepted in its other geographies. Alternatively, it might end up being the case that booths become more necessary, in order to securely capture & send to Government agencies not only a photo, but also biometric data connected with that person.
PHTM also operates in other markets, such as laundry machines, other kiosks, and there was talk of introducing self-service banking kiosks too. With various geographies having different dynamics, it all looks far too complicated for me to be able to work out what's going on, let alone predict what might happen in the future. I think researching this share would need a lot of work, to understand what Government policies are likely to be in its various markets.
My opinion - people have been predicting the demise of this business for about the last 20 years. Yet it's still churning out big profits & cashflow, and paying a whacking great 9% dividend. That very high yield is the market clearly signalling that it doesn't see the dividend yield as sustainable. If the market's wrong, then the share price would recover well from here.
I would have to spend days solely focused on this one share, to understand all the different markets, and products, that this company offers. Even then there would be a lot of guesswork involved, to form a view on the future prospects of each. That means I have to file it in the too difficult tray. But good luck to holders. This company does have a long track record of multi-bagging from near-death experiences. Just look at the long-term chart below;

.
.
A couple of snippets to finish off with;
Ilika (LON:IKA) ( I hold a long position in this share) - invites investors to apply to attend a company visit, in Romsey, near Southampton, on 5 Dec 2019. I attended a similar event in Jan 2014. The company's laboratories are like something from a 007 Bond film - everyone wearing white coats, machines whirring away with robotic things inside them, doing stuff.
The narrative was tremendously exciting, and a number of us on the visit texted our brokers to buy shares in this tremendously exciting company, developing new materials, and solid state batteries. We thought we were geniuses, when the share price shot up from c.25p to c.100p. It then took nearly 4 years to come all the way back down again!
What's happened since 2014 then? The share count has doubled, and it's generated losses of £3-4m each year, with nothing of any commercial value having been achieved, seemingly. Revenue is mainly Govt grants. It all looks pretty dismal.
That said, I've kept a tiny residual holding, just in case something commercially viable does eventually come out of Ilika. It's working in a very interesting area, of battery technology.
If the share price 4-bags again after this next investor visit in Dec 2019, then I'll happily release my shares into the market for someone else to treasure!
.
OK, that's me done for today. Hopefully this has been useful/interesting for readers, and thanks for your comments.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Just looked at Cerillion (LON:CER) and I reckon there's a short hypothesis for the company...being a bit contrary but started looking with interest and then felt that it might not all hang together well. View welcome...put me right...here's my quick notes from looking for anyone interested or who likes the stock to counter me...
1) High customer concentration
2) Recurring revenue only c.33% of total and think the valuation implies its more as a slow down in customer acquisition could have drastic impact,
3) £1m pa director remuneration on £17m revenue, Workforce of other 185 get £8,5 (mainly support staff software engineers in that number -> £46k total remuneration average -> suggests that the development work is pretty low value).
4) gross margin of c.72% based on accounts likely overstated as 70% of revenue comes from 'ad hoc' services supplied rather than recurring software based stuff. Only c.30% from recurring (ie more rev requires more elbows to the wheel and for like for like with 'industrial' company means cost of sales should be higher. In addition near 10% of annual wage cost is capitalised
5) Doesn't make sense not paid down debt quicker
6) Very low expensing of R&D which hints that the development being capitalised is all standard customer work rather than anything fancy and new. This work should be expensed knocking £800k off of profit. Its an old business and so this is just accounting manipulation to overstate profit,
7) relatively high bad debts in trade receivables suggests that they have payment vulnerability in industry chain
I think that Cerillion looks quite vulnerable to any setback in customer wins or big customers and like they provide a product that may be vulnerable to capital cycle events in end client (telecos mainly)
I am new to stock trading and find Stocko a fantastic education tool. I also really value the daily reports Paul. However, I am somewhat surprised at the positives for Sosander. I appreciate they are trying to market their way into profit using investor’s cash and also that high returns are a feature of an online clothing business but half the purchases returning? That seems incredibly high for a very small new brand with a good demographic customer match and great ads which promise so much, or am I just a grumpy old bear today?
Sosandar (LON:SOS)
I appreciate they are trying to market their way into profit using investor’s cash and also that high returns are a feature of an online clothing business but half the purchases returning?
Hello Chriskay
I think if you look back at the previous discussions on Sosandar (you can search for previous days where the stock has been commented on and go to discussions) you will find there has been pretty thorough discussions about the returns % - as long as the gross margin is reasonable enough the % of customer returns is completely meaningless. looking at boohoo gross margin is 54% and Sosandar manages 55% - don't know if this is a fair lfl comparison but as long as the margin is decent enough the level of actual returns isn't too important. The high returns rate is just a symptom of the fussiness and of the customers in the market sector they work in :). I think is par for the course this sector type will have to try and 3 to find one they want to buy - if their customers are keeping 1 out of 2 thats probably pretty good going :)
Why do so many folks get hung up on returns? Have you seen the number of garments women in particular try on in a store before they buy? They hand back a lot more than 50% there. Dealing with returns is an unavoidable cost of not having to pay for shops and changing rooms. So long as SOS isn’t out of kilter with other online female brands - and it isn’t - it’s not worth worrying about.
Hi Chriskay,
The returns rate for online womenswear is typically 40-50%, that's the industry norm. It makes sense if you think it through. When trying on clothes in a physical shop, it's normal for people to buy about half the items they choose, and put half back. So it's the same online, where the customer's own home is the fitting room.
A lot of women tend to order 2 sizes of the same style, keep the one that fits best, and return the other. Shopping habits have also changed in recent years, such that women often deliberately over-order, then keep the items they like best, fully intending to return quite a lot of the things they order.
If you talk to Sosandar (LON:SOS) management about this, they regard it as "a cost of doing business", and try to manage it down, but it's not something that concerns them. The CFO referred to it as being "some additional administrative costs", but he's not worried about it in any way. So neither should investors be worried.
SOS has a big advantage, in that its average order value is about £100. Therefore, paying (guessing here) maybe £5 in additional costs for postage & the outsourced warehouse to handle returns, is not a problem. Returned stock "goes straight back out again" to a new customer. SOS management has told us before that they don't have a problem with customers abusing the returns policy. That might possibly be because they serve a more mature, affluent customer, possibly?
Overall then, returns is not an issue that investors should worry about.
Regards, Paul.
Hi Paul, or anyone else who can help,
A quick thought on Sosandar (LON:SOS) margins.
If:
then does this mean the "adjusted" Gross Profit per order = £21 or 21%?
And presumably one would need to take away postage/warehousing costs from this, though I'm not sure where postage costs sit in the P&L.
I have no idea if this is a positive/negative adjusted figure for an online fashion business, just trying to get my head around the figures.
Cheers
A
Photo-me International (LON:PHTM) I have been a holder for some years and recently attended the AGM to try to get a better understanding. It does seem a play on whether global acceptance of smartphones for official ID purposes will ruin them before laundry/fruit juice become big enough to more than compensate for ID decline. Think CEO (and 20% + shareholder)Serge Crasnianski said decline in UK ID revenues was about 23% on last year, so other geographies are holding up well and weak sterling will help. What was clear is that laundry is growing as planned and Sempa (fruit juice) is trading very well, with payback now looking likely to be no more than 3 years. Cash implications will become clearer when half year results come out 10th December, but the business still looks to be throwing off lots of cash at the operational level. I suspect that if dividend is cut at all, it will be for good reason i.e to invest more in the growth areas. One likely bonus this year comes in the form of an investment property they hold (factory in Grenoble let at just over £1M p.a to decent covenant and being put on the market for sale). Rents on this were forward sold in 2011 until April 2019, but now revert back to PHTM. Valuation was reduced when the rental deal was agreed and it is in the books at just £648K. Looking through my rather rose tinted spectacles, I added a few more to my fairly modest holding after the AGM, so disappointed with the reaction today.
Paul, thankyou for your excellent coverage of SOS today and also for your coverage generally. Both your and Graham's analysis have really improved my understanding generally. I'm still relatively new to stocko but have decided to subscribe for a second year thanks in part to the work you two are doing.
Hi Phil,
I'm still relatively new to stocko but have decided to subscribe for a second year thanks in part to the work you two are doing.
Excellent news, thanks for your kind message of support!
Regards, Paul.
I would have Instagram users represented a younger cohort than the average SOS buyer. Happy to be proved wrong.
Must say their models are rather attractive..or are you no longer allowed to say such things?
Why don't they send some stuff in the post to Diane Abbott?
Haha, that reminds me that one of my suggestions to Sosandar (LON:SOS) management was that they try to get Angela Merkel to wear one of their frocks. I didn't get a reply.
Very good report today Paul, you sure have put the hours in including your Sosandar (LON:SOS) management call. Personally I think you've gone the extra mile so I have no idea why two muppets would give you down votes as it's absolutely undeserved. All done before 3pm is really impressive too.
cheers
Francis
Thanks Francis, much appreciated. I am trying to improve the quality, timeliness, and depth of these reports, so it's good to hear you noticed!
I switched to the new site today. One of its advantages is that I don't see the thumbs downs at all now - just the net total, so am delighted with that change. Our 2 resident thumbs-downers are now completely invisible!, which means they can no longer demotivate the writers here.
On Sosandar (LON:SOS) one thing I do is follow how many Instagram followers they have as a proxy for the interest in the brand. In fact you can do this fairly simply with any retail brand really (depending on demographic for products). It can allow you to get ahead of news in a trading update by seeing the trend before it comes through in sales.
Ideally I need to be looking at the same periods of time to factor in any seasonal variations, but I at least calculated how many followers gained per day since the last update which is still useful.
19-10-19
34.9k (92 new followers a day)
6-10-19
33.7k (60 new followers a day)
6-7-19
28.2k (32 new followers a day)
28-12-18
22.1k (42 new followers a day)
31-12-17
6,560
I'd been seeing that followers had increased quite a lot recently so was hoping to buy this morning for the first time at 16p but typically there was then the trading update which confirmed that things seem to be going well at the moment. I still got in at 17.2p though so can't complain too much!
In terms of fundamentals, at 3x expected sales it's priced similarly to Boohoo (LON:BOO) so I don't see this as particularly expensive for a fast growing stock providing they can continue to execute well.
I'm curious about the relationship between Instagram followers, and sales. I'm a bit sceptical about it. A private eCommerce business which I seed-funded, has got more Instagram followers than Sosandar, but it literally hardly sells anything.
I can't remember specifically what Sosandar management said about Instagram followers when previously asked, but am pretty sure they said that it's not a good measure of what people are actually buying.
Sosandar (LON:SOS)
Graham Ford
See what you’re saying but other companies’ interims seem not to have this issue (expected revenue rather than actual). Take a look at Boohoo’s interims from September
I guess each company has its own criteria as to how confident they are in stating numbers - so rather than look for companies that don't do what Sosandar do lets look at some other companies that do and hopefully that will confirm the principle that not all companies confirm turnover as being quantified exactly until release of interims or finals. I would expect the smaller the company and/or the more moving parts (eg trading outlets - sub companies) the more likely it is that they will err (rightly) on the side of caution in this regard.
Here are two example which use similar wording to Sosandar - that's two of my current holding so i didn't have to go looking too far to find companies that are similarly circumspect about quoting finalised numbers per the "trading update before any interims or finals"- i haven't ever taken this as suggesting the company has any specific reservations about the numbers.
Norcros (LON:NXR) trading update 17/10/2019
Group revenue for the 27 week first half is expected to be approximately £181.2m (2018: £162.6m),
Portmeirion (LON:PMP) trading update 17/1/2019
Portmeirion Group, the manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel and Wax Lyrical brands, is delighted to announce that it expects to report record revenue for the year ended 31 December 2018 of at least £89.2 million.
Note your comments ref Boohoo - you seem to be mixing apples and pears there - Boohoo only quoted the actual numbers when they released the interim accounts - the trading update earlier in the month didn't have any specific turnover numbers that i could see. I would always expect confirmed numbers when we have 3 monthly / 6 monthly or final accounts being presented but NOT when its simply an after period trading update with no accounts. When when sosandar release the interims the figures won't be subject to the same caveat they used per the trading update.
Paul
I have learnt its generally not a good idea to buy dresses or clothes for women, unless you are some sort of style guru, and as you commented in the past about shopping at Primemark for teeshirts, I am guessing this is not your strongest area. So maybe its best you keep the dress in a cupboard unless you provide a receipt, and returns number and expect never to see it worn, except by some miracle of happenstance she likes it. :-)
I bought some Sosandar (LON:SOS) shares and have since sold out. I think the ads look good. So it will be interesting to see if it can escape its possible destiny as an online boutique offering. Sometimes a brand catches fire, and this may well happen. I think you can legitimately look at statistics in the round, but I think growth in this instance is the key metric that will prove the concept of a stellar stock. Weren't they using other channels to sell through as well as online? So if the ads are working on generating brand recognition, I would expect at least some of these other channels growth to help prove the concept.
But as mentioned this is an area on which I would hesitate to have any useful views, but being a man, lack of knowledge is never going stop me having an opinion.
Sosandar (LON:SOS) have obviously done a good job with the large increase in sales but I do find some the metrics quoted don't give me the clarity and specifics I need to conclude on the investment.
to me Repeat Order levels of 1.66 might imply that if a customer orders once then in the next period they order 1.66 times. Thus sales should be rising by 66% without any marketing spend. I know this is simplistic etc..
I am also confused how the metric has risen year on year. It is calculated as total orders up 47% year on year,
divided by the active customer base up 70% year on year
I don't understand how if the bottom part of the equation has increased more that the ratio has risen.
Probably to do with phasing, or monthly averaging or seasonality etc... but I have a lack of trust if the logic of figures quoted don't cross calculate. I would rather have the full detail of the calculations reconciled to published figures in an appendix.
the customers are described as 'sticky' yet the active customer base has declined from 84,500 total customers a year ago to the current active customers 75,056. So despite 12 months to recruit more active customers (with a very large marketing budget!) the number of active has reduced. So obviously not all customers are returning which is to be expected but I would like to know what is the retention rate - like insurers have renewals % for insurance.
my last statistic gripe is (as I predicted with a previous post) they have boasted about a fall in the returns rate. The reality is that they have sold a total different mix of product (they talk about this and this is why the average basket size is reduced) and they have explained before that women's fashion dresses have the highest returns rate. So the lower returns rate in this period is nothing to do with customers liking their product more - it is down to sales mix. Again I would appreciate the accuracy and specificness if they also said that within returns in Like for Like product categories had declined.
for me, because I cant fully understand the statistics as I would like to, it builds up a scepticism. so I wont be investing. I am not saying that I think there is any inaccuracy just that it is outside my comfort zone.
DISC: no position
Some interesting bear points which (as an investor) I felt worth pursuing. Here's my response to some of them:
to me Repeat Order levels of 1.66 might imply that if a customer orders
once then in the next period they order 1.66 times. Thus sales should be
rising by 66% without any marketing spend. I know this is simplistic
etc..
No, I think the repeat order level is simply an indicator of the value of the customer. If it stayed unchanged between periods and the number of customers stayed unchanged then the number of orders would too. An increase in sales would then be due to an increase in customers.
I am also confused how the metric has risen year on year. It is calculated as total orders up 47% year on year,
divided by the active customer base up 70% year on year
I don't understand how if the bottom part of the equation has increased more that the ratio has risen.
I think it might be worth bearing in mind that 'active customer base' will be reported at the end of the period. It won't be that high throughout the period, especially when the big marketing push is at the end.
the customers are described as 'sticky' yet the active customer base has
declined from 84,500 total customers a year ago to the current active
customers 75,056. So despite 12 months to recruit more active customers
(with a very large marketing budget!) the number of active has reduced.
I think perhaps you are comparing apples and oranges. The 84,500 figure was the size of the customer database (i.e. the size of the mailing list) last period, compared with 44,096 active customers. The figures for the latest period are 148,884 and 75,056. Both measures have clearly increased rather than declined.
Sosandar (LON:SOS) just goes to show the value of free to air advertising, despite the rise of the internet.
I used to invest in Photo-me International and so follow them for interest. Not sure what catalyst is required to return them to their glory days, although their auto-washing machine business seemed to be working well.
J
Paul, I remember well your fruitless chase to find the digital adverts for Sosandar (LON:SOS) - To me the savvy spend just in peak periods (target audience) speaks volumes about their knowledge and focus for the business - I don't currently hold but maybe should
Ezlifeme - I'd be very surprised if peak time digital tube ads were not priced differently (ie higher) than off-peak times. So unless we know what they paid and how many orders it generated we don't know if they are savvy to do so or not! P&G used to buy bucket loads of off peak TV ads for proverbial buttons (as well as expensive prime time ads) as they found it cost effective and reached a different audience.
Whilst I don't know if they will keep with tube ads, the very fact that they are testing before going big and exploring alternative options with costs related to orders ie revenue, gives me confidence they will ultimately their money spend well. I hope so as I hold.
There's a positive Q3 update today from Water Intelligence (LON:WATR) :
Results for 2019 through Q3 are ahead of market expectations for revenue
and comfortably in-line with expectations for profits before taxes
(statutory and adjusted).
Sosandar (LON:SOS)
An interesting update today.
One thing that caught my eye was the announcement of Q2 revenue (£1.77m) being 84% up Year-on-Year.
Based on previous announcements Q2 2018 revenue was £0.99m*, so in fact a 79% Year-on-Year increase.
Why the discrepancy? This should be a fairly easy metric to get right and it's not the first time a Year-on-Year figure published by the company didn't match up to their previous announcements.
It is of course no big deal if the company is growing at such a rate, but I do question whether I am making a mistake somewhere, or if the finance team made a mistake/exaggeration around 2017-18 (I think they did) and therefore subsequent quarterly YOY figures that are published are therefore impossible to calculate.
A copy of my workings are below for any interested.
Cheers
A
NB: All numbers below are calculated from numbers published by the company.
Ingenta (LON:ING)
I'm going to guess this company has very little interest given its a hotch potch of small revenue products that has seen decline for many years. Anyway if you are interested, I have a question....
Why in the restated H1 2018 results used to compare H1 2019 results is there a reduction in the revenue by £1.3m and drop in operating profit of near £900k to a £564k loss with the only explanation re the restatement being that they adopted IFRS 16?
I've spent too much time puzzling this minnow for now and hoping someone has a to hand explanation?....thanks
Paul
Could you comment on the way Sosandar (LON:SOS) have expressed their revenue please? They say “expect” to report revenue of £2.82 million for the period ended 30th September. Why would this only be an expected number rather than an actual number? Surely you know exactly what orders you have taken and dispatched and so the revenue is the one number there should be certainty about. It’s a small e-commerce business not a hugely complex organisation with lots of manual adjustments.
Is it that they are making provisions for future returns (which are huge by the nature of the business) and so until the deadline for returns has expired you don’t really know if you have sold something or not? I don’t recall Next or Boohoo reporting interims only as an expectation.
Sosandar (LON:SOS)
Graham ford
"Could you comment on the way Sosandar (LON:SOS) have expressed their revenue please? They say “expect” to report revenue of £2.82 million for the period ended 30th September. Why would this only be an expected number rather than an actual number? "
There is a pretty simple answer to this - the accounts haven't been fully completed yet (interims) . Until the accounts have been fully completed they rightly have no certainty that the final figures will end up exactly the same as the calculations they have done - albeit one would normally expect the figures to be the same a very high % of the time. Note how to annoy an accountant in one easy step - ask them what the final figures will be before a set of accounts have been finalised.
I wouldn't read anything strange into this wording and i would be very surprised if the numbers don't come out as stated - albeit even if they don't that's as fine as long as the explanation provided is reasonable or the difference is not material.
See what you’re saying but other companies’ interims seem not to have this issue (expected revenue rather than actual). Take a look at Boohoo’s interims from September
Hi Graham,
I agree with what rmillaree has said above - i.e. the wording just sounds cautious, in case there are any final adjustments to the interim figures. I wouldn't worry about it - it's not anything significant.
Regards, Paul.
Boohoo will also likely have end-to-end automated returns which also update their ledger. This might not be the case for Sosandar.
Sosandar (LON:SOS)
Figures look to be semi back on track
Last year h2 sales were 2.6 mill - if we say they do 120% of that total that would be 5.7 mill + 2.82 h1 = 8.5 mill for the full year. Note that is a full million short of current estimates - but we still have the busiest period ahead so time to find that missing million. In some respects if there is slight shortfall they have done well to get where they are factoring in the slow start to the year. I can't see any explicit mention whether they are still on track for £9.5 mill revenue (slightly annoying) so thats all my guesswork.
The sting in the tail here is the extra spend they need now to get where they want to be - albeit we don't know if that may be ahead of the 9.5 mill previously advised. I guess we shouldn't really be surprised the cash is getting deployed quickly.
Overall i take the viewpoint they have slipped slightly from where they hoped they would be pre fundraising (note they don't concede that fact anywhere) - they appear slightly behind sales trend (this may not be the case if they know autumn/xmas will be super bumper) and they are splashing more cash than they expected as they have more. All correct business decisions but i am not 100% convinced the optimistic pre fundraising expectations are quite being met. Ignoring that quibble generally speaking the more important thing is that the sales growth is still enough i would guess to please the fans here.
Perhaps one request for management would be less of the 100% + / record figures quotes and more info on where they are compared to previously released expectations for the year thank you.
I agree with this. After the last set of results I find myself reading back through the other results to make some kind of comparison myself, I too get they are a little behind.
One quibble I may have is that it seems that the investment case is based around their investments in marketing being 'sticky' (in that once people are introduced to the brand they will come back again and again), but the repeat order rate is unchanged (1.66%) from the last annual report. As some of the earlier cohorts of customers have had more time to become repeat customers I'd have thought this metric would be rising.
Perhaps I've misunderstood this metric, but it would be good to know at what number they envisage this settling out at.
Hi Snoo,
I asked management about the repeat order rate. It's not 1.66%, but it's that an average customer orders 1.66 times in a year. This is suppressed by the high volume of first-time customers placing orders. Stripping out those, the underlying rate is that an established customer orders from Sosandar about 2.0 times per year.
See the main article, near the end of the Sosandar section, where I did a Q&A with management over the phone, at about 9:30am today.
Hopefully that helps clarify things for you and others! (including me, as I'd forgotten how they calculate that stat).
Regards, Paul.
My morning smallcap tweet: LEAF payout wilts.
Leaf Clean Energy Co (LON:LEAF), Sosandar (LON:SOS), Autins (LON:AUTG), Cerillion (LON:CER), Water Intelligence (LON:WATR), Photo-Me International (LON:PHTM)
Leaf Clean Energy (LEAF) returns rump cash -122p/sh. Has 159p/sh cash at present. Keeping a surprising £6.5m for further costs and liabilities, including: £2.7m for incentives plans payments to employees and directors relating to the Redemption. These guys don't wait for a tip, they just take it straight out of your wallet.
Sosandar (SOS) H1 tradimg. Rev up 53%, and Q2 up 84% as it turns on the marketing taps again. Returns reduced to 49% (52%). I hold.
In line: Autins (LON:AUTG), Cerillion (LON:CER), Water Intelligence (LON:WATR), £PHTM
Sosandar (LON:SOS) seconded - I hold. I'd also like to hear the possible bear case from readers / Graham!
Hi runthejoules,
I'd also like to hear the possible bear case from readers / Graham!
The bear case on Sosandar is very simple - that the company is only achieving rapid growth by spending a load of money on marketing (which is true). Bears think it could run out of money again before achieving breakeven. And/or that growth might stall.
What the bears don't get, is that marketing spend is actually building a rapidly growing, loyal, repeat customer base. Hence money spent now, has a long-term payback, so it's money well spent.
You can't build a new brand without spending a load of money on marketing. This is why a lot of smaller e-commerce fashion businesses are now biting the dust. They're easy to set up, but very difficult and expensive to achieve scale.
With hindsight, the original Sosandar business plan significantly under-estimated the marketing spend needed. Although practically all small, growth companies that list on AIM, under-estimate the cash burn, and under-raise. I wish brokers/promoters would build in a large contingency reserve into growth companies which float, as this problem happens time & time again. In fairness, part of the problem is that founder management often don't want to be diluted themselves.
However, with the Sosandar coffers freshly refilled, management is really going for it now, which is what most shareholders want. Hence why the placing was so well received. Investors want management to scale up the business fast, not fall into the usual UK trap of doing things by halves, and never quite making it.
Regards, Paul.
Hi Paul,
Can you please cover Sosandar (SOS) trading update briefly before market opening? Appreciate that.
Morning Pavel,
I'm just reading the Sosandar (LON:SOS) H1 trading update for the second time, and making notes on it. Also I'll need a bit of thinking time! So a full section will appear in today's report a bit later.
However, my initial reaction is positive. The sales trend looks very good, and is performing how they guided. That's coming at the cost of increased marketing spend, but I think that's what investors want them to do - going for growth. These things can't be done by halves. Once customers have bought something from Sosandar, they tend to become loyal. Hence the customer lifetime value could be enormous, spanning 30+ years potentially, due to the demographic being a lot wider than originally planned. Core demographic is 35-55, but they're actually selling a lot either side of that range as well.
More later. I'm also hoping to have a quick call with management at some point today.
Regards, Paul.
Many thanks Paul for being able to find time to reply in a busy morning