Small Cap Value Report (Mon 30 Sep 2019) - CALL, WATR, CTG

Good morning, it's Paul here.
Please see the header for the results & trading updates which caught my eye, on my initial sweep of the RNS first thing.
Estimated completion time - I'm writing mainly this afternoon, so should be finished by about 8pm. Update at 17:19 - I'm exhausted, and need a break. So will finish off later this evening. Actually, I'll put any further updates from now on into tomorrow's placeholder, so that people don't have to keep checking back to see if this report is updated or not. Hence this report for today is now finished.
Cloudcall (LON:CALL)
Share price: 98.5p (down c.7% today, at 12:48)
No. shares: 26.6m existing shares + 12.0m new shares = 38.6m
Market cap: £38.0m
(at the time of writing, I hold a long position in this share)
CloudCall is a software-as-a-service ("SaaS") and unified communications business ("UCaaS"), that has developed and provides a suite of cloud-based software and communications products and services, which enables organisations to leverage data in CRM systems to enable more effective communications.
There are 2 announcements today, interim results, and yet another placing
This is a conditional placing & open offer, at 100p per share. This is a pleasingly small discount to the previous market price, which I am pleased about. Placings are only a problem, if existing shareholders are diluted a lot, at a big discount, which is not the case here.
What is striking is how much larger this £12m placing is, compared with previous fundraisings. The company seems to be significantly scaling up its ambitions, stating;
Funding customer led growth capital opportunities, with ambitions to achieve >£50 million in annualised run-rate revenue by 2025
To put that in context, the annualised run rate of revenues at June 2019, was £11m, so increasing that to over £50m in the next 5-6 years is a big deal, that could trigger a re-rating of the shares, possibly.
To have got away such a (relatively) large placing, in very tough markets, demonstrates that management must have told a very convincing story to institutions & high net worth investors, in the meetings that usually precede placings.
A couple of more general points;
Liquidity - for companies this small, the institutional & private investor markets are almost completely separate, which can create strange anomalies where private investors are negative and constantly selling, at the same time as institutions are enthusiastically putting money into placings. The CEO of a listed company told me that most institutions don't tend to transact in the open market for any share unless/until the free float has reached about £250m - under that level, there isn't usually enough liquidity for institutional transactions.
Public vs private? - my view is that a stock market listing often holds back UK growth companies, because UK investors starve them of funding, and prioritise reaching profitability over more rapid growth. This is why so few UK small tech companies achieve decent scale. The approach in the USA is the complete opposite - they throw big money at startups, and don't care about profitability. That may seem crazy to us, but it's a key reason (aside from its economy being 6-7 times the size of the UK's) that the USA produces so many globally dominant tech/growth companies.
Back to CloudCall - this is a great example of a company that has consistently under-estimated the funding it needed, and had to repeatedly come back to the stock market for more money. Every time it assured us that it now had enough money, but despite this, came back over & over for more. This has held back growth, held back the share price, and annoyed investors - denting confidence in management.
I think growth companies like this are far better off in private ownership, with shareholders that are prepared to pile in enough money to rapidly scale up right from the start.
There's a neat summary of the upside case in the placing RSN;
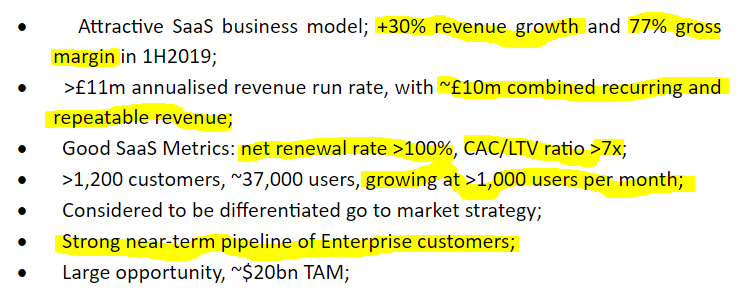
(note: CAC/LTV >7x, means that the lifetime value of a customer is estimated to be more than 7 times the original cost of acquiring the customer)
My view - I'm surprised the company has gone the other way this time, and raised more money than it needs. This is confusing, because in the past management has been reluctant to dilute their own holdings, which in retrospect was a mistake.
Having raised so much additional funding, management clearly intends spending a lot of it. This implies faster growth, but also an increase in operating losses. Therefore the mirage of future profitability looks likely to have disappeared even further into the future. Historically, broker forecasts have been consistently too optimistic about profits & cash balances, so should be taken with a large pinch of salt.
Having said that, CALL has an excellent product, and should be commended for having gained significant traction in the (huge) US market. Therefore, on balance I like the fact that management has decided to go for it, in terms of more rapid growth.
I think the most likely outcome is a US investor bidding for the company at some stage. If the premium offered is good, then I'd be very happy with that outcome. The shareholder register has already had a US investor, Kinderhook, join with a significant sized stake, so the company is clearly already attracting some attention over the pond. Note that Kinderhook is putting in £1.4m into this placing. This could get interesting at some stage, although private investors don't seem impressed, given the share price dip this morning.
Interim results - Given that the strategy has now changed, to accelerate spending & growth, then I don't know how much value I can add by poring over the details of these now historic numbers?
Key numbers;
Revenue up 30% to £5.2m (all organic growth)
Operating loss of £1.7m - slightly down from £1.8m in prior period
Outlook statement - trading in line with management expectations post period end
Balance sheet - not very relevant, as the £12m placing will transform it to bulletproof status, at least for a couple of years or more. One slight oddity is that receivables fell from £1.86m at end Dec 2018, to £1.36m at end Jun 2019. Given that revenues rose by 30%, then I would have expectected receivables to rise by a similar amount (implying c. £2.4m), so the actual figure of £1.36m implies an improvement in collection of funds of about £1m. I'll query this with management & report back.
Cashflow statement - the faster collection of receivables has helped the cashflow figures look better than would otherwise be the case.
Capitalised development spend of £700k in H1 is not excessive.
My opinion - the company has a terrific product (I've used it for several years, finding it reliable & useful), and has a good niche in the recruitment sector. It's suitable for many other sectors in due course, so the potential for growth here is almost open ended. That's what makes it such an interesting share to me. Customer retention is very high, which combined with high gross margins, and monthly recurring revenues, is an attractive business model once it passes breakeven.
On the downside, the road so far has been bumpy, with repeated failure to meet budgets, and repeated fundraisings. Every time breakeven looks to be on the horizon, management loads on tons more costs, and breakeven is pushed out again.
Therefore I think we have a situation where there are probably plenty of stale bulls in the share, yet at the same time clearly more enthusiastic institutional shareholders, prepared to fund a large new placing. It might be logical for the company to use some of the placing proceeds to buy out stale bulls in the market? (i.e. small to medium shareholders who are suppressing the share price).
This is a classic glass half full, or half empty situation. I completely understand why many private investors will point to the track record, and dismiss this share. However, it's the future that interests me, because that's what drives share prices, not the past. Hence with the bank soon to be bursting with cash, and faster growth then possible, I remain a bull on this share.
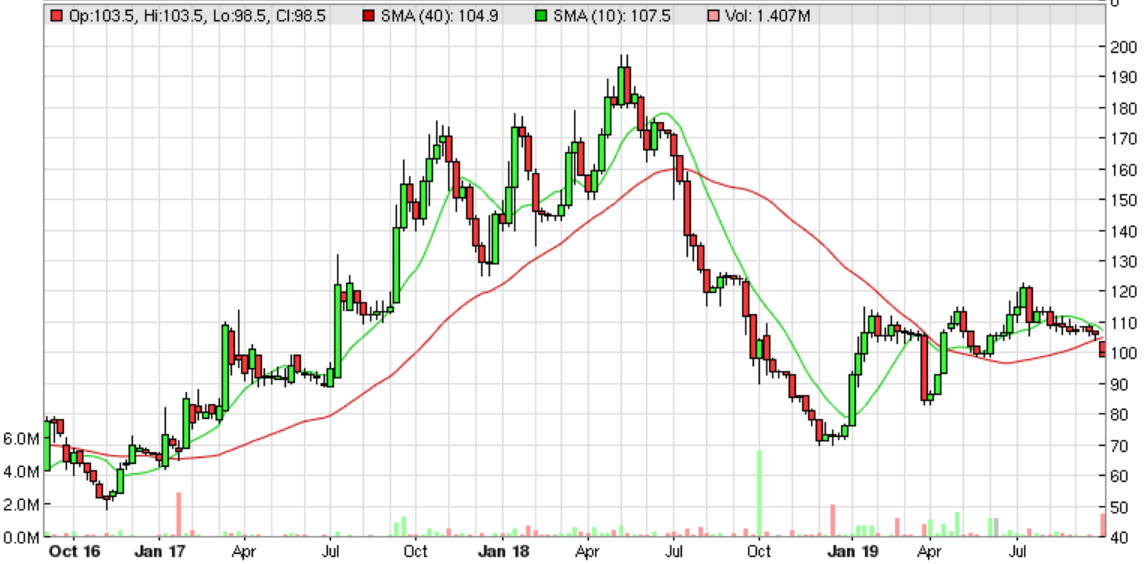
Here's the 3 year chart. With £12m fresh funding secured at 100p, I reckon the downside on the share price looks fairly limited. It could dip to say 70-80p, if private investors who don't like the new more aggressive expansion strategy, decide to bail out. But really, who cares? For longer term shareholders like me, I think upside to say 200-250p is more likely, if the growth plans work out as planned. 250p equates to about £100m market cap, which is the ballpark figure I have in my mind as the medium-term outcome I'm looking for.
EDIT at 15:36 - I can't find any updated broker notes yet. Arden has put out a one-pager today, saying that it needs to re-work its model, so I'll keep an eye out for that, hopefully in the next few days. Also, I have a phone call booked in with CloudCall for later this afternoon, so will update here if anything interesting comes out of it.
Water Intelligence (LON:WATR)
Share price: 284p (up 8% today, at 14:17)
No. shares: 16.96m
Market cap: £48.2m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence", "Group", or the "Company"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide its Interim Results for the six months ended 30 June 2019.
The market likes this announcement, with the share price up 8%, so let's take a look.
Summary at the top of the RNS - a good idea, by the way, more companies should do this, as it helps us sort the wheat from the chaff more easily/quickly in that very pressurised hour from 7-8am:
Results are ahead of market expectations for annual revenue and comfortably in-line with expectations for profit before tax. The Company continues to perform strongly on its growth plan based on key performance indicators ("KPIs") identified in more detail in the Strategic Report to the Annual Accounts with 1H KPI results discussed herein.
Here's my quick review of the figures;
- Strong revenue growth in H1, up 34% to $15.9m (note that it reports in US dollars)
- Important to note that some sales are via franchisees, so the end customer sales were >$50m in H1 - hence the business is bigger than the published revenue figure suggests
- Adjusted profit up 29% to $2.0m - the only questionable adjustment is for share based payments - I see this as remuneration, so tend to add it back in as a cost
- Balance sheet looks OK to me. Although note that there is a $2.1m creditor for deferred consideration, which will have to be paid out
- Cashflow statement not great, as increased receivables consumed most of operating cashflow. Receivables generally look high. $1.7m spent on re-acquisition of franchises, all of which was funded by a $2.7m placing, and a $1.4m increase in borrowings.
My opinion - I'm not convinced by this. The headline growth is good, but some of that is coming from re-acquiring former franchisees. Therefore you could argue this is inflating the headline organic growth figures. Also, presumably the franchisees were not successful, hence being re-acquired by the company, which puts a question mark over whether the franchise model is any good?
Is this company really worth nearly £50m? That's my main issue here - challenging the valuation. It doesn't pay dividends either, which to me reinforces the reality that it's not very cash generative. Although you could argue that it's spending the cashflows on expansion.
The other issue is that we're in a market which brutally punishes every company that disappoints on earnings. So why pay an elevated price for something, when that risk is ever present, and you might lose say 30-50% of your money, if you wake up to a profit warning. Sure, trading now is OK, but there are no guarantees with any share that will remain the case. Hence why, personally, I'm not interested in paying a premium price for anything right now.
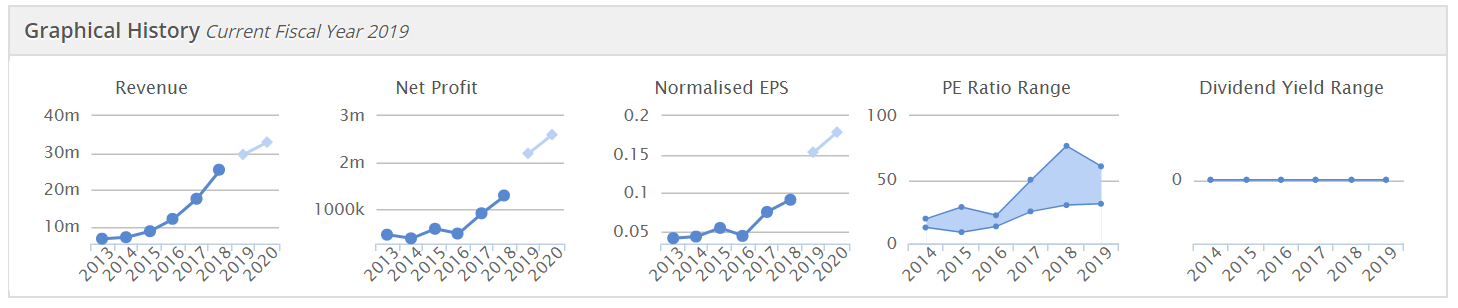
As usual, the Stockopedia graphs neatly summarise things - good progress, ambitious forecasts, PE rating has gone up a lot in recent years, and no dividends;
Christie (LON:CTG)
Share price:
No. shares:
Market cap:
Christie Group plc ('Christie' or the 'Group'), the leading provider of Professional & Financial Services and Stock & Inventory Systems & Services to the hospitality, leisure, healthcare, medical, childcare & education and retail sectors, is pleased to announce its Interim Results for the six months ended 30 June 2019.
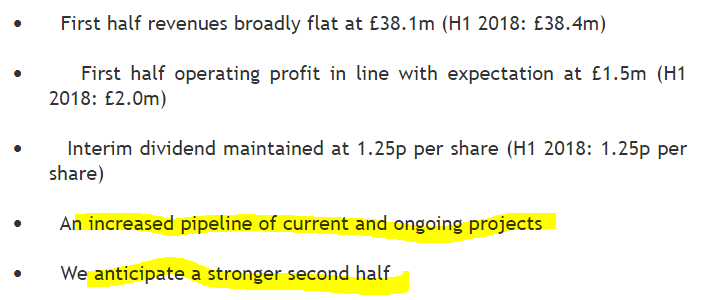
This sums it up quite well - interim results not great, but better H2 expected;
Sale & leaseback of property -
Away from day to day trading matters, following a review, we have decided to have realised the freehold value of Pinder House in Milton Keynes. The recommended reserve exceeds book value by approximately £2.8 million. We will continue to operate from these offices under an occupational lease.
Balance sheet - is unsatisfactory, with NAV negative, at -£2.3m, which worsens to -£5.5m once I write off goodwill & other intangibles.
The main reason for the balance sheet weakness is the £12.6m pension deficit. Given that (guessing here) interest rates appear to be permanently low, and it's difficult to see what would change that any time soon, this means that pension deficits are an ongoing problem and likely to be a drain on cashflows for many years to come.
Valuation - given the weakish balance sheet, and operating in a boring & seemingly ex-growth sector, then I cannot see the attraction here. Stockopedia has the forward PER at 8.8, and the dividend yield is unexciting at c.3%.
My other concern is that the retail & hospitality sectors are under well known pressure, which must be a drag on Christie, even though it has other sector exposure too.
My opinion - it looks OK, but not a particular bargain.
Why invest in this, when there are so many other companies with probably better prospects out there?
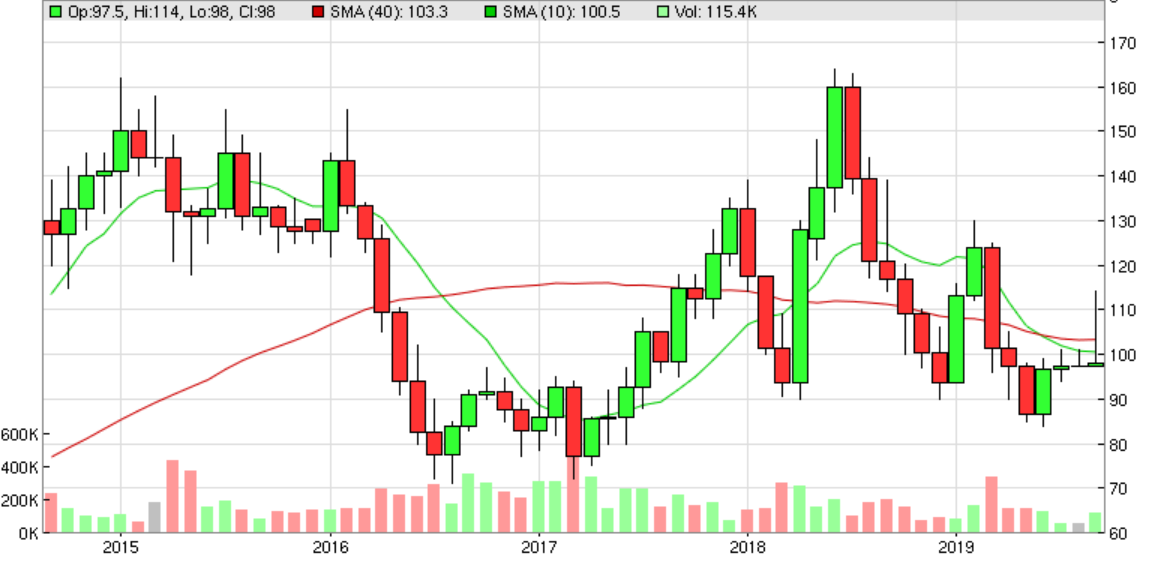
It's gone nowhere in the last 5 years;
A couple of updates from today will go into tomorrow's placeholder now.
Thanks for your reader comments.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
CTG: Useful and like the bit on the pens deficit.
Thanks, Gromley. Governance is certainly a very legitimate concern at Water Intelligence (LON:WATR) and is the only thing stopping me from adding to my holding, as I still believe that the value opportunity is compelling.
I want to give a different perspective on some of the bearish comment that has been made here on Water Intelligence (LON:WATR).
Excellent rebuttal EC ( Water Intelligence (LON:WATR) ),
I have been looking (as something of a side project) to develop an extensive investment 'checklist' to take in as many possible factors as I can - together with acceptable reasons / mitigations for exceptions. You've certainly given some more ingredients with those points!
Some of your arguments I think stand up by themselves without too much further thought, a few though make me really want to check the facts further - which is always good.
I'll certainly be interested in your further thoughts on why "the margin situation" is complex (such a description is rarely in my experience positive - but I very much respect the work you have done here so I'm not going to leap to conclusions)
For me the governance issues are a far bigger no-no, but I remain intrigued and potentially could be interested again. (Despite my overall concerns I did speculate on a momentum play a while back which resulted in a small loss - would have been a small gain if I had properly followed the momentum rules I was following.)
Just in reply to point 6 about the moat for Water Intelligence (LON:WATR) being national coverage, I would be very wary of counting too much on that.
In my experience purchasing managers very rarely are content to have only a single source of supply (particularly as the size of the spend increases and the length of tenure of the supplier increases). Yes, it makes life easier for them to do a deal with a national supplier but in the absence of other national suppliers they will encourage smaller regional competitors to either collaborate geographically with each of to form a consortium with national coverage or allow competitive bids for just some parts of the business.
So, I would take this aspect as a temporary advantage rather than a sustainable competitive advantage (or moat).
Graham, welcome to the discussion. Unsurprisingly, perhaps, I disagree with the point you make.
The national coverage Water Intelligence (LON:WATR) provides is extremely valuable in selling their services to major insurance companies. Insurers don't want to do deals with individual plumbers or with loose local coalitions of businesses - it is simply not cost-effective. WI offers them the opportunity of negotiating an attractive fee scale (this is lower margin work than normal work for WI) whilst ensuring the work is carried out to a contractual standard. They can then implement this solution nationally.
Water Intelligence (LON:WATR) offers US home insurers with a one-stop fix for water leak claims across almost their entire domestic portfolio.
"Weasel seems to think it is in some way remarkable that the Chairman/CEO has total remuneration that is over 25% of operating profit. Gostevie identifies that this amounted to $502k for 2018. Well, firstly, measuring remuneration relative to profit is a pretty silly measure for a small, high growth company. And is $502k really excessive remuneration given the performance being delivered, especially in a US context? I don't think so. There is certainly good reason to complain about all the related party issues but not, in my view, about remuneration."
I suspect we will have to agree to disagree on that. For me that level of remuneration relative to OP is excessive. If you feel it is acceptable given the performance being delivered then fair enough. Each to their own. As I said, I don't hold and haven't looked at the company in detail so I have no idea on the relative performance. Not doubting you, just saying I have no horse in this race and everyone has different things they look for or look to avoid in a share.
A difference of opinion is what makes a market after all.
I wish you and all holders well.
Ps, As we disagree and this is the internet, do I call you a bleep bleeping bleep first or do you start by calling me one!? I'm never too sure, dammed etiquette! * Lol
* For the avoidance of doubt that is a JOKE!!!!
Was tempted by Water Intelligence (LON:WATR) before but too many red flags.
1. Don't like it when the Cashflow from Operations is less than Net Income. With Water Intelligence (LON:WATR) It's consistently lower every year.
2. CAPEX is fairly high at around 50% so there's not much free cashflow
3. They're having to issue shares to buy companies (I assume its their franchisees they are buying out). Would have preferred if they were buying out with internal cashflows
4. Renumeration for chairman is excessive (thanks for that)
5. Operating margins aren't great at 8% which indicates there isn't much of a moat (though if the chairman took a pay cut, it'd be 10%).
A forward PE of 21x times is perhaps too much.
Crimson Tide (LON:TIDE) announced half year results last Friday. Major sales effort highlighted during the half, with a doubling of total head count. But sales and overhead costs are only marginally up. Has the year end report been brought forward six months, or am I misunderstanding?
Crimson Tide (LON:TIDE) (which I hold) is way below most investors minimum cap levels but is an interesting comparison to Cloudcall (LON:CALL)
Both companies appear to have large markets to grow into and at this stage may have the timing of some lumpy contracts to disrupt short term forecasts ( but that will not be so obvious as they grow). Cloudcall has chosen go-for-broke expansion on the back of frequent placings to fund “investment” in sales. While Crimson Tide has expanded within its cash flow, still adding sales resources but not (yet) calling on the market and year after year showing a small profit and useful cash generation.
Cloudcall found a couple of years ago that the market wanted a severely discounted pound of flesh to get a critical placing away, but maybe Crimson Tide has underplayed it’s hand and will find itself getting pushed out of the market they have created by latecomers with more cash to invest.
It will be interesting to watch the two approaches play out.
Cloudcall (LON:CALL)
davidjhill
I don't share rmillaree's opinion that the numbers were poor today. 30% revenue growth is good
It depends what numbers you are looking at :) - the fact is all of the sales growth and more was eaten up as additional expenses - if you adjust for the increase in capitalised costs compare to the same time last year (add 140k to expenses). all the extra income has gone out the door in expenses and a bit more - so in that sense the numbers looked poor to me taken as read.
Also they had estimates of £2.65 net loss for year and hit £1.56 mill loss in H2 - so H2 does have to be materially better to hit targets - so there is an element of second half weighting risk in these numbers - again to be expected with the fast growth in sales expected h2. In some respects this will make the numbers look good at the year end when they hit h2 expectations and do 11.7 mill that will be 37% sales growth h2 lfl which is an increase over the 30% growth rate shown in h1.
I know the reason for the "poor numbers from my perspective" makes sense due to the quite significant payback period before the upfront onboarding costs are recouped and then the operating gearing kicks in - in that sense the numbers were never going to be pretty reading today so i don't think whether the numbers look good or bad matters too much as long as they are still on track compared to previous expectations which seems to be the case- not all the numbers in here are bad (30% revenue growth is decent) there is certainly enough in here for everyone to be happy with what they read.
Hi rmillaree
lol indeed. I agree entirely around operating margin. Growth I am happy with. 30% compound annual will make holders very happy indeed in the medium term as long as they don't continue with this rate of operating cost expansion, but I'm with you on concerns around that element. Once again with this share we have to wait and see....hmm. Not entirely convinced by the boards expectation management approach.
Deloitte have today published a good presentation on the current economic growth outlook which is worth a read:
https://www2.deloitte.com/content/dam/Deloitte/uk/Documents/finance/Deloitte-uk-global-economy-in-charts-q2-2019.pdf
In short, most charts aren't looking good but interestingly UK retail sales figures are looking pretty decent and not far off 10-year highs for year-on-year growth.
From last Thursday, Sumo (LON:SUMO) analyst presentation with CEO/Founder and CFO.
A good overview of the business, the strategy, the market and the outlook.
c.50 mins
Second Water Intelligence (LON:WATR) .H1 EPS $0.079 slightly ahead of Stocko FY forecast of $.15. SP has been very weak of late but up 6% this a.m. I hold, and it is a sector which I believe has good medium and long term prospects as water demand grows around the world.
Richard
With today’s placing announcement Cloudcall (LON:CALL) continues to keep its placing amount comfortably ahead of its gross sales!
I know that Paul is among those who see this glass as half full, but it continues to ensure that jam is still “tomorrow”. When (and if) it does arrive any holders who have not been regularly paying for more stock will have had their jam massively diluted
Cloudcall (LON:CALL) not sure I follow. The placing wasn't done at a discount so no dilution.
The question is more whether the cash will be invested wisely to accelerate and increase growth. The key metric will be the IRR on the cash being raised.
What I don't like in this announcement is that EBITDA b/e now moves out 2 years so we've moved from cusp of operating profit to a growth model targeting £50m of run rate revenues by 2025. Therefore losses will continue for a further 2 years as operating expenses go up 40%.
However, given growth profile in users and US slant it wouldn't surprise me to see an American competitor take them out, and if they do at considerably higher price.
From an asset perspective I guess that is true - in fact with Cloudcall trading at a P/B of > 6x then in fact the asset share of existing investors is improved.
However the placing does increase the ultimate size of the potential market opportunity and future earnings. So if earnings once they reach the promised land will be the same, but there are more shares in issue - it still looks like dilution to me.
Oh and as you mention it will now take 2 years longer to reach the promised land.
No position currently and I haven't looked in any great detail recently, just picking up on the general point re dilution.
hi Gromely - like you say it is a dilution if future earnings only stay the same as projected with no placing. That's bad dilution because the IRR on the placing is zero.
Cloudcall (LON:CALL) aren't saying that. They are saying that the size of the opportunity is now much bigger and they need to ramp up operational costs in order to support that growth but the pot of future earnings will be greater than if they bumble along without it. What we don't see, of course is just how much IRR is in the internal model !
Thus we can't really calculate, which is irritating. I have a small long position and I am reasonably happy to keep it but growing sceptical about the way in which they invest funds. I want to know at what point does operational gearing kick in as it seems to be a moving target.
I don't share rmillaree's opinion that the numbers were poor today. 30% revenue growth is good and would indeed get them to £50m+ by 2025 on a compound basis, which is what they are saying, but that's only good if margins ratchet up.
Cloudcall (LON:CALL)
ref the placing at £12 mill i have to presume this puts to one side any funding worries the company may have , as long as they hit their projections this should leave them with £5mil + i would guess spare on top of what they need to get to breakeven. I am guessing they will use this extra £5 mil though to invest for the long term or get to larger sales quicker so it might still end up going down the plughole in the medium term (for the right reasons)
At a market cap of £28 mill i think they have got this away at a decent price all things considered (the poor current numbers) - albeit for current holders the future upside returns are slowly being reduced as the share count continues to rise.
I guess the doubters (me slightly in this camp as far as being good investment return at present) won't be adding and the believers won't be selling.I do think in theory they are showing enough growth to get where they need to be if they can hit £15 mill sales minimum 2020 and presumably £20 mill sales ish year after that. At that stage the high profit margin should eventually show up in good cashflow once "customer acquisition costs" are distorting the figures less and they are down to the 100% repeat revenue cashflow (as they like to say net renewals rate over 100% woop).
Please can you cover the interims from Water Intelligence (LON:WATR) Paul? Everything seems to be going well, with a positive outlook - revenue +34%, profit before tax +20%, though statutory eps only +8% presumably due to the last placing.
Water Intelligence (LON:WATR) is the CEO's pay still C25% of Operating Profit!?
Water Intelligence (LON:WATR) is the CEO's pay still C25% of Operating Profit!?
From the 2018 Annual Report and Accounts:
http://www.waterintelligence.c...
Profit before tax: $1,754,350
Executive Chairman's total remuneration: $501,872
So, yes, about 28.6%
Gostevie
Cheers!
It's not a company I follow, but I had a note from before that the CEO was paid a ridiculous amount relative to OP. I see that hasn't changed.Not sure I would be tempted to look at it any further after that.
Brand Architekts (LON:BAR) nee Swallowfield - reported final results today. Lays out the situation post the disposal of their manufacturing business to leave them focused on higher margin owned brands. Looks like it could be an interesting value situation if management can deliver on their plans without wasting the cash realised from the disposal. Summary is £20m Turnover business making high teens margins. New product development ("NPD") continues with 80 new products launched in the year. -- Net cash as at 31 August of GBP24m. -- Net Assets as at 31 August of GBP38m. Market cap. £35m
jjis and others interested in Brand Architekts (LON:BAR) (previously Swallowfields pre sale of manufacturing business).
I had a look at this stock around the time of the announced sale of manufacturing for wedge of cash similar to market cap (bit less I think). Seemed attractive on face of it with a smaller but higher margin business left. However, I had the following questions and concerns:
1) Trading in the remaining brands business has been poor in year to end of June. I felt why it had been weak was not well explained in annual report
2) I observe that their brands are mediocre and probably lack pull with punters in any serious way and very victim to own brand and new brand and need to discount their stuff to sell it - all a bit Superdrug apart from Alice Hart Davis.
3) If 2 above is correct then they need a lot of ongoing new product development to keep refreshing and feeding the retail beast...that leads me to wonder whether losing the manufacturing arm will bring extra costs and diminution in product development capability...
4) To what extent was manufacturing an input on brand development
5) Departure of Tim Perman as CEO following announcement of manufacturing business sale is surprising as he's only been CEO since May 2018...one would guess the sale would have been driven by him and his 'strategic vision'. To depart straight after its been agreed suggests otherwise. What's going on?...
6) They've got a shareholder base that whilst not activist includes a heavy disposition to investors that can be quite active with their companies plus some big individual holders. Perhaps the shareholders are running the show - at present BAR is without CEO or CFO and professional oversight of operations is being provided by two people who went with the manufacturing business
7) My guess from this is that Brand Architekts is not long for this world as a independent entity. Sold, closed or broken up? Dunno. Selling all as one might be hard as its a hotch potch of small middling brands. Closed doesn't make sense as that's money down the drain. Break up by selling brands they can might make sense and be more manageable/digestible path. Obvs they will be seen to be forced sellers so the price wont be great
8) Perhaps the biggest conundrum is that it appears that the small brand business has kept the big (in relative terms) pension deficit. At the end of June pension liability is £9.4m up from £4.5m end of last year. Note that brands business has revenues of £19.7m and underlying OP of £3.6m (which is before shared central costs of old combined Swallowfields). These liabilities originate primarily (I think wholly) from the old Swallowfields manufacturing business (which bought Brand Architekts a few year ago). Why would the pension liability stay with the brand business? Smacks of desperation TBH...the investors are not mugs so they must have felt it was a good quid quo pro to get their hands on the £35m cash from KDC/One for manufacturing.
So what to think re BAR? £7.2m net debt at year end turns into £28m net cash...that's roughly current market cap which looks nice as brand business is free...but then its also carrying £9.4m pension liability. To wind up the businesses and generate cash return for investors they would need to organised a buyout of the pension...don't know how that would price but lets call it a round £10m for simplicity...
So BAR is £18m cash plus a weak brand business with £20m revenue pa (that seems to be going backwards). Obviously, a bit more of the £18m gets used up winding down the business.
Or they could use the net cash to invest n and acquire more brands....that doesn't look attractive and probably not what the shareholder want either as that could mean a decline in SP at worst or a a long duration J-curve effect.
On balance I'd say that despite the high cash position Brand Architekts (LON:BAR) seems more short candidate than long.
At the time of the transaction announcement I took a tiny spec long position in spread bet account. Initially I made a nice little profit...then the share price turned on me. I closed out with the release of prelim for a small loss. The spread bet position was just to have me interested and doing some work and watching.
Note, I sought to ask management some of the above questions and got no response from IR or now departed CEO.
Probably a bit small and illiquid for most around here but fantastic results from AEO, Aeorema Communications this morning.
Circa £3m market cap but over £2m net cash.
3.2p eps on 30p offer price.
1p dividend (I was expecting a special divi)
Relatively new management team, major blue chip clients, growing turnover for the first time in a few years and very positive outlook statement.
Ridiculously cheap imo but not for everyone.
Hi tiswas,
Thanks, at your prompting I had a quick look at results from Aeorema Communications (LON:AEO)
Pre-exceptional profit of £374k, up 29% on prior year - but why would such a tiny company have a stock market listing (which must cost it £100k+ p.a., and be a lot of hassle)? I can't see the point. There's also the risk of de-listing, for something this tiny - an instant 50% loss, why take that risk?
Balance sheet looks good, with healthy cash, as you say.
Dividends - small, and were considerably cut back a few years ago - hence not a dividend you can hang your hat on.
Small companies in the events sector strike me as being people businesses - the risk being that successful people want big rewards, and/or leave to join a competitor or set up on their own. Hence this is not likely to attract a high valuation. PER of 10 seems about right, but only because the balance sheet has so much cash on it (hence an ex-cash PER of about 4 or 5 would be about right).
Given that, to buy or sell, even in small size, you'd probably have to take a hit on the bid:offer spread, and probably wouldn't be able to sell in any size if you managed to buy in size, then something this small looks very unattractive to me overall.
Sorry to pour cold water on you, but thank you for the share idea.
Regards, Paul.
Hi both
I think the counter-argument to Paul's fair point re listing is Aeorema Communications (LON:AEO) has ambitions to pick up small, complementary businesses going forward, and being quoted may help to facilitate that.
I hold, but it's not a conviction position.
Jon
Hi Paul.
"Thanks, at your prompting I had a quick look at results from Aeorema Communications (LON:AEO)
Pre-exceptional profit of £374k, up 29% on prior year - but why would such a tiny company have a stock market listing (which must cost it £100k+ p.a., and be a lot of hassle)? I can't see the point."
I do wonder how much ego plays a part with some of the very small companies on AIM. Do some CEOs and other directors feel that being a director of a publicly quoted company gives them some sort of kudos that is worth the cost? (Not that it's them personally paying anyway.)
For the avoidance of doubt I am not specifically suggesting that is the case at Aeorema, whose management I have never met.
Gostevie
Hi Paul any chance of a ramble on Altitude (LON:ALT) slightly higher loss, but seem to have enough net cash to keep going for a while longer yet to try and get to profit. A punter favorite but another one that has suffer last six months along with the likes of Somero Enterprises Inc (LON:SOM) and Character (LON:CCT) with small caps being out of favour and any hint of bad news hitting the price hard.
Thanks
Andy
Bidstack (LON:BIDS) - comedy interim from Bidstack.
Valued at £57m and revenue of £27k - price to sales ratio of >1000 pre open. Now going for bargain 900x.
Interim results (unintentionally) detail how the company is a fair distance from commerciality. If the tech functioned meaningfully well and integrated into a meaningful demand side platform for ads then why only print H1 2019 revenue of £27k compared to H2 2018's £317k. Sniff sniff...smells like a lot frantic re-engineering in play to make the narrative.
Missed the Bidstack (LON:BIDS) value opp...back to 1000x revenues...
I like the idea of this company and in game advertising solution it provides and beyond the sarcasm would be interested in a case for why its a good buy today at £55m market cap. Why is the execution path to significant revenues and margins so compelling?
hey Mojo
first disclosure - i have held Bidstack (LON:BIDS) from 5.5p and sold sufficient at 30p to cover my outlay so I am in for free.
This company is a potential unicorn in the making and probably has all the risks that go with it. A fair value is nigh on impossible to estimate at this stage.
However, in-game advertising is a hard thing to get right but Bidstack (LON:BIDS) have that technology. I believe there is only one other credible competitor trying to do the same thing and they are behind.
Bidstack (LON:BIDS) has the exclusive licence to provide in-game adverts for Football Manager by Sports Interactive and a collaboration with EPIC games (Fortnight engine) as well as Codemasters. It also now has agreements in place with some of the top 10 global DSPs. Thus Bidstack (LON:BIDS) now have both the inventory and access to the advertisers on a programmatic level.
The market is enormous. It has been hard to crack previously because the advertising needs to be seamless in game. eg the Billboards on FM are as you would see in a normal stadium but the brands are genuine and need to change/track etc.
The management and advisory board are a who's who. If you were wanting to back management likely to succeed go and check out their profiles.There are some of the most senior, well connected people in the industry onboard.
The 2nd half of this year is where the revenues start to ramp up according to the CEO. Operational progress has been super impressive so I'm inclined to believe them but am keen to see revenues start to materialise and ramp aggressively to add another leg of credibiility.
I was surprised by the large drop given the RNS on Friday after the close, but this afternoon bounce is something else! Not one for the faint hearted either way.
Good morning Paul,
I'm not sure if this is worthy of your analysis time but interesting news from Intercede (LON:IGP) this morning with their non exec Jacques Tredoux increasing his control/interest to just under 30% of the shares. Does this signal a possible bid or is he just supporting the SP? Time will tell.
cheers
Francis
Hi fwyburd,
I spotted that too, but was wondering whether or not I should include it in today's SCVR, as it's not a trading update or results.
Seeing as you mentioned it, I'll comment! My view is that it's always interesting when a major shareholder increases to a whisker under 30%. As you say, this can be a precursor to a full takeover bid at a later date. The point being that going over 30% triggers a requirement to launch a takeover bid, as you know, so stopping buying a whisker below that is obviously a signal that the major shareholder is bullish, and wants to buy more, but has been forced to stop buying by the takeover rule.
I've done a search for Azalia Trust (the vehicle which holds some of the 29.7%) and it doesn't seem to have any other >3% holdings in listed companies. It seems to be a family trust, so it's not clear whether the trust has the funds to buy the whole of Intercede or not? Because of that I have to file this in the don't know tray. But it's certainly a positive sign that the biggest shareholder has just increased to 29.7%.
We should have a trading update any day soon. That implies that trading must be in line with expectations, as if it's considerably above, then I don't suppose Mr Tredoux would have been allowed to buy any more stock, just before a trading update.
I really like the turnaround potential for this share, and hold Intercede shares personally.
I had a very good meeting with CEO & CFO a few months ago, who I found refreshingly open. They came across as people who know what they're doing. The relatively new CEO has already stripped out a load of cost, and brought it to positive cashflows, so I'm hoping no dilution will be needed. He was upbeat about the potential, without being rampy, which I liked.
The key reason I bought Intercede shares is because of the amazing quality & size of its clients, including multiple departments in the US Govt, major banks, aerospace companies, etc. It's astonishing for an AIM company valued at only £15m. The CEO agreed on this point, and said it was the quality of IGP's client base which made him want to join the company. Previous management seemed to enjoy developing tech, but were not focused on actually selling it! The new CEO has changed all that, so with the expected time lag, I hope we could see progress.
There again, the company has disappointed in the past, hence why investors don't yet seem ready to bid up the share price to reflect the future potential. From £15m, we could see a multi-bagger, if sales start to grow strongly. Or we might not, time will tell, as you correctly point out :-)
Regards, Paul.
Thanks Paul
cheers
Francis
Cloudcall (LON:CALL)
Is it just me or do the intangibles numbers not add up on the figures released today - ahh looks like typo as they left in the figure from last year in the sub column. Anyway capitalised spend is up.
Numbers look woeful but are on track I think however there is a known long lag before customers become profitable so it shouldn’t be a shock to holders.
My morning smallcap tweet: SpaceandPeople yet another warning.
Accsys Technologies (LON:AXS), Spaceandpeople (LON:SAL), Ceps (LON:CEPS)
Accsys (AXS) rev up 40% in last 5 months. Tricoya plant in Hull now won't open until H2 2020. "The delay is expected to result in overall project costs for the project being significantly higher than initially expected and we are discussing the associated funding arrangements with our project partners noting that a portion of this is likely to be paid by Accsys."
SpaceandPeople (SAL) H2 rev flat, loss down but warning buried at bottom: Guides FY pretax £0.1m, lower than mgmt expected (F/C £0.46m). Blames Brexit mostly.
CEPS (CEPS) H1 poor was previously warned.