Small Cap Value Report (Mon 29 July 2019) - JE., PHD, RCH, YOU, SFOR

Good morning, it's Paul here.
See Friday's report for a couple of updated sections that I wrote up on Saturday morning, including a review of the Sports Direct (LON:SPD) debacle - in particular a potentially huge tax liability that has cropped up in Belgium. I'm expecting a big drop in share price there today.
The catalogue of things that have gone disastrously wrong is quite astonishing. There is the huge, total loss on DEB shares - which Ashley tries to blame on anyone but himself. He now admits that buying House of Fraser was a mistake. Some see him as a brilliant entrepreneur, but I feel he's far too arrogant & erratic, to be able to sleep at night as a shareholder. Hence why I'm steering well clear.
Takeover bids
Continuing a theme from last week, I note that there seem to be a surge in takeover bids for UK listed companies. Tech companies in particular. This could be an area for rich pickings, if we can identify any patterns in takeover bids, and then buy shares in similar companies which might become bid targets. Tech companies which dominate a particular niche seem to be popular targets at the moment.
Last week, bruised shareholders in accesso Technology (LON:ACSO) got a nice surprise, when it announced it had received potential bid interest. This morning we have a similar announcement from Proactis Holdings (LON:PHD) . A takeover deal would be a good move for PHD, as management have over-geared their balance sheet, and not performed well (profit warning in Feb 2019), so getting bought out would possibly be the best option for shareholders.
There is also news that a Dutch company called Takeaway.com NV is bidding for Just Eat (LON:JE.) at a modest 15% premium, in an all share deal. The two companies are a similar valuation - JustEat shareholders would own 52%, and Takeaway.com shareholders 48% - those percentages strike me as rather appropriate, given that the bid is from Europe! I can't see why JustEat shareholders would want to own Dutch shares though. Selling this deal to JE shareholders might be a struggle. Takeaway.com looks to be well behind JustEat, with smaller revenues, and is still loss-making. Therefore I would reject the deal, if I held JustEat shares. The inferior company seems to be over-valuing itself in this deal, judging from the StockReport on Takeaway.com
Therefore this looks a bum deal for JE. shareholders, in my view. The problem with all share deals, is that the subsequent share price can be weak, as sellers rush to get rid of new shares that they don't really want.
EDIT @ 08:28 - the JustEat share price has risen 24% to 790p - a long way above the 731p implied price of the all-share deal. It looks as if the market now considers JustEat to be in play, and is pricing in a higher, competing offer. Exciting times for JE shareholders! It just shows that conventional valuation metrics such as PER simply don't apply to growth/tech shares right now. How long that state of play continues, is anybody's guess.
Reach (LON:RCH)
Share price: 85.6p (pre market open)
No. shares: 299.3m
Market cap: £256.2m
This newspaper group (formerly called Trinity Mirror) reports interim results, for the 26 weeks to 30 June 2019.
In a separate RNS, it says that CEO Simon Fox will be stepping down on 16 Aug 2019. No explanation is given as to why he's leaving, which might concern some investors. A new CEO is lined up, Jim Mullen, formerly CEO of Ladbroke Coral. It's usually not a cause for concern if a new CEO has been lined up, as opposed to more worrying situations where a CEO is suddenly sacked out of the blue - which usually means something has gone wrong.
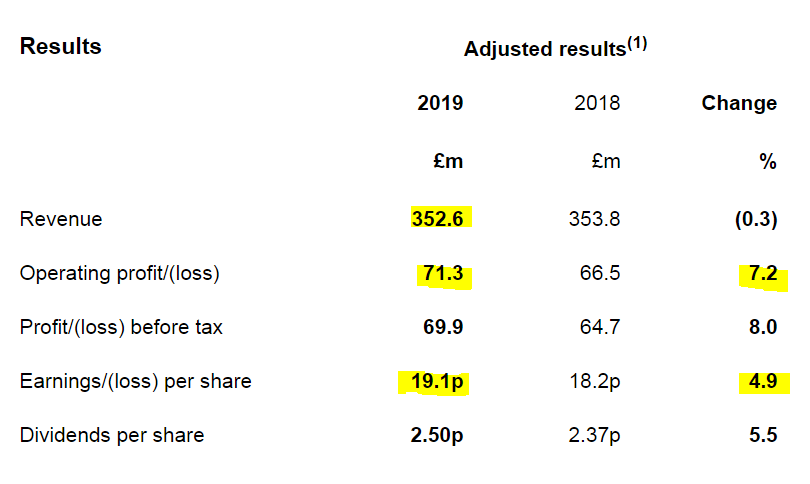
For a share that is priced for failure (fwd PER is only about 2.5!) these seem remarkably resilient figures;
Of course, we already know why the share is priced on such a lowly valuation, it's because;
- Newspapers are seen as a structurally dying sector
- Massive pension fund/deficit
Reach seems to have done a remarkable job in maintaining its profitability. This has been done by;
- Continued, multi-year cost cutting - which is only finite, there would come a point where no more costs could be cut. There's also a risk that with lower editorial budgets, that content quality could suffer, leading to a downward spiral in circulation, and then hence advertising spending by customers.
- Bargain acquisitions - often with cost synergies.
Note the outstandingly high operating margin of 20%. It's difficult to think of other structurally declining sectors which have remained as astonishingly profitable. That matters, as it gives Reach options. Being this profitable, it could be that the business could actually survive long-term, in some form, perhaps?
Revenue - on a like-for-like basis, this fell 6.3% - a slight improvement from -7.2% in H1 2018. The acquisition of Express & Star boosted total revenue to -0.3%
Digital revenues are significant now, at £48.7m for H1, up 17% on prior year H1. This is potentially interesting. If growth can be accelerated, then there's the possibility that this share could re-rate, into being seen as a growing digital business, with a newspaper business attached? Maybe that's far-fetched, but you never know.
Let's look at the big issues;
Pension scheme - note that payments of £24.5m were made into the pension funds - that's just in a half year, so we're looking at almost £50m p.a. - a huge cash drain, and more than double the dividends paid to shareholders.
Contributions have been agreed at £48.9 million per annum for 2019 and 2020, £56.1 million per annum for 2021 to 2023, £55.3 million per annum for 2024 to 2026 and £53.3 million for 2027.
The challenge for Reach, is whether it can continue generating prodigious cashflows enough to fund the pension deficits, and leave enough left over for generous dividends. Since the pension schemes rank ahead of dividends, it would be dividends that are cut, in the event of profit falling. Hence the big divis should be seen as risky, and cannot be guaranteed.
The word pension is mentioned 85 times in today's RNS.
The accounting pension deficit barely changed, at £348.2m (£284.8m net of deferred tax). Note that both these figures are greater than the £256m market cap, so this is a huge issue, very material to valuation of the shares.
The scale of the problem is fairly mind-blowing: the total scheme liabilities are now £2.66bn, with partially offsetting assets of £2.34bn. The deficit is therefore the difference between two very large numbers, hence it's difficult to know what's likely to happen.
Actuarial deficits are usually worse than accounting deficits.
The problem is that rising interest rates now seem to be on hold. Asset prices are clearly now addicted to ultra-low interest rates, and whenever the USA tries to raise interest rates, it causes a stock market plunge, and they reverse track. That's happened several times in recent years. Interest rates elsewhere are strongly influenced by USA interest rates. And the EU of course too.
That environment leaves little prospect of Reach's pension deficit being reduced by higher interest rates (which have the effect of reducing the calculation of future liabilities).
Dividends - the company says it plans to increase dividends by 5% p.a. - although as mentioned above, the pension scheme comes first.
Net debt - excluding the pension deficit, this is now low, at £12.9m [corrected, many thanks to davidjhill for pointing out that I'd picked up the prior year figure by mistake], hence is not a problem.
Balance sheet - this is a bit complicated.
NAV: £578.2m
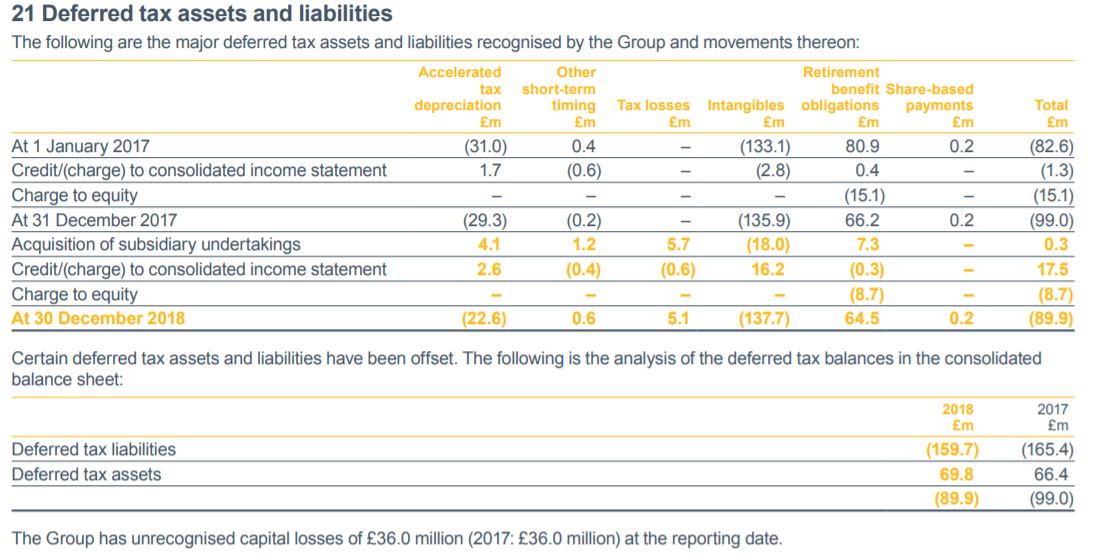
NTAV: I'm inclined to write off £42m goodwill, £810m other intangible assets, but also the £159.6m deferred tax liability, which mainly relates to the intangible assets (see below). That arrives at NTAV of -£114.2m - not good, but not a disaster either - especially considering the group is so strongly cash generative. Also the main reason for the negative NTAV is the pension scheme, which is a long-term, manageable liability - unlike say bank debt, which can be pulled if the covenants are breached.
Here's the note from the last Annual Report on deferred tax:
Outlook - sounds fine, it's in line:
Whilst there are uncertainties arising from the UK's exit from the European Union, we are confident that our strategy will enable continued progress to support profit and cash flow.
The Board anticipates trading for the year to be in line with market expectations.
Bull case - this is still a fantastically profitable & cash generative business, however counter-intuitive that may seem. It's extremely cheap on a PER basis, and paying a high dividend yield.
The cashflow statement shows that it can currently easily afford the pension deficit recovery payments - operating cashflow after tax was £66.6m, which comfortably covered the £24.5m pension deficit payments, with enough left over to pay out £11.2m divis, fund minimal capex of £1.6m, fund the debt interest, pay down £20.3m in bank borrowings, and still left cash up by £7.6m. Remember these are just 6 month figures too. That's an astonishing level of cash generation.
Digital revenues are becoming quite significant at c.£100m annualised, and growing,
Bear case - newspapers are a dying sector, so earnings not likely to be sustainable. Reach has made acquisitions & cut costs to maintain profits, but that can only last so long.
Size of pension scheme dwarfs the market cap. Recovery payments could end up consuming future cashflows, meaning divis might only last a couple more years before finishing for good.
My opinion - I've got to conclude that I'm neutral on this share. It's impossible to say what scenario might play out. I'm probably leaning more towards being long than short, as the short term outlook looks fine, and the ultra-low PER and high divi yield could attract buyers. Someone might bid for the whole thing, you never know - although that would require agreement with the pension fund trustees.
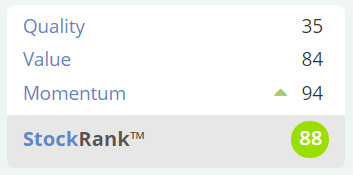
The StockRank system likes it a lot, and seems to suggest that the downside is more than priced in;
YouGov (LON:YOU)
Share price: 569p (up 7% today, at 12:23)
No. shares: 105.2m
Market cap: £598.6m
YouGov, the international research data and analytics group, today announces a pre-close trading statement for the full year ending 31 July 2019.
This is a positive update, with the key bit saying;
We are pleased to report that the Group's trading for the year ending 31 July 2019 is now expected to be comfortably ahead of expectations for the year.
With these results, YouGov has achieved another year of strong revenue and operating profit growth. Notably, revenue has continued to progress substantially ahead of the global market research sector.
Valuation - you can't argue with the strength of today's update. We can however argue with the valuation, which looks bonkers to me.
Last year it made 7.3p in diluted EPS. At 569p per share, the historic PER is 78.
Why so high? The company seems to have been successfully steering investors towards its adjusted figures, which is 16.6p adjusted EPS for FY07/2018 - a PER of 34.
The adjusted figures are nonsensical, because they ignore both capitalised internal costs, and the amortisation relating to them. I've been pointing this out for years, but nobody seems to care. The shares have done very well, so maybe ignoring a ton of costs and pretending they don't exist is the way to go?!
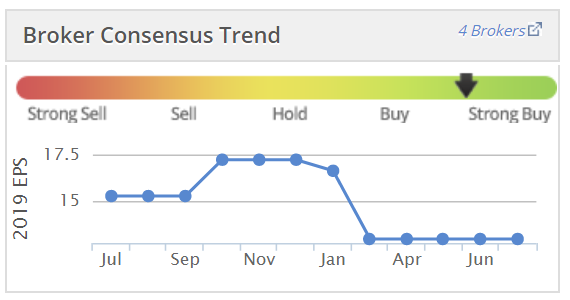
Broker forecasts - note that the bar was lowered considerably in early 2019. So beating lowered forecasts is not as impressive as it might initially look.
My opinion - this looks a good business, and is a well-known brand name. Growth in revenues & profits is good.
It's only the accounting, and the valuation that I have issues with.
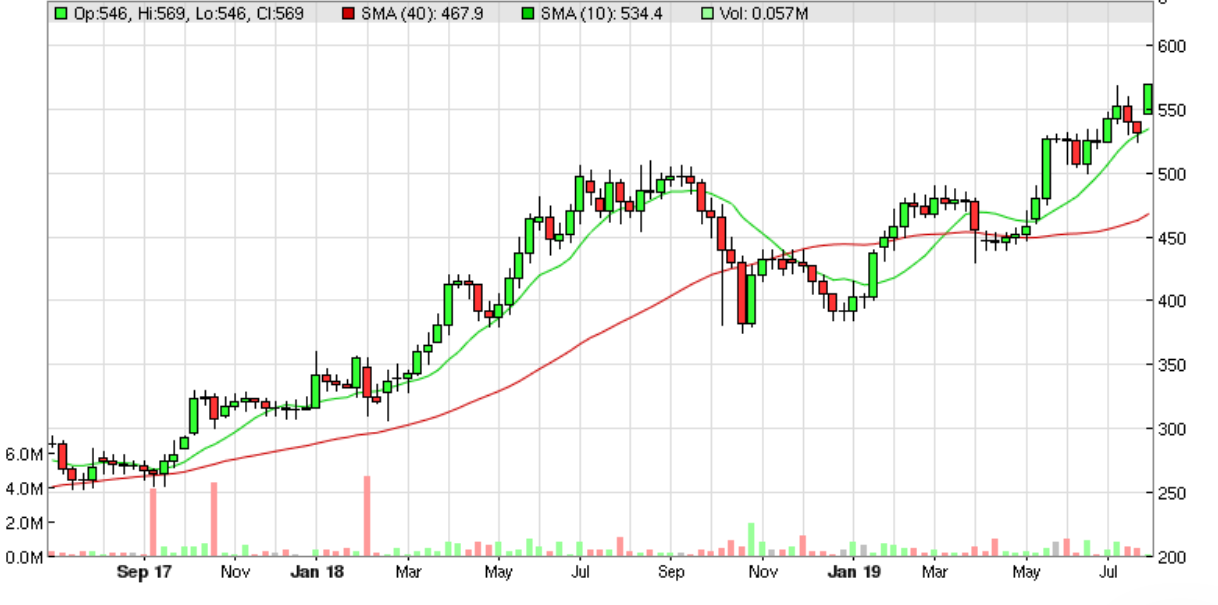
The share looks wildly over-priced to me. I cannot get to anywhere near a £600m market cap. I would only be interested in looking at this share if it had more than halved in price. That would be getting closer to a more sensible starting point for considering a purchase.
Still, it doesn't matter what I think, look at what the share price has done in the last 2 years!
S4 Capital (LON:SFOR)
Share price: 155.5p (up c.3% today, at market close)
No. shares: 364.2m
Market cap: £566.3m
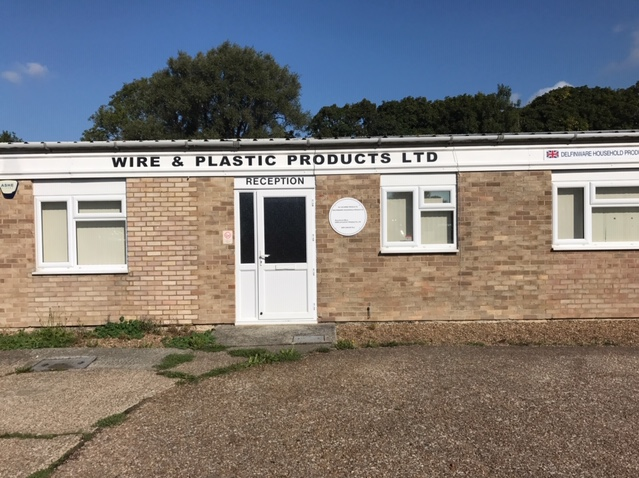
I've been asked to look at this by a subscriber. Coincidentally, this company also cropped up in a phone call with an investor friend, who texted me this picture of Sir Martin Sorrell's original business headquarters at WPP. It went on to become rather larger.
S4 Capital is Sorrell's latest vehicle, focused on digital advertising.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Reach (LON:RCH) nice Gromley. Thanks for the summary, that was really useful. I am away so haven't seen the analysts presentation.
Reach (LON:RCH) - a minor but important point Paul is that net debt is down to £12.9m rather than the £40m you refer to. It will be about £8m by now too.
In the half year they reduced net debt by £27m whilst still paying increased dividends and pension contributions. That is prodigious cashflow of £70m, so I doubt very much dividends are at risk in the foreseeable future. In fact management are guiding to progressively increasing at 5% p/a.
Once the net debt is eliminated I expect them to buy the JPI assets they referred to at a good price. This will allow another round of rationalisation and cost benefits for the following 2 or 3 years, further increasing annual cashflows, revenues and profitability. It will of course push net debt back up again and that will get paid back over the 2 following years. This is a pattern at play.
The market is dramatically under appreciating the amount of cashflow this business will generate before it "dies off" as everyone says it will. It produces £140m of cash each year against a pension deficit effectively just a couple of times that.
As you also point out the digital revenue line is now £48m and growing at circa 10% p/a. Whilst you don't expect it to take over as the lions share of the business anytime soon on a 5-10 year horizon it should be pretty material to the resulting valuation of the business. Management generally seem to have done a good job.
I personally think this is mis-priced and way too undervalued. It feels like a long wait for that perception to change but at least I get a 9% yield in the interim growing by 5% p/a.
Very good summaries from Paul and this response from davidjhill on the subject of Reach (LON:RCH) .
I may have mentioned once or twice that I hold these shares. I have also definitely mentioned the amazing consistency in their reporting, today they confirmed "The Board anticipates trading for the year to be in line with market expectations", this is probably the 20th or 30th update in a row that has given us the same update (except for the ocassional small beat, usually in Q4.
The reduction in debt is certainly very impressive and it is true to say that by the end of the year they could be debt free again should they so choose. (They probably won't as it does seem likely they will take some of the JPI assets.)
However, one should not forget the deferred consideration re the recent acquisition this amounts to £59m over the next 4 years. I see no reason to view this as a risk, but you could argue that it pushes the effective "debt free date" a little into the future. (There is no interest on the deferred consideration I should point out.)
I have for some time held the view that the amount of cash the legacy business throws off during "run down" far more than supports the current valuation even without the digital future.
And on the subject of the digital future it is worth noting that the Q2 like for like growth was 13.6% - this I view as being the best guide as the Q1 figure was somewhat impacted by algo changes adopted by Google and Facebook in early 2018. That is still short of their KPI which is for 15% growth and this in turn is lower than they were targeting in previous years (20%).
It is clear that driving digital growth has been more of a challenge than originally expected however the 13.6% is encouraging and whilst I do agree that as things stand one has to look a long way out to see digital growth outstripping legacy declines. Nevertheless, the existing cashflows and efficiencies in the legacy business continue to support both the valuation and the ongoing progress in the project.
I do sense that the market sentiment may be turning now, but it is quite fickle. I would say that the business in better shape now than it was five years ago when the share price was more than double the current level. I do not suppose this will set the world on fire from these levels, but like david I do think the shares are currently undervalued.
Hi davidjhill,
Thanks very much for pointing out that I'd picked up the wrong figure for net debt at Reach (LON:RCH) , accidentally putting in last year's figure, instead of this year's. It's really important when people spot an error (thankfully rare!) and point it out to me, so I can quickly correct any mistakes. Much appreciated.
You're probably right re dividends - they don't look under any immediate threat, and could conceivably continue for several more years without any worries. But it all depends on what happens to profitability. The acquisitions are masking a declining core business, which does worry me.
I'm quite tempted to pick up a small position in Reach (LON:RCH) despite the various concerns, as you could well be right in thinking that the market has over compensated for the known problems.
There could be a bid from European or American publishers at some point.
Regards, Paul.
P.S. Thanks also to Gromley, for pointing out the deferred consideration liabilities, which need to be taken into account, and should probably be added to net debt for valuation purposes.
I didn't have time earlier to listen in to the Reach (LON:RCH) analysts presentation, but having done that now I would throw in a few more observations.
(If anyone interested in taking a position I would strongly recommend watching it here )
Anyway a few "take-outs" :
Happy to remain holding based on what I heard.
I hold S4 Capital (LON:SFOR) and am encouraged.
Biggest risk I see is Sir Martin’s age and what happens if he becomes incapable of continuing. Because of this Insee it as a short term holding rather than a buy and keep forever.
As an owner of JE. Shares I'm unsure what to do but inclined to sell after earnings on 31st as I think it will be somewhat of a rebound to their previous earnings.
I guess this takeover debacle could move quickly but they seem to be giving it a few weeks to confirm..
Considering further cashflow of both JE and Takeaway, I can't see how this is a good deal for JE shareholders as it currently stands even with some deferred tax benefit on the deal.
If anything, I think it shows how undervalued JE were to takeaway.com and potentially how undervalued UK shares are in general compared to their international counterparts.
Future cashflow*
Martin Sorrell's new age/new era digital advertising and marketing services Company S4 Capital issued a positive trading update today. Revenues and gross profits are growing faster than the targeted rate needed to double revenues and gross profit organically in the 3 years since the start to 2021.
Acquisitions so far seem to be going well though how well will be clearer with results on 11th September.
Martin Sorrell who built WPP from scratch before being unceremoniously dumped seems to feel he has a point to prove and targets similar success at SFOR. So far it's looking good , though after a good run share has flat lined for a few months now., but up 4p so far today at 155p.
Would welcome reader comments if anyone else holds or follows and also Paul's opinion too, though maybe Paul or Graham will want to wait for next results.
Agreed on
Sports Direct (LON:SPD) ridden that shorting horsey all the way the last couple of months, the guy reminds me of an old boss I had, treated the company like his private money box and ego boost. Since he owns 62% and the price is now "cheap" - he might even consider taking the company private, less stress and having to explain his decisions to the world at large. Long might be the next opportunity - though I would defo spread bet with guaranteed SL, if I did.
Just Eat was a nice little earner, got in just before close Friday.
Sold Reach this morning , on reading your report, made a small gain, but on reflection too risky.
Any thoughts on Keller (LON:KLR) interims announced this morning. 1H poor but claim signs of improvement in 2Q. Promising further improvements in 2H and will achieve expectations for full year. High level of debt perhaps not being reduced fast enough. Market not impressed with shares down +5% this morning so far. Following Stocko profit warning guide this looks like another share that should have sold on first profit warning back in early October 2018. Surprisingly Stock Ranks show it as Super Stock with rank of 89 - not sure the markets agree.
£ SPD Sports direct.
I see it has been reported (telegraph) that the sports direct auditor didn't know about the Belgian tax demand until friday !. Quite unbelievable that results would still be released the same day if that is the case bearing in mind the materiality of the demand figure quoted.
Suprised £SPD only down 10%. Opening a small short position...
My morning smallcap tweet: Leaf spouts cash.
i-nexus Global (LON:INX), YouGov (LON:YOU), Liontrust Asset Management (LON:LIO), Eden Research (LON:EDEN), Leaf Clean Energy Co (LON:LEAF)
i-nexus Global (INX) warns FY rev and cash below Board's expectations but EBITDA in line. Still has sufficient funding to execute on its growth strategy.
YouGov (YOU) guides FY comfortably ahead of expectations (whose?). Cash conversion poor here.
Liontrust Asset Mgmt (LIO) approach by Neptune Investment Management Limited.
Eden Research (EDEN) has received a 120 day "emergency use" authorisation for fungicide, Mevalone, in France for apples. "We are working actively with Sumi Agro to support the full authorisation of Mevalone for use in the treatment of pome fruit storage disease." No idea on numbers. I'm short.
Leaf Clean Energy (LEAF) to return 101p/sh. Will retain an equivalent cash amount to the interest award of $30m together with its best estimate of further costs and potential liabilities until final resolution of Invenergy's appeal on interest. LEAF very likely to win in appeal IMO. I hold.
Thanks to Laurie who points out that Liontrust Asset Management (LON:LIO) is in talks to BUY Neptune, not vice versa as I said.