Small Cap Value Report (Mon 29 June 2020) - macro, PRV, LOOK, STAF, DISH, REAT, SAL

Good morning, it's Paul here with Monday's SCVR.
Estimated timing - there's very little news today in my area, so I should be finished before 1pm.
Update at 13:07 - today's report is now finished.
Here are my Sunday afternoon thoughts, to get the week off to an early start;
.
Pubs re-opening
Hot weather seems to make some Brits go round the bend, and decide to get drunk and sometimes do a bit of rioting. The pressure of lockdown this year seems to have exacerbated this long-standing tendency. There have been various incidents recently, with open air parties turning nasty. Of course in my own locality, Bournemouth beach has achieved international notoriety when half a million people turned up on the beach, made a lot of noise & got too close to each other, left behind c.40 tons of litter (much of it on the beach itself, rather than in the overflowing bins). Throw in a few fights & stabbings for good measure. There was even a picture of Bournemouth beach on my daily email from CNBC (within the article itself, not just an advert), showing a very busy beach.
Although I would say that the media exaggerates the lack of social distancing, by using camera angles which make everybody look as if they’re packed in like sardines. When on the ground, or from the air, you can actually see that most small groups of people are sitting well apart from other small groups. Outdoors. So not likely to be spreading the virus. Bournemouth Council’s outrage at people descending on the beach when the weather was glorious, strikes me as a fig leaf for their own lack of preparation, in failing to provide adequate facilities (which I’ve lamented here before, but let’s not go there, as it upset a few people apparently, and we can't have that).
Against this backdrop, what on earth were the Govt/civil service thinking, to re-open the pubs on 4 July, a Saturday night? What could possibly go wrong?! They weren’t thinking, obviously, as seems to be so often the case at the moment. It’s going to be absolute carnage, isn’t it? Wetherspoons is apparently going to open all its sites - there was an update last week from it here. No ranting about Brexit this time from Tim Martin. Its staff survey results published here were interesting. I'll be popping into my local 'spoons on re-opening night, for a pint of remarkably cheap Thatcher's cider - sharing a name with my favourite female Prime Minister, as a happy coincidence.
I feel so sorry for the police, as they seem to be regarded as society’s punchbags, for the whole spectrum of hooligans, from the hard left statue puller-downers (although I sympathise with their motives - statues of slave traders have no place in prominent public areas, and should have been retired to museums a long time ago), to the far right permanently angry about everything mob. In fact lots of people seem to be permanently angry. I was too, when I was allowed on social media - it brings out the worst in people.
I see Revolution Bars (LON:RBG) (I’m long) has sensibly delayed its re-opening of just 6 sites (out of about 75) until the following Monday. Then it plans to open batches of 9 more at a time, learning as they go along. Sounds sensible.
At the moment, the High Street looks forlorn, with many smaller shops having chosen not to re-open. This makes complete sense, when staff costs are covered by the furlough scheme, which combined with low footfall, means it’s cheaper to remain closed. These retailers almost hold a call option on whether to re-open or not. If High Street spending bounces back once bars, cafes & restaurants re-open (some of them anyway), then maybe smaller retailers might re-open when the furlough scheme ends at end October? This scheme is clearly providing a perverse disincentive for the economy to re-start. I wonder if it might be better for the Govt to give targeted support to particular sectors, rather than across the board support?
Rents - some of the figures being published, about very low rent collections by landlords, from retailers/hospitality sector, for the 24th June quarter day, make me wary of going back into property REITs. I managed to catch a lovely short squeeze, more than doubling my money on Hammerson (LON:HMSO) , but thankfully sold out when it started going back down again.
INTU going bust was no great surprise (although a close shave for me & others here), but I think other property owners might struggle too, once properties are written down heavily in value, to more realistic valuations. When looking at any such shares, remember to take a hatchet to the balance sheet values - these could be written down hugely, once vacancies increase, and rents are reduced very greatly on lease expiry, or break clauses being triggered.
Plus landlords are likely to have to give away reverse premiums (a cash outflow) and/or long rent-free periods, in order to re-let empty sites. The pain for landlords is only just beginning, I reckon.
Whilst Newriver Reit (LON:NRR) gave a very good account of things in their recent webinar, and it doesn’t face any immediate liquidity concerns, I think it could sail a bit too close to the wind for my liking, with its 2021 covenants. Therefore I’m happy to remain sitting on the sidelines with that one, for now. It's easy enough to buy back in again, in future, if risk:reward improves. We don't have to marry any shares. In fact, it's better not to develop some passionate commitment to any share. Be careful about that, because I've got plenty of scars from making that simple mistake. Sometimes reader comments here worry me, that the writers have become irrational, and perhaps see liking a share they own as akin to supporting a favourite football team.
I’ve sold or trimmed back on quite a few of my recovery type shares. So I’ve ditched Marks And Spencer (LON:MKS) and Vertu Motors (LON:VTU) recently. Generally I’m in cautious mode again, as the economic recovery looks like it’s likely to be slower than I previously imagined.
.
US market
At long last, a dose of reality seems to be entering the mindset of investors across the pond. To help focus my thoughts, I’ve summarised the bull & bear points as follows;
Bull points
- The Fed - has forced money into equities, by killing bond yields, flooding the system with liquidity. Big companies are not going bust, as they can borrow seemingly unlimited amounts to ensure survival.
- Absolutely massive Govt stimulus, on a much larger scale than 2008-9 cannot fail to make the economy recover. Markets look forwards,
- Permanently low interest rates mean that equity PERs should be higher than in the past. In this environment a PER of 20 for a growing company is arguably great value - that’s an earnings yield of 5%, when decent yields elsewhere are hard to come by.
- Economic recovery is underway, as the lockdown is eased.
- Vaccine/treatments - absolutely key. If the virus is under control some time in 2021, as seems possible, then the economy recovers, and stocks could start posting new all time highs, given the scale of the stimulus.
- If the economy doesn’t recover, then the Fed/Govt are likely to continue with more stimulus packages. What if the Fed starts buying shares directly, or via ETFs? It has been mooted.
- Election year in the US - so the incumbents are motivated to throw the kitchen sink at the economy and markets, until the desired result is achieved.
- Apparently large numbers of investors in the US (35% of the over-65’s - source: CNBC last week), sold out at or near the March lows, and many haven’t since gone back into equities - thus crystallising losses at the worst point, and missing out on one of the fastest & largest market rebounds in history. Could that provide continued buying of shares, due to FOMO?
Bear points
- Worrying resurgence in covid-19 in some states in the US, plus fresh outbreaks in other countries. Can these be contained? We don’t know yet. Texas has ordered bars to shut again, apparently. Is this the future for all of us maybe - i.e. local or regional shutdowns, to contain outbreaks (if possible?). This thing could be around for a while.
- Few corporate earnings forecasts. I remain of the view that Q2 figures could be a lot worse than the market expects. This was borne out by Nike’s results (05/2020) which were a lot worse than expected.
- Massive unemployment has been masked by furlough schemes. The full scale of this problem is likely to become apparent in the coming months, as the scheme winds down. That would then inevitably feed through to lower consumer spending, and more bank debt going bad.
- In the US, Joe Biden is well ahead in the polls for the Nov 2020 presidential election. Getting rid of the nutcase Trump would be a good thing for the world I feel, but the stock market doesn’t care about that. Biden’s stated intention is to increase taxes on corporates, and investors. That’s bad for share prices in the short term.
- Slower economic recovery. The hoped-for V-shaped recovery seems to be receding somewhat. If 2019 peak earnings are not likely to be recovered until 2022 or even later, then arguably share prices might need to reflect that by coming down a bit more?
It’s really up to each individual investor to weigh up all of the above, and come to our own decisions on what stance to take. It seems to me that, with so much uncertainty, and impending bad news on the cards (plunging profitability, and battered balance sheets), paying top whack for any share is asking for trouble. Hence why I’ve put my cautious hat on again. I make no apologies for frequently changing my mind - that’s essential at times like this, and it’s a willingness to adapt to changing circumstances that has made this a successful year so far for the paulyfolio. Pride often comes before a fall, so I had better stop at that point!
Commentators always seem to say, “This is a stock pickers market”, in pretty much any market conditions. Personally, I think we’re in a market for traders , not stock pickers, this year. Everything seems so uncertain, and so volatile, that I think there’s a lot to be said for grabbing profits, if something does unexpectedly well.
.
Porvair (LON:PRV)
Share price: 589p (up <1% today, at 09:46)
No. shares: 46.06m
Market cap: £271.3m
Porvair plc ("Porvair" or "the Group"), the specialist filtration and environmental technology group, today announces its half yearly results for the six months ended 31 May 2020.
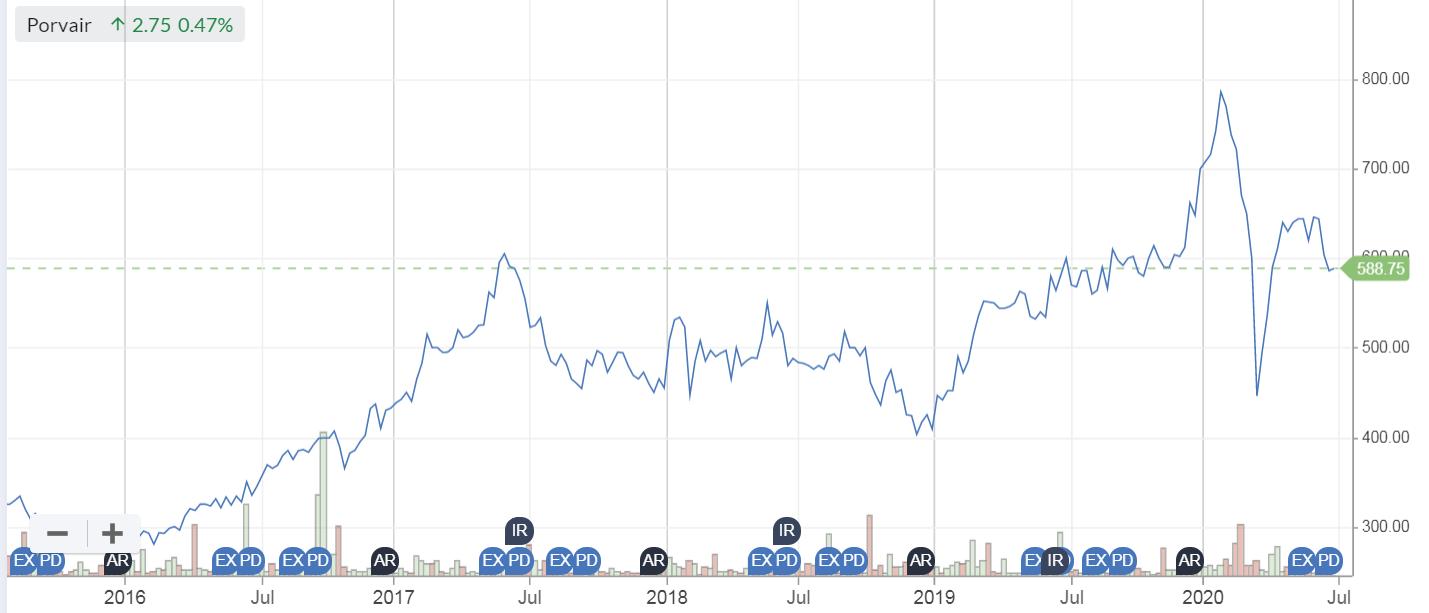
This share has been a good long term performer, although in the last 3 years it has overall just gone sideways. I've always liked this company, but found its valuation too expensive;
.
Interim results look very good, considering about half the 6 months ending 31 May 2020 would have probably been affected by covid.
H1 revenues up 2% to £73.2m
Adjusted operating profit is up 13% to £9.0m. We have to be careful when looking at operating profit, because IFRS 16 has messed up the prior year comparisons. Some property rent cost ends up in finance charges, which appears after operating profit on the P&L. Hence we always need to check that for anomalies. This looks fine, as adjusted profit before tax is up a similar percentage, at £8.5m (up 12%). Note the strong profit margin of 11.6%.
Adjusted basic EPS should be fine as a comparison y-on-y, and that's up 11% to 14.3p - very good in the circumstances.
A small interim divi of 1.7p is maintained - demonstrating some confidence we might infer, although it's really too small to matter either way.
Balance sheet - NAV is £101.5m, dominated by intangibles. Deleting those, NTAV is £27.8m. Overall the balance sheet looks fairly strong. Note there is a pension deficit of £15.2m. With ultra-low interest rates of late, pension deficits are generally on the rise, so this issue would need to be checked out properly before buying this share.
Outlook - surely the company could have given more information than this?
The outlook for the next six months is unpredictable and, as previously announced, until patterns of demand stabilise the Group has withdrawn earnings guidance... Management's second priority has been to prepare for recessionary conditions should they arise... The near term may be challenging, but the Board remains confident that the Group is well positioned and remains resilient....
Not exactly brimming with confidence, but I wouldn't expect them to be.
My opinion - neutral. It's a nice company, but given current uncertainty, I wouldn't be interested in paying anywhere near the current share price. It looks to be valued at just under 24 times forecast earnings. Unlike most shares, the forecast earnings look achievable. This group seems to operate in nicely profitable niche markets, and it's a good business. My only reservation is on valuation.
.
Lookers (LON:LOOK)
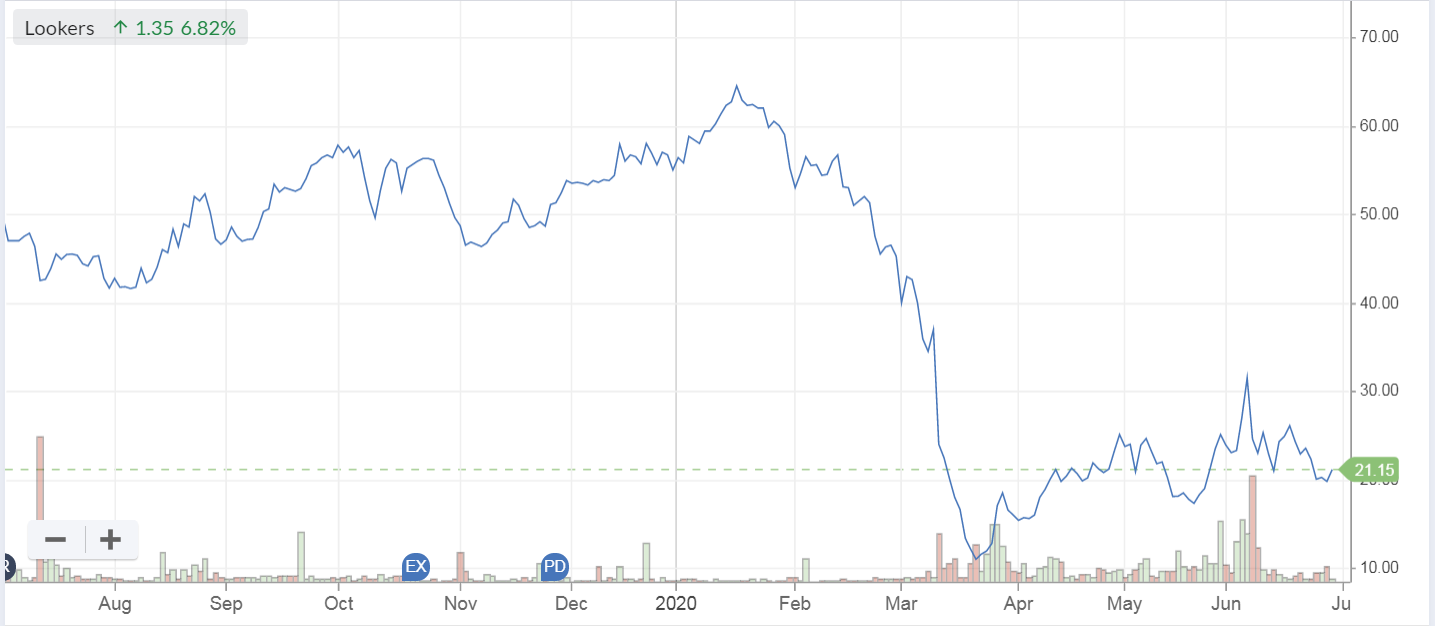
Share price: 21.0p (up 6% today, at 11:21)
No. shares: 390.1m
Market cap: £81.9m
Update on Grant Thornton Investigation
This is an investigation into accounting irregularities.
The original £4m accounting problem has now gone up by another £15m, to £19m total. It says today;
The remaining £15m of the Draft Adjustments relate to the incorrect or inconsistent application of policies, processes and accounting standards. The Draft Report also highlighted several areas where certain financial controls and some behavioural and cultural aspects require strengthening.... Whilst the Company is making good progress in resolving the investigation there remain a number of outstanding issues and until such time as these issues are resolved and Deloitte LLP have completed their audit, it is not possible for the Company to confirm the full impact.
That sounds as if it could get worse still.
My opinion - I wouldn't touch this share. If we can't trust the accounts, then I'm not interested, at any price. I wonder if it will become a bid target? One of the Sunday papers ran a story about a Russian man supposedly looking for UK takeover targets, and mentioned that car dealers are one sector he's looking at. The big freehold property portfolios in this sector make them interesting potential takeover targets.
.
.
Staffline (LON:STAF)
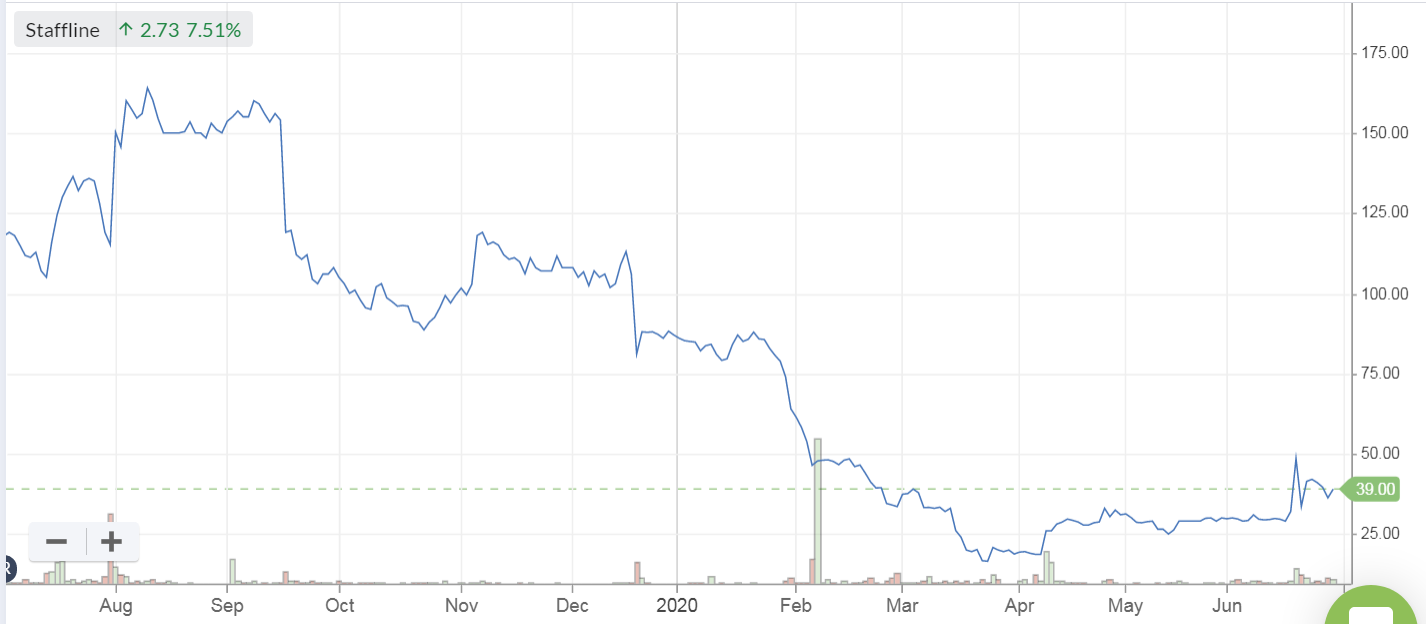
Share price: 39.2p (up 8% today, at 11:42)
No. shares: 68.9m
Market cap: £27.0m
Staffline, the recruitment and training group, announces that it has agreed a revised financing structure with its lenders.
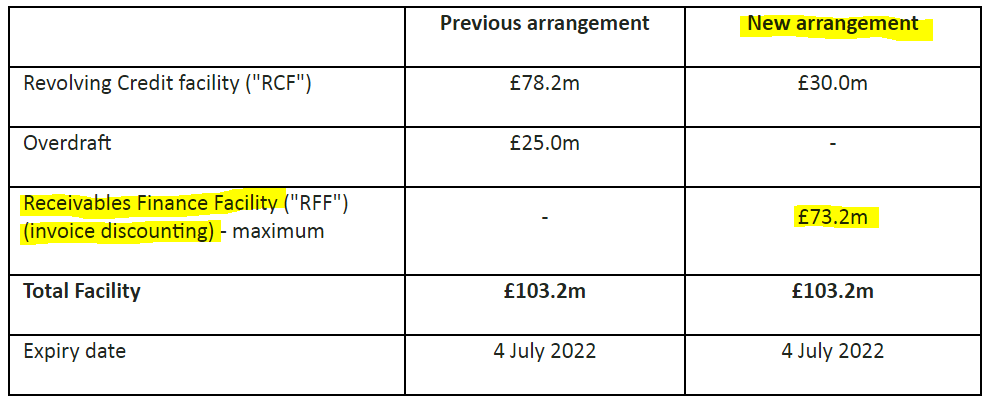
This is quite interesting. As the table below shows, the total bank facilities are unchanged, but have been moved to primarily an invoice discounting facility - i.e. lending against the group's receivables book. That makes a lot of sense for the bank, as STAF has a high quality receivables book, and lending specifically against it should provide the bank with solid security (hence little to no lending risk). If the business were to go bust, then the bank would have security over the receivables, hence would collect in that money to repay the bank debt.
.
The interest cost on the invoice discounting facility is 3.5% over base rate, which looks reasonable.
Divis & acquisitions are banned for the next 2 years.
"More appropriate" bank covenants agreed.
Liquidity - this bit concerns me. The way I read this, it sounds like the company is going to run out of money in March 2021, when it has to pay up for large deferred VAT liabilities. Directors are working on a turnaround plan. I thought they had already done a turnaround plan?
My opinion - not out of the woods yet. Another placing on the cards maybe?
For years this looked like a really good business. Then it turns out, it wasn't very good after all. It still rankles that the founder walked away with a £multimillion haul, just before all the problems emerged.
.
.
A few brief comment on some tiddlers:
React (LON:REAT)
Down 7% today, at 1.46p per share. Mkt cap c. £7.3m
This is a specialist cleaning company, so its shares have gone up considerably due to covid. It's a turnaround under new management, which a friend flagged up to me recently, so I've already had a quick look at its figures, and decided it's too small for me to want to get involved.
Do today's H1 results for 6m to 31 March change my mind? Not really. It made a tiny profit on £2m revenues in H1. There was a £1.25m placing done after the period end. New contracts won after period end.
Outlook sounds promising;
The second half of the year has started well, with good trading across key sectors, especially healthcare, rail and facilities management. We remain confident of delivering a performance ahead of management expectations for the year to 30 September 2020 including a full year maiden profit."
My opinion - neutral. Why is a company this small listed on the stock market? It might make sense if the company plans to make acquisitions, doing a buy & build maybe? Otherwise, I would worry too much about the de-listing risk. That said, deep cleaning & disinfecting, is clearly a very topical area of activity.
.
Bigdish (LON:DISH)
(I am long - highly speculative)
2.33p (down 12% today). Mkt cap: £8.1m
This is a yield management software/app for restaurants. It's a fantastic little app, or rather was, when restaurants were open. The plan is to re-start the business when restaurants re-open shortly (some of them anyway). I think the new market conditions should be great for DISH, because spreading their business more evenly across each week will be crucial for restaurants to survive.
We can't value this company on earnings, as it has negligible revenues. It's a growth company, which are valued differently, which makes value investors very cross!
Today's update doesn't really say much. Another update will be provided around 4 July re-opening date.
Funding - same as before. There's enough cash to last through to end of 2020. More funding will be needed, which we already knew.
The Company acknowledges that further funding will be required at some point in the future and is optimistic that this can be achieved without the need for an equity placing.
That would be great, providing the cost of funding isn't too expensive. A funding deal sounds like it's been delayed;
... a successful outcome may only be possible at such time when management can travel internationally.
15.2m new shares have been issued.
My opinion - mildly disappointing, as I would have liked to see more progress on securing funding. This is a hot area (food tech), and the company has proven adept at raising funds in the past (the last fundraise was at 7.2p). It's highly speculative, but I like the multibagger potential. Definitely not one for widows or orphans!
.
Spaceandpeople (LON:SAL)
6.75p (down 4% today). Market cap c.£1.3m
At this valuation, it can't make any sense for this company to remain listed. It's been a disaster for shareholders, and is one of my mistakes from the past. I gave up on it a while ago, seeing little chance of it recovering to former decent levels of profitability.
2019 results out today are very late, and not very good. It's trundling along around breakeven. Presumably that has been worse in 2020, when many shopping centres were seeing little footfall. It has secured a £1.0m 5-year loan through the CBILS.
For people who like wild punts, this could be a bit of fun. A £1.3m mkt cap leaves plenty of scope for a multibagger, if things start going well. How likely is that though? I have no idea. Historically it has been a counter-cyclical business, ie. it does better when times are tough, because shopping centres seek out additional income through SAL's kiosks, pop-up shops, etc.
The balance sheet has £1.3m in NTAV, so not too bad.
All done for today! Thank you for reading & commenting.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Diageo are helping their customers out, although $100m doesn't go too far spread across the world it does show some intent from a major drinks supplier.
Diageo launches $100 million recovery fund to help pubs and bars welcome back customers after lockdown
https://www.diageo.com/
Codemasters Group (LON:CDM) FY20 results presentation by CEO & CFO, here. This follows on from FY20 results last Monday. I believe written up in SCSW this weekend. It's a comprehensive overview. The Group achieved good growth in revenues, gross profit and digital sales. The period included the acquisition of Slightly Mad Studios. The outlook includes a strong pipeline of game releases and next generation platform for Microsoft & Sony. Trading for FY21 has begun well. (Webinar given to investors 25.6.20).
Two piworld webinars this week:
1. Wednesday 1st July, 12 noon - Retail Charity Bonds. Allia City & Continental give an overview of Retail Charity Bonds, and discuss their program, which includes bonds for Golden Lane Housing (MENCAP) the Charities Aid Foundation and Alnwick Garden Trust. Register here.
2. Thursday piworld webinar (educational) returns this week with David Thornton, who writes the Growth Company Investor. David will discuss: Small is Beautiful. Why Small Caps? And, What to Buy Now? It's a great presentation, with some useful recommendations. (I've had a sneak preview!) Register here.
Against this backdrop, what on earth were the Govt/civil service thinking, to re-open the pubs on 4 July, a Saturday night? What could possibly go wrong?!
Paul you always manage to give me a chuckle. I can see you covering for Graham Norton on Eurovision.
Morses Club (LON:MCL) is a very interesting situation. On Friday, on high volume, Morses shed 8%, I couldn’t find any news anywhere which might have given a reason for the sharp decline. Then this morning on the RNS, Morses disclose that a very small part of their business, has suffered due the the wirecard developments. The total revenue affects is under 2% and no client money is at risk. The shares have fallen again today, a further 8% but this time on very low volume. What do I conclude from this. Firstly that someone had knowledge of the possible loss due to connection to Wirecard last Friday, before investors did and institutions sold in big volumes. Then today’s small volume trades are probably retail investors panicking. I could be completely wrong in my assumption and I would be very happy to be corrected by someone with a greater mind than my own. Either way, a 16% fall in the share price for a company performing very well, certainly not expensive last week, with only a very minor exposure to Wirecard must be even better value now and a traders opportunity ( I’m not a trader but I do hold a long position in this stock). I would welcome any thoughts and observations.
Firstly that someone had knowledge of the possible loss due to connection to Wirecard last Friday, before investors did and institutions sold in big volumes.
No inside knowledge was required to identify there might be an impact here. See:
https://www.forbes.com/sites/b...
As to whether the response was overblown - well, that's another matter.timarr
you also had Non-standard Finance (LON:NSF) news that might have drawn comparisons
you also had Non-standard Finance (LON:NSF) news that might have drawn comparison
Yep, looks like a more likely reason for the movement in Morses Club (LON:MCL) than the tiny Wirecard exposure.
timarr
Many thanks, really useful. Unless one trawls every magazine on the planet at 07.00am it is impossible to find information when it would be useful. I did google, looked on the company website but at the early time I did that, nothing was apparent. Perhaps I should have re googled throughout the day, that might have uncovered something.
I also on't think it was insider trading. Just the market working.
I think NSF fell because its results announcement last week reminded of its desperately weak balance sheet with covenants technically expiring in a few days ie end June. A separate good news announcement covered this today, announcing these had been fixed (for the moment).Separately, MCL fell because of the Wire Card news because whilst Wire Card problems were becoming visible last week, the link to MCL was not so clear. Only very well informed investors (a very small minority of professional investors comprising some analysts and the best private investors....which excludes me) will have known Wirecard provided the U bank card (with Barclays involved holding the actual customer money). As more people came to know, more people sold and then momentum kicks in on relatively small volumes traded. I don't think this particularly reflects insider trading, just better informed trading
(FWIW I wonder if there is a small compensatory upside from the news, as it reminded me there was I think £5Mn in deferred performance payment due this year on the acquisition of U Bank. Surely this will not be paid out as performance of U Bank is going to have been affected by Covid).
As it happens, I think Morses will recover fine over time as it gradually pivots from pure doorstep lending/collection to doorstep lending /online collection and online lending/banking (from U Bank and Curo acquisitions of last year). I think lot of doorstep lending will go under/sell and Morses were the go-to buyer up until last 2 years and other competitors are exiting even as demand rises for distressed lending. I think it would be backed if chose to issue more equity or even raise more debt once we see Covid retreating a bit more.
MCL had a much better balance sheet than NSF going to all of this so, if I feel able to take on more risk, I think MCL are a high reward/risk share and might buy more. NSF either needs 5 years recovery or else an equity issue or could go under. I now hold in the hope not expectation of a multibagger - it either recovers a lot or is worthless. Not worth selling.
I agree with Paul that Saturday isn't perhaps the most sensible day of the week to be reopening the pubs. There are quite a few Greene King ones around my way and I am on it's mailing list. It is planning on opening about two thirds of its pubs on Monday with the rest following at an as yet unspecified later date.
https://www.greeneking.co.uk/newsroom/latest-news/greene-king-managed-pubs-reopen-from-monday-6-july/
It will be interesting to see how many pubs do in fact reopen next week. My usual watering hole in Paddington is quite a small independently-owned pub that doesn't sell food and that, apart from a handful of regulars, seems to rely heavily on tourists and football crowds for its business. I just can't see how it will be viable for it to open until they start to return.
Personally I shall let the weekend go by and have a wonder into town during the following week to see what's open and what the 'new normal' looks like for pubs. I'm quite an unsociable person and am quite happy to sit down on my own with a newspaper and a pint or several, but if the atmosphere is too sterile I could well decide that i can do that at home and more cheaply.
I've been watching for Fullers pubs reopening and they are also taking a phased approach. The brewers did say to the Government that they needed some time to plan because beer takes three weeks to brew whatever politicians say or do. I suspect that they have only gradually restarted brewing operations because they didn't trust the Government not to change their minds and they don't want to have to pour a lot more beer down the drains.
Don't forget that Fullers don't brew these days
Yes I know but they will have to order from Asahi. The Griffin brewery still makes their beer.
Which pub @Gostevie? I live in Paddington. Several bars along the canals are already open for takeaway (plenty of places to sit/stand outside)
The Sussex Arms (London Street).
The only way that £K3C raised £30m today is that institutions have been given decent site of a further meaningful acquisition during the accelerated book build roadshow and like it. The rns this lunch time is stronger in hinting that something else is imminent
https://www.londonstockexchange.com/news-article/K3C/result-of-fundraising/14595465
Hi Paul,
As you may know, I am a newcomer and am in an absolutely disastrous situation having nearly all of my savings etc. in the market. I read your reports every day, and kindly you had mentioned you may be able to go through some solutions with someone who finds it difficult to deal with. Would you be so kind as to help me out if possible? If yes, how should I reach you?
Thanks a lot in advance,
bests,
Sayed
Sure, if you send a message to Stockopedia HQ, using the green blob on the lower right hand side of the page, and ask them to forward me your email address, then we can have a chat by email.
NB. I'm not authorised to give you any financial advice, but am happy to listen & help in any way I can.
Paul - thanks for your write up of React (LON:REAT). I would challenge this part, however:
"My opinion - neutral. Why is a company this small listed on the stock market? It might make sense if the company plans to make acquisitions, doing a buy & build maybe? Otherwise, I would worry too much about the de-listing risk. That said, deep cleaning & disinfecting, is clearly a very topical area of activity".
It seems strange to me to query why a business is listed when it has just carried out an equity fundraising (as you also mention in your write up). Additionally, the document setting out the background to the placing mentions potential acquisitions:
"The Board of REACT believes there is an opportunity to scale the business through organic growth and carefully selected acquisitions ...".
In my opinion, the chance of React (LON:REAT) delisting is minimal.
OK fair enough. As I mentioned, if the business intends to make acquisitions, then I agree there is some rationale for it being listed.
Heavy director buying today at £TSL after an encouraging trading statement last week.
You many not like Trump Paul but god help us all if Biden gets in!
The geezer can’t even stay awake!
LOL well, I would not quite put it like that myself but it must be said he is very old. 78 by the time of the election and he has clearly struggled in some of the debates so how he will do in the presidential ones is a moot point. Personally I think it is crazy to appoint anyone to such a incredibly stressful and demanding post who will be in their 80's in mid term.
Mid term the next president of the USA will be 76 (Trump) or 80 (Biden). Impossible to be sure who will be fitter. I will only be 74, but am ineligible for the office.
At the risk of starting an argument (so this will be my only comment) I don't think it is age that makes Trump unsuitable, unfit or in any way appropriate for any form of leadership!
A nice Q3 report from Avation (LON:AVAP) today. Revenues and profits up, plenty of cash, good spread of customers, many of which are in companies less affected by Covid-19, and Net asset value per share increased to £3.24 - around double the current share price.
What’s not to like?
ricardo
Disc: I hold.
It's certainly intriguing. Can you hazard a guess as to why the free cashflow per share has been negative for the past 6 years?
Given that the company appears to make decent enough profits, I'm thinking it must be a quirk of how customers pay for leases, but it would be interesting to hear other ideas.
There is a detailed cash statement in the H1 accounts to 31 December 2019 (p12 of 35) which is available on the company’s website, but I do not have the expertise to analyse this.
You do realise the NAV you are quoting is as at 31st March 2020? I don't follow the news as assiduously as some, but I think things have happened since then.
Now that's not to say the shares don't trade below current NAV, they might do, but I wouldn't get overly anchored to a Pre-Covid valuation. That is to say the market, and you, should be forward looking, not backward.
Go to Note 25 of the trading update, and you will see the interesting stuff, namely the "Subsequent Events" section.
It’s a fair point, but all of those “subsequent events” have already been announced.
Perhaps surprisingly, AVAP seems to have had no problem so far in re-letting aircraft when a customer gets in trouble even since March.
Stocko says the NAV per share is £4.28.
Actually there is a very good presentation from management that you can find on their update from late May that gives some excellent insight into Avation (LON:AVAP) and the current situation. They address the Subsequent events in great detail. It was fascinating.
My take away at the time was that the impact on the business has actually been remarkably minimal. I think the total deferred rent agreed was around 7% of annual income. Most of that is offset by a reciprocal arrangement with borrowers. It's all deferral, none forgone.
The Virgin Australia insolvency was a most interesting case study. I won' regurgitate it here but if you are genuinely interested in Avation (LON:AVAP) then its worth listening to as the CEO goes through the entire asset base and what is happening. It is very different to what I think most of us assumed would be happening when planes got grounded and the airline went bust.
Asset sales of the type of plane Avation (LON:AVAP) lease also appear to still be going above book value rather than less. I guess this is because no planes are being made either so the demand/supply imbalance still remains. Overall I expect NAV to have held up very well against the 31st March number.
The vast majority of the planes they lease and operators they lease to (by revenue) are still flying and in the case of Viet airways expanding.
I think the market has got the wrong end of the stick with Avation (LON:AVAP) and is misinterpreting the covid impacts on its business. That is why management have been going to great pains to try and explain. Personally I don't think it will make much diff to the share price until European aviation market normalises though. Even though it is an apples and pears comparison it's about perception rather than reality.
I increased my long position post management presentations as I saw it as an unusual opportunity to top up on a very well run business where I consider the market to be mis-pricing assets due to a lack of understanding. Time will tell if I'm correct.
Equals (LON:EQLS) had been on my watch list but looks like it has been hit by big cash burn whilst it changed its focus to b2b and recent acquisitions; covid and the drop in travel and now some exposure to wirecard who it issued some of its cards through. A drop in the share price from 120p to 27p in a year.
"In fact lots of people seem to be permanently angry. I was too, when I was allowed on social media - it brings out the worst in people". Hi Paul you are so right! Keep up the lack of reverence.
"In fact lots of people seem to be permanently angry. I was too, when I was allowed on social media - it brings out the worst in people"
Funny. One of the things that makes me angry is social media itself. It's turning everyone into "sponges" who are easily influenced and have forgotten how to think and act for themselves. Take the smartphone away from most young people and there heads will explode because they will feel like they have ceased to exist. I know because I tried it with my nieces once - I hid their iPhones! :-)
All the best, Si
I agree with Paul's comments except I would say to his "far right permanently angry about everything mob" it is to me the left that are permanently angry containing all of the people who wake up waiting to be offended by something. Anyway, looking at shares I can't help but think it is only those that are tech based (which can include online retailers) that have what could be regarded as very good prospects as opposed to a very slow recovery to where they were prior to Covid-19. There are special cases such as food manufacturers where they have been run off their feet but those I know are private companies. If vast amounts of money keep being printed then eventually it must depreciate the value of the currency in comparison to, say, gold and that is something I am looking to maybe hold for the next few years.
I agree with Paul's comments except I would say to his "far right permanently angry about everything mob" it is to me the left that are permanently angry containing all of the people who wake up waiting to be offended by something.
They feed you the stories that you will click on. If you like to read stories about angry left-wing people then that's what they will keep feeding you. You are telling us more about yourself than about "the media".
All Facebook wants is engagement, i.e. keeping people permanently wound up and addicted to being angry so they click on links and the advertisers keep paying them. There is some cautious reason for hope that the current boycotts of Facebook by large advertisers in the US might bring some change but it's a long way back from here to reason.
Just take a look at any comments on a Daily Mail article; it's full of Disgusted from Tumbridge Wells types, usually condeming immigrants/poor/religious group/celebrities, for examples of right wing expressions of anger. More visably you have personalities like Katie Hopkins and Donald Trump.
This is off topic however.
One Media Ip (LON:OMIP) had a good RNS today. Two new initiatives should help garner further interest in a business that's probably as corona-proof as it is possible to be. Full article https://www.proactiveinvestors.co.uk/companies/news
I’m taking a look here, but where has £4 million cash gone in the last year?
Thanks as usual Paul for your excellent commentary. Required reading first thing in the morning. I really like your comment about falling in love or marrying a share as you put it. Certainly I have been guilty of that but I wonder whether the same could be said of your infatuation with Revolution Bars (LON-RBG)? :)
As with many companies, shareholders in Revolution Bars (LON:RBG) were unlucky that covid struck, just at the point when the turnaround was beginning to work (positive LFL sales, and profit moving up, debt reducing).
By loading up heavily c.18p per share, I've actually got back most of my losses, so holding my nerve & averaging down proved the right thing to do.
So I refute your allegation of infatuation! :-)
It's got enough cash/facilities to survive well into 2021, and it will be interesting to see how trading goes on the re-opening. Pub companies are all, at the moment, a bet on covid being tamed before they run out of cash.
Regards, Paul.
Paul - you have very often made profits of a level I have never achieved but I have to say that I could never hold a share going down from over 200p to 50p (ignoring the further Covid drop). I always cut my losses at the first indication of the charts indicating that it is going wrong. This undoubtedly means that I have missed significant rebounds but I know it has also saved me from many complete wipe-outs. Your comment about not falling in love with a share is so true and to that I would add that it usually pays me to avoid the temptation to go back in as I find that shares are totally unaware that they owe me anything! Thanks for all your brilliant comments
It is difficult to see a recovery any time soon. If COVID-19 persists then this sector is in real trouble. If COVID-19 nightmare ends sooner, say a vaccine becomes available then Revolution Bars (LON:RBG) face the same problems as before, oversupply in the market and rising costs (minimum wage for example). Either way, this is still worth selling. (see model below.)
Good management working in a difficult market can result in a bad outcome for shareholders.
BSV
Hi Paul, you recently took me to task over using the word will in my scepticism over RBG. My 'wills' were about how drastically the distancing rules would affect the operation (I am an ex operator) of this type of business which by its very nature depends on very intensive and profitable crowded sessions with a large number of guests standing on Thursday, Friday, Sat nights plus maybe Sunday brunches. The rest of the weeks sessions are often just barely covering costs or in the early week loss making.
The crowded and profitable sessions are now constricted by distancing rules and the brunches on Sunday by table distance rules. However I would think it is very difficult to operate these lower turnover but comparatively busy sessions with a skeleton staff.
I think it is brilliant that by loading up at 18p you have managed to get back to almost level. I don't think that having enough cash/facilities to survive through until mid 2021 is likely to be enough. The rate at which this type of business hemorrhages cash at below break even turnover levels is terrifying. I've been there and gone bust. I've also had great successes too.
The problem as I see it is that the Govt are enjoying all this control that they have but they have no comprehension of or ability to foresee the unintended consequences. Bournemouth beach and the lack of bogs spring to mind.
It is only reasonable that the guys at RBG do their utmost and are optimistic about the future but with that debt load, the distancing rules and the dead hand of govt dictating how they can trade I remain pessimistic.
Regards
Hugh
Re today's RNS from Non-standard Finance (LON:NSF) , as expected an equity issue is ever more clearly on the cards.
"Preliminary discussions with a number of the Group's larger shareholders regarding a possible equity issue to facilitate such a plan have been positive and are ongoing."
This is essential to repair a balance sheet damaged/weakened by paying too much for assets initially; necessary and (I think) productive investments in new systems and branch roll outs; a vainglorious takeover bid for Provident; and now massive and sudden (ie impossible to reprice fast enough for impairments. Fair enough. I was writing to the Board in January asking them to do this when the share price was >30p vs today's <7p .
More equity backing is essential to unlock better borrowing / the securitisation deal and because the next 18months are going to be a good time to grow market share in non-standard lending as rates are rising fast as mainstream lenders withdraws/ many small players go bust , leaving only well run specialists. (Question is of course, are NSF are one of those!)
However, my question is: how can and other large shareholder consultations like pre-arranged Bookbuilding placements not be akin to insider trading. Surely it would not be hard these days to arrange a virtual town hall style event or even solicit written inputs. Difficult to not feel one rule for the few and another for the rest - sad and dangerous when even a middle class, share owning, above average wealth, highly educated person feels this way.
Morning Paul
#K3C.
Interesting placing and acquisition announced this morning.
Looked good to me.
FY TU looked as expected too.
Would be interested in your take.
Michael
Hi Michael,
I've read the announcement from K3 Capital. It seems self-explanatory, so there's not anything I can add to it. I didn't spot a full year trading update, where did you find that?
Regards, Paul.
Paul,
This was in today's RNS, Year end was end May:
3. Current trading update
The year ended May 2020 closed in-line with full year expectations with revenue of £15.0 million and EBITDA of £6.8 million. Cash on the balance sheet as of 31 May 2020 was £8.3 million.
As announced on 25th March 2020, a cost reduction exercise ensured monthly overheads were reduced by c.70% from April 2020. This was achieved through the use of the furlough scheme and salary sacrifices.
New client mandates slowed during lockdown as sales staff were unable to visit client's premises, however, transition to Zoom consultations is underway and generating client mandates. The execution of existing pipeline deals has slowed during lockdown although buyer activity and deal completions are still taking place.
The Board remain confident in the medium and long-term outlook for the Company and as such still intend to recommend a final dividend for the year ended 31 May 2020.
The Board continue to actively look at acquisition target of complementary professional services businesses as they consider ways to further diversify the Company's revenue streams.
Interesting fundraise by £K3C
I'm not sure I approve (although the way they've placed shares seems good) of the acquisition. They keep saying it's complimentary but I'm not convinced a business sales broker is complimentary to the new company.
There's a lot to be said for sticking to your knitting. I remain interested on the sidelines.
Complimentary acquisitions are way better than complementary ones!
Randd optimise R&D tax credits which is a cracking service to offer to businesses they work with while trying to sell the business, which can take years. I think there are a number of "optimisation" services they could add and offer to their clients many of which will not end up with a sale. K3C get to know a lot about what they are promoting/selling, so additional services brought in by experts, managed with a light touch by the mother ship means even more growth. I do not HOLD.
Good round up as usual Paul.
Always interesting to hear your thoughts.
Cheers
Thx Paul an excellent early pre-amble.
The FT article this morning on the resurgence in the States (or some of the states) Makes for some frightening reading IMO.
I am not over 65 or American but am just in (early) retirement I was one of the people who sold out at the low but if you see all you retirement plans about to go up in smoke it is hard not to worry/panic (whatever you want to call it). I am certainly more cautious but I am not yet in FOMO mode as I still think that we will test and then go through March lows. Maybe wishful thinking on my part but that seems more logical than a continuation of the up and to the right pre-covid direction of the market, which even then I felt was built on sand.
Have a good day.
Michael
I must say a big thank you to Mr Contrarian for his post on 26 Jun about Redcentric (LON:RCN)
being ordered by the FCA to pay restitution to shareholders in the wake of them having mis-stated their accounts. I was a beneficial owner of these shares, but would not have spotted the restitution order without Mr Contrarian’s sharp observation. Scanning the RNSs daily must take considerable time, and I know from other subscribers’ comments that we are all extremely grateful to you. Please keep it going!
Watchdog - You can sign up for email alerts for RNSs for shares you own or are watching - for free - e.g. at www.morningstar.co.uk ('email alerts' under the 'Equities' tab). I use Morningstar email alerts - apparently their formatting is better on smartphones than that of other services.
ed_miller - Thanks very much for the tip. :)
I agree with what you have written Watchdog. The case of Redcentric (LON:RCN) is quite unique as shown in the FCA press release here: https://www.fca.org.uk/news/press-releases/fca-publicly-censures-redcentric-plc-market-abuse
1) "This is the first time that an AIM listed company has offered to implement its own scheme to pay some compensation to those affected by the harm it caused as a result of market abuse".
2) As a result of that there was no further financial penalty
3) There are criminal proceedings against three former employees
What is less clear is the procedure for obtaining compensation. I bought shares in the company during the qualifying period (9/11/15 to 4/11/16) in my ISA - a nominee a/c. All the implications on the company's website are that you claim direct - no mention of nominees. There is a form with instructions here: https://www.redcentricplc.com/...
There must be a lot of people who bought in that year and then sold (particularly just after the November 16 warning - three and a half years ago) - who no longer follow the company. Will their brokers be reminding them?
sharw - My understanding is that the final approval for the compensation scheme should be in place by 9th July, and the scheme will be open for claims from 13/7 to 30/10. But I'm not yet clear if one should submit a claim through one's broker or direct.
I very much welcome the news of criminal proceedings against three former employees. I would not want to prejudice these proceedings, but the Redcentric (LON:RCN) RNSs of 25 Oct 16 (et seq) shed some light on those who might be responsible and the company's connection with £MXC.
H & T (LON:HAT) all stores are now open. Co has reduced its drawn credit facility and reduced overall net debt. "While it is too early to determine the trading impact of Covid-19 on our performance for the year as a whole we are reassured by the volume of customers being serviced since we have safely re-opened our stores, and the early recovery in new customer lending."
Camera Angles Paul .....?
Right oh!
https://www.theguardian.com/world/video/2020/jun/25/huge-crowds-on-englands-south-coast-as-people-flock-to-beaches-video
The contrast between the beaches at Brighton and Bournemouth in the video is telling.
The video backs up the point Paul made.
The low horizontal angle deliberately looking along the beach makes it look like people are packed in like sardines.
Any angle from higher up, or looking out to sea shows groups (which may be families), typically separated by 2m or so.
Certain media organisations have been endeavouring to bias Covid news reporting for months. This is no exception.
Certain media organisations have been endeavouring to bias Covid news reporting for months. This is no exception.
Like the UK's 65,000 excess deaths, you mean?
Anyway, the problem isn't outside, the issue is inside so if there's a spike due to this it'll probably be due the travelling rather than the beach. Some ridiculous stories coming out of the US, like this one about the 16 people who went out to celebrate the end of lockdown and all ended up catching it:
https://www.standard.co.uk/new...
It's really contagious in confined environments, especially when people have had a few drinks and starting getting loud and lairy.
H & T (LON:HAT) reopening is interesting, although the delay to the FCA investigation leaves a bit of question mark hanging over them. Apart from that, though, you'd think they'd be in a decent position to navigate through these tricky times.
Note also the Ramsdens Holdings (LON:RFX) are one of the companies that have had their prepaid cards blocked due to the issues with Wirecard. That, presumably, won't be helping their FX business just as it's reopening.
timarr
Like the UK's 65,000 excess deaths, you mean?
Will still result in a lower Mortality rate within UK than Germany though.
As with media pictures of beaches, Perspective matters...
Will still result in a lower Mortality rate within UK than Germany though ... As with media pictures of beaches, Perspective matters...
It does indeed ... Iraq has a lower mortality rate than the UK. So has Venezuela and the West Bank and Gaza. This is nothing to do with healthcare provision and everything to do with demographics - and it doesn't mean you'll live longer if you live in the UK rather than Germany.
Crude death rates, which is what are being referenced here, are impacted by a whole range of factors but the obvious one is the size of the population over 65. If you have more old people more of them die in any given year. Germany has more older people than the UK which, in turn, has more older people than Iraq, etc.
For Covid-19 deaths the standard comparitor for the performance of countries is excess all causes mortality. That doesn't rely on variable measurements of who's actually died of coronavirus but simply shows the difference year on year of the total number of deaths recorded. It's a good indicator of how well a country has handled the crisis.
In the case of Germany and the UK the two countries are similar in terms of population size but the UK's excess death is running at six times that of Germany's. Remember too that Germany has more older people.
So, yes, perspective matters.
timarr
That link actually makes his point.
You see low angle telephoto of Bournemouth and high angle drone of Brighton.
Comparing apples and oranges.
(this does not mean that Bournemouth was not overcrowded, just that the video in that link tells a story the newspaper wanted to push)
My morning smallcap tweet: 17 companies
£K3C ASA International (LON:ASAI) GYG (LON:GYG) BigDish (LON:DISH) EQTEC (LON:EQT) Gulf Marine Services (LON:GMS) Non-Standard Finance (LON:NSF) Morses Club (LON:MCL) ECO Animal Health (LON:EAH) Lookers (LON:LOOK) Omega Diagnostics (LON:ODX) Staffline (LON:STAF) PV Crystalox Solar (LON:PVCS) Mountfield (LON:MOGP) SIMEC Atlantis Energy (LON:SAE) Stanley Gibbons (LON:SGI)
K3 Capital (K3C) £30.5m (max) placing and PrimaryBid offer at 150p, a 14% discount. Needed to acquisition and possible further acquisitions.
ASA International (ASAI) Business update. "The most relevant waivers for expected temporary PAR>30 covenant breaches have been secured." $110m of unrestricted cash. Collection efficiency continued to improve.
GYG (GYG) FY19 finals delayed to end July. Trading in line.
BigDish (DISH) cash will last only to year end, so will need more funding. Boutique corporate advisory firm hired in March still trying to find non-equity funding.
EQTEC (EQT) 2 year Collaboration Framework Agreement with Ireland's Carbon Sole Group to jointly participate in projects in Ireland involving biogas and district heating, waste-to-energy etc using EQTEC's Gasifier Technology.
Gulf Marine Services (GMS) Year-to-date performance remains ahead of plan, sticks with $57-62m EBITDA guidance. Cost saving target raised to $16.5m PA from $13m.
Advanced Oncotherapy (AVO) Agreements provide access to up to c. £42m of funding o further develop and advance manufacturing of additional LIGHT systems to address unmet medical need.
Non-Standard Finance (NSF) further to Thursday's RNS, discussions with its lenders are proceeding positively and gets waiver extension on £200m securitisation facility.
Morses Club (MCL) U Account customers' money frozen due to Wirecard collapse. Affects only 2% of total income and client money not at risk.
ECO Animal Health (EAH) as expected, gets Euro marketing authorisation for the use of Aivlosin for the treatment and metaphylaxis (disease control) of Mycoplasma hyopneumoniae in pigs.
Lookers (LOOK) Draft Report on financial shenanigans shows £19m of non-cash reductions to profit, c. half of that in FY19. Mgmt believe FY19 will still show and U/L profit.
Omega (ODX) reaches design freeze for the COVID-19 Rapid Test. Abingdon Health still to complete verification, validation, transfer the manufacturing protocols to consortium members and gain regulatory approval.
Staffline (STAF) reaches revised finance agreement with covenants "more appropriate for the Group's current trading levels." Remaining problem is paying deferred VAT due on 31 March 2021. "The Directors are working on options to mitigate this liquidity risk, including the implementation of a turnaround plan." I hold.
PV Crystalox Solar (PVCS) to return £2m (max) by tender offer by and Sept. Will delist then.
Mountfield (MOGP) majority of its sites have now been re-opened. Delays FY19 accounts to Sept.
SIMEC Atlantis Energy (SAE) FY19 accounts delayed to Aug.
Stanley Gibbons (SGI) some "volatile but defined [sic] improvement in trading" with last 8 weeks rev down 11% (from -45%). Financial position improved. Has liquidity for 4-5 months without taking any further mitigating steps or drawing on debt facility.
Hi Paul, great stuff, keep up the good work.... but you'll have to stop doing the SCVR live from Bournemouth beach.
Excellent overview Paul.
hi Paul, could you have a look at React Group React (LON:REAT) who came out with their half year numbers today- thanks.
I think this is a nice little business with good potential to exploit the possibilities in large scale cleaning projects it focuses on.
Sure I've just added a brief new section on it. You may not like my viewpoint!
All makes good sense to me Paul. Good job!
has anyone else found this website, its good for seeing how big a dent fees make in your trading account
https://larrybates.ca/t-rex-sc...