Small Cap Value Report (Mon 3 June 2024) - Main: HERC, BOWL, PMI. Brief: IMM, SONG, HTG, FRAN, TPFG, PHE, FADL, MORE, GENI, HVO

Good morning, it's Paul & Roland here today. Welcome back Roland!
That's it for today! 3 main sections for the things we found most interesting, and then loads of brief comments on everything else. I've tweaked the format again, so hopefully that goes down well, including our colour-coding in the list of companies reporting. Let me know either way.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
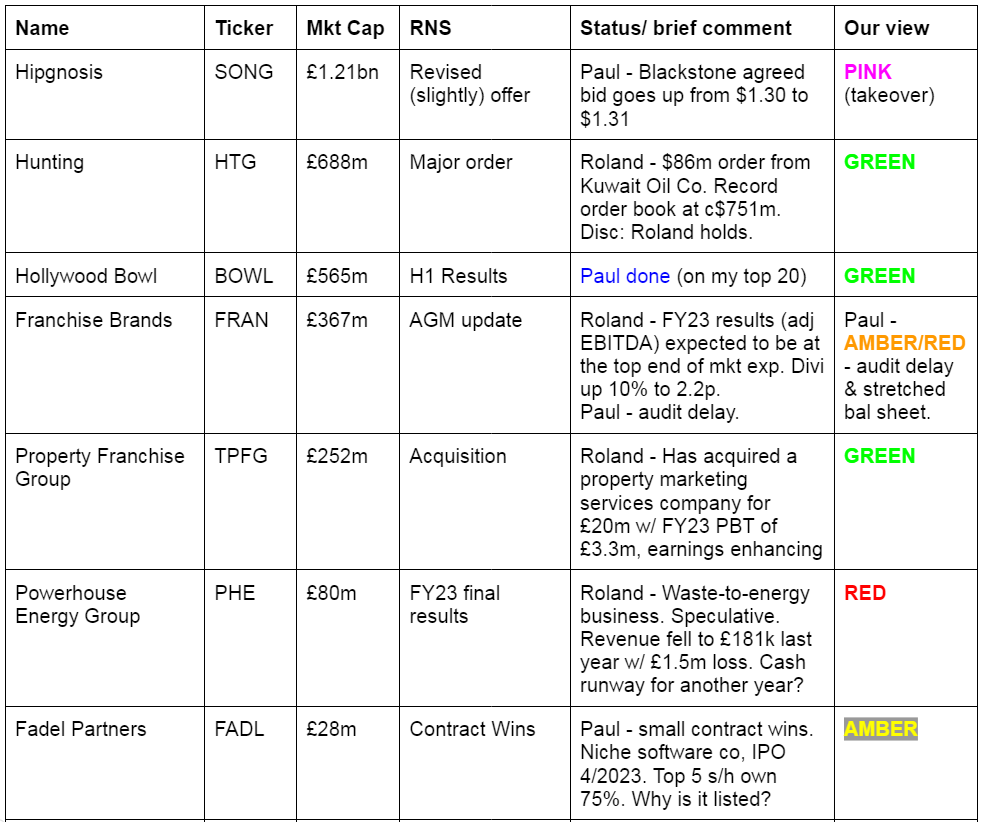
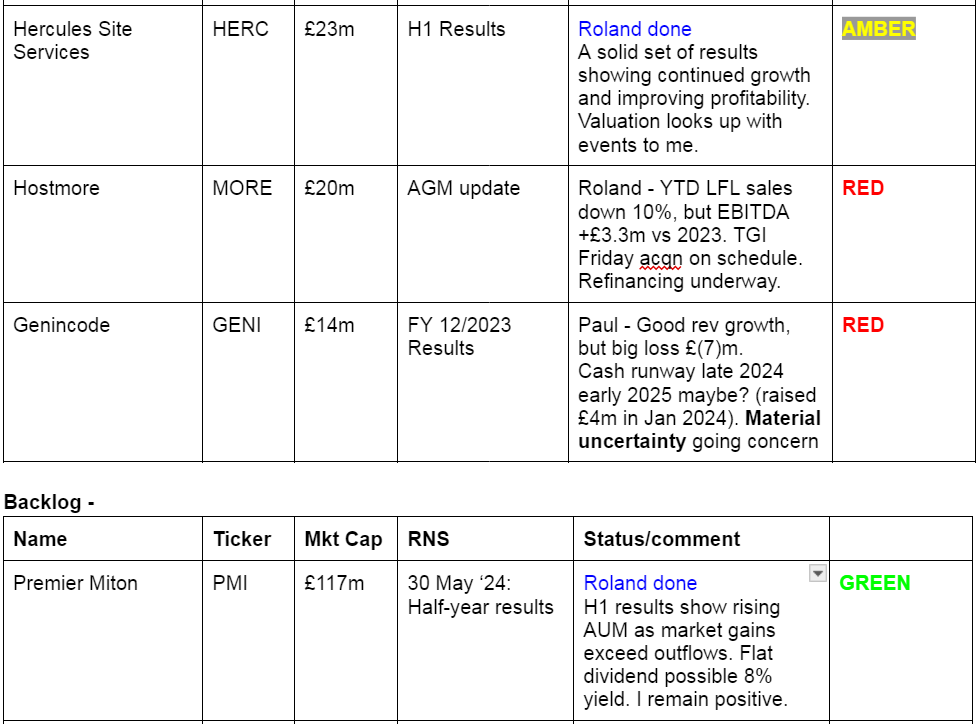
Quick comments & Movers
Treatt (LON:TET) - new CEO David Shannon appointed today.
hVIVO (LON:HVO) - signed £2.5m contract with mid-sized pharma. Most revenue to be recognised in FY 12/2025. Interesting detail. Says its new Canary Wharf facility is largest of its type in world, and about to open. No change to forecasts, but "gives a little more clarity" to FY 12/2025 revenues (per Cavendish), on top of existing "good visibility". We like HVO here, and have been GREEN on it multiple times this year & last.
ImmuPharma (LON:IMM) - up 17% to 2.5p (£11m) - Disposal - Paul - No colour (too speculative)
IMM has raised £1.5m from selling shares all its 9.9m shares in Aquis-listed Incanthera (OFEX:INC) (which have risen in the last 6 months from 6.3p to 18.6p). I looked at Incanthera a few weeks ago, and it’s an interesting-sounding story, of major orders from a large client, which it claims keep being increased, and will see Incanthera into profitability. As Incanthera has been a zero revenues jam tomorrow company to date, punters in its shares are taking an all-or-nothing binary bet on management telling the complete truth, as there are no historical numbers to rely on, and on nothing going wrong. Good luck with it!
IMM itself has a bit more cash to play with now, and also retains 7.3m warrants in INC (exercise price of 9.5p is in the money now, expiry 6/9/2024)
See our archive here for two previous mentions of IMM in Mar 2024. I did have a brief dabble in this share myself, and made a bob or two as a fun punt only, but don’t currently hold. As previously, I don’t think we can sensibly give either IMM or INC a colour code, as both are too speculative.
Summaries
Hercules Site Services (LON:HERC) - up 4% to 38p (£24m) - 23/24 interim results - Roland - AMBER
This construction manpower specialist has delivered solid growth over the last year. Both profitability and cash generation appear to have improved and I’m more positive about this business than I was a year ago. The valuation looks up with events to me, for now, but I think Hercules could be worth watching.
Hollywood Bowl (LON:BOWL) - up 3% tp 344p (£587m) - H1 Results - Paul - GREEN
Profit and divi both rise in H1, and we get an in line with expectations full year outlook. Balance sheet and cashflow are both fine. I wobbled with the last (annoyingly vague) trading update, but seeing these numbers and reassuring update, makes me reinstate it to fully GREEN! A smashing self-funding roll-out of a successful leisure format, that is also paying decent divis along the way.
Premier Miton (LON:PMI) - up 2% to 74p (£117m) - 23/24 interim results (30 May ‘24) - Roland - GREEN
This small-cap fund management specialist has seen assets under management return to growth as market gains outweigh continued net outflows. Fee margins remain under pressure but net cash of £30m helps underpin the dividend and the valuation looks undemanding to me. I remain positive.
Paul’s Section:
Hollywood Bowl (LON:BOWL)
Up 3% tp 344p (£587m) - H1 Results - Paul - GREEN
This is the UK’s largest operator of 10-pin bowling centres. Also a smaller, but growing operation in Canada. We’ve been positive about this share here for a while, as it’s a lovely cash generative business that has a proven ability to self-fund expansion into new sites, refurbs, whilst at the same time paying decent divis.
Checking our previous notes -
18/12/2023 - 285p - GREEN - I positively reviewed its FY 9/2023 results, in line with previously raised forecasts, and found nothing I could fault.
16/4/2024 - 333p - AMBER/GREEN - I moderated my positive view slightly, due to an unclear TU, and share price looking up with events.
Turning to the latest news, interim results for the 6 months to 31 March 2024 - I’ve highlighted the most important numbers (to me) below. I find EBITDA numbers now so unreliable, that I tend to ignore them. Pre-IFRS 16 EBITDA has some use, but post IFRS 16 EBITDA is completely meaningless, as much of the rental operating costs by-pass it.
Adj PBT is fine, providing the adjustments are sensible (which I think they are here).
Profit (and divis) are still moving in the right direction, upwards, as you can see below -

UK (71 sites) LFL revenue growth was less than I would have expected, at only +1.3% - that’s not good when its wages costs will have risen by c.10% vs last year (LY). Much better 8.0% LFL revenue growth in Canada (11 sites).
Note that finance costs of £5.9m nearly all relates to leases. Finance income is £1.0m (interest on bank balances, which confirms it usually operates in a cash surplus position), and only £100k interest on bank borrowings. So it doesn’t really use, or need the bank facility I would argue. Although maybe there might be blips where it briefly goes overdrawn due to timing of supplier payment runs, VAT, payroll, etc? Anyway I always like to check finance income/charges to make sure it ties in with the reported balance sheet snapshot of cash/debt, which it does here, everything looks fine (see note 5).
There are two outlook sections, here are both -


I see the ridiculously vague “profitable growth” buzz phrase has found its way into the second outlook section above, albeit with a comma. All this actually means is that they expect to remain profitable - I would hope so! It doesn’t mean profits will grow. This doesn’t fool anyone, and it irritates the hell out of me every time I see it. “Profitable growth” does not mean profits are going to grow, it’s a deception that I wouldn’t expect to hear from a quality company like this.
On the positive side, I am pleased to see it specifically state above that trading is in line with expectations. Board/market are interchangeable really, but market expectations is better, with a footnote to say what it is. Communications at BOWL is not very good, there’s always something that gets up my goat every time I report on BOWL. It’s a pity to see own goals, but doesn’t alter the investing case, so let’s move on.
Broker forecasts - I can’t find any detailed notes, which is another gap in BOWL’s communications. All small to mid caps need to make sure that broker notes get out to private investors, as we create the liquidity and set the share price! Such an obvious oversight, which is all too often the case I’m afraid.
The consensus graph below shows that 7 brokers cover it, none of whom let us see their notes. So only for the privileged to get access to information that will have obviously been guided by the company itself.

Current year FY 9/2024 is 21.8p, giving us a PER of 15.8x which strikes me as a reasonable valuation for a cash-generative, self-funding roll-out. We’ve had a disposable income squeeze on consumers, which has now more recently reversed, as inflation has dropped to only 2.4%, and average wages are rising well above that. Therefore I think this could be an interesting time for leisure companies to possibly start beating forecasts as households relax the purse strings.
Also, think about the big gross margins that BOWL achieves. Of its £119m H1 revenue, direct cost of sales was only £19.8m, giving a ludicrously high gross margin of 83%. So even a small rise in revenues mostly drops through to the bottom line. Although it would probably have to employ more staff to deal with significantly increased customer numbers.
For this reason, I think there could be significant potential upside on the forecasts.
Balance sheet - NAV £151m, less intangibles of £94m, gives NTAV of £57m. That’s not huge, but it’s ample for this business model, since current assets contains little in receivables or inventories. The big numbers are fixed assets (the fit-outs of all the sites) of £91m, and lease entries - which show a surprising negative net liability of £44m. I got into trouble before with another company XPF, for assuming that negative lease entries means it has loss-making sites, which management strenuously denied. The shortfall there was claimed to be due to rent-free and reverse premium incentives from landlords being netted off. Lease accounting is complicated, so all I would say is that if management at BOWL do a webinar, it would be worth asking the question why there is a £44m deficit on all the lease entries, and does this mean they have some problem, loss-making individual sites? Even good retail/leisure operators would normally have a few loss-making sites, so that is quite normal. The question then is what are they doing about it, and can they exit problem leases?
In all other respects the balance sheet is fine, and includes £41m in cash (with no interest-bearing borrowings).
Cashflow statement - we have to manually adjust these, to make commercial sense, given that IFRS 16 stupidly puts some of the property rental costs into financing activities, thus overstating the cash generation above that line. Adjusting the figures, I get to £32m post-tax cash generation in H1. This was spent as follows: £7.5m acquisition of 3 subsidiaries (Lincoln Bowl, Woodlawn Bowl Inc, and Lucky 9 Bowling). Then there was £15.5m in conventional capex (which will be for new sites, and refurbs), and £19.4m in dividends paid in H1. With a few other small items, that adds up to an £11m cash outflow in H1, which is why the cash pile reduced from £52m to £41m in H1. I’m not concerned by this, as the big cash outflows are almost all discretionary items (divis, capex, etc), not a sign of any underlying malaise. Also there’s ample cash remaining. Still it’s good to check these things, and the very useful cashflow statements are often overlooked by many investors, which is a mistake I think, as cashflows often show reality a lot better than easily manipulated P&L statements in my opinion.
Paul’s opinion - seeing the figures in full has renewed my confidence in BOWL. It’s such a good business, and will continue growing organically with each new site it opens.
I think the valuation stacks up on existing forecasts, looking probably about right. However, I suspect there could be good, highly operationally geared upside to the forecasts as consumer disposable incomes are now rising well above inflation. The GfK consumer confidence numbers are also strikingly better than a year ago, as I mentioned in my podcast over the weekend.
Therefore, whilst BOWL looks priced about right, I suspect there could be (can’t be certain of course), a decent probability that BOWL might start to out-perform the existing forecasts as 2024 progresses. If that’s what happens, then progress for this share could be driven by ahead of expectations updates maybe. With an 83% gross margin, the profit numbers could really fly - eg a 10% increase in LFL revenues would add £9.9m extra gross profit. Even if it had to increase centre staff by 10%, that would still be a £7.9m increase in gross profit, which would drop through to roughly a 25% increase in PBT (profit before tax). Those are only my rough numbers of course.
Put all this together, and the potential for a private equity takeover offer, and I’m moving back up again to GREEN.
Roland’s Section:
Hercules Site Services (LON:HERC)
+4% to 38p (£24m) - 23/24 interim results - Roland - AMBER
Confidence we will match market expectations for the whole of FY2024
Hercules Site Services is a construction and manpower group that floated in early 2022 and was founded in 2008 by CEO Brusk Korkmaz, who remains a 66% shareholder.
I covered last year’s half-year results in June 2023, when I was cautious about cash consumption and low margins. Since then the shares have round-tripped and are now unchanged from when I last covered them.

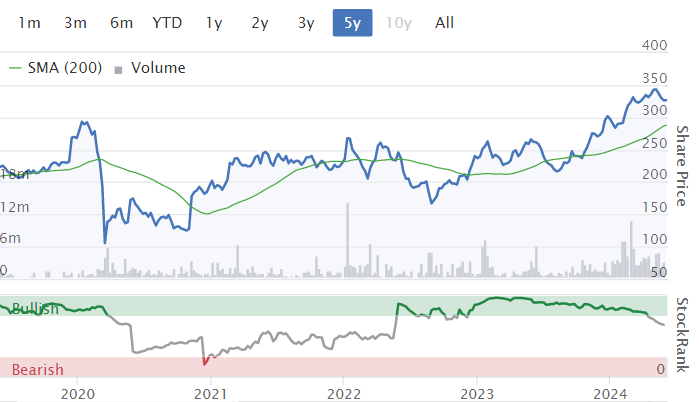
However, the business appears to have expanded significantly over this period. Hercules’ StockRank has also improved, as the chart above highlights – when I looked at the shares a year ago, they scored 16/100. Today, the StockRank is a more promising 88/100.
I’m curious to see if an opportunity may be emerging here.

H1 24 financial highlights: These figures cover the six months to 31 March 2024. Hercules’ results are typically weighted to the second half of the year, but these numbers seem to show good momentum. Management are confident the group is on track to hit full-year expectations.
Revenue up 32% to £48.8m
Gross profit up 21% to £8.1m
Pre-tax profit of £0.2m (H1 2023: -£0.2m)
Free cash flow of £2.3m (H1 2023: -£1.5m)
Net debt ex. leases : £4.3m (H1 2023: £6.1m)
Interim dividend held at 0.6p per share
Cash generation and profitability appears to have improved versus the first half of last year.
To allow for the second-half weighting I’ve calculated trailing 12-month figures for profitability. My sums suggest a TTM operating margin of 2.8% and TTM ROCE of 13.3%.
Low margins are typical in staffing and recruitment businesses, but both figures show an improving post-IPO trend:

Operational highlights: Hercules is still very much in growth mode. So far this year, the company has opened up a new Rail contracting division and has launched its Construction Academy. This initiative aims to work in partnership with education and business to train new generations of construction workers.
Hercules also made its first ever acquisition in November, buying Future Build Recruitment for £1.25m. Management describe this as a white collar recruitment company operating in the UK construction sector. Future Build is expected to be complementary to Hercules’ existing blue collar business (this is how the company describes it).
Relying too heavily on acquisitions for growth is always a risk, but organic growth still seems quite strong.
Management says that Labour supply to HS2 Phase 1 (Northern Section) increased to 450 operatives at the end of March, up from 400 one year ago.
The new Rail division is said to have “started well” with “steady growth continuing”.
Meanwhile, labour supply to other sites has increased to 550 operatives at 31 March, from 500 one year ago.
Various new contract frameworks have been secured, but for me the highlight is the company’s first contract in the nuclear industry, at Sizewell C. This power station project is apparently expected to be in construction for up to 20 years with an estimated cost of £30bn.
I see nuclear power as important going forward, so I think securing a reputation in this industry could be valuable, long term. Renew Holdings (LON:RNWH) is one example of a construction/engineering group that’s done very well by specialising in areas such as nuclear and rail.
Outlook: management sound confident in the outlook this year and full-year guidance has been left unchanged:
The opening of the construction academy, the steady growth in the new rail business, as well the development of the commercial possibilities from Future Build, all give us confidence we will match market expectations for the whole of FY2024.
However, Hercules’ profits are actually expected to dip this year before returning to growth in FY25. This is due to the drag from the setup of the new Rail and Construction Academy divisions.
An updated note from Cavendish on Research Tree today leaves FY24 adjusted earnings per share at 1.1p, down from 1.27p per share in FY23.

Interestingly, the dividend is expected to rise to 1.9p per share this year (FY23: 1.8m), at a cost of about £1.2m.
To me, the dividend looks like it may be covered by free cash flow but not earnings. So it may be more affordable than it first appears.
These forecasts put Hercules on 34 times FY24 forecast earnings, albeit with a useful 5% dividend yield.
Roland’s view: My normal reservations about this sector remain – low margins and the potential for losses on big contracts. However, financial performance seems to have improved over the last year and I am encouraged by progress.
The growth focus on infrastructure as well as general construction makes sense to me and will hopefully help to create a business that is more differentiated and less exposed to cyclical downturns.
One point I’d make is that much as I like dividends personally, I would argue that Hercules’s payout seems a little generous, given its lack of earnings support.
Given the growth focus of the business I would prefer to see a focus on eliminating bank borrowings and paying a reduced dividend. But perhaps this payout is a sign of the group’s owner management – CEO Brusk Korkmaz is in line to take home two-thirds of any dividend payout.
On balance, I don’t see any fundamental problems, but I think the shares are up with events for now. So I’ll go AMBER.
Premier Miton (LON:PMI)
+2% to 74p (£117m) - 23/24 half-year results (30 May ‘24) - Roland - GREEN
we are encouraged that shorter term investment performance is on an improving trend as market breadth improves and mid and small cap stocks recover.
As it’s a quiet day for news today, I thought I would circle back to take a look at last week’s half-year results from this well-known small-cap fund manager.
Conditions have been tough for most UK asset managers over the last year. But this comment from CEO Mike O’Shea really highlighted the longer-term scale of the headwinds companies such as PMI have been facing (my bold):
It is estimated that the Investment Association UK equity sectors have now seen net outflows every year since 2015, totalling more than £50 billion, equivalent to almost a quarter of the total 2015 assets under management.
One might argue that the UK asset management sector has clearly not been doing a good job of demonstrating the value it can create for investors. Or perhaps domestic asset managers have simply been the victim of wider macro and structural trends, such as US tech growth and the shift to passive funds.
To be fair, O’Shea also acknowledges these points directly in his comments:
Looking forwards, it seems logical to us that the demand for savings will continue to grow as investors have to fend for themselves. Active managers such as Premier Miton will definitely have a role to play in managing these savings. To do so, our funds will need to demonstrate that they can add value, over and above the returns from the major indices [...]
Moving on, let’s take a look at the results,
2023/24 half-year results summary: Premier Miton’s half-year results present a mixed picture, in my view. The good news is that assets under management rose, thanks to strong market/investment gains (and an acquisition).
The less good news is that net outflows continued and the company continues to see fee erosion, with profits down sharply.
Total assets under management rose by 9% to £10.7bn during the six months to 31 March. However, this included a £560 contribution from the acquisition of Tellworth Investments in November. Excluding this, AUM rose by 3.4% during the period, as market gains of £937, outweighed net outflows of £486m:

To put these figures in context, Premier Miton’s AUM was £10.8bn at the end of Sept 2023 and £12.6bn at the end of Sept 22.
Net revenue for the half year fell to 14% to £30.1m, with adjusted pre-tax profit down 28% to £5.7m. Amortisation and share-based payment charges meant that reported pre-tax profit fell by 75% to £0.6m.
Premier Miton did report some cost savings during the period, cutting overheads by 8.5% to £24.8m. However, these savings did not outweigh the 15% drop in management fees. This reflects a lower average AUM during the half year than the prior H1 and a reduction in fee margins:

Management say the reduction in fee margin was “primarily” due to a change in business mix, but I suspect there could still be some pricing pressure here, too.
PMI’s fee margins have now fallen from 64.6 basis points (0.646%) in FY22.
Balance sheet/cash: the impact of this lower profitability on the balance sheet seems to have been limited. Net cash was £30.7m at the end of March, down from £31.5m one year earlier.
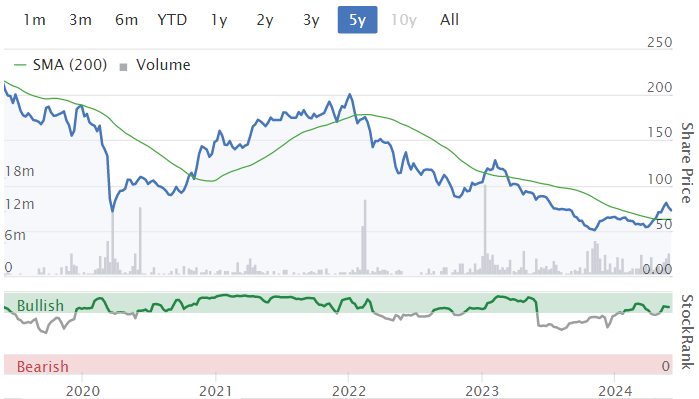
The group reports an equity value of £120.7m, which is broadly in line with the current market cap. According to Stockopedia, PMI’s average return on equity has been 10.4% since 2019. So a valuation in line with book value seems about right, to me.
However, if profitability does start to recover, I think there’s scope for a significant re-rating here.
Dividend: the group’s strong cash position has allowed management to maintain the interim dividend at 3p per share. If the full-year payout is held at 6p this year, that would give a tempting 8.2% yield.
However, management reiterated that the company’s dividend policy is to payout 50%-65% of adjusted net profit. This slightly cryptic comment was also included:
We will of course consider all relevant circumstances when we decide on the overall level of dividend for this year
Outlook: no specific guidance was provided with the results and I’m not able to access any broker notes for this company.
However, consensus forecasts shown on Stockopedia appear to be unchanged following the results and suggest adjusted earnings could fall by a further 30% to 6.1p per share this year, before starting to recover in FY25.

For what it’s worth, these forecasts also suggest the dividend will be held at 6p, a view I share given the group’s strong cash position.
These estimates put the shares on a P/E of 12, with an 8.2% dividend yield.
Roland’s view: To some extent, Premier Miton is at the mercy of market conditions and external events. The rampant outperformance of US markets over the last few years has meant that even beating UK indices is not necessarily enough to outperform a cheap S&P 500 tracker.
Premier Miton’s performance track record seems a bit mixed to me – the company says that 68% of its funds are above the median investment performance since launch or tenure, down from 76% one year ago.
However, in fairness, even the UK market has been distorted by a few big cap performers (oil, pharma, banks) over the last year or so. For a small-cap specialist like Premier Miton, it’s not been an easy market.
For me, the key point to remember is the operating leverage that fund managers can deliver when they achieve net inflows in a rising market. Profits could rise sharply if this kind of favourable environment reappears.
Of course, there’s the risk that this might not happen.
Personally, I remain positive on UK fund managers generally at current levels and believe Premier Miton probably offers decent value at this level, with useful backing from a cash-rich balance sheet. I’m happy to stay GREEN on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Any thoughts on today’s Gsk Zantac news?
Shares of GSK dropped more than 9% after a Delaware judge allowed more than 70,000 lawsuits alleging its discontinued heartburn drug Zantac caused cancer, to go forward
Sale on today on Berkshire Hathaway (NYQ:BRK.A)!99% discount.https://www.ft.com/content/034...Hope you all filled your boots when you could!
'Forbes’ real-time billionaires tracker briefly showed Buffett, who is the seventh-richest person in the world,as losing $136 billion on Monday, knocking out almost all of his
fortune'
Ref Berkshire Hathaway (NYQ:BRK.A) here is waht CSS Invetmnets are saying:
NYSE has seen trading halted in a number of companies including Berkshire Hathaway after an IT glitch possibly linked to the recent move to T+1 settlement."
Ref Berkshire Hathaway (NYQ:BRK.A) here is what CSS Investments are saying:
NYSE has seen trading halted in a number of companies including Berkshire Hathaway after an IT glitch possibly linked to the recent move to T+1 settlement."
Anybody got any knowledge on David Shannon who has just joined Treatt as CEO? Market is down 20p which suggests not good. I know he has come from Croda, a business I quite like. He has relevant experience. I like and hold Treatt.
Raspberry Pi IPO open. Price range 260p to 280p value between $600m -$£650m, with a turnover of $266m that gives a price to turnover ratio of 2.2 - 2.4, which seems reasonable for an IPO as most of the time it's a lot higher.
Massive thank you Paul for flagging Surface Transforms (LON:SCE) as a trade in your weekend podcast - it's worked a treat so far as a short term trade following it's recent refinancing. I'm also not that confident it will sort out it's act with manufacturing given the many false dawns and finally deliver on it's bulging order book but v. happy to ride the wave for now...
Card Factory (LON:CARD) Teleios holding decreased to 9.92% from 10.99%. Wish it was more but hey ho, off they go. Just checking back as well - they held 14.92% to 25/9/23 so shifted 5% of total company shares in 8 months. Will they carry on dumping or hold for now?
It was 10.99 last Feb, so its taken an age to shift that 1%. This was my fear that people had overstated the extent to which and caused me to sell out last week. Seems more than coincidental that immediately after the holding TR-1 the CEO announced he's bought just under £100k of shares.
Ben it was 10.99 to Feb-24 so not so long ago ;)
Card Factory (LON:CARD) Not a "clean" buy as far as I am concerned:"This share purchase was made pursuant to the requirement in the Company's Remuneration Policy requiring one third of bonus payments (after tax) to be invested in Ordinary Shares, where the minimum shareholding requirements are not met."
Hadn't picked up on that. Good spot. Such a frustrating share as Card Factory (LON:CARD) clearly held back to an extent. If it's taking 3 months for Teleios to shift 1% we could be stuck here for a good while longer. 3 years at that rate!
I hold Card Factory (LON:CARD) l think Teleios will continue to sell, probably when the price is higher around 110p. I will join them. This is stuck in a band between around 90-110p. I sold half at 110p, should have sold them all. The dividend was paid last week which is why the shares fell on Thursday. The director buy is interesting may rise the share price.
Alumasc (LON:ALU) - good call by Turbo last Thursday. https://www.stockopedia.com/co...
Happy as a holder to be proved too cautious. Yiannos1's comment highlights support for further upside.
Not a small cap but I believe a popular share here, so I thought I'd share some scuttlebutt with readers concerning Games Workshop (LON:GAW)
I happened to be at the UKGE (Games Expo) at the NEC this weekend and I was surprised to see that Games Workshop had no official presence whatsoever in stark contrast to last and prior years where they were principal sponsors with the largest and most prominent stand.
Asking around, nobody had any explanation as to why it might be (somebody suggested that they pulled out at the last minute but I can't confirm this). Others pointedly suggested that they had "flooded the market" and were therefore concentrating on US events (if true, I rather like this explanation).
I had an interesting discussion with a former longstanding employee of GW who suggested that UKGE used to be their most successful recruiting ground for new hobbyists and he expressed surprise that they were not attending. He also suggested that they didn't want to spend the money on exhibiting this year but I don't know how he could know this.
I'm an investor but not a gamer so I spoke to several different people including distributors and hobbyists to try to gauge the temperature. The general view seems to be that the hobby is growing and that although GW is too expensive, it has a virtual monopoly on table top wargaming. There are many small indy competitors (many started by ex GW employees) but there appears to be a network effect whereby if somebody starting out wants to be able to play games with other hobbyists, then their best chance is to play GW games because of its prevalence. One distributor had a decent selection of GW games at the show and said that it was flying off the shelves. They said that they are restocking by the pallet load at their store.
Even gamers who are a little jaded by the corporatisation of GW seemed genuinely enthusiastic still for the product and explained that they still purchased and played GW games in spite of the costs.
I spoke to a member of a tabletop gaming club who answered my question concerning the fear that 3D printing might spell the end of GW's monopoly and he explained that 3D printing is a hobby in itself and requires a good deal of skill and commitment to do. He said that although he has his own 3D printer, he still purchases GW pieces because it's so much less hassle.
Overall, I came away quite reassured although I am slightly perplexed by their absence from UKGE 24 and would love to know if any readers have any insight as to why they were not in attendance.
Love the term Scuttlebutt, I had to look it up - the original ‘water cooler’ an old Naval term for the water barrel. V clever
Comments like this are worth the Stocko sun alone.
Thank you.
I hold Games Workshop (LON:GAW)
Regards
Michael
Another really good podcast over the weekend - thanks for these. I also hold a small basket of shares to benefit from a recovery in the housing market - as well as Alumasc (LON:ALU) and Eurocell (LON:ECEL) I also hold Michelmersh Brick Holdings (LON:MBH) and keep meaning to take a look at Epwin too as keeps showing up on some of my screens.
I had a look at Topps Tiles (LON:TPT) yesterday and think this might be my pick for a recovery in the housing market. While sales and volumes have dropped massively, they've held up gross margin, which suggests to me they have pricing power. After all, they did hit their strategic ambition of £1 in £5 spent.
So when the housing market returns and the volumes start to grow again, they'll benefit massively. Currently trading at 40p-ish. I think when the housing market volume increases even modestly, they could make 6p to 8p EPS easily.
I had a look at Topps Tiles (LON:TPT) yesterday and think this might be my pick for a recovery in the housing market.
I also selected this one in a basket of cyclicals, several of them building supplies-related, back in December. But I sold quickly when I saw its operational performance diverging from those construction stocks which benefit from regulatory requirements, such as Alumasc, Epwin, Volution and Genuit. If/when the housing recovery occurs, however, I’m sure it will do well.
FTI travel group just filed for administration. 3rd largest touristic company in Europe with a 4 billion Euros turn over. They are Germany's 3rd largest tour operator.
This does leave a gap for other tour operators. TUI AG (LON:TUI) and easyJet (LON:EZJ) holidays for example.
Wow this is big news. FTI used to be a strong force in package holidays in Germany.
Wonder if there will be some opportunistic buying of the brand + part of the current operations, by existing players?
On Beach group (LON:OTB) could buy out the brand and some of the existing relationships with suppliers and the customer list, and re-platform the online site to the OTB platform? After all, they used to have overseas ambitions (Sweden I think?) and I am sure OTB management have the appetite for strong growth in the next few years.
(I hold OTB in the Boon Fund)
All I can say is wow! Who needs a Bloomberg terminal when you have Paul/Graham analysing the data!
Regards
Michael.
Don't forget Roland! He hit the ground running today with a guest appearance :-) He's a machine, I could hardly keep up!
I had been thinking for sometime that colour coding on the list would be a good addition, thank you
Thanks Friday31, we'll keep doing it then!
appreciate its not smallcap but any ideas why CRH is top of the leader board today - I cannot find any news to back this up! (Yes, I hold)
CRH (LON:CRH) which leaderboard? I can't see it top of any on here.
I'm referring to the top risers of the day! Click on the CRH link and you will see its up about 5.5% On a technical note as the main listing is now in NY its no longer an FTSE100 company - but still listed in London.
JD Sports Fashion (LON:JD.) was top FTSE 100 stock, with over 7%. CRH (LON:CRH) l wondered why it was not among the highest movers. No idea why it is up today, maybe a share tip?
Beeks Financial Cloud (LON:BKS) remains in high regard on SCVR, and is very highly rated. There's a high moat, and more and more users of their existing customers mean steady growth. But I wonder whether the anticipation of many new customers may not be a bit high as the geopolitical risks get bigger. How many worldwide financial institutions would want to tie themselves fully to a UK based service whose largest customer is the NYSE? ( Beeks Financial Cloud (LON:BKS) remains one of my two major holdings, but I sold a few this morning)
A lot of SAAS companies got whacked last week in the US on commentary that getting new deal were taking longer so I do not expect Beeks Financial Cloud (LON:BKS) to be any different.
A few things would stand out though for me, they are nowhere as much pumped on price as their US counterparts, they are nearly profitable which is something escaping most US companies and lastly the cloud business works that the more you use the more you pay so I suspect even with their current customers they will see good growth.
I continue to hold this but expect it'll continue its bumpy road to an eventual sale
Where can I find more info about NYSE being Beeks Financial Cloud (LON:BKS) largest customer?
Is it for their Exchange product?
When will we find out who bought the recent big director sell off at Warpaint London (LON:W7L) or is there no fixed period for such announcements?
Sam was asked that question at Mello. He wasn't allowed to declare but he mentioned Fidelity had been involved as well as a number of other well known managers.
Have you asked Warpaint London (LON:W7L) ? I ask as Sam was at Mello recently, presented 3 times and is very approachable in my experience
They also have an IR contact who answers emails when I’ve sent them
I asked the same question of Sam and he said he d confirm, which he has now done: William Currie Group
Canaccord
Fidelity
Artemis
Chelverton
Charles Stanley
Premier Milton
Rathbones
Aegon
Telworth
Columbia Threadneedle
Hope this helps, AG
Anyone any idea why dull old Alumasc (LON:ALU) is up around 10% this morning on no news?
Breaking out it would appear?
Re Alumasc (LON:ALU), of what Viz? Has someone laid an egg?
I would not be surprised if it was down to Paul’s bullish comments in the weekend podcast. I know he is concerned to have it known that he is not recommending stocks, but inevitably his positive remarks have consequences !
Alumasc (LON:ALU) (I have held for some time)
Hurrah.
See no news. Dont see unusual volumes. Went to ADVFN, post there says it was in a podcast (PS did mention but didnt think it was that widely listened to). This burst up makes me think it was tipped by SimonT or in SCSW. So (please correct me) this looks like noise to me.
I suspect that a seller might have been cleared at Alumasc (LON:ALU) [I hold].
I say this because I've been buying smallish clips of it repeatedly in recent weeks, especially after readers here flagged it up as great value, which reminded me that I had liked it back in Jan & Feb 2024. Every time I bought, the price remained unchanged, so it was clear that there must have been a sell order being worked in the background. That seemed to clear last week, and the bid price began to rise (a good indicator sometimes that a seller has cleared, as the MMs now want to buy).
This morning's big rise seems to confirm my view that the seller has now finished.
Me mentioning it in the weekend's podcast might have also have flagged it to some listeners, although as we'd already been discussing it here earlier in the year, it wasn't news to any subscribers here.
I don't like the long gaps that ALU leaves between trading updates, they need to update us more frequently, as people obviously get more nervous that silence over 4-5 months might mean it's struggling in some way. I know companies are supposed to inform the market straight away if something is going wrong, but often they hope to recoup shortfalls and don't reveal problems immediately.
I feel that ALU got through the current building downturn very well, and management say this is a mixture of its highly regarded brands, and new product innovation which has recouped lost business and maintained its good profit margins. Paying decent divis too. Let's hope the next TU is reasonable.
Regards, Paul.
Maybe I got lucky, I did post this last Thursday (I hold):
Just flagging up for anybody interested there seems to be decent positive trading activity today, coupled with a bullish chart signal suggesting a breakout to around 200p
On 9 Feb 2024 Paul gave a thumbs up (179p, £65m):
"Readers asked me to look at recent in line H1 results. I'm glad they did, as this looks a smashing value share. I think it's too cheap, with upside on future earnings and a possible re-rating onto a less mean PER. Thumbs up from me, but as always, this is just on a quick review, so you need to do your own more in-depth digging."
That was it, thanks turbo, a really timely reminder from you about Alumasc (LON:ALU) last week, thanks. We had a bit of a discussion about it last week I recall.
As we're covering >600 companies here, each day seems like a separate event to me, in fact by lunchtime I couldn't even tell you most of the companies I've written about that morning! So it's really helpful to get reminders like yours about overlooked potential bargains. We just have to hope that the seller is a distressed fund forced seller, not someone who knows more than we do and wants out! Always the risk though isn't it. Hence a portfolio approach.
Thank you to all, especially Paul S. with your comments on Alumasc (LON:ALU) some of which I had missed. I purchased relatively recently, impressed by the range of quality products with a terrific range of quality customer examples, though always a bit turned off by the fact that they are generally in a sub contractor type market of big guys who don't often pay their bills on time!
I daren't suggest JD Sports Fashion (LON:JD.) are better this am on the Maltese Falcon’s weekend comments but it could be a combination of that and the fact Fidelity have upped their stake with the announcement coming this am first thing.
Haha thanks TheOx. Yes I doubt that me making JD Sports Fashion (LON:JD.) my weekend podcast mystery share would be responsible for today's £503m increase in its market cap. Far more likely to be other factors, as you say, like Fidelity increasing its position ;-)
We are officially out of the "sell in May and go away" period now.
Well my portfolio is up 0.84% so far this morning. Sell in May is a hangover from the pre big bang era, when the City was a more leisurely place.
Ah the 80's and 90's great days when you could go out to the pub at lunchtime have four pints head back to the office and nobody batted an eyelid, I can even remember early on in my financial career when it was acceptable for people to have a fag at their desk.
Simpler but great days (bar the fag at the desk policy).
Andy
May was my sixth-best month ever. It's June where my portfolio struggles, having only made money 14% of the time, the next worst month I make money 50% of the time, which is September. That 14% may change, as it was 8%, but I'm up so far this month. The best month, December, I make money 93% of the time.
Crikey that’s some analysis
Of course not sure “make money” is the correct way to look at it but nothing wrong with knowing the ebbs and flows of what Mr Market thinks your companies should be priced at .
“Stock market is a voting machine not a weighing machine”
I’d be careful jumping in and out of any companies based on monthly movements but sure you know this .
Sorry, replace "make money", with "up months and down months". I don't make any buying or selling decisions based on the time of the year, it's just how my portfolio seems to have developed.
Whatever works for you sir!
Whatever works for you sir!
I have to say Jon you have the best name tag on this forum.
It's the Santa Rally!It's a known market force.https://www.investopedia.com/t...
I'd agree that June tends to be a bad month, I haven't been up in June since 2016 when I was up 3% or so. However, at the moment we are enjoying something of a recovery after a couple of very difficult years and it seems sensible to stay invested.
Morning Paul, Roland and everyone. Hope you all had a good weekend.
Is there any chance you could take a look at Springfield Properties (LON:SPR) today?
They have released a RNS this morning for sale and partnership with Barratt Developments (LON:BDEV) of their land. Money will reduce debt and make the company a little more financially stable. Broker target has increased to 140p from 130p. So there is still an upside of 40% from current price.
Hi gmtrader,
Sorry but Springfield Properties (LON:SPR) news slipped through the net today. I see its shares are up 4% to 98p, almost doubled since the low in Nov 2023, and still seems to be at a hefty discount to NTAV, per the StockReport.
I'm too tired to do any more work now, and have just found a stray "Diane Abbott" in the fridge (one of those ready mixed small cans of gin & tonic), so I'm now in wind-down mode, sorry about that.
Thanks for flagging the SPR news though.
Regards, Paul.
lol that’s ok. For a second I thought you were hiding MPs in your fridge!
Is anything going on M&C Saatchi (LON:SAA) uber low volumes but the price stays remarkably the same like somebody is buying them all up. I hold and my largest holding from the depths 2020 so a multi bagger for me. Any thoughts out there ?
Good news on Property Franchise (LON:TPFG) and Franchise Brands (LON:FRAN) but what will the PBT be ?
Morning Mike,
Yes I have wondered about the stability and gently rising share price of M&C Saatchi (LON:SAA) that I also hold.
I did top slice at around 185p, although still hold a reasonable amount. The company is relatively small on a market cap basis, but is in my view one of the best know global brands in advertising, although this is now only one facet of its offering.
It will be a beneficiary I feel of the forthcoming general election and the advertising division will improve as interest rates decline, whenever that might be.
Also the simplification of the business by off loading various subsidiaries that contribute little to the bottom line and are a distraction for management, such as the recent disposal of M&C Saatchii (Switzerland) is a positive.
It appears financially sound and is hardly expensive, certainly on a crude PE perspective and given its brand recognition must be considered a potential bid target, given that it has received two failed bids. One from Vin Murria at around £2, who continues to hold some 12% of the equity and a share/cash offer at worth 247p at the time from Next 15 (LON:NFG). Richard Staveley at Rockwood Strategic (LON:RKW) considers the shares to be worth at least £3. Time well tell.
All the best
Thanks for note we continue to hold then, I to did top slice as it had become disproportionately large and having taken a severe hair cut thankyou CAKE and the crooked directors you do fret a tad. SAA obviously had issues around reporting some 4/5yrs ago.
Morning Paul
You may want to add Property Franchise (LON:TPFG) to your list given the significant acquisition announced this morning. It looks on first reading to be sound business extending its services and geography. Property Franchise (LON:TPFG) is paying a total of £20m of which £15m is payable on completion and £5 one year thereafter.
"Highlights
· The Guild and Fine & Country provide services to a total of 1,036 outlets, of which 65 are international outlets
· In the year ended 31 December 2023, the Acquisition produced audited revenues of £13.2 million, audited EBITDA of £3.5 million and PBT of £3.3 million
o 73% of FY2023 revenues were from recurring memberships and licences
· Total consideration represents c.5.7x 2023 audited EBITDA
· Initial consideration of approximately £15 million, payable in cash, has been funded through a new facility with Barclays Bank
· Post-Acquisition leverage for the Group will be below 1x FY2023 pro forma adjusted EBITDA
· The Acquisition fits within the Group's strategy to acquire accretive businesses with complementary and recurring revenue streams which deliver network expansion and geographic growth
· Well regarded and experienced management team, including Iain Mackenzie, who will remain with the businesses
· Expected to be immediately earnings enhancing."
Acquisition of The Guild and Fine & Country | Company Announcement | Investegate
Morning Jonno,
Property Franchise (LON:TPFG) is already on our list, Roland did a quick comment on it.
I see broker forecasts have been raised, but there wasn't enough room in the box to add any more.
We like TPFG here, we've been GREEN on it for ages, same with Belvoir too that it took over/merged with. The good things about the Belvoir merger are that a larger market cap should attract more institutional interest and hence get a higher PER and more liquidity in the shares. Plus some duplicated costs can be saved. Price probably now getting close to being up with events though? Although today's deal sees forecasts going up.
Regards, Paul.
Cheers Paul, you and your colleagues, Graham and Roland do sterling work, not sure where you find the bandwidth. Full marks for passion and industry.
Like many on Stockopedia I really enjoy and appreciate your weekly podcast. A must listen for me.
All the best
Thank you jonno, much appreciated! It is a lot of work, so it helps us keep up our motivation when people give us a pat on the back :-)
Hercules Site Services (LON:HERC) H1 results confirm another excellent performance culminating in record revenues, EBITDA and PBT. The Group is on track to meet market expectations for the full year. All three businesses reported double-digit growth for H1, benefiting from underlying market demand, Hercules’ investment in new service lines and technology, as well as a maiden contribution from the Future Build acquisition.
Contract momentum continues, with over £5m in civil projects and new framework agreements signed with Costain and Hill Group. The integration of Future Build is progressing well, and the Hercules Construction Academy is already developing a reputation for first class training. Importantly, H1 was a period of strong operational cash generation, supporting an interim dividend of 0.6p per share.
The outlook statement indicates that Hercules is on track to meet market expectations and anticipates further strong demand for the Group’s services. We also take confidence from recent market indicators with April’s PMI survey highlighting the strongest pace of expansion since February ’23.
In our view, Hercules is a business with good trading momentum, an ambitious management team and a focus on the most attractive segment of the construction market. We see scope for forecast outperformance in the second half, note the attraction of a 4.7% dividend yield, and reiterate our 55p Fair Value / share estimate.
Link to research note here: https://www.equitydevelopment....
Property Franchise (LON:TPFG)
At first glance a good earning enhancing acquisition of Fine & Country and The Guild of Property Professionals.
Cannacord raise TP from 521p to 589p.
A.
(I hold)
The acquisition by Property Franchise (LON:TPFG) today looks like a cracker. Less than 6x EBITDA, immediately earnings enhancing (+7% FY24, +13% FY25 as per Cannacord) and more than doubling the number of estate agency outlets, including some international ones.
Another one broken by Sky News on Sunday evening!
Such a good business, and lots of sensible well priced M&A.
Another one that sky news reported last night - don’t know how they do it?!
Yet another Sky News last night https://news.sky.com/story/onl...
Online fashion giant Stein to file prospectus for £50bn London Float.
Surprisingly? - they are choosing the out of fashion London exchange
Who knew German beer vessels could fetch such a hefty valuation!
Surprisingly? - they are choosing the out of fashion London exchange
They wanted New York, but in view anti-Chinese feelings in US they settled for London, so we're second choice. Not sure how much Chinese influence in the company there is now that they are headquartered in Singapore.
Perhaps the vendetta by the Guardian (slave labour etc) can now turns on Shein in lieu Boohoo
Hi dartagnan, I had read that we were the poor relatives second choice exchange amongst all the geopolitic pressures. I was merely making a MrContrarian style pun on "out of fashion". Very lamely obviously!
Pennant (PEN)
RNS out after close of play Friday that Rockwood increased from 7% go 10%.
Not sure if that was as a result of the placing or buying in the market, I’m guessing the latter .
Be interesting if they keep buying do watch out for further increases in the next weeks if they are increasing to a main holding .
There’s definitely something brewing with new Chsirnan who’s a Rockwood guy (I think) plus a “failed corporate activity” cost of 300k in the recent update .
Somewhat smoke and mirrors and inspector clouseau skills required but at a minimjm it seems pretty copper bottomed at this price as it makes money and has cash and excess property to sell .
I think there’s an acquisition of a much bigger entity in the pipeline that will surely mean a fund raise and a some tyoe of reverse takeover though no idea who this is or what a deal looks like (it could be a good deal for big shareholders and a poor one for minority )
Pure and total speculation based on nothing more than a brief conversation I had 12 months ago with a bloke at a bar in Chiswick
Planetx: Pennant International (LON:PEN) it appears that PEN was due to release full year earnings today, according to Stockopedia.
Re Pennant International (LON:PEN) results on 24 April, co stated early June for FY23
My morning smallcap tweet: Disorganised crime
Infrastructure India (LON:IIP) Hostmore (LON:MORE) WH Ireland (LON:WHI) Property Franchise (LON:TPFG) Franchise Brands (LON:FRAN) Fadel Partners (LON:FADL) Marlowe (LON:MRL) hVIVO (LON:HVO)
◄Infrastructure India (IIP)► proposes to delist to ease the realisation of assets. With a 99.9%+ value destruction, its work on AIM is done. [SP=0.1 Cap=m]
◄Hostmore (MORE)► AGM stmt - rev in 20 weeks ended 18 May down 10% but EBITDA up £3.3m. In line? [SP=16 Cap=21m]
◄WH Ireland (WHI)► sells Capital Markets Division to Zeus For £5m max. Only £1 now, rest contingent. Outlook - "improving market conditions, the benefits of the cost reduction programme and the sale of the Capital Markets Division announced today will, should the recent market improvements continue, enhance the prospects for the WH Ireland Wealth Management Division". [SP=4.2 Cap=9m]
◄The Property Franchise Group (TPFG)► £20m acquisition, immediately earnings enhancing. [SP=400 Cap=252m]. I hold.
◄Franchise Brands (FRAN)► guides FY-Dec adj EBITDA at the top end of market expectations of £29.3m to £30.1m. FY accounts delayed due to regulatory technicality following a takover. [SP=190 Cap=367m]
◄Fadel Partners (FADL)► wins c$1.5m 3 year contract and a $0.2m contract . [SP=140 Cap=28m]
◄Marlowe (MRL)► confirms timetable for £150m special div resulting from sale of division. [SP=558 Cap=540m]
◄hVIVO (HVO)► wins £2.5m contract for world's first Omicron BA.5 (ie Covid) challenge model. [SP=26.6 Cap=181m]
Hollywood Bowl (LON:BOWL) half year results out, top line pretty flat in the UK against high like for likes. Running out of steam? I wonder if the strategy of not rising prices is starting to bite.
Canada continues growing and more sites added.
I really like the management at Hollywood Bowl (LON:BOWL) and I think they understood that the UK in bowling wouldn't add much more growth and hence the Canada move. They are also tentatively moving into the putting area which could be good addition. Whilst I do not see them having outstanding growth mid single figures is achievable. Depends what you are looking for really but I don't see anything that would make me want to sell on todays numbers
Barratt collaboration to accelerate Durieshill Village - new research here: https://www.equitydevelopment....
Springfield Properties (LON:SPR) has entered into a strategic collaboration with Barratt for the development of the group’s Durieshill site. Springfield and Barratt will work together to develop this new, sustainable 3,000 home village within commuting distance of Edinburgh and Glasgow. Barratt has made a cash payment of £10m to Springfield and will, in consideration for half the land at Durieshill, provide and fund the infrastructure development for the entire site over the next five years.
The cash payment of £10m reduces Springfield’s bank debt to £41m as of 31st May, well below the stated target of £55m. More significantly, Barratt infrastructure funding will materially accelerate the development of the site, whilst also eliminating Springfield’s requirement to tie up capital for the next five years, This minimises development risk to Springfield and optimises the group’s return on capital.
In addition, Zoopla’s House Price Index for April was published last week. On their measurement, house price inflation was -0.1% for the UK, but with regional variations. They highlight 1.4% price growth in Scotland in contrast with negative inflation in London and the South of England.
Given today’s positive news, we increase our ED Fair Value / share to 140p (from 130p). This is based on sector average ratings (FY’24 P/E of 17.5x and P/Book of 1.0x) and still looks undemanding to us.
Franchise Brands (LON:FRAN) accounts (and hence AGM) delayed owing to challenges from their auditor relating to upgrade of accounting requirements on the occasion of their market cap exceeding regulatory threshold. Hopefully just a sign of extra audit workload but there is room in the RNS for this to signal some lax accounting practices that require tightening.