Small Cap Value Report (Mon 30 July 2018) - BoE, LUCE, ARDN, CLG, XPP, FOXT

Good morning!
Today I'm planning to take a look at:
- Luceco (LON:LUCE) - trading statement
- Arden Partners (LON:ARDN) - interim results
- Clipper Logistics (LON:CLG) - preliminary results
- XP Power (LON:XPP) - half year results
2:30pm: Edited this list in response to reader requests.
By the way, I stayed in my first ever AirBnb this weekend: a privately owned, 16th century castle deep in the Irish countryside. Admittedly, not much of the original is left standing from the 16th century. But it was a fun introduction to the world of AirBnb!
Bank of England
In economic news, we are on the cusp of seeing interest rates rise again at the Bank of England, for only the second time since 2008. There is a 90% chance of a rate hike on Thursday, from 0.5% to 0.75%.
Personally, I've been reducing my exposure to GBP-denominated assets in recent months, thanks to the tardiness at the BoE. I now have close to 20% of my portfolio invested in funds which own USD-denominated debt.
Leaving the economic arguments to one side, my viewpoint as an investor is straightforward: I want the biggest returns and yields possible! If the choice is to earn (say) 3% in the US or 1% in the UK, then I don't mind swapping the currency risk and moving funds to US instruments instead.
Long-term, I remain a bull on GBP relative to EUR and perhaps even relative to USD. If we saw several rate hikes along with clarification on trade rules after Brexit, then I still believe we could see a very strong pound Sterling - brilliant news for owners of GBP-denominated assets (like many readers of this report, I suspect), for importers, for British tourists, etc. Not so brilliant for others, of course.
Luceco (LON:LUCE)
- Share price: 33.8p (-9%)
- No. of shares: 161 million
- Market cap: £54 million
It's an H1 update for this LED lighting manufacturer.
I'm amazed to see that this share price has halved since I wrote about it last, in April.
Since then, there have been two interesting bits of news:
- It admitted defeat in the US and announced the closure of its US business.
- At its AGM, 18% of votes went against receiving the company's Annual Report and Accounts. 22% of votes went against re-appointing KPMG as auditor of the company.
This is the company where the financial controller resigned after Luceco failed to value its inventories correctly. The CFO left the company not very long afterwards. It's a fine example of an IPO stock that has failed to live up to expectations (it only listed in 2016). Large numbers of former and prospective shareholders are now evidently giving it the bargepole treatment.
Right, onto this H1 trading update. Key points:
- UK retail did very badly, sales down 20% and poor margins.
- Sales growth remained strong overseas
- Adjusted operating profit "close to break-even" for the period.
Outlook: With cost reductions, a higher order book and improved pricing in place, Luceco expects adjusted operating profit to show year-on-year growth in H2.
My view
It's a pity the company is carrying so much net debt (£41 million), as otherwise it could be a low-risk value play.
Even with the net debt, it could be tempting for some people to punt on it around current levels, betting that profitability will recover.
Personally, it's beyond my risk tolerance. I am looking for good businesses that aren't too accident-prone, and I want to be able to sleep at night!
The attempted revolt against the auditors and the Annual Report by some shareholders hints at the unease and general loss of faith in the business.
For what it's worth, I calculate that Luceco made an adjusted operating profit of £5.7 million in H2 2017. The company is predicting that it will beat this in H2 2018.
The enterprise value is £82 million. So if H2 improves as forecast, and then we get a "normal" H1 in 2019, the current share price will not look too expensive.
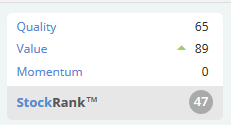
This means it's potentially at a good level for a contrarian bet. It passes Stockopedia's "neglected firms" stock screen. I wouldn't say that it's extremely deep into value territory yet, but it's getting there.
It is categorised appropriately as Highly Speculative and Contrarian. Check out the Momentum score!
Arden Partners (LON:ARDN)
- Share price: 42p (-1%)
- No. of shares: 31 million
- Market cap: £13 million
Interim Results - Six months ended 30 April 2018
This is a small (but full-service) investment bank with offices in London, Birmingham and Bristol.
It came to my attention again recently when Glen Arnold reported that he had sold out, for a variety of reasons.
One of these was that Luke Johnson, an 11% shareholder, had decided to step down as Arden Chairman. This could be interpreted in different ways, but it is at the end of the day a bad news announcement from the company.
These results, for a period during which Mr. Johnson was in office, are as follows:
- Corporate client list up by one third, from 40 to 53
- Research service agreements in place with "a significant number" of clients, enabling it to charge them for equity research following the implementation of MIFID II.
- Strong start to H2
Despite all of the good news, we unfortunately see a pre-tax loss of £2.3 million, on reduced revenues of £2.6 million.
The outlook for H2 should be better, after completing what the CEO describes as "a root and branch restructuring". The number of clients is up significantly, the equity research team has doubled, and Arden reports "a significant pipeline of well-advanced corporate transactions".
My view - the main attraction with this stock, in my opinion, is the balance sheet and the potential that it could buy back more chunks of its own shares or go private in an attractively-priced deal.
It reports net assets of £10 million, with zero intangibles and very liquid assets including £5.1 million cash. Buying the shares at a discount to NAV or at just a modest premium to cash would be attractive, in my view.
The one in this sector that looks most appealing to me in the short-term is Cenkos Securities (LON:CNKS). It has a well-known activist investor who is calling for a sale (thank you for pointing this out in the comments last week).
If Cenkos did sell up, I imagine that a trade buyer would be willing to pay more than the current share price. This values it at 1.6x its December 2017 net asset value, or just 1.35x its December 2017 cash balance.
Clipper Logistics (LON:CLG)
- Share price: 313.5p (-23%)
- No. of shares: 101.5 million
- Market cap: £318 million
I don't follow the logistics sector closely. There is plenty of reader interest in this announcement, however, so let's take a look.
Many of you who follow the e-commerce business Sosandar (LON:SOS) will know that Clipper provides warehousing and logistics services to that company. It has also started doing some work for Boohoo (LON:BOO) subsidiary Pretty Little Thing, for Marks and Spencer (LON:MKS) and for ASOS (LON:ASC).
These are good headline numbers from Clipper. In summary:
- Group revenue up c. 18% to £400 million
- Group EBIT up c. 16% to £21 million
- Dividend up 17%
There are no references to expectations, except that net debt is said to be in line with expectations at £31.7 million.
In fairness to Clipper, it followed a similar format last year.
It's a general problem with the market that companies don't state clearly what they expect to achieve, and some companies don't state whether performance has been good or bad, relative to their own expectations.
This means that only those with access to some kind of broker research can compare results to forecasts.
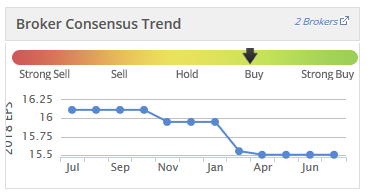
Another option is to check on Stockopedia or other investment software for forecasts. On Stocko, for example, we can see that Clipper's 2018 "EPS Normalised" was forecast at 15.5p. The actual EPS achieved by Clipper is 14.2p. A substantial miss.
I can see a broker note where the broker had an even higher EPS forecast: 16.5p. So it's an even bigger miss by Clipper against that target.
The outlook has deteriorated, too. Today's statement brings with it some caution, mentioning "wider forces affecting the UK retail sector".
We are mindful of the wider economic climate, and in particular of the headwinds facing our customers in the retail sector. We continue to monitor the situation closely and engage with our customers to find new ways to pro-actively assist them.
My view
I think it's an understandable fall in the share price.
The EPS result is 7%-14% below broker's forecasts.
For a highly-rated stock (P/E multiple in excess of 20x), you always run the particular risk of suffering the double whammy of an earnings miss and a compression in the valuation. In a nutshell, that is what is happening with CLG.
Given the earnings miss and the cautious outlook, brokers have reduced PBT forecasts by about 10% for FY 2018 and FY 2020. Cutting the share price by 20% from a high level seems reasonable to me, in that context.
With the company still profitable and winning new business, we do have a potential buying opportunity for anyone who has been on the fence with this one.
I'm happy to sit it out, as I find logistics to be a tricky sector to invest in.
Note that earnings momentum has been poor for a while at Clipper:
When it comes to the UK retail sector, the numbers haven't been that bad. Perhaps the issue is that Clipper doesn't have enough of the Sosandar (LON:SOS) / Boohoo (LON:BOO) / ASOS (LON:ASC) type of business, relative to mainstream retailers who are finding life more difficult?
I'd welcome further comments on this.
XP Power (LON:XPP)
- Share price: 3650p (+2%)
- No. of shares: 19 million
- Market cap: £701 million
A nice H1 report from this developer of power controllers (converters, etc). You can get a comprehensive list of its products via its website.
These results leave expectations unchanged for the full year.
XPP is an example of a stock that no longer fits our market cap limits, thanks to the successful execution of strategy:
The Group has applied a consistent strategy of moving up the value chain and our growth derives in part from the targeting of key account customers. Once we are approved to supply these larger customers, we have a strong track record of successfully gaining a larger share of their business.
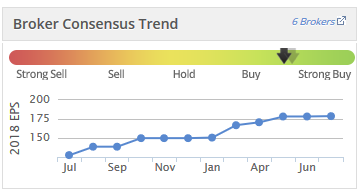
Besides this organic growth, it has also made some successful acquisitions. It hasn't put a foot wrong, and EPS expectations and the share price have reflected this. The EPS trend chart:
Currency effects are huge for this stock, and can distort things. So I always urge people to focus on the "like-for-like" results. Latest numbers:
- Order intake increased by 9% to £101.4 million (+17% in constant currency and 10% on a like-for-like basis in constant currency)
- Revenue increased by 16% to £93.2 million (+25% increase in constant currency and 13% on a like-for-like basis in constant currency)
These are some decent organic growth rates. XPP describes the global capital equipment markets as "buoyant", making for a benign external environment.
Other forms of progress
- Own-design products now 78% of total revenues (H1 2017: 75%).
- Book-to-bill ratio greater than 1 (i.e. more orders coming in the door than being done).
- Second manufacturing facility in Vietnam is on track to complete, production on stream in H1 2019.
Margins - XPP reports "some shortages of components together with component price inflation", causing a minor decline in gross margin in H1. I would guess that the XPP management team will be able to manage this supply chain risk, as they have managed so many other challenges. It's probably the most obvious and important risk mentioned in today's report.
Balance sheet - It's holding some debt now after paying for dividends, acquisitions and inventory growth. Doesn't look excessive.
My view
I've consistently had a positive view of this stock, and continue to do so.
Being value-oriented, I tend to resist paying up for High Flyers, and that's how this share is rated by the Stocko algorithms:
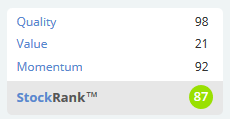
Given the track record and continued progress, I am heavily inclined to think that XPP deserves its high rating.
Foxtons (LON:FOXT)
Half-year Report - Fascinating to see this London estate agent swing to a pre-tax loss in H1.
Despite bouncing higher today, the Foxtons share price is looking rather sad now at 53p compared to the 2013 IPO price of 230p (and 350p was breached in early 2014).
The lettings business has been mostly flat (revenue down 1%), as anticipated.
The volatile sales side of the business, on the other hand, sees revenue down 23%.
CEO comment:
The property sales market in London is undergoing a sustained period of very low activity levels with longer and less visible transaction outcomes, which clearly impacts our business.
What will it take to see a resumption of normal activity levels in London? A capitulation by sellers, perhaps? Or perhaps once Brexit is sorted out, that will drive lots of capital back in, and things can get moving again?
At least Foxtons enjoys a £12 million cash balance and no debt.
If your timeframe is long enough and you can see activity levels returning to normal (which presumably they must, sooner or later), then this could be another interesting contrarian play.
All done. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Clipper Logistics (LON:CLG)
Hmmm, I hold CLG and Computacenter (LON:CCC) - is the new trend for companies to issue woolly forward statements to let the share price tank, then load up?
If CLG issue a statement saying that 2019 is going really well at the end of Q1 I'm going to be really mad - especially as the directors offloaded millions at £4.30 and have decided to reload at £3.18. I feel like I'm being taken for a ride.
I was getting excited about Asian LED stocks around 20 years ago. They didn't do much then and they don't do anything now, especially as I imagine these UK tiddlers are competing against huge volume producers. LUCE looks like a potential basket case to me and the financials look quite awful - much higher debt and inventory. No thanks.
Hi, thank you, I'm aware of that issue, and it's a very valid point. In the case of Clipper Logistics (LON:CLG) the normalised EPS forecast on Stocko was lower than the actual EPS forecast from a broker whose research I was able to access. If the actual EPS forecast that I could access had been less than 15.5p, then I would have phrased my remarks differently. Cheers, G
Graham
Is there any chance you could give the Stocko development team a nudge on fixing this issue - forecast EPS and normalised historical eps not being on the same basis? Sometimes it doesn’t cause a problem. But I have seen shares with a Stock Report forecast eps growth of 80%+ when the like for like growth was nearer 15%. This can be very misleading when reading the stock report, the Stock Ranks and the guru screens all of which use these numbers. It’s the one problem with an otherwise excellent and much loved service
I have reported this several times but so far nothing has changed
Thanks
Julian
Julian
I entirely agree with you on this point. I have also raised this point with Stocko. It can make the projected EPS growth figures very misleading and this then feeds across into all other figures which are based on EPS growth. I can understand that it might be difficult to work out normalised EPS from broker adjusted EPS forecasts. The alternative I suppose would be to include historical adjusted EPS figures as well so at least you can compare the broker forecasts with historical figures on a like for like basis.
Hi Julian,
The Stocko team reads the comments so I am sure you are being heard loud and clear. I agree that this is an issue and I hope there is a solution!
I wonder what can be done about it. Brokers have a habit of forecasting results on an adjusted basis. For many stocks, it might not be possible to find any forecasts on a reported or properly normalised basis. And the data provider probably doesn't know which forecasts are for statutory EPS vs. which are for adjusted EPS.
So I suspect that the only way to deal with this would be to remove the EPS forecasts from any calculations being used by the algorithms.
Regarding XP Power (LON:XPP) there is an 8 minute talk by CEO and CFO here:
https://www.edisoninvestmentresearch.com/edison-tv/clip/xp-power-2018-interim-results
The only negative I can see is the shortage in component supply but they are very candid about this saying it has impacted working capital in H1 and will affect gross margin in H2.
I like the sensible attitude to pace of acquisitions that comes across.
I hold XP Power (LON:XPP) too, and in fact topped up this morning.
In addition to Wildshot's summary I'd raise another couple of points:
1 It wouldn't need to rise much to be considered for FTSE250, would this give it another boost with forced buyers? In fact I think there's a strong chance it will end up there in time.
2 For a company it's size the daily volume is often tiny, sometimes only a couple of hundred shares. Does anyone know why?
Hello Graham,
Another vote for Clipper Logistics (LON:CLG) from me
Hi sbotting... yes I'm looking at Clipper Logistics (LON:CLG) now. Half-way through writing about it. Cheers! G
Clipper Logistics (LON:CLG)
Looking at the accounts from 2017 revenue was up 17.24% and PBT, 22.33%. In their interim statement from December 2017 the management suggested that H2 was the profitable period for the company due to the Xmas trading period.
“Trading continues to perform well in the second half of the year and there is a strong business development pipeline, some of which is at an advanced stage of discussion. Our peak trading period has seen significant year-on-year increases in activity in all sectors, enhanced by the impact of new contract wins coming on-line. Further, the seasonal nature of the Clicklink joint venture means that significant profits are generated in the November and December peak months, with losses typically resulting outside of the peak trading months, such that Clicklink profitability is skewed into the second half of Clipper's financial year.“
The 2018 accounts show a similar revenue increase of 17.65%, but a PBT of only 11.92%, which is down on 2017 and I’d imagine short of market expectations considering what was written in December.
Clipper Logistics (LON:CLG) results. Appears to be below £400m. A reasonable share price sell-off today. Just qualify under £400m after today's 20% share price fall. I can't seem to see the reason for the large share price fall at first glance but the rating was fairly high to start with.
I'd be interested in hearing your thoughts on Clipper Logistics (LON:CLG) as well Graham given the brutal 20% drop in share price this morning! This seems like an over-reaction to me but I think that people are reading this as a profit warning with the reported EPS of 14.2p being much lower than the forecast of 15.5p.
What's confusing is that no mention is made of this being a "miss" in the results and in the last update (in April) the board confirmed that they were trading in-line with management expectations. So are we seeing a big disconnect between market and management figures? Something has been mishandled here but I'm not clear what just yet.
Could be a buying opportunity?
Clipper Logistics (LON:CLG) I see directors sold millions of shares earlier this year at 430p.
duplicate deleted.
Damian, I'd agree with you here. Clipper's update didn't appear to be straight forward with regard to whether they were on track or not. Companies that spin things like this are not very helpful. The risks to me are that Clipper Logistics (LON:CLG) is working with larger companies that have a better negotiating position.
Hi Damian,
As described in my report, the results from Clipper Logistics (LON:CLG) are indeed a miss and expectations for the future have been downgraded as a result.
It's a shame that these simple facts can be left out of an RNS, but that is the system we are working with!
Graham
Graham
Although Stocko report forecast EPS under the "normalised" heading, very often these are in fact adjusted EPS figures quoted by brokers (ie excluding share based payments etc) rather than normalised using their criteria for that. It can sometimes be misleading therefore to compare the statutory EPS given in final results with the Stocko forecasts which are the adjusted figures because you are not comparing like with like. I'm not sure whether this is the case with Clipper Logistic or not but I have found in the past that something which looks on the face of it to be a profit miss is not when you compare EPS on a like with like basis.
Profit warning from Ibstock (LON:IBST), which at least they quantify:
"As a result Ibstock now expects that adjusted EBITDA for the year ended 31 December 2018 will be in the range of £121m to £125m with reported EBITDA in the range £130m to £134m."
Will have new factory coming on stream next year and demand apparently robust, so is this a "good" profit warning that provides a lower entry point?
RTC (LON:RTC) looks to have good interims, with revenue £71.1m+17%, pre-tax profit £0.77m+31%, eps 4.38+22%, results would have been better without delays in the Ganymede division. Current PER seems to be around 7, stockrank is let down by terrible momentum.
Connect (LON:CNCT) has a new CEO who seems to have some of the right experience in realising value. Starts Sept 1st so there may be even more kitchen-sinking to come.
We have just published the final (7th of 7) in the AI series: Hampleton Partners: “Tech M&A in AI – Hype, Hope, Winners and Losers”
https://www.piworld.co.uk/2018/07/30/newgate-redleaf-ai-conf-hampleton-partners-tech-ma-in-ai-hype-hope-winners-and-losers/
Given by Jonathan Simnett, Director, Hampleton Partners who is an eloquent speaker, and well placed to indicate the conditions for M&A, and why it will be the most important element for investors to consider. One comment I thought very interesting: 'M&A is the new R&D'. It's well worth watching.
Also, here's a link to all 7 presentations we published over the last week. We thought this AI even was an interesting subject, and chose to film so everyone could benefit. Do share / like / comment. If there's enough interest we'll continue to record these sort of events.
https://www.piworld.co.uk/category/capital-markets-seminars/newgate-redleaf-ai-conference/
My morning smallcap tweet: London calling, London falling.
Premier Global Infrastructure Trust (LON:PGIT), Luceco (LON:LUCE), Foxtons (LON:FOXT)
Premier Global Infrastructure Trust (PGIT) The grandly named £23m microcap reports H1 total return -7.2%. Blames portfolio being on the wrong side of macro trends. "Neither the Board nor the Managers are satisfied with the lacklustre performance of the portfolio over the past 18 months...The underlying performance of the Company’s investments remains very encouraging, with strong earnings growth...While the macro environment remains challenging for global trade, interest rates and currencies in the short term, your Board remains confident in the prospects for the long term..."
Luceco (LUCE) H1 trading. H1 UK retail sales almost 20% down but overseas growth remained strong. Blames 'previously highlighted' retailer destocking and lacklustre consumer confidence. Guides close to break-even adjusted operating profit in H1. Q3 retail order book is over 30% higher than Q2, reflecting an end to destocking in its UK retail business. Expects year-on-year adjusted operating profit growth in H2.
Foxtons Group (FOXT) H1 rev down 9%. EPS -1.1p (1.2p). Div passed 'in line with our policy'. "As expected the weak sales market impacted our performance in the first half of 2018. After a slow start to the year, performance in our lettings business improved throughout the period delivering another consistent result...will continue to invest in our proposition to enable us to maintain our differentiation in the minds of buyers, sellers, landlords and tenants." I'm short.
Half year results out this morning for XP Power (LON:XPP) some of the key points for me:
- revenue up over 10%
- order book exceeds revenue year to date and ahead of this time last year
- gross margin is slightly down but net margin up
- supply shortages have been a challenge but overcome with good management of safety stock. Unsure how long this will continue but has been an affect on margin
- new Vietnamese factory will be in production later this year
- 2 notable acquisitions in earlier 2018 will now have a noticeable affect for future business but has also meant a rise in net debt
- sterling headwinds but these have still been overcome by good trading results
- dividend up 6% year to date
I continue to hold.
One for the album from Hon Hai Precision Industry Co (LON:HHPD) :
https://www.investegate.co.uk/hon-hai-prec-ind-co--hhpd-/rns/explain-media-reporting/201807300728251235W/
A classic indeed from Hon Hai Precision Industry Co (LON:HHPD). They are a major Apple supplier so my first thought is that someone is trying to push the Apple share price down ahead of their quarterly results announcement this week.