Small Cap Value Report (Mon 31 July 2023) - MSLH, DUKE, SCE, QTX, FLO, VLG

Good morning! It's Graham and Roland here with today's report.
It looks like another busy day today, so please feel free to share your thoughts and views in the comments. We'll do our best to cover as much as possible, but probably won't be able to cover everything.
Today's report is now finished (11am).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions
on them as possible candidates for further research if they interest
you. Our opinions will sometimes turn out to be right, and sometimes
wrong, because it's anybody's guess what direction market sentiment will
take & nobody can predict the future with certainty. We are
analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or
serious problems, so anyone looking at the share needs to be aware of
the high risk.
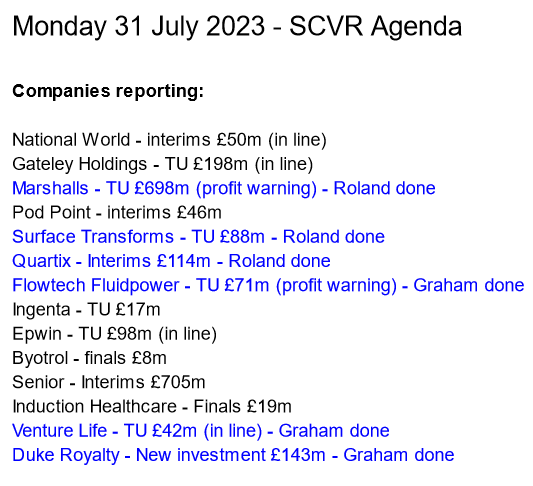
Summaries of main sections below:
Marshalls (LON:MSLH) - down 10% to 248p (£630m) - Trading Update (profit warning) - Roland - AMBER
Another profit warning from this building products supplier, which is suffering from the twin impact of lower sales volumes and lower utilisation of its manufacturing facilities. Debt levels have become a priority for the board. I think it makes sense to stay on the sidelines for now.
Duke Royalty (LON:DUKE) - up 1% to 34.6p (£144.5m) - New Royalty Agreement - Graham - GREEN
Duke announces a medium-sized (£9m) investment in a Texas-based company. I discuss various aspects of the deal, which is structured on similar terms to Duke’s other investments. It’s a good step forward in diversifying Duke’s portfolio, using their new credit facility.
Surface Transforms (LON:SCE) - unch at 36p (£88m) - Trading update - Roland - AMBER/RED
This high-performance brake disc manufacturer is making progress ramping up production and expects a big step-up in revenue in H2. However, a loss is forecast for this year and cash burn so far suggests to me that another cash call may still be needed.
Flowtech Fluidpower (LON:FLO) - down 18% to 95p (£58m) - Trading update (profit warning) - Graham - AMBER
I find it hard to get excited about investing in this one, despite the lower share price, as the company struggles to get back into growth and to restore profit margins. A new CEO offers hope of strategic improvements but I personally wouldn’t be in any rush to buy in here.
Quartix Technologies (LON:QTX) - up 4% to 244p (£118m) - H1 results - Roland - AMBER/GREEN
I’m encouraged by evidence of new subscription growth at this fleet telematics business. However, continued price erosion and elevated attrition make me wonder how strong the group’s competitive advantages are.
Venture Life (LON:VLG) - up 4% to 34.5p (£44m) - Trading statement (in line) - Graham - AMBER
Venture Life are “cautiously optimistic” they will hit forecasts this year, although it will depend on the seasonally stronger H2 period. I am cautious when it comes to my interpretation of the company’s EBITDA and cash flow claims. Cheap, possibly for good reasons.
Graham's section
Duke Royalty (LON:DUKE)
Share price: 34.6p (+1%)
Market cap: £144.5m
I’ve written about many aspects of this stock recently: both in early July and in June, and I won’t repeat all of those points today.
The big-picture summary is that I think Duke’s track record now means that they are worth a second look, especially below book value (last seen at £164m). Some points of caution are that the company’s investment portfolio is still not as diversified as it ultimately should be, and more fundraisings will be needed to get it there.
Today, Duke has announced an $11.5m (£9m) investment in a Texas-based company (“Glasshouse”) that was founded in 2002. It produces luxury custom glass for the residential and commercial markets.
One of the original selling points of Duke was that they brought a financing method popular in North America - the royalty that adjusts with revenues - to a European market where it is rarely used. But Duke still likes to invest in the US/Canada from time to time.
Today’s deal enables a management buyout at Glasshouse, putting equity control in the hands of the son of the company’s founder. Duke will also own 9.9% of the company.
Graham’s view
This has the usual positive features of an investment by Duke: there is no change in day-to-day management, who will be highly incentivised through equity ownership.
I don’t comment on every deal announced by Duke, but this one is a decent size (£9m) and will push up Duke’s net debt (which I recently estimated to be c. £40m). The newly-acquired business might be quite cyclical, being tied to real estate spending, but should still boost Duke’s overall diversification.
I’m going to remain positive on Duke. However, given the various risks I’ve outlined previously, my stance is going to be highly price-sensitive: between 40p and 45p per share, I’m likely to switch back to neutral.
The normal pre-Covid price of these shares was about 40-45p:
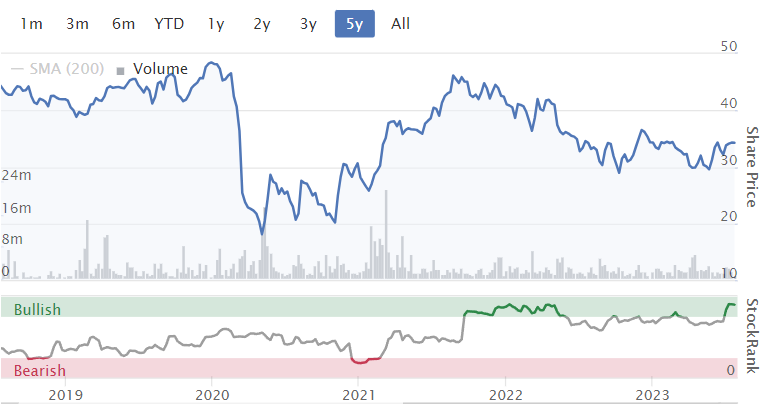
Duke and its portfolio got through Covid surprisingly well, with hardly any mishaps. Therefore, even with interest rates being much higher now, I think these shares may be slightly too cheap at this level:

Flowtech Fluidpower (LON:FLO)
Share price: 95p (-18%)
Market cap: £58m
I’ve not covered this one since last August, when I thought it was fairly priced at 121p (market cap £74m).
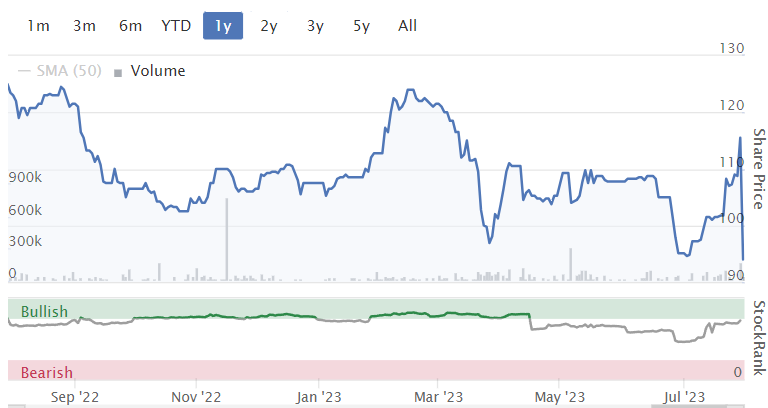
Share price performance has been mixed since then, culminating in today’s H1 profit warning:
Last year, I noted that “Primary Fluid Power” was performing much better than the larger (by revenue)“Flowtech” part of the business. That’s still true today:
Overall Group revenue has grown by 2.6% in the period with a mixed performance between the divisions. The Solutions and Services divisions have continued to operate well, showing strong growth, however, the performance of the Flowtech division has been disappointing with a decline in revenue of 5.7%. Given the lower gross margins in the Solutions and Services divisions and the underperformance of the Flowtech division, Group EBITDA in HY1 2023 is behind Board expectations.
With inflation running hot over the past year, overall revenue growth of 2.6% means a decline in real revenue. Combine that with lower margins and it’s really bad news.
Net debt is £15.6m, down by £4m over the past year. I previously thought that headroom on the company’s debt facility looked uncomfortably low; headroom is currently £9m with a further reduction in net debt expected in H2.
Comment by new CEO Mike England:
In the Flowtech division, specific actions are in flight to address commercial and operational shortfalls adversely impacting performance, some of which require targeted new capital investment and some to address legacy issues; we intend to comment more on this at the time of the interim results... The Board now expects the out-turn for FY23 to be significantly behind previous expectations.
Estimates: according to the company, it was previously forecast to generate PBT of £8.8m on revenues of £119.4m this year.
A note issued by Liberum today suggests PBT of only £5m on revenues of £115.2m this year, with a slower reduction in net debt as a result. They are still positive on 2024, looking for improvements to performance coming from the new CEO.
Graham’s view
I am reluctant to give these shares the thumbs down, as the company performed quite well in the years leading up to Covid. That said, ROCE never made it to double-digit territory as far as I know. The company doesn’t have a great deal of owned IP and is perhaps best thought of as an industrial distributor, so it suffers from a) volatile demand; and b) unimpressive profit margins.
Perhaps this is priced in now, at 12x this year’s PBT estimate and 6.5x next year’s PBT estimate? Although it’s more expensive than that when you factor in the debt.
Once again, I view this one as fully priced at current levels, so I’m staying neutral.
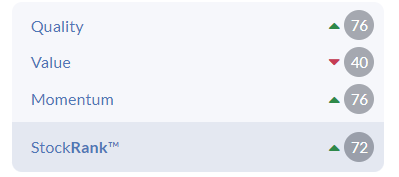
I’m in good company as the StockRanks also see limited value on offer here:
Venture Life (LON:VLG)
Share price: 34.5p (+4%)
Market cap: £44m
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the international self-care market, announces a trading update for the six months ended 30 June 2023…
Some key points from this H1 update, which is “cautiously optimistic” that results will be in line with expectations:
Revenue up 10.4% on a “pro forma” basis, i.e. if an acquired company had been owned during the prior period.
Excluding the newly acquired company entirely, revenue is up 11.4%.
Total revenues up 24% to £23.5m
Order book +30% since the end of the previous year, in line with expectations.
VLG tells us that cash generated from operating activities is up 158% to £4.6m, but I would treat that information very carefully as it only relates to a six-month period. Certain elements of operating cash flow have a tendency to reverse direction every few months. Also, the company capitalises some spending, so that spending goes to another part of the cash flow statement rather than to operating activities.
Going back to December 2022, net debt then was £16.6m (excluding leases). VLG tells us today that net debt reduced by £1.2m in H1, and the leverage multiple (net debt/adjusted EBITDA) reduced from 1.6x to 1.4x.
1.4x would normally be considered a modest leverage multiple, but again I would treat this cautiously as the difference between adjusted EBITDA and real profitability may be significant. Last year, VLT reported adj. EBITDA of £9m but then adjusted operating profit was only £3.5m (and actual PBT was only £0.7m).
Outlook is cautiously optimistic, with a second half weighting which the company says has been seen historically.
CEO comment:
The acquisitions we made in 2021 & 2022 are now fully integrated and delivering good organic growth, and we will be launching some great newly developed products in the second half of the year and increasing our distribution points in the UK, which will both contribute to the expected stronger revenues in H2… we expect this strong cash generation to continue through the second half, further reducing our net leverage.
Graham’s view
I have to reiterate what I said in April. I’m not convinced that VLG’s brands have a great deal of pricing power (feel free to disagree, that is just my perception), and so I would be reluctant to pay a very high earnings multiple for these shares.
The company structure is complicated by selling a broad range of products in different product areas, making it appear to lack focus. Additionally, it needs to manage that debt load and its historical financial results are uninspiring:

These shares may be “cheap”, but I am neutral on them for these reasons.
Roland's section
Marshalls (LON:MSLH)
Share price: 276p (pre-market)
Market cap: £698m
Unfortunately – but perhaps not surprisingly – today’s trading update from this building products supplier is a profit warning.
“[the company] expects to deliver a result for the full year that is lower than its previous expectations.”
Shares in this FTSE 250 firm have fallen by 65% over the last two years, highlighting the cyclicality of this business, which now falls into our small-cap coverage universe.

Profit warning/outlook: Broker forecasts for this business have been drifting steadily lower and Marshalls has already lowered expectations once this year, in May.

In today’s statement, the company says trading is no longer expected to improve in H2, due to a combination of macro-economic factors and the financial impact of scaling back production.
Marshalls has cut production to reflect lower demand, in order to manage its working capital and prevent a buildup of unsold stock. This is quite logical, but it’s having an adverse effect on operating efficiency. In effect, margins are down because the company’s fixed cost base is no longer being fully utilised.
We often talk about operating leverage here – improved profitability on higher volumes. But it's always worth remembering that operating leverage can also work in reverse, as seems to be happening here.
"Taking these factors together, and in the absence of a recovery in demand in the Group's end markets, the Board believes that the result in the second half will be markedly weaker than the first half, and consequently expects to deliver a result for the full year that is lower than its previous expectations."
Unfortunately, the company hasn’t provided any indication of its new profit expectations for the year, so we’re left guessing.
Trading update: revenue for the half year is expected to be £354m, 2% higher than the £348m reported for the same period last year.
However, adjusted pre-tax profit is expected to fall to £33m (£45m), presumably because of the double whammy of lower volumes and lower margins due to production cutbacks.
The company says that its Landscaping Products division has seen H1 revenue fall by 20% to £174m due to its exposure to new build housing.
The Building Products division, which supplies bricks, masonry and mortars, has been more resilient, with H1 revenue down by 9% to £87m.
The Marley Roofing Products business, which was acquired in early 2022 – perhaps not the best timing – is seeing “mixed demand”. Half-year revenue fell by 7% to £93m.
Management are taking steps to cut costs, including closing one factory and making a further c.250 people redundant. However, they say the company still has sufficient capacity to meet “materially higher demand than that being experienced in 2023”.
Balance sheet: the company says net bank debt was £185m at the end of June, broadly in line with the £191m reported at the end of 2022.
The board’s “ongoing priority” is to reduce leverage using free cash flow. This suggests to me that there’s a chance the dividend could be cut further than already expected:
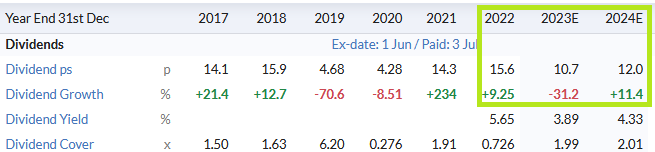
Depending on the shortfall in this year’s profits, I estimate that Marshall’s leverage could now be c.2x EBITDA. That’s not necessarily critical, but it’s unfortunate timing.
Roland’s view
I don’t think this is a bad business and I suspect the share price is coming down to a level that might represent value, on a through-cycle view.
However, given Marshall’s relatively high leverage and falling profit expectations, I would be inclined to stay on the sidelines until the balance sheet improves, or the trading outlook stabilises.
For these reasons, I’m going to go AMBER on this one.
Surface Transforms (LON:SCE)
Share price: 36p (unch)
Market cap: £88m
“the Board maintains its 2023 revenue expectations.”
Just a quick comment on this ceramic brake disc manufacturer. I last covered Surface Transforms at the end of June, when I speculated that delays ramping up production could mean some risk of further cash shortages.
Today’s pre-close update provides some more detail on the situation.
Trading/revenue: Output rates have continued to improve, with half-year production volumes 80% higher than the same period last year.
A further £3.4m will be spent on installing additional production capacity over the remainder of this year.
The company confirms half-year revenue of £3.3m, compared to £2.9m for the same period in 2022.
Customer arrears are said to have reduced since June’s update. As a result, full-year revenue expectations are unchanged.
Revenue of £16.1m is forecast for the current year, which implies that the business will generate H2 revenue of £12.8m. If so, that would be a sizeable step up (and a decent achievement) after a difficult H1.
However, broker finnCap no longer expects the business to report a profit this year, due to the impact of the additional costs suffered so far. In a new note available on Research Tree this morning, finnCap has cut its profit forecasts and now expects an adjusted loss per share of 0.7p for 2023.
This appears to be a reduction on this consensus figures shown in Stockopedia ahead of today’s update:
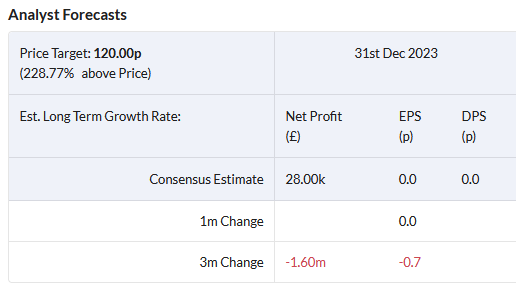
Cash: revenue expectations for 2023 and 2024 are unchanged, but the production problems suffered this year “have inevitably had cost and cash implications”.
The company says that cash has been managed carefully, but gross cash at the end of 2023 may now be up to £1m lower than previously expected.
Gross cash on 30 June 2023 was £4.5m, down from £14.9m at the end of 2022, so the company burned through £10.4m of cash during the first six months of this year.
finnCap’s updated forecast guides for gross cash of £2.5m at the end of this year, with net cash falling to just £0.4m. However, analysts appear to expect the business to become cash-positive next year, with net cash rising to £2.1m in FY24.
Roland’s view
Surface Transforms’ share price has drifted steadily lower over the last year, perhaps reflecting the risk that further fundraising will be needed to get the company to a point where it’s financially self-sufficient.
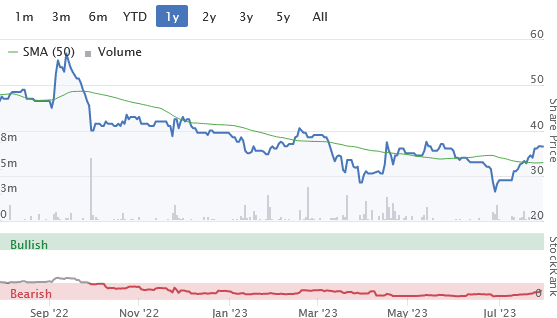
Operational progress seems encouraging to me, but today’s update strengthens my previous concern that cash might still run short.
I’m going to go AMBER/RED on this. While I believe that this long-running growth story is finally starting to come good, I’m not convinced that shareholders will escape another cash call.
Quartix Technologies (LON:QTX)
Share price: 244p (+4% at 09.30)
Market cap: £188m
“This promising momentum and product innovation positions Quartix optimistically for the rest of the year."
I’ve always had a positive impression of this AIM-listed telematics specialist, but it’s looked expensive in the past. Profits have also flatlined for several years now.
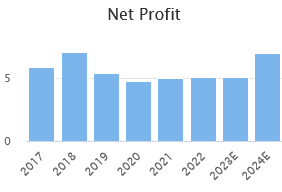
However, the shares have sold off sharply over the last couple of years and recent newsflow has seemed promising to me. I’m interested to see if today’s interim results show any fresh momentum.

Financial highlights: the headline numbers from today’s refreshingly straightforward results do not seem to suggest a powerful increase in momentum.
Revenue rose by 10% to £14.6m, with annualised recurring revenue rising by 8% to £28m. This compares to reported revenue of £27.5m last year.
However, pre-tax profit fell by 7% to £2.4m, while earnings per share for the half year fell by 10.2% to 4.16p. The interim dividend was maintained at 1.5p per share.
Free cash flow was 26% lower, at £1.4m, but this was due to a higher tax payment relating to a change of accounting policy. This resulted in net cash falling from £3.9m to £3.2m. This sounds like a one-off to me, so I don’t think it’s a concern. Cash conversion has historically been very good in this business:
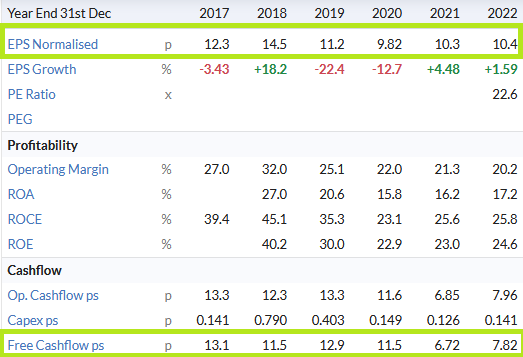
Trading summary: Quartix has now largely wound down its insurance business
and is focused on the fleet sector.
The company’s KPI table provides us with some clues that may help explain why profits fell in H1. I think it’s encouraging that some of these metrics are disclosed so prominently, even when they’re not all positive:
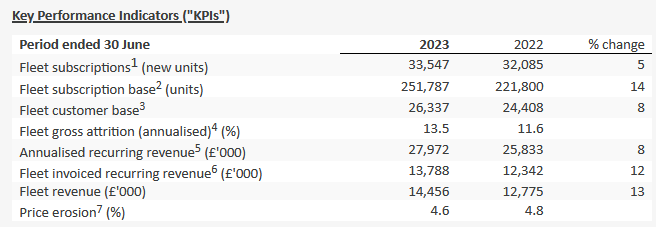
The increase in new subscriptions and the total number of units subscribed seems positive, to me, but I can see a couple of negatives:
Fleet gross attrition: if I’ve understood this correctly, this represents the proportion of unit subscriptions discontinued during the year, as a proportion of the mean subscriber base.
Chief executive Richard Lilwall says that increased attrition was the result of “increased liquidations and customers downsizing their fleets”. I would expect telematics to be a fairly sticky service, but I can see that in the SME space, in particular, there will be some natural attrition each year.
Are there any sector experts out there who know what kind of attrition figures are normal? Quartix’s H1 figure of 13.5% seems slightly high to me, but I may be mistaken.
Price erosion: this represents customers renewing their subscription at lower prices than the prior year. An average reduction of nearly 5% per year in an inflationary environment suggests to me that Quartix may have limited pricing power, or may be operating in an increasingly competitive market.
We might also question what this continued price erosion tells us about the value created by the firm’s products for fleet operators – or alternatively, how differentiated Quartix products are when compared to rival alternatives.
Strategy update: Quartix is continuing to focus its US spending more carefully and is now investing more heavily in European countries, which are said to offer “stronger return on investment”.
Two new analytical software features have been introduced over the last year, EVolve and Quartix Check. These are an EV fleet planning tool and a paperless vehicle check and incident report app, respectively.
They seem useful, but not especially groundbreaking, to me.
Outlook: it sounds like the newish chief executive is continuing to place new importance on strong commercial execution:
"sales execution excellent continues to be a key focus point for senior management”
Management say they're mindful of the uncertain economic climate, but confident in the opportunities to grow revenue in the UK and Europe.
As a result, the board expects “an accelerated financial performance for the remainder of 2023” and is confident in achieving market expectations.
To me, this sounds like we should see an second-half weighting to profits, if all goes to plan. This will be needed for the company to meet expectations.
Roland’s view
Today’s half-year results show an operating margin of 16.5% and a trailing 12-month return capital employed of 26.5%. Both are strong figures that suggest to me this business may have some degree of competitive advantage.
Top-line revenue growth of 10% is encouraging, but seems fairly modest to me given the level of inflation seen over the last 12 months. Price attrition remains a concern too, if Quartix cannot scale up quickly enough to offset this.
I’d like to see more evidence that this is converting into profit growth, but I’m encouraged by the quality and profitability of the business. I also like the strong cash conversion and net cash balance sheet.
2023 consensus forecasts on Stockopedia show earnings of 10.4p per share, which would be slightly below the 10.9p reported last year.
However, now that the exit from the insurance business has largely dropped out of the figures, I’m hopeful that the renewed commercial focus on fleet subscriptions in the UK and Europe will yield a return to growth.
Broker forecasts suggest the company will use some of its cash balance to bump up the dividend this year, giving a useful forecast yield of 3.8%. This seems to imply that profits are expected to be sustainably higher, going forward.
I would suggest the shares are probably fairly priced at the moment, but if the company delivers on consensus forecasts over the next 18 months, then I think Quartix could have decent upside.

I remain positive on this business, so I’m going to go Amber/Green on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Pleasing Operational update from Gemfields (LON:GEM) this morning, with details from recent auctions, a nice detailed breakdown on their website showing progress. Net cash risen to $61.8m and net debt 29m. net cash position excludes the outstanding balance of auction receivables of USD 63.9 million as at 30 June 2023. Thought I’d mention as this was highlighted here a couple of times. I hold.
Happy holder as well , net cash will be about 50% of market cap and after expecting a 20% dividend (3-3.5p) which will be maintained for at least the next three years. Need to start the construction though of a second wash mine at the Montepuez ruby mine in order to maintain/increase previous production levels.
WANdisco (LON:WAND) is close to tripling in price in just a week. Well done Paul. Makes me realise that I was focusing too much on oil and gas shares, which served me well last year, but very badly so far this year. One of which, Jadestone Energy (LON:JSE) was a total disaster - greed got the better of me there. I will be paying much more attention to your posts in the future as you seem to have a knack of finding the multi-baggers.
Hi Guybrush,
Thanks re WANdisco (LON:WAND) - I see it as more of a lucky escape, than a triumph! Although overall it was profitable for me, which is not something you expect when a company reveals that it's entire order book was fraudulent!
Quite an interesting one, where with it being fully refinanced before being unsuspended, aggressively averaging down did actually make sense, despite breaking all the conventional rules of throwing good money after bad.
as you seem to have a knack of finding the multi-baggers.
One swallow definitely does not a summer make!!!
Regards, Paul.
Are there any swallows this summer? Maybe they knew it was going to be a poor summer in the UK?
I take a more optimistic view on Surface Transforms (LON:SCE) cash situation, hence why I hold.
As long as they can sustain good production for a few months, and today's trading update indicates they're on course, they should be able to get bank financing to bridge them over. Next year's forecast is for good profits - and FCF.
With a combination of proven sustained reliable production over months, as well as documentary proof of their strong order book, I don't see why banks won't see this as a safe loan/RCF type situation. So I really don't see the need to fundraise.
And if they need to, they could always just wait till they announce firm details of their next OEM to transition to firm delivery schedules. That would cause a nice SP spike and therefore ability to raise funds at a much higher level than the current SP.
(I hold in the Boon Fund)
Surface Transforms (LON:SCE)
How much did you pay for those rose tinted glasses?
Surface Transforms (LON:SCE) I see that four directors have made purchases recently.
I like my rose tinted glasses :) they are specially tinted only when looking at the SCE ticker
National World (LON:NWOR) Good solid figures from this company. £22 m of cash, low p/e, no pension fund to worry about. Confirms full year forecasts despite difficult advertising conditions. Some lower costs to come eg news print.
National World
Yes on paper good numbers but unfortunately self serving management led by modern day Dick Turpin David Montgomery mean the only people getting rich out of this is the management .
One to avoid at all costs .
Disgraceful self enrichment “special vehicle of David Montgomery”
Makes my blood boil when this goes on right under our noses and it is pretty much a stain on the way the stock market can be manipulated by a rotten management team full of their own self worth over their responsibility and requirement to work for the good of shareholders .
If you haven’t noticed so far in this post I am not a fan of the management though I like the brands .
National World (LON:NWOR) What is it that David Montgomery or Vijay Vighella or even Mark Hollinshead has done that you so disapprove of planetx ? I think they play with a pretty straight bat.
Capital (LON:CAPD) Took the painful decision to stop loss on Capital (LON:CAPD) this morning. I can find no reason that the share price is tanking and the most recent trading reports were positive. However, the SP broke down below key support levels this morning so I have to accept that something is wrong or there is a large seller out there.
I still like what the company is doing but won’t go back in until I can see a bottom forming on the SP.
I dont think that they have operations in Niger, but I think they do in Mali and Nigeria - it may be because of percieved instability in the area. I hold.
Capital (LON:CAPD) fall seems to have stared with the recent placing, when some of the directors sold part of their positions. That often does hit sentiment. Interestingly, I was looking to buy back in this morning as noticed the recent fall, but the sprea looked too wide, so decided to stay on sidelines for now.
Re Capital (LON:CAPD) I did the same this morning, which probably means the bottom will be in today...
Isn’t that what e we all worry about when selling at a loss! It’s how people get trapped with huge losses.
Capital (LON:CAPD)
Some might be being spooked by the suspension of Leo Lithium (ASX:LLL) in which they have a large investment and drilling operation.
https://cdn-api.markitdigital....
Capital (LON:CAPD) I sold today too but, having held since 3/21, still managed to make some profit. Big director sales in June may still be unwinding but the prognosis for this area of Africa is worrying.
Morning all.... I have caved in slightly! and made a few adjustments around the edges...not a wholesale move but for instance I was fairly happy in Gen Accident Prefs as a substitute for bonds but Im now worried the bond market is going to get frustrated by a lack of recession and inflation that might prove more stubborn in the US. So an undated pref isn't cash like enough for me....and then round the edges some loosely held defensive shares, in attempt to increase cash levels. My ambition is to have 10-20% cash or near cash ... so bonds with close redemption dates, money market funds etc. This then acts as a buffer if ( mainly US equities) cause a bit of a market wobble.
As I have said before, it's not always easy esp when I haven't really changed my view so I just take the top off most positions... and then see how we go. I think the Julian Brigden interview on Fwd guidance most concerned me re Fed policy, current market levels and the stand off between bonds and equities. I did take the top off my Yellow Cake (LON:YCA) which is potentially still too large a position but then I read this morning's statement, and felt more inclined to buy than sell. That's the current dilemma and the age old problem, you have to cut things when you like them not afterwards....and accept that risk management may reduce return. Anyway, Im sure like many of you, not all my positions are that easy to cut.... so having a bit more cash into Q4 feels appropriate. I have also cut my gold etf....which can behave a bit like an undated bond at times... Im not bearish Gold, but am hopeful Sterling can strengthen so just not sure Gold will continue to do the job.
You should take all this with a pinch of salt, I lean more towards preserving capital and retaining a few large positions. It's not a strategy for everyone that's for sure. In the interests of collegiate debate I post my thoughts.
Good luck all with another busy week.
I've started to cut back winning positions and topslicing with gritted teeth - got to take some profits. But I've been looking at opening small positions in some really undervalued companies (Reach (LON:RCH) & Vistry (LON:VTY) ) for example, hoping to ride out the cyclical nature of the business.
That said, my personal situation has changed and I accepted an unexpected offer on a foreign property I owned, so now am cash heavy and I am spending my time trying to get some high yielding risk free savings accounts, whilst considering where to deploy these next.
I have decided to wait to see where the economy is around xmas before committing to any major purchases (car/stocks/property) as I'm really not sure how much of a depression there will be - I'm hoping to pick up some bargains, but who knows.
Maybe a good strategy is to slowly dribble money into the markets? Then you don't have to worry about timing.
Jim
More profit warnings! I have manged to dodge several notably Portmeirion (LON:PMP) and Headlam (LON:HEAD) , but not this morning Flowtech Fluidpower (LON:FLO) stlii I am in good company Richard Staveley, Stuart Widdowson and Judith Mackenzie all have substantial holdings in their respective investment trusts. Just goes to show that even some of the best investors get it wrong from time to time.
Liberum have just issued a broker note. So will take a look and see what they say, but suspect that I will park my holding and wait to see what the new CEO, Mike England does. He was the Chief Operating Officer as RS Group, formerly Electrocomponents so he has an ideal background in distribution. Hopefully he will get the train back on the rails, but patience is required more than ever now, given the current economic malaise. Hey ho!
Hopefully some comment from Graham, Roland or Paul later.
Hi Jonno, thanks for flagging up Flowtech Fluidpower (LON:FLO) . I'm a fan of RS Group, so I agree that the new CEO appointment seems encouraging.
I'll aim to take a look at Flowtech next.
Roland
Cheers Roland. I look forward to hearing your views.
Thanks Jonno - Graham beat me to it as it happened, his comments are now up!
Odyssean Investment Trust (LON:OIT) does seem to be high risk, judging by some of the top holdings.
Hi Jonno
I watch all these companies too.
I note Flowtech Fluidpower (LON:FLO) is a large holding for Rockwood, Downing and some other investment trusts. Strikes me that it is very difficult for them to exit these large positions, even if they wanted to. So that these investment trusts have large positions does not necessarily mean they are good investments. All 3 investment managers will, however be pushing very hard to turn Flowtech Fluidpower (LON:FLO) around. They have been trying for quite some time now without success. Maybe they will look for a way out in the shape of a sale of the company if things don't start to turn soonish?
Hi Michael
Point taken as to whether Flowtech Fluidpower (LON:FLO) will be a good investment, certainly not at present and previous management I would suggest have not be scintillating. Most companies are swimming against the tide at present given rising interest rates and general political incompetence.
The background of the new CEO, Mike England seems ideally suited to sorting out the challenges at Flowtech Fluidpower (LON:FLO) . I suspect the resignation of his predecessor was in part orchestrated by Messrs Mills et al given their considerable holding in the company. I also think that there is a half decent company in Flowtech, which with a competent CEO and helping hand, once interest rates plateau and hopefully begin to fall will start to emerge.
Christopher Mills and his colleagues at the Harwood stable are very savvy investors and as you infer they will be doing their level best to facilitate a turnaround at Flowtech Fluidpower (LON:FLO) . In the meantime I shall sit and watch.
All the best
The background of the new CEO, Mike England seems ideally suited to sorting out the challenges at Flowtech Fluidpower (LON:FLO)
RS (LON:RS1) used to be one of my very largest clients. We built their online sales channel - up to100 consultants at any one time. A really good company and one I bought into just recently. Hopefully Mike England can bring his learnings to bear on FLO.
Cheers BnB. I know of RS (LON:RS1) but other than it is an international distributor of electrical components, which I suspect is a bit simplistic, I don't know it, if you see what I mean.
Mike England as you will, I suspect be aware, was the Chief Operating Officer at RS (LON:RS1) but decided to accept the CEO position at Flowtech Fluidpower (LON:FLO) . It is rumoured that he was overlooked for the CEO job at RS (LON:RS1) and decided to take his expertise elsewhere. I don't know how true this is, but any insights (views) you have into Mr England and his skill set would be appreciated.
All the best
I’m afraid I haven’t got insights to offer regarding Mike England himself. But I’m an extremely biased fan of the digital transformation wrought at his employer RS when he was UK country manager. Nevertheless you can see the change in the company’s revenue trajectory from 2017 on, as the project came to life.
I’d also highlight that RS (LON:RS1) shares are as cheap as I’ve ever seen them right now. Given that much of their revenues come from the USA, and less than a quarter from the UK, the firm is well insulated from a UK-specific downtown. As I mentioned earlier, I bought in recently, and I think they offer great value at these levels.
Epwin (LON:EPWN)
Nice simple clear update here today , no signs or any worsening of expectations.
The Board remains confident of the Group delivering underlying operating
profit for the full year in line with market consensus expectations*.
*Company collated analyst consensus for FY23 underlying operating profit is
£24.0m
Per stocky pe is under 7 here now. This company imho does seem to have eeked out its owne niche ref what it sells. The company does carry debt but its at very manageable levels (approx 1 years net profit) and debt should reduce nicely if they are not invvesting in new outlets/acquisitions. Perfectly happy to keep holding here despite the pitiful shareprice performance.
Thanks rmillaree for the Epwin (LON:EPWN) heads-up. I held some long time ago and only sold as I need the cash at the time. Sounds like one for me to revisit with some updated research.
Cheers
Mark
Don't you mean Debt (NetDebt, 107m(22)) is about 10 times (years worth of) Net Profit (8.4m(22),13.8m(23e))?
Epwin (LON:EPWN)
Don't you mean Debt is about 10 times Net Profit
Most definately not no !!!
proper net debt is approx 1 * net profits - the vast majority of the total included on stocky calculated figures/year end reports is simply the future rental payments that are included due to accounting standards rules saying we need to (£87 mill per last annual report). In any proper world this aint any sort of debt so should be excluded.
Thankfully the company concentrate on the proper debt in their updates - company confirmed today that the "proper" net debt was down to £16.1 mill at 30/6/2023.
Per the company today
The Group retains a strong balance sheet with covenant net debt at 30 June2023 remaining low at £16.1 million (31 December 2022: £17.9 million), which is approximately 0.6x adjusted EBITDA. This provides the Group with over £60 million of headroom on its facilities to support its strategic objectives, including value enhancing acquisitions.
Note epwin along with some of the other "better" listed companies provide broker forecasts sumary on their own website. These arent always up to date (last updated may) but are worth monitoring to see how trend performs over time. figures inlude 2025 not showing up on stockopedia at present.
https://investors.epwin.co.uk/...
I see Marshalls (LON:MSLH) has issued a profit warning. It's a share that I've dabbled with it once in the past. It's one of those companies that seem to coast along , not getting anywhere in particular, although you can make money out of it if you get your timing right. I doubt it's a share I'd bother with these days. Looking over its 20 year chart, it was around 239p back then, and looks to be heading back that way. Oh well.
Just looking at the numbers, analysts forecast a 2024 net profit of £60m. That looks way too punchy. Average net profit over the last 6 years was around £40m, so I presume that a more realistic estimate will be even lower than that. The RNS says that it has net debt of £185m at the end of June, which is an improvement to the figures shown in the latest Stockopedia report.
It will be interesting to see how the market reacts at the opening. "Not well", presumably.
I had a chuckle at their Outlook statement:
"The Board remains confident that the Group is well placed to deliver
profitable long-term growth when market conditions improve"
In other words, once it hits rock bottom, it will go up again. Not really sure that the company has delivered much in the way of long-term growth given how the share price has performed over the last 20 years.
Really enjoyed this weekends podcasts, especially the bit where Paul mentioned Hargreaves Lansdowne writing to him to tell him his current portfolio is too risky. His response, 'It's a good job they don't know what I did in my past!'
Delighted to hear you are visiting Norfolk. If you find yourself in Norwich you will receive a very warm welcome at Oriental Rugs of Norwich Ltd (I Hold!).
Enjoy your break, North Norfolk is absolutely beautiful!
And, on the subject of North Norfolk, I am heading there tomorrow to make preparations for my son’s wedding next Saturday. He’s fallen for a local lass and they are settling in Suffolk.
I live in Suffolk, there are worse places to live.
I live in Suffolk, there are worse places to live.
My son is born and bred in Yorkshire, so it’s a high bar! We’re set deep in the hills and moorland and dales, so it’s going to be a big change for him. Still, love finds a way!
A lot less rain down here. Which part of Suffolk is he moving to?
A lot less rain down here. Which part of Suffolk is he moving to?
His wife-very soon-to-be is a teacher in Bury St Edmonds.
Which part of Suffolk is he moving to?
He’s today completed on a small house in Fornham All Saints. I’m there now, waiting in the cafe for him to show me round in about half an hour. The village is lovely.
OK, near Bury, I'm the other side near the coast.
Easy to get to Cambridge and the A1. Can take me 90 mins to Bury.
We’ll be in Southwold tomorrow, sorting flowers for the wedding. Looking forward to seeing the town - and the beach huts!
I am born & bred in God's Own, and live in Suffolk. It is a most acceptable substitute. Though I do miss them hills!
I am born & bred in God's Own, and live in Suffolk. It is a most acceptable substitute. Though I do miss them hills!
It'll be nice to visit - for the contrast. But I wish the journey wasn't so flipping long. Our daughter lives works in London so it's just mum, dad (me, obvs) and grandma left in Yorkshire now.
I get those types of emails from Hargreaves Lansdown too, I don't think my shares are too risky. It may be due to the fact that the majority of the shares are small caps.
Not had that one, but they tell me I have too much in cash and shares outperform cash. I must move some of that away from HL.
Me too, its usually followed by an email suggesting I pay one of their experts for a portfolio review!
Hargreaves Lansdown sent me same risk warning I think they want us to invest in unit trusts so they make more from us
Haha, must be them wanting us to invest in their 'safe' investments :)
My morning smallcap tweet: Ferrying news across the Styx
Aptamer (LON:APTA) Marshalls (LON:MSLH) EQTEC (LON:EQT) Flowtech Fluidpower (LON:FLO) Harland & Wolff group (LON:HARL) Glantus Holdings (LON:GLAN) Aiq (LON:AIQ) Chrysalis Investments (LON:CHRY) Real Estate Investors (LON:RLE) Polarean Imaging (LON:POLX), Gateley (Holdings) (LON:GTLY), Venture Life (LON:VLG), Surface Transforms (LON:SCE), Ingenta (LON:ING), Epwin (LON:EPWN)
◄Aptamer (APTA)► £3.6m placing at 1p, a disgraceful 79% discount, to keep the lights on. SP was 95 a yr ago. Cost cuts. 4 directors resign. Ends Formal Sale process. [SP=4.56 Cap=3m]
◄Marshalls (MSLH)► warns FY-Dec below exp. Blames "sustained high levels of inflation, increasing interest rates and weak consumer confidence". [SP=276.2 Cap=699m]
◄EQTEC (EQT)► successful completion of steam-oxygen gasification tests for Biogaz Gardanne project. [SP=0.16 Cap=18m]
◄Flowtech Fluidpower (FLO)► warns FY-Dec significantly behind expectations of rev c.£119.4m and pretax c.£8.8m. Flowtech division H1 rev down 6%. "Specific actions are in flight to address commercial and operational shortfalls adversely impacting performance, some of which require targeted new capital investment and some to address legacy issues." [SP=117 Cap=71m]
◄Harland & Wolff (HARL)► get Notice to Proceed (= Letter of Intent) for the mid-life upgrade and dry docking of a large vessel worth £60-70m in early 2024. [SP=11.58 Cap=20m]
◄Glantus (GLAN)► guides H1-June rev ahead of mgmt exp. [SP=18.25 Cap=10m]
◄AIQ (AIQ)► extends convertible facility by 1 yr, to Jan 2025. [SP=10.48 Cap=8m]
◄Chrysalis Investments (CHRY)► June NAV 136.86p/sh, up 5.3% since Mar. [SP=74 Cap=440m]
◄Real Estate Investors (RLE)► trading update. Sounds OK. Snippet: "We have experienced slow occupier decision making since the year end, however, due to our healthy pipeline of lettings, and with our further scheduled sales, we anticipate improved contracted rental income, WAULT and occupancy." [SP=29.82 Cap=51m]
◄Polarean Imaging (POLX)► University of Missouri Health Care to begin clinical imaging with XENOVIEW. [SP=21.32 Cap=45m]. I hold.
In line: GTLY, VLG, SCE, ING, EPWN
Mr C
Thanks so much for these wonderful early morning summaries. They are so useful.
Unlike Glantus Holdings (LON:GLAN) who can say they are trading in H1ahead of management expectations - which on first read, I imagine is shorthand for ahead of broker expectations for the full year. But when at NOMAD and sole broker Shore Capital’s last note (30 June), they are no estimates for 2023 or 2024!!
I, too, would like to congratulate MrC for his excellent write-ups.
You guys have probably heard of him, but there's a Twitter account does really good one-line summaries:
https://twitter.com/andrewdc20...
How he manages to rip through so many RNSs each morning is beyond me.
Mr C
Thanks so much for these wonderful early morning summaries. They are so useful.
Unlike Glantus Holdings (LON:GLAN) who can say they are trading in H1ahead of management expectations - which on first read, I imagine is shorthand for ahead of broker expectations for the full year. But when at NOMAD and sole broker Shore Capital’s last note (30 June), they are no estimates for 2023 or 2024!!