Small Cap Value Report (Mon 5 Aug 2019) - DIA, BLV, EZH, RTC, PHO

Morning, it's Paul here for the whole week!
Dialight (LON:DIA)
Share price: 361p (down 7.4% today, at 10:29)
No. shares: 32.5m
Market cap: £117.3m
Dialight plc (LSE: DIA.L), the global leader in sustainable LED lighting for industrial applications, announces its half year results (unaudited) for the six months ended 30 June 2019.
I last looked at Dialight here on 2 July, when it put out a profit warning, and fell sharply.
As you can see from today's H1 financial highlights, underlying profitability has almost evaporated. On a statutory basis, it made a pre-tax loss of £2.1m (due to non-underlying expenses of £2.7m);
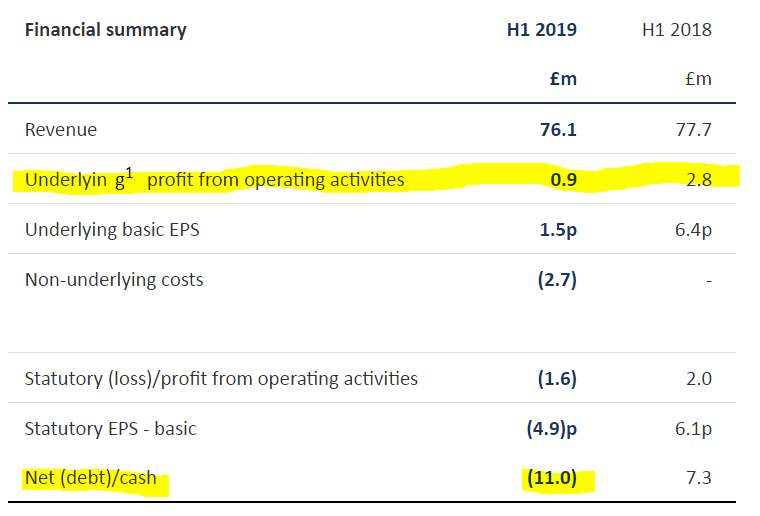
There seems to be an H2-weighting to profits, judging from last year's results.
Guidance - the last update on 2 July, told us that full year underlying profitability is expected to be £10-13m. Given that H1 has delivered only £0.9m, that leaves a lot of catching up to do in H2.
Today the company says;
Full year guidance for 2019
We expect some gross margin recovery in H2 2019 as we return to more normal levels of service. We continue to expect our capital expenditure for the second half of the year to be in the region of c£2m together with c£4m of capitalised development costs. The tax rate for the year is expected to be c26%, and we are expecting inventory levels to reduce by year end but it will take us to the end of Q1 2020 to fully unwind the excess inventory build up.
The Board's expectations for the year ending 31 December 2019 remain for underlying operating profit within the range of £10-13m, which is before incurring c£4m of non-underlying costs.
This assumes a pickup in orders and sales activity in H2, in part due to new product launches. As in previous years, Q4 is expected to be an especially important period of activity.
It's difficult to interpret these things, but it sounds a bit wobbly to me. Therefore my hunch is that there seems an above average risk of another profit warning to come in H2. Maybe. I don't know, it's difficult trying to predict the future.
Outlook comments - are split into two. Firstly, the CEO says;
We remain confident that the combination of the reputation of Dialight products as the best in the market, our improved operational performance, and the launch of our exciting new products will result in significant long-term growth in revenue and profit.
We are taking all appropriate actions to convert these to improved financial results as quickly as possible. Our full year outlook for 2019 remains unchanged."
There's some good stuff in that excerpt above. Although I do wonder, with both CEO and Chairman stepping down, whether I would want to rely on their comments or not - since they won't be held to account if the guidance is not achieved.
Another outlook section seems to me to introduce doubt about the turnaround;
Medium-term outlook
We have made considerable progress in transforming our operations and continue to work towards industry leading levels of service to our customers. The strong focus on product development lays the foundations to restore our market share and drive future growth. The exact timing of the recovery with our customers is difficult to predict.
Our market proposition remains compelling, with the sustainability benefits of reduced energy usage, lower carbon emissions, reduced maintenance and improved safety offering real value to our customers. We remain excited by the Group's prospects over the medium to long term and are confident of delivering future growth.
I'm not keen on the use of medium to long term. That implies things probably won't be so good in the short term!
Balance sheet - debt has increased sharply, but overall the balance sheet still looks strong.
Inventories are particularly high, at £50.0m, which is mentioned in the commentary above. I wonder if there might be write-downs in the pipeline for excess stock? Reducing inventories to reduce bank debt, looks a key issue to focus on in the full year results.
Chairman steps down - a separate announcement this morning indicates that Wayne Edmunds has stepped down, with immediate effect, from the Chairman role. An existing NED, David Blood, has become the new Chairman.
This is rather unnerving, as it seems to be a sudden change - has something gone wrong, or possibly a Board Room bust up? The new Chairman is also not independent, which is rather unusual;
The Board believes that David is well placed to do so given his knowledge of Dialight, its operations and people. David is co-founder and Senior Partner of Generation Investment Management, a 20.1% shareholder in Dialight, and is therefore not considered "independent" under the UK Corporate Governance Code. However, the Board continues to consider David independent in character and judgement.
I'm not quite sure what to make of this. On balance, personally I would rather have a Chairman with a 20% shareholding, who is properly motivated to make the company work, than a box-ticker with little to no shareholding. Other people might disagree, and prefer having a genuinely independent Chairman.
This comes on top of news on 2 July 2019, that the CEO also plans to step down, shortly after these interim results, to be temporarily replaced by the CFO, who became interim CEO. So there seems to be something of an exodus going on at senior Board level - clearly a worry. Will new management kitchen-sink the full year results, I wonder?
My opinion - there's only one place to file this - in the too difficult tray.
I'm worried that the existing forecasts might prove too challenging, given that H1 was barely above breakeven. Can it really recoup the shortfall in H2?
Both CEO and Chairman departing, doesn't exactly fill me with confidence that things are going well.
On the upside, most of its sales are in the USA. Therefore sterling weakness is a good thing for the share price. Given the takeover frenzy going on at the moment, could Dialight be another share which attracts a premium bid from its main market in the USA? Who knows, but it wouldn't surprise me if someone does swoop for it.
Overall, I'll probably give this one a miss.
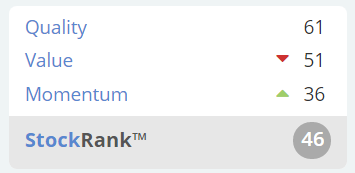
Stockopedia's computers are not madly impressed either;
Belvoir (LON:BLV)
Share price: 108.5p (down c.4% today, at 11:39)
No. shares: 34.9m
Market cap: £37.9m
Belvoir Group PLC (AIM:BLV), the UK's largest property franchise, is pleased to provide the following update ahead of publishing its interim results on 3 September 2019.
Interim results will cover the 6 months to 30 June 2019.
Checking the archive, I made a brief comment here on 16 May, when Belvoir reported a "robust" Q1, and expressed confidence in achieving market expectations for FY 12/2019.
It's more of the same today, the key bit saying;
... the Board is confident of meeting market expectations for the year ending December 2019.
That's exactly the same wording as was used in the last update in May.
Directorspeak today is upbeat - despite the sector challenges. The ban on tenant fees is mentioned, which was introduced in June 2019 - so won't have had much impact in H1. It is not mentioned what impact this is likely to have in H2. Although it must have been baked into the company's forecasts, as a known factor.
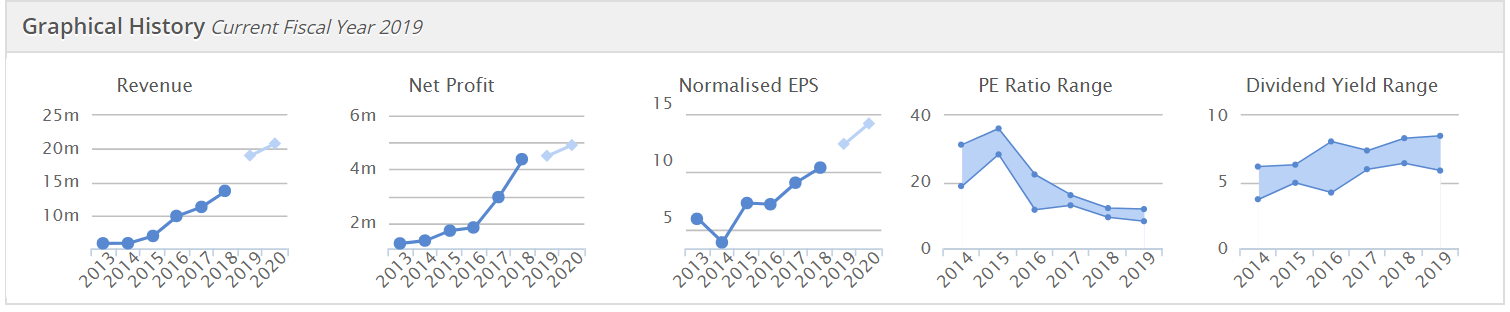
The Stockopedia graphs show very good progression in all metrics;
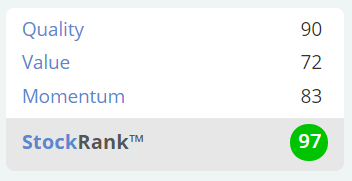
The algorithms love it too;
Dividend yield - is strong, at 6.6%
My opinion - whilst I like the performance of Belvoir, the balance sheet looks too highly indebted for my tastes. Therefore, anyone considering a purchase should probably take a close look at the last balance sheet, to ensure you're comfortable with the level of debt.
NTAV was negative, at £-7.56m as at 31 Dec 2018. I feel that the group has been paying excessive dividends, at the same time as making acquisitions, which has left its balance sheet looking stretched. That's not necessarily a problem though, if it remains as decently cash generative as it has been in the past.
easyHotel (LON:EZH)
Recommended cash offer - at 95p per share. Congratulations to shareholders!
Yet another takeover bid, from overseas. Whilst we're all agonising over Brexit, overseas buyers are hoovering up UK listed companies at quite a remarkable rate. I find this a very peculiar situation. Clearly one side is wrong! Either we (UK investors) are under-valuing UK shares, or the overseas buyers are over-paying. Time will tell who is correct!
To my mind, the surge in takeover bids from overseas is telling me that at least some UK stocks are cheap. That gives me the confidence to hold/buy more, particularly as at least half the shares in my portfolio strike me as potential bid targets.
RTC (LON:RTC)
Share price: 52p (down c.10% today, at 12:55)
No. shares: 14.6m
Market cap: £7.6m
RTC Group Plc (AIM: RTC.L), the engineering and technical recruitment Group, is pleased to announce its unaudited results for the six months ended 30 June 2019.
Profit is slightly down, but note that the divi is up, and the yield looks very attractive (assuming it can be maintained).
As we know already, the recruitment is out of favour with investors at the moment.
Outlook - mentions the "fog" around Brexit, and concludes;
... we remain confident of continuing our satisfactory performance in the second half of 2019 and as such are maintaining our progressive dividend policy.
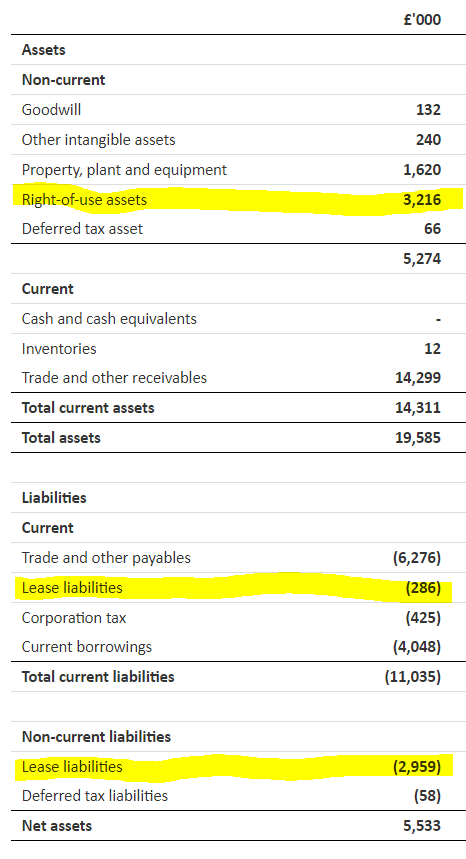
Balance sheet - this is the first balance sheet I can remember seeing which incorporates the ridiculous new rules on lease liabilities.
I've highlighted the entries below - a theoretical asset, offset by the future lease rental payments, shown as liabilities.
I imagine investors are likely to do what we do with goodwill - cross out these book entries, and ignore them.
My opinion - I'm not sure what the rationale is for RTC being a listed company? It strikes me as being too small, and illiquid.
Peel Hotels (LON:PHO)
Share price: 40p (down c.39% today, at 13:50)
No. shares: 14.0m
Market cap: £5.6m
Restoration - the shares of this tiny hotels group were suspended on 29 July 2019, due to late accounts (not able to meet the 6 month deadline for AIM shares). They resumed trading this morning, on publication of those late accounts.
De-listing - today's bombshell announcement is that the company intends to de-list, saying that the costs outweigh the benefits of being listed. The last day of trading is expected to be 26 Sept 2019.
Accounts for FY 01/2019 - not great. A small operating profit of £580k was generated, on £15.6m revenues.
The problem is excessive bank debt. It may not look excessive, relative to the book value of its hotels, but I wonder what the properties are actually worth (as opposed to book value)? Given that they're not generating any meaningful profit, then why are they in the books at an asset value of £33.8m?
A bank covenant has been breached, but the bank is being accommodative.
This could possibly be an interesting special situation, for experts only, who are prepared to hold shares in a private company. The key thing would be to independently value the properties, and ascertain whether there's any value in the equity?
Anyway, bad luck to shareholders.
It's another reminder that tiny companies, which are struggling with trading and/or debt, are prone to de-list. That is usually an instant 50% loss, and that's if you can find a buyer in the market at all. The price quoted on screen is usually in tiny quantity, so not a real price.
Signing off for today!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Peel Hotels (LON:PHO)
Reading Paul's write up above, made me think there was probably a warning sign that could have allowed investors the opportunity to exit once it became clear that the accounting deadline would be missed.
However looking at the string of events - after the Interims were announced last October there were no announcements until after market close on Friday 26th that "the Company will not be able to publish its annual audited accounts for the year end 27 January 2019 (the "Accounts") by 27 July 2019 as required" and hence the shares would be suspended from the following Monday.
Very bad form imho not to even flag the risk that the deadline would be missed.
Perhaps the lesson then is that as investors we need to keep a careful eye on the reporting deadlines and enquire of the company perhaps a week before the deadline (or just sell anyway).
That all sounds like putting too much onus on shareholders to me, rather in fact I think I would tend to steer clear of companies that have a track record of meeting reporting deadlines by the skin of their teeth. (It looks to me like Peel Hotels (LON:PHO) had form in this respect)
£PHO A tiny company should near enough have its accounts complete within a week or two of the year's close as they will closely mirror the cash account. Once the 3 month mark has passed it is bad news for certain and thus qualitatively it makes little difference whether the announcement is 1 day before the deadline or one day after. I would go further Gromley and make tardy result reporting a no-invest rule. Similar to no foreign listed AIM, the hit rate of such a rule will be 99% and thus more than make up for the small handful of successful investments forgone.
Hi Paul
Not sure if you can help me on this one but I have a short position on Peel Hotels s o a decent gain so far today.
However what happens to a sort with a delisting?
Should I hold or exit now?
Thanks.
Hi maxwright,
You would need to discuss the situation with your broker that has facilitated your short position.
As far as I'm aware, short positions would have to be closed before a stock de-lists, but you would need to confirm that with your broker.
Paul.
Thanks Paul, will do.
Actually, thinking about it overnight, short positions do sometimes exist in companies that have de-listed. I remember situations where listed companies have gone bust (i.e. been placed into administration) and had their shares suspended, and short positions remain open until the dust has settled.
There can often then be a long wait, until the spread bet and CFD brokers agree that the shares are of no value. Then the short position is paid out in full. That's what happened with Globo a few years ago. I was a long-time bear on it, having written 29 articles here demonstrating how the accounts looked dodgy, with numerous red flags. However, frauds can take years to unravel, as was the case with Globo.
Thankfully, my good friend WShak, who is a genius with distressed bonds and shorting, messaged me to say that it looked like Globo was about to go pop. So I managed to get a £10k short onto it, and it indeed was suspended within days, after the CEO admitted to having fabricated the saleds figures. The short position was then frozen (at IG) and I think they might have even moved it to 100% margin, but that might have been something else. Anyway, nothing happened for something like 3-6 months, then they paid out in full, once it had become clear that the company was bust, with no assets.
With Peel Hotels (LON:PHO) the situation is different, as the company has decided to de-list, but is still solvent (at the moment). It has given the date of when the shares are going to de-list, if shareholders agree at an EGM. Therefore this is an orderly de-listing. In such a case, I'm pretty sure that shorts would be forced to close out, because you can't have a short position in a private company.
I've asked my broker to find out, and will edit this reply when he does, as it's an interesting point.
Regards, Paul.
Hi Paul
Many thanks for your update, I hope to hear more from you on this.
Regards Max
"To my mind, the surge in takeover bids from overseas is telling me that at least some UK stocks are cheap"
They're certainly cheap if you're buying with euros or dollars.
Nothing like as attractive if you're starting off in sterling.
Paul,
NTAV was negative, at £-7.56m as at 31 Dec 2018. I feel that the group has been paying excessive dividends, at the same time as making acquisitions, which has left its balance sheet looking stretched.
Wouldn't you expect what is largely a franchise business to have very few tangible assets though? I agree about the debt but I understand this was taken on to acquire financial services companies to mitigate the effect of the impending tenancy fee ban.
The free cashflow conversion and operating margins are a thing of beauty as with most franchise type businesses, so my interest was piqued enough to have had a quick skim through the last annual report and this is what they say about the introduction of tenancy fees:
As a business we have diversified our offering even further to include more of a focus on financial services and property sales to spread our risk and reduce the potential impact of the tenant fee ban.
Whilst we are confident in our own ability to mitigate the impact of the tenant fee ban, we predict that the ban will have a much greater effect on the landscape of lettings agents as a whole. We have previously predicted a 20% reduction in the number of lettings agents in the UK as smaller independent agents, who rely on tenant fees as a significant element of their income and have no external support, will struggle to remain profitable. This was increasingly apparent by the number, and indeed the size, of agencies being offered for sale in 2018 with many citing that their decision was driven by the impending changes in the sector. Our franchisees are already feeling the benefit of this change with 26 acquiring a local competitor in 2018, with the average size of the business acquired up 85% to£266,000 (2017: £144,000) which reflects a contraction of the number of agents in the sector not only amongst the smaller but also many of the larger independent agents
All the best, Si
Re: Belvoir (LON:BLV) there was a 5 minute video interview with the CEO published earlier today
https://www.proactiveinvestors.co.uk/companies/news/900113/belvoir-group-plc--in-good-shape--and-encouraged-by-strong-first-half-trading-900113.html
My takeaway was that they are growing market share in a flat overall market environment. The real benefits of this will be seen when market conditions improve, in my opinion. Also, I note Paul’s concern about the balance sheet strength and level of dividend payment. So far, they are demonstrating an ability to pay down debt and grow while paying a healthy dividend and therefore, further acquisitions notwithstanding, I am comfortable with the balance management have struck. It is something to be reviewed each results cycle though and will be interesting to see the level of debt reduction when the interims are published early September.
Cheers
Simon
RE: Dialight
It's not a company I follow but the 1 year chart at the bottom of the article has just made me really laugh - not easy on a Monday. Anyone investing in it (short or long) is really just playing a big game of snakes and ladders, aren't they? I'm sure there are clever types who can time it so they just go up the ladders and avoid the snakes, but most people without this great foresight are just completely wasting their time with this company...
All the best, Si
Bit of a 'risk off' day with Trump's trade war escalating but more importantly China's Renminbi rate fell below 7 to the Dollar. Basically, lobbing one right back at Trump which invites a response.
Most of my UK small caps sold off this morning, interestingly balanced by a good increase in my Silver holdings (via an EFT). All luck, but some points for diversification.
My very fuzzy and completely inaccurate plastic crystal ball says the scale back of business investment in the UK has yet to fully appear in reporting results (because of the lagged effects). Small caps maybe catch a bid after the trade war is settled next year before the USA elections and also the UK gets an early general election out of the way. In the meantime, I suspect more pessimism and cheaper prices yet. Maybe the run since January needs to be sold off first.
But a few game firms will pick over the bones for takeovers. Any good tech firms in growth mode could be bought. PE firms are awash with cash and need to do deals. Personally, I think they will like firms in growth mode with low debt, as they can load up the gearing.
Of course just my opinion, but, i think things are complicated.
Some importing companies may have bought a load of stock up front, others wont. Some may have hedged currency, others not.
The same applies to companies that export
We will not know until the next results.
My only useful opinion is that companies that import or export or have significant overseas earnings will be a bit more volatile than usual.
Seems like a volatile few days out there, FTSE down almost 2%.
Hopefully we may see some bargains emerge.
Positive trading statement from £BLV, Paul, if you have time to review.
All the best and thank you for your industry and expert eye that you provide to Stocko members.
My morning smallcap tweet: Easy money for easyHotel holders
easyHotel (LON:EZH), Global Ports Holding (LON:GPH), Inland Homes (LON:INL), Dialight (LON:DIA)
easyHotel (EZH) 95p recommended offer, a 35% premium.
Global Ports Holdings (GPH) guides FY growth 'low single digit' due to weak trading at its commercial ports. Cruise business strong.
Inland Homes (INL) has quickly agreed Section 106 for the large Cheshunt Lakeside site following July's planning approval.
Direlight (DIA) H2 weak. EPS -4.9p (+6.1p). Already warned of weak trading. Blames soft demand and delayed market share recovery after its production problems. FY outlook unchanged.
Morning Paul, Take a look at TERN. It was one of the biggest risers on AIM last year. Investors got over excited at one point when it rose to 47p (from 3p) in just a few months. The TERN board issued an RNS that killed the SP, and we dropped back to around 8p. But the key companies that comprise the TERN portfolio have been announcing some very significant partnerships , with some very big players. Those that have followed the share for years are now expecting a divestment by TERN which is expected to result in a re-rating of the SP.
CheshireUK - I see that you have recently subscribed so welcome to these boards. With a very few exceptions chosen by Paul or Graham the SCVR deals with companies with a significant RNS on that day so you may find it best to wait for such a day before a request to look at Tern (LON:TERN)
sharw - thanks for the heads-up, still learning how to get the best out of stockopedia
Hi CheshireUK,
Classy response, well done :-)
Oh, and welcome to Stockopedia!
Best wishes, Paul.
Hi Paul. I'm a big fan of SCVR. One thing that helps me a lot is when you formally sign off - something like 'I've run out of bandwidth for today' stops my OCD side from further checking through the evening.
Hi anothersaxman58,
Good point, thanks for the prompt.
I'll try to remember to sign off properly, so you know the reports are finished.
The only reason that doesn't always happen, is because I want to write more, so take a break, but end up being too tired to do any more some time later. Or, on other days, I get a second burst of energy, and write more sections in the evening. I know it's all a bit haywire, but being a professional investor there are always lots of other things going on too.
Regards, Paul.