Small Cap Value Report (Mon 5 Jun 2023) - HERC, GTC, ITX

Good morning, it's Roland here with today's small-cap report.
The RNS feed is pretty quiet today, so I've taken a look at a few smaller and lesser-covered stocks.
Today's report is now finished (10.20).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Main section - summary
Hercules Site Services (LON:HERC) , 36p (unch at 09.00) (£23m) - H1 results, in line - Roland - RED
Strong revenue growth at this contracting business, but poor cash flow, low margins and rising debt. The balance of risk and reward doesn't look attractive to me at current levels.
Quick comments
Getech (LON:GTC)
Up 3% to 13.7p (£9m) - FY results - Roland - AMBER
Getech used to provide geological data to oil and gas companies, but is evolving into a broader business with a focus on clean energy. I’ve always thought that this company’s intellectual property should have some value, but its performance has been disappointing for a long time.
Today’s full-year results cover calendar 2022. They show revenue up 18.6% to £5.1m and management report a record order book of £4.6m. But while the group’s cash balance remains positive at £4.3m, revenue of £5.1m was still significantly below the group’s cost base of £7.9m. The business reports an after-tax loss of £2.8m for 2022.
The operating commentary does suggest some positive developments. There was a 42% year-on-year increase in the number of subscriptions sold, with new services launched to help customers locate copper, gold, cobalt and helium. Getech also won its largest minerals contract to date, worth $900k.
The company is also continuing to invest in its wholly-owned subsidiary H2 Green, which is aiming to build a hydrogen fuelling network in Scotland. H2 Green is being chaired by Dr Graham Cooley, whose previous job was as CEO of hydrogen firm ITM Power (LON:ITM).
Getech saw cash outflows of £1.6m last year, so does not seem in immediate danger of a crash crunch. The group also has a freehold building its hoping to sell, which could provide further liquidity.
Roland's view: I continue to think there could be some value here, but given the group’s long record of losses I see this as a special situation that would require in-depth research and understanding of the group’s operations.
Itaconix (LON:ITX)
Unchanged at 5.1p (£34m) - FY22 results, in line - Roland - RED
Itaconix is a new business to me. The company describes itself as an “innovator in sustainable plant-based polymers used to decarbonise everyday consumer products”. According to the CEO commentary, his aim is to build a high-margin specialty ingredients business.
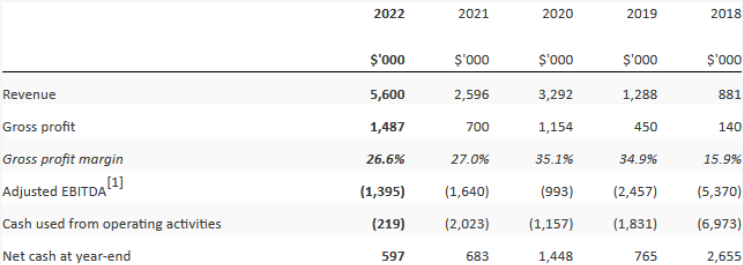
Today’s results cover the 2022 calendar year. Trading results over the last five years suggest some progress has been made in this time:
However, the company has been listed since 2012 and long-term shareholders have suffered significant dilution:
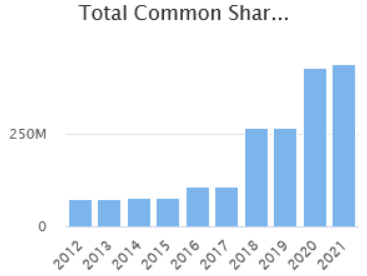
Sure enough, Itaconix has been tapping shareholders for cash again recently, with a $12.7m placing in February this year (not yet reflected above).
However, last year’s performance does not provide me with much hope that the business will become profitable in the near future.
Revenue rose by 116% to $5.6m in 2022, while gross profit increased by 112% to $1.5m. Unfortunately, the adjusted pre-tax loss for the year was nearly unchanged, at $(1.8m) (2021: $(2.0m)).
Operationally, management says that last year’s growth was driven by “success in the cleaning segment”.
As a result, the group’s commercial base has expanded. Its products are now found in “over 145 different consumer brands and in major retailers” in Europe and the US. Sixteen families of patents have now been filed.
An updated note from house broker FinnCap is available on Research Tree. FinnCap has left its forecast for an EBITDA loss of $0.7m in 2023 unchanged, but has nudged down its forecasts to show another loss in 2024. EBITDA breakeven is not expected until 2025.
Roland’s view: Itaconix business appears to be delivering strong revenue growth, but its operating expenses continue to rise sharply. Any prospect of real, cash-generative profit appears to be several years in the future, at best.
If you believe the company has some valuable, proprietary intellectual property, then Itaconix could be worth further research. But for me, the shares are too speculative and impossible to value at this time.
Roland's section
Hercules Site Services (LON:HERC)
Share price: 36p (unch. at 09.00)
Market cap: £23m
Roland's view - RED
This AIM-listed company floated in February 2022 and appears to be a manpower agency providing skilled labour and equipment hire to large construction companies.
Hercules’ share price performance so far has been decidedly middling, but this business has founder management with a big shareholding and substantial revenues. I thought it might be worth taking a look at today’s results to provide an initial marker in our coverage.
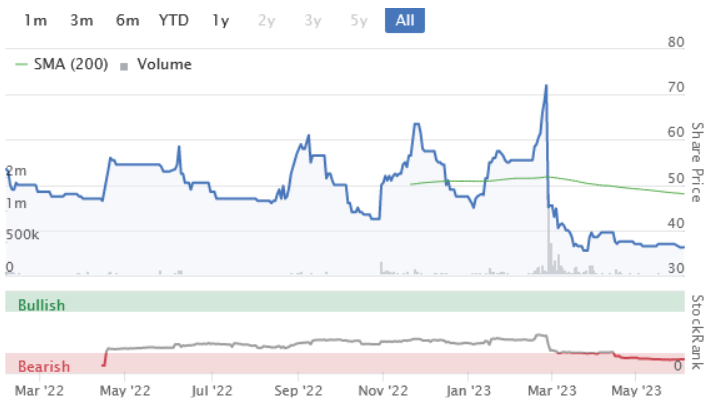
The big share price slide at the end of February appears to have been triggered by a discounted £1.7m placing to provide working capital funds to support growth. Slightly ominous, in my view, but let’s keep an open mind and take a look at today’s results.
Operating highlights: founder-CEO Brusk Korkmaz says a number of new projects with major clients have scaled up during the first half of the year:
The number of operatives working on HS2 Phase 1 has increased from 180 to 400 over the last year
Now supplying labour to Taylor Woodrow at the Exxon-Mobil oil refinery expansion in Fawley, near Southampton
New clients included Amey and SGN Ltd
A training portal project has become revenue generative
Mr Korkmaz is also bullish about the outlook for the remainder of the year:
Further investment in people and procedures in H1 2023 has prepared the business for expected growth in the second half of the year ("H2 2023"), particularly labour supply and suction excavator services.
Has this progress translated into an improved financial performance?
Financial highlights: these interim results cover the six months to 31 March 2023 and appear to show strong growth. Here the main highlights:
Revenue up by 85% to £37.0m
Gross profit up by 71% to £6.9m
Adjusted EBITDA up by 83% to £1.1m
Interim dividend of 0.6p declared (H1 2022: 0.6p)
Declaring a dividend so soon after raising money to fund working capital suggests to me that management must be confident the cash performance of the business will improve.
Unfortunately, I don’t see much evidence of this in today’s results:
operating profit for the period was £331k (H1 22: loss of £213k)
operating cash outflow of £30k for the period (H1 2022: £2.1m outflow)
net financial debt rose to £6.1m (H1 2022: £1.5m) - I assume this includes the benefit of February’s £1.7m placing
Hercules has expanded its equipment hire fleet as well as its labour operations over the last year. But my impression is that much of the firm’s equipment is leased.
My guess is that the cash outflows relate to the need for the company to fund worker’s wages on (perhaps) a weekly basis, while only receiving payment from its clients on much longer terms.
The balance sheet shows average receivables of c.£18m during H1, set against £37m of revenue. That seems to imply that it’s taking Hercules nearly 180 days to get paid by its customers.
However, the company says it’s performance is normally H2 weighted. Checking last year’s accounts gives me a days receivable figure of 96 days, so perhaps that’s a more representative picture.
Even so, these figures suggest to me that this business could continue to struggle with cash flow as it expands.
Profitability: one other problem I can see is that Hercules’ profit margins appear to be very slim.
Most of the group’s revenue is simply the pass-through cost of wages. So I think a more meaningful measure of operating margin is to divide operating profit by gross profit (approximately equivalent to fee income). This gives me a margin of about 5%.
A quick check of some other listed recruiters suggests they generate equivalent margins of 15%-20%. While this isn’t an exact comparison, it suggests to me that Hercules could either lack scale or lack pricing power.
The group’s growth doesn’t (yet) seem to be delivering economies of scale, either. Last year’s 71% increase in gross profit was mirrored by a 70% increase in “recurring administrative expenses”:
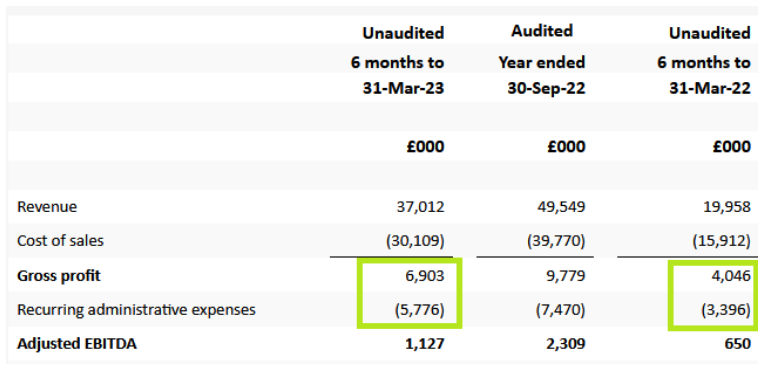
Outlook: it’s possible that some of these metrics will improve during the second half of the year. Hercules expects to report a stronger performance during the second half of the year and says full-year performance is expected to be in line with expectations.
Market conditions are said to remain strong, with “continued buoyancy” in the infrastructure and construction sectors.
House broker SP Angel is forecasting adjusted EBITDA of £3.5m for the full year (available on Research Tree).
This doesn’t seem to map onto the consensus earnings estimate of 9p shown in Stockopedia – my sums suggest a figure of c.0.9p is probably more likely. I think there might be a glitch in the data here.
My estimate would put Hercules shares on a forecast P/E of 40, falling to a P/E of 15 in FY24. That seems pretty strong to me, for a low-margin business with negative cash flow.
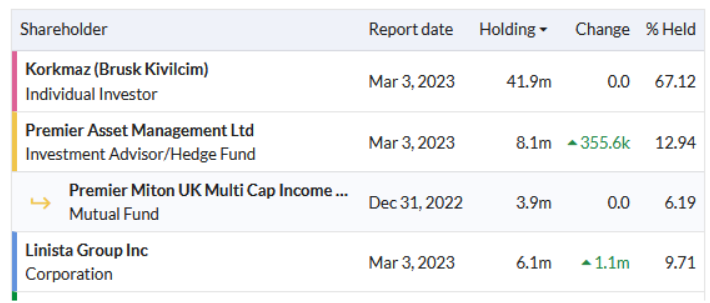
Roland’s view: Hercules’ chief executive Brusk Korkmaz founded the company in 2008 and has built it into a £50m+ turnover operation. The business has clearly generated some profitable growth and positive cash flow at some points during its history.
Kvorkmaz still has a 67% shareholding, so presumably he is motivated to successfully expand the business.
However, my initial inspection suggests that this company suffers from all the traditional problems associated with construction contracting business, such as poor cash flow and low margins.
Net debt has risen sharply despite a placing earlier this year. I don’t think dividends are appropriate without some evidence the group is generating free cash flow.
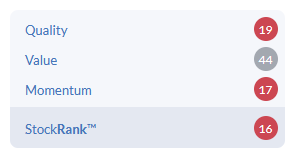
I haven’t researched this business in detail, so I may be missing something. But based on today’s interim results, I can’t see any good reason to want to own these shares. Stockopedia's algorithms appear to share my cautious view:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Yet again you miss out on the very important announcement from Tristel - it is likely to be a real game changer.
Tristel (LON:TSTL) It was certainly bullish language but to be fair it wasn't a trading update - the usual prompt for SCVR coverage and there were no numbers. I presume it will take some years to get the new US markets up and running.
Bit harsh IMO - Paul commented on Stocko only recently and given its my largest holding I tend to keep an eye out. Stock is expensive, especially in the current market, but think it could result in 50%+ sales growth over the next couple of years.
Hi kendal,
What do you mean "Yet again" we didn't cover Tristel (LON:TSTL) ? If you'd checked the archive, you would have discovered that we've written about TSTL 41 times since the SCVRs started, about 4 times per year! Always best to check the facts I find, before launching a broadside! Anyway, never mind.
TSTL announced it had FDA approval, so that didn't come up on our to do list of trading updates/ results statement. However, I did notice the sharp rise in share price, so circled back to it later this week.
FDA approval has been long anticipated, so it will be interesting to see if the spike up in share price sticks, or comes off again. TSTL is an excellent little company, profitable, with a nice cash pile, I've followed it for many years. Valuation is the tricky bit - it's very pricey, but it might grow into the valuation if sales in the US do take off. People do tend to forget that it takes time & money to grow into new overseas markets. Tristel traditionally has sold very small amounts into lots of markets, very much niche products. So it will certainly be interesting to see if sales do gain traction in the US now it's got the necessary approval. It might be a game-changer, or it might not. It certainly needs to be a game-changer, with the shares now trading on 38x existing forecasts.
Personally, I don't like paying up-front for a doubling of profits that may, or may not happen. Particularly in a bear market. But good luck with it! Tristel is a decent company, just to be clear, it's only the valuation we're quibbling over here.
Regards, Paul.
Interesting article today relevant to holders of Boohoo (LON:BOO) and £FRAS
Suggestions of sharp tactics by both with their suppliers leading many to shut up shop. Wherever the truth lies in the reporting, my take home is yet further cost pressures facing these two companies.
https://www.theguardian.com/bu...
Thanks JonBirdy,
Unfortunately, it seems that Shein is crushing this sector. It allegedly uses "slave" labour in China, and has no scrutiny, so has lower costs. Meanwhile UK fast fashion companies get press scrutiny for their sharp practices.
The inevitable conclusion seems to be that manufacturing in the UK just won't be viable on an ethical basis. Or maybe just for small test orders, where speed is of the essence?
Thanks for flagging this, much appreciated.
I'm steering clear of both Asos and Boohoo at the moment, until it's becomes clearer what's happening. Asos looks to be in real trouble, but the stake-building by Frasers is interesting . Although as a friend pointed out over lunch this week, Mike Ashley has a terrible track record of making investments in the sector, but has only been good at buying things out of administration. Therefore small shareholders should not necessarily see it as a good thing to have FRAS pop up with a disclosable stake, as it could be a precursor to a deal between big shareholders that shafts outside shareholders (as happened with Studio Retail for example).
Regards, Paul.
My morning smallcap tweet: Will Tristel clean up at last?
Tristel (LON:TSTL) Batm Advanced Communications (LON:BVC) Watkin Jones (LON:WJG) Deepverge (LON:DVRG) Diaceutics (LON:DXRX) Avacta (LON:AVCT) LifeSafe Holdings (LON:LIFS) Hunting (LON:HTG) Vianet (LON:VNET), Bigblu Broadband (LON:BBB)
◄Tristel (TSTL)► FDA approves sale of ULT as a high level disinfectant. Will launch in Oct. [SP=417.11 Cap=197m]
◄BATM Advanced Communications (BVC)► 5 yr contract from a leading provider of emergency connectivity services in North America. No $$$. [SP=23.6 Cap=104m]
◄Watkin Jones (WJG)► £155m forward sale of Loft Lines, Titanic Quarter, payable over the course of the development. [SP=73.3 Cap=188m]
◄Deepverge (DVRG)► cash-strapped calamity cost cutting. Possible delay to FY22 results due to change of auditor in March. Seeking financing and also potential sale of one or more lines of its business. £2.3m 4 yr contract for subsidiary Glanaco. Down 98% in 2 yrs. [SP=0.45 Cap=3m]
◄Diaceutics (DXRX)► $10.1m 3 year enterprise contract with top 10 global pharma company. Options to significantly increase the scope and value. [SP=91.75 Cap=78m]
◄Avacta (AVCT)► second milestone equity payment has been triggered resulting in an increase in Avacta's shareholding in AffyXell Therapeutics. [SP=110.9 Cap=305m]. I'm short.
◄LifeSafe (LIFS)► Jan-Apr rev £2.1m, 15% higher than internal budgets. [SP=40.58 Cap=9m]
◄Hunting (HTG)► 10-year Strategic Alliance Agreement with with Zhejiang Jiuli Hi-Tech Metals for corrosion resistant alloys for Oil Country Tubular Goods, carbon capture and geothermal applications. [SP=226 Cap=375m]
◄Vianet (VNET)► has received the £925k tax refund. [SP=76.9 Cap=23m]
In line: BBB
Thanks for writing up some new (to me) companies Roland. Interesting read on a quiet RNS day.
Sorry to mither (hassle in southern) you Paul, but did you get a chance to have a look at ME International (LON:MEGP) on Friday?
Also does anyone know if ME International (LON:MEGP) was tipped anywhere this weekend? Or is it just a case of the market catching up
More a case of broker upgrades to revenue and eps for FY23 and FY24 by the look of it.
Just pointing to an excellent write up for any SCVR readers who haven’t seen it by ShoeShineBoy on the recent Mello Chiswick event. It’s a great read, and if I didn’t live 300 miles or so from London it would have convinced me to go to their future events.
Sounds as though Lord John Lee (the first ISA millionaire?) was brilliant. Great commentary on his contribution by ShoeShineBoy. I’ve cottoned on to John Lee’s investment style and wish I had years ago! ShoeShineBoy’s post is worth a look for that alone, but there’s so much more he has covered on the events there too.
Hey Ken, where is that Mello write up you refer to? Like you it's impractical for me to Attend Mello otherwise I'd be there in a shot.
Tango99. Here’s the link to ShoeShineBoy’s” Mello update.
https://www.stockopedia.com/co...
Thanks
Tango99 - if you come straight in to the SCVR you could miss out on a number of thngs like that. I always come in to Stocko at:
https://www.stockopedia.com/di...
Very useful thanks.
Good morning Roland, I'm pleased to see Getech on your list, we're long term holders in this small company which I hope might have multi-bagger potential.....eventually!! A measured opinion from you would be appreciated.
Morning JASVFS,
I've just published a quick comment on Getech (LON:GTC). Agree it's always seemed potentially interesting -- but never really managed to deliver commercially.
Roland
Thanks to Paul for his enlivening Sunday podcasts.
The term “corporate woke-washing” enters the Stockopedia lexicon, and ain’t it the sad truth?!