Small Cap Value Report (Mon 5 November 2018) - Rob Terry, Mello London, AFN, GROW

Good morning!
Rob Terry's Return?
A couple of newspapers have been running stories on Rob Terry (thisismoney, Telegraph) over the weekend, and his plans to create another stock market vehicle.
It doesn't look like a breaking news story to me. The "entrepreneur" has been threatening to launch another stock market vehicle for several years.
He originally planned to launch one called Quob Park Estate:
But plans to launch under that name have come to nothing, and the website has been converted to showcase his vineyard only.
His new venture is typical of the man: a nebulous business plan, grand financial targets and gobbledygook descriptions of what the business actually does.
The sad fact is that he probably will find a few more unsophisticated people to fleece. But hopefully not too many this time, as his modus operandi has been highly publicised.
The disgraceful element of the story is that he is even allowed to try it on again, for the third (or is it the fourth, or fifth?) time.
It was all the way back in March 2015 when Australian law firm Slater & Gordon bought the core business of Rob Terry's failing Quindell venture for £637 million. Slater & Gordon has since sued Quindell (now trading as Watchstone (LON:WTG) ) for fraudulent misrepresentation in relation to this deal.
My view - not a controversial one these days - is that Quindell would have gone bust if it had not been bailed out by Slater & Gordon.
The Serious Fraud Office began an investigation into events just a few months later. More than three years have now passed and Mr Terry is apparently still free to rip off investors. Progress at the SFO must be glacial!
KPMG admitted misconduct in relation to its audit work at Quindell and was fined £4.5 million. So at least there was some accountability from that angle. But what about Mr Terry?
The tiger cannot change its stripes and I would be supremely confident in any future Rob Terry venture ending the same way that his previous ones did: with him enriching himself, his investors walking away with very little, and with dodgy financial tricks and flowery language being used to camouflage the truth. No economic value will be created.
Different investors put different levels of emphasis when it comes to the importance of backing the right management team. But no matter what kind of investor you are, you can benefit by avoiding outright charlatans such as this man.
Mello London
Some news in relation to Mello London which is coming up in Chiswick in a few weeks. I've agreed to take part in the Masterclass session on Day 2 which will also feature Glen Arnold (highly recommended). There will be two further expert speakers to round out the panel.
It promises to be a great conference, so I hope you'll be able to make it for at least one, if not both of the days!
Right, onto some companies.
Today I'm interested in:
- ADVFN (LON:AFN)
- Draper Esprit (LON:GROW)
The RNS feed is looking a little thin today as far as RNS updates from good companies are concerned. I'll have to look at it again, a little harder!
Cheers
Graham
ADVFN (LON:AFN)
- Share price: 26.5p (4%)
- No. of shares: 26 million
- Market cap: £7 million
It's below our market cap limit but this financial information website will be familiar to many readers.
Crypto seems to have provided the company with a bit of a boost. I hadn't looked at their main crypto page before - here's the link.
Revenues are up 12% and operating profit improves from c. breakeven to £384k. Not bad.
Clem Chambers:
We are very bullish about the potential of future demand for Cryptocurrency information and feel this can be a business multiplier for us in the next 3-5 years.
Anything is possible, but if crypto is a late-stage bubble phenomenon and the coins are basically worthless (as I believe), then it's unlikely to be a business multiplier over the next 3-5 years.
I note this reference to operating costs:
Our main costs are relatively fixed but licence and exchange fees are continuing to rise and it is these we must keep a close eye on and if need be change what we offer.
A reminder of the quasi-monopoly position of London Stock Exchange (LON:LSE) - it's the type of company I would like to own shares in, if I can avoid overpaying. See the LSE Group's Information Services.
R&D: Our R & D investment this year has been £353,000 (2017: £379,000) and all of this investment has been to develop the website and has been capitalised.
I'm going to have to raise an amber flag here. The company has spent £353k on intangible assets, but only amortised £202k. Last year, it capitalised £379k and amortised £302k.
This means that the intangibles have been building up on the balance sheet (at £1.3 million this year, versus £1.16 million last year).
That might be fair enough, but you have to agree with the idea that ADVFN's website is increasing in value thanks to this investment. But the website hasn't improved in any significant way for many years, at least as far as I can tell. Maybe those who subscribe to its premium services would disagree?
Balance sheet: if you subtract goodwill from the balance sheet, the company has a net worth of £1.1 million. Of this, the website is worth £1.3 million - so there is negative tangible net worth.
Outlook: the company is looking to build new opportunities in blockchain/crypto. There is no reference to results vs. expectations.
My view: there doesn't seem to be a great deal to get excited about here, I'm afraid. Unless you think the crypto market is going to multiply again and be around for many years, and that ADVFN is going to be at the forefront of providing information about it. Looks doubtful to me.
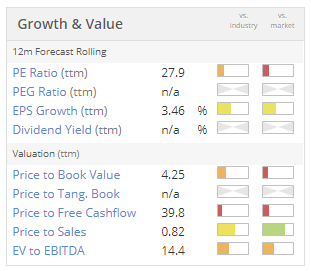
Quantitatively, the shares are overpriced:
Draper Esprit (LON:GROW)
- Share price: 544p (+3%)
- No. of shares: 99 million
- Market cap: £539 million
Draper Esprit (AIM: GROW, ESM: GRW), a leading venture capital firm investing in high-growth digital technology businesses, today announces its interim results for the six months ended 30 September 2018.
This is a proper technology-oriented VC firm (i.e. it's not pretending to be something it's not, like a Rob Terry vehicle would).
I first mentioned it in an SCVR in May. The share price has made good progress since then (up 21%) and it has raised additional funds.
Checking Draper Esprit's portfolio, I note the presence of Revolut. That's quite exciting - I've heard through word-of-mouth from multiple sources that it's an extremely useful product.
Other recognisable names are Currencyfair, Seedrs, TransferWise and Trustpilot.
Performance over the last six months seems very good: "hard NAV per share" is up by 10%, from 402p to 444p. The "fair value increase" is 20%.
The company is dual-listed in Dublin and London, and has a broad mandate to invest in disruptive European companies. So hopefully there will be a smooth continuation post-Brexit. The outlook comment strikes a nice balance of cautious optimism.
My view - there are too many investees for me to be able to get a grip on their prospects in any meaningful way. But I do think GROW is worth investigating in further detail, if you're interested in VC investing.
I would be a little bit worried about the valuation at the current level. As regular readers will know, I have major concerns over tech valuations at the moment, not just in the NASDAQ but among UK firms with themes such as artificial intelligence, blockchain, cloud computing, etc. So I would have some doubts about whether now is a particularly good time to get involved in a VC firm such as this, especially at a premium to NAV per share (officially this is 454p).
GROW's portfolio valuations and return calculations are based on the most recent transactions at its investees - so if somebody puts money into an investee at a higher level, this is booked as an increase in fair value. That's reasonable in isolation but if you have an economic environment where valuations have risen to silly levels, then most of the gains will be illusory.
On the other hand, just one big winner could end up making such a huge return that the current valuation turns out be attractive.
As I said, worth investigating.
I'm not loving the RNS feed today. Lots of junk and not much that's good to write about. So I'll call it a day there.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Can you imagine the crazy posts that will appear on any Rob Terry forum for any of his vehicles? Would hate to be a green newbie poster who supports Rob Terry in his ventures on any forum.
A good question - just why is he not facing charges of fraud?
Just to remind you all that if you want to come to #MelloLondon then as a Stockopedia reader you are entitled to claim £25 off your ticket so just enter the code MLStocko25 in the box when buying a one or two day ticket.
We will be releasing the full programme schedule next week so you can plan ahead if you are just coming for one day but thoroughly recommend both as they are completely different and Graham is doing the SCVR one day and Paul the other.
I know this is an old(ish) thread now but a couple of points in favour of ADVFN and Clem.
Firstly, I like the way their balance sheet data has a very simple overview display, with various assets and liabilities on one side or the other, in boxes and colour coded for ease. It is better to get the up to date info from the latest company reports, however this overview is handy and easy to assimilate.
Secondly, years ago I read an e-book by Clem Chambers on Value Investing. It was quite straightforward and not wishy-washy at all. It referenced ADVFN quite a bit, but this was fine, as it gave examples of setting up filters/screens. Could be turned around I guess, but if left as is, I wouldn't be surprised if it faded.
In terms of an investment, not one for me I'm afraid. Especially if they think Crypto is going to be a major contributor to their success. Block-chain will be invaluable for securing transactions and contracts in the future, but I'm not keen on the currency as an investment. I made a good profit on Ether around the end of last year, but it felt like a pure punt, not an investment. Didn't enjoy the ride and I knew it would be short-lived and I was riding a mini-bubble.
I have used advfn for years too, on the positive side I must say that the portfolio display is much better than the one here so I continue with it for that reason.
I certainly would not pay for anything, the free boards mostly seem to be populated by poor quality posters, I hope those on the premium boards are better!
I have used advfn for years I must admit and it has rather died I agree. Competition is tougher nowadays of course. I fully claim the credit for starting a thread called “time to have a punt on ASOS” when the latter was just below 4 pence. Yes the shares went to £76 so I called that one correct. I actually phoned the company only for a young woman to say “I am really sorry everyone is in the warehouse packing orders”...the orders were for copies of Pearl jeans worn by Victoria beckham. Always liked her..,
In defence of ADVFN, there are BB threads on some companies that are active and that include (amongst the bile, the ramping and the deramping) some well-informed and very interesting posts. Burford Capital (LON:BUR) and Plus500 (LON:PLUS) are examples.
So I think it still has its uses. The intrusive adverts ... and the psychopaths ... are a bit of a drawback, I will admit.
The free BB at ADVFN seem reasonably active to me, 16 of my current holdings have had new posts today.
Pretty sure it was a post on ADVFN that first led me to stockopedia, so it's not all bad :)
Rob Terry's wine leaves a very sour taste in the mouth.
Ah but there isn’t actually any Quob wine to drink. You can pre order the 2018 Premier Cuvee Millesime at just £100 per bottle which is a generous 50% discount to the target price of £200. That seems quite an ambitious price for the first production from a new vineyard, doesn’t it?
It will be ready to drink in 2020 so I don’t suppose it will ship until then. It will be aging on site.
But rest assured that they already know it’s finished characteristics just after harvesting the grapes. Well it was a good harvest this year.
Blend: The blend of Chardonnay and Pinot Noir.
Tasting Notes: A beautiful, vivid wild strawberry pink with a hue of red onion skin on the rim.
Nose: A whiff of magnolia blossom followed stridently by perfumed wild-strawberry compote with a hint of buttered white sourdough toast.
Palate: Rich mouth-filling flavours of strawberry balanced by zingy tart cranberry and pithy Amalfi lemon notes. The texture is creamy with a clean, crisp, yeasty finish.
Ageing: Ready to drink in 2020.
https://www.quobpark.com/shop/sparkling-wine/quob-park-classic-cuvee-rose/
Knob Park Premiere Fraude Millésime would be a more appropriate name.
ADVFN claims it has 4.5m users.
This has to be the biggest lie in amongst a whole host of lies this company tells.
The site is more or less dead.
You can tell this by user posts and how long a post remains before the next one pushes it down the list and the same for companies place in that list. Years ago there would be about 10 to 15 full pages of companies that had active posters posting each day.
Now there are 2 pages only and most of the posts are from the same group of bucket shop spivs trying to ramp a placing.
The site is like a ghost town.
At a very accurate guess, I would say there are about 300 active users on the site but would accept a number of 500 to cover for the passing trade.
4.5m users will refer to the users who set up a free acc since 1999 and then posted for a while and left forever.
Active users has to be less than 500 per day.
Only 500 ADVFN (LON:AFN) users, really?
Some individuals seem to have that many active aliases!
I would guess the thrust of your argument that the number of users is exaggerated holds true however.
It is difficult to judge however just based on the bulletin board posts however, I would suspect that the majority of users do not post at all.
I'm not sure how many active posters we have here at Stockopedia, but it will be a much smaller number than the number of readers and probably also much smaller than the number of paying subscribers.
But the quality of the posts are much, much higher here!
I actually learn (from both the staff posts and other members), rather than have my intelligence insulted.
I have used ADVFN for screening. Still have some filters that I use, as not replicated them yet, but I hate the BBs there.
L2 info. is the main useful functionality of ADVFN. I get my live prices for free at HL.
"At a very accurate guess, I would say there are about 300 active users on the site but would accept a number of 500 to cover for the passing trade."
Really? Are you sure?
That's an awful lot of aliases then
Our Robbo seems to like companies beginning with the letter "Q".
If anyone wants to see a masterclass in gobbledygook I would recommend watching the interview that Clem Chambers did on Online Blockchain (LON:OBC) for Proactive Investor (available on Youtube). Clem Chambers states that 'we don't want to passively misled people', which must have been a Freudian slip as he is basically saying he prefers to "actively" misled people.
Classic interview:
https://www.youtube.com/watch?v=GcdxOlEhpII
Clem is actually less coherent in this interview than I remembered him being. Exactly the sort of scatterbrained leadership I try to avoid when researching potential investments!
ADVFN (LON:AFN) has a momentum score of 0 on Stocko – I’ve never seen that before. Some may remember Clem Chambers, who runs the company, has another company Online Blockchain (LON:OBC) which rose 10x in 2½ months late last year after he mentioned the magic word “blockchain” and changed the name of the company. He raised £1m at the peak price and the SP from that point has since dropped 80%. I see Stocko awards Online Blockchain (LON:OBC) 0 for each category and does not even give it a StockRank Style – I have never seen that before either for a mature stock.
Rob Terry may not be the only AIM “entrepreneur” to stay away from.
Just to let you all know that if you want to come to #MelloLondon then as a Stockopedia reader you are entitled to claim £25 off your ticket so just enter the code MLStocko25 in the box when buying a one or two day ticket.
I used to use ADVFN for a few years up until 3 years ago. The website was plain bumpy with adverts jostling for position making research a tiring process. So much so I stopped using it for anything other than up to the minute pricing and price pressure (level 2) while using stockopedia for core data. Then I discovered LSE offer level 2 at a cheaper price than ADVFN and I finally got rid of them.
Messy website, relatively expensive.
Comments from others on their blogs! I would advise against reading such nonsense, very few people know "owt" and adding to the mix is not a good use of life-time.
I cannot personally recall the ADVFN (LON:AFN) website changing materially in the last decade, however it is only comparatively recently that I have been subscribing to one of their cheaper premium packages, so there could well have been changes of which I was not aware.
It seems to me personally that the website performance has deteriorated materially over the last six months or so and if I could find an alternative provider of the information I need at a similar price, I would probably migrate (or as an alternative I am looking at whether with a bit of software development I can obtain my required data from free resources.)
Personal opinions aside though, surely the intangible value of their website derives from it's ability to deliver revenues. Looking at the stock report revenues have barely changed over the last five years so that does not seem to me to be supportive of increasing value of the website asset.
Stockopedia rates it as a falling star (High Q , Low VM) - it has a very high Quality rank (88) and passes all 9 tests in the Piotroski F-score, so obviously has some merits but not enough to encourage me to dig any deeper.
ref ADVFN. I fear it's days are numbered unless it changes its strategy to registered members. I have been an active contributor the ADVFN Bulletin boards for many years. However the site is plagued by idiots and large numbers posting repetitive biased and often incorrect information for their own benefit. As a ''blue'' user it was possible to BAN most of the 'morons'. Recently that has changed, anyone who is banned now receives numerous marketing messages from ADVFN for them to upgrade to a blue user, which in effect is encouraging them to carry on as before, as blue users cannot be banned by the author from any threads. It seems to me ADVFN is absolutely desperate for paying subscribers and has no interest of the quality of the subscriber, or the content they post. I am losing patience...
Sorry, meant Rob Terry. Emphasis on the Rob!
Trident - just a polite reminder that if you spot a mistake after posting you have an hour to correct it using the Edit button which appears to the left of Report/Link/Share
Thanks sharw for the info, but can't see any edit button.
-2 minutes after posting-
But now, I can! :-)
Any institutions, nomads or legal advisors who take part in a Terry Terry venture that plans to list, should be red flagged for all future issues.
Sounds like he might be trying to list in North America, with a pool of investors/institutions who don't know his full background.
Hi Graham.
I do wish you wouldn’t sit on the fence with your opinions. Why don’t you tell us what you really think about Rob Terry!
Gus.
Hi Graham et Al,
Was wondering if there was any chance of a comment on Totally (LON:TLY) - an outpatient healthcare provider that I came across today - only a cursory look so far and don't know much about the history of the company.
£12m market cap, interim results today show £9m in cash. Full year revenues should be in the region of £80m and valuation is generous in what ought to be a growth sector.
They made a large acquisition last year Vocare (which is why their revenue has increased from £3m to £40m (prior year had £45m in revenue (15 month period, which included 5 months of Vocare).
Stocko suggests its a value trap but they do seem to have a decent shareholder list (management own very little), but certainly interims imply a cheap valuation, especially when adjusted for cash and seems OK volume and spread given size of company. Would welcome any thoughts - to be honest there is something about this that seems off - not sure what that something is!
I should add that Totally (LON:TLY) recently added canaccord as broker (other broker, I hadn't heard off).
Might be a fundraising coming, which would really question the validity of current cash balance
Totally (LON:TLY) : receivables and payables
Hi, thanks for the comment. I agree there is something about Totally (LON:TLY) that seems off. Not something I'd like to write about, sorry. G
Would someone like to take a good look at SQZ following this morning's news? It is certainly becoming the consolidator of choice for North Sea assets and is doing some amazing deals. The Stockopedia rankings still seem to regard it as expensive junk, which might be putting off some investors.
Serica Energy (LON:SQZ) - It is worth noting that the stock rank will be based on the most recent interims which were published on the 28th of September. The interims did not have any revenues from the BKR transaction, although of course, now that the transaction has been confirmed they will be entitled to the revenues over that reporting period. Erskine was also shut down for almost all of the period as well. So the interims look utterly terrible and thus the stock rank looks terrible. But we now know that this isn't the full picture.
You can see the issue in the Stock Report. The TTM column in the Financial Summary is based on the interims. It is showing EPS growth of -94%. But the full year 2018 estimate shows EPS growth of 350.3%, which is what us Serica Energy (LON:SQZ) holders are waiting for.
The structure of these transactions is quite unusual, so it's not surprising that the stock ranks are struggling to keep up. Serica Energy (LON:SQZ) has mostly been quite highly rated by Stockopedia for the time I've owned it (since July 2016). One reason for my original purchase was that it appeared as the top ranked Energy share on my screen at the time.
(Long Serica Energy (LON:SQZ) )
Looks like it's curtains for MYSQ.L with the shares suspended today 'pending the clarification of the Company's financial position'.
https://www.investegate.co.uk/...
Credit to Tom Winnifrith for flagging this one up at this year's UK Investor Show back in April:
https://www.shareprophets.com/...
Gostevie
I'd be interested in any comments please on the results from Draper Esprit (LON:GROW) out today. On the face of it, a gross primary portfolio value increase of 45% sounds great. "Hard NAV" increased to 444p from 402p in March... but I'm not sure whether this is boosted by the placing that happened...?
Hi Andrea... I'll take a look at that, cheers. G
My morning smallcap tweet: Mysquar off to abattoir?
Idox (LON:IDOX), WANdisco (LON:WAND), Velocity Composites (LON:VEL), Mysquare (LON:MYSQ), Symphony Environmental Technologies (LON:SYM), CAP XX (LON:CPX)
IDOX (IDOX) sells lame dog for a quid. The digital division lost £3.2m in 2017.
WANdisco (WAND) wins $1m sale from existing China client.
Velocity Composites (VEL) sacked COE Jon Bridges and co-founders Gerard Johnson and Christopher Banks demand board changes including reinstatement of Bridges.
Mysquar Limited (MYSQ) suspended - looks like $1m has gone missing. Supercrock.
Symphony Environment (SYM) Says "Judge finds case for oxo-biodegradable tech proven". Misleading. A QC and ex-judge hired by SYM says the scientific case for oxo-biodegradable technology to be "clear and compelling".
CAP-XX (CPX) raises £1.75m at 8.5p, an 8% discount.
LPA (LON:LPA) , the specialist LED lighting supplier, issued an end of year update this morning.
https://www.investegate.co.uk/lpa-group-plc--lpa-/rns/end-of-year-trading-update/201811050700052692G/
Record sales and in line with expectations profits indicated despite tough market conditions. Tone of the release is gushing (last year trading finishing “at a gallop” etc.,) but they’ve done this in the past and the market has been more sanguine (e.g. the big sell off after the June interims which seemed optimistic until it dropped news of large contract delays). As ever, as a small supplier/contractor to rail infrastructure they’re at the mercy of government procurement vacillation. Shares seem cheap, but possibly with good reason.
Gus.