Small Cap Value Report (Mon 7 Jan 2019) - SOS, RBG, TRCS, CHH, UPGS, EYE

Good morning, it's Paul here. I'll be writing all of this week's reports.
Graham posted an excellent end of year portfolio review of 2018 here. It's well worth a read, if you haven't seen it. The format is great - looking at winners & losers, and what he has learned from each.
I might do something similar next week, but am holding fire until then, because my (by far) 2 largest positions are both reporting imminently. Sosandar (LON:SOS) is my main holding, intended for the very long term, and is reporting on peak Q3 (Oct-Dec 2018) trading around Wed-Thu this week. That's the normal reporting schedule, if you look back at its previous updates. We already know that autumn trading has been good, as the company has said so, in recent results meetings & presentations.
Revolution Bars (LON:RBG) is my second largest holding, and its peers (Stonegate, and others) have reported very strong trading in Dec 2018. Particularly in town/city centres, and at the premium end (cocktails, etc), which is right in RBG's sweet spot. So we should hear positive news from them on Monday next week. The wild card is potential for takeover approaches to resurface. A competitor (Stonegate) offered 203p cash for it some time ago, so there's very obvious value now the share price is half that level.
I regard a lot of recent share price plunges as being spurious, and providing some excellent buying opportunities. However, only if accompanied by a positive, recent trading update. Profit warnings also seem to be, very selectively, providing some remarkable buying opportunities - if you can time purchases with skill.
There are some very good rebounds underway from recent disappointing updates too - e.g. ASOS (LON:ASC) and Superdry (LON:SDRY) , both up strongly in percentage times from recent lows, although both still miles below previous highs.
So, interesting times, especially for traders. Less so for buy & hold types like me (I hardly do any trading these days, having decided there's not much point - as gains seemed to net off against losses, thus making it a stressful waste of time!)
Tracsis (LON:TRCS)
Long-standing CEO, John McArthur has decided to stand down, from the group he created. Tracsis floated in 2007 at 40p. Shareholders have enjoyed a remarkable 15-bagger since then to date, under John's stewardship. What a terrific track record - and proof that, if financial discipline & skill are used, then a buy & build can work very well - without using debt, either.
John has also been a fantastic CEO from the point of view of private investors. He's been happy to meet us, at events like Mello and ShareSoc. I even managed to drag him down to Brighton, to give an illuminating talk about AIM, to a small investor event that I organised, years ago.
Stockopedia members were even able to ask him questions directly in the comments section to these reports, and he replied to them all. Why can't all companies be that open & engaged with private investors? It's PIs who create the market liquidity, and set the share price, so failing to interact with us is a glaring oversight by many companies, and their city-focused advisers.
The share price of Tracsis has barely moved today, which I suppose is good, but might be slightly galling for the outgoing CEO! The main reasons may be that it's been handled rather well;
- A new CEO, with relevant experience is simultaneously announced today, and
- John McArthur is staying on in an advisory role, concentrating on M&A - which is where he's added the most value historically I would say. So in a sense, it's business as usual, just with a new operational CEO
I don't see anything untoward or worrisome in this announcement, and confirmed that hunch with a brief chat with John this morning. So three cheers for an outstanding outgoing CEO who has done a fine job at Tracsis, and has been a good friend to the PI community along the way. Incidentally, I've made it clear that we want to be kept informed about what he decides to do next!
Churchill China (LON:CHH)
Share price: 1040p (up 10.6% today, at 11:25)
No. shares: 10.96m
Market cap: £114.0m
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce the following trading update for the year to 31 December 2018.
This looks good, although the reporting is too vague for me to be able to quantify things;
We have made substantial progress against our strategic objectives in 2018 and have enjoyed a strong finish to the year.
Revenue growth in export markets remained strong across the year.
Our performance in the UK improved in the second half of the year.
As a result the Board now expects that operating performance will be ahead of current market estimates.
What do we reckon the upside might be? 5-10% perhaps? If so, why couldn't the company have just told us the range of upside - accepting that it needs to be a range, because the company will obviously need to allow for any audit adjustments that might arise between now and publication of the results on 27 March 2019.
We should hopefully soon get an update note from N+1 Singer, on Research Tree.
Lack of liquidity - this is the biggest problem with CHH shares. I like the company, but can't see any point in trying to build a position, as the market is so illiquid.
Currently, the quoted market price is 1000p bid, 1080p offer. As we know, the system is bent, so the quoted prices are not the real prices in small caps. Querying with my broker, the real prices right now are actually: 1004p to sell (but only in 2,500 shares maximum), and 1052p to buy (only in 1,000 shares size).
To summarise then, the quoted bid/offer spread is 7.4%, and the actual bid/offer spread is 4.6% - diabolical, and very bad, respectively!
Therefore the only way to deal in this share would be to leave an order (at your maximum price) with your broker, maybe for a few days, and hope you get a fill.
My opinion - this is an excellent company, with a great track record. There doesn't seem to be any sign of it struggling with the downturn in the hospitality sector. Plates get smashed, so restaurants have to buy more.
Churchill is very good at product development. I invested in a restaurant in 2016, which turned out to be a very quick way of squandering a lot of money (note to readers, if you're ever tempted to invest in pubs or restaurants, I've got one word for you: DON'T!!!). We (or rather, I) paid for a lot of very nice Churchill products. The feeling was that they're very competitive on both designs/fashion, and not bad on price.
As an aside, I also paid for some lovely, premium cutlery (not sure of the supplier). The theory being that customers then perceive the food as higher quality, so will pay more. The theory omitted to note that, once some customers have eaten a meal with nice cutlery, they believe that ownership of the cutlery has transferred to them, taking it home as a memento. Supplies depleted rather quickly unfortunately.
Going back to Churchill, how about this for an excellent track record?
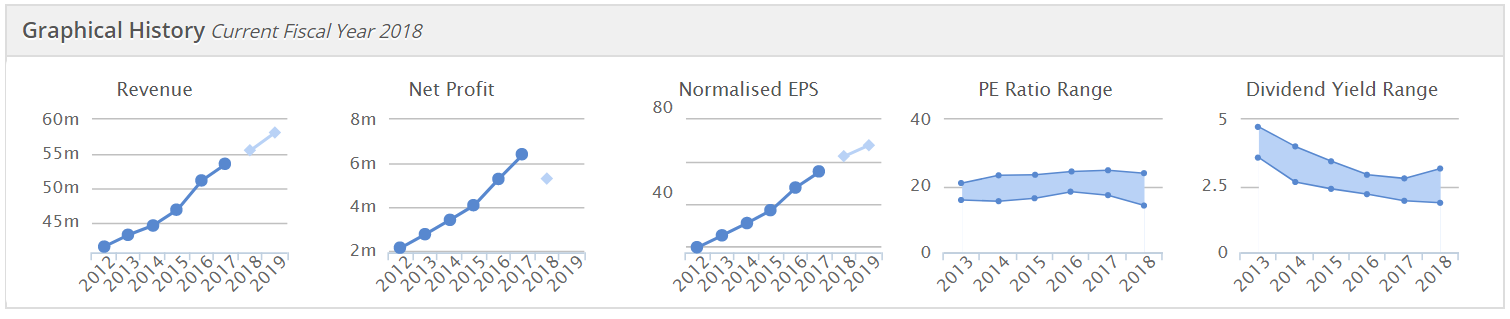
The valuation looks reasonable to me, for the first time in ages. It all depends on what your macro view is though. If you think a cyclical downturn is on the way, and/or that exports might suffer due to the dreaded "B-word", then it might not seem quite so attractive to you.
My view is positive overall, but it's not liquid enough for me to want to get involved.
UP Global Sourcing Holdings (LON:UPGS)
Share price: 44.5p (up 12.8% today, at 12:51)
No. shares: 82.2m
Market cap: £36.6m
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces the following unscheduled trading update.
This is a positive update, relating to the year ending 31 July 2019;
The positive momentum that the Group referenced in its FY18 results, announced on 6 November 2018, has continued.
There has been stronger than expected revenue growth across each of its four strategic pillars (i.e. discounters, UK supermarkets, online platforms, and international customers), with international business continuing to account for a larger share.
As a result, and notwithstanding the higher overhead costs associated with servicing the increased revenue, the Group now anticipates that its EBITDA performance in FY19 will be above the market's current expectations.
Why does it mention EBITDA? Memo to the City - EBITDA is NOT PROFIT!
Nevertheless, this sounds a positive update.
My opinion - I don't really have one, as this type of business doesn't interest me.
If you are interested though, this appears to be a good value share, with a low forecast PER, and a high dividend yield.
My reservations are that its financial performance seems quite variable, with a big profit warning in autumn 2017. Does it have much sustainable competitive advantage? Probably not, which is why the shares are cheap on value metrics.
Still, after this positive update, it's a better investment today than it was yesterday.
Eagle Eye Solutions (LON:EYE)
Share price: 101p (up 4.4% today, at 13:11)
No. shares: 25.4m
Market cap: £25.7m
Contract win
Eagle Eye, a leading SaaS technology company that allows businesses to create a real-time connection with their customers through digital promotion and loyalty services, is delighted to announce a new five-year contract with Waitrose Limited ("Waitrose & Partners").
I don't normally mention contract win announcements. However, in this case, EYE is on my watchlist as something I might buy in future, so want to keep my notes here up-to-date, for easier reference in future.
There's also a trading update buried in today's contract win announcement;
The Company continues to trade in-line with the Board's expectations.
This contract follows on from existing work with John Lewis Partnership. So clearly by rolling it out to Waitrose too, the customer must be happy.
My opinion - I'm keeping a watching brief on this one. It looks potentially interesting, and has a great client list.
On the downside, it's still loss-making, although not horrendously.
The share price has come down a lot in the last year, along with many other smaller, more speculative shares. It's not far off getting into the sort of price range where I might consider dipping in my toe.
Gotta dash for a meeting now! See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
UP Global Sourcing Holdings (LON:UPGS) We are organising a site visit to UP Global Sourcing for private investors on Thursday 7th February 2019. There will be an opportunity to look round their Oldham showroom and speak with Andrew Gossage, Managing Director, and Graham Screawn, Finance Director.
The schedule for the day would be as follows:
11am Arrive at UPGS offices
11.10 tour of the Showroom and offices
12.45 Q&A session
14.00 Visit finishes
If you are interested in joining us, please email hannah@equitydevelopment.co.uk
An article on Investopedia today quotes Goldman Sachs as applying the following criteria in selecting shares in the current turbulent times:
Adjusted forward P/E less than 10% above 10-year historic median
Strong balance sheet
Pays a dividend
Low beta, below the S&P 500 median
Low ownership by hedge funds
I wondered why "Low ownership by hedge funds" would be relevant, and how one might easily identify hedge fund ownership. Has anyone any thoughts on this, please?
Hi John
Re Tracsis (LON:TRCS)
Disappointed you have decided to step down from Tracsis. At 39 or so, I certainly hope you are not headed for semi retirement! Obviously a change of CEO in a successful company for an investor, is never entirely encouraging as it tends to signal something the CEO has seen 'down the track' that the investor would not have the insight for,
For me my concerns would be that M&A is perhaps looking increasingly expensive, and that of course opens up more risk. Investments in the data mining and video analytics may pay off, or they may not, but at some they may have to be written down.
It may also be that the CEO is less attractive to a pure managerial role rather than the dynamics of a buy and build model, opportunities for which for a young ambitious chap perhaps lie in being on the books of a Private Equity outfit, or similar, where personal rewards can be higher.
Of course you may have found an interest in Zen Buddhism, and have discarded all earthly trappings!
Whatever it is good luck.
Trident,
I'm 43 but will happily take 39. No plans for semi-retirement or private equity I assure you.
The reasons for my transition are entirely personal and I suppose slightly selfish. I have a young daughter of 4 who starts school in September and I wish to spend the summer with her unfettered from work commitments and obligations. With that said I would never choose to depart without knowing there was going to be some favourable tail winds for my successor and I'm confident the stars have aligned nicely.
We don't see any change with regards M&A pricing and the potential of a Corbyn government eliminating entrepreneur's relief is a genuine and very material concern to owner managed businesses.
Best regards
John
Thanks Paul. i really appreciate your frankness and can see why you might invest in Revolutuion but not a one off pub or restaurant.....must confess to a little angel investment into Love Lane ahead of their raising some more cash via SEEDRS. I am really backing a friend who has gone in as Exec Chair....he was the light behind Meantime
The comments on Tracis are particularly helpful I have been watching for a while and was concerned at the CEO change. Do you know how much John McArthur has invested in the business and whether he will be leaving his more In?
A request if I may? Can you comment on Accesso Technologies whose share price dropped by 60% and has come back a bit? It seems there were a couple of very negative analyst reports on the way they were calculating growth but, it is unclear whether these also come from close to an entity that wants to/is shorting the stock.
HNY
Hi there,
I currently hold 3.4% and am therefore a significant shareholder who appears on the share register on Tracsis' website (Rule 3 - Significant Shareholders). Therefore all trades I make are RNSable.
I have no immediate need or intention to sell stock and have my own view of where the sp should/will be in years to come...
Thanks
John
"Revolution Bars (LON:RBG) is my second largest holding" Vs. "if you're ever tempted to invest in pubs or restaurants, I've got one word for you: DON'T!!!)." ... So which is it , Paul?
A lunchtime update from Gresham Technologies (LON:GHT) has sent the shares up 20%
A rather spectacular £47m loss for Missguided - saved by £27m shareholder loan. Sounds like they got it badly wrong.
Paul - what was the name of the restaurant you invested in? Hopefully not a chicken related one in Brighton.
You can bring back the cutlery at the next Mello meeting, no problem at all.
As well as Revolution Bars (LON:RBG) Superdry (LON:SDRY) and ASOS (LON:ASC) there seem to be a number of other rebounds in shares recently heavily sold. Check out QUIZ (LON:QUIZ) and On The Beach (LON:OTB) too. That sentiment hasn't benefited £G4M today though!
Thanks for the coments on Churchill China Paul. The other point potential investors may wish to consider is whether our likely exit from the EU would affect Churchill's business owing to the potential loss of protection provided by EU anti-dumping regulations for ceramic products from China (China from China!). I believe that there have been calls for the UK to introduce similar regulations if we leave the EU. My opinion is that the impact on Churchill will be limited so I remain a holder.
£G4M (Gear4Music) it looks like Directors have started buying (albeit in modest amounts). Less risk of any imminent fundraising and demonstrates confidence in the business at the current price. Could we see a bounce from here?
Nicobos
At these modest levels, it could be a coordinated effort to try to indicate confidence rather than evidence that they really believe the fall is a major overreaction.
£G4M
FREng - Yes, you could be right although the non-exec Chairman has bought £24k which isn't pocket change (although could be for him!). Seems a lot to commit if you didn't have some confidence in future prospects of the business !?
It’s a couple of months worth of his non-exec income (about 100k per annum for 3 part time gigs) which is unlikely to be his sole income...
Paul
Many thanks for the comment on Tracsis today and my pending transition. Very kind words and, no, I'm not fussed at all about lack of share price movement - quite the opposite.
As per the RNS, I will remain in post as CEO for at least the next 3 months if not longer but I'm happy to field any and all questions from your readers.
Best regards and catch up soon,
John
Hi John ,
This is why I think you are fantastic CEO , I wish you every success in the future .
Regards
Tony
Hi John,
Firstly, I hope you enjoy your calmer life when you step back (is it semi retirement?)
Secondly, My opinion on today's shareprice is it's a reflection on the way the changeover has been handled, the quality of the new CEO and the fact that you will remain with the company.
Thirdly, since you asked, a question: Rail related news seems to be more negative and more frequent these days. Does this offer opportunities for you, threats or just business as normal? Will a franchisee in trouble call the experts, or try to cut costs, even if short sighted?
Thanks
Hi doug2500,
Certainly not semi-retirement! I will be staying on at Tracsis albeit in a reduced role (and non-board) helping out with M&A as there is still loads to go at.
Regarding your question, to be honest I'm not entirely sure. Ever since we started Tracsis in 2004 the mainstream media would have you believe traffic and transport is in 'chaos' - especially rail. This is an easy target for obvious reasons but the truth is more services, far greater safety and a huge rise in people using the network over the past 20 years. With that said there remains myriad problems to solve and this will continue wherever you have a dynamic of rising demand and limited capacity.
Rail franchises (TOCs) are key customers to Tracsis and as you will know we assist them on various fronts and they are far more innovative than you might imagine. Cost cutting really isn't an option given their operations are already creaking so it's typically better processes and technology that help move things forward.
All the best.
John
Thx John - you should be very proud.
Re. Sosandar (LON:SOS)
Happy to be corrected, but last year the trading update was issued on 12 Feb 2018.
Also InvestEgate has a useful feature which shows forthcoming results, one week and one calendar month ahead. No mention of SOS.
i track the scheduled updates and none listed for Sosandar (LON:SOS) as yet for the coming month: although many AIMers do update the market on their own timescales: I reckon that flexibility helps sometimes to close deals and flatter results
Hi Ramridge,
The Sosandar (LON:SOS) Q3 trading update is definitely this week, Weds or Thurs.
I wouldn't have mentioned it unless I was sure of my facts!
Regards, Paul.
@Paul, guessing you must hold enough Sosandar (LON:SOS) to have the inside track then as they haven't released that date nor is it on their published financial calendar: last year was 12 Feb for the TU. I don't hold but used to , guessing there is good news to come then.
Big week for retail reporting : Dunelm (LON:DNLM) did much to cheer today and Greggs (LON:GRG), Joules (LON:JOUL),,Footasylum (LON:FOOT), J Sainsbury (LON:SBRY), Shoe Zone (LON:SHOE), Ted Baker (LON:TED), Majestic Wine (LON:WINE) etc all report this week. Given the amount of shorts in this space there may be a few explosive short squeezes if results exceed beaten down expectations
Can you have a look at Stanley Gibbons (LON:SGI) today - its looking like it might not be quite the dead duck after all (which is nice, as it'd be a shame to see a company like this destroyed completely by an idiot).
their interim report from last month said:
"This report covers the first six months since the refinancing in March earlier this year. The previous 2 years have been mostly about fixing things and plugging holes - this work is largely complete now as one-off costs diminish and we start to rebuild from a cleaner slate. It would be nice to say that our problems are behind us but as the results show we still have a lot of work to do to achieve sustainable profitability. However, the more rewarding rebuilding phase has commenced, and some exciting work-streams have been initiated which it is hoped will unlock the full potential of our business. Technology improvements are high on that list."
old stamps and new tech... interesting.
Staffline (LON:STAF)
decent contract announcement today from the prison service £104 mill over 4 years. I am semi hopefully about trading update tomorrow(?) - they seem to be on track with their 5 year plan to get EPs to 200p per year - at current shareprice of under 1300p one would expect that would result in potentially 50% shareprice increase - nice Kahuna's to have the target but i guess we shouldn't get carried away and presume it will actually be achieved :)
I am always slightly wary about these larger government contracts too as they invariably get ditched a year or two after inception when they are found not to be working as planned - or turn out not to be profitable - i would say though any money spent invested in prison education and rehabilitation support will probably be well spent providing they get the basics right IF actually helps offenders get back on track, an area where we probably woefully under invest as a country.
Looking at the current 2019 forecasts as ever the pe seems to be stuck below 10 so still decent value on that basis- perhaps thats always going to be the case for recruitment type businesses - but up to now STAFF seem to have done a very decent job getting the fundamentals right. I guess we are only a recession away from it all going TU.
Positive update for Real Estate Investors (LON:RLE) . A Midland based Real Estate Investment trust. Keeping away from the London Bubble seems to have helped them. Divi now over 7% rental inc. Up, occupancy up
Further vote for MJ Gleeson (LON:GLE) Paul. The inference in the trading update suggest a possible earnings beat for he full year to end of June, albeit early days.
Positive updates from MJ Gleeson (LON:GLE) and UP Global Sourcing Holdings (LON:UPGS) today. No financial details until next month.
Outside the scale scope for SCVR, but homeware specialist Dunelm (LON:DNLM) provides a Q2 update this morning that gives another reference point for state of U.K. retail.
https://www.investegate.co.uk/dunelm-group-plc--dnlm-/rns/second-quarter-trading-update/201901070700032904M/
LFL revenues up 9% with OK store performance and strong online growth. Similar to Next (LON:NXT) report last week in that success in retail requires both barrels of the gun to be working together. Pretty downbeat commentary on prognosis for second half due to market uncertainties over Brexit etc., but suggesting they’ll be at top end of market expectations overall.
Gus.
Re: Dunelm (LON:DNLM) I am not sure that the 9% LFL headline figure at Dunelm is quite what it appears. Several websites have been consolidated into the main Dunelm website (www.kiddicare.com, www.worldstores.co.uk). It appears that the rise in revenue online (35%) is due to this--that LFL is the combined revenue of all of the sites...but I can't be sure from the wording in the RNS.
[from the RNS-
4. Non-LFL Online - Worldstores.co.uk, Kiddicare.com and Achica.com (these websites are now closed)]
Do you have an insight here, Paul, accepting that it isn't a small cap...? This isn't how most of us understand LFL. NB: half year revenue in store up 5%, online up 35%, but YoY group total is up 1.2%.
(no position)
Good call laurie.
group up 1.2% - share price up 11% ?
When they must have the same Brexit/UK worries as friday, and every other retailer has.
My morning smallcap tweet:
Avon Rubber (LON:AVON), Churchill China (LON:CHH), UP Global Sourcing Holdings (LON:UPGS), Mattioli Woods (LON:MTW), Infrastrata (LON:INFA)
Avon Rubber (AVON) wins US defence order worth up to $92.7m over a duration of up to seven years.
Churchill China (CHH) guides FY operating performance ahead of current market estimates.
UP Global Sourcing (UPGS) guides FY EBITDA above the market's expectations.
Mattioli Woods (MTW) guides FY profit in line with management's expectations despite rev growth slightly lower than expected.
Infrastrata (INFA) FY loss up to £1m. The gas storage development co issues going concern stmt, prob as expected. Did so last year
At long last AAOG has delivered :-0
True quality shines with a beacon so bright it is not dimmed by brevity.
Two thumbs up now.
Happy hangover!
It is 1.50 a.m. Admittedly i'm a tiny bit pissed but has Paul's (non existant) article really been read 117 times
It's nearly 1 a.m. and to be honest I'm a little bit pissed, but already 117 people have read your article place holder and someone's already given it a thumbs up . It must mean you have an appreciative audience . Have a lovely day in these turbulent times !
/
Hi Zoiberg
RE: Reads
This is a bit of code (JavaScript or similar) that will register a read when someone visits a page for example two leave a suggestion of a company they would like Paul/Graham to comment on.
It doesn’t check whether they have read the words, just whether they have visited. It could also detect how long they stayed on the page, where they visited from, where they went after etc etc.
Best wishes
Michael