Small Cap Value Report (Mon 8 June 2020) - RBG, UPGS, LOOK, TTG, SOLI, ACT, SDY

Good morning, it's Paul here.
Estimated timings - I need to rest my eyes for a bit, but will add a few more sections after lunch. 16:30 finish time.
Update at 17:40 - I added 4 more company sections this afternoon. Today's report is now finished.
I'll be writing Mon-Wed SCVRs this week. Graham has kindly offered to write Thu-Fri, in order to give me a 4-day weekend to celebrate my 52nd birthday! What a kind man! I shall enjoy that! :-D
Probably much like yourselves, I needed to take a good break over this weekend, to recover from such an intense week, trying to work out what the hell is going on with the world, the economy, and the stock market.
Where do we start? Firstly, thank you for all the positive comments, I really appreciate it. I have no idea what is going on, and am just trying my best to interpret it from one day to another. Some will be right, some will be wrong. Anyone who uses words like this "will" happen, is wrong. People should use words like "could", or "might". Otherwise, they are charlatans overly optimistic about their forecasting ability! Nobody knows what will happen for sure.
It's fine to express opinions. But not to express false certainty. Let's measure commentators - let's make a note of what each commentator said on each date, and then challenge them afterwards when they were completely wrong! (I got that idea from "Superforecasting" by Tetlock & Gardner. The best forecasters express their uncertainty, and readily change their mind when the facts change.
I'm the first to admit that, I had no idea the Dow would go from 29,500 in early March, to 18,500 low, then rebound to 27,000 now, all within less than 3 months. This is unprecedented. Anyone who did know this, would be a billionaire could have become very rich by now. Personally I kept my thinking flexible, and survived this turmoil intact. I hope readers survived it all OK.
My latest feeling, for what it's worth, is to stop fighting market recovery, so I've been forced to close my Dow shorts (due to large short-term losses) . Let's enjoy the longs on recovery - much more profitable than the losses on my hedges I should add.. That is clearly the way things are going. Hence I'm about to double up on increase some of my recovery longs for the UK economy today.
What do readers think? I think we've done a pretty good job of steering through this nightmare.
Shops start re-opening this day next week, 15 June. I suspect there could be pent-up demand, and plenty of people just wanting to be able to shop again, even if they don't specifically want to buy anything. Evidence from the USA is that re-opening has gone better than expected, so the same is likely here, I reckon.
(apologies for the strike-throughs above. I wanted to tone down my Sunday evening comments, and make them less emphatic - following my own advice! But also leave an audit trail of what I'd amended, so that people who had already given a thumbs up can see what's been changed)
Revolution Bars (LON:RBG)
Confirms it has executed final documentation re enlarged bank facilities, as expected. No surprise there, so it's not price sensitive. Together with the equity fundraising underway, I see this as a belt & braces situation - the company now has plenty of liquidity for the time being, well into 2021. Therefore the share is a lot less risky than it was previously. Medium term there is still risk of course, if covid returns badly & forces re-closure of sites.
Allocations in the placing went out on Friday afternoon. It was scaled back, as placings usually are, because people expect them to be scaled back & hence over-apply! It's a bit of a balancing act. Occasionally you get a full allocation, which is actually a bad sign, as you end up with more shares than you really wanted, and the price is likely to go down, because of lack of demand. Equally, if you get scaled back too much, then you end up with a scrap of stock too small to bother with. Therefore the ideal situation is where you get somewhere between c. 50-75% of what you applied for .
Sorry for the confusion about when RBG shares go ex-open offer entitlement. Some posters thought I'd got it wrong, but I've just checked with my broker, and I was correct originally. If we buy (or sell) RBG shares today, then they carry with them entitlement to 3 for 5 new shares priced at 20p. The last trade is close of play tonight. Therefore, tomorrow morning RBG shares are likely to gap down a few pence, taking into account that transactions from tomorrow will not carry any open offer entitlement, it will be fixed according to who owned the shares at close of play tonight. But please do double-check with your broker before acting on this.
The open offer is effectively underwritten - by the investors in the placing. i.e. if the share price of RBG were to fall below the 20p issue price in the coming weeks, then existing investors might decide not to take up their open offer entitlement. It wouldn't matter, because the £6m new open offer shares (or part of them) would revert to the placing investors. Therefore the £15m equity fundraising is now a done deal (subject to approval at a GM, which should be a formality).
Short covering
I've noticed some large rebounds in several shares lately, which have the look of a short squeeze. Examples include Hammerson (LON:HMSO) as mentioned last week (I'm long), and N Brown (LON:BWNG) (I'm also long).
I think this is a good investing theme to follow up - i.e. looking for cyclical companies which are heavily shorted, and going long for a rapid rebound, as the shorters scramble to buy back.
This is risky though - so it's essential to identify companies which are not going bust. I had recently taken a very high risk, and probably idiotic, long on Intu Properties (LON:INTU) - purely on the basis that there could be a big short squeeze if the shopping centre re-openings go well from 15 June, and the banks/bondholders waive covenants due to be tested near end June. However, weekend press saying that administrators have been lined up spooked me, so I sold for a loss in the opening auction this morning. In at 9p, out at 7p, so not a disaster, but also not one of my better trades!
I'll have a rummage when time permits. Does anyone have a link for the most shorted UK shares, to give me a starting point?
NB. I'm not thinking about long-term investments with this short covering theme, more shorter term trades. So my intention is to sell both HMSO and BWNG once the rebound has run out of steam. The risk is that shorters might regroup, and have another go at these shares. Hence why I think it's sensible to bank the gains. Or sell half, which is what I'm thinking of doing.
I don't think it's a good idea to short anything at the moment, it's too risky when the market is on fire, as bizarrely enough it seems to be at the moment. On reflection, I under-estimated the boost that the Fed/BoE have given to equity markets. After all, with interest rates at zero, where else are people going to put their money? Bonds provide a lousy return, and put your capital at risk from falling if interest rates rise. When you can't find yield anywhere else, then equities look attractive, even if they are expensive by historic standards. If interest rates are staying low forever (which looks increasingly likely), then a PER of 20 is not expensive at all. Maybe we need to recalibrate? That sounds dangerous, but why fight against reality?
.
Up Global Sourcing Holdings (LON:UPGS)
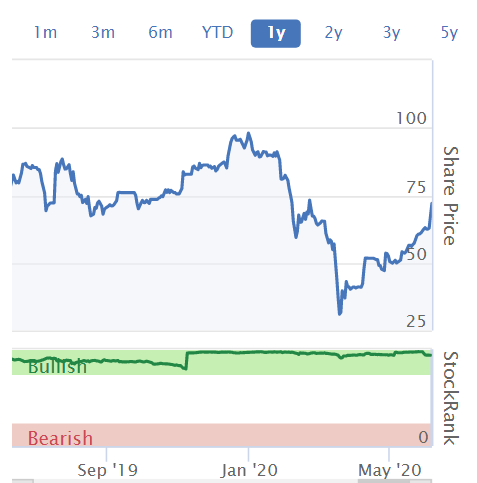
Share price: 72p (up 14% today, at 08:32)
No. shares: 82.2m
Market cap: £59.2m
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces the following unscheduled trading update.
UPGS has an unusual year end of 31 July 2020. I interviewed its MD, Andy Gossage, here on 20 Feb 2020 (audio). The worry then was how Covid-19 would impact its supply chain in China. Then of course the far more serious problem later emerged of demand drying up, as UPGS's retailing customers were forced to close, as the virus spread to Europe.
This is a surprisingly good update today;
Since the Group announced its interim results on 30 April 2020, the invoicing and delivery of the Group's order book has progressed at a steady pace. Total invoiced revenue for FY20 as at Friday 5 June 2020 was £97.2m (FY19: £102.5m) and there was an order book for the remainder of FY20 of £10.6m (FY19: £16.4m).
As a result we now anticipate that Underlying EBITDA* will be above the market's current expectations.
*Calculated before share based payments and income from the Coronavirus Job Retention Scheme
It's not clear why the company refers to underlying EBITDA. Underlying profit before tax is a more realistic measure. Anyway.
The footnote is intriguing. I hadn't given any thought previously as to how companies will account for the income from the furlough scheme. I assumed it would be offset against wages cost, but perhaps not? If I'm reading this correctly, then it sounds as if UPGS has beaten market expectations, with furlough income over and above that, possibly? I'm not sure how many staff it put on furlough, that would need checking.
Net debt - modest at only £2.6m at 5 June 2020.
Order book - note that the order book for Jun-Jul 2020 is soft, at £10.6m, down 35%. Still, that would be taken into account in the positive full year outlook.
My opinion - this business has proven far more resilient than I anticipated. Thinking this through, the reason must be that its products continued to sell in retailers which remained open (supermarkets).
Well done to shareholders, who kept your nerve during this traumatic period, which has paid off nicely.
.
.
Lookers (LON:LOOK)
Share price: 26.75p (down 14% today, at 09:47)
No. shares: 390.1m
Market cap: £104.4m
Late accounts, possible suspension of shares, auditor resignation
I've re-titled the announcement. from the original, which was "Update on Results".
This is a worrying announcement.
To recap, accountants Grant Thornton were brought in to investigate previously disclosed fraud within Lookers accounts. The draft report has been shared with auditors Deloitte, who have decided to resign once the 2019 audit is complete! That's damning, in my view.
2019 results won't be ready by the deadline of 30 June 2020, which would result in LOOK shares being suspended.
My opinion - I have a policy now of not touching any share where accounting irregularities are discovered. This is because quite often the initial discoveries can be the tip of the iceberg. The auditor handing in its notice is a huge red flag, in my opinion. If I held this share, today's announcement would have had me hitting the sell button at 8am. It might turn out alright, but why take the risk?
Other companies in the sector might be worth a closer look. I say that because it is reported that the Govt might be considering another scrappage scheme, to boost new car purchases. Call me old fashioned, but I would prefer to home in on a company where there has not been accounting irregularities! I'll probably re-visit the numbers for Vertu Motors (LON:VTU) . Companies in this sector have lots of freehold property usually, so they're interesting hybrids of property & car dealing companies.
Are cars big ticket items? Not really, as these days most are sold on personal leases, with affordable monthly payments. There could be pent-up demand, as we come out of lockdown.
.
Tt Electronics (LON:TTG)
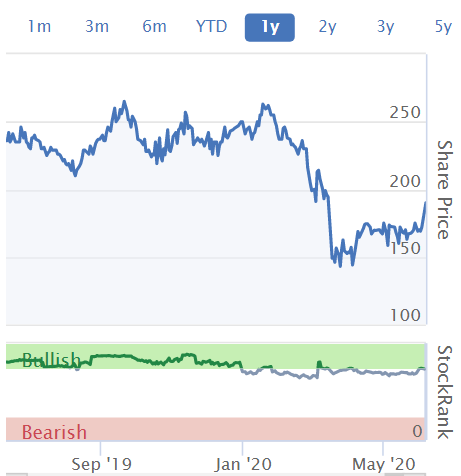
Share price: 194p (up 9% today, at 16:04)
No. shares: 164.1m
Market cap: £318.4m
TT Electronics plc ("TT", "the Group"), a global provider of engineered electronics for performance critical applications, publishes the following Trading Update on the Group's performance in the five months to May 2020.
This group seems to have traded relatively well during the crisis, and is recovering nicely now;
... Group revenues in the first quarter were 11% lower than the prior year on an organic3 basis and for the five months to May were 14% lower organically, reflecting both reduced economic and industrial output globally and the direct impact of COVID-19 related restrictions. The peak of the disruption was experienced in April (21% organic reduction) and some sequential recovery in revenue was already evident in May. The order book at the end of May remained broadly in line with the prior year on a like-for-like basis...
It has reduced costs & conserved cash.
Restructuring - a hefty bill here, of £18m, for restructuring & capex, half to be spent in 2020. Good benefits though;
Full year run rate benefits from these projects will be £11-12 million in 2023, with initial benefits in 2020 and 2021 helping to mitigate the demand slowdown in certain end markets and protect the Group's margin improvement plans.
Recent acquisitions are going well. Looking at further acquisitions.
Outlook comments - general, but upbeat.
My opinion - this looks good. Covid is bound to have had some impact, but it doesn't sound serious. The restructuring cost-cutting looks set to improve future profits. I like this - worth a closer look.
.
.
Solid State (LON:SOLI)
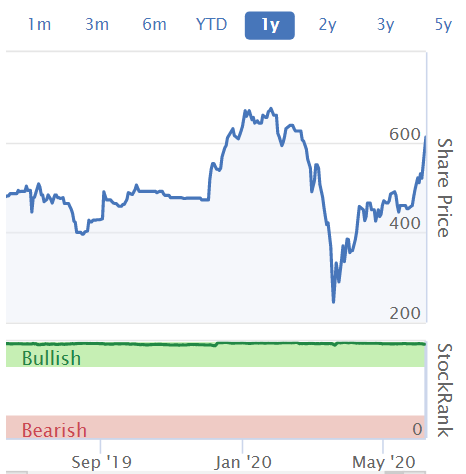
Share price: 625p (up 14% today)
No. shares: 8.54m
Market cap: £53.4m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added distributor of electronic components, announces a trading update and notice of results for the 12 months ended 31 March 2020.
This looks surprisingly positive;
The Board is pleased to announce that trading since the update given on 15 April 2020 in respect of the first two months of the new financial year has been ahead of management's expectations, despite the impact of the COVID-19 outbreak.
Although it sounds as if the company is benefiting from a strong order book which sounds like it is running down somewhat - hence the pain might only be deferred possibly?
We are seeing and expecting some slowdown in order intake but the diversification in our sector and product exposure, and strong open order book, is providing some resilience to the effects of the COVID-19 outbreak.
It says food retail & medical sectors are compensating for slowdown in other sectors (e.g. oil & gas, aviation).
Using technology to win new orders, e.g. online meetings for agreeing design & spec.
Order book is £37.9m, up 6% on last year. Not stated whether this is like-for-like, or if benefits from acquisitions.
Liquidity looks fine - net cash of £4.5m, and unutilised RCF of £7.5m.
Outlook - uncertain. Serves sectors which likely to benefit from Govt stimulus, so well placed.
Dividends - held level with last year. Final divi of 7.25p - sends a strong signal that the business is OK.
Results presentation - good to see that another company has signed up for the Investor Meet Company platform, which I like. A results presentation will be done through IMC on 30 June 2020.
My opinion - I'm impressed with how the company seems to have sailed serenely through this crisis. Although the slowdown in order intake could be seen as a mild profit warning.
This type of company is never going to attract a high rating. The share price has reflected the fact that the company has traded well through the crisis. The price looks up with events now, in my view, so I can't see any point in getting involved at this level.
.
.
A few quick comments to round off, as I need to go for my constitutional;
Actual Experience (LON:ACT)
Embarrassingly poor interim results. Only £972k revenues. It would have to increase revenues by a multiple of 6 times, just to achieve operating breakeven.
This company is a jam tomorrow, heavily loss-making digital analytics business. It told a compelling story when it floated in 2014, but the financial results since then have been pathetic.
It talks about future contract wins in today's commentary, but given the poor track record, who would want to gamble on it achieving commercial success?
Amigo Holdings (LON:AMGO)
Some fractious comments from the outgoing Chairman in today's update. Large liabilities appear to have arisen from customers lodging complaints. Deal to sell the company has fallen through because of the economic situation. Looks very high risk to me.
Speedy Hire (LON:SDY)
April - revenues down 35% vs LY, but higher than expected.
May - activity levels steadily improved (no figure given) as customers resumed activity.
Last week (ending 5 June) - improved to -17% vs LY.
Furloughed 50% of workforce in April, reduced to 33% as at 5 June.
Liquidity looks fine - strong cash collections from customers in April & May, plus Govt support measures, resulted in net debt actually falling 14% to £68m between 31 March to 31 May 2020. Plenty of headroom, with £180m bank facility, committed to Oct 2022. Confirms scenario testing fine, even in prolonged period of reduced trading activity.
Problems at its Geason training business. Trading below expectations, and possible £2.6m claim from a funding body, relating to overpayments & poor financial controls. Probably not material to the group as a whole.
Guidance - remains suspended, due to economic uncertainty.
My opinion - the company really should be resuming guidance by now.
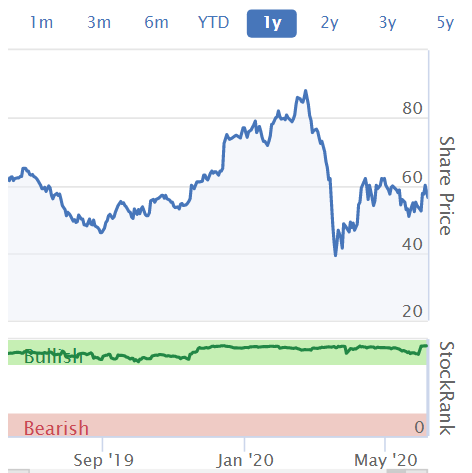
The share price has recovered to where it was last summer/autumn, which doesn't entirely make sense to me, given that the outlook seems far worse than it was then. I suppose it's possible there could be pent-up demand to be unleashed, but given that it's a hire company, lost business cannot be recouped.
It might recover a bit more, but there's probably better upside potential on other shares. The other thing to consider is that a lot of boring companies will probably be focusing more on balance sheet improvement, instead of paying divis. Therefore this type of share is less attractive for investors.
.
.
All done for today. See you tomorrow morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

115 comments
This isn't Facebook and all this nonsensical speculation about covid is hugely off-topic.
Many Happy Returns Paul :)
Sure there is a simple reason, but why does Diaceutics (LON:DXRX) score 0 on all the stockranks?
It’s only been public since March last year may have something to do with it. Nevertheless, I would flag it up to Stocko and see what they say.
Anyone know why £BLV is down over 9% today?
For shorts you can always follow: UKShorttracker on Twitter though I know Paul is no long Twitter.
https://twitter.com/UKShortTra...
Pugh have announced a formal tie up with Estate Agents in UK to securely sell properties that are unsuitable for sale by private treaty or require an immediate, unconditional sale.
It doesn’t seem significant enough to put out as a Begbies RNS and arrived by email as part of Pugh auction info. Pugh have run the last few auctions online with apparently some success and this might have encouraged them to scale up the idea.
One stock where there is a large shorting position...Metro Bank £MTRO. About 9 per cent declared. Beginning to rally today albeit from a very low price compared to one and two year price. (Disclosure; I hold)
Paul
Don't know if this link is any good for your purposes or if anyone else has suggested:
https://shorttracker.co.uk/
Keep up the good work - thanks.
Can anyone explain why there are now so few new virus cases in London - less than 50 a day for the last fortnight
The damage was done in late Jan/Feb through to March. Be interesting to see in a couple of weeks if the numbers can remain flat (here is hoping.
I have long held a suspicion that a lot more Londoners have had the virus, and much earlier than lockdown. Interestingly a business I know in London with circa 65 people did anti-body tests and found that over 60% were positive. Only 2 of those had experienced anything other than very mild cold like symptoms since Christmas. I have no idea how accurate the tests were and clearly a sample of 65 isn't exactly statistically representative anyway but it raised my eyebrows when I heard about it and does make me wonder whether, in London at least, there were a lot more cases than ever reported (me possibly included), which is why we are now seeing such low numbers of cases comparatively. Purely anecdotal I know.
I have no idea how accurate the tests were and clearly a sample of 65 isn't exactly statistically representative anyway but it raised my eyebrows when I heard about it and does make me wonder whether, in London at least, there were a lot more cases than ever reported (me possibly included), which is why we are now seeing such low numbers of cases comparatively. Purely anecdotal I know.
The sample testing suggests about 8% of Londoners have had it. However, I know a couple of business where everyone caught it - basically lots of people in close contact inside all day long. In both cases it was linked back to skiing in the French and Italian Alps, all coming back end of February and early March.
If you think about the differences between how, for instance, Brits and Germans travel to and from skiing it may explain some of the differences - basically we had a lot more cases circulating before lockdown than anyone realised. We then cooped everyone up together at home so we had another spike and it then started to decline from early April as the virus couldn't find new people to infect outside of care homes.
It'll probably circulate at very low levels while everyone is outdoors and then spike again come winter. If they get track and trace right it should be containable outside high density gatherings. That's a big if, though, given what we've seen so far.
timarr
I think this is the big unknown (the actual number of people who have been infected) because of the lack of testing. The only figure that there is any certainty over is excess deaths (and even this might be slightly distorted because of increased efficiency in reporting deaths see (https://www.ons.gov.uk/peoplep...
Beyond that we have very few data points.
I am not the most sociable of people but I know no one who has died from it or who has had serious symptoms but many who think they have had it with mild symptoms).
I am not the most sociable of people but I know no one who has died from it or who has had serious symptoms but many who think they have had it with mild symptoms).
With the reported infection rate of around 8% to 10% then most people who think they've had it haven't. But I know of 5 people who've died of it - all old - 3 people in my +50 age group who've been hospitalised (one very seriously and only slowly recovering) and about 20 people in two connected groups who had it, or at least if they didn't it was some form of group hysteria (the 3 older definite cases were connected). Of the other people 3 of them had it badly enough to be off work for over a month, 2 of them in their 20's.
At this point all we can say with much certainty is that it's deadly for anyone with pre-existing conditions, it's very infectious and you probably don't want to risk getting it if at all possible. As far as I'm concered the longer before catching it the better as the treatments will improve over time, if I happen to be unlucky and badly affected.
But overall I don't think personal experience is a good basis for making judgements about this stuff one way or another. The media is publishing contradictory speculative findings from authorititive figures on an almost daily basis to the point where any of us can find "evidence" to support any point of view we wish to promote.
timarr
hit the nail on the head timarr about contradictory reports. Only today I read two reports from eminent virologists who say categorically that the disease is now far less virulent to those catching it with viral loads on hospitalised patient cases being significantly less than in March. Then I read another report from an equally eminent scientist saying there is no evidence of that! So I guess we now also need to be careful of confirmation bias on our Covid analysis.....who'd have thought :)
Only today I read two reports from eminent virologists who say categorically that the disease is now far less virulent to those catching it with viral loads on hospitalised patient cases being significantly less than in March.
I'm no immunologist but I understood that the viral load is proprotionate to the exposure - so medical staff exposed to multiple cases were at greater risk than the average person which is why the lack of PPE for them in the early stages was so dangerous. If the prevelance of the virus in the community is vastly reduced particularly in situations where it may be re-circulating like company offices then presumably the impact of that would be to lessen the viral load being experienced by sufferers as they will be exposed to it less?
There seems like a large element of magical thinking going on at the moment along the lines of "there are less cases so it's less dangerous". Although given that our PM is on record as having argued that all the money spent on the Y2K bug was wasted because nothing went wrong we should be cautious about assuming people can link an absence of consequences to actions even when those actions are specifically intended to ensure that self-same absence.
timarr
I agree with everything you say (particularly on using personal experience) except
“At this point all we can say with much certainty is that it's deadly for anyone with pre-existing conditions”
The chances of dying of/with Covid 19 (and especially if you are under 60 with no co-morbidities) is vanishingly small.
https://www.england.nhs.uk/sta...
https://www.ons.gov.uk/peoplep...
I am not saying the impact on health is not possibly significant, I have no idea and cannot find data on this.
Michael
Hi Michael
The chances of dying of/with Covid 19 (and especially if you are under 60 with no co-morbidities) is vanishingly small.
Err, yep, but that's (more or less ) what I said - it's deadly for anyone with a pre-existing condition?
To be fair that's a bit of a stretch from the data for under 65's - the death rate is about 1 in a 1000 and 89% of those have some underlying condition. But I don't know what the recovery rate is of under 65's with an underlying condition, so the best we really can say is that's a major risk factor.
https://www.worldometers.info/...
timarr
I think I had it late Jan / early Feb time.
Nurse friend of mine thinks that the recent 'wave' was in fact a second wave.
All anecdotal obvs...I dunno...although on looking at global data it has been my longstanding opinion that reality has long not conformed with model/expectation. I'm not claiming there isn't a problem just that we assessed it wrong. One of the most startling claims I read last week was a claim from senior german medical scientist (I think near govt) that he thinks germans had some form of dark immunological matter that helped them have low mortality rate! Sounds a bit crazy....but then that plus other factors from weather to T-cells to prior exposure to related viruses (Japan) may ultimately describe the variability around world.
Maybe it will come back with vengeance. Maybe it will dissipate away. I think the latter and with that look for a fear-hysteria tipping point ...which is perhaps best evidenced by protests and riots! (A more pressing reality pushed away the unreality)
Riding the #FOMO to #OHNO wave is going to get wilder...
https://time.com/5848949/covid...
This bit is scary:
Another concern, says Topol, is that the virus may be damaging the bodies of asymptomatic in other, silent ways. Among the 331 passengers on the Diamond Princess cruise ship who tested positive but did not have symptoms, 76 people had CT scans of their lungs and nearly half showed signs of lung tissue damage typical of coronavirus infection. “People who are getting infection without symptoms are actually doing a lot of damage to their bodies and they don’t know it,” says Topol. Another small study in South Korea that studied 10 asymptomatic people from a group of 139 COVID-19 patients supports these findings.
Maybe, maybe not.
The story of humans from treetops to skyscrapers is that we have good periods of symbiotic relationship with our diseases and parasites that occasionally get knocked out of whack....but generally we live with and cope with it. Something super deadly and devastating like bubonic plague is the oddity (and impossible of that same ilk in our modern more knowing times)
As the disease/parasite matures its relationship with humans it will find a way to have both longevity (inc dormancy) and not too deleterious an affect (assuming the humans keep equilibrium in other ways eg nutrition)...if it is to be a successful disease that sticks around. Most typically such a disease is likely to be seen as a disease of childhood (like measles) rather than adulthood....here Covid19 is unusual and maybe robs itself of ability to stick around?
The people from Dimond Princess are okay and if healthy will be healing/coping. More important from that story is that a high risk (as elderly) and captive audience didn't have higher mortality (only 1%). It was an earlier indicator that we were overreacting.
I really don't know. Despite a bit of reading I'm not an expert...but my bias is....chill....we're going to be much more normal. And we'll find out soon given all the protests.
...a bit tangental but I think also interesting context...
When tuberculosis first arrived among a tribe of remote Canadian indigenous people it seemed like something else entirely. The infection attacked organs in their body (which didn't happen to whites) Symptoms like meningitis were more dramatic and progress of disease much more rapid than anything European origin populations had seen on TB. Ultimately it normalised into the lungs as we know it and was less deadly. Host and parasite found a balance.
IMO there are hints this may be the case with C19 (not expert and I don't really know...always aware of that but got to look at what's before me and weigh it up). There are hints that in Asia populations dealt with it better (eg Japan) as their bodies had some sort of greater familiarity with the bug. So not immunity but better bodily coping.
This is not an unusual story when a disease common one place jumps somewhere else. There is an aggressive flare phase. In history this was more devastating as simply we tended to live at the edge of existence...our populations would go to the max of what the local biome would support (mainly nutrition) and a disease would come kill productivity and so create malnutrition which then weakened our ability to cope with the disease...until we based out lower and the disease had run enough.
It's burnt itself out. I think there are still a lot in the north of England though.
heron - presumbaly the r0 number has been low enough for the cases to be continually decreasing so they are at such a low level now - this decrease has probably been in place since mid march (possibly earlier).Note i would presume 50 a day is under reporting if thats the offical known cases - the trend is clear though thats its been heading down albeit not as fast as i would like to see. This number does look acheivable/ believable if you look at where Spain / Germany / France and Italy are at now - where they are probably reporting on average well under 400 new cases per day per country. A manageable level to serious target and try and push down to close to nil - ignoring the obvious spikes that may/will happen whatever we do until such time as there is nothing left to go after.
My thanks to everyone who has responded. If anyone comes across explanations they are welcome to contact me at ires@dlmi.ie.
Sorry for going off topic but if the virus is dying out in the western world it helps explain the current strength of markets
Hi heron,
I missed your question originally.
My first point would be that you will not get any particularly insightful analysis on a question like that here.
That observation applies to my comments too, but I'll offer them anyway.
marigold suggests : "It's burnt itself out."
At face value this makes no sense - the highest credible estimate I have seen for total cumulative infections in London is 15% [ONS] that is miles away from "herd immunity". (Other as yet unpublished research suggest that 15% is on the high side).
BUT, what if (say) 75% of Londoners have achieved totally effective social isolation?
15% of total population compared against 25% of circulating population might suggest that of the population that have exposed themselves to the pool of potential exposure. That IS very close to herd immunity.
As we start to unlock though we could potentially exposing a group (of previously locked down) people with virtually no herd immunity to exposure.
Without access to all of the data that SAGE has we are pissing in the dark to be frank, but personally think it will be c. 3 weeks before anyone can claim (using public data_ that the lockdown was well timed.
There is lots of gung-ho non-sense from the Government about having the enemy in retreat; I do actually hope that they are right, but unless the censored data is telling (and if it is why not share?) I worry that this is all bluster.
Off-topic for here of course, so I might also pick it up on the "lockdown" thread over the weekend.
But I was surprised by the figures from Track & Trace today. On average they have found c. SIX contacts per infected person.
That is having spent more than 15 minutes within 2 metres of someone not in your household. WOW1
Personally despite exercising and shopping on a daily basis I don't think I have spent more than 1.5 SECONDS within 2 metres of anyone for at least 3 months.
I would love to get my hands on some data about the circumstances of these contacts - it would be hugely valuable IMHO.
Are you referring to this document:
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/891703/NHS_test_and_trace_bulletin__England__-_28_May_to_3_June_2020.pdf
You have to read what they say very carefully. They contacted 5407 people who provided the "test and trace" service with 4485+551+168+74 = 5278 contacts. That is less than one contact each.
The other 26985-5278 contacts we have no info about at all. But it sounds like the local public health protection teams did the hard work for those.
The contacts which were handed to the local teams were the ones described as "complex" because they involved schools, prisons, hospitals or care homes.
So the new service is not exactly over-stressing itself yet.
For Paul re UP Global Sourcing Holdings (LON:UPGS)
1/3 of staff were furloughed.
Net debt at £2.5m is the interesting figure. I'd guess at the following factors:
1) Senior mgt cut salary significantly and some other employees too
2) Receivables have come in in an orderly fashion (when revenue grows they accumulate debt to finance trade, so when revenue shrinks they should get reverse if other pay up_
3) I don't know how many have been kept on furlough but perhaps shows that govt scheme has a positive cash flow effect for them....this could be as they are a growing company and they have somewhat been recruiting ahead of their current needs in anticipation (they tend to recruit local and on post grad trainee course...most of workforce come this way). So it would be a natural and prudent response to furlough a lot of these people as they are more cost than productive at the moment (being v simple).
Overall, crisis period shows mgt are good, responsive and know what they are doing from product to financial mgt. Interestingly, that they managed to pick up orders quickly could be a hint at taking a bit more shelf space too from competitors if they've outperformed them during the dip.
Pleased that there's no comment on here about the company. Hints that they are not exciting enough or that there has been a lot of sellers. Leaves room for upside surprise.
Revenue will always be a bit volatile as they don't have tied sales agreements with customers...but this is a good thing as it protects their margin. There's a chance that UPGS can be a long term compounding winner (a la Chuck Akre)...they have a niche they know really well and they invest and expand it. There are decent barriers to others copying.
Guess what Mojomogoz? I agree with you!
Wild times. We'd better warn the others ;)
Watch out below
Re not fighting against the market, this has been my mantra for a very long time, so ordinarily I would ride this wave, but I find myself not doing so, primarily because I find this rally somewhat bizarre.
I can only think that the Markets are looking further ahead than they have done so before, as such they are pricing in earnings that are very questionable in my mind, in both the short and medium term. Which arguably, if your investment horizon is long enough, is fair enough, but it does strike me that once earnings are released we may be facing a bit of a tumble. Either because we are over-paying now, and that realisation will dawn within this corporate year, or if we are happy to overpay now, but then the following year will have some odd comparatives to deal with.
I'm sure we are all aware that for some sectors this could well be a dawning of a brand new age, both positive and negative. Also for some it's just a case of waiting it out. But at a macro level, and looking at market performance in aggregate, especially in the US, I can't help think things are getting a little over-heated.
Obviously as Paul has said, who knows, most definitely not me, but for me I'm not planning on any new longs (and for that matter shorts either, I have very recently got my fingers singed), unless the investment case is pretty concrete in my mind.
I think we've done a pretty good job of steering through this nightmare.
Err, completely baffled by this comment. I'm not sure who "we" means for a start. If we means "the UK", then no, absolutely not. We have over 40,000 dead, many others left with life-changing damage to their health, and a huge amount of economic damage , with the country still partially locked down and many livelihoods already lost. Much of this could have been avoided if the lessons of SARS/MERS had been learned, if the country had locked down 2 weeks earlier, if care homes had been properly supported, if Public Health England had outsourced their testing needs, if contact tracing had been expanded rather than being abandoned. An absolute shambles would be a better description.
If "we" means the general population, then we did pretty well at first, until we started packing ourselves onto beaches, and holding protest marches.
I couldn’t agree more but I think that in this case when Paul (Paul please correct me if I am wrong) wrote “we” he meant the SCVR community.
Unfortunately this member failed but am slowly clawing my way back. -20% YTD -1.5 TTM and still 50% cash/gold..
I don’t have the skill or mentality to trade short term and so I am biding my time. I have bought a few small positions but don’t have confidence in the term to deploy all of my cash.
I would concur about the emotional and mental strength to have +/-20% in a day without any news or logic is not something that I can personally cope with.
Add to that the day job, home schooling, elderly parents and the rest of life, taking some opportunities, down on the year, but slowly improving but as you say with baby steps and very small positions and exiting with some amazingly rubbish timing sometimes too!
I presume he means protecting many businesses and workers where the Government has done sensationally well. A lockdown two weeks earlier would not have put businesses or the economy in a better position. On reflection they could have looked after the over 60's which would include care homes and those with health conditions and let everyone else get on with it. The average age of people dead in Italy is 80 with over 90% of them having underlying conditions and no doubt it will finish up pretty much the same here. I know of a food manufacturing company with 500 plus staff and touch wood no reported cases amongst them. A strange pandemic!
A lockdown two weeks earlier would not have put businesses or the economy in a better position.
I'm not sure that's true. The modelling seems to suggest an earlier lockdown would have saved a lot of lives and allowed an earlier relaxation of lockdown.
Th e'modelling' appears to be a dodgy excel spreadsheet! We shouldn't have locked down. Just made sure the most vulnerable were properly looked after. Instead we locked everyone down and failed to protect the most vulnerable.
Thats a top assessment dodge1664
Maybe he means Revolution Bars (LON:RBG) holders.
Sorry, misunderstanding. I should have expressed myself more clearly. I meant the Stockopedia community here, and us navigating through the financial/market chaos of recent months. So nothing to do with what you got indignant about!
Paul, you wrote: When you can't find yield anywhere else, then equities look attractive,
even if they are expensive by historic standards. If interest rates are
staying low forever (which looks increasingly likely), then a PER of 20
is not expensive at all. Maybe we need to recalibrate? That sounds
dangerous, but why fight against reality?
How do we know what the PER is? It seems to me that the historic figures relate to a different world now and few companies seem willing to make forecasts of future earnings. I have read several economists' views that the UK faces a serious recession because of the economic damage done by the pandemic, even if there is no resurgence as the lockdown is lifted. On top of this existing threat, in the short to medium term, the possibility (however big or small) of a resurgence in infections and consequent lockdowns appears to me to be a further downside risk, and so does potential disruption in trade when the Brexit transition ends.
I'm struggling to find countervailing upside possibilities. If the economy and the Treasury can shrug off as irrelevant the creation of billions of pounds of new money by the BoE and it's distribution to enployees and companies, why did we have a decade of austerity, with all the economic and social damage that it caused, when we could just have printed money and ignored the debt and deficit?
So how can the economy just grow back to deliver pre-covid earnings, growth and dividends? And if it can't, how can share prices recover and grow either?
Martyn
Good point! It's all la la land at the moment to me... I just don't get what's happening. Maybe I'm stupid?
I've made some cracking money this past few months with some pretty average recovery type stocks but just feel uncomfortable now... so have gone 90% cash after selling some more stuff this morning.
If I miss out on yet more rises I miss out... I don't really care tbh! If I don't understand something I figure it's best to just sit largely on the sidelines.
As Warren Buffet said: Be greedy when other's are fearful and fearful when others are greedy.
Looking at the current market trend of BUY BUY BUY.... I think people are far from fearful so I'll sit it out for the time being.
Re VTU, I hold Cambria Automobiles (LON:CAMB) and they might also be worth a look/revisit at the same time. I for one would be interested in a comparison.
Birthday greetings to you and I hope you have a good one - 52 -you are only a baby !!!!
My birthday present to you would be a suggestion that you have a look at Thruvision ( LON:THRU) who reported their results for the y/e ending 31/3/20 today . I know they are loss making which is normally against your (and my ) religion - but their balance sheet is strong ( enough cash in the system to last 12 months without any sales at all ) and they are operating in a sector which could benefit massively in the post Covid 19 world . Thruvision is what is left after Digital Barriers sold their video business a couple of years ago for £25 million - after paying off debt the company was left with £17.6 million and having returned £8 million to share holders the balance of aprox £8/9 million was retained in Thruvision . The new company is described this morning as follows
" Thruvision is the leading provider of safe distance, people security screening technology. Using patented passive terahertz technology, Thruvision is uniquely capable of detecting metallic and non-metallic threats including weapons, explosives and contraband items that are hidden under clothing, at distances between 3m and 10m. Addressing the growing need for safe, fast and effective security, Thruvision completely removes the need for physical "pat-downs" and has been vetted and approved by the US Transportation Security Administration for surface transportation. Operationally deployed in 20 countries around the world, Thruvision is used for aviation and transportation security, retail supply chain loss prevention, facilities and public area protection and customs and border control."
Since the change sales have doubled in year one from £3 mill to £6.0 million and from £6 mill to £8 mill in year two , losses have come down from £2.9 to £1.2 million in the same period .Cash has remained around the £8 million mark
Their comments below on Covid 19 are really interesting
"The COVID-19 crisis caused inevitable delays in order flow in the last month of the period but, more significantly, it has had a profound impact on our industry landscape, which is likely to drive long-term positive effects for the Group. Legacy security solutions, such as walk-through metal detectors and traditional airport body scanners, often require close-proximity physical searches to resolve alarms. It is now clear that the security industry cannot continue with such searches, and many organisations are therefore reviewing how they can safely maintain security in the future. Since Thruvision operates at a physically distant range of several metres and obviates the need for physical searches, our 'safe distance' security technology is attracting considerable new interest."
There will be some beneficiaries of the pandemic and I believe that Thruvision are likely (not "will" of course ) to be one of them
Hopefully this can be my birthday present to you
happy birthday
Interesting comments. I think the "safe distance" security angle is currently in the price - the share price has come up a lot recently. The update is cautious on the short term - new orders will inevitable be held up. SP indicates broker forecasts around 11 million for 2021 - covid could have made that a bit ambitious. So, as ever, what price jam tomorrow? (I hold.)
There is a report in the FT that ministers are hoping to reopen pubs and restaurants serving customers outdoors as early as June 22. That is just 2 weeks away, and I have to say is earlier than I was expecting, but a very positive development if true.
I don't know how many sites this would apply to for Revolution Bars (LON:RBG) for example though.
I think we are at a really interesting moment. Strict social distancing has been breaking down for the last 2 weeks or so if the news from the tourist/beauty spots is anything to go by. The pretty riverside village I live in has never been so busy. I would expect to see a huge leap in infections in the last week or so . We are not seeing that so far - nor am I hearing panic warnings of a second wave from the authorities. Says to me the odds are the virus has largely run its course (care homes and hospitals being the exception). IMO we may be back to normal by August.
I live in a tourist town and have just walked back to my suburban home from a visit to the town centre (take away coffees have been doing a steady trade for the last couple of weeks). Having done this trip more or less daily for the last month, I can say that traffic, both vehicular and on foot, is significantly up today. I counted 4 premises having work done (painting or maintenance) that were not there on Saturday. All people around seemed local and not tourists though - no surprise. Social distancing seemed more or less still intact however. Lets see how it works with volume increases.
I cannot see that the government will need to reimpose lockdown. The health system got through the first wave with significant spare capacity so I would imagine that no more lockdown would be necessary in the case of a second wave. Anyway, could the genie be put back in the bottle ?
Against that the government appears to react to ' popular feeling' (focus groups and the media I guess) rather than acting reasonably and in the long term interest so maybe they would try and impose it anyway. Heavens be that we would expect a government to provide leadership I suppose.
I completely agree about the focus group nonsense. I think this will be the nub of the legal action re quarantine being brought by IAG, Ryanair, and Easyjet. It should be an interesting case if it gets to court.
Seeing most retail now installing “Hygiene Shields” at their tills, I did a google to see who actually sells them, with the top result on google coming back for a company called safetell.co.uk.
After some research, I see that they are owned by a company called Newmark Security (LON:NWT)
They have a Superstock label with a StockRank of 90, with Q-V-M ranks evenly above 60. Marketcap of £6M despite Revenues 3* this. Their directors have decent holdings with a buy was last week worth £376,300, with only 1 sell of shares logged in the past 17 years! And the graph shows upwards momentum in my opinion.
My screener had missed this because it's under my market cap limit and the spread is wide but is this an obvious multi-bagger? Am I missing something here? All opinions most welcome. Thanks :)
Re Newmark Security (LON:NWT) - run for the benefit of the concert party? CEO's daughter cost £310k and total directors' remuneration was £633k in year to 30/4/19. For a company that made £220k PBT, that seems excessive.
Re LON:NWT, anybody can buy a piece of Perspex on a table stand and sell this as a protective screen. I wouldn't touch such a small Market Cap company with no Dividend history. How's an investor going to get their money back?
Till point hygiene shields are mostly being supplied by private companies £500k to £40m turnover in the print and point of sale industry. These companies have already existing relationships with the retailers. Screens and face shields have saved these companies lives recently with very low furlough rates!
One issue is that there is now an enormous shortage of PETG, polycarbonate and acrylic sheet material from which the screens are made (routered). Manufacturers of screens are waiting 6-8 weeks for their “rationed” allocation. (I recently retired from the industry after nearly 30 years).
Re Newmark Security (LON:NWT) and hygiene shields: How long is a decent spike in income from extra sales of hygiene shields likely to last? Retailers deploying them will surely want to fit them sooner rather than later, if they haven't already? Granted, a big spike in sales might well still be in full swing since non-essential retail and hospitality have not yet re-opened, but multibagging usually takes time and enduring growth in sales, whilst a rush on hygiene shields seems time-limited to me.
I've no position, but good luck to you if you're on board.
Hi Paul, interested to get your thoughts on management of open positions, you have mentioned quite a few over recent weeks, do you have a number that you would consider optimal? Appreciate this is going to vary dependent on where the market is at.
Also just to note, the SCVR reports have been an excellent resource over recent months, thanks to yourself and Graham.
Good to see that Marks And Spencer (LON:MKS) has now hit and exceeded my target of 120 pence today. A decent rally from the day before the results were released of about 45%. Where next? The market is clearly excited about the start of home food delivery I think and more gains are possible. I now have a target of 150p although in these roaring markets who knows?
To put that into perspective William Hill (LON:WMH) are now above 160p. On 19th March the shares hit an incredible low of just 29p. That is an astonishing rally in less than 12 weeks.
I read today that "the S&P 500 is valued at 23 times this year’s expected earnings, a multiple that was only exceeded during the dot.com bubble" and that nearly every hedge fund manager is nervous and is looking for protection against a heavy fall. Markets are supposed to go up on a wall of worry so more all time highs (as the Nasdaq hit last week) are possible I suspect.
personally I think comparing current share prices to the March low is meaningless as there was virtually non existent liquidity to buy much at those crazy low prices. prices based on thin volumes are not representative prices
Great stuff Paul, on forecasting and NOT shorting anything too. I haven't read beyond your macro analysis yet. But I like your very common sense approach. These are dangerous times. I am building a position in Gold Phyiscal using ETFs, Miners ETF and perhaps some actual Bullion, as well as a bit of Silver in an ETF. Its going to be a very volatile road but I believe there will be significant rewards to come in 12-18 months. Also this Qualitative easing, and Macro economic plays by Govts and central Banks has got to be good for the Gold Bugs, plus its only a small part of my diversified portfolio for the moment. Thank you. Enjoy your long weekend to come and Many Happy Returns!
check £GBSS - an ETF from Wisdom Tree - it is 100% backed by physical Gold and you can even request to have your holding converted to physical should you wish.
Gold trade is old news methinks, risk on means safe safe haven selling to buy assets which generate cashflow
Probably far from over....unless you think that govts are going to withdraw monetary and fiscal supports and raise taxation to fix their balance sheet holes immediately.
So far gold has done really well give extent of risk on and the sharp yield curve steepening (so real rate rising). The level of bullish sentiment has been high but interestingly despite this toppiness gold has not yet fallen to a sharp deep sell off. It might but growth expectations will shift to some inflation expectations and can guarantee central banks will slam the breaks on yield rises (yield curve control).
In many respects its looks as if gold is waiting to make a meaningful move...
Guess it depends if we see inflation from stimulus taking over or deflation from supply and demand pressure and increased leverage from the crisis, I don't have much of a hunch on gold either way but I do think gold will hold up fine. With that said, at this stage I'm more bullish solid free cashflow generative equities.
Maybe check out Royal Mint Physical Gold ETC Securities (LON:RMAP) too, backed by the Royal Mint, supposedly you can still access your gold even if the ETC provider (HAN) goes broke, and they even provide you with a process for requesting physical delivery.
Slightly curates egg-ish update from Amino Technologies (LON:AMO) today - "increased business levels with existing customers", as more people use streaming services, but "new business wins may be delayed in the second half of the year". The company suffered a sharp reversal a year ago, on announcing a shift away from lower margin boxes, and towards more SAAS revenues. This seems to have settled down now, but they will need those "new business wins" to regain a growth rating. Personally I think this company's management record deserves something better than the current rating. (I hold.)
I also hold Amino Technologies (LON:AMO) and like you think it deserves better than the current rating. Today's trading statement is in line with expectations. In the most difficult period for the vast majority of companies it has increased revenue and net cash although some of the revenue will have come from last July's acquisition of 24i which has strengthened the software side.
finnCap has reiterated its 215p target "with the current FCF yield showing the unappreciated value in the resilient model".
re Short Squeezes
Short squeezes have been great trading plays of late
I aggregate the FCA daily short interest data and compare to recent price momentum as an indicator of a squeeze in play.
Below is an abstract of some of the data showing most shorted along with recent price moves and price YTD: the relative price YTD also gives a feel for well the shorters have "fed" and often infers the size of the squeeze that may occur. The moving average data (8, 21, 50, 200) gives a sense of trend : typically it is best to wait for a close or two above at least an 8 EMA as indicative. Finally , volume is important not just as an indicator of the move so far ( a short squeeze will always occur with increased volume), but also of the underlying typical volume: low volume shares can sky-rocket in a squeeze but positions may be difficult to unwind if volume dries up or shorters reharden. These are high risk strategies so need appropriate stake and risk management and good disciplined execution
I've also attached squeezes in the past week that included INTU, HMSO: this scanner did well in identifying these before the big moves
Thank you DSC for this interesting and thought-provoking list.
On a side-note, does anyone have any idea why Croda International (LON:CRDA) has seen a sizeable short interest extending about two years back. There is an obvious logic to the short interest in most of these stocks, but Croda International (LON:CRDA) does not look obvious to me.
Thanks DSC. I agree with Sunday Trader about the difficulty understanding some of these shorts. Why for example are four groups shorting Primary Health Properties (LON:PHP) at the moments? https://shorttracker.co.uk/com...
Why for example are four groups shorting Primary Health Properties (LON:PHP) at the moments? https://shorttracker.co.uk/com...
They are probably also major holders of the convertible bonds. BTW I haven't checked but this is normally the reason for these types of short positions. So it's probably just a hedge and nothing to be concerned about.
All the best, Si
Nice one DS, Ive been doing similar , also keeping an eye on Twitter traffic for newbies trading whilst furloughed who start bidding these up
M&G have announced their holding in NRR presumably picking up from the fire sale at Invesco. There are obviously multiple uncertainties but it gives me some confidence that they are neither going bust and that they will benefit from a significant re-rating. Results due on 18th June.
I like Newriver Reit (LON:NRR) because the market seems to be ignoring the fact that its pubs have strong alternative use value, which underpins the balance sheet valuation, even if they remain closed. There's a very good broker note which points out this anomaly on Research Tree.
The downside worry I have, is that appointing a joint broker recently suggests a fundraising might be underway behind the scenes. If that coincides with INTU going bust, then it could scare off investors maybe?
Thanks Paul. I hadn’t considered the implications of the broker appointment. Have you had any dealings with NRR management? They appear astute operators albeit in extraordinary circumstances.
Might the appointment of a broker by Newriver Reit (LON:NRR) have been the bookrunner who placed the Investco 20%?
Ooh that's a great point, FREng, I hadn't linked the two issues.
www.shorttracker.co.uk
Great, thanks!
Morning Paul may be of interest I have heard from a reliable source that social media influencer's have been earning huge sums monthly for people signing up to share trading platforms via their media sites.
Given that gambling has risen during lock down I would imagine there is an army of amateur traders entering markets for first time bored as a result of lock down probably using leverage also.
Personal thoughts are this event and the central bank trillions are responsible for the fastest bounce back in markets ever.
Enjoy the 52nd they come round far to fast these days.
Paul - re Revolution Bars (LON:RBG), am not trying to be a pedant but don't grasp your point about a scale-back already. There is no change on my dealing account this morning which reads as below, and the last RNS on Friday stated details of the placing & open offer will be released on around today. Am I missing something then ?
Details in my account this morning are :
"Revolution Bars Group Plc has announced details of an open offer. Your account will be credited with a number of entitlements which can be exercised at a fixed price, with no dealing charges, to receive additional shares in the company.
Your account will be credited with 3 basic entitlement shares for every 5 ordinary shares you hold as of the ex-entitlement date, 9 June 2020. These entitlement shares are expected to be credited to your account on or around 10 June 2020 and this will form your basic entitlement, which will not be subject to scaling back.
You will also be credited with excess entitlement shares which will allow you to apply for shares in excess of your basic entitlement but excess applications may be subject to scaling back.
Each entitlement share can be exercised at a price of GBP0.20."
Paul is talking about the placing... which covers the open offer just in case no-one takes it up.
You are talking about the open offer.
So I am being drawn into being a pedant. There are 2 parts to the overall fundraise, a Firm Placing of 45,000,000 shares (without clawback) and a Placing and Open Offer of 30,017,495 shares. Within the 30,017,495 there is the 3 for 5 open offer and a level of excess application which I imagine will be subject to over-application and scale back once actually open.
I see nothing in RNS about allocations in the Firm Placing, and only that details are not yet published for the Placing and Open Offer - hence my question.
Anyhoo, as the institutional Firm Placing does not involve me, and is done anyway, I will simply await notification of my opportunity later today and draw a line under this on here.
Currently 50m shares in issue. Company is raising £15m by placing 45m new shares with institutions @20p (£9m) (the firm placing) and offering existing shareholders the opportunity to subscribe for 30m (3 for 5) new shares at 20p (£6m). Not everyone will take up this open offer for a variety of reasons. However that second part has already been underwritten by certain parties. The firm placing is also now guaranteed. The company has its money. When it is known how many shareholders have taken up the open offer for new shares, those shares will be clawed back from the parties who have committed to the placing (not the firm placing) and issued to the entitled shareholders. In other words these parties have put their hand up and will take up any unsubscribed shares. You won't have any visibility on which instos participated in the firm placing until the usual regulatory disclosures. There will now be 125m shares in issue.
I have a Halifax share dealing account and have seen no Corporate Actions updates for Revolution Bars (LON:RBG). All very puzzling
I have had a Halifax account for a while now and thinking of changing, the crash of the whole system on Friday afternoon was one more frustration which made me put this on my list of things that must be done. They are often very slow on corporate actions and the helpline is none existent currently or over an hour to wait
I have had a Halifax account for a while now and thinking of changing, the crash of the whole system on Friday afternoon was one more frustration which made me put this on my list of things that must be done. They are often very slow on corporate actions and the helpline is none existent currently or over an hour to wait
My N Brown (LON:BWNG) call at 16p is looking pretty good. Unlike you Paul I will look to hold this above 100-150p I think there is plenty in the tank and the company is worth a lot more than the current valuation.
Glad I also ducked Plus500 (LON:PLUS) I was so close to buying and the sudden leave of the CEO completely put me off.
Good morning, Paul. In reference to the most shorted shares, the Investors Chronicle provides a weekly updated list of the 40 to 50 largest short positions in the market. Kind regards Phillip.
Friday's sharp rise in Melrose Melrose Industries (LON:MRO) has the look of a short cover.
Hey Paul - here's what I use for short tracking.
https://www.fca.org.uk/markets/short-selling/notification-and-disclosure-net-short-positions
Like many I continue to run some stock longs with some brakes on in the form of L&G Super Short FTSE 100 (painful last week but I don’t have the guts to double just yet) and gold. Also getting my fingers burned on the Vix but will drip feed in through June. Thanks Paul for SIG and Computacentre!
Personally I’ve found BH Macro to have been a good place to hide ytd but have now taken profits as the premium to Nav adds some potential for whiplash.
However bullish sentiment looks I can’t seem get my head around the apparent detachment prices exhibit relative to 2020 earnings. Tough to read but maybe I should stop trying....
Hi Paul. I think as you've mentioned before the Dow is possibly a bit of a special case. The 30 companies in it are are worth over $8 trillion compared to the 100 companies in the FTSE worth $2 trillion. A lot of the top Dow seem to have done well in the recent environment, as have top British investment trusts, MNKS, SMT, MWY all back to pre corona virus levels and predominantly invested in Dow. Companies in uk have been busy recapitalising and saving cash, not to mention government financial support. So some but not all will be ok. From sky news :- British companies could be saddled with unsustainable taxpayer-guaranteed loans of up to 36 billion pounds as they try to survive the coronavirus pandemic, a report from a panel of business leaders will warn next week. Another bomb shell from BT possibly. Anyone know what old Buffet's being doing in recent weeks, having seemingly sat out the turmoil apart from flogging off airlines? Buying them back maybe? There is an air of caution (Europe new isolated outbreaks of virus and as yet still no definitive vaccine). Not being pessimistic , just trying to be realistic. No doubt planet Dow can sail on. It has to.
Its a view and you may be right. In 12-18 months we will all know perfectly well what we should have done. The journalist will write how obvious it was that such a large stimulus would work...or the reverse, that it would just inflate a bubble in assets followed by a collapse.
For now,
US 10 Year Treasury Yields are rising... to a whopping 0.93%.
The 10/2 and 10/30 spreads are rising.
Oil and Copper have been rising.
Other commodities are mixed.
The $ is weak.
The bond market will worry about inflation before the equity market for obvious reasons. Small cap stocks worry ahead of large cap stocks. High yield will worry more than investment grade.
We have been here before many times in the last decade. 10 year Treasury yields got to nearly 3.2% in 2018 before upsetting the markets. The pace and quantum of debt issued means I would expect fear to set in earlier than 3.2% but where ... I don't know. I suspect that the $ will be important. Why? well weakness is inflationary, so if the $ becomes "too" weak at the same time yields rise...the market will freak quickly. ( Interest rate expectations will spike).
To be clear, at the moment, rising inflation expectations are positive. This trend could fade, yields fall back and economic data soften. The problem investors face is that option 1, inflation picks up and option 2, the economy stagnates ( at best) necessitate quite different portfolios. As Paul says, not only do we not know which... we could stay in option 1 for twelve months before option 2 takes over!
If you decide to double on longs on UK recovery ... I would humbly suggest that liquidity is your friend. Being able to sell if you are wrong. Have a read of the investment letters just posted on GMO website by Jeremy Grantham, a far better investor than me. I would say retaining cash so that you can take advantage of future volatility is very sensible. It feels good to add at the bottom. Within 3-4% the S&P 500 will reach the 100% Fibonacci retracement....having successfully passed the 61.2%. There will be many commentators who expect a pull back around this time... even if that is not substantial, a few months of setting support and establishing resistance could unfold.
I have also closed most of my expensive hedges at losses. The account I use allows me to trade options. Buying calls does have the advantage that you can only lose your premium but participate if the run continues. For some of you this could be something to consider. Im looking to bolster my hedge account with some call trading profits!
Hopefully I am expressing caution without giving the impression I know what will happen. Wishing everyone a profitable week.
Hi RD
Just out of interest which broker do you use that lets you trade options?
Cheers
Hi Ben, I use Saxo Bank via Internax. The saxo platform is very good - execution is excellent. It just doesn't have the coverage in small cap etc. The process to set it up is somewhat arduous so stick with it - its worth. They also do i regular market call podcast which i enjoy.
I agree fighting the markets rarely wise. They seem to be telling us that we'll look back in a year's time and wonder what the fuss was about. Tough to imagine that, living in the UK where we have had one of the worst pandemic experiences in the developed world and where politicians and mainstream media seem to be in the game of inducing fear. Even the most anxious need to answer 2 questions. 1) why has there been no second wave anywhere even in countries which opened up a while ago now. 2) why has the disease stopped in its tracks in big cities like London, NYC and Madrid when no survey suggests more than 15-20% of people have antibodies?
Perhaps R is highly dispersed and a whole bunch of super-spreaders are waiting in the wings for colder weather. But perhaps lockdown and Government intervention are just not that critical and hand-washing and common sense would have sufficed. And then there's the idea now coming into mainstream that as many as 40% or higher of the population have some immunity conferred by cross-reactive T-cells from years of colds and flu.
2 web-sites have been excellent in this crisis: unheard.com and themarketear.com.
This interview from the former worth listening to https://unherd.com/2020/06/karl-friston-up-to-80-not-even-susceptible-to-covid-19/
Nothing certain but roll on the end of lockdown, yes to doubling those recovery plays and look forward to new highs soon. Thanks to Paul and Graham for their help
think that is unherd.com not unheard.com
Major changes at Hurricane Energy (LON:HUR) this morning with the Founder and CEO, Dr Robert Trice, stepping down immediately as well as a nominated director from the largest shareholder Kerogen Capital. It would appear that there have been serious technical differences over the water production (previously described as "Perched water") from the 205/21a-7Z well, (now shut in,) withe possibility of a shallower water contact now being considered. Beverly Smith has been moved up from a non-exec role to "Interim CEO". I worked with Beverly some years ago at BG where she was shown to be very competent both technically and commercially and have every confidence that she will do a good job in achieving the best outcome for the field and company going forward. I hold.
My morning smallcap tweet: Looking grim at LOOK
TT electronics (LON:TTG) Solid State (LON:SOLI) Croma Security Solutions (LON:CSSG) Ceiba Investments (LON:CBA) UP Global Sourcing Holdings (LON:UPGS) Bion (LON:BION) £the g Amino Technologies (LON:AMO) Parity (LON:PTY) Midatech Pharma (LON:MTPH) Crossword Cybersecurity (LON:CCS) Surface Transforms (LON:SCE) Actual Experience (LON:ACT) Lookers (LON:LOOK) Speedy Hire (LON:SDY), Plus500 (LON:PLUS)
TT Electronics (TTG) rev in 5 months to May 14% own organic. Order book at end of May broadly flat YoY. Expanded cost cutting programme.
Solid State (SOLI) First 2 months of FY trading ahead of management's expectations but some slowdown in order intake. "Confident that given its niches in sectors currently in demand and those likely to be in receipt of government stimulus packages, for example transportation and medical, it is well placed to navigate these exceptional trading conditions."
Croma Security Solutions Group (CSSG) covid impact light. Guides FY(June) EBITDA at least £1.6m. The net cash of £2.4m boosted as a result of Government support initiatives.
CEIBA Investments (CBA) Cuba is close to announcing a staged reopening of its tourism industry and national borders.
UP Global Sourcing (UPGS) deliveries since Apr "progressed at a steady pace." Invoice rev UTD down 5%. Guides FY U/L EBITDA above market expectations.
BiON (BION) FY(Dec) rev MYR24m (MYR1.92m). Confident co will have sufficient cash to remain viable in 2020. Some businesses resumed ops in Malaysia.
HUR bad news - well 6 (the good one) water cut 8%. Admits may be oil water contact. CEO sacked.
Amino Technologies (AMO) guides H1(May) up 10%. $3.7m gross cash and undrawn credit facilities of $13m. Increased business levels with existing customers but new business wins may be delayed.
Parity Group (PTY) CFO scarpers. He is thanked and will assist handover.
Midatech Pharma (MTPH) research collaboration with Dr Reddy's, onea global pharmaceutical co.
Crossword Cybersec (CCS) three year contract with Agria Pet Insurance. No numbers.
Surface Transforms (SCE) wins sole supplier contract for Koenigsegg Gemera, a 1700bhp hybrid car.
Actual Experience (ACT) H1(Mar) rev up 2%. Discussions regarding potential new contracts are well progressed. "Material uncertainty" going concern stmt.
Lookers (LOOK) additional procedures needed to finalise the 2019 Results which will not be ready by June 30. Shares will be suspended on 1 July.
Speedy Hire (SDY) Apr rev down 35% but ahead of mgmt expectations. Most recent week in June down 17%.
In line: Plus500 (LON:PLUS)
Super respect to you today Mr C - I've never even heard ofmost of these outfits.
MrContrarian Thanks for the early warning info on LOOK yesterday...... very helpful
Umm, you stated ‘clearly the way things are going’ with a fair amount of certainty!!!
Well yes, because "clearly the way things are going" refers to the Dow having risen from 18,500 to almost 27,000, as stated. That's just a statement of fact, not an opinion! It could change of course. But so far that's what has happened.
Edit - although, please do pull me up, if you think I'm being too emphatic about things! I'm trying to unlearn some bad habits myself :-) Hence there's an element of "memo to self" in the preamble above.
Best wishes, Paul.
Paul, love reading your articles, just being sardonic or facetious (not sure which), but meant as humour.
A great announcement from Croma Security Solutions (LON:CSSG) this morning (I hold).
https://www.londonstockexchange.com/news-article/CSSG/trading-update/14568233
This tiny (£11m market cap) security business appears to have "had a good pandemic". EBITDA to end-June will be "at least £1.6m". By my reckoning, that equates to c.£770m+ net profit, as opposed to the £910k that I was expecting pre-COVID. It also seems that the interim dividend, which was cancelled, is likely to be reinstated.
£770m + net profit against £910k expected is certainly impressive!
Whoops! Too late to edit - will just have to settle for looking foolish. At least Croma Security Solutions (LON:CSSG) is up nicely on the news.
There has been another good update from Solid State (LON:SOLI) this morning, first two months ahead of expectations and recommending the final dividend.
Annoyingly no further update on the year ahead, but that unfortunately seems to be the new normally.
I continue to hold (and wish I had bought more in the dip)
I am not a charter, but do find that http://ichimokutrader.com (Free) helps me interpret the mood in the market. Put simply Green highlighting of the major indices are Bull trends and Red or Pink highlighting are Bear.
I'm hoping we're close to max pain now for shorting dow (me too - very painful lesson not learned again! And ruins all the good work done on mainly good UK long positions over last 3 months in the last 3 weeks!) and that the bears have capitulated so we may head back down now.
Reading about record call vs put option volume in US and the amount of new trading accounts opened punting their brains out on all the big name stocks would back this up. I think we underestimated the power of the Fed and the appetite for stocks in lower interest environment meaning higher P/Es are acceptable.
The job report from Friday was a surprise but we're still at c15% unemployment in US, IF its accurate, the knock on impacts on that will not be seen until salary protection schemes and the like end. I'm the first to think the scaremongering has been very over hyped of a mild respiratory virus but if there is a second wave then with lockdowns ending and mass protests not helping the situation then downside vs upside risk vould well be greater now. With markets near a peak which at the time only in Feb was looking too frothy time will tell.
May I be the first to wish you Happy Birthday! You certainly deserve the break with all the analysis and insight you give us on the small caps and the markets in general. Hope you enjoy the break, you've earned it!. If you are going to double up on your recovery longs, you certainly think the recovery has started and we are not going to get an increase in cases to suggest any more lockdown restrictions.
I'm getting less worried about a second wave of covid, because the authorities are learning what to do - i.e. lockdown vulnerable people, not healthy people, and it would have to be done in specific virus hotspots, not across the whole country.
Plus there do seem to be encouraging signs that some kind of treatment might be developed next year possibly.
This (via an FT comment I read this morning) on second waves from the Centre for evidence based medicine.
https://www.cebm.net/covid-19/...
Nice article thanks.
A Professor of Virology said that it is unlikely that there will be a mutation to a more virulent form of CV19, because of its structure.
There have been lots of small variations of CV19, but none ofsignificance.
The Spanish flu second wave was a different more virulent flu from the first wave, as an influenza virus tend to mutate.
CV19 is a coronavirus and not an influenza virus.
Hoping this pattern continues.