Small Cap Value Report (Thu 10 Dec 2020) - SBIZ, MMH

Good evening/morning, it's Paul here with the SCVR for Thursday.
Covid isn't even touching the sides in Zimbabwe. Please listen to Margaret, who I met in 2019, she's an amazing woman. This is just 9 minutes.
Free Xmas Harp Recital!
A few days ago I promoted Lauren Scott’s (my sister-in-law) online Zoom harp recitals. Unfortunately I think we left it a bit late for the paid-for concerts this year, which have been reduced to just 23 & 24 December, which seems to be when there is demand, there are a few tickets left.
In the meantime, I’ve decided to personally pay Lauren to perform live and exclusively for you, my lovely cultured Stockopedia readers! See it as my Xmas treat for loyal readers here, and a way of helping a talented musician in a year when all her usual gigs have been cancelled.
This special, free, harp recital for Stockopedia readers;
** Saturday 12th December at 6pm, for 45 minutes **
Lauren can only fit up to 100 people on this Zoom concert, so please only sign up (free) if you’re definitely going to attend, as we don’t want a load of no-shows, leading to other people missing out! Lauren only needs your name & email address to send you the Zoom link, that’s it. No spam.
If you like the recital, we’re hoping that you’ll help us spread the word on social media, and recommend Lauren’s Xmas recitals to others. I’m spoiled, because for about the last 20 years, I’ve enjoyed Lauren’s beautiful harp playing in person. It’s a great way to kick off the Xmas season, and singing along with your family/friends is a smashing experience, especially if you get really Christmasy & crack open the mulled wine & mince pies, which is what the Scott family usually do every year! (but not this year).
Harp music is extraordinarily calming, and peaceful to listen to. It’s almost other-worldly in my experience. Whenever Lauren starts playing, I feel the stress just drain away. Ideal treatment for profit warnings, for us investors!
Here’s a reminder (new video below) of Lauren playing Xmas tunes. Like the rest of Xmas, it’s only religious if you want it to be. Personally I’m not religious, but I really enjoy singing along to Xmas tunes, as it reminds me of my childhood, and it’s fun! You can sing along if you want with loved ones (pdf lyrics will be supplied), or just have it as soothing background music, up to you.
Here's a new video (which I've not posted here before) of Lauren playing Silent Night. Feel your blood pressure return to normal as you listen to this! Harp music should be available on the NHS. Actually, Lauren often plays gratis in local care homes (pre and hopefully post covid), as the residents respond so well to it.
Simplybiz (LON:SBIZ)
Share price: 172.5p (down 8% yesterday)
No. shares: 96.8m
Market cap: £167.0m
Capital Markets Briefing & Trading Update
SimplyBiz (AIM:SBIZ), a leading independent provider of compliance, technology and business services to financial advisers and financial institutions in the UK, will be hosting a virtual Capital Markets Briefing...
This was held yesterday, I'm not sure if there's a recording available of it, or not. If anyone finds a recording, please give me the link via the comments below, and I'll copy it here.
Capital Markets days are usually done to drum up some interest for a possible fundraising (maybe for another acquisition?) or if an existing holder wants to sell down.
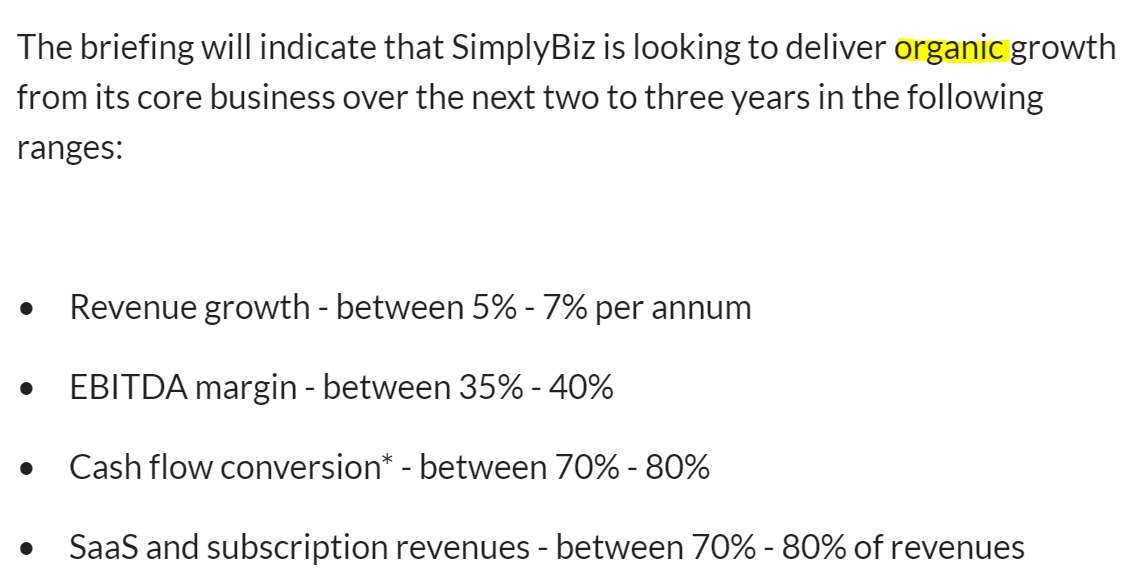
Medium term targets are provided - I've not compared these with actual results, but they look impressive, if achieved;
.
.
Trading update for FY 12/2020 - very clear guidance again, in line with what it's said previously about 11p EPS, a PER of 15.7
• The Board reaffirms, and is confident, that its adjusted EPS will be no less than 11.0p**
• The Board is confident that Defaqto*** will deliver double-digit EBITDA growth in 2020
• The Board announces its intention to propose a final dividend for FY20 of 2.0p per share
*Free cash flow conversion is calculated as adjusted EBITDA, less working capital movements, lease payments, CAPEX, development expenditure, corporation tax paid and interest, as a percentage of Adjusted EBITDA.
** As stated on 23rd July 2020
***Acquired 20th March 2019
As mentioned before, personally I feel divis should be scrapped, and cashflows instead used to strengthen the weak balance sheet (with significant negative NTAV).
Outlook -
... We have an exciting strategy for growth built on firm strategic foundations, and our strong finish to 2020 sets us up well for the year ahead."
My opinion - I covered things in more detail here on 15 Sept 2020 on publication of interim results. My main concerns are balance sheet weakness, and poor cash generation in H1. There was some impact from covid, but overall the business seems resilient.
It's not clear why the company has done a Capital Markets presentation today, but I expect we'll find out in due course - my guess would be possibly a fundraising for another acquisition?
Overall, this does look an interesting group of companies, operating in quite lucrative niches, with lots of recurring revenues. The business model makes a lot of sense to me - financial advisers outsourcing their regulatory & compliance stuff to experts at SimplyBiz. I'm not comfortable enough with it to want to buy any shares, but it's not far off. So it gets filed in my "potentially interesting" tray.
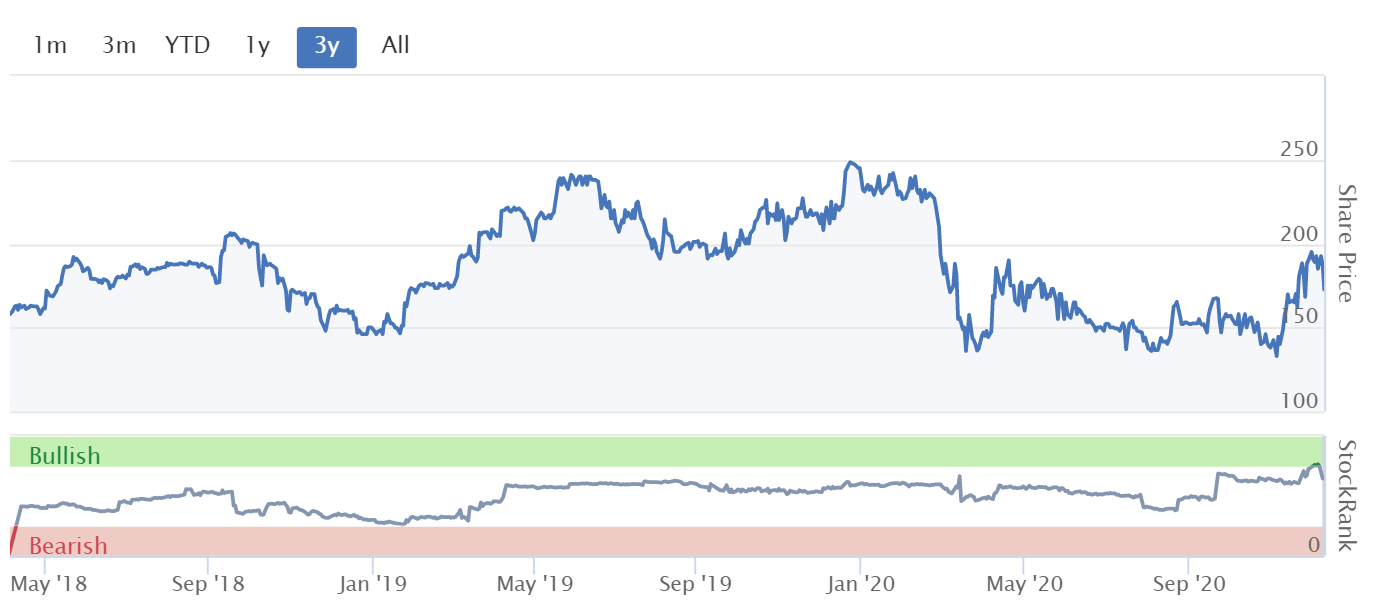
The 3-year chart looks uninspiring. StockRank score looks strong.
.
.
Marshall Motor Holdings (LON:MMH)
Share price: 145p (up c.9% yesterday)
No. shares: 78.2m
Market cap: £113.4m
What a lovely clear update -
Marshall Motor Holdings plc, one of the UK's leading automotive retail groups, issues the following update on recent trading and announces that it is now anticipating an underlying profit before tax for the year ending 31 December 2020 ("Year") of not less than £19m (previously £15m).
That's a good upgrade, coming almost at the end of the financial year.
Marshalls seems to have shrugged off the November lockdown. That does make me wonder, are people seeing cars as a big investment now, or just an affordable item to hire? I was bored the other day, today actually, and almost ordered a Ford Fiesta hybrid on a cheap lease deal (£150 per month) to use as a local runabout. Probably the only reason I didn't hit buy, was I've only got one parking space where I live in Bournemouth, and I wouldn't want to leave a spangly new car parked on the road, underneath trees and seagulls which ruin the paintwork.
Cars are not big ticket purchases any more, most of them work so well, do we even need to test drive them? Just order on the internet, and send it back if you don't like it, that's the way things seem to be going. A new car is now arguably the same as buying a new frock, e.g. Marshalls says;
The Group continued to trade strongly for the remainder of October, benefitting from previously reported sector tailwinds. New retail unit sales were up on a like-for-like basis and significantly outperformed SMMT*-reported new retail market registrations, with like-for-like used car unit volumes also performing strongly.
Whilst trading was negatively impacted by the closure of its showrooms throughout November, the Group was able to continue to operate all of its aftersales businesses, take orders online and by telephone and deliver new and used vehicles through 'click and collect' services. The Group's strong outperformance of the wider new car market continued.
This looks important, as any further lockdowns look subject to the law of diminishing returns, or impact. Something we're seeing in lots of sectors - good businesses are finding ways around lockdowns, and in any case we probably only have a few more months left of covid, so let's look beyond it.
My opinion - there's more positive detail in the RNS, but I've seen enough to say that I think this share looks interesting. It might be something that readers could look into further.
I should mention short term headwinds. As Redde Northgate (LON:REDD) mentioned recently, there is under-supply from Europe (vans mainly, I think), and the press is widely reporting congestion at ports (not just the UK, but more widely), and large increases in freight costs. Those things tend to be temporary, but the UK stock market often reacts violently to short term problems, especially with small caps - because lack of liquidity can cause wild, and completely irrational price movements.
For that reason, I'm adding car dealers to my watchlist of things I'll be buying after Xmas, if temporary supply problems cause a big drop in share prices. It could be a good time to watch from the sidelines, rather than take a risk now, who knows?
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Warming to you - but when was the last time a Sarf Londoner chastised some as a "rascal"?
Horsham etiquette and a refined audience now dictate my language ...you Slag !! :)
WARNING Stocko'sRNS feed seems to have failed this afternoon and I have missed from my list -
AVEVA (LON:AVV) rump placing (I allowed my rights to lapse)
Venture Life (LON:VLG) Slater goes from 5.3% to 15.2% (I hold)
Codemasters Group (LON:CDM) 7 holding RNSs from 11 32 on - last on Stocko 11.29 which puts breakdown at 11 30 (I am reporting highlights of the games being played for a higher bid on the Stock Pitch thread).
I am reporting this via green button
Thanks sharw for the updates because I also hold Venture Life (LON:VLG) & £CDM. Interesting times ahead.
Dear Paul,
Thanks for the link to Zane. I was running Pizzaland restaurants in RSA in the late 70's and many of our chefs were from Zimbabwe (Rhodesia, in those days). Wonderful people , as were almost all of our African staff. I have donated and will do so again.
Before I returned in 1979 I flew to Vic Falls on Flame Lily Airlines Dakota DC3 . The pilot had to spiral down to the airstrip due to the recent loss of a plane to Zambian rebels with a rocket launcher.
In the Vic Falls Hotel on the bathroom mirrors were signs telling you what to do in case of mortar attack. Basicall fall to your knees and crawl into the corridor. A memorable trip.
Wow, thanks alpha2, makes my trip sound like a walk in the park! Thx for sharing/
Blimey ,I thought Croydon was rough !
When I lived in the proper SaarfLondon I always assumed that Croydon was in Surrey.
Behave yourself u rascal ! Born in Fornton Eef and lived in Streatham but kept moving saarf.Now Horsham based.
Agreed, Gromley. Croydon was an exotic place we made a long, slow, journey down the A23 to once in a while for exciting new foreign things like Ikea and trams
Good comments Snoo.
I agree. The websites don't impress me, and anyway, why "gamble" when one can invest and win with the Stockopedia and Co toolkit?
I am watching the charts and volume (in defence) for any sell indications by the big holders.
Minded to set a Limit Order @50p.
Definitely my worst performer at the moment.
SCS (LON:SCS) moves to StockRank 90 today.
Currently 217p +7% on tiny volume.
With this stock and its small volume and horrible spread, we've seen a range of 180p to 224p in the past week..
Stocko says 224p which is back to the beginning of March's price.
An RNS today shows Scion (Bermuda) has reduced from 5.01% down to 4.71%.
Ignore the spread. It's usually rubbish,
Scs (LON:SCS) -> superbly run business. Really like it and owned it for a couple of years from sub 150p when they disappointed post IPO and sold (I think autumn last year) at about 230p, collecting a near 10% dividend along the way.
I sold as I think there's a chance they do something splashy with their cash in terms of an acquisition. They looked at Sofa.com in early 2019 and sensibly got out of the way rather than bid against Mike Ashley. They wouldn't have paid much but they would have needed to commit significant development capital to a sofa proposition outside of their area of competence.
They can grow stores a little bit thro new out of town sites. They are super focused on getting the right venues...this is good but the problem is that there are only approx 30 UK sites they want and they got to wait for their opp to get them. In the meantime they work down leases or exit on some of their less good stores (they went on an ill considered expansion spree in mid noughties and struck a lot of long term leases that still weighs a little in some places).
IMO the thing to focus on with SCS is buy at a price that gives max dividend and then look for a bit of capital appreciation from there. When I bought I felt that there was upside to their House of Fraser tie up (op leverage was coming through) and that management would get round to embracing a share buyback with all that extra cash.
HoF went bad through no fault of their own (...and great mgt by SCS to get out without significant cost) and there is no sign that they will buyback stock (and my suspicion is that they are ambition to buy and expand). When their big private equity investors departed that was great window of opportunity to state they'd return cash. They didn't.
I would love to be holding SCS at the point they announce a major buyback program but sadly I don't feel confident of that. A new CEO may institute that...but given behaviour of mgt and board to date they will perhaps employ someone they view as an acquire and build person.
I guess that the price trajectory will be moderate up but large down on moderate trading disappointment. SCS are perhaps vulnerable to negative impact from post covid opening.
John Auther's excellent newsletter today contained some thought provoking commentary about the potential for inflation to return. This chimed with a similar piece that I listened to recently on a podcast (Tuesday's Money Talks from the Economist Radio - "Will Inflation Bounce Back?").
I'm curious to ask the many knowledgable and experienced investors here how they would approach that threat in order to try to crowd source some ideas for investing in an inflationary era?
Problem, people have been saying this since 2008 GFC and 2012 Euro crisis. Sure it will come back eventually, and there will be people saying “told you”, but it’s just stuck clock phenomenon. Separating those who have the correct understanding of what’s going on from those who sound (and probably are) clever but have it wrong is almost impossbible
History is always a trap as it stunts imagination ;) (I love market and economic history but I do choose to be careless with it)
The answer to inflation comes from focusing on debt first.
We have preposterous amounts of debt. There's zero chance it will be paid back in real terms. They may or may not be paid back in nominal terms. I believe the 'surprise' this time is that many debts, particularly govt, will be disappeared rather than paid back through the amazingly fluid and flexible balance sheets of central banks (they are like magic compared to a domestic or corporate balance sheet).
Usually we learn a bit more each market phase. What has been learned by policy makers and central bankers in last decade post 2008? They fought a debt depression successfully through QE etc but they did not fully prevent economic malaise...the way I think about it is the real economy has had a decade long demi-depression pre covid.
During covid they showed that they have learned the lesson on the real economy and actions were taken in many ways to ensure that policy interventions where direct and into the economy. Things like furlough obviously but CBILS and grants to biz too, straight cash gifts to consumers by some countries (helicopter money), govt underwriting of credit risk, etc
Its a brave new world. 2008 taught us money isn't actually real...if it were then we would have had a massive depression. And 2020 is teaching us that debt is not as real as we assume.
We actually learned this a long time ago:
This was the slow way of making debt not count and it relied on growth plus sustained modest inflation. I'm not saying we'll do exactly the same this time...and I think we might do some rapid debt write-offs...look to Japan and the massive ownership they have of JGBs (they started QE earlier)...might they just effectively write what they own off? Would this be deflationary or inflationary?
I don't know exactly how inflation comes but it must as the alternative is impossible for our societies
(I realise this is too long for IGPJ but maybe some others find it interesting...listening to boring conf call so handy distraction for me)
Hi Mojo good read they are already disappearing debt in the billions as per link below, the figures used to terrify me but with most developed world debt being probably 40% held by central banks my guess is it will vanish as fast at the point of repayment as it was generated to start with. To be fair though at the moment what is the alternative if the B of E were not underwriting furlough we would probably be north of 10% unemployment.
https://www.thisismoney.co.uk/...
I agree clarea....the debt and way of making disappear are far from riskless...but high unemployment and debt driven austerity and deflation is a known super risk we want to avoid.
Some people will say that economies and money operate almost as natural laws so we must pay the inevitable inescapable price which is austerity/deflation....I think this abuse of maths and historicism (a la Karl Popper)
Just got this in my inbox...related tangent...
https://heisenbergreport.com/2...
Indeed, a good read Mojo. Thanks for taking the time to post your views. With this sort jiggery pokery in central bank financing, you can see why people start believing that bit coin is a legitimate asset class. The B of E is the UK's big competitive advance over the European Union countries. They probably know that all to well, which is why a Trade Agreement is proving so difficult to conclude.
Thanks Paul
Hi Paul- have made a donation to Zane and thanks for sharing again and a great charity. Shocked by the govt. actions with pensioner US dollar savings.
Thanks JJB. Every little helps. W e cannot say anything political. ZANE is a totally humanitarian charity. We're just keeping old people alive.
RE SBIZ-i was holder until recently but was totally frustrated by market makers manipulating price on regular basis which would be written down at close of play and written back the following day! This is only holding that i have experienced such write downs.
There is rare news for long-suffering XLMedia (LON:XLM) investors, bumping the share up 14.9% as I type.
* My second largest position, just 2.95% up.
"XLMedia (AIM: XLM), a leading global digital performance publisher, today announces a significant step forward in its stated priority to expand its presence in the burgeoning US Sports market, through the completion, on 9 December 2020, of its acquisition of the sports gaming and sports betting business of CBWG Sports ("CBWG").
CBWG, which was formed early in 2020 through a combination of CB Sports and Warwick Gaming, is a highly successful and fast-growing digital media publishing group, based in the northeast United States, focused on professional and college sports, sports gaming and sports betting. CBWG is registered as a sports gaming affiliate in six states, including New Jersey and Pennsylvania. The business owns and operates the sports and gaming assets CrossingBroad.com, PASportsBooks.com, BetNewJersey.com, EliteSportsNY.com, PromoCodeKings.com and ActionRush.com and already has agreements in place with leading regulated online sportsbooks in the United States. The business also has an agency arm, which partners with leading sports media brands to drive user acquisition in the regulated betting markets of Colorado, Illinois, and Tennessee. Through the due diligence process, management have estimated the owned sites receive around 550,000 visits per month, and generated unaudited Revenue and EBITDA, before founders' compensation, over the trailing 12 months, ending October 2020, of approximately $4.6 million and approximately $2.7 million respectively.
Under the terms of the definitive documents for the acquisition, XLMedia will pay upfront consideration of USD$12 million in cash and issue 7,954,546 new XLMedia plc shares (representing an aggregate value of USD$3.5 million), as well as potential future contingent consideration of up to an additional USD$9.5 million, based on net revenue performance of the acquired business, payable over three years to the end of 2023.
Application will be made to London Stock Exchange for the newly issued shares to be admitted to trading on AIM, and such admission is expected to become effective on 15 December 2020. Subject to certain limited exceptions, the sellers and founders have agreed not to sell, transfer, or otherwise dispose of the newly acquired shares for a period of two years after the closing of the acquisition."
https://www.stockopedia.com/share-prices/xlmedia-LON:XLM/news/xlmedia-plc-us-sports-acquisition-urn:newsml:reuters.com:20201210:nRSJ1956Ia/
So
XLM gains USD 7.3M in revenue
XLM Pays USD 12M and dilutes the existing shareholders by USD 3.5M
Last set of XLM figures says it had USD 27M in cash in the bank
Stocko will have to recompute its data sheet.
UK_Investor_8888
XLMedia (LON:XLM)
Very interesting acquisition that looks right up XLM's street as far as core competency is concerned, in some respects its a shame they need to pay to get this product as its almost the kind of thing one would have hoped they would internally generate as part of their core buisness proposition. I suspect though that the regulation is everything in America - so its probably not quite as simple to set up a money making affiliate in the US as it is in the ROW? - if they are going in tis direction - could they end up with their own sportsbook operation - probably a step too far.
I would be interested in your expectations with regard to earnings potential for XLM next year - it has sort of slipped off my radar recently as it seemed like all the areas where it did earns its cash profits were simply not delivering - the main bod had departed and they kind of seemded to me a bit ruderless with regard to the future? - do you think will they make $10 mill profit next year ?
The potential for recovering former glories and the deep value play here with cash in bank and low market cap do kinda make this a very tempting punt type play. I am trying to limit my punt type invetsments now i am past 50 and the earnings opaqueness here is pretty horrible. I do admire (and i do somewhat worry that you are going big in companies like XLM and Plus which i see as both having red flags in some impportant areas) your Kahuna's for going biggie on this share - i guess the cash pile is the backup plan if the former money making machine is no longer albeit the shareprice has done very well from its sub 20p low point where the risk reward was probably even better than it is now.
Hello Rmillaree. Thank you for your comments, and you did indeed amuse me.
I think you are spot on about The USA. With 50 states and therefore complex law and (LOL) politics, its probably easier for XLM to acquire what they think is a proven winner with "oven-ready" (LOL) profits, than brew their own.
I've also felt the business has been rudderless in earlier parts of this year. I had written to Investor Relations without any acknowledgment of my existence, asking why there was no news releases, no commercial activity, no real turnaround plans in the public domain, etc.
The profit forecasts, and company reports are obfuse to me. It doesn't really tell you what its 2000 assets achieve. Its probable that there is may be 20 big earners and the rest is padding?
This leaves Private Investors simply looking at the figures and metrics we see here in Stocko.
I would NOT recommend this share to others. There are better StockRank, Magic Formula and Piotroski ranking shares to own, and I'd certainly want to own shares on Mr Scott's fine list of winners first of all. The risk reward indeed is diminishing as the price has risen.
I've gone in deep as I was originally interested in this share, 2 years ago, being top of The Magic Formula and StockRank screens. I've managed a bad losing position by rounding down to mere Break Even. I figured it wouldn't drop below 35p for long given its cash and scrap value.
Its the big institutional Investors that control and drive this share, particularly The Mitterand Family's "Premier Investissement SAS".
38% of the company is owned by the 4 biggest shareholders, and so their sells or buys is what drives the price.
When a big player accumulates 1%, there's a short blip of maybe 10% for an hour or too.
I invest with a screen permanently on dedicated to watch the prices, volumes and movements. If I saw it hit an exit point, I'd exit.
PS: I exited Plus500 (LON:PLUS) @1375 (my largest profit taken ever at the time). It hit 1600p, currently 1440p, but the sale proceeds have made easier profits in EVRAZ (LON:EVR) International Personal Finance (LON:IPF) Apax Global Alpha (LON:APAX) Boohoo (LON:BOO) Central Asia Metals (LON:CAML) IG Group (LON:IGG) without the drama, complications, highs and lows.
For me IG Group (LON:IGG) is the more sustainable choice of financial-trickery-sters and my second best share, with Telecom Plus (LON:TEP) from the 2000s in 1st place.
I am sure in the past I read a list of what they owned. You have some very big sites like 101GreatGoals which has some very high traffic. On the other hand there were some pretty bland, cookie-cutter type sites probably getting hardly any traffic.
It is telling that they haven't managed to get the sites re-indexed, personally I don't think they ever will but they can constantly kick the can down the road. Google dislikes duplicate content nowadays, and search algos are rapidly improving to discern good quality and poor quality content. XLMedia has plenty of the latter, and in future I think a lot of clickbaity content will go.
The consideration for these new sites seems quite high, a maximum of $25m. They say the assets are attractive, if you visit the sites I would disagree - basically some thin content wrapped around affiliate links written for the search engines. They are not the 'authority' type sites that I think Google would prefer.
Betting affiliate revenue is extremely lucrative as it can pay over and over if the clients keep on betting, from that point of view I think it's the best vertical for them to go after. But I question whether these businesses are actually worth this type of multiple now - they are entirely dependent on Google and if they are demoted in the search engines get hardly any traffic. Given that, I think they should be valued at much less given the rug could be pulled at any time.
I have to say that as a big football fan I have never heard of the XLM's site "101 Great Goals" nor have I ever read anything about it.
I'm troubled by Xlmedia (LON:XLM) as I'm currently 37 percent down on what is a sizable part of my portfolio having bought more just prior to my finding out that the Google search engine algorithm's had scotched it's business.
My full sympathies Silver Moon re XLMedia (LON:XLM)
The broker target is still 1 dollar (about 75p)
There's 716K volume in the green colour today.
If we're lucky, we may see 50p... then two more hops to the 60p where you get your money back... We are looking for an earnings surprise.
XLMedia (LON:XLM) made $27m revenues in 6 months to 30 June without high Google rankings and no sports fixtures for much of that time. Given the high margins, if they regain their rankings and get a foothold in the US market, things could rebound sharply. I hold, albeit small and tentatively.
Well its a bit of a light news day to day so I listened to the ZANE podcast. I have to confess, that I know a fair bit about Zim and have visited the country. I also, like many of us I suspect, suffer from charity fatigue and am sceptical as to where much of the Africa bound aid really goes. Zim is a remarkable country and I personally found the people dignified, always trying to offer a service (like finding a car parking space) - not for them aggressive begging. I've chosen to make a monthly donation and I hope it goes to helping, in a very small way, them maintain that dignity.
A good choice in stocks Paul and a good choice in Charity.
Excellent comment..I too started a monthly donation a few months ago..Paul Scott has helped to significantly improve my investments..If only 10% of other readers do the same We will really make a difference.
Thanks STOKIE much appeciated, and others.
I was married in Zim and our first child was born there. It’s main asset is it’s people who are uniformly intelligent and hard working . Many have moved to SA where I now live and you can be sure that the very pleasant good English speaking waiter or waitress is from Zim. Many of course are over qualified for the job but have little choice as work is hard to find here.
It’s a tragedy what has happened to a country that used to have a thriving tobacco and tourism industry and was rich in natural resources .
A good choice indeed for the Charity
Oh how lovely, thanks Berksbee.
My visit to Zimbabwe last year, accompanying the ZANE trustees, was an unforgettable experience, hence why I keep going on about it. ZANE is frugal, and the money gets right to where it's needed. It doesn't have a UK office for example, the small UK team all work part-time from home, long before covid made that fashionable/necessary.
As an example, and I hope he won't mind me saying, but coming home, when I was in the business class queue (at my own personal cost, I hasten to add) in Jo'burg airport, I heard a loud voice boom out across the airport, "Oi! Scottie!". I looked round, and it was Tom, the founder of ZANE. He mouthed the words, "You bastard!", accompanied with a broad smile, as he queued with the other elderly trustees for an 11 hour flight in economy, seeing that I had upgraded myself! That's the type of charity it is though - everyone flies economy, if the charity is paying.
Best wishes, Paul.
Beautiful harp playing...Thankyou for posting the link Paul
Thanks Penny!
Character (LON:CCT) surprised aren't up more today. Prelim results were predictably down on last year for obvious reasons but still made 20p eps and really the news was in the outlook section. Coming up to Christmas they are 30% ahead of last year on revenues and even though only in Q1 are now confident they are ahead of market expectations for the full year. Super cash generative with £19m net cash (25% of market cap) and should add another big chunk to that pile this year.
Broker forecast upgraded to 37.6p for coming year but that looks very light to me. 30% increase in revenue even for say just H1 (with no growth in H2) equates to £15m additional revenue and would suggest more like 47-50p+ eps range from what I can make out, so perhaps broker is being conservative and room for further upgrades as year progresses?
Extension and expansion of Peppa licences with Mattel to end 2023 is great and plays into my theory that Character (LON:CCT) are considered best in class and Mattel probably won't take it in-house any time soon but actually the whole product range including own brands appear to be performing very well and now looks much better diversified.
Minimal impact from a no-deal Brexit according to directors
So appears that Character (LON:CCT) may end the year with 125p+ worth of net cash and stripping that out a PE of maybe 6 ? Share buyback programme may also be on the cards by looks of things, which would presumably support. Looks interesting I think.
NB: I hold a small position for me - considering an upgrade in my portfolio weight.
agree with this - and I own - but I would caution that gross margins are down on mix of sales so it may feed to slightly less EPS that that but still.. the potential for a tender is interesting as they are severely hampered by MAR rules on open market purchases
Impressed by the sale of its storage business by CML Microsystems (LON:CML) for $49 million. That is against an EV for the company of £40 million odd, even after the jump in the price today. Storage is roughly half the business, so that leaves the rest of the business pretty much for free. Suggestive of the value lurking in many smaller manufacturing businesses sitting on lowly PERs. I hold.
Christ alive Paul, that Zane radio is a sobering way to start the day, I don't mind saying I had to do some frantic blinking to keep the tears at bay (works for me). Thanks for posting it, I've donated.
Cheers
Chris
Thanks Chris. It's a really vivid account of the situation in Zimbabwe, isn't it. What makes it even more real for me, is that I spent a lot of time with Margaret, last year, and know what a genuine and intense lady she is, helping destitute pensioners every day. She's literally keeping people alive, taking food and medicine to vulnerable people every day, in the back of her clapped out ancient 4x4 (because the roads are so bad), having to queue for hours to get petrol, when intermittent supplies arrive at filling stations which are usually empty.
The ZANE workers couldn't be more hands on. I'll never forget meeting an old boy, Patrick, in Bulawayo, and hearing his story - a proud old man, stick thin, who explained how his 5 cattle were dying in the drought, and his only income was breeding & selling chicken. He'd fought for the British crown in some long forgotten war, and now gets no support whatsoever. Not even basic healthcare. He'd spent half the day walking & on buses, to reach ZANE's office, asking for help for the first time, as he was so desperate. ZANE distributes basic medicines to people like Patrick, who fought for us in the 1950s & 60s.
I'll never forget how calm, polite, and dignified, Patrick was (a trait of many people in Zimbabwe). He agreed to me observing the interview with ZANE's case worker, who treated him gently and with respect. He told us how he had deserted from the army, as he didn't want to fight his own people, decades ago. They put him in prison for several years as a result. He brought his war medals with him, to prove that he'd fought for the Crown. He gave them to me, quietly saying, "you have these". I declined, and gently pushed them back across the table to him, unable to speak - I just didn't know what to say.
After taking down all his details, the ZANE lady conducting the interview, said to Patrick, "I don't know if we'll be able to help you, as we have to do everything according to very strict rules set out by the Commonwealth fund that we manage", for ex-servicemen. "How will you get home?", she asked. A series of buses, then an 8 mile walk, he replied. He was 74, and it was 31oC that day. The ZANE lady said, "Wait here please". She went into another room, and came back with a little cash, saying to Patrick, "This is to pay your bus fares. I don't know if we'll be able to help you or not, but we'll do our best". Patrick quietly thanked her. I don't know what happened to him.
Hi Paul. There is a market for war medals. Maybe you could help Patrick sell his? I only say this as he was about to give them away and I'm guessing that a cash injection would help him more than the medals...
I see the On The Beach (LON:OTB) share price has barely reacted to a pretax loss of £46m in today's results. There must be huge pent-up demand for holidays, and commentators say that household savings are high.
(not a ramp - I don't hold! - I'd welcome others' opinions).
I imagine there is Massive Pent Up demand for everything that the population has not been able to do for 9 months.Although technically we are in a recession we are not really, the government just closed the economy. I am sure that for a lot of products and services there will be no where near enough supply in the short term. There are a lot of people out there whose income has not been affected but whose livestyle has . I can see this causing quite a few social problems when this demand is released but not satisfied. How this pans out from an investing perspective I am not quite sure, i am in airlines,cruises, pubs and restaurants and some retailers bought at fairly low prices over the last few months. Fingers crossed.
I see the On The Beach (LON:OTB) share price has barely reacted to a pretax loss of £46m in today's results. There must be huge pent-up demand for holidays, and commentators say that household savings are high.
The Tui results today (https://www.investegate.co.uk/...) indicate that they don't expect to see "normal" patterns of travel until 2022, which seems prudent and realistic. Tui's already received €3 billion from the German government to keep going which gives a picture of how badly the industry has been hit. However, they've also shut their UK and Ireland stores which will presumably benefit the likes of OTB going forward.
Tui report winter holiday bookings down 82% on 2019 but summer bookings up 3%, so there's no doubt the demand is there. However, the bigger question is when restrictions will be lifted.
Probably the safest thing is to assume that 2021 will be another bad year. Really we shouldn't have allowed overseas travel last summer - recent studies indicate that a majority of the second wave infections came from abroad. However, as of January 1st the UK will automatically be on the EU's no-travel list until such time as infections are under control, so we can't then choose to travel and quarantine - personally I wouldn't want to be booking a holiday until we have visibility of when that will end.
Anyway, I hold OTB and with a cash burn of £2 million per month and £36 million in the bank they ought to be one of the survivors. But I'd be very happy with any kind of profit in 2021.
timarr
I agree. I think there is massive pent up demand for holidays. I know people who have booked already for this year as they are really missing travel. Even viewing 5 day quarantines with tests potentially acceptable. I'm probably similarly minded. As you say household savings are good too. I have a feeling travel will bounce back very strongly at some point this year - maybe Easter onwards.
That said I don't see much value in travel businesses or airlines at present - looks frothy to me. Many, like Easyjet borrowed or diluted heavily and if you factor that additional capital into the share price they are basically trading at similar levels to pre covid, which I find remarkable given the ongoing challenges. Good businesses and long term winners no doubt but possibly ahead of themselves.....climbing the wall of worry no doubt.
I do see value in Avation (LON:AVAP) and Saga (LON:SAGA) though and hold both. The former because it has strong lessees in Asia who focus on regional travel and trades at half book value and the latter because I don't think the cruise and travel business is really factored into the price at all, but is also a special turnaround situation. Avation (LON:AVAP) does need to sort the bonds maturing in May 2021 which it is focused on and I see that as the biggest risk, which I am keeping an eye on.
I have just listened to the broadcast on Zane radio that Paul posted above, and was absolutely appalled by what I heard. I have sent the link to my MP and asked him to do whatever he can to raise the profile of this issue at Westminster in order that the suffering of Zimbabwe residents might be alleviated. If other Stocko subscribers would like to follow suit here is a link to find your MP's email address: https://members.parliament.uk/FindYourMP
Totally agree on the calming and other wordly nature of harp playing. We are lucky to have our own in house harpist and it is a joy to listen to. So wish Lauren all the best with her Christmas shows and hope as many as possible can enjoy them :)
Thanks for the free ticket Paul. I've just signed up. Merry Christmas :)
Hi Paul, thank you for the Xmas concert gift. I’ve just signed up too. Merry Christmas!
RWS is the big one today but possibly too large (£2.2bn market cap) for the SCVR. But it is am AIM stock and widely held in IHT portfolios. Also there is read-over to Learning Technology Group (LTG) which is also an "Andrew Brode" company. RWS is a great example of a small company which has grown to become a world leader - an excellent example to set for many other small companies.
Does anyone have an idea of how a motor dealers margin on a lease vehicle compares to that on a new car sale ?
Please.
The dealers don't really sell cars, they sell finance arrangements. The cars are just the vehicle (pun intended) for them to sell credit. So I assume they make their margins regardless.
Try going in and saying you want to pay cash for a car to see their faces fall.
Didn't realise, but that's so true!
My car term thing is coming to an end so they keep calling me to take advantage of the "equity" I have built in my car.
Saw a car where dealer doesn't offer 0% finance and said in that case I would buy cash. Either they thought I couldn't afford it or weren't interesting in selling the car.
Just read your opener Paul, nice touch and very generous of you. There's more to life than share trading and it's good to lighten the mood with more personal observations now and then, (in my opinion). It certainly makes some of the less polite comment seen in these threads this week seem rather petty. Keep right on Sir!
Thanks Andrew!
There is a webinar today at 12pm with Capita (LON:CPI) Head of IR Stuart Morgan.
Capita is undergoing a transformation under the leadership of Jonathan Lewis who was brought in as CEO in December 2017.
Covid has meant Its been a tough year but progress has been made and the ambition is to return to revenue growth in 2021 in combination with improved margins. There have been some decent contract wins and the orderbook is healthy.
The busines is being simplified with the sale proceeds from non core assets used to strengthen the balance sheet.
Register here: https://us02web.zoom.us/webinar/register/3716058710355/WN_swU59WU8TuyFjs0R5hPnXA
Continuing the motor trades theme Paul please might you take a look, time allowing, at Inchcape (LON:INCH) ? They've issued a positive update this morning with talk of dividend restoration. Thanks, Andrew
I bought a new car from MMH not long ago. Needed one in the next year so bought early in case no trade deal and cost of car would increase by quite a lot. Trade deal not looking too good now so might be difficult to sell cars in a few months time.
My morning smallcap tweet:
[edit to correct Applegreen ticker]Iconic Labs (LON:ICON) Abbey (LON:ABBY) Walker Greenbank (LON:WGB) Bion (LON:BION) Applegreen (LON:APGN) £7IG Active Energy (LON:AEG) Shield Therapeutics (LON:STX) Quixant (LON:QXT) VR Education Holdings (LON:VRE) Wincanton (LON:WIN) Corero Network Security (LON:CNS) McColl's Retail (LON:MCLS) CML Microsystems (LON:CML)
Iconic Labs (ICON) monthly contracted rev now exceed £135k. "Legacy revenues have now largely been dealt with and running costs for the Company are running at a level similar to or less than revenues received." Seeking acquisitions and more partners. Discussions with previous provider of convertibles re settlement of outstanding amounts due which are to be resolved. [SP=0.01 Cap=5m]
Abbey (ABBY) 1575p rec offer, a 1.6% premium, for the 4.38% stub. [SP=1550 Cap=NA]
Walker Greenbank (WGB) new name from tomorrow, Sanderson Design Group ticker SDG. [SP=NA Cap=NA]
Bion (BION) createst solar power subsidiary with a conditional acquisition of solar assets. "With the solar market in Malaysia expected to grow substantially, supported by government incentives, we look forward to expanding our portfolio in this sector." [SP=2.3 Cap=10m]
Applegreen (APGN) possible cash offer of 575p, a 48% premium. Co would recommend such an offer. [SP=NA Cap=NA]
7digital (7IG) became operationally profitable as per mgmt expectations. Detailed update. [SP=NA Cap=NA]
Active Energy (AEG) get US patent for its CoalSwitch process. [SP=0.55 Cap=8m]
Shield Therapeutics (STX) alongside ongoing discussions with potential licence partners co will explore the potential launch of Accrufer in the US by Shield itself. Would need $30-40m to reach cash positive. Talks with lenders and has received a number of term sheets on acceptable commercial terms. Co's cash runway extended into Q2 2021. All sounds a bit squeaky bum. [SP=103.02 Cap=121m]
Quixant (QXT) guides FY adj pretax at least $1m on revenue of at least $61m as trading in its core gaming market exceeds expectations. [SP=135.3 Cap=90m]
VR Education (VRE) ENGAGE released on Apple App store. ENGAGE is a next gen comms platform which provides meetings, events, training and remote learning solutions within virtual reality. [SP=15.1 Cap=37m]
Wincanton (WIN) wins multi-channel contract from Dobbies garden centres. No £££. [SP=245 Cap=305m]
Corero Network Security (CNS) wins orders of $3m in the first two months of Q4. Rev recognised over the lifetime of each of the contracts. [SP=8.5 Cap=42m]
McColl's Retail (MCLS) guides FY(Nov) rev up 2.3%. Margin cut from product mix and covid costs knocks adj EBITDA (pre IFRS16) down to £29m to £30m (£32.1m). HQ sale delayed to Jan but 1/3 of cash received. In FY21 expects LFL growth to moderate and sales mix to normalise. "We expect our strategic focus on the larger convenience store format, such as Morrisons Daily, to drive incremental sales in grocery, fresh food and BWS in particular, providing opportunities for sales mix improvement." [SP=30.6 Cap=35m]
CML Microsystems (CML) to sell Hyperstone storage division for $49m. Expected to close in the first few weeks of 2021, subject to regulatory approvals and other customary closing conditions. [SP=274.1 Cap=47m]
Good morning Paul
Thanks for the heads up regarding REDD, should I read your opinion as the possibility of price drop with REDD in the short term?
Any share that has had a big rise could possibly drop back with little reason. That is how the market works. However, taken from the recent report there does not appear to be significant risk of profits being impacted and indeed they finish by mentioning an opportunity. This is a company where I am hoping the share price will be significantly more over the next year or two.
"Impact of the UK leaving the European Union without a new free trade agreement
The Group has planned for the potential impact on its business of the UK leaving the European Union without a new free trade agreement in place. The greatest risks identified would be a disruption to the supply of new vehicles and vehicle components imported into the UK from the EU, including additional import costs which may be imposed:
o Around 90% of vehicles purchased or leased by the Group from UK OEMs are imported from the EU. Assurances have been sought from these OEMs, who are confident that there will be no material long-term disruption. Any potential short-term supply disruption can also be mitigated by the Group itself, by slowing the rate of vehicle de-fleets in order to maintain vehicle availability for customers as has been seen in the response to COVID-19.
o Components for vehicles manufactured in the UK are also imported from the EU. However, normal OEM stock levels are considered to be sufficient to address any potential short-term supply issues and we are in active discussions with FMG RS suppliers to ensure continuing supply.
o The introduction of import costs could potentially create some margin pressure in the short-term. However, the Company believes that in the medium-term, it will be able to pass through to end-users any significant additional costs that might be imposed on imported vehicles.
A potential upside for Northgate in the event of supply disruptions or higher purchase costs, would be the likely increase in rental demand and stronger residual values that could result".
Hi Mnachiappan,
I have absolutely no idea what share prices will do in the short term! Anything can happen.
I take a long term view, and focus on fundamentals. This can (sometimes wildly) diverge from short term market sentiment.
So if you're looking for trading tips, this is the wrong place!
Best wishes, Paul.
Thanks Paul, I am relatively new to markets and very new to Stockopedia, I am trying to make sense of what I read and hence my question might have sounded a bit silly, never mind, thanks