Small Cap Value Report (Thu 10 Nov 2022) - BME, TTG, NXR, SMV, PCF

Good morning, it's Paul & Graham here! Today's report is now finished.
Agenda
Paul's Section:
CEO Interviews - people seem to be finding these interesting, so I've lined up 2 more companies to interview tomorrow. Please remember these are definitely not recommendations or tips. I'm just flagging up companies that seem to be trading alright in the current difficult circumstances, and seem sound on long-term fundamentals. Some will be right, and some will be wrong, inevitably, as I cannot predict the future. So please DYOR - remember we just flag up lots of ideas here, but it's up to each investor to apply your own filters to our ideas, and select the things that float your boat, with your own insights & more detailed research.
Virgin Wines UK (LON:VINO) - this has bounced a fair bit recently, so the opportunity might have passed. But I did flag it here on 28 July, and again here on 1 November, as a share that looks potentially interesting. The key question I'll be exploring, is whether it can weather a recession whilst still keeping its subscribers?
Norcros (LON:NXR) - perpetually cheap, but with known issues. Is it too cheap now? See section below for my review of its interim figures. I think NXR shares are looking attractively cheap now, and providing a nice dividend yield. Although a large recent acquisition has increased net debt significantly. Overall though, I think the low valuation means it justifies a thumbs up on valuation grounds.
B&M European Value Retail SA (LON:BME) [no section below] - one of the mid-cap retailers I keep an eye on. Interim trading update today for 6m to 24 Sept 2022 looks pretty decent. Profit guidance is maintained for FY 3/2023. Q2 much better than Q1, and current trading in Q3 is good. Divi maintained (decent yield of c.5%), and net debt seems reasonable. Profits down on pandemic-boosted period, but still strongly up on pre-pandemic. As a value products retailer from large sheds, I think this company should fare well. The shares have bounced strongly recently, but still look sound value. [no section below]
Graham's Section:
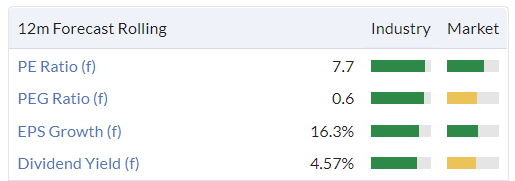
TT electronics (LON:TTG) (£263m) - a solid H2 update from this provider of electronic components. Revenues have shifted higher, as anticipated, but the important book-to-bill ratio remains over 100% as old customer orders are replaced with new ones. Inflation is being passed onto customers and financial leverage is being reduced. And yet the share price is down by nearly 50% since the high it reached last year At a PE ratio of only around 8x according to Stocko, I think these shares could offer nice recovery prospects when sentiment in small-cap equities eventually improves.
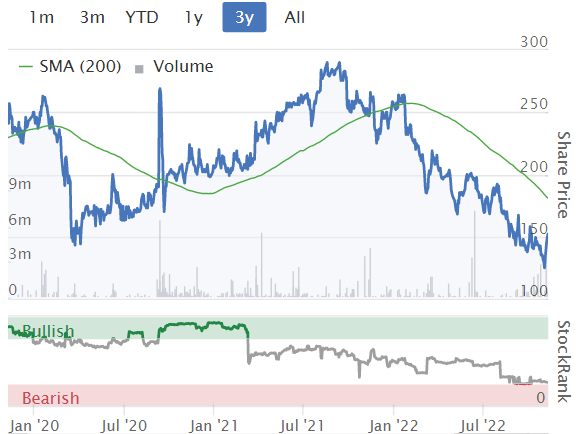
Smoove (LON:SMV) (£22m) - poor H1 results from this company. It owns and runs websites that make the home buying process easier, but recently its activities have been led by the remortgage segment. This is low-margin work. When combined with an increase in administrative expenses and revenue growth of only 4%, the underlying loss doubles in H1, compared to last year. I remain interested in the possibility that Smoove’s growth initiatives might actually work, as it also has £17m in cash to help support the valuation. £5m will soon be returned to shareholders. I’m neutral on this share but I could quickly turn bullish if there is some more positive news from the company, or if the market cap gets much lower.
PCF (LON:PCF) (£1m) [no section below] - I thought I’d provide a short note on this failed challenger bank. It issued a statement yesterday that appears to spell the end: the additional “growth capital” it wanted has not materialised, and so it will “commence a process of withdrawing from the UK banking market”. The loan and savings portfolio will run down, and the AIM listing will be cancelled. I previously thought that PCF’s problems were unfortunate symptoms of over-expansion and some bad apples inside the company. However, I think we also have to consider the role played by the majority shareholder, Somers (a Bermuda-listed investment holding company). While I’m under no illusions that they are a charitable enterprise, it’s gravely disappointing to see them allow PCF to delist and to see PCF’s minority shareholders left with no bid at all for their shares. There were only a few warning signs at PCF to get out before the whole thing fell apart. But perhaps I should have been more wary of the presence of a majority shareholder whose intentions and whose influence on the company were unclear. In the end, the majority shareholder has enabled a situation where PCF’s shares are deemed almost worthless by the market: a sad end to what looked so promising, just a few years ago.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Norcros (LON:NXR)
181p (up 3% at 12:49)
Market cap £161m
Norcros, a market leading supplier of high quality and innovative bathroom and kitchen products, today announces its results for the six months ended 30 September 2022.
'Resilient performance reflecting strength of business model.'
The headline figures look pretty solid. Given macro conditions, I’m not expecting companies to be reporting earnings growth, and nor is Mr Market, judging by how beaten down so many share prices are, in anticipation of a slowing economy & hence falls in profit.
A few key numbers -
H1 revenues £219.9m (up 21% vs H1 LY)
Underlying PBT £19.9m, down 5%
Statutory PBT £14.0m, down 21%
Adjustments of £5.9m are £1.0m pension admin costs, and £4.9m acquisition-related costs (seems a lot. But note 4 explains that £3.1m of this is goodwill amortisation, so that’s OK to ignore)
Diluted underlying EPS 17.8p, down 11%
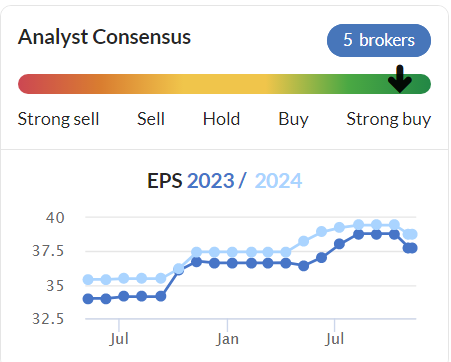
Full year broker consensus EPS is about 38p, which looks consistent with H1 performance.
Interim divi of 3.4p is up 10%, and well-covered by earnings. Total divi yield is close to 6%.
Presentation slides are here, under “Latest downloads”
Balance sheet - NAV is £214.5m, but this includes £108.1m + £68.0m in intangible assets (relating to acquisitions). Eliminate those, and NTAV becomes a fairly modest £38.4m. Although there is an argument for also eliminating the deferred tax liability (which relates to acquisitions - see note 6) which would boost NTAV by £17.3m to £55.7m, which is getting more sensible for the size of business.
Working capital looks healthy, with current assets of £229.1m, less current liabilities of £121.6m, giving a surplus of £107.5m. The current ratio is strong at 1.88.
This is financed with £90.0m in gross bank debt, in non-current liabilities.
Bank facilities mature in Oct 2025, and there’s decent headroom on a RCF of £130m (plus £70m accordion). I wouldn’t want to see the company draw down any more on this, and hope they reduce bank debt as we are probably entering a recession.
Interest charges seem to be at floating rates (per note 8), which could mean finance costs increase.
There was £31.1m in cash, so net debt looks more manageable at £58.9m (at end Sept 2022), but it would be nice to see that coming down in a slowing economy, rather than more acquisitions being undertaken, just my opinion, you don’t have to agree!
Prior to the big acquisition of Grant Westfield, NXR had reached a net cash position of £8.6m at end March 2022.
Cashflow statement is dominated by a large acquisition, with a £78.3m cash outflow for this, partly offset by a £18.1m equity raise cash inflow.
Pension scheme - the problem here is that the numbers are very big, running into hundreds of millions, so only small movements in asset or liabilities can make a big difference. My main worry with big pension schemes at the moment, is that the real world value of assets (often heavy holders of bonds) has plummeted recently. Whereas liabilities may have technically fallen (because they’re valued using bond yields), but the real world liabilities haven’t fallen at all - they still have to pay out to pensioners, and with higher inflation, those actual liabilities have gone up, not down. This makes me very wary of any company with a big pension scheme.
NXR says its accounting valuation on the pension scheme is in surplus, although that has deteriorated from £19.6m at Mar 2022, to £8.2m at Sept 2022. Sounds harmless, a surplus.
I tend to look for the actuarial calculations, as that is what drives real world cash payments into the pension scheme. At the end of note 3, it says that pension fund deficit recovery contributions in H1 were £1.9m. That’s about 10% of underlying PBT, so it looks a relatively minor problem. I would just discount the PER by 10%, to allow for these manageable pension recovery payments. Or if we include the £1m admin costs onto that, the total looks to be about 15% of adj PBT. Not ideal, but it seems OK, nothing to panic about, unless something extreme happened with asset values or assumptions. If interest rates come back down again next year, but asset prices remain depressed, that could be a problem.
Valuation - there are no broker notes available on Research Tree. Although Stockopedia does have consensus figures based on 5 brokers, as follows -
.
At 181p/share currently, that gives us a PER of only 4.8
Why is it so cheap, given that the pension scheme doesn’t seem to be much of a problem? Maybe the market thinks earnings could drop below forecasts, in a recession?
A big chunk of the business is based in South Africa, which makes some UK investors nervous.
Net debt of £59m is 37% of the £161 market cap, so has to be taken into account with valuation.
My opinion - this looks oversold to me.
I like the group’s strategy, of growing by reasonably-priced acquisitions, which then dilutes the problems (like the pension scheme) over time. That strategy seems to be working.
The problem is, with its equity valued so low, Norcros can’t issue much equity to fund deals, as that would be too dilutive. Plus it’s at the top end of what I’m comfortable with on bank debt.
Overall, I think this is a decent business, and the current valuation looks too low to me. The downside risk is obviously that earnings could plunge if we go into a deep recession here, and in S.Africa. So we all have to make up our own minds on whether the low valuation factors in that risk adequately, or whether it’s better to sit on the sidelines and wait to see how things pan out? Your money, your choice! Sometimes, being bold in downturns can produce excellent long-term results.
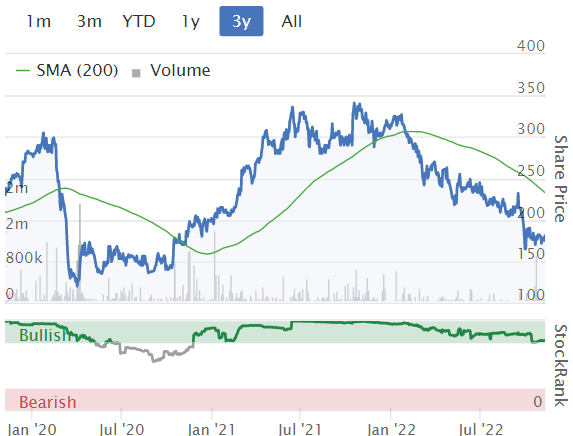
See below, the StockRank has been very high for the last 3 years, so the Stockopedia computers like the data. I'm happier when my own stock ideas also have a high StockRank.
.
Graham’s Section:
TT electronics (LON:TTG)
Share price: 149p (pre-market)
Market cap: £263m
This electronics supplier issues an update for the four-month period to 29/10/2022. It is in line with expectations.
Revenue growth has accelerated, as expected. Year-to-date organic, underlying revenue growth is now 18%. This metric was only 8% in the interim results, so that’s a very significant movement.
Book to bill is the ratio of orders received to orders fulfilled and billed to customers, and is a useful indicator of future revenue growth. In simple terms, it measures whether or not the order book is increasing.
This ratio cooled down to 106% in the four-month period (it was at the lofty heights of 144% in the interims).
But the key point is that despite very fast revenue growth in the period, TTG’s book-to-bill remained over 100%. This means that the company was not simply running down its order book as quickly as possible, but was also replacing the orders it fulfilled with new ones!
For the entire year to date, book to bill is now 127%, which I would say is still a very healthy level.
And as noted previously, the company is passing inflation onto customers:
Global supply chain constraints persist alongside continued inflation pressure from wages, material costs and energy. Prices are under continuous review to recover these costs; the ongoing nature of inflation dynamics will mean some lag in recovery.
Balance sheet: net debt was last seen at £142m (including leases), which looked on the high side to me. The company says today that it remains on track to achieve a leverage multiple of 1-2x by year-end, in accordance with its previous guidance.
This leverage multiple is defined as net debt (excluding leases) divided by adjusted EBITDA. A multiple of between 1x and 2x would normally be considered modest, and I think it’s important they achieve that.
Outlook
Despite the challenging backdrop, given the strong performance of the Group, we expect to report adjusted profit before tax in line with the Board's expectations for the full year, with benefits of foreign exchange offsetting the headwinds from increased interest costs.
The CEO says “While mindful of the wider macroeconomic backdrop, the continued growth in order book extends our visibility of revenues for 2023.”
My view
The company helpfully informs the market that it believes the adjusted PBT expectations to be between £35.4m and £39.8m.
For a company that is apparently firing on all cylinders, enjoying a positive book-to-bill ratio despite fast revenue growth, and passing inflation onto customers, perhaps the market isn’t giving it enough credit?
Let’s remind ourselves of the borrowing situation: as of June 2022, the company had £267.6 million of total borrowings. Of this amount, £75m was in the form of medium-term notes at a fixed rate (average rate 2.9%). These notes don’t worry me at all.
The company’s major source of borrowing is an RCF. This charges a floating rate of interest and I’m looking forward to seeing how much of it the company can pay off by the year-end. When they don’t need to worry about paying a floating rate, that will be one less headwind to deal with in this environment.
Overall, I do think that these shares could be undervalued at current levels. To me, it looks like a decent-quality company with an ability to pass on inflation to customers (albeit at a lag) and with a management team that does attempt to earn a respectable return on invested capital for its investors. So I think this one could be worth investigating in further detail.
Smoove (LON:SMV)
Share price: 35p (-3.5%)
Market cap: £22m
This company, formerly known as ULS Technology, owns eConveyancer, DigitalMove and Legal Eye. Today it issues interim results for the period ending September 2022.
The stock came to my attention due to it having a £20m cash pile as of last March (currently £17m). The company is about to launch a £5m tender offer to return some cash to shareholders.
But unfortunately, there is little to cheer about in these numbers. The company made an underlying loss before tax of £3m (H1 last year: £1.5m), “reflecting increased investment in eConveyander and new product areas”. Revenues were up 4% to £10.6m.
Operationally, there are a range of growth initiatives to offer some hope of an improved future:
- The remortgage segment on eConveyancer was developed and took up a larger share of instructions (remortgages are low-margin work but are very busy right now)..
- Smoove Start has been launched.
- Smoove Complete is launching, too - this is “a co-working platform that is designed to bring together self-employed conveyancers”.
In an acknowledgement that the recent rate of losses is unacceptable, the company has carried out a series of cost reduction measures. It announces today that its administrative expenses peaked in Q1 and “are expected to decline continuously into the first half of the next financial year”.
That’s important, because it’s much easier to make a case for owning these shares on the basis of the cash balance than it is on the basis of business performance. Having said that, I do find Smoove’s growth initiatives intriguing and I’d like them to succeed, to improve the homebuying experience for everyone!
Outlook
Signs of a slowdown in the property market are starting to emerge, as banks take a more cautious approach to lending and potential home buyers delay purchases… the outlook for house prices and transaction levels is less certain than before.
Our new propositions, Smoove Start and Smoove Complete, are performing ahead of our expectations and have very exciting prospects. The Board believes that these new propositions will make the Group more resilient over the long term by diversifying sources of revenue. Our future investments in these businesses will be subject to continued validation of market demand for the propositions.
My view
The slowdown in the property market is a concern but other important factors are at play here.
With costs reducing, growth initiatives underway, and a very strong balance sheet, I’ll take a neutral stance on this share for now.
I’d want to switch to a bullish stance if the market cap slipped below its cash balance without any deterioration in trading, or if we get a trading update or results statement indicating that the company has stopped burning its cash pile.
Note that when the £5m tender offer is complete, the market cap here should have more to do with the valuation of the business, rather than the balance sheet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Just a reminder that the two day Mello London conference is next week and the companies presenting and speakers including Ed and Graham from Stockopedia are listed here https://melloevents.com/mello-...
Nasdaq now up over 6%, not sure what it will finish up at. Some good news for a change.
This lower inflation rally is messing up my entry points. Having to pay 5% more than when I researched the companies on my buy list the day before!
I was buying this morning before all of this hype and I must say it was a pretty painful experience, not sure whether the last few weeks were the end of the dead cat bounce, and I was buying at a high....I had to go and walk the dog to get some prospective.
Keep some powder dry, take some profits along the way, one swallow does not make a summer.
Me too, almost everything on my watch list is on the first page of Market Advancers this afternoon and the one I have been dithering about the most Integrafin Holdings (LON:IHP) is up 9.9% today. Travis Perkins (LON:TPK) was down 5% at one point on Hargreaves' screen, as I type it is up 6.9% so an intraday swing of about 12%. If this is a sign of a sea change I need to scrap my dividend screens and go back to growth. We shall see.
It's a bear market rally. CPI still too high, so FED will raise rates again although maybe not sharply.
Time to selectively take profits imo in the next few weeks. I'm only looking at companies with a decent cash balance and negligible debt.
Public sector strikes are doing enormous damage to the economy and the shock to companies is still to be revealed. Yes some inflationary pressures are coming down but energy likely to go up substantially next April as will mortgage rates with BOE likely to hike next month again.
I cannot understand why an extra bank holiday was declared next May. Surely another day without GDP contribution is unaffordable in the current climate?
Some Prefs mentioned here a few days ago are looking tasty and I've added a couple of them.
GLA
Container rates are certainly reducing back to normal levels so that’s another pressure point in inflation reduced .
Obviously a lot to get excited about in the number. In the short term I imagine a fair bit of hedging still needs to come off. Expect VIX to continue to fall. Importantly MOVE (bond vol) which has been extremely elevated all year can also continue to fall. What does this mean?
Don't expect all the price moves to make sense... as shorts rush to close now since the scope for meaningful negative surprise has vanished short term. However this is an opportunity to square your book... if it suits... we have all made mistakes this year. If you haven't positioned yourself for next year then the net week or two is a great time.
In the first week or two of January there will be a fair amount of volatility as companies come clean about earnings. In fact, I would be rushing those statements out now... there is even probably a little window to raise some money for decent businesses. There is no point starting the year with stocks you want to be out of.
Furthermore you could easily find some of the very sensible stocks actually comes under pressure. Dependable earnings will remain attractive next year... as we speak eg Imperial Brands (LON:IMB) under significant pressure.
For me personally the weaker Dollar is what Ive been hoping for... but it does mean big $ earners come under pressure and favours 250 over FTSE. Its pretty good news for metals, precious metals and emerging markets.
Crazy day...best of luck out there.
Inflation read in the US has come in well below consensus. Looks like it may have rolled over. Can see a big rally coming. US 10Y now below 4% !
Yes, some manufacturers are rising nicely, Volex (LON:VLX) on the up
I feel this could be huge. Inflation was the underlying driver for recent bear market - if this is now finally easing then we could see a huge relief rally, perhaps even like we had when the first vaccine was announced.
agree. If investors start to believe the US can hit a soft landing there could be a very big risk on rally - wouldn't surprise me if that were the case to see a 50% retrace of losses for the indices to end the year maybe circa 10% down. A single reading unlikely to make that happen but if the data consistently starts to support the narrative it could.
We could see a huge relief rally, perhaps even like we had when the first vaccine was announced
Powell will stamp on that, albeit more rhetorically than with another 75bps. The Fed needs financial conditions to stay tight for a while longer
Split Government in the US could also mean tighter fiscal policy over the next two years though, giving the Fed some leeway.
Just because inflation momentum looks to be petering out.. The next question is how low can it get? Can it go back to the norms over the last few years, of 1-3%? Or will it stay stubbornly high at 4%+?
Investors are celebrating today as though inflation has just been struck a fatal blow and on its way to dying. But that's not a given... In one scenario it could decrease but then due to second order inflation stay stubbornly high at 4, 5%. Which will mean rates need to stay 4-5% for longer, maybe past 2024, 2025. And surely equities will go cheaper if that is the assumption.
All that is true and in the short term the Fed will want to avoid the risk of “doing a Volker” and easing too soon, only to have to push rates higher still if inflation resumes. Today’s exuberance is understandable and even justified to a limited extent. But we are still some way from a definitive pivot and only a week or two from Powell’s “rates will have to stay higher for longer”, which I’m guessing they still will.
The question of course is whether markets are prepared to look sufficiently far into the future to see beyond the eventual pivot. And will the Fed even allow that to happen? I fully expect the various Fed governors to come out in force over the next week or two to try to dampen spirits.
what you should remember about inflation is that it rises very quickly but also falls very quickly. That is why investors generally care about it rolling over. Bond markets are generally quite good and they are peaking at 4.6% in the 1Y and down to 4.2% in the 3Y now. 10Y back to 3.8%.
Markets have not been going down because of inflation in recent months particularly. They have been going down because investors think the FED have been too aggressive and will cause a major recession, possibly global. Signals that this will ease pressure on rates significantly increases the chances of a relatively soft landing. It's the shape of the recession people are generally worried about.
Todays numbers will make the FED re-analyse. Not because the numbers came down but because they were way better than consensus. If that data is accompanied by softer jobs data the FED will know they are at the aggressive end of the strategy, predominantly because the data they are looking at is a lagging indicator.
I doubt markets go up in anything like a straight line from here but the signals are that the current pricing of impending doom is likely to have overshot a bit so markets should retrace some of those losses before find equilibrium.
Indices rising sharply, US inflation data positive!
"There were only a few warning signs at PCF to get out before the whole thing fell apart. But perhaps I should have been more wary of the presence of a majority shareholder whose intentions and whose influence on the company were unclear. In the end, the majority shareholder has enabled a situation where PCF’s shares are deemed almost worthless by the market: a sad end to what looked so promising, just a few years ago."
Absolute poetry Paul but of course in the end the benefit of hindsight can only be claimed by self deluded smart arses!!
PCF is one of Graham's, not mine. Paul.
Bank of Georgia (LON:BGEO)
Read a lot of comments about geopolitical risk but risks shouldn't be considered in isolation. People often say "oh I don't invest in xyz bank because of geopolitical risk but I do invest in abc bank as its in the UK"
A few things to consider
Lloyds bank : share price in 1994 52p : 2012 38p : today 42p
HSBC : share price in 1994 220p : 2012 577p : today 473p
Bank Georgia : share price in 2012 680p : today 2500p
One has 14% compound growth annually over the last 10 years (excluding dividends) and now pays a dividend of around 8.5% and still only trades on a PE ratio of 4...........the others, well...........!!!!!
My point being think about risk holistically (including geopolitical).
I've held Bank of Georgia (LON:BGEO) for the last 10 years - I don't find many shares with that level of compound growth but I continually hear a lot of people say "oh I'm not interested in holding them" but then take much higher levels of risk to achieve much lower levels of return (or worse - boom to bust)
From memory, Bank of Georgia demerged Georgia Capital and adjusted for that the equivalent 2012 price would have been even lower.
correct - you got a one for one holding in Georgia Capital (LON:CGEO) in-specie so really the price is around 3200p and around 17% compound annual growth over 10 years. Very good return
Regarding Virgin Wines UK (LON:VINO) , Naked Wines (LON:WINE) , Laithewaites, Averys and various others: I've had plans, subscriptions etc with virtually all of them over the years, but then I joined The Wine Society (a mutual organisation/non-profit - you have to buy a 'share' to become a member) and rarely buy wine from a shop now, let alone any of the aforementioned companies...I know it's not directly investment related, but The Wine Society's definitely worth checking out if anyone likes their wine! (postage is free too for any number of bottles, often with next day delivery in their smart branded vans - just to show the neighbours that you might have a problem ;-) https://www.thewinesociety.com/about
What mjgfs said.
The wine starts at ~£7 but is generally better than the £7 supermarket wine.
The share is redeemable on death (!) - mine is currently worth £18.76
I find it very pleasing to be part of a non-mainstream capitalist enterprise, there are not many genuine mutuals around, there seem to be more on the continent.
and they do very little discounting.
And their wine tasting dinners are like the 1960s. If you can remember them you weren't there.
Due to too much wine..or boredom? Serious question btw as never been to one, but was considering it...
I'm a member of The Wine Society and now broke!
Definitely a trend going on here for me. Buy a share and watch the price go down.
Buy a case of wine and watch the contents go down.
Happy Days.
Try to stay positive and not drown your sorrows!
It's not the shares I worry about....It is the diminishing supplies of Rioja that concerns me. They have sold out, I will have to start on their extra strong Gin.
On a positive note the markets have just gone bonkers .
Shares in the WIne Society also accrue value. A notional profit in all your purchases gets added to it (not clear on the detail). So the more you buy (drink) the more it's worth. The catch is that you can't cash it in. It's only repayable on your death. So your heirs may be able to inherit not only your fine wine cellar, but a bit of cash to go with it!
Paul - I have held Norcros (LON:NXR) for several years and think they have built an increasingly solid business. They have grown, diversified and added better potential brands through small, friendly add-on acquisitions in areas very close to a single central competence in 'bits for Bathrooms' and they still have plenty of room to grow steadily if not spectacularly in markets they are already in, especially given their focus on NPD and sales network. Growth has also diluted their pensions overhang and the cycle of cash generation funding the next acquisition is working well. The latest buy, Grant Westfield, looks a case in point. South Africa is also doing well although some political risk obviously remains and obviously a cyclical down in UK construction /RMI would hurt. But I enjoy my divis and expect to continue to collect them even through a recession (although I applaud their focus on getting debt down fast again as the priority).
My key worry is what is their plan if there is an issue with sourcing from China (eg trade war, China invades Taiwan) - I see no back up sourcing / re-shoring preparations and it is easy to see trade frictions and taxes on China imports growing.
Hi Zipmanpeter,
Great points, thanks. I'll probe mgt about China a bit more closely, when I interview them tomorrow.
I usually google abbreviations that I'm not familiar with. But for your "NPD" all it comes up with is - Narcissistic personality disorder
That doesn't seem to fit the context, so I'm guessing you meant something else?!
Regards, Paul.
That would be New Product Development for NPD
NPD = New Product Product Development (apologies for jargon ) For a boring bathroom products supplier they always promote this in presentations and whether the level is distinctively high within the industry or not, I think it is a good focus to have. If snr mgt talk about the need for NPD, then it tends to happen.
My other Q might be around - if they really want 50% non-UK sales, where do they see this coming from - more S.A. and Eire sales don't really diversify from now. I'd like to see a foothold established in a European market like Spain somehow and leverage recent Merlyn and especially Grant Westfield acquisitions - the latter to become a leader in the emerging wall panel segment which I expect is not so well developed there.
Lord Wolfson of Next (LON:NXT) is always worth listening to. Noteworthy that on the BBC's Today programme just now he said that the UK's migration policy needs fixing fast as there are too many vacancies in his industry which is stunting growth.
lord wolfson was a vociferous supporter of brexit - guess that hasn't helped..
https://www.bbc.co.uk/news/bus...
Summarised here.
Lord Wolfson of Next (LON:NXT), grumpy5 you say he is 'always worth listening to', referencing labour shortages flowing from Brexit. Lord Wolfson voted for Brexit, that was about (i.a.) immigration , but now he sees the consequences he says 'this is not the Brexit I want'. Oh yeah.
I checked their job vacancies, many low-skilled jobs which presumably he wants to fill with (cheap) foreign labour. There are four in my area, all 'Team Members, all part-time and the hourly wage offered is £6.89 to £9.50, I ask: who wants to work for that! A few hours each day, 3 hours, you get £21 deduct travel cost and you end up with perhaps £18 for your 3 hours. The national 'living wage' is £8.90. He's got to get real.
Spot on!
Not sure if I have ever seen it covered on the SCVR, but interim results from Young & Co's Brewery (LON:YNGA) appear upbeat, especially given the current economic climate. It is in my view the pick of the 'pub' operators, with a mainly freehold estate of223 good quality managed houses, 37 of which are also hotels. It declared an interim dividend of 10.26p up 20% from 8.55p.
The share structure is somewhat anomalous in that it has both voting and non voting shares, the only difference apart from the price is that one carries voting rights, obvious perhaps! Beyond that they confer the same benefits in terms of dividend and other financial metrics. The non-voting shares trade at a discount to the voting shares often by as much as 40%. I own the former. At last night's close the voting share were 1000p or thereabouts and non- voting 600p
The nearest rival is Fuller Smith & Turner (LON:FSTA), but Young & Co's Brewery (LON:YNGA) is my preferred pick by some way. Both have much smaller market caps that their overly indebted contemporaries. Needless to say the shares have been battered
Not sure if Paul/Graham are inclined to take a look?
How interesting, thanks Jonno.
We don't seem to have covered Young & Co's Brewery (LON:YNGA) before, I'm not sure why. Possibly because of the strange shareholding structure.
You make a good case for it though, so I'll add that to my list of things to research, although it might be too tight to squeeze it in this week, as I have to prepare for the next 2 CEO interviews tomorrow.
Thanks for posting, we love it when readers flag up interesting companies that we might have missed, and give a helpful synopsis, as you have. Much appreciated!
Regards, Paul.
Cheers Paul, I would be interested in your views or those of Graham, when and if time permits.
Hi Paul
I highly recommend you mystery shop a few Young & Co's Brewery (LON:YNGA) pubs, they are excellent. I've used them for years. Drinks, food, staff, environments are all excellent, and ofen have a great backstory to them.
A particular USP of theirs I think is that they hold freeholds to several truly charming riverside pubs along the Thames.
They have other pubs not on the Thames, but these riverside ones are special IMHO.
Historically they had their brewery - The Ram Brewery - in the center of Wandsworth, consequentially there are many Young's pubs in South West London.
This is a great location locator, with sensible selectors to help find what you are looking for.
https://www.youngs.co.uk/our-p...
I'm not a holder of £YNGA but an enthusiastic customer, these are my locals ....
My closest https://www.youngs.co.uk/our-p...
My close river pubs ...
https://www.dukesheadputney.co...
https://www.boathouseputney.co...
https://www.boathouseputney.co...
I'm happy to treat you to a meal and beer if you were to try any of these, and explain what I consider to be the USP's of £YNGA :) Lol
EDIT: Note there are two classes of share Young & Co's Brewery (LON:YNGA) 1060.00p with a 333bps these are voting shares, non-voting shares Young & Co's Brewery (LON:YNGN) 604.00p 68bps ... if you compare these two charts over time you will see they can diverge quite a lot. Indeed looking at a compare over the last year it is almost as though they performed in opposite direction to each other. Could almost suggest buying them as a pair to spread risk whilst capturing the divs. I'm going to look deeper.
Regards
Howard
Cheers Howard,
As you say Youngs pubs are well maintained and very pleasant places to enjoy a pint and a bite to eat. Like Fullers they tend to be a little more expensive than other operators, but as with most things in life, you get what you pay for.
All the best
Do Young & Co's Brewery (LON:YNGA) still allow all shareholders to drink unlimited beer at their AGM? A dedicated band of people used to own a single share then turn up at the AGM for a drink every year.
Bank of Georgia results highlighting that the Georgian economy is very strong with 10% growth .
Be interesting how the market reacts, Unfortunately I sold 70% of mine 3 weeks ago at the bottom of the trough so timed that one very badly .
Having said that I’m not interested in holding too many bank shares as I prefer simpler companies that I can understand .
Georgia capital looks to be rerating after it’s results.
Despite the supposed geo political risks I think it’s a reasonably simple and logical move to invest in a country showing 10% growth as opposed to most others in negative growth / recession .
Results at Manolete Partners (LON:MANO) affected by the recent adverse judgment (which it is appealing) but interesting to see that it is piloting a Bounce Back Loan recovery scheme
"Commenced BBL pilot with Barclays Bank covering 102 potentially unlawful BBL cases. Early results are impressive, and we are engaging with the other main BBL lenders. While there can be no guarantee of further cases from these sources, we believe that the recovery data from the pilot will be instructive as to how the Banks and the UK Government can maximise recoveries from the minority of companies that abused the various Covid financial support schemes."
Paul Hill interviewed Steve Conklin of Manolete and discussed the Bounce Back Loan recovery.
He said they are straight forward cases where quite a few recipients haven't spent the money but need a prod. This has involved statutory demands and compulsory liquidation but expect settlement/recovery times of around4 months. Recovery after IP costs appear to be split 50:50 between Manolete and the government. It seems a streamlined process and Manotele are one of the only companies that can do this at a cost that makes it viable. Barclays are happy and have received a 6 figure recovery sum.
https://www.voxmarkets.co.uk/a...