Small Cap Value Report (Thu 13 Feb 2020) - FLO, DOM, ACSO, HYNS, FEN, FLTA, KEYS

Good morning, it's Paul here with the SCVR for Thursday.
No lengthy preamble today, as I was too tired last night to write up anything, and lacked inspiration on topics.
Estimated time of completion: 1pm
Edit at 13:04 - today's report is now finished.
It all looks really boring today, so I'll try not to let my lack of motivation show! In fact, it is worth putting in the effort ploughing through lots of apparently boring companies, as occasionally a nugget of gold is unearthed.
Coronavirus update
Reported cases in China have shot up overnight. The website I follow (after I verified it's from a trustworthy source, essential these days in the era of fake noooz) showed a jump to 60,332 cases (59,807 in China) this morning. 24 hours earlier it was showing c.45k cases. Although the 15k jump overnight could be due to changes in how the numbers are being calculated in China. It's been previously reported that the Chinese were under-stating cases, by reclassifying some outside of the reported numbers. Plus of course there could be any number of milder cases where people don't seek any medical help at all.
Edit: the BBC website confirms that the way cases are being reported in China has indeed been changed, hence the big jump overnight. It also points out that this has thrown trend analysis into chaos. End of edit.
I'm conscious of the fact that we're talking about a situation with horrible human consequences. Please take that as a given in the discussions here, nobody needs reminding of that, I'm sure we're all concerned. We have to focus here on the impact to businesses, and shares, because that's the topic here. It's probably the biggest single risk factor to markets & the economy right now.
The overnight jump in cases, even if it's due to a recalculation of the numbers, clearly moves this issue up the priority list, and has slightly dented futures overnight.
I remain of the view that markets seem far too sanguine about coronavirus, and it could cause a lot more disruption than is currently factored in. Particularly in the US, where amazingly markets are hitting new highs. They must just see the virus outbreak as a temporary & remote issue that doesn't affect them. I'm not sure that is correct, but time will tell.
It seems to me that this is probably a time to be cautious. After all, equities are generally expensive, some very expensive, yet there is a serious risk to health, and hence economic activity, globally. To my mind, that makes risk:reward look adverse. Hence I think it's possibly too soon to go bargain hunting for shares which have been hit by coronavirus fears.
Flowtech Fluidpower (LON:FLO)
Share price: 101p (up c.4%, at 08:55)
No. shares: 61.2m
Market cap: £61.8m
Trading update & restructuring activities
London: Thursday, 13 February 2020: AIM listed specialist technical fluid power products supplier Flowtech Fluidpower (LSE: symbol FLO), is pleased to announce the following unaudited update on its performance for the year ended 31 December 2019 and to the period up to this announcement
No surprises here, as the company warned on 2019 profits on 14 Jan 2020. I covered that here, and note that it hit the share price by 20% on the day, to 101.5p. Today's price is slightly lower, at 97p, no bounce as yet. Edit: while I was writing this section, the share price has started rising, so I've amended the header above. End of edit.
Re-reading my previous notes, the key issue here is whether recovery in 2020 is going to happen, or if the deterioration in trading from H1 to H2 in 2019 is setting the scene for further weakness in 2020?
I've checked through the numbers given today for 2019, and they're all at, or very close to, what was guided in the update on 14 Jan 2020, therefore no issues in the numbers, which are;
- FY 12/2019 revenues £112.5m
- Underlying PBT £9.0m (8% margin - not bad for a distribution business)
- Net debt £16.6m
Fairly decent numbers there, it's still a nicely profitable business, despite the profit warning.
Can any readers who know this sector well, explain what this means below, as I have no idea what "cyclical services associated to our OEM business" means!
As the year progressed, we saw a significant slowdown in some of our key end markets, most particularly cyclical services associated to our OEM business, which culminated in the profit downgrade of 14 January 2020.
Restructuring - cost-cutting was mentioned in the last update. More details are provided today, which looks like a strategy of centralising warehousing & dispatch into fewer, more efficient sites. Cost savings of £1.6m are indicated, at a cash cost (exceptional presumably?) of £1.8m (of which £0.5m has already been incurred in 2019). That all sounds sensible. After all, a payback of just over one year, is a very good return. That's providing the cost cutting actually delivers the intended savings, which is not always the case.
This bit sounds interesting - it sounds like there's plenty more scope for further cost savings;
Importantly, we believe there is further scope for significant cost savings, particularly in warehousing, our procurement activity (where we expect to take the number of suppliers down from over 1,000 to around 500), and the centralising of certain back office functions.
We might question why management allowed the business to be inefficient in the first place? It grew by acquisition, so it makes sense to me that cost-savings could then be achieved by combining acquired businesses, and making efficiency gains. That's a good reason for an acquisition strategy.
Balance sheet - this has been one of my main concerns in the past, so this section is music to my ears;
2019 was a year in which great emphasis was placed on working capital and net debt management. Despite the disappointing trading outcome, net debt reduced by £3.3m, after paying c.£2.6m in earn out considerations relating to historic acquisition activity.
A combination of strong operational cash flow, the absence of any further payments of deferred consideration, and the continued focus on working capital, should see our net debt reduce again in 2020 and 2021.
That's excellent. It also gives me comfort that the group can continue paying generous divis, which I questioned in the past.
Outlook - we've previously been warned that H1 2020 would be soft, so no surprises here.
Isn't it refreshing to read a company statement where they just tell it like it is? This is impressive clarity and sensibly guiding investors to take a cautious view of the short term. I wish all companies would report like this.
The actions we are taking to reduce costs, and the investments we have made in our central platform will continue to strengthen and streamline the operating efficiency of the Company. At this stage, we expect revenue for the full year 2020 to be down by low single digit percentage points, with a weak first half largely offset by a return to growth in the second, leaving underlying profit at a similar level to 2019.
A return to revenue growth in 2021, coupled with further planned cost savings, should deliver significant leverage to both margins and profit.
There's always the danger that H2 won't recover as planned.
Dividends - policy unchanged, final divi will be up 5% on last year. The yield is stand-out, at almost 7%. I'm gaining some confidence that this might be sustainable, because of the focus on cost savings & working capital.
My opinion - I'm very impressed with how this statement has been couched. It comes across as straightforward, tell it like it is - which is always the best approach in the long run. Honesty is the best policy! Congratulations to the company, and its advisers (Zeus, finncap, and Tooley Street Comms). I think investors appreciate straightforward guidance, as it builds trust, hence making investors more likely to buy the shares.
Overall, I give FLO a thumbs up, it's growing on me.
Despite current soft trading, management seem to be doing all the right things. A period of soft trading can actually be helpful, if it's temporary, as that prods management into stripping out inefficiencies that were tolerated in the good times perhaps. Post-restructuring, there should be a more efficient platform for future growth. More acquisitions would probably follow, once everything has been sorted out, and debt reduced.
.
Domino's Pizza (LON:DOM) &
Possible read across to Dp Poland (LON:DPP) ?
Proposed disposal of Norweigan business
I mention this, because it details the terms today of DOM's exit from the consistently loss-making Norway operations, via a sale of DOM's 71% stake, to the minority shareholders.
Dominos Norway made an underlying loss of £6.6m in FY 12/2018.
Sweden is also mentioned, DOM seems to be taking full control of this as part of the transaction, but I found the announcement rather complicated, and not clearly explained, so I might have got that bit wrong.
This bit could be of relevance to Dp Poland (LON:DPP)
The Transaction follows the announcement of 17 October 2019 regarding the Group's intention to exit its directly operated international operations in an orderly manner, and find more suitable owners for these businesses.
To my mind, that seems to remove the possibility that Domino's Pizza (LON:DOM) might bid for Dp Poland (LON:DPP) - the independent & separately listed loss-making Polish operation, which I frequently criticise here for its dismal financial performance over many years.
It's interesting that Domino's couldn't make its operations work financially in Norway either, which apparently consumes the highest number of pizzas per capita, of any country in the world.
I don't see a positive outcome for DPP - it's incapable of generating any profit, so what's the point in it existing? DPP's equity is likely to end up being worth zero, in my view. Unless there is a significant turnaround in performance, which has been elusive over the last 10 years.
Today's news re Norway reinforces the fact that Dominos just doesn't work in some countries.
Accesso Technology (LON:ACSO)
Share price: 482.5p (up 10%, at 09:34)
No. shares: 27.6m
Market cap: £133.2m
RCS - Positive momentum with renewals and new contracts
This is an "RNS Reach" announcement - i.e. it's non-regulatory. RNS Reach announcements are marketing messages, so should not really be price sensitive. Today's 10% price rise suggests that some investors might have mistakenly taken this to be a positive trading update, which it isn't.
It starts by saying;
accesso Technology Group plc (AIM: ACSO), the premier technology solutions provider to leisure, entertainment and cultural markets, saw positive momentum in 2019 with several noteworthy customer renewals and 43 new or expanded ticketing contracts.
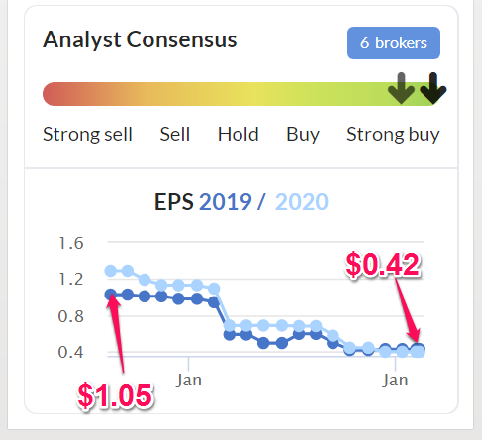
That's very nice, but if it was such a good year, why did broker consensus earnings expectations more than halve in 2019? Note also how brokers gradually reduced 2020 forecasts even more, from a premium, to a slight deficit on 2019 forecasts;
.
It goes on to mention some client names, and client loyalty, cross-selling, but again, it's not reflected in the numbers, is it?
I don't like positive commentary, when the facts have been deteriorating. It strikes me as dishonest & manipulative.
The CEO, Steve Brown, says;
"Our range of products continue to deliver powerful business results for our clients around the globe, paired with highly personalized service and support from our exceptional staff. These contract wins and renewals reaffirm the strength of our product offerings, underscore the confidence our customers have in our solutions, and start us off with forward momentum in 2020."
My opinion - Accesso has always looked an interesting company, dominating its niche. The big drawback, is that it's never really made any proper profits/cashflow. Also, the company put itself up for sale, after some bid approaches, and nothing came of it. The inevitable conclusion is that possible buyers ran their slide rules over it, and were not prepared to pay a premium price, despite the share price having crashed heavily.
The problem with this, is that we don't have adequate information to assess the value of the company. It might be that bidders made indicative bids, but the price wasn't high enough for management to recommend it to shareholders? Or the bids might have been non-existent, or below the current share price? This is crucial information, which management is withholding from us. Therefore, we can't sensibly value this share without that key information.
Instead of today's puff piece, I would have preferred a statement from the company telling us, "We received indicative bid interest at xxx-yyy p, but after consulting major shareholders, decided not to proceed with a sale". Something along those lines, which would allow us to benchmark the value of the business to bid interest levels.
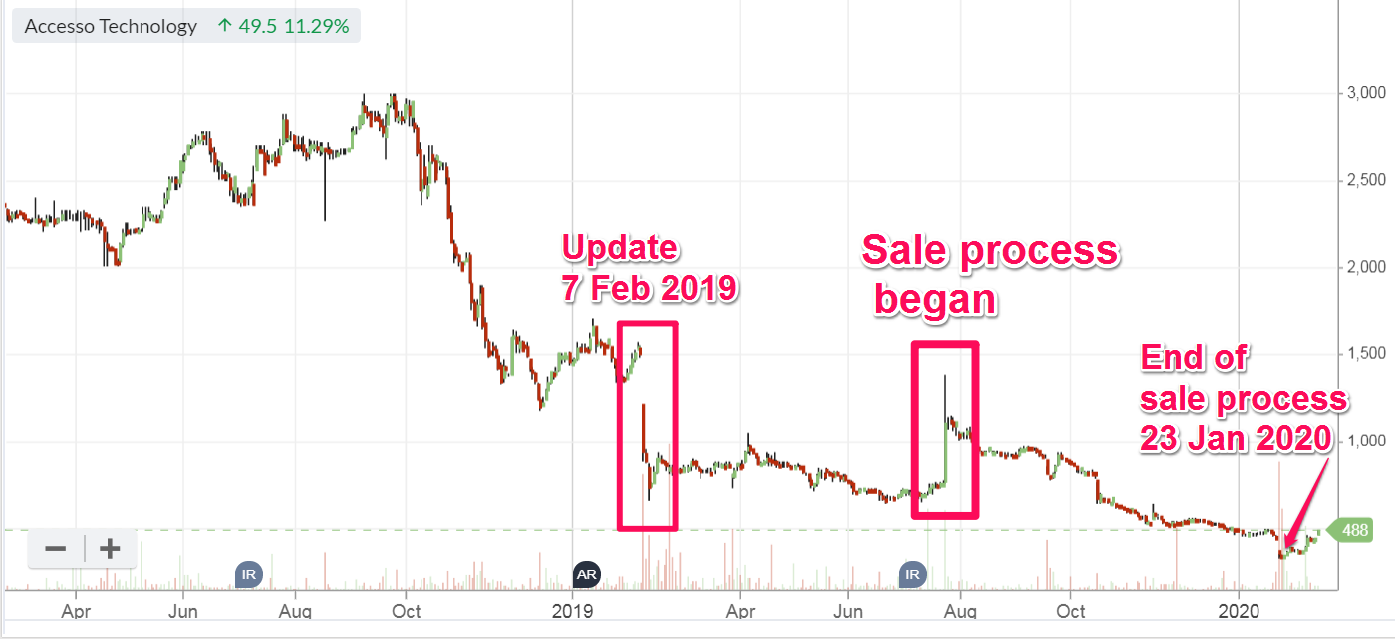
I've added key events to the 2-year chart below;
.
It would have made an amazing trade on 23 Jan 2020, well done to anyone who caught the falling knife at that specific point, as you'd be up by over 50% today. With so many uncertainties surrounding the value of the company, I'd be tempted to bank the profit if I'd nipped in around the 300p level.
That said, on the long term chart, the recent bounce is barely a blip.
How likely is to regain the previous 3000p highs? It looks very unlikely to me, as nobody wanted to buy it at a much lower price, once the sale process was underway. But who can say? Strange things can happen. As mentioned yesterday, there are vast amounts of cash swilling around at VC/PE funds, often willing to pay crazy valuations for tech companies. It's possible that one of them might target Accesso in future.
Another thing to consider with ACSO, is whether the large amount of payroll that it classifies as R&D, is genuine R&D, and likely to generate a decent future return? There's a well known argument for investing in companies that spend heavily on R&D, as they can often generate excellent long-term returns from that spending.
I honestly cannot make up my mind on Accesso. The bull argument sounds quite good at today's more realistic valuation. But on the other hand, a protracted & failed sale process tells me that there's perhaps nothing much here of interest. Who knows? I don't have enough information to form a view.
** Breaking news! **
Haynes Publishing (LON:HYNS)
Recommended cash offer at 700p - a whopping 62% premium.
Hearty congratulations to shareholders here, you can borrow my bunting, this is a marvellous result.
Frenkel Topping (LON:FEN)
Share price: 41.5p (down 9%, at 11:07)
No. shares: 75.6m
Market cap: 31.4m
End of bid talks & trading update
There are 2 announcements this morning;
Harwood Capital got in first, at 07:00, saying that it does not intend to bid for Frenkel Topping (bid talks were announced on 28 Jan 2020). It reserves its rights, if someone else decides to bid, which is boilerplate stuff in announcements like this.
At 07:01, Frenkel confirms that discussion with Harwood were held, but have now been terminated. This announcement also includes a trading update, as follows;
- FY 12/2019 results in line with expectations.
- Assets under management increased 15% to £897.9m
- Revenues to exceed £8.5m (Stocko shows forecast of £8.6m)
- Robust start to 2020, record month for new business since 2010, substantial AuM mandates won, new income from expert witness work
- Company positioned favourably for 2020
Directorspeak -
"We have made significant progress in the last two years and delivered excellent results; with AUM at a record high and a healthy pipeline of new business wins, we are strongly positioned to continue delivering further growth and value for our shareholders. The Board has a fiduciary duty to look at any serious interests in the business and it is a testament to the company and its achievements that we received this interest."
My opinion - I've not looked at it in detail, but remember meeting old management at a function several years ago, and thinking that it looks an interesting niche fund manager.
A positive trading update today, coinciding with ending of bid interest, means that arguably this might be a good time to nip in and buy a few shares? On the other hand, having looked over it, Harwood deciding not to bid, does rather suggest the upside might be limited. Harwood (Christopher Mills) are very shrewd, and don't like over-paying for anything. Whilst I very much respect their stock-picking abilities, Harwood tend to grab the upside for themselves, with low-ball takeover bids, thus pushing out private investors when they buy into something cheap. That limits the upside on shares where they have an interest.
Filta Group (LON:FLTA)
Share price: 167.5p (up 20%, at 11:53, only 19k shares traded so far)
No. shares: 29.1m
Market cap: £48.7m
Filta Group Holdings plc (AIM: FLTA), a provider of fryer management and other services to commercial kitchens, provides its trading update (unaudited) for the financial year ended 31 December 2019.
I've moved this up the running order, as the share price has reacted very favourably to today's update - albeit on a tiny number of trades printed so far today. There might be bigger trades reported at the end of the day (or later) of course, as beyond a certain size, trades can be delayed - e.g. if say a market maker is working a large buy or sell order in the background. That's why it doesn't pay to obsess over what the printed trades are in real time - as you're only seeing part of the jigsaw.
Today's update starts off with specific numbers;
The Company expects to report adjusted EBITDA* for the full year in the order of £3.2 million on turnover of approximately £25 million.
* Adjusted EBITDA represents earnings before interest, taxes, depreciation, amortisation, acquisition related costs and share based payment expense
Why can't they just report underlying EPS, as that's the easiest figure for me to compare with broker consensus forecast? They're creating extra work for me, by reporting EBITDA. I've now got to calculate how that compares to forecast. Actually, there isn't time to do that today, and as there are no broker updates available to me, I'll have to park this until the results come out on 21 April 2020.
Outlook for 2020 - sounds good - this must be what has pushed up the share price this morning;
Although still early in the new year, we are seeing strong interest from potential franchisees in North America, where we have added two new franchises and completed one resale, and in Europe we have added one new franchise each in Germany and Switzerland, which will drive higher revenues in the year ahead.
This, together with the good progress made in the final quarter of 2019 in both reducing costs and improving productivity in the UK, gives the Board confidence that Filta will deliver a much-improved performance in 2020.
That sounds really good actually. I like expansion into the USA, because it's such a massive market, with GDP something like 7 times the UK.
Acquisition of Watbio - see the RNS for more detail, but the quick version is that there were problems with a large acquisition, which are now being sorted out. That should be good for future performance.
My opinion - this share looks interesting, and subscribers might want to take a closer look.
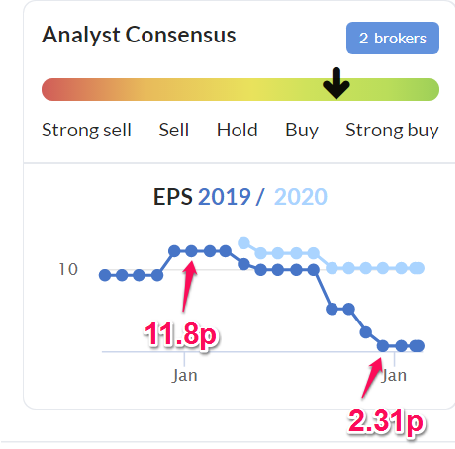
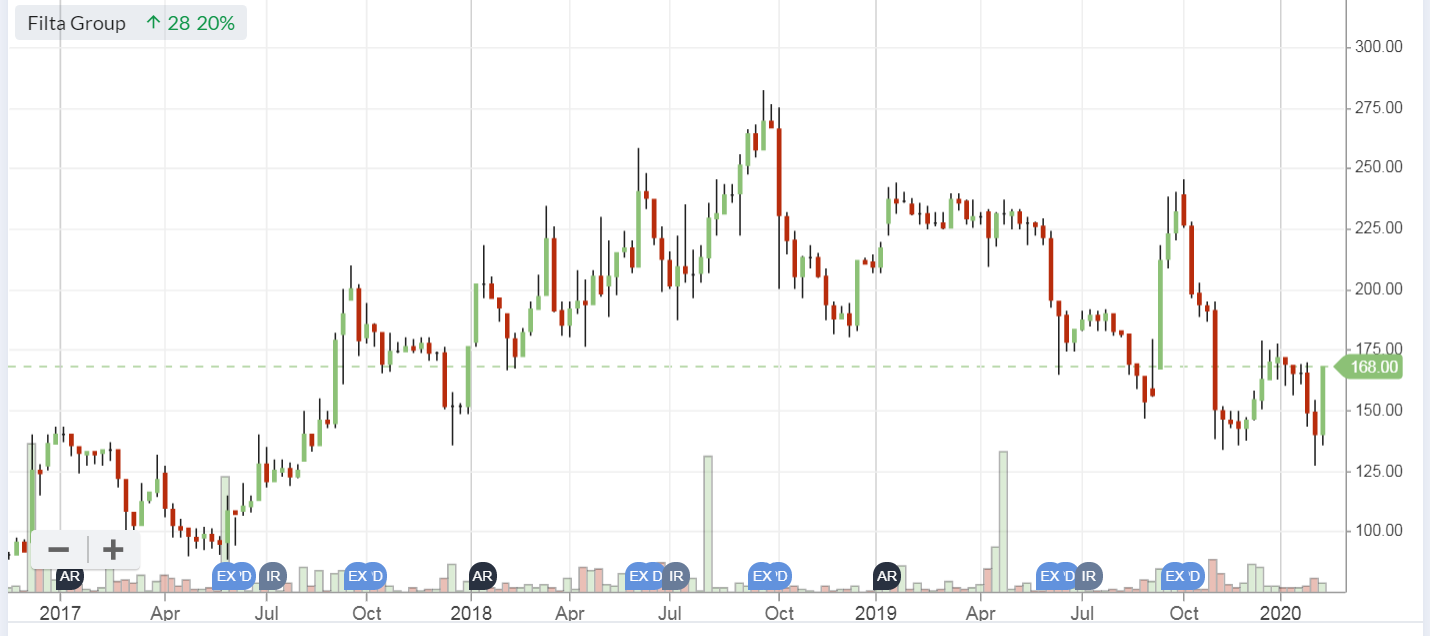
However, I would caution that today's perky sounding update does rather gloss over the sheer extent of the downgrades in 2019, see the usual handy little Stocko graph;
.
Clearly then, at c.168p per share, the price is already factoring in a huge recovery in earnings in 2020.
I'm keen to take a closer look, when the 2019 numbers come out, but it doesn't look particularly interesting as an immediate purchase, due to the turnaround good news already being baked into the current share price.
The concept looks quite interesting - a "where there's muck there's brass" type of share! Also, getting franchisees to do the hard grind, looks a smart move. Franchise businesses should split out the profits made from the initial franchise sales, and operational profits. Investors can end up getting a nasty shock with franchise businesses, because sometimes once growth stops, it can turn out that recurring profits were not very high at all. The real money-maker can sometimes be selling the franchises. Hence why the split is essential info.
A couple of quickies to finish off with;
Keystone Law (LON:KEYS)
Has published an in line update for 2019.
Share price is down nearly 6% today.
Why on earth is the forward PER so high, at 37.4? That looks crackers to me, for a people business. Even one with a very impressive track record of growth.
Do any readers understand why the price has gone so high over the last year?
That's it for today!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Evening Paul i’ve just noticed you are continuing dry January into Feb. I wondered if by March you might think of adopting Melvyn Braggs drinking habits
Mr Google will explain if asked just that
Strange activity over at Malvern International (LON:MLVN) (assuming my app isn't faulty) as looks like volume of 1.78m today for this tiddler market cap of £1.55m. But the share price hasn't moved. Major shareholder exiting?
That's about a £9k trade!
Good point!
Hi Paul - Just to let you know on accesso that I suspect Stockpedia's EPS numbers should be in dollars, not pence. The last broker note I saw from Peel Hunt forecast an adjusted EPS of 43 cents for 2019 - admittedly back in Sept'19
Hi edmonda,
I've just checked, and Stockopedia does correctly show Accesso's figures and forecasts in US dollars.
It was me who had a brainstorm, and wrongly added the annotations in pence, not cents. Drat, I'll have to re-do it now! Apologies for my error, and thank you for pointing it out. Now fixed!
Regards, Paul.
Keystone Law - down 6% . I feel that as a 'people business' that is an overkill drop. This appears to be a very well run operation which is growing nicely. Personally I have bought more today - I'm not worried about the forward PER
FYI - financial forecasts for accesso can be found here:
https://twitter.com/CapitalPmh/status/1227897503477051392
Coronavirus - just to cheer everybody up - this BBC documentary (along with Cambridge University) from 2018 on a simulated pandemic to Spanish Flu of 2018:
Contagion: The BBC Four Pandemic: www.bbc.co.uk/iplayer/episode/... via @bbciplayer
43 million UK citizens infected resulting in approx 900,000 deaths.
Coronavirus - just to cheer everybody up - this BBC documentary (along with Cambridge University) from 2018 on a simulated pandemic to Spanish Flu of 2018.
But we're not in the EU anymore, so it can't affect us, surely?
The sunny uplands of Brexit!!
Re Filta Group (LON:FLTA)
Hi Paul
Thanks for the report on Filta Group (LON:FLTA) (which I bought recently).
I was happy with today's updates, due to the following reasons:
You mentioned some risk around revenue from signing up new franchises slipping away.
This of course could be an issue, though there is perhaps some downside protection in the fact that 81% of H1 revenues were recurring in nature. It's also worth noting that 9 franchises were added in that same period to bring the total to 204 franchises. Quite a small amount relative to the size of the group. And as you rightly pointed out, the entry into the US leaves a lot of room for upside, alongside already expanding franchises in Europe right now.
Like you it will be interesting to see the final results in detail when they're published.
Thanks again for today's report.
Cheers
A
Thanks abtan, that's great additional detail from you! All makes sense to me.
Best wishes, Paul.
Some more news from China: I have just seen on the news that EV car sales in China are down 54% in January, it said subsidies have been cut. Overall new car sales are down 18%. This is before Coronavirus has had an impact. Many car plants iare being shut down due to lack of parts from China. I will have a look at Tesla when the US market opens.
re Flowtech Fluidpower (LON:FLO), they distinguish between sales to end-users of equipment, i.e. for maintenance, and sales to manufacturers (OEM). Sales to manufacturers are obviously more cyclical, and the reported downturn presumably reflects the general downturn in UK (and European) manufacturing which started in 2019, and which anyway seems to have been distorted by stock-building ahead of the Brexit which didn't happen, and subsequent destocking. I may be wrong, but I think there is also a manufacturing element to the OEM sales, so presumably the leverage is greater. In any case, the explanation of the downturn makes sense in the context of the economic data - as is the projected recovery second half of 2020. I don't hold, but it is looking a plausible Buy.
Thanks Sunday Trader, that's really helpful.
If an OEM is buying parts from a distributor, then presumably they must be a low volume producer? As otherwise they would presumably be buying in bulk direct from the parts manufacturer?
I wonder if you could give any examples of companies & products that FLO might supply on the OEM side? That would help me visualise things, and hence understand the business model better!
I get the distribution business for lots of hydraulic parts, to end users - e.g. if the hydraulics on a digger on a building site goes wrong, then the builder or the hire company would need to buy a new O-ring for it, or something like that. Hence FLO holding lots of items in stock, and supplying them fast, creates their opportunity to make a decent profit margin - both customers and suppliers need a distributor to sit in between and hold the inventories.
Thanks, Paul.
Paul
I know nothing about £FLO's business other than what is on their website and what I think is the one Annual Report since they went public. Mind you, if I had made a rule of never buying shares in a company without studying the Annual Report first I would be a lot better off.
They give a revenue split of 87%/13% between distribution and services. Services is the design and supply of bespoke equipment to OEMs. Distribution includes both supply for repair and maintenance, and supply to OEMs. I can't find a breakdown between the two - they may not have been able to do one given the comments about centralising their IT systems.
Their markets are heavy equipment and industrial, not consumer. In transport they talk about off-highway, construction, and waste management vehicles, for example. Their segmental reporting breaks down approximately as FlowTechnology 40%, PowerMotionControl 54%, Process 6%.
PowerMotionControl(Hydraulics) they illustrate with the hydraulics on a digger - there is a wide range of industries, from Agriculture through to Shipbuilding, but all relating to heavy duty equipment. FlowTechnology (Pneumatics) they illustrate with a range of pneumatic equipment used in a factory. Process they define as the "process sector". In these markets I would expect their OEM customers to be making small volumes of specialised kit to order - as you say, the likes of JCB have their own parts warehouses.
They estimate an underlying 4% growth in the markets they serve. The geographical breakdown is approximately 80% UK, 18% Europe (Belgium and Netherlands) and 2% rest of the world.
Regarding Flowtech Fluidpower (LON:FLO) Paul says:
"We might question why management allowed the business to be inefficient in the first place? It grew by acquisition, so it makes sense to me that cost-savings could then be achieved by combining acquired businesses, and making efficiency gains. That's a good reason for an acquisition strategy".
A key to looking at this company is the abrupt change in policy announced in September 18. Prior to that the company was all about acquisitions:
(Hope you can cope with the width)
They then announced:
"Our activities have created many more opportunities to grow through acquisition and we plan to take advantage of this in the medium to long term. However, in the short term it is appropriate to work with the infrastructure we presently have and continue to focus on delivering on our four layered synergy approach - back office, procurement, operational efficiency and commercial".
This coincided with the retirement of the CEO and so they are now at last getting the efficiencies out of combining those 14 acquisitions.
Re Coronavirus - I have been following this guy for a while on YouTube - Dr John Cambell
He is a Nurse Teacher and A and E nurse based in England. He also teaches in Asia and Africa when time permits. He covered the changes to the assessment criteria last night.
How interesting, many thanks!
I love the new feature allowing videos to be embedded in posts/comments.
Hi OldManFit
Very insightful posting, thank you. What a great guy Dr John Cambell.
Regards
Howard
Paul - With the new version you are becoming a chartist - thumbs up again
I wonder if the winter air pollution that is quite common in China has also exascerbated lung problems for those who are more vulnerable, on top of which they then may get infected with the coronavirus.
I hope we can quickly see the virus burn itself out, and bring some relief to the poor people trapped in Wuhan.
Hi Paul, on Corona Virus, the National Health Commission of China has posted today: " Starting from February 12th, confirmed cases are now considered by officials as both tested confirmed cases as well as clinically diagnosed cases. All percentage values that have this note tag, are calculated using the confirmed cases values which are the sum of both the tested and clinically diagnosed values. Thus any very large percentage value changes seen from the marked percentage when compared to previous percentage values are caused by this."
Yep - this is a key distinction. It doesn't mean there is any change to the situation and the real numbers were perfectly obvious before the change as discussed a few days ago. What is more unhelpful though is the change in statistic as it makes it harder to see either peaks or acceleration or trends.
No position and just musing, but wondered if there is a potential deep value play developing for the patient in today’s announcement by Mxc Capital (LON:MXCP) of its delisting from AIM? Shares are already at a decent discount to asset value (Price to Tangible Book Value of 0.82x) and given the delisting the shares are likely to sell off heavily as those unable/unwilling to hold unlisted shares become forced sellers into a market with little likely demand. Company has indicated its intention is to self liquidate its assets and distribute cash over next 5 years to shareholders while managing down operating costs as far as possible. Don’t yet know much about the nature of their asset holdings, but at a cheap enough price assuming a big sell off arising from the delisting, is there an attractive five year income stream available to anyone happy with an illiquid position?
Gus.
I agree Mxc Capital (LON:MXCP) looks like an interestng situation. I believe you can hold unlisted shares in a SIPP so this might be a good one to tuckaway if you're in no hurry to realise the full value. Definitely one to keep an eye on in the run up to the delisting on the 16th March.
Had a bit of a dig into Mxc Capital (LON:MXCP) that announced its AIM delisting and orderly self liquidation of its investment portfolio over the next five years. Plenty of information on the company website and the annual report as of August 31 2019 is reasonably current. Then then cash position was £21.5m and the investment book was valued at £30.1m. The listed book included a 15% shareholding in Adept4 (now Cloudcoco (LON:CLCO) ) which at current market value is about £750k and a 45% holding in Ide Group (LON:IDE) worth about £6m. There are also various loans outstanding so attributable book values/exposures shown are higher than this (see accounts for more detail). In addition there is a further £15m invested various unlisted companies. Stock ranks on the two listed companies are not great (don’t think I would invest in either personally but this kind of tech is not my bag). All told NAV as at August 2019 is stated at £71.3m but not entirely sure what else there is apart from the cash and the investment book. As of last night close after the markets have digested news of the delisting, the reduced market cap was about £38m so discount to NAV is now over 40%.
Ongoing Opex is shown as approximately £2.2m per annum which would hopefully come down during the wind down if the company is not actively increasing its book. Company shares are quite tightly held by directors and individuals. Not a lot of institutional holdings but presumably those that are will probably look to sell ahead of delisting. Given the alignment of interests, one would hope the company liquidation will focus on maximising exit value given the big equity stakes of the principal directors. (The cynic might even suggest the delisting is more about creating an opportunity for personal nest feathering rather than what’s in the best interest of the company).
At first blush it does seem interesting. Main questions for me is what is the real value in the investment book as they may be a lot of dogs, yet one killer investment could make a huge difference. Also need to get happy that the liquidation proceeds will go to shareholders rather than be bled out via fees and emoluments to the executive. Initial thinking is the risk:reward trade off is quite attractive, especially if the share price continues to drift downwards in the run up to delisting. Worth watching also to see if the current executives/individual shareholders start hoovering up more shares which for me would be a strong buy signal.
Gus.
Yes, MXC Capital (LON:MXCP) looks interesting, but it raises the question of how to deal with unlisted shares in an efficient way. I used to hold share certificates years ago but have no idea how to manage unlisted shares today.
I would normally file in the "too dfficult" draw and move on, but it seems to be a question worth answering due to the apparent trend towards more delisting. Sooner or later, it seems likely, a share I hold will delist and there may be opportunities such as MXC Capital (LON:MXCP) in the unlisted space.
Does anyone have any knowledge or suggestions?
Mj Gleeson (LON:GLE) interim looking positive this morning! Great company here in my opinion well poised to take advantage of a more favourable climate and also the governments Northern regeneration plans - any other holders in this ?
I held Mj Gleeson (LON:GLE) until last year's final accounts. There was a big ‘debtor’ increase which seemed to be booking profit on a land sale before completion. I tried to clarify with investor relations but got no response. With other accounting irregularities in the market I decided to bail out, with a pretty good profit. This also pushed the F score on stocko down to 5 which i view as a amber light.
Quick glance at the interims the debtor seems to have gone, but inventories are up. I would like to buy back in but feel the need to really analyse these movements to make sure, that like a fat man in an ill fitting suit, issues are not bulging out in other places.
My morning smallcap tweet:
accesso Technology (LON:ACSO) Lidco (LON:LID) Flowtech Fluidpower (LON:FLO) Filta Group (LON:FLTA) Frenkel Topping (LON:FEN) Transense Technologies (LON:TRT) Futura Medical (LON:FUM) MXC Capital (LON:MXCP), Keystone Law (LON:KEYS), Checkit (LON:CKT), Safestore Holdings (LON:SAFE)
Accesso Technology (ACSO) contract wins. Doing its best to sound positive after calamitous 12 months.
LiDCO Group (LID) guides FY rev up 3% with a larger proportion of higher margin LiDCO rev giving a higher overall gross margin. Guides positive adjusted EBITDA. Is this a beat? I wish they'd say.
Flowtech Fluidpower (FLO) guides FY in line with the poor trading announced in Jan. Cutting costs. Will still hike div 5%. Outlook "we expect revenue for the full year 2020 to be down by low single digit percentage points, with a weak first half largely offset by a return to growth in the second, leaving underlying profit at a similar level to 2019. A return to revenue growth in 2021, coupled with further planned cost savings, should deliver significant leverage to both margins and profit."
Filta Group (FLTA) guides FY rev in line at £25m, adj EBITDA £3.2m. New scheduling software introduced in 2019 is now delivering improvements in productivity and will further increase both revenues and margins. Confident of "much-improved performance in 2020."
Frenkel Topping (FEN) takeover talks off. Guides FY in line. A 'robust' start to new FY.
Transense Technologies (TRT) extends joint collaboration agreement with Bridgestone to Feb 2022.
Futura Medical (FUM) after positive talks co has "commenced formal proceedings for MED3000, the Company's gel formulation, as a clinically proven treatment for ED to be approved as a medical device...Feedback from these initial discussions also indicates that MED3000 represents a wider overall commercial opportunity [for impotence]."
MXC Capital (MXCP) proposes AIM delisting.
In line: Keystone Law (LON:KEYS) Checkit (LON:CKT) Safestore Holdings (LON:SAFE)
Filta Group (LON:FLTA)
Update today seems nicely positive in that the issues from last year seem to have been out behind them. Would be interested to know if there are any 2021 forecasts available yet. If 2021 is expected show decent growth in profits the shares are looking pretty interesting again. One slight negative here was the slowness with which they released the bad news last year - I don’t particularly like companies that keep moving goalposts but their excuses last year did sort of make sense as being of the reasonable variety.
i met with these guys and would be wary
Flowtech Fluidpower update today is interesting regarding stock build up over Brexit uncertainty:
2019 TRADING UPDATE
2019 was undoubtedly a disappointing year, with volumes inflated as customers built up stock ahead of a Brexit hiatus that never occurred. As the year progressed, we saw a significant slowdown in some of our key end markets, most particularly cyclical services associated to our OEM business, which culminated in the profit downgrade of 14 January 2020.
https://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/FLO/14421468.html
haha were you watching the mighty Luton Town launch themselves off the bottom of the championship?
Accesso Technology (LON:ACSO)