Small Cap Value Report (Thu 14 Jan 2021) - WINK, CAY, SIS, RNO, BOO, BOTB, G4M, PMP

Good morning, it's Paul & Jack here with the SCVR.
We're hitting the ground running today, with 3 backlog sections that Jack & I wrote last night. We've split the report into two parts, so it's hopefully clear which of us is writing each section. The idea is to get some work up early, so that I can concentrate on the trading update from Boohoo (LON:BOO) today (my largest personal holding, and the most popular share in the 2021 stock picking competition here).
Just as an aside (not applicable to BOO of course), the main problem with stock picking challenges, is that people tend to pick speculative stuff that could multi-bag, as there's no downside if you get it wrong. That's what I usually do too, to be fair!
Reader comments
Thousands of people are reading these reports now, and the comments. So I think we need to tighten up a bit on what gets posted, to avoid wasting a lot of peoples' time. Could people please consider the following;
- Does your comment really add value? Announcing that you've bought or sold something is irrelevant - nobody cares!
- Please don't comment on thumbs downs - again, nobody cares, and it wastes time for other people having to scroll through so many pointless posts
- Agonising over intra-day price moves generates pointless background noise, we're more focused on company fundamentals here, it's not a day-trading forum.
- Please don't bicker with other readers, and then clutter up the comments section with tit for tat replies. It's incredibly boring for the thousands of other readers, and me!
- Keep it courteous please, that's the style here (most of the time anyway)
- Above all, before you hit the submit button, please consider deleting your post if it doesn't add value for other readers.
- Intelligent & informative comments are hugely welcomed, so please try to keep it to those.
- Let's stick to the subject matter. Nobody cares about our political views, and there are plenty of other places to discuss politics if we want to, so try to stick to shares, markets, economics.
- Please don't waste the time of the lovely admin people at HQ, they're very busy, and it's extremely unhelpful to start flagging comments for review, and generally being a PITA. If you disagree with something, that's fine, but don't make a fuss & waste everyone else's time.
Hope that sounds OK, and many thanks for your indulgences.
Timings - lots to cover today, so I'll probably keep working away until mid-afternoon. Jacks' doing some customer support work now, but many thanks for his contributions today, which takes some of the pressure off me. Today's report is now finished.
Agenda -
Jack's section
M Winkworth (LON:WINK) - Trading update from yesterday for FY 12/2020
Charles Stanley (LON:CAY) - Q3 Trading update
Science In Sport (LON:SIS) - Trading update for FY 12/2020
Paul's section
Renold (LON:RNO) (Paul holds) - Trading update
Boohoo (LON:BOO) (I hold) - Strong trading over seasonal peak - 4 months to 31 Dec 2020
Best Of The Best (LON:BOTB) - stunning interim results!
Gear4music Holdings (LON:G4M) - strong trading update, exceeding expectations.
Portmeirion (LON:PMP) - good update.
.
Jack’s section
M Winkworth (LON:WINK)
Share price: 155p (+8.77%)
Shares in issue: 12,733,238
Market cap: £19.7m
I presented Foxtons at this week’s Mello Monday as a slightly contrarian pick based on the idea that the “exodus from London” narrative has been overplayed. A couple of people suggested M Winkworth as an alternative to Foxtons, and it has just yesterday released a trading update, so that could provide some interesting read-across for the wider sector.
Winkworth is a franchisor of residential real estate agencies established in Mayfair in 1835. It focuses on the mid to upper segments of the central London residential sales and lettings markets. In total the company operates from some 100 offices.
The franchise model provides some attractive investment characteristics, namely strong profit margins, returns on capital, and cash generation. We can see that coming through fairly clearly on the group’s StockReport:

In fact, for all the negative news flow around Covid, lockdowns, and the economy, Winkworth’s shares have been remarkably sturdy over the past twelve months. It’s a tiny free float (c30%), with Simon Agace owning just over 40% of the company, but perhaps this illiquidity has reduced volatility over the past year.
Mind you, if somebody did decide to sell, that could move the share price quite a lot so volatility could always increase here. It looks like that illiquidity has gone the other way on yesterday’s update though, with shares up nearly 9%. Estate agencies are to remain open for business in the current lockdown, although you might expect some impact nonetheless.
Trading update - released 13th January 2021 for the year to 31 December 2020
Despite all the negative news flow, Winkworth's total revenues are broadly flat year-on-year, although profits before tax will come in a little lower and the total dividends have been reduced by 15%. More detailed final results will be released on or around 8 April 2021.
Q4 2020 sales applications were up 44% and lettings applications were up 12% year-on-year, and with a record pipeline of sales still to feed through to trading in Q1 2021, Winkworth has ‘entered the current year with considerable momentum.’
That might not be quite what people were expecting to hear. Additionally, Winkworth says that the group has seen an ‘underlying strength of demand in the sales market’ for much of the year.
The group does credit the stamp duty holiday incentive for helping to fuel a ‘post lockdown boom’. Demand is driven at least in part by these government initiatives which could be changed or adapted for political reasons. It’s a risk worth bearing in mind.
The second half of the year remained strong and Winkworth increased its market share of sales subject to contract in London (where it is number two) from 4.2% in 2019 to 4.6% in 2020. That said, the group adds that ‘until international interest recovers, we see reduced rental prices in London limiting growth’.
The rate of new office openings was subdued in 2020. On the whole though, Winkworth has avoided making significant cost cuts to its operations so that it is well placed to support franchisees once conditions improve.
Conclusion
I do think at some point the London property sales and lettings markets will recover. Now is the time for stronger operators to gain market share, while weaker competitors struggle to steady the ship.
It looks like M Winkworth is firmly in the “eventual winners” category. It remains small, and liquidity will continue to be an issue, but this looks like a well-run company for its shareholders, which occupies a useful niche in one of the most valuable property markets in the world.
Growth has been an issue for Winkworth in the past though. This looks like a high quality, well run company that is prudently managed for shareholders, but some might be looking for more evidence of earnings growth and capital appreciation over the years.
Winkworth does talk about its market share gains this year, so let’s see if that can lead to a step change in revenue and earnings down the line.

.
Charles Stanley (LON:CAY)
Share price: 304p (+2.7%)
Shares in issue: 52,110,163
Market cap: £158.4m
The thing that jumps out to me about this one is that Charles Stanley, apparently, has more than 50% of its market cap in cash.

There are a few cashed up asset and wealth managers around at the moment. The SIC just bought Polar, for instance (see the pitch here).
M&A has been a feature of this sector as operators scramble for scale, so putting two and two together it looks like we can expect ongoing corporate activity here. It could be that CAY services a slightly different niche, though.
A quick look at the StockReport shows that Charles Stanley has some attractive valuation characteristics (for example, a price to free cash flow ratio of 6.7x) and also has some quite respectable operating margins and returns on capital.
It qualifies for seven Guru Screens:
- Dreman Low Price to Cash Flow Screen (Value)
- James O'Shaugnessy Cornerstone Growth (Growth)
- Josef Lakonishok Momentum Screen (Momentum)
- Best Dividends Screen (Income)
- David Dreman Low PE Screen (Value)
- Richard Driehaus Screen (Momentum)
- Free Cash Flow Cows Screen (Bargain)
So we can conclude from this that there are a variety of quantitative indicators across a range of factors that suggest we look at this one.
It’s a brief update for the three months to 31 December, so there’s not a whole lot of substance to move the reader one way or the other.
Total Funds under Management and Administration (FuMA) as at 31 December 2020 rose by 10.1% quarter-on-quarter to £25.1bn, largely due to a market improvement of £2.2bn, with net inflows of £0.1bn.
That compares to a 7.0% increase in the MSCI WMA Private Investor Balanced Index over the same period. The outperformance is good, but the net inflows seems a bit feeble and average FuMA for the year-to-date was £22.6bn, which is 7.8% lower than over the same period to December 2019.
Total revenues over the three months fell by 1.2% to £42.2m (Q3 2020: £42.7m), with increases in fee income of 3.2% and commission income of 4.3% offsetting a ‘significant contraction’ in interest turn.
Revenues for the year-to-date fell from £128.1m to £124.1m, largely as a result of this 65% drop in interest turn following the fall in interest rates in March 2020.
Paul Abberley, Chief Executive Officer of Charles Stanley, said:
The Group has continued to demonstrate significant resilience in the face of the ongoing pandemic, and we are encouraged to see modest net inflows of FuMA during the third quarter as well as stable revenue levels.
Conclusion
Upon reflection, given the year that was, a small net inflow in FuMA for the three months to 31 December is respectable. It does suggest an improving trajectory as well, given the decline in FuMA over the nine month period.
Is Charles Stanley in an attractive niche, or will its margins and possibly even business model ultimately come under pressure? It’s hard to say. The vast majority of CAY’s operating profit comes from Investment Management Services.

There is a question mark over how well CAY can protect its margins over the long term, in my opinion. But, on the other hand, this stock is being flagged across a broad range of indicators and Guru Screens.
The dividend yield has been growing recently, there is a material net cash position, and CAY does operate an asset-light, cash-generative business model. The valuation is undemanding, so it could be worth a closer look for those interested.
.
Science in Sport (LON:SIS)
Share price: 39.95p
Shares in issue: 135,100,931
Market cap: £72.9m
Science In Sport (LON:SIS) is an interesting company that is seeking to become ‘the world’s #1 premium performance nutrition business’. Helmed by chairman John Clarke, the global President of GSK Consumer Healthcare from 2006 to 2011, and CEO Stephen Moon, the ex-Business Development Director for the Nutritional Healthcare Division of GSK, you would think there’s enough experience here to realise that ambition.
This is a fast-growing and higher margin area in sports science that can have a real impact on both elite level and mass market performance. Unfortunately SIS has struggled to impress so far, diluting shareholders and burning through cash as it builds its brands and distribution network.

Those brands are PhD and SiS. While revenue has compounded at about 50% per annum over the past six years or so, losses have also widened. In 2019, sales came in at £50.6m but the net loss was £5.62m.
The group’s cash reserves were once again looking thin in 2020, but the group got a placing away in April 2020 and now has £10.5m of cash (FY19: £5.4m), including £4.2m net proceeds from the placing.
Trading update for the year to 31 December 2020
- Adjusted EBITDA profit of £1.1m (FY19: loss of £0.3m).
- Online grew strongly, +39% to £25.0m and Q4 Online performance was +65% year-on-year. PhD.com revenues grew 105% to £3.2m, and momentum continues to be strong here.
- Retail was affected by COVID but total revenues of £50.3m were in line with the previous year (FY19: £50.6m).
- Online sales were 50% of total revenues, compared with 38% in FY19, and the group ‘see[s] this strong channel switch continuing’.
- Gross margin was up 5% year on year to 49%. The gross margin was 50% for the second half, thanks to Supply Chain efficiencies and the shift to Digital.
So that shift to online is bringing with it enhanced profitability. It could be the break SIS needs.
Meanwhile the group’s balance sheet is secure for now although its track record of shareholder dilution is something else: there are now 135m shares outstanding post-placing in April, compared to around 15m at IPO back in 2013.
Key SIS growth markets of Australia, Football, Italy and the USA contributed 28% of total revenue at £7.2m, with US revenue up 35%. Cash burn ‘is significantly reduced’.
Sales from new products contributed £2.2m, or 4% of total revenues. That’s a promising feature for future growth, and SIS says ‘the 2021 new product pipeline is extremely strong’.
Key senior hires have also been made in Online, Technology, and Customer Experience, and the group has agreed to heads of terms for a new 160,000 sq ft supply chain facility in Blackburn which will be fully operational by Q1 2022. Management says this will give SIS room to grow to ‘more than £150m in revenue’.
Final results for the group are expected to be on the 17th of March 2021.
Conclusion
This sounds good to me, but the massive shareholder dilution in the past is a very clear warning sign.
Putting that aside for a second, the global sports nutrition market is obviously big and SIS cites reports valuing it at over £11bn with projected 8%pa growth to £18bn by 2023. The chairman and CEO look like a highly experienced duo that have worked together before at Glaxo, and probably understand what operating at significant scale looks like.
And the shift to online accelerated by Covid could be an important inflection point, potentially marking a step change in business model, revenue growth, and gross margins.
There is still plenty to prove though and the scale of dilution so far at this company is a serious blot on the copy book - if management were significant shareholders, how would they feel about seeing their stakes diluted by orders of magnitude over the past decade or so?
But at some point, I think that dilution will stop and SIS will make it. Perhaps that stage is at hand? I continue to think caution is required here, as I would want to convince myself that management does indeed consider shareholder value alongside its ambitious talk of becoming a global leader in the sports nutrition market.
For that reason I class it as high risk, although the fundamental picture does appear to be improving.
.
Paul’s Section
Renold (LON:RNO)
(I hold)
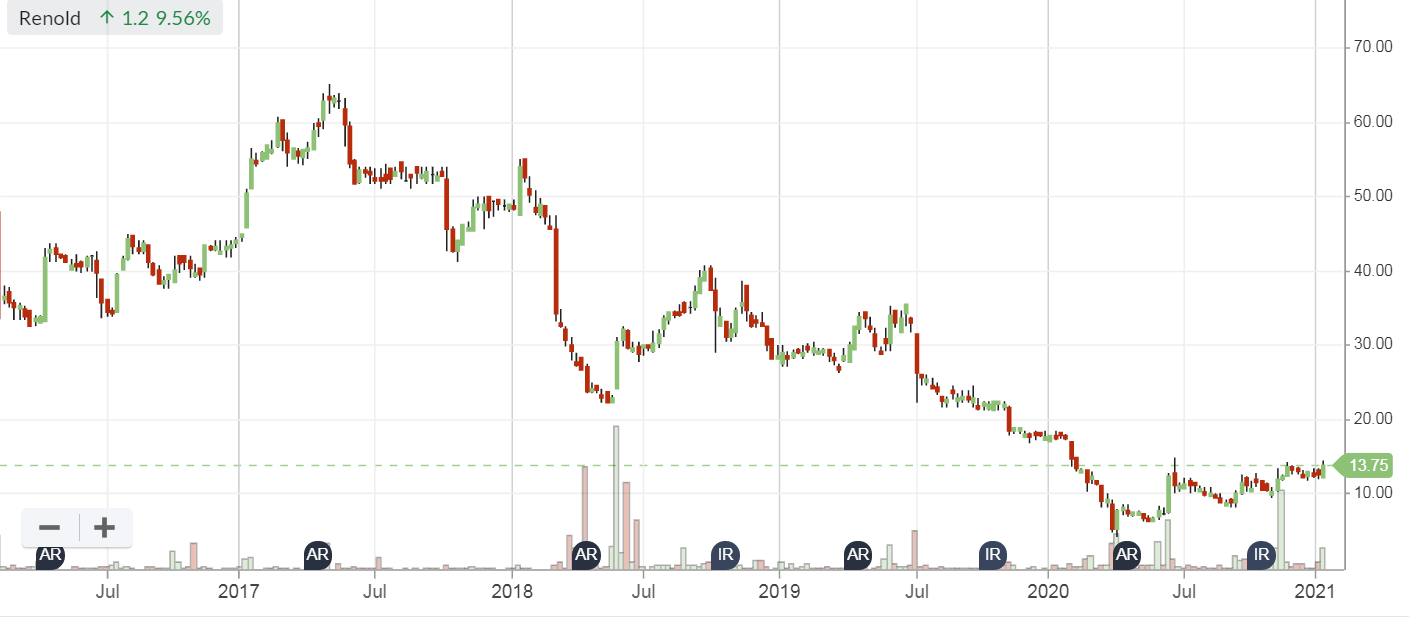
13.75p (up 10% yesterday) - mkt cap £31m
Renold, a leading international supplier of industrial chains and related power transmission products, today issues a trading update covering the three months ended 31 December 2020 (the "Period").
The year end is 03/2021, so this update is for Q3 of the current financial year.
Key points;
Continued to deliver a robust trading performance, despite covid disruption
Recovery in revenues & order intake has continued in Q3
Guidance - adj operating profit for H2 should be “broadly similar” to H1
Net debt £23.0m, down £13.6m since 31 March 2020 - not stated whether there has been any creditor stretch or not.
Considerable market uncertainty, but Renold is diversified.
Focused on cost control, efficiency, cash management.
Since H2 is said to be a bit below H1 (“broadly similar”) then I need to look back at the last interim results, which I reviewed here on 11 Nov 2020. Renold made £5.8m adj op profit in H1. Therefore it’s probably heading for about, say £11.3m in FY 03/2021.
The company has to pay about £5m p.a. Into its pension schemes.
Everything else in my previous notes still stands, so there’s not really any change.
My opinion - the huge pension deficit still scares me, but a market cap of only £31m seems extremely low, given that the business itself is trading well. Add some recovery potential onto the numbers, once covid is on the wane, and there could be geared upside on the share price maybe?
Overall I’d say that I'm warming to this one, whilst still rather nervous about the pension scheme deficit. I’m minded to move my position up from a small, to medium size, and then leave it there. I wouldn't want too much exposure to something with such a big pension deficit, in case the deficit explodes upwards. But even then, would it really matter that much? The company looks strong enough to cope with the cashflow drain from the pension scheme, and hasn’t had to raise any fresh equity through the covid crisis.
It would be good to see management - I wonder if they could be persuaded to do a private investor online webinar as part of their annual results roadshow? All companies should do this, it’s incredibly helpful, and helps generate more private investor interest in the shares, thus improving liquidity, and raising the share price if we like the cut of their jib.
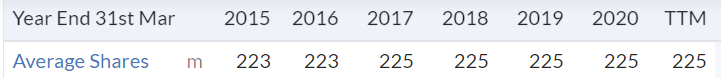
I always check this data field (see below) on the StockReport, to see if the share count is rising. In the case of Renold, the company has implemented a decent-looking turnaround, without issuing any material number of new shares. That's a strong positive, and means that there's no reason why the share price couldn't fully recover in due course, if performance justifies it.
.
.
An investor friend who usually talks sense, reckons this could be a takeover target, with the pension deficit helping to make the takeover price potentially attractive. He reckons the pension deficit could reduce, if Renold were acquired by a larger group, because it could be revalued down on a lower risk basis. Interesting idea! Although a big pension deficit might put off many potential bidders, who wouldn't want to take that onto their books. So you can argue that point either way.
.
.
Boohoo (LON:BOO)
(I hold - my largest position)
369p (pre market open, likely to rise today) - mkt cap £4.66bn
This covers peak seasonal trading, 4 months to 31 Dec 2020.
It looks very good. Key points;
Revenue growth of +40%, both UK & International grew by the identical +40% percentage - better than Asos which grew sales over the same period by +23%.
Asos mkt cap of £5.3bn is 14% larger than BOO, which looks wrong to me - BOO should be worth more than Asos, as it's growing faster & makes a higher profit margin.
USA is noteworthy - becoming an important market, at 25% of total sales, and growth of +52% - this could trigger a further re-rating of the shares, once investors spot the growth potential in this massive market, only scratching the surface.
Gross margin down very slightly (50 bps) at 53.0%, again better than Asos, which achieved 47.4% gross margin in its last annual results (not stated in recent trading update).
Net cash of £386.9m looks very healthy.
Guidance for FY 02/2021 - revenue growth raised from 28-32% previously, to 36-38% now. Very impressive to be raising full year revenues guidance that much, near the end of the year.
Adj EBITDA margin c.10% - no change, as indicated in last update with interim results, published 30 Sept 2020. I'm very impressed that BOO has managed to absorb extra costs such as supply chain investigation & remediation, freight & carriage cost increases, etc.
Brexit - doesn't sound a problem, "small cost headwind"
Sir Brian Leveson is on BOO's website here, I've read the executive summary, which looks fine. No new issues.
Zeus has raised its EPS forecast EPS FY 02/2021 by 5.6%, to 8.7p, a PER of 40 (at current price of 350p, which has inexplicably fallen at the open this morning). Forecast likely to be beaten, as it assumes slow growth of only +9% in Jan-Feb 2021.
We should of course be focusing on FY 02/2022 earnings now, which are forecast at 11.7p, a PER of 29.9 - which looks terrific value to me, for an exceptional growth group. Particularly as BOO usually beats forecasts, which tend to be raised throughout the year. So the actual PER in 12 months time could turn out to be 20-25, not 29.9.
My opinion - this is a very strong update. Unless I've missed something, this should have moved the share price up, not down, so I've no idea why the market has initially reacted the way it has. Still, as we've seen repeatedly in the last year, spikes down with BOO are terrific buying opportunities.
All good, as far as I'm concerned.
.
EDIT: Analyst/investor call - I listened in to this, and took some notes. It's mostly just repetition of the RNS, but did include some useful extra colour in understanding the business better, here are the key points;
USA market - strongly emphasised this as a "huge opportunity". BooHoo, PrettyLittleThing, and NastyGal are doing well in USA, with PLT being the "stand out" growth brand.
Gross margin lower in H2 than H1, as High Street re-opened in Nov 2020, so market was very promotional (i.e lots of discounting)
40% growth achieved despite there being no Christmas party season - very good considering seasonal sales of party wear & shoes didn't happen.
Marketing spend increased in H2. Was c.8% of revenues in H1, higher in H2.
NB. The most important point in my view - of the 40% revenue growth reported, it's mostly organic - e.g. the "established brands" produced 35% of that growth, with just 5% coming from new brands. That's much better than I was expecting.
They held back marketing spend on new brands (e.g. Karen Millen) in 2020, but are now cranking up marketing for expansion. Good results, ahead of plan so far.
Question asked about why period 4 (Jan-Feb 2021) guidance is for only c.10% growth - Answer - just being conservative, due to uncertainties. Seems pretty obvious they're going to beat this, as the Zeus note says, so next trading update likely to be another upgrade.
Buying new brands - is it more competitive? Not really. BOO is only interested in buying brands that have global potential. Plenty of opportunities, e.g. BOO only has 1 menswear brand, not represented in sportswear brand either.
Guidance for 2021/22 not being given just yet - will be provided at time of results. So many uncertainties at the moment, re lockdowns, vaccines, etc,. Although we do have the medium term guidance of 25% p.a. revenue growth target, and 10% EBITD A margin.
End of edit.
.
Best Of The Best (LON:BOTB)
(I hold)
2050p (up 30% at 12:09) - mkt cap £189m
Best of the Best plc runs competitions online to win cars and other prizes.
Online-only model and efficient marketing investment drive ongoing revenue and profit growth
Absolute blow-out numbers here. Amazing stuff. The company has achieved profits/EPS in H1 that’s not far off the full year forecast (itself raised greatly last year).
It’s a long-time favourite here at the SCVR, but I never imagined it would achieve such stellar performance, and am kicking myself for selling many of mine last year, when it looked like the takeover bid wouldn’t happen. The trouble is, with something this illiquid, it’s often not possible to buy back in when you want to.
Yes, BOTB will have benefited from lockdowns, and people not having other things to spend money on, like holidays, going to the pub, etc. However the interims today cover May-Oct 2020, when lockdown had mostly finished, or been eased.
The financial highlights really are superb, and this is all organic growth remember;

.
Broker updates - I can’t find anything, but it doesn’t really matter as it’s so easy to work out our own. I would say double H1, to get to c.120p EPS for FY 04/2021, is possibly a reasonable base case. The company is growing so fast, it could be well above that, who knows? If we run with 120p EPS, then at 2050p the PER would be 17 times - very cheap for such a strong growth situation.
However, I also take on board reader comments that there must be some risk of a well-funded competitor trying to replicate what BOTB has done. Also this area does come with regulatory risk too. There are lots of small competitors springing up - they keep appearing on my Facebook timeline, but I’ve checked them out, and they’re mickey mouse companies, not serious competition..
Even allowing for risk, a 17 times PER seems unduly pessimistic to me.
Takeover bids? Talks are still ongoing, but given these numbers, I don’t want to sell out! Let’s keep going, if this is what can be achieved as an independent company. Unless of course potential bidders are really prepared to offer big money. Management have controlling stakes, so won’t sell out on the cheap. They look after us very well, so I have complete trust in their judgement and integrity;.
The Company, together with its advisers, remains in ongoing discussions with interested parties from a number of sector verticals and including private equity, who are reviewing information in a data room and having management team meetings. These discussions are continuing despite the renewed constraints of Covid-19, though the related restrictions are naturally impacting the speed of discussions and decision making.
The Board wishes to reiterate that there can be no certainty that an offer will be forthcoming or as to the terms of any such offer and looks forward to keeping shareholders updated in due course.
Outlook - given that H1 isn’t far off the full year result, then I’m surprised the statement below didn’t use “substantially”, instead of “materially” - which is usually code for about 10%.
The first half of the year has delivered encouraging sales and profits growth, and importantly, we also completed the transition to an online-only business which has driven a step change in growth. This momentum has continued since the period end and, as a result, the Board now expects full year pre-tax profits to materially exceed management expectations.
BOTB has built a substantial and valuable database, which not only supports its existing competitions, but also offers interesting opportunities for new products and strategic partnerships, which are currently under review.
Special dividend of 40p announced, emphasising how cash generative this business is. More are likely in future, in my opinion.
Balance sheet & cashflow statements both look fine to me. It strikes me how small a lot of the numbers are - i.e. this is a highly profitable business, operating from a lean overhead. Ideal really. Some businesses have to build massive factories & employ thousands of people to make profits that little BOTB manages from a smallish office in London.
My opinion - my only regret is not holding onto more of my shares.
I can’t see any reason to sell, and based on these stellar numbers, it is tempting to throw caution to the wind, and buy some more. It’s so difficult to find stock though.
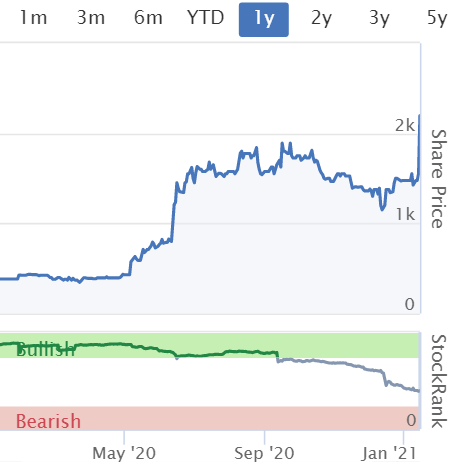
It's interesting to note that the StockRank has been declining. That's probably because the computers didn't realise that BOTB was going to blast forecasts out of the water! I imagine the StockRank should significantly improve once (or if) updated forecasts feed through.
I've emailed the CEO to thank him for doing such a great job here, and looking after his small shareholders so well.
.
.
Gear4music Holdings (LON:G4M)
(I hold)
885p (up 5% at 13:31) - mkt cap £185m
Like all investors, I’m looking first at the shares I hold personally. Loads of them seem to be reporting positively today. Let’s hope a trend is starting!
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a trading update for the three months to 31 December 2020.
This is Q3 of FY 03/2021.
Here is the revenue growth table for the peak Xmas season;

.
I’ve highlighted the bits that look striking - namely good, but comparatively modest UK growth of 10%, but absolutely stonking international growth (mainly Europe, I believe) at +51%.
Remember that G4M’s revised strategy is to go after margin, ahead of revenue growth, which has worked superbly, greatly boosting the bottom line. Hence why the share price has recovered so well to previous highs (and beyond possibly in future?)
Gross margin - also decently up on LY at 29.9% - that’s quite low, but the average spend is over £100, so it works out fine. Also, low margins don’t attract too many competitors seeking to eat your lunch.
EBITDA - this looks superb;
FY21 EBITDA to be ahead of expectations, and not less than £16.5m (FY20: £7.8m)
Directorspeak makes the point that when restrictions are lifted, many musicians will be itching to perform together again driving other product categories. Therefore I don’t think lockdown should be seen as a one way street (i.e. just boosting sales), as it’s actually more mixed.
Brexit - carefully planned for & managed. G4M had already set up hubs in Sweden & Germany, some time ago, which has helped get round port & Brexit issues.
I am pleased that the planned reconfiguration of our delivery systems and transport network has performed well, and has supported stronger trading since 1 January 2021 than the Board had initially expected.
Outlook - all good;
As a result of the very successful Christmas trading period, and early indications of positive trading post-Brexit, we expect to report results for the full financial year ahead of recently upgraded consensus market expectations. Notwithstanding what has been an exceptional period of trading since lockdowns began in March 2020, the Board remains confident that the Group is well resourced and positioned to deliver further growth."
Broker note - many thanks to N+1 Singer, for making available to us an update, via Research Tree. This now forecasts 44.8p adj EPS for FY 03/2021. At 885p per share, that’s a PER of 19.8 - that seems great value to me for a growth company.
I suppose it depends if you see this year as a one-off, boosted by lockdown, or if growth is likely to continue (maybe not as such a rapid rate?).
My opinion - I think this looks a very attractive share. Growth at reasonable price. It’s clearly a very well managed business, well done and thank you to Andrew Wass and his team, not forgetting the European division who’ve delivered superb growth there. I very much like that growth in the biggest market is expanding the fastest, as there’s so much more growth to go for in Europe.
An emphatic thumbs up from me.
.
Portmeirion (LON:PMP)
548p (up 10%, at 14:12) - mkt cap £77m
Encouraging performance, ahead of market expectations, due to strong seasonal trading
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Wax Lyrical, Nambé and Pimpernel brands, is pleased to announce that it expects revenue for the year to 31 December 2020 to be at least 6% ahead of market consensus expectations following a strong second half and seasonal trading performance.
H2 sales down 7% LFL, better than 20% in H1 LFL
Online - this is the key area for me, and it looks very good;
Online sales channel growth remains a key area of strategic focus and investment. Online sales performed strongly through the second half of the year. We now estimate that 47% of our total UK/US sales are made through online channels (2019: 30%) and sales from our own ecommerce platforms grew by 60% from 2019 and now represent 13% of total Group sales. We expect to see continued growth in online sales channels in 2021.
My opinion - there’s plenty more detail in the RNS, I’m getting tired now, so want to wrap this up.
Broker notes are available on Research Tree. I don’t see PER as a relevant way to value the business right now, as it’s in gradual recovery mode. To my mind, it should be able to gradually return to previous levels of profitability, so I think that implies a share price which could recover to about double where we are now, with patience.
I see this as a tuck away & forget type of share in my portfolio. Small to medium sized position, long term.
Today’s update reassures me.
.
That's it for today, see you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

164 comments
Re Saga (LON:SAGA) and insurance. They already do.
From their website:
We’re working hard so you can travel with us again soon. Our award winning holidays and cruises now offer more peace of mind:
Our optional included travel insurance for over 50’s is on all overseas holidays and includes up to £5m emergency medical and repatriation cover for coronavirus.
I've been back invested in Boohoo since the last substantial pull back, buying a decent-sized chunk (by my standards) at 288p. It's going well so far. I sold out my original holding - bought at 47p - when the shares first passed 200p, foolishly deciding to re-invest the profits elsewhere, including in Sosandar at around 30p, which seems a long, long time ago. In retrospect, that was an obvious mistake. Doing nothing would have been a much more profitable course of action. The same applies to the other shares that I was selling in the first quarter of 2020 - namely Treatt and XP Power. Both rebounded from the initial Covid Shock a lot more strongly than the shares that I opted not to sell...
Moral of this story? If it ain't broke, don't fix it. If it's making money and growing, leave it alone. Will I, though?
Thanks and a belated Happy New Year to Paul, Jack and all readers here.
B2V
I'm highly sceptical of these "gurus" talking their own book especially when the stock has already had a very strong run. They'll always drone on about how "there's much further to run" etc. Classic ramping so they can further pad out their profit. Xaar (LON:XAR) was a value/recovery type situation so inevitable that a profit taking peak was coming.
RE: BOO. Great notes Paul much appreciated. Ive held BOO since 2017 and my tactic has been to ignore the noise and add when it’s cheap. Seems to have worked a treat as I’m over 100% up. I can never understand the reasons why we see the dips on good news and whilst they are frustrating the general trend is up, it won’t be down for long with earnings upgrades. When you think about the challenges we have seen and overcome this year, to be expecting 70% growth in earnings is quite amazing. I wonder what can be achieved next year when restrictions are over and higher margin products like dresses are back in favour. I was concerned that the pe might start contracting at some point if growth couldn’t be maintained but with the expected 9.3 eps this should support higher PE valuations we have seen in the past. As you say it looks cheap to me when you consider future earnings and the potential we have for further acquisitions.
Ref vaccine rollout
there is one really bit of good news If the linked story in the daily mail can be relied upon (we all know daily mail aint always a good source of the truth!!!)
According to their article there are now 21 million doses of vaccine on uk soil - this is most excellent news if true.
Note the article is clear that a high % of these doses still need to be put in vials and then they will need to undergoe regulatory checks but it is pleasing that what is probably the hardest part of the full delivery chain is probably done for enough doses to give most vulnerable people an initial shot.
https://www.dailymail.co.uk/news/article-9144509/21-million-reasons-hopeful-Huge-number-Covid-19-vaccines-UK.html
Its the local distribution that's the weakest link, not the central supply.
Let's hope that the pilferage rate is also low and that corruption is limited.
I do think that holidays will return relatively quickly.
Just think of all the people going stir crazy in lockdown in their small flats and houses with their screaming kids. And if the adults have been vaccinated and the kids are not in a high risk group, why not take a holiday? (Assuming that all the adults in the general population have been vaccinated).
But timing will be crucial as we see that different countries are at different stages. So, if the timing of the opening up of the travel market is delayed but just a couple of months, that could devastate the summer holiday period. So, travel stocks are still too risky in my view.
WARNING!!!! - FOOTNOTE OF NO VALUE BELOW!!!!
On a more flippant note, we have a lot of cruise ships hanging around doing nothing. In days of old ships were turned into prison hulks holding inmates before transportation to Australia etc. (as happened to one of my ancestors). I do think that these idle cruise ships could be repurposed to hold the anti-lockdown protestors, the mask refuseniks, the anti-vaccination mob and any other group that feels it is ok to spread the virus about because it is their individual right not to give two hoots about the health of anyone else or believe anything they are told by government or anyone else for that matter except for those nice conspiracy theorists who are always right about everything . Mr Musk's self driving technology can drive the ships round in a circle until the rest of us have decided where to deposit the 'passengers', if any of them survive that is.
News just in from Aa (LON:AA.) the meetings have been held to approve the Scheme of Arrangement and implement it - the scheme passed with large majorities as detailed here https://www.stockopedia.com/sh... and "the Scheme is expected to become effective in the first quarter of 2021." So ends another sorry tale in which PE owners extract value through borrowings and float a business which then struggles for years under the weight of unsustainable debt. It's a great brand that deserved to be treated with more respect, in my view - as did the staff. Hopefully the new owners will do better.
papers at it again with Boohoo (LON:BOO)
https://www.ft.com/content/f1e...
I imagine many fashion retailers are just as bad if not worse than used to be the case at £BOO. Just haven't had the spotlight on them so are getting away with less than ideal behaviour.
Low margin and sales flatlining LON:RNO. Im guessing 3D printing will disrupt this type of business
Paul - I'm sure you managed to bank some nice profits from £BOTB. If you've recycled them well in other stock and you've kept some skin in the game, then it's no bad thing! You were dealing with information that you had at the time by the sound of it.
Greatly appreciate your work as ever.
An interesting read on Naked Wines (LON:WINE) seems like they have doubled the size of the business. Not sure by what metric. Stock seems a potential issue but a nice problem to have. https://www.retailinsider.com/...
Can anyone explain why Xaar (LON:XAR) was hit so hard today, the result didn't seem so bad?
I imagine that the problem today was that many people had invested in Xaar (LON:XAR) with the expectation of achieving rapid share price growth. The trading update was not of the shoot the lights out variety, so many of these investors were disappointed.
Trading was in line with expectations, the balance sheet remains strong. I agree with you, today's price action was over the top. I would hope that the price will rise tomorrow.
Wasn't Xaar (LON:XAR) heavily tipped by some "guru" investor as a top pick at the end of 2020? I vaguely remember reading or watching about it.
You only have to look at the ADVFN bulletin board to see which shares are full of private speculators.
Boohoo (LON:BOO) is an example too. Upgraded revenue forecast for the FY by a good margin, yet the SP is down! You look at the ADVFN boards and its one of the most active. Way too many private speculators = share price is probably artificially too high atm.
Xaar (LON:XAR) - The "guru" investor that you referring to is no other than the Cockney Rebel who I've seen is a also a member of stockopedia ....if only we had a crystal ball!
Gear4music Holdings (LON:G4M)
Hi Paul - I am also long here. Love how this business seems to be managed and reminds me of Boohoo (LON:BOO) in a lot of ways....came to the market on a high, made a mistake that cratered the share price but management good enough to understand how to amend model to return to strong growth metrics. Todays results were phenomenal in my view and back to net cash as well by the looks of things.
I would say that I think the share price is heavily hampered by the lack of analyst expectations for next year. Anyone looking at these will just see the old estimates of around 26p eps forecast and clearly the share price would look up with events if you take that in isolation. However, given the increase in margins and strong growth in Europe I'd be really surprised if they don't at least match this years numbers and a PE of 18 looks too cheap. to me. One thing that people need to remember on this share is that management report on gross margin at approx 30%. The remaining costs of running the business appear to be pretty fixed, so a big chunk of the 30% on new revenue drops straight to the bottom line. Thus from here on in relatively small increases in revenue will have a much larger impact on EPS as the operational gearing has kicked in.
I think this is a v well run company with interesting plans for the future in terms of European expansion and developing its offering. I'd expect it to continue to benefit from lockdown at least until the financial year end (March). However once we unlock although there will likely be a boost to the "live" music part of the business e.g. live & PA, and maybe orchestral, these are only 18% of the business vs Guitars, Keys, Studios and Drums being over 80% (as per H121 numbers) so I'd expect these to ease off in FY22, and I'd think equalling FY21 revenues in FY22 might be challenging. If so, and assuming forecasts reflect this, the SP might pause for a bit before the solid growth trajectory resumes in FY23.
If anyone is interested, good old unsteady eddie Eddie Stobart Logistics (LON:ESL) - it's on a tear! A turnaround story with good recent positive TU + fundraising. New clients Nike, Amazon and Morrisons. Loads of debt tho but then what else to expect after rescue by PE firm Dbay. What captured my attention today was https://motortransport.co.uk/b... + recruitment of staff - must be busy with a crossread to Wincanton and Clipper.
Not share related but it is SCVR related.
Some idiot(s) cut and paste sections of this report, Boohoo (LON:BOO) today but its happened before, onto other Bulletin Boards. I am sure there is a copyright issue, but remember we are paying for this and you are giving it away for nothing.
I would raise it through to the admin team, not a lot that they can do but others want to get credit for something that they have not done, it unfortunately is a part of life, whether here or at work...
This differs somewhat from the Public Health figures in the link (updated 12/01/2021) - which says
"Flu vaccine uptake rates are higher than the same time last season for all other eligible groups."
Also, we are still administering the Flu jab for this winter and percentages will rise further.
Boohoo (LON:BOO) Q4 is a key trading period for them.
Y-on-Y and some slowdown in growth in some areas:
US (57%; 19-20, down to 51%; 20-21),
RofE (54%; 19-20, down to 32%; 20-21) - biggest drop in growth so could be more to it?
Small slow down in UK when looking at last year to this (42%-40%).
Still strong considering everything which is going on with covid but that seems to be why some selling.
Rest of Europe poses a question of whether it is more trend/brand related, but the other two could just be covid related.
Markets are also a bit down in the dumps today.
I took some risk off coming in to this update and got a lot of slack for saying that here but it was just my opinion. The reaction isn't a big one but might provide a new re-entry point as it is still overall a good update - just a question over RoE...
Hi Jack,
Love the sectors you like to cover. Keep adding value to Stocko's SCVR
BSV
Portmeirion (LON:PMP) has been motoring along quietly under the radar with a rather positive TU today. Very encouraging!
Hi maxistaxis,
Portmeirion (LON:PMP) is next on my list!
I'm typing this on my exercise-bike-with-a-desk-instead-of-handlebars. It's a terrific thing, but there might be some typos to correct later!
PMP section should be up by about 3pm today.
Regards, Paul.
haha sounds like me - typing whilst jogging on the spot!!!
Exceeds expectations Portmeirion (LON:PMP) trading update today - revenue at >£87Mn, "at least 6% ahead of market consensus expectations" . How precise is that ! Net Profit will also exceed expectations .
Although LFL will end 2020 12% down, own website sales are up 60%(at >10% better margin according to MD on Investor Meets Company call I saw) and are now 13% of total.
Online (as for everyone) has been a stated strategic focus area but now real signs they are improving. In support of this, qualitatively, as an ex FMCG Mkt Dir, I review their promotions /websites regularly and see real improvements in both their online strategy (eg new gift products) and execution (better photos, use of clearer fonts) which I attribute to the new hires brought in in last 12M and investments made like new fulfilment warehouse. Not rocket science but they were behind the times in online before before and their product line up and brands is ideal for direct to consumer selling . (However, IMHO still cheapening brands with with constant huge discounts and much more that can be done to build equity / sell collections).
Getting online right from being weak could be a real catalyst. Having issued equity and raised £10Mn at 380p in the summer with a 25% dilution, £PMP now has all the money (and talent) it needs to drive sales online. At the same time it is cutting costs via automation and a new fulfilment operation.
Price in p5Yrs before COVID was in range 800-1100p vs current 550p. Very easy to see how it could get back to this range in 12-18months even allowing for extra share count.
I obviously hold and want to buy more. What negatives do people see on a 2 year basis?
Sorry not a negative but I would add the average EPS over the past 3 years was 58p. If they can get back to those levels which certainly seems achievable given the online growth (47% of total UK/US sales online in 2020) that puts it on a PE of around 10. Compare that to Churchill China (Results were out on Monday) which has a forward PE of 29 and is very reliant on the UK hospitality sector. (I hold)
Portmeirion (LON:PMP) Primarily execution risks - I recall from the CEO's interview with Paul that they have not entered the Chinese market yet. Big big market there.
In the 1980's it was the Japanese who were intrigued with the British culture (from music, to our culture and clothes (I had many Japanese friends) , let's hope that it is the Chinese' turn to be fascinated with our fish and chips, our pint of beer and last but not least our Portmeirion (LON:PMP) dishes particularly our Botanic Garden series!!!
So it seems that the market had already priced in the Boohoo (LON:BOO) trading improvement this morning with the share price up 20% over the last month. The improvement wasn't much of a surprise since other retailers like Next and ASOS had already reported good online trading.
Maybe it needs some good news from the Agenda for Change programme to tempt major shareholders back. Perhaps there will be some good news in the A4C report alongside the Annual Report. Also Boohoo will be publishing their UK supplier list by the end of March and their global supplier list by the end of September. This could negatively affect the share price if there are any further supplier problems, but presumably the delay in publishing the lists will allow them to get rid of any problem suppliers..
I'm hopeful for an improvement in the Boohoo share price in 2021, but it may take some time by the look of it.
Also of interest to holders of SAGA or similar, the BBC say TUI travel is seeing an increase in bookings by the over 50s due to "vaccine confidence"
https://www.bbc.co.uk/news/bus...
And can everyone please take note of the guidance on posting please.
The growth does look a little priced in at Boohoo (LON:BOO)
Even at new Zeus EPS estimate for FY21, at 8.7p. Let's say it is a good beat in the last two months, put it at 8.9p.
The medium term guidance from the company is 25% revenue growth YoY. For next year FY22, given the huge boost in FY21 due to COVID, lets assume maybe slightly below. 20% revenue growth, maybe translating to 30% EPS growth due to operational gearing.
Certainly, a 30% increase from FY21 to FY22 looks factored in by Zeus in their FY22 EPS estimate.
So 30% increase FY21>FY22 EPS is 11.3p.
Then it all becomes a game of what you're willing to pay for the growth:
25x: 283p
30x: 339p
35x: 396p
40x: 453p
Personally I think at the current 360p it makes sense, as over the next 12 months I can see this easily shoot up to 50x EPS (565p) on Market Euphoria. Therefore there's potential 57% upside, in my mind. Downside is valuation multiple bubble popping, this goes to 20x (220p) representing a 37% downside at 360p.
All assuming though that management can keep growth going in FY22 and there's no bumps / issues on the road...
Actually I think 20% is too modest. Boohoo (LON:BOO) management typically tend to steer to the downside and beat rather than miss so I suspect they are confident of 30%+
Nonetheless the key takeaway for me is the US growth. They have barely scratched the surface here and if, as now seems a not unreasonable assumption, they have genuinely cracked that market then it seems to me that they really do have the nouse and opportunity to be a global juggernaut. I bought recently down at 260p but rather wish I'd bought more and may well do so if it drifts.
Charles Stanley discretionary business is one in decline. The 5 year chart clearly illustrates this
Does Pressure Technologies (reporting today) fall under your remit ? (LON:PRES) Interesting Co. lots of potential upside, successful fundraising, pivoting in to Hydrogen storage. They look well run and have managed Covid headwinds well. Are you planning to review them ?
Thanks
Alan
U might this useful Alan - file:///C:/Users/New%20User/OneDrive/Documents/Other/Pressure_Tech20201103.pdf
Investors champion may even have an updated version.
Pressure Technologies (LON:PRES) oops - appears to be an internal doc - here is the link for the report investor champion produced.
https://www.investorschampion.... 3rd time lucky!
I'm too busy today to look at Pressure Technologies (LON:PRES) sorry about that. Also it's so small & illiquid that if it's good, then readers probably wouldn't be able to get much stock, and could end up competing for it, and triggering a spike up in price, which wouldn't be a helpful outcome.
Paul apologies I know Whitbread are too big for this page but just as Next provides oversight for retail I think Whitbread give an insight to the hotel market. What is more I like Whitbread because balance sheet strong as got funding away early and good growth story in Germany. I think Premier Inn section of industry will be less impacted than luxury. Accommodation thru 2020 broadly flat but 2021 to end of 3rd qtr down 70%. At end of qtr 3 had 91% of hotels open. Now since this the lockdown has been initiated so I am guessing pretty much shut down now. Germany is under similar rules. Whitbread have added to their portfolio in Germany adding 13 hotels from Centro group. So my point is there are going to be clear winners here which with strong b/s, clear focus and good management will emerge in a slimmed down and less competitive market. What will this mean for hotel room rates? Airbnb at the ridiculous valuation they keep quoting. Is the strategy buying smaller weaker groups to be bought out? or stick with the titans? I see hotels as a more robust way of playing hospitality rather than cocktail bars etc. On that subject i see Nightcap (NGHT) came to aim yesterday.
"less competitive market"
I take a contrarian view to Whitbread (LON:WTB)
While many hotels might be going bust, all the big chains have survived more or less intact. And when a hotel goes bust, the building usually can't be easily turned into apartments, offices, shops, etc. So the landlord has no choice but to find another hotel tenant. So I don't think capacity is coming out of the market anytime soon, as those bust hotels will just be bought by existing chains (of which there will still be many) or hoteliers, who will get super cheap rents, and/or rent-free periods.
Arguably with softer inner-city long term rental market, more landlords, unable to sell at the valuation they desire, and long term rents not covering mortgage & operating costs, will maybe see no option except go to the short term, AirBnB market when travel resumes. Thus maybe more competition.
Paul at the risk of breaking the rules could your rules not be in a permanent drop down div above the Securities mentioned section on the right? I know all at Stocko must be up to their eyes combined with the difficulties of WFH but would have thought this could be quickly implemented and help newbies to SCVR understand the “rules” and help regulars not suffer from a moment of weakness (of which I know I can suffer from sometimes :-))
Regards
Michael.
re BOTB, terrific interims again. Having done so well on this share I decided to enter a competition, the checkout failed to tel me that I had put in incorrect credit card details (card expiry 1 month out by mistake) the site just did nothing, I noticed though and was then able to enter. I have fed this back to BoTB as I believe they have stated that some people do not complete entries. I hope this is a great help to them.
Many thanks for this tip Paul.
Saga (LON:SAGA) - an interesting update regarding the increase in bookings in the travel sector from the over 50's. Saga shares seem to be up on the back of this.
Saga still seems like an astonishing opportunity to me. Volatile in the short term but almost certain to double over the next 2 years.
Camraid - £SAGA Your comment - an interesting update regarding the increase in bookings in the travel sector from the over 50's. Saga shares seem to be up on the back of this.
I am interested - Where is this news? It doesn't appear to be on Saga (LON:SAGA) news
Hi ezlifeme, it's a BBC story you can read here. https://www.bbc.co.uk/news/bus...
Implications for Saga (LON:SAGA) are positive
cheers
Francis
fwyburd - Re the Saga (LON:SAGA) Related Story - Many thanks for the link
Hi ezlifeme, it's a BBC story you can read here. https://www.bbc.co.uk/news/bus...
Implications for Saga (LON:SAGA) are positive
Surely this is no different to any other year though - aren't the first few weeks of January traditionally when people of that age book their holidays? I know my folks do. Given that this time last year no-one had heard of Covid what we really need is a like-for-like figure for bookings. Whilst it may seem positive, I bet the number of bookings is way down on 12 months ago. This looks like a usual Beeb advertorial puff piece to give airtime to the travel industry. I really despair at the quality of journalism on the Beeb website.
I don't really have a view on Saga as a company (and can't think of a worse kind of holiday than being stuck on a boat with hundreds of other people for weeks!) but I would think if you go on a cruise you would reasonably expect to disembark occasionally when in port? It will be interesting to see how many other countries want a boat load full of Brits walking round their port cities anytime this year.
All the best, Si
Re £SAGA 'Concerns about having Brits walking around their port cities' - well if the Brits have been vaccinated then I guess that other countries will be delighted to start up their tourist businesses again!
Re Saga (LON:SAGA) 'Concerns about having Brits walking around their port cities' - well if the Brits have been vaccinated then I guess that other countries will be delighted to start up their tourist businesses again!
I think you're maybe missing the point. I'm not sure if the borders are still closed that people will be able to disembark from a a ship, regardless of whether they have been vaccinated or not. The risk of doing so far outweighs the reward to the host country. And we haven't even considered the effect of Covid nationalism? Even if the government of a country allows entry, the local population may not be happy or receptive. I'm sure I have detected strong signs of such nationalism between the English, and Welsh and Scottish devolved governmenets over the course of the past six months, or maybe I was just imagining it?
There have also been instances of nationalism in Switzerland where Brits allegedly left a ski resort and fled the country when they were supposed to be isolating. And then the world famous Lauberhorn downhill was cancelled supposedly because a British superspreader caused an outbreak in Wengen. Reality and perception are very strange bedfellows. I would say the perception of us is already not great, and who wants to go on holiday somewhere where they are not made to feel welcome.
All the best, Si
Re Saga (LON:SAGA) I've never been on a cruise and have no desire to do so but wonder if ships would fill up anyway with people more than happy to go on a floating hotel where they experience good weather, seeing a few different coastlines, being pampered, eating and drinking as much as they want and don't really care if they can't get off the boat to mingle with the locals.
I rather suspect enough might to make Saga (LON:SAGA) shareholders happy.
Of course, one of the main issues will be the availability of travel insurance for the age group attracted to cruises. Once you get into your 70's and have even quite minor underlying health conditions I have been told it's hard to get cover in normal times. In a world still reeling from a pandemic it could be virtually impossible. Given they have an insurance arm this could be a real advantage for Saga i.e. providing customers travel insurance with their holiday.
Purely on personal experience, I don't know anyone among friends and family who is even thinking of booking a holiday currently. So I'm a little sceptical about the Beeb report today.
All the best, Si
Given they have an insurance arm this could be a real advantage for Saga i.e. providing customers travel insurance with their holiday.
Excellent point re £SAGA.
On a separate tack, I imagine travel insurance for anybody over 50 who has not had the vaccine will be either very expensive or unobtainable.
On a separate tack, I imagine travel insurance for anybody over 50 who has not had the vaccine will be either very expensive or unobtainable.
I think that would be a reasonable assumption. Only last night I was reading about a care home that was prepared to take in Covid patients that could not get indemnity insurance renewal for a policy that runs out at the end of the month.
All the best, Si
Sorry. I forgot to add the link: https://www.bbc.co.uk/news/bus...
Re Saga (LON:SAGA) and rising booking by older consumer with vaccine roll out, the same story is in the Daily Mail today - it's origin seems to be PR driven quotes by TUI (travel abroad) and National Express (domestic). Nevertheless, it re-inforces the idea of pent up demand led by cashed up , locked down elderly. https://www.dailymail.co.uk/ne...
Such narratives if they get into mass media , can become drivers in their own right.
FWIW, some info that might provide some context to the bookings of all travel agents. The cruise line I normally use is now allowing bookings up to the end of 2023 – a year further ahead than ‘normal’. It could well be the surge in bookings is for travel in 2022/23.
Re Boohoo (LON:BOO) - I was disappointed that they didn't break down revenues and margins per brand this time.
Same TU last year gave breakdowns for BooHoo, PL and Nasty Gal. Would have been good to have got some colour on these as well as the newer brands to see better where the growth was coming from and just "how well" the newer brands are bedding in and contributing to the long term outlook.
Paul, do you read anything into this omission - or maybe more colour is/was given during the investor and analyst conference this morning call which I missed.
Or am I being a bit too pedantic??
Hi Laughton,
Re Boohoo (LON:BOO) - I was disappointed that they didn't break down revenues and margins per brand this time.
They stopped doing that, and said so at the time, at some point last year. So it's not a surprise, hence no, there's nothing to read into it.
Regards, Paul.
COVID-19 seems lilely to remain a big factor in market performance in the next months. https://henrytapper.com/2021/0... has an interesting actuarial analysis of the effects of the vaccine.
The conclusion says in part:
Nevertheless, if the programme goes reasonably to plan it can be expected that there will be an 85% to 90% reduction in COVID-19 deaths by the middle of March, although the reporting of this will take a little longer to emerge completely.
However, the stresses on the health service, and particularly ICU units, will not be completely addressed by this first phase – the need to manage this through some degree of continuing non-pharmaceutical interventions will undoubtedly be a challenge as society will increasingly be looking for a return to some degree of normality.
COVID-19 seems lilely to remain a big factor in market performance in the next months. https://henrytapper.com/2021/0... has an interesting actuarial analysis of the effects of the vaccine.
That's really interesting. It suggests ICU loading will remain high into April but hospital admissions will start dropping noticably from the beginning of March.
However, it also assumes 100% take up of the vaccine, that the vaccination targets can be hit and doesn't take account of second-order effects - e.g. lower age groups starting to engage in more risky behaviour. Nor does it take account of the extra transmissability of the new variant.
If anything, I'm tending towards expecting a slower lifting of restrictions than I originally expected. Perhaps reductions from mid March and full "normality" towards the end of April?
timarr
I report my status on the Zoe/King's College app daily. I just noticed today that they have added a question to ask if I will be prepared to take a vaccine when offered. The fact they feel the need to ask suggests there are people declining.
Anecdotally I hear that some older people in the risk groups currently being targetted are declining the Pfizer vaccine because it's German and saying they want to wait for the British one. Strikes me as a good way to risk dying of racism, but there we are.
I report my status on the Zoe/King's College app daily. I just noticed today that they have added a question to ask if I will be prepared to take a vaccine when offered. The fact they feel the need to ask suggests there are people declining.
Recent Oxford study suggested 72% prepared to take it:
https://www.technologynetworks...
That should be enough for herd immunity but there's going to be other sorts of pressures - so, for example, Pimlico Plumbers are changing their terms & conditions to make working for them conditional on having had the vaccine. Unilever are saying staff either need to get vaccinated or have regular tests.
You can understand why - no company is going to want to be sued for providing an unsafe workplace or putting their customers at risk.
On a tangent, Unilever also the latest company to confirm that they won't return to full-time office working. It's going to be really interesting to see what the new normal actually looks like.
timarr
On a more positive note I see this report in the FT says that a previous Covid infection has been shown to provide as much immunity as vaccines. So we can add those people who already survived the disease to immune part of the herd for now at least.
On a more positive note I see this report in the FT says that a previous Covid infection has been shown to provide as much immunity as vaccines. So we can add those people who already survived the disease to immune part of the herd for now at least.
That research is odd - of the 44 reinfected people there were 2 probables, both of whom self-reported their first infection and didn't have a test, and 42 possibles. Nonetheless the consensus medical position is that immunity after a coronavirus infection should last between 6 months and 2 years, so hopefully it's correct.
We'll have to wait until enough time has passed to see what the reinfection rates actually are. Given mass vaccination in China and Europe that may mean seeing what happens in the US and Brazil, where the response has been chaotic.
On a side note, natural immunity tends to last longer than vaccine induced immunity because a vaccine is a weakened form of the virus. It's not always true, but it's a decent rule of thumb.
timarr
If the eventual result is 72% take up then I would be a little disappointed. I would guess that this will not be much different from the Flu figures for winter 2019 /2020.
Government figures for Flu can be found here and show a predictable uplift on previous years.
I had a look the 2019/20 figures for flu, it is only 72% for persons over 65:
"72.4% for patients aged 65 years and over compared to 72.0% in 2018 to 2019.
• 44.9% for patients aged six months to under 65 years old in one or more clinical risk
group(s) compared to 48.0% in 2018 to 2019
• 43.7% in all pregnant women compared to 45.2% in 2018 to 2019
• 43.8% for patients aged two and three years compared to 44.9% in 2018 to 2019"
I had a look the figures for flu, it is only 72% for persons over 65
Yep. The main problem is likely to be that younger people don't bother to get vaccinated as they don't perceive themselves to be at risk and will, presumably, feel that once all the oldies are vaccinated that they don't need to worry any more. Unvaccinated older people will probably be at quite significant risk for years to come.
There are lots of issues with low levels of vaccine take-up but probably the biggest one is that by allowing the virus to circulate you increase the chance of a mutation occuring which will escape the vaccine. Which is just one of the reasons that the "Swedish" approach and the Great Barrington Declaration were wrong.
There is a good chance we'll have a recurrence of CV-19 down the line and the longer it takes to vaccinate the whole world then then greater the risk. But on a stock related note I think this means that the demand for testing services isn't likely to decline much. We also probably want to make sure that any businesses that require face to face contact have really strong balance sheets, because they may face further restrictions in future.
I'm really in two minds about the travel sector. Clearly there's huge pent-up demand but you just know that a single slip-up could cause havoc. But still, I hold On The Beach (LON:OTB) and Saga (LON:SAGA) - got to take some hope from the vaccine rollout ...
timarr
I think the Covid vaccine uptake will be higher than for flu vaccine, which I never have had. Yes not sure about travel either, I do hold Saga (LON:SAGA).
My 72% figures, were for the 2019/20 winter, the link was for this year was not there when I responded.
Timarr,
Regarding travel sector, I'm fairly clear at this point that at the very least, we can expect extremely strict border controls throughout the western world over the next 12 months (and more likely 24-36 months). There are several factors I think are important:
1) Even if the UK is able to roll the vaccine out, other countries will not be able to at the same pace. And each country is likely to have different rules for people moving between them. So in effect, no country is safe unless they enforce blanket travel controls.
2) We still don't know the effective protection from the various vaccines and won't until they have been tested at a population level. 90% for Moderna may turn out to be 60%, 70% for AZ may turn out to be 95% - we just don't know.
3) We don't know how long the vaccine protection will last (although latest reports indicate antibodies last for about 5 months on average).
4) We know the virus is mutating and will continue to mutate. Although RNA vaccines are slightly quicker to tweak and produce (circa 6m) than AZ version (7-9m) it still will be a race requiring continual adaption and updating.
5) Although the UK has good vaccine acceptance, it is still only 77%. In other countries it is much lower (only 40% of France's population willing to take in last poll). The virus is too infectious - assume best case 80% take vaccine by 80% effectiveness means 64% reduction in virus only - it will still be here.
Any need to be tested before travel is not only added expense, it also is added level of difficulty. Any need to quarantine makes the majority of travel unattractive. Any reduction in scale makes travel much more expensive. Foreign travel is likely to become exceptional rather than the norm over the next few years IMO.
Hi Phuntt
Regarding travel sector, I'm fairly clear at this point that at the very least, we can expect extremely strict border controls throughout the western world over the next 12 months (and more likely 24-36 months).
I agree, but am a bit more optimistic around short-haul. Countries that rely on tourism - Spain, Greece, even the UK, will welcome visitors as long as they have proof of vaccination.
Getting vaccination up to herd immunity level everywhere is needed to reduce the amount of infections in circulation and reduce the chances of a mutation that can escape the vaccines. We're seeing a lot of mutations because there's a lot of the virus in circulation. Achieving herd immunity on a global scale will take time, so we may suffer another setback, but this time we're looking for it and have tools to fight back. Hopefully Biden will quickly reverse the defunding on the WHO for everyone's sake.
How long immunity lasts is the big question but the fact that we are beginning to see evidence that infection does result in some protection is enough to show that a vaccination program will work. We're only at the beginning in terms of developing treatments so I feel we can be optimistic looking forward.
That said, I agree, there's no room for complacency.
timarr
I agree, but am a bit more optimistic around short-haul. Countries that rely on tourism - Spain, Greece, even the UK, will welcome visitors as long as they have proof of vaccination.
The calculation is extremely difficult at country level. Countries like Greece are dependent on tourists but where do they draw the line? Vaccinations would have to recent so if vaccinated this month can you still travel there in July? Could I get another more recent vaccination if I needed it (vaccine stocks being what they are)? Could I book a holiday now relying on the fact that I (as a 44 year old non key worker male) will be vaccinated by July?
At a local level, yes there is will be some backing but also some resistance. For example, Donegal in republic of Ireland made it clear to all in Northern Ireland that they weren't welcome last August/ September even if virus levels were low in both jurisdictions and their economy depends on this tourist flow.
For the individual tourist, they now are faced with a more inconvenient, more expensive and less welcoming holiday where their freedoms and movement are likely to be heavily restricted. That's not even factoring in the increased risk to themselves of picking up the virus.
Holidays aren't gone forever but I don't think they will be staging a comeback any time soon.
timarr - you obviously keep more up to speed on the evolving covid situation than many (definitely me). Have the powers that be not been keeping track of what protection is given to those who have had covid? Surely the way to go would be to test say 1,000 people who had covid in February and measure how many still have antibodies and/or T cells giving protection on an ongoing basis. So, for instance if they test those 1,000 people in January 2021 and 950 of them show protection then isn't that saying that having covid is at least as effective as having the vaccine for a period of 10 months.
Then measure those same 1,000 people each month going forward plus test a different 1,000 people who had covid in March, April, May and so on and so on.
If, as I suspect, good long lasting (at least 1 year) immunity is gained by having had covid then isn't that a good argument for those who have had covid delaying having the vaccine to enable more of those who have not had covid to be vaccinated?
If the 10 million plus people who have had covid delay then we could reach "herd immunity" that much sooner.
Have the powers that be not been keeping track of what protection is given to those who have had covid?
It's not simple because there's no marker that says that someone is immune. We know that antitbodies decline quite rapidly but that there's still an immune system response in most people after that point. T-cell responses are an indicator but they don't signal whether people have immunity or not, just that there is an immune system response.
The only way of testing this is to see how many people get reinfected - I know it's incredibly crude, but that's the reality. We're dogged by the fact we don't know who had it a year ago, so it'll take time to tease out the data. Most likely this will come from Brazil and probably from Amazonia where 75% of the population have been infected - and are unlikely to get vaccinated soon.
But if you think about the sheer scale of the vaccine rollout and the limited data we have on who has had it or not and the fact we don't really know who is protected after having it then coming up with some algorithm that says that if you've had CV-19 in the last 6 months you can't have a vaccine is pointless. It would take more time to adminster than it's worth.
In any case, even if 10 million people have had CV-19 and they have immunity we don't know who they are and how long it will last. Far better and simpler to get everyone vaccinated.
timarr
How long immunity lasts is the big question but the fact that we are beginning to see evidence that infection does result in some protection is enough to show that a vaccination program will work. We're only at the beginning in terms of developing treatments so I feel we can be optimistic looking forward.
That said, I agree, there's no room for complacency.
PHE are obviously keen to avoid complacency too. There is what I find quite an odd phrase in their press release on the SIREN study today
.
This is factually correct, but it might be more informative if it also included a clarification : "We only have 5 months worth of data, therefore we can neither prove nor disprove whether protection lasts longer".
SIREN is an excellent study (tracking Healthcare workers with antibodies & going forwards those that have previously tested positive and/or have received the vaccine). I'm not sure how often they intend to report, but for a view of how things pan out in the real world , it is definitely one to keep an eye on.
Interesting take Gromley - I made that exact mistake. I read this originally as people could expect only 5 months protection. Hadn’t factored in the “at least” part and that of course that’s the only data that would be available at this point.
I read this originally as people could expect only 5 months protection.
The research out of Arizona suggests at least 8 months, but probably longer:
https://www.healthline.com/hea...
Research into seasonal coronaviruses suggests immunity normally wanes after about a year:
Reinfection with the same seasonal coronavirus occurred frequently around one year after the initial infection, which suggests that caution may be needed when relying on policies that require long-term immunity, such as vaccination or natural infection to reach herd immunity.
https://www.natureasia.com/en/...
As CV-19 as only been around just over a year it's a bit early to know. China has almost eliminated it, so we won't see reinfection data from there. The next epicentres were Italy, Spain and the UK which are engaged in mass vaccination programs, but we might get early data in the next few months.
I think best guess is we'll all be having a booster in the autumn for the foreseeable future.timarr
"As CV-19 as only been around just over a year it's a bit early to know. China has almost eliminated it, so we won't see reinfection data from there. The next epicentres were Italy, Spain and the UK which are engaged in mass vaccination programs, but we might get early data in the next few months."
Yes but, seasonal flu is also the same. This year's strains are "new" variants sufficiently different in their effects and vaccines from last years (a bit like how Apple with change the charger jack, head phones adapter, or leads every year or too, on what is essentially the same product, "a telephone computer").
Corona viri have been around for millions of years. Some form of COVID and related respiratory disease has been around for at least 20 years.
There's some articles saying how the diseased was reservoir-ed in Bats way before the breakout.
This isn't a surprise new problem. The medical scientists were dealing with these problems previously with the Bird Flu, Swine Flu, Ebola, Polio, Cholera. We had some drama over all of these previously.
Yeah, I think it is really poor communication.
If they had wanted to they could have presented the results as : "we have no evidence that immunity decreases over time and we have no data to suggest that post infection immunity is not permanent"
That would be equally true, but equally unhelpful.
I have no influence whatsoever with PHE, but I will be pursuing this nonsense with them.
I'm really in two minds about the travel sector. Clearly there's huge pent-up demand but you just know that a single slip-up could cause havoc. But still, I hold On The Beach (LON:OTB) and Saga (LON:SAGA) - got to take some hope from the vaccine rollout ...
I think as always during times of great uncertainty things lurch between being over pessimistic one minute to over optimistic the next. IMHO we are now in a period of the latter due to the vaccine rollout. Lots of stuff is priced to perfection with a return to "normality" expected far too soon IMO.
I have great faith in science, always have had, and it's astounding how quickly multiple working vaccines have been developed and made available for use. However, I take the view I don't need to gamble on the timing of the recovery and so don't need to invest in the worst affected sectors like travel, which let's face it, does not have the greatest business characteristics even during good economic times.
All the best, Si
"Yep. The main problem is likely to be that younger people don't bother to get vaccinated as they don't perceive themselves to be at risk and will, presumably, feel that once all the oldies are vaccinated that they don't need to worry any more. Unvaccinated older people will probably be at quite significant risk for years to come."
I think many people are absolutely, err, dying for a holiday and will party and **** like its 1945 as soon as they think this crisis is over...
Also, just to remind everyone that every corner of every high street has a tattoo shop on it these days. The "yoof" certainly don't have any issue with needles and minor short term pain be it tattoos, piercings or eye brow threading.
I think it is inevitable that having the jab will be a condition of travel on airplanes. Who would operate a plane where crew and staff could come into contact with infected fools?
You'd have to be some kind of idiot (or have a special reason like allergy, some cancers, or immune issue) not to take it.
Another point is that anti-lockdown hawks like myself are in a very small minority. The vast majority of The Public are irrationally scared of this terrible disease and so compliance is likely to be quite high and they are willing to accept disproportional cost both financially, in their lost dignity, in unfairness across society and in forfeiture of their freedoms. My side lost.
Good luck!
I think that some have more concern over the Pfizer vaccine because it relies on messenger-RNA co-opting our cells' genetic machinery to produce spike protein, and a theoretical concern with this new type of vaccine is a mooted cancer risk should these mRNA genetic instructions go awry. Those in vulnerable categories because of their age or underlying health conditions should certainly consider the potential mortal threat to them from Covid - as well as the point that vaccine safety issues have been thoroughly investigated - and they should joyfully accept whichever vaccine they are offered.
variant+s - Kent, S.Africa and Brazilian ....what's next?
The UK and South Africa have been among the few countries sequencing in any volume to find mutations. Now the US has started they have found two mutations in Ohio, one being identical to the UK one that appears to have arisen spontaneously there.
https://www.ft.com/content/e92...
Re. variant+s - Kent, S.Africa and Brazilian ....what's next?
I would expect an India, Pakistan, Afghanistan variant.
As an aside, I watched this morning:
https://www.youtube.com/watch?v=D5uh1kE_CDM
Those 3 countries were the very last in the world to eradicate the scourge of Polio virus for various local reasons and poor local health infrastructure.
I've noticed a fairly muted (at best) response to some very positive updates this week. Games Workshop (LON:GAW) , Boohoo (LON:BOO), and Jd Sports Fashion (LON:JD.) all down (I think) since their trading announcements - all of which, on the face of it, seemed very positive. Interesting. Seems the market has very high expectations right now for these companies priced at a relatively high PE.
Probably lends weight Paul to your view that Boohoo would be much better off with a U.S. listing?
Yes some are muted but others have gone crazy such as Reach (LON:RCH) which went up over 50% to 230p in the first hours and then fell back to around 214p.
I think Games Workshop (LON:GAW) the news was already in the price and usually the updates are more than expected, this seemed to be more or less as expected.
A lot of comments on here recently suggesting various, exciting UK companies should possibly seek a dual US listing to boost the share price. One thing to bear in mind, is that if all the attractive UK companies were to do so, and thus be exposed to the speculative froth of US markets, you may no longer be able to buy the shares at a sensible price. A US listing does little to improve the underlying investment opportunity in my mind, rather all it does is expose the stock to the unique American brand of enthusiastic fervour.
Also when AIM shares move or start a dual listing in the US they no longer qualify for UK inheritance tax relief because they are being traded on a recognised exchange.
With regard to Boohoo it was possibly muted because I think they referred to growth of 42% for 10 months to 31.12.20 but 40% for the 4 months to that date. So Sept/Dec increase was down on the previous 8 months and then they forecast 36% to 38% for the year to 28.02.21 which suggests a marked reduction for Jan and Feb although Paul believes this to be too conservative. It depends on the time scale of your investment/speculation but a quick reading of the RNS this morning suggested to me that it wasn't going much higher at the present time bearing in mind the PE ratio. Long term holders should not be too concerned.
There aren't many companies growing at 25% p.a. on a PE(f) less than 30. But that's what we have here. It's a 'no brainer' as far as I am concerned.
There might be dips and falls along the way (look at the chart - it's like the Big Dipper :D) but long term holding I'm just going to tuck these away, buy on dips and look to scalp 20% here and there if opportunities arise.
Good update from CAPD (London:CAPD)
Capital (LON:CAPD) , superb TU - ticks all the boxes. Can only guess, former shareholder Craig Burton is still selling his shares leaving overhang.
Hi Max.Yes a bit of muted response to very solid performance and excellent prospects. I think it might also be correlated more to gold price than is actually the case. Same problem with AIR partner that keeps getting aligned to airlines, travel and leisure which is also mostly not the case. Both should do well despite or in spite of current circumstances.
Interesting to see Science In Sport (LON:SIS) pop up as an occasional user of their products.
I've always seen this market as being one in which its hard to differentiate (variations on sugar, electrolytes, carbohydrates and protein) and hard to innovate (staying on the right side of sporting regulations, probably nitrates are the only new thing I've seen in recent years - and perhaps chewable energy blocks - ie gummy bears!).
It seems no surprise the total addressable market is set to grow "over £11bn with projected 8%pa growth to £18bn by 2023" so even if their slice of the pie does not increase, at least it will be a bigger slice of a bigger pie.
Also a fiercely competitive industry with direct competitors off the top of my head such as Nuun, OTE, Gu, High5 and Wiggle - but also indirect or unexpected competitors such as Nakd bars and Soreen! (ie food)
I've spent most of my time thinking about SiS rather than the PhD brand but they will have similar competition from expected places ie MyProtein and Bulk Powders (and less expected such as Huel, and again food products).
It seems that affiliations with professional athletes and teams as well as leveraging social media (and influencers) may be key in this market.
All opinion. I don't hold.
Paul
re Boohoo (LON:BOO)
I wonder if the big finds who were looking to exit are taking this as an opportunity to sell a load into positive results ?
With respect to Charles Stanley I tend to be cautious. Stock Broker stocks are a play on stock market exuberance. I note a lot of talk on twitter and bbs about penny stocks and explorers. Historically this talk comes at the end of a bull run. When a correction does come it will knock a lot of these short term traders out and impact on CAY. However I could be wrong and stocks could keep rising forever, in that case BUY BUY BUY and anyway it could be different this time...........
Off topic. How to win friends and influence people is 99p in the amazon kindle books deal of the day. Digital copy.
£boo The trading update was way better than I expected this morning. Where can you find a company growing revenue at the same rate for the same price? Let’s not forget about its adaptability – this is a company which thrives on selling dresses for nights out and yet is managing to thrive in absence of parties, pubs, clubs & dining out- a welcome relief for me. Also, when lockdown eases and these taps are turned back on boohoos growth surely can only accelerate around the world.
Re: US growth: I’m reading a lot more positivity on the UK market online these days and am hopeful that boo will soon be a beneficiary of this renewed optimism. I’d say the US market as a whole isn’t much cheaper on a PE basis when compared to boohoo’s forward earnings and there is no way it’s growing its collective top-line at 38%. If I were a US investor, I’d be eyeing boohoo very enviously.
Worth of note for Science In Sport (LON:SIS) they have a presentation this afternoon (1400hrs) on the Investor Meet Company site, may provide some extra details and insights in to their performance
£BOO. Headline on Bloomberg TV just now:
“Primark versus Boohoo becomes case study about need for online”.
Paul & Jack -I would just like to say thankyou for these monster SCVRs you have put out the last few days.
Xaar (LON:XAR) (Xaar) (I hold) (shares down 10% at opening)
it appears to me to be a very vague trading update. the only thing I learned was they hold just over £20 mil. in cash and the revenue was £48 mil.
have I missed something?
Re Xaar (LON:XAR) the update is indeed vague. It remains loss-making and, although the turnaround continues, profitability does not sound imminent. The valuation (2.6x P/B and 2.7x P/S) seems full at this stage so not surprised by today's fall. I believe the jury is still out on this one.
Hi Paul, many thanks for your excellent update on Boohoo. It's been mentioned elsewhere that ASOS gross margin doesn't include distribution costs whereas Boohoo's does. This means that ASOS gross margin should be even lower, if these were included. What's your take on this?
Mr. Market being unreasonable once again at Boohoo (LON:BOO)
I'd suggest that Mr. Market is always "reasonable", it just depends if you/we were able to guage a possible reaction and predict accordingly.
I often can't see why price movements occur differently to how I expected, but I've put this down to my inexperience in judging the entire world's view on what constitutes a good price for a certain stock or what all their motivations might be - "its more likely me getting it wrong than them".
in this case however, I agree that the update from Boohoo (LON:BOO) looks good so perhaps some big players have different expectations or as suggested elsewhere, might be offloading volume for other (eg ESG) reasons.
Oh, come on people! You can do better that this one-line twitter-like trader chit chat nonsense! And PLEASE make clear which company you are talking about. What a poor start to the comments today.
Si
I very much agree with simoan - cheerleader comments on every move of a share price should be reserved for the ADVFN boards.
Another plea to remember that there are SEVEN options for ways to read these boards so any reply will be meaningless to people using one of the four non-threaded options unless you put the company code in. Likewise please do not refer to posts 'above' or 'below' as it will be the other way round for half the readers.
Boohoo (LON:BOO) , what type of modern automated warehouse creates 1,000 jobs? That's either very padded or a very inefficient manual set-up. Details would be good to see.
a very, very big one?
A very big one that runs 24 hours a day, 7 days a week?
Utilizing some part time workers for flexibility
Fast Fashion = low inventory, fast production and re-production, low dead-stock. Small warehouse a sign of an efficient business. Only my guess (and hope) because I hold Boohoo (LON:BOO), the 1,000 is exaggerated.
Just a note re Boohoo (LON:BOO) Warehouse project
JOBS quoted on capital projects in my experience include everyone involved in creating the project NOT just working on it long term.
For instance - The guy and his mate who fit the hand dryer in the toilets in 2 hours are 2 people, etc etc
Re Boohoo (LON:BOO) warehouse. Assuming three 8 hour shifts, five weeks Holliday a year and 10% (too high?)sickness, that’s 267 people per shift. Doesn’t seem too excessive but may be I am wrong?
Regards
Michael
Michael,
They have four shifts. 12 hours per shift, 3 days on, 3 days off.
Many years ago I was a manager in the outsourced M&S warehouse covering London & the South-East. We had three shifts each of approx 30 people each plus a support office (HR, finances, planning, canteen etc) of about 50 and a transport team of about 50. This must've served approx 30 stores (including its biggest couple) so had a pretty sizeable footprint - approx 4 floors and about the size of 8 football pitches roughly. Therefore 1000 people must either be one of the largest warehouses ever or as stated above include evry Tom, Dick & Harry who touches it.....painters, decorators, security, gardners etc etc
I visited the Amazon Tilbury warehouse last year. Admittedly very big, but also very automated and modern, and they employ over 2000 people there (much more at peak times). It may not be a fair comparison but 1000 doesnt seem like a crazy number to me for a company like Boohoo.
Good update from Polar Capital Holdings (LON:POLR) today, makes Charles Stanley (LON:CAY) look a bit lacklustre.
Polar Capital Holdings (LON:POLR) while it's risen a lot lately still isn't on a demanding valuation.
Doug - Dont think its fair to compare these two companies - they are in quite different sectors of the market - but agree that on the face of it - CS appears lacklustre - am especially surprised how small the CSdirect division is. Shareholder list is interesting with 35% held by family and an impressive list of Inst holders. suspect there is more to this company than can be seen from the surface.
£BOTB half year results this morning were expected to be good and they didn't let down.
Revenue up from 7.6m to 22.1m and profit up from 1.4m to 6.8m.
EPS from 12.4p to 59.84p and another special dividend this time of 40p (giving me a yield of 20% from my original purchase price)
Whether this gets taken over eventually or not its a quality company that continues to deliver outstanding results. There was an interesting comment today about them seeking new ways to commercialize there database of 350k customers.
I hold and may trim in the forthcoming days if it gets above 2000 but plan to stay for the long term.
over £20 already and still undervalued. Even on a modest PE of 25 it should be £30
The takeout price will need to be north of this
Tried to buy more this morning but none available. Dummy sale in volume i was getting quoted £20 .
I would be interested in Paul's view as he is a big fan and a holder
.
Best Of The Best (LON:BOTB) (I hold) my concerns surrounding this company is what are the moats to protect it? It seems like it would be very easy for one of the large gaming companies such as £FLTR or Entain (LON:ENT) to replicate their model. I assume there is a bit of brand loyalty but there surely would be margin erosion should one of those companies start competing directly. This is why I feel it's rating will stay fairly modest for the growth it is achieving.
I think there are two main risks which do hold the company back. One is exactly what you say, it's surprising no one strong has come into this market so far and tried to take some market share. Most of the competitors are small and actually very poor.
2nd risk is with any gambling company related to government intervention and if legislation changes.
Best Of The Best (LON:BOTB) I don't agree it would be that easy. It takes a lot of money and management time to build up a business like this. The other thing is that the market is relatively rather small. The big gaming players are completely focused on the USA and sports betting where the potential market is in the billions of dollars.
This from today "Texas looks like it may bend to the pressure of competition, as the Governor’s office has now started putting out feelers about adopting legal sports betting. The office of Governor has reportedly been reaching out to states where sports betting is legal to get an idea of how to do it"
The potential market in Texas is just stunning in terms of turnover. Many billions rising rapidly year by year. By contrast, the "win a car" market is almost irrelevant. So I think this is most unlikely.
Well done to all holders! What a fantastic stock this has been. Many more special dividends on the way to all of us shareholders.....fingers crossed! It would be wonderful if our portfolios were full of stocks like this one.
When Graham wrote on this blog he noted that from a regulatory perspective Best Of The Best (LON:BOTB) relies on Spot the Ball being classified as a 'game of skill'. There's always a risk HM Treasury could decide it'll tax such games more highly or someone challenges whether this classification in Best Of The Best (LON:BOTB) case is correct. Note the lifestyle game does seem to be more obviously a game of skill and I have sometimes wondered if they have trialled that out in case they suddenly needed to switch away from Spot the Ball.
Fair to question what its moat is but I would now say it is the user database and the number of prizes it has on offer. Plus the website is very easy to use and they have built up a great digital marketing team.
Also important to remember that each £1 in revenue almost entirely feeds through to the bottom line. Hence the stellar revenue growth today has resulted in massive EPS gains.
I hold and topped up at 1900p today.
My morning smallcap tweet: 19 summaries. Phew!
Diurnal (LON:DNL) Capital (LON:CAPD) Lamprell (LON:LAM) Conduit Holdings (LON:CRE) Cyanconnode Holdings (LON:CYAN) Instem (LON:INS) £G4M Science in Sport (LON:SIS) Frenkel Topping (LON:FEN) Portmeirion (LON:PMP) Everyman Media (LON:EMAN) Senior (LON:SNR) Applied Graphene Materials (LON:AGM) Zinc Media (LON:ZIN) Finsbury Food (LON:FIF) Xaar (LON:XAR) Card Factory (LON:CARD) Powerhouse Energy (LON:PHE), ATTRAQT (LON:ATQT)
Diurnal (DNL) guides H1(Dec) rev up 6%. Sales growth in core commercial markets offset by timing of bulk sales to Nordic partner. Believes growth will significantly accelerate post pandemic. [SP=65.5 Cap=91m]
Capital (CAPD) Q4 rev up 18%. Outlook: "Trading conditions are extremely positive for Capital, with the gold price remaining robust, equity markets supportive and strong levels of tendering activity." [SP=62 Cap=117m]
Lamprell (LAM) trading in line. Strategic reorganisation "to increase the Group's focus on renewables and the energy transition, increase alignment with customers and enable the Group to take full advantage of the significant opportunities in its core markets." [SP=58.17 Cap=199m]
Conduit (CRE) Jan 2021 renewal season: Gross Written Premium of c$160m being in line. "Market conditions continue to show improvements across our targeted property, specialty and casualty lines." CFO scarpers. He is thanked. [SP=496 Cap=NA]
CyanConnode (CYAN) Q1-3 rev £3.4m. No comparative given! Module volume at record level. [SP=7.48 Cap=14m]
Instem (INS) guides FY(Dec) rev up 11%, in line. [SP=505 Cap=103m]
Gear4music (G4M) beats exp again with 3 months to Dec rev up 30%. Guides FY ahead of recently upgraded market expectations. [SP=836 Cap=175m]
Science in Sport (SIS) guides FY(Dec) adj EBITDA £1.1m (-£0.3m). Rev flat. Gross margin up 500bp. Will spend £4.3m on new Supply Chain facility. Co "remains very optimistic about the long term growth prospects." [SP=39 Cap=53m]
Frenkel Topping (FEN) says trading in line as takeover of NAH pulled. [SP=45 Cap=49m]
Portmeirion (PMP) guides FY(Dec) rev at least £87m down 6% but 6% ahead of market expectations. Net profit ahead of market expectations. [SP=507.5 Cap=71m]
Everyman Media (EMAN) the small cinema chain shows a brave face. We remain optimistic for the coming year post-lockdown and continue to have confidence in people's appetite to socialise and to be entertained; we believe we will be in a strong position once it is safe to welcome back our customers and teams." Strong position? [SP=111.6 Cap=102m]
Senior (SNR) slightly ahead of mgmt expectations. "Given the ongoing and unpredictable nature of the pandemic, our view remains that it is likely to be 2022 before we see a meaningful recovery in Group revenues and in 2021, Aerospace is set to be at least as challenging as 2020 given the current customer-announced production rates." [SP=91 Cap=382m]
Applied Graphene Materials (AGM) EU approves the use of graphene powder at larger volumes supplied by members of the Graphene REACH registration consortium." I'm surprised it's even regulated. Is there an environmental issue? [SP=58 Cap=29m]
Zinc Media (ZIN) Pre-booked rev for 2021 more than double from Nov update to £9.3m. Guides H2 rev up on H1. [SP=57 Cap=9m]
Finsbury Food Group (FIF) guides H1(Dec) rev down 4%: 'resilient'. Guides FY in line. [SP=74.3 Cap=97m]
Xaar (XAR) guides FY(Dec) rev flat. "On-track to return to profitability and growth." [SP=163.5 Cap=128m]
Card Factory (CARD) guides FY(Jan) rev £284m, pretax c. -£10m. Comparatives? "Whilst our short term cash requirement can be covered within our existing £200m bank facility, we anticipate that current covenants will be breached at the end of January....constructive discussions with our banking syndicate. " [SP=40.1 Cap=137m]
Powerhouse Energy (PHE) 'strategic' £10m placing at 5.5p, a 15% discount. Needed to "expedite signifcantly [sic] financial close of the funding of the first commercial scale DMG installation utilising the Company’s technology." That's not strategic, that's just to execute their business plan. [SP=8.5 Cap=316m]
In line: ATTRAQT (LON:ATQT)
the mighty Boohoo (LON:BOO) delivers again. Expect this to be a £6 stock within a year or so.
Shame the sp does not think so, as a large holder what a disapointing open
buy more at this price . At least I have
You really can’t worry about the price in the first 15 minutes on a results announcement day on a volatile stock like Boo.
Less than 30 minutes later we’re pretty much back to where we were yesterday.
and yet the shares plunge. Go figure!?
buying again
@Caper4, please note Paul's guidance today on 'reader comments'.
They haven’t plunged.
Lol at the person who ticked this down.
At 10:20 they're -2.4%, less than the spread on most stocks.
Boo has risen >20% in a month and >60% in 6 months. "Plunged" lol.
I think the thumbs down is not, as perhaps you perceive, due to someone disagreeing with your assessment of it (BOO) not having plunged, but more, or even entirely due to the nature of the comment itself and assessed against Paul's opening comment regarding readers comments:
"Does your comment really add value?"
I think there are more than a few people here who would agree that comments sure as "They haven’t plunged", and the comment you replied to "and yet the shares plunge. Go figure!?", would fall into the category indicated by Paul of not "really add(ing) value". Although these two posts are, sadly, far from being the only offenders of that this morning.
And now further, regarding your comment about your post receiving a thumbs down:
"Please don't comment on thumbs downs - again, nobody cares, and it wastes time for other people having to scroll through so many pointless posts".
Does your comment add value?
How many comments here really add value?
This bulletin board is paid for at best. and recommend everything said should be taken with a pinch of salt.
As always DYOR is best to add value.
BSV
My post wasn't about the "thumbs down", it was about the fact people think a tiny move represents "a plunge". I am commenting on the expectations of posters, and yes, I think explaining to people their expectations are off "adds value".
Whereas your post highlights you've failed to comprehend the basic point and ironically, frankly, adds no value.
SP action first thing seems a bit churlish.
Boohoo (LON:BOO) is my largest holding (13.63% of pf). £6 was the top end of the estimate I came to in reviewing my holdings at the beginning of the year (https://investing4value.wordpr... ) based on simple maths of 10 eps at 60 pe though I think say 11eps at 45/50 pe (495p/550p sp) is probably more likely.
Regards
Michael.
Agreed Michael. Boohoo (LON:BOO) now represents over 30% of my portfolio after buying more at 353 today. Too good an opportunity to miss .
The issue I think we need to consider with BOO (and asos et al), is that they've done really well in lockdown, they have focused on cheap stuff that people will buy anyway to feel good, and the shops are closed, so less places to buy clothes. Surely there must be some level of return to normal coming up ? what percentage of that huge growth, would have been spent int he shops ? Some of that will go back next year, (not all I accept some will permanently change), however if it's a quarter or a third, that will make next years figures look quiet different. 40% is incredible growth, but doesn't this (and potentially a higher one next year demand high growth). Lets run with my hypothesis, lets say that growth would have been 30% without lockdown, and humour me, half of that is going to disappear next year. That means we are starting with a headwind of 5% lfl growth, and if the underlying growth is say 30%, and no lockdown boost, does that mean all else being equal we would expect/get 25% growth next year ? pretty different feeling to 40% in terms of valuation. Now this is all rough cut figures and I know they;'re smart and will target higher price items next year, and party dresses will fly off the shelves as lockdown eases etc, but I'm just trying to illustrate that next year will be a lot tougher than this year, and boo will be up against tougher comparators than this year. I'd be interested in what others might expect. There's the possibility of picking up arcadia brands, I know, and not saying they won't do well, I'm just trying to consider why the muted response to pretty sparkling results. The market looks forwards, whether the pandemic has been good to you or bad.
They've got a load of new brands and they're expanding their geographical reach.
They're targetting 25% growth over the mid term and investing to scale to that level. I can't see them going backwards - the increased profits mean they've got more marketing budget at the same level of margin driving more growth. At some point they'll run out of runway, which is possible for the UK market without expanding the client base (ie move upmarket and to an older demographic) but the RoW is pretty much untapped.
The UK literally leads the world in terms of the amount of online retail engagement and Boo are amongst the worldwide leaders in terms of capability. There's a huge untapped market across Europe, Asia and the US and, imo, Boohoo (LON:BOO) are just getting started.
Re Boohoo (LON:BOO) - another factor (likely only minor, going by recent evidence) is the impact of changing sentiment from the mainstream media. This piece in the Evening Standard today is one example . Also, if the company follows through in dealing with their supply chain and general ethical standards improvements, this could open the door to more institutional investment and ESG money. I cannot find the source now, but I read Investec analysts only put the profit margin impact of moving 90% of output to more ethical sorces at less than 100bps .
I am baffled the price hasn't risen today - I've not been investing long though - but see it as an opportunity and have duly increased my holding.
Re £BOO - I am struggling to remember when I last made any substantial purchase of clothes in a shop, it was certainly well before 2020! Online clothes shopping now has so many advantages. Companies such as Boohoo will only get better over time at sizing / style issues which will reduce returns and hence costs.
On a separate note, what I really like re Boohoo now is that they have got over the 'its unfair' reaction stage of the ESG 'scandal' and now appear to be focussed on making themselves ESG standard setters. Respect to the team to have got to this position so quickly and to recognise the opportunity that being an ESG market leader will likely bring. Hopefully when the institutions realise that Boohoo is an essential holding, the price will be driven much higher.
I hold, and tomorrow morning will hold more!
Hi Paul, any thoughts on the update from Gear4music Holdings (LON:G4M) this morning?
Someone voting this comment down? I guess someone really needs their coffee this morning or really doesn't like Gear4music Holdings (LON:G4M) :)
The spread is outrageous your having to pay 900p now sell 860p, ROW sales fantastic
The spread isn't real. You can trade inside the price at both ends. I do find it irritating when MM's show such wide spreads and put people off when the true spread is much lower.
The spread is the max. and min. price with a normal size trade, so you should always get within the spread unless you have an abnormal size trade.
Spreads in thin trading tend to be wider. I did look at G4M prices this morning and the spread did look quite wide. At the moment you should be getting 900p to buy and 870p to sell.
If you have time interested in your thoughts on Science In Sport (LON:SIS) - the TS this morning suggests they may now finally be delivering as promised. They've certainly done a great job on their online channel growing sales 39% with momentum increasing throughout the year and Q4 growth 65%
Yup, I thought SIS looked like they've turned the corner, lots of growth potential, online growing strongly, into profit and building new capacity, could be a perfect turnaround stock
Agreed Donald, for me it looks like it may have hit that inflection point. I guess COVID has dramatically sped up their online push, be interesting to see how many customers/sales they have via their own website vs what they've done on Amazon (or marketplace as they call it). Am sure own websites will be far more profitable than their sales on Amazon.
Morning Paul, hopefully an exciting day, however you may wish to check out your stock picking link
I normally read what you write Paul, and generally enjoy it. But sometimes you do witter on about your dog, or your social life etc. So "Does your comment really add value?" is a bit rich.
Live & let live.
All the best.
Nicely said, Live and let live.
BSV