Small Cap Value Report (Thu 14 Sept 2023) - GLV, GLE, LOOP, TUNE, CKT, THG

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Some interesting companies reporting today! Here's our list (remember we can't cover everything) - we might have bitten off more than we can chew here, let's see how we get on. Update - annoyingly we didn't manage to cover a couple of quite interesting ones, but I've earmarked them for tomorrow.
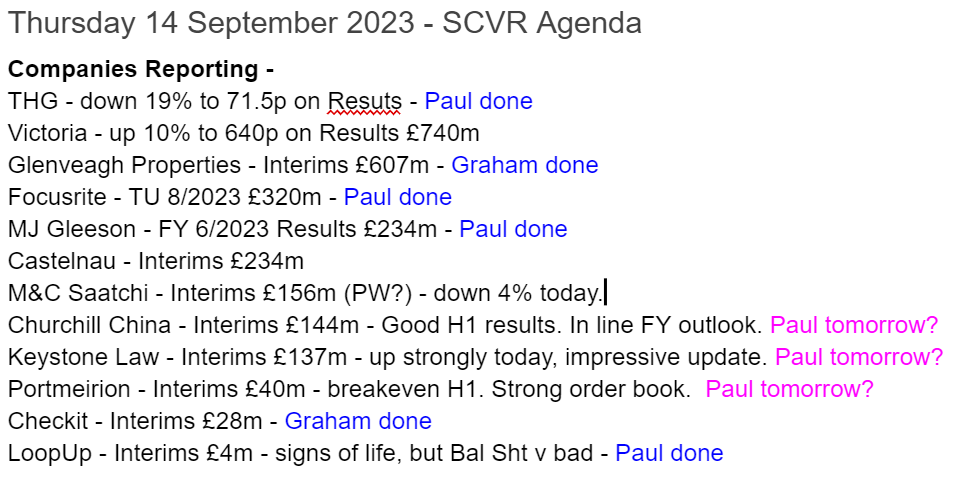
Summaries
Glenveagh Properties (LON:GLV) - down 1% to 97c (£473/€550m) - Interim Results (in line) - Graham - GREEN
The market is unimpressed by these numbers as H1 falls to almost breakeven. However, the full-year forecast suggests that H2 will be much better. Glenveagh has already reduced its share count by 33% in three years and I’m excited that this trend might continue.
MJ GLEESON (LON:GLE) - up 3% to 403p (£238m) - Results FY 6/2023 (audited) - Paul - GREEN
In line results for FY 6/2023. Fantastic balance sheet, with shares trading at a significant discount to NTAV. Cash pile has been spent on building invetories (land and W-in-P), but that's not a problem as it has a large unused bank facility available. Surprisingly upbeat outlook comments. I can see more medium term upside than downside, so I'm happy to give this the thumbs up. Although, as with everything, I have no idea what the share price will do shorter term, in this choppy & illiquid small caps market.
Focusrite (LON:TUNE) - up 5% to 525p (£311m) - Trading Update for FY 8/2023 - Paul - GREEN
A reassuring update (towards lower end of a very tight range of forecast EBITDA numbers, so it's as good as in line to me). Negligible net debt. Very difficult markets, but its holding its own. Looks a good quality business at a reasonable price, in my view, I like it as a long-term buy & hold. You're only being asked to pay a share price that's the same as it was 4 years ago, despite profitability having substantially improved since then. Thumbs up from me.
Checkit (LON:CKT) - up 14% to 30.7p (£33m) - Interim Results (outlook ahead) - Graham - RED
Encouraging results here as cash burn slows down and even though revenue growth isn’t quite as fast as hoped, the outlook for the full-year loss is reduced. Runway at the current rate of burn is about two years. If they can stretch this out further, maybe I can turn neutral.
THG (LON:THG) - down 17% to 72.3p (£1.05bn) - Interim Results - Paul - RED
Another set of dire numbers from this eCommerce business. aEBITDA numbers are total fantasy in my view. Substantial, and growing net debt looks ominous to me. It urgently needs to start making genuine profits, otherwise this could end very badly I think.
Loopup (LON:LOOP) - up 50% to 3.25p (£6m) - Interims - Paul - RED
Tiny, but I know the company quite well, so had a quick look at the numbers. Interim Results to 30 June 2023. Interesting growth product, cloud telephony. Most revenues come from legacy online meetings product. Signs of life with rapid growth (from low base) in cloud telephony. “Broadly meeting” market expectations for FY 12/2023. Ignore EBITDA, as heavy development spend is capitalised, so continuing heavy losses are reality. It’s almost out of cash, so another fundraise (or delisting) is practically certain. Very weak balance sheet, dependent on bank debt. Receivables very high too. Paul’s view - I’m steering clear until it’s done another fundraise, as dilution/delisting/insolvency risk is now extremely high, so best avoided for now I think. for investors. One for gamblers only, as risk is so high. [no section below]
Paul’s Section:
MJ GLEESON (LON:GLE)
Up 3% to 403p (£238m) - Results FY 6/2023 (audited) - Paul - GREEN
This is a housebuilder mainly in the Midlands & North, which specialises in low cost compact houses (not apartments), which it famously says can be afforded by a couple earning minimum wage. Therefore I think it probably has a competitive advantage vs other housebuilders at the moment, due to this affordability, and the fact that new build houses are well insulated, thus giving buyers a potentially decent saving on their heating bills.
There’s also a benefit from buyers who now cannot afford a mid-range house, trading down from higher priced alternatives, to a Gleeson affordable home.
Another aspect of Gleeson that I like is it recently announced a block sale of houses to a financial investor, intending to rent them out. So it’s not just dependent on private sales of new houses, which are obviously under pressure due to the large & rapid increases in interest rates impacting affordability, particularly in the South.
Another housebuilder whose shares are doing well, which we briefly mentioned the other day, was Vistry (LON:VTY) . That also has a differentiated business model, building a lot of houses for local authorities and other partners, giving it a much more resilient outlook than plain vanilla housebuilders.
Overall then I think a deeper look at this sector, focusing on the differentiated business models, could be well worthwhile. As opposed to just assuming they’re all the same and buying the ones that have the deepest discount to NAV.
On to the FY 6/2023 Results, which are obviously looking in the rear-view mirror now, since the higher interest rates only started to bite in the most recent few months.
Headlines -
Results in-line with expectations, reflecting shifting buyer demographics
Pre-emptive actions and higher selling prices ensured resilient operating margins
Some key numbers for FY 6/2023 -
Total revenue down 12% to £328m, but most of the fall is from the smaller land division. Homes division saw revenue down 4% to £321m.
Pre-exceptional PBT was £31.5m, down 43% on LY - this has been worsened by the land division’s collapse in profits (lumpy transactions). The core housebuilding division saw a 32% fall in operating profit, and a reduction in operating margin from 15.3% to 10.9%, so it’s a marked fall in profitability by any measure.
EPS 42.9p (down 45%). The StockReport is showing 39.6p consensus forecast, so it looks a beat. Although a note from Singers today says it’s in line with their expectations. At 403p/share, the PER on FY 6/2023 actuals is 9.4x - not particularly cheap given market conditions have deteriorated since.
I’m really more interested in what the outlook comments say, because we’re already aware that the housing market is struggling due to interest rate hikes, and that builders have suffered a bout of build cost inflation.
Outlook - I have to say, this is considerably more upbeat than I was expecting -
Current trading and outlook
Economic uncertainty has continued to subdue the wider market over the summer months. Gleeson Homes' net reservation rate for the 9 weeks to 1 September 2023 was 0.43 per site per week compared with 0.54 per site per week over the comparable period last year. Cancellation rates of 0.10 per site per week were unchanged from the comparable period last year.
However, with a steadying mortgage market and the implementation of a range of sales and marketing initiatives, including the introduction of a shared ownership package, we anticipate an increase in our net reservation rates during the Autumn selling season. We also continue to receive interest in multi-unit transactions, which would further strengthen sales.
Gleeson Land started the financial year in a stronger position with six consented sites and has already completed the sale of one significant site. Demand for consented sites remains strong and further site sales are anticipated throughout the year.
We therefore view the current year with confidence, whilst remaining cautious around continuing risks in the wider economy and any further impact on customer demand. As market conditions improve, we look forward to returning to significant growth.
Rather mixed messages in the last paragraph! Confident and cautious, at the same time?!
Forecasts - Singers has FY 6/2024 profit forecast roughly flat, at 41.8p. Does that look reasonable? I’d say yes, since the outlook and commentary give us good reasons to expect GLE might be able to hold profits flat, without any improvement in market conditions. The cost of living squeeze is starting to ease, as average wages have now returned to being above inflation. Possibly mortgage rates might have, or be close to a peak? And of course there’s an ongoing structural shortage of affordable housing - too many people, and not enough houses, means I cannot see any significant price drop for Gleeson’s bottom end of the market being likely.
Balance sheet - net assets are £286m, all tied up in inventories (land and W-in-P) of £345m.
Cash has fallen sharply, from £34m to just £5m. There’s no interest-bearing debt, and other creditors are dwarfed by its huge inventories. There’s an unused £135m bank facility, so absolutely no issues over liquidity. In any case, it could reduce inventories to generate cash, should it be necessary (which it isn’t).
So the shares trade at a discount to NTAV (not unusual in the sector), market cap at £238m, NTAV at £286m, and probably only a small risk of assets having to be written down in value (e.g. Gleeson uses very cheap land, so low risk of having to write its value down), so I reckon this looks a rock solid, asset backed investment. I don’t think the same can necessarily be said of all housebuilders, operating in much higher priced regions, where selling prices could be falling faster than expected I reckon.
Although for balance I should mention that if house prices really drop hard, at the bottom end of the market, then GLE could see write-downs being required. It is possible, for sure.
Cashflow statement - looks very simple. All the cash generated was invested in additional land and W-in-P (inventories) - this is something the company largely controls itself, so it’s not a problem. The cash pile was nearly all spent on other cash outflows, eg capex, tax paid, finance charges, divis, etc. All looks fine to me.
Paul’s opinion - I haven’t read all the commentary, just plucked out the key bits. I’m reassured by the in line results, and more importantly the surprisingly upbeat outlook comments. It seems to me that, even if the housing market hasn’t bottomed yet, it looks credible that GLE’s profits might have bottomed, due to its key advantages of being at the low cost end of the market, and seeing interest from bulk purchasers (to plug any shortfall from individual buyers).
I don’t know if the share price has bottomed yet, anything could happen in this choppy stock market. I’m tempted to start dipping my toe in here again, with a small initial purchase, then monitor events and decide whether or not to top up depending on how things seem to be heading.
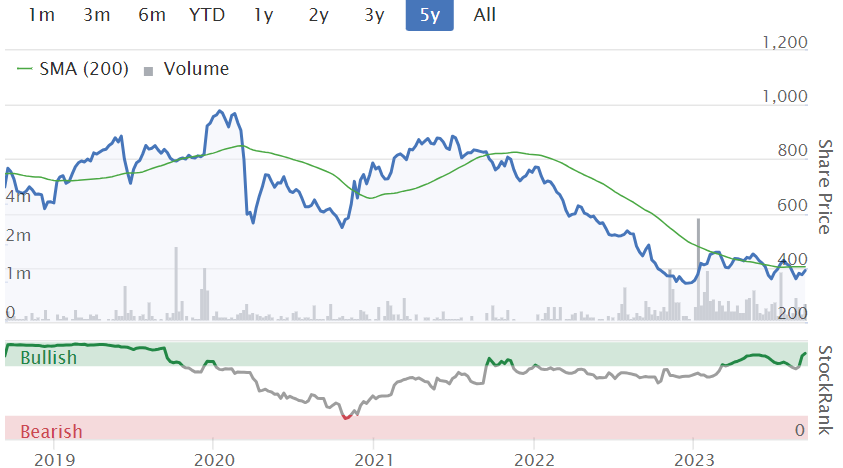
Chart below - forming a base possibly? Time will tell. High StockRank. Very little dilution over the last 6 years, so this chart is saying to me GLE shares could double in a general economic & property market recovery -
Focusrite (LON:TUNE)
Up 5% to 525p (£311m) - Trading Update for FY 8/2023 - Paul - GREEN
Focusrite plc (AIM: TUNE), the global music and audio products group supplying hardware and software used by audio professionals and musicians, is pleased to provide the following update on trading for the year ended 31 August 2023 (FY23).
Given tough macro conditions, I think this update seems reasonable. The market seems relieved, with shares up 5% -
…revenue for the Group in H2 FY23 was slightly ahead of the comparable period in FY22. As a result, Group revenue for FY23 is expected to be not less than £177 million (FY22: £184 million). Supported by improved gross margins, our expectations are for EBITDA1 for the full year to be around the lower end of current market expectations, which currently range between £38.2 million and £39.0 million.
That’s a very tight range, so being “around the lower end” is absolutely fine, I think.
Debt & working capital - this all sounds fine, no concerns here with such modest debt -
As at 31 August 2023 the Group had net debt2 of approximately £1.5 million (FY22: net debt £0.3 million, FY23 H1: net debt £13.2 million). This includes the acquisition of Sonnox Ltd in December 2022 for a net cash consideration of £7.2 million. Working capital has improved significantly in the second half as inventory in the channel has reduced as expected to more normal levels.
Valuation - we’re hampered by the lack of broker notes here. Surely management should be addressing that omission, for a share that a lot of private investors find interesting.
Working on the StockReport’s broker consensus numbers, we’ve got 39p EPS for FY 8/2023. It sounds like actual could be slightly below, guessing at say 37p. That would give a PER of 14.2x, which looks reasonable value I think considering it says market conditions are tough -
background of extremely challenging trading conditions throughout the year.
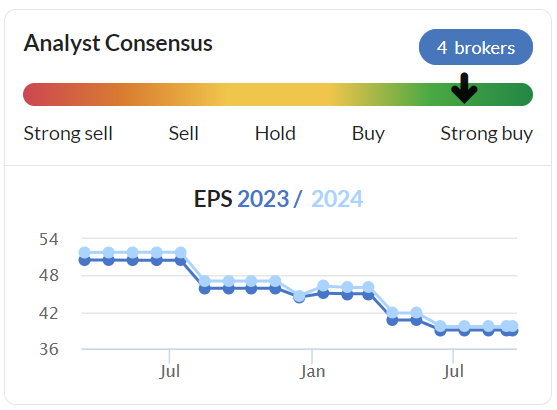
There have been a series of downward revisions to forecasts, which helps explain the share price weakness this year -
Paul’s view - looking at my notes previously this year, I viewed TUNE as GREEN on 3 Feb (755p), 14 Mar (665p) and 28 Apr (451p). So I was rather too optimistic earlier this year, but finally got it right on the third attempt at 451p in April!
The price looks on a firmer footing now at 525p, and looks OK value for a decent quality business. I also like that TUNE is owner/managed, has a good track record since listing, and seems to have made a series of self-funded acquisitions in a sector it knows well.
As you can see, the pandemic gave it a big boost, but it’s managed to hold on to most of the profit growth, not an easy thing to do -
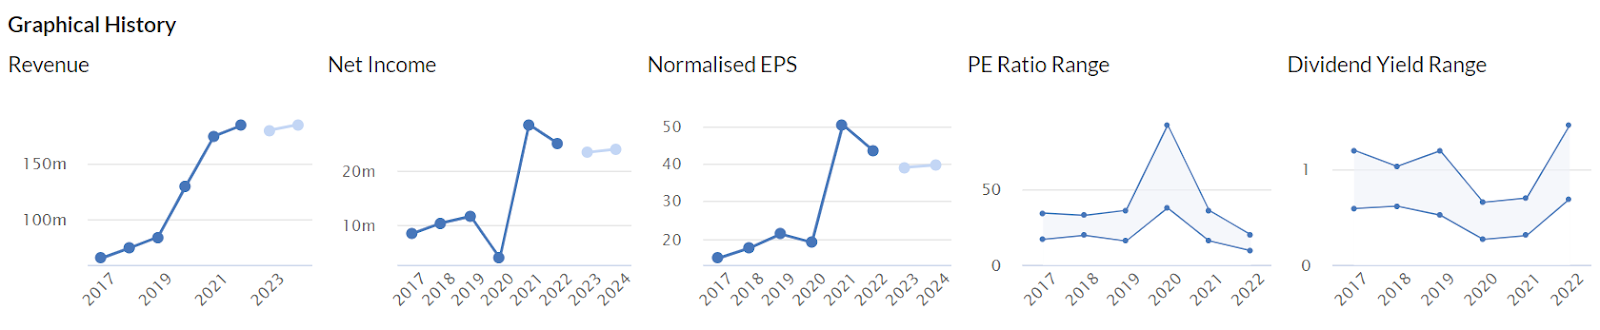
Divis are modest, because its using internal cashflows to make acquisitions. That’s fine.
As you can see from the chart below, I’d say the speculative froth has come out of the price, and you’re now getting a nice quality, innovative business, at a reasonable price.
So it’s another thumbs up from me. Bear in mind I’m not a good predictor of share prices, but I can spot nice companies at fair valuations, and this is one of them.
THG (LON:THG)
Down 17% to 72.3p (£1.05bn) - Interim Results - Paul - RED
If you like adjustments, then these accounts are a must-read. There’s a gulf of real world costs between its £50m adj continuing EBITDA, and the £133m loss before tax in H1 results (worse than £108m LBT in H1 LY).
THG strikes me as an insanely overpriced tech boom share that is now struggling to work out how to become a viable business, before it runs out of cash.
True there’s a big cash pile still, of £393m. However, it’s all been borrowed - £672m of (expensive) debt. The terms of those borrowings will be key - a breach of the covenants could end up with borrowers potentially controlling the company, and wiping out equity completely, sooner or later. Net debt is £268m excluding leases. How is that debt going to be repaid, given that THG doesn’t make any profit?
Outlook comments suggest it can reach positive free cashflow in H2, achieving cashflow breakeven for the full year. I’d like to see how it defines free cashflow, because it probably won’t match how the rest of us define it, at a guess!
Paul’s view - very negative. This looks an accident waiting to happen. It’s not growing any more, is nowhere near profitability, and has a large and growing pile of debts. It’ll take a miracle to turn this thing around, in my view. Every now and then takeover bid rumours start circulating. Surely at some point the delusional valuation expectations of management and shareholders are likely to meet reality?
Mind you, look at Ocado (LON:OCDO) - that’s been treated as a huge valuation tech stock for many years, despite it only growing modestly, and losing £300-400m every year. So these bubble valuations can last a very long time. The story is usually that the company has some amazing underlying technology which is world-beating, and the earnings from that could dwarf its trading losses. But it never actually happens in most cases - just heavy losses, year after year.
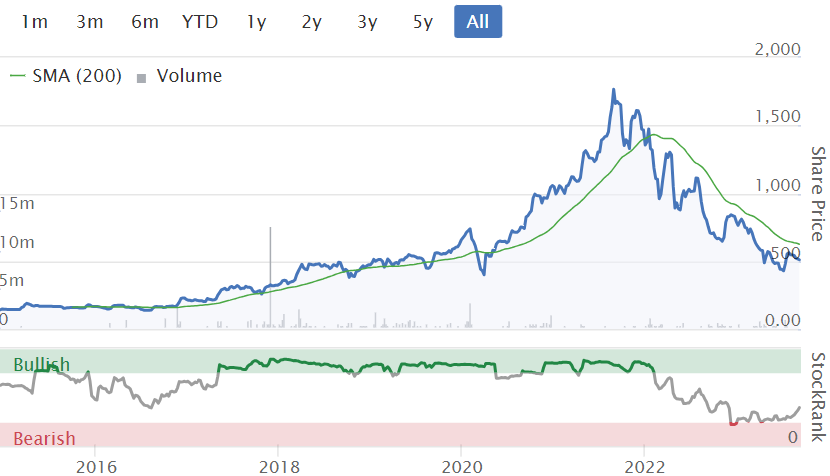
It’s amazing to think that THG is still worth just over £1bn, when you see its chart since floating. The original IPO surely deserving of a literary award in the best fiction category?! And the buyers of the stock at IPO getting most gullible investors of the year award? Mind you, we all make mistakes, so I shouldn't really say that.
Graham’s Section:
Glenveagh Properties (LON:GLV)
Share price: 97 cents (-1%)
Market cap: £473m (€550m)
We have interim results from this Irish home builder.
I first looked at it in January, when it issued a profit warning, as planning delays were set to put the brakes on suburban unit deliveries in 2023.
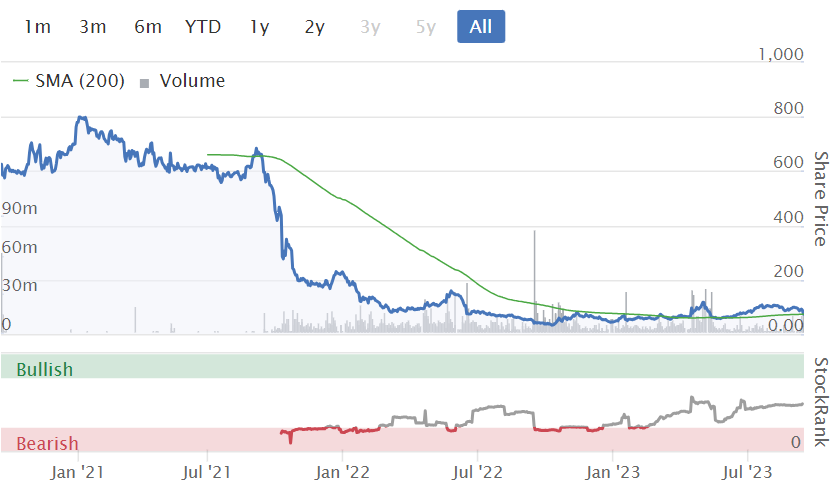
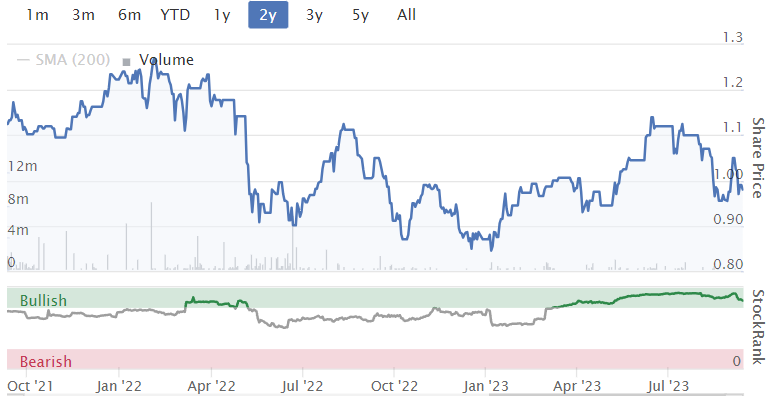
However, the share price hit a low that day and has been higher even since. Here’s the two-year chart:
Today’s interim results show revenues declining year-on-year and profits evaporating. However, the results are in line with expectations and H2 should be better. Note that the full-year revenue forecast is €599m (vs. only €171.6m generated in H1)..
Perhaps the performance over six months isn’t too meaningful for smaller house builders, where sales of new developments might be lumpy, and we should try to stick to analysing annual results?
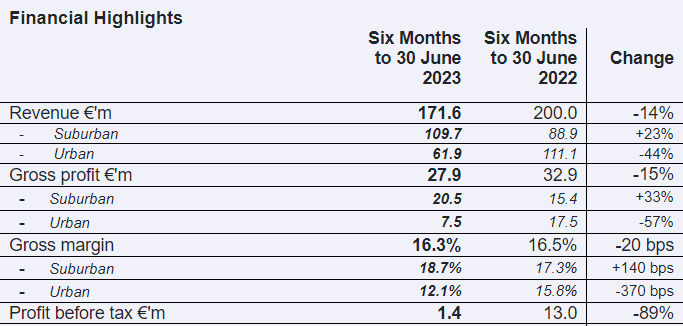
The decline in profits in H1 is blamed on “lower urban revenues, reflecting a higher H1 2022 comparative that included approximately €63m from the disposal of the East Road site, along with increased financing costs.”
At least the overall gross margin has been maintained. They say that build cost inflation was kept to only 4-5% - impressive.
In other positive news, they say they are now benefiting from “strong planning momentum”. They’ve received planning permission for 4,000 units so far this year, which sounds like a lot! All expected deliveries for 2024 have planning permission.
Buyback - they finished a c. €63m buyback programme at the start of August. There are now only 578m shares outstanding (vs. 638m at the end of 2022, and 772m at the end of 2021). Excellent!
I’m not very fussy about where future EPS growth might come from - if it comes from a declining share count, I’m fine with that!
Outlook - they reiterate full-year 2023 guidance, EPS of 7.5 to 8 cents (about the same as 2022)..
The 2024 outlook is worth a read:
A very healthy land portfolio and forward order book, combined with strong planning momentum and robust operational and manufacturing capability, gives the Group increasing confidence in its capacity to generate strong revenue and profit growth across its Suburban, Urban and Partnerships business segments in FY 2024. We are comfortable with current consensus EPS expectations for FY 2024 of approximately 17 cents
That would be an excellent EPS result (especially when you consider the share price is currently just 97 cents, so that’s a very low PER).
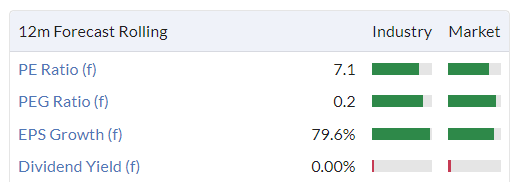
They also say that the return on equity target of 15% in 2024 is “our key capital metric” - excellent! I like the choice of KPI and I like the target they’ve chosen. 15% would be a fine return for shareholders.
I really like the way they have used a large share buyback to reduce the E in ROE (i.e. equity). In my book that’s a very efficient way to return surplus capital to shareholders, and it’s the right choice when you are trading at a cheap earnings multiple.
CEO comment: I’ve picked out some of the most interesting bits.
While planning delays proved challenging at the start to the year, we have seen a strong upturn in permissions granted through 2023 and are on track to have over 70% of our current landbank fully planned and available by the end of FY 2024.
We began 2023 with no planning achieved in our Partnerships segment, to now being commenced on two of the largest such sites in the country. We are proving that public and private entities can work successfully together to deliver sustainable mixed tenure developments…
The outlook across Glenveagh's businesses is favourable and the opportunities are compelling. We are ideally placed to serve what continues to be strong private demand, in addition to working constructively with State agencies on supply-side initiatives.
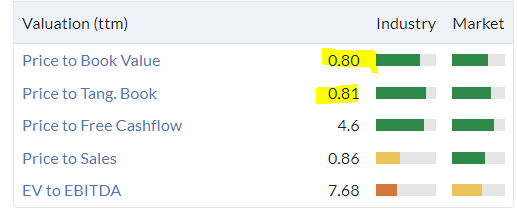
Balance sheet does not appear to be excessively geared, with €240m of loans and borrowings being used to finance total assets of €970m (almost entirely tangible). Equity is high at €637m, so the company’s stock trades at a discount to book.
Graham’s view
I’m going to give this one the thumbs up due to the rapidly declining share count over the past few years, and the still cheap valuation (whether viewed through a P/B or PER perspective).
If the company hits its targets over the next 18 months and if it chooses to plough its earnings into further buybacks rather than a dividend, the share count here could collapse. Either that, or the share price would have to rise to prevent that from happening.
Either way, I think the prospects for shareholders are positive. Planning permissions have picked up to match the extraordinary demand for housing and so it should be full steam ahead for the likes of Glenveagh.
Checkit (LON:CKT)
Share price: 30.7p (+14%)
Market cap: £33m
The outlook here is ahead of expectations.
What it does: Checkit provides software and sensors that enable businesses to automate tasks, and monitor their staff and their operations more generally, improving efficiency. Key industries served include hospitality and healthcare.
Their goal is “to become the market leader in augmented work management for the deskless industry.”
The two-year chart isn’t pretty, but could it have formed a base?
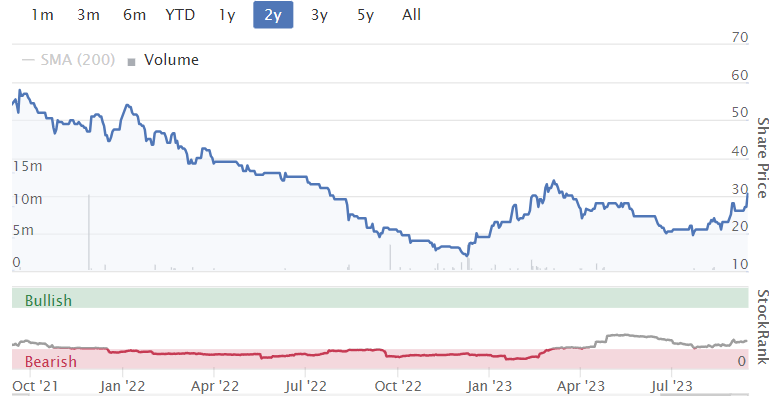
Here are the key points from the interim results, for the period ending July:
H1 revenue from continuing operations +19% to £5.7m (nearly all of this is recurring).
Annual recurring revenue +24% to £12.6m.
Pre-tax loss £2.5m (H1 last year: £4.5m).
Cash £12.8m (it was £15.6m six months previously).
CEO comment:
Checkit is on an accelerated track to profitability. We're scaling growth through our land and expand model, while prioritising operational efficiency and cost reduction. Despite the challenges in the wider economy, our diverse customer base and a product suite that is built to deliver operational efficiency uniquely positions us for market capture.
The company will host a webinar today at Investor Meet Company. Here’s the link.
H1 performance: there have been “a number of small wins with potential for future upsell”, plus a large agreement with Compass (LON:CPG) involving multiple contracts and more opportunities being discussed. Checkit has also achieved its largest contract renewal with John Lewis (£6m over three years).
Cash flow is much improved, with only a £2m operating cash outflow in H1 (H1 last year: £3.6m outflow). The investing outflow was less than £1m, about the same as last year.
Outlook
We continue to execute against our growth strategy, with an exclusive focus on high quality, high value subscription revenues in our target verticals and geographies. The picture for the business remains positive; high net revenue retention rates underpin our land and expand strategy and continued contract momentum. With an accelerated focus on operational efficiency, the Board is confident in delivering an operating performance for FY24 ahead of current market expectations.
Estimates from Singers for the current year (FY January 2024) are adjusted as follows: revenues down 4% to £12m, and adj. EBITDA improves 7% to minus £3.6m.
Graham’s view
I’m impressed by the reduction in cash burn, which means that the company should be able to survive longer than I previously expected with its current cash pile. At their current rate of losses, they could survive about two years without raising more funds. And if the burn can reduce further then their runway will get correspondingly longer.
I don’t feel like I have much choice other than to maintain the negative view on the stock, however, because it’s still at such an early stage. If you like investing in early-stage companies, this could be worth a second look. From a value perspective, I have to concur with the Stockopedia ValueRank of 15. But well done to Checkit for keeping its costs under control and making its cash last that bit longer.
If they can reduce their rate of burn further, I may turn neutral on this one.
Paul adds: I'm a bit more risk tolerant than Graham, and to me Checkit looks quite interesting. I like small growth companies that are reducing cash burn, and probably have enough remaining cash to survive. This update strikes me as interesting, nice review from Graham, and I'd be willing to view it as AMBER, and do some more research on it. Although £33m mkt cap for a loss-making cash burners isn't particularly enticing. I'm not sure there's much immediate upside on that price. Although for a value report, I can see why Graham has stuck with RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Checkit (LON:CKT) (I hold). The more rapid the future growth the higher the likelihood that the existing cash will need to be supplemented by fund raising, hopefully by means of a rights issue so private investors can participate.
Checkit (LON:CKT)
There are some comments here on whether there is enough cash to last to breakeven.
There is a note from Edison today https://www.edisongroup.com/re... where they say:
"Our net cash forecasts are maintained and we continue to estimate that the company has sufficient
cash to reach cash flow break-even".
(I have a small holding in Checkit as a result of the disposal of the main subsidiary of the old Elektron Technology (EKT) when the bulk of the cash was returned to shareholders leaving what was considered sufficient at the time (Nov. 19) to take CKT to breakeven).
Fundamentally with Checkit (LON:CKT) it's really just a question of whether you believe their sales pipeline of near term opportunities
Cashfllow Breakeven occurs at ARR of around £18m - today they are at £12.6m
The pipeline of expected sales is £15m and a decent amount expected before year end.
Thus convert £5m of the £15m pipeline and the group hits breakeven. Given the relatively near term nature of this I think you will know within a few months.
So cash runway looks like it has more than enough space to fund them through to profitability and beyond unless they have a dramatic slowdown but actually the opposite looks to be the case - ie momentum appears to be building.
I think the business looks pretty interesting. Not a short term play but far from blue sky
If anyone is sad enough to want to check Wilko exposures (like me!) the statement of affairs is at Companies House. Had a quick look out of interest. There is an estimated deficiency of c£343m.
Looking at exposures excluding landlords:
UP Global Sourcing Holdings (LON:UPGS) is one of my large holdings - only £63k owed. Other holdings - Britvic (LON:BVIC) £166k, A G Barr (LON:BAG) £22k, Luceco (LON:LUCE) £3k and Unilever (LON:ULVR) £3,207k.
Biggest exposure is P&G £8,878k.
20% VAT is always recoverable. Debts may have been insured or provided for anyway.
Not full disclosure, more confession time. In spite of Paul's excellent advice today on Loop-up we bought 5000 before the 'bounce' after reading those signs of life very early. No applause please as they join the 11000 we already had, bought in excitement during it's brief growth period in the Pandemic. at an embarrassingly high price. It's been a clear out day though, our biggest loss maker for years was Centrica of all companies. A decent holding bought over many year plummeted and I stubbornly -- stupidly held on, thankfully we added quite a few near the bottom and today we sold them all at a small profit, it's now above analysts consensus and I cannot see any Government taking kindly to generous dividends in the near future no matter how good the profits. We topped up on Ninety One, RWS Holdings and bought into Sanderson Design in the hope they will prove more rewarding. Comments welcome, brickbats fielded.
Hi JASVFS,
I'm afraid I don't have much confidence in Loopup (LON:LOOP) surviving. Cloud telephony is not the latest and greatest, it's been around for a decade+. I was working on a cloud telephony solution involving Broadsoft (now owned by Cisco) ten years ago. The big incumbents, e.g. Microsoft Teams, Cisco have the market more or less sewn up. Smaller players really need something special in a niche area to survive. So I expect Loop-up will just continue to decline.
In spite of Paul's excellent advice today on Loop-up
I. DO. NOT. GIVE. ADVICE.
How much clearer do we have to make it? We give opinions.
https://www.ft.com/content/0a6...
Far more comfortable kicking the UK and moaning about Brexit this must have stung the FT. A German double whammy - utterly insane (and expensive) energy policy mixed with falling exports to China.
I suspect as net zero plays out across Europe, politicians will be in for a kicking.
“Nobody works less than Germans,” he said, adding that the quality of candidates for its apprenticeship scheme is “way below what we got 10 years ago”.
“There is a cyclical downturn. Then on top of that there are the structural issues,” said Clemens Fuest, president of Munich’s Ifo Institute, one of Germany’s top economic research bodies. “This is the combination that leads to the gloom we see today.”
Economists like him worry that the industrial fabric of Europe’s largest economy risks being slowly eaten away as more companies shift production and investment abroad.
In line with that, Winkler told the Financial Times that Heller planned to reduce dependence on Germany and build up more presence in Asia and the US. The manufacturer of machines for crankshafts, a vital component of petrol and diesel engines, even plans to expand its UK site in the Midlands town of Redditch, despite the complications of Brexit, because of its “big competitive advantages” in cheaper labour costs compared with its headquarters in Nürtingen."
EU Responds the way the EU always responds.
"The EU has announced an anti-subsidy probe into China’s electric car industry in an attempt to shield European manufacturers before they are priced out by Chinese rivals.
While imports of Chinese electric vehicles represent only a small share of the bloc’s market, they are growing fast and could hit 15 per cent within two years — in a repeat of what the EU experienced with solar panels more than a decade ago.
“We cannot afford to lose our car industry,” said a senior EU diplomat.
The EU is banning the sale of new combustion engine cars from 2035 to cut carbon emissions and fears their electric replacements will be made in China, not Europe."
MG - Morris Motors.
The Germans will survive but maybe not as the behemoths they are today. Brand recognition.
The Chinese MG is imo a good looking car. Teslas becoming a bit "common" (harsh but only jealous) - but do have the brand, marketing, presume constant upgrades and treating you special - marketing masterclass.
I've got my eye on this auction - looks fantastic - somebody buy it for me, so I can cruise around Poole Harbour on my days off!! (or sink into shallow water average 18 inches deep, if the 3 bilge pumps prove inadequate, hoping to refloat at high tide)
The water in Poole Harbour may be only 18" deep, but the mud is far deeper than that.
ARM returning to a screen near you today . Arma gonna keepa eye on for trading ...should fly and then unfly
Feels overpriced to me but as you say I will probably kick myself as it flys up to even loftier heights and then breathe a sigh of relief as it crashes back down :)
More than 10 times oversubscribed…..wow…..suspect that’s more an indication of such a lack of quality companies coming to market than it is about real demand for Arm itself
Yep , agree. Arm may temporarily 'drain' some of the other FANG's as the masses jump ship. Ive traded many unattractive fundamentals for a short term gain from the crowd.
I am sure ARM is a good company as no doubt is Nvida, but they both strike me as crowded trades as was the likes of Novacyt SA (LON:NCYT) during the pandemic. The latter went north of £12 and now trades at 77p!
What can go wrong? I have no idea, but the risk/reward see-saw is in my view very much weighted in favour of the former.
If one has the skill or perhaps better described as the luck to step off the roundabout at the right time one may well make a handsome profit, on the other hand when the music stops you don't want to be left holding the proverbial baby.
As for me I am happy to take Peter Lynch's advice and avoid the hottest stocks in the hottest markets.
On Checkit (LON:CKT) it really does depend if you think the company has enough runway left for continued losses as it grows.
My own calculations is that it probably needs to do another £8-10m/yr revenues to reach that cash flow break-even.
Given that ARR is now only just at £12.6m, there's still quite a mountain to climb, with a 20-30% growth rate.
There is, in my mind, a possible M&A value. It might attract an existing large player that supplies the same set of industries, to bolt this innovative new product into their catalogue. Paying 3-4x revenues is possible for a strategic acquisition of this tiddler size, and would mean a 60% premium to the current share price.
Personally, I prefer Phoenix group (LON:PHNX) Chesnara (LON:CSN) Legal & General (LON:LGEN) Aviva (LON:69WR) and M&G (LON:MNG) in this space (and I hold all) rather than Just (LON:JUST) - I did have a poorly timed investment in the latter, but exited. The problem that they have is high exposure to equity release which is very cash negative (i.e. the money goes out on day 1 and comes back (with interest) on death of the individual. They are also now on the end of reducing residential house prices. I get that it is a natural hedge to annuities (where the opposite is true: the money arrives on day 1 and is paid out over 20 or 30 years), but the Just (LON:JUST) cash flow statement is normally much worse than the income statement (because of its large equity release portfolio) which explains why it isn't able to pay a big dividend. It also raises capital through high interest subordinated notes.
I am going to top-up in the five I hold over the next 6-12 months, but am a little wary of doubling-up too early as these companies normally get sold down going into a recession.
Keystone Law (LON:KEYS) up 17% on a positive update today.
"Current Trading and Outlook:
· Activity levels and client demand remain strong
· Recruitment market conditions have moved in the Group's favour, with the Keystone model continuing to attract high-calibre talent, although economic uncertainty continues to weigh on candidate flow
· The Board is confident that the business will continue to trade well for the rest of the year and that FY 2024 results will be comfortably ahead of current market expectations(1).
James Knight, Chief Executive Officer of Keystone, commented:
"I have been delighted with the performance of the business during the first half of this year. As anticipated, recruitment market conditions have moved in our favour and Keystone's model continues to prove highly attractive to the high-calibre lawyers we pride ourselves on being able to attract and retain. I look forward to the rest of the year, confident that Keystone's core business fundamentals will continue to deliver strong results."
May have some read across? One that looks OK is Knights group (LON:KGH) which Ive been trading in and out every couple of months. Id sold again start of August but bought back when a large buyer appeared on the order book 3-4 weeks ago buying 250k blocks on the bid. Right now theres 450k at 85p but no sellers appear interested.
200 d moving av is flattening out for the first time in 2 years, when it fell off a cliff. Its not the greatest business in the world but its trading on 4x earnings this year 3.7 next. EPS growth forecast at 5.7% + 11.6%. For some reason the brokers went mega bearish on it in 2021. Shore upgraded to buy in July.
Should be a trading update at the agm a week on Tuesday.
Warning to holders of MJ GLEESON (LON:GLE: I bought a full position last month, and with my magnetic affinity for falling knives, this should be of some concern to you.
I do however like its position in the market as a provider for low income households at prices that engender a lower monthly cost than renting. And I took good comfort from the numbers and tone of today’s report.
PS has put this on my radar .Like the idea of entry level home ownership -will start £ cost averaging on this
BnB
There are many of us who feel that we have the uncanny ability to identify a good company, undertake our research, agonize over the "buy" button, and when we finally do buy spend the next few minutes, hours, days and weeks agonizing over I could have got it 5p/share cheaper why did I not know that???
This is normal, and a good thing, and in the current market it is always a challenge...
Says me who is absolutely amazing at the follow strategy!
Buy High
Sell Low
Buy back even Higher (FOMO)
Sell again even Lower (OMG you numpty why did you give into FOMO again get out of there!)
So if you ever want to sell as you think you have hit peak, I am your person to buy, if you ever want to buy at a low, then I am your seller. If I ever sell for a second time that is definitely a buy signal as I will delete the stock from all portfolios including ideas, and it will go on to all time highs followed by a premium bid :)
Good Luck
Tommy
Welcome to the crowd. 100% marks for your honesty. To restrain myself I only like to talk about my losers. A shower of cold water quickly wakes one up.
I'm a THG (LON:THG) holder, and Boohoo (LON:BOO) and Heiq (LON:HEIQ) - if the wife knew I'd be divorced under the grounds of being and idiot.
Worth pennies so just in the so called "coffee can" as write-offs.
I own two of these ! not THG as even I could see this was the most overpriced bit of rubbish ever floated, but hey , it will now explode upwards.
Is THG (LON:THG) really the basket case that is made out to be? Looking at shorting activity, sure there were plenty last year, but the shorts have now largely been unwound, despite the share price being stuck in the doldrums and the unanimous consensus here on Stocko that it is to be barge-poled. The 6% community green rating backs it up the apathy towards this share.
Yet - these all look to me as contrarian signals. When the future looks bleak based on extrapolating current performance, when the amateur investors all unanimously agree that it is a basket case. After all, it is the marginal £ that trades that moves share prices, which is usually the amateur investor.
But yet - THG still has a pile of cash, so in no danger of being in distress. They could always sell off one brand to raise more cash. And the shorters all had a look, some took a stab last year, made some money, but despite their research and being on the radar, have decided to skip on and move to other fish at the moment.
THG is now going to be firmly back on my watchlist radar :)
THG (LON:THG) - the tech IPO which wasn't - Ocado anybody?
Beauty products seems a huge market and into the US. We were moving out of Covid and End of The World so some people (most) turn to small pleasures - make up and etc.
Then the future turned brighter (before inflations) so lets get healthy, restore the immune system and beat any future bugs/virus/baccy so what better than a breakfast smoothy with high protein, carbs, and good stuff, rather than a bacon sandwich.
Think they had their own airplane and airport slot in Manchester (maybe fake apologies).
Who has time for DYOR. Certainly not me. Quick squizz and charts. Set alerts both up and down and try to be contrarian and cold unemotional. Set rules and keep to them - if only.
Probably by now "the" THG holder ;-)
I cannot remember where I heard it, but I like the observation that ‘you should not worry about the bottom of top eighth’
Edwin Lefevre in Reminiscences of a Stock Operator:
"One of the most helpful things that anybody can learn is to give up trying to catch the last eighth - or the first. These two are the most expensive eighths in the world." (Quoted by Michael Taylor in a Stockopedia article titled Trading the Trend, 8/1/2021)
Sylvania Platinum (LON:SLP) - chart says good to go.
Fundamental question is why? as if we will ever know.
Mark Simpson highlighted Tharisa has chrome as well as platinum etc so a better bet but their chart is not there yet.
I am willing to bet quite a lot of money that you will not regret your decision. A very fine, well managed company , operating in a good market segment with a very strong balance sheet . One of my larger positions and has been for a couple of years .
@LOOP - Thanks for the comment on this stock,Paul - despite it being a tiny market cap. I find this company fascinating. But I agree that until the group has more cash on hand, it is a punt on where a future fund raise might (or might not) get done. I was tempted to have a punt on the news on 30 June that the Bank of Ireland had agreed to extend the loan maturity by 12 months (to 30 Sept 2024) - this gave the company more time to see if the Cloud Telephony business could accelerate. But seeing today’s results, I am not clear that that optionality is actually worth that much now. The Cloud Telephony business is growing but seemingly not fast enough to fill the void caused by the decline in the legacy business.
Clearly the next set of results (FY23) will be with less than 12 months until the BoI loan new maturity date, which will create new issues around the Going Concern statement.
I think directors have been quite savvy here - both in managing to negotiate the PCi deal in Sep 2022 and in the Bank of Ireland negotiations - buying precious time for the company. But I have not seen directors buy the shares recently.
Hi Wimbledonsprinter - good points well made re Loopup (LON:LOOP)
It's been scraping along with the tank on empty (cash) for a while now, and I'd be worried about more simple things such as, can they make payroll at month end, and are they illegally trading whilst insolvent? (pretty near to it, I reckon).
Bank of Ireland hasn't really got a lot of choice than to extend the loan term, but I would imagine are probably having kittens about how best to get their money back.
So the way it looks to me, equity probably now worthless, and another fundraise on AIM probably unlikely. They did find a saviour though who pumped in loads of fresh cash in the last fundraise, Andrew Scott (no relation), who seems to be a serial startup funder from San Francisco. So it depends on how deep-pocketed, and optimistic, he is I would imagine.
Can they pull off a miracle? It's possible. Upside scenarios might involve some tech investor/company doing a deal with LOOP, and giving it fresh cash, or a saviour takeover bid, if someone thinks their tech is good.
More likely I would guess, is that existing equity probably hung out to dry, and new equity and lenders controlling events. But we don't know, that's just how it might turn out.
I see the founder Directors only have negligible value shareholdings now, and I understand have outside interests (one of them owns a hotel I think), so they could just walk away from it, if things get worse.
Super high-risk. Let's hope LOOP works out well for holders, but I wouldn't bank on that.
Regards, Paul.
I was going through some of my stocks and realised that Petrotal (LON:PTAL) is now paying a 17% dividend and buying back shares.
End of next year I think they will have net cash making up 60% of market cap, a production profile spanning 20+ years with solid reserve base and they should be generating prodigious cash flow.
Odd they are trading so low - usual risks apply of course but you’d imagine downside is limited given net cash position and at 17% annual returns it doesn’t take long to derisk the position considerably.
Hadn’t noticed this - rather crept up on me but thought I’d share given high income level that appears sustainable.
I'm not sure I have 'repeated altercations with angry indigenous populations' on my list of 'usual risks'... :)
But I think that’s where some investors Mis-read the local situation and assume it is a angry altercations between the company and the indigenous population whereas it isn’t.
The company is seen as friendly to both sides - it has been the arbiter between what indigenous population see as failed government promises and the government themselves. It has actually done this rather well.
It is true it gets caught up in the uprisings from time to time but never (so far at least) against the company itself.
They have set up a voluntary royalty scheme for the indigenous population now in the many millions which also keeps that relatively sweet.
The disruptions that happen are factored into the annual guided production profile too so they actually expect this to happen and why the share price rarely reacts much to it.
As your post suggests unless you take the time to understand the situation I can see how you might well form an I’ll informed view on it.
Ps can’t edit as am on mobile but I didn’t mean that last sentence condescendingly. Should have read, can understand why someone looking at it from the outside with no knowledge might form an inaccurate picture. Hence maybe that is also holding back the share price maybe?
There are 2 main operational issues facing Petrotal (LON:PTAL) imo. The first is the social issue which they seemed to have solved with the voluntary 2% of revenue social fund. Clever move - it's bought peace. The second is how they get their oil to market. They're hampered at the moment by low river levels effecting barges in the dry season but once the ONP pipeline is back up and running then they should be able to reliably hit their 20kbopd + target. They're also looking at various other methods of reliably delivering oil to market so a fix for the second issue is firmly in their sights as well. Once these two main issues are fixed then this will be a cash flowing machine for decades. The reservoir quality is genuinely world class. There are so few low cost, huge onshore fields like this. It's currently yielding me 20% plus on my original purchase price and I'm confident that this will rise to 30% plus from next year with increased production, special dividends, steady production etc. If only all my shares were like this. On a side note, it's a shame there's no O & G/mining expert commentator on Stockopedia. Energy & materials are such a huge part of both the real world & investment universe that it would be nice if they were covered more. Just my 2c worth.
Hi Joe
Yeah I have held from 18p on Petrotal (LON:PTAL) so I’m currently on a 43% dividend yield on original money plus it’s more than doubled. As I mentioned in my original post this had gone completely under the radar for me and it was only yesterday I really noticed and was suitably staggered. I’m not selling as I’d hope this will eventually go above 100p but given its income profile thought might be interesting for people. Never going to be everyone’s cup of tea but I like the vaguely methodical steady price rise.
If don't mind taking a punt and risk on South America Stocks. Petrobas, the Brazilian partially state owned oil and gas giant might be interesting for some. Dropped under $10 on fears the elected left wing President Lula would nationalise company completely and which still might do but looking unfounded so far, up from under $10 to around $14 for the ADR's under ticker PBR. A, traded on NYSE. Extremely low PE under 3 and high dividends going forward.
Your 2c is worth many dollars. The future world will be defined by its natural resources and who has them imo.
Not seen much chat on water but one of the most significant for human life. MTI Wireless Edge (LON:MWE) - another coffee can waiting in hope.
Agree with Mr Hill the news looks for newsworthy things - my dustmen, sorry waste workers are striking soon so expect rubbish in the streets, rats running amok and the plague re-emerging.
The Petrotal (LON:PTAL) chart aka tea leaves tell me a sustained breakout of 50p would be nice to see before getting too excited - not far away.
Just (LON:JUST)
The business is now mainly about defined benefit transfers - £1.4b out of £1.9b in sales in the last report. Those should go up as a big bump of pre-2001 db pensioners hit retirement age.
But there are also the IFRS 17 changes that mean they can only book sales when the money is received, not up-front, so that'll reduce headline profitability, but make no underlying difference to the business.
No idea how this will impact the share price, but the business now looks like it's in good health.
timarr
You’re absolutely right Timarr
never seems to get any momentum though - I hold, somewhat impatiently. It needs to start paying 5%+ yields realistically though to justify my hold.
Just (LON:JUST)
never seems to get any momentum though - I hold, somewhat impatiently. It needs to start paying 5%+ yields realistically though to justify my hold.
Agreed, it's why I don't hold at the moment, but I do think the cash will start to flow now - it's small and focused (in comparison Legal & General (LON:LGEN) are also seeing the db flows come through, but are now being held back by the asset management arm) and should be able to take as much business as it can handle. Hopefully their risk processes are up to it.
They'd also be a mere morsel for a bigger player.
timarr
MJ GLEESON (LON:GLE) Thank you Paul for your take on Gleeson. I have just listened to their presentation today and was very impressed by their openess and optimism for the Future. Regarding the selling of plots to Institutions , they stated that these are typically done at a 10-15 discount to selling Prices, So not a disaster as the trypical cost of a plot is less than 10% of the selling Price. They have also removed all restriction on selling to buy to let Landlords, which will definately help and are actively seeking new partnerships with organisations regarding shared Ownership. I recently bought into Gleeson and more than happy to hold for the next few Years.
Just a point on MJ GLEESON (LON:GLE) for laul.Asi understand it,their claim is affordability for a pair on the living wage rather than tje minimum wage but imaybe wrong.
Unless you have deep pockets time and knowledge the buy to let market is dead. There is money to be made but no longer the individuals retirement fund.
Not a small cap, but thought I'd flag up an unusual, not often seen announcement!
Phoenix group (LON:PHNX) have just announced a pre-pre-results update?
"We'll be announcing official HY results on 28Sep, BUT we'll release a pre-results Trading Update on 18Sep. However, TODAY we want to pre-pre tell you that we had a strong first half performance that is expected to be in-line with OR ahead of consensus forecasts"
Surely they should already know today, 4 days before the TU date (of the 18th), whether they are in-line OR ahead of forecast? Or is their financial controls and financial reporting process so bad that they don't know 4 days before a scheduled update date?
Very bizarre.
But good news that trading has gone well, as expected; there's such big macro structural tailwinds in their books, that IMO it'll be a big shock if they don't keep meeting expectations or even beating for the next few half years. The 10% dividend, IMO, is one of the most secure available at the moment.
(I hold in the Boon Fund)
Agreed - I also hold as a long term I ncome play boon
I can see Just (LON:JUST) ending up a similar story over next couple of years. Trades on a 65% discount to TNAV which seems way too steep for a business now generating own capital.
Just (LON:JUST) have been on a discount for years - Ive only traded when they drop significantly. Complex biz that analysts dont seem keen on - even when reporting great figures and now capital self sufficient. Currently Equity Release (high margin) is suffering as rates high and LTVs low. Annuities (low margin)highest volume since pension freedoms but regulatory fears and housing market will keep these down for a while.
Yeah agreed but they have largely desensitised to house price movement but investors don’t seem to have cottoned on to that yet. I suspect that will change when the dividend gets to an appropriate level but who knows when…. It has certainly languished for a long while but NAV is actually going up not down despite any housing concerns.
Thanks Boon, I hadn't seen that. This sounds like the actions of a very excitable small cap, not a £5bn elephant.
Cheers
Chris
Morning all, not sure what to make of yesterdays none event CPI data. If I plug their data in my spread sheet I get a higher month on month core...at 0.46%. This is quite high... and means we prob start 2024 at 4%. It's mainly energy, ie Oil and Gas driven. If there is such a thing as good inflation this is it. Maybe that's what's behind the market reaction. OR maybe it's just not how everyone is positioned. So the recession still hasn't arrived.... yet. For sure we will switch to the employment data to scrutinise for more evidence of a slow down...somewhat ironically I can imagine this is less well received since the Fed would appear to be a little boxed in.
I must confess Im finding the outlook somewhat confusing. The media will report all price rises as inflationary but we know this isn't the case. It strikes me that if the economy hangs in there, has its problems but no collapse then actually, nothing we are seeing is that bad for equities. Nominal growth is not too bad for real assets .... in Europe incl. the UK things could improve a little "if" China also improves.
No real change in view from me. All my positioning is in place but Ive exited some shorter term non core trades to increase firepower where possible. Not that easy to be honest when you "believe" all yours stocks are very cheap.
I note Yellow Cake (LON:YCA) a large position for me, is nudging NAV again in the current wave of enthusiasm. I remain very committed to the position but wouldn't be surprised to see a placing to cover next years options with NAK Kazatomprom AO (LON:KAP). If things get really silly these options could of course be seen to have franchise value to justify a premium.... but enthusiasm ebbs and flows... the Nuclear conference in London last week generated a lot of interest, and this story looks set to gain more attention into 2024. I also own a small amount of Geiger Counter (LON:GCL) and am kicking myself for not getting into Rolls-Royce Holdings (LON:RR.). The macro voices podcast last week discussing recycling waste (old rods) just highlights all the interesting stuff going on in the background. If anyone has any companies to look at in the space Id be interested. iShares have a launched an energy transition ETF and more will follow. Nuclear will figure prominently in these which will generate more interest in stocks into 2024 as a potential theme of the year.
Happy hunting everyone and all suggestions gratefully received.
Hi RDHOWARTH, you might like the Uranium discussion, which had some chat on this yesterday.
I also hold Geiger Counter and Yellow Cake. I bought Cameco as it was out pacing Geiger Counter, but have since sold and rotated the money into Geiger Counter (where it is a large holding). The discount on Geiger Counter is starting to narrow but still has some way to go. I also hold Centrus Energy and have done for many years. It is worth a look if you want to move further down the fuel supply chain.
For those unaware of the extent of current (and expanding) supply deficit in U3O8 you can read:
Goehring & Rozencwajg's commentary here: https://blog.gorozen.com/blog/...
Kupperman has just published his commentary on his visit to the recent nuclear conference here: https://pracap.com/the-bigger-...
Mike Atkin of specialist hedge fund Sachem Cove is worth listening too if you are new to the sector. There is a lot of material on You Tube, one recent example being:
You can get useful information here: https://sightlineu3o8.com/
and here: https://www.iaea.org/
In essence, the nuclear buyers for the power stations are short ... some of them very short.
There is a separate post on Uranium, you may want to post there as well: https://www.stockopedia.com/co...
Watkin Jones (LON:WJG) continues to slide. I guess the impending cladding fines in Scotland, where I believe WJG have built quite a lot, are a bit of a sword of Damocles.
Paul/Grahm/Roland, can you please have a look at Regional REIT (LON:RGL) . I know it's a disaster ): but your input will be much appreciated.
Paul, I was looking forward to your views on Wickes (LON:WIX). It was in the backlog yesterday but has disappeared altogether today.
I'm guessing it's a GREEN, but would very much appreciate your expert opinion on it. Thanks.
Oh yes thanks for reminding me about Wickes (LON:WIX)
We're getting a bit swamped with the quantity of companies reporting this week, so I'm hoping for a quieter Friday tomorrow where I can catch up, even if it's just brief comments.
Re Portmeirion (LON:PMP) - my take H1 results today: uninspiring.
Sales a bit down (and thus volume more sharply down) driven by US retail destocking but Christmas order book ahead of last year. Since the 2nd half is when they make nearly all their profit, and they say their distributor sales out data is strong, this the 'on track' message is probably about right - especially as they also call out expected H2 margin gains in H2 from automation, freight, energy use savings, email replacing some marketing costs and home fragrances finally getting back into profit after absorbing Aromaworks. Spode quoted as an ongoing success....so silence on other brands a bit of a worry .
My biggest concern is their online progress. This had gone through a period of strong underlying online gains ( not so much the sales that were helped by Covid but better photos, better offers, claims of other behind the scene improvements) but online fell this year as a % of total sales (51% to 48%). Own website sales are not called out which is usually an indication of weak performance. Since this channel offers +/-10% ppts better margins (CEO statement in webinars) and IMHO a big opportunity to build low marketing cost incremental sales from people who have bought once already, this is a concern. They brought in new online skills & staff 18 months ago, updated websites and it seemed to be going somewhere. I hoped this would be a big driver as their slightly older customer base went digital finally but it does not seem to be kicking on.
With debt up but inventory promised to come down, and dividends still paid but flat, it is all OK in tough times but not great. Margins are still over a 1/3 down vs 5 years ago despite 20% more sales value (reflecting the volume issues). So on track, leading to no movement up or down today and a depressed share price, seems about right.
I still think it offers good potential and enough resilience to wait for better times but they haven't quite got it firing yet. Perhaps someone else has something sharper to say on one of my 'favourite' stocks.
Full upfront disclosure. I have held this stock for a while lost 30% ish and finally sold on this update.
I think I have just lost some trust in them.
The top line revenue figure is bad, Assuming inflation is being somewhat passed on to maintain (poor) margins this is more like a 8% drop?
Online has stalled and given that retailers where destocking you would expect online as a % to have increased? It would be great to see them breakout online sales in the segmental analysis.
The only thing that seems to be underpinning the shareprice is a dividend they are now funding through debt and the trust that the second half the year will be stronger.
This is the quote from the interims today...
"H2 has started in line with our expectations and we have a strong Christmas order book, which is ahead of the same period last year."
This is the quote from the finals in March that preceded the July trading update that was a profit warning..
"Trading in the first few months of 2023 is in line with our expectations and our forward order books remain healthy. "
Portmeirion
Online consumer is tough right now, well thats not true it is brutal, customers are so bombarded and used to amazing offers that nothing really works at the moment, unless you spend big of FB/IG and then you just make Mark Zuckerberg richer.
Online demands higher costs, reduced margins, and dis-interested customers.
Very interesting though in the business I am helping / playing around with / mentoring / have invested (banana industries) is exact same thing, online is pulling teeth but if we go to an event or show face to face you get great sales and interestingly have a jolly good giggle all round
Maybe people want to go out and enjoy the face to face talking and meeting the sellers ?
Guess ultimately this is "the buying experience" that people are looking for and a jolly good giggle wit a nice vendor beats ordering online
Its the same in the other business I own (marine salvage) everything being done face to face and everyone happy .
Back to Portmeirion simply a case of doing the day job and getting that inventory under control and taking care of the long tail, the long tail is what they need to remove . Watch the stock file and make sure they have correct and transparent provision policy
Would be wise for Portmeirion (LON:PMP) to get out their numbers a few days before Churchill China (LON:CHH) as the comparison today doesn't help that's for sure.
Hello Zipmanpeter re: Portmeirion (LON:PMP) H1 (I hold),
Results very much as anticipated in the July Trading update. No surprises. At least no further bad surprises. Lots of talk of improving tailwinds, through falling freight costs (peak shipping season probably just approaching) and self-help measures, productivity and automation, reduced energy usage and waste reduction.
Lots of other major global retailers and Maersk shipping have commented on the US retail destocking since Portmeirions trading update. Seems real and long according to Maersk taking longer to clear than they originally thought. No shame for Portmeirion (LON:PMP) being in such company?
From the last presentation I understood that they shipped a lot of stock to the US (and into the UK and other markets ) at high shipping rates for the last season - as they sell down the remains of that stock it will be at much lower margins than normal - so good cash improvement coming but poor profitability until this stock is cleared? Be good to be more stock efficient but brands like Spode make high margins and long term sales from being able to replace breakages and add place settings to old and expensive crockery? Until they can be 3d printed on demand - which would likely defeat the object of the exercise - I don't see the long tail disappearing completely.
Useful input from Planetx - thank you - on how brutal it is out there in retail land. Btw I am still delighted with my Jobsworth/planetx bicycle workstand. Ideal for an occasional user. Main bicycle activity at the moment is carrying 30kg of apples in panniers down from the orchard to my cider press. Hence my late comment on Portmeirion catching up this morning. But now off to press some more apples. Early season this year.
Like you I have plenty of questions over sales and marketing strategy and execution. Particularly direct channel. Though I have read somewhere recently that at the moment consumers are enjoying the experience of buying face to face when they splash out - and can imagine that applies very much to premium purchases? So perhaps the rise of on-line sales is temporarily stalled? It seems to proceed ever upwards. But in fits and starts?
I shall be interested to listen to the Q&A at the presentation. I currently rate the management here and assuming that doesn't change then I see Portmeirion (LON:PMP) as doing the right things to recover from current US sales plunge and emerge stronger. The question for me is - how long? Should the restocking end in the next couple of months - then the recovery may be quicker than I currently envisage. But I'm not counting on it.
Churchill China (LON:CHH) versus Portmeirion (LON:PMP) Not so fussed myself. It looks to be horses for courses. Very different markets with very different prospects? Churchill China (LON:CHH) remains highly rated, and deservedly so given its consistent performance. But the opportunity for price re-rating looks limited? Portmeirion (LON:PMP) currently trading on 8x FY24 profits and 0.6x book value. With the work being carried out by the company there is a good chance of exceeding the forecasts. But if not, it's still good value. If it goes much lower (I am disppointed its not fallen further on the results ) I'll be happy to buy more. I much prefer the current risk/reward on Portmeirion (LON:PMP) at the moment as a long term investor. But if I was a trader I suspect I'd view it differently.
cheers
Mark
Mattioli Woods (LON:MTW) full review of FY results now published, with FV held at £9 per share. NB Management Webinar tomorrow (15th) at 12.30. Read note here and register on ED website to attend: https://www.equitydevelopment....
Hi Paul,
Just a minor quality of life improvement, but I like what you have done today putting numbers next to the companies you hope to look at. I work full time but check the site a couple of times throughout the day, it gives me an indication of when to expect a report on any companies I hold or that are on my watchlist. I have also enjoyed the quick comments you are putting up more recently, some of which are on companies that are not small caps but are in the news or could impact other small caps.
Podcast was great as always last week - keep the content coming!
Ben
Morning Paul & Graham,
Hope you're both well and thanks for the continued content, Paul, the weekend podcasts continue to be great, so 2x thanks to you and 2x beers next time :)
Not an RNS but spotted ~30% EPS upgrades for SOS this morning (NY and the following year) which may be of interest to you Paul in case you missed it.
All the best.
Thanks. I see the Sosandar (LON:SOS) Graphs have ticked up. Sainsburys shop-in-shops about to open (24th Sept I think). Did you see news anywhere?
Nope - No news - Quite common that us common folk don't see it
Just a reminder on Brooks Macdonald (LON:BRK) that post FY results this morning, we are hosting an online investor presentation TOMORROW at 11.00am with the CEO & CFO - you can sign up here: https://www.equitydevelopment....
Brooks Macdonald (LON:BRK) - Revenue & profit beat forecast but outlook cautious (new research report here: https://www.equitydevelopment....)
FUM closed FY23 (30 Jun 23) on £16.8bn, 7.5% up y-o-y (30 Jun 22: £15.7bn). This was the second-highest growth rate among adviser-channel-focused wealth management peers. Net flows totalled +£817m (FY22: +£785m), investment performance added +£363m, 2.3% of opening FUM, above the benchmark MSCI PIMFA balanced index which returned 1.6%. BM has flagged a healthy pipeline for FY24, although investor sentiment is still subdued.
We forecast FUM, revenue and underlying PBT growth of 10%, 2%, and 3% respectively for FY24 (down slightly from our previous forecasts) with BM expecting net flows to be muted but positive in FY24, while it continues to target organic net flows of 8-10% p.a. of FUM over the medium term (it has been attracting assets faster than competitors for some time now, evidence of a competitive, if not superior offering).
We remind readers that BM is in a huge market: c£1.2trn of UK household investable wealth is administered by advisory businesses. This market is subject to significant tailwinds, and advisers are increasingly outsourcing investment management to companies such as BM. BM also has a huge opportunity to grow its international business in the Channel Islands and Isle of Man.
Our fundamental valuation reduces from 3,100p to 3,000p per share, still 55% above the current share price. We also see potential for a sector re-rating (median PE of 17 versus 30 in late-2021) and for BM to command a premium rating given its outperformance compared to peers.
My morning smallcap tweet: Applying a bulletin boost-start
Focusrite (LON:TUNE) Checkit (LON:CKT) Loopup (LON:LOOP) M&C Saatchi (LON:SAA) Ethernity Networks (LON:ENET) ZAMAZ (LON:ZAMZ) Tremor International (LON:TRMR), Portmeirion (LON:PMP)
◄Focusrite (TUNE)► guides FY-Aug rev £177m+ (£184m) and EBITDA at the lower end of market expectations of £38.2-39.0m. Well, that's virtually in line then. [SP=500 Cap=296m]
◄Checkit (CKT)► H1-July in line. Guides FY ahead of current market expectations. [SP=27.7 Cap=30m]
◄Loopup (LOOP)► H1-June rev up 85% and adj EBITDA £2.5m (-£1.5m). Guides FY broadly in line. [SP=2.23 Cap=4m]
◄M&C Saatchi (SAA)► H1-June rev down 7%, pretax down 45%. Cost cutting. Outlook - "In light of the continued challenging macro environment, we are taking a cautious view overall on H2". [SP=130 Cap=159m]
◄Ethernity Networks (ENET)► share subscription agreement with 5G Innovation Leaders Fund extended again, to Mar 2024. $1.4m outstanding. [SP=1.25 Cap=2m]
◄Zamaz (ZAMZ)► name change to Dispensa (DISP) happens tomorrow. [SP=4.5 Cap=30m]
◄Tremor International (TRMR)► seeks court permission to repurchase a further $20m shares. [SP=139.85 Cap=200m]
In line: PMP
Focusrite (LON:TUNE) I hold
Creditable performance I think in today’s trading update. Cash marginally down but is after Sonnox acquisition. New Scarlett range very well received. Expects to meet lower end of current market expectations. Would appreciate you views Paul.
What is good about Focusrite (LON:TUNE) is that they are not low cost 'box-shifters'. All their brands are above the middle range when it comes to quality (& price). Sequential & Oberheim particularly are very high end, high price brands.
I'm unsure about Sonnox, I've never used any of their software. But the big problem with music software plugins is they are regularly on sale. If you are are a savvy musician/consumer, you never have to pay full price for music software - you can just wait it out until one of the many sales come along. 70-80% discount is pretty typical.
But apart from that, I would rather hold Focusrite (LON:TUNE) than a music retailer - speaking from experience, most just buy from whoever is cheapest. There must be a constant squeeze on margins to get business.
A fairly routine set of results out of Oakley Capital Investments (LON:OCI) today. I have a substantial holding, and continue to hold. An enormous amount of net cash in the fund, which is both good and bad.
Oakley Capital Investments (LON:OCI) £248m cash, but over £800m in commitments to the Oakley funds, so looks like all this cash will have a home and wouldn't treat it as spare cash, that could for instance be returned to shareholders.
If you listen to the presentation they stare spare cash ( above commitments) will be used for buy backs. Timing is not stated, but as I heard it there will be further buy backs. Personally this discount to nav is excessive for a fund that performs well. I have held for 5 years.
I agree with Bouden54. Also have a substantial (for me) holding, and I wish I had the courage to diversify LESS and not insist so much on dividends to live off. Their track record continually impresses, with many aligned interests and an impressive handle on digital transformation of industries across Europe. This is one vehicle where it pays to listen to Steven Tredget's updates and go back to sleep, feeling your longer-term money is safe in their hands.
Agree with comments on Oakley Capital Investments (LON:OCI) and I hold too alongside a basket of several simialr trusts such as HgCapital Trust (LON:HGT) , but don't forget the average debt of the underlying companies is 4x EBITDA (down from 4.3x), so this is not as boring as some might wish!