Small Cap Value Report (Thu 18 Apr 2019) - D4T4, TRI, MONY, FCH, RWS, AVST, Loungers

Good evening/morning, it's Paul here!
These 7am flying starts have been a bit of a shock to my system this week (being more of a night owl), so I'm jolly glad that it's the long Easter weekend coming up, to chill out a bit!
I'm off to Munich for a couple of nights, tomorrow. No particular reason, other than it was a £150 per person special offer from BA, flights and a nice hotel - pretty good, eh! I can recoup a fair proportion of that in the executive lounge before take-off too.
So I'm brushing up on my O-level German. A phrase I remember from school is, "Was?! Du lieber gott! Das ist doch nicht moglich!", or something like that. I'm looking forward to using that phrase, in an indignant tone, if presented with an extortionate bill of any kind.
Let's hope I don't cause a diplomatic incident over Brexit. I've always liked Germans anyway. They make fantastic cars & machine tools, love their beer, and have a wonderful sense of humour.
Early Skim of the RNS
(7-8 am brief reviews)
D4T4
Year end trading update - 31 Mar 2019 - adjusted profit "slightly ahead" of expectations.
Strong pipeline, so confident will achieve market expectations for 31 Mar 2020.
Share price has risen c.60% since end 2018, so good performance looks to be already baked into the share price.
An interesting company, so I will take a closer look later this morning.
Trifast (LON:TRI)
Trading update - for FY 03/2019.
Underlying profit "slightly ahead of management expectations".
New banking facilities agreed, gives headroom for more acquisitions.
Positive outlook, despite macro headwinds.
I'll write an enlarged section below.
Moneysupermarket.Com (LON:MONY)
How are the friendly meerkats getting on?
Q1 2019 trading update today.
Revenues up 19% - driven by more people switching energy suppliers, but growth expected to moderate during the year.
Confident of meeting market expectations. Confirms special divi of 7.46p.
Share price has been strong this year. Price looks a bit toppy to me (fwd PER of 18.4) for an intermediary with no moat. Terrific track record of growing profit each year.
As nearly £2bn market cap, I won't expand on this. Was just curious to see how they're trading, and little other news today.
Funding Circle Holdings (LON:FCH)
Mid-cap, with mkt cap around £1bn.
I looked at this share earlier this week, with a friend who is thinking about shorting it.
Q1 2019 trading update today, confirms it is trading in line with expectations.
Its business model looks absolutely terrible to me. It's burning cash at a prodigious rate (although has over £300m cash pile, from the IPO proceeds). Overheads look way too high, especially very high staff costs, and marketing.
It originates loans, and earns transaction fees on loans advanced to SMEs, and ongoing fees after that. External investors provide the funds, so FC sits in the middle.
It seems to me that, when the next recession hits, default rates on SME loans are likely to be high, which would then lead to transactions drying up. FC would then be high & dry.
At some point I think this could be a cracking short. Just not sure when? No further reporting on this one here today.
RWS Holdings (LON:RWS)
H1 trading update, 6m to 31/3/2019.
Says it has had an "excellent first half", and "performed strongly", but no comment is made on how this compares with market expectations (broker consensus is anticipating a big increase in earnings this year).
I cannot therefore judge, since this announcement does not give the key information investors need - of actual performance versus market expectations. A thumbs down for this ambiguous announcement. Companies need to be much more clear than this, when reporting performance.
This share has done very well in recent years. High fwd PER of 25.5.
Avast (LON:AVST)
Cyber-security company which floated last year.
£2.7bn market cap. Excellent growth track record. Seems to have a lot of debt. PER surprisingly low (12) for a growth, tech company. Might be worth a closer look perhaps?
Says Q1 performance has been strong.
Dentist - 9-11 am
(including travel there & back)
Walking home, after an uneventful dental inspection, I always try to think of ways to research companies. So today I tried one of the now world-famous vegan sausage rolls, from Greggs (LON:GRG) - what a marketing coup this idea was. It was even mentioned in a recent trading update, as having notably boosted profits.
I can report that the vegan sausage roll looks, smells/tastes exactly like a normal sausage roll. Which left me thinking, do vegans actually want an alternative to meat that tastes & even has the same texture as meat? I was a veggie for 5 years, in the distant past, and I wanted meat alternatives that were nothing like meat.
So maybe these vegan sausage rolls are a lower guilt alternative for meat eaters?
Loungers
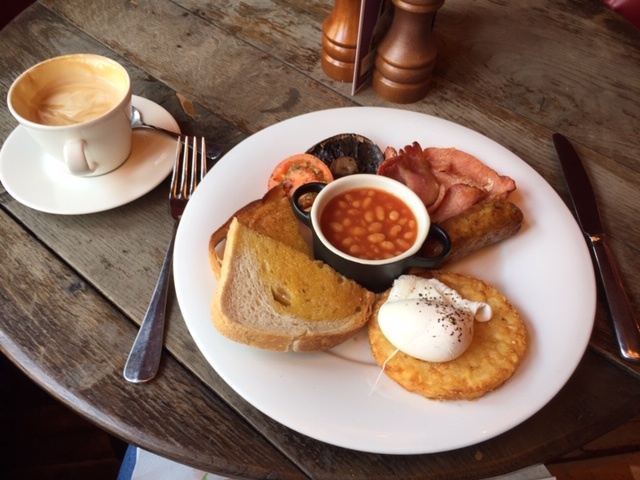
Also, I took the opportunity to visit a "Cosy Club" - part of a bar/bistro chain that is soon to list on AIM - called Loungers - intention to list RNS is here. I was really impressed, having had a "breakfast club" cooked breakfast (tasty & good quality ingredients, speedily cooked), and an excellent, if not quite hot enough coffee, in pleasant surroundings, for £8.25;
The coffee was delicious, and had smart Cosy Club branding on the cup & even the sugar cubes;
Why's that gone sideways? Oh well, it works if you tilt your head to the left.
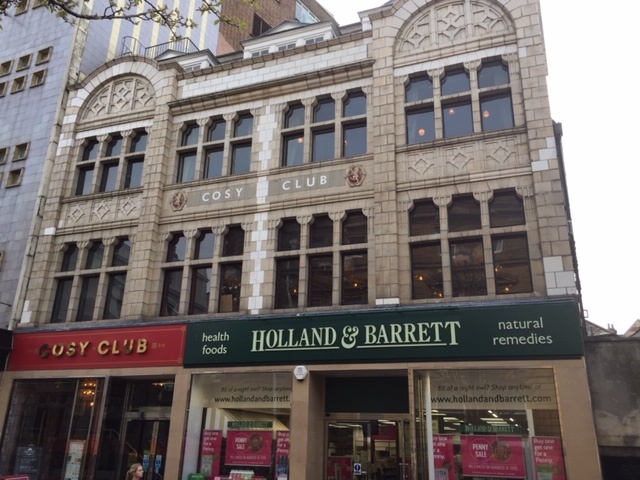
Above is the Cosy Club site I visited today, in Bournemouth. I've walked past it many times, and always mistaken it for an amusement arcade, due to the name, and appearance of the small ground floor facade, which is all red and chrome. Once inside, it's a large 1,2 & 3rd floor emporium, with several bars, a restaurant, private hire rooms, and a terrace on the top floor. A terrific place, nicely decorated, and with good value all-day food offering. Plus drinks & coctails. The top floor would make a nice venue to do investor meetings/socials actually, and it has a lift - handy for people with mobility issues.
So that has whet my appetite to read up more about Loungers imminent launch on AIM. It'll probably be over-priced though, as IPOs usually are.
Main Report
(more detailed sections on shares of particular interest, which might be a little later than usual, depending on how things go at the dentist!)
D4T4
Share price: 266p (down 4.3% today, at 11:31)
No. shares: 39.2m
Market cap: £104.3m
D4t4 Solutions Plc(AIM: D4t4), specialists in data solutions, is pleased to provide the following trading update, ahead of the publication of the Group's final results for the financial year ended 31 March 2019 which are expected to be released in the week commencing 24th June 2019.
To save me re-tying it, the highlights section summarises the key points, in a nice red font;
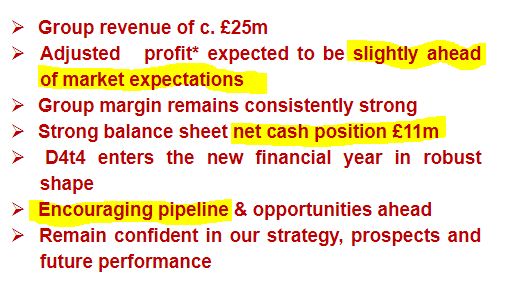
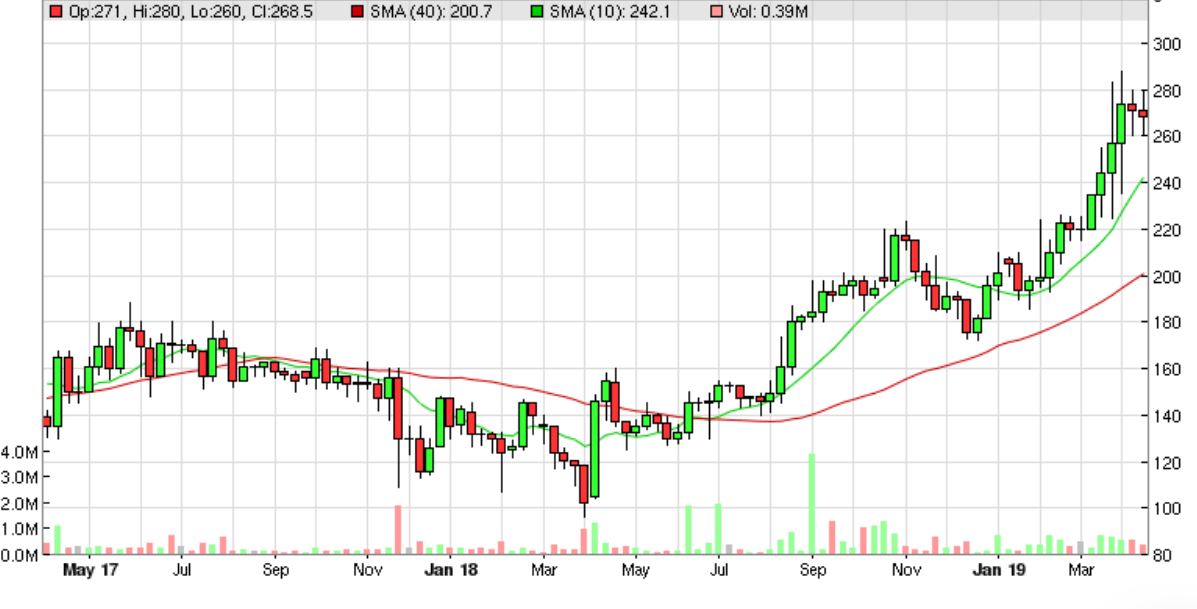
As I mused above though, the question is whether this positive trading had already been factored into the share price, in the big recent rally? The share price falling 4% today, at the time of writing suggests that, yes the good news is already baked into the share price. Clearly some punters are banking their profits today - which probably makes sense if you have a small position, and think short term, which in my experience is how many private investors (or traders really) do operate;
Broker update - the house broker has published a useful update note, available on Research Tree. This is essential reading, as it flags up some important issues to consider when valuing this share, namely;
- IFRS 15 adoption has skewed results, to the benefit of the FY 03/2019 revenues & profits, if I've understood this issue correctly
- "Exceptionally low" tax rate for FY 03/2019
This has caused fluctuations in EPS. The forecast EPS & PER are as follows;
FY 03/2019 is 13.3p (PER of 20.0)
FY 03/2020 is 13.4p (PER of 19.9)
The underlying increase in EPS is greater, as the FY 2019 EPS figure is flattered by the two issues in the bullet points above. Hopefully that makes sense!
Balance sheet - I've reviewed the last reported balance sheet, and it looks fine. With net cash of £11m reported today (as at 31 Mar 2019), that's down from £12.2m reported at 30 Sep 2018.
With good overall working capital - a current ratio of 2.22 when last reported at 30 Sep 2018, and no long term debt, this is a very soundly financed company. Shareholders can relax, even if it were to go through a patch of bad trading (which it did e.g. in H1 of FY 03/2018)
Directorspeak/outlook - sounds upbeat;
"Our strategy continues to deliver and is reflected in our strong overall growth. At the same time we continue to innovate our product, grow geographically and deepen our relationships with our strategic partners.
The business enters the new financial year in robust shape after closing a number of significant contracts in the second half year, these contracts will have an impact on 2018-19 and on subsequent years, and we are encouraged by the opportunities and outlook for the business in the coming year.
Consequently, as a Board we are confident of delivering results in line with expectations for the financial year ending March 2020."
That's a solid update, so it sounds as if the company shouldn't be at risk of a profit warning for a while.
My opinion - I don't really understand what this business does. It seems to be a software company specialising in managing data, not something I understand. Hence it's difficult for me to assess the shares.
Yes the company is doing well, but the PER of 20 already reflects that.
Historically, its project-based sales have been very lumpy at times. So I'm not willing to pay top dollar for a business that could potentially run into problems again in future, with contract lumpiness. The narrative does talk about increasing recurring revenue though.
It would be interesting to find out more about this company though, as it's clearly performing well, so the products must be good. We saw with Sopheon (LON:SPE) how a software company that gets onto a roll, with increasing sales, can be very lucrative.
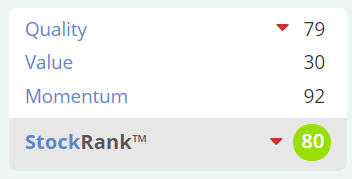
What do the Stockopedia algorithms think? Strongly positive - "High Flyer" classification, and a strong StockRank - neatly encapsulating that this seems a quality business, with good momentum, but it's pricey;
Trifast (LON:TRI)
Share price: 229p (up 6.5% today, at 15:58)
No. shares: 121.9m
Market cap: £279.2m
This is an acquisitive, international, industrial fastenings group. It updates us today, for the year ended 31 Mar 2019.
The market clearly likes this trading update, with the share price up 6.5% today - although there are only 50k shares traded so far today. There could possibly be some delayed (larger) trades printed after the close of play.
A solid finish to the year, leaves Group underlying profit slightly ahead of management expectation...
Helpfully, the house broker has quantified this, as an increase from 14.1p to 14.3p - giving a PER of 16.0 times.
Forecast for FY 03/2020 is a rise to 15.0p, giving a forward PER of 15.3
I'm struggling to think why the rating should be any higher than that?
Outlook - comments seem upbeat throughout, despite macro headwinds.
Recent contract wins and a solid pipeline across the business bodes well for the future...
I like that these specific reasons are given, rather than the more usual "well placed" type of outlook comments that many companies give us.
Balance sheet - I've checked the most recent balance sheet, and it's fine - quite strong actually.
It looks to me as if Trifast has done a good job in maintaining a sound balance sheet, despite making acquisitions.
New banking facility - new £80m facilities give it £40m headroom for organic expansion (capex presumably), and acquisitions.
Is this the right stage in the economic cycle, to be gearing up? I'm a bit wary about that.
My opinion - this group seems to have done a really good job in growing profitably. Indeed, the graphs below look almost uncannily smooth;
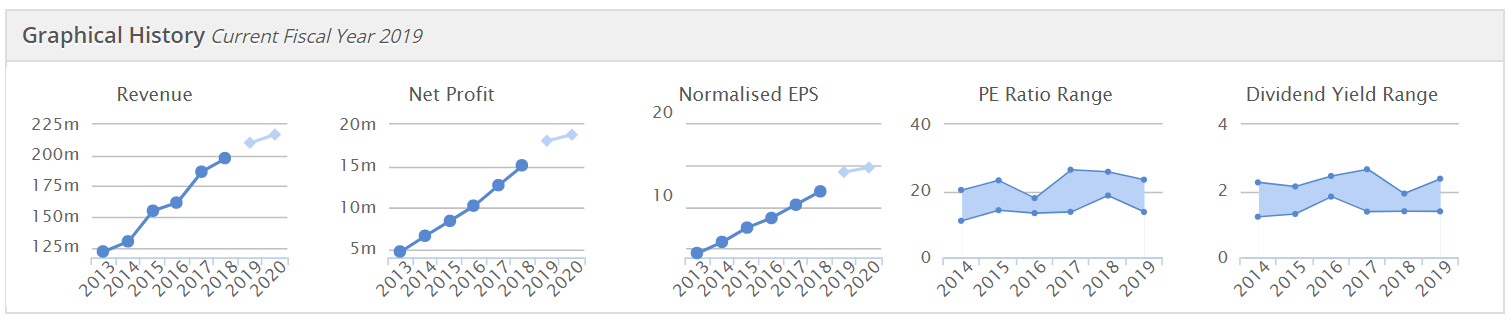
Maybe there could be more upside on the share price? It doesn't strike me as obviously undervalued though - the valuation looks about right to me. Sentiment could take it higher though.
Exposure to the automotive sector worries me a bit too, although that doesn't seem to have hurt TRI to date.
I've also reviewed the Loungers "intention to float on AIM" document. I'll report back to you with my views once the price is set, as it's all meaningless until we know valuation. It will provide a very interesting comparison to Revolution Bars (LON:RBG) (in which I hold a long position), so I'm looking forward to crunching the numbers on this one in future.
Have a lovely Easter break!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Error
Love your new approach Paul and wish you courage to keep it up..........early mornings can be a great time of day and after a challenge you can reward yourself o a well deserved basis......great way to start the day.
Re £d4t4;
There is another thread on £d4t4 on Stocko, wrote the below material in quote last Dec 18 which gives a little bit of background on what the company does and the Celebrus offering - other thread is here
While probably innocuous enough , the FD gave 3 month notice a couple of weeks ago: she is leaving on good terms
Finally, most of today's 6.5% drop is probably attributed to a very big holder selling ( a hedgie selling 0.25% issued a TR-1 this afternoon) most of the buys today were small PIs
Funding Circle Holdings (LON:FCH) is a bit of a mixed bag for me. I have interest in two respects 1) I opened an ISA with them in August 2018 so I earn money from loans with them 2) I bought into the IPO at launch.
As a lending customer of Funding Circle, I really like the hands-off approach to getting a better return than 0.2% in the bank account. I just drop money in, and every day I can see it grow with the principle and interest repayments (which is reinvested automatically for me). I think they sell this point well to the public, and it is attractive. Helping small british business is a marketing point that got me interested. I can earn good returns and help Britain (that's the speil anyway). I think this is the niche area that they cater well for - punters who want to make their money work more than cash ISA accounts with their bank, but aren't quite ready to get down with picking funds, trusts and shares (or have no desire to learn). I'm aware of rate setter and others, but for some reason funding circle spoke to me - I liked the name, the logo, and the way they "big up" helping small business thrive. So in that respect, the marketing spend has worked on me!
However, I am nursing a loss as an investor in funding circle in the region of 30% - 5% depending on the price action. I still hold because I want to see this share stare me in the face everyday to remind myself to do proper research next time (don't just blindly buy an IPO which is what I did).
As far as I can make out, FC is one for the distant future. It's all about them growing the US business (and other regions) and growing more organic origination (and essentially becoming the household name for innovative finance). I actually think the business model is good - they take 1% of the interest payments and then pass the rest onto you. They never have capital at risk, it's always the investors money that will be lost to defaults. So originating more loans, and ensuring they have investors willing to fund the loans is the growth strategy. Which going by their reports is working!
Time will tell on this one ...
Jared.
Paul
Not sure whether your reference to meerkats was a case of brand confusion or simply to highlight the competitive landscape in price comparison websites. Moneysupermarket.Com (LON:MONY) of course had its somoneysupermarket campaign which it has now swapped for a calmer ad campaign. I was a holder principally because of the company's consistently good cashflows but also reached the view that the valuation had become tippy, sold out recently and then missed the bounce today! I am not feeling quite "so moneysupermarket.com" now.
I too really enjoy the new format. Thank you. But please don't feel under pressure to feel you have to do it that way all the time if you feel like a lie-in or duvet day.
This new format makes me hungry
I agree that the Greggs vegan sausage roll is great, as is yours and Graham's commentary on here. Keep up the good work
Re Loungers I have been a regular customer of one of their lounges in Glossop called The Pico for the last 5 years or so.
In that time they have grown significantly, initially selecting locations like Glossop, Market Harborough and Rugby where they could make a big impact.
I have always believed in investing in companies where the service you receive is good ( that theory of course was blown apart by my investment in Valarie Patisserie!!) but there is a lot to admire in Lounges operation and they respond well and positively to feedback.
One word of caution though, the outlet management does seem to change quite often, they may need to do something about staff retention but if the price is right, I might be tempted to invest.
Hi Paul
Congrats on the new format and starting work so early.
Like you I have never realised what the Cosy Club in Bournemouth was, I will certainly have a look at it soon. Do you live locally, I do. If you do organise any Investor clubs or meetings locally, do count me in, please!
(LON:AQX) investor presentation by Alasdair Haynes, CEO & Jonathan Clelland, CFO & COO
Not related to any news today (AQX had FY results 20.3.19). However, we've just published this video presentation, and quite aside from the investing opportunity it presents as a MiFIDII/compiance play (mentioned by Stephen English's interview Pt 1, the insight it gives to how pricing and liquidity in equity markets works, is fascinating, and a must watch for any equity investor.
mind-blowing really and I know where my first port of call will be on Tuesday morning.
thanks for bringing it to our attention.
I used to like Henning Wehn, but don't now the more I watched him.
In the clip you have linked to , Henning Wehn dies on his ass at the end because he tries to tackle a subject that he doesn't understand, and is way to big for him. And all he succeeds in doing is insulting the audience, who regularly boo him.
He really has got a lot to learn about the craft of being a comedian.
Hi, TheShareWhisperer,
Yes, I know what you mean, when you say;
I enjoy his contributions to panel shows, mainly because he has such a funny accent.
Reminds me of my German-Swiss cleaning lady, many years ago, called Rita. At the time, I was a heavy smoker, and she would always say to anyone who would listen, "Oh, I wish he (i.e. me) would schtopp schmoking! The whole place schtinks!!!"
If my Mum was around, she would crease up laughing. The time Rita asked Mum how to clean the new "non-schtick" frying pan, I think Mum almost collapsed.
Then I accidentally spilt an entire packet of coffee all over the worktops that Rita had just cleaned, and she yelled, "Ahhh scheise!" (that means oh shit in German)
Best wishes, Paul.
Hi Paul,
Regarding £D4T4 - I like this company, unfortunately I'm no longer a holder though I was intending to get back in.
"strong demand for our Celebrus software" - I think this is perhaps it's key appeal as it handles all Data Protection concerns alongside it's key functionality. I work in software and spent some time assessing the implications of GDPR and to the best of my knowledge, most small-medium companies are still not equipped to handle their obligations, and I haven't seen a flood of notable companies offering their services in this regard.
Regards,
Lee
Topps Tiles (LON:TPT) has announced the acquisition of Strata Tiles in the Commercial Tiling Business – so a considerable extension from the existing Parkland activity (acquired August 2017). Topps will Initially buy 80% for £3.3m plus £0.4m (closing adjustment). Strata had sales of £4.8m and PBT of £0.7m in the year to March 2018. This compares to revenue from Parkside of £2.3m in FY 2017 – Parkland revenue has been growing strongly since then, although I can not find a revenue breakdown for 2018, although it made a trading loss of £1.1m in FY 2018 and it was reported that losses were expected to continue “at a similar level as we invest in the future.” Even after the Strata acquisition though the commercial tile business will still be only a mid-single digit percentage of total sales.
Topps Tiles' RNS also said that net debt, post the initial payment for Strata, would be approx. £22m. This implies by my calculation that free cash flow of only about £2m in the first 6 and a half months of FY 19. This is perhaps understandable given that FY 2018 saw very strong working capital management. Brokers Liberum have a forecast of approx. £12m of FCF in FY19.
Paul, I speak on behalf of all subscribers, raid the Stocko petty cash box, for a few beers.
Pip
On Funding Circle Holdings (LON:FCH)
From what I understand FCH
-takes money from people
-has a bunch of spiffy software rules that they use to select who to lend to
-lends to ...
-passes money back to people
-makes money on the interest gap
Not to say that they will not be successful but
- they lack scale compared to a bank
- those spiffy rules will be replicated or bettered v. quickly
- the bank _always_ knows more about its own customers than anyone else
- banks can be quite lean and adapt where there is competition
and
- once the loan is made, in FCH that's it.
With a bank effectively they have loaned at Z% and borrowed at Y% (Y < Z).
If at some point in the future they can borrow at X% (X < Y ) they can probably 'move' the borrow - making more money. I doubt FCH can.
(disclaimer - I am not a banker :)
Not to they will never make a profit, but I doubt it will be ever be v. big.
There are aspects of the business model that I appreciated: they used to allow you to lend to specific businesses in specific areas (not anymore)
but I actually wanted to support small business near me (the South West) and would accept a slightly lower return if I could do that.
As an 'investor' with them I do think there was a certain beauty in the previous model which allowed people to pitch their business and in a reverse auction type scenario, the market would set the rate.
I do think at the outset they were designed to assist those businesses who the banks would refuse to lend to, and these businesses had to justify themselves. I do remember the facility to engage with the owners.
But very quickly, that had vanished in the search for scale. They could fill a loan almost instantly now instead of wait 1 week to wait for the market to make their bids. The type of business also seems fairly indiscriminate now.
Their returns are being blighted by things that almost resemble fraud, ie businesses taking a loan and not paying it back after a month. Transparency across the whole business has gotten worse instead of better as time has gone on. I do think these factors are behind the closure of FCIF, because the poorer returns were bringing heat from the institutions.
I do think it will be a case that one day the tide will go out and they have been swimming naked.
Perhaps Ratesetter may be next for the IPO treatment? Although I see no real competitive advantage for them either.
I don't myself understand why they are choosing to lose so much money. Other people in this space are managing to make money at a more modest scale. I don't believe this is a Facebook, winner takes all, sort of business. Making money out of SME lending is all about weeding out those who are never going to pay you back. That does not need scale.
On the other hand, from the short-side perspective, there must be an awful lot of cost could be taken out quickly.
Morning Paul.....may I say ,not being a morning person either, how I appreciate your early start as I really like this new format. I like the concise nature of your early reports,lots of useful info that help mould my investing and the lengthier follow ups later on....
Thankyou and enjoy Germany
Pennyledges
Good Morning Paul,
I have to say, I really am enjoying the new style of reporting. Experimentation, done in the open, often can yield interesting results. You get fast feedback to enable you to tweak direction, often so beneficial. So thank you, for that!
In terms of Germany, I love it and the people. We were in Munich for a Stag do a few years ago. After a good few Steins in the Englischer Garten, a rather drunken member stumbled outside and into a cycle lane. A cyclist ran into him, and they both fell into the side of a parked taxi, knocking off a wing mirror. At this stage I was expecting an argument / Police involvement - but no such thing occurred! Rather, everyone was rather apologetic to each other, and the wing mirror went back on with no damage done. Later, the Stag, rather cheekily, stole a mini electric van thing used to ferry the large glass beer steins back to the bar for cleaning. When the driver caught up with him, after he crashed it into an empty table, everyone laughed as he was given a polite dressing down. No harm or damage done.
I was astounded at the patience and acceptance of what, in both cases, could have been dealt with in totally different ways. Ultimately neither incident caused harm or damage, and everyone had a hug after. I was happy and please to admit my view of Germans prior to visiting was not that of which I experienced - but this is why we travel, to broaden our horizons and dispel these silly, often ignorant, ideas we have of people from other nations.
The only warning for you is that I was told before visiting that German Beer doesn't cause hangovers. I can say, with some authority, this is not true!!!
Thanks,
IG
"Later (he) rather cheekily, stole a mini electric van thing used to ferry the large glass beer steins back to the bar for cleaning... (and) crashed it into an empty table"
Were you in Germany with Prince Phillip?
Who says this is not a great tipping service ? At £150 for a break to Munich, I shall pay more attention to BA city break offers. Thanks Paul.
RWS Holdings (LON:RWS): They have done well in more than recent years. Stockopedia shows the share price as 5.87p back in July 2003, now 561p. A 95 bagger. [The Stockopedia graph appears to be correctly adjusted for share splits]. I have held since 2010.
If only I had done the same with Trifast (LON:TRI), purchased for 22.5p in 2009 and sold for a quick profit within 12 months, therefore missing out on a 10 bagger.
£AVST I have been using either Avast or AVG anti-virus software since about 2004, with no viruses. The paid for Symantec anti-virus used prior to that did not stop a virus.
So I think Avast have good products. Avast have acquired AVG in 2016.
I use the free version and since there are no adverts, presumably they derive no revenue from me. So I guess the business model is to get as many customers as possible onto the paid products. Further research was put on hold when I noticed the AIM admission document is 300 pages long. Deciding which companies to research in depth is always tricky.
£AVST I have been using either Avast or AVG anti-virus software since about 2004, with no viruses. The paid for Symantec anti-virus used prior to that did not stop a virus.
So I think Avast have good products. Avast have acquired AVG in 2016.
Of course, the fact you've got no viruses doesn't tell you anything about how good the product is :-) I've never had a virus in 25 years of internet use, and I suspect the vast majority of internet users who use even the most basic common sense and internet hygiene have never had one either. In security terms, Anti-virus is a mere fig leaf but worth having none the less.
Having said that, there is not a bargepole long enough with regard to investing in these kind of companies. They are always one hack away from having their reputation trashed, and reputation is everything in cyber security. For instance, Avast bought Piriform, maker of the popular CCleaner tool. What about this?: https://blog.avast.com/update-to-the-ccleaner-5.33.6162-security-incident
I haven't used a third party Anti-virus suite for many years as the basic Defender AV and firewall built into MS Windows OS is more than adequate, and actually comes out better than many third party products in tests. How can you compete with something that is free and built into every PC, laptop etc. ?
All the best, Si
Hi Simoan,
I have also used AVG anti-virus software, free, for years.
They try very hard to get you to upgrade to other products, such as PC tune-up things, etc.
I did once succumb, and agree to pay something like £20-30 subscription for tune-up software on my laptop. I did this on the basis that I trusted AVG to scan my computer for viruses (I agree, not really necessary these days, unless you do something really stupid). Therefore I trust AVG to tune-up my laptop. It didn't really make much discernible difference, but might help very slow computers speed up a bit by, e.g. putting background programs to sleep, then waking them up when they are needed.
For all I know, I could still be paying £20-30 per annum, as I don't tend to check my bank statements for small items.
Regards, Paul.
I set my parents in law up with an Avast (LON:AVST) subscription and prepaid for a 3 year licence naively believing that would be helpful for them
Not so: the constant push and pop-ups with warnings caused them to sign up for yet another subscription fearful of the barrage of warnings (on a PAID sub)
On principle that annoyed me, it's no different than doorstep rogue traders exploiting OAPs
I then undertook the task of getting a refund from the fragmented organisation that is the post acquisition estate of Avast (LON:AVST): they really don't seem to do backend integration and are not really sure who bills whom in their various profit centres.
Coupled with that , they use fairly sharp practices in embedding software on their downloads, hijacking browsers and search engine functionality : all the bad old stuff of 10- 20 years ago
Clearly I am jaundiced by my experience and biased beyond objectivity. In the Peter Lynch school of investing I'd be a short
Many software companies have updates which try to get you to install other software. For example, every time I upgrade Flash player, I need to make sure boxes are unticked so nothing else gets installed.
This problem is not specific to Avast (LON:AVST), although they are among the many guilty software companies.
All the pop ups and other irritations can easily be turned off, so you forget it's there.
In response to some comments from others, Avast claim over 400 million users and their accounts suggest there is significant revenue, so whatever each individual here thinks, people DO use Avast and some are prepared to pay for it.
As for the importance of reputation, well yes that matters. Reputation also matters with many other industries - airlines, aircraft makers, car makers, food producers, jewellery retailers -it is almost endless.
Boeing have suffered a recent reputational hit, but despite a few crashes along the way, anyone buying the stock for 20 cents in 1973 would still be quite happy with the $380 current share price.
As another example of reputation, anyone owning Ratners stock might not have done so well.
I don't own Avast (LON:AVST) but may research it further.
Many software companies have updates which try to get you to install other software. For example, every time I upgrade Flash player, I need to make sure boxes are unticked so nothing else gets installed.
Hi jonesj
You must be resident outside the EU (or disguising your location): under GDPR they're not allowed to do that - you have to specifically consent to the update, not have to de-select it. Since GDPR came into force the Flash upgrade display I get has changed to the opt-in model.
One of the many advantages of the much derided GDPR ...
timarr
No doubt, but it is a confused business model : that can be tolerated in ad-financed freeware or monitisation by affiliate marketing or search-redirect when the core product is FREE. My point is that in PAYING for a software licence this kind of nonsense is unacceptable. Most software providers of any repute simply don't use these practices in paid-for-services and those that do are barge pole for me.
I have also used AVG anti-virus software, free, for years.
They try very hard to get you to upgrade to other products, such as PC tune-up things, etc.
Hi Paul,
The great irony is that all this additional software only further slows down your PC because there will be all kinds of CPU processes running in the background and using up memory. I've never had to recover from a computer virus but I have wasted many hours of my life trying to uninstall "free" AV software! It's a menace and almost as bad in hammering your PC performance as what it is supposedly protecting you against.
Thanks for the great reports this week. Enjoy Munich!
All the best, Si
We should expect an update from "Tooth Hurty" then Paul?
Apologies Easter W/e mentality kicking in already
PS - Love the new format and I do really appreciate the workload it puts on you and Graham
Funding Circle Holdings (LON:FCH) was started on the premise that fintech could do the SME lending task more cheaply than traditional banks due to lower overheads. That doesn’t appear to be the case, or it is the case but the interest rates that can be charged are just too low (in the current low rate environment) to make significant profits doing that activity. The diversification they are trying appears to me just to be a smokescreen for that fundamental problem. Uninvestable in my view.
£d4t4 has had a super run since last April's break-out and rode the downturn in Q4 very well. I took a bit off into results as it was looking toppy: slightly ahead is probably well baked in
On a related point, breakouts (or breakdowns) in price can be very useful indicators of bigger changes in the fundamentals of the company, the macro/structure of the market, sentiment etc
I track gaps daily as they do open opportunities both shorter and longer term: published daily on my website and via Twitter. They are often the Yang to the RNS Yin, the initial market/price reaction to the news.
Have recently done a backward study of Gaps Down, typically big gaps down occur in multiples and mirror the multiplicity of profit warnings (they are often the price reaction to those anyway, but not always as they can frontrun they actual RNS ) ..will pull together an article at some stage to highlight a few case studies and some broad principles based on the data.
Clearly £SIMI. Tanfield (LON:TAN) and £GAT have delighted the market while Block Commodities (OFEX:BLCC) and Starcom (LON:STAR) have fallen short. (I've ignored Aimer resources as they are crap shoots in both directions typically)
Looks like Modern Water (LON:MWG) results are delayed again. Prelims were supposed to be out no later than 31st March. That was then revised to finals will be out on or around 18th April. Nothing yet so unless released later today it’s going to be Tuesday so not very “around” either. Folks may remember that this is one of the “high quality” companies exhibiting at Mello last year. Never a good sign when results are delayed.
£D4T4 gives off a strong message being: "confident in delivering results that will be in line with expectations for the financial year 2019-2020, so early in this financial year.
Worth noting its particularly, strong demand for our Celebrus software and a move to a recurring revenue model. Declaration - My 2nd biggest holding. Ian
Funding Circle Holdings (LON:FCH)
Funding circle must spend wads on advertising their wares to small business (just checked and they do indeed) , in some respects i think this has worked for them as they must now be one of if not the top dog(s) in this area i would guess?
looking at sales we have 141 mill 2018 - 200 mill 2019 and 281 mill 2020 expected . so this is decent growth.
Would i want to invest in Funding circle - Hell no. I wouldn't necessarily agree that everything will dry up in a recession - small business has always and will always continue to exist and available funding for small business is shockingly expensive and hard to come by unless you don't need to borrow the money. I would say though from an investment point of view funding circle doesn't turn a profit and would need prospects of £100 per year profits in the future to justify the £1 bill tag - i just don't know where that is going to come from anytime soon.
Would i short Funding circle or be confident it is over valued? - Hell no - why take the risk - its got excellent sales growth - has the huge market presence it needs now and presumably it could be generating decent profits right now if it wasn't still investing for expansion / discretionary advertising to speed up growth. I am kind of guessing once they have a customer the potential to keep this customer long term next time funds are needed should be very high.
I would put this in the category "anyone who thinks they can value this may be made to look a fool either way" - probably up there with the likes of Ocada (that was always overpriced right - well no it wasn't) and that Carpet company that was always over valued for years and i can't remember the name of (that was always overvalued RIGHT? - yes it was but i am guessing everyone gave up shorting it well before the price crashed)
I have been watching £D4T4 from the sidelines while it has shot up from just below £2 to where it is now, wanting to buy but wanting to buy it cheaper which has never happened.
I was a bit worried about the CFO leaving as announced recently and about the high valuation but maybe I should have just bought and I would already be significantly into profit...
Ah well no panic... Will be interested to see what you think Paul
Also interested to hear your thoughts on Trifast (LON:TRI) (I am long TRI ) I feel they are a steady growing company held back a little by the slump in the car industry but a good quality company for the long term
PS I note that all tickers with a number in them do not work as a link so £D4T4 or £G4M doesn't work etc I have already highlighted this to Stockopedia...
My morning smallcap tweet: Trifast is holding the world together.
Trifast (LON:TRI), £D4T4
Trifast (TRI) guides FY underlying profit slightly ahead of management expectations. NIce strapline: "Holding the world together". You know whom to blame when WW3 starts.
D4T4 Solutions (D4T4) guides FY adj profit slightly ahead of market expectations
Seems a quiet day for small cap news. Noticed that MMGG Acquisitions have taken their notifiable position in perennial disappointer Gattaca (LON:GATC) above 11% and wondered if anyone had any insight as to the background here?
https://www.investegate.co.uk/gattaca-plc--gatc-/rns/standard-form-for-notification-of-major-holdings/201904180700075601W/
A quick google guests MMGG is a private recruitment business that has made acquisitions in the sector in the past (Morson Group in 2012) and given the strong rise in Gattaca (LON:GATC) over the past month (share price up c. 40%) wondered whether the view is that they’re in play or whether it’s just an investment holding.
Gus.
Henning Wehn is great. When I was in Hamburg last month I saw him on an advert on TV, I asked the German hotel receptionist is she knew who he was, she was completely baffled so I explained that he was a famous German comedian in the UK, almost as rare as hens' teeth.
Hmmm. A sense of humour?
https://www.1843magazine.com/dispatches/dispatches/let-me-explain-the-problem-with-german-humour
Not to mention schadenfreude....
Just don't mention the war :-)