Small Cap Value Report (Thu 18 July 2024) - KBT, NIOX, TM17, GNS, ALU, CRW, FRAS, DNLM, EVOK, RNO, IUG

Good morning from Paul & Graham!
That's us done for today - we've covered nearly everything on the long list today, with at least a brief comment, or a full section.
Renold (LON:RNO) update - re share options, etc. I spent a bit of time last night going through the accounts again for Renold (LON:RNO, in particular trying to unravel the accounting treatment of share options and employee benefit trust, dilution, etc that we were discussing yesterday. I've figured it out now. What they've done is buy shares in the open market for the employee benefit trust, to meet share option awards. I flagged this in the cashflow statement in yesterday's results, as a £4.5m cash outflow in FY 3/2024. There was nothing in FY 3/2023, however another £4.9m cash outflow called "Own shares purchased" in the FY 3/2022 cashflow statement. I would have just glanced at that, and thought good, they're doing buybacks for cancellation. But the shares are not cancelled, instead they are gifted to the employee benefit trust, which seems to be mainly share options reward schemes for Directors. That's £9.4m cash spent on buying shares to be given away (at nil cost) to Directors in the last 3 years. That seems excessive to me.
Note that the way this is accounted for, the cost completely by-passes the P&L. It took a while to track down the double entry, but it goes like this: credit cash on the balance sheet (ie cash going out, as double entry is the opposite of how we see it on our bank statements), and there where has the debit gone? It should be showing as either a cost (debit) on the P&L, or an asset on the balance sheet. Actually it's neither. The debit goes through reserves, and is shown in the reserves section of the balance sheet (below share capital) as "Other reserves". Nicely hidden! Therefore this entry lowers NAV, to reflect that RNO has spent £9.4m in cash on buying shares to give away to Directors.
The diluted EPS figure therefore seems a red herring, since the company apparently confirmed in the webinar last night (I missed it, due to being asleep in the sun) that there would not be any dilution. So I'm happy to go back to using the higher EPS figure that strips out dilution which should not happen.
Bottom line though, is by a roundabout route, a big chunk of Renold's cash has been syphoned off by management, to pay for a load of free shares for them. I'm not happy about this - the amount looks really excessive. That's cash which could have paid shareholders pleasant divis. We've had nothing over the last 3 years, whilst Directors filled their boots with £9.4m of free shares, bought by the company for them. For whose benefit is this company being run, and why did shareholders agree such a generous scheme?
To balance that, I remain very pleased & impressed with the turnaround in trading, and of course the share price, so probably shouldn't grumble too much.
I'll scrutinise employee benefit schemes more closely in the future at other companies, as it seems to me this is an effective way to hide substantial rewards for Directors in ways that wouldn't be obvious to a casual observer.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
A busy day!
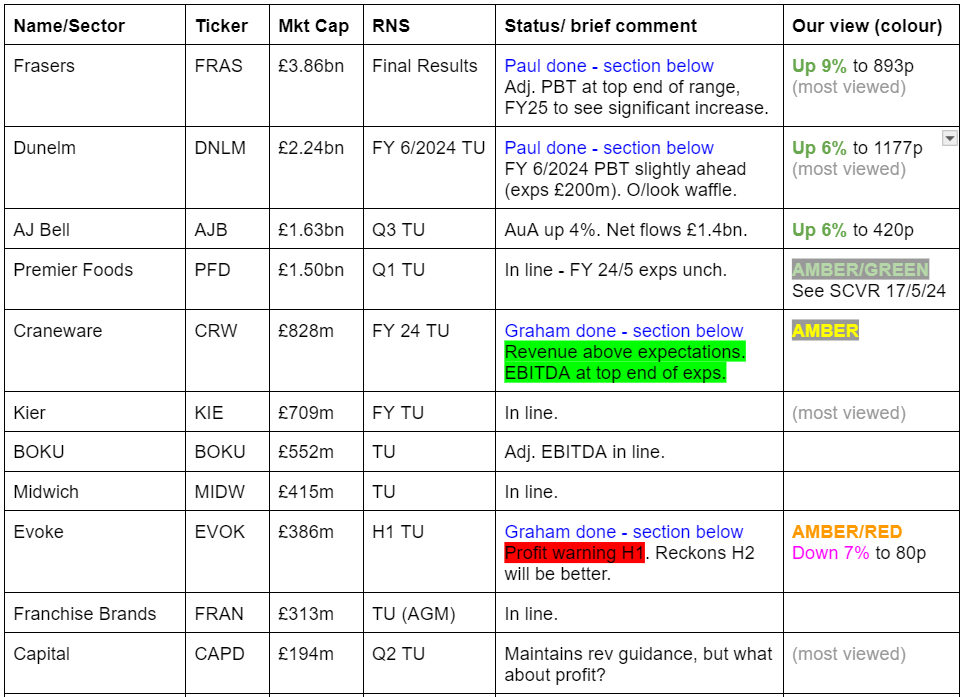
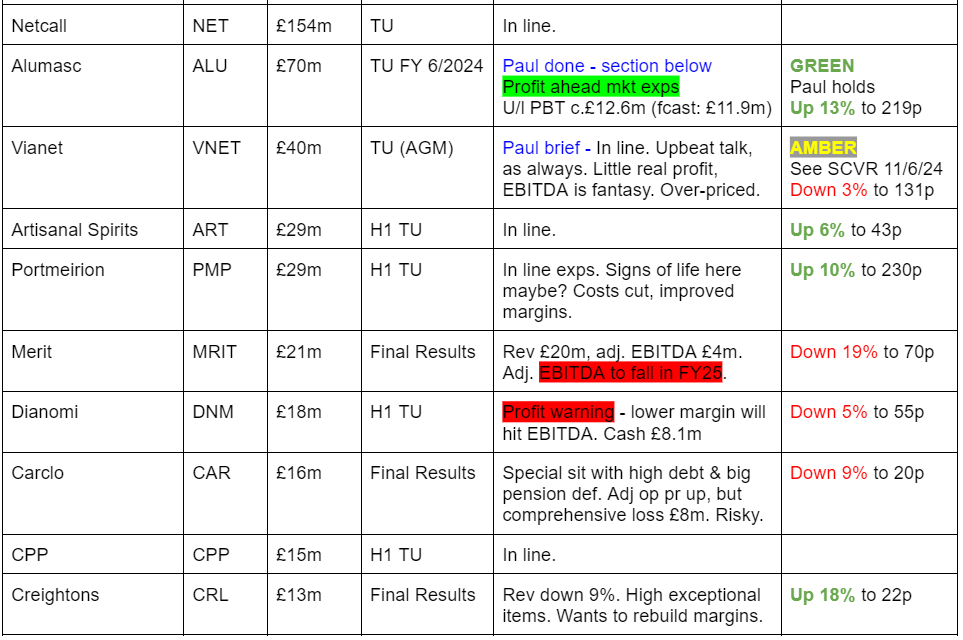
Other mid-morning movers (with news)
Intelligent Ultrasound (LON:IUG) - up 48% to 10.75p (£35m) - Proposed sale of clinical AI business for £40.5m - Paul - AMBER
This looks a sensible move. H1 trading update shows lower revenues, and almost out of cash. So selling its main (cash burning) division to GE Healthcare for a premium price (above its market cap) makes a lot of sense. Says it will consider returning some cash to shareholders. This will leave the listed company with its small NeedleTrainer product. Paul’s opinion - probably too small to be listed. I don’t see any further upside on the share price after today’s 48% rally, so won’t be getting involved. Probably a lucky escape for shareholders overall. It just shows though, that private buyers can sometimes see more value than the stock market, we’re seeing a lot of that at present with takeover deals. The stock market is the wrong place for small, cash burning, development companies.
Summaries
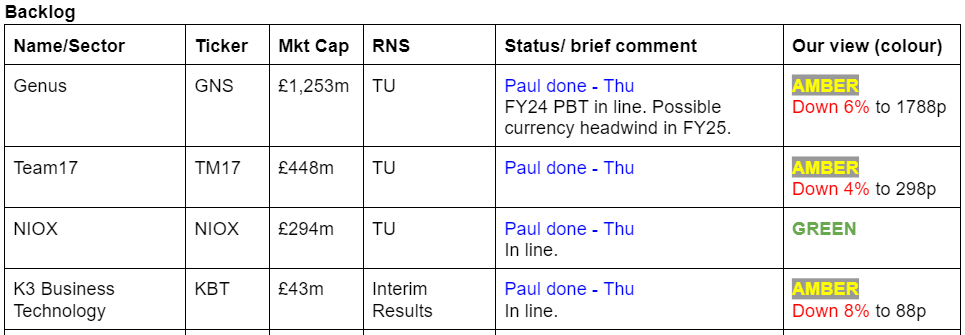
The first 4 items below are catch-up news from yesterday -
K3 Business Technology (LON:KBT) - down 8% to 88p y’day (£39m) - H1 Results - Paul - AMBER
Loss-making in H1, but it says seasonality is heavily H2-weighted each year from year end contract renewals, so still expects adj PBT to double to £1.6m for FY 12/2024. This strikes me as a declining business, propping up (small) profits through cost-cutting. With a tiny free float, and 5 large shareholders, I would expect this to de-list at some stage, hence probably best avoided. AMBER is probably being generous. Why get involved?
Niox (LON:NIOX) - unch 68p (£291m) - Trading Update - Paul - GREEN
I think this looks an interesting growth company, profitable, soundly financed, and its shares have been >3-bagger in the last 5 years, so I think there’s something good here. It's not cheap though, and the shareholder register is very interesting (see below).
Team17 (LON:TM17) - down 3% y’day to 300p (£438m) - Trading Update - Paul - AMBER
I last looked at this video games group a year ago, when it warned on profits. Since then, the share price has recovered very well, doubling from the lows. It now looks reasonably priced, on a reasonable PER, with a good balance sheet and cash pile. Trading is in line with expectations. Could be worth a look, if you invest in this sector, which I tend not to.
Genus (LON:GNS) - down 11% to 1698p y’day (£1.12bn) - Trading Update (y’day) - Paul - AMBER
In line trading for FY 6/2024, but it lowers FY 6/2025 profit expectations by 13.5%. I can’t see any attraction to this share based on these numbers. It looks expensive, has quite a highly indebted balance sheet, and performance is lacklustre. So why pay a premium PER for it? I’m being generous with AMBER.
Alumasc (LON:ALU) (Paul holds) - up 13% to 221p (£79m) - Trading Update (FY 6/2024) [ahead exps] - Paul - GREEN
The value seems obvious here, for a decent quality niche building products supplier, making good & improving margins. Today's update says it's traded ahead of expectations for FY 6/2024, and management sound confident there's more to come. Well worth you taking a closer look, I see potentially c.50% upside here, if we're patient, and we get paid generous divis whilst we wait.
Craneware (LON:CRW) - up 2% to £24.60 (£869m / $1,130m) - FY24 Trading Update - Graham - AMBER
An excellent full-year update from this healthcare software company, with revenue beating expectations. I’d like to take a more positive stance on this stock as I’m a big fan of the story and the management team, but it seems fully priced to me with the PER in excess of 30x and the price to sales ratio over 6x.
Frasers (LON:FRAS) - up 9% to 894p (£4.03bn) - FY 4/2024 Results - Paul - GREEN
Mike Ashley's sprawling retail empire, that he still owns 73% of, but is supposedly not involved in managing any more. Yeah, right! These numbers look great, and with a confident outlook and clear guidance too, sound balance sheet, good cashflows, and a PER of only about 9x, there's a lot to like here. It has to be GREEN.
Dunelm (LON:DNLM) - up 7% to 1,179p (£2.39bn) - Q4 & FY 6/2024 Trading Update - Paul - AMBER/GREEN
Homewares retailer ended the FY 6/2024 year with a pleasing surge, leading to it reporting today profit will be slightly ahead of expectations. I think it's an excellent business, and pays decent divis of almost 5%. With the share price looking up with events, I've moderated a little to a still positive AMBER/GREEN. Freight costs rising worries me. Although a consumer recovery gives potential upside. A stronger pound could also be a buying tailwind helping margins, after a time lag.
Evoke (LON:EVOK) - down 8% to 79.15 (£387m) - H1 2024 Trading Update - Graham holds - AMBER/RED
This remains a complex situation. Bondholders are relaxed, the share price has been stable, and management still insists that leverage is going to reduce by 2026. However, they have made precious little progress on that front so far, and H1 has been poor with adj. EBITDA up to £40m below target. But they leave FY25 expectations unchanged, and so shareholders can continue to dream of recovery.
Paul’s Section:
K3 Business Technology (LON:KBT)
Down 8% to 88p y’day (£39m) - H1 Results - Paul - AMBER
Provider of business-critical software solutions focused on fashion and apparel brands.
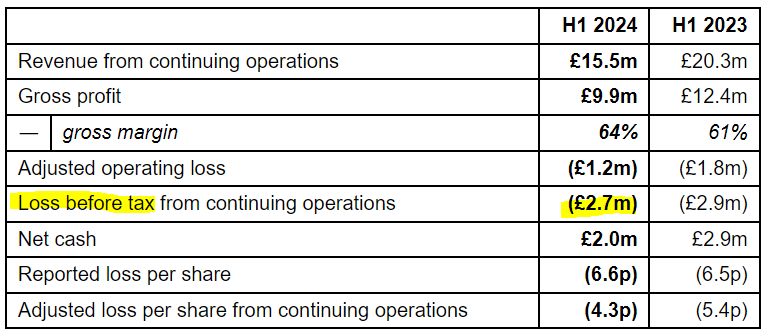
Poor H1 results here, with a marked fall in revenues, and a hefty loss -
Outlook - suggests we shouldn’t judge it on the seasonally softer H1 figures -
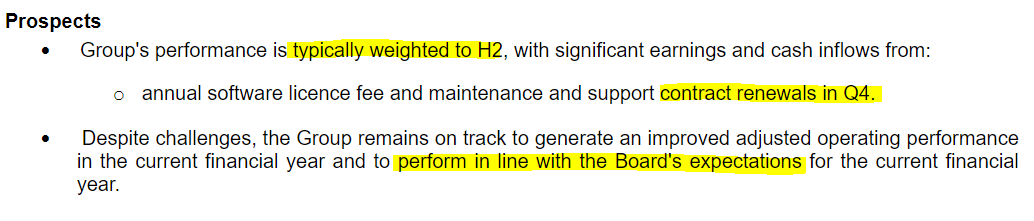
"The second half of the financial year is typically our stronger half, with significant cash inflows from software licence and maintenance and support contract renewals. Our priority is to deliver shareholder value while maintaining strong financial discipline. The Group remains on track to perform in line with our expectations for the current financial year."
Note the last divi was paid in 2018, so this seems a business that is managing decline, and note it’s incurring hefty restructuring costs of £2.1m last year, and £1.25m in H1 this year.
Broker update - Cavendish helps us out with some numbers.
It’s left FY 11/2024 adj PBT at 1.6m, double the previous year. To achieve that would require a very heavy H2 weighting - with the risk being contracts don’t get renewed as expected. Although in this type of business, I would expect them to know in advance if a customer was not intending to renew. It would be useful to see the client list, to find out if any are at risk of going bust - clearly a risk in the fashion sector.
EPS forecast is 3.1p, for a PER of 28.4x, which clearly looks too high.
Balance sheet - is weak. NAV at 31/5/2024 was £24.3m, but intangible assets are £26.3m, giving NTAV of negative £(2.0)m.
That’s not great, but it’s probably adequate for a software company, since it has negligible fixed assets and inventories. Plus customers tend to pay up-front. Put that together, and a weak balance sheet can actually work OK.
Paul’s opinion - distinctly lacklustre. I cannot see any reason to get involved here, it looks like a business in decline, keeping itself going through cost-cutting.
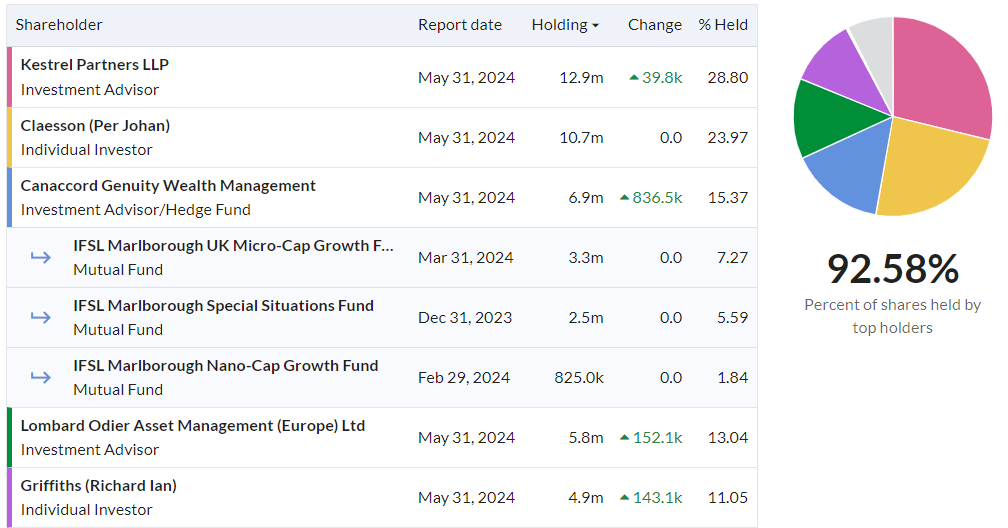
Look how concentrated the shareholder register is, below. So there’s absolutely no point in having a stock market listing, which is an unnecessary cost & hassle, and is probably harming the potential to do deals in the private market, but attributing a low market cap of only £39m. So I would be very worried that the big 5 shareholders might decide to take it private - at an unknown price.
For those reasons, I’m tempted to raise a warning flag here.
Niox (LON:NIOX)
Unch 68p (£291m) - Trading Update - Paul - GREEN
Oxford, UK - 17 July 2024: NIOX Group plc (AIM: NIOX), a company engaged in the design, development and commercialisation of medical devices for asthma diagnosis and management, today announces a trading update for the six months ended 30 June 2024 ("H1 2024" prior period "H1 2023").
“Continued strong performance driven by Clinical Business”
This seems to be an in line update, so not price sensitive -
“Ian Johnson, NIOX's Executive Chairman, said: "I am pleased to report continued growth in revenues and profits in the first half of the current financial year, during which the group has traded in line with management expectations. Our core Clinical business, which continues to benefit from a high degree of recurring revenues, grew at 14% in constant currency terms.”
H1 revenues up 12% to £21m
Adj EBITDA up 14.5% to £7.1m
Forecast - Singer helps us with an update note. It leaves FY 12/2024 unchanged at £13.7m adj EBITDA = £10.7m adj PBT = 2.4p adj EPS (PER 28.3x)
That’s showing a nice uptrend, from 1.4p EPS in 2022, and 1.9p in 2023, to forecast 2.4p in 2024, then 2.9p and 3.5p in 2025 & 2026.
So this looks an interesting growth company, which was the same conclusion I reached when viewing it GREEN on 18/7/2023.
Balance sheet at end Dec 2023 looks very good to me, with ample capital, including £20m net cash. So I see little to no dilution or solvency risk. This healthy cash position also enables it to pay a divi yield of about 1.8%, twice covered. That’s modest because the shares are rated on a high PER.
Paul’s opinion - it’s obviously not a value share, on a PER of 28x, but I’m impressed by the growth track record, and high gross margin - thus providing leveraged upside as sales grow.
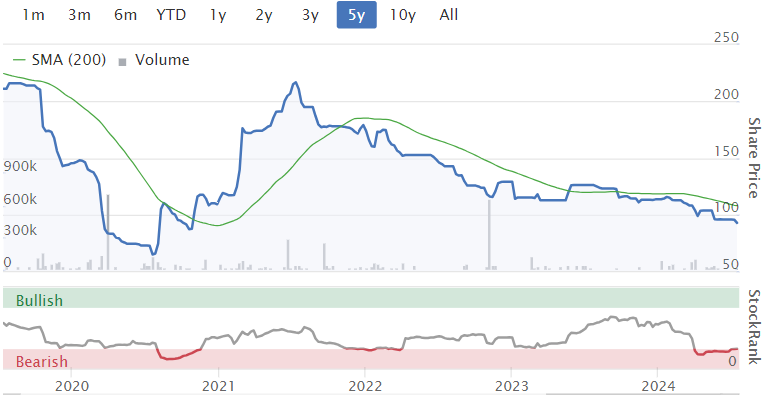
I know nothing about life sciences businesses, so cannot offer any view at all on the products, competition, etc, it’s your job to research all of that. My view is purely on the numbers, and I think this looks an interesting growth company, profitable, soundly financed, and its shares have been >3-bagger in the last 5 years, so I think there’s something good here. If you do have a deeper dig into things, then do let me know what you think!
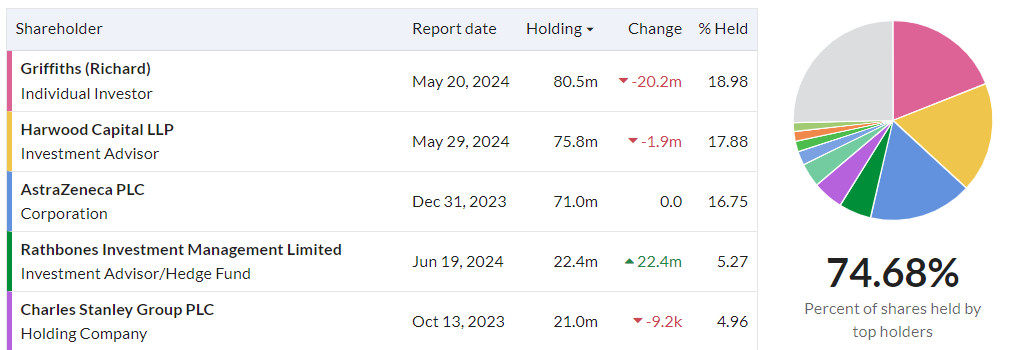
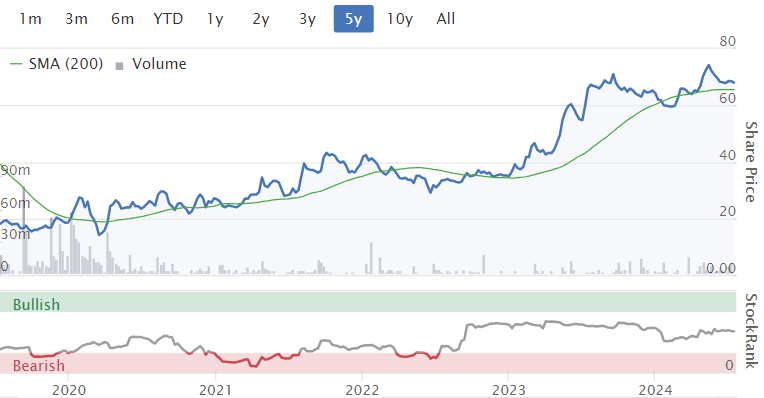
Another way of looking at it, is to admire the top 3 shareholders, who arguably have done the due diligence for us already - although note the two largest have reduced their positions this year - picked up by Rathbones -
Team17 (LON:TM17)
Down 3% y’day to 300p (£438m) - Trading Update - Paul - AMBER
Team17, a leading global independent ("Indie") games label developer and publisher of premium video games and apps, provides the following trading update for the six months ended 30 June 2024 ("H1 2024").
Short and sweet! -
“The Group has traded in line with the Board's expectations during H1 2024 and management remains confident of delivering full year results in line with market expectations.
The Group's interim results will be announced in September, with full details to follow nearer the time.”
We’ve not looked at TM17 since its profit warning on 24/11/2023, when I wasn’t keen, due to complicated accounts and lack of broker notes.
However since then, shares have recovered in a steady trajectory, to double from the Dec 2023 low c.150p to c.300p now. It’s actually quite surprising how many smaller company shares have recovered well from profit warnings in the last year, including this one.
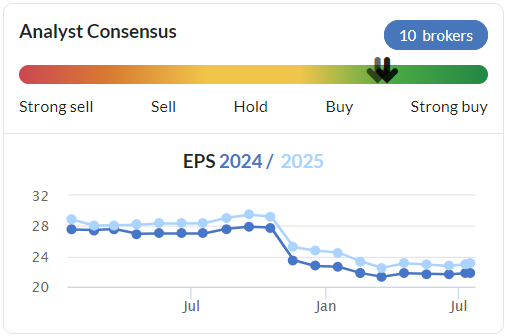
Forecasts for this year and next seem to have stabilised -
Looking back at its FY 12/2023 results, they showed adj PBT down 39% to a still respectable £28.7m, equivalent to 17.5p adj basic EPS (a current PER of 17.1x). Although the adjustments were large, making a statutory loss of £(1.1)m, due to a £32m impairment of intangible assets.
Balance sheet at Dec 2023 was healthy, with £42.8m net cash, and c.£37m NTAV.
It’s expected to do 21.9p EPS this year, so a PER of 13.7x seems reasonable.
Paul’s opinion - based on the reasonable valuation, and in line trading, this share looks worthy of further investigation, although personally I don’t get involved in the video games sector. I’m happy to sit on the fence at AMBER, but with a slight leaning towards a positive view, because trading has stabilised, and the balance sheet is robust, which has been reflected in a good recovery in share price. TM17 doesn’t pay divis, so seems to be growing by acquisition instead.
Genus (LON:GNS)
Down 11% to 1698p y’day (£1.12bn) - Trading Update (y’day) - Paul - AMBER
Genus (LSE: GNS), a leading global animal genetics company, publishes the following unaudited trading update for its fiscal year ended 30 June 2024 ("FY24").
An in line update yesterday for FY 6/2024 -
“Management expects Group FY24 adjusted profit before tax in actual currency to be in line with market expectations of between £58m and £61m.
Group Net Debt to EBITDA is expected to be circa 2.0x at year-end supported by strong cash conversion in the year.”
Panmure Liberum helpfully issued an update, it has 68.2p fully diluted EPS for FY 6/2024, a PER of a hefty 24.9x.
Forecast reductions - Panmure Liberum reduces FY 6/2025 forecast by 13.5% to 77.4p, due to weak demand and stronger sterling creating a headwind. So the PER is 21.9x on this revised forecast.
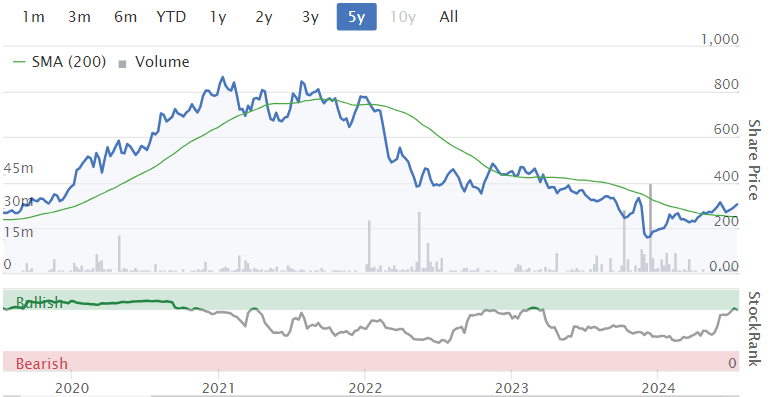
Paul’s opinion - I can’t see any attraction to this share based on these numbers. It looks expensive, has quite a highly indebted balance sheet, and performance is lacklustre. So why pay a premium PER for it? I’m being generous with AMBER. Looks like the downward trend in share price is justified, and could continue.
Alumasc (LON:ALU) (Paul holds)
Up 13% to 221p (£79m) - Trading Update (FY 6/2024) [ahead exps] - Paul - GREEN
Alumasc, the sustainable building products, systems and solutions group, provides a trading update for the year ended 30 June 2024, ahead of publishing its FY24 results on 3 September 2024.
Strong performance, with profit ahead of market expectations
Readers here flagged this share to me in Feb 2024, suggesting it was good and I should review it. Sure enough, my review of H1 results here on 9/2/2024 was very positive, GREEN at 179p. Given my positive view, I took up the offer of a briefing call with management, to better understand the business - which left me with a positive impression. More recently I picked up a small position in ALU shares personally, which we have to disclose here when writing about companies we hold personally, because it can create bias in what we write - although we try very hard to be objective with everything, whether we own it or not.
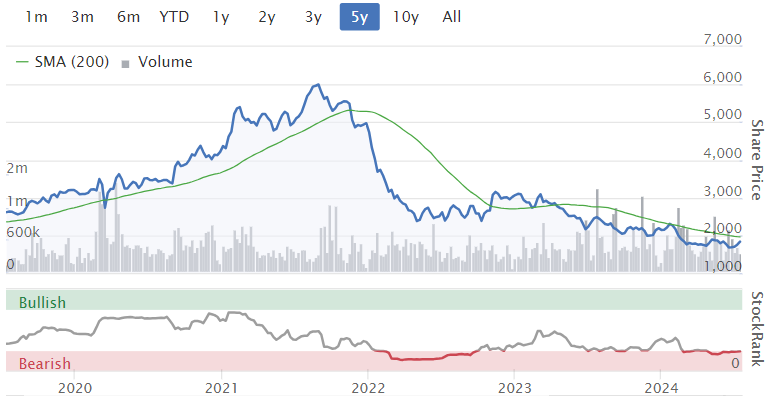
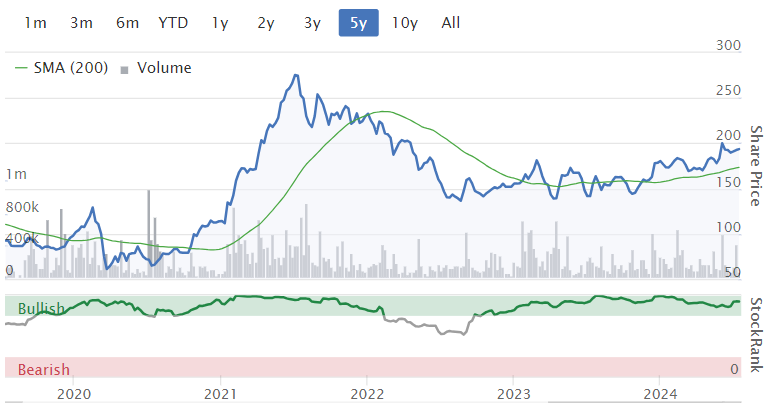
ALU shares seem to have oscillated in a sideways trend for the last 20 years, but that overlooks its generous divis. So the total shareholder return has been OK -
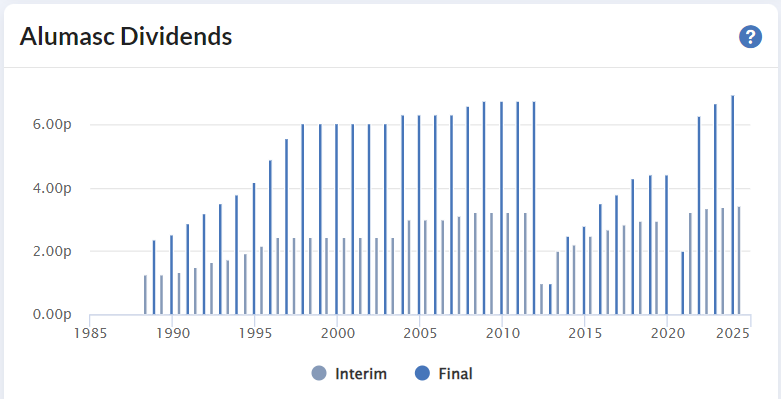
Margins have improved in recent years, and I think this is a much higher quality, niche products business than the market gives it credit for. So there’s a re-rating opportunity here, in my view. Stockopedia shows the forward PER as 7.3x, which seems too low to me. Surely a rating of 10-12x would be more appropriate, given its resilience during the tough macro in recent years?
It’s priced like a low quality, low margin building supplies company, but the quality scores are actually excellent -
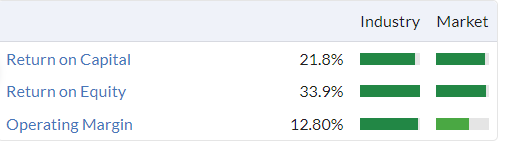
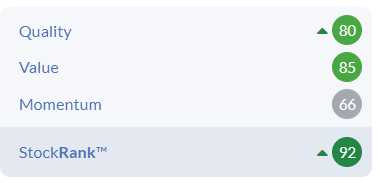
StockRank is high, and the momentum score could rise, as more investors spot the attractive investing case here, and shares re-rate, possibly? I have about 300p+ in mind as my price target. Although from watching the shares, I suspect there might be an intermittent seller, so possibly an overhang, as with lots of small and mid caps - look at the series of secondary placings we’ve seen lately, eg at Gulf Marine Services (LON:GMS) (I hold), Trustpilot (LON:TRST), and something else. Still, for the patient investor, I think anomalies like that create opportunities, especially when you’re paid nice divis whilst you wait for the market in the shares to normalise & overhangs clear.
ALU also seems to have done some good acquisitions over the years.
Management say that ALU’s out-performance has been helped by new products selling well.
Today we get a lovely ahead of expectations update, with nice clear guidance, this is for FY 6/2024 -
“Underlying profit before tax ('UPBT')1 now expected to be at least £12.6m, ahead of current market forecasts2 and the prior year (£11.2m)
2 The Board understands current market UPBT forecasts for the year ending 30 June 2024 to be in the range of £11.7m to £12.1m, with a consensus of £11.9m.
That’s a c.6% beat against consensus.
Outlook comments - indicate further margin improvements are coming -
“Over the medium term, the Board believes that the Group can generate significant further value, which is reflected in its targets to generate organic revenue growth ahead of underlying UK construction markets and achieve operating margins of 15-20%.
FY24 represents a period of strong delivery against these objectives and the Group would expect to make further progress as market conditions improve.”
Net bank borrowings were a modest £7m at year end, only 0.5x EBITDA.
Latest acquisition of ARP has “performed very well”, reinforcing my view that management know what they’re doing with their acquisitions strategy.
Paul’s opinion - there’s plenty more detail in the update, which I don’t need to go into here.
Check out an update note from Cavendish this morning, forecasting 26.1p adj EPS for FY 12/2024, rising to 28.0p next year. With the building sector set for recovery in calendar 2025 onwards, there could be upside on these forecasts. Management sound confident.
Concluding then, I remain of the view that ALU seems an overlooked and under-priced, good quality business. Hence I’m happy to remain at GREEN.
Dunelm (LON:DNLM)
Up 7% to 1,179p (£2.39bn) - Q4 & FY 6/2024 Trading Update - Paul - AMBER/GREEN
Things are going well at this homewares retailer too.
This all sounds good -
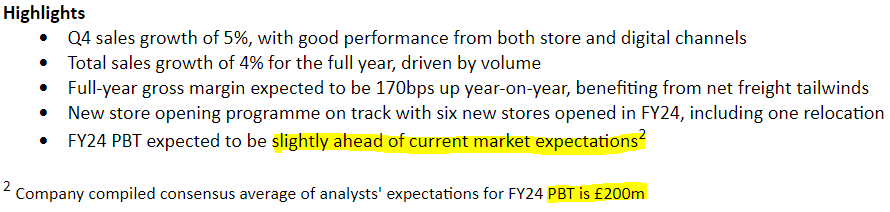
Broker notes - nothing available. Stockopedia has consensus at 73.3p, so I’m guessing slightly ahead could mean 75p-ish?
That gives us a PER of 15.7x, which I’m struggling to justify having just looked at FRAS on 9.3x.
Outlook - I’m puzzled it doesn’t mention increasing freight costs -
"Going into FY25, we have a significant opportunity ahead of us. We are finding quality sites for new stores, and are increasingly confident in our smaller format stores. We are also continuing to invest in both our digital offer and wider operations to support further market share gains. However, we will need to maintain strong operational grip given ongoing wage inflation. Notwithstanding the continuing uncertainty in our markets, we're both excited and confident in our plans."
Paul’s opinion - I can see that a consumer recovery is likely, and that gives retailers an operationally geared upside. However the supply chain issues which are re-emerging, especially freight costs, could turn a tailwind into a headwind in the new financial year, who knows?
You do get a yield of close to 5% at Dunelm. It has very high quality scores, and is undoubtedly an excellent business. Balance sheet is adequate, with a small net cash position.
Overall, I think I should moderate to AMBER/GREEN (from green) because the share price looks up with events for now, but I still really like Dunelm as a proven business, resilient through the pandemic. Also I mystery shopped it for curtain poles & curtains, and found the products excellent quality for the price!
A strengthening pound is good for retailers' margins, after a time lag.
Frasers (LON:FRAS)
Up 9% to 894p (£4.03bn) - FY 4/2024 Results - Paul - GREEN
The sprawling sportswear & apparel group.
I’m not saying anything -
“ Profitable growth
· APBT (1) of £544.8m (+13.1%), at the top end of our guidance range (£500-£550m).
· Adjusted EPS (1) of 95.8p (+33.6%).
· Continued strong profitable growth - FY25 APBT expected to be £575m-£625m.”
Retail revenue was £5.35bn, so that’s a healthy 10.2% adj PBT margin.
PER is only 9.3x adj EPS of 95.8p.
Adjustments look reasonable, and are not excessive.
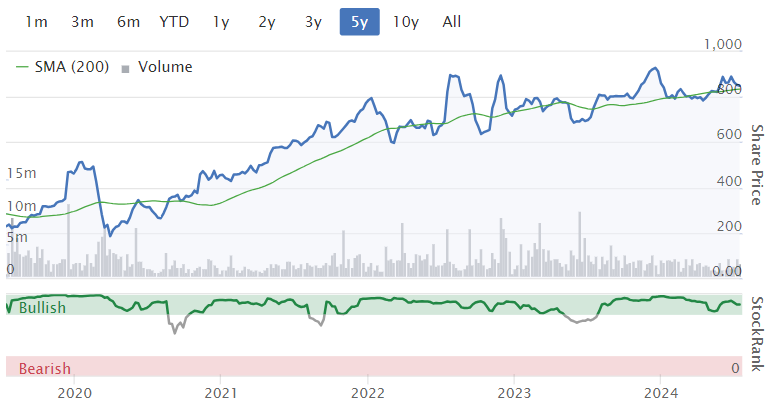
Share buybacks - note that there is an ongoing reduction in the number of shares in issue, down from 531m in 2018 to 450m today -
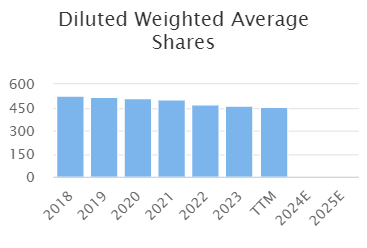
However, it doesn’t pay dividends.
Outlook - there’s so much going on at FRAS, but it seems to be working -
“Our successful Elevation Strategy is powering our strong financial performance, with strategic brand relationships giving us better access to product across the Frasers Group. As we move into FY25 and the Summer of Sport, we remain confident that our strategy will drive continued strong performance, and we expect significant synergies from both our automation programme and the integration of acquisitions. We continue to build a diverse business within retail, both in the UK and internationally, and also within financial services and property, that can deliver sustainable multi-year profitable growth. For FY25, we expect to achieve another strong increase in APBT in the range £575m-£625m.”
Cashflow - it generated c.£483m in cash (after tax, leases, and finance costs). This was spent mainly on capex (£211m), net purchases of listed shares (£249m), and buying its own shares (£126m). There were also £109m cash inflows relating to equity derivatives. So you can see this is not a vanilla retailer, it does a lot of wheeling & dealing too - where it has a patchy track record (eg losses on Debenhams, and Matches).
Balance sheet - NAV is £1,873m, with intangible assets being only £42m, so NTAV looks robust at £1,831m, which supports 45% of the market cap.
Net debt is not excessive at all, at £448m (includes securitisation borrowings, but not leases).
Paul’s opinion - just a quick skim of the numbers, and I have to say this does look a quirky, but interesting share!
It’s difficult to understand why the PER is only about 9x, so there could be upside from a re-rating at some point.
I always have a nagging feeling that FRAS could end up making some giant cock-up at some point, since its strategy has at times looked quite reckless - eg taking stakes in numerous other retailers, and sometimes with obviously not enough due diligence, eg Matches, where it was quickly put into administration after being bought. Mind you, it is encouraging that failure was recognised quickly, and acted upon, to stem the losses. I think its 20% stake in Asos could be problematic, although taking out a large online competitor has obvious attractions. It also has a sizeable stake in Boohoo, and others. The threat from Shein and other Chinese companies can't be ignored.
That said, its balance sheet is strong enough to be able to absorb mistakes.
I have to say, it can’t be anything other than GREEN, based on these good numbers, and confident outlook.
Graham’s Section:
Craneware (LON:CRW)
Up 2% to £24.60 (£869m / $1,130m) - FY24 Trading Update - Graham - AMBER
It’s an impressive full-year trading update from this provider of software to the US healthcare industry.
Key points:
Revenue up 8% to over $188m, above the upper end of market expectations.
Adj. EBITDA at least $58m, up 6%, towards the top end of market expectations.
Annualised recurring revenue is up by about 2% to $172m.
Net cash is still around zero (bank debt offsetting cash reserves). $13m was spent on dividends and $3m on share purchases, including shares bought for employees.
Outlook: says the company is well positioned for FY25:
The strong sales performance during the year demonstrates the strength of the Trisus platform, increasing partner success and the unique position the Group holds in its market.
The breadth of solutions the Craneware Group can provide though its Trisus platform, combined with the new market opportunities, accelerated innovation and exploration of new AI-based applications that will result from the recently announced alliance with Microsoft, give the Board confidence in the Group's ability to provide the insights its customers need to deliver greater value healthcare to their communities.
Alliance with Microsoft
We didn’t cover it at the time, but earlier this month Craneware announced a deepening of its relationship with Microsoft. This included “co-innovation with Microsoft's AI experts to accelerate the application of AI enhancements to existing Trisus offerings and the exploration of new AI-based applications”
Craneware’s Trisus will be available on Microsoft’s cloud software shop, the Azure Marketplace.
Graham’s view
I interviewed company management in March, publishing my notes here afterwards.
Unfortunately, I’ve not been bullish enough on Craneware stock:
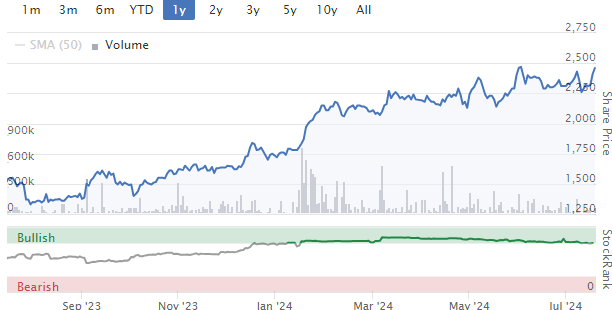
My stumbling block has been the high rating vs. modest revenue growth:
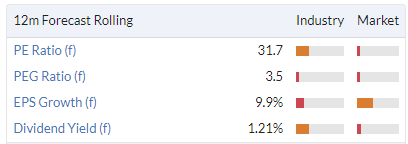
Again today we have 8% revenue growth, ahead of expectations and a perfectly good growth rate for a large company, but not what I would consider to be “rapid” growth.
In March, I suggested that sustained double-digit growth could support Craneware’s valuation and generate upside for investors.
Perhaps the partnership with Microsoft will enable faster growth?
Besides earnings multiples, I’ve also tried using US-style price to sales or price to ARR multiples.
After recent share price gains, the price to trailing ARR multiple for Craneware is now about 6.5x. This could still be considered normal by US valuations standards, but US valuation standards are of course on a different level compared to the UK.
For further context, I should point out that Microsoft (MSFT), one of the Magnificent 7 stocks and Craneware’s partner, is currently trading at a price to sales multiple of 14x, with the following valuation multiples. It seems overpriced to me:
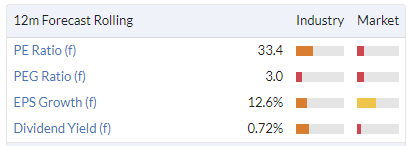
Overall, I still have a very positive impression of Craneware as a company, and its management, and I think its prospects are positive in the short and long term. Given the valuation, I’ll stick with my neutral stance.
Evoke (LON:EVOK)
Down 8% to 79.15 (£387m) - H1 2024 Trading Update - Graham - AMBER/RED
At the time of writing, Graham has a long position in Evoke.
Unfortunately, this is a profit warning from the company formerly known as 888.
This stock has a long history, please refer to Paul’s notes in April and my notes in March if you’d like to get up to speed.
With an almost completely new management team, and a new name, the company is trying to see itself as a new entity, and approach its business in new ways. But of course it still has to tackle the legacy of debt from the prior management team.
Some key points from today’s H1 update:
Q2 revenue £431m, “broadly stable” but below expectations..
Small gains in revenue from UK online and International divisions, but UK retail (William Hill) revenue down 8%.
Solutions to the decline in UK retail? Various initiatives planned, such as an improved self-service betting terminal product, along with a change of leadership.
Continuing with the financial news:
Adj. EBITDA margin 13-14%. The update doesn’t mention that this is down from 17.7% in H1 last year.
Cash £116m, total liquidity is “nearly” £300m, a little lower but not much change compared to last year.
Strategy: they have “fundamentally re-organised the Group’s operating model to streamline decision making and increase effectiveness”. £30m of cost efficiencies will be delivered by the end of this year.
Outlook: unfortunately the cost savings aren’t in time to help H1 adj. EBITDA, which is £35-40m behind plan.
By my sums, H1 adj. EBITDA is in the region of £110m-£120m (H1 last year: £156m).
The company insists that H2 will be much better. Marketing costs in H2 will be lower by up to £40m, revenue growth is expected to be 5-9% (in line with medium-term guidance), and the next round of cost efficiencies will be delivered.
So the adj. EBITDA margin is forecast to improve back to 21% in H2.
Importantly there is also no change to the company’s view of FY25 expectations.
And most critically, they are still targeting a leverage multiple of less than 3.5x by 2026. But is that realistic? I’m not sure.
In H1 last year, management guided that leverage would be “slightly below 5x” at year-end, i.e. by Dec 2023.
The actual leverage multiple at the end of the year was 5.6x, calculated on a net debt load of £1.7 billion. So they didn’t hit their forecast, and weren’t all that close. There was no improvement in the leverage multiple from Dec 2022 to Dec 2023.
CEO’s comment uses our favourite phrase “profitable growth” a couple of times.
He emphasises that the business is completely changing how it is run:
"We are focused on mid and long-term profitable growth and value creation and during the first half we have made bold, decisive changes to improve almost every area of the business. We are undertaking a complete reset and transformation of the business, and the scale of change is significant, but necessary. This transformation will take time but will enhance operational efficiency, leading to a bigger, more profitable and more cash generative business in the future…
Graham’s view
As I’ve noted above, I’m not sure if it’s realistic that the company might achieve a leverage multiple of 3.5x by the end of 2026.
Attempts to reduce the multiple haven’t worked thus far. But they do make a strong argument that H2 will be better. I guess it’s time for them to prove it now with a strong end to the year.
The annual interest charge on bank loans and bonds last year was £176m. With adj. EBITDA of over £300m, they were able to make those payments, but it wasn’t comfortable. After all charges, including large non-cash charges such as amortisation, they made a hefty loss for the year.
This year, I’m expecting another loss but I’m hopeful that the cash performance might be a little better.
I’ll be keeping an eye out again for excessive costs being thrown into the “exceptional” category, e.g. nearly £50m of “integration and transformation costs” were exceptional last year - I want this number to be very small in 2024!
Overall, this stock remains a can of worms - maybe we need a special colour for this category? I’ll stick with AMBER/RED. It’s a special situation where the bondholders and the banks are taking most of the risk, while the equity is just an option on the company being able to pay off its debts.
If, somehow, we got a leverage multiple of 3.5x, without any equity dilution, I’d be delighted and would expect an enormous re-rating of the equity. This is still a large business with well-known brands, and whose revenues should approach £2 billion in the years ahead. Good management could make a big difference and squeeze decent profits out of that sort of turnover. And we know that there has been takeover interest from the industry in the recent past.
For now, it’s a risky bet and one that I would think is inappropriate for most investors. Stale bulls like myself will hold on and go down with the ship if that’s what it comes to, but there is probably little reason for others to want to get involved, at least not without a great deal of conviction in the recovery potential.
Stockopedia’s algorithm is surprisingly risk tolerant, calling this a “Super Stock”. But I think there will be a big gap between the consensus earnings estimates (which are based on adjusted numbers) and the actual outturn.
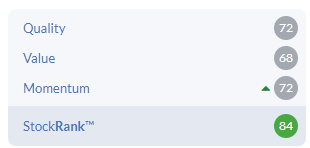
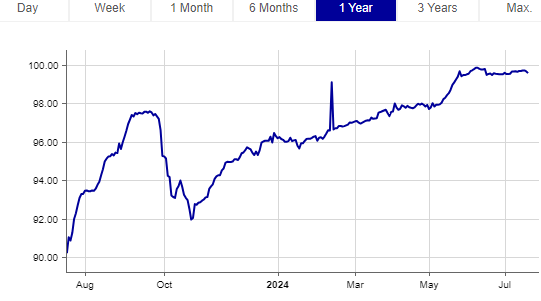
The share price has been stable:
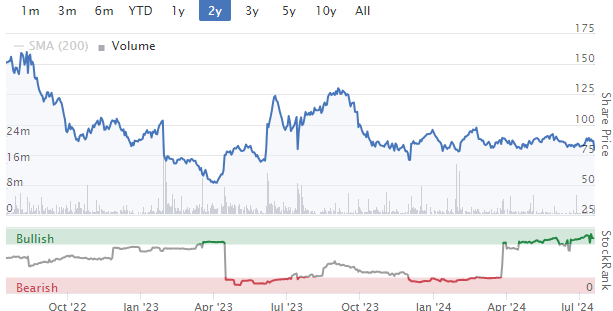
And bondholders remain relaxed:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
RNS on Renold (LON:RNO) today confirms the extent of options going to management; helped themselves to another ~1.6M share options....
Following the grant of the Awards, the total options over ordinary shares in the Company held by Robert Purcell and Jim Haughey pursuant to the Plan and other Company share option plans are as follows:
Director
Options held prior to the Awards
Options granted under the Awards
Total options held
Robert Purcell
11,206,443
1,277,366
12,483,809
Jim Haughey
3,023,456
412,520
3,435,976
Renold (LON:RNO) - they do state that these options will only vest on 26 July 2027, subject to certain performance conditions and the terms of the Plan (summarised on P36 of the 2013 annual report). This suggests that minimum vesting is contingent on 30% CAGR of eps and max only at 50% CAGR of eps. That's quite a target, roughly speaking if the SP were to go up in tandem with these raises, then for the CEO to get nearly 1.3M shares after this nearly 40 month period, the SP would have risen from 37.5p (price as of 1 April 2024) by a factor of 1.5^(40/12) ie to 145p. So CEO gets nearly £1.9m in nil-cost shares, while shareholders see a £213m increase in the value of their company. On this basis the CEO is getting a little under 1% of the value created by him and his employees and the CFO a third of that. I don't know what's normal, but that doesn't sound too bad to me - assuming I've got my sums right and not missed something (such as other overlapping awards). Anyone?
I think Paul's concern about the £9.3m spent over three years on purchasing shares for the EBT is very valid, and particularly its obfuscation in the company report, but perhaps more critical are the performance metrics according to which shares become vested, which to my mind look a bit more reasonable.
Jim
I’m not convinced the performance targets are still at those old 2013 levels
If you look at the RNS announcements subsequently, I think they drifted down to easier levels with the “entry”/“maximum” achievement targets going down to
2014 award - reduced to 20%/30% EPS CAGR
2015 award - reduced further to 10%/15%
2016/2017/2018 - again 10%/15% but half award now linked to TSR targets
2019 onwards - disclosure starts to become less clear from this point on but the wording of the option grant RNS seems focused only on EPS.
During the pandemic, I think some special one-off targets were introduced that year.
EDIT
The last two Annual Reports show:
2022 AR (presumably 2019 option grant) - 10% eps growth achieved, with 5% growth being the entry threshold, and 10% being MAXIMUM. So the vague 2019 grant RNS completely hid the fact the targets had been softened once again!
2023 AR - special pandemic targets - surprise, surprise achieved in full.
In fairness, lots of the awards in previous years seem to have lapsed with no payout, but it feels like the awards have more recently been achieved by virtue of softening the targets rather than stunning outperformance.
We need the 2024 annual report I think to know what the 2021 grant targets were. My hunch is they might repeat the 2019 year softer 5% entry/10% maximum. If so, that seems a pretty low bar.
Thank you M48 - you're quite right. It seems that in spite of the RNS referencing the Company's 2013 Performance Share Plan, which on p38 of the 2013 annual report highlights a 30%/50% target, they have subsequently varied that target. The recent 2024 annual report now confirms a 5%/20% range for the just ended 2021 scheme, which fully vested. I cant help feeling that if the target varies from the 2013 performance share plan referenced in the RNS they should have made that plain, so that investors have the information needed to vote on the directors renumeration at the AGM. Meantime my revised working assumption is that the 20% max target will carry over into the new scheme such that the SP will have to exceed an altogether less challenging 69p target in order for the lastest batch of nil-cost performance shares to fully vest. If the SP were to hit 69p by July 2027 (and Id hope for better by then) then the CEO would stand to get £880k, while shareholders would have seen a 50m increase in value since 1 April 2024 or a £22m uplift from today. So perhaps just about ok. I think the real problem is that needlessly purchasing so many shares for the scheme ominously suggests excessive payouts to come (as Paul assumes in his £9.4m over 3 years calculation), when instead they could have purchased the majority of them for cancellation and still been able to support reasonable payouts for directors.
Problem is that the total lack of any fair disclosure regarding the remaining outstanding options means it’s impossible to know whether the CEO is in line to continue getting bumper rewards.
As a cynic though, given the option awards have “maxed out” in each of the last 3 years, it’s hard to think the targets set are that stretching and it’s sure a whole lot easier to hit any target when the earnings start from a low beaten down base.
I slightly leapt to Renold (LON:RNO’s defence when Paul was exposing the somewhat hidden cost of the options in the accounting (even though the accounting was not wrong in my view). With hindsight I wish I hadn’t, I think there’s plenty not to like about how generous these options are.
Perhaps, in effect, the most onerous requirement to be met for the Renold (LON:RNO) options to vest is that the CEO and FD are still in post on the vesting date?
"for the CEO to get nearly 1.3M shares after this nearly 40 month period, the SP would have risen from 37.5p (price as of 1 April 2024) by a factor of 1.5^(40/12) ie to 145p."
Is this right??
Renold - Good points from Paul. Having noted the substantial payment (via shares) into the employee benefits trust, one wonders if the pension scheme trustees are asleep, possibly the regulator as well. The priority should be to pay off significant amounts of the deficit with a view to insuring the scheme as the end-game.
Totally agree. Company has been doing well of late, so they should sort out the pension deficit while they can. Have done well holding this share but as the recent fall triggered my stop loss I’m currently out of this share bit on the fence about buying back in when you take into account the pension deficit and share options
You guys rock ! Great report - timely, detailed, concise ... hard to ask for more.
Work on Renold (LON:RNO), hats off
Capital (LON:CAPD) as noted in the summary above. Looks like they are going to keep us waiting until Aug 14th to find out about profit!
A big thanks Paul & Graham for the excellent and consistent output.
Congratulations, Paul on your delving into Renold. (Lon;RNO) I'm a reasonably good long-term investor, but could never manage that type of scrutiny. I'm too ignorant. So the laymen among us are both interested and very grateful.
My head swims with the complexities around the incentives for the directors, and made more complex by the support for Renold given by some viewers. i struggle to understand most of it.
But i would say this. If a company doesn't make these matters startling clear to laymen like me, then, whatever the rights or the wrongs, this is always a massive Heads Up.
Renold (LON:RNO)
Bottom line though, is by a roundabout route, a big chunk of Renold's cash has been syphoned off by management, to pay for a load of free shares for them. I'm not happy about this - the amount looks really excessive. That's cash which could have paid shareholders pleasant divis. We've had nothing over the last 3 years, whilst Directors filled their boots with £9.4m of free shares, bought by the company for them. For whose benefit is this company being run, and why did shareholders agree such a generous scheme?
Is the obvious solution here not simply to treat the earnings as lower by this higher amount of shares - seems odd to give them credit for the contrived pretty obvious fake buyack personally that cover the real dilution taking place - each to their own though - as long as its out in the open that its clealry smoke and mirrors and that the freebies are real then hopefuylly everyone happy.
To be fair to some company directors - where options are issues that are contingent on shares doubling in price or earnings doubling and thats laid out in advance - not convinced that is the case here though
There is an interesting note in the 2022 annual report that says teh following:-
Outstanding commitments to issue new shares under all share plans operated by the Company are subject to
a maximum of 10% of the Company’s issued share capital in any ten-yearperiod.
That would probably put my mind at rest if it is really 1% dilution per year - odly that note seems to have vanished from 2023 annual report .
So not sure what dilution is here are they sticking to less than 10% here ? if they are this might be then reward of 10 years effort all at once.
No opionion personally here other that its an obvious anoyance unless it really is kinda limited to 1% pa just with 10 year being taken in quick order?
The 10% dilution limit over 10 years is consistent with Investment Association guidance. it applies to newly issued shares - not to shares purchased by an EBT.
RNO - Good detective work Paul and thankyou for that as I had completely missed it. Must say it rather changes my view of the management. I don't like it but I would have been happier if they had been more transparent. One of my big no no s.
Hi Paul, re Frasers (LON:FRAS) ; I'm cool with companies using the descriptor 'profitable growth' ; on the one condition that they also use the other 3 boxes in the 2x2 when appropriate ; profitable decline/unprofitable growth and with even more honesty unprofitable decline.. :)
Maybe we just need a ban on the word growth. Since turnover is vanity, profit sanity cash-king etc
Hi Paul
Thanks for the deep look into Renold (LON:RNO) share options. I no longer hold as the market seems very unimpressed by their well disguised self generosity. Small caps have to be careful not to lose PI confidence. I think this drop has further to go. 50p or 46p maybe? Long term the numbers will tell but short term the voting machine looks to be turning negative.
Agreed Revs8 and thanks also to Paul for the deep dig. I've sold my positions in full banking a healthy profit (which I am very grateful for). I have no problem with Directors being well rewarded for success, but they should be completely transparent, and in this case I don't think they have.
I'd like to see some clarification from the Company, acknowledging they f***ed this up, as well as some forward guidance!
Thanks for that work and info on Renold (LON:RNO) Paul. Very interesting but annoyed to see extent of directors' greed.
That said I note I got in here at 21.7p when your target was 30p - and you subsequently wrote that you were happy to hold on when price rose to 33p. So this is yet another case of Stocko more than paying for itself - thank you very much indeed.
Renold (LON:RNO)
Paul, I am not sure if you saw my reply to Sharewallah yesterday, but one point on Renold is that I think you do need to look at the diluted eps of 6.9p, because they have excluded the EBT shares from the calculation of adjusted eps of 7.8p.
In more detail below:
Shares in issue at the start of FY24 were 225.4m and as per Stockopedia, that is also the number today. This would imply that any options have been exercised in y/e 2024 are from shares held in the EBT, ie no dilution. However the number of shares they use in their calculation of eps of 7.8p for FY24 is 206.9m, which implies that they have deducted 18.5m shares which relates to the average EBT holding during FY24. But the shares in the EBT are going to be given back to the participants as the schemes vest. This is why they have correctly added back all the outstanding options over 27.5m shares to get to a diluted average number of shares of 234.5m to give the diluted EPS.
Technically no new shares are issued, so you can argue that there is no dilution. As others have noted, the impact is in the cash which has been paid out by the company to buy the shares. However that is not to say that you shouldn't use diluted eps as Cavendish does in their broker note.
It's also interesting to note that there will probably be another issue of options after the results. Last year on 25 July 2023, they issued 3m shares to the CEO and CFO. Probably at this price, it will be closer to 1.5m.
Its also worth noting that they have charged £1.9m (LY:£1.5m) (note 2) to the P&L for Share based incentive schemes, so there is a charge going through the P&L.
Hi martin,
Yes I covered your first point in my update above - namely that yes I'm happy to use the 7.8p adj EPS figure, now we know that the shares have been bought in the open market and there should not be fresh share issuance.
However, it remains the case that c.£9m+ mgt remuneration has completely by-passed the P&L, with the cost debited to reserves, but has been paid out in cash to buy these free shares.
So the way I look at it, shareholders have paid for these very generous mgt option schemes in cash, thus avoiding dilution, in a roundabout route. But the cost to shareholders is the same.
Regards, Paul.
Sorry Paul, obviously I wasn't clear enough, the diluted eps figure of 6.9p is the most relevant. Because these shares in the EBT have been taken off the issued share capital of 225.4m shares. The 7.8p figure uses 206.9m shares.
And no I don't think the cost has completely bypassed the P&L, that is what the £1.9m charge in note 2 relates to. There will probably be further charges in future P&Ls as some of the options run to July 2026.
On your third point, yes shareholders have paid, but it isn't that unusual to purchase shares in the market rather than issue them for share awards..
I should also flag the Creightons (LON:CRL) results finally dribbbled out this morning, after their premature articulation regarding the write down of Emma Hardie on 8th July.
I think a few of us bought the dip - main thing of note was that they've paid down debt, are now cashflow positive, and can easily add shifts to scale up again. Not expecting that in a hurry, but the risks are now to the upside, in my view.
So the ship is upright again. Question is whether they will one day sale it into another acquisition iceberg given the statement says absolutely nothing about lessons learned (the directors in charge are thanked), other than the resounding "will be much more focused on ensuring a good return can be delivered on its investments".
They've reinstated the divi to perk us up, and plan to "increase penetration of the private label sector".
Frasers (LON:FRAS)
On Frasers, the shares bought back are being held in Treasury and are not being cancelled - I recall seeing a note about this in an Annual Report.
These will inevitably be used for the huge employee reward scheme and I'm expecting a flood of shares back onto the market when that happens. I looked a while back and I think the share count would increase by 33%, a material dilution.
I think it's therefore important to include the material expenditure on share buybacks as an on-going expense that I don't believe is being accounted for in the P&L.
It's still an amazing business, but once the above is factored in I don't think it generates as much cash as many think it does and accordingly I don't understand why it's valued so highly.
Or maybe my analysis is wrong as I've never seen anyone else mention this.
Also Ashley has a majority shareholding and that's enough to keep me from buying in.
A
Frasers (LON:FRAS)
I don’t understand the valuation as well… and there are so many red flags.
How can a company be a member of the FTSE 100 and have a single shareholder with such a big holding?
All the best
The staff scheme pays out at £10 in October 25. Very generous scheme as you say if SP hits £10 and holds for 30 days. I agree many employees will cash in early so you would want to be watching closely at that point, I understand that they would not get all shares, they would be given options in 2 tranches. CEO and CFO incentives are at £15 so they still have much work to do. The new development in Coventry should see a huge automation improvement. The SP I suspect will hit £10 as Mr Ashley will want to reward his team with a bonus at the end.
Thank you for the Renold (LON:RNO) update and clarification of the Employee Benefit Trust (EBT) share purchases.
I watched the investor call last night and I think there are a some important points to add:
Firstly, Note 2: Operating costs includes a cost of £1.9m for Share Based Incentive Plans, so I do think the cost of the share schemes is recorded in the income statement. Hopefully, the points below explained on the call will help explain the difference between the cash cost and the income statement cost.
EBT scheme
In summary, I think they get to the same place from an income statement and cash flow perspective as if they issued new shares to employees and then bought the same number of shares back in the market and then cancelled them as part of a share buy back programme.
I agree either way though that management costs are high given the level of profits and free cash flow.
A lingering concern for me is how much those purchases pushed up the share price last year and without further purchases this year, will the share price drift down, everything else being equal.
Huge trades in H & T (LON:HAT) - seller cleared? Gold price is on a tear, p/e of 6.4 and yielding 5%. NED buy of £38k last month. Half year report on August 8th.
H & T (LON:HAT) is my biggest holding. I've been very patient on this one but hoping it'll come good at some point.
Fantastic report today Paul/Graham. I cant keep up and I'm only reading it!
Yiannos, just look at how Portmeirion (LON:PMP) has outperformed NVIDIA (NSQ:NVDA) !
You ready to yield to the power of the teapot yet? :)
Portmeirion (LON:PMP)
That’s BnB’s expertise!
Portmeirion (LON:PMP) thanks for the acknowledgement yiannos1. WOSS I’m right now getting onto the tech analyst at my bank to persuade him to start covering PMP. AI-powered teapots, anyone?
I wish your tech guy all the best BnB. Mines not worked right since I dropped it making a pot of lapsang souchong
It keeps calling me Joshua now and asking if I'd like to play Global Thermonuclear War.
Easy to fix, ask it to brew you some OXO instead !
Like a bull in a china shop.
FRAS It's the biggest position in Artemis Alpha Trust (LON:ATS) . You can see Alpha's shareholder presentation over on IMC (InvestorMeetCompany). The manager did a good job of explaining why FRAS was attractive,
FRAS is one of my ISA top-up ideas for QARP: https://www.stockopedia.com/co... I am tracking the portfolio performance, which I am very happy with.
Its ROCE is a little weak, but it has a quality stock of 87, and a PE of 9. It doesn't pay a dividend, but operating cashflows have been increasing at around 14% CAGR. Free cashflow has actually gone down due much greater capex, so hopefully this will feed into increasing operating flows over the course of time.
What’s going on at Hornby (LON:HRN), anyone know? - seems to be up heavily on no news so wondering if a tip? Been watching this for signs of turnaround / growth but surprised at rapid upward movement.
It has dropped a lot since the initial boost following news of Ashley's involvement so maybe a mention in the Fraser's results somewhere? There is a small insider but but nothing to get excited about.
Kier (LON:KIE)
Excellent cash generation announced this morning
Since no one is talking about it I have added to my position -:)
All the best
Them and Keller look decent Yiannos.
Annoyed with myself on the latter as was about to pull trigger at 1290p
These type of low margin businesses never trade on a rich multiple though so am wary of chasing.
Love these low margin businesses!
Kier (LON:KIE) especially if you can spot the difference and the impact on FCF of the net margin from 1.25% in 2024 to 1.7% in 2026 for a business of £4B+ revenues.
All the best
Low margin is fine when the multiples reflect it!
And I agree with you, Kier (LON:KIE) did indeed reflect it.
I have lots.
Sadly I should also confess to having some when it went in the other direction in years gone by.....so perhaps put me in the Stopped Clock category.
Good results from AJ Bell (LON:AJB). Everything chugging along in the right direction and mention of trading volume picking up (at last). This should provide a further boost to end of year and to all the companies in this sector (CMC Markets (LON:CMCX) Plus500 (LON:PLUS) Hargreaves Lansdown (LON:HL.) IG group (LON:IGG)Jarvis Securities (LON:JIM) ) some of which I'm happy to be holding.
Alumasc (LON:ALU) Not many investors have heard of this company, which is ridiculously undervalued. Attendance at retail investor events such as Mello would boost their share price. Why doesn't their Chairman or advisors encourage them to do that?
A Private Equity share at massive premium
While most PE shares languishing at discount of 30-40% , I am astonished to see 3i shares rising above £31 when it announced the nav of £21..
the main contributor is a discount super market called Action.
Lack of diversification has helped!
I assume the 3i NAV underestimates the Market Value of Action, synergy alone would not account for the difference
I would personally ignore the 3i NAV and carry out my own valuation of Action (using a multiple of earnings approach) as this makes up the bulk of their portfolio. Given its track record doesn't necessarily look that expensive, but certainly not cheap either. Unfortunately I sold out of 3i last year way too early as thought it was starting to look expensive - good lesson to run your winners!
Northern Bear (LON:NTBR)
Steady as you go year end numbers - £1.6 clean profits at the bottom line same as prior year.
Cash has swung to net debt here - thats no biggie they spent £3 mill buying back shares and working capital movements went against them with some chunky debtors not paying till april. Overall they should be broadly cash neutral within 18 months i would guess.
quoted eps is 9.5p - practicably speaking its probably closer to 11p based on the actual year end share count rather than the average over the year used.
With shareprice of 62p thats p/e of 6.5
This is mature company delivering real cashflow and has pretty good consistent track record here ignoring intangible w/offs its delievred profiuts every year since 2009 perhaps with one covid year exception.
The large shareholder than turned up and was added to the board has now departed so all back to tickover stuff.
They will be investing 300k this year for potential new organic growth activities
Not sure if stocky figures are adjusted for goodill w/off they have 1.98 mill net profit pencilled in for 2025 - with 300k investment announced today i would say if they do £1.5 mill this new year that would be fine tickover stuff.
they are committed to didend which is 2p this year - so 3.2% yield paid out while you wait for absolutely not alot to happen.
Northern Bear (LON:NTBR) is a strange one. The p/e suggests there should be substantial upside potential but then you look at the detail and find that in 2025 they project to make the same (tiny) £1.98mm net profit that they made in 2018 after increasing sales by 50%. Their operating margin of 3.3% is razor thin and the ROE at 7.6% seems like a rather pointless bonus over the rates obtainable for far less effort. They started to pay a small dividend after many years without one.The Directors do not appear to overpay themselves (good) but they have zero institutional holdings although one private investor holds 26%.
It has 17 subsidiaries with 11 different registered offices, which seems unnecessary and if its Stockrank is good it is largely based on the P/s and p/e numbers which, as you note, seem to endorse the idea that “absolutely not a lot happens”. What exactly is the point of this company?
Good results from Alumasc (LON:ALU) this morning. Can’t wait to see what Paul thinks of the concept of UPBT … is that just a re-branding of EBITDA?! More information on the actual numbers would be nice! Either way, I see it as a good value stock, well run and well positioned to benefit from the upturn in the property sector.
Hargreaves Lansdown website unavailable this morning - anyone else having problems?
Just opened my HL account without problem.
Thanks psin, just logged in so sorted.
A member of my dogpack, Alba Mineral Resources (LON:ALBA) has put out an RNS today telling that a Retail Offer opens this very day and the New Share Placing will be admitted on July 26th, trouble is, it doesn't mention the share price. Perhaps ii will be on the ball to help me decide whether to partake or not.
p.s. It must be Black Thursday as Sondrel (Holdings) (LON:SND) has terminally drawn out this dog from my kennel, it's apparently delisting no sooner than let out from Suspension. I've sold, even though it hurt.
Mixed TU from Midwich (LON:MIDW) this morning, with tough conditions continuing in the UK&I, particularly in mainstream AV (panels/displays). However, the US business is going gang busters. That is the main long term growth driver from here as the UK business is much more mature. They seem to have several interesting acquisition opportunities too and historically have acquired well during periods of difficult trading. Overall, I'd say it looks like a very attractively owner operated business. (I hold)
Private Investor Webinar with Currys (LON:CURY) today at 12.30pm. Bruce Marsh, CFO and Dan Homan, Director of Investor Relations, present the FY results and discuss future prospects.
Register here https://us02web.zoom.us/webinar/register/3917165324943/WN_3OUFvfL4SZay8lWKBqblxQ
My morning smallcap tweet: Downtown Shabby
Evoke (LON:EVOK) Mattioli Woods (LON:MTW) Trufin (LON:TRU) Crossword Cybersecurity (LON:CCS) Novacyt SA (LON:NCYT) Graft Polymer (UK) (LON:GPL) Versarien (LON:VRS) Pensionbee (LON:PBEE) Alumasc (LON:ALU) Northern Bear (LON:NTBR), KRM22 (LON:KRM), Midwich (LON:MIDW), Portmeirion (LON:PMP), Netcall (LON:NET), Artisanal Spirits (LON:ART), Franchise Brands (LON:FRAN), Vianet (LON:VNET), Capital (LON:CAPD), CPPGroup (LON:CPP)
◄evoke (EVOK)► warns H1-June adj EBITDA £35-40m behind plan. EBITDA margin only 13-14%, "primarily driven by phasing of costs with marketing costs heavily weighted to the first half, together with lower than expected revenue and the timing of cost saving actions taken...Profitability in H2 2024 is expected to increase significantly, with H2 2024 Adjusted EBITDA Margin expected to be approximately 21%." [SP=NA Cap=NA]
◄Mattioli Woods (MTW)► takeover completion delayed to Sept due to delay in satisfying the NS&I Act condition. [SP=NA Cap=NA]
◄TruFin (TRU)► wins contract with a Specialist Lender to provide its customers with invoice financing. No £££. [SP=NA Cap=NA]
◄Crossword Cybersecurity (CCS)► £500k placing at 5p, a 26% discount, to keep the lights on. [SP=NA Cap=NA]
◄Novacyt (NCYT)► AGM stmt on impact of DHSC Settlement - up to c. £7m net cash increase following VAT reclaim. [SP=NA Cap=NA]
◄Graft Polymer (GPL)► follwing a review co has selected Awakn Life Sciences fot co's first commercial collaboration. Directors "believe that the combined know-how surrounding drug delivery systems and small molecule therapeutics for substance use and mental health disorders between the Company and Awakn will enable the development of innovative therapeutics for the large addressable market for trauma related mental health disorders". [SP=NA Cap=NA]
◄Versarien (VRS)► preliminary Employment Tribunal hearing on Neil Rickett's claim delayed. [SP=NA Cap=NA]
◄PensionBee (PBEE)► launches in US. [SP=NA Cap=NA]
◄Alumasc (ALU)► guides FY-June U/L pretax at least £12.6m, ahead of forecasts of of £11.7m to £12.1m. [SP=NA Cap=NA]
◄Northern Bear (NTBR)► FY-Mar rev down 1.5% but EPS up 9.5p up 12%. Current trading in line. [SP=NA Cap=NA]. I hold.
In line: KRM, MIDW, PMP, NET, ART, FRAN, VNET, CAPD, CPP
Diploma (LON:DPLM) in line update from one of my favourite holdings. I have to say however that the valuation, for so long lagging that of other highest quality industrial compounders, has finally caught up. So the value I’ve pointed to in the past can no longer be captured. That does not mean the shares are a sell. It was never cheap, and most holders will tell you they found it expensive on purchase and yet will express delight at their decision to swallow the high price. I tend to add on dips.
Diploma (LON:DPLM)
Completely agree, BnB, I've built over time, always thinking it is expensive and it's now my third largest holding. They focus on the key metrics for acquisitive companies with a laser-like focus on organic revenue growth, operating margin, eps growth and free cash flow conversion.
DPLM is my second-largest holding, having held since late 2015. I had held prior to that but sold because the share price seemed a little toppy. If I had held on since my original purchase I'm pretty sure it would have been a ten-bagger for me.
One thing that did put me off a little lately is that I saw a snippet of a director presentation, and it had a lot of MBA-speak.
Alumasc (LON:ALU) ahead of expectations update, by about 4.5%, although that relates to the year ending last month. Not much to say about FY25. Quite a jaunty tone, so I’d assume the year is starting satisfactorily. Cavendish raise forecast by 3%. I see tremendous value here, more than most other building supplies companies, given the alarming increase in the need to manage the effect of rainfall. The company’s future isn’t just backed by regulation, but by those leaks and flooding that we’re all suffering recently and of which we can unfortunately expect to see far more. The valuation just looks wrong.
I completely agree with you BnB about Alumasc (LON:ALU) . Solid figures despite a weak UK housing market and delays to the Chek Lap Kok airport contract. Very cheap valuation and useful dividend yield for a company with strong secular growth potential and cyclical recovery prospects.
I do agree that Alumasc (LON:ALU) looks reasonable value especially if a recovery ever really starts taking shape. However, before anyone gets too excited, I would caution that they love to quote Underlying PBT which excludes pension contributions as well as annually recurring "exceptionals" that Paul would no doubt point out, "are not paid for by the tooth fairy".
For a balanced and more nuanced take, I would highly recommend reading Mark Simpson's excellent analysis: https://www.stockopedia.com/co...
Thanks johnsmith68,
Re Alumasc (LON:ALU)
I covered all the issues (eg pension deficit) in my review of H1 results from ALU here on 9/2/2024. We always try to cover bull & bear points here at the SCVR.
Mark Simpson tends to always take an overly negative take on everything! The trouble with that, is you end up missing great opportunities. That will be more the case as we move from bear into bull market, I suspect.
Regards, Paul.
Interesting, I’ve spent the last few days reading and watching old videos about this company. In those videos it has been spelt out quite clearly that value is on offer here even when adjusting for the pension. In fact I had talked myself into buying just yesterday but was trying to make funds available.
I like to see the tangible impacts of businesses I invest in within the real world and have seen a variety of their products specified within a number of schemes I have exposure to. One such item is the wade gully (perhaps not the biggest revenue driver) but I remember working for a repeat build contractor (pre-Covid) who try as he might, attempted to wiggle out of specifications for suitable and cheaper alternatives however they were stuck supplying these items.
Now I’m not carried away by that example but that anecdotal experience makes this an interesting proposition to me. I’ve also seen items such as Alumasc aluminium gutters specified quite widely, and specs for Gatic slot drain as indicated (acceptable by an airport in HK, I wonder what the approvals process is for this). I’m not sure of the moat characteristics of these latter examples as they seem quite low tech to the uninitiated but I’m sure there must be some reason spec writers refer to them (quite consistently in the RWG example).
Anyway I’ve taken an entry position, after the horse has bolted it seems. However I’m aiming for moderate capital appreciation and a steady stream of untaxed dividends in my ISA and I think this company is set up to do just that.
There's consolidation in the building sector. Could Alumasc (LON:ALU) fall prey to a bigger player? Mtk cap of around £70m as of yesterday.
Fully agree - I think Mark is an excellent commentator and always good to get both the bull and bear cases, but I remember his Alumasc (LON:ALU) article at the time and thinking it was overly negative. That's probably good if we going into a downturn, but not when we're about to go into a new bull market (hopefully).
Thanks Paul I read with interest your coverage of Alumasc in February, did my own research and agree that this is an interesting Company with some unique IP. Took a small position then like you and pleased with today’s announcement. One certainly to keep an eye on.
Thanks BnB and Paul, I was looking for some UK housing market exposure where the company is currently growing profits so bought into Alumasc (LON:ALU) a few weeks ago. So I'm at the start of understanding the business, it always useful to get others' views.
Morning, thanks for the writeups already Paul!
Does anyone know of an ETF or similar that is focused on the housing construction sector? I.e. the likes of Van Elle, Ecel, Brck, Epwin. ALU etc?
Thanks
Hi- only aware of US ones https://www.etf.com/topics/hom...
Great news
Residential landlords (see below comments from Grainger CEO) seem to like Labour's new housing strategy that was outlined in yesterday's Kings Speech.
Meaning (hopefully) greater investment in Build-to-Rent, new homes, RMI & reprovisioning. Boosting the whole industry including the beaten down building materials/products sector, which has been recently hit by the UK's H1 wet weather & disruption caused from the early general election.
Grainger CEO Helen Gordon adding: "The proposals set out in the King's Speech to speed up housing delivery, particularly through reform of the planning system, is welcome and will give housing providers, such as Grainger, greater certainty to invest and build homes across the country. Ensuring local plans are in place with local housing targets, and removing planning uncertainty for housing schemes that comply with local plans is a very welcome change and aligned to Grainger's primary focus of housing delivery on brownfield land in urban centres with high housing demand."
Morning Paul
Just a quick post to say I watched your interview with Gervais Williams yesterday, the first one of your interviews I have watched. I really enjoyed your style and subscribed.
Thanks, Alastair
I really like interviews with fund managers, and their presentations over at IMC (InvestorMeetCompany) . There's nothing in the way of "talking to their hat" and they are able to articulate their strategy and why they are buying, holding or selling a particular share.
Good for the corporations, not for private BTL landlords that are being squeezed out.