Small Cap Value Report (Thu 20 Jul 2017) - IQE, EGS, UCG, BOOM, CARR, MTC, JDG

Good morning ladies & gentlemen. It's Paul here.
They say that the early bird catches the worm, and that's very true in stock market terms. I wish I could discipline myself to start work properly at 7am each weekday, but I can't. It's usually more likely to be a quick run through a few RNSs on my iPad, then back to sleep.
As luck would have it, I started work today at 5:30am, wanting to get the monthly accounts done for a share club where I'm treasurer. So by 7am I was fully functioning. That was good, as I spotted 2 companies in particular, where some really good news came out, and I was able to buy, or top up, at the opening bell.
So let's start today's report with those 2 companies.
IQE (LON:IQE)
Share price: 97.75p (up 15.0% today)
No. shares: 676.5m
Market cap: £661.3m
(at the time of writing, I hold a long position in this share)
Trading statement - this is a Cardiff-based company which describes itself as;
the leading global supplier of advanced wafer products and wafer services to the semiconductor industry
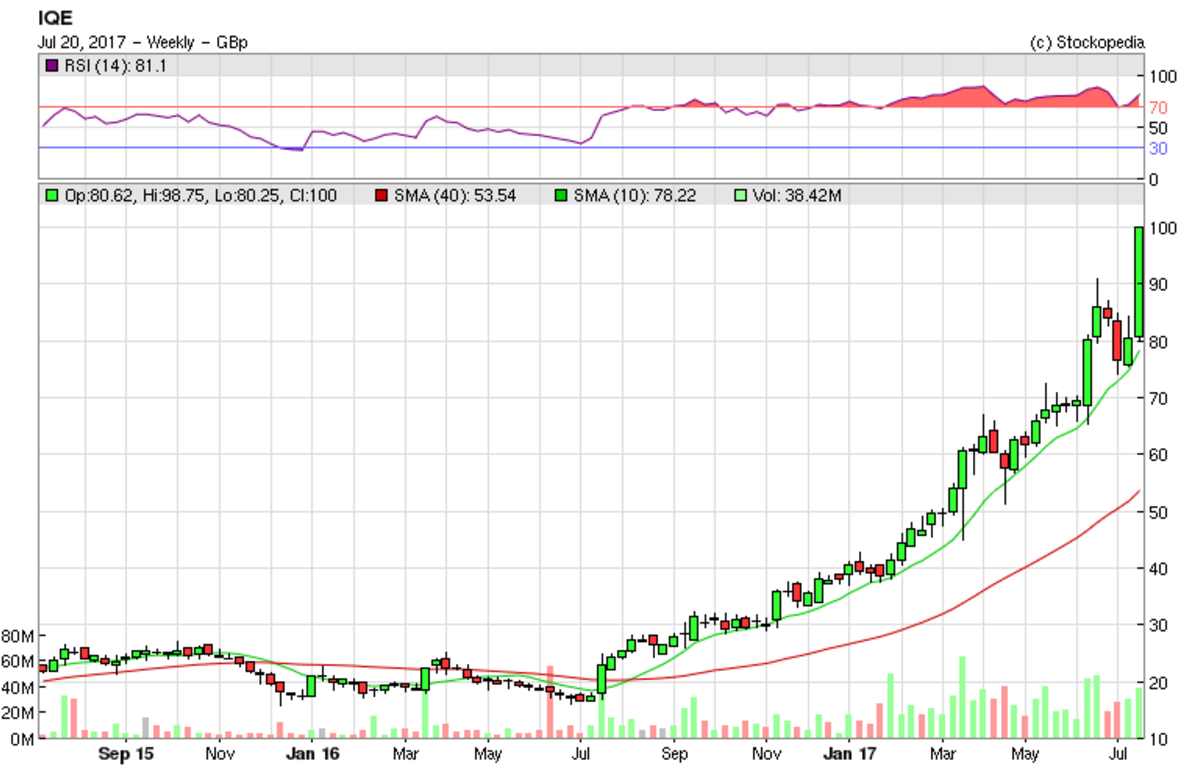
I've covered this company here before, but have never really understood the sector, or the future potential - I just crunched the historic numbers. Several readers were well ahead of the curve, spotting the opportunity some time ago, and have been rewarded handsomely so far - the share price has risen a remarkable 5-fold in the last year.
Reading its trading update today, I was struck by the comments at the end, which look game-changing to me. In particular this bit;
...In light of recent progress and its increasingly confident outlook, the Board expects the Group will now exceed market expectations for the full year and whilst it remains early into the start of the mass-market adoption of our technology, it is possible that with the current contract momentum, a more significant upgrade to current market expectations could be delivered for 2018."
We're in a roaring bull market at the moment, so that's exactly the kind of announcement which is likely to put a rocket under a share price. To a certain extent, this is the type of growth situation where the share price can easily detach from conventional valuation metrics (PER, etc).
I'm not really comfortable with that approach, but it's where the big money is being made right now. So I think it makes sense to join the party, even though I'm very late compared with more switched-on readers, who researched the company properly.
Our Graham did spot the opportunity in his report here on 14 Dec 2016, and the share has 3-bagged since then.
H1 2017 performance - the company has a 31 Dec 2017 year end, so it updates on H1 today as follows;
The Group announces that it expects to deliver revenues of c. £70m for the first half, reflecting increased sales in each of its three primary markets. Notably, photonics continued to deliver strong double-digit growth, enjoying the early phase of a significant ramp in VCSEL wafer supply for mass market consumer applications. As a result, overall wafer sales are expected to grow by c.16% against H1 2016. This has also been supplemented by c. £1m of license income (H1 2016: £3.5m).
That's not particularly exciting, because most of the 16% gain comes from favourable forex movements.
Capacity expansion - existing facilities are not enough for expected demand, so a further increase in capacity is being implemented - so about £15m more capex, one broker suggests today.
Free cashflow - I've been concerned in the past that the company produced very little free cashflow. However, I'm coming round to the view, that in a bull market, this might be ignored. It's all about new products, and strong growth - in particular from "photonics", which apparently is a new computer chip which allows 3D sensing, for the next generation iPhones, and other products. I think one of our best reader/commentators, Jane, mentioned this in the comments section a few months ago.
Broker notes - I've seen 4 broker notes this morning, 3 of which are bullish. One mentions that the upside case could be EPS shooting up to 12-15p EPS, if the new products really take off. That would clearly be very bullish indeed for the share price, even after big gains this year.
Although one broker concludes his report today by pointing out that the share is far from cheap, especially on a free cashflow basis. Although on a PER basis, it doesn't actually look particularly expensive, for a tech growth stock. Here are the Stockopedia valuation graphics from last night. Obviously the big share price rise today will subsequently move these numbers somewhat;
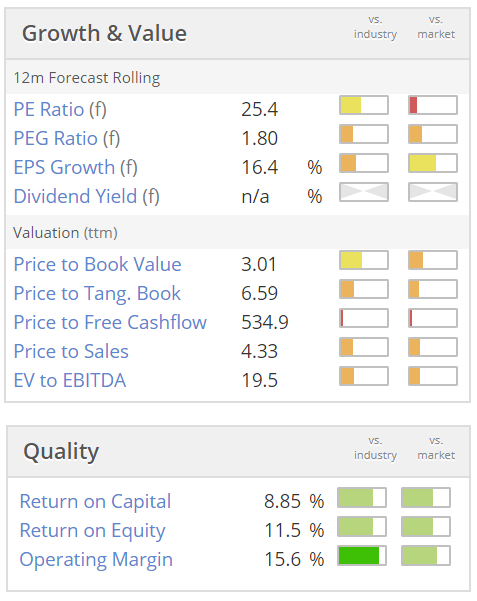
These figures are based on broker forecasts which look very conservative. The opportunity here is if the company absolutely smashes forecasts in future - which they clearly hint at in today's update.
There's an interesting post here on Stockopedia, from nickwild, who wondered if IQE is a Minervini stock in the making? I think he might be right, I can see similarities with Minervini's highly successful approach.
Our own Ben Hobson interviewed Minervini in Mar 2017, here.
My opinion - there's not a lot more to say really. Just that this could, potentially, be a very interesting company. The upside from making a new type of chip that is maybe about to take off in mobile devices, seems pretty exciting.
Also, on a PER basis (if you accept the basis on which the accounts are prepared), it's not crazily valued. The best stocks are rarely cheap, and if you stick to low PER things, you'll generally end up buying mostly junk, as I've learned the hard way. Sometimes it pays to push the boat out, if there are clear signs of something game-changing going on.
The risk with higher-rated, growth companies, is that if the market as a whole has a big correction, then often this type of stock gets hit hard. So it was a nervous buy for me today, being well outside my comfort zone! Reader comments on this one very much welcomed - as I'm learning from you on this one, rather than the other way around.
eg Solutions (LON:EGS)
Share price: 93.4p (up 11.2% today)
No. shares: 22.7m
Market cap: £21.2m
(at the time of writing, I hold a long position in this share)
Pre-close trading statement - this covers the 6 months to 31 Jul 2017, so H1 of FY 01/2018.
This is a software company, which describes itself as:
the back-office workforce optimisation company
It's a positive update:
The Group is pleased to report that trading in the first half of the financial year has been strong. The Board now expects results to be ahead of market expectations with Revenue for the full year ended 31 January 2018 to be not less than £10.5m (2017: £8.2m) and Adjusted EBITDA to be not less than £1.9m (2017: £1.2m).
It's interesting that the company is sufficiently confident at the half year stage, to forecast a beat on its full year numbers, and even give precise figures (always good). That suggests to me that the pipeline is solid, and there's possibly scope for a further increase in forecasts in H2 maybe?
I'm less keen on trumpeting EBITDA as if it were a proper profit number, which of course it isn't, especially for software companies which chuck a load of the payroll onto the balance sheet, instead of expensing it.
Looking back at the cashflow statement from the last full year accounts, this company has been capitalising about £1.5m p.a. of development spend. Therefore the EBITDA of at least £1.9m above, would really only mean about £0.4m in cash profits the way I look at things.
Therefore, even on improved performance, the business isn't worth the £21.2m market cap, in my view. However, it's all about the future. This company has a great client list, of big organisations, and seems to be on a roll, in winning new contracts. That could transform future profitability, if things continue in the same vein.
Order book - is also strengthening. As this grows, it should hopefully see a smoother progression of profits, instead of the erratic performance in the past.
Contracted orders of revenues to be recognised beyond the current financial year end have also increased by a further 14% to not less than £21.1m (31 January 2017: £18.5m) due to the increase in sales of the Group's Managed Cloud Services, contracts for which are longer term in nature.
So that's about 2 years' revenue, in the order book, a decent underpinning. Although I think it's spread over more than 2 years, so the company will have to keep winning new business on top of that.
My opinion - I'm still nervous about this company's past, but am slowly gaining confidence that it might be coming good.
United Carpets (LON:UCG)
Share price: 10.0p (down 2.3% today)
No. shares: 81.4m
Market cap: £8.1m
Final results - for the year ended 31 Mar 2017.
This company calls itself;
the third largest chain of specialist retail carpet and floor covering stores in the UK
These figures look OK. This is a tiny, illiquid share, so I'll only mention the key things briefly.
- LFL sales +1.3% - not too bad, in a tougher environment
- Revenue flat against last year, at £21.2m
- Profit before tax also flat, at £1.5m
- EPS of 1.58p, for a PER of only 6.3
- Sound balance sheet, with net cash of £2.6m
- Divis - note that the company has paid out bumper special divis, so there could be more to come perhaps?
- Current trading - "challenging", but LFLs have remained slightly positive. However, marketing activity has increased significantly, so that might mean profits start to slip?
My opinion - a nice little company, which is now vastly improved from when it went bust a few years ago (due to onerous leases, as is usually the case). Obviously it's cyclical, so dependent on consumer spending, although I think it serves the cheaper end of the market, so might be more resilient than others perhaps?
A while back, I made a nice little profit on this small company, and got some lovely divis too. If you strip out the cash, then the PER is really low. Although it probably should be low.
It's too difficult to get in & out of this share, due to illiquidity, so it's not one I would revisit personally.
Audioboom (LON:BOOM)
Share price: 2.2p (up 10.0% today)
No. shares: 930.6m
Market cap: £20.5m
Half year results - to 31 May 2017.
The company calls itself:
the leading spoken word audio on-demand platform
I'm afraid these results are just more of the same. Lots of gushing narrative, but unrelenting losses, and once again cash is running low.
Revenue is up 460% to £1.8m for H1, but so what, if it generated only £497k in gross profit. Yet the overheads were £3.4m in the 6 months. So an operating loss of £2.9m was incurred.
If the gross margin percentage remains the same, then revenue would have to increase 7-fold, from here, just to reach a breakeven run rate. How likely is that?
With only £3.2m left in the kitty, it looks like BOOM will need yet another fundraising in early 2018, in order to continue in existence. The delusional CEO thinks he has a strong balance sheet, with enough cash to see it through to breakeven.
Dilution - note that there were 638.0m shares in issue at 30 Nov 2016. Just 6 months later, there were 930.6m, an increase of over 45%. Management reckons that monthly cash burn is reducing, but I'd be amazed if the company can actually reach breakeven without having to raise more cash, thus diluting existing holders even further.
My opinion - it seems obvious to me that this is not a viable business. So why on earth would anyone keep pouring money into it? This is where it helps to have very wealthy shareholders - as propping it up is pocket change for them. Shoving in a few more millions is probably more about saving face, with a topping of wishful thinking.
Risk:reward here looks dire, so it's not something I would even consider investing in.
The Stockopedia computers agree with my assessment that this is one of the worst companies on the market - giving it a StockRank of zero!
There's a small chance that management might prove the doubters wrong, but why I want to gamble on that outcome, since it's so improbable?
Carr's (LON:CARR)
I last reported on this agricultural products & engineering group when it put out a mild profit warning in Mar 2017. Better news today, with an in line update:
Overall trading for the Group remains in line with the Board's expectations for the current year.
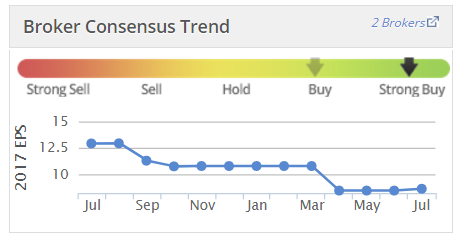
It's worth pointing out that expectations have come down quite a bit, this making it easier to achieve them:
The agricultural division is seeing improvements in performance.
The delayed contract in the engineering division has now been signed.
So it sounds like the group is getting back on track. Maybe there's some value here, but I can't really see it. It just looks like a boring, ex-growth, low margin business. That's really not what the market is generally looking for at the moment - in a bull market people want growth stocks mainly. So the risk is that this one could just drift down, or sideways, due to investor apathy.
Still, on the upside, the company's shares have recovered about half the fall caused by the profit warning in Mar 2017. I've no idea why the StockRank is so high, at 94 - maybe there's something here that I've missed? Do any readers like this one? There is a 3% divi, which is worth having.
Mothercare (LON:MTC)
Trading statement - obviously this is a UK & international retailer & franchiser of children-related products. I've been keeping an eye on it for several years now, waiting for a convincing turnaround to occur. I last reviewed the annual accounts here in May 2017, and came to the conclusion that it looks like a company which is running, just to be able to stand still.
That was 124p per share. We're now down to just 101p per share.
Q1 update today - UK seems OK, with LFL sales up 1.9%. Online sales growth is poor, at only +3.3%. That's not at all good, when online generally is growing at about 20% p.a. in the UK. So clearly Mothercare is losing out - probably to Amazon, like so many other conventional retailers.
International - this is a concern, as sales have fallen back badly - Q1 saw constant currency international sales down 8.3%. This is worse than any individual quarter in the prior year. Favourable forex movements mean that this does translate into a rise of 2.2% in sterling.
The Middle East is flagged as the problem area.
My opinion - this is looking increasingly like a struggling, old school retailer. I'm not convinced by the turnaround. More like managed decline, I'd say.
£JDG
Trading update - for the 6 months to 30 Jun 2017.
Performance at this acquisitive group of medical instruments companies, has been quite erratic in recent years. There won't be any complaints about today's update though, it looks very good.
Strong order intake augurs well for H2 results;
Order intake in the first quarter was very strong, reversing the trend seen since 2014. This was followed by a good second quarter. Consequently, for the first half as a whole, the Group experienced 28.1% Organic growth in order intake from the same period last year. The Organic order book finished the first half at 16.5 weeks of sales against 11.2 weeks at 30 June 2016 and 14.9 weeks at the beginning of the period.
H1 results sound like they should be respectable:
The Board expects the interim results to show solid progress in revenues, EBIT and earnings per share.
Outlook - I'm a bit surprised it's only an in line outlook for the full year. Maybe they're just being prudent, and holding a bit back? I'd say there's probably a fair chance that the company might now beat existing expectations:
The sustained strength in order intake in the last twelve months and the continued weakness of Sterling provide the Board with confidence that the Group can deliver a full year performance in line with market expectations.
My opinion - a nice group of companies, with strong management. It's good to see them getting back on track. Although this arguably has already been reflected in a share price up about 50% from the lows about a year ago.
Great, that's me done for the day!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
I don't think IQE (LON:IQE) is risky or speculative. It looks a terrific growth company, with big contracts now coming through. The brokers seem to admit that their forecasts could be way too low (Peel Hunt are explicit about this). It's not particularly expensive on the existing forecasts.
As such, I think it looks a very good risk:reward stock, and I've backed up the truck on this one in recent days.
Regards, Paul.
Hi Paul, out of interest, when you back up the truck, what percentage of your portfolio do you typically load onto it?
Hi Paul,
You wrote:
"I don't think IQE (LON:IQE) is risky or speculative. It looks a terrific growth company, with big contracts now coming through."
I respect your views on the riskiness of IQE. Stockopedia's risk rating for IQE is 'speculative'. But Stocopedia's risk rating is based on past volatility, and that is not necessarily a good measure of risk for a particular stock. Interestingly, Stockopedia gives IQE's Beta value as 0.6, and some people consider stocks with Beta less than 1 as being less risky than the market as a whole.
Hi Seadoc,
I agree that IQE is risky and speculative, but from what I've read I think there is a reasonable chance that it might turn out to be a great success over the long-term. The management borrowed money some years ago to make some acquisitions and investments in R&D, which I think have put it into a very good business position for the future in a wide range of potential high-growth markets for 'compound semiconductors'. It's possible that they might have done some slightly dodgy things from an accountancy point of view to make their figures look better when their debt was high (although I have no reason to think that other than what you'd written previously), but their cash flow and debt situation seems to have improved recently, so they may have no need for such tricks in the future. I was persuaded enough by what I'd read to buy a significant number of shares at the high price of 108 pence last Friday, so personally I think it was worth a punt for the long term, even at that high price and its corresponding highish historic PE of about 30. But everyone should do their own research.
Hi Seadoc,
"You are probably right that it is a good thing for the company, but did you mean the shareholders or the directors?"
I meant the shareholders, but I expect it will be a good thing for the directors too!
pka,
pks??? Eyesight or fingers?
"I meant the shareholders, but I expect it will be a good thing for the directors too!"
I am sure you are right about the directors and I really hope that extends to the shareholders. Paul is holding so there cannot be anything blatant in the accounts but having sold (sour grapes perhaps?) I still see demons. Seadoc is getting old, grumpy and clearly either half blind or fat fingered, but nonetheless I am still not totally convinced (and no longer holding).
But ATB to holders,
Seadoc
I agree that's an encouraging point for IQE's future prospects.
Does anyone know what patents IQE (LON:IQE) hold on any of their product sets? I can find nothing on their website or any mention in the presentation I watched.
This web page says IQE has over 100 patents, but doesn't say what they are:
https://www.electronicsweekly.com/news/business/sparkling-results-from-iqe-2016-03/
Many thanks. In the Mello presentation he says something similar but I'd like to understand the detail, especially relating to the Epitaxy process on Silicon.
A search for IQE on Google Patents throws up several items referring to epitaxial structures:
https://patents.google.com/?assignee=iqe
I wonder how important patent protection is in electronic chip manufacture. If a competitor in Taiwan (for example) infringed IQE's patents, would IQE ever know and even if they did would they be able to successfully sue? Another issue is that by applying for a patent, IQE has to reveal its intellectual property to the world.
In these kinds of areas it tends to turn into a numbers game. So each big player has a huge number of patents and if you try to challenge them the response is effectively "if you sue us we'll find a patent in our portfolio that you infringe". As a result your best protection against being sued is to have a decent sized portfolio of your own.
Companies generally don't go after others in the space with patent portfolios of their own, but they can go after anyone trying to enter the space without any patents. For example Premaitha Health (LON:NIPT) is currently being sued by Illumina. NIPT have no patents (I think) and Illumina have over a hundred.
Hi Nick,
Thanks for your very useful comment on patents.
I suppose one of the tricks in applying for patents is not to fully reveal all of one's relevant intellectual property in the application, so the information in the patent application is not enough for a competitor to use.
Another point made by Mr. Rasmussen in the PI World video was that the things that IQE do are difficult to replicate even where there is no IP protection, so that their know-how built up over the years is also a competitive moat that for example enabled them to persuade a customer to let IQE take over the customer's in-house operation because the competitor was unable to get their processes to deliver the required yields.
Guys -
Yesterday luthrin wrote
"On Private Investor World there's a video from Jan 2016 by Phillip Rasmussen, IQE's Group Finance Director, in which he outlines the long-term investment case for the company. It's almost an hour long, but it's probably the best overview you'll get of the company"
So I took the time last night to view it. I wish I had done it sooner. It is both a primer of the advanced semiconductor technology and detailed overview of IQE's position in this world.
Below is a screen grab which shows IQE's dominant position in their three primary technologies, wireless, photonics and infrared. There is a wealth of information he provides on this slide. You need to view it for that; it's about 23mn into the presentation.
Thank you Luthrin.
Hi Ramridge,
Thanks for your post in which you wrote:
"Below is a screen grab which shows IQE's dominant position in their three primary technologies, wireless, photonics and infrared. There is a wealth of information he provides on this slide. You need to view it for that; it's about 23mn into the presentation."
I think there's tremendous potential for growth in those three primary technologies. But I think there is also enormous potential for exponential growth in their three non-primary technologies, solar, power and CMOS++, although that growth might take longer to really take off. And IQE should be able to use the cash-flow and expertise developed from their primary technologies to put themselves in excellent business positions for their non-primary technologies when growth in those eventually does take off in the future. As Philip Rasmussen pointed out in his hour-long presentation, there are inherent technical limitations on what relatively cheap silicon chips can achieve in those technologies, and there will be technical and economic pressures encouraging the greatly increased use of the more expensive but much more technically advanced compound semiconductors in the future, and as the dominant outsourcing manufacturer of wafers for compound semiconductors at present, I think IQE is in a fantastic position to benefit from these long-term trends for growth. The cash flow and spending needed to fund future technical developments is the main concern, I think, but hopefully IQE's management will be able to cope with that. It's not as if they are a jam-tomorrow company, as they already have good sources of cash revenues and dominant positions in their 3 primary technologies. But everyone should do their own research and draw their own conclusions.
Hi pka - Re IQE (LON:IQE) I bought into this company about a month back following a cursory analysis. Had I done a more thorough analysis I would have bought much more.
Always difficult to draw the right balance between the number of stocks one holds and time available to do in-depth analysis. The usual depth vs breadth dilemma.
The one thing that has been nagging me of late is Rasmussen's and Williams's sale of shares, 1.9m each, on 19/5 @68.29p. I re-read the RNS this morning and the reason they offered was to do with forward retirement planning. The RNS also mentions that their sale was roughly half of their total holdings so they still have serious skin in the game. From their point of view and in hindsight, it was real bad timing as it looks like they left over 60% of potential gains on the table.
Anyway I have decided to accept their explanation for selling in May as genuine.
The retirement of the two principals is worth thinking about. In this case it does seem as though some thought has been given to timing and hopefully to succession.Anyway it maybe some years ahead.
I looked at CARR and it doesn't do anything for me - I always dislike the word "overall" coming before the statement "trading is in line with management expectations", it implies that at least one division is struggling and one or more other ones are propping it up - sure enough, the engineering division is struggling (in part due to a contract delay) and the outlook doesn't look rosy for it. There is also a potential ongoing impact due to falling cattle prices. Considering the lacklustre single-digit profit growth in the last interims and finals I don't see them as great value; I'd argue there are plenty of better shares offering a comparable yield...
http://money.cnn.com/2017/07/20/investing/nasdaq-10-day-winning-streak-stocks/index.html
IQE - First sign of euphoria ?
Not usually a fan of technically analysis, but the IQE (LON:IQE) chart is frightening, almost perfectly parabolic...
Paul,
IQE (LON:IQE) "I've covered this company here before, but have never really understood the sector, or the future potential - I just crunched the historic numbers."
The historic numbers were what they would have made had they sold the product at the going rate rather than at a discount they agreed as they did not have enough cash to purchase the manufacturing division of RFMD mid 2012.
On 25th July (edit: 2013) you commented on another techno because of capitalization of costs into intangibles. I am pleased that you do not see this problem with IQE (LON:IQE) but I do wonder about the write off of the equipment donated with the trumpet herald of Welsh Development Authority (who gave their share of costs in tax payer cash) to the new compound semiconductor cluster:
http://www.walesonline.co.uk/business/business-news/world-first-technology-cluster-south-12993990
"Plans to create the world’s first compound semiconductor cluster in South Wales, which eventually could lead to the creation of 5,000 hi-tech jobs, is expected to receive a multi-million pound funding boost next week from the £1.2bn City Deal.
The cluster, in a project being driven by one of the Wales’ leading technology firm, IQE, and Cardiff University, would see a major compound semiconductor manufacturing facility at its heart alongside:
I was invested but like you struggled to reconcile profit and cashflow so sold out at about 40p. Clearly I should have held on, I share your nervousness and if Ed is right in that the rate of posting on bbs and long term prospects are inversely related then a quick visit to the usual sites would suggest it is indeed appropriate to be nervous.
Regards,
Seadoc
Hi Seadoc,
You might be right to be suspicious of some of IQE's accounting practices. However, the fact that the Welsh and UK governments are supporting initiatives using large amounts of taxpayers' cash for compound semicondctors in Wales, in collaboration with IQE, seems to me to be a very good thing for the company.
pks,
"However, the fact that the Welsh and UK governments are supporting initiatives using large amounts of taxpayers' cash for compound semicondctors in Wales, in collaboration with IQE, seems to me to be a very good thing for the company."
You are probably right that it is a good thing for the company, but did you mean the shareholders or the directors?
Seadoc
EG Solutions - I fall very much into the bargepole camp.due to the past unbridled greed of EG.
Although I think I read that she has been reined in a bit, leopards & spots.....
Having worked in a company with a v greedy CEO and seen the effect on morale, I'd much prefer to find companies where remuneration is seen to be fairer......
Hi Paul,
Thanks for the report(s). Useful and informative as always!
I just wondered when you changed your view on EGS and went long? I recall the historical posts regarding Management and so was intrigued as to what made you revise your bearish opinion? Just the fundamentals or did you meet Management? If I missed it then apologies...!
I actually used to work for the company many moons back and have kept my eye on the sp for over a decade. Seems to have started increasing around the time I left; coincidence I'm sure.
Cheers.
Hi GG79,
Checking my main small caps dealing account, I first bought in late Mar 2017, about a week after writing about it here - where you can see I was starting to feel a bit more positive about it. Then added more in May 2017, and July 2017, after further positive updates. So I've just been following the positive newsflow, as usual - that's basically my investing strategy in a nutshell - it's driven by newsflow (hence these blogs).
You can search by ticker on Stockopedia, for any stock, then click on "Discuss", and it brings up the archive of mine (and other people's) articles relating to this stock.
Here is the archive for my articles on EGS: http://www.stockopedia.com/sha...
So if you go through those articles, you'll see my tone become more positive on EGS, and then the disclosure appear of me having gone long, in the next report which mentioned it.
Regards, Paul.
Re Science in Sport (LON:SIS) In recent months I have looked at SIS a few times because it has various attractions such as a huge global addressable market, ecommerce potential, respected and popular products.
But in every instance I stopped dead when I remembered management paying out huge share based payments, as much as 13% of revenues when it is actually in a loss making situation.
Greedy management is a red flag that I have learned to pay attention to. If and when they make substantial profits, yes I can accept small to moderate share based incentives, but not before.
: Re SIS Check out Moon's involvement in PXS. Bargepole for me.
Yes I would agree with your concerns about management of Science in Sport overpaying themselves and this is certainly a major negative but I don't always regard it as a red flag. Perhaps it's what management is used to as the most senior ones used to work for big pharma!
Hi Paul, over the years painful losses in some sectors have taught me to avoid them totally. One such sector is semiconductors, some years ago I became a fan of Wolfson Microelectronics, ended up losing on that one. The typical comment around their results was lack of earnings visibility etc. that put me off investing in that sector as I noticed similar companies saying the same thing. IQE may be different, I don't know the company, but just wanted to offer a counterpoint to other views on here.
And eg solutions, was that the one with the outstandingly greedy CEO with some crazy package? That instantly renders the company uninvestable for me. Also software companies, after investing in a few duds, have too much chance for earnings manuipulation through capitalization of development costs etc.
I don't want to rain on any parade, just sound a note of caution. Markets increasingly seem detached from reality, and especially the economic situation in the U.K. When the tide does eventually go out, those boats that have been lifted impossibly high by this raging bull market will fall the furthest.
"eg solutions, was that the one with the outstandingly greedy CEO with some crazy package? That instantly renders the company uninvestable for me."
That's right. It's a bargepole for me too.
Hi ricky65,
Yes, but all the stuff about the CEO and previously excessive remuneration, etc, is all known, and in the price. That's why EGS could now be a bargain (maybe). I think the price would probably be twice the current level, if there hadn't been all those shenanigans. Now that the business seems to be turning a corner, oddly enough I see the previous problems as being a positive thing, that has enabled me to get in cheap.
It will be interesting to see if EGS does turn out to be a winner. Or, whether the sceptics turn out to be right, and that the recent stronger performance turns out to be another false dawn? I don't know the answer, hence am keeping my position size reasonably small - less than 2% of the portfolio. So I doubt it will make it into BMUS - which is my conviction buys only.
Regards, Paul.
Hi Paul
I look at it this way - there are plenty of companies where management aren't greedy to invest in so why do I want to get involved here?
It's one of those shares whereby, if I invested and it went wrong I'd be really annoyed with myself. Thoughts like "I knew about the CEO being greedy but still bought" and so on. And then on top of that it's been a serial disappointer over the years.
I think a small position is wise here. The skeptics have been proven right thus far. It actually meets Minervini's Trend Template criteria and if it clears the overhang and breaks 110p it looks good for me from a technical point of view. Good luck with it!
Kind regards
Ricky
A word of warning for those of you buying into IQE (LON:IQE) today. The share price tends to make a step change on each piece of progressive news (take a look at post AGM, post full year results etc) and then the hot money gets taken out when the momentum runs out of steam - typically there is a sharpish retrace followed by a spell of consolidation before the next news which in this case will be 5 September. My own view is that the house brokers and the City know they have a rare beast on their hands here and are somewhat stage managing the share price progress. As a long-term holder (IQE is my largest holding by some distance) I am delighted with this approach but if you don't fully understand the business, nervous holders can easily get taken out by stop losses.
I concur that there have been some excellent posts by Jane on this site and also, if you can stomach ADVFN, the deep expert is "sweenoid" although his communication style can sometimes be a little pompous. I am travelling at the moment and have a busy weekend ahead but I will try to put some useful links and excerpts together next week to help those interested develop a deeper understanding of the business. In short, IQE (LON:IQE) are a picks and shovels player in many of the big technology transformations that are under way such as next gen smartphones (not just Apple), data centres, internet of things, 5G, automated cars. 3D sensors in smartphones is not even likely to be their biggest revenue stream over the next couple of years.
I don't want to appear too rampy about this company but it is well worth conducting some deep research. Unless others beat me to it, I will try to post some further info to aid that research next week.
Cheers
Simon
"Here's our Graham with a quick reminder..."
He pointed IQE (LON:IQE) out last December and once again turns out to have been bang on the money.
Thank you Graham - your contributions are greatly valued and has made this report even better, despite the very high bar Paul has set.
IQE used to be a 700p share - heading back there rapidly!
Yes it did - in the year 2000. Since when, IQE (LON:IQE) did a share split 10:1. So what's your SP forecast, in what timeframe and for what reason?
Can your Graham :-) run his ruler over Jarvis Securities (LON:JIM) ? I think the results are excellent but I value his trained eye.
Also for the benefit of readers who might have missed it, Tristel (LON:TSTL) had an open day and trading update yesterday which has been very well received. I hold both as long term holds.
With regard to IQE (LON:IQE), I'm not bothered by the lack of free cash flow at this stage in the development cycle. There is an upward trend in operating cash flow but it is being consumed by capex to support the ramp up in production. That would appear to be a good thing rather than a negative. Higher FCF will arrive as the volumes increase and capex only needs to increase at a reduced rate.
Previously, the share was being chased higher based on the prospects for growth but without confirmation of substantial concrete progress. It would seem that this growth is much more definite now and so it is moving higher still.
If you prefer companies that have minimal need for capex then perhaps something like Purplebricks is your preferred risky buy. However, a company like IQE surely has much more IP to protect it from competition along with tech expertise that is much harder to replicate than you would find with Purplebricks. Or put another way, Purplebricks competitive advantage comes from its business model which can be copied by others, and possibly from their marketing spend but others do not need to match or exceed that to have recognition in the market.
So, I continue to hold IQE as I like their growth prospects and their strong competitive advantage.
Ramridge and others - do you have a link to any explanation of what IQE does aimed at the intelligence of primary school children like me? I held IQE earlier in the year and now annoyed I sold at 56p! I bought it originally because I thought it was being priced like a value share even though it looked more like a GARP share. But I didn't have the conviction to continue holding because I didn't properly understand what it does. I've bought back in just now and want to do some further research. Because I monitor Welsh politics I am also aware the company is very highly thought of by Welsh Government who are excited that it might create a silicon valley in Wales; although given the state of current politics that might be a bad sign?!?!
There is a tremendous amount of material on Research Tree, going back two years or so,
worth the subscription simply for this alone.
Also, perhaps unusually, the free bulletin boards are providing quite a bit of info, particularly (as pointed out by Ramridge) in the contributions from one particular poster by the name of "Dave Sweeney" on iii and "Sweenoid" on ADVFN.
The company itself also provides a great deal of info on their activities, on their website, as well as in their last results RNS.
Thanks Jane. Your posts are also very helpful on IQE (LON:IQE). You're one of the best contributors on here.
To be fair the reference to the expert blogger on the iii forum was made by peterthegreat.
Ramridge and others - do you have a link to any explanation of what IQE does aimed at the intelligence of primary school children like me?
On Private Investor World there's a video from Jan 2016 by Phillip Rasmussen, IQE's Group Finance Director, in which he outlines the long-term investment case for the company. It's almost an hour long, but it's probably the best overview you'll get of the company, particularly as Rasmussen is cognizant of the fact that he's making his pitch to a financially savvy yet non-technical audience.
[A more recent video, this time with CEO Drew Nelson can be found here.]
Rasmussen discusses the various markets where compound semiconductors are likely to play an increasingly prominent role, and photonics (which is creating much of the current buzz with IQE) is not by any means the largest potential growth area, but it's the most immediate. Tim Cook hasn't disguised his enthusiasm for Augmented Reality (AR) technologies and all the evidence suggests that this is where Apple's core focus will be over the coming decade, first on its next generation of smartphones and eventually on wearables (glasses). IQE is the leading global supplier of vertical cavity surface emitting lasers, otherwise known as VCSELs (pronounced VIC-SELL), and these are a key component of the 3D sensing tech required to map environments in real time for AR applications. VCSELs are also used in LIDAR devices, which are gaining increasing prominence due to their sensing capabilities for autonomous vehicle tech.
I took a large position in IQE between July and October last year and I see it as a long-term hold, one of those that you stick with through thick and thin unless the story materially changes. I believe the company has tremendous potential, but of course nothing is certain in the tech world, and the persistent demands of capex to keep ahead of the competition can mean a paucity of cash returns for investors despite strong revenue growth.
I bought some more shares at the beginning of this month, but not as many as I would have done had Dr Howard Williams (IQE's Operations Director) and Rasmussen himself not sold 1.9m shares apiece at a price of 68.29p on 19 May. Granted, the share price had quadrupled in less than a year and at the time IQE looked overbought, but on the other hand it seemed a curious time to part with such a substantial portion of their shareholdings if IQE's future looked so bright.
Hi Luthrin,
Thanks very much for your excellent post on IQE. I've just watched the two videos you mentioned, which are at:
http://www.piworld.co.uk/2016/01/18/iqe-investor-presentation-mello-18th-january-2016/
https://www.youtube.com/watch?v=t-EihVaxIyA
Watching them has greatly improved my understanding of IQE's business. I would strongly recommend them to anyone considering investing in IQE's shares. I particularly liked the first video, which is a Mello presentation by Phillip Rasmussen, IQE's Group Finance Director, who I think manages to explain highly complex technical issues in ways that can be understood by people without scientific backgrounds. It's an hour long, but I learnt a great deal in that time about both IQE and the electronics industry in general.
Hi Luthrin,
You remarked that: "I bought some more IQE shares at the beginning of this month, but not as many as I would have done had Dr Howard Williams (IQE's Operations Director) and Rasmussen himself not sold 1.9m shares apiece at a price of 68.29p on 19 May. Granted, the share price had quadrupled in less than a year and at the time IQE looked overbought, but on the other hand it seemed a curious time to part with such a substantial portion of their shareholdings if IQE's future looked so bright."
I agree it does seems curious. However, Rasmussen did say in the Mello video you linked to that he is risk-averse by nature. Perhaps he and Williams did not want to have too many of their investment eggs in the same basket as their jobs.
Thanks for the IQE article Paul. In answer to your request for comments, I would recommend having a look at the III board if you have not already done so as there appears to be at least one regular poster there who appears to have intimate knowledge of the company and good knowledge of its sector. Like you, I am not a typical technology investor but IQE appears to be a rarity as it is a rapigly growing, jam-today technology company which, even after today's share price rise, is not ridiculously valued. I find it impressive that the company appears to be a component supplier for multiple US companies which, themselves, are growing rapidly and is serving multiple sectors.
RE. IQE (LON:IQE) There is additional bit of discussion on the thread, " IQE - doing what Minervini predicts " , with very useful insights from Jane Bolacha.
IQE....on Aim so many instits cant buy and I notice the directors sold 4 million in May. A real punt I think so I am in lol. I think tech is the growth area for the next ten years with amazing inventions in phones etc and robotics and all the equipment going to make fortunes. Nasdaq going to 30,000 in 10 years...its just over 6,000 now....suggest some commentators I follow.
But if you are going to punt in dangerous Aim stuff like this you also have to look at oil and resource stocks ......ukog is up nearly 500% in just over a month on a huge possible find and although I would not suggest buying this after such a rise its probably no less risky than IQE in these markets
Hoping you get round to United Carpets (LON:UCG). I've held for a few months, mainly on a decent dividend and the continued commitment to paying out. The figures aren't particularly exciting, though after the closure of 4 stores, the like-for-like is up. But management seem quite downbeat about the immediate future.
Hi samholloway,
Yes, I've now added a brief section on United Carpets (LON:UCG) into the main article above.
Regards, Paul.
I don't like eg Solutions (LON:EGS). Management has a history of greed and in my experience this often leads to share price destruction (Vislink comes to mind). Shame as the business looks decent.
Hi Paul,
I have had IQE (LON:IQE) on my watchlist and also took the plunge just after the opening today on the basis of the bullish update and equally bullish comments in the brokers report I read. They seem to be indicating that the future potential is substantial so, in my estimation it seems to be well worth the risk of taking a punt. The company is obviously dependent on a small number of customers with high volume orders which may indicate a relatively short lifecycle for their products and the need for incremental investments on their part to develop their technology. I would not describe this as a buy and forget share for the long term but on a two year horizon it could prove interesting.
Many thanks to you for your insightful analysis on this and other shares which you cover.
Andy
Welcome to the IQE party Paul. I think it could be quite rewarding.
I've been developing my holdings in semi conductors generally as we do seem to be in a strong uptrend so it's good to be able to back a British technology company that looks ready to reap the rewards of a lot of R+D work.
Hi Paul,
Having also recently finished Minervini's book, I also saw this morning as an opportunity to jump on board a share which seems to pass his tests. Historically I would likewise have been very nervous buying this morning, but now I follow another of his rules which is a tight stop loss on investments/trades like this. I strictly apply an initial stop- often guaranteed- at half my average annual gain (11% for me, though maybe half your average gain might be a bit high!) and review as the price moves. This basically helps me sleep at night and saves me from myself. Where the potential rewards are very high it feels like I am defying probability theory!
Hi Paul, any chance you would have an interest in reporting on Safecharge's (LON:SCH) trading update today? On its face it is a mild profit warning and that has been the market reaction today, although perhaps a bit more than mild. The company has previous form warning and then ultimately meeting and/or exceeding expectations. I continue to hold as I think that may well happen again. Many thanks in advance.
Hi willhampson,
I don't usually cover financials, and am busy with other companies today, so I'll have to disappoint you on SafeCharge International (LON:SCH) . Also, I dislike payment processing companies. I cannot understand why they exist? The only credible explanation seems to be to disguise gambling, and other similar payments, which would otherwise not be able to get through the conventional banking system. That's too risky for me. I'm not sure whether that applies to SCH or not, but personally I just keep away from the whole sector.
Regards, Paul.
Hello Paul, I was interested to hear that you dislike payment companies and was wondering if you would include the likes of PayPal and VISA as payment companies? The reason I ask is because one my favourite fund managers, Terry Smith, regards such companies as having exceptionally low risk for investors for his usual reasons which include high ROCE and large moat. They are of course an entirely different ballpark from Safecharge because of their size but would be interested in any comments.
Hi Peterthegreat,
I was interested to hear that you dislike payment companies and was wondering if you would include the likes of PayPal and VISA as payment companies?
Sorry, I should have made myself clearer. I only meant that I don't like the smaller players in the payments sector, where I struggle to see a reason why they exist. Clearly VISA & PayPal are big, and have very good reasons to exist, as they're part of the main infrastructure.
Whereas smaller players often seem to exist in order to facilitate gambling transactions that would otherwise be blocked by the main payment systems, and are often dependent on one or two large clients. Those are far more risky than people realise, I reckon.
Regards, Paul.
Most card payment transactions ultimately flow through Visa or Mastercard (or Amex or Discover): they're the glue that connects the merchants to the cardholder's bank. So if I stick my card in a terminal in Thailand then that is sent to a payments process or acquirer who routes it to the appropriate scheme (e.g. Visa or Mastercard) who routes it to my bank.
May banks actually outsource their payments processing to processors and there are a vast array of these companies across the payments ecosystem, many of whom do opaque things, much of which is valuable. Safecharge seem to fit into the merchant processing arena - so they're providing services to retailers to allow them to take payments and providing data to help them to manage their customers - they're exploiting the ever-present omni-channel trope.
When I looked at SafeCharge International (LON:SCH) a while ago I was quite impressed but it's a Teddy Sagi vehicle so a decision to invest is very much a decision about him. I'm not ever too keen on businesses with single controlling interests.
In passing, as of January next year there's a whole new retail payment solution being rolled out on the back of the new EU Second Payments Services Directive (PSD2) which will be in competition with the card networks - so I'd recommend any investment in payment companies is predated by some research around that and what it means.
timarr
Thanks for the reply Paul, that sounds reassuring. I don't hold any of the smaller payments companies and would agree that these are more risky.
Regards,
John
While they're not as risky as the gambling money laundering shops, PayPal seem to have very poor execution and are at risk of being atomised when the ebay lock-in (which allows them to keep the ebay business regardless of execution quality) expires in a few years. Visa are at risk of not handling the transition to cardless payments (can't imagine anyone still carrying plastic cards 10 or 20 years from now). They benefit from network effects now, but a lot of that is priced in.
Thanks cig for your comments on PayPal and VISA. I will review them in the light of these comments and will also keep an eye out to make sure that Terry Smith's funds continue to hold them.
Hi Paul,
Many thanks for your response. Always interesting to hear other people's view. My personal view is that entities like Safecharge play a useful role in the crowded, but in demand, payment system. I see that Paysafe (LON:PAYS) had an offer confirmed this morning, which follows that of Worldpay earlier this month. Thank you again.
Hi willhampson,
Looks like I've missed a trick, by not looking at payment companies, as you suggest, given the potential bid for Paysafe (LON:PAYS) announced today, and the one for Worldpay.
Regards, Paul.
I made a moderate gain from SCH last year but observed that their growth has started to stagnate a bit - the word 'solid' in respect of growth in my view underlines this for me. I consider that "the revenue growth to maturity from these long-term Tier 1 clients is taking slightly longer than anticipated" is a mild trading warning with the potential to get worse - it's all very well having an encouraging pipeline, but if this doesn't convert then they aren't going to benefit.
Hi Paul......thanks for your comprehensive and informative input in general, and this post in particular.....very interesting as I had a look at IQE a few days ago and decided to give it a miss as this sector, (semiconductors) is very small, not much choice and not great value in the UK. Just take a look at what's happening on the Nasdaq in recent months. I agree with you and I think this specific sector is going to take off for various reasons...AI, Blockchhain and Cryptocurrencies, Information, Big Data and the Cloud, Driverless cars, Industrial and Manufacturing processes and last, but not least, the nascent IoT! So I'm focusing on this sector at the moment on the Nasdaq...looks like it could be a lot of fun.
jim.
I thought the update from Science in Sport was good although the strong growth rate is probably baked into the share price and still burning a fair bit of cash.
Regards
Andrew
I would certainly agree with cholertonandrew in the first post on this board of today in relation to Science in Sport. I would highlight today's statement that "Sales increased 28% to £8.27 million in the six months to 30 June 2017 compared with the same period for the previous year (H1 2016: £6.48 million)" with the additional statement that "revenues are expected to accelerate in the second half of the year". That sounds pretty positive to me. However, perhaps the most interesting news to me is that the company expects to lauch "a novel immunity product" in August 2017, thereby opening up a new market sector (health foods) for itself. Whilst I am sure this immunity product is likely to be quite low tech, the company's most senior management have pharma industry backgrounds and should know how to market it. I also like small companies genuinely addressing global markets as I have found from experience that they seem to do well.