Small Cap Value Report (Thu 20 July 2023) - CBOX, LOOK, PMP, FAN, PDG, FSTA, FNX

Good morning from Paul & Graham.
Today's report is now finished.
Quick comments -
SKY News said last night that Cake Box Holdings (LON:CBOX) has received a low-premium 160p bid approach from an Australian cheesecake company, so it will be interesting to see if that's true or not (it usually is with SKY, who for some unknown reason has now become the pre-RNS go to place to leak news). The founders probably have enough shares to block this, so it would need to be an agreed bid. There have been too many slip-ups (being polite about it) from CBOX, so even though it looks an interesting growth company, personally I wouldn't lose any sleep if it went private, because I don't trust management.
UPDATE at 09:50 - no RNS from CBOX as yet, so it's not clear what's going on. Perhaps SKY can update us?! Share price up 5% to 158p.
UPDATE at 10:30 - CBOX has rejected the bid approach, issued at 10:00, here's the full text -
Response to Press Speculation
The Company notes the recent press speculation.
The Company confirms that it received an unsolicited approach from River Capital to acquire the entire issued and to be issued share capital of the Company (the "Indicative Approach"). The Indicative Approach was made in early June and with an indicative price of 160 pence a share.
The Board unequivocally rejected the Indicative Approach as materially undervaluing the Company and no further discussions with River Capital have taken place.
This announcement has been made without the consent of River Capital.
Paul's view - pretty much as suspected, the controlling shareholders are not interested in selling out at 160p. I think this rather strange approach (why was it leaked, and by whom?) seems mildly positive for the shares. At least shareholders now have some validation of the current price being seen as attractive to a potential bidder. That's probably why it was leaked.
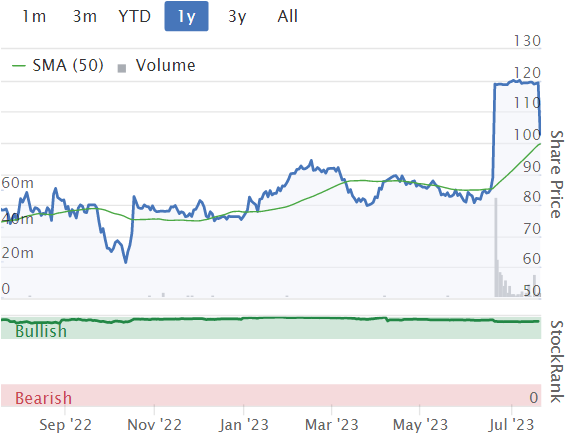
Lookers (LON:LOOK) - many thanks to davidallen77 for flagging in the reader comments below that it looks as if the Canadian takeover deal might be off - because it's been announced that 19.2% shareholder Cinch has switched sides, and says it will now vote against the deal. This was a strange situation, and I've mentioned here a couple of times before that I thought banking the bid premium at c.118-119p looked the safest option. What was strange, was that insitutional shareholders who had given undertakings to support the deal, were then selling in the market. I've not seen that before, and it made me think that deal risk looked high. So let's see what happens next! Expect a fall in share price today though, I imagine. Upside possibility might be if an alternative bidder appears at a higher price perhaps? Who knows!
Update at 09:48 - LOOK share price currently down 14% to 102p -
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
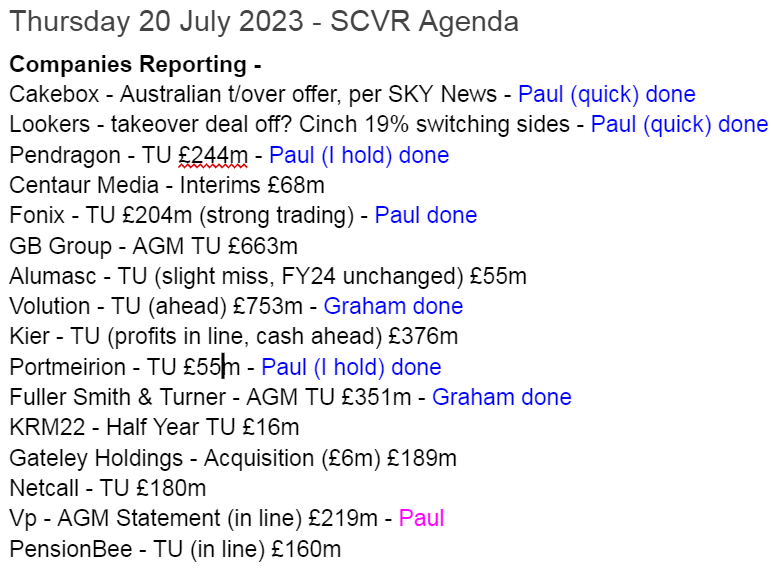
Here's the list of today's announcements, which we'll pick the most significant from (we can't cover everything, as there's loads!) -
Summaries of main sections below
Portmeirion (LON:PMP) - Down 28% to 285p (£40m) - H1 Trading Update - Paul - AMBER
A fairly tame sounding update from this pottery maker, but the "significantly below" sentence is the tip of the iceberg, with broker notes revealing the full scale of the damage - profit forecasts slashed by 68%. Clearly disappointing, and has been badly handled by the company. So I've shifted from green to AMBER, and that's probably generous in the short term. Longer term, earnings should recover, and it's soundly financed, so not a disaster.
Volution (LON:FAN) - up 0.4% to 384p (£758m) - Pre-close trading update - Graham - GREEN
This large ventilation business gets the thumbs up from me. Sturdy refurbishment demand and pricing discipline are enabling it to keep organic revenue growth at 5% and adjusted operating margin over 20%. I like its style of communication, which appears trustworthy.
Pendragon (LON:PDG) - Up 1% to 17.5p (£245m) - H1 Trading Update - Paul - GREEN
H1 profit up 9%, and in line with expectations outlook comments for FY 12/2023. High used car prices are helping margin, with tight used vehicle supply expected to continue for the foreseeable future. Looks excellent value to me, so I'm happy to continue holding. Takeover bid might resurface, who knows?!
Fuller Smith & Turner (LON:FSTA) - up 3% to 600p (£366m? - see below) - AGM Statement - Graham - GREEN
This family-controlled pub and hotel group reports a bounce in like-for-like sales as workers return to offices in London. I study the confusing share structure and conclude that the company might be cheaper than it first appears. A fresh buyback has been announced.
Fonix Mobile (LON:FNX) - Up 1% to 208p (£206m) - FY 6/2023 Trading Update - Paul - GREEN
One of my favourite small caps, but it usually looks too expensive. Giving it the once over today, with a good FY 6/2023 update, and Finncap raising forecasts about 5%, I think the current valuation does (just about) stack up. Tantalising talk about further international expansion also gets me excited enough to consider a purchase here.
Portmeirion (LON:PMP) (Paul holds)
Down 28% to 285p (£40m) - H1 Trading Update - Paul - AMBER
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, updates on trading for the six months to 30 June 2023.
Sales for our first, traditionally quieter half, are expected to be £44 million, down 3% on the same period last year.
The last update which I covered here on 23 May 2023, said H1 sales were expected to match last year. So today saying H1 sales will be down 3%, is a small deterioration, although given that it’s happened in the last few weeks only, that could be a more worrying trend, if it continues.
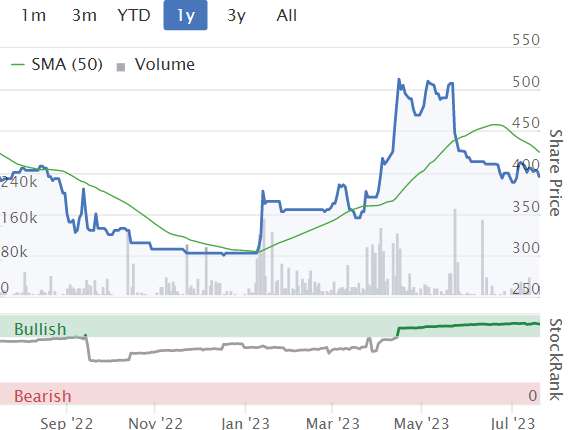
The 23 May update did say that it had seen “some increased caution” from US customers in recent weeks. This spooked the market, understandably, and triggered a significant downward move in the share price in the last couple of months, as you can see below -
Seasonality - H1 is the weak half year - almost all the profit is made in H2, hence at this stage, H2 outlook is more important than H1 results. The same cyclicality happens every year. It’s because a key range is the seasonal “Christmas Tree”, and other products bought as gifts at Christmas, which obviously falls in H2.
Other comments in the update all seem a bit confusing - some markets are OK, others growing, others challenging, so let’s cut to the chase…
FY 12/2023 outlook - oh dear, this is disappointing -
In terms of the full year outlook, it is challenging to assess how long the North America caution amongst our retailer customers will endure and whilst we note the encouraging end customer sell through data and our strong Christmas order book, the Board believes that it is prudent to assume that this caution will continue through the second half resulting in the Group's sales being below and profits for FY23 being significantly below current market consensus.
Broker updates - helpfully, both Singers and Shore Capital update us today (via Research Tree). The downgrades are pretty hideous, and this is another case where the tone of the company’s update (which doesn’t sound too bad) seems to be trying to gloss over the harsh reality. I think whoever writes these updates from PMP needs to be transferred to other duties. I would prefer a much more direct, and clear type of update that just tells it like it is, warts & all. If it’s bad, it’s bad, and we’re going to find out from the broker updates within a few minutes anyway. So where’s the benefit to putting a positive spin on the bad news in the RNS? There isn’t any benefit, it just leaves investors feeling temporarily misled, and opening bell buyers who haven't seen the broker notes are getting fleeced!
FY 12/2023 forecast EPS (from Singers) is now only 16.7p (down from 46.8p in 2022). The StockReport shows a broker consensus of 51.5p, so today’s reduction to only 16.7p is a huge 68% drop in forecast profit for this year. That doesn’t tie in at all with the tone of today’s trading update, so I’m rapidly losing trust in management here, I’m afraid.
On reading the RNS, I thought to myself, this is quite mild, maybe I’ll put in a buy order? On reading the broker update, I jettisoned any idea about buying more, because this is a major change in forecast profits, and hence the company’s valuation. Never buy on a profit warning without first seeing broker updates!
If it is just a customer de-stocking issue, which the RNS suggests, then profit could rebound in 2024. Singers has 38.9p pencilled in for 2024, which could support a share price of say 300-500p, depending on market sentiment at the time.
Shore Capital has a slower rebound in 2024, at 33.4p, with a very similar 2023 forecast of 16.8p.
Remember that the broker forecasts ARE the company’s forecasts, as John MacArthur of Tracsis (LON:TRCS) told us at a brilliant presentation he gave years ago to an investor group I organised in Brighton.
As an amusing aside, in a very recent online webinar (I won’t mention the company name) the CFO started saying, “Our forecasts have been adjusted…. errrr, I mean Finncap’s forecasts have been adjusted….”, which reinforces my point!
Inventory levels - this was a previous concern of mine, but PMP says today it has successfully reduced inventories, and expect to further reduce by end 2023. Good, but I’d like to see the figures in due course to judge properly.
Paul’s opinion - as you can probably tell, I’m not happy with the way this has been handled. It feels like we’ve had the wool pulled over our eyes somewhat, with PMP management very reluctant to deliver bad news that investors needed to hear.
So this is clearly a company where selling on the first sniff of bad news on 23 May was the best strategy, I’ll bear that in mind for the future, and not give the company the benefit of the doubt again.
My view now is that the share price has taken two hits, first from the May update revealing the first sign of trouble, and again today with the company belatedly revealing a large drop in forecasts. Yes, some of that is due to operational gearing, but the forecasting needs to be improved, and communication with the market more timely. So I’m not happy with this.
On balance, I’m neither a buyer (need to let the dust settle first, and think I’d want a lower price than the current 280p), nor a seller (as it’s fundamentally a fairly decent business, when the economy is operating normally, so earnings should recover in due course).
There’s always an outside chance of a takeover bid from overseas too, which we’re seeing a lot at the moment, hence why I’d rather just park my (smallish) position in PMP into a dusty corner of my portfolio and forget about it for a while, with the possibility of a nice surprise one morning that you can only benefit from if you actually hold the share (rather than sitting on the sidelines waiting for the market price to bottom out).
I’ve now been hit with 2 profit warnings this week from my top 20 value/GARP picks for 2023, which sounds bad. However the total 20 shares have barely moved, showing the value of a portfolio approach - now being up 4% YTD, as opposed to up 6% a week ago. In this type of macro situation, we just have to expect a few profit warnings. But we’ll also get some out-performers, and some premium takeover bids. So small cap investing is always swings & roundabouts, and not for nervous types.
Profit warnings happen, and is part of the process of owning small to mid cap shares. The winners usually outweigh the inevitable losers. And if it’s a decent, soundly financed business, we don’t have to panic sell anyway, it can just go into the long-term portfolio for an eventual recovery.
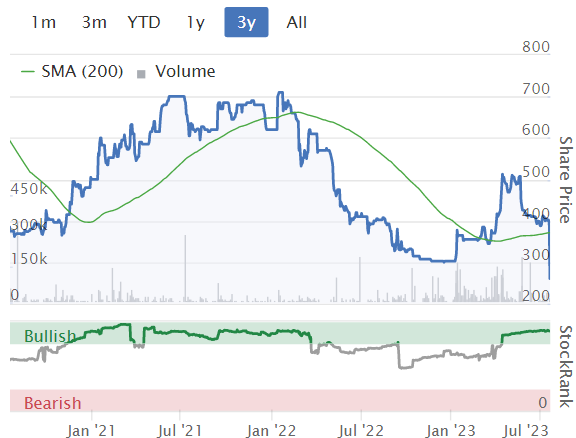
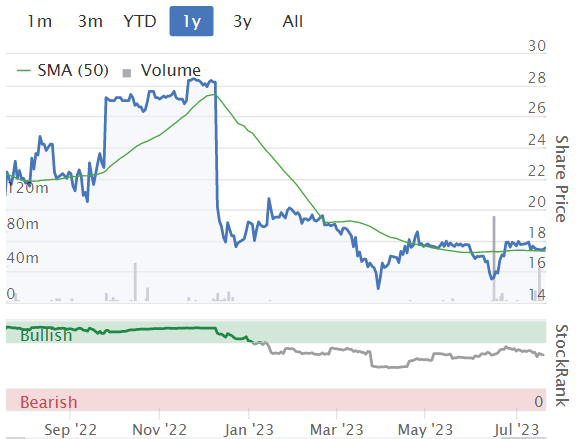
It previously found support around 300p, but that was when they were telling us that trading was going well -
Pendragon (LON:PDG) (Paul holds)
Up 1% to 17.5p (£245m) - H1 Trading Update - Paul - GREEN
Pendragon PLC (the "Group") today provides a post-close trading update covering the period from 1 January 2023 to 30 June 2023 and its outlook for the remainder of the year. Unless otherwise stated, figures quoted in this statement are for the six months ended 30 June 2023 and the comparative period being the six months ended 30 June 2022.
Interesting goings-on today with the Canadian bid for Lookers (LON:LOOK) apparently falling through. I take a close interest in the motor dealers sector, as it’s deep value, with low PERs, and usually very nice freehold property asset backing too. For the required disclosure, I currently hold PDG (bought recently on the Odey dip) and VTU shares personally.
This sounds encouraging -
The Group delivered another robust performance in the first half of FY23, with growth in gross profit more than offsetting the underlying pressures of interest rate rises and ongoing cost inflation.
As a result, the Group expects to report a c.9% increase in underlying profit before tax to c.£36.5m for the first half of FY23 (H1 FY22: £33.5m).
Net cash of £40m at June 2023 was much better than net debt of £23m at Dec 2022. Although bear in mind the listed car dealers have large working capital, with big fluctuations possible in inventories, trade creditors, and vehicle stocking loans. So I would expect net cash/debt to vary a lot. Even so, with interest rates higher, moving into net cash should save on finance costs. Note that the finance costs line in the forecasts has risen a fair bit, so stocking loans could be a nasty headwind, requiring effort to reduce inventories maybe, to mitigate? We need to be told the average daily net cash/debt (for all companies), as period end snapshots are of limited use, and are easy to manipulate.
Outlook - is in line for FY 12/2023, and interesting comments about used car supply remaining tight - this has helped boost profits at car dealers remember, so it’s a good thing! -
There were encouraging signs of improvement in production and supply of new vehicles during the first half, although used vehicle supply is expected to remain tight for the foreseeable future. The Board remains mindful of the influence that both high inflation and increased interest rates have on consumer sentiment, with the potential for these factors to impact demand in the second half.
However, the Board believes Pendragon's strategy, market-leading proposition and mix of business models means it remains resilient in the face of these challenges and it continues to expect to deliver group underlying profit before tax in line with Board expectations.
Paul’s opinion - looks fine to me. The valuation here is really striking, the StockReport has a fwd PER of only 5.7, so to get an in line update on such a low rating, is pleasing.
PDG also has a software division, which makes it potentially more interesting, say if that were to be hived off at a good valuation maybe?
Pendragon did have problems in the past, but I can’t remember the specifics, it will be in our archive.
PDG got up to about 29p on takeover talks with 28% shareholder Hedin Mobility Group AB late last year, so maybe bid interest might resurface? The whole sector is clearly in play, so I think it’s a nice idea to own several of them, so that you’re more likely to catch a premium-priced takeover bid.
Who knows how the macro position will play out? New cars are not really big ticket items any more, as so many people lease them. New car production seems to be gradually returning to normal, leaving a 2-3 year shortage of used cars, hence nice margins for a while yet.
Threats from EVs? Maybe, they need a lot less servicing apparently. Although more recently, I'm hearing that customers are pushing back, and don't want EVs so much, having seen how massively the refuelling cost of electricity can vary due to unexpected macro factors. Whereas the end user price of petrol/diesel was a lot less volatile (because most of the price is tax). Range anxiety is still a big issue, although likely to be resolved as battery tech improves.
At this valuation, I’m happy to stick with PDG indefinitely - why on earth would anyone be selling at this bombed out price?
Also, a lot of the VC-backed new entrants (online) will be running out of cash and retrenching, or going bust. So less competition for the traditional dealers like PDG.
Relationships with manufacturers is another complicated area.
Let’s see what happens, but overall I reckon risk:reward looks pretty good on PDG shares at 17.5p, within a portfolio where you know one or two are bound to go wrong, but hopefully the winners should mop up any such losses most of the time.
Fonix Mobile (LON:FNX)
Up 1% to 208p (£206m) - FY 6/2023 Trading Update - Paul - GREEN
Fonix Mobile plc, the mobile payments and messaging provider, is pleased to provide an update on trading for the year ended 30 June 2023 (the "Year").
This is a nice company, in a good profitable niche, with very sticky repeating revenues. It processes the payments for TV shows where viewers vote, or make charitable donations mainly by phone I think.
Checking our previous comments this year, the quick version is (for background) -
25 Jan 2023 - 219p - GREEN - solid H1 12/2022 TU. Strong outlook. High valuation justified.
3 Mar 2023 - 237p - AMBER - ITV partnership extended. Good, but too expensive at 26x PER.
17/3/2023 - 195p - GREEN - good H1 results , strong pipeline. Tempting to buy recent dip.
So as you can see, I like the company a lot, but quibbled over valuation at the peak.
On to today’s FY 6/2023 update -
Strong trading momentum continues with significant growth in international markets
Revenue & profit have grown, being “marginally ahead of market expectations”
Adj EBITDA up 13% to £11.6m. I have no idea why the company scores an own goal by reporting adj EBITDA, when actually adj PBT is very similar, at £11.0m, whereas many investors (including me) assume that EBITDA is an artificial, inflated number, but in this case it’s not! Most odd.
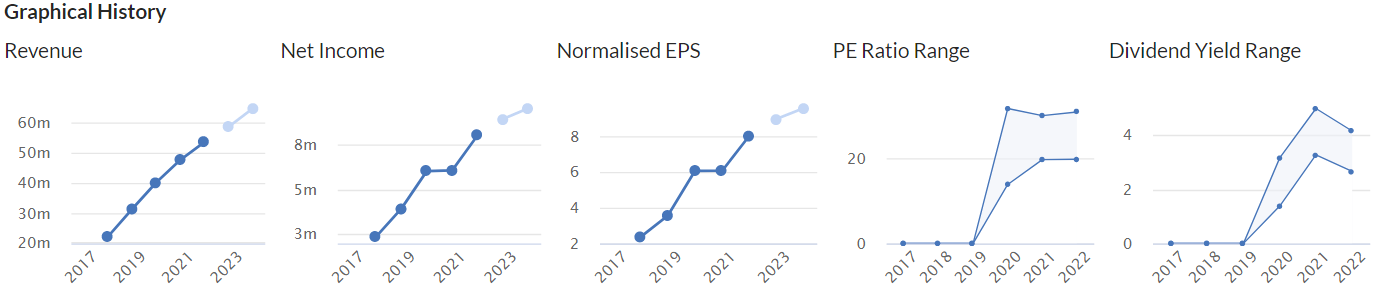
Finncap (many thanks!) puts through a c.5% uplift today, and now says 8.9p adj EPS for FY 6/2023, so a PER of 23.4x - not cheap, but remember FNX has such a reliable track record - it’s increased profit & EPS by 50% in the last 3 years, despite the pandemic & cost of living crisis - and the profit is also real cashflow, which is mostly paid out in growing divis (policy is 75% of earnings become divis).
If it can keep that growth going, then FNX shares should grow into the valuation.
There’s no dilution either, and all growth seems to be organic.
There are lots of very nice qualities about this business, I like it very much.
“100% retention of all significant customers” - very impressive. Customers use Fonix on the basis of: if it ain’t broke, don’t fix it, so I think it has a decent moat.
Confident outlook -
With high levels of repeating revenue, a strong run-rate entering the new financial year, recent tier 1 wins in the UK and Ireland as well as a growing pipeline of client prospects across all sectors and markets, the Board continues to be confident in the growth potential for Fonix going into FY24 and beyond.
"We are delighted to announce another year of strong profitable growth. We started the financial year with an ambition to be a market leader in a second territory within two years of launch and have achieved that feat in the first year. In recent months, we have announced significant new contract wins in both the UK and Ireland, underpinning our growth expectations for the year ahead and furthering our aspiration to be the world's leading provider of interactive services.
As well as clear growth opportunities in our existing markets, we now also have a proven template for success in international markets, which we will look to replicate and announce as and when other new territories are making a meaningful contribution to our growth."
Paul’s opinion - an intriguing hint above about further international growth - I wonder which countries they have in mind?
Based on continuing good performance, and possible overseas growth, I have to give FNX a thumbs up again, so am happy to stay at GREEN.
Yes it’s a little pricey, but it’s very high quality.
My only potential worry is over technological change. Will this activity become old hat in the future maybe? No signs of that now though.
An October 2020 pandemic float, this is a rare one that has actually worked out well! -
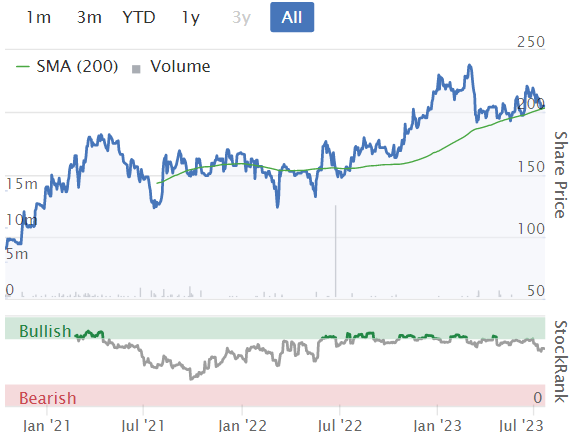
A terrific track record here -
Graham’s Section:
Volution (LON:FAN)
Share price: 384p (+0.4%)
Market cap: £758m
Volution Group plc ("Volution" or "the Group" or "the Company", LSE: FAN), a leading international designer and manufacturer of energy efficient indoor air quality solutions, today releases a scheduled Pre-close Trading Update for the financial year ending 31 July 2023…
This is a substantial international company with 20 brands.
I’ve remarked previously that I like the KPIs it focuses on, and thought the valuation might be interesting to investors after the sell-off that lasted from mid-2021 to mid-2022. The shares fell by around 50%, peak to trough!
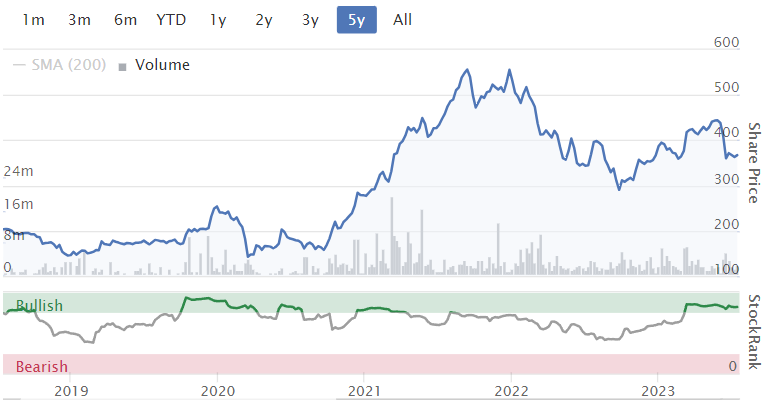
Key points from today’s update:
Adjusted EPS will be towards the top end of current market forecasts. The consensus forecast is 24.4p, while the top end of the range is 25.6p.
Organic revenue growth at constant FX is around 5%
(Adjusted) operating margin maintained c. 21%.
Latest acquisition (£8.7m) due to complete in August 2023.
One slight weakness is the organic revenue growth, which remains below the level I’m looking for in this inflationary environment. The company cites “a challenging macroeconomic backdrop in which the rapid rise in interest rates has adversely impacted new build construction levels and consumer confidence”. There is no arguing against that - new build construction is under some pressure at the moment (see our comments on Springfield Properties (LON:SPR) yesterday)..
Interestingly, Volution says that it’s growing faster in the UK than it is in other geographies, thanks to demand for refurbishment RMI (repairs, maintenance and installation), while new build UK demand is underpinned by regulations. Continental Europe is weaker, particularly Germany and the Nordics, and revenue growth has slowed down in Australasia.
The CEO explains it like this:
Whilst higher interest rates, leading to higher mortgage rates, are dampening new build construction demand, RMI, which accounts for approximately 70% of Group revenue, has proved resilient enabling us to deliver Group organic growth of c.5%.
Op. Margin is maintained thanks to “pricing discipline along with robust cost control, value engineering initiatives and good factory efficiency”.
Balance sheet should still be fine. Net debt/EBITDA below 1.0x would in general be considered very low, so the company might continue making acquisitions confidently for the time being.
Graham’s view
Once again I reach the end of a Volution RNS and I feel better informed, without having suffered excessive jargon or any attempts to obfuscate.
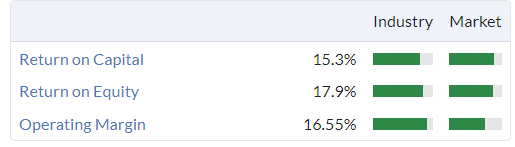
As I said before, I like the company’s simple focus on operating margin, and I’m impressed that it continues to get that 20%+ figure it demands. My impression as an outsider is that this must be a disciplined, well-organised company.
Their “actual” operating margin is a little lower than 20%, but overall they have a good track record of quality earnings. Nothing spectacular, but very solid:
There is no founder at the heart of this story who has led the company from its very beginnings, and I don’t think any members of the management team have truly enormous stakes in the business, so that could perhaps be seen as a bear point.
However, I note that their CEO has been with the business since 2008 and has been instrumental in creating it in current form. Based on the director dealings he looks like a seller of shares rather than a buyer, but he does still own over 1% of the company. I would treat him as a “quasi-founder” - not the person who invented the business, but the person who invented it in its current form!
I’ll give this stock the thumbs up because I think there is a lot more to like about it than to dislike, and the rating is reasonable (PER 15x). Worthy of a second look!
Fuller Smith & Turner (LON:FSTA)
Share price: 600p (+3%)
Market cap: £366m (? - see below)
Fuller, Smith & Turner P.L.C. (“Fuller’s” or “the Company”), the premium pubs and hotels business, provides the following trading statement in advance of the Company's Annual General Meeting…
This sounds very good: like-for-like sales up 15.1%. It’s related to the post-Covid recovery: ”Increased tourism and events, along with workers returning to their offices, have contributed to like for like sales growth of 17.9% in our City and Central London sites.”
Buybacks - since business is going well, the company plans to buy back one million “A” shares (these are the shares listed on the stock market). It just finished a buyback of the same size whose purpose was to settle employee bonus schemes, but this buyback seems to be entirely discretionary.
Speaking of the “A” shares, I’ve had to dig deep into the footnotes of the company’s annual report, to find out about the share structure. The company has three classes of ordinary shares: A, B and C!
This goes back to the family roots of the business, as the “B” and “C” are held by founding families.
Let me try to summarise what I’ve learned. I think there are major implications for how we value the company:
A Shares - listed on the stock market. 39 million shares outstanding. Collects the normal dividend.
B Shares - not listed. Held by the families. 85 million shares outstanding. Each of these shares gets one vote but only one tenth of the dividend of the other share types.
C Shares - not listed. Held by the families. 13.5 million shares. Collects the normal dividend.
Total number of shares and total number of votes at meetings: around 137 million.
Things can get very confusing when you have shares classes with different voting rights and dividend rights.
For example, how do we calculate something simple like the market cap of this company? I can find several different answers, depending on which service I use!
What I would do to calculate market cap is to start with the FSTA share price. It’s the only share price that’s available, as the others aren’t listed.
I would then add the number of A shares and C shares together. But I would only add one tenth of the number of B shares, as those only collect one tenth of the dividend.
This gives a notional “share count” of 61 million shares. But if you ask anyone else, you will probably get a different answer!
At £6 per “A” share, I am therefore happy to consider Fuller’s as having a “market cap” of £366 million.
The point of the structure is that the families continue to control the company. The “B” and “C” shares together have over 70% of votes. Economically, however, they collect only about a third of the total dividend payments from the company.
Shareholders of “B” and “C” are restricted on selling their shares and the company rules imply that they should only transfer their shares to other “B” and “C” shareholders, or to certain family members, etc. So the families who founded these pubs and hotels should continue to own and control them for the long-term.
Let’s turn back to today’s AGM statement.
CEO comment excerpt:
…The hard work of our teams, coupled with London’s continued recovery, is driving strong sales momentum.
Our comprehensive strategy, combined with the investments we have made in our people, infrastructure, marketing and estate, is delivering excellent results; and while cost inflation and the ongoing train and tube strikes continue to present challenges, we are pleased with our progress.
Graham’s view
I like family-run businesses which are run for long-term dividends. This one has paid a dividend every year since 1992 (we must have some subscribers who weren’t born then!) with the sole exception of Covid-impacted 2020, when pubs were shut.
I also think the market cap may be a source of confusion, which could cause the shares to be mispriced. It may not be as expensive as it looks, after you factor in that the B shareholders only get one tenth of the dividends.
With what looks like a discretionary buyback looming, maybe the families are hoping to reduce their liability to pay out chunky dividends to the A shareholders?
I am going to give this one the thumbs up.
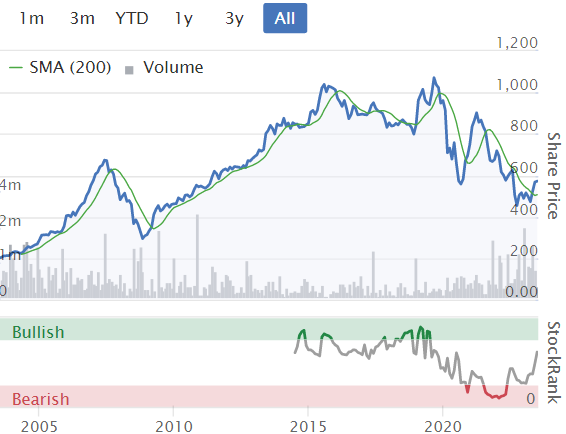
Long-term chart -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Hargreaves Services and general
Very strange movement looks like the market just got squeezed on stock .
In the soace of 15 min big spike up with squeeze on stock, couldn’t buy many but could sell a lot .
My feeling is that there is a lot of money coming back into the small cap market that has been sat on the sidelines even a bit of FOMO
My quality holdings that haven’t moved anywhere in past 6 months but drifted all getting quick and strong upward bounces .
Wynnstay, Somero , now Hargreaves, Equals all have strong moves .
Those that have stayed fully invested will see these bounces .
Those say on cash will have to watch and try to tune the market .
I actually sold 10% of my Hargreaves holding at 4.80 level , My total holding by value still higher than at 9am this morning .
Sone strong moves I think a few big players are worried their are sat on the sidelines and the tide is turning ??
Hargreaves Services (LON:HSP)
It was rising steadily all day TBF and then spiked up near the close on much higher than normal volume even after the general market turned down. Something afoot maybe? or as you say just market sentiment changing for some stocks that could be seen as undervalued ?
The sudden rise in HSP could be caused by any of the reasons suggested here but my bet would be that it is connected with the German subsidiary - either a long awaited return of loans and retained profits to HSP or better still a potential sale of the business.
Hi planetx,
I too have been keeping an eye on HSP, I didn't have much cash left in my 'stage1' portfolio (I was waiting for another leg down to add to positions), so didn't act over the past few days. They have results due out next week, and I was willing to take a punt on it being positive (based on recent RNSs and their latest webinar). I checked today, and decided I had probably missed the boat !
(edit: i am not one of the few big players... just clarifying !)
not sure you have “missed the boat” Christopher Mills of Haywood Capital has a break up value around £7.00
I would have to sell something, and if my conviction was not strong enough on the price 10% lower, then I shouldn't act now. If the price had dropped by the same amount, I would have acted. Probably wrong, but my discipline is getting better !
Buying pre earnings (26th July) risky. As a chartist would need to hold above 465 for more than a couple of days to be on the radar.
A takeaway from recent chats is that don't get too carried away with story's and management - DYOR can mean your trying to convince yourself rather than being contrarian.
The price and the chart tells the story. But if think some great opportunity and lock away in the SIPP then fair dues - my "coffee can" is rather large and rather worthless.
Regarding Fonix Mobile (LON:FNX), I note that voting for the Eurovision song contest was by app only and I wonder how much more of this we are going to see. For this reason I took a heavy top slice a month or two ago.
If I was Fonix I'd design a bespoke app for each poll as an alternative to texting - you can scrape data maybe with something like this too perhaps?
Jim
Pensionbee (LON:PBEE) - Invested customers reached 211k on 30 June 23, with 28k added over H1-23 (+15%) and 52k y-o-y (+33%). Assets Under Administration was up £678m over H1 (+22% over 6m, +38% y-o-y), reaching £3.7bn, with £469m added from net client inflows and £210m from positive investment performance.
This progress is on track to meet our previous growth targets and confirms that PensionBee continues to gain market share in the £700bn UK transferable pensions market (it is aiming for a 2% share of this market i.e., 1m customers, in the next 5-10 years).
They remain on track to be adjusted EBITDA (H1’22: -£15m; H1-23, -£8m) positive in FY24, a target set back at the 2021 IPO.
Our forecasts remain unchanged, as does our fundamental value of 150p per share which is now 100% above the current share price. Full note here: https://www.equitydevelopment....
Pensionbee (LON:PBEE)
Cheers for that - this one is starting to look semi interesting as they get closer towards being EBITDA positive - presumably even if growth in subcribers slows/stops one should expect that AUM would continue to grow as peeps ad into their pension over time. In theory one would guess the operation gearing could look very good here in a few years time if its mostly stuff done via automation. Does anyone here have a semi positive outlook ref this share. As its still obviously loss making for now i suspect most peeps may have looked at this one as being too risky? I am only keeping watching brief here - but will be intersting to see if they hoit targets or have growing pains.
Does anyone have views on this one ?
Graham reference your view on Fuller Smith & Turner (LON:FSTA) you might want to look at Young & Co's Brewery (LON:YNGN). These are the non voting shares and in my view Youngs is the pick of the listed pub companies. Below is my post from earlier today on the Paul Hill interview with Josh Northrop of Whitman AM.
I fully admit to bias.
"I hold Youngs non voting shares Young & Co's Brewery (LON:YNGN) . They carry all the benefits of the voting shares Young & Co's Brewery (LON:YNGA) except the right to vote at the AGM, or as Andrew Hollingworth, manager of VT Holland Advisors Equity Fund puts it the entitlement to tea and biscuits.
Young & Co's Brewery (LON:YNGN) trading at 875p, yield 2.65%, discount to NAV around 30%.
Voting shares Young & Co's Brewery (LON:YNGA) trading at 1229p, yield 1.83%, trading around NAV.
Seems a no brainer to me."
The local fullers near Bank station is absolutely heaving on Wed, Thrs and Fri. Takes hours to get a drink (well at least 5-10min) and you have to fight your way towards the bar. So, the 15.1% sales uplift is not surprising.
SOMERO
Having a good old bounce up to 350 thats a big weekly jump.
Kicking myself as I held a full position for so long then got sucked into the bear trap decline last week and reduced to rotate half into filtronic / trifast.
The tipping point to sell half was the weakness of USD so I cracked last week despite knowing its a great business with a huge dividend and a bid target .
Guess ultimately I got bored and twitchy and succumbed to the dopamine hit of trading out of one stock into another so have to learn that lesson.
Just goes to show you can read all about Warren Buffet and Charlie Munger but to sit and old for us amateur investors requires balls of steel in a tough market.
Having said that I dont like holding US companies right now .
Anyway just a tale that practicing what you preach is tough sometimes .
Having said that I dont like holding US companies right now
Interested to hear why. US companies are leading the world into a new technological revolution, potentially bigger than the internet. And we’re sitting here discussing the troubles of a teapot maker!
Definitely those areas are massively outside my “circle of competence”
I just think the US is totally screwed and the decades of printing frothy money ultimately has to catch up with it at some point.
When the point comes when the USD is not the worlds choice of currency as no one will want to hold dollars then it’s going to topple over .
AI. Whilst it’s coming is now the latest bandwagon everyone wants to jump aboard and if a company mentions AI they can expect a surge of interest and it’s the next big thing . That feels frothy .
I understand stock, bricks and mortar , forestry, hard assets and cash generation . That’s my circle of competence . Outside of that I have zero competitive advantage and am a seal in a sea of sharks .
Not a great place for a seal to be
My first chairman called me out in a board meeting once “your like a bloody northern pig farmer” and he hit it on the head .
Definitely the case that one should invest in what one knows. But you and I have both run companies and surely you can see the US ones are in better markets, geographically and thematically. Better to be an average company in a good market than a great one in a bad one. Better still, the US is packed with great companies in those better markets. My belief is that you don’t need competitive advantage, just some discernment. Then sit back and wait.
For full disclosure, the wait has been a long and painful one since Nov ‘21, thanks to interest rates. But this year has gone rather better thanks to the diversification.
I think you are correct for 99% of investors but my circumstances generally rule me out and my mindset definitely .
I’m quite non neurotypical and have a decent amount of time so I can do some what I might call “deep dive” investing in a very concentrated portfolio which I really enjoy .
For example Crestchic I had a very large holding in but I had built that confidence after three factory visits and seeing with my own eyes what was going on, I knew the business very well and recognised their growth and improvements.
IHT is also an over riding need so that again limits me to AIM and small caps .
USA markets past success built on the Alphabet / Facebook / Apple, well my non neurotypical brain I would rather poke my eyes out than invest in these companies with tax policies that gives us no tax for our NHS and schools . Jeff Bezo gets rich at the expense of my sons teachers and we have a word for that round here .
Anyway part rant over I’m a bit weird for sure and I stick to what I know and enjoy that’s how I stay happy
I stick to what I know and enjoy that’s how I stay happy
And there’s nothing more important than that :-)
That’s a great post , perhaps the best I have came across here.
And I will add to that , the US economy almost doubled since the 2008 banking crisis. The UK economy still struggling to match its GDP prior to that crisis.
Re: SOMERO, @SOM
Commiserations planetx. None of this investment game is easy (and those who think it is are overdue a harsh lesson from the market, in my view).
This is just to note that Somero report in dollars. That's not to say that dollar weakness is helpful, given the dominance of SOM's US sales, but it would likely be much more harmful to SOM's valuation if it reported in Sterling. (I hold)
It’s ok , I’ve still got a good few didn’t bail out completely !
If company is valued in pounds and reports in dollars I think the net effect is the same, ie dollar weakness not good for it .
That’s my interpretation .
Re: Somero
I agree dollar weakness is not great for Somero but I've seen it has the worst effects in companies reporting in non-dollar, stronger, currency - I thought selling 2/3 of your holding just because of dollar weakness was quite a strong reaction, but you confirm above you actually sold half, and any way there are other reasons to be cautious of Somero.
Somero Enterprises (LON:SOM)
That's not to say that dollar weakness is helpful, given the dominance of SOM's US sales, but it would likely be much more harmful to SOM's valuation if it reported in Sterling. (I hold)
Ed can you explain to a buffoon like me why the reporting currency should have any effect on valuation? If we take the viewpoint they would have the same income and funds in each currency anyway - i would have expected the valuations would mostly be the same whichever currency they reported in ?
Another thought on Portmeirion (LON:PMP) I was brought in by the good interview Paul did with thr CEO. I may have to defer to the wold of small street's method of not listening to management! I do have a general rule from my investing in Globo years back - never trust management who present with a suit AND tie. One or the other is okay.
Portmeirion (LON:PMP)
I guess us holders get what we deserve here ref holding this company - they never really seem to tell us how it is. Everything seems so sketchy they are really unsure ref numbers. In some respacts thats ok if they provided concrete specific range that suits and update in timely fashion. I just feel what we are given is always lip service updates that dont really give me confidence the overall picture matches reality.
Having said all the above i am not personally selling up here today as hopefully they have gone straight from over optimistic to over pesimistic - i am not convinced their cluelessness is meant to deceive in any manner but i do have slight niggling doubts that they are being sketchy for reasons that suit them rather than us.
Deffo deserving of amber flag here.
I can't for the life of me see how Paul can classify this as AMBER and say that it's not a disaster. A 25% fall today brings the SP down to 288p. It was over 500 2 months ago. Not having a go but isn't that view just a tad bit blinkered. Just my view. I sold when it dropped to 400.
Hazarding a guess (I know, dangerous), I suspect that Paul takes a medium term (2-3 years) view on Portmeirion (LON:PMP. Within that time frame, unless there are further profit warnings, the share price should more than recover the loss incurred over the last couple of months. That’s the view I’m taking- for now. I may yet rue that decision :)
Does anyone think Brand Architekts (LON:BAR) might be starting to looking interesting? Net cash of £8 versus market cap of £5m so trading at 40% discount to cash alone. No value attributed to the business or brands.
Interestingly net cash went up in the period as losses have been slashed, so it appears as though perhaps it’s stabilised at least around cash flow b/e. If that’s the case it might start to look interesting?
anyone looked in more detail?
I don’t think the market cap is £5m.
DYOR.
No - looks like 28m shares in issue so around £8m market cap. Weird as my real time price provider has it as £5m
So trading at net cash then rather than a discount
Any thoughts on Shield Therapeutics (LON:STX) up 12%, great update this morning with huge growth in prescriptions of their iron product Accrufer in the US
Forecasts are for a 5 fold increase in revenues for 2023, so an increase in prescription growth of only 50% doesn't look enough to meet that forecast, so I was surprised to see the shares so strong this morning. Note that revenues were not mentioned in the RNS.
If they do fall short, then because of the increased sales force adding to costs, the loss could be substantially higher, so caution is warranted in my view.
Thanks for your insight, as a doctor myself I can see the treatment having huge potential. Side effects of normal oral iron are very poorly tolerated and IV iron is expensive and requires trained staff to administer. Iron deficiency anaemia is also incredibly common. I can see them needing more time to build revenues with their new completed sales teams. There was mention in this update of cash estimating to last until end of next year. I'm keeping a close eye!
Surely if want to up iron then eat baked beans, oatmeal, lentils, spinach, beef, almonds, egg etc. Understand supplements are popular with busy lifestyles but protein shakes and Huel etc are perhaps a better market to follow.
Or perhaps the obesity market - a bit expensive but Inmode (NSQ:INMD) is breaking out of $40.
Iron is prescribed by doctors in much stronger forms than supplements. You can be iron deficient from not consuming enough of course but most prescriptions are for clinical conditions where absorption or excessive loss of iron through bleeding is present (pregnancy, inflammatory bowel disease, coeliac disease, cancer, kidney disease etc). Iron deficiency anaemia is such a common problem and the current treatment is very poorly tolerated, causes GI upset, and is very poorly absorbed. Shield Therapeutics (LON:STX) has an incredibly novel treatment where you get high absorption and low side effects which is greatly needed (I'm a GP!). This is a medication so you wouldn't be able to use it as just a supplement.
Good to have what I believe confirmed independently by a doc re Shield Therapeutics (LON:STX) …as I said earlier there are high execution risks here (and some past slips too) but I believe the upside is very significant. A stock with a real option payoff profile. My position is suitably small
Shield Therapeutics (LON:STX) is a very high risk stock as its got to sprint just fast enough not to run out of cash and need another refinance. One could make a lot or lose the lot in this stock. Post refinancing earlier this year I took a small position (I have a slowing building basket of life science linked names...no one stock is safe but I think there's an opportunity in the area from general capital cycle perspective)
I disagree the update was troubling. Operationally Q2 was a period of recruitment, training and full sizing the 100 person sales team agreed in the deal with Viatris (NSQ:VTRS) - each partner runs 50 people.
A 50% increase in prescriptions Q on Q doesn't cut the mustard if extrapolated for sure...but Q2 is not a quarter to be extrapolated for reasons commented in paragraph above. However, a 157% Q on Q increase in first time writers is a very strong hint that sales are on a very accelerated path and there should be significant acceleration into H2 2023 as a result. 73% of Q1 writers also wrote prescriptions in Q2. That's a decent result...and Q1 was still a period of relative sales team hiatus, whereby cleaning up and out of existing resource was taking place ahead of the team ramp to come so perhaps it was a very decent result. Dunno. Only time will clarify.
Do they hit their very big step up sales target for 2023 of £25m from £4.5m. That's an eye watering leap. The partnership with Viatris and sales team growth give them a chance of hitting it...but GBP strength will also add another small hurdle on top of a large hurdle.
IMO the price of the stock implies the sales target wont be hit. I don't know what number they need to hit but I'd hand wave that if they can get approx £20m the sp will be okay....and with a change in market winds even a decent bit higher. For me operational success but sp disappointment could give an opp to go heavier in the stock.
I'm no medical or iron deficiency expert but I know from experience of women in family that it is a common problem across all ages (inc young but high intensity athlete and need for supplement at times). Current treatment is unpleasant, hit and miss and often inconsistent. Shield have a big opportunity to grasp in a large badly served market.
Re future refinance. I hope they don't need it...their cash and debt position is decent-ish. But good operational execution and any raise is likely taking place at a price well above current and not very dilutive. Also additional debt finance is possible instead of equity
Defo DYOR...risky
I like robbie burns idea about how to approach a stock which is forget that you own it and look at it fresh. Portmeirion (LON:PMP) would I buy today? - no, with a hideous statement which tried to mask the problems and eps forecast now at 17p I wouldn't even think of buying unless sub 200p. So sell it is.
Well that's what makes a market? I applied a different test to Portmeirion (LON:PMP) the 'is the blood on the streets' and bought a few more at 287p. Clearly there is risk - but in the longterm I don't think the risk is as high as the market reaction indicates. May take a while to get to the longterm is certainly a down side.
cheers
Mark
I don’t think the “blood is on the streets” with Portmeirion (LON:PMP)
My definition of that test is when a company’s share price is on the floor, trading at such a lowly valuation that it just doesn’t justify such a rating. Usually found when sellers are indiscriminate and liquidity is low. There are quite a few stocks I’d put into that category now but Portmeirion (LON:PMP) isn’t one of them.
don’t get me wrong - I like the brand and think it probably has a decent future ahead but the reality is that based on the new forecasts it is trading on a PER of well over 10 which for a retail based business isn’t particularly cheap.
I understand that long term this may do well but the thing many of us struggle with is the time value of money. We are all guilty of it I suspect. Ie we buy a stock for the longer term and when it goes down we look 3 years out and say it will recover but actually if you took that money out and invested it in something else (even cash now!) would it make you a better return than sitting in an underperforming share for the long term.
I'm firmly in the "if in doubt, get out" camp when it comes to small caps, tho admittedly I do have the pain threshold of a toddler when sitting on losses.
There's too many trading updates lately where it reads reasonably OK but then the broker numbers are hideous, Portmeirion (LON:PMP) being the latest.
I think I could actually make money, certainly save plenty, by ignoring the daily RNS news feed and just reading the broker notes every day.
Not a small cap, so pls scroll on if offended....
Babcock International (LON:BAB)
This is an interesting situation - even if just when you think they've finally turned the boat around they discover another leak below the waterline (Type 31 frigate, disclosed in April). Net debt now under control after disposals (AES sale brought in £640m and offloaded £240m of leases), down from £556m to £346m. Cash generation ahead of expectations.
Contract backlog up 7% organic to £9.5bn, which is >2x annual revenue, and this excludes a further expected £3.4bn under framework agreements.
Superficially they are in the right areas - defence (68% ), long term marine support contracts, AUKUS, nuclear decommissioning.....oh, and a major land war.
Superglueing the heads back on plastic screws in a nuclear sub and being in a £100m dispute with your major customer, however, should dispel any complacency....but it remains the case that the MOD has little option but to stick with Babcock in certain areas. There is also export market upside to balance the risk equation a bit.
So is Babcock a cheap defence company (P/E 8.3x vs 14.9 at BAE Systems) that has now aired more of it's dirty laundry than the others, or are there further mispriced contract revelations to come for years ahead, Capita style?
I don't know, but having bought the turnaround story too early, the balance of probabilities is now clearly improving.
An anecdote from Stocko member Caduceus has put me right off Babcock International (LON:BAB) after previously thinking along the same lines as you…
In summary, they clearly don’t have good control within their manufacturing as they made replacement rudder bearings in the wrong size! More like Babcock(up).
I have heard many stories such as the one you mention, and I'm sure there are many more that haven't seen the light of day.
Thing is, all companies have screw-ups. They are run by human beings. Even the clever ones screw up. Remember the Hubble space telescope mirror?
It is therefore a relative game, and I'm sure BAE Systems has plenty of stories it is desperately trying to keep out of the press. Just look at the trouble General Dynamics has had with Ajax.
Anecdotes can be very revealing, but they can also make us miss the wood for the trees. If Babcock is consistently incompetent throughout then our subs would all be on the ocean floor by now. Nuclear engineering is not a forgiving sector.
The big question is whether the disparity in valuation is appropriate - and I accept it may be (which is why I have a much larger position in BAE!)
Anyway, that's my ESG credentials blown, and I expect Coutts will de-bank me later today.
You may well be correct that the turnaround is underway, but as someone who works in a QA dept, I likely have bias towards such inefficiencies! Good luck with it, it is an interesting sector though. I’ve been looking to get in but prefer those with greater US exposure, I’ve been looking at Raytheon Technologies (NYQ:RTX) & Kratos Defense and Security Solutions (NSQ:KTOS) but haven’t ‘pulled the trigger yet’!
I also own Qinetiq (LON:QQ.)
Worth a look if considering defence sector exposure.
I should have added, 2 key phrases from today's Qinetiq (LON:QQ.) trading update:
Our visibility on revenue under contract for FY24 has increased to £1.3bn, up from £1.1bn at April 2023. Consequently, we remain confident of delivering in-line with our expectations.
Our performance momentum in the US continues, integration activities remain ahead of plan and we are making good progress on new business opportunities.
Thing is, all companies have screw-ups. They are run by human beings.
“Buy companies that would thrive even if an idiot was running them, because sooner or later, one will” - Warren B
should also be noted that Babcock International (LON:BAB) although it is not a small business it is absolutely tiny compared to BAE Systems (LON:BA.)!
£2.5B vs £32B in enterprise value (quite literally over 10x the size)
If been looking at #DRO - Droneshield
Any #ASX defence company, if it's a field your interested in then have a look
$200m Market Cap with orders now coming in
Drones, AI, Prison Services - recent order with the US and some background noise regarding NATO.... could be something in the water
Lots happening this morning in the family portfolios this morning. I am glad to say no repeat of the Watkin Jones (LON:WJG) update that caused much head scratching and which I exited at 50.5p yesterday with a 35% loss. I think it will recover, but the outlook and the Progressive broker note made grim reading and the cash can be better deployed as there are so many bargain small caps at present.
The problem as always is avoiding value traps. Still as many will know I am a big admirer of Howard Marks who maintains that the secret to successful investing is buying well and not over paying; price is what you pay value is what you get as is said.
The questions I ask myself before buying are:
Despite the above I have gotten it wrong on more than one occasion, as Watkin Jones (LON:WJG) testifies to.
Anyway enough of my ramblings and on to this morning. Firstly condolence to holders of Portmeirion (LON:PMP), a company that I like and bought earlier in the year but exited on the previous up date when it cautioned on sales in America. Profit warnings are part of investing but never easy to deal with.
I hold Centaur Media (LON:CAU) IG group (LON:IGG) and Howden Joinery (LON:HWDN) all of which reported this morning and without wishing to appear clever which I am not, were purchased below the current share price (thank you Mr Marks).
Centaur Media (LON:CAU) is a significant holding for Rockwood Strategic (LON:RKW) and Downing Strategic Micro-Cap Investment Trust (LON:DSM) . IG group (LON:IGG) was just too cheap at 640p given its prodigious cash generation and the interest earned on cash balances with the rise in rates.
As for Howden Joinery (LON:HWDN) although far from immune to the current economic turmoil it is in my opinion a very well managed company with an excellent strategy. I appreciate that Howden Joinery (LON:HWDN) is outside the scope of the SCVR but mention it for completion as it is together with ITV (LON:ITV) are the only companies of significant size that I hold.
VP (LON:VP.) looks very interesting, trading in line, but as mentioned by planetX the founder holds 50% of the equity, which is potentially a left field risk.
All the best
Chapel Down (OFEX:CDGP)
A positive half year update from Chapel Down this morning.
6% increase in total wine volume, 32% in sparkling wine ( champagne ish) volume , another good harvest in prospect after FY22's record harvest, Chapel Down will have 1000 acres planted by sometime in 2024, a big increase in customer brand awareness but to me what goes unmentioned is the French Champagne houses must be struggling with the weather in their region which I have a feeling will make Chapel Down a takeover target of one or more of them.
It may become a takeover target, if not so already, but champagne can only ever be made in Champagne by French law. The grapes that constitute the champagne may also only be grown in Champagne, so unless they change the law passed decades, possibly centuries, ago, Chapeldown sparkling wine will remain an English sparkling wine, albeit of very high quality. This makes me wonder how much more they can increase prices. The ultimate prize, as evidenced in the very clever Chapelle En Bas promotion, is for people to move away from Champagne and buy Chapeldown instead. It is undoubtedly interesting that one of the French champagne houses, Taittinger, has bought land in the UK for vine production
Grape varieties | Le site officiel du Champagne
ABOUT US – Chapel Down
The grape varieties used in Champagne are the same as Chapel Down use in their English Sparkling wine , you are correct in that CD, or for that matter any producer of sparkling wine that is located outside the Champagne region of France, cannot call it Champagne, however to all intents and purposes however much the French complain it is the same product.
Hence they have been buying land in Kent and across the South Downs.
Champagne Taittinger to produce English sparkling wine in Kent | Food & drink industry | The Guardian
Portmeirion (LON:PMP)
Hadn't seen the extent of the fall when I posted my thoughts.
It's back down to where I was last buying - despite the improvements in the business.
So just tried to buy a few on-line and the only account I have cash in at the moent won't let me! I'm totally not good at timing markets - so probably just as well!
cheers
Mark
Portmeirion (LON:PMP) The market gives me another valuable lesson to stick to my stops. I had a mental stop at 400p, ignored it thinking maybe the trading update will be okay. Now from a 10% loss to a 40% loss and 10k poorer :( (I sold first thing)
Portmeirion (LON:PMP) H1 Trading update and profit warning (I hold)
Portmeirion on the naughty step this morning. And another disappointment. I should be getting used to it but the optimist in me makes that hard.
FY revenue is expected to be below, and profit significantly below market expectations if de-stocking by US and Canadian retailers (currently down 14%) and flagged at the AGM statement is not reversed in the all important H2 period.
As the US and Canadian sales have not yet reversed in Q2 then the board has adopted a prudent approach and assumed they won't improve in H2.
Signals are mixed. As the forward order book is ahead Yoy as this stage, direct sales consumer demand remains 'strong' and orders for the no1 selling line 'Spode Christmas Tree' is up double digits YoY. On this basis wholesale orders should recover in H2.
The board is assuming that US and Canadian sales won't recover. Prudent. But uncomfortable. Sales data says they may well recover. Reality may turn out to be in the middle somewhere.
In the absence of any hard data and with confusing signals I've reduced my estimates for revenue in H2 by 4% (the current reduction in sales in H1).
FY23 my rough estimates
Rev £113m
Profit £5.8m
eps 42p
In the last couple of years sales in the US and Canada have risen sharply, with their US business Nambe doing particularly well. I slightly suspect that this slow down is something of a re-adjustment to more normal levels of overall growth. Underlying this is the continued weakness in UK sales which have been going backwards at a fast rate in the same period. Until this is reversed it's likely that Portmeirion's sales revenue will trend upwards but remain volatile year-to-year.
I expect H1 results to be reasonable Yoy despite today's warning - as there should be no repeat of last years £1m one-off reorganisation costs for Wax Lyrical and the international sales and marketing team. At the same time the continued investment into production efficiencies, facilities, logistics and their direct sales channel will all provide a tailwind of improving margins. The fall in freight costs should be significant but may be balanced to a large extent by the rise in energy costs as long term contracts capped until spring 2024 are replaced.
As I tend to be a long term investor - I see the long term plan as remaining on course - with today as another uncomfortable bump in the road.
Until today my 5th largest holding. Might not be now. In which case I'll be looking to add, but as I am fully invested it will be difficult, and there is no rush I think?
cheers
Mark
As the slowdown in sales is because of destocking you would think there is a good chance this could reverse with consumer end demand remaining strong.
With inflation in the US seemingly coming under control, there is a possibility this may just be temporary and with the profit warning out of the way, a further deterioration looks unlikely given the order book and so because of a combination of the above, I have bought some this morning
Don’t think slowdown in sales is caused by de stocking .
The stock was too high before and needed reducing
It is when attempting a stock reduction that you find out if the stock was good stock just too much of it or bad stock not selling .
If it’s bad stock then you have to clear it or provision it .
It is key to watch stock levels and make sure they are kept to a good efficient stock turn . Stock management in a trading business is pivotal and it is a very important skill set and requires a good FD to have a foot up the bum of sales and purchasing teams and a good trading director .
Back in the day I had a 16 million business with 8 million stock and 2 million debt and could never meet payroll .
My new FD took me to one side, poked me in the eye and said
“You have an amazing business I’m going to give you a target, I know you like targets .
Drive your stock level down to 4 million in 6 months , forget about margin just get it to 4 million .
And if you do that you have
4 million stock , 2 million cash and everyone gets paid and you can ride your bike”
I did 300k a week for 6 months with tight purchasing control and at that stage we became a world class business .
Took me 24 years to get a world class FD who taught me the simplest of lessons .
Excellent post.
Portmeirion (LON:PMP). You may have hit the nail in the head with regard to the price and
hence gross margin at which they are managing to unwind stock in the US. Given the freight excess to get it there last year and the effect of sterling if not hedged.
I agree I don't think the slow down in sales is caused by de-stocking. Or rather, not just by de-stocking which may be a symptom as much as a cause? Probably a bit of both. In recent years US sales have risen very fast - assisted by the x-change rates - which has now reversed.
It will be interesting to see the interim results.
BTW - I recently invested in a bicycle workstand for the first time. My back is not what it used to be. The 'jobsworth' - great name by the way- being signiicantly cheaper, to the point wondered why, I decided to mystery shop. Given the low price I am very impressed - and as an occasional user - definitely jobsworth! Right now, where can I get a landrover workstand similarly low in price :-)
Not a great day for me. But these things pass. Time for some meditation. Where's my axe............
cheers
Mark
Mark if it's of help, Singer have cut Revenue to 102m and EPS to 16.7p this year.
105m + 38.9p 2024
Re: Portmeirion (LON:PMP)
Thank you Wolf - no I'd not seen the brokers note.
That leaves me looking hopelessly optimistic I think. I like to think its contrarian - but in this case it might just prove to be hopelessly optimistic.
I probably wasn't clear - as an optimist, my figures are a middle case. Where the de-stocking is not completely reversed but the orders do recover to some extent in H2 as indicated by forward order book and customer direct buying.
If I'd read the broker note before posting I would have been much more pessimistic. But is that right - given that nobody actually knows? Not me, not the market, not the board, not the broker. It could be as bad as the board/broker estimates. But is that the most likely outcome. Though to many investors that probably semantics? But I sense blood on the streets.
I'll have to play with some numbers to figure out how they get down to 16.7p - which is about £2.3m profit. Savage. It seems to me that there is something else in the figures I'm not seeing. Yet. Sterling and gross margin come to mind.
We'll see when the dust settles. In the mean time I'll have to get used to looking like a plonker,cheers
Mark
re Portmeirion (LON:PMP)
Everyone may already know this, but while it wasn't explicit in the trading update, PMP do publish analyst expectations - https://www.portmeiriongroup.c...
Analysts were expecting PBT of £9.3m. This hasn't been updated yet to reflect the "significantly below" statement, but if we take that to be 20-30%, then PBT could be in the region of £7-8m, with EPS 43-42p
I'd really like to understand the forward order book.
Are they being promised orders by their customers and then the product isn't moving and so the customers don't fulfil/need that order?
Or have they made assumptions and retailers are destocking and therefore their forward order book number is incorrect ?
I feel like the only way sales are down by this much for this period and the forward order book is "strong", is if they know that the retailers have actually finishing destocking.
If they know that then the broker EPS cuts don't make sense. If they don't know that then the forward order book can be taken with a large pinch of salt.
Alphawave IP (LON:AWE) a long time poor holding for me. I like the business but my timing was atrocious to be fair. However it is up 60% in last few months and good results today. Should also be a stealth AI play. Looks like they will far exceed $100m of profits next year ($87m this year) but finally seems to be coming back to live….. fingers crossed.
Good research posted in Ed Shing’s AI article comments and in the thread for Alphawave IP (LON:AWE) , one of my largest holdings; my timing was good on this one and I’m in no hurry to sell.
https://www.stockopedia.com/co...
Oo-er, Lookers (LON:LOOK) takeover falling to bits by the look of things, glad I sold out when I did while seeing the price of Wentworth Resources (LON:WEN) shares dwindle while I am holding on tight. Civitas Social Housing (LON:CSH) another bugbear what with Bidco planning to claw back the dividend which by rights should already have been paid.
No mention of Litigation Capital Management (LON:LIT) which is currently quietly realising a bunch of returns from investments. Unlike others, it has up until now (about to change), marked its investments at cost rather than fair value so given the IRR this approach materially understates the real book value. Ie very conservative
however, it’s also doing nicely for its asset management arm which pays them handsomely for winning cases but incurs no company money risk. This is good business. The recent case win at $70m should provide a big chunk to Litigation Capital Management (LON:LIT) and equally importantly bring new investors into their funds as returns in fund 1 start to be validated.
Need to go back and look at the valuation as haven’t done that for a while but this looks to be a non hyped business doing very well.
Morning David!
We don't tend to cover litigation financing shares in the SCVR reports (but feel free to discuss in the comments, as always!), because they're too complicated to analyse (case-by-case is the only logical way I think), so they're more special situations than need in-depth research that we haven't got time to do here when we need to cover 5+ companies every day.
Briefly looking at the StockReport for Litigation Capital Management (LON:LIT) I see the figures are in Aus $, and it seems to have a good track record of decent profit almost every year. Lots of share issuance though, so looks cash-hungry (to expand presumably). No divis. Shares have swept up and down in a range of 60-120p since listing in late 2018, currently in the middle of that range after a nice recent rebound.
I like the points that you make about marking cases at cost, and a big recent win. Could be an interesting one for readers to look at in depth, if you understand the sector, and the risks.
I wonder what management take out? Is it run for their benefit maybe, sometimes these type of companies are, especially when they're not paying divis, yet shareholders take all the risk!
Thanks for flagging.
Regards, Paul.
Thanks Paul
I’d probably add that directors have been regular buyers in decent size so aligned to achieving a good share price.
Litigation Capital Management (LON:LIT) (I hold)
Hi David (and Paul)
I'm a little late, but thought I'd respond with some comments.
I for one am slightly confused by the depressed share price after so many recent positives:
The market cap is currently c £110m.
The company regularly announces its case outcomes (well, at least some of the winners) and accordingly I calculate PBT for FY23 (June 30th, 2023) to be at least $30m AUD = £16m.
I personally would expect the share price to therefore be a little higher to reflect the seemingly strong balance sheet and ability to generate cash.
There are plenty of investments on the balance sheet too, so one would hope that there are more positive outcomes to come over the next few years, hopefully bolstered by the funds on the balance sheet yet to be invested.
The big risk here, ironically, remains a change in the litigation financing rules. For now though, I remain a content holder.
A
Chapel Down (OFEX:CDGP) trading update this morning looks promising
Hi all, as we belong to a community of thoughtful contributors here, I don't think any of us wish that the tone of the comments board is discouraging people from posting their thoughts.
Ray Dalio calls it thoughtful disagreement and even though we may be very convinced of the validity of our own view...expressing it forcefully, could be discouraging others. This is the opposite of what we should be aiming for ... since the collective view will be one of loud agreement which I reckon is normally wrong. My own best views im often not so confident of....and so it would be my view we want to encourage these views out, not silence them. The loudest voice can be reserved for other forums.
Not pointing fingers at anyone, we all get carried away, but we should be encouraging ....which obviously most of the time we very much are.
A good old fashioned Thursday deluge is sure to keep us busy today, good luck out there.
My morning smallcap tweet: The Big Weep
Amte Power (LON:AMTE) Pittards (LON:PTD) Fuller Smith & Turner (LON:FSTA) KRM22 (LON:KRM) Litigation Capital Management (LON:LIT) Netcall (LON:NET) Brand Architekts (LON:BAR) Arecor Therapeutics (LON:AREC) Portmeirion (LON:PMP) Iofina (LON:IOF) Fonix Mobile (LON:FNX) Aew UK Reit (LON:AEWU) Acuity RM (LON:ACRM), VP (LON:VP.), Kier (LON:KIE), Pendragon (LON:PDG), Alumasc (LON:ALU) Lookers (LON:LOOK)
◄AMTE Power (AMTE)► will go into administration if no funds forthcoming within a few days. [edit] What a disastrous IPO - Mar 2021 at 175p. Now 4.75p. In Dec the replacement CEO trilled "I am delighted to have joined AMTE Power at such an exciting stage of its growth trajectory...The business is well placed with high performance products and manufacturing expertise." [SP=8.44 Cap=3m]
◄Pittards (PTD)► a trade Investor will subscribe for £1m max shares at 4p contingent on co raising a minimum of £1.16m and new banking facilities. Share remain suspended. Will probably go bust if investments don't happen. [SP=5.47 Cap=2m]
◄Fuller, Smith & Turner (FSTA)► AGM stmt - recent 15 weeks rev up 17%. CEO 'very pleased'. In line? 1m share buyback. [SP=572 Cap=225m]
◄KRM22 (KRM)► guides H1-June rev £2.4m (£1.9m), ARR £5m (£4.1m). In line? [SP=45 Cap=16m]
◄Litigation Capital Management (LIT)► a funded party has succeeded in its claim. May be appealed. LIT investment A$5.7m; cannot calculate overall return until case concludes. [SP=91 Cap=108m]
◄Netcall (NET)► guides FY-June rev up 21% with underlying total annual contract value also up 21%. Net funds £24.8m. 5 yr contract renewal worth $20m tot. [SP=112.5 Cap=180m]
◄Brand Architekts (BAR)► the absurdly named beauty biz guides FY-June up 41% but only c. 7% LFL "due to strong international sales offset by challenging trading conditions in UK channels". H2 op loss down. In line? "We are confident that our brand development and brand reach strategic pillars will help us achieve our profit goals." Why am I not persuaded by that MBA bollx? Settles claim by its Mr Haircare JV partner for £200k + legal costs £225k. Will buy JV partner's 55% shareholding. [SP=29.75 Cap=8m]
◄Arecor Therapeutics (AREC)► biz and drug dev update. [SP=200 Cap=61m]
◄Portmeirion (PMP)► guides H1-June rev down 3%. US and Canada weakness continues with rev down 14% but "end customer demand remains robust". Elsewhere in line. [SP=399 Cap=56m]
◄Iofina (IOF)► guides H1 production in line. IO#9 needed additional equipment and installation costs compared to other plants. Total expenditure including reused equipment $5.5m. [SP=31.75 Cap=61m]
◄Fonix Mobile (FNX)► guides FY-June rev and profit marginally ahead of market expectations. [SP=205 Cap=204m]
◄AEW UK REIT (AEWU)► NAV 107.03p/sh cf 105.48p in March. [SP=98.2 Cap=156m]. I hold.
◄Acuity RM (ACRM)► wins 3 yr contract worth £388k for software platform STREAM. [SP=6.66 Cap=8m]
[edit]
◄Lookers (LOOK)► 19% holder Cinch withdraws Letter of Intent to vote for rec offer. "Lookers is re-engaging with other shareholders to understand whether the resolutions required to effect the Scheme of Arrangement in order to implement the Acquisition are capable of being passed."
In line: VP., KIE, PDG, ALU
Shanta Gold (LON:SHG) (or Zurrin Industries™ as I like to think of them) RNS this morning very positive.
Yes CM couldn't really ask for more. Q2 Gold production 23% ahead of Liberum forecasts. My first foray into a gold miner in 10 years, thanks to Mr Tickle exiting.
Yes, shame Eric Zurrin has resigned as CEO though.
Volution (LON:FAN)
I’d like to highlight another in a long line of positive updates from this high margin, high ROCE suppler of regulatory-driven ventilation equipment. I find the report slightly less positive than previous owing to weakness in Europe and a peak in Australia - yet still eps is expected to be ahead of consensus for the year ending July 23. Imagine how it will perform when the backdrop changes. Shares lost 20% on market weakness lately and I topped up. Terrific record of compounding growth and earnings for a cyclical business with a similar return profile to market darling Howden Joinery.
Buyers have moved in after traders sold the news in early action. Currently up 10% in last 2 days.
VP (LON:VP.) - "All fine on the infrastructure front" *** Note here: https://www.equitydevelopment....
Sharp eyed investors would have noticed the recent mixed messages from the UK’s June Construction PMI report, whereby positive output across infrastructure and commercial was offset by weakness in house building due to rising borrowing costs. Equally though, input cost inflation and supply chain bottlenecks were said to be reducing, which should help alleviate margin pressure.
Similarly in today’s ‘on track’ trading statement, Chairman Jeremy Pilkington commented that Vp had also “experienced varying levels of demand across a range of markets.” With water, transmission and rail being “supportive”, in contrast to housebuilding, where activity had stabilised at a level 10% below LY.
Elsewhere Vp’s international divisions (re AirPac & TR Ltd) continue to make good progress. Meaning that overall the Board expects FY’24 to be in line with consensus estimates.
As such, we reiterate our £10.90/share valuation and FY’24 forecasts of adjusted PBTA of £42.8m on revenues up 2.8% to £381.7m. Alongside net debt (pre IFRS 16) closing Mar’24 at £123.9m (vs £134.4m LY), equivalent to a comfortable 1.3x EBITDA.
What’s more, we would argue that for investors with a 2-3 year view, there seems to be exceptional value on offer from this specialist equipment rental group, which has previously demonstrated consistent delivery through thick & thin. In fact at 570p, the stock trades on a PER of only 7.1x whilst paying a bumper 7.0% dividend yield. To us, the shares are simply mis-priced.
VP
Over 50% held by chairman Jeremy Pilkington is a littke high for my comfort zone .
Paul Lookers (LON:LOOK) deal looking to be off cinch reject it
Oooh great spot, thanks for flagging! I've mentioned here before that selling in the market at c.119p looked the best option for LOOK shareholders, as the deal support looked inadequate (before today's news), and it was strange to see institutional investors that had given a letter of intent in favour of the bid, then selling shares in the market.
As you say, it does now look as if the deal could be off, given that Cinch's 19.2% shareholding is now switching sides to be against the Canadian takeover.
No doubt the company will be commenting shortly. Will be interesting to see what the share price does - maybe a drop of c.20% would be my guess.
Is there a possibility that Cinch (Constellation) might counter offer? Seems a good fit with their old BCA portfolio to me.
Lookers (LON:LOOK) (no holding) - Here is a link to a story suggesting a higher bid may come from Lithia Motors (NYQ:LAD) and that's why Constellation withdrew their support. https://cardealermagazine.co.u... Also Lithia Motors (NYQ:LAD) had tried to buy Pendragon (LON:PDG) last year.
Morning Paul - With Portmeirion (LON:PMP) a Top 10 holding for me - I will be sharing your pain this morning - Shore downgrades on EPS are not pretty !
Thanks for flagging Portmeirion (LON:PMP) downgrades, I'll have a look at that shortly.
Thanks for your thoughts on Portmeirion (LON:PMP) Paul - The RNS is terribly worded except for the substantially below bit, I have now sold all of mine as faith in management is now too low, I find it odd too that there was no comment on freight costs which I had assumed, even in a slowdown, mentioned in the previous update, would have provided decent support to profits!!!!! Perhaps this has been low-balled by brokers so PMP can claim a big beat when they next report to try and restore some kind of faith - Who knows eh ! Thanks again.
Thankfully I sold Portmeirion (LON:PMP) on Tuesday. The market seemed to have been expecting this news and I'm fed up of taking big hits on the day even for core holdings. I find myself almost using the Minervini stratergy of selling before results are released, saving some pain - you can always buy back in. Plus the divis were rubbish and in this climate cash in the bank is doing well thank you, together with some inflation proof assets (whisky and rental property).
Portmerion
I missed out buying before the huge surge in price and it’s probably going to end back where it started .
I said at the time this was about stock turn and stock holding .
Todays report confirms stock reduction but unfortunately does not give what level .
Should be at least a 4 times stock turn on this eveni higher as they still have sone uk production .
With a 6 time stock turn and good cost control even you have a wonderful business here even in tough markets .
My opinion is long established brands with great businesses cannot get growth in tough markets but they can “do the basics” which is maintain lean stock levels and cost control and they are simply a good business .
Sadlly in retail abnd consumer markets you can’t beat the tide, retail is tough right now so company owners (ie investors) just have to run a tight , profitable , ship .
When there is a retail boom they can swim with tide
But absolutely nothing wrong with having no profit or sales growth in tough times provided there is excellent inventory management and cost control .
In fact it is these times you find out who the excellent companies are .
I would not be too down beat on Portmerion provided cash is good, I’m entity is lean , costs are under control , ie it’s a good business
It is the share traders that will be in and out here but the share holders are still holding a good company .
I don’t hold as I thought it just became frothy in the rise.
Re Portmeirion (LON:PMP) - what a dreadful trading update.
Not the bad news (which is not good!) but the update itself. It gives some specifics (overall 3% down in H1) and tries to re-assure that in key US market trade sales in are 14% down but its sales out are up (it claims 60% coverage so actually very re-assuring if true) and that sales are up in other areas are up.
However, for a volume driven, de-stocking led "significantly below" profit warning to not give a sense of what it expects the overall picture to be vs current expectations is not acceptable.
Portmeirion (LON:PMP) is a big long term holding for me and I expect the market to hate not just the usual 2nd half weighting but this uncertainty and punish it with a big drop today (down 30% as I write). Worse, it will undermine its credibility going forward. It was already thinly traded.
Its going a very tough decision on how to react. I had really thought the Mgt to be a safe pair of hands but this has been handled very badly.