Small Cap Value Report (Thu 25 Feb 2021) - G4M, RCDO, MACF

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Agenda -
Gear4music Holdings (LON:G4M) - yet another increase in guidance for FY 03/2021 - this share looks cheap at 725p, expect a decent rise today.
Macfarlane (LON:MACF) - resilient results from 2020. Big increase in divis, and net debt paid off. Looks good value to me.
Ricardo (LON:RCDO) - improving conditions and reinstated dividend from this engineering consultancy (this section by JAck)
.
Gear4music Holdings (LON:G4M)
(I hold)
725p - mkt cap £152m
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces the following trading update.
This is the latest in a long line of above expectations trading updates.
We are pleased to report that Group trading performance in the 2021 calendar year to date [Paul: FY 03/2021] continues to be strong. Both our UK and European Operations have performed well post Brexit, helping to drive revenue growth and support margins that have exceeded our previous expectations.
The Board now expects EBITDA for the 12 months ending 31 March 2021 ("FY21") will be not less than £18.2m, up from the guidance provided on 14 January 2021 of not less than £16.5m.
That’s a useful increase in forecast EBITDA, especially coming near the end of the financial year. G4M seems to be going from strength to strength.
Forecasts - I can’t see any updated broker notes yet, but using a previous note from N+1 Singer, I can manually update it to adj PBT of £13.1m, or 50p EPS.
That means the PER is only 14.5 - clearly the wrong price. It should be on a PER of 20-30 in my view, implying a share price of 1000-1500p - good upside from 725p currently.
My opinion - I think broker forecasts here look way too cautious. The assumption seems to be that G4M has had a one-off boost from lockdown. That’s probably true to some extent, but bear in mind that once lockdown lifts, then live music should return with a vengeance. That means customers wanting to buy new equipment. Therefore some categories such as speakers, might see a boom, even if others fall back a bit.
I really can’t see EPS falling from 50p FY 03/2021 to 27.73p next year (current broker consensus). Hence upgrades to next year’s forecasts seem inevitable.
In my view G4M is a high quality growth company, that is a core part of my long-term portfolio. I can’t see any reason why the share price is below 1000p, so it’s a really good buying opportunity in my view at 725p. Although it’s likely to be marked up before trading begins shortly (I’m writing this at 07:31).
G4M has also impressed for its foresight in opening distribution hubs in Germany & Sweden some time before Brexit. Therefore it can service the important EU markets from within, an important logistical advantage over other UK-based competitors.
Shareholders who backed the company’s strategy change in 2019, to focus more on increasing gross margin ahead of revenue growth, have been richly rewarded.
This share ticks the box for having an entrepreneurial owner/manager with lots of skin in the game (Founder, Andrew Wass still owns 30% of the shares), and he’s built a terrific team, that are really delivering the goods. I’m giving this factor a lot more emphasis in my stock picks these days, as it really does seem to be closely correlated with investment success.
.

.
EDIT - I’ve had a look at the new note on G4M from Progressive, which came through after I’d written the above. It ties in with my figures, with 50.9p EPS. They’re not changing subsequent years due to uncertainty, which seems unnecessarily cautious to me. Are earnings really going to almost halve to 26.4p in FY 03/2022? That seems highly unlikely to me, but only time will tell. If that gloomy scenario does play out, then the share price is probably high enough for now.
Fund manager Stephen English was brilliant in the latest Mello Monday on 22 Feb 2021. He made a point which in particular stuck in my mind. He said that, for the best companies, analyst forecasts for later years are nearly always far too conservative. That provides an opportunity. I’d add to that my observation that, coming out of a recession (as we are effectively now), analysts also tend to be far too cautious. For some reason, they don’t seem to like factoring in the operational gearing, and strong revenue growth, which usually accompanies an economic recovery. Conversely, when the economy is doing well, they extrapolate out current growth rates forever, with no slowdowns. Too optimistic in the good times, too gloomy is the bad times. Hence why forecast numbers should never be taken as gospel. They're just a starting point, and I frequently adjust them for my own purposes.
My feeling is that G4M was already growing strongly before covid, and in the long-term is likely to be a very much larger, and more profitable company than it is now. The growth runway is massive too - large markets, and global, since it sells almost completely online. All the ingredients seem in place for a long-term major success. So why play around the edges, going in & out of the shares, trying to time the market? I think it’s just a buy & hold forever type of share.
Book recommendation
I’ve been strongly influenced by a superb book that I’m reading at the moment, recommended by a reader, sorry I’ve forgotten who, or I would have mentioned you. It’s called 100 Baggers, by Christopher Mayer, and although I’ve only read 8 chapters so far, have found it full of brilliant insights. Without spoiling the book for you, which I highly recommend, his key point is that history shows that 100-bagger shares are often entrepreneurial, high growth businesses (with a very long growth runway ahead of them), have a high ROE, and great management (who hold lots of shares personally). Investors who have 100-baggers are the ones who buy, and then do nothing. Just buy & hold for 10+ years. It's also a very easy strategy to follow!
He recommends having at least some of your portfolio in a "coffee can" portfolio - which in 20th century America was used by people to store their valuables, in a coffee can. After their death, relatives would apparently find the deceased person's coffee can, containing some long-forgotten stock certificates, one or two of which would be massive multibaggers.
It strikes me that G4M almost perfectly fits the bill for a potential 100 bagger (from its original float price, maybe not from today’s price!). Hence I've put it in the "coffee can" part of my portfolio, along with Boohoo (LON:BOO) and Volex (LON:VLX) . These are shares I don't intend selling ever, unless something serious goes wrong with the fundamental case. But even then, Mayer suggests you should look through bad news, and even be prepared to absorb drawdowns of as much as 50-80% which occur with most 100-baggers.
Just imagine if I'd put my Asos shares in a coffee can years ago! I bought 500,000 Asos shares at about 4p (the all-time low), and sold them a few months later, thinking I'd been terribly clever, more than doubling my money, a profit of £25k, selling at 9p. Those shares would now be worth £29m.
.
Macro thoughts - City centres & offices
I suppose we’re all wondering how quickly people will return to city centres, once lockdown restrictions are removed. Particularly once bars & restaurants are open again. Personally, I’m not too bothered about going shopping in town centres again, but have a long list of friends & city contacts that I’m looking forward to meeting up with again, over long lunches.
Everyone’s different though. When we last discussed this here, several readers pointed out that many women in particular see shopping as a social occasion, to meet up with friends, do some shopping, have a nice lunch, etc.. Therefore we could see people flocking back into city centres, particularly at the weekends. When people are denied access to something they enjoy, it becomes more desirable. Hence I can see why holidays, and city centre shopping & hospitality could see boom times over the summer & maybe beyond.
What about offices though? Has work from home (WFH) changed things forever? Do companies actually need offices any more? Again, everyone has their own view on this, but we’re starting to see some interesting newspaper articles covering what companies are actually going to do. The link above is from the Guardian, reporting that HSBC is planning to slash about 40% of its global office space, and Lloyds Bank 20%. Those are seriously large numbers. Who's going to fill that vacant office space?
The Guardian questions whether this is more about cost-cutting than changing work practices, and also questions the reported figure surveyed of 77% bank employees who want to continue working from home for 3 or more days per week.
Personally I question whether employees really do work as efficiently from home, as they do in an office? I’ve worked from home, on my own, for 19 years now. I find you get into increasingly bizarre working practices, of working in intense bursts, at weird times of the day or night. It’s very difficult to work consistently throughout the day. In some ways that makes me more efficient, working very efficiently with no distractions, when I’m focused on something. Or being 0% efficient, when I’m asleep on the sofa after lunch, or any other time when I feel tired! Can people with kids really get much work done, once they're home from school?
All of which makes me feel that we simply don’t know what’s going to happen in future. Although I have seen enough evidence to convince me that flexible working seems the most likely outcome - people going into the office for some of the time, when it’s necessary, and working from home the rest of the time. That makes hot-desking more likely, and companies needing less office space overall. Which is very bad news for commercial landlords, and commercial property developers. Hence I’m completely avoiding investments in those sectors, regardless of what their figures look like. There could be a risk of buying into value traps, in both those sectors - things that look superficially cheap, but where profits and net asset values could be in a long-term down-trend.
I think it also puts a question mark over retailers & hospitality. Will the weekend trade be enough in future to compensate for probably slower mid-week trade, with fewer people around? It could be. I remember the CEO (I hold) of Revolution Bars (LON:RBG) telling me that “We make our money on Fri & Sat nights”. Hence why the business was so focused on those periods, and it didn’t really matter that they were almost empty during the week. I also remember being asked to help a nightclub owner in 2008-9 who was at his wit's end, by thinking up ways to get people into the site during the week, and the day. He said forget it, it's cheaper to be closed. It's all about maximising the peaks on Fri & Sat. He was right! He became very successful once the economy recovered, with the key element being finding up & coming DJs, then promoting the hell out of their party nights on social media. People came for the music, not anything else. So my ideas (which included ballroom dancing during the weekdays!) were rightly consigned to the ideas dustbin, along with my credibility! Lesson - don't get a former fashion retail FD to advise on how to run a nightclub!!
It will be fascinating to see how all this pans out. I don’t know the answers, but one thing I’m pretty sure about, is that we’re likely to have a bonanza over the summer, with so many households having hoarded cash over the last year. Holidays, hospitality, and maybe retail, look set to be sectors which should see the release of pent-up demand. That’s also why I think fears of a recession, and permanently high unemployment are probably also wide of the mark. The stock market is fairly buoyant, which is telling us that recovery is more likely than a lasting recession. I’m seeing that almost every day in trading updates too - they’re mostly doing better than base case scenarios from last year.
A wave of optimism is at last sweeping the nation, and the stock market.
Should we be selling online retailers? Definitely not, in my view. I think a lot of business has shifted permanently online. There's also evidence to back up this view. If you look back at what happened last summer, when we did re-open for a while, before the second wave covid struck, I recall that a lot of shops didn't actually re-open. Footfall was too low, and many smaller shops remained closed. Footfall was well down in the larger shops.
If you look back at Boohoo (LON:BOO) (I hold) trading updates last year, the group's very strong sales growth during lockdown actually continued unabated despite physical competitors at least partially re-opening over the summer. This is evidence that a lot of retail spending has possibly permanently shifted online. Plus of course the Arcadia shops, and many others, have disappeared altogether, now being online only and owned by Asos and BooHoo mostly.
How much of a danger is an online sales tax? Reader comments have persuaded me that there is an argument for this, mainly to replace lost business rates taxation for the Government. A figure of 3% is mooted. I can't see that doing much damage to online retailers. They'll just put up their prices by 3%. That's not likely to put much of a dent in sales or profit growth, in my opinion, although it's clearly not helpful. It might actually be a long-term help, in driving out some weaker online competition - remember that many online retailers are not profitable, e.g. BooHoo's local competitors MissGuided came very close to going bust a couple of years ago, and has still only recovered to barely breakeven, apparently. The competitive advantage that online retailers have in saving on business rates, is offset by the nightmare of having to deal with 40-50% customer returns, and the necessity for heavy digital marketing spend, to draw customers in. So I remain of the view that a lot of the critical comments, supporting an online sales tax, haven't really thought through the whole business model. Above all High Streets just need lower rents! (and lower business rates, to be fair).
.
Macfarlane (LON:MACF)
94p (up 10%, at 12:35) - mkt cap £148m
To get up to speed, here are my notes from the interim results published on 28 Aug 2020, for the 6 months to 30 June 2020. It’s a neat summary, covering the main points, even if I do say so myself! The short version is that I was generally happy with the numbers, but couldn’t see a lot of upside to the share price (about the same as it is now). Also the pension scheme was sucking £3m p.a. In deficit recovery payments in cash, out of the business. I feel the actual cash drain is far more important than the accounting deficit (which often under-states the scale of the problem). More on that below.
Final Results - for FY 12/2020 - published today. The market likes the numbers, with a share price up 10% today.
EPS 6.45p (up 5.9% on LY) - that’s usefully ahead of the c.6p which I estimated back at the time of the interims (haven’t got access to any broker notes, unfortunately).
.

.
Clearly that’s a solid performance for 2020 in the circumstances.
Adjustments - note that Macfarlane seems to present its numbers without any adjustments, or underlying figures. I see that it is amortising £2.5m p.a. of acquisition-related intangibles through the P&L. Most companies would adjust this out, and show underlying profit of £15.5m, instead of the £13.0m shown above. That’s a 19% improvement, if we manually adjust out the goodwill amortisation.
Applying the same adjustment to EPS, means adjusted EPS would be 7.7p, thus reducing the PER to 12.2 times, as opposed to a PER of 14.6 as reported.
I hope my numbers are correct, I’ve checked back through the 2019 Annual Report (see note 10) and think I’m correct. In other words, if you adjust MACF’s figures to make them comparable with how other companies report profit, then it’s 19% cheaper than it looks on the reported numbers.
Dividend - a big increase. Dividends normalising is a key investing theme at the moment, which I very much like. We can anticipate which companies are likely to be able to resume decent dividends quite easily, by spotting companies that;
- have been trading resiliently in 2020, and
- have sound balance sheets, and
- have previously paid out good divis.
I think at the moment, this manual approach is more important than screening for high yields, because that can throw up a lot of anomalies in unusual times like these. I think it makes more sense to screen on historic yields, than rely on often incorrect or outdated analyst forecast yields, at the moment. The forecast numbers should gradually sort themselves out over time, as companies reinstate guidance, and analysts then have more to base their forecasts on.
Net debt - I’m impressed with this. At the interims, net debt was £0.8m, but had been boosted by £5.4m Govt support & deferral schemes, which it indicated at the time had been repaid in H2.
Therefore, the year end net debt being only £0.5m, means that cashflow has been generated sufficient to cover repayment of Govt support in full - impressive.
Pension deficit - big news here. I tend to ignore accounting deficits, as they’re often wildly different to reality. It’s the actuarial deficit that matters. In this case, the deficit recovery repayments have dropped dramatically, which is great news for shareholders -
The triennial valuation of the pension scheme on 1 May 2020 has now been concluded and the Group has agreed with the Scheme's Trustees to reduce contributions from £3.1m to £1.3m per annum with effect from 1 May 2021. The recovery period for deficit contributions now runs until April 2024.
Bank facilities - look ample, and relatively long-term compared with most other companies I look at - indicating that the bank is comfortable lending to MACF, as they should be - it’s a stable & resilient business -
The Group's bank facility of £30.0m with Lloyds Banking Group has been extended until December 2025 and accommodates normal working capital requirements as well as supporting acquisition funding.
Balance sheet - looks OK. NTAV is about £19.2m, which seems adequate. With net debt reduced a lot, and the pension scheme drawing out less in cash recovery payments, then I think there’s scope here for more acquisitions, and increased divis. No risk of dilution.
Outlook - this seems reassuring -
2021 has started well despite the ongoing impact of Covid-19. There are still significant uncertainties about the duration of disruption caused by lockdowns and the consequential impact on demand levels which means that 2021 will be another challenging year. However the Board is confident that, given the resilience seen in 2020, the strength of our business model and the commitment of our people, Macfarlane Group will progress in 2021 and is well positioned to benefit when the UK economy begins to recover.
Cashflow statement - looks strikingly cash generative, but do remember that IFRS 16 has messed things up. So ensure you take into account the £6.7m “repayment of leases” which is in the wrong place thanks to IFRS 16, down at the bottom in “financing activities”. Hence all the numbers above that line are over-stating real world cashflow. Not MACF’s fault, it’s the damage done by IFRS 16, which needs to be eliminated from accounts to give a meaningful view.
Hence we need to re-work the cashflow numbers to manually move the £6.7m lease repayments up the cashflow statement, out of financing activities, and instead put it higher up as a deduction from operating cashflow.
Even when you make this amendment, the cash generation is still very impressive.
My opinion - I question why MACF has a manufacturing division, as it is now barely operating above breakeven. How does it add value? Does it have turnaround potential? Thankfully the main packaging division, is strongly profitable.
Overall, this share gets a thumbs up from me. It looks a decent, resilient business, and is attractively priced, especially when you adjust out the goodwill amortisation charge, which is what other companies generally do.
Cash generation is good, it’s paid down the net debt, the pension scheme is now much less of a cash drain, the balance sheet looks fine, and divis are being restored to pre-covid levels.
It’s not going to set your portfolio on fire, but as a sensible value share, to hold long-term, I think this could be a good entry point.
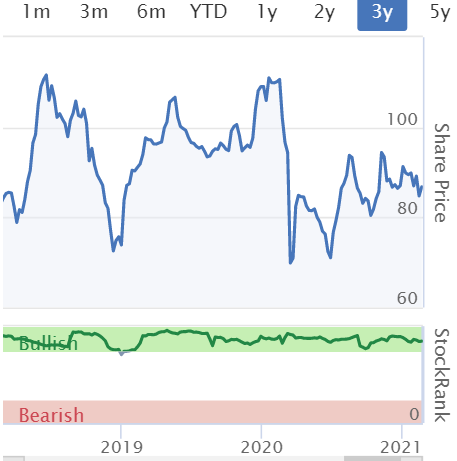
The share price oscillated sideways for the last 3 years. That doesn't necessarily mean it will do the same thing for the next 3 years though.
.
.
Jack's section
Ricardo (LON:RCDO)
Share price: 467p (-1.06%)
Shares in issue: 62,218,280
Market cap: £290.6m
Ricardo (LON:RCDO) is a global strategic engineering and environmental consultancy that specialises in the transport, energy and scarce resources sectors.
Its work encompasses a broad spread of sectors including passenger cars, commercial vehicles, rail, defence, motorsport, energy and environment. Within these sectors, the group covers a wide range of assignments including strategy development, cost reduction, safety management, regulatory compliance and environmental impact assessments.
The past year has been rough for such companies but note Ricardo was underperforming the market before Covid. So that’s something to look into.

The share price has recovered partially since we last covered it in November 2020, from around 350p to today’s 472p. Back then, the group had just RNSd an update and a proposed placing.
In January Ricardo released an ‘in-line’ half year update (Management succession plan and trading update - January 25th) and today we get the more detailed results for that period. Dave Shemmans, the CEO for the past 15 years, is leaving but this was flagged previously.
Highlights:
- Order intake, revenue and operating profit have all increased on the six months to June 2020, but remain lower year-on-year;
- Revenue down 15% year-on-year to £164.7m;
- Underlying profit before tax down 69% to £5m; statutory loss before tax of -£2.1m;
- Automotive market is improving slowly; good performance in Energy & Environment and Rail; Performance Products in line with management expectations;
- Share placing completed, raising £28m, ‘to reset the capital structure of the group’; net debt of £50.4m
- Interim dividend of 1.75p declared.
CEO Shemmans comments:
Whilst the economic outlook continues to remain uncertain, we have a robust order book, good pipeline of opportunities and our diversified business platform offers leading edge capabilities to support the global environmental agenda. We remain cautiously optimistic about the economic recovery and for further progress of the business as we deliver on our strategy.
The net debt improvement reflects £28.2m of proceeds, net of fees, from the share placing in November 2020, and a strong working capital performance. Excluding the placing, restructuring costs and acquisition-related payments, the group generated a net cash inflow of c.£3.0m in the half (and the whole of the 2020 calendar year).
Order intake of £181.1m represents a decline of 13% on HY 2019/20, however it is a 13% increase on the six months to 30 June 2020, indicating that order volumes are recovering from the impact of COVID-19.
Conclusion
Management is keen to impress a sense of sequential improvement, with conditions recovering and a positive trading trajectory.
Whilst the economic outlook continues to remain uncertain, the company continues to trade and looks well placed for a global recovery with its strategic focus on the Net Zero agenda.
It could be one to watch. Yes, Ricardo has made a loss for the period, but given what companies have endured over the past year or so, a small loss in that context is not so bad. And before Covid, Ricardo was busily building a solid track record of top line growth.

Although brokers have been nudging down earnings estimates, they all rate RCDO as either a buy or a strong buy and expect revenue to more or less recover to FY19 levels by FY22. That’s no substitute for your own research, but the forecast PEG of 0.8x does suggest the stock offers value if it can hit targets.

Not one I have a strong view on but it could be worth a closer look for those interested in this kind of recovery play. The reinstated dividend is cause for cautious optimism.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Re. changes in working patterns, interesting snippet on the wireless today that Network Rail is contemplating moving essential track-closure maintenance to weekdays, rather than the traditional weekend, as the travelling population is likely to be lower during the working week for the foreseeable future while leisure travel will recover sooner https://www.theguardian.com/uk...
Quick note on the continuing IG saga.
I had sold out of my Polymetal International (LON:POLY) position on IG yesterday at a profit (a £7b company - this isn’t about size for them, it’s about what is profitable). I was expecting the price to recover so decided to reopen the position as it fell but market was closed all day on SpreadEx and Spreadco. Called SpreadEx in the afternoon and was told they had suspended trading on the 900 companies in the IG list and might be a month+ until they worked out what they were doing moving forward.
3 points:
1) IG changes forced my sale yesterday and not getting back on Polymetal International (LON:POLY) today saved me money as price didn’t bottom as I expected and gold is yet again flirting with bottom level. No bitterness from me.
2) This will have a major effect on small cap trading over the next few months. It’s been an incredibly profitable hunting ground for me over the past 10 months but might be that is gone. If IG removing markets effectively causes rest of players to do same, trade in small caps must reduce. If access to cheap credit (at IGs expense) is being withdrawn, effectively the ability for PIs to influence prices is significantly reduced. I’m surprised how far this is reaching...
3) I couldn’t be more complementary about SpreadEx here. Picked up the phone on the third ring, it was a voice and name I know, he happily spent ten minutes+ talking me through their position. I can’t ask for more than that.
4) While this business is obviously not profitable enough versus risk taken on for IG, this is the core offering/ differentiation of SpreadEx’s business. It’s important to them so my guess is they will solve this although this trade is likely to become a lot more expensive for PIs.
With ref to Macfarlane (LON:MACF) and having been in the packaging industry for 30 years, I'm not at all surprised by their results (I don't hold). The sheer demand for home deliveries in 2020 due to Covid has been a godsend for many existing and "covid-converted" e-commerce businesses - the packaging industry has followed. Since the start of this year, the price of paper and plastic raw materials have rocketed so unless packaging companies are able to pass those costs on to the end user, the 2020 levels of profitability are going to be hard to repeat in 2021.
My lead time for a lot of the Packaging I order has gone from next day to up to as month and beyond. I would say around 25% of our warehouse is used to store cardboard boxes at the moment to guarantee supply, it is unusual and costly.
A major fustercluck for UK_Investor:
EVRAZ (LON:EVR) has had a good day closing @598p. A 30 cents Interim Dividend to come for holders.
My error has cost me about £18K, about 9% too early not including the yield missed. Believe me, I will be taking this out on myself, and analysing my error for weeks to come.
XLMedia (LON:XLM) has closed +9% which helps me. Patience of a saint required.
Today, I've bought £50K in Centamin (LON:CEY) @106p.
Centamin is looking very unloved, is Number 4 on my Magic Formula screen. Centamin has been depressed since its profit warning of September in 2020 re a potential mine collapse.
I figure its been dead quiet on Centamin, and so after 5 months of negative momentum, the chance of a turn around is increased in the next 3 months.
(This is how my best profits usually begin... pure blind jumping... based on StockRanks and Magic Formula. Who knows? Not I!)
SR83 Q99 V93 M13 Yield 5.9 PE 10.4
I've parked £30K on British American Tobacco (LON:BATS). BATS is Number 2 on my Magic Formula screen. Again, it looks unloved, has deep value, has growth indicators,
SR 84 Q81 V94 M30 Yield 8.6% PE 7.7
A look at BATS history, suggests to me it falls in Q1, has a revive in April typically. It looks weak to me on its yearly chart.
I seriously had a look at Boohoo (LON:BOO) - Not sure its the right moment to jump in. I prefer a little more weakness in the price, if I was so lucky.
I regret missing my chance on Saga (LON:SAGA) - Again, not so sure about now as the timing. (I don't quiet trust HM Government / The Media narrative that the faux crisis is over yet - I fear more nonsense to come.)
With my 24% in cash today + book, I am within 0.5% of my highest valuation ever recorded.
Perhaps as dear Paul rightly said... one shouldn't be too greedy!!!!!
Amazing outcome on Sylvania Platinum (LON:SLP) for Silver Moon above! Well played!
Cheers to you Investor 8888 , I've been quietly confident all along about Sylvania Platinum (LON:SLP) while I hold Centamin (LON:CEY) and think there could be a political taint beyond the landslide. Maybe governments want a bigger slice from miners even as big as Rio Tinto (LON:RIO) so I tread carefully. Xlmedia (LON:XLM) is a personal disaster are having greatly increased my stake just as Google bashed it about. British American Tobacco (LON:BATS) was put on my buy list last week, now to look for some funds!
Silver
Paul - feeling your pain re ASOS.
Could be worse, you could be the guy that threw away a hard drive with 100's of Bitcoin on (now he is offering the local council millions to dig the landfill up). Every time BC goes up must open the wound even further :-(
https://www.bbc.co.uk/news/uk-...
There is a start up I know which offers just this service Andco www. andco.life. For 20 a month you get your pick of bars/restaurants/hotels etc to pop in and work from.... Works well or did when they were open. Worth a look
One solution for bars might be to offer their tables / spaces out to rent in the week for people who are working remotely but dont have the office space at home or dont want to be at home (cos of the kids). Pay a rate for a day, and get free wifi, water and coffee all day. Plus networking with others in a similar boat. Or even rent out to companies who no longer need as much office space. Im sure it could be a nice little earner if done right, especially for those bars who get very little revenue during the week.
Pre pandemic you call already use Wetherspoons as a virtual office, for the princely sum of something like £1.10 for an all day refillable coffee.
Not much of a money spinner I would imagine!
Superb reflections Paul-we all have a tale of one stock that went to the Moon and we sold out early - as you quite rightly point out its what is the next 10/100 bagger and whether we can be disciplined enough to wait. Time favours the value investor.
Really enjoy reading your articles -watch out John Le Carre..
Sylvania Platinum (LON:SLP) is quite the Value share. I see in my spreadsheet that I bought at 10.35 pence in 2017 and sold it at 22.35 pence in 2018. Re-bought into my ISA and there they have been added to from time-to-time. Last Friday was the last date to have bought, at 118 pence and no regrets. A rare occurrence in my portfolios though, it is mostly as UK_Investor_8888 does.
Paul, that comment on those Asos shares (£29m value today) reminds me of Roy Raymond, the founder of Victoria’s Secret. He sold the company for $1m and then it exploded. Missing out (on the money and those catwalk shows!!) depressed him so much he ended up jumping off the Golden Gate bridge aged only 46. You seem to be holding up a little better!
Hi Nebraska1977,
That's a sad story, what a pity, and a waste of a life.
I try to channel my mind into thinking positively, and never looking back, other than to learn lessons from my mistakes. But time spent agonising on what ifs, and if onlys, is time not only wasted, but also self-destructive. We can't change anything in the past, so there's absolutely no point in having regrets at all.
I see my Asos story as more amusing than anything else! Of course I couldn't have possibly known that it would go up over 1,000 times from my 4p original purchase price. I made a logical buy decision, it was a tiny speculative company that looked interesting, and my sale at 9p was also logical at the time - I'd made a nice, fast profit, and it looked expensive on a PER of 29.
What could I have done differently? Probably a smaller position size would have been better, because my portfolio was small at the time, and putting £20k into one stock, which quickly became £45k, was too big a temptation to bank the profit. Hence it would have been better if I had put say £5k into Asos at 4p, then just treated it as a small speculative, long-term position, and just put it away & forgotten about it.
Ironically then, maybe 100 baggers are more likely if we originally just invest a smallish amount, and forget about it?
The other thing was, that I resolved to sit tight & not sell too early, when I found the next Asos. Hence when Boohoo (LON:BOO) (I hold) came along in about 2015, I was raving about it here when it bottomed out at about 23p. But I made the same mistake again! Instead of just buying a smallish position & forgetting about it, I put £100k into it, and then when it had more than doubled, the temptation to sell became too strong, and I sold out between about 50-100p.
Thankfully, the supply chain issue provided a nice opportunity to buy back in last year, at 200-300p, and I'm still buying now.
Trouble is, I've probably made the same mistake for a third time, of over-sizing the position size again, and hence the next big leg up will probably prove too tempting again, and I'll no doubt sell BOO too early again, if it gets up to say 600-800p, where it would be very tempting to sell, in the shorter term anyway.
Maybe I should resolve to designate a certain percentage of my BOO holding as being forever, and only make the balance eligible for selling before say 10 years?
All good to ponder, for future strategy. But never worth wasting a moment over, in terms of "if only" I'd done something different.
Regards, Paul.
Hi Paul
Your commentary reminds me of the Raider versus Connoisseur style of trading as outlined in the 'The Art of Execution' by Lee Freeman-Shor.
If you haven't read this book already, I'd suggest you might find it very interesting given his contention that execution approach makes a fundamental difference to overall returns.
Regarding stock analysis, I think you've pretty much got that covered!
Cheers,
Mark
Powerful - well said, forever forward!
Paul
I think top slicing is the key to very big multi-baggers. As you say just because a stock starts to make it and doubles/trebles doesn't mean it will continue in perpetuity, no matter our confidence in it, or its prospects. How many of us have the foresight to pick the precise very few companies this will happen to over a decade and stick with them through thick and thin? History is littered with far more stocks that appeared to be doing well and then didn't than those that continue to power ahead!
My strategy is to top slice. As an example I was lucky enough to own Argo (LON:ARGO) at sub 10p and understood the company well enough to know it could easily go up 10 times. As it started to fly and got to 75p I sold 1/3rd. At 150p I sold 20%, then 10% at 225p and 10% at 275p so although my 75p sale looks somewhat early my average sale price to date is 150p or 15* my money and I have some stock left I can leave on if I think the company can justify it going forward.
I find this strategy does 3 things.
1) If I'm ultimately wrong on a share I've still made money
2) I don't sell too early and look wistfully on as the stock powers ahead. Instead I take a good chunk of the available profit on offer.
3) I don't sit there anxiously trying to decide if I should be selling every time the stock moves a few % down because it has become such a large portion of my portfolio. It allows me to take that longer view - ie if I think a macro trend will give them a strong tailwind for a few years.
Paul - regarding your comments on working from home/hospitality industry there are some very interesting points in the video Tamzin pointed to earlier - https://www.piworld.co.uk/2021/02/25/various-eateries-vare-full-year-2020-results-overview/
In particular the all-day Coppa brand of Various Eateries (LON:VARE) see potential for working from home becoming working from one of their venues (5m 23s in). I imagine Loungers (LON:LGRS) could also work that niche.
EVRAZ (LON:EVR) touching 597p +5.7% today now.
UK_Investor has a tremendous sense of self-loathing having sold on Tuesday and missed +9% and an Interim Dividend.
This is a classic case of Investor folly: To act too soon or unnecessarily sabotages a rising investment. I've made this mistake too many times.
XLMedia (LON:XLM) is spiking +7% at the moment. I notice XLM often does this on a Thursday afternoon, its all absorbed by Friday lunchtime. I'm NOT touching it. It will do whatever the opposite I do.
Its not the wins one notices, its the losses!
I think that there are a lot of frustrations out there at the moment, the build up to results and a large spike down the day that they come out, even if they are good news. Then a large move upwards.
I can say the same as you selling Sylvania Platinum (LON:SLP) for example then watching today
I still have not worked out what I am trying to do, other than buy high, sell low, buy back higher than before, sell even lower than before seems to consistently work for me FOMO
Card Factory (LON:CARD)
a bit frustrating as a non holder (with regard to my attempt at bottom fishing this one once banking issues are sorted) here that despite the company not having sorted out the covenant breaches problem the shareprice seems to be gaining some great momentum - not sure if this is leaky info coming out that they have some good news to announce later today otr tomorrow. All very frustrating in that it now looks like by the time the funding is sorted the price will already be up perhaps 50% from the recent lows - sigh.
So whilst i know not investing without the good news that will surely be coming tomorrow morning ? was probably the right decision - it looks like a bargain to be had may have been missed. At least being on the sidelines if it does get messy with the banking issues i will avoid that potential banana skin. Peversely the higher the price goes i a suspect the less shareholders will be worried about the dilution that will probably arrive tomorrow. Lets hope small shareholders are not scerwed over if/when funds are raised.
Am i alone in thinking its very poor leadership here leaving these banking covenant issues till the last minute ? perhaps they are playing hardball with the bank or praying for shareprice bounce (they have got that wich:)) but it just seems like this should have been fully put to bed last month if not earlier. I know the dbet is chunky but the buisness model and future prospects should be reasonably clear (and good).
Re Card Factory (LON:CARD) and "Lets hope small shareholders are not scerwed over if/when funds are raised"
As a holder I obviously agree - especially as unlike raises in March 20, this has been coming for months ie time to have organised a fairly generous open offer. Real test of Mgt concern for smaller holders.
With Moonpig (LON:MOON) valuation settling at +/- £1.5Bn it shows the value of the card market - especially when even the Moonpig IPO file expected offline to be the majority (>75% from memory) of the market still in 5 years time where CARD absolutely dominate. With their brand and a new MD coming, they should be able to get a much bigger online share share as well. Very quickly cash positive once re-opens.
I am very ready to support the business if given a chance. Even at 50p, I think the risk/reward is good on a 2 year basis.
The problem for CARD, like other retailers, is how much footfall has been permanently lost from the high street. I'd be amazed if senior debt were going to be generous ( though price action seems to be suggesting otherwise..)
Re Card Factory (LON:CARD) and reduced footfall, I think the LT impact will turn on the type of retail and margin. Fashion will be a permanent loser but cards are high margin, low cost purchases picked up just before need (B'day, kids party). So whilst weak competitors (Clintons, Cards Galore) may suffer, IMHO think CARD will come back OK - pre-COVID its margin were best-in-class.
Can you explain the 'senior debt' comment. My working assumption is that whilst not good to breach covenants (!), actually CARD should be able to get someone to fund them urgently to avoid this if necessary so existing lenders do not own all the cards? If this is wrong, my position is much weaker.
Card Factory (LON:CARD)
actually CARD should be able to get someone to fund them urgently to avoid this if necessary so existing lenders do not own all the cards? If this is wrong, my position is much weaker.
I guess we follow things at its most basic level - the banking covenents have probably already been breached based on january announcement - so come 1st March unless they advise otherwise i would presume covenants have been breached - that presumably gives the right to whoever has issued that debt to take whatever action they deem necessary withi the agreed rules between the two parties and that presumably may not end pretty.
Practicably speaking i think we are all agreed this should probably not be an issue and that funding will turn up or covenants will probably be waived again but the lack of confirmation of funds being in place suggests they need to sort something in the next 36 hours (possibly 48 hours more if they need to go to the weekend) - not really ideal position. I have witheld investing more due to the uncertainty of how much dilution will be at play and what price that dilution will be at (£60 mill at 25p??) rather than concerns over the ability to get funsing sorted end of - but i am guessing if they cant sort something by monday the current debt providers could turn nasty if they so chose? - presumably we would need to specifically ask the company what the consequences of failing the covenant test are to know how nasty this could be.
I'm not sure Peter, but if i were a lender to retail at the moment I'd want it off the books or charge appropriately for it until clarity returns, especially if they have a weak online presence. Its impossible to predict footfall going forward.
Also don't forget they have circa £30m seasonal stock ( Mothers Day, Valentine, Easter ) left unsold. They can sell it next year but likely to accelerate cash flow problems..
is £card on igg list shorts being closed?
Here are my SCVR heat maps for today (prices as at ~9am). Sorry for the delay, I am absolutely convinced I'd posted it earlier but...
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
EVRAZ (LON:EVR) FY report looks pretty good, with some areas I notice as contra-indicators.
I'll unsystematically read out my notes.
Net debt is down only 2.6%
Cash flow is down 20%
The Net Profit is massive, possibly a massaged figure.
It reports cost decreases over 2020.
Interim Dividend of US 30 cents a share.
All the detail at
https://www.stockopedia.com/share-prices/evraz-LON:EVR/news/evraz-plc-annual-financial-report-urn:newsml:reuters.com:20210225:nRSY3208Qa/
Attention all investors: As I sold @543.86p on Tuesday, you can be sure its price will rise thereafter, currently 576p.
I sold Gear4music Holdings (LON:G4M) last year. Re customer service I submitted an order (in stock online) with G4M beginning of December and received the items Monday this week, delays somewhere in the chain. I changed the delivery address on their system, and phoned and spoke to a customer service rep who stated the order hasn't been despatched yet so I can sort with the courier. I asked for a call back to confirm, but the rep wouldn't agree to this request, I then received an email stating the items might arrive at the old address. The items arrived at the old address 200 miles away, and a neighbour phoned me to ask for instructions for the courier. It wasn't a good customer experience, however, saying that their website is excellent and customer reps have a good knowledge of the products (need to improve problem resolution) and they did apologise for this issue. All companies can improve processes and procedures and I'm sure G4M will make continuous improvements, and online is certainly the place to be right now. I'm talking myself into buying G4M again.
I have some doubts about the sustainability of sales growth at Gear4music Holdings (LON:G4M) . No doubt the company has been a lockdown winner but as people start to leave their homes again many will lose interest in their instruments and there will be a surge of secondhand supply via sites like ebay and gumtree. Not too different to the collapse in dog prices we are now seeing. Also there are many established online music retailers in Europe so I think the expansion potential there is limited. The shares have had a great run and if I held I'd likely take profits.
I too sold G4m a couple of months before lockdown, for a very modest profit, thinking it had spent too much time going nowhere... Possibly my worst-ever-timed disposal. Ho hum.
Hi Paul - Gear4music Holdings (LON:G4M) I am also a holder. I believe the 2021 forecasts are basically withdrawn rather than analysts "expectations" for the year. Whilst some analysts withdrew guidance altogether for lots of stocks with this one they just didn't update on the back of Covid uncertainty. Thus guidance hasn't changed at all despite trading, margins etc.
Unfortunately I think this approach is somewhat unhelpful to holders as I think it is having quite an impact on restraining the share price unnecessarily alas. I agree with you that the PER is miserly.
Gear4music Holdings (LON:G4M) have quite a lot of operational gearing. From memory their fixed cost base is around £17m so when they same gross margin is 30% most of this drops straight to p&l now and can have quite an impact on EPS. It wouldn't surprise me to see revenues up just a couple of % next year but with EPS pushing closer to 60p. If the core market is growing at even 7-10% (and I think it is higher) then the reduction from perceived "one off" covid sale increases is actually more than offset by this growth so you could reasonably expect overall revenues to still go up next year, albeit at a much small pace, but EPS should still go up 20%.
Anyway we will see. Hopefully I'm right :)
The EPS will increase from 12p last year to 50p. I just struggle to believe that earnings could have increased by anything like this much without Covid, although very difficult to put a figure on it. I do know that all sorts of products where in very limited supply and people were willing to pay well over the odds (from my own experience I tried desperately to buy a kettlebell and ended up paying over £100!). I'm just wondering if there has been a huge one-off margin boost that could unwind next year? Would be interested to hear other thoughts.
Do you have any comments on price rise for Big Dish (DISH) consequent on proposed name change to Amarla foods?
Do you have any comments on price rise for Big Dish (DISH) consequent on proposed name change to Amarla foods?
Not really, it's just a name change to reflect the changed strategy they previously announced. So can't see why that would be price-sensitive. But markets are not rational at the moment, so it's generally pointless trying to work out why prices are moving in whatever direction they are! Just speculative money flowing in & out of things.
Another pie in the sky valuation - $JOBY. It is all looking a bit frothy over there.
https://on.ft.com/3aRR1wH
More interesting interim results from CAP- XX ( Cap Xx (LON:CPX) ) ( I hold ) an Australian producer of Supercapacitors and energy management systems operating in the world of the Internet of Things . The company has been going nowhere for a long time but their R & D and subsequent intellectual property now appears to be bearing fruit - the IP has been tested in the USA and so far it is 1-0 to CAP-XX with one more ( a subsidiary of Tesla ) to go . Their unique selling point is that they produce the world's thinnest high power supercapacitors and are now gaining traction with the order book double the level of the same time last year driven by IOT markets . Potential demand already exceeds the annual capicity of the new factory they have set up .
Very much a micro cap but operating in a potentially huge market and more importantly with solid IP - another disruptor .
I agree with your view fred. I am also a holder of CAP XX (LON:CPX). A cursory read of the results indicates they they are potentially seeing more orders than available capacity...so a nice problem to have. News on patent infringement cases could break anytime.Also getting traction with an auto supplier and a smartphone company.
Another vote for a look at Macfarlane (LON:MACF) please. I agree with comments below - this is a fantastic result. They are ahead of last year on almost every metric despite COVID impacting their automotive and other business - build in likely an uptick in some of those industries for H2 of this year and material growth looks very likely.
Better still, they are rapidly turning into a cash generating machine - this year alone (in an extremely difficult COVID year...) they managed to pay off 10.5m of bank debt, make 3.3m in pension contributions and still end up with 2m more cash than they started with this time last year. The really exciting bit is that next year there is almost no debt left to pay off, and the pension scheme contributions have just been revalued and are dropping by 2m a year to just 1.3m. So even if revenue was the same this year as last (very unlikely - it seems sure to be higher) they would have about 12m extra cash generated this year compared to last (for a business with a market cap of just 134m this is extraordinary). Granted, last year they cancelled the final dividend, but even if we were to say this comes back it only strips out around 2m cash, so they are still +10m over last year in cash terms, without even factoring in any growth at all (and of course that 2m comes straight to shareholders as a dividend too which is a useful extra).
Management are conservative here and the report is notably lacking in any marketing blurb or enthusiastic management exuberance - the tone is very much "yes, we are ticking along nicely, and yes we think we will continue to do so next year, but lets not get complacent - we've got work to do and times are uncertain" - I like this a lot as a management style. They could easily have talked these results up a lot more and consequently I expect this stock will continue to stay a bit under the radar for now, however I expect when people start to see the results of what's going on here - a debt-free cash machine in the making with a growth aspect from e-commerce thrown in - we may well see a re-rating over the next 12 to 18 months. It's not a shoot the lights out share but it looks like one of the most robust slow and steady bets out there for my money.
BIACS
I agree with BIACS Macfarlane (LON:MACF) comments but I have held them in the past and they never seemed to go anywhere and I lost interest, although had anyone held them for the past 7 or so years they would have done very well. I was aware the results were coming out and thought about buying last week but then forgot. The only downside is that the spread is a bit wide on occasions and I can't help thinking when I look at the packaging arriving on an almost daily basis at our house that they should have increased sales over the past year by 20%!
I don't see why packaging should necessarily have gone up so much. Not going out much, I'm buying far less than I normally do. I might have more home delivery, but all the packaging to get stuff to shops will have dropped significantly. Think MACF should be looking at share buy-backs now with all the cash they will be generating. But, based on the cash flow performance, I have to think they will become a takeover target soon if management don't do a better job at getting the business value reflected in the share price. Being cautious and overdelivering on promises is good to a point, but most other management teams would have been hailing today's results from the rooftops.
Macfarlane (LON:MACF). Because of lockdown, more people are ordering online, so more packaging. I live is a small road, can't believe how many deliveries per day the neighbours have and it's not food either.
Shops tend to have large deliveries, not one package per item?
I'm working on Macfarlane (LON:MACF) now, section should be up by about 4pm hopefully.
Two results with overview videos by management:
Dotdigital (LON:DOTD) interim results. Milan Patel, CEO, outlines the key drivers during the period, including new and existing customers, with SMS channels being particularly strong. Growth still comes from product innovation, strategic partnerships and geographic expansion. Digital spend is going up, accelerated by CV19. Paraag Amin, CFO, summarises the financials with 22% revenue growth, 93% of which is recurring revenue; with ebitda margin 37%; and Adj op profit 27%. Cash £27.6m. For the outlook, DOTD experiences strong trading momentum as global digital marketing spend continues to grow dramatically. Video & Podcast.
Various Eateries (LON:VARE) FY20 results overview with Andy Bassadone, Chairman, Yishay Malkov, CEO & Oli Williams, CFO, who outline the business, and the opportunities in the post CV19 world. They highlight that they are an experienced management team, confident in their brands with a strong balance sheet. They face a market of pent-up demand, less competition, a massive choice of sites and great talent. They say they are ‘a coiled spring ready to pounce!’ Video & Podcast. Quite interesting how they see the eating out / entertainment market post CV19.
Whoever came up with the name “Various Eateries” should be banned from ever naming anything again. Seriously, they’re a mid to high end bar/restaurant and they might as well have called themselves “whatever, we can’t be bothered to think of a decent name”.
One hopes they take more care and pride in the actual running of the business.
I like the name - I think its amusing.
Looks to me like the company may have to do another fund raise.
Another profit upgrade this morning from Gear4music Holdings (LON:G4M) with the broker Progressive Equity now suggesting 50.9p fully adjusted EPS for this financial year ending 3/21 (their research is free to access). The broker has consistently decided not to upgrade their broker forecasts for FY22 and continues to leave it at 26.4p - I think this is probably an underestimate given this was set before the present lockdown and people will largely still be at home in the early part of April and no major international holidaying until at least July. (I am making an assumption Gear4music Holdings (LON:G4M) is benefiting significantly from people not being able to go out as much but stay at home and play music). I hold. It is also interesting to note the broker is suggesting margins fall next year and the year after so as well as benefiting revenues, there may have been some COVID margin boost with high demand?
My morning smallcap tweet:
£7DIG Dev Clever Holdings (LON:DEV) Asimilar (LON:ASLR) £G4M Trakm8 Holdings (LON:TRAK) Digitalbox (LON:DBOX) Ilika (LON:IKA) Macfarlane (LON:MACF), CAP XX (LON:CPX)
7digital (7DIG) wins 2 year contract from FORME Life to cache or stream music content that can then be synchronised with a training video. The FORME Life hardware and programming launches in Spring 2021 in the US. No $$$. [SP=1.44 Cap=39m]
Dev Clever (DEV) Novation of subscription agreement from One Nine Two Pte Ltd to Sitius, an investment vehicle wholly owned by Dr David vonRosen. Sitius has conditionally agreed to acquire a material interest in the Company by way of entering into a series of transactions. Also Grant of Call Option agreement by CEO to Sitius. [SP=26.8 Cap=137m]
Asimilar (ASLR) subsidiary has assigned its right to subscribe for up to 30m shares in Dev Clever to Sitius. See DEV RNS. [SP=32.22 Cap=35m]
Gear4music (G4M) FY(Mar) EBITDA guidance hiked to at least £18.2m (prev £16.5m). [SP=713.51 Cap=149m]
Trakm8 (TRAK) wins long term contract for over 1,000 RH600 integrated telematics and cameras systems. No £££. Guides H2 rev up 15% on H1, FY 20% down. [SP=14.75 Cap=7m]
Digitalbox (DBOX) guides FY(Dec) rev flat at c.£2.2m and adj EBITDA c. £0.3m (£0.5m). Q1 trading ahead of initial expectations. "Digitalbox made significant and exciting progress through these challenging times." Well the numbers don't say that. [SP=6.13 Cap=7m]
Ilika (IKA) Stereax new factory update. Doesn't think construction material shortages will have a fundamental effect on expected timings. So nothing new really but IKA uses RNSs like an airbed pump for its shares. [SP=215 Cap=299m]
Macfarlane (MACF) FY(Dec) ahead of mgmt's previous expectations. Rev up 2%, EPS up 6%, FY div 2.55p (0.69p). [SP=85 Cap=134m]
In line: CAP XX (LON:CPX)
Great results from Macfarlane (LON:MACF) today [I hold], ahead of the previous year, ahead of my projections and even further ahead of broker consensus.
As well as revenue, profits and dividend going up, net debt has gone down materially (with all government support repaid) and the pension scheme deficit has almost gone (£6.5m down to £1.5m). This last outcome is in stark contrast to most companies with pension deficits and is due to Macfarlane's clever use of liability-driven assets.
I consider this a real QARP business, the likes of which are scarce in the current market.
I’m very happy with Macfarlane (LON:MACF) results and glad I jumped in at 88p recently. Yes they’ve been cheaper since but I really hope to see a re-rate from here.
As you say, to me skimming the results it looks like last year’s cancelled dividend has enabled them to be virtually debt free and they’ve already got a £1.8m tailwind next year with the pension scheme payments reducing by that amount.
Hopefully being virtually debt free will give the board confidence in their abilities and we can start seeing them stretching their legs with acquisitions and growth. I was just going to play this as a trade on a much overlooked share, but actually I’m thinking this year’s results will act as a springboard and I’ll look to hold a bit longer.
Re Macfarlane (LON:MACF)
EC and Igotpoes - good points and I agree with you. For some reason and despite signaling their improving figures this one is still not on the radar?
I also note that that there is £1.5m in bad debt and end of lease provisions holding back the profits uplift in packaging distribution in this years figures - seems a little convenient to me and perhaps a tad generous. A little put by for this year maybe? if you add that to the pension uplift then they already have this years forecast figures in the bag? Cue - a profits upgrade perhaps? and maybe in turn an uprating of the shareprice on the way? Hope I can grab a few more before then...... 12p does seem such a long time ago now?
cheers