Small Cap Value Report (Thu 25 Oct 2018) - DEB, SCS, DIS, BEG, FTC, ALU, ECK

Good morning! It's Paul here.
Please see the header for the announcements that I intend reporting on today.
Do let me know, in the comments, if you spot anything else interesting.
Market comments
US markets were wobbly again last night, so we're probably likely to suffer more pain today in the UK. Such is life - corrections happen from time to time.
It seems to me that this market is now throwing up some bargains. Quite a few of the stocks that I own, or are on my watchlist, have reported good figures & outlook, yet in some cases are now 20-40% cheaper than they were only a few weeks ago. That doesn't make sense to me. Maybe they were over-priced to begin with, but not that much.
The falls in price have generally happened on lowish volumes, in most of my small cap stocks. I find that reassuring. It's a combination of a few nervous small shareholders selling up, and a buyers' strike because of concerns over the US markets falling, Brexit, Corbyn, Italian/Eurozone crisis, China, trade wars, and anything else you can think of!
In one extreme case, a very illiquid micro cap stock I hold, Malvern International (LON:MLVN) , some idiot sold a few thousand pounds-worth of the share, and the resulting fall in share price knocked c.£50k off the value of my shareholding! As you can imagine, I wasn't best pleased, but we have to accept volatility & illiquidity as the price we pay for operating in a very imperfect market. That imperfection is also what creates the upside opportunities. So it means that prices rise fast, when good news comes out. If you operate in the micro cap space, you have to learn to live with volatile prices.
It's important to remember that, with illiquid micro caps, the share price is quite artificial. It can go all over the place, in the short term, on tiny volume. Therefore the chart patterns in small caps mean nothing, and the share price isn't a very good way of valuing the company, in the short term anyway.
Someone reminded me yesterday of a good Buffett quote about wanting to be being greedy when others are fearful, and fearful when others are greedy.
Although as always, we have to be very selective in picking the right stocks. I'm thinking about doing some shopping, as there really are some attractive opportunities out there at the moment. After all, BLASH is a good motto (Buy Low And Sell High).
I suspect that the momentum trade may have ended now - i.e. buying anything that keeps going up, without needing to do any research at all. I can't stand it when that approach works so well, as it has in recent years, because that means the laziest and stupidest people make the most money!
Maybe we're now going back into historically more normal market conditions, where volatility has returned, and you can't rely on momentum only to succeed? Instead, stock picking on fundamentals might now be the more important skill once again. I do hope so.
Debenhams (LON:DEB)
Share price: 10.0p (up 17.4% today, at 11:01)
No. shares: 1,227.8m
Market cap: £122.8m
Preliminary results & strategic update
Retailer Debenhams plc today announces preliminary results for the 52 weeks to 1 September 2018, confirming the EBITDA, pre-exceptional profit before tax and net debt data released on 10 September 2018.
Key points;
- Gross transaction value down 1.8% to £2,900.4, of which 79% is UK, 21% overseas
- Statutory revenue £2,277m. The difference is mainly that GTV above includes sales from concessions (stores within a store, operated by third parties)
- Underlying profit before tax down 65% to £33.2m. That ties in with the estimate of c.£33m published by the company here on 10 Sep 2018.
- Pre-exceptional EBITDA is still good, at £157.3m (down 28% on LY). EBITDA is a good proxy for cash generation at retailers. However, department stores are so large, that they require continuous large maintenance capex. So it's fairly meaningless here, in my view.
Like for like ("LFL") sales decline of 2.3% sounds quite reasonable at first sight, given how tough retailing is right now. However, further on, the commentary discloses that it's far worse at UK stores;
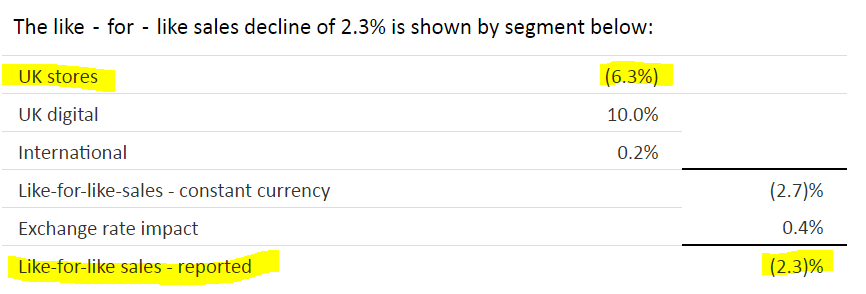
This is the key point to understand: If LFL store sales keep declining at that rate, then profitability will inevitably collapse, into ultimately heavy losses. This is because most of the costs relating to stores, are fixed costs, or even rising. Rents cannot go down, as DEB is locked into long term leases, unless deals are done with landlords, who are not known for their generosity.
Other big costs, like business rates, and staff wages, are rising. I cannot see how DEB can survive in its current form, if these trends continue, as seems highly likely. The only way out, is to do a CVA, or pre-pack administration, which is what happened with House of Fraser. It seems to me that DEB is just delaying the inevitable, unless it can pull off a miraculous turnaround fairly soon - very unlikely in the current climate.
Store closures - the company already had 10 stores ear-marked for closure. Today it adds another 40 to that list, over 3-5 years. It says that these 40 are not currently loss-making, but are likely to become loss-making if current trends continue.
It's all very well wanting to close stores, but as we know, it's the leases that are the problem. If you're locked into a 15 or 25 year lease, then you can't close a store, unless you can find someone else to assign the lease to, which could mean having to pay a huge dowry (known as a reverse premium). Even then landlords can veto lease assignments, if they don't think the proposed assignee is sufficiently strong financially (known as a weak covenant).
Exceptional items - these are huge, but mainly non-cash balance sheet write-offs;
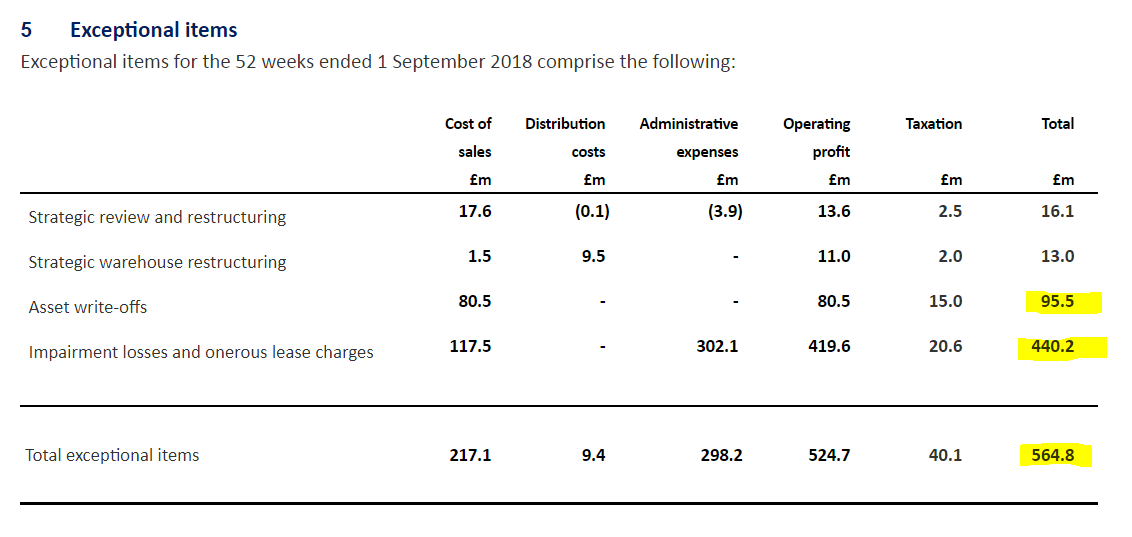
Dividends - the final divi has been eliminated. Don't expect DEB to ever pay any divis again. As with many companies in financial distress, management were too slow to stop the divis. This should have been done years ago, and it has left the balance sheet in a more precarious position.
Balance sheet - is very weak. Writing off intangibles, and the accounting pension surplus, then NTAV comes out at negative -£289m.
There is an argument for eliminating the £354.4m creditor detailed in note 12, which is an accounting adjustment for previously received lease incentives (i.e. cash and rent-free periods received from landlords as inducements to enter into leases). These are not actual liabilities, but are accounting entries which are gradually fed into the P&L over time. If this creditor is eliminated, then NTAV moves back into positive, at £65.4m.
Working capital is not good, with current assets of £528.1m, but current liabilities much larger at £807.0m. That's a current ratio of 0.65 - very low. Therefore, it is the banks & the trade creditors which are funding the business.
Net debt is much too high, at £321.3m. There's no breakdown given on that, but in the past it included £200m in a July 2021 5.25% bond. Finding out what the covenants (if any) on those bonds are, is very important in considering whether the equity is worth anything or not. Quite often in distressed situations, the bond holders end up calling the tune, and equity is wiped out.
When I last looked at DEB here on 19 Apr 2018, the bonds were trading at 92-94p in the £1. They're now trading at 73.8 bid - 75.7p offer. Therefore bond investors (who are often more astute than equity investors) are losing confidence in being repaid in 2021. Remember that bonds rank ahead of equity. So the bond market is telling us that the shares are probably worth nothing.
Cashflow & debt reduction are mentioned as key aims.
DEB has probably left it too late to do a meaningful equity fundraising, unless that is combined with a CVA.
Capex - has been reduced, with plans for only £70m in FY2019. Is that going to be enough to maintain the quality of the stores? Probably not. Although the commentary mentions that capex is being focused on the best performing stores, which makes sense. We should expect the stores ear-marked for closure to become more & more tatty, as they are starved of capex. Unavoidable, but it will cause damage to the brand.
Trade credit insurance - the company has had problems with this cover being reduced or removed, for suppliers. This is bound to cause difficulties - some suppliers may now demand pro forma (cash on delivery), or might only be prepared to trade at reduced levels, without insurance.
That said, persuasive buyers & finance staff should be able to work around this issue, and switch to alternative suppliers. DEB is so big, that many suppliers may assume it's too big to fail. It could even bring some positive results, in forcing DEB to move stock faster, and carry lower levels of inventories, calling stock from suppliers when needed. It's certainly a big issue, and a test of the calibre of staff DEB has at head office, in terms of whether they can manage this problem well, or not.
My opinion - this looks a precarious situation.
The figures as they currently stand are not too bad - the business still generates decent EBITDA, for example. The problem is the direction of travel. As the commentary admits, stores which are currently still profitable, are heading towards becoming loss-making in future, if current trends continue.
In order to survive, DEB needs to shed a load of stores with no future, and concentrate on its best stores. By far the best way of doing that, would be a pre-pack administration, as HoF did. The trouble is, that usually means finding a new owner with deep pockets (Mike Ashley?) who is able to renegotiate all the leases onto much lower rents, or hand back the ones where no agreement can be reached. There are also heavy losses to be funded whilst that process is underway. It's also difficult to procure supplies after a pre-pack, as suppliers that have just been hit with a huge bad debt might go bust too, or at the very least are reluctant to continue supplying, unless they're paid cash up-front.
If DEB had cash in the bank, then it could restructure solvently, as on a much smaller scale, French Connection (LON:FCCN) (in which I hold a long position) has been doing. Unfortunately though, DEB has debt, and far too much of it. The risk is that bank facilities could be withdrawn or reduced. It's being squeezed from all directions.
The commentary says that £350m of cashflow is set to be released by FY2020, before asset disposals. That sounds preposterous to me, and I would certainly like to see how they're arriving at such a huge number?
This brings me on to the general tone of today's announcement, which strikes me as over-optimistic, even delusional. They're clearly trying to gloss over the seriousness of the company's situation, and that just undermines the overall credibility of the commentary. Sometimes the PR people over-egg the pudding, and cause more harm than good, which is what I'm seeing here. Other people may view it differently, that's what makes a market.
I admire management determination to do their best in trying to turnaround Debenhams, but the odds seem stacked against them. There's no doubt that Debenhams will survive in some form, but shareholders need to understand that there's a very high likelihood that they will be wiped out or severely diluted here, sooner or later. So this share comes with a major wealth warning from me.
Possible upside could come from the mooted disposal of Magasin du Nord, Debenhams' Danish operation, which is profitable. Although that would then tip the remaining group into losses - you can see from today's segmental analysis that international generated all the underlying profit.
Risk/Reward looks terrible to me for this share. Your chances of getting a multibagger on the upside are basically nil. Your chances of getting a 100% loss are high. So why on earth get involved? It's little more than a gambling chip at this point. Short term traders could get lucky though - if a decent asset disposal is agreed for Magasin du Nord, then that would certainly be a short term boost to the share price - maybe a 50% bounce? Is it worth risking 100% loss, to get a 50% gain though? Probably not, in my view.
Increased competition from a revitalised House of Fraser is another issue, once Mike Ashley has renegotiated rents onto a dirt-cheap basis, and refitted HoF stores to make them the "Harrods of the High Street" - although that would take several years to accomplish. It would be worth looking into how many towns/cities in the UK have both a Debenhams and a House of Fraser in competition with each other.
I can't see any good reason to punt on DEB shares at this stage. For gamblers only, I reckon.
SCS (LON:SCS)
Share price: 218p (down 1.4% today)
No. shares: 40.0m
Market cap: £87.2m
Trading update & House of Fraser concessions
ScS Group plc, one of the UK's largest retailers of upholstered furniture and floorings, today provides a trading update for the 12 weeks ended 20 October 2018 and an update in relation to its House of Fraser concessions.
- Core business doing very well, with LFL order intake growth of 4.5% - surprising, but we have to take it at face value, and assume it's correct
- Trading in line with management expectations
- House of Fraser concessions have slumped - LFL orders down a whopping 52.5% - luckily they're a relatively small part of total sales (2.7% in the period being reported today)
- Closing all HoF concessions by end Jan 2019 - sounds sensible, given the appalling recent sales
My opinion - ScS never struck me as a good fit for HoF, as ScS product is really too down-market for a more aspirational outfit like HoF - especially as new owner Mike Ashley plans to take HoF considerably more upmarket.
Stockopedia's algorithms like ScS a lot;
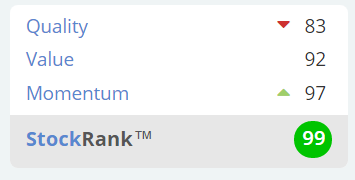
It's classified as: Adventurous, Small Cap, Super Stock.
The balance sheet is very good, as is the high dividend yield.
I covered it in more detail a little while ago, here on 2 Oct 2018. I was tempted to buy some, after writing that report & pondering things. In the end I decided not to - despite the attractive figures, rightly or wrongly I just don't want to own shares in a sofa retailer.
The house of Fraser situation isn't a big deal overall, so that doesn't alter my view of this share.
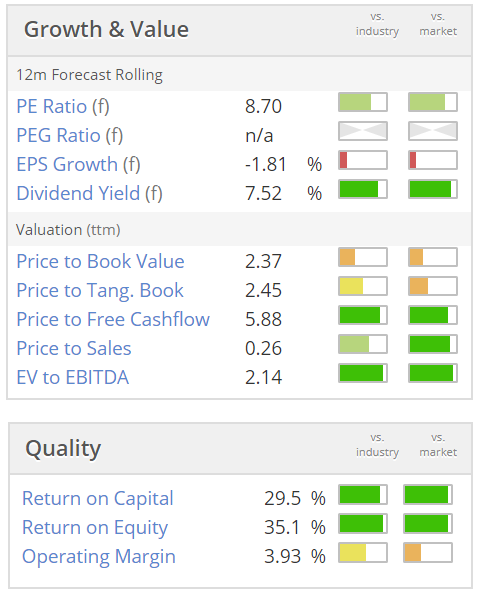
Here's a reminder below of the attractive valuation metrics - perhaps why this share has been impervious to the recent sell-off - which suggests shareholders are solid holders, rather than the irritating fly-by-night characters that are constantly buying & selling other small caps, depending on which way the wind is blowing!
(that's a bit tongue in cheek, before traders start haranguing me for being offensive towards them!! I'm just having a bit of fun. Or ban-ahhhh as they say now)
Due to popular demand, Graham has kindly emailed me the following section for inclusion in today's report. What a star!
Distil (LON:DIS)
Share price: 2.55p (+16%)
No. of shares: 502 million
Market cap: £12.5 million
(Please note that Graham currently holds DIS shares.)
Graham Neary writes - Encouraging news from this developer of spirits brands as H1 revenue is up by 42%, an acceleration compared to previous top-line growth (last year, sales growth was 23%).
We also have an improvement in gross margin to 61%, as revenue growth exceeded volume growth. Gross margin was 56% in H1 last year, or 58% for the full-year.
International distribution continues to improve with new listings in France and Canada.
Marketing spend is a key executive decision and driver of sales growth: it increased by 57% in H1. Despite that increased spending, the company does enjoy the benefits of operational leverage as other administrative expenses increase at a much slower pace (c. 10%).
Add it all together and Distil has generated its first ever H1 profit. H2 (the winter period) tends to be much stronger again.
I’ve been doing some projections and I think that if H2 sales growth can remain high at 40% in H2, at the same high gross margin, and assuming continued 57% growth in marketing expenditure, then Distil could generate operating profit for the current financial year in the region of £400k. This is double the level that is currently forecast by official estimates.
I have also made projections for the next couple of years, and I can see Distil potentially making £500k of operating profit in FY 2020 (from April 2019 to March 2020) before making £650k of operating profit in FY 2021. The official estimates before today’s results were for operating profit of £400k in FY 2020 and £600k in FY 2021, respectively.
Using my own projections, the price/EBIT multiple relative to FY 2020 comes out 25x, falling to 20x in FY 2021.
I think my assumptions to arrive at these projections are conservative:
FY 2020: 55% growth in marketing spend, 35% sales growth, and reduction in gross margin to 60%.
FY 2021: 35% growth in marketing spend, 30% sales growth, and reduction in gross margin to 58%.
If these assumptions turn out to be too pessimistic, then the shares could start to look tasty on an earnings multiple basis by FY 2021. For example, if marketing spend increased in FY 2020 by only 50%, and achieved 35% growth in sales, then my operating profit estimates would increase to £550k (FY 2020) and £700k (FY 2021).
Balance sheet: the company has £1 million in cash and is careful with how it spends its money.
Outlook: Christmas will be competitive, but the company has its promotional plans in place along with new PR/social media campaigns.
Graham's view: Happy to continue holding this one.
Paul's view: I defer to Graham having done much more work on this share than I have.
My impression is that this company has been around for donkey's years, and repeatedly failed to gain traction with its products. The share used to be called Blavod Black Vodka, see the long term chart below. Maybe it's finally getting somewhere, but how can we be sure that growth continues? Drinks come in & out of fashion too, so any growth now could conk out later?
Also, it's too illiquid for me to consider for my portfolio. The danger is that, if you do accumulate a decent sized position, you may not be able to sell, especially in nervous markets that we have at the moment.
I hope it works out well for Graham & other holders, but it's not for me. The valuation doesn't look cheap either. Although there could be upside, if its products really take off & smash forecasts, and someone comes along and offers a premium takeover price.
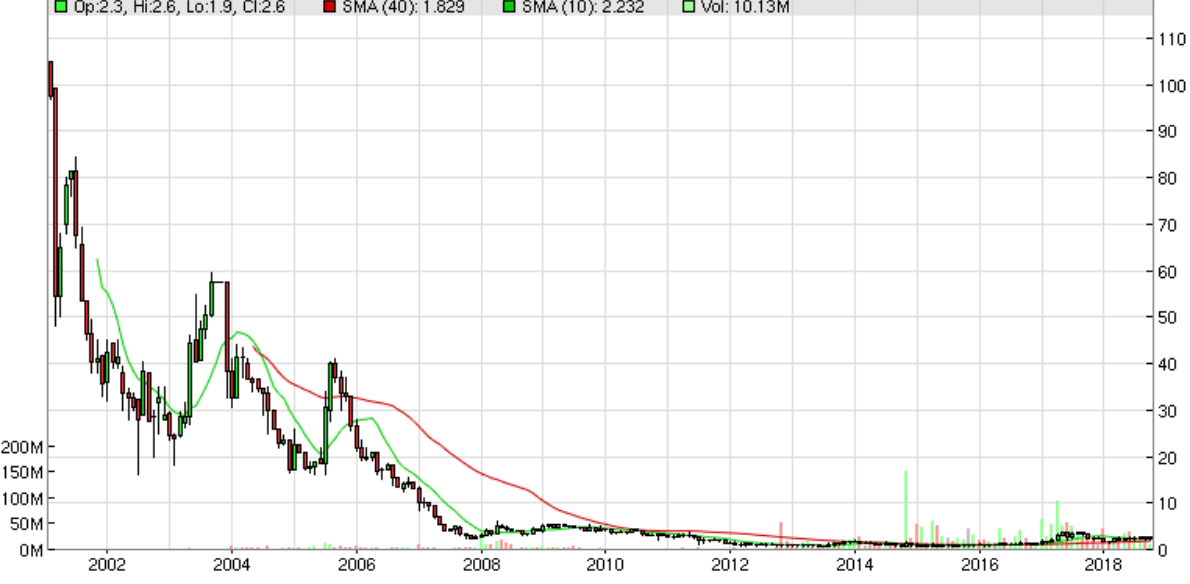
OK, I'm taking a break now for lunch.
I'm trying out the new food menu at £RBG (one of my largest holdings) at the moment. I went there last night too, and had 3 "grazers" which were quite good, and a "MotherClucker" burger (with chicken, hence the name - I had to be careful typing that lol!). Initial impressions are that it's an improvement on the old menu, but still far too deep-fried orientated, and not a very good fit with a bar that's supposed to be all about premium. Pricing isn't competitive enough either.
Today I shall be sampling RBG's £6.25 lunch deal. There's a danger I might succumb to the temptation to have a pint or two, and pass out on the sofa when I get home. If so, I'll finish off this report tonight.
Update: the prawn caesar salad + diet coke was good value for £6.25, although a bit too much lettuce. I've succumbed to temptation, and had a pint of Magners as well! Brought my laptop with me, so am finishing off today's report from Revolution Bar in Bournemouth! Maybe I could organise a Bournemouth shares social at some point? Anyone interested, let me know. If there's enough demand, II'll organise it.
Begbies Traynor (LON:BEG)
The useful red flags report is out today for Q3, from the UK's only listed insolvency practitioner.
There's nothing much of interest in it.
Filtronic (LON:FTC)
Share price: 16.9p (down 20.5% today, at 15:07)
No. shares: 207.0m
Market cap: £35.0m
Trading update (AGM) - this is for the year ending 31 May 2019.
Filtronic plc (AIM: FTC), the designer and manufacturer of antennas, filters and mmWave products for the wireless telecoms and critical communications markets, is pleased to provide the following update ahead of its Annual General Meeting to be held later today.
Trading is in line with expectations, so far this year. So why is the share price down 20% today? I think it's probably due to the uncertain outlook;
Whilst we continue to enjoy good baseload volumes from our long term defence contracts, the uncertainties regarding the timing of the market take-up for mMIMO and the rate of tail-off of our legacy filter sales make near term forecasting very difficult. However, we are confident that our position overall continues to strengthen and our outlook remains positive.
My opinion - erratic performance has always been this company's Achilles Heel. I don't think it is at all suited to a stock market listing. Although the ability to raise fresh capital did stop it going bust a few years ago.
There are no divis, and performance is highly erratic, depending on which products are hitting a sweet spot, or in decline. That makes it uninvestable for me.
Alumasc (LON:ALU)
Share price: 128.5p (unchanged today, at 15:30)
No. shares: 36.1m
Market cap: £46.4m
Trading update (AGM)
Alumasc (ALU.L), the premium building products, systems and solutions group...
The current year ends on 30 June 2019.
Some detail is given, but the conclusion is;
... In view of the above, management's expectations for the full year performance remain unchanged.
My opinion - the PER is very low, and there's an excellent dividend yield too.
However, there's a big pension scheme deficit. If equity markets continue falling, then companies with pension deficits could once again become a no-go area, so some caution is needed.
Eckoh (LON:ECK)
Share price: 38.5p (down 1.3% today, at 15:55)
No. shares: 252.7m
Market cap: £97.3m
Eckoh (AIM: ECK), the global provider of secure payment products and customer contact solutions, today issues a trading update for the six months ended 30 September 2018.
- Trading is in line with market expectations in H1
- USA secure payments - "excellent momentum"
- UK also going well
- Net cash of £3.4m
My opinion - this company has been around a long time on the stock market, and I question whether the revenue and limited profit growth justifies such a high rating? Particularly given that we're having a sharp correction at the moment, with growth companies taking a battering.
The upside case seems to rest on some impressive contract wins with big customers. If those can be replicated more widely, then I can see why investors would be prepared to pay an apparently high price now - the company could grow into the valuation maybe?
Good, I think that's everything for today! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
@Paul Scott: Would your comment on momentum investors include the type of investors who follow Quantitative Investing and QVM (Quality, Value, Momentum) type of investors?
Also would a NAPS Investor also fall in this category?
Thanks!
Hello Paul. I have just read yesterday's report and would be interested in your idea of forming a shares social group in Bournemouth. However whenever you are next in Bournemouth and you want a pint just contact me.
Perhaps Paul indulged in one too many beers at Revolution yesterday?
Perhaps we could use https://www.stockopedia.com/content/i-read-the-news-today-oh-boy-26-oct-2018-412239/ as the placeholder for today until SCVR wakes up. I feel sure that Matylda won't mind.
AHA - excellent thank you for that Leo - I had totally misinterpreted how the figures were presented.
Will have a futher look at that later then,
I saw this comment from you yesterday
“In one extreme case, a very illiquid micro cap stock I hold, Malvern International (LON:MLVN) , some idiot sold a few thousand pounds-worth of the share, and the resulting fall in share price knocked c.£50k off the value of my shareholding! As you can imagine, I wasn't best pleased, but we have to accept volatility & illiquidity as the price we pay for operating in a very imperfect market”……
I am curious to discover why you felt why he/she was an idiot ?
Hi Gromley
Is the larger number just the total annual comitted lease expense...ie up to break points?
Hello All,
I am trying to get a better handle on the lease commitments at Debenhams (LON:DEB) as I actually think the difficulty they face in right-sizing the estate over 3-5 years is very much overstated.
However, there is clearly something I am missing and I’m hoping that someone more knowledgeable than me can shed some light here.
I am working on the 2017 figures as there is important detail that I think we only get to see once the full AR is produced.
From the 2017 AR -note 30 (page 134) – we see the OPERATING LEASE COMMITMENTS by length of commitment.
These figures show “The future aggregate minimum lease payments under
non-cancellable operating leases” by duration of lease - the first two columns come from the AR, the 3rd column is my assumption and the last two columns are the derived result.
[1] My assumption on average length based on the ranges.
Now these figure suggest that despite Debenhams (LON:DEB) having some EXTREMELY long leases, nearly 70% (by value) are escapable/renewal within 5 years – this was what I expected to be the case.
But here is what I do not understand, these figures suggest a total annual lease expense of £875m, however this compares with (Note 6 – page 104) actual “Operating lease rentals” in 2017 of £221.4m.
I must have hugely misinterpreted something here, but I just cannot see what.
(I know that the forward figures probably include contractual rent increases etc , but even the implied figure for agreements with less than 1 year to run exceed the actual reported cost, so that is not the answer)
Could someone with more expertise in this area show me where I have gone wrong? (I'm sure it will be something stupid that I have missed, but I just cannot see it)
Gromley, re Debenhams (LON:DEB) low annual lease rentals compared to lease commitments.
My first thought was that perhaps they are continually agreeing lease extensions with reverse lease premiums thus deflating annual lease costs in the short term. Having such nefarious thoughts probably reflects badly on me.
However, in the last annual report it says:
This seems to eliminate my theory and also provide a maximum size for your contracted rent increase theory.My next thought is whether the lease commitments are on a NPV or a gross basis. This could make a massive difference for the longer leases. Note 30 isn't explicit, but a reference to it is:
So these lease commitments are a clear over-estimate in present money terms. Not least because a deal could trivially be done with the landlord to discharge their commitment using the landlord's cost of capital as the discount rate.
AlsoI note the following clause in the depreciation policy:
This could be taken to imply that they have some long-leasehold buildings with terms over 100 years.
This still cannot explain most of the discrepancy. Hopefully I will have time to look into this further later today.
Debenhams (LON:DEB) Lease commitments.
The first column is the payments due within that period for all leases regardless of length, not total payments for leases that terminate within that period. Thus the under one year figure is the next year's expected annual lease costs.
It should still be possible to infer something about lease lengths, it is just a lot more complicated to do so.
As I said earlier, the figures further out are significantly overstated for practical purposes because they are not discounted (i.e. not NPV).
RE Filtronic (LON:FTC)
There are actually two potential interpretations of the guarded outlook view :
One interpretation is that this is leaving the door open for a profits warning before the end of the FY (May-19), Paul references the lumpy performance that they have often experienced and in that context it is indeed not unreasonable to take this view.
However, I took a different view. There is a view out in the market that 5G mobile networks will create transformational demand for Filtronic's mMIMO products, I outlined the speculative bull case here a few months ago . Various subsequent industry news, not to mention some comments that Rob Smith made to SmallCompanyShareWatch , have reinforced these views together with the view that it could happen sooner than expected.
There was certainly hope in some quarters that today's trading statement would tell us that this acceleration has started to ramp up.
That was the context in which I took these comments, essentially to say that the potential future upside is still very much there, but that they cannot readily predict precisely when it will come.
So I remain pretty optimistic here and I'm not overly concerned about short term price volatility here.
1pm seems to have disappeared from the header list.
Paul
I agree with your comment that the £350m DEBS property lease incentives shouldn't counted as a liability when looking at tangible book value but they will certainly make negotiations with landlords even harder than they will be anyway.
Thanks for the Debenhams analysis, Paul.
I didn't know Debenhams stores were tied up in "decade-long" leases. My thoughts were some stores are seeing near the end of their lease and marked for closure.
Personally, I thought the cash flow is okay unless we see the business deteriorates even more.
Feel sorry for the shareholders, but even retail gurus like Mike Ashley made a huge loss on this punt and he is a billionaire!
A bit off topic, because nothing to do with today's news! But, we've just published it, so is that newsworthy? And perhaps a distraction from red markets!
From ShareSoc October 18, Supermarket Income REIT (LON:SUPR) investor presentation:
https://www.piworld.co.uk/2018/10/25/supermarket-income-reit-supr-at-sharesoc-october-2018/
Sounds interesting, if you're looking for income. I've heard others talk about the attraction of buying leases, so helpful to hear their perspective.
This was a great ShareSoc event. A really good set of companies. We only recorded this one and Bioventix (LON:BVXP) - already published. I'm sure I'm preaching to the converted, but do get to the ShareSoc events if you can, well worth it.
At the risk of being shot at as a messenger, this is what Mark Minervini tweeted an hour ago.
"
This is still a dangerous environment. A market that is falling on increasing volume thru support levels, and ignoring oversold readings has all the makings for a potential meltdown. Even if the market makes a low, prepare for whipsaw action - reliable bottoms take time to form.
"
As one who is sitting on 100% cash, every day I keep asking myself the same question, "are we there yet?! " , i.e. can I spend like crazy and buy up so called "bargain" shares?
And so far, the answer has been "no". Like Minervini, I am looking and waiting for the formation of a reliable bottom. It will of course mean missing out on the early sp rises, but that is a lot better than seeing today's bought "bargains" turning into expensive mistakes a few days/ weeks later.
We could be waiting a while I suspect.
At the risk of being shot at as a messenger, this is what Mark Minervini tweeted an hour ago.
"
This is still a dangerous environment. A market that is falling on increasing volume thru support levels, and ignoring oversold readings has all the makings for a potential meltdown. Even if the market makes a low, prepare for whipsaw action - reliable bottoms take time to form.
"
Why would you be shot? I don't agree but it's just the opinion of one person. Why look at the whole market and what market is he talking about? I guess the S&P 500? So a very American view point.
The trouble is, once you look at some individual companies many of them do not look that expensive. Apple is on a EV/EBITDA of 14 and Microsoft (who announced excellent results last night) is on 16. These are quality companies with bullet proof balance sheets, impressive returns on capital and great cashflow. Who on earth wants to be holding USG bonds for very long when you can hold such great investments?
In my day job I am seeing a lot of activity still across many different technology sectors and there is no sign of anyone putting the brakes on and turning out the lights. Look at the Xilinx results last night to see the kind of thing I mean - very strong with a strong outlook. I think some people who only inhabit financial circles need to get out more and see what is happening in the real world rather than just pontificating on social media.
All the best, Si
I respectfully opine that there are no bargains - at least not based on normal historical yardsticks.There may be stocks made to look undervalued by current bond yields,but interest rates are being artificially suppressed.
There was an interesting tweet last night from a chap called Charlie Bilello:
Image Charlie Bilello (@charliebilello)
24/10/2018, 22:57
% Below 52-week high:
$VZ: 0%
$MCD: -1%
$KO: -4%
$PG: -4%
$AAPL: -8%
$BRKB: -11%
$CSCO: -11%
$V: -11%
$WMT: -11%
$MSFT: -12%
$XOM: -13%
$JPM: -13%
$GOOGL: -18%
$HD: -18%
$AMZN: -19%
$C: -21%
$BAC: -21%
$T: -23%
$INTC: -26%
$NFLX: -29%
$NVDA: -32%
$FB: -33%
$BABA: -34%
$TWTR: -42%
Thought it might be of interest.
Hi purpleski,
That is interesting and those are big percentages, I’ve been waiting for a time to get into Scottish mortage IT (James Anderson) and this might now be the right time? I’m thinking a thread on ‘what’s of value now’ would be interesting, there are a lot of small caps I liked and still do but are now a lot cheaper. Value is opinion but 30% cheaper than two weeks ago is often worth a scale in position.
Value is increasing. Shares magazine has just pointed out that Burford Capital (LON:BUR) is now 15% below the price the institutions bought at in the recent placing.
Dear Paul,
I was very intrigued by your comments about liquidity and price volatility in these markets. These are sage words of comfort to long-term holder, nervosa stock'ia types! Thank you.
Are there some "rules of thumb" re market cap, and/or daily traded volumes - I pay not attention to traded volumes but I should - which you look at? I am wondering how to assess whether I might be buying into a stock with such unstable price characteristics?
Mark
SCS (LON:SCS) - have watched it go up from the sidelines for a while now - still on watchlist - anyone wondering whether this is a little too good to be true. They are selling sofas like Amazon sell books.
To be scarred Patisserie Holdings (LON:CAKE) holder
Sharmvr, on SCS (LON:SCS) ....
What's suspicious about the numbers? LFL in own store have been strong other periods during this tough environment and the update is not out of whack with historic.
They trade nearly exclusively in out of town retail parks targeting the space to be beside other furniture retailers and in areas that align with their target customer demographic. New openings happen but in controlled fashion as the new store must fit their profile. Currently they have 30 locations they want to open new stores in and are waiting for the right opportunity to arise.
Cash doesn't lie and SCS have been producing lots and paying lots out.
I've spoken to CFO in the past and I'm very impressed with how on the ball they are. They know what they do best, who their customer is, what they want and how to position to sell to them.
By comparison, DFS Furniture (LON:DFS) is a bit stuck in aspirational no-mans land...a strategic jumble with a stretched balance sheet. I'd guess that in these tougher times for those less affluent than your average Stockopedia punter that SCS are picking up custom from other stores.
As you can tell, I'm a fan and just surprised that everyone doesn't own some :)
Through a combination of organic growth, new stores and doing something with their giant cash pile I believe SCS can triple earnings per share on a 5 year horizon (a double is in the bag). That will be pretty impressive off of this valuation level.
mojo out (hopefully not delusional)
To be honest my biggest problem with SCS (LON:SCS) is that I have watched it go up some 60% and missed out on another 15% in divis.
Nothing wrong with the numbers that I can see and I tend to agree cash doesn't lie - but then I had the same view of Patisserie Holdings (LON:CAKE) , albeit SCS has a lot more value going for it.
Also their bullet proof balance sheet has I think allowed them to gain market share while competitors went out of business.
My concern is on their operating margin - there really is not very much wiggle room in these businesses for a bad year or 2, then again, bullet proof balance sheet!
Presumably they can double EPS just by using cash to do a buyback
In short, I am a fan and if I wasn't anchored on a price closer to 150, I would probably have bought already - DFS Furniture (LON:DFS) is a joke in comparison.
You might be right re SCS (LON:SCS) operating margin. It is a negative I have heard from others. The top of the range for them is going to be 6-8% with their current business set-up. Revenue growth can be good and may hit high single digits LFL for a sustained patch if a really motoring but will never be absolutely flying (absent acquisition or large store opening programme). So a p/e multiple into the teens is top of sensible range. Netting out cash p/e today is approx 5.5 (allowing for working capital impacts) so that's a lot of multiple upside...and once a company like this is liked the market can particularly like a bit of leverage being employed to add to earnings (I'm not recommending that as I don't think its a sensible strategy for this sort of business...but whilst the story was good it was liked for DFS).
My analysis and discussion with the company has lead me to believe that the margin is quite robust to cyclical factors as they have a lot of flexible costs and ability to adapt to circumstance and they are very conscious of the need to do that. Of course, a massive secular drop in revenues would cause margin problems.
At the risk of showing my ignorance what I dont understand about commercial landlords in the context of Paul’s comment:
“...it's the leases that are the problem. If you're locked into a 15 or 25 year lease, then you can't close a store, unless you can find someone else to assign the lease to, which could mean having to pay a huge dowry (known as a reverse premium). Even then landlords can veto assignments...”
If landlords’ intragedence drives the tenant into bankruptcy, instead of receiving say 50% of the original rent he receives 0% of the original rent and probably, in the case of units that the likes of Debenhams occupies, an unlettable unit.
Can someone with more knowledge than me explain. Thank you.
I am very negative on “The High Street”. I think it was a passing phase of a 100 or 200 years. If you look at pictures where I have a holiday home what is now shops, was only 100 years ago luxury sea front houses. I see no reason why medium term property will not revert to this use.
Perhaps centres (Oxford Street, Knightsbridge) migh persist but not relatively small centres. It will just be all online. But this may just be a result of my own bias because I really don’t shop for anything on the “high street” apart from fresh fruit and veg at the local market. I do it all online often on the go on my phone or ipad.
Best wishes in these turbulent market (it is hard isn’t it)
Michael
Hi Purpleski,
I work in the financial re-structuring world and the main problem "big retailers" face with onerous leases is that it is very difficult to do a deal with each and every Landlord outside of a formal restructuring such as an Administration or CVA or indeed an Examinership as happens in Ireland. Landlords see the "big retailer" as a strong covenant and know that they can go after the Parent Co. (which usually guarantees the lease) if they stop paying the rent or stop trading at the store and close the doors (as some retailers choose to do). So financial matters deteriorate to the extent that the parent Co is left with no choice but to call in the administrators, do a CVA or apply to Courts for protection from Creditors, and do a deal with all the Landlords and other creditors at the same time. Unfortunately doing a voluntary write down with creditors is like herding cats you will always one awkward so and so who won't cooperate so you have to force a deal on them using a formal process governed by Company Law. Best DG
Although as always, we have to be very selective in picking the right stocks. I'm thinking about doing some shopping, as there really are some attractive opportunities out there at the moment. After all, BLASH is a good motto (Buy Low And Sell High).
I suspect that the momentum trade may have ended now - i.e. buying anything that keeps going up, without needing to do any research at all. I can't stand it when that approach works so well, as it means that the laziest and stupidest people make the most money!
Maybe we're now going back into historically more normal market conditions, where volatility has returned, and you can't rely on momentum only to succeed? Instead, stock picking on fundamentals might now be the more important skill once again. I do hope so.
Paul,
I really couldn't agree more. Do you remember the good old days when there was a thing called "value investing"? Whatever happened to that?
Experience has taught me that these market conditions are where you make real money for the long term and the impatient hand the baton to the patient. Good times!
All the best, Si
"he laziest and stupidest people make the most money!" - they only keep it if they get out at the bend at the end.
not to wade into a big debate on index lurches but even if the S&P fell another 12% it would only have retraced HALF the gain since the Trump Bump from 2016 (and his fiscal icing on the monetary flambe to mix culinary metaphors). It was at 1850 in Oct 16 and put on 1000 points in 2 years . What has been eerie of late is the lack of volatility so I for one welcome it and am relatively unsuprised and significantly prepared. We are also in a big rotation as the markets realign for the next phase of the cycle.
What is interesting is that daily volume in the US has increased by a factor of 4 since Oct 2016 having been flat for over a decade. Potentially numerous sources of that : algo buying, programmatic passive ETFs, and a LOT of retail involved: choose your narrative. The numbers are undeniable (that step change in the below plot).
Volume moves price and that level of volume will move price very fast. We are tail-end of a long cycle so this is likely to get very bumpy . If you hold with mean reversion then either volume has a long way to go to mean-revert: or alternatively we have a "new" normal. Combine the very narrow market leadership in hugely valued growth-stocks and you have a highly engineered market with little tolerance for failure.
Market reaction to earnings reports from $AMZN and $GOOG today will be key: they report after the US close.
The good thing about these gyrations is forced-selling throws up bargains.
DS, The lack of volatility may be options related, BUT... that is the problem. I cannot remember the exact formula but Mr Wiki can:
https://en.wikipedia.org/wiki/Black%E2%80%93Scholes_equation
Now the key to this is that the intrinsic value is simple but the time value depends on both time and volatility. The greater the volatility the greater the time premium. Simplistically a share whose price jumps all over the place has a bigger chance of being above or below the present price at some future date. So the price of an option is greater the higher the volatility. And there are megawatts of computer power doing these sums ever faster, and I cannot reference this but I saw that options traded daily exceed the total monetary value of the planet . So masters of the universe taking out all these protections drives down the volatility and so the price of options. It has negative feedback. It is stable. It gets daily more stable the more megawatts are used to make pennies. But the price of shares is not SHM (Simple Harmonic Motion) it is not on the normal distribution curve and the entire premise of the Black Scholes is invalid. This is the revelation of Nicolas Taleb it will be the "Black Swan" event. I thought I had sold everything that "I would not be prepared to hold for ten years" but I am going to have another look and sell into any strength.
"sell that you are not willing to hold for 10 years"
I paraphrase but think that is from a better investor than you :) (more famous at least).
Purpose of this comment is to hopefully get some feedback from those more experienced than me and have lived (and invested) through not so good times
I am struggling with this one - I have 3 ( WPP (LON:WPP), Redde (LON:REDD), Vertu Motors (LON:VTU) ).
Wpp is my stupidity thought about selling already sitting on a 35% loss before today - believe the Sage calls this dilly dallying hoping the next results will cause a bounce (boy was I wrong and read too much into publicis, which seems to be eating their lunch after Sir Martin takes breakfast)
Redde (LON:REDD) great performance for me so don't want to let go, not to mention this is a great stock - not yet me thinks although certainly a call for a cut me thinks.
Vertu Motors (LON:VTU) - performance solid relative to sector (another buffett quote comes to mind) and cheap asset play - happy to hold land for the next 50 years.
Hello again sharmvr
I owned Vertu Motors (LON:VTU) but decided to sell. Its probably now very undervalued but I'm not tempted back as I think the evidence hints that have historically misallocated capital and really ridden the coattails of the car financing boom up rather than created specific value themselves. Here's why...
https://www.stockopedia.com/content/some-thoughts-on-vertu-407134/
However, if the times turn rosier there could easily be a double in the price
Hi Mojo,
Indeed I read that article which was very helpful and saved me some money!
To be honest, I am struggling to push the sell button on the valuation.
It is a small holding in a cyclical sector so I would suggest I should sell out or buy more and on valuation grounds - erring towards the latter.
I think the balance of probabilities are you will make money from here on VTU
sharmvr, of course it was a quote from WB. In my defence I started a long time after him, am a bit younger than him and annualized return of 16% so doing OK!
"Purpose of this comment is to hopefully get some feedback from those more experienced than me and have lived (and invested) through not so good times"
There is an annotated reprint of Benjamin Graham - The Intelligent Investor. I picked it up in NZ at a charity shop for a couple of dollars, It is still on the boat in NZ so sadly cannot give you the exact reference but looking on Amazon was probably the fourth edition annotated by Jason Zweig
No doubt, but low volatility is a proxy for complacency and even more overtly. shorting volatility, which was de rigueur, was symptomatic of the artificial nature of QE infused markets and no-interest rate environments. The CBOE VIX was around 8-9 in July this year, last time it was that low was in 2007 and that didn't end well.
I've read the Black Swan, great book: on my desk is a book I bought almost 10 years ago but haven't read, Anatomy of the Bear by Napier: I am no Nostradamus but now seems a good time
to read this.
Volatility makes for great trading environments so I see it as a positive and natural
The generally accepted definition of a stock market correction is when an index has fallen over 10% from the highest value over the past 12 months. By this definition, major indices as of last night have fallen as follows.
FTSE 100 -12%
FTSE 250 -14%
AIM All Shares -12%
The US markets:
Nasdaq Composite -12%
Dow -9%
S&P 500 -9%
Russell 2000 (US small and medium caps) -16%
This year's corrections from peak are in line with market behaviour in the past 40 years.
Research from JP Morgan shows that Equities (S&P-500) have suffered an annual intra-year decline of 13.8% on average since the start of the 1980's, yet still managed to finish in the black 75% of the time:
Interesting chart, Howard. Perhaps we need to bear in mind that the period covered by the study coincides with one of the longest underlying bull run in history?
Not really Ramridge, the data has been remarkably consistent over time
If we go back to 1948, the S&P 500 has had intra-year declines of an average of 13.4% ... despite which the annual price returns have been positive 73% of the time ( 51 of the past 70 years ).
http://topforeignstocks.com/20...
Yes we all know that the markets have fallen but what are you saying? They also fell in 2016 but then after Brexit had a major rally. Surprising the UK indexes are up today despite the falls in the US markets yesterday, not sure why.
Morning
Quite a bit going on, apart from the fall out stateside. Time permitting your thoughts on the interims at Air Partner (LON:AIR) and AGM statement from 1pm (LON:OPM), both of which look encouraging and have been mentioned above would be appreciated.
All the best
Debenhams (LON:DEB) is the second highest short in the UK : around 12% of the issue: Odey has a big position of over 7%.
Might be on for a squeeze if the kitchen-sinking goes down well
Request for LON:OPM please. AGM statment confirms in-line (strong) trading, and shares off 7.5%. Eq Devs say "A good company whose shares have been hit too hard by market falls."
Biggest drop in S&P since 2009, fastest drop in S&P since 2008.
Not quite true, slopsjon
Yesterday's points fall in the S&P-500 has been exceeded three times already this year!
And in percentage terms, yesterdays 3.1% loss has been beaten eight times since 2009, the largest being the drop of 6.7% in on the 8th August 2011.
The markets are breathing.
Sorry I should have said that I got that from Bloomberg's battle of the charts this morning. I think it was referring to this months performance on the S&P. The point being not how much it has dropped but how quickly.
Air - the divi rise reflects the results perfectly.
Hi Paul,
Would appreciate it if you could cover SCS seeing that it is exiting House of Fraser.
Thanks!
Paul -can I also ask for Distil Distil (LON:DIS) please
I know that Graham holds this.
Nice headline growth in revenue and gross profit. Good balance sheet
Maybe a good opportunity to buy a tiddler beverage company that is valued cheaply and is growing?
Important thing re AIR is that the market, I think, was fearing a large restatement of the accounts after the announcement of an accounting review and delay to their publication. That does not seem to have been necessary.
Re: Air Partner (LON:AIR) - the restatement is in Note 1, most of the £4.4 million has been taken in prior years. There'll be £400k taken in the 2nd half and the same again next year. The accounting review and a resultant abandoned acquisition cost a bit over a million.
Unwind all that and the results look flat, which is a pretty good result considering the chaos. Their air freight division is interesting - you'd imagine a lot of companies are considering this in the event of a late no-deal Brexit. Only 8% of revenues though so it won't radically change the full year results.
And net cash, which is always nice in times of uncertainty.
timarr
timarr,
Thanks for your thoughts on Air Partner (LON:AIR). Under the circumstances of the past 12 months they were pretty reassuring I felt. Anyway, nice to hear some thoughts on a small cap in amongst the market noise. In other news, my Yorkshire tea bag split this morning :(. When I'd finished my brew I could have sworn the tea leaves left a picture of the devil in the bottom of my mug...
All the best, Si
Hi Si,
And my cat ate my chicken entrails and threw up over my crystal ball ... it's not looking good ...
There are some interesting opportunities beginning to to pop up, but I still think some of the prices of popular AIM shares look out of whack with normality (whatever that is). I'm hanging fire waiting for the Budget which may introduce the long awaited changes to IHT with particular reference to BPR on AIM shares. If that happens there'll be another leg down on AIM regardless of everything else. Latest chat suggests it won't happen this time, but it's surely coming.
But Air Partner (LON:AIR) (which has a full listing btw) already looks interesting. And it is, of course, one of the few companies out there where we can be pretty sure there are no lurking issues in the accounts.
timarr
And my cat ate my chicken entrails and threw up over my crystal ball ... it's not looking good ...
Yes, I think I must be overdue another Rorschach test so disturbed was I by this mornings tea leaves incident...
There are some interesting opportunities beginning to to pop up, but I still think some of the prices of popular AIM shares look out of whack with normality (whatever that is). I'm hanging fire waiting for the Budget which may introduce the long awaited changes to IHT with particular reference to BPR on AIM shares. If that happens there'll be another leg down on AIM regardless of everything else. Latest chat suggests it won't happen this time, but it's surely coming.
Agreed. I also fear that sooner or later the IHT benefits of AIM shares will be hit. Who knows it could be Monday just to add some more fuel to the AIM rout. It will be interesting to see what kind of bargains that may throw up.
But Air Partner (LON:AIR) (which has a full listing btw) already looks interesting. And it is, of course, one of the few companies out there where we can be pretty sure there are no lurking issues in the accounts.
Sounds like famous last words, but yes, probably the most robustly analysed accounts of any of my holdings!
All the best, Si
Hi Paul
I’d appreciate your thoughts on Distil (LON:DIS) I hold. Today’s interims are dripping with positives (to use a phrase of yours and pardon the pun!).
A big increase on marketing spend appears to have fed through to increased revenues and profits. I wondered what you thought about Distil (LON:DIS) listing elsewhere too.
Thanks
Jon
hi paul, please share your view about DIS
hi paul, please share your view about DIS
Distil (LON:DIS) please - Falling Star with good results, GB (LON:GBG) though might be too big, profits up about 8% (adjusted)
I might buy Lloyds though. Seems safest apart from gold. What does Goole-bug our Graham think? Is there enough blood on the streets to start licking it up or should we wait for Hallowe'en?
My morning smallcap tweet: Butcher attacks DEB estate.
Debenhams (LON:DEB), Centaur Media (LON:CAU), Cohort (LON:CHRT), Zinc Media (LON:ZIN)
Debenhams (DEB) FY figs as guided in Sept. As leaked to press, will close up to 50 stores, no div. "Above-market digital growth of 12%." Above market? Seems pedestrian for online. Next is up 15.5% for example. Lots of cost savings, brave face. No current trading. "Our transformation strategy is gaining traction." Has included risk of suppliers losing more credit insurance in going concern stress tests. No mention of selling Magasin Du Nord to cut debt, now at £321m net. up £45m. CEO aptly called Butcher. I'm short.
Centaur Media (CAU) guides FY adjusted operating profit up 18%, below market expectations. "Centaur has received approaches for a number of its assets...Board believes this value is not reflected in Centaur's current share price." The dimwits issued 2 RNSs, the 2nd having the addendum missing in the first.
Cohort (CHRT) selected as preferred bidder for an eight-year contract from 2019, valued at over £50m. Contract subject to final negotiation and MOD approval.
Zinc Media (ZIN) wins $6m in TV comissions, most in current FY.
Half-year update from Air Partner (LON:AIR) as well. Looks ok. Doesn't matter. Will be carnage today!
6:52
"Oct 25 (Reuters) - Britain's FTSE 100 .FTSE index is seen opening 42
points lower on Thursday, according to financial bookmakers."
Hope this is correct.
The American markets had another bruising day yesterday. At the close
Dow down 2.4%
S&P down 3.1%
Nasdaq down 4.4%
The FTSE 250 was actually up a short time ago.
today is looking like its going to go red
Surprisingly, so far it's pretty level. We'll have to wait and see what happens when the US wakes up.
At the moment Dow futures predict a rise this afternoon (UK time) of 230 points or nearly 1%
Following from your marvelous words yesterday Paul, brought to mind your namesake, the novelist, Paul Scott. In particular his novel "The Mark of the Warrior". It opens with the words
"Three things are to be considered:
a man's estimate of himself,
the face he presents to the world,
the estimate of that man made by other men.
Combined they form an aspect of truth".
Hi Paul, I am sure you will cover it but would be great if you can cast your eye over the Debenhams (LON:DEB) update in the morning. The newspaper trail sounds grim for staff if not shareholders: https://inews.co.uk/news/consumer/debenhams-store-closures-latest-branches-sales-plan/
Also worth investors keeping in mind the impact on brands that sell a large amount through Debenhams (LON:DEB) including QUIZ (LON:QUIZ) which has a large exposure to Debenhams (LON:DEB) stores (although in my opinion the high net cash and current low share price more than factor this risk in). I've posted more about this previously: https://www.stockopedia.com/content/small-cap-value-report-tue-11-sep-2018-jd-bry-luce-upgs-mai-blv-sbiz-pil-onev-midw-cyan-397619/?comment=29#29
I would be highly surprised if there's not something in Monday's Budget to help highstreet retail.
Yes I am sure that Debenhams (LON:DEB) results will be a significant news story tomorrow and hopefully Paul can be tempted to give a view - especially as this does now fit the bill of being a 'small cap'.
Personally I think there has been a lot of rabid (and superficial) hyperbole over how bad things are with Debenhams (LON:DEB) so I look forward to reading what they actually say.
Ref Tesla
Very decent q3 numbers - are these decent numbers sustainable going forward ? - hmmmmm lets hope so