Small Cap Value Report (Thu 30 Nov 2017) - LAM, LTHM, SIV, OTB, HMLH,

Good morning! It's Paul here - bright-eyed & bushy tailed!
I've added 5 companies in the article header above, which have been interesting companies before, and have issued either results or trading updates today. There might be time for 1 or 2 reader requests too.
Lamprell (LON:LAM)
Share price: 63.4p (down 9.5% today)
No. shares: 341.7m
Market cap: £216.6m
(at the time of writing, I hold a long position in this share)
Project update (profit warning)
Lamprell plc is a United Kingdom-based provider of fabrication, engineering and contracting services to the offshore and onshore oil and gas, and renewable energy industries.
The company really should have entitled this announcement as a trading update. By giving it the apparently harmless title "project update", this announcement didn't appear in the "results & trading updates" categorisation used by investegate. It's actually a profit warning;
... While we expect revenue for FY2017 to be in line with current guidance, we now expect earnings and EBITDA to be materially below current market expectations.
The problems seem to be relating to one particular project;
Lamprell provides an update in relation to the East Anglia One offshore windfarm project. As announced previously, there were start-up costs and inefficiencies in relation to the project and the learning curve has proven to be steeper than anticipated.
We remain confident of meeting our client's expectations in terms of schedule and quality but we will incur extra costs to achieve this.
As a result, we now expect the project to make a significant loss, which will be booked in 2017.
I hate to say it, but that sounds like management shortcomings. Should Lamprell really be undertaking projects where it has to learn on the job?
It sounds like the full financial impact is not fully known yet, which usually means it's likely to be more than expected;
... the Company will be in a position to make an announcement with respect to the financial impact in due course.
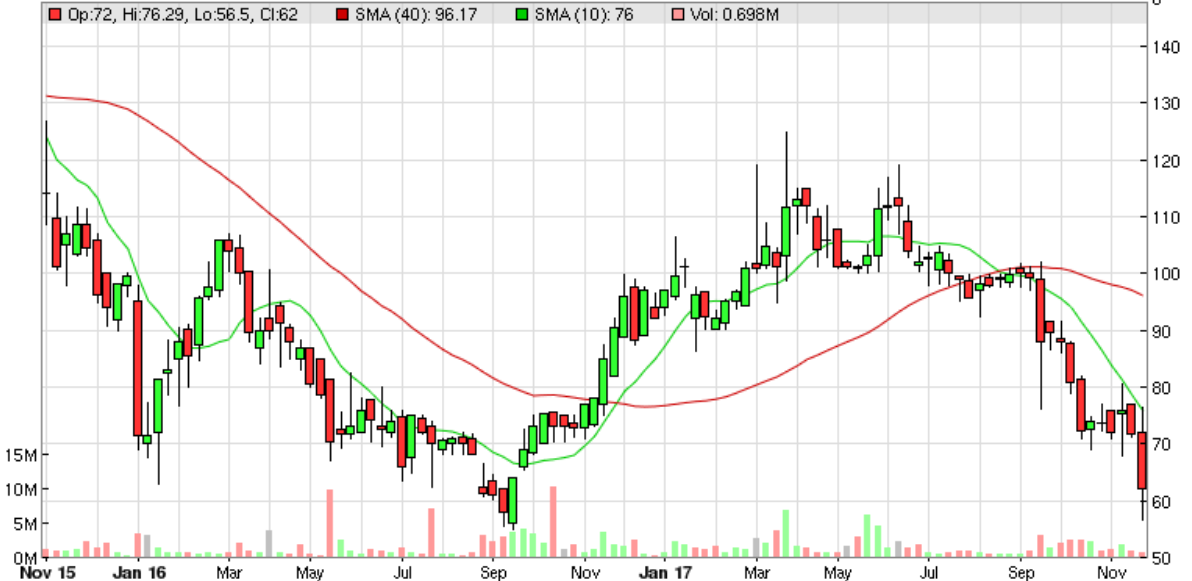
My opinion - we might expect this type of profit warning to trigger a 20-30% fall in share price. So why has Lamprell only dropped 9.5% today? It's still early days (I'm writing this at 09:15), so there could be delayed selling yet to happen. However, I think a more likely explanation is that this is a value share - with the valuation mainly underpinned by the balance sheet (large net cash balance), rather than the more usual multiple of earnings.
Lamprell has already warned on profits before, and broker consensus is for it to trade at a loss this year and next, before today's further bad news.
Balance sheet - the last reported figures were as at 30 Jun 2017. This is a pretty remarkable balance sheet, considering Lamprell only has a £216.6m market cap. Key figures;
NAV: $559.4m
NTAV: $526.6m
Working capital (net current assets): $389.1m
Long-term liabilities: $61.6m - of which $32.3m is a pension deficit, the balance being borrowings.
If you convert these figures into sterling, then the company is worth less than its own working capital, less all liabilities. That seems unduly harsh - or maybe it's fair, considering the company is not profitable. Also, what an amazingly inefficient use of all that capital - which is tied up generating an overall negative return.
It's cyclical though, as Lamprell's main business is related to the oil industry - building & servicing oil rigs, which has tailed off since the big oil price drop a few years ago.
Even in the good times its performance was erratic though, so it doesn't look like a very good quality business;
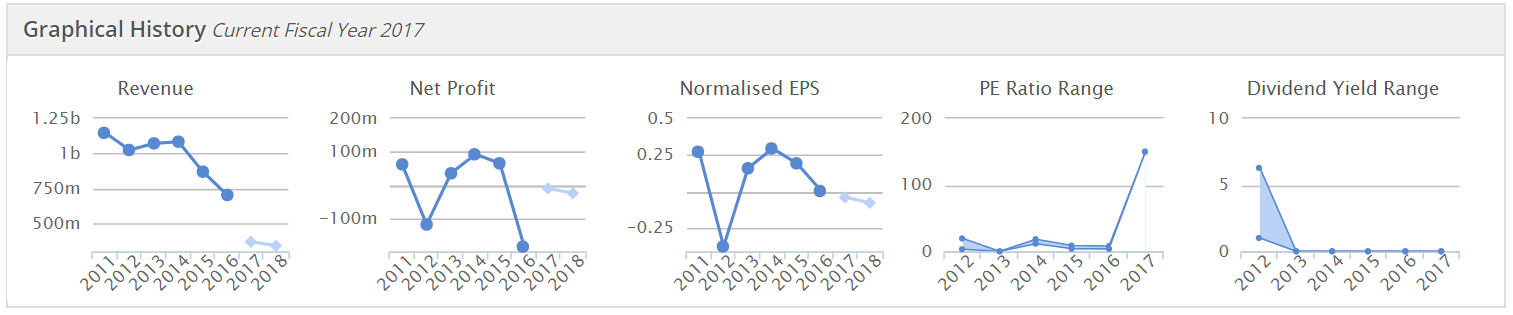
Dividends seem to have stopped in 2011. All that capital tied up in the business, and shareholders don't see any of it - which does make you wonder just for whose benefit this company exists?
So you might be wondering why I bought some shares in it? The reason is because at the current valuation the business is in for free, with the entire share price backed by liquid assets. Therefore the downside should (in theory) be well protected, but the upside is in for nothing. I noticed that the oil price seemed to be rising, so thought that might provide a catalyst for earnings to improve in 2019 and beyond, maybe?
Today's muted share price reaction to this latest profit warning tends to confirm my feeling that the downside is mainly already in the price. So there could be healthy upside if any good news comes along. Also, I imagine the company is in the sights of potential bidders, at such a lowly valuation.
James Latham (LON:LTHM)
Share price: 862.5p (down 8.7% today)
No. shares: 19.64m
Market cap: £169.4m
Half year report - for the 6 months to 30 Sep 2017. James Latham plc is a timber and panel products distributor.
This company last updated the market on 23 Aug 2017 at its AGM. It mentioned pressure on margins, due to higher import costs, and other increased costs from relocating a depot. On the positive side, it reported revenue for Apr-Jul 2017 was up 6%.
Today's interim results show profits falling, which looks to have taken the market by surprise on the downside, hence an 8.7% share price fall today. Key points, remember these are half year figures;
- Revenue up 7.0% to £107.3m
- Cost of sales rose faster, at +8.9%
- Gross profit fell 1.2%
- Other costs were also up, resulting in operating profit falling 11.2% to £6.96m
- Diluted EPS fell 10.9% to 27.7p.
There seems to be an H1 bias to profitability, so it looks as if full year EPS is heading for about 50p per share on a diluted basis. Stockopedia shows broker consensus as 54.4p for this year, ending 31 Mar 2018, so this looks as if full year expectations may now be missed. The company doesn't say anything about market expectations in today's announcement.
Outlook - the way I read the comments below, it sounds like things might be improving a bit compared with H1. Maybe they're hoping to recoup some of the H1 profits shortfall in H2?
The second half of 2017/18 has started well with growing revenues at slightly higher margins. Trading conditions continue to be mixed, but despite the uncertainties in the economy, we and our customers remain busy.
We are confident in the long term prospects of our key product drivers, and this underpins our plan to continue to invest in our business to further improve the offering to our customers. Following the successful relocation of our Yate depot, we are looking forward to a relocation of our Wigston depot to a site closer to the motorway network in Leicester ahead of schedule in January 2018.
Balance sheet - remains very strong, in fact it's got stronger mainly due to a big fall in the accounting valuation of the pension deficit - down from £23.2m a year earlier, to £8.5m at 30 Sep 2017. Remember though that in the almost incomprehensible world of pension scheme accounting, the deficit recovery payments are calculated on a triennial actuarial valuation, which is usually considerably larger than the accounting deficit;
The calculation of the pension deficit remains very sensitive to changes in assumptions, and the pension deficit under IAS19 is now calculated as decreasing from 16.6m at 31 March 2017 to 8.5m. This is largely due to updated membership data and an increase in the discount rate. Positive asset performance and changes to the mortality base tables also reduced the net liability. The triennial actuarial valuation as at 31 March 2017 is currently being calculated.
NAV: £83.8m
NTAV: £83.6m - as you would expect, this is little different to the NAV figure, as wood yards don't tend to generate much intangible assets, unless acquisitions of other companies are done.
It's been a heavy year for capex, presumably on the new depots opened recently. So property, plant & equipment has increased 26.2% to £31.9m, compared with the equivalent number a year earlier at 30 Sep 2016.
Working capital is very strong indeed - current assets are £92.7m, versus current liabilities of £30.3m. Divide one by the other, to get the current ratio of 3.06. Even if you deduct the £12.26m long term liabilities from net working capital, there's still a very strong surplus. Does this matter? Very much so - it means the company should not need to dilute shareholders, and it should also survive any future recession. There's also the possibility that the company might acquire competitors using its surplus cash.
Valuation - if we assume that the company is probably heading for around 50p full year EPS in its current financial year, then the PER is 17.3 . That may not look particularly good value for a fairly basic, cyclical business. However shareholders also get a load of surplus assets too, which we should attribute some value to. The way I look at things, I'd say about 20% of the share price could be seen as surplus assets on the balance sheet, which would bring the PER down to just under 14 - which looks reasonable value.
My opinion - maybe the share price here ran a bit ahead of itself? The same could be said of many shares at the moment - we've had a long bull market, and lots of things look over-priced now.
In this case though, I don't see any collapse in its end markets being likely - housebuilding has gone up the political agenda a lot lately, so Lathams seems likely to see continued strong demand from builders.
It sounds as if the company is starting to pass on some cost increases to customers. So this could be seen as a bit of a blip in profits in these results today.
Overall, I like the company a lot, and think it looks sensibly priced at the moment. I would like to see the company pay much more generous dividends, instead of hoarding cash.
ST Ives (LON:SIV)
Share price: 79.25p (up 7.1% today)
No. shares: 142.8m
Market cap: £113.2m
St Ives, the international marketing services group, provides the following trading update covering the three months to 3 November 2017.
I like the format of this announcement - starting off with summary, then giving more detail below.
Overall, trading in the period has been positive and ahead of management's expectations, with Group revenue running approximately 4% ahead of the equivalent period last year.
Management expectations must have been rather low, if a 4% uplift is ahead of it. More detail is given on the divisional split of trading. One part of the business seems to be trading well, with other parts struggling. This was explained in more detail at the last results, which I wrote about here on 3 Oct 2017.
My opinion - the balance sheet is the deal-breaker for me with this company.
Also, given macro headwinds, I'm trying to avoid marketing companies. It can often be the first cost that customers slash, when they encounter difficult trading conditions. Plus there seems to be a flow of marketing spend towards Google & Facebook, to the detriment of others. Although SIV does mention today positive progress in its digital businesses, so it looks like they're getting a slice of that particular cake.
Overall, this one's not for me. I think it would require a lot more research to get my head around all the issues. Whereas I prefer much more simple investment propositions.
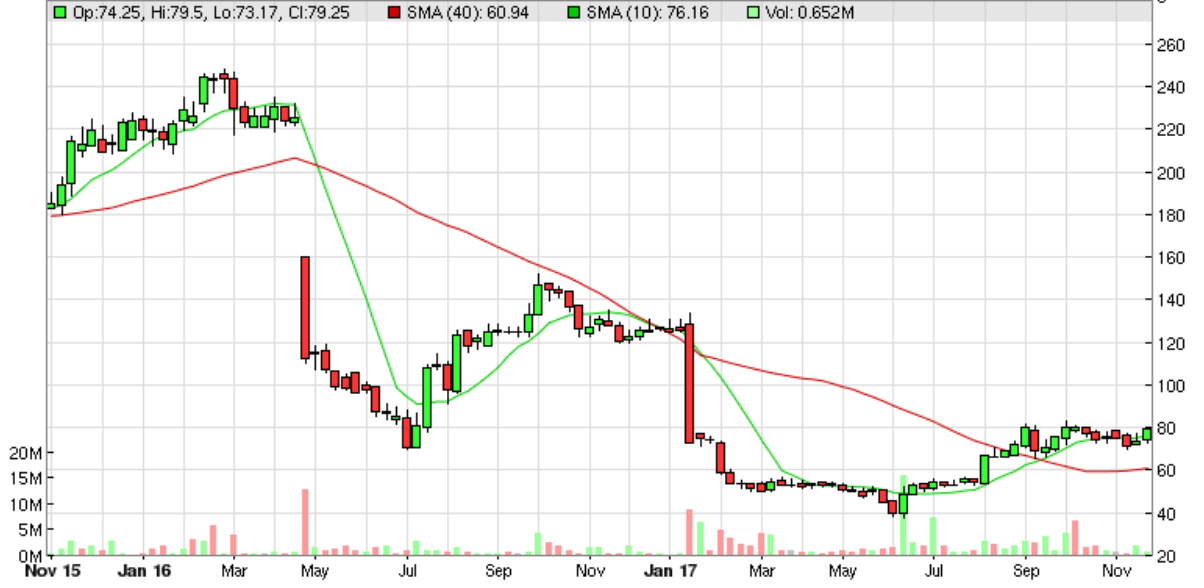
That said, the chart above is looking attractive - having formed a good base this year, and having moved above the moving averages. So there could be some mileage in it, possibly?
On The Beach (LON: OTB)
Share price: 444.75p (up 11.5% today)
No. shares: 130.4m
Market cap: £580.0m
Preliminary results - for the year ended 30 Sep 2017. This is an online travel agent.
Today's results are very impressive. This could be the last time we report on this company, as it's now above our usual upper end market cap (of c.£400m) - although we bend the rules if something looks interesting.
Both Graham and I have written positively about this company before. Looking through today's accounts, it strikes me as a growth at reasonable price company, and am kicking myself for not buying some a while ago, when it was on a cheaper rating.
All the P&L measures are up today, e.g.
- Revenue up 17.2% to £83.6m (14% organic, and the balance being from a small acquisition called "Sunshine".
- Adjusted profit before tax is up 33.8% to £28.5m
- Adjusted proforma EPS up 35.4% to 17.6p - a PER of 25.3 - that's a whisker ahead of broker consensus of 17.5p
Note that this share has re-rated a fair bit - when I reviewed it here on 2 Feb 2017, I thought it looked a nice GARP share, and at 280p per share then, the forward PER was only 15.3. In the 10 months since, the shares are up 59%. So this was clearly a missed opportunity for me, and am kicking myself for not having bought some, when the value was so obvious.
Forecasts - looking through broker notes today, earnings are forecast to continue growing strongly, as follows;
FY 09/2018: EPS 21.9p - forward PER 20.3
FY 09/2019: EPS 26.1p - forward PER 17.0
Those multiples don't look stretched to me, considering this is a fast-growing, profitable online business. If anything, I could see scope for this share to re-rate upwards more - in a bull market this is very much the kind of thing that would be attributed a premium rating.
Reading through today's narrative, the company's business model seems to focus on having a low cost overheads base, and negotiating deals (sometimes exclusives) directly with hotels.
Marketing costs - reaching sufficient scale to be able to fund a large & growing marketing budget, and increase profitability too, is what all online businesses seek to do. Many fail to achieve the necessary scale. In this case, the company has clearly succeeded, and manages to generate a high net profit margin too. I'm really warming to this share.
Note that the marketing spend in FY 2017 was by far the largest cost, at £40.3m. To be able to spend that much, and still achieve a £28.5m adjusted profit for the year, is really impressive.
The blurb today says that OTB has 20% market share of UK online sales in the short haul beach holiday market. I find it remarkable that this relative newcomer has managed to grab that sort of market share from the bigger, established holiday companies. So whatever OTB is doing, it's clearly very good at it.
Current trading - is going well;
"The Board is pleased to report that current trading is in line with expectations and believes the business is well positioned for the key trading period that commences in late December and continues into Q1 2018."
Balance sheet - is nothing special. However, travel companies can often manage with quite weak balance sheets, as they receive payment up-front from customers. So this isn't a worry.
Cashflow statement - I've reviewed this, and am happy with it. There aren't any funnies - this is a genuinely cash generative business. It
My opinion - as you've probably already gathered, I really like these numbers.
OTB is currently a mainly UK-focused business, but is also expanding (from a low base) in Scandinavia, with a launch in Denmark imminent too. If it can crack some overseas markets, then that could drive a further re-rating.
There is also potentially more M&A, and expanding the product range into longer haul destinations.
Overall, this looks a very nice business, at a reasonable price. It's not easy to buy into a company which has more than doubled in price in the last year, but in some cases that can still make sense.
HML Holdings (LON:HMLH)
Share price: 34p (down 4.2% today)
No. shares: 45.4m
Market cap: £15.4m
Half year report - for the 6 months to 30 Sep 2017.
This is a property management services group, which is growing by multiple small acquisitions.
- H1 revenue is up 25% to £12.7m
- Profit from operations is only up 5% to £713k.
- If we add back the amortisation charge, then operating profit of £993k is up 9.5% against H1 last year.
- Adjusted diluted EPS actually fell from 2.0p in H1 LY, yo 1.9p in H1 TY. That occurred because the average number of shares in issue has risen from 39.9m a year earlier, to 46.2m.
The balance sheet is also showing the strain of multiple acquisitions, with £18.6m of intangible assets, within a total NAV of £13.5m. So NTAV is negative, at -£5.1m - something I wouldn't be happy with if I were invested here. Trade payables looks stretched to me, although this type of business does tend to have a favourable working capital profile.
My opinion - I can't see much attraction here. Maybe management should re-assess their strategy of multiple acquisitions, and why that is not feeding through into much profit growth?
The comments about increased regulation sound interesting though, as that could increase business for HMLH and other regulated companies, as unregulated competitors might be forced out?
With a weak balance sheet, and questionable strategy/execution, I can't see any particular appeal to this share.
All done for today.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Somero Enterprises Inc (LON:SOM) has been weak recently. Possibly because the pound has strengthened against the dollar, thus its earnings in pounds are less. But surely if the US tax bill passes then its corporate tax rate will go down from 34% to 20% thus increasing eps and therefore fair value by 21% to about 25p/share. And there is net cash of about 18p per share. This doesn't seem to be factored into the price as once you reduce the price by net cash then it is about 250p and potentially on a pe of just 10. The company is cash rich so won't be affected by reductions in interest deductibility. I am long and have hedged currency risk by buying pound/dollar.
Does anyone have any counter-arguments?
Re: Somero Enterprises Inc (LON:SOM) etc.
The US tax proposal is not just about tax rates:
In the Republican proposal, all overseas assets from US-owned companies would be considered repatriated and taxed at a one-time lower rate of 12%. Illiquid assets like real estate, meanwhile, will be taxed a lower rate of 5%. From http://uk.businessinsider.com/trump-tax-plan-repatriation-taxes-2017-11
The 12% and 5% rates have been moving. The Senate plan has suggested 10% on cash assets and 5% on non-cash assets and the House suggestion was 14% and 7% respectively. https://www.accountancyage.com/2017/11/14/gop-tax-reforms-will-affect-multinationals-foreign-earnings/ I don’t know the current proposal. This can be thought of as a capital tax on overseas subsidiaries. I imagine that there will be bankruptcies, especially in capital intensive businesses. There will be covenant breaches. Working capital will need to be replaced. Assets will need to be sold, and bonds and shares issued to pay the tax. All this will make it difficult to fund growth.
Will the US tax proposals be ok in the long run for companies that do not have capital intensive overseas operations? Yes, if the companies involved can survive. The US worldwide tax system, where US companies/people/etc. have to pay taxes in the US AND in the country in which the profit is made, is … expensive/unworkable/difficult/traumatic.
KPMG explains: “Whilst this measure directly impacts US shareholders, there will clearly be wider repercussions and impacts on financing decisions for multinational groups.” (ibid.)
My translation: There may be some chaos.
Laurie, I'm not sure why those aspects of the bill that you quote should be relevant to Somero Enterprises Inc (LON:SOM) - as far as I understand it they don't have overseas assets or subsidiaries, even though they export a lot. They seem to generally pay the full corporation tax of 34%. So I can't see why they should be impacted by the rules that you mention.
Please correct me if i am missing something.
Dear dgold,
I don't know if this will have much impact on Somero Enterprises Inc (LON:SOM) . (I am not a holder, although I appreciate the merits of the company.) The company might be one of the immediate beneficiaries of the changes.
Somero also maintains a Sales, Service and Training Facility that is home to the Somero Concrete College in Shanghai, China as well as sales and service offices located in Chesterfield, England and New Delhi, India. https://www.somero.com/about-u...
If an office building is owned or leased abroad, if there is working capital abroad, perhaps even pensions for employees, etc. etc., this could be taxed if the bill passes in its current form. Much depends on what form the new rules take, and how the IRS implements the changes. There is uncertainty.
I spent quite a bit of time trying to estimate the potential damage to companies that I held, looking at websites and financial accounts, although carefully worded emails to the CFOs would probably have been a quicker and more accurate way to get the relevant information. I chose to sell every US holding, but that reflects what I held, rather than what I would do if I held Somero.
30% of Somero's turnover is non-US, and there is a physical presence in at least three countries, so it is unlikely that there will be no extra tax bill for this 'deemed repatriation'. It might, however, not be a meaningful tax bill, and shareholders would continue to hold, happy in the knowledge that a lower tax rate would mean increased earnings in future years.
Re. your question on Somero Enterprises Inc (LON:SOM) - the main counter argument I would run would be that I think the majority of the effect of the US corporation tax cuts was likely built into share prices several months ago when the market got very excited about this particular Trump promise, and this has fuelled a lot of the gains we've seen before the actual bill has passed. That's not to say the effects won't still be beneficial long term of course and may as time passes filter into more gains, but I would contend that much of this may already in the prices we are seeing. It's also worth bearing in mind that SOM has historically traded on a relatively low P/E reflecting its business type, but which has increased quite a bit over the past year or so - the hard part is working out how much of the gains are down to the good performance of the business and how much is down to the background and the well-publicised US tax reforms etc. I suspect at least some of the gain is down to the latter and is priced in to some degree already so I'd be surprised if we get any sudden uptick on the tax reforms coming in.
I like SOM a lot and am a former holder - I sold out a few months back feeling things had got a little ahead of themselves and have not yet made a call on what level I might be wiling to go back in at, but I'm keeping a close watch.
Thanks for your reply and thanks to Laurie's reply too.
I accept that some of the run-up in price was probably to do with the tax reform, although I note that I personally didn't notice that the price changed continually in line with the prospects of the reform waxing and waning, as eg bonds and the dollar did. Maybe that's just because it's less liquid, so not a lot can be read into it.
I still think though that a pe of 10 is low, given its strong balance sheet, the present strength of the American market and its present (and potential for further) international diversification.
Re Revolution Bars (LON:RBG), To those of you who invest in this segment of the market, I recently read that every restaurant group quoted on the LSE had now issued a profits warning. If this is true it confirms what a rather wealthy friend of mine has told me. A couple of years ago he remarked that he had found this an unusual recession in that he had always found it difficult to get a good table at a restaurant. However since the middle of this year he had found it much easier and had recently dined where he was the only customer. The owner told him that business had declined markedly since August.
Does depend a bit on what you call a restaurant. Are Revolution Bars (LON:RBG) a bar or a restaurant? J D Wetherspoon (LON:JDW) who do a lot of food are doing ok. Patisserie Holdings (LON:CAKE), who do more than just coffee and cake are doing ok. But it does seem to be a tougher market that is now exposed to stronger headwinds on costs and disposable incomes than it was a while ago so only the very strong or very special situations are investable.
Disclosure - I have a small long position in Patisserie Holdings (LON:CAKE)
re Revolution Bars (LON:RBG), there was also a significant sell -down by Sandgrove who offloaded 5% on Tuesday: that said there has been a fair bit of accumulation by a few players over the past couple of months, I took a trading position off the recent pullback following the no-deal as the upside does look good with Revolution Bars (LON:RBG)
Is Shareholder info available within Stockopedia? If not, it would be very handy, thanks.
Interesting to see mention of Northern Bear's interims today. This is a share I have looked at more than once but never purchased on the weak rational that it was to good to be true. EG. Rank 99,PE7.45, F/Cast EPS Growth 44.1%, Dividend 2.98% My real reservation was the Intangible Assets at almost 50% of total assets. But it is still a cheap and seemingly growing company and I fear I may regret my decision not to invest.
RE: RBG
Deltic Group (The) Notification of Major Holdings - 3% crossed on 28th Nov
RE: RBG
I'm surprised at the muted market reaction as this puts RBG back in play?
Lamprell (LON:LAM) is a tricky one. I used to cover them when I was an analyst. A lot of their asset value is tied up in its quayside yards and fabrication works in Sharjah and Hamriyah (ie the Emirates). Also the high levels of working capital is a feature of their main products, ie delivering big lumpy items like jack-up drilling rigs and wind turbine installation vessels.
The lumpy nature of its order book means the delays that are always a feature of these kinds of businesses are that much more painful as they relate to a small number of big contracts.
Lamprell (LON:LAM) investors took a big hit about 5 years ago as operational issues led to Working Capital shrinking pretty drastically, covenant issues with the banks and about 5 profit warnings if I remember correctly. The drivers of this were because:
1) The supply market tightened for key vendor equipment on its jackups,
2) A slow-down in new project awards, and
3) Their costs overran on building turbine installation vessels.
The real kick in the proverbials came when it emerged that some of the key Management (eg the Head of Operations at one of the yards) sold all their shares a couple of weeks before the first profit warning. This did not go down well with investors...
Anyway, since those volatile days, the business restructured and brought it new, well-respected Management. I don't want to cast aspersions on them but just wanted to highlight that when things go wrong with contracts in these sorts of companies they can go wrong very quickly and painfully.
Paul - It would be interesting to know why OTB doesn't qualify for any screens. The stockopedia thing says the value is 9 out of 100. That just seems wrong to me. Before the share price rally today the forward P/E was about 18X. For me that doesn't really merit only a 9 out of 100 value rating. Will have to research how stockopedia assesses this. But this could be one area where the computer was wrong.
Put On The Beach (LON:OTB) into a portfolio; click on the "ranks" tab; click on the "Value Rank" circle for On The Beach (LON:OTB), and a pop-up will show you how the Value Rank was calculated.
ratioinvestor
The Value rank is based on 6 ratios, all historic:
https://help.stockopedia.com/product-guide/stockranks/basics/the-value-rank
On The Beach (LON:OTB) scores poorly on all, although after todays results the historic p/e will drop from 40x to 27x so the Value rank should move higher
Paul, I was wondering what your thoughts on
The placing for Cloudcall (LON:CALL) were, as I believe you still have it on your bmus? Ta!
CVS (LON:CVSG)
Interesting to see the comparison to Pets At Home.
Positives from their RNS statement today:
CVS Total sales over the last 4 months up 20.6%
LFL sales up 4.3%
However, take out Animed Direct, and the LFL sales are 1.5%
Stocko graphs look v. positive (haven't worked out how to put them on here!)
5 year chart also looks positive with a steady increase in share price
Negatives:
Gross Gearing 121%
Net Gearing 113.6%
Potential higher costs of staff
I have held CVSG for a few years. Human nature will always pay out for medical treatment for their pets, either at the Vets or Veterinary medicine because none of us like to see our favourite pooches suffer.
However, Animalcare (ANCR) also falling. Is this a trend in Pet healthcare or are they totally overpriced?
Perhaps Lamprell will copy what their ex competitor Thalassa has done and give up the underwater business,sell up and buy in their own shares at a large discount to cash.
Good morning Paul,
Could you take a look at Northern Bear (£NTBR), a specialist builder in the north of England. Positive results, but a few questions about profit margins reducing and winter working, but a well managed company. It would be great if you could run your eye over the numbers.
Many thanks,
Nick
I think winter-weather has always been a factor for NTBR; I'd say that the price fall today is all around the reduced margin. I looked back through several years of results and I find it a bid odd that they are very selective in their mention of margins.
Thanks for replying Andrea and I take your point. Given the quality of the management and not being a trader, I will continue to hold for the long term.
Regarding brokers, I would say almost everyone likely to be reading this should have more than one broker as even the best of them will have occasional problems. Here are a list of problems / disadvantages I have encountered over the last month:
* iDealing - unable to quote a price when Selftrade could. Slightly worse prices than Selftrade on some shares.
* Selftrade - account inaccessible for a week following a poorly tested revamp. Short outage more recently. Not able to quote so put in a limit order at market maker quoted level. A couple of trades then went though at this level before the price moved against me 10 minutes later. Limit order disappeared without explanation leaving me unsure whether executed or not (it wasn't).
* AJ Bell / You Invest - deals I'm sure I made not being confirmed immediately - usually 10 seconds to 1 minute but currently waiting for a trade I did 30 minutes ago. Very aggressive automatic logout necessitates use of browser extension to keep logged in.
* IG Index - spreads based of market maker quoted prices effectively preventing online dealing where these are fake. Frequent changes to margin requirements, e.g. if there is any kind of election or market volatility. Threatening to replace powerful online dealing system with a toy version.
I'm a client of IG and trying to understand your complaints against IG.
About the market maker quotes - note that if you are doing share dealing then you will request a specific quote and will get one which will often be inside the spread. With CFD trading too, you can use their L2 platform and get market maker quotes. With spreadbetting admittedly you need to call to get a better price.
Margin changes - I think that's fairly understandable and regarding CFDs/spreadbetting with shares they rarely change their margins (exception was before Brexit vote when I think all they did was to make a minimum margin of 10% - this only affected the stocks on 5%).
Threatening a "toy version" - I have no idea what you mean, please explain.
Re: Having more than one broker / IG.
These weren't really complaints about IG rather than reasons for having other brokers. When I said "IG Index" I was referring to their spreadbetting service - I should have made this clearer especially as they stopped using the name "IG Index" for spreadbetting (and "IG Markets" for CFDs) quite some time ago. I did try editing to clarify this when I saw your reply but it was already too late.
True market maker online quotes - I very much doubt anybody offers these on a spreadbetting service, so absolutely not a complaint, just a reason not to put all you eggs in one basket.
Looking through my emails I've had 4 temporary event margin changes in the last year (i.e. excluding the US election and Brexit), plus at least 4 others. Often these are with around 3 days notice even if the event was known about months/years in advance or the policy change had been planned for months. I know that if there was a big market correction they would increase margin at very short notice. My point really is that it is not only Barclays that change their T&Cs at quicker than you can move.
Replacing dealing system with a toy version: Every service I have used have completely changed their dealing system in the last few years. iDealing changed to an improved version without disruption (for me). Selftrade have changed twice with medium-large amounts of disruption. AJ Bell changed once with very minor disruption. IG Index have handled it better than all of these by running old and new together and offering a choice (there was some login flakiness for a while, but it could be worked around). However the new one is still missing features and I know that one day I'll log in and find it is the only option. Again, my point is that it is not only Barclays that remove features that most people don't use.
Finally, in case I gave the wrong impression, I should say that I've found IG (spreadbetting) by far the most reliable at executing trades. I can't remember ever having problems not even during the most extreme market conditions. But there is no guarantee they will keep this up and that alone is a reason to have a second account in place.
Amanda re your note 10 on CVS (LON:CVSG).
I believe the market is concerned that like-for-like sales have grown by much less than last year.
One reason suggested for this is the increasing shortage of qualified staff, particularly since Brexit, which could restrict further growth.
I have held in the past but sold at 1,300p.
Hi Paul
I noticed RBG has had a couple of good up days. Have you any news?
Cheers Dave
Hi lupehaho,
I noticed RBG has had a couple of good up days. Have you any news?
No, there hasn't been any news from the company.
I'm not going to speculate on why the share price has moved up or down, I just focus on company trading updates & results statements.
Regards, Paul.
Morning all, just published, (following on from the Achieving Exceptional Returns interview with Leon Boros http://www.piworld.co.uk/2017/11/08/leon-boros-on-achieving-exceptional-investment-returns/).
Leon provides more insight, with a later interview: Understanding Accounts:
http://www.piworld.co.uk/2017/11/30/leon-boros-understanding-accounts-interviewed-by-tamzin-freeman/
A fascinating insight of what he’s looking for in a set of company accounts, using examples to highlight some of the hidden factors to look for. For non-accountants it can be quite a heavy watch, particularly at the midpoint, but there are many gems, and it’s worth making it till the end – even if you watch it in chunks!
First focus: cashflow statement & free cashflow – 00:31
Amortisation – 08:20
YouGov’s earnings – 12:17
P&L and Balance sheet ratios – 15:30
Return on total assets – 18:29
Paul
Any chance of looking at CVSG. AGM at 11am today and price plummeting over 15% even though profits reportedly up and small increase in like for like sales. Everyone loves their pets and would rather go without than see them suffer.
Thanks
CVS (LON:CVSG) sales growth (LFL) has shrunk to 1.5%
In the past I've compared the p/e ratings of Pets at Home (LON:PETS) & CVS (LON:CVSG) (12x v 25x) & wondered whether the former could get re-rated.
Now it looks as though parity will be more likely achieved via a de-rating of CVS (LON:CVSG).
I'm not sure of the logic comparing these two groups. One is a chain of vet practices and the other is retailer of pet related products. Just because dogs and cats come in through the door of both companies doesn't mean they have the same dynamics. Pets at Home faces the online threat and general retail competition. CVS Group has more of a competitive moat with people having a relationship with their vet.
ratioinvestor
You might be suprised to learn that Pets at Home (LON:PETS) operate around 400 vet practices, a similar number to CVS (LON:CVSG) (!)
Basically PETS = CVSG + a retail operation
I don't disagree. But the relative importance of vet practices to both is markedly different. In terms of profit generation it remains the case that CVSG is vet practice group and Pets at Home is a retailer. Or at least this was the case when I last looked at it.
Relegations/promotions of the FT100 and 250 confirmed by LSE.
The 250 results in particular may be worthy of consideration as this puts small companies on the radar of more funds and analysts-
List provided by Alliance News
DS Smith, Just Eat, Halma Oust ConvaTec, Merlin, Babcock From FTSE 100
[ 29 Nov 2017 17:42 ]
LONDON (Alliance News) - FTSE Russell confirmed on Wednesday that the following changes will take effect to its UK indices from the market open on Monday, December 18, after completing its quarterly review.
-------
FTSE 100 Adds:
DS Smith
Just Eat
Halma
-------
FTSE 100 Deletes:
ConvaTec Group
Merlin Entertainments
Babcock International Group
-------
FTSE 250 Adds:
BCA Marketplace
F&C Global Smaller Co
Purecircle
RHI Magnestia
TI Fluid Systems
-------
FTSE 250 Deletes:
Electra Private Equity
Nostrum Oil & Gas
PayPoint
P2P Global Investments
Restaurant Group
Paul, Any chance you could you circle back to some results from your duvet day -in particular, Treatt (£TET) and Gooch and Housego (£GHH)?
Thanks!
Hi Paul - Lamprell (LON:LAM) ? I thought oil & gas sector was not your patch?
Hi Ramridge,
Hi Paul - Lamprell (LON:LAM) ? I thought oil & gas sector was not your patch?
LAM is an engineering company, so I've reported on it plenty of times before. I don't look at explorers or producers of oil, gas, or any other natural resources, as that's too specialised, and most of the explorers are pre-revenue, and hyped up rubbish. Plus there are too many of them. Whereas an engineering company like Lamprell is fairly straightforward to analyse - although obviously its business is heavily influenced by the price of oil.
Regards, Paul.
Hi Paul
Any chance of a paulypilot Shareholder Action Group to try to realise some of the NTAV trapped in Lamprell?
Count me in if you feel like getting your shareholder activist hat back on!
I can't see that this would work for Lamprell? The assets are 'trapped' by the very nature of the business itself, rather than by decision of management? They can't release cash as they're going to need that to survive in the horrific market they currently find themselves in. Have not looked at the books but I would imagine the bulk of their NTAV is made up of their yard and fabrication facilities and if they start selling those off then they are literally selling their primary business itself (and worse still probably at a discount) and ruling out any chance of a recovery in trading if/when things pick up. Overall as I see it you can only hold this share if you believe the rig market will recover over the coming years in time to save them - in my view there is little chance of any form of asset release happening to give shareholders any return by that route.
My morning smallcap tweet:
James Latham (LON:LTHM), ST Ives (LON:SIV), Lamprell (LON:LAM), Hargreaves Services (LON:HSP), Flowgroup (LON:FLOW), HML Holdings (LON:HMLH), Graphene Nanochem (LON:GRPH), Seeing Machines (LON:SEE)
Latham James (LTHM) H1 rev up 7% but pretax down 12% due to higer material cost. Pension deficit under IAS19 down from £16.6m at 31 March 2017 to £8.5m. H2 has started well with growing revenues at slightly higher margins.
St Ives (SIV) 3 months trading ahead of management's expectations. Rev up 4%.
Lamprell (LAM) warns FY earnings materially below current market expectations due to worsening cost overruns on East Anglia One offshore windfarm project. Project now expected to make a significant loss
Hargreaves Servs (HSP) H1 trading in line but anticipates a strong H2 from coal outperformance.
Flowgroup (FLOW) Decides to limit costomers to <250,000, will save the Company approximately £2.5m due to lower regulatory payments. Should beome profitable 6 months sooner. CEO Tony Stiff kicked out to save money. "Whilst profitability remains broadly in line with market expectations, the flat level of customer accounts will have an impact >HML Holdings (HMLH) H1 fev up 25% but adj EPS 1.9p (2.1p). "Adjusted earnings are calculated before interest, amortisation and share based payment charges." Before interest? WTF? EPS 1.2p (1.4p). Blames ne-off costs primarily relating to the integration of acquisitions and associated investments in infrastructure. Margins here actually getting worse as it increases scale. Has beome a serial disappointer.
Graphene Nanochem (GRPH) suspended pending reverse takeover of CG TekBuild Pte a special purpose vehicle set up by Austrilia's Coulter Group Pty "to consolidate a portfolio of projects and opportunities undertaken by the Coulter Group in the development, construction, installation and operations of enhanced modular building."
Seeing Machines (SEE) has won two major Guardian deals in 2017 in the Middle East and Russia, total 5,620 Guardian units. Delivery over a one to two year timeframe. SEE's largest single fleet customer deals to date.
Paul, could you look at Northern Bear (NTBR) if you get a chance? Profitable Microcap.
I'd second Northern Bear (NTBR)
Good morning Paul, welcome back.
It would be good to get your views on Seeing Machines (LON:SEE).
Also, there was lots of discussion yesterday about which broking platforms people use and their experiences. I thought it would be interesting to poll this board and see what everyone uses. So I whipped up a quick survey on Typeform if readers feel they want to share. I hope that's ok? I'll publish the findings with this board once we've got some responses.
Link here: https://voxpops.typeform.com/to/Z7OaLN
Francis
I get an error when I follow the survey link. I’m on my iPad in case that’s relevant.
“Uh oh, the typeform you’re trying to view doesn’t exist”
Sorry, there seems to be a glitch. Try this one https://voxpops.typeform.com/to/Z7OaLN
Very nice user interface on my tablet. Thank you (satisfied share centre customer)
Jon
Maybe you can create a new thread for this - Then we could all find the relevant thread for your subject (assuming you use a sensible subject) and then this thread can be used for company discussion - Just a thought - Note, I filled the form in earlier this morning.
@matylda
I guess you meant to reply to fwyburd?
Thanks Matylda, great suggestion. I have started a thread here:
https://www.stockopedia.com/content/what-trading-platforms-and-information-sources-do-you-use-247753/
So far 56 people have completed this today alone (thank you), so please join in.
Thank you
Francis
BTW: Lots of posters today not using the £sign before the ticker symbol. It helps everyone when you do, as it creates a hyperlink which highlights the stock you are discussing
Re £sign and ticker
I wonder whether there is any way of modifying the posting template to make it mandatory for 'posters' to either insert the ticker or select from a drop downbox with one or two other options like 'general discussion' 'request for coverage'?
I have never been able to make the £sign plus ticker work as described, either on my tablet or PC. Not sure what I'm doing wrong, or whether it's a website glitch.
Hi Francis
Survey is a great idea. I have just completed it but note it does not allow multiple selections under do you pay for research.
Will interesting to see the results.
KR
Michael
thanks for pointing it out, michael. I didn't mean for that to happen and I can't change it now, so i'll have to live with that limitation. Francis
Hi Michael,
I came across this too when completing one section (information sources?). I thought I'd done something wrong and so started over. The same thing happened again but I found I could scroll back up and complete more than one entry.
Cheers.
Malcolm