Small Cap Value Report (Thu 30 Nov 2023) - POS, WYN, AT., MUL, DOCS, MEGP

Good morning, it's Graham and Roland here with today's report. We also have a section from Paul covering Plexus Holdings (LON:POS).
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions
on them as possible candidates for further research if they interest
you. Our opinions will sometimes turn out to be right, and sometimes
wrong, because it's anybody's guess what direction market sentiment will
take & nobody can predict the future with certainty. We are
analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
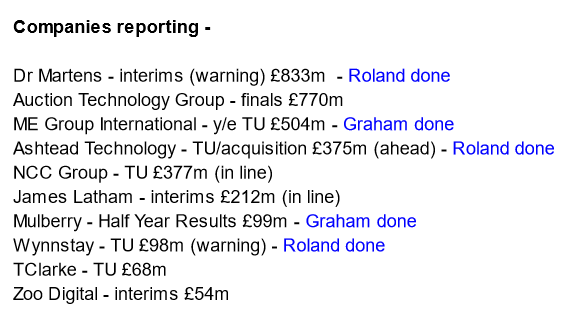
Agenda
Summaries
Mulberry (LON:MUL) - down 15% to 140p (£84m) - Half Year Results - Graham - GREEN
These are poor H1 results as various costs increase. It remains unclear whether the company will benefit from a switch to retailing instead of wholesaling/franchising in certain markets. This is a high-risk choice and in net debt. Valuation (price/sales) extraordinarily low.
ME International (LON:MEGP) - down 4% to 128.5p (£485m) - Year End Trading Update - Graham - GREEN
Full-year revenues are slightly below the bottom end of the range of expectations and this is likely to weigh on growth expectations for now, but this photo booth/laundry machine operator has recovered well post-Covid and continues to offer a high-quality proposition.
Wynnstay (LON:WYN) - down 15% to 363p (£83m) - trading update (warning) - Roland - AMBER/GREEN
A profit warning from this well-run agricultural supplies group suggests earnings may be c.9% lower than expected this year. However, with the shares now trading at a significant discount to book value and offering a 4.5% yield, I suspect there’s value here.
Ashtead Technology Holdings (LON:AT.) - up 17% to 565p - trading update/acquisition (ahead) - Roland - AMBER
This offshore equipment rental group has announced a decent-sized acquisition and reports trading ahead of expectation for 2023. We don’t have any updated guidance, but I’ve been impressed with this business and do not see any major concerns with the acquisition.
Dr Martens (LON:DOCS) - down 26% to 84p - interim results (warning) - Roland - AMBER/RED
This footwear brand is continuing to suffer problems in the US. These seem to be related to both market conditions and operational execution. Repeated profit warnings and rising debt mean that I’m cautious here, although I think it’s a fairly decent brand.
Plexus Holdings (LON:POS) (Paul holds) - down 9% to 20p (£21m) - prelims FY 6/2023 - Paul
Graham's section
Mulberry (LON:MUL)
- Share price: 140p (-15%)
- Market cap: £84m
Mulberry Group plc (the "Group" or "Mulberry"), the British sustainable luxury brand, announces unaudited results for the twenty-six weeks ended 30 September 2023...
This announcement comes with an unusual PR headline:
Investments will power future growth
Instead of being provided with some numbers straight away, we get CEO comments with the following final paragraph (emphasis added):
"Looking ahead, we are well placed to capitalise on the important festive trading period and expect the usual second half weighting to trading.
"There is no doubt, however, that the macro-economic environment has deteriorated, and this has had a knock-on effect on consumer sentiment. At Mulberry we have ensured that we are prepared to navigate this tricky environment, and we are confident in our ability to continue to execute our strategy. I continue to believe that offering VAT-free shopping in the UK would be one of the most effective ways to encourage business growth in this country. The fact this has not been reinstated is creating challenges for all sectors; impacting not only the luxury players, but also hospitality, travel and tourism…”
And then we get the numbers, not expecting very good news:
Revenues +7% to £70m. There is a major shift from franchise/wholesale to retail, as Mulberry has taken many international stores into direct ownership.
In the Asia Pacific region, “underlying” (i.e. like-for-like) retail sales decreased by 7% “due to the challenging China macro-economic climate and reduced footfall across the region”.
Gross margin 69%, down from 71%
Underlying pre-tax loss is £12m (H1 last year: £3m) with a variety of new and additional costs including a SaaS project and new stores in Sweden and Australia.
Current trading:
The wider macro-economic environment and geo-political climate continues to present some uncertainty, but we are well positioned to navigate this given our beautifully crafted product, made in our Somerset factories and sold at the best value price point in the luxury market
A large H2 weighting is expected.
Net borrowings rose to £13.6m (H1 last year: £0.5m). In addition the lease liabilities are worth £53m. There are also some loans (£4.5m) from minority shareholders in China and Japan.
Graham’s view
I last covered this one in April, taking a positive stance on it at 210p.
Unfortunately, sentiment around this share has collapsed over the last two months, and it is now down at 140p:
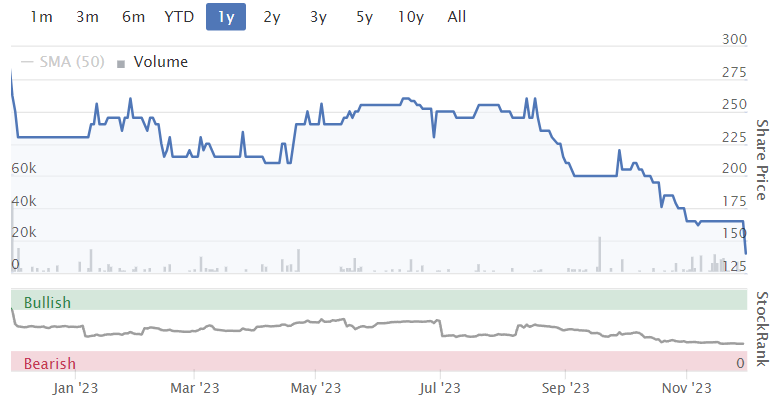
The cash burn was a concern in April too, but I continued to rate it positively due to a very low price/sales multiple, totally out of kilter with the luxury sector.
According to the StockReport, Mulberry’s expected revenues for FY 2024 are £176m. Even if we chop that down to £170m, price/sales for Mulberry is still only 0.5x.
Burberry (LON:BRBY) (in which I have a long position) has seen its share price greatly diminished in recent months, but it still has price/sales of 1.65x. It previously traded at 3x. Kering (KER), the owner of Gucci and Saint Laurent, is at 2.3x. LVMH (MC) is at 4x.
I suspect that one of the main problems for Mulberry is that it is sub-scale, compared to the luxury giants, meaning that it can’t enjoy their efficiencies. The giants consistently earn tremendous operating margins, while the same cannot be said for Mulberry.
So where do I stand on Mulberry? I am tempted to abandon my positive stance, as the company has suffered a bigger H1 loss than last year and is now in a substantial net debt position.
EPS momentum is not encouraging:
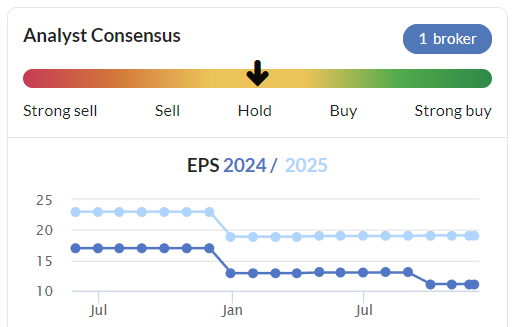
Overall, while I acknowledge that this share is extremely high risk, I would like to stubbornly keep my positive stance on it until we have full-year results, including the stronger H2 season.
My positive stance comes with caveats:
This is not a historically high-performing company
Its cash position is now weak
The main reason I am positive on it is that I see it as a likely takeover target
Note that it is owned by a family (56% shareholding) and Frasers (37% shareholding), so they will ultimately decide its fate.
If the full-year results are very poor, then I’ll again have to reconsider my positive stance. For now I’d rather not change my stance after a poor H1, without seeing the full picture for the year including the stronger H2 period.
ME International (LON:MEGP)
- Share price: 128.5p (-4%)
- Market cap: £485m
ME Group International plc (LSE: MEGP), the instant-service equipment group, announces a post-year end update in respect of the 12 months ended 31 October 2023.
Here are the key points from the full-year update:
Revenue “marginally below the lower end of previous guidance but to be no less than £298 million” (guidance was £300m - £320m)
EBITDA in line with previous guidance (£100m - £110m) and “significantly above £11 million”.
PBT no less than £67m (guidance was £64m--£67m)
Some investors don’t mind seeing a revenue miss if the company still hits its profitability targets, although if you are more growth-oriented you will probably not fall into this category.
Strategic progress: next-generation photobooth rollout is underway, with a range of new features, initially focused in France. There are also various hardware and software upgrades.
After a cheap acquisition in Japan, they are now the leading photobooth operator in that market. Paul covered that deal here.
Laundry machines are expanding: 16% growth to 5,533 units.
Financial position: net cash £34m at the end of October (vs. £24m at the end of H1).
In November, MEGP paid an £11m dividend, so net cash will be lower now.
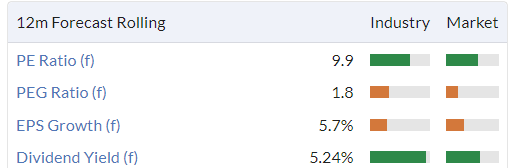
The shares do offer a nice yield:
Graham’s view
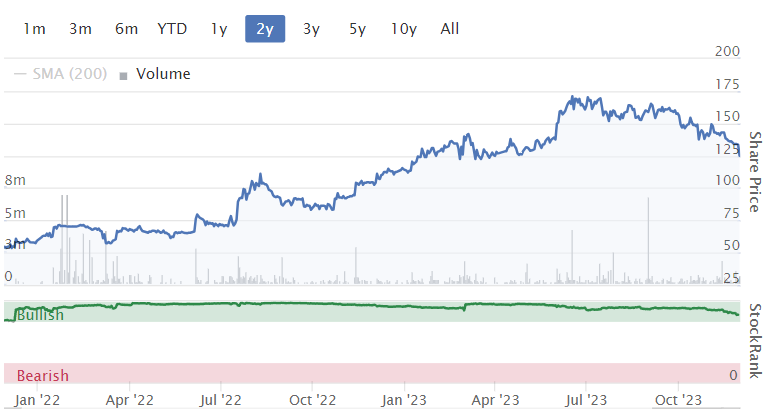
I’m inclined to keep my positive stance on this one. The shares are 40p cheaper since the last time I covered them, in July:
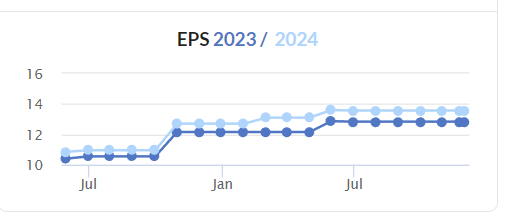
Earnings estimates have held up well, although of course there has been the revenue weakness mentioned above:
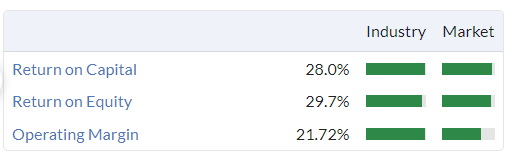
Returns remain impressive, painting a picture of a high-quality stock (QualityRank is 87):
So even if revenues are a little soft, I’m happy to stay positive on this one.
Roland's section
Wynnstay (LON:WYN)
- Share price: 363p (-15% at 08.10)
- Market cap: £84m
Unfortunately it’s a profit warning from this agricultural supplies and merchanting group:
the Group's results for the financial year are now expected to be below current market expectations.
This refers to the company's financial year which ended on 31 October. Management says that sales have been hit by a combination of market conditions and wet weather:
The trading environment in the second half of the financial year was more difficult than the first, with lower farm-gate prices adversely affecting farmer spending patterns. In addition, the seasonally critical final quarter has been impacted by abnormally wet weather.
Due to the disruption caused by heavy rain, sales of winter seed products were lower than usual in October. Demand for feed and fertiliser was also lower due to lower farm-gate prices for milk, in particular.
Sales from the group’s merchanting division (country stores) were also down, due to reduced feed sales and lower demand for hardware products.
Frustratingly, Wynnstay doesn’t provide any indication of current expectations, nor of the likely shortfall in profits this year. That leaves investors on an uneven playing field, with only those who have access to broker notes able to gauge the likely impact.
Fortunately, there is an updated note available from house broker Shore Capital on Research Tree this morning - many thanks.
Shore’s analysts have cut their forecasts for FY23 adjusted earnings per share by 9% to 33.2p per share. That puts the stock on a forecast FY23 P/E of 11 after this morning’s opening drop.
Outlook: the company remains cautious in the short term but is confident of making progress next year:
Looking ahead, with uncertainty over milk and other farm-gate prices, farmer sentiment is likely to remain cautious in the short-term, but with a strong market position and balanced business model, the Board still anticipates that the next financial year will show an improvement over FY23.
However, Shore Capital’s forecasts for FY24 have also been cut and are down 7% to 38.3p per share, giving a P/E of 9.5 and implying 15% year-on-year growth from FY23.
Roland’s view
Wynnstay enjoyed record profits last year due to supply chain disruption, but a return to more normal trading always seemed likely to me.
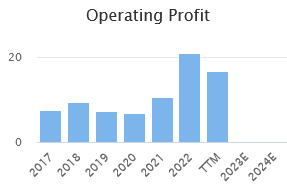
On balance, I don’t think there’s too much to worry about here. However, there’s clearly a chance – or perhaps an expectation – that trading will remain more difficult for a little while.
Wynnstay shares are down sharply this morning, but have already de-rated significantly from last year’s highs:
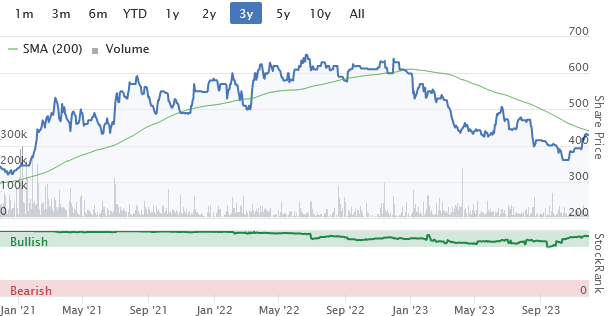
At the time of writing, the shares are trading at 363p. That’s equivalent to a 38% discount to the net asset value of 590p per share reported with July’s interim results.
The share price slump also means that the forecast dividend yield on the stock is up to around 4.5% – I think a cut is unlikely, given that the c.17p payout should still be covered almost twice by earnings.
Wynnstay’s book value may be revised downwards in the full-year accounts, but has generally trended steadily higher over time:
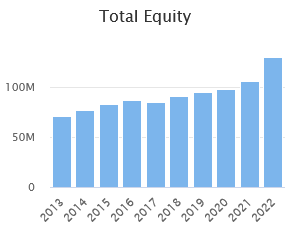
My impression is that this is a well-run business with a coherent strategy. Notwithstanding the risk of further downgrades, I suspect that Wynnstay shares offer reasonable value at current levels.
Ashtead Technology Holdings (LON:AT.)
- Share price: 565p (+17% at 09.15)
- Market cap: £455m
Shares in this subsea equipment rental and solutions provider are up by 16% this morning, thanks to a short-but-sweet trading update contained within an RNS entitled “acquisition of ACE Winches”.
The Board continues to be very encouraged by the Group's performance through H2 2023 and now expects FY23 to be comfortably ahead of its previous expectations before taking into account the additional growth from ACE Winches.
This is clearly good news, but once again there’s no updated guidance on expected earnings.
There aren’t any updated broker notes on Research Tree either, so we’re left in the dark until updated consensus forecasts filter through to Stockopedia. Not ideal for a £450m company, as institutional investors will presumably have access to updated forecasts from house broker Numis.
Let’s move on and take a look at today’s acquisition.
ACE Winches acquisition: Ashtead has bought a business called ACE Winches for £53.5m from its founders, Alfie and Valerie Cheyne.
ACE has been trading for 31 years and specialises in equipment needed to install, maintain and decommission offshore energy infrastructure:
The company's in-house designed and assembled equipment rental fleet is one of the most comprehensive and diverse ranges of back deck machinery in the industry and is designed to deliver reliable, fully integrated solutions to address all complex lifting, pulling and deployment challenges.offers a fleet of in-house designed rental solutions to address all complex lifting, pulling and deployment challenges.
The company's website suggests its involved in some fairly large and complex projects.
The acquired business generates about 80% of its revenue outside the UK and has offices in Norway, the UAE and USA – so presumably this gives us an idea of its main markets.
ACE Winches’ existing chief commercial officer will run the business, which will be integrated into Ashtead’s Mechanical Solutions offering. Founder Alfie Cheyne will remain with the business for 12 months as an advisor.
ACE Winches had gross assets of £55.7m at 31 March 2023. The business is expected to generate revenue of £43.4m and adjusted EBITA of £10m in 2023. This suggests an underlying operating margin of more than 20%, so it seems quite an attractive business.
Set against these metrics, Ashtead’s purchase price of £53.5m gives a multiple of about 5.3x EBITA. This doesn’t seem too expensive to me, assuming earnings are sustainable in the acquired business. In my view, this sounds like a retirement sale, so perhaps the sellers were also motivated by finding a good home for the business they’ve built over the last 31 years.
Ashtead’s management say they’re confident the acquisition will generate a return on invested capital “materially ahead” of the group’s weighted average cost of capital in year one.
I agree that the price paid for ACE Winches seems reasonable, but this is still a material deal for a £450m business such as Ashtead. The company says the purchase will be funded by drawing on its existing revolving credit facility (RCF).
The interim results indicate that the RCF had a total commitment of £100m at the end of June 2023, of which £31.5m was drawn. There was also an additional unusued £50m accordion facility.
The RCF carries an interest rate of 2.25%+SONIA, which is currently about 5.2%. So that’s a total cost of around 7.5%.
Assuming this situation hasn’t changed, funding the ACE purchase from the RCF seems reasonable to me.
Ashtead says that following the acquisition, group leverage is expected to be 1.4x EBITDA, reducing to less than 1x by December 2024. Cash generation seems quite strong in this business, so I don’t see any obvious concerns here.
Roland’s view
Ashtead Technology’s main customer base is the oil and gas sector, but the group also has a growing presence in renewables.
The shares have already three-bagged since the firm’s 2021 IPO, making it a rare standout performer among recent flotations. Congratulations to investors who spotted the opportunity early:
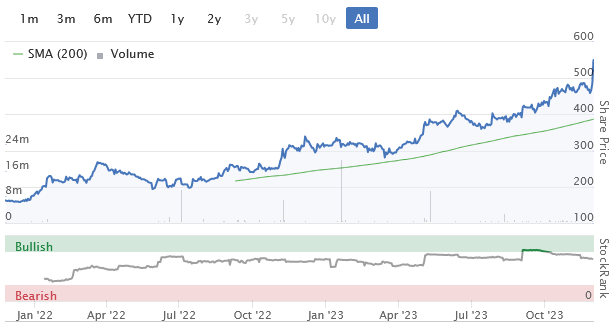
Today’s valuation seems a logical add-on to Ashtead’s capabilities at a fairly reasonable price.
However, in the absence of updated broker forecasts, it’s a little hard to take an informed view on valuation.
Prior to today, we know that Ashtead’s adjusted earnings were expected to rise from 19.5p in 2022 to 28.1p per share in 2023 – an increase of 44%.
Growth was then expected to ease in 2024, with an 8% increase in earnings to 30.5p per share expected
These forecasts priced the stock at around 16 times FY24 forecast earnings. If today’s share price reflects the expected increase in earnings – so the P/E remains the same – then I would say that Ashtead might still be reasonably valued, given the group’s excellent quality metrics and record of growth:
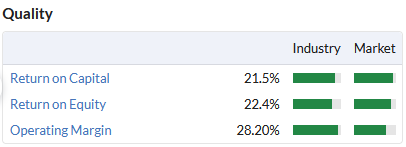
However, given the absence of updated guidance and the cyclical risks in this business, my preference would be to wait for the full-year results to get a more detailed understanding of the group’s trading and financial performance.
Paul went AMBER/GREEN on this stock following the interim results in September. For now, I’m going to go AMBER, reflecting the increased valuation since then and additional risk/complexity resulting from this acquisition.
Even so, I remain impressed with this business and fairly positive about the outlook.
Dr Martens (LON:DOCS)
- Share price: 84p (-25%)
- Market cap: £817m
Today we have interim results and another profit warning from this accident-prone bootmaker, which was floated at an exorbitant valuation by private equity in 2021. The shares have fallen by 80% since then:
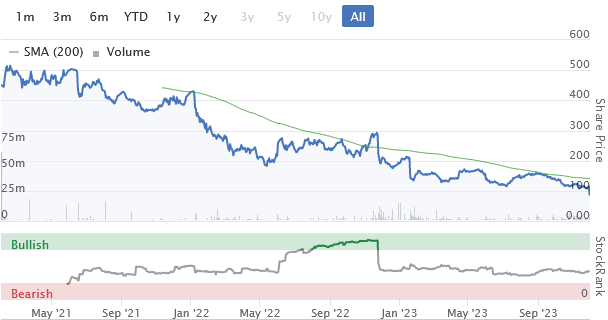
Dr Martens problems seem to have been caused by a mix of poor operational management and slowing growth. Paul reported on a previous warning in January, when the company admitted that its US operations were causing serious operational problems.
Today’s profit warning also seems to be linked to the US:
“We saw a continued strong DTC performance in EMEA and APAC. In the USA, where there is an increasingly difficult consumer environment, our results have been more challenged, led by weakness in wholesale.“
The company has beefed up its US leadership team and they are focusing on marketing and ecommerce, but…
It is likely, however, that given the challenging backdrop it will take longer to see an improvement in USA results than initially anticipated.
Outlook: the current financial year ends on 31 March. The company still has the key Christmas trading period to look forward to but says that “widespread macro-economic caution” among US retailers has resulted in “a weaker order book than in prior years”.
As a result, full-year revenue is expected to decline by a “high single-digit percentage year-on-year, on a constant currency basis”. Profits are now expected to fall below expectations:
Assuming this revenue outturn, we expect FY24 EBITDA to be moderately below the bottom end of the range of consensus expectations, with PBT also impacted by c.£5m higher net finance costs in addition to this lower EBITDA *.
The company has helpfully included a footnote specifying current sell-side consensus estimates:
FY24 EBITDA: £223.7m-£240.0m
FY24 pre-tax profit: £128.7m-£148.0m
For context, the equivalent FY23 reported figures were EBITDA of £245m and pre-tax profit of £159.4m. So pre-tax profit was already expected to fall by around 13% this year, taking the mid-point of forecasts. My reading of today’s results is that a drop of 25%-35% in pre-tax profit from last year is now probably more likely.
Today’s half-year results do not make for very encouraging reading, either, in my view.
Half-year results summary: I’m not sure that the half-year numbers are all that much use at this stage as there's quite a lot of seasonality, but they do give us a picture of performance versus the same period last year.
Here’s a snapshot of half-year performance, to save me retyping all the numbers:
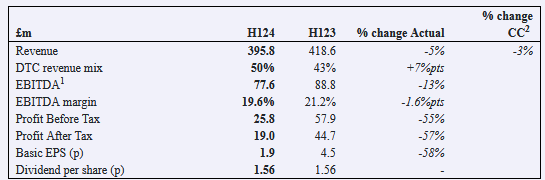
We can see here the impact of operating leverage in reverse. A 7% decline in sales results has resulted in a 55% fall in profits, due to the impact of the group’s fixed costs.
It’s worth noting that this profit slump happened despite a respectable 2.8% increase in gross margin to 64.4% during the period. The real killer for profits seems to have been an 11% increase in H1 operating costs, which rose to £214.6m (H1 22: £192.5m).
The other problem is rising finance costs – these doubled to £16.2m in H1, from £7.8m in H1 last year.
Cash flow / net debt: operating cash flow for the half year was -£23.5m, as the company spent a further £55.5m on inventories and saw receivables rise. This appears to be a typical seasonal pattern, with the second half of the year being more cash generative:
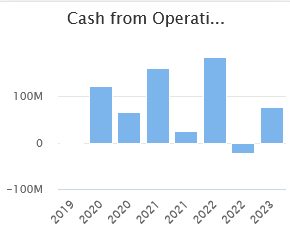
My sums suggest net financial debt (excluding leases) was £277m at the end of the half year (H1 22: £163m). Including lease liabilities, this increases to a statutory net debt of £484m.
The company says that this equated to a leverage multiple of 2x EBITDA at the end of the half year, but that this would reduce to 1.7x reflecting average cash balances through the year. Management expect to repay a £25m RCF drawdown by the financial year end.
My concern is that leverage can rise quickly when the denominator (EBITDA) falls. Dr Martens’ debt level doesn’t seem an immediate issue, but if profits fall too much further, then I could imagine debt becoming a problem.
Roland’s view
I think that a lot will depend on H2 trading and whether Dr Martens can finally get its US operations under control and performing effectively.
Although I think this is a decent brand with a reasonably positive future, I am not tempted to try catching this falling knife at the moment. I would prefer to wait for some signs of stability and a return to growth before considering an investment.
There might be an opportunity here -- I don’t know. But given the potential risks from rising leverage and the repeated disappointments this business has delivered since its IPO, I’m going to go AMBER/RED for now.
Paul's section
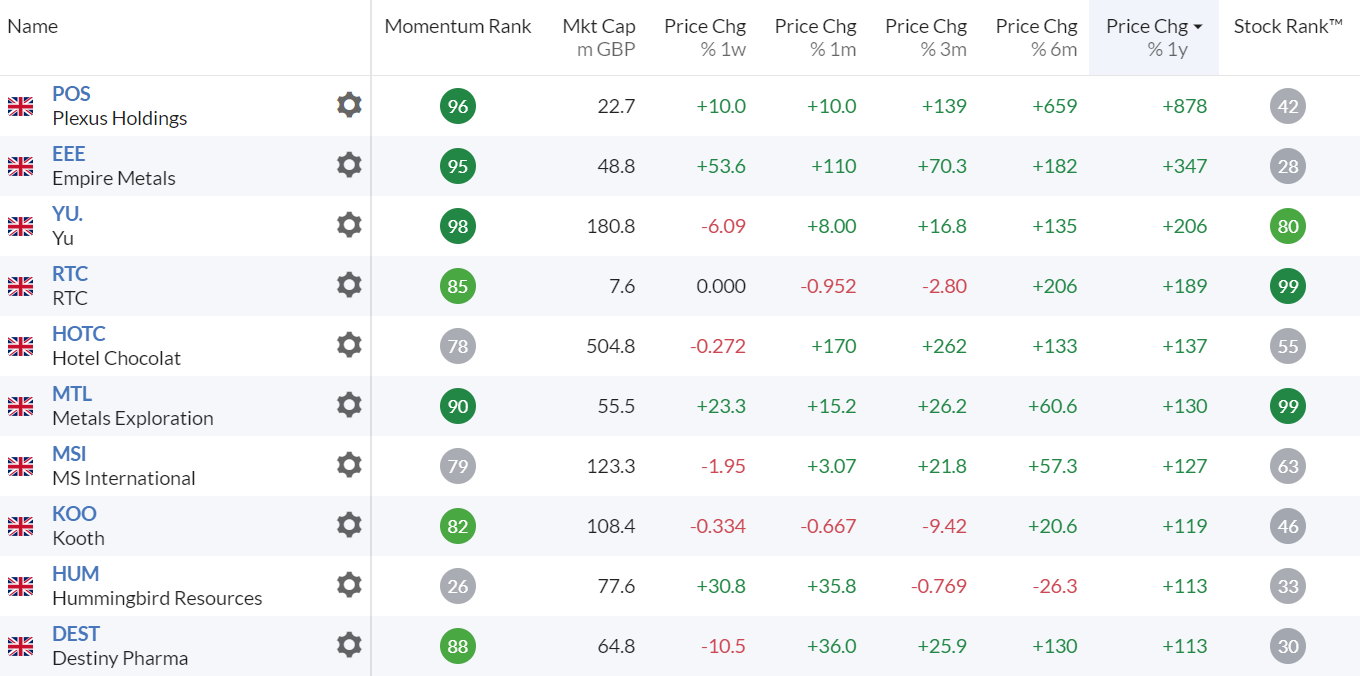
I’ve mentioned this innovative oil & gas sector engineering company a lot in my podcasts, but not much here because it’s previously been too small, and not even remotely a value share! With the market cap now about double our £10m lower limit, and some figures out today, I’ll get some details into the system here if people want to look it up. At present, the archive here has old coverage of it, but when N.Sea oil exploration dried up c.2015, Plexus’s track record of expansion, decent profits (£4-6m pa), and a peak valuation of about £300m went into a sharp decline, down to a low of just £2m in 2022, when everyone seemed to have just written off the company.
It’s coming alive again though, and has been a 10-bagger in the last year, by far the largest % gainer on AIM - here are the top 10 using a momentum view I created in the “Browse” section of Stockopedia - easy to do, and very useful! -
Results for FY 6/2023 - are in line with expectations (see note today from Cavendish) - with poor, loss-making figures, similar to the last c.7 years of continuous losses -
Revenue £1.5m (down from £2.3m last year)
Adj EBITDA (similar to operational cashflow, they say) of a £(2.5)m loss
Note the gross margin is good, at 73%, it just didn’t sell or hire anywhere near enough!
Loss before tax £(4.2)m.
Cash remaining is tight, at £1.45m (although a Lombard loan facility of £4m has been paid off, using up its remaining cash reserves)
“Material uncertainty” note re going concern, as a fundraise was flagged as necessary back in autumn 2022, when the CEO (mainly) put in £1.55m in a convertible loan. So this is high risk, but if you go through the company’s history, Plexus has an aversion to dilution, and in total the CEO has put in £3.2m in various loans & asset purchases - he’s the founder in 1987, and when I had a call with him, it’s obvious this company is his life’s work, and he’s deeply passionate about getting the oil+gas industry to use Plexus’s advanced wellheads, which are methane leak-proof.
Methane leaks - is becoming a massive global issue, as it turns out the O+G sector is polluting far more than previously realised, with widespread methane leaks, and this is a far worse greenhouse gas than CO2. Therefore Governments, environmental bodies, etc, are now beginning to prioritise improvements to ensure the sector cleans up its act. This is the big opportunity Plexus now has, with it’s patented & proven tech (a new suite of patents is being prepared, to give another 20 years protection). Potential markets are also opening up for Plexus is plug & abandonment of oil wells (of which there are many in the N.Sea, where Plexus has decades of experience & knowledge). Recent contracts have been won in this space.
So the upside case on Plexus is -
Proven, patent-protected technology that has been used, profitably in the past.
A new driver for demand, in legislation to stop methane leaks.
Wider markets, which now include plug & abandonment, CO2 storage facilities, and others.
Licensing deal with the world’s largest oil services group, Schlumberger, which is close to launching a new range of wellhead (and other) products, using Plexus’s tech - which should open a new royalty stream soon, of 3-6% of contract value.
Prospects for FY 6/2024 were transformed when Plexus won its largest ever contract of £5m, increased to £8m, and today it says this might be increased further. Amazingly, it’s a high margin rental deal, which is forecast to move Plexus into profit this year, Cavendish confirm this in a new note today (620% increase in revenues to £10.8m, and £0.3m PBT). I put it to you that this looks transformational, and could attract the attention of growth investors, or rather it already has done, with the market cap rising from an absurd £2m, to £20m now. If more contracts of size come in, then we could be only part-way through a serious re-rating. That’s my view anyway, which is why this (speculative) share is by far my largest personal position. Of course it’s risky, but I don’t think it’s necessarily as risky as some people might imagine based on the weak historic figures. I’m buying the future, not the past.
That’s probably enough for now. The best thing is just to read the full results commentary today, which explains what the excitement is all about. Then weigh up how this sits against the downside risks, and make up your own mind. I summarised the bull & bear points on another bulletin board this morning, and repeat this here, which I hope is fair -
BULL CASE -
Proven superior tech, patented & decades of knowhow, experience & contacts.
Previously profitable before drilling dried up in 2015, and valued at peak £300m.
Licensing deal with world's largest oil services group, with products to launch globally shortly = new royalty stream.
Environmental & legislation now prioritising methane leaks - precisely what Plexus's products do - a new & significant tailwind.
Current financial year move back into profit forecast by Cavendish & confirmed in today's commentary from Plexus.
Mgt own 59% and jealously guard the share capital & have backed co with £3.2m of own money in innovative funding recently - commitment & belief this will work.
BEAR CASE -
Needs more funding, hence going concern material uncertainty - dilution unknown.
Has 10x share price rise overshot? (or was starting price of 2p just ludicrously low?!)
Will £8m special project contract win this year be a one-off?
General uncertainty over execution & to what extent they can commercialise the tech?
Paul’s opinion - I think this has the most exciting upside opportunity for any company around this £20m market cap. I also think the risks should be manageable, and I’m anticipating about 15% dilution (which mgt say should come with an open offer for existing holders). That’s why I’ve taken a calculated risk on this share, and taken a large position. It may work out, or it might not, I accept the risk here.
Not the usual sort of thing for the SCVR, but I thought we’d get something up-to-date into the archive here, as obviously my coverage back in 2013-2016 here is now completely out of date! Although it does give a flavour for how valuable this share once was, when its products and services were in demand. Demand is now coming back, as the O+G sector and Governments, realise that gas in particular will be around for decades, and is a key fuel for energy security - instead of relying on imported gas from tyrants.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Interesting article here on damage methane has in the atmosphere with announcements from COP28. Plexus Holdings (LON:POS) .
https://www.nytimes.com/2023/1...
I'm still perplexed regarding Plexus Holdings (LON:POS) as the price to earnings is quite unworldly at 985 or minus 4.8 depending where one checks. The Director seem to have little skin in the game while private companies are all over it:
Hi Silver Moon. On Plexus Holdings (LON:POS) Ben van Bilderbeek has a substantial stake in these private companies so has lots of skin in the game! For what its worth I was a shareholder well over a decade ago and did quite well before selling out. (EDIT - 2010 to 2012 - purchased a small stake at 37p and sold at 81p and 170p but it then went much higher and then much lower!).
I always got a bit frustrated with Ben van Bilderbeek's statements as he always seemed to write numerous pages of complex narrative when a few bullet points and salient comments would be much more understandable. He doesn't appear to have changed!
He is no doubt an intelligent fanatic and has developed some great technology - this is probably his life's work and impressive it is. Well done to those that have done well in this over the last few months. In my view this could maybe 5 bag from here, or run out of money. Its probably evenly balanced. Probably a reasonable risk reward as Paul points out - £nominal to £100m+ maybe. It always pays to be cautious where the auditor has a material uncertainty on going concern as that probably flags a c50% chance of the lower end. You also need to watch the founders age as he is nearly 76 already. Hopefully, he has many years left to drive Plexus forward, but he is not exactly young.
The point that isn't being explicitly covered, from my historical knowledge, is the capital cost of the rental equipment. It looks like its not completed and ready to rent.....so probably in assets under construction with milestone payments partly offsetting. Rental contracts are not normally cash positive in the near term, if you have to build the asset that you are renting out. Rented assets are normally in fixed assets rather than inventory, although sometimes they are dumped incorrectly into inventory and then reclassified out into fixed assets at a later point. The narrative doesn't appear to cover this or the capital commitments from what I can see. Apologies if I'm missing something, but just flagging that its probably quite a capital intensive rental business; it needs to manage its cash flows very carefully given the poor balance sheet. Something to ask management on if you get the chance - i.e. what is the capital cost to build the assets subject to rental agreements signed to date? Hope this helps.
topvest, your reply with its comprehensive reasoning is much appreciated, I think I'll wait a bit to see how things develop. Plexus Holdings (LON:POS) is very interesting but I have thrown away too much of late.
Has anyone any thoughts on the proposed de listing of Quarto (LON:QRT) ?
James Latham (LON:LTHM) H1 30/09/23 (I used to hold)
Background: long established business importing, manufacturing, and distributing timber, panels, and decorative surfaces to trade customers only. No net debt.
Revenue down 10.3%.
Cost prices relatively stable and few signs of price weakness
Some customers moving to cheaper alternative products - the main reason for the reduction in revenues.
GP down, 16.8% cf 19.4%
Overheads down.
Operating profit down 38% (high comparators)
PBT down 31%
EPS down 36%
Surplus in the pension scheme, deficit recovery payment £3m a year will cease from 1 December 2023.
Interim dividend up 6.8%
OUTLOOK
Similar volumes & margins. Some contracts being postponed rather than cancelled. Continued shift to lower value products
Results for the year ended 31 March 2024 will be in line with market expectations.
(NB: most commentators say the family control over 50% of the shares but the last annual report showed, in the list of holdings over 3%, only 16% of shares in family hands).
Re: James Latham (LON:LTHM)
I think it's worth adding some context to Michael's comments above. The company benefited greatly in the short term from the supply chain issues during Covid and posted a couple of years of extraordinary profits. The fact that these would not be sustainable was clearly flagged and we are now seeing a return to some sort of normality.
The broker estimates for full year 2024 were, Net Profit £19.3m and eps of 96.2p.
The half year report that came out yesterday published 6 months eps of 61.5p.
The outlook for H2 has started with "similar volumes" and "similar margins" to H1.
Not only does the company have no net debt, it has cash of £66m, equivalent to 30% of the market cap.
The pension scheme is now in surplus to the tune of £10m and the deficit recovery payments of £3m per year cease from 1/12/2023 (today). £3m is equivalent to 15% of the estimated yearly net profit.
The investment case for James Latham (LON:LTHM) comes down to what you believe the "normal" profitability of the company will become and how they can grow the revenue over time. Margins seem to have returned to historic levels but the company says that customers are shifting towards "lower value" products to contain costs. They are gaining market share in these products, but it's not clear if this could affect margins down the line.
Personally, I like the look of Lathams as a long-term hold. I just get a good feeling about the management and the straightforward way they communicate with investors; no sugar coating, just tell it the way it is. I always get the feeling they're under promising and will over deliver.
I HOLD (in my coffee can)
Vertu Motors (LON:VTU)
Cinch must be getting close to 10% now.
Vertu Motors (LON:VTU)
Good spot Yiannos1.
Looks like Cinch have bought another 10.4m shares today.
Sorry but where do you get that info? I see an RNS from yesterday morning but nothing from today.
hi Bouden54
I checked todays trades on Sharepad. There are three standout buy trades each around 3.5m shares at 85p and 85.1p.
Don't think you need to be a genius to work out the likely buyer.
I guess an RNS is likely to follow tomorrow.
Snazzy
Cheers Snazzy, useful to know.
A number of shares in my portfolio showed moves to the upside only for those gains to be eradicated in the last week or so. The frustration with this market seems never ending.
Yes some have fallen back but November, is probably my best month, for my UK shares, this year. Currently up 6%. I have been selling a few that have recovered or look peaky. Have taken some profits on Ashtead Technology Holdings (LON:AT.) today. There is just not enough demand at the moment to drive the market upwards, until that returns, I can see it continuing, as people take profits. A lot shares have been going up and such Card Factory (LON:CARD). Maybe a Christmas rally?
Yep, seems like lots of instis selling down still before year end. Hopefully a rally in next couple of weeks.
Re ME International (LON:MEGP) photo booths, as more biometric/3D is implemented into passport security, it seems quite likely to me that photos taken by any other means will be viewed as technically inadequate. Presumably a big plus for ME International (LON:MEGP) if any country does this.
Indeed. given how (surprisingly)easy the Photo - me UK process now is( I had my passport within 4 days, the day after they received my old passport.) i am amazed HMPO are accepting photos from any other source.
Yet they have gone away from photos booths, you can use a phone or iPad or tablet. I'm surprised they accepted my ipad one but they did. Why pay for photobooth images when you can just do a selfie for nothing?
While there are undoubtedly some risks on the photography side of the business (although we'll always need ID) , for me the investment case is far stronger in the laundry space, which in their interims contributed nearly £38m in revenue with 37% revenue growth. Looking at the basics:
1. We all need clean pants.
2. Properties are getting smaller meaning people might not be able to fit their own machines in smaller living spaces.
3. The cost of running your own washing machine/dryer are going up.
4. Commercial property rates are falling, and likely to continue to do so, so new site lease costs will be advantageous.
I cannot for the life of me see any of the above facts changing in the forseeable, and it was good to see the beat on numbers of units rolled out.
I am not a fan of the Food side - I just don't get it trying to peddle fresh food/drinks from a machine, but given the lack of contribution here I am prepared to ignore.
Photography is clearly still a key part of the group and given their continued/extensive R&D here, and new machine rollout, the company clearly feel there is plenty of long term opportunity.
All in I see a very solid business with 2 critical divisions, both of which are performing well and by their nature are very cash generative. I'm happy to hold and long term, I see huge potential here. Might not become a multi-bagger, but it has many of the characteristics.
Thanks for your response. I do hold ME International (LON:MEGP) I tried to top up today, but could not get the right price, maybe tomorrow. Re photos I think, they could get more demanding for passports, in the future. The new passports, the image is not very clear, probably why the readers can't read them at airports, as I found out.
Washing machines, I feel is rather niche. They are large, 18 kgs, unless they have smaller ones now? The nearest one to me is about 8 miles away, so not practical. I would only use it, if I had something bulky to wash, such as duvets.
Cost is £8? Tumble drier is the same? That is pretty expensive.
Re Plexus
My experience in the offshore industry is over 20 years ago with mainly pipe jointing systems so I won’t profess to be an expert about Plexus in 2023. I do know that the industry was very risk averse and didn’t adopt new products and procedures without some considerable thought.
I read through the Plexus press announcement and my initial thoughts were that it was possibly a piece to help win over investors when more funding is required. There might be some genuine growth prospects here but there are far too many variables for me to evaluate. In my view this is one to risk money that you can afford to lose.
Copied from my post on another thread yesterday ….Just an idea …with predictive text mess up included :/
Most of which…..I have no idea when Maoist came from
2Reply
PennyledgesJoined 2017 28 postsYesterday 11:26 am
Useful article ….I have had just a few multibaggers (Maoist of which came back down to earth with a a bang) but they were picked up from ideas and comments from subscribers rather than digging through endless lists.
Would it be possible to have a ‘ Subscriber’s Potential Rocket Launch List’…….where great ideas are put out there (NOT TO RAMP) so that we can all do our own checks and research and maybe have a dabble if inspired……That’s how I got into EEE at 2.5p not that long ago….Without a comment from someone I wouldn’t have even heard of the company
Augmentum Fintech (LON:AUGM) Interesting presentation this morning following interim results. Some time spent on explaining how valuations are reached at. The fund trades at a significant discount to NAV of £1.60p. If you want exposure to the unlisted Fintech market it looks good value for both NAV growth and hopefully a narrowing of the discount. I Hold. https://presentations.investor...
Thanks for posting that Charles. Don’t know whether you saw it but I posted about Augmentum Fintech (LON:AUGM) on Tuesday immediately after their positive results. I’ve pasted it below this.
There were some useful replies too, including infuriation at the likes of Hargreaves putting unnecessary hurdles and warnings about Investment Trusts, when most of them are far less risky than single shares. And as KevinS1 replied, there were no such warnings from Hargreaves about now disgraced Neil Woodford and his disastrous open ended fund that Hargreaves continued to promote to the bitter end!
Here’s the post that started that thread on the Small Cap bb on Tuesday:-
“I bought Augmentum Fintech (LON:AUGM) at 89p today after their very encouraging results.
https://www.stockopedia.com/sh...
Since IPO in 2018 AUGM has had an unbroken run of NAV increases, though the latest increase to 160p is small. Yet the share price has gone from the biggest premium of any Investment Trust at one point to a now big 41% discount! And if stripping out the £58 million cash the Discount is 51%. So while NAV has gone up consistently the share price has gone down consistently.
Note that AUGM have £58 million in cash and no debt. Their top 3 holdings, TIDE, GROVER and ZOPA and the cash are above the current AUGM market cap, with no value at all attributed to their £125 million of other investments.
So far AUGM have had 5 realisations since IPO and all were above the holding value.
They have been buying back shares to try and reduce the discount. They can’t issue new shares while AUGM is at a discount but the bought back shares will be held in treasury to potentially be reissued if AUGM goes to a premium again. NO chance of that for a good while but very good chance of the discount narrowing from current undeserved extreme level.
This is yet another example of Investment Trusts being SO out of favour with discounts at near record levels. The tide will turn at some point, and AUGM looks yet another oversold Investment Trust worth checking out.
28
Redacted.
A tentative (I think) first post here then… first all of thank you to you Paul, Graham, Roland and everyone that contributes here. It’s saved me from myself on many occasions! I actually came across an old email the other day, referring to something called SmallCapValue.co.uk! How times flies!
Regarding Plexus Holdings (LON:POS) , (I do not hold), I can offer some (bear) points:
My background is spending most of my working life in the oil and gas industry, though not as a piping / mechanical engineer. Reading the Plexus announcement and the general information available on their website, it would sound as if most wellheads in the world leak, but this is not the case. There are also many other leak sources around the wellhead that need to be accounted for, including the first piping connection (flanged) and other downstream piping, valves, instrumentation, etc. All can be considered leak sources and when they do leak, generally fire and gas detection systems will alert that event and typically, automatically shutdown (and blowdown) production. This of course represents a cost to the production company, but it is not a daily or even monthly occurrence. Furthermore, I doubt the cost involved justifies the expense of a wellhead replacement program and associated downtime costs, even if fines are to be paid. I haven’t done any calculations to justify this statement, but I do really doubt the economics here. A new build project could be a different story, but then again, fire and gas detections systems will in any case be required, no-one will sign off on a “guaranteed” doesn’t leak wellhead, of that I am sure. I guess Plexus also do not assume any liability in this respect.
I don’t really buy the argument that early focus was on oil, rather than gas production. It was, but gas was always an associated by-product of oil production and designs were appropriate to keeping it contained. Typically, it was flared, but now is utilized. Even in those early days some fields, typically Southern North Sea, Morecambe Bay were and still are gas production fields, they were always so.
Yes, there are strict, and becoming stricter limits on emissions, but there are plenty of sources other than wellheads to address, that I would suggest are higher priority, e.g. storage tanks, flares, exhausts, etc.
Plug and abandonment of wells generally (simplistically) involves recovering what you can from the well bore, filling with concrete and capping. I don’t see any need of Plexus specialist technology in this case.
Certainly, they have a useful product and interesting technology, but no golden bullet, IMHO.
Good luck to holders!
Regards, Jon
Very useful thank you.
That's interesting thanks.
Schlumberger has licensed Plexus's tech, and is preparing to launch (globally) a range of low cost wellheads & other products which incorporate Plexus's patented POS-GRIP technology. They wouldn't be bothering to do this, unless they saw a substantial market for wellheads that are leak-proof for the life of the well. As opposed to existing technology, which can develop leaks after years of operation.
Also plug & abandonment - Plexus is winning contracts for this work, so again, there clearly is a market for its products & services. This year, Plexus won its largest ever contract for £5m, expanding to £8m, just for 1 years' rental of equipment.
As regards the North Sea, there are plenty of Plexus wellheads in operation, so it's established tech. If you look back to pre-2015, Plexus was growing, making profits (peaked at about £6m), and the market cap peaked at about £300m. Then the price of oil crashed, and new drilling dried up, so demand fell away. Demand is coming back now, as energy security and methane leaks are driving demand. This is why Plexus is forecast to move back into a (small) profit this year. So I don't think we can just dismiss all of these bullish factors.
Regards, Paul.
Won't that North Sea demand dry up if Labour get elected? Maybe there is a rush before that happens?
To be honest, I would have thought that what happens at sea stays at sea.
Hi Paul
Plexus Holdings (LON:POS) sold off the largest part of their business long after the glory days of £6m profit/ £300m m/cap
RNS was in February 2018 https://polaris.brighterir.com...
it’s also 3 years ago almost exactly since they announced their last licensing agreement with Cameron/Schlumberger
https://polaris.brighterir.com...
Obviously this didn’t lead to anything significant by way of profits…hopefully the latest licensing deal is more successful
Best of luck anyhow
A 3-year non-compete agreement has expired, and Plexus has re-entered the business they sold off.
Lots of research needed on this one!
Morning Paul
it’ll be fascinating to see how they manage to fund the new equipment they’ll require to re-enter the jack up business…that represented over 90% of revenue back in the glory days
Hi Paul,
Thank you. All that you say is true, I guess my main point is that Plexus Holdings (LON:POS) are not the only player in town. Granted the only player claiming leak free, but this alone isn't such a driver of demand in my view. Other wellheads while not guaranteed leak free, don't leak on a regular basis. You cannot operate with leaking equipment, just cannot.
Certainly the Schlumberger tie up helps. Often, despite technical preferences of engineers, final choice comes down to cost. If I am assessing 3 different wellhead offers on a technical basis and all meet the technical requirements, then the cheapest offer will be selected, even if one offer has some technical advantage (this process applies throughout all disciplines when assessing equipment).
I sincerely hope it works out well for you and all holders.
Regards, Jon
Plexus pos grip technology is the entire solution.
Let me explain with a simple analogy. Your kitchen cupboards and drawers get loads of wear and tear so the screws, etc., come lose. This is what happens with conventional equipment used by oil and gas companies hence methane emissions, greenhouse gases. Conventional equipment needs loads of maintenance shutdowns to overcome these problems.
With plexus pos grip technology this doesn't happen at all. Pos Grip technology equipment doesn't need any maintenance at all.
So, all oil and gas companies need to be using Plexus pos grip technology.
Plus, Plexus are back in the Jack up business with help from SLB, Schlumberger.
The link to the plexus holdings website page is to help you understand their pos grip technology.
Here it is:- https://www.plexusplc.com
Paul/Roland just to alert you to another delisting that has just been annouced. Quarto (LON:QRT) . Bad news for shareholders with the shares dropping by 1/3 and a further kick in the nether regions for UK small cap investors.
Quarto (LON:QRT) has had a consistently high stock rank for a long time, but one investor holds over 50% and this is the result, they do what they want.
After seeing people getting caught out earlier this year (was it IBPO?), the major shareholder list is one of my pre-buy checks.
Such an important check. I was caught by iEnergizer (LON:IBPO^E23) so learned this the hard way. Bizarrely IBPOs delisting may have saved me money, as I then checked all holdings and sold out of a much larger position in Quarto (LON:QRT) before the price tanked. Interesting Quarto seem to be offering a post delisting tender - likely little use to many small shareholders, given many platforms dont seem to allow you to continue to hold post delisting (or at least mine doesn't and forces a sale).
Initial gut reaction possibly misplaced. They intend to make a tender offer at 150p per share sufficient to take out all the independent shareholders. The tender offer is not guaranteed to take place so you have to trust them to do it, but the market seems to be thinking it will happen, as the price has now edged up. (I have added modestly to my original small holding.)
Hi Paul,
Firstly thanks for all the great work that you and the team do. I've always listened to your podcast right from episode 1 and find it informative and entertaining.
Thanks for the right up on Plexus Holdings (LON:POS) . I read the FY results per my comments yesterday. I have just watched from the sidelines since you first mentioned them in your podcast back in August (I think). I must say that it does appear to be a really exciting opportunity but I can't understand the rationale to make this the largest holding in a portfolio. It could either be a big win or potentially lose it all. As you say very high risk / reward. I do hope that anyone who has invested has written their investment off in their minds and are OK with that.
I think there are a few more points to consider -
1. General election next year with a change in government looking very likely / certainty. What will they do to our North Sea O&G industry and how would that impact Plexus Holdings (LON:POS)
2. The convertible bond loan is due to be repaid in October next year. This either has to be paid in cash or in shares at a 20% discount. If its shares there will be an obvious dilution but who knows how much as it will depend on the share price at the time. If the share price is back with a market cap of £2m it would nearly be a 50% dilution. If its cash I don't see where that would come from. Cavendish forecast net debt of £0.4m at the end of FY24 up from net debt of £0.3m at the end of FY23.
3. There is no forecast from Cavendish for FY25 reflecting the payment of point 2 above, but why hasn't the company put any forecast together for FY25 which starts in just seven months time.
4. 5 months in to FY24 and no comment of substance as to how FY24 is trading to date. Surely there would have been some of the $8m contract traded, what are the terms?
5. The Gross Margin of 60% for 2024 equates to £4.3m of costs. Assuming the inventory of £2.2m on the balance sheet is all associated with FY sales then they need to spend another £2m for COGS and currently only have £1.5m in cash in addition to owing £4m to their suppliers. As you say it's very likely they will run out of cash but we don't know the payment profile from the £8m contract.
6. So far its just a story with very little reflected in the Financials.
Not sure if I have all my facts 100% correct but please do feel free to correct any errors or make comments.
If I invest it's likely to be just from dividends that I don't mind losing if the story doesn't come true.
Cheers Andy
re Andy's Plexus Holdings (LON:POS) comments...
Cheers Andy ... and congrats to Paul on a great purchase. Obviously the question for us mortals who have watched from the side lines is what to do now... I have just reread the convertible announcement. It makes a little more sense now... I had thought that since the 4p and 8p conditions were met, what would stop the conversion happening any time ? The answer is of course who would convert into a fund raise. The conversion itself doesn't raise any funds ( I think) just a net issue of shares. These shares will be a 20% discount to the fund raise level.
The loan I am ignoring since I assume that the sale of KMS "should" neutralise this. So we have £1.55m convertible. Assuming a 20% discount on the current mat cap at 19.5p the conversion is 10% dilutive. Not the type of thing to put anyone off investing I would argue. So how much money does Plexus Holdings (LON:POS) need?
The contract win will get them a profitable and cash flow positive outcome to 2024. They don't really talk about how many well heads they need to commission in their statement. Nor do they really talk too much about pipeline (order book) activity. The conclusion I think is that they are "hoping" SLB are successful in the US fracking market...which opens the door for the company, prospect wise. Obvs I could be wrong on this. But it does make it pretty hard to forecast what sort of fundraise the business needs. If you are going to do one...It might as well be comprehensive.... let's say £5m ? that would be enough see them through the next couple of years ....and a decent punt? £5m is 25% dilutive at the current market cap.
They just managed a fund raise at 19.97p so there would appear to be demand ... but an open offer needs to be assured of getting through. Why? well if you do a £5m open offer at 19p.... and sellers get the price below 19... it fails... and you have an awful situation where the convertible can't convert but represents an overhang. lets say 10p is a no brainer.... could they do it at 15P maybe, the shares have traded 30p recently. £5m at 15p.... is 33m new shares. Then you convert £1.55m at 12p....is 13m shares give or take. So that's 46m new shares.
Now you have a problem, unless my maths is nonsense. What's the problem...existing market cap £20m....divided by 146m shares = 14p. So the open offer doesn't work because you have to pay more than the X entitlement price. The discount needs to be larger...at 12p it works....just.... £5m at 12p = 42m new shares plus £1.55m at 9.6p = 16m .... 58m new shares .... £20m market cap over 158m shares is 12.6p ... a premium to the 12p offer.
Please forgive me if my maths is wrong. £5m is just a wild stab finger in the air job anyway...but it does indicate that the convertible and fund raise is potentially tricky. I must be missing something but I want to wait to get this out of the way... however my risk is they can extend the existing £8m contract further and need substantially less money ... and I thus miss out. 10-15% dilution looks optimistic to me.... but what do I know?
PS the deadline for this is Oct 24 ... the 2 year anniversary of the convertible issue.
I have a tiny holding in Plexus Holdings (LON:POS) as bit of fun. For me investment case rests on the big $8m order. Will this be repeated on a consistent basis ? If so then shares should do well as operational gearing significant. The Schlumberger licensing deal seems to only provide small fees at moment so not game changer. Slightly frustrating thing is we don't know much about who big order is from and what it's really for so it's hard to work out if we can expect more such big orders.
I understand that Paul invested in this company in the past (according to Stockopedia write ups history) and lost money. He was a holder after a nasty profit warning so I assume that he did lose money.
There will be 100% a big dilution here next year as the balance sheet is just simply terrible.
What I don’t quite understand is that many readers (including myself) have many times asked coverage about companies involved in the oil&gas sector and Paul has many times replied that he is not familiar or expert in the field.
Also after extensive research I have realised that there are many big US companies involved in this kind of business. I have also read and analysed Cavendish report as and it is clear that will not be making any money next year.
Although this one is not for me to touch or follow (as I do not buy the whole story) I do wish all holders good luck.
I did make a comment early on this morning then scrubbed it but it was along these lines yiannos. Dilutions have cost me thousands over time and Plexus Holdings (LON:POS) scares me. Neverthe less I plumped for Empire Metals (LON:EEE) yesterday.
Hi Roland, thanks for your review of Ashtead Technology Holdings (LON:AT.)
this is cribbed from a well known bulletin board, this is apparently from broker Numis " ... we upgrade our FY23E EPS by 3%, FY24E EPS by 25% and FY25E EPS by 28% ...”
“ On our upgraded forecasts, the shares trade on a FY24E EV/EBIT of 9.8x and a P/E of 13.3x”
Target price raised from 475p to 618p.
Ashtead Technology Holdings (LON:AT.) from broker Numis " ... we upgrade our FY23E EPS by 3%, FY24E EPS by 25% and FY25E EPS by 28% ...”
Gosh. Better than I had expected even if already foreshadowed by the SP jump. How cyclical is this business going to prove? That's the question because performance has been great - but is it all coming in a quick lump before a prolonged slump? Frankly I don't know, But if it follows the feast or famine pattern of O&G then it could be a bumpy ride for long termers like me.
Thanks for sharing, Helvellyn.
Future (LON:FUTR) big drop this morning on seemingly no news - suggestions that it might be a broker downgrade but haven't seen anything on this yet.
yes i couldnt see any broker notes anywhere. must be a tree shake. im still holding as bought lower down
Future Plc drops as much as 6.8% after Canaccord Genuity downgrades the media company to sell from hold, saying there is material risk of downgrades to consensus. It is the stock’s only negative analyst rating.
Analyst Karl Burns writes that consensus estimates appear to be very optimistic, expecting group revenue growth and flat Ebitda margins despite a deteriorating macro environment and structural pressures
Notes that updates from peers have been fairly weak, and that global advertisers and retailers have reported weakness in consumer electronics, which is Future’s main revenue category
Sits 15% below consensus on FY24 pretax, with downside risk to own numbers
PT cut to 758p vs 827p pence, implies a 21% decrease from Wednesday’s close; stock now has 8 buys, 1 hold and 1 sell among analysts tracked by Bloomberg
Dr Martens (LON:DOCS) has now hit scvr territory!! Another crazy PE float at ridiculous valuation at the time, another profit warning today (is that the 3rd or more now. They do come in 3s)
Would think this is a likely takeover candidate at these levels perhaps?
They interviewed me for a middle/senior management job a few years ago. It was a shit show, literally couldn't organise a piss up in a brewery! Ended up being 6 interviews over about 4 months for various reasons to not make a decision!
Hi topturkey,
I've added Dr Martens (LON:DOCS) to the agenda for a quick look, given the size of today's fall.
Roland
Wilson bought £400k worth in July at 129p. We'll under water Dr Martens (LON:DOCS)
Floated in 2021, I see. If memory serves, this makes it another in a disturbingly long enough list of companies floated around 2021 which have since exploded. I reiterate my general rule to only buy shares when they've been on the market for at least 7 years. A lot of pain is avoided that way. The only exceptions I make are for government floats and spin-offs. 400p to 85p is pretty manky. It seems that most brokers just lob a share into the market and run for cover these days.
Think it got to c600p and a £6bn valuation!!! Tried to short a few times but couldn't get stock at the time.
Both Buffet and Munger (RIP) have said private equity is basically a fraud.
I haven't properly looked at results yet but worth checking out how inventories are doing.
To be fair I think this is exactly the type of product which surely must struggle in a cost of living crisis. So in the next bull market it might do well and worth monitoring until then. But there's also a question about management competence given they opened 25 stores recently despite flatlining, and now declining, sales. Now is the time to consolidate and get the US division back in order surely.
Edited out.
here are the top 10 using a momentum view I created in the “Browse” section of Stockopedia - easy to do, and very useful!
Paul, that’s an interesting screen, what are your rules or can you share the screen?
Hi Neil,
No need to create a new screen.
Choose Browse - Indices from the left menu, click on AXX then choose the Momentum table view.
You can then sort the results by whichever column you like eg. Price Change % 1y.
Tough update out of Wynnstay (LON:WYN) today. I hold and will continue to hold. It's disappointing, but this is an agricultural holding. I would like to have seen clear guidance. For PI's who don't have access to house brokers, and I am one, this should be a prerequisite.
Hi GreyInvestor,
I've just published an update on Wynnstay (LON:WYN) including updated earnings forecasts from the house broker.
Roland
A good update, thank you
I'm amazed at how fast you were with this report, including the valuable house broker forecast. I really value this feedback.
One day I'll ask you to do the same with TP Icap (LON:TCAP) , my largest individual shareholding.
Yes, a disappointing update at Wynnstay (LON:WYN). A guidance range would have been useful. Dividend cover was about 2, so dividend record should not be broken. It might be a good top up in the next 6 months. I am a holder. Volumes and prices are always volatile. They previously exceeded expectations, but now its under shot. Quite rare to have a warning, but maybe that's what a very wet October causes. General trend is up, but its definitely not a straight line!
Do Wynnstay (LON:WYN) still sell bulk fuels? As the cold end to November will be a boost there.
I know from friends they were praying for two weeks dry weather to finish the autumn preparation and planting, and did not get it, so a lot going to be now rotated into spring, and looking at the fields that were planted, there are some big brown patches where the floods are receding, they will not be replanted, but not great for next years harvest quantities for those who produce their own feeds on farm.
Potential read across to NWF (LON:NWF) as that is also engaged in the manufacture and sale of animal feeds and other agricultural products?
For me, I'm probably going to dump that puppy come ISA top-up season. The share has gone nowhere in a decade.
Wynnstay (LON:WYN) Trading update
"The trading environment in the second half of the financial year was more difficult than the first, with lower farm-gate prices adversely affecting farmer spending patterns. In addition, the seasonally critical final quarter has been impacted by abnormally wet weather. As a result, the Group's results for the financial year are now expected to be below current market expectations."
No figures given.
Solid update from ME International (LON:MEGP. Long and strong for me.
Solid but market not liking thus far
Maybe it will do a Volex (LON:VLX) which fell initially around 6% but ended up on the day around 6%?
I hope so!! Can't see it though. Looks like someone selling down/out lots of fairly large sells happening last couple of weeks
ME International (LON:MEGP) Overall looks good to me. The slight miss on revenue growth is the question. Historically H2 has been quite a bit better than H1 (presumably passport photo driven) but the difference this year is much smaller (£154m v £144m).
H2 PBT is 39.8 so significantly higher sequentially v 27.2 and v H2 last year 33.4. So that's good.
Is the photo booth business reaching peak revenue? And can the other areas takeover the growth if it is?
I am comfortable continuing to hold at a PE of 10.
Hello Robert,
Good point regarding photo business reaching it's peak. It's possible it has.
Cash pile has increased which is very positive.
On a PE of 10 though, hold for now.
ME International (LON:MEGP) Applied for a new passport last week. The whole Photo-Me process is much improved cf 10 years ago with (1) payment right at the end, (2) auto-checking the photo meets HMPO requirements, and, (3) the photo being sent to HMPO, linked idpass provided.
Well worth the £10 IMHO not to have the hassle of sending in unvetted photos.
Last time I did a passport photo my wife took it on my phone, me standing against a blank, whitish wall at home. It then got processed and assessed automatiically online by the passport office, I got told to retake it, which I did following instructions, submitted it and it worked fine. No hassle of finding a Photo Me site or paying £10. I can't see the Photo Me part of ME International (LON:MEGP) having much in the way of a moat, or secure business model.
Absolutely agree with that. Certainly I've got no plans to invest. Bit like investing in Royal Mail (or International Thingummy now)
peterg
You make a good point; I have no idea how much business ME International (LON:MEGP) is currently losing to mobile phone photos. It's probably a very considerable amount
AIUI, new standards, being gradually phased in from 01-Jan-25, are defined here...
https://www.icao.int/publicati...
So maybe mobile phones will cease to cut the mustard at some point?
The mobile issue is just the UK, as far as I know. They have a lot of booths in France and JapanI will try to find a breakdown of the revenues. Not everyone will want to do mobile phone images, many get rejected.
ME International (LON:MEGP)
Recently bought some on the basis that they fit my criteria of having a relatively low P/E, good ROCE, decent dividends, good cash generation as well as doing share buy backs. The drawbacks are fairly well known with issues over photo booths being a bit retro in the age of the selfie . They are upgrading the technology of photo booths, but sadly does not include the necessary plastic surgery required to make me look presentable!
Alongside a revenue miss ME International (LON:MEGP) I think a key downside was the 'operational challenges' in the Feed.me division, that appears to have required a remedial reorganisation.
Management called out their accelerated growth investment in Feed.me in the July interims but it seems the business hasn't grown as management had hoped.
I wonder if the enthusiasm for new and updated passports post Covid gave a boost to ME International (LON:MEGP) that is hard to maintain? [I hold]
A nice mention for Ed and the gang in this morning’s Times.
Surprising lessons for the vanishing art of stockpicking
https://www.thetimes.co.uk/art...
Stocko marketing director earns his bonus ;-)
@ grumpy5 - that was completely organic! Obviously, we're delighted. Thanks for sharing, Ox.
https://www.voxmarkets.co.uk/r...
An another acquisition for Ashtead Technology Holdings (LON:AT.) and also a trading update saying that they expect FY23 to be “comfortably ahead” of previous expectations.
Hi Helvellyn - I'm going to look at Ashtead Technology Holdings (LON:AT.) next this morning!
Roland