Small Cap Value Report (Thu 31 Jan 2019) - STAF, BOTB, SOS, BLV, FOXT, FLO, FA., SCS, CTO

Good morning, it's Paul here!
Cloudcall (LON:CALL)
As promised, here are the videos from the Cloudcall (LON:CALL) (in which I hold a long position) Capital Markets Day, which I reported on here, on 22 Jan 2019. Clicking on the links below will take you directly to the videos, on Vimeo.
Staffline (LON:STAF)
(suspended at 670p)
Not another accounting scandal?
What on earth was AIM thinking of, allowing Staffline shares to continue trading yesterday, after a bombshell announcement at 7am that results would be delayed? Investors understandably started panic selling, and the shares dropped by about a third. Only at 3:50pm were the shares suspended. This is madness/incompetence.
With some sort of accounting problems probably having emerged (why else would results be delayed?) then shares cannot be allowed to trade, as it's a false market. People don't know what's going on, hence the shares have to be suspended.
The company update given at 6:14pm yesterday says very little. Key bits;
... concerns were brought to the attention of the Board relating to invoicing and payroll practices within the Recruitment division.
Given the nature of the allegations, the preliminary results will not be published until the matters have been fully investigated.
The Board is confident that its policies in relation to these matters are appropriate, particularly given that these practices have been the subject of prior audits.
However, if the allegations are substantiated this could have a material impact on the Group and its profitability and until further investigation has been undertaken the Board cannot assess the potential materiality.
Materiality is usually defined as 10% of profits. So it looks as if the problems, if genuine, could be at least 10% of profits.
There doesn't appear to be any cash impact, as far as we know;
Other than that noted above, the financial position of the Company is unchanged, as reported on 8 January the Company expects to report net debt of c£63m for the year ended 31 December 2018 and can also report that in July 2018 the Company refinanced its £150m lending facilities.
My opinion - this sounds as if sales & hence receivables might have been overstated in some way? Hopefully that shouldn't have any cash impact - so probably not another Patisserie Valerie, but we don't have enough to go on at the moment to be sure.
We'll just have to wait for more information from the company.
Surely the time has come for a comprehensive overhaul of corporate governance? We seem to be getting numerous problems emerging at companies - often not long after floating, and/or when founders have disappeared into the sunset with a large bag of swag.
Investors have lost £billions in recent years, with accounting scandals - e.g. Quindell, Globo, Patisserie Valerie, and of course numerous Chinese frauds, and junior resource sector semi-frauds. This is bound to affect investor confidence. Yet so few of the people perpetrating such accounting scandals ever seem to be punished - and certainly not in a timely manner. No wonder accounting scandals are proliferating. You do start to wonder, is anything safe?
Best Of The Best (LON:BOTB)
(in which I hold a long position)
Tender offer - I'm not terribly au fait with tender offers, as they rarely happen in my portfolio. I understand the basic principle - it's a share buyback, but offered to all shareholders simultaneously, for the same percentage of their holdings. Take up is optional.
Management at BOTB are very open, so I asked for a quick update, to answer my basic questions. I recorded the call (with permission of course), and published it here, in a 10-minute audio. I left the blooper in, as it might amuse people - after all, shares don't have to be deathly serious all the time!
Sosandar (LON:SOS)
(in which I hold a long position)
Your questions please for CEO/CFO interview
My next audio interview will be with Julie Lavington (CEO) & James Bowling (CFO) of this small fashion eCommerce brand. As mentioned before, this is my largest position in the market, and I foresee a very exciting long-term future for the company, due to;
- Bespoke product styling & fit, to suit an overlooked gap in the market
- High levels of repeat business - indicating customer loyalty is building fast - lifetime value of customers should be very high
- Extremely rapid growth (albeit from a low base)
- High gross margins & rapid full-price sell through (indicating that the product is in demand, and allowing inventories to be kept low)
- Scaleable, out-sourced business model, using the successful "test & repeat" model pioneered by BooHoo
- Funded to breakeven
- Above all, this is all about backing experienced & highly capable management.
However, both brokers used by the company (originally Turner Pope, and now Shore Capital) produce research, but don't seem to want anyone outside the City to read it, which is ridiculous. Therefore, many private investors don't understand the business very well. This is evidenced by numerous bulletin board posts which are often factually incorrect, and display little to no understanding of the business.
There also seems to be a malicious element who are anti- Adam Reynolds, who reversed Sosandar into a cash shell originally. I had lunch with Adam recently, and found him to be charming, and very clever/experienced. Nobody is obliged to buy any of his companies' shares, and Sosandar is the only one from that stable which currently interests me.
Anyway, please either leave questions for SOS management in the comments below, or email them to me at QSCquestions at gmail DOT com . Deadline - midnight this Saturday.
Incidentally, I don't have a strong view on the current share price, as the business is still quite early stage. So it's currently worth whatever people are prepared to pay for the shares. Some people think it's expensive (as it's small & loss-making). Other people (e.g. me) think it's longer term potential could be a serious multi-bagger, so I see it as cheap.
My investing time horizons are much longer than for most people. I fully understand that most investors are happy to wait until the company is nearer to, or has passed through breakeven, before investing. That's fine, but of course you would then have to probably pay a lot more for the shares.
In the meantime, I thought it would be useful to help inform private investors about the company & its business model, and of course debate its pros & cons.
Here's the link again to an excellent, fairly recent investor presentation done by Sosandar.
Belvoir Lettings (LON:BLV)
Share price: 92.5p (up 2.2% today, at 11:28)
No. shares: 34.9m
Market cap: £32.3m
Belvoir Lettings PLC (AIM: BLV), the UK's largest property franchise, today provides the following update on the outcome of the financial year ended 31 December 2018 and the outlook for 2019.
Today's update reads well. I'll summarise the key points;
- Acquisitions have helped drive growth, but good organic growth too
- 2018 results in line with market expectations
- Dividends will be increased further (very high forecast yield of c.8%)
- Franchise model & strong bias towards lettings, has insulated Belvoir from downturn in property market
- Govt ban on tenants fees - from 1 June 2019 - has been mitigated. Initially 6% reduction in gross profit, dropping to 3% (previous guidance was 8%)
Outlook - vague, but upbeat;
The Board believes that Belvoir is well-prepared to both meet the challenges and take advantage of the opportunities anticipated in 2019."
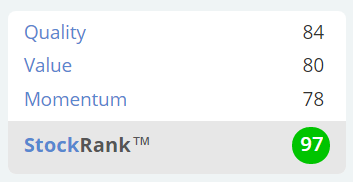
My opinion - this share looks great value, especially the excellent dividend yield. The market has priced the share as if earnings and hence dividend yield are under threat, but that seems misplaced negativity. Therefore I think this share looks worthy of a closer look.
Stockopedia's computers like it too, which is encouraging, as overall that should improve the chances of picking a winner, if used on a whole portfolio;
Foxtons (LON:FOXT)
Share price: 52.6p (down 1.7% today, at 12:33)
No. shares: 275.1m
Market cap: £144.7m
Foxtons Group plc (LSE: FOXT) (the "Group"), London's leading estate agency, issues its trading update for the year ended 31 December 2018 ahead of its preliminary results on 28 February 2019.
(I can't seem to get rid of the bolding, sorry - it was like that in the RNS)
- Lettings business has been resilient, a bit like (on a smaller scale) above, with Belvoir
- Writing off £16m, mainly goodwill, but also £3m cash cost of branch closures
- Branch closures will deliver £3m of cost savings in 2019
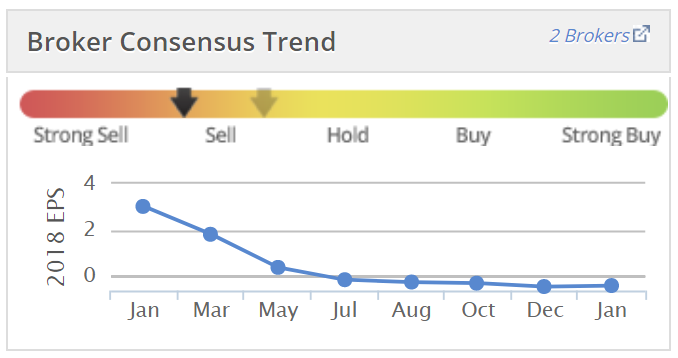
2018 performance in line with management expectations. Although note from the Stockopedia broker consensus graph, that expectations have been considerably reduced over the last year.
Big fall in profitability versus last year;
Adjusted EBITDA(1) for the year is expected to be approximately £3m (2017: £15m). The reduction in Adjusted EBITDA compared to the prior year was driven mainly by the fall in sales volumes alongside planned increases in operating expenses as we invested in our people, technology and brand.
Those are very badly timed increases in opex. You would think that Foxtons would know, and be able to predict, the London property market, but clearly it can't.
Cashflow & balance sheet - today the company says;
Cash flow was good in the period, supporting a strong balance sheet with no debt. Year end cash was circa £17m (2017: £19m).
Checking back through my historic notes, I last looked at the balance sheet here in Nov 2018, finding it adequate - low risk of insolvency.
My opinion - the sales side of the business is really struggling, and has been for a while, so that's not news. Lettings is doing OK. Overall then the business looks to be resilient enough to survive, and to do better when the sales market improves. Cost-cutting in the meantime looks to be a sensible move.
This share is therefore a straightforward bet on the London property market improving in due course.
Flowtech Fluidpower (LON:FLO)
Share price: 117.75p (down 2.5% today, at 13:34)
No. shares: 60.9m
Market cap: £71.7m
AIM listed specialist technical fluid power products supplierFlowtech Fluidpower (LSE: symbol FLO), is pleased to announce the following unaudited update on its performance for the year ended 31 December 2018 and to the period up to this announcement
- Strong revenue growth - up 42% to £111.1m, although only 6% of this growth is organic, the rest from acquisitions
- Gross margins in line with prior periods
- Underlying profit before tax for 2018 expected to be £10.6m to £10.8m
- Debtor days seems a bit high, at 75 days (I prefer 60 days or less)
- Sounds like Q4 might have been boosted by customers stockpiling on Brexit worries maybe?
- Acquisitions from March 2018 are performing in line
- Final dividend will be raised 5% on prior year, which looks in line with forecast
Outlook - self-explanatory;
Within the fluid power market sentiment generally remains positive, and this is reflected in the order book for our PMC division businesses which provides some insight on Q1 2019. The Board is therefore expecting a solid start to 2019 on which we will report in April.
Beyond that our sector shares the general unease with the potential effects of Brexit, although with a strong element of Group revenues generated from repair and maintenance, and refurbishment programmes, coupled with a widely spread sector base of OEM customers, the Board believes the Group has developed a sensible defensive position.
Further progress has been made regarding the Thames Tideway project with work now likely to take place over a three-year period.
The new Executive Management team is fully focussed on extracting synergies and creating a strong platform for future organic and acquisitive growth. Therefore, the Board remains confident in both the strategy and long-term outlook for the Group.
Net debt - reported at £19.9m which doesn't seem excessive to me. It's supporting largish inventories & receivables, so you could regard it as being asset-backed.
My opinion - confident in long-term outlook, means somewhat hesitant in short to medium term outlook. Overall though, the above looks pretty reasonable, in the circumstances.
Here are the valuation figures, with favourable scores on PER & divi yield;
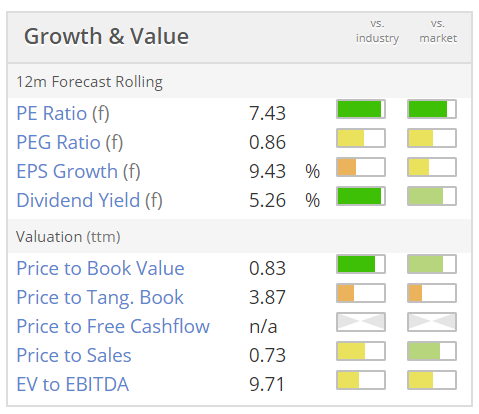
It's worth noting that, if you were to adjust out the debt, then the PER would rise to something nearer 10, so maybe not such a bargain? Also, I'm not keen on companies paying dividends which also have significant levels of net debt.
Overall then, to me it looks OK. I can't see any reason to rush out and buy this share now though, given all the macro uncertainty that pertains.
Fireangel Safety Technology (LON:FA.)
Share price: 30.0p (down 23% today, at 14:20)
No. shares: 45.9m
Market cap: £13.8m
Trading update (profit warning)
FireAngel (AIM: FA.), one of Europe's leading developers and suppliers of home safety products, announces a trading update ahead of the release of its audited final results for the year ended 31 December 2018
Profit warning - 2018 results;
... are expected to be below market expectations, specifically at the underlying operating loss level. The figures set out in this announcement are subject to audit.
Quantifying things (helpfully), it says today;
For the year ended 31 December 2018, sales are now expected to be approximately £37.6m (2017: £54.3m) and the underlying operating loss1 is expected to be approximately £2.0m (2017: underlying operating profit of £4.7m).
2018 was a year of significant disruption and distraction for the Company which has been well documented in previous announcements.
There's a note from Stockdale, available on Research Tree today, which shows that this is only a relatively small miss on the 2018 numbers. Just £0.4m lower on revenues, and £0.6m increased loss, compared with previous forecast.
About £1m profit has been shaved off 2019 forecasts too.
What's caused this latest profit warning?
Since release of the Company's trading update on 22 November 2018, sales remained broadly in line with market expectations. However, a warranty provision release which the Board had expected to make has been prudently retained based on current higher product costs, which are described in more detail below. Levels of product returns in 2018 were in line with the Board's expectations.
Net debt - this is the most worrying bit, in my view;
The Company has operated within its banking facilities throughout the year. Net debt at 31 December 2018 was £4.7m (31 December 2017: net cash of £3.3m).
The group has burned through a previously large cash pile, at an extraordinary rate, due to a catalogue of mishaps, and now has net debt. That's a big worry.
Outlook - production problems are ongoing, which increases the current cost or production.
The Board remains confident that its expectations for revenue growth are achievable. Gross margins and profitability are forecast to grow, but the impact of higher current product costs has led to a reduction in the overall level of profitability expected in 2019.
Both the Company and its primary manufacturing partner are focused on reducing production costs. In addition the Company is undertaking a range of other initiatives to improve profitability.
My opinion - it's been an unbelievable catalogue of woes from this company, in recent years. The unavoidable conclusion is that the root cause has been poor management.
I've had worries about this company's solvency for a while, and I consider it uninvestable for that reason. Why take the risk on a turnaround, at a badly managed company (historically anyway), which has burned through a huge cash pile, and is now in debt?
The upside case, is that if the company returns to decent profits, then the shares could multi-bag from here. The new, internet of things, fire safety products look interesting, and there have been some apparently good contract wins recently.
I wish the company luck, but it's not something I would want to gamble on. Let's hope the ticker is not an omen for the eventual shareholder value.
SCS (LON:SCS)
Share price: 228p (down 2.6% today, at market close)
No. shares: 40.0m
Market cap: £91.2m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update ahead of announcing its interim results for the 26 weeks ended 26 January 2019 on 19 March 2019.
Overall, trading has been OK;
The Group has traded in line with the Board's expectations in the first half of the financial year. Whilst we are mindful of the risk from the impending Brexit outcome, we believe the Group's increasing resilience puts the business in a strong position to manage the continued economic uncertainty and take advantage of opportunities.
LFL order intake - growth is still positive for H1, but has slowed down somewhat.
When I last reported on ScS, here on 25 Oct 2018, LFL order intake growth for the first 12 weeks of FY 07/2019 was up 4.5%
Today, the company is saying that LFL order intake growth for the first 26 weeks is up 1.5%. Thi suggests that the later 14 week period must have had flat, to slightly negative LFLs, to have brought down the overall 26 week average from +4.5% to +1.5%. Even so, it's still not a shabby performance, given macro headwinds & deteriorating consumer confidence.
House of Fraser concessions - have now all ceased trading, so we can forget about that issue.
Valuation - remains attractively low, as I've mentioned several times recently.
Low PER, high dividend yield, and a strong balance sheet stuffed with (customers') cash - is a very attractive combination.
My opinion - this sofa retailer has remained resilient in tough market conditions. The share looks attractive, providing we don't see a meltdown in consumer confidence.
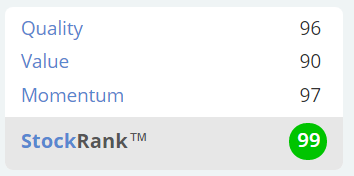
StockRank remains exceptionally good;
T Clarke (LON:CTO)
Share price: 97p (flat on the day)
No. shares: 42.9m
Market cap: £41.6m
TClarke plc ("TClarke" or the "Group"), the Building Services Group, announces a year end trading update for the financial year ended 31st December 2018.
It's an in line update;
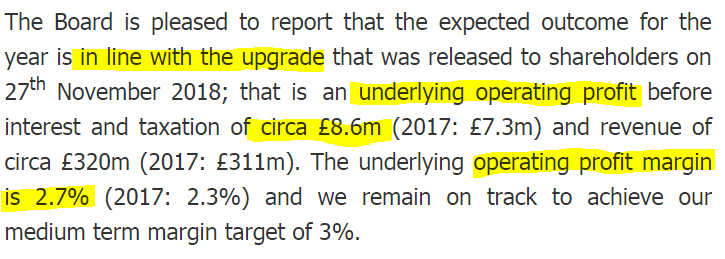
Year end cash is £12.4m
Order book - is up decently, standing at £411m (up 22% Y-on-Y
My opinion - it's good to see the company trading well, and having a good outlook.
I looked into this group quite closely a few years ago, and in the end decided it's not the sort of sector I would want to invest in going forwards. The margins are too low, and these are often large, complex contracts. So the risk of something going wrong, on low margin contracts, would worry me too much to want to hold this share.
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Thanks Paul. An excellent article as always.
In a previous article, I think it concerned Sosandar, you expressed the opinion along the lines that you were not worried about Brexit because the consequences of the UK leaving without a deal would be so horrendous that no UK Government would ever allow it.
I am holding onto the shares I have, including Sosandar, hoping for the best, but I also have a pot of money to invest when the picture is clearer after Brexit.
We are just three weeks to leaving and it looks increasingly likely that we will be leaving without a deal. What do you think investors should do?
Re Best Of The Best (LON:BOTB)
Exceptional accounts for the 9 months to January 31st have just been published:
https://beta.companieshouse.gov.uk/company/03755182/filing-history
YTD PAT = £3.5m, or £1.0m if excluding exceptional income from recent tax rulings.
The above figures are vs PAT expectations of £1.2m for the full year.
So either Q4 (Feb-April) performance is expected to be weak, or broker expectations are far too low.
For reference, my very rough-full-of-assumptions calculations imply that 50% of the announced annual marketing budget of £2.8m will be spent in Q4.
A
That's a good spot! I am surprised this doesn't have to be released in a RNS? Isn't it price sensitive information?!
Do any of the changes in remote gaming duty affect Q4? Might be a factor.
Yes, it made me wonder too why there wasn't a more official release, although some figures were disclosed a few days ago.
Change in RGD doesn't come into place until April, so only one month impact this FY.
Re Best Of The Best (LON:BOTB) would anyone have any inclination what Best Of The Best (LON:BOTB) actually pay for their Dream Car prizes?
I'm assuming they don't buy a car at full retail price and would receive some sort of discount?
Any thoughts (or facts) would be appreciated.
Thanks
A
My question for Sosandar (LON:SOS) would be, given the plague (and wastefulness) of free online returns, what steps are they taking to reduce their return rate? It seems to be an expensive and widely-recognised global issue, eg https://www.smartcompany.com.au/industries/retail/hidden-costs-online-shopping/ and https://cebr.com/reports/many-...
There was I think another thread that referred to tech solutions to encourage shoppers to buy the correct size; it would be nice to hear that Sosandar (LON:SOS) are actively appraising solutions, perhaps in conjunction with other retailers.
Apologies if this is already on the question list.
Hi Paul,
Would you be able to ask the following question.
I saw recently that discounting has allowed some troubled retailers to delay the inevitable over what is a very tricky period. If a wave of retail failures hit the high street what would be the impact on Sosandar?
Also please don't feel the need to ask about returns, I feel that the company has explained this is part and parcel of online clothes retailing and it is slowly coming down. They also addressed it in the presentation you linked.
Re Sosandar (LON:SOS)
Questions to ask:
1. What is the split of their Admin Expenses into i) Marketing ii) Distribution & Fulfilment iii) Other
2. Building on 1, are they testing more aggressive marketing plans whilst they seem to have a winning proposition even if this put the breakeven date back by another 6-12months.
3. What other brands do their consumers also buy by (since none will be exclusive)
As a further comment, different to some comments above, I really hope Sosandar (LON:SOS) do NOT branch out from womenswear into Menswear (or Kidswear or Athleisure or Lingerie.....) - at least until they they are > £100Mn revenue ie many, many years out.
Their claimed edge and USP is superior insight into fashionable middle-aged women. Only once they have a well established brand reputation AND big revenue base should they consider going much wider. Market size is plenty big enough where they are now. IMHO this is mistake many fashion companies make (eg Quiz = glamourwear was easy to understand and distinctive but Quizman, QuizCurve etc are me-too ideas (no irony intended).
Focus on a single proposition means concentrated, meaningful marketing spend against clear idea to a well defined target group. This (along with good product) is the key to success. Given business structure if Sosandar can hit just £50Mn pa it will be very profitable ..........and the fastest, most efficient way to do this is to win big in womenswear where they are off to a great start..
I own and am very optimistic on business value in 2 to 3 years IF they keep their current focus.
As a holder of Staffline shares, I was amazed that AIM allowed trading to continue right into late afternoon. I entirely agree with you that suspension should have happened immediately on the 7 a.m. announcement.
Surely the answer is that in addition to the audit there is a fraud specialist on each audit committee that looks for fraudulent activity specifically at audit time and any other ad-hoc without warning, not dissimilar to an unannounced tax inspection
Sosandar (LON:SOS) - Do reported sales reflect net of returns? if half of everything they sell is returned are gross sales are really accurate. Also is it possible to be profitable and deliver acceptable returns if half of items are returned and you pay for the postage back then pay postage again to re-send to next customer.
Hi Sher3141,
I think the answer is reported Sales *are* net of returns (and removing VAT)
For example Q3 Revenue was reported as £1.6M, Q3 Avg Shopping Basket Value was reported as £105.58 and Q3 Orders were 35,183 which means that
Q3 Total Value of Orders was £3.7M, remove VAT £3.1M factor in returns for that quarter which were 49% and you land pretty squarely on £1.578M which tallies with their figure of £1.6M
Hope that helps
top stuff, cheers
sher3141
The revenue recogntion policy for Sosandar (LON:SOS) is detailed on page 49 of the Accounts
"Revenue represents net invoiced sales of goods including posting and packing receipts, excluding value added tax. Revenue from the sale is recognised when the company has transferred the goods to the buyer on dispatch from the warehouse, less actual returns and provision for expected returns. Revenue consists primarily of internet sales."
Best Of The Best (LON:BOTB) - bit strange that CEO felt the tender price was picked arbitrarily. What if it was £20 or £30, the inference is it just doesn't matter when it absolutely does. If the tender price is above intrinsic value they are destroying value, that is a truism, if it is below they are creating value. That is the only barometer that matters when assessing if good or not.
I think we can sometimes take what CEO's say with a pinch of salt. To suggest the Best Of The Best (LON:BOTB) tender price was just sort-of random does not strike me as true. In circumstances where something like that was put forward it would be discussed by the board, and no doubt their advisors. They would be trying to understand what signal it sent etc., what was the inherent value of the Company etc.
The CEO did sort of also imply that it was also to make it attractive to take up. So at one level the price is a marketing tool for the Tender Offer.
I think the main motive was to share the distributed cash as equitably as possible. But I wouldn't be surprised if there was a secondary motive. If there is an increase in their ownership, and let us say there have been thoughts of selling up or de-listing, they will have been honourable and distributed some surplus cash, and not forced anyone to sell up. So hands are pretty clean, and if an offer were to be made, they will have the opportunity to increase their take of the sale price.
In the spirit of total speculation I suggest there will be a part two to this story.
Hi Paul,
Another request for Flowtech Fluidpower (LON:FLO)
Thank you and Sosandar (LON:SOS) for organising the call and for asking for questions, mine are:
1. Celebrity Endorsements are an important plank of their marketing strategy. Could Julie comment on recent articles about celebs feeling obliged to declare their endorsements (both paid and unpaid) - How do management view this, I can't work out whether it's positive or negative - what are their / your thoughts.
example
https://news.sky.com/story/celebs-vow-to-say-when-they-are-being-paid-to-promote-brands-online-11614991
2. Regards Animal Print, seems like 30% of the catalog has some kind of AP, I asked Adam Reynolds about this (see below) and he agreed that there was a lot of AP but that it sold very well. My feeling is that it's almost become a category of clothing in itself, like denim or leather and as such it's timeless and simply the styles change over the years. However they may have an over reliance on it, if for one season it goes out of fashion then they could face problems, what is Julie's opinion.
3. Which companies do they view as particular competitors in their space and what do they admire about them?
4. If I'm understanding it, they used up ~ £1M in the quarter ending 2018-12-31, with £4.6M left at the end of the year, how do they view their progress to break even and do they think that their current cash balance is sufficient for this?
I met Adam Reynolds at a recent investor event (Investor Show / Share Prophets) I was also impressed by him, he seemed genuine, soft spoken, intelligent and surprisingly humble. There was definitely a contingent of people who had suffered under some of the companies that he'd been involved with, and were vocal about it. He seemed very excited about Sosandar (well he would wouldn't he) and I get the impression it is something that he is relatively active on.
Hi Paul,
A couple of questions here for Sosandar (LON:SOS) from a fairly long term holder;
The first, obviously prompted by your comments above, " will you consider appointing another broker who will make their research available freely to private investors or insist that one of your existing brokers make their research freely available? After all, Sosandar are paying for it.
Secondly, given the very high level of returns (and I accept that this is a general e-commerce problem) can you tell us what measures you take or are considering taking to reduce the impact of returns? For example keeping track of persistant "offenders" so that they can be excluded if not profitable and/or attaching some kind of large " Property of SOSANDAR label" to the front of the garment so that it can't be worn to one or two "events" and then returned "unused". Returns only accepted if lable not removed.
As a follow-up to Laughton, I'd like Sosandar (LON:SOS) to clarify how their high returns interacts with their KPIs - or maybe you know already Paul. For example, presumably their average order value includes returns which therefore means the real revenue per customer is potentially about half that being reported?
p.s. there's obviously space for more than one online brand but Sezane seems to be well performing. Its photos are better quality although it is competing for the more expensive end of the market.
i noticed that TK Maxx have started doing this (adding a fairly significant electronic tag) for their gold label products - so people cannot do this bizarre trend of taking an expensive item, instagramming it and returning it - or wearing it to a wedding etc.
my view is this is definitely the way to go and should be adopted by all retailers - esp. online
Looking forward to T Clarke (LON:CTO).
Terrific update today - I am sure some might now like the sector but it looks cheap considering that they have a cash pile.
Although I don't think the type of business will ever demand a big multiple valuation and operate on thin margins the new technology projects do look exciting and could be a big driver of further growth.
Hi Paul,
Will you comment on Sylvania Platinum?
Thanks!
I am a holder of Sosandar (LON:SOS).
I have a question that I have phrased before on here that not had asked formally.
The competitive strength of Sosandar appears to be the experience of Ali and Julie knowing what women want, and offering it.
Would this current position then be reliant on them remaining with the company? What would happen if one or both were not around?
Also, what would they say has given rise to their perceived insight to the market? There must be thousands of women who work in fashion magazines whose experience equals or exceeds that of them, yet they seem to have discovered a genuine new niche, in effect having something that the others do not.
Paul
A question for SOS meeting/call if I may. I am a long-term holder.
"Is there an over-reliance on Clipper Logistics as a supplier, and does their internal risk management consider options for alternative operations support should Clipper fail to deliver or have financial issues".
Although Clipper looks like a good business, it does seem to have quite a bit of debt.
Thanks in advance.
Greyster
My pennyworth on the frauds is that perhaps one has to look beyond the figures and actually attend AGM’s, look management in the eye and look at their C.V.’s. I hold seven stocks listed on the AIM (Boohoo (LON:BOO) £AZZ XLMedia (LON:XLM) Taptica International (LON:TAP) Fevertree Drinks (LON:FEVR) Somero Enterprises Inc (LON:SOM) £BVXP) and five on the main market (Treatt (LON:TET) Avation (LON:AVAP) Avon Rubber (LON:AVON) XP Power (LON:XPP) £PLUS). I am not going to avoid AIM because of Patisserie Holdings (LON:CAKE) or others but I am going to be more careful. If I had decided that AIM was the Wild West I would have missed out on Fevertree Drinks (LON:FEVR) Somero Enterprises Inc (LON:SOM) and Bioventix (LON:BVXP) which in my opinion are of the highest quality regardless of exchange (not sure I would say that of Taptica International (LON:TAP) or XLMedia (LON:XLM) but that is another story!)
All very well but attending AGMs is not possible or difficult and expensive for most investors. I never attend them but I do hold some AIM shares, some are listed above. I agree you can't just go by the figures hence people getting their fingers burnt on certain Chinese AIM shares.
Sosander question please
Hi Paul. Firstly I declare I hold long positions in Joules, and BooHoo.
Your catalogue looks super, however it seems over burdeoned by animal print fashion.
How well is it selling ?
@pippasfan (#17) re Sosandar (LON:SOS)
In the link Paul provided to the SOS presentation, one of the last questions was along the lines of "What is/will be the next 'must-have' fashion?" The presenter, wearing a leopard-print top, stated "Leopard print" :o)
Paul, as for Sosandar (LON:SOS) questions, I had three nagging me for a while, the first two of which I'm more knowledgeable on now:
1) High rate of returns - Although high compared to other online sectors, it seems this is the norm with clothing, and is priced in to their budget(s). I've explained to many online clothes buyers about these costs to the retailer, and instead of ordering size 14 and 16 (in the case of women), why not order one, and if it doesn't fit, return and buy the smaller or bigger one.
2) Reliance on a few celebrity/TV promoters/wearers - This seems to be mitigated, due to their expanding celebrity base. This, along with the increasing range of items, should lessen any impact if a celebrity 'defected' or a style (leopard print?) became unfashionable.
3) The only thing you may like to include, is that their expertise is obviously women's fashion, but this limits their clientelle to approx. 50% of the population. Would they, if the right opportunity arose, expand into menswear? This may mean bringing male versions of themselves on board, but could enhance their average order value (women adding a shirt for their husband etc.), and reducing returns (would the husband dare tell their wife he didn't like the shirt ! lol)
Re: Sosandar (LON:SOS)
DJCP - I've explained to many online clothes buyers about these costs to the retailer, and instead of ordering size 14 and 16 (in the case of women), why not order one, and if it doesn't fit, return and buy the smaller or bigger one.
You assume that the buyer cares. In part it's a case of "I want it and I want it NOW!" And, as the return isn't costing me anything, I'm just reducing the chances that what I want might not fit first time.
Thanks DJCP, good observations, however I would still love to know how well animal print is selling. Obviously they believed it would sell well,but I have my doubts. Thank you
As an advocate of both fundamental and technical analysis and the importance of both being in concert for maximum success probability: the likes of Patisserie Holdings (LON:CAKE), Staffline (LON:STAF) etc. help to re-balance the arguments that the root of all wisdom is fundamental analysis while technical analysis is akin to examining goat entrails. Staffline (LON:STAF) was outperforming the market until December '18 but then took a dive off a double top reversal falling 40% into early January..and then it's cataclysmic collapse yesterday .
While it is a low liquidity share and therefore prone to poorer technical behaviour, the price action was clearly signalling all was not well. The prescience of price action!
regarding Staffline (LON:STAF) and the assertion that charting rather than fundamental analysis spotted a problem in early January, the significant drop only really occurred after the trading update on 8 Jan which revealed £20m of exceptional costs.
Surely loads of perfectly ok company share prices were also taking a dive about the same time?
While it is a low liquidity share and therefore prone to poorer technical behaviour, the price action was clearly signalling all was not well. The prescience of price action!
Really don't understand that: are you saying that the share price movements are information in their own right, independent of any fundamentals?
Basically, there would appear to be two possible explanations for the share price movements - (1) that someone knew something and that something was sufficient to persuade people to sell, and other people followed the signal or (2) it's purely random. Unless you can tell those two apart then the price action signal isn't predictive of anything, however much hindsight makes it appear that it was.
In the case of Patisserie Holdings (LON:CAKE) given that pretty much everyone is agreed that no one saw this coming then it's almost certainly random. Without looking at Staffline (LON:STAF) in detail it's hard to know in detail, but I'd note that the recent large drop corresponded with their last trading update, so it does rather look like the market took exception to that.
timarr
@timarr, your challenge is well made and deserves a response in the same spirit of objective if robust discussion:
to qualify, lower liquidity shares tend to be lumpier in their response to relatively smaller increases in volume. Its a matter of physics and volume at price. Shares that only trade tens of thousands in volume on a daily basis like Staffline (LON:STAF) will move very quickly on a few orders unlike the mega caps. That in itself may not be indicative of a change in fundamentals : it is a bit of a nuanced argument and wasn't well articulated in my fairly offhand comment
( though that is often the appeal of small caps and why they can give great rewards as well as risks). Directionally Staffline (LON:STAF) had changed in trend, given-up its 200 daily moving average and was increasing volume on days when price was dropping.
Equally to amplify my original point: having fundamentals and technicals in concert maximises probability of success: it is at the heart of most successful systems except the buy and hold forever crew.
No doubt everything makes much more sense in hindsight: like any analysis in multivariate and complex systems, it is subjective and rarely axiomatic. Using rules based systems to detect significant changes in trend is pretty common in many risk management strategies(and again that is nuanced and subjective based on the definition of that trend and relative risk) @ Seadoc's comment does illustrate that point
I'd argue that price action by definition cannot be random since it is a summation of all of the decisions of those buyers and sellers..but then we are into another argument and I'll take a random walk away from that one.
I'd argue that price action by definition cannot be random since it is a summation of all of the decisions of those buyers and sellers..but then we are into another argument and I'll take a random walk away from that one.
The question then comes down to whether those decisions are independent of each other - i.e. you're looking at a wisdom of crowds result - or not - i.e. you're looking at noise trading. Almost by definition most technical analysis is the latter, and the more uninformed punters who are attracted to it the lower the signal to noise ratio is likely to become.
I'm not dissing technical analysis in general, just pointing out that the same signals can be generated either by real information or by noise. Identifying the false positives can only really be done by fundamental analysis. Of course, very smart traders can make money by trading on the noise generated by idiots, but that's an entirely different sort of investing.
timarr
@Tim
although trend analysis ,for example, is a de-facto summation of signal over noise: that's been around for a while since Livermore's day if not before and does work well.
There are so many flavours of technical analysis and most of them are bunkum. I don't go with wave analyses as a proxy for crowd psychology . However I do know that price moving on strong volume is more signal than noise and that signals such as these can and do inform subsequent buying/selling. I am evidence-led and data driven : that is in my nature and in my original background as a scientist: but I get that opinions vary markedly on this. If nothing else, Minervini has done some good for a much maligned and misrepresented suite of tools.
If we ever meet IRL, we can debate with vigour : whatever about the wisdom of crowds, I try not to get fooled by randomness
With Patisserie Holdings I would have thought the chart simply indicated that the strong momentum trade that had taken it up from around 340 to 500 in a period of only a few months had at least temporarily ended. Had I held the share on this run up it may have made me get out about the time it broke below its 50 day moving average at around 440. Much more importantly it would have stopped me buying back in until the situation resolved itself with a move up out of the sideways trend that continued until the death although this did not signify anything more than a possible pause before perhaps continuing upwards. I always say that if charts do only one thing they can stop you trying to catch a falling knife although Patisserie never came near this category.
dsc, I no longer hold any Staffline (LON:STAF) but would concur with your comment about prescience. I bought in on an analysis on here and supported by Stocko metrics, 5000 shares 18 months ago. I think the Stocko number was high 90s. Perhaps one clever than I can give the rating on 19/5/17? Just over a year later based on review of full portfolio on what I could and/or should sell I decided to sell and could get an on line quote for only NMS, I think at the time 200 shares. I phoned the broker's dealing room around 1000 and we agreed a sell at a small discount for the full holding at just under the bid at NMS. Within a few hours I got e-mail confirmation of sale. The sale was late reported 4 hrs later and for a couple of days the sp fell below that for which I sold. The sp soared 50% over the next few months. Yesterday morning I could have bought back for less than I sold. Just an observation. I do a 4 weekly review of my portfolio and as part of the review I may start doing dummy sales in my remaining holdings.
"While it is a low liquidity share and therefore prone to poorer technical behaviour, the price action was clearly signalling all was not well. The prescience of price action!"
Too true.
PS to timarr: Neither 1) nor 2). I think the problems may have been apparent to some a year ago and the double top noted by dsc may have resulted because of knowledge/suspicion. Probably just old age paranoia on my part. But I will be interested in the Post Mortem.
PPS. Never had two downvotes before but just lost one of them. Probably gave it to myself? But if anyone does have constructive comments I would be interested.
Here is Stockopedia report Staffline (LON:STAF) for 10/5/17: http://reports.stockopedia.co.uk/18893038/Staffline_LSE_18893038_20170506.pdf
Herbie, Many thanks for Stocko report of 10/5/17 for Staffline (LON:STAF) 97 no less. Did you get that from the website? And if so how? Many thanks, Seadoc
Yes it is under the print button, it has reports roughly monthly.
1 x virtual beer. I did get to UK Investor last year, on my way back from NZ, so just put it on tick and it could become real. Seadoc
PS Thanks Ed, really made a brilliant tool here.
Hi dscollard said;
While it [STAF] is a low liquidity share and therefore prone to poorer technical behaviour, the price action was clearly signalling all was not well. The prescience of price action!
That's all very well, but I don't think it is necessarily true overall. In the big sell-off over the last 6 months, there have been numerous shares that fell heavily. Some have since posted positive updates, some have posted negative updates.
I don't think negative share price action has been a good indicator at all, when everything is selling off due to macro issues.
The more illiquid the share, the less relevant the share price graph becomes. Most institutions don't buy in the market, for illiquid shares. They just buy or sell to each other, or buy in placings & IPOs. Therefore usually the institutional shareholdings are locked away, and have zero impact on the share price. It's the small trades from private investors that move the share prices up or down.
Therefore, a handful of small traders hitting a stop loss, or becoming nervous about Brexit, can slam the share price down 20% or more, for a small cap. Is it telling us anything negative about the company itself? Not in the slightest, as the trades are usually placed by people who know little to nothing about the company.
To my mind, the only thing that charts are telling us right now, is that the market is generally more nervous than it was when everything was soaring upwards.
Regards, Paul.
@ Paul
agreed it isn't true overall, in the case of Staffline (LON:STAF) it was outperforming AIM All-Share up until early December : AIM -All Share had dropped 22% while Staffline (LON:STAF) actually rallied to £13.6 it's highest value ever before a TU in early December so in the same period it had a very positive relative strength to the underlying market. It is exactly that change in relative strength that was significant and indicative of problems
re instis. Staffline (LON:STAF) is 76% owned by instis, like you say, their tight hands often contribute to the lack of liquidity
Good to debate relative interpretations
Keywords Studios (LON:KWS)
I have taken a punt on KWS - organic growth -looks ok - pe under 20 now - still aint cheap though, tone seems confident enough.
andrea
(Awful Stock rating... though is this largely due to the sell off particularly)
Looking at the stocky numbers momentum is poor (22) due to the depressed price but its the value number of (5) that looks to really be keeping the overall score down - stocky aint wrong this share aint cheap.
I would say though 2 or 3 years of 20% growth in EPS and a rebound of shareprice and i think the numbers will start to look better quickly if the company grows into its lofty expectations. No room for poor numbers with this company thogh - the slight worry is expectation are now trending in the wrong direction - they just about get away with the downgrades being minor enough to be a rounding error - but i would rather they under promise and ensure they hit their targets
The oddest aspect of Staffline (LON:STAF) case is that the auditors informed the co of concerns supposedly hours before the prelims were to be published.
I bought just before suspension. I am in suspense.
Mr Contrarian I don't know what has gone on at Staffline (LON:STAF) but my presumption would be different from yours.
The auditors would have started their end year process, presumably in late 2018. At some stage they would flag up outstanding issues. Presumably one of these would have been the invoicing and payroll procedures in the Recruitment Division. The finance team presumably has gone back saying that this is the way we have done it for years, believing that the auditors would accept their line. Then they would have been some back and forth. Then when it has come to actually sign off the results, either the auditors have said they will not sign off or someone on the board (maybe a non-exec), hearing the issues, has raised concerns on finalising the accounts.. Obviously the above is all conjecture.
Maybe also a relevant point is that this year is the FD's (Michael Watts) first set of financial results - he was previously FD of Staffline's People's Plus division - so not the division where the current issues are.
Whilst on the subject of Auditors, the following has today been announced on one of my previous investments Assetco (LON:ASTO)
https://investegate.co.uk/assetco-plc--asto-/rns/litigation-update/201901310924176755O/
In a judgment, which was handed down this morning in AssetCo's case against Grant Thornton LLP ("GT"), AssetCo has been awarded damages of approximately £21 million before an additional amount for interest on the damages and costs of the litigation.
Quite a substantial amount for a company with a market cap. of £31m
So far, my list of things to look at today is;
Anything else that catches my eye, if I have enough time left.
Best wishes, Paul.
The board statement re Staffline (LON:STAF) by stating that accounting practices were subject to prior audits, implies that whatever the current practice is has been the practice for a while.
I cannot help but recall the surprise resignation of Andy Hogarth (long-time CEO and who had built up the company since he joined in 2004) on the publication of the 2017 results (Jan 2018). He said at the private investor presentation of the results that he had confidence in the company - then a few days later sold 2/3 of his shares. He then resigned as a non-exec at the end of June. Co-incidentally, his 12 month lock up on his remaining 500,000 shares ended 12 months after 30 Jan 2018 (yeserday?). According to Companies House, Andy was appointed a director at Finncapp in November 2018. Companies House also shows that Staffline has had six different FDs since Nov 2004.
Staffline (LON:STAF) has always excelled at the speed with which it released its year-end results - normally I would think a good sign.
While Keywords Studios (LON:KWS) is slightly too big for here, it's only by a wee bit so I'll comment.
I would class their TU today as very nearly in line with (very high) expectations (very slight miss on eps) but very upbeat in tone.
Given current conditions I thought the price may get a spanking but no, they're up 7%.
Shares were already down almost 50% since peak, I think this one is oversold, so I think it is good value now. I have a small holding.
Hi Herbie (and everyone actually!),
Please could you always include the ticker or name of the company you are referring to.
It's not clear otherwise. I just see a 6-figure post number, which is not shown on the original post. Hence I have no idea which company you're talking about, unless you clearly state the company name/ticker.
Thanks, Paul.
Sorry Paul, I usually do but forgot that time. This meaningless reply number is a downgrade I don't know why Stockopedia changed it, at least before it showed who you were replying to, so it made sense, now you don't know who the response is to without going into each post. It was Keywords Studios (LON:KWS).
Hi Paul
If you click on the actual reply post number (6 digit) it opens a window that shows the thread of the original post and the replies.
Hope that helps
This is not aimed specifically at Chris, although I've written it as a reply to Chris' comment...
Whilst true, this is time consuming when in a hurry and also more difficult on a mobile phone. Frankly a lot of the time I can't be bothered as the payback for my effort is often disappointing (for example if about a company I'm not interested in). If the comment does not say which company or what topic of conversation (such as quoting the relevant bit) then I'll most likely pass on by. I assume some or more others here might do the same.
I'm not sure why Stockopedia don't make it mandatory to enter either a stock ticker or Topic on any posting.
A disappointing quarterly report from Sylvania Platinum (LON:SLP) with PGMs down 22% and revenue (partially helped by PGM prices) down 12% with EBITDA down 22%; the assorted technical issues, including 20 days downtime at one mine, have been resolved.
Conversely there is a good update from Keywords Studios (LON:KWS) - "Board expects full year revenues of at least €250m (FY17: €151.4m) and adjusted profit before tax* of approx €37.8m (FY17: €23.0m). The Group's effective tax rate, has continued to reduce and is expected to be 19.0% (FY17: 20.5%). As a result, adjusted earnings per share are expected to be c.47.0c, an increase of 51% compared to the prior year (FY17: 31.18c)" This is despite a "weaker than expected performance from Localisation Testing which saw a number of titles move from the last quarter of the year into the current year". This seems quite good value now.....? Any view, please, Paul? (Awful Stock rating... though is this largely due to the sell off particularly hitting tech stocks since the summer?)
Staffline (LON:STAF)
Well said Paul
To add insult to injury with regard to yesterday the following comments really annoyed me (it reet got my goat up !)
The Board is confident that its policies in relation to these matters are appropriate, particularly given that these practices have been the subject of prior audits.
Why would they say that - loads of audits don't pick up items that may be "pimped up more than they should" or manipulated for whatever reason, is it not 100% responsibility of the directors and board to ensure everything is fair and reasonable when presented for audit.
If you "the board" are confident you the board should say "we as directors are confident that we have done our duties in providing accurate figures for audit that meet auditing requirements" - if they can't say that don't say nowt.
They should be revisiting every aspect of their organisations structure in this regard so that THEY the directors put figures up for audit that are fair and reasonable - not something that can be maximum acceptable spin wise.
Even if it turns out there are no issues (unlikely IMHO) the board here really have let the shareholders down communication wise and it really shows the board as either having no clue, being useless or disingenuous.
A fewquotes from Langton Capital this morning re Auditors:
• Telegraph reports Grant Thornton boss as telling MPs that auditors are ‘not set up’ to spot fraud.
• Grant Thornton refers to an ‘expectation gap’. It says ‘we're not looking for fraud or the future or giving a statement that the accounts are correct. We saying they're reasonable, we are looking in the past and we are not set up to look for fraud.’
But surely fraud on the scale of Patisserie Valerie to name but one involved accounts that aren't correct. To say we are not set up to look for fraud is at best a bit thin given the fees raised to carry out the practice.
Morning Paul. Surely a tender offer is a very effective way for management to reward investors by 1) returning cash, 2) increasing eps and other measures per share by reducing shares in issue, on the otherhand 3) assuming they don't take up the shares themselves increasing their own % ownership which could lead to taking private or reducing liklihood of takeover, but certainly increasing managements stranglehold on the business. I look forward to hearing your audio which doesn't seem to be attached at present.
On Staffline etc I do wonder what role the Auditors are playing given their role is to give investors confidence in accounts. If issues are arising at the rate they currently seem to be cropping up what is the role of an auditor encapsulate?
RE: Best Of The Best (LON:BOTB)
Thanks Paul for the interview. I will be interested to see if their ownership % will go up after the Tender Offer. This may happen if there are lots of small investors who cash out. Also, they did seem to hint at some potential future change regarding the newly imposed tax regime, but didn't elucidate in their Trading update.
Perfectly reasonable for the management who are substantial shareholders to participate in the Tender Offer. They will believe this also a signal for all shareholders to participate. Good sense to do this at the lowest possible tax threshold. Who knows if a Corbyn style Govt will try and align in the future CGT rates and Income Tax for high earners, to avoid tax structure devices.
There was some commentary that because of the fear that Corbyn or Corby style Govt may get control at some point that some business owners are trying to sell up to take advantage of the current 10% Entrepreneurs relief, which allows owners who have developed businesses to pay a reduced rate of CGT.
I wonder if that could be on the agenda for £BOTB?
My morning smallcap tweet: FireAngel slams holders into the wall again
Eservglobal (LON:ESG), SRT Marine Systems (LON:SRT), Fireangel Safety Technology (LON:FA.), Newmark Security (LON:NWT), Ashley House (LON:ASH), £R4E, NAHL (LON:NAH), AO World (LON:AO.), Watchstone (LON:WTG)
eServGlobal (ESG) wins 2 PayMobile contracts with existing customers in the Middle East totalling ~€1m.
SRT Marine Systems (SRT) £4m placing at 30p (an 18% disc) "to accelerate the development of coast guard specific system functionality in order to meet project delivery schedules for expected new contracts, to expand and [blah blah keep the lights on]" Trading: "progressing discussions on three further contracts with separate government agencies/Ministries in the Philippines worth up to £152m". I hold.
FireAngel SafetyTechnology (FA.) guides FY op loss below market expectations. Rev down 31%, underlying operating profit c.-£2m (+£4.7m). A warranty provision release has been prudently retained based on current higher product costs. Manufacturing problems fragging on to this FY.
Newmark Security (NWT) H1 rev-cont up 20%. EPS-cont 0.09 (-0.1). Warns revenue within asset protection division expected to be lower "due to seasonality factors as in previous years among reasons.
Ashley House (ASH) H1. Warns on FY due to scheme closures lower than initially anticipated.
Reach4Entertainment (R4E) guides FY adj EBITDA significantly ahead of expectations. Also expects 2019 profit ahead of expectations.
NAHL Group (NAH) granted a licence to launch its own law firm. I hold.
AO World (AO.) CEO has had enough. He is thanked and will be part time adviser. Founder John Roberts jumps back in the seat today.
Watchstone Group (WTG) guides FY rev £37.7m down 16%. F/C was £41m. Expects Slater & Gordon Claim to go to trial October. I'm short.
Morning Paul,
Please would you cast your eye over Flowtech's trading update today.
Revenue up 42%, organic growth 6%.(I Hold).
Thanks.