Small Cap Value Report (Tue 13 Nov 2018) - IQE, FOXT, IDEA, BWNG, CAR

Good morning, it's Paul here.
To get you started today, I finished off yesterday's report in the evening, with a new section (a reader request) on Northern Bear (LON:NTBR) . Here is the link to that report, if it interests you.
At some point this week, I'm wanting to look at results last week from GAME Digital (LON:GMD) , Tracsis (LON:TRCS) , and £GATC
IQE (LON:IQE)
Share price: 67p (down 29% yesterday, at close)
No. shares: 776.0m
Market cap: £519.9m
Profit warning yesterday - thank you to the readers who flagged this up in the comments yesterday. This profit warning was issued at 4:20 pm, i.e. just 10 minutes before the market closed to go into the 5 minute closing auction.
I imagine that the share price is likely to continue falling today, because many private investors won't have seen the profit warning in time to take any action in just 10 minutes. It's just not right that profit warnings can be put out during market hours. That creates a false market, and is unfair to ordinary private investors, who get the news later than city insiders who are screen-watching every second of the day.
Rather than issuing a profit warning during market hours, companies should instead be compelled to temporarily suspend a share, then publish the profit warning after hours. Then resume trading at 8 am in the morning, once everyone has had a fair chance to read the announcement.
The news looks pretty bad to me;
IQE plc issues this trading update in response to reports made by a major chip company in the VCSEL supply chain on 12th November 2018 that they had received notice from one of their largest customers for 3D sensing laser diodes to materially reduce shipments for the current quarter.
The Company is currently assessing the impact of this news but at this stage, it expects there will be a material reduction in its financial performance in the current year.
My opinion - I'm keeping away from this share these days, having realised some time ago that I don't really understand the company well enough to be sure either way. So the profits I made on the share previously were really more luck than judgement.
It's amazing how many high growth, high momentum shares seem to be falling out of bed recently. Not just in terms of deteriorating fundamentals, but also less investor appetite to chase valuations relentlessly higher.
It's becoming increasingly clear that the momentum trade on high growth stocks now seems to have broken down.
Further trading update today - bizarrely, IQE has now issued 2 trading updates in rapid succession. This morning's update gives more detail, compared with last night's brief update.
Key points;
Revenues FY 12/2018 now expected to be £160m. This compares with forecast of £176.5m shown on Stockopedia. Coming late in the financial year, this clearly means a sharp slowdown in Q4, below what was previously expected.
The key VCSEL product (on which face-recognition chips are made) has seen weak demand in Q4, due to previous inventories being used instead - suggesting weaker demand for iPhones & similar consumer products.
Photonics wafer revenues growth for FY 2018, on a constant currency basis, is now expected to be approximately 11% (previous guidance for FY 2018 Photonics wafer revenue: 35% to 50%) and based on early initial indications, is currently expected to return to previously guided levels of 40% to 60% revenue growth in FY 2019.
Revenue growth of 40-60% in 2019 would surely be on a lower 2018 base figure? So to me, this suggests lower actual demand in FY 2019 as well.
Wirelesss & Infrared product sales look to be at or above existing guidance.
Revised EBITDA guidance is given;
As a result, FY 2018 Adjusted EBITDA is now expected to be approximately £31m (FY 2017 £37.1m).
Unfortunately, I cannot access any broker research on this, so am in the dark as to how this EBITDA guidance compares with previous guidance. Clearly though, EBITDA going down by £6.1m compared with 2017, can't be good news, for a supposed growth company.
This company is also capex-intensive, so EBITDA really doesn't show the full picture.
My opinion - I don't understand it properly, so am steering well clear. This share is really only for experts, or punters, in my view. There doesn't seem to be adequate visibility.
The question is whether today's update is better or worse than what investors feared last night? Is this just a bump in the road, with orders delayed, or will the market see something more serious? We'll soon find out. I've got no idea how this one will pan out. The share price has fallen heavily from last year's peaks.
Foxtons (LON:FOXT)
Share price: 51.9p (up 3.8% today, at 08:14)
No. shares: 275.1m
Market cap: £142.8m
London's leading estate agency, issues its trading update for the quarter ended 30 September 2018.
There's been widespread publicity about the London property market cooling, for various reasons, including excessive stamp duty on high value properties, Brexit concerns, and that prices are way too high on traditional metrics like salary multiples.
Therefore it comes as something of a pleasant surprise for shareholders that business in Q3 wasn't actually that bad - flat against last year (revenues) seems respectable, in a tough market;
The Group delivered a solid third quarter performance as the trends set out in July continued through the period.
Group revenue was flat year on year at £35.1m (2017: £35.1m), taking total revenue for the nine months ended 30 September 2018 to £88.1m (2017: £93.7m).
Year-to-date revenues are down 6% on last year. So flat in Q3 is an improving trend.
Lettings - makes up the bulk of revenues now. This is cushioning the business from the downturn in sales.
Lettings revenue was £23.1m (2017: £22.5m), as our enhanced offer and improved resourcing enabled us to capitalise on demand in what remains an attractive market.
Property sales - remains in the doldrums;
Sales revenue in the quarter was marginally lower at £9.9m (2017: £10.3m), which is a solid performance amidst ongoing reduced transaction levels. Revenues in our mortgage broking business, Alexander Hall, were £2.1m (2017: £2.3m).
Cashflow - as expected.
Current trading - October was in line with Q3 levels.
Branches - 6 have been closed, following a review. No more closures planned.
My opinion - current forecasts are for Foxtons to trade at around breakeven. Therefore, the valuation is based on anticipation of a recovery in future profits. That's what's happened in the past - profits here are highly geared to housing market transactions.
The London residential property market has been through a long boom, which seems to have fizzled out now, with prices at stratospheric levels. Who knows what happens next, it's anybody's guess.
There's also internet competition to think about. Foxtons prices are very high, and whether that's sustainable, who knows?
Foxtons' balance sheet is adequate, so I don't see insolvency as a risk here. Unless the London property market completely freezes up.
Possible upside could come from a change in Government policy, after idiotic hikes in stamp duty some time ago - which killed the top end market. A classic case of politicians and civil servants not understanding how markets work. They saw a multi-year property boom, and decided, pretty much at the top of the market, to hike tax on high value property transactions. A similar thing happened in 1988, when double MIRAS tax relief for couples was removed, which triggered a rush to complete transactions, and then a slump.
We also have to consider the impact of higher interest rates. A good element of the property price boom must have been encouraged by ultra-low interest rates. That era seems to be coming to an end - with the USA hiking interest rates, the rest of the world inevitably is likely to follow. That seems likely to negatively affect property prices at some stage.
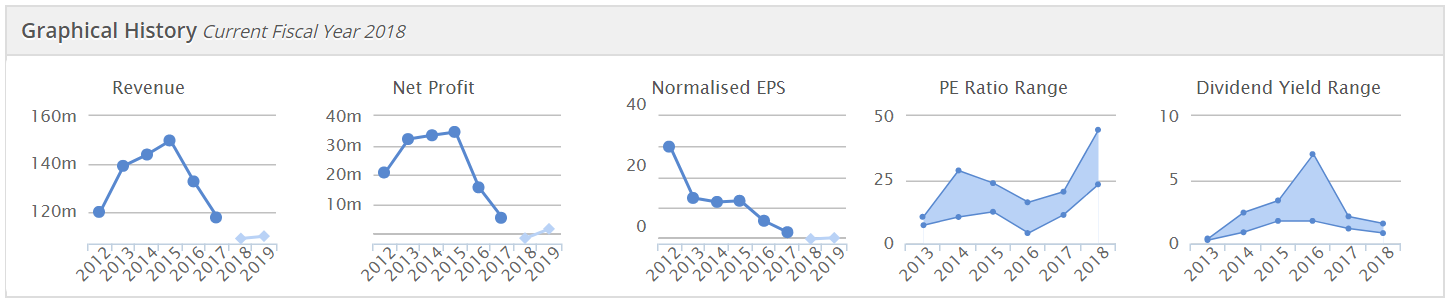
Overall, there are far too many uncertainties to make me want to get involved with this share, at this time. You can see just how geared Foxtons is to the market, from the usual Stockopedia graphs below;
Ideagen (LON:IDEA)
Share price: 141.5p (down 0.7% today, at close)
No. shares: 219.2m
Market cap: £310.2m
Ideagen PLC (AIM: IDEA), a leading supplier of Information Management Software to highly regulated industries, today provides an update on trading for the six months ended 31 October 2018.
There's a lot of positive-sounding stuff in today's update, but the bottom line is that performance is in line with expectations;
The Board is pleased to report that trading has remained strong in the first half of the financial year and that revenue and EBITDA are both expected to be significantly ahead of the same period last year and in line with management's expectations.
This group has been highly acquisitive. This has resulted in a balance sheet that is very top-heavy with intangibles. When last reported, as at 30 April 2018, NTAV was negative at -£9.8m. I prefer to see positive NTAV.
Other points from today's trading update;
SaaS - Transitioning from a licence, to SaaS model - which should increase the proportion of recurring revenues, making revenues & hence earnings more predictable over time
Bookings growth - starting to report this in trading updates, as it's a key KPI. The figures look impressive;
Total like for like bookings growth increased by 34% and total like for like SaaS bookings increased by 80%.
Recurring revenues - this also sounds good;
Given the momentum of our SaaS business the Company now expects to generate 74% of its revenues from recurring contracts by the end of 2020, up from the 70% previously anticipated.
Organic revenue growth in the period was 8% which, in the context of an accelerated SaaS transition, represents a strong performance.
New business - some impressive big client names are mentioned.
Net debt - modest, at only £1.3m
Outlook - strong platform for H2.
My opinion - the above all sounds great. However, I just can't get my head around the valuation here, of £310m. This seems to rest on a lot of accounting adjustments.
On a statutory basis, the group only made a profit before tax of £1.4m last year.
With software companies, I prefer to value them on a multiple of cashflow. In this case, it generated £8-9m in net operating cashflow in the last 2 years. It then capitalised c.£2m each year in development costs. So it's really only generating about £6m p.a. in cashflow. Is that really worth over £300m market cap? Not to me it isn't.
Another thing that bothers me, is that it pays virtually nothing in corporation tax. Maybe there are tax losses brought forward, I don't know. But it's something that I would need to look into, if I intended buying any shares.
Overall, it's not for me. I prefer to see more straightforward accounts, and more obvious cash generation, without lots of adjustments to arrive at that situation.
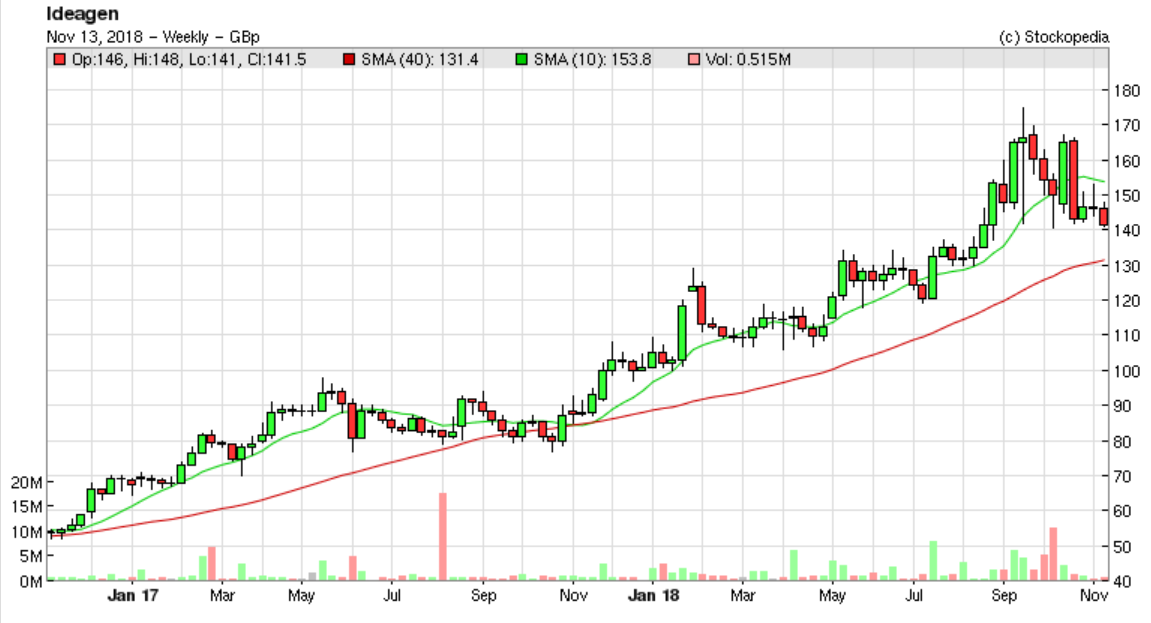
Shareholders seem to have largely held firm in the recent market sell off. If this was in my portfolio, I'd be tempted to take some money off the table, given wobbly market conditions;
N Brown (LON:BWNG)
Share price: 126p (down 6% today)
No. shares: 284.5m
Market cap: £358.5m
This is a mainly online retail group, specialising in large sized fashion, and offering high-cost customer credit. Brands include SimplyBe, and Jacamo, which you've probably seen advertising on TV.
There has been a dispute between the company and HMRC, concerning what proportion of its input VAT on marketing costs should be recoverable.
The RNS today is a bit complicated, but the standout sentence is this;
The draft ruling has mixed implications for N Brown and we are disappointed by the current outcome.
So it's negative, hence the share price dropping 6% today. N Brown might appeal, and it's only a draft decision anyway, by the VAT Tribunal.
Financial impact - this may change, but it's a hit to future profits. Therefore broker forecasts will be adjusted to show reduced earnings forecasts;
... the Group expects that irrecoverable VAT on its marketing costs will increase by between £6m to £9m per annum on a full-year basis from FY20 ...
My opinion - I'm wary of this share, as the stock market clearly doesn't like it, despite the apparently ludicrously low PER.
The trouble seems to be that the profit mainly comes from high interest charges to customers who pay by instalments. Very little profit seems to be made from actually selling products. Is that sustainable, and therefore is the big dividend sustainable? I simply don't know. The share price seems to be suggesting to us that there could be some doubt over these things.
The group has a high level of debt, but this is more than covered by an enormous customer receivables book, so may not necessarily be a problem. A key issue is whether impairments on the customer receivables book are adequate? As the nature of this kind of customer credit, is that many customers default. Which reminds me of Lily Savage, who always boasted of ordering clothes from the catalogue, and then moving house to avoid paying for it.
I'm tempted to have a bit of a punt here, but due to market uncertainty, probably won't.
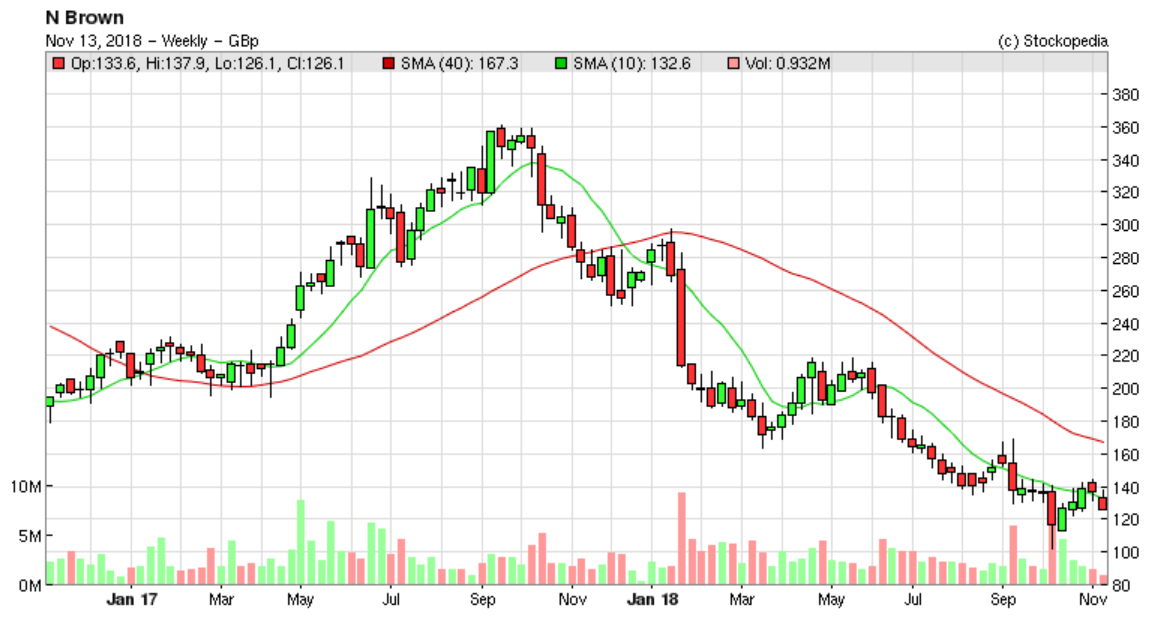
The 2-year chart below clearly shows how perception has changed from it being an internet growth company, to being ex-growth and riddled with problems.
I've run out of time now, but a quick comment to finish off with;
Carclo (LON:CAR)
Interim results show adjusted profit down from £4.55m to £3.57m
Outlook comments not bad;
The Board anticipates full year trading will be in line with its expectations and the Group remains on track to grow substantially over the medium term.
Net debt quite high relative to market cap, at £35.9m - so low PER not quite as cheap as it looks. Company says "well within" banking covenants.
Note there is also quite a large pension deficit.
Overall, this could be worth a closer look, as a possible recovery. I'm intrigued by the upbeat commentary about new sales programmes & products in the pipeline.
All done for today, see you in the morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Regarding the articles about the VCSEL market.
These articles confirm the substantial potential in the VCSEL market. Note that the M&A activity doesn’t expand capacity it is just rearranging who owns it. So, this all validates to my mind that there is a bright future for VCSELs and plenty of business for IQE (LON:IQE) regardless of the slow down from Apple.
Carclo has been about to go nuclear with their car lighting division since 1990. Since then nothing. I'd avoid.
Trifast, basically this has no stategic games to play, no moat and frankly can only ever run a marginal business.
I know both companies well. Their independance amazes me. But then who would want companies that are going no where.
Re IQE (LON:IQE) - in retrospect, well done to IQE for taking advantage of its higher share price last year to strengthen its financials with a capital raise! This gives it the stability to weather this Apple-driven squall and back its bet on investing in capacity to retain its market share and thus (hopefully) lowest cost position. This could be a brilliant move if the market for 6" VSCELS takes off medium term with a wider range of adoptees - or create a herd of white elephants if not.
Personally, I still believe in IQE (and continue to hold) as a risky mid-term, 3-5 yr opportunity that was always likely to see a lot of volatility hence it my son's JISA !!
Re IQE, the OEM end customers will always want to have at least two suppliers for security of supply and to allow them to negotiate pricing down, so it's no surprise to see other capacity being put in place.
It just looks to me like the II-VI and Finisair combination, assuming it gets past competition regulators, and once they achieve volume production, will be a strong vertically integrated supply chain and likely to be a preferred supplier.
Also from August last year
II-VI buys large UK wafer fab to expand laser production
Additional VCSEL capacity acquired in $80M purchase from Kaiam, which bought the facility just three months ago.
The fast-growing optics and photonics firm II-VI is set for further expansion, with the acquisition of a large compound semiconductor wafer fabrication facility in the north of England.
Pittsburgh-headquartered II-VI announced that it had purchased the 300,000 square foot site, a third of which is a clean room suitable for epiwafer production, from current owner Kaiam for $80 million. It comes just three months after Kaiam had itself acquired the facility from previous owner Compound Photonics.
Capacity grab
The Newton Aycliffe site, originally built by Fujitsu to make memory chips but in fact used mostly by subsequent owners to produce gallium arsenide (GaAs) RF devices for mobile phone power amplifiers, will give II-VI potentially enormous additional capacity for making vertical-cavity surface-emitting lasers (VCSELs).
http://optics.org/news/8/8/10
Finisar buys wafer fab to ramp VCSEL arrays for 3D sensing - Dec 2017
700,000 square-foot facility in Sherman, Texas, will host 6-inch VCSEL wafer production, with CEO Jerry Rawls expecting ‘gigantic’ future demand.
Optoelectronics company Finisar is to expand its VCSEL production capacity dramatically next year, with more than $100 million of investment earmarked for a 6-inch wafer production fab in Sherman, Texas.
http://optics.org/news/8/12/14
That Texas fab is to produce VCSELs. It even says it in the report.
"The CEO added: “In the second half of calendar year 2018, we expect this facility will allow us to produce VCSEL arrays using 6-inch wafers for both consumer and automotive applications.” The company’s fab in Allen produces VCSEL devices on a 4-inch wafer platform."
Who supplies Finisar's wafers (or wafer platform as they also describe it)? Don't know and I doubt they'd tell me.
IQE sell wafers. They sell blank wafers to WinSemi. WinSemi are a fab who use those blank wafers to produce VCSELs to designs by Lumentum.
IQE and Finisar are completely different businesses.
Re IQE (LON:IQE), their competitor Finisair is being acquired by II-VI
"II-VI Incorporated to Acquire Finisar, Creating Transformative Strategic Combination with Leading Positions in Photonics and Compound Semiconductors"
http://investor.finisar.com/news-releases/news-release-details/ii-vi-incorporated-acquire-finisar-creating-transformative?_ga=2.87297567.640372077.1542184863-125073114.1542184863
IQE (LON:IQE) does not compete with Finisar, since Finisar does not make wafers. They are much higher up the value chain than that. The nearest competitor to Finisar, that IQE (LON:IQE) (eventually) sells to, is probably Lumentum. Though Finisar is a bit more vertically integrated than Lumentum.
(No position in any of the stocks mentioned, though I do work for a company where we have some products where we compete with Finisar)
Paul: I think the reason for the very low tax charge at Ideagen is the "Enhanced R&D Tax Credit".
Iqe had a sudden fall at approx 4pm. Maybe a big seller. When an institution wants out it will sell at almost any price. I think the ship is sinking myself
Hi Paul.
Interested in your view of the £Tracsis results of last week.
Regards
Orchard Funding (LON:ORCH) (I hold) has reported final results today in a commendably comprehensive RNS.
As a financial microcap it is not part of the SCVR remit but others here may find it of interest.
Before noting a few highlights I would point to the strange position of the Stockrank which - ranked against its European peers - shows as a lowly 31 with a classification as a "Momentum trap". For a stock that has gently declined over the last year and now exists on a modest 12.6 p/e this is hard to figure out. But wait - there's more!
If you change the ranking to rank it against its "Global Peers" than the SR shoots up to a fairly respectable 51 and it is now a sober "Style Neutral"
But wait - there's more!
It is part of the the James Montier Unholy Trinity screen for short selling. I am going to go out on a limb and suggest this is plain bonkers.
Orchard has grown its Revenue (13.4%) and Profit after Tax (12.7%), raised its dividend payout for the year (again) to give a yield of over 3.5%.
Its future includes lower cost borrowing after it gets a banking licence and plenty of headroom in a niche market for insurance premium lending despite two large players in the market.
Bad debt is low, as is debt concentration. The term of the loans is short (mostly 9 months) so rate rises will not leave them unmatched for long.
The RNS gives many other things to consider but the tone is of a company well managed, not carried away by the excess enthusiasm which sometimes affects finance companies, and with a credible long term vision of steady growth.
I may like this company too much so I would appreciate any other thoughts here that might give an alternative view.
How was the gym yesterday Paul? I hope your only bicep curl wasn't picking up a pint at the pub on the way!
Thanks for you comments Paul on IQE (LON:IQE). I sold out this morning and should have done so back in October when I could have booked a 50% profit in 3 months, rather than topping up near the peak. I sold out this morning, with the loss having cost me 1.85% of my portfolio.
I should have sold out earlier but I was guilty of being a rabbit. I was fortunate to have just watched Leon Boros’s presentatio at Mello Derby in March, where he talked about the book “The Art of Execution” (which I had read), and reminded the audience that if a share price drops significantly (and probably if it rises significantly), one must do something and not be a rabbit!
I can highly recommend the book and Boros’s presentation (bizarrely it has only had 324 views):
https://youtu.be/xGj3pF3r1bo
Those institutions that took part in the IQE (LON:IQE) placing at £1.40 must be sobbing loudly, I imagine!
It wasn't their money though!
I expect they may be sobbing over a reduced bonus, but not as much as the fundholders who are the ones nursing the loss.
I'm sobbing a little myself, but at least I could get out of my tiny position.
It was a punt for me, and it kicked me back.
Happy to see N Brown (LON:BWNG) in the header. Today's RNS news that the preliminary ruling on the VAT reclaim (net, an extra £6Mn pa to pay on the tax bill!) is not good, being around 10% of current annual profit. However, it will at least draw a line under the issue, closing out another uncertainty/legacy issue. Only a final exceptionals/ writedown on the weaker secondary/traditional brands should then be left for the acting CEO to deliver in the finals. Perhaps that's why the share are only down 2-3% today
Putting on my optimistic tin hat (or is it deaf to bad news ear mufflers), the value in the online power brands and supporting credit business should then start to come through in 2019, giving a new CEO the chance to declare a successful turnaround in next years finals.....so only 18 months to wait then!
Trifast (LON:TRI) half-year out today.. steadily-growing high-quality name that has recently been de-rated a little bit. would be interested to hear thoughts - its a name that's appeared here in the past
Another vote for Trifast (LON:TRI), dull business with interesting prospects - not sure if it is yet in "value" territory, but it has a good record over the past five years.
Good Morning Paul, any chance you could cover IBPO, good trading update from them this morning.
Re IQE (LON:IQE) this Bloomberg article makes a good point. As iPhone volumes peak, Apple has a Plan B in its services business, but Apple’s suppliers don’t.
https://www.bloomberg.com/news/articles/2018-11-13/apple-has-a-plan-b-as-iphone-demand-peaks-many-suppliers-don-t?srnd=premium-europe
Yes but this is utter twaddle in the case of IQE (LON:IQE)
They have spent the year qualifying with 25 OEMs and own 90% of the entire market in these wafers.
Apple, whilst a brilliant brand (I love em), make up a very small proportion of mobile and other device units globally. The size of the "other" plan B market for IQE (LON:IQE) dwarfs anything Apple throw into the mix. The reality is just that they were the first ones ramping up and overstocked and everyone loves an Apple supplier story......up and down!
The company actually spent this year building capacity to service the industry so profits will be lower anyway as Capex was higher and a chunk of this doesn't get amortised. Time spent on OEM certification also costly but only gets done once/
Making these wafers is pretty hard to do and even if you do produce them the level of efficiency/performance is absolutely critical to suppliers. A decent size moat to retain a good market share.
The future use for these wafers and projected market size over next 10 years is huge and has many likely uses over and above smartphones. That said their wireless business is growing at 10% p/a+ at the moment and is twice the size of the photonics business. That's why you see 25% EPS reductions.
With this share I've said all along that 2019 is actually the critical year. This is when the company should see 40% photonics growth that is less lumpy, more diversified and with similar growth levels predicted for 2020 and 2021. If that proves to be the case then the shares will trade a lot higher.
Lumentum's announcement yesterday didn't help and proved a boon to the ultra large short community. Would have been far better if they had met expectations for the year of course. That goes without saying. So at the moment 60-80p range feels about right to me until they show the expected diversified growth levels in 2019. But IQE (LON:IQE) are not dependent on ever increasing iPhone volume growth for this.
I agree with that David.
From the discourse one would think that Apple are critical to IQE (LON:IQE) success. As you have clearly outlined that is not the case for the VCSEL market and additionally they have other potentially large and growing markets such as 5G communications supporting their future prospects.
So, if one is looking very short term through the lens of Apple, then the picture is not great. However, if one is looking long term at the whole picture the future is bright.
Hi Paul
Will you be covering Flybe H1 Results tomorrow. Market Cap £23million?. My worst investment ever.
Your Reports and Grahams are a must read for me every day. Thank you .
Morning Paul
Would appreciate your thoughts on AdEPT Technology (LON:ADT) interims and trading update from TT electronics (LON:TTG). Both appear to be performing well and have in my view undemanding investment metrics going forward.
Positive interims from AdEPT Technology (LON:ADT), although debt is starting to creep up. Still unlike some companies the acquisition strategy is funded and debt controlled by profits and good cash conversion. The CEO, Ian Fishwick has shown himself adept (no pun intended) in managing the acquisition strategy and merits investor confidence.
Richard Tyson, CEO at TT electronics (LON:TTG) is overseeing a step change in the performance of the company that is reflected in the recent interims and this morning's trading update.
All the best
Sometimes we get companies issuing a profits warning RNS during the trading day apparently following a board meeting that considered poor operational numbers that had been building for weeks or months. I agree that this is completely unacceptable. If board members can't trust themselves not to leak the information while the market is open then it is easy enough to schedule such meetings so they do (or can be delayed to) finish after 16:30.
However in IQE (LON:IQE) 's case the share price had already responded to news from the US a couple of hours before. Any close watcher of the share would have been alerted to this share price movement and discovered the cause by around 14:00. The board cannot be blamed for news coming out of the US within UK market hours, and it is then a matter of judgement about whether they could add anything meaningful before the UK market closed. I understand usual practice would be to get advice from the Nomad and also that this process could have caused it to be delayed so close to the end of the day.
I don't like the dynamics of IQE (LON:IQE) 's business. I don't like the lack of focus from directors on hard financials (cashflow and real profits rather than EBITDA, turnover and "machines"). I am biased against academics running businesses (and perhaps in general). I (amongst many others) don't like the heavy reliance on Apple which we knew would result something like this sooner or later.
Yet I am impressed by this morning's statement. It provides an impressive amount of detail under the circumstances and shows an understanding of and commitment to shareholders. Clearly there was a late night / early morning and lots of hard work involved. There are also several genuine positives particularly around diversity of customers. It is quite easy to imagine that the ongoing delays in photonics ramp up followed by this further setback will result in a more solid, diverse base for growth than would have been the case if everything had gone to plan.
They have cut revenue estimates by just 10% from previous forecasts and EBITDA below last year's. This was already forecast to be a weak year. If they were somehow worth 94p yesterday morning then I strongly believe they must be worth more than 67p this morning, implying a jump not a further fall at the open. Unfortunately I don't think they were worth 94p yesterday - looking at the figures I think 50p was about right then and 45p now.
(not currently a holder)
Hi Leoleo73 - Re. IQE (LON:IQE) I am puzzled by the share price moving ahead this morning following the RNS details provided today.
The relevant numbers to me are : revenues now expected to be down 10% ;
adj EBITDA down to 31m from 37.1m. Broker forecast EBITDA for FY18 till yesterday was £44.5m
Broker forecast FY18 adj eps yesterday was 3.47p.
So back of envelope calculations tell me adj eps forecast must drop to range 2.4p- 2.7p, say 2.5p
The shares were trading on a prospective PE of 28 (much higher than the sector mean). This profit warning must take it down a peg of two, say 25.
The implied sp today is therefore approximately 2.5p * 25 = 62p . Personally I would start considering a trading position around 55p,
The sp as i write is hovering around 70p. IMO too high given the circumstances.
IQE's profits are likely to be down this year following Apple's pause in purchasing VCSELs, because sales of iPhones have been lower than Apple had hoped. However, over the longer term there is still likely to be strong growth in demand for IQE's VCSEL wafers for the following reasons:
(1) Models of Android phones currently under development from many mobile phone manufacturers are expected to contain VCSELs for face recognition, in order to compete with that feature in the latest iPhones.
(2) The next generation of iPhones is expected to contain a "world facing" 3D depth camera (which can be used for Augmented reality). This will probably contain a VCSEL array of much greater power output than that used for face recognition.
Hi Ramridge,
The rise in price in IQE this morning, may, in part, have been due to shorters buying the shares back to close their position (or part of), to take profit. As it is is a heavily shorted stock.
Be interesting to see where the price goes from 70p.
Hi ramridge,
I have actually been looking at the EBITDA forecast of £IQE in much the same way and if anything I think you are being a bit generous.
The only forecast I can put my hands on is from Edison and dates back to January.
Even though it is an old one, it was already below the latest concencus in terms of eps at least.
So assuming this is actually a like for like comparison we are looking at a revenue miss of £16m and an EBITDA miss of £13.5m.
I cannot think of any reason that the whole of that £13.5m doesn't drop straight through to PBT so unless I've got something badly wrong that looks like PBT of c. £16.6m and an EPS well South of 2p.
Just joining the dots, but I'm guessing that no only are they bearing all of the costs of the previously expected orders, they are also having to write off/down some of the stock.
So whilst I would still take the view that the medium term outlook here is probably little changed and that the 2018 numbers are probably not what the share price should be based on I am not convinced that the market has yet fully comprehended the scale of the 2018 profit miss.
On this basis, although I had been steadily buying back in here (having sold a chunk earlier in the year) I have cut that position now and will continue to watch from the sidelines for now.
They have now warned us of the bad news to come in the results, but there is imho potential for further negative reaction once they deliver that bad news.
Gromley
IQE (LON:IQE)
There are some other forecast numbers from PH and Stifel in the linked FT Alphaville blog (at 11:33) if your interested:-
https://ftalphaville.ft.com/marketslive/2018-11-13/
Not considering getting back in here until at least Dec TU or more likely year-end results (I think the adjustments to statutory profits may be eye-watering).
Phil
Thanks Phil,
So PH detail there only reiterates what IQE said, the Stifel view is curious though, they reduce their EPS forecasts by 22% this year and 25% next year.
That makes no sense to me , the EBITDA numbers above indicate a much larger decrease this year, but I would expect next year to be less impacted as customer concentration should decrease and presumably Apple will no longer have surplus inventory.
I agree with you though, I've no desire to be involved here now this side of the results.
The other thing I've noticed today (I'm pretty UK blinkered) is £LITE (hope that works) which you can have limited info about from Stockopedia - looks a better bet.
Definately one to watch from the sidelines at the moment IMO.
Have fun. Phil
Edit: It didn't work - just put Lumentum in the search.
Just a further note on IQE (LON:IQE) Edison have now issued an update they concurr with my view that the EBITDA miss drops straight to the bottom line ( there was no logical reason to assume otherwise)
They drop their forecast for 2019 by a lesser amount, which I also agree with.
This gives a potentially attractive looking forward PE of 16x, however I think that IQE (LON:IQE) will need to actually deliver those numbers before the market believes them.
Positive trading update from Ideagen (LON:IDEA) this morning : The Board is pleased to report that trading has remained strong in the first half of the financial year and that revenue and EBITDA are both expected to be significantly ahead of the same period last year and in line with management's expectations. This has been achieved through both organic revenue growth and the acquisitions of Medforce (acquired in April), InspectionXpert and MK Insight
I am interested in continued coverage of the IQE (LON:IQE) saga (I topped up just before the infamous and unnecessary RNS) but perhaps later Paul will get the chance to comment on £G4M 's ambitious share options policy: seems to be long term and based on not just sp but other criteria: https://www.investegate.co.uk/gear4music--g4m-/rns/new-long-term-incentive-plan/201811130700091183H/ on first glance I approve (small long.)
Good morning, runthejoules,
Re the G4M B shares scheme announced today - I like stretch targets for entrepreneurial companies, based on achieving a multibagger share price, over the long term. This can be a key way to lock in talented management. I see this type of arrangement as being far more justified at small companies, where the key people really are the business. That's very different to top management at large companies like Persimmon (LON:PSN) where their main job is to not do anything stupid, and the business is actually run by the middle management, and performance is often related more to the economic cycle than anything management do or don't do.
I'm perplexed as to why the G4M scheme is so small - it seems to only be for about 1% of the company. I would have thought management deserve more, if they achieve the stupendous share price rises mentioned in today's RNS.
Regards, Paul.
I have to say I was impressed at what I saw as the sensible size of the £G4M scheme, worthwhile, but not outlandish rewards for doing their jobs well.
However, I was less impressed that the hurdles are 75% based on SP and 25% on fundamental performance. I would much prefer to see those switched.over. Rewards should be based primarily on real fundamental performance, not on SPs, which can be an invitation to manipulation.
Peter
Ideagen provided an encouraging trading update today. I would be interested to hear your view Paul.
My morning smallcap tweet:
Coral Products (LON:CRU), Cohort (LON:CHRT)
Coral Products (CRU) Wins £800k order.
Cohort (CHRT) wins orders for €11m and £3.2m over 2 years and 18 months respectively.
Can't see the sense of a 1620 RNS yesterday from IQE (LON:IQE) when this morning's is far more coherent. Paul's comments re suspending shares intra-day pending a profits warning RNS, makes even more sense in this context.
Arguably, IQE (LON:IQE) created a false market in their own shares for 10 minutes yesterday afternoon with their partial update, an issue that is addressed by this morning's RNS.
Cheers, Martin
Hi Martin.
Market in IQE (LON:IQE) was already “false” in that the shares were down at least 18% by mid afternoon (presumably a leak rather than just well informed “speculation”) so they were obliged to say something (although I agree it only fanned the flames and led to a further panic in last 10 minutes of the day). I agree with Paul, some form of mandatory suspension mechanism would seem fairer but devil in the detail of working out when and how it would apply.
Not close to the company figures, but at face value this morning’s release is either clever spin or suggests it’s not quite as dark as the tone of last night’s release suggested. Guess we’ll see at market open.
Gus.
Lumentum in the US (also an Apple supplier) gave the bad news about orders, so IQE were forced to follow suit as the tech supplier share prices reacted to the news.
In fairness I don't think there was any "leak" at IQE (LON:IQE) . There was a fairly obvious read across from the announcement made by Lumentum (IQE's direct customer in the supply chain).
It's quite amazing however that IQE appeared to hear about this news only at the same time as the rest of us, it doesn't strike me as being much fun being a supplier to Apple.
As to the numbers, a c. 10% reduction in revenues and knock on profit impact strikes me as being savage enough this late in the year. Probably not sufficient though to justify the scale of yesterday's fall, but sentiment is so fragile that it's hard to know what will happen this morning.
In the round, I don't see this as a major dent in the medium term story; dependence on the Apple supply chain (I think c. 20% of the business currently) is due to lessen over the short term.
More detailed RNS follow up this morning from IQE (LON:IQE) . Credit to them for getting some clarity (if we can trust the figures) out so promptly.
https://www.investegate.co.uk/iqe-plc--iqe-/gnw/trading-update-and-comment-on-vcsel-supply-chain/20181113070000H6202/
Gus.