Small Cap Value Report (Thu 4 Jan 2018) - DEB, SPE, CHH, CAMB, WGB, TAP, ENET, BHRD, CYAN

Good morning, it's Paul here.
Please see the article header for the companies whose trading updates I am covering today.
Debenhams (LON:DEB)
Share price: 28.9p (down 18.8% today)
No. shares: 1,227.8m
Market cap: £354.8m
Trading update - the department store group announces trading for the 17 weeks to 30 Dec 2017.
The problem with updates from retailers, is that too much emphasis is put on like-for-like ("LFL") sales. However, there is no consistency in how this measure is calculated - some include refurbished shops (e.g. Moss Bros (LON:MOSB) ) which I think is clearly incorrect. The whole point of refurbishing a shop is to increase sales, so it's not a LFL comparison once it's been refurbished. Other retailers merge retail sales and online sales in their LFL calculations, which muddies the water. Farcically, Mothercare (LON:MTC) even reports customers in-store ordering on one of their tablets as online sales!
For these reasons, I'm increasingly just focusing on forecast profit. After all, that takes into account everything - sales, gross margins, and costs. The guidance given today is as follows;
Looking ahead, should the current competitive and volatile environment continue into H2, FY2018 profit before tax is now likely to be in the range of 55m to 65m
To put this into context, timing-wise, FY2018 is the year to end-Aug 2018.
Broker updates - I've got several in my inbox this morning. To give a flavour, one has reduced its PBT forecast from £79.0m to £55.4m - a reduction of 30%.
The key thing is to consider that this is based on forecast revenues of almost £3bn. So Debenhams profit margin is wafer thin, at about 1.8%. What that means, is that only a small further deterioration in sales & gross margins could easily tip the company into losses, and possible insolvency (if shareholders refuse to refinance it).
More details from today's RNS;
- Digital sales are up 9.9%, giving 2 year growth of 22%. So optimists might latch onto the possibility of Debs transforming itself into an eCommerce company with some big stores also acting as warehouses. The new CEO is ex-Amazon, so who knows what might happen in this area?
- UK LFL sales down 2.6% in the 17 weeks to 30 Dec 2017. The basis on which this figure is calculated is not explained - does it include digital and stores, or just stores?
- Gross margin in H1 is down 150 bps, which is a lot in cash terms - annualised, that's about £45m less profit on £3bn revenues. The problem seems to be that Debs is having to do price promotions to drive sales - not good.
- Cost savings of an additional £10m over previous guidance have been found, with another £10m in future years. As with all retailers, costs are rising (especially wages, and imported goods), but revenue & gross margin are falling. That's a really toxic combination.
My opinion - I agree with the bearish consensus on Debenhams. It's being squeezed from all directions, and is only marginally profitable now. Therefore, the most likely outcome seems to be a continuing deterioration in profitability, possibly moving into losses next year & beyond.
To survive, let alone prosper, I think retailers need cost flexibility, as mentioned in yesterday's section on Next (LON:NXT) . Next has short leases, which means that any loss-making stores are only a temporary problem, with renegotiated rents now only costing it 5% of revenues (previously 7%) - a very low level. To preserve profits, the rents have to come down, for almost all retailers. Apparently Debs has long leases, and the conventional lease structure in the UK is for upward-only rent reviews. Therefore, I think its leases could potentially bring down the whole company, and force it into a CVA in future, perhaps?
Forex is another key question mark over Debs. I recall that it had very long forex hedges, resulting in favourable cost prices for product. These favourable forex hedges (at pre-Brexit vote levels of £:$) are expiring in 2018. That could mean further gross margin pressure in 2018, as more expensive product begins to flow through.
Overall then, I feel the bears have probably called this right, and we could be witnessing the beginning of the end for Debenhams, perhaps? Upside potential could possibly come from something transformational happening, but it's difficult to see what. The trouble with department stores, is that they're so big, the ongoing capex spend is massive, and relentless. To transform performance often requires a very expensive refit. I don't think Debs has the financial firepower to do that, and its balance sheet overall looks weak.
So overall, I can't see anything positive here - it looks doomed to eventual failure.
EDIT: I would also treat the big dividends as being past their sell-by date. A dividend cut (possibly to zero) now looks inevitable. The company cannot afford to keep paying out big divis as well as refurbishing its stores.
Sopheon (LON:SPE)
Share price: 440p (up 21.6% today at 10:31)
No. shares: 10.0m
Market cap: £44.0m
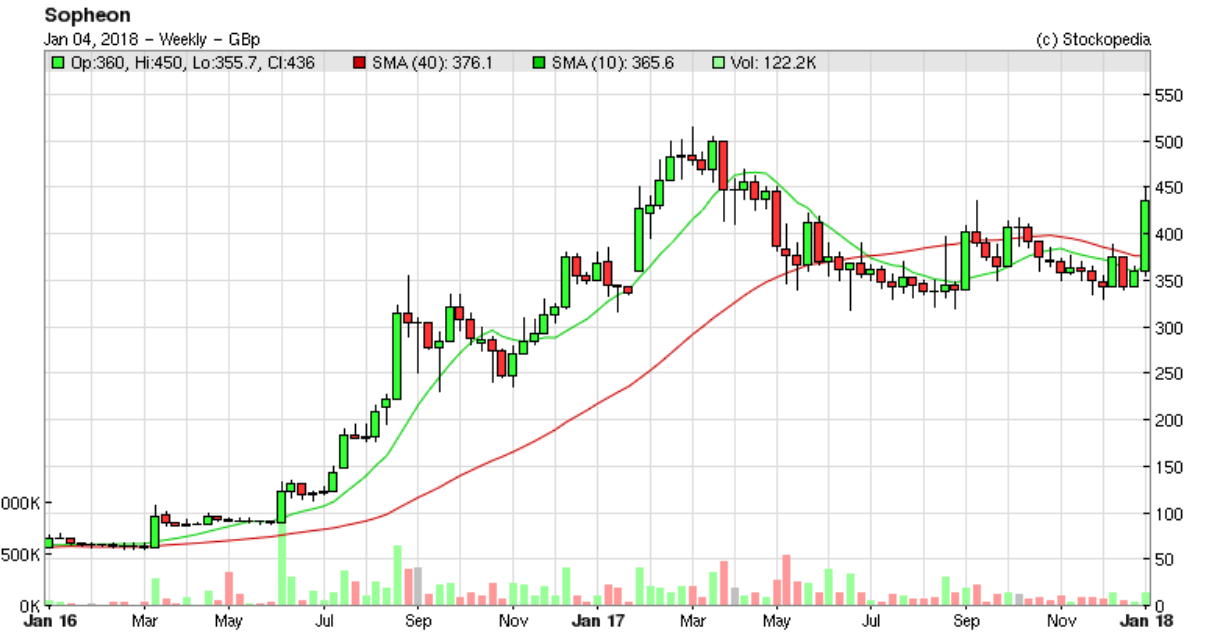
Sopheon, the international provider of software, expertise, and best practices for Enterprise Innovation Performance, is pleased to announce an initial indication of the Group's performance in 2017.
Today's update will have resulted in lots of happy shareholders, including a friend of mine who has been nagging me for ages to buy some of these shares! I tried, but it was so illiquid that I couldn't get any, unfortunately.
Anyway, the company is performing well, and has a positive outlook;
In our interim report issued on 24 August 2017, we highlighted continued building of momentum and enhanced market recognition of the Company's product set. We are pleased to report that this has again translated into solid growth, with particular strength in the closing quarter of the year.
As a consequence, early indications are that revenues, EBITDA and pre-tax profits for the year ended 31 December 2017 will all exceed market expectations.
In addition, we expect improved recurring revenue and visibility into 2018.
Capital structure - an important point to note is that the company normalised its capital structure in Dec 2017. So the 10.0m shares in issue shown above, is no longer subject to dilution from loan stock which has now coverted into share. So that problem is solved. However, bear in mind that the EPS calculations for 2017 will use a weighted average number of shares in issue, hence will overstate ongoing EPS. Therefore this issue still needs careful checking, when looking at EPS calculations & forecasts.
Another issue to consider is how you treat the company's brought forward tax losses. Personally I like to normalise the tax charge, to avoid over-paying for any share.
Note also that the company reports in US dollars.
My opinion - the company sounds like it's on a roll - this is a good update today.
I'd like to get properly stuck into the figures, which are due out on 22 Mar 2018. It's difficult to work out the valuation & upside potential, with very little research available on the company.
So for now, I'll park this one to one side, even if that means potentially missing out on any further possible share price appreciation.
Churchill China (LON:CHH)
Share price: 1240p (up 9.3% today, at 11:31)
No. shares: 10.96m
Market cap: £135.9m
Churchill China plc (AIM: CHH), the manufacturer and distributor of performance ceramic and related products to hospitality and retail markets worldwide, is pleased to announce the following trading update for the year to 31 December 2017.
I hadn't noticed what a terrific run this share has had, since the dip in Nov 2017;
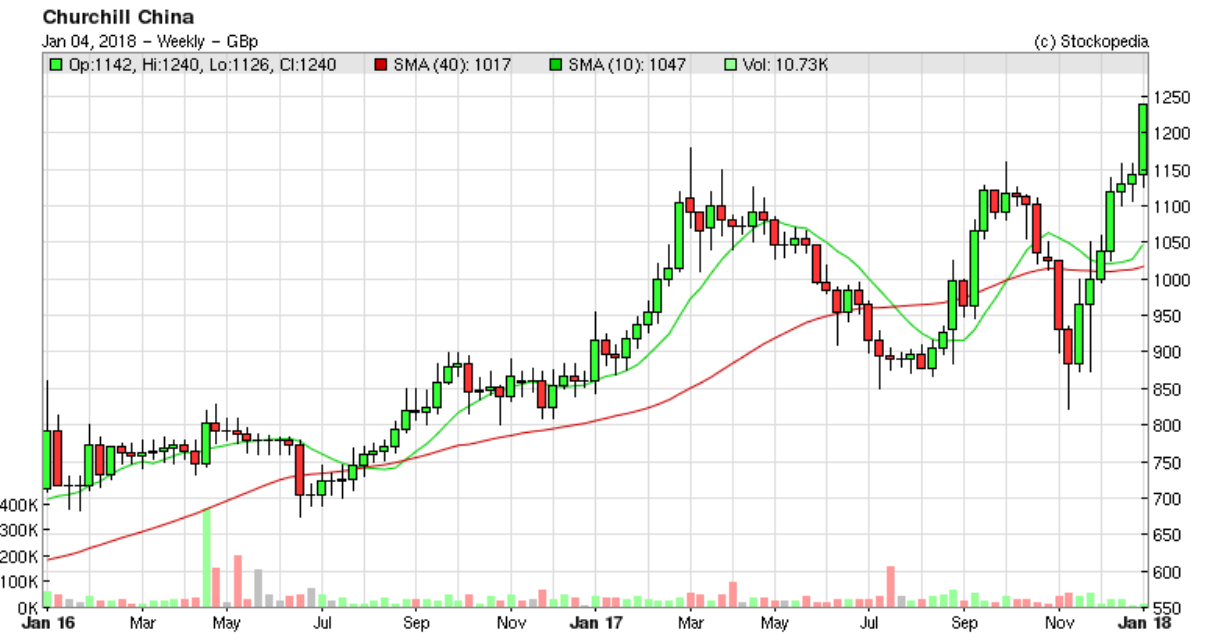
Given that there had already been such a big move upwards, I'm a little surprised that today's slightly ahead update has pushed it up another 9.3% today.
We have continued to make solid progress against our long term objectives throughout 2017. Revenue growth has again been good in export markets. As a result the Board now expects that operating performance will be slightly ahead of current market estimates. Additionally, cash and deposit balances are also expected to exceed current market expectations.
Valuation - I see that one broker has slightly raised its 2017 EPS forecast to 55.8p. That equates to a PER of 22.2 times - quite a rich rating, given that only modest increases in profitability are forecast for 2018 and 2019.
My opinion - this is a good company, in my view - excellent products, innovative, and selling well into Europe, aided by weak sterling. It also has a strong balance sheet, with net cash. Note there is a pension deficit too, but it's not excessive.
In my view the price seems up with events, so I wouldn't be interested in buying at this level.
Cambria Automobiles (LON:CAMB)
Share price: 60.5p (down 0.8% today at 11:47)
No. shares: 100.0m
Market cap: £60.5m
AGM trading update - and franchising developments.
This is a group of car dealerships. It has a 31 Aug year end, so is today updating us on trading in Sep-Nov 2017.
The Group's trading performance in the first three months of the current financial year has been in line with the Board's expectations, albeit behind the corresponding period in 2016/17, both on a total and like-for-like basis. This trading performance in the first quarter continues the trend highlighted in the Group's preliminary results on 22 November 2017 and means that the Group is trading in line with market expectations for the full year.
Other points in today's update seem to be consistent with existing trends - i.e. tough new car market, mitigated by reasonable performance from used cars & aftersales;
New car sales down 14.4% on an LFL basis. Gross profit per unit also down - sounds a nasty combination.
Used vehicle sales down 2.8% on an LFL basis. Improvement in gross profit per unit.
Aftersales - LFL profitability up 5.9%.
Outlook - it's interesting that the group seems to be focusing more on the luxury car market;
The Board remains cautious about the new car market in light of the general uncertainty in the consumer environment and the pressure that vehicle manufacturers are under as a result of the current Sterling exchange rate.
Nevertheless, the franchising progress that has been made through 2017 and into 2018 has further enhanced the Group's excellent portfolio of dealerships and leaves the business well positioned with strong representation in the high luxury segment of motor retail.
Valuation - this whole sector looks dirt cheap at the moment, so it's a good hunting ground for value investors. It all depends what view investors hold about the future. There are some amazing deals around on secondhand cars, and new cars are now mostly sold on cheap personal leases. There's considerable uncertainty now about the future of diesel, with electric cars starting to creep into the market. So considerable changes are happening. What that holds for the dealers, who knows? They might adapt, or become extinct in the long-run, I have no idea - few people accurately predict the longer-term future.
Given that all car dealers can be had on a low PER, then I think focusing on balance sheet strength is very important, particularly freehold property assets, which might have good alternative use value. There might be consolidation in the sector, with takeover bids at some point?
My approach is to stay away, and buy on any plunges. So I picked up some Pendragon (LON:PDG) at 22p last year, and have a nice profit on that now. Similarly, I'm inclined to watch on the sidelines, and try to repeat that process - by buying shares in any other financially strong dealerships which also spike down on negative trading updates. Most in this sector look to be much of a muchness, although I like Vertu Motors (LON:VTU) in particular for its balance sheet (don't currently hold any, but am considering a purchase).
Walker Greenbank (LON:WGB)
Share price: 140p (down 2.1% today)
No. shares: 70.9m
Market cap: £99.3m
(at the time of writing, I hold a long position in this share)
Walker GreenbankPLC(AIM: WGB), the luxury interior furnishings group,provides an update following the announcement on 6 December 2017 regarding a machine fire at the Company's Loughborough wallpaper factory, Anstey Wallpaper Company.
A "minor fire" damaged one of 6 wallpaper printing machines in their factory. The company previously said that the maximum impact on profits in y/e 01/2018 would be £0.5m. That figure is reiterated today;
As previously announced, the maximum potential impact on profitability in the current financial year is expected to be less than 0.5m.
The repair to the embossing machine, and fire damage to a small amount of stock, is covered by the Company's comprehensive insurance policy.
It doesn't mention business interruption insurance, so I'm not sure if that is covered too - since some orders have been delayed into the new year (not quantified). EDIT: broker coverage suggests there will be no loss of profit, just a deferral into the new financial year.
No other information is given in today's update, therefore I assume we must be in line with revised guidance given after the profit warning which I covered here on 15 Nov 2017.
Valuation - helpfully, there's an updated note today from a high quality broker, available on Research Tree. Adjusted, fully diluted EPS forecasts are as follows;
y/e 01/2018 13.6p giving a PER of 10.3
y/e 01/2019 15.3p giving a PER 9.2
That seems a very modest rating for what remains a good quality business, operating in a profitable niche.
My opinion - I've always quite liked this business, but most of the time it has looked too expensive for me. Therefore, I used the profit warning last autumn as an opportunity to buy. I just waited a few days for the share price to stop falling, then picked up some stock at 123p, which for once was nicely timed. It's recovered about 14% since then.
The big question is whether the profit warning was just a blip (said to be due to subdued demand in the UK, but not overseas). Or, whether there's something bigger going wrong, e.g. products going out of fashion, or not price competitive?
On balance, I'm prepared to give it the benefit of the doubt, because the forecast PER is now very low, and it has a sound balance sheet, plus should continue to pay a reasonable dividend yield of about 3.3%.
The joker in the pack is the potential for an overseas takeover bid. Prestige British brands are attractive to Americans in particular, and US companies on high ratings arguably need to buy in growth to justify those ratings. So I foresee the possibility of Walker Greenbank (LON:WGB) and possibly Portmeirion (LON:PMP) (both of which I hold personally) becoming bid targets at some stage, maybe, who knows?
I always sense-check my views against the StockRanks. In this case the Stockopedia computers are not convinced, as you can see below, with a poor momentum score dragging down the overall rating;
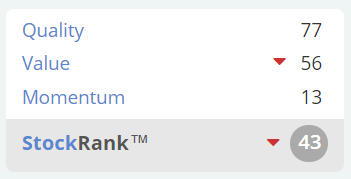
In this case I'm prepared to ignore the low StockRank, as I believe that momentum could return, if trading stabilises. Although a low StockRank will usually act as a brake on the position size I'm prepared to apply to a purchase. So in this case, I only bought a fairly standard sized position in it, and probably won't increase that unless & until current trading has improved.
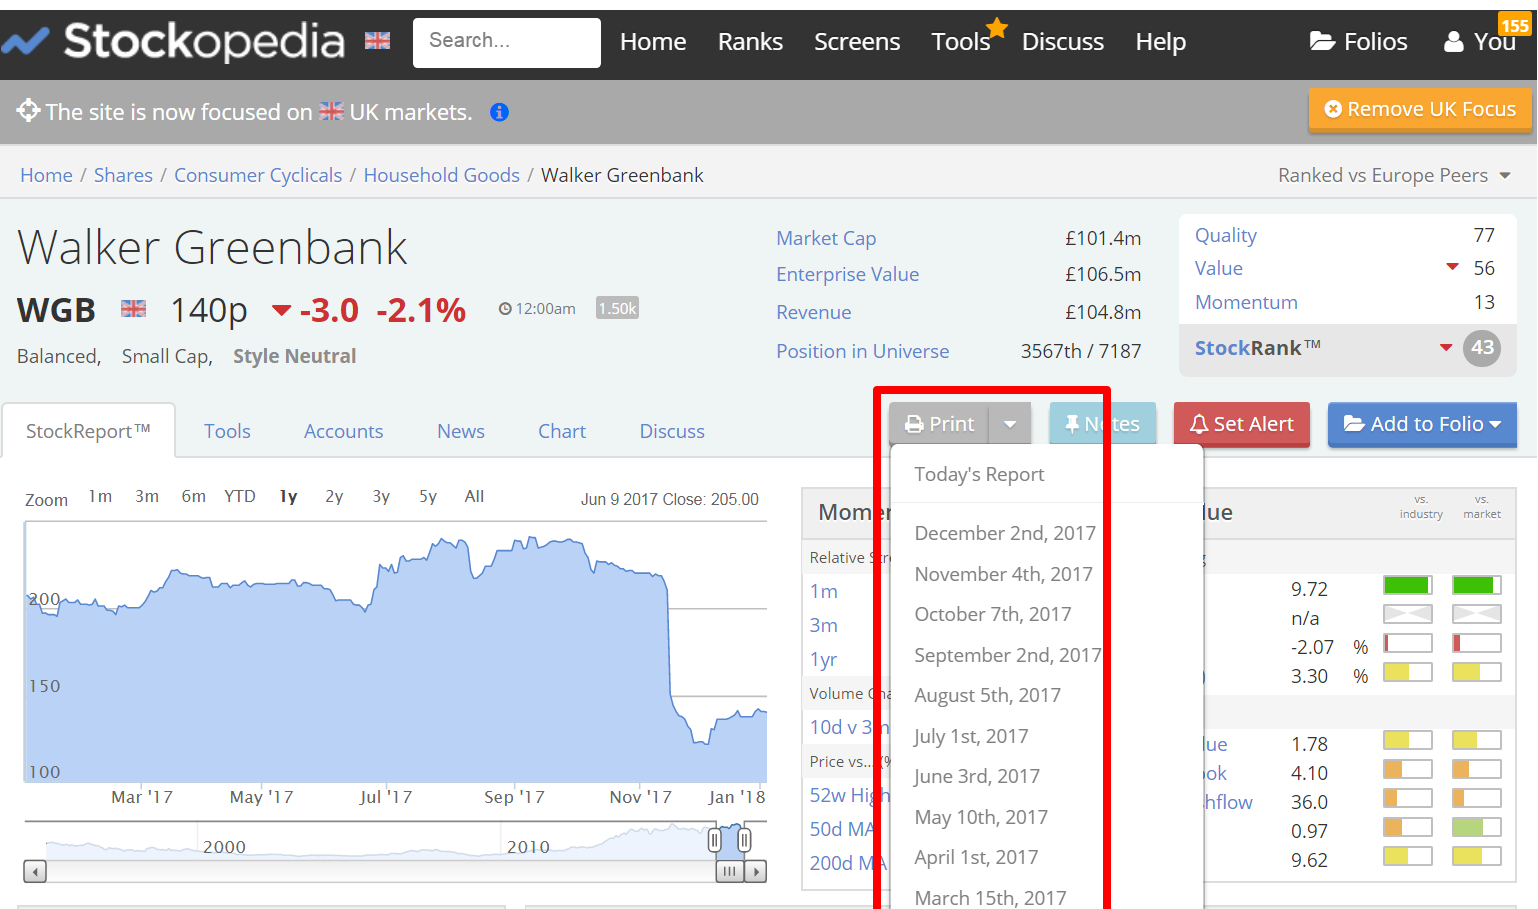
The StockRank was 69 immediately before the profit warning. You can check historic StockReports by clicking on the "Print" button - this then gives you a drop-down menu of historic data to choose from, which is very useful I find;
It's also interesting to note (from chart no.4 below) that in the last few years this share was given a much higher PER by the market (before the profit warning). Therefore I see a potential opportunity here for the multiple to expand back up again, if confidence in the company returns.
Taptica International (LON:TAP)
Share price: 490p (up 5.4% today)
No. shares: 62.4m
Market cap: £305.8m
Taptica (AIM: TAP), a global end-to-end mobile advertising platform for advertising agencies and brands, provides the following update on trading for the year to 31 December 2017.
The key part of today's announcement says;
... the Company expects to report adjusted EBITDA for FY 2017 ahead of market expectations and revenue broadly in line with market expectations demonstrating a higher-than-expected EBITDA margin.
The Company remains confident of delivering solid year-on-year EBITDA growth for 2018 in line with market expectations.
So, revenues a bit below, but EBITDA ahead. That sounds OK, providing you're happy with EBITDA. What a pity the company couldn't stick to proper metrics, like profit before or after tax, EPS, etc. It's such a nuisance when companies report on EBITDA, because that then forces investors to check the accounts, to make sure that EBITDA is a safe figure to rely on. The trouble is that, very often with tech companies, EBITDA is not a safe figure to rely on (due to often excessive capitalisation of costs into intangible assets).
Having checked the last interim results, I'm pleased to say that Taptica seems to capitalise very little development spend - only $555k in H1.
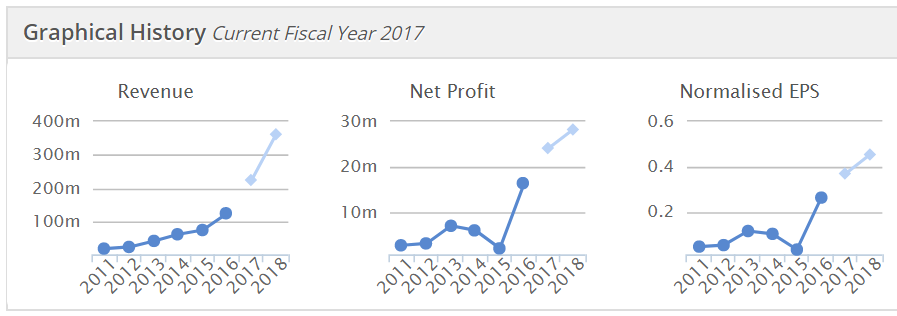
So the cashflows look real to me. The company seems to be using its healthy cashflows to pay modest divis, and make further acquisitions. The track record of growth looks stunningly good, with particularly impressive growth kicking in from 2015 onwards;
Valuation - is modest, because I think the market doesn't generally trust overseas AIM stocks, especially where many investors won't necessarily understand how the company generates its profit & growth (I'd put myself in that category).
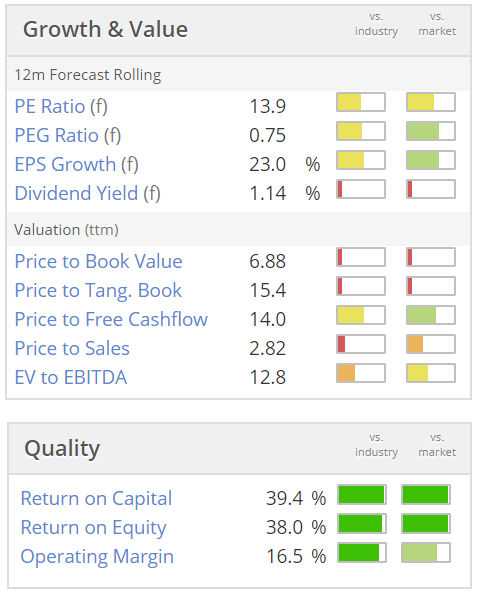
However, if you do understand the business model, and are happy with it, and if you think profits & growth are sustainable, then this share is cheap. Here's last night's growth & value data - which seems to be showing a growth company priced like a value share;
Updated broker forecasts- FinnCap have upped their 2017 adjusted fully diluted forecast for 12/2017 from 36.0c to 40.7c (30p). So at the current share price of 490p, the 2017 PER is 16.3.
In terms of 2018 forecasts, FinnCap has pencilled in 43.3c, or 32p - giving a forward PER of 15.3.
Tremor Video DSP - this was a big, $50m, acquisition made in Aug 2017. This seems to have used the entire cash pile, plus required a $30m HSBC facility. In today's update Taptica makes positive noises about this big acquisition;
...Tremor Video DSP performed better than anticipated, including achieving profitability during 2017 rather than in 2018 as initially expected.
My opinion - I like the numbers, but won't be investing again because I don't understand the business model or sector. The meltdown in the ad tech sector a couple of years ago scared me away from this type of business, because innovations can turn business models upside down, and it's such a fast-moving sector. Good luck to holders though, so far so good - it's been nearly a 10-bagger in the last 2 years, so fantastic returns for those who backed it.
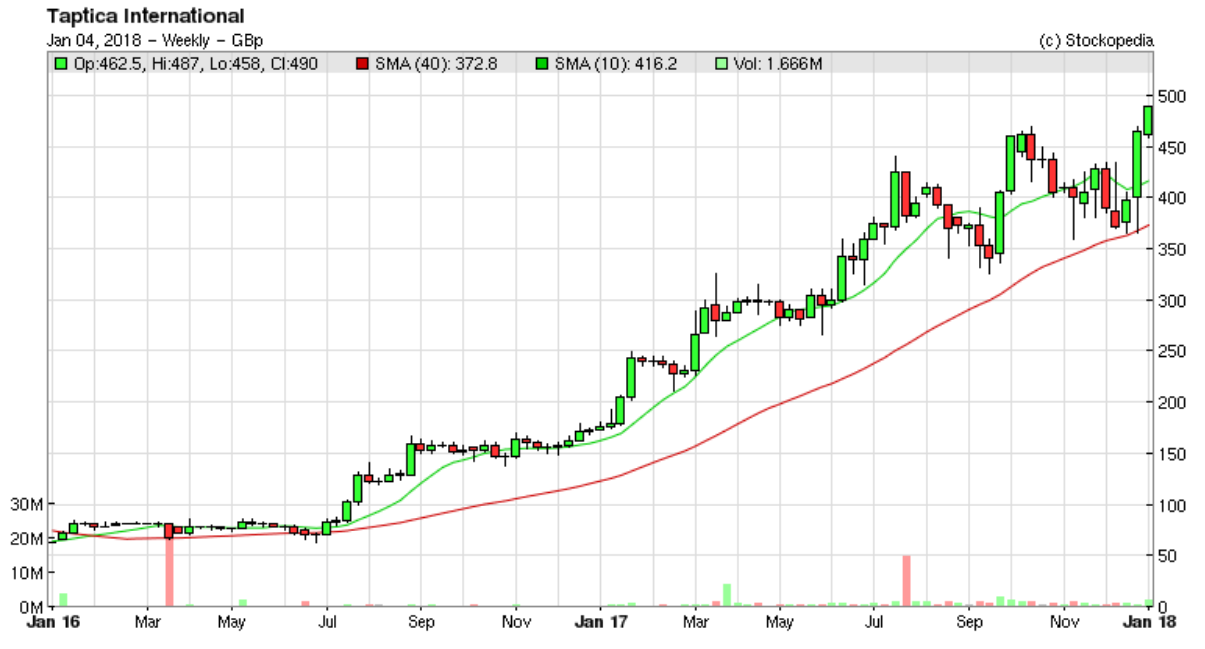
Note that the Stockopedia computers like the numbers too - a strong StockRank of 90.
Ethernity Networks (LON:ENET)
Share price: 80.8p (down 38.6% today)
No. shares: 32.5m
Market cap: £26.3m
Trading statement (profit warning)
Ethernity Networks (AIM:ENET),a technology solutions provider that develops network data processing technology used in high-end Carrier Ethernet applications, today provides the market with an update on trading for the year ended 31 December 2017.
This company only listed on 29 Jun 2017, and has today issued a profit warning, barely more than 6 months after floating. That's diabolical, and probably one of the worst things a company can do, in my view. If the numbers were in any doubt, it should not have floated. Let's have a look at the Admission Document, and see who floated it - it was Arden Partners. The placing price was 140p, so it's already lost 42% of its original price.
I'm having a quick skim through the Admission Document. A few points;
- The company is domiciled in Israel - higher risk, but a country which does have a strong track record in producing impressive technology companies.
- This is a very small company - revenues only c.$2.2m in 2014, 2015 & 2016.
- Reason for flotation is good - raising fresh funds for the company, and not cashing out existing holders. Increased profile & balance sheet strength were sought to impress potential customers - which makes sense.
- Pro forma balance sheet (see page 86 of Admission Document) is very strong, with nearly $17m in net cash.
- Some of placing proceeds are being used to increase R&D, and increase sales & marketing. So expect losses in the short term (it was modestly profitable prior to floating).
- Management remain substantial shareholders - plenty of skin in the game.
There are some quite good things in the bullet points above. What a pity then that the company has had to warn on profits.
Profit warning - what's gone wrong then? I find the RNS today rather too technical in terminology, but it seems to boil down to expected contract wins or renewals not happening by the end of 2017.
It doesn't sound too bad though;
As a result of the above, the Company anticipates that revenues and profits for the year ended 31 December 2017 will be below market expectations, however the Company has significantly increased operating profits when compared to the previous year...
For comparison purposes, the Admission Document (on page 37) shows $339k operating profit for 2016. I can't find any updated forecasts today, but Stockopedia is showing broker consensus of a forecast net (i.e. after tax) profit of $1.31m for 2017, and $3.22m for 2018. From the information we have available, it's impossible to quantify how big a miss is likely, but at a guess it looks as if 2017 profits might be only around half the forecast, if that. So a substantial miss, I'd say.
My opinion - I know absolutely nothing about this sector, so have no idea whether the company's business model is any good or not.
I do however like that the company has a big cash pile relative to its reduced market cap - that nicely underpins the valuation at some level (maybe below where it is right now).
It's overseas, AIM, is very illiquid, and just warned on profits though, so for me it's best avoided. People who understand the technology, and rate it highly, might disagree though. Do we have any techies in the house, who can give an informed view on the merits of this company's products? If people think the tech is good, then I might have a little punt on it - as the decent cash pile protects some of the downside risk, and means that there's no risk of dilution or insolvency. Also the company is still profitable, albeit at a lower level than planned. So it wouldn't be a ridiculous punt.
Be Heard (LON:BHRD)
Share price: 2.23p (down 22.1% today)
No. shares: 981.9m
Market cap: £21.9m
Trading update (profit warning) - and Board changes.
Be Heard, the digital marketing services group, announces a trading update for the year ending 31December 2017 and the evolution of its management structure.
I've only reported on this company once before, here on 2 Aug 2017. My conclusion then was that a horrible balance sheet made it uninvestable to me.
Here is today's profit warning;
Whilst annualised revenues and new business wins provide an excellent platform for 2018, profitability for 2017 is expected to be below market expectations due to a number of unexpected factors...
The factors explained in more detail are basically contract deferrals, and a reduction of activity, which occurred too late to be mitigated with cost savings. There was also a problem with cost overruns on a substantial contract.
Forecasts - there is an update from one broker on Research Tree, but they haven't yet changed any forecasts. So we're in the dark about the extent of the 2017 profit shortfall. That's not satisfactory, and means that it's currently impossible to value the share on its 2017 results.
2018 forecasts remain unchanged, with a big rise in profitability pencilled in, to £3.5m. I'm not sure how realistic that is now looking, given that the company has failed to achieve its £2.0m forecast profit for 2017.
My opinion - if the company had a sound balance sheet, then it might be worth a look, as it is generating impressive organic revenue growth, and has some big name client wins. However, for me its the underlying financial strength which is essential before I'll invest - i.e. a strong balance sheet. That is conspicuous by its absence here, hence I fear that at some stage this company will probably need to do a discounted placing, to repair its balance sheet. I wouldn't consider investing unless & until that has been done.
Water Intelligence (LON:WATR) - this was a reader request. However, it's not a trading update, and gives no information on performance against market expectations, so I can't meaningfully comment on it. Sorry about that.
Cyanconnode Holdings (LON:CYAN) - I've just seen what looks like a profit warning from this company which has been promising great things relating to smart meters. The shares are only down 5.5% today to 18.9p, but in my view things are looking very wobbly here.
It says that a contract delay means that 2017 revenues will only be £1.2m. Stockopedia shows broker consensus of £2.1m 2017 revenues, and a gigantic forecast net loss of -£9.4m.
The company says that it had an end of year order book of $100m, and a pipeline of $320m. I'll believe that when I see it turn into real revenues & profits.
It says net cash was £5.5m, with receipts of £1.3m from tax credits also due, and funds yet to be received from its Sep 2017 fundraising. It's not clear what proportion of that £8.6m fundraising has not yet been received. The trouble is, the company has prodigious cash burn, so it looks like yet another fundraising is going to be needed around spring/summer 2018. Will investors have the appetite to keep pouring in money? Who knows - it's a fundamental uncertainty that makes me want to steer clear. I don't mind having the occasional punt, but only when companies have plenty of cash in the bank (e.g. Ethernity Networks (LON:ENET) above)
This thing looks very high risk to me. I hate under-funded jam tomorrow situations like this, so wouldn't go near this one. Occasionally punters hit the jackpot with jam tomorrow shares, but the vast majority disappoint, and destroy shareholder value, in my experience.
All done for today! Graham will be looking after you tomorrow, as is usual on Fridays :-)
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
I think that focusing on where EV charging is going to be a problem risks missing an opportunity. Inevitably it is starting as a niche. But given the number of vehicles on the road it is a sizeable and growing niche.
Fret not about terraced houses or flats where people cannot park the vehicle for overnight charging, or rural areas where range becomes a problem because the places where it can work are more than sufficient to represent a large potential market.
That said, it doesn’t mean I would buy Tesla!
Paul,
Re: Ethernity Networks (LON:ENET). I'm familiar with the company and understand the market they operate in. I can vouch that this is a proper company with real products and customers - it categorically is not one of the dodgy overseas AIM companies we have seen down the years. Whether you believe it is investible is down to you, but one of the reasons I would stay clear is the nature of their customer base and it is unfortunate that this has been highlighted so soon after the IPO.
I know its bad form to warn so soon after listing, but I know from personal experience working with large Telcos that the reason for the delays leading to the warning was very likely completely unforeseeable 6 months ago. Short of working with government departments, I cannot think of anything worse than having large Telcos as your main customer base - these are the least efficient, most bureaucratic and slowest moving organisations known to man. Their internal management structures are appalling, their procurement processes prolonged and painful in the extreme for all concerned, and they are the slowest paying companies on earth.
All the best, Si
Monster job thanks Paul!
I notice that CAMB chairman just sold 1/3 of his shares citing house purchase. Not sure how far £57k goes in a house purchase these days, but not the vote of confidence we (holders!) are looking for.
Rgds
R
Warning possibly frivolous and ill-informed post.
I have to confess that I know nothing about Sopheon (LON:SPE) and I probably never will.
About a second in to reading Paul's write up of this company I recalled an article I wrote for Motley Fool (many years ago now) about a company that had a totally jargonisitc and ridiculous description of what they did. I cannot now recall what the company was or what it was they did (I think it might have been "marketing") .
As "luck" would have it that company went belly up within days of my write up and I became a hero in my own lunchtime.
So when I read from Paul's write up that Sopheon (LON:SPE) are a provider of :
for
I have lost track of the number of management meetings where we have concluded that we need to improve the innovation performance of our enterprise and that we need someone to sell us "best practises" , "expertise" and "software".
I have though not lost track of how much money businesses I have worked for have lost by engaging "expert consultants" who in fact know nothing - lets just say that if I had 10% of the savings that would have been made had my recommendations been followed then Dickie Branson would not own Necker Island.
So getting back on topic - life is way too short for me waste my time finding out anything more about this company.
My scepticism might prove 'costly' but hey I own no bitcoins either.
The point you make is not frivolous at all. I believe companies with management who cannot communicate who they are or what they do in a clear and concise way are harder to invest in. To my mind, if they can't do so with investors, they probably also struggle to be clear with their staff, market partners and even customers.
And when they use absurd hyperbole to describe their place in the world (look at the rubbish RhythmOne (LON:RTHM) spouts) when they are small or loss making, you have to ask yourself whether this lack of intellectual honesty raises questions about their trustworthiness.
If I have time this year, I might run an analysis of company RNS's and see if there is a correlation with share price performance.
Happy new year to all
Francis
So getting back on topic - life is way too short for me waste my time finding out anything more about this company.
Actually, I find this quite sad and is not what the ethos of the SCVR is about. One of the main attractions of Sopheon (LON:SPE) to me was that it is completely under the radar of everyone and experience has shown me that this is where the most money is to be made i.e. small caps that are not covered by Paul on the SCVR, have quiet or non-existent ADVFN BB's and never get a mention in the press. If they also happen to have a niche technology product that 99% of people cannot understand but is used by some of the biggest multinational companies, then so much the better.
I won't say much else because my opinion of TMF editorial is so low but perhaps they could do a "3 Reasons not to invest in Sopheon" article along the lines of:
1. My ex-wife was called Sophie and I always used to ask my friends "What is Sophie on" so it brings back bad memories.
2. I don't know what it does.
3. I've missed the boat.
All the best, Si
Good point Simoan and well made. I certainly would want to discourage anyone, it's just for me personally with so many stocks to potentially investigate further; there is no real economic sense in spending much time on a stock that I would be highly likely to reject anyway.
I learned sometime ago on a pyscho-babble management course that I tended to over analyse things even when I had a strong initial gut feel so I tend to follow my nose a little more these days - at least in terms of the negative decisions.
Interesting your views on the standard of the Fool articles by the way. It's a good few years since I wrote a few articles for them but even back then, there was a bit of pressure towards writing "click-bait".
TMF with it's original ethos of teaching people to take control for themselves was quite formative in terms of my investing. It's sad that they didn't invest in developments that the could 'monetise' (other than tip sheets). With the closure of the message boards over there I don't really see there is anything left of the original ethos and I certainly don't think the target market for the articles is particularly towards the more "sophisticated" investor. (In fact Stocko feels like the natural successor to the original TMF)
(No offence intended to any of the MF writers around these parts, I understand that you are writing to a brief).
Anyway to come back (in the end) to Sopheon (LON:SPE) - I think you suggested that the high level of receivables (4-5 months of revenue I think) might be down to conservative accounting. I didn't really get that - surely if they are recognising loads of revenue that is not yet collected (even though believed to be earned) surely that's the opposite of conservative?
On this score I would wonder whether there is a risk of customer disputing what is due and also whether the upcoming FRS changes to revenue recognition will impact them.
Loved your MF article suggestion btw. As coincidence would have it, my daughter is actually called Sophie and as she can sometimes be somewhat "blonde" I often ask what's Sophie On. And this indeed wraps it up she's great company but has cost me loads rather than made me money. (clearly not a good investment omen)
I learned sometime ago on a pyscho-babble management course that I tended to over analyse things even when I had a strong initial gut feel so I tend to follow my nose a little more these days - at least in terms of the negative decisions.
I agree, and I have a highly sensitive BS detector too! However, that's not really an excuse for not looking further at what a company does. Some companies, like it or not, do have products that are not easily explained to a layman and so some investors put it in the "too hard" pile and move on as you have done with Sopheon (LON:SPE). This is how it should be i.e. those prepared to put in the hard yards have an advantage. Let's face it. it's pretty obvious from reading threads about IQE (LON:IQE) that most people invested do not really have a clue what it does but were maybe happy to jump on a bandwagon, most people invested in ARM didn't really understand its products etc.
I guess I have a slight advantage that every day I work with large multinational technology companies with project teams working at different sites all around the world, so I can easily see a need for the software products and consultancy that Sopheon (LON:SPE) provide. It's almost embarrassing how these companies work with the arse not even knowing that the elbow exists! :-)
On the receivables, clearly with software companies receivables is open to some interpretation and the policy will differ from company to company. I agree the receivables are high for Sopheon (LON:SPE) at roughly 6 months sales but this has always been the case. They have a mixture of revenue streams from software licensing, recurring maintenance fees, and ongoing consultancy so it's difficult to get a handle on but given the nature of their large multinational customer base this is probably more to do with the way these companies pay than hiding any bad debts.
As for The Motley Fool, the original ethos was great and there are many of us around that learnt a lot in the early days, however it became something it shouldn't have and now the editorials are embarrassing. Really, Stockopedia only exists because TMF screwed up and failed to monetise it's users in a way that added value for the vast majority of them. So of course, like many others, I'm really glad and thankful that Stockopedia exists, and long may it prosper.
All the best, Si
Phenomenal effort today Paul, thanks , Dave
Thanks Dave,
I'm putting in extra effort now, to make up for my duvet days in December.
Regards, Paul.
EV charging is very simple:
* Charge overnight at home. The power companies have always been very keen to see customers using electricity at night (hence Economy 7 discount tariffs etc). A standard charger in your garage or driveway only uses the same power as a basic electric shower (7kW) so can easily be accommodated in a normal house, especially when everyone is asleep. In fact, as domestic energy storage becomes viable, many houses are now using solar panels to charge up a battery during the day (free), which then discharges into the car overnight. Of course there are capital costs, but overall it's still cheaper. A standard 7kW charger might take 8 hours to charge a car, but if you start it at 10pm (hence avoiding the Corrie kettle spikes) it should be ready by 6am.
* If you don't have a garage or driveway, you can instead charge up at work, or at the train or Metro station where you park your car for the day on your commute. A lot of train stations are now installing charging points (initially most were free but most are now starting to 'charge' £5 or so... still cheap!) and some workplaces on the same basis. Or even at the supermarket on a 'rapid charger' which gets you up to 80% in 30 minutes while you're shopping.
Also don't forget that the vast majority of UK drivers don't drive anything like 200 miles a day. If you do (e.g. travelling salesman), an EV today is probably not for you. The vast majority of drivers in the UK only do 20-30 miles a day. So in reality you wouldn't even need to charge your car every day, just every 3rd day max, or maybe before a 100-mile 'day out' type trip. The only issue comes if you're driving 'occasional' long distances e.g. on holiday. Well then you just have to deal with it - stop at petrol stations for quick charges etc. Or take the train.
I don't disagree that there needs to be more infrastructure for EVs. But I don't think it's as impractical as everyone makes out, today. People got nervous with the original Nissan Leafs which had a 100 miles range - a range of 200 miles is a game changer.
Great to see a positive comment about EV and one I agree with.
We will buy an EV in 2018, while there is some residual value in the diesel we'll sell, which we suspect will be unsaleable in 2 years. Range is now sufficient for 70 mile there-and-back journey, and we are blessed with a second car to keep for the occasional long journey. People should be careful about 'range anxiety'. The majority of people buying now do ALL charging at work or home. We will night charge on automatic timer and NEVER think about topping up or waiting in line at a filling station in this car. Seems easier to me. And by the way, the evidence is that batteries are lasting longer than predicted. There are companies ready and waiting to re-use car batteries for static storage, but there is isn't enough supply, because they're going on too long.
OK, we're middling-early adopters, but another two years of battery progress and the penny will drop. And by the way, filling at night does not tax the Grid, just evens out its flow. NG estimate 2m EVs are needed before they have to think about it.
As for auto dealers, I'll not be investing. Not only will it become more complicated to shift secondhand cars for many £000s, EV service is cheaper, and I think it ever more likely that the manufacturers of these 'computers on wheels' will sell direct, as the expertise is more firmware/software than physical intervention.
"...I think it ever more likely that the manufacturers of these 'computers on wheels' will sell direct, as the expertise is more firmware/software than physical intervention."
Sounds like a perfect opportunity for a car manufacturer/dealership to service your car and send you a bill with the description 'software update'. Given the recent reports on Apple slowing down there old iphones, who knows what tricks the car manufacturers could get up to.
One issue that I haven't seen discussed much is the effect of substantial charging of electric vehicles on power quality. As I understand it, chargers are reactive and cause a phase shift in the electicity suppy locally, which can damage some elctronic circuits if there are enough chargers operating. I was told that ground storage heat pumps have the same effect.
Then there's the matter of the location of the load from charging. The transmission grid won't be affected (and anyway it's well instrumented) but the local distribution grids are sized for the forecast load and are not well instrumented, so there must be the possibility for damage if more and more EVs are bought by people on the same local grid.
A third issue that worries me (and this is getting a bit further off topic) is the consequences of a fire involving a concentration of batteries. The energy has to go somewhere, batteries don't release that energy in the same way as a petrol fire does, and the smoke will contain some highly toxic compounds.
Of course, none of this will effect EV sales in the next decade ...
Hi FREng
As far as heat pumps go, isn’t this pretty much the same tech that is in a fridge or a freezer? Basically a refrigerant absorbs heat in one place and gives it up in another place with a compressor in the middle.
I’m no expert but it would seem unlikely that ground or air source heat pumps would be a cause of concern by the nature of the way they use power.
Yes, same technology but far higher power. You won't find your neighbours complaining that your fridge ruined their hifi! Heat pumps and EVs won't be a problem until the local density gets high, but it is an issue that has engaged members the energy policy panel in the IET (who know far more about this than I ever shall!).
The heat pump problem is over. We had an old one, from 2006. In our new house we installed from the first batch of soft-start inverter-driven pumps. This does more than the first generation off a standard power supply, 30 amp fuse, like a cooker. They'll all be like this soon, I'm sure.
Now we just need to get people in Britain to demand invert-driven fridges/freezers, like we have in Costa Rica, and the loading will actually get easier.
What metro? What about a normal car park, do they have chargers everywhere? Or in the street. How many work car parks have chargers? Maybe some for directors? It may happen but it's available yet. Yes you can go to a supermarket but what if they are all being used? Also in my area no supermarkets have any charging points, so I don't think it's as easy as you make out.
Debenhams has the misfortune of being owned by PE firms that made out like bandits leaving it with huge amounts of debt (£1.2bn).
They spend the rest of the next decade paying the debt off while their rivals made their move online much earlier.
So, unable to keep up with the competition it's where Debenhams find themselves today.
I agree with Paul views that dividends are unattainable. Also, I believe they need to reduce the size of their operations because department stores are becoming out of fashion. They need to follow the path of WH Smith by focusing on profitability while reducing sales.
Maybe at a much smaller size, they could survive.
One other point about Debenhams (LON:DEB) -- online growth is clearly a positive (the only one?) and Paul referred to a potential ambition to use the stores as warehouses serving online orders as well as retail outlets.
However, i think some investment might be required to make Debenhams a true online success story.
I don't usually make investment decisions based on personal experience, but I'd be willing to make an exception here. Our household experience of the online service is pretty poor. I'd say that considerable improvements in IT and process would be required to bring it up to the standard of most rivals.
Returns handling appear to be a particular problem. We've received previously returned items that have been sent out incomplete (i.e. they were probably returned incomplete without anyone noticing).
On a similar note, almost every time my wife returns a package with more than one item, the resulting refund will be incomplete. Typically it's as if one of the returned items hasn't been scanned back in.
Trying to correct this on the phone is difficult as the staff appear to have no visibility of what's been returned (obviously, as it hasn't been scanned...). So they typically refund for whatever my wife says is missing, verifying the refund only against her original order.
If this experience is replicated across the group's customer base, it's not hard to see how it could result in poor inventory control and consequent financial costs.
Obviously you would expect ex-Amazon CEO Sergio Bucher to be very aware of such issues and to know what's needed to bring the online service up to scratch. Yesterday's profit warning mentioned progress with Mobify to improve the ordering/shopping experience, but I fear that back-end improvements may also be required.
Does anyone else have any views/experience of this?
Regards,
Roland
Ref Camb
I think the looming electric car potential disruption to the the way cars and sold and maintained is now starting to "quickly" gather pace from the perspective of delivering an electric car that will match a petrol one convenience wise- if Camb makes most of its dosh by OTT price wise service charges that wont be needed to the same degree with a "less bits" electric car then thats not good news. My particular concern would be that Nissan/others like Tesla swap to all maintenance in house and ditch the dealers from the loop.
Evidence of the impending transformation has come from an announcement by Nissan last week that their 2019 leaf will have a 225 mile range (note not all range figures are the same !! and the european ones i think are a bit of a con)
I really wasnt expecting the leaf to go that far that quick with the increase in range and this must increase the potential customer base massively - where one car manufacturer goes range wise the rest will follow - no doubt this is like the iphone second generation probably still not fit for purposes for everyone but surely if its 225 miles next year that will be 300 miles plus as standard within 5 years. Surely 270+ miles practical range and 45 min top up charge time to do another couple of hundred would do for 90% of bods as long as they can ensure there is sufficient on street charging options - surely it cant be that hard to start adding those in when necessary.
https://gas2.org/2018/01/03/2019-nissan-leaf-trolls-tesla-w-225-mile-range/
Hi,
Re Cambria Automobiles (LON:CAMB)
Isn't the problem of infrastructure the main one to overcome now as the tech for the cars is evolving extremely quickly but the infrastructure is not moving at anywhere near the same speed?
One of the biggest problems is that the grid hasn't anywhere near the capacity available to cope with the likely evening surge in demand when electric cars would return home and need to be charged. There is scant detail on how that supply problem can and will be addressed. Furthermore, the need for wholesale charging points is also a major issue which is not being tackled as it needs, for imminent wholesale adoption. It seems that government action will eventually become necessary.
There is no doubt that these issues will be resolved in time, but it is possible that they will block widespread usage of electric vehicles for a time possibly a number of years hence. The head of Valeo apparently said as much last year.
In the meantime, the massive LFL declines in car sales could reverse as others, like me, have found that the reality of buying and using an electric car is still a way off. (I bought a new car Q4 last year having intended to buy electric or at least a hybrid and was extremely frustrated to find it just wasn't a workable option for me yet).
For that reason I continue to hold Pendragon (LON:PDG)
Regards,
Hello hawkipa
good comments - i am deffo looking into the future here (2-5 years minimum) but i see no problems whatsoever that cant easily(??) be overcome and in some respects not sorting the solution until one is needed means that the eventual solution will likely be a better and cheaper suited to the purpose - i can see no technical challenge in putting cables down streets and adding charging points on the pavements - we certainly have plenty of bollards performing no proper use on out streets as it is - this will be a bit bitty for so,e time to come though probably in a similar manner to broadband - but we are mostly townies or have a garage i guess??
with regard for demand - there has always been less demand for electric during the night - so doing overnight charging to me would even grid usage over a 24 hour period - if bods are willing to pay extra for more electric surely the demand will generate the solution as it always has done how long would it take to get new some new gas power stations up and running - we are building new transmission lines to norway etc so i dont see the worry particularly altho i am sure there are concerns that we arent adequately planning ahead so we dont have to overpay for a solution.
ref the workable solution for you i am guessing if you could plug in where you park at night - set it to charge overnight and then do 225 miles before needing a topup you may have been up and running now- i would guess in 36 months that option will be available for a sizeable % of new car buyers if we can do things right - Just look at norway and how quickly they have gone to over 50% of new cars being electric - change is a coming
How do you charge your car up overnight, if you park on the street, maybe not even outside your own house? Don't electric cars need special charging points?
Hi all, interesting comments regarding EV and charging.
I would expect many houses will adopt home batteries over the next few years which, when combined with solar, have a huge impact on smoothing out that peak demand on the grid in the early evening.
Fully Charged have a great video on this (https://youtu.be/nWLzlrGGuxQ).
The presenter Robert Llewellyn's house has solar panels and a Tesla Powerwall meaning he uses almost zero grid electricity during the expensive peak hours now:
- The solar charges the battery during the day,
- The battery powers the house during the evening,
- Then at night the low-cost Economy 7 tariff and the remaining battery charge can top up the EV.
The battery has enough power output (5kW) to comfortably cover the highest conceivable load from the house (ie kettle, dishwasher, etc).
Power providers will love this trend because if you smooth out the power demand then less plants like gas-fired turbines are needed for the spikes. These plants sit redundant most of the time and are therefore expensive and inefficient uses of capital.
Bring it on I say!
Most house in the UK don't have solar, I think it's around 7%. Even ones that do will only produce about 3kw per day. Yes batteries will help. How much to charge up an EV about 50kw?
Very true regarding the solar coverage, although my inner physicist just wanted to come back on the kW numbers.
A typical roof with solar produces around 3-4kW during the sunlight hours. So over the day that amounts to 24-32kWh (assuming 8 hours of sun, ie 3kWx8hrs and 4kWx8hrs).
EV batteries range from around 30-85kWh of storage. A typical Tesla is 60kWh.
So one day's solar energy on a typical roof (24-32kWh) should fill up 40-50% of the 60kWh car battery, assuming of course nothing is used in the house, which I admit isn't realistic.
Please do let me know if I've got my numbers wrong though as I always used to get confused with kW and kWh.
Regarding solar coverage, 7% of UK houses is about right from what I've read. 1.5 million homes vs total number of UK homes of c. 25 million if memory serves. Not saying this will happen overnight but that 7% will grow significantly as cost of photovoltaics continues to plummet.
Cheers
Rob
Thanks, maybe I misunderstood the kW, did find this "An average 4 kW solar panel system will generate around 3,400kWh per year" so about 9kWh per day then.
I thought solar companies were going bust after the Govt. reduced the subsidiaries? Certainly I have had calls recently about it. I did look at solar about 3 years ago but it was about £10k and that was before the EU added VAT onto it. Yes I could probably get it for around £8k but my roof gets some shading in winter, at the time it did not seem worth it but I may revisit it in the future. Maybe everyone will be switching to electric heating?
Herbie,
I think from a purely economic perspective you need to commit to keeping a house for at least a decade to justify a solar installation. I doubt if when you sell a buyer will pay you £10K extra because it is installed. The property market doesn't tend to work that way. Yes it will be a selling point but looking at two identical properties, one without, one with solar at a £10K higher asking price, most will go for the lower priced option.
Dave
Yes I quite agree that is part of the problem. Also some people don't like them on the roof, I can see why, so it may not be a plus selling factor.
""An average 4 kW solar panel system will generate around 3,400kWh per year" so about 9kWh per day then."
Yes that might be more realistic... My numbers probably stack up in southern Spain but perhaps a tad optimistic for the UK... Well I am an ex research analyst so maybe over-optimism is to be expected.
9kWh/day could assume the 4kW system runs at only 2kW in our climate, and for roughly 5hrs a day. My parents had some installed about 8yrs ago. They cost £15k but the feed-in-tariffs back then were amazing so it yields over £2k pa and had a 7yr payback period, so a 13% ROI.
The wife and I were quoted £5k late last year which shows how much costs have dropped, but feed-in-tariffs have come down too, from 15p down to a miserly 3.5p/kWh now. When you take electricity bill savings into account the payback period looks to still be around 7yrs now on my numbers, which is fantastic.
Anyway, to bring it back to equities (before I get told off by Paul & Graham), I agree with other comments that there are lots of hurdles to mass-adoption of this new technology but none look insurmountable and it is increasingly hard to see how the established 2nd hand car market, the auto-service industry, the supply chain and so on aren't going to be under severe pressure over the coming decade.
Have a great weekend all,
R
I am personally quite sceptical about the electric car scene. I would like to question the reliability of those range figures, especially as its a well known fact the batteries in general do not perform well in cold conditions, and there useable time drops dramatically. Would be interesting to see Jeremy Clarkson and his crew test this!
I also just don't see the charging times coming down to anything acceptable any time soon.
I also very much agree with you on the point about "less bits" for electric cars is a big negative for service charges at dealerships and an industry as a whole. This is also a very interest subject in its self, if the Government wants the country to adopt to electric cars, then surely this creates a huge shortfall in vat from fuel, additional service parts, and the supply chain for those parts as well?
If electric cars became the majority of vehicles in the UK I wonder how the creative TAX man could fill that shortfall in their 'greener' future. (which is only as green as our power stations).
They'll tax electricity - arguing that energy usage, even in the new "clean age", has to be brought down.
Then when the planet runs out of copper, lithium, cobalt, various rare earths........ they'll introduce a scheme to promote the purchase of the new environmentally friendly petrol powered vehicles.
Phil
Great point Rmillaree and I can’t remember the exact figure but I think I read somewhere that 80% of all car journeys are less than 20kms so 40kms round trip.
I think with car sharing, Uber, Blablacar (a French long distance ride sharing service), electric cars and road pricing driving more people on to trains etc the car industry in general is going to be very disrupted. But not just the car industry car insurance and repair for example but also somebody pointed out recently that 50% of all cigarettte purchases in the United States are made at service stations.
Interesting times and I certainly would not be in car dealers, just too uncertain.
Regarding Sopheon (LON:SPE) I have always been put off buying because of the perpetually high receivables (as well as the small float) - does anyone have a reason that these high receivables are nothing to worry about? One time I saw their accounts they had made an acquisition, but that cannot explain why their receivables are perpetually high.
Regards,
Ed Miller
Regarding Sopheon (LON:SPE) I have always been put off buying because of the perpetually high receivables (as well as the small float) - does anyone have a reason that these high receivables are nothing to worry about?
I've always felt this is just a factor of how conservative (or otherwise) a software company's policy is on revenue recognition? Perhaps the policy is ultra-conservative at Sopheon (LON:SPE) ? I've never compared with similar companies as the level of receivables is reasonably constant and importantly has not grown a great deal over the years. Although I agree they are higher than most similar software/consultancy type businesses, they do also have a higher percentage of recurring revenues and this is maybe one factor. Tbh it's not something that concerns me too much about holding Sopheon (LON:SPE) but I take your point about the small float and illiquidity which has to be a major factor in the large rise today.
All the best, Si
Thanks for your view on Sopheon (LON:SPE) receivables (and small float), Si - will take another look at the accounts with that in mind.
Regards, Ed
"I would also treat the big dividends as being past their sell-by date."
I love this turn of phrase!
I was long Symphony Environmental Technologies (LON:SYM) until today. Their profits trajectory is great due to their small cost base and operational gearing. However, I was never really comfortable with the technology, which has been disputed for years (see the Macarthur report most recently). However, I think that if oxo-biodegradables aren't outright banned in Europe and the US then they could become mainstream as plastics manufacturers who already export to the likes of UAE and Saudi Arabia, where they are a legal requirement, add d2w to all of their plastics. The share price here will blow with the regulatory winds, which are behind them at the moment - but could change quickly in the opposite direction (see 2011).
Paul,
I think it's worth mentioning the good trading update from Stonegate this morning that will have some read across for Revolution Bars (LON:RBG): http://www.stonegatepubs.com/m...
It's definitely been a happy start to the New Year for my portfolio with the updates from Next (LON:NXT) yesterday and Sopheon (LON:SPE) today :-) It'll never last...
All the best, Si
Taptica International (LON:TAP) requested as well please Paul - Graham was positive, I hold a bit, doesn't *seem* like another Israeli buzzword fraud, may be discounted because of those that have been. I hold. Also interested in Symphony Environmental Technologies (LON:SYM) which I am researching today!
Anyone else @MarkHowitt famous shortseller of Ocado who emailed them regarding his shorts on the stock? They thought he was a customer as shorted means something different in delivery terms
There's a useful note from Ed about recent LSE price feed problems here: https://www.stockopedia.com/content/notice-about-london-stock-exchange-quote-irregularities-292508/
Sopheon (LON:SPE) loan stock conversion happened on 28/12/17.
Forecasts for SPE quoted above are incorrect - suspect its due to poster mixing up GBP / USD as Sopheon (LON:SPE) report in USD. Before their statement today revenue, EBITA & pre tax profit were all forecast to increase in 2017, with EPS static due to loan stock conversion.
Thankyou for clearing that up @darlocst. My research was sloppy (I deserve a thumbs down) and indeed last years figures were in USD vs GBP for this years forcasts. (I got my information from Digital look). SPE is a company i know very little about but will keep an eye on.
Symphony Environmental Technologies (LON:SYM) please.
An interesting stock at present given the recent media on china's ban on plastic waste import.
Good morning Paul/Readers
Please can you cast your eye over Sopheon (SPE) today?
It has a Market value of 36M and about 10M shares in issue (very illiquid)
The company says in this morning trading statement that "As a consequence, early indications are that revenues, EBITDA and pre-tax profits for the year ended 31 December 2017 will all exceed market expectations. In addition, we expect improved recurring revenue and visibility into 2018"
I particularly like this quote from the statement "with particular strength in the closing quarter of the year"
No numbers are given but forcasts are for 19.6M in revenue and 2.21M PTP. This is actually behind last
Years figures of 23M Turnover and 3M Pre-tax
There is a risk of just a few major Shareholders as far as i know. This company has been on my watch list for a year but has traded sideways in a tight range (im not a holder)
Would welcome your thoughts:)
Thankyou.
One thing to remember with Sopheon (LON:SPE) is the potential dilution for existing shareholders. Not sure if it has happened but Paul highlighted in the SCVR on 24/8/17. The additional shares are significantly in the money (think price was 74p). Therefore, EPS figures will need to take account of these.
Sopheon Sopheon (LON:SPE) released an ‘ahead of expectations’ Trading update this morning. They appear to have now dealt with the convertible stock issue too. Unlike other software companies their share price has been weak of late (PE ~12) so you thoughts would be appreciated.
Disc: I hold
My morning smallcap tweet:
Cyanconnode Holdings (LON:CYAN), Symphony Environmental Technologies (LON:SYM), Sopheon (LON:SPE), Be Heard (LON:BHRD), Green & Smart Holdings (LON:GSH), Escher Group (LON:ESCH), Churchill China (LON:CHH), Debenhams (LON:DEB), Taptica International (LON:TAP)
CyanConnode (CYAN) warns on FY due to a customer delaying deployment to 2018. "Delivery is now expected to be made during 2018, hardware and service revenues relating to this project will now be recognised in the Company's current financial year." Surely *not* be recognised? Rev will be significantly below market expectations at £1.2m." Order book over $100m, global pipeline ~$320m. Outlook "continued positive momentum in the pipeline has been aided by re-alignment of key employees to create a world class team." Re-alignment? Did you take them to a garage?
Symphony Environment (SYM) exp FY rev £8.2m, marginally above market expectations and pretax significantly higher than current market expectations, at least £400k.
Sopheon (SPE) FY trading - rev, EBITDA and pre-tax will exceed market expectation.
Be Heard Group (BHRD) warns FY profitability to be below market expectations "due to a number of unexpected factors....MMT, agenda21 and Freemavens experienced a reduction in activity towards the end of the year and some deferral...MMT suffered cost overruns on a substantial contract. Sounds too bad to be true. All this since last update 15 Dec. Also joint CFO & COO will become COO.
Green & Smart Holdings (GSH) Malaysian power co warns FY to end Sept rev only RM45m due to failure to get new funds. It is in advanced negotiations to secure funding. Three months to add up the rev figure!
Escher Group (ESCH) CEO retires end May after 10 years. Showered with garlands.
Churchill China (CHH) FY operating performance will be slightly ahead of current market estimates. Cash to exceed current market expectations.
Debenhams (DEB) warns - post Xmas sales poor despite further "markdown investment". It's not effing investment. I hate that use of the word. H1 gross margins expected to be c150bps down. Cost cutting: "expect to generate further annualised savings of c£20m, of which c£10m will be realised in H2 FY2018. Consequently, FY2018 costs are now expected to rise by c+1% compared with previous guidance of +1% to +2%." I'm short.
"Taptica (TAP) FY trading - rev in line, adj EBITDA ahead of market expectations."
Cambria Automobiles (LON:CAMB) and Water Intelligence (LON:WATR) please, Paul.
I know it’s Israeli so maybe you’ll put it in the XLMedia (LON:XLM) bucket Paul, but on the basis it may be a quiet news day, Taptica International (LON:TAP) issued a very positive update today.
It trades at a reasonable multiple and has strong market tailwinds behind it being at the forefront of digital marketing with a scalable platform. Would be good to hear your views !
Hi Nicobos- Taptica International (LON:TAP) has always traded at a reasonable multiple and delivered positive updates. Perhaps the reasonable multiple is a result of it being a foreign company. I believe it’s a marketing company that tailors it’s efforts specific to customers, therefore gathering data on individual consumers. However, I would be interested to know if the upcoming GDPR legislation will impact Taptica International (LON:TAP). Can anyone provide any insight?
Nicobos: I made this note from the Taptica International (LON:TAP) last conference call...
The CEO said that they welcomed the new EC regulations as in their view it would "clear the space" as they always complied with international regulation. They collect no data via cookies, but only take data from the device i.e. they collect no personal data on the people using the mobile device. They then direct advertising back to the device, not the individual.
I also see they handle 22 billion requests per day and has data on 220 million devices in its database. Clever enough! Ian
P.S. Finncap today: We lift our FY 2017 earnings expectations and target price from 500p to 550p.
Many thanks iwright, I have the same comment in my notes from the conference call. They also helpfully dealt with the changes by Apple in iOS11 to deal with data tracking prevention in the September interim results and how these would actually assist the business. Very happy holder here.
@lwright7 re Taptica International (LON:TAP) -
I think that device data will be deemed to be personal data under GDPR. You can tell a huge amount about someone from what their device has been doing and where it has been, including some very personal data such as their sexuality, their health conditions, their political leanings and who they spend the night with. Indeed, if the data wasn't highly relevant to the device owner, what would be the point of directing advertising to the device? Mobile phones don't buy things, people do (to misquote a slogan from the US gun lobby).
I recall (but haven't gone back to confirm) that IP address was specifically said to be personal data.
Hi FREng
The general legal view is that IP addresses are personally identifiable information, so if Taptica International (LON:TAP) are holding this then they're caught by GDPR. The status of the other data is less clear-cut.
To get round this they'd need to generate some kind of unique Taptica specific identifier which could then be linked back to the handset - which isn't so hard to do, but does slightly increase the uncertainty in identification.
timarr
Hi timarr,
I am not a techy but is it not correct that if the data is encrypted then this complies with GDPR?
I presume that Taptica International (LON:TAP) could undertake this at relatively little cost? A more relevant question at this stage could be the risk that as Taptica International (LON:TAP) appear to be ignoring the legislation on the basis they think they comply which could lead to huge fines. They need to be seen to comply by implementing a risk control mechanism.
Of course in one sense as a capital light company a 2% or even the max 4% fine on revenue would only dent their profits. The affect on the share price could be a different matter.
I would appreciate your further thoughts on this.
Dave
@daveinthelakes: AFAIK, GDPR requires that you have obtained informed consent from the data subject for the processing that you are carrying out with their personal data. Encryption is important to protect the data in transit or while stored - a different GDPR requirement.
Thanks FReng,
As the vast majority of all consummer data and advertising appears to be inolve three parties, namely Facebook, Google and Amazon can they get customers to simply tick a box allowing them and their approved parties to collect data? I imagine if faced with the prospects of never receiving any advertising most may tick said box.
The above companies work closely with TAP as they fully appreciate the benefits to their advertisers.
Sorry if this is too simplistic a view!
Dave
"I imagine if faced with the prospects of never receiving any advertising most may tick said box."
I must be peculiar then since I never want adverts, newsletters or marketing from associated partners cluttering up my mail box. Why on earth would you?
The ads are not email but appear on your facebook etc page. You and I may not be typical facebook users but I think the average user doesn't mind ads about products they may be interested in. After all it's little more than like buying a newspaper where adds sit alongside every bit of editorial, we don't have to read the ads. We have to pay for newsprint but facebbok etc is free-some would say a small price to pay.
Dave
I'm no lawyer, but it seems to me that if GDPR is enforced strictly then most tick-box interfaces won't satisfy the test of fully informed consent.
However, that strict interpretation would be highly disruptive to huge numbers of on-line businessses, so I expect that GDPR won't be interpreted that strictly, at least initially.
But that leaves a possibility that case law will develop that does introduce a stricter interpretation than many companies are preparing for, and that the case law will then allow much wider action in the civil courts.
So it's a risk, in my view, but probably not an imminent threat. I'm keeping a watch on the Article 29 Working Party http://ec.europa.eu/newsroom/article29/news-overview.cfm which has been highly influential.
Hi FREng
Tick-boxes won't be sufficient, and consent has to be sought transparently for each separate use of the data. I believe that the ambulance chasers are tuning their engines ... the penalties under GDPR are so severe - up to 4% of global annual revenue - that many companies will be prepared to pay off complainants rather than risk sanctions.
And consent is only half the issue - data breaches are potentially subject to fines of up to 2% of revenues. Which may sound like the lesser problem but if a company loses emails and passwords which then allow hackers to attack third-parties - as in the originally undisclosed Yahoo breach - then the third-parties can sue the source of the breach for their damages, and that's before consumers launch class actions.
GDPR is one situation where you don't want to be asking for forgiveness when you get it wrong. I expect the regulators to make a few very high profile examples in 2018. I certainly wouldn't want to be a non-EU company who gets this wrong.
timarr
Hi Dave
Sort of, but not exactly. If they hold the IP address, even in encrypted form, then it must be because their systems can recover it in order to compare with the incoming address of a phone - which would be caught under GDPR (probably, this is all legal stuff)..
What they actually need to do is generate their own ID from the phone data which no one can match with personal data held in someone else's database.
It's all a bit nerdy and esoteric, but it the kind of thing lawyers and security experts are worrying about right now.
timarr
Tim,
Mightn't the logic that led to the IP address being regarded as personal information for GDPR also catch a broader range of data, such as a MAC address or a device "fingerprint"?
The obvious test would seem to me to be that if it can be used to target personal advertising then it's personal data!
Hi FREng
The argument is that the IP address that Taptica International (LON:TAP) hold, along with non-personal data, can be matched to an IP address that someone else holds (e.g. the MNO) along with personal data. So I think as long as their fingerprint is not some form of standard that's widely used elesewhere they would probably be OK.
But it's not absolutely definite, either way.
timarr
I would second the request on Taptica International (LON:TAP) but there is also a good summary over at Johns Investment Chronicle at
http://johnsinvestmentchronicle.com/taptica-good-trading-update/
I hold.