Small Cap Value Report (Thu 5 Apr 2018) - AIEA, WGB

Good morning, it's Paul here.
Just a quick reminder that it's the last day of the tax year. So the last chance to add up to £20k into our ISAs for the 2017/18 tax year, and any other tax planning measures that you might wish to undertake.
Airea (LON:AIEA)
Share price: 59p
No. shares: 41.4m
Market cap: 24.4m
(at the time of writing, I hold a long position in this share)
Interesting news for shareholders here. Floorcoverings distributor, James Halstead (LON:JHD) has announced that it is in the early stages of considering a bid for Airea;
James Halstead plc ("James Halstead") notes the recent movement in the share price of Airea plc ("Airea") and confirms that the Board of directors of James Halstead (the "Board") is at the very early stages of evaluating making an offer for Airea which could lead to an offer being made for the entire issued and to be issued share capital of Airea (the "Possible Offer").
As a consequence of this announcement, an "Offer Period" has commenced in respect of Airea in accordance with the rules of the City Code on Takeovers and Mergers (the "Code").
There was an excellent results statement, with lots of positives in it, which I reported on recently here, on 21 Mar 2018.
The big pension scheme (which is now quite well funded) could be an obstacle to a bid. Although in some cases, agreement can be reached with pension fund trustees whereby an acquirer injects a one-off cash sum into the pension scheme, in order to get the green light for the acquisition.
I've got mixed feelings about this. On the one hand, it's always nice to get a portfolio boost from a takeover bid, if the premium is sufficient. On the other hand, Airea has already committed to a 6p special dividend, and looks to be on a roll (geddit?!) operationally. It would be a shame to have the upside whipped away from us, before the big surge in profitability comes through (from closure of its heavily loss-making carpets business). Its commercial flooring operation is highly profitable.
Anyway, I'm writing this just before the market opens, so don't know how much the share price will rise today. My hunch is that 70p+ could be on the cards, but we'll see.
UPDATE at 09:37 - Airea (LON:AIEA) has put out a fairly standard response to the news from James Halstead (LON:JHD), as follows;
Response to statement by James Halstead plc
The Board of Airea notes the announcement released yesterday by James Halstead plc ("James Halstead") which confirms that the board of directors of James Halstead is at the very early stages of evaluating making an offer for Airea which could lead to an offer being made for the entire issued and to be issued share capital of Airea (the "Possible Offer").
Airea confirms that it has not received any approach from James Halstead regarding a possible offer by James Halstead for Airea nor has Airea had any discussions with James Halstead in relation to a potential offer.
Airea shareholders are strongly advised to take no action at this stage. There can be no certainty that any firm offer will be made nor as to the terms on which any firm offer might be made. Further announcements will be made in due course as appropriate.
The put up or shut up date, under the Takeover Code, is 5pm on 2 May 2018.
The response above seems consistent with Halstead's announcement - i.e. I would not have expected it to necessarily have yet approach Airea, as it's only in the very early stages of considering a bid - which I suppose would be desktop due diligence of the sort you & I would do.
Note that AIEA qualifies for 2 Stockopedia screens, as follows;
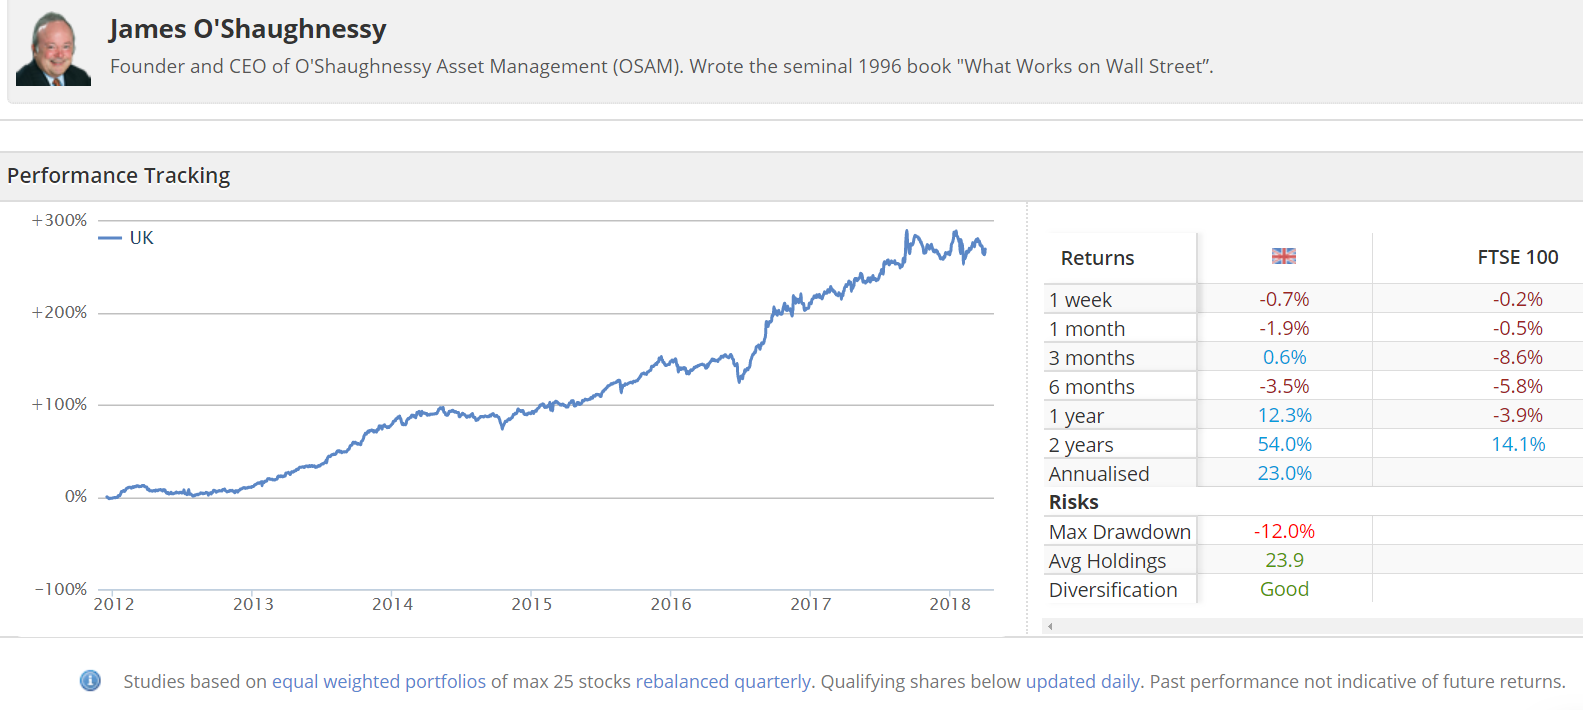
Tiny Titans (modelled on James O'Shaughnessy's investing approach) has a terrific track record, and I often look to see which stocks are in it. Quite often there will be some overlooked gems in there. This performance track record is strikingly good;
Airea also qualifies for inclusion in this Stockopedia screen (which I've not looked at before, but sounds interesting);
The Stockopedia screens are a great way of finding a shortlist of potentially interesting shares to research. I tend to focus on the best performing screens, and then look to see what stocks are in there. The occasional nugget of gold crops up this way!
Walker Greenbank (LON:WGB)
Share price: 126.5p (down 5.2% today, at 08:53)
No. shares: 70.9m
Market cap: £89.7m
(at the time of writing, I hold a long position in this share)
Walker Greenbank PLC (AIM: WGB), the luxury interior furnishings group, is pleased to announce its financial results for the 12 month period ended 31 January 2018.
Note that these results are flattered by the acquisition of Clarke & Clarke.
This excerpt from the highlights section shows some decent figures;
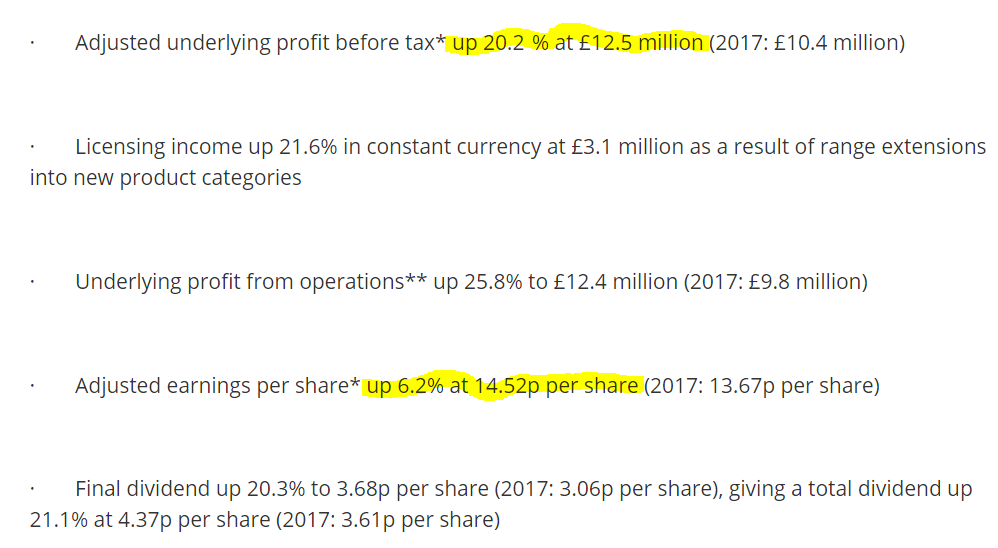
I particularly like businesses with licensing income, as it's money for old rope really. It also shows that there is considerable value in the brands being licensed - otherwise people wouldn't pay to use the brand.
The adjusted EPS of 14.52p is above the consensus forecast of 13.8p shown on Stockopedia. There are a couple of broker notes out this morning, both of which refer to only a slight beat on earnings, so there's a little confusion over the precise figures - but it's in the right ballpark anyway.
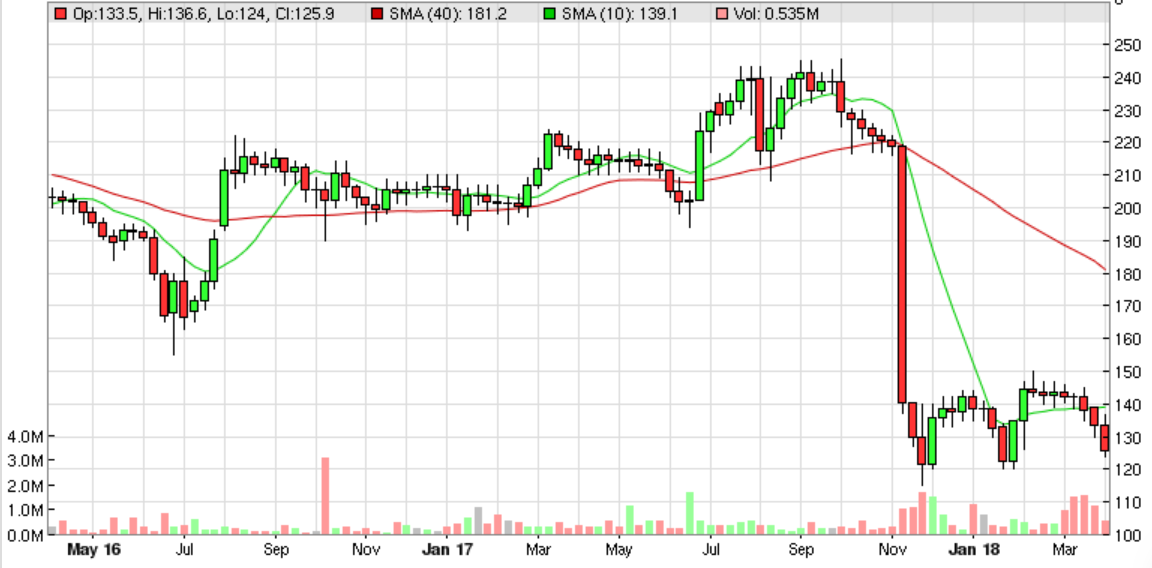
There was a profit warning in Nov 2017, causing a big drop in share price, which I reported on here. I've just re-read that, to refresh my memory.
Outlook - we already knew from previous updates that the UK market was soft. That continues to be the case, with another cautious update today;
Trading to date in the current financial year reflects a difficult marketplace particularly in the UK. In the first nine weeks of the current financial year, Brand sales were down 8.3 per cent in the UK and down 3.8 per cent overseas in constant currency, down 6.1 per cent in reportable currency.
The Board is focused on delivering growth-based strategic initiatives including targeted investment, cost savings where appropriate and a greater emphasis on Brand sales overseas. Additionally, our high margin licensing business is expected to continue to show strong growth.
However, trading to date in the current financial year makes us cautious about the outlook; as a consequence, the Board expects that profits for the full year will be ahead of last year's but below current Board expectations. We will provide a further update on trading at our annual general meeting in June 2018.
That's a mild profit warning. I think there was such a big reaction to the last profit warning, that more disappointing news was already baked into the share price. This is confirmed by only a c.5% drop in the share price today.
Forecasts - the above guidance from the company seems to be steering us towards about 14-15p EPS for the current year (ending 01/2019). At 126.5p per share, that equates to a current year PER of about 8.7 - which strikes me as excellent value, for a decent quality business.
Brokers are talking today about a 6-10% reduction in 01/2019 forecasts, so nothing too serious.
Balance sheet - note there is a pension deficit of £7.3m, and the recovery payments were larger than I had realised;
The Group made additional payments to the pension schemes of £1,521,000 (2017: £1,374,000) to reduce the deficit, part of the ongoing planned reduction, along with £386,000 (2017: £392,000) of pension fund scheme expenses.
So I would need to look into that in more detail before considering any additional purchase of shares here. It doesn't look a deal-breaker though, but would require some adjustment of the market cap - mind you the PER is already low, so it looks as if this issue is already in the price.
Net debt - seems fine at the year end, but note that the average monthly figure was a lot larger. I commend the company for disclosing its average monthly net debt - this is very helpful, and should be done by all companies, to give a more accurate view of the underlying cash/debt situation throughout the year (as year-end figures are often window-dressed to show an artificially favourable picture);
The Group had net debt as at 31 January 2018 of £5,263,000 (2017: £5,309,000). Average debt during the year varies due to the timing and seasonality of revenues and investment in products.
The average monthly net debt increased by £8,206,000 to £11,246,000 (2017: £3,040,000) as a result of the Group starting the financial year with net debt following the Clarke & Clarke acquisition which increased the need to utilise the bank facilities.
Total bank facilities are £22.5m, so the group seems to be in a comfortable position regarding headroom.
Overall, the balance sheet looks fine to me - I don't have any concerns.
There's a solid NTAV base of £29.8m.
Working capital looks fine, with a current ratio of 1.80 (note this includes all bank debt)
Long-term liabilities are modest. So it's absolutely fine in my view - there are no solvency worries here.
Dividends - there's quite a useful rise in the final divi, up from 3.06p last year, to 3.68p this year. There's also a small interim divi to take into account. The overall picture is this;
This brings the total dividend for the year to 4.37p per share (2017: 3.61p), an increase of 21.1%.
That suggests management are confident about the future, and happy with the financial position of the group, which I find encouraging.
My opinion - It all depends whether this is a temporary downturn in trading, or whether a more serious longer term downtrend has started. That's for each of us to figure out, and essentially guess at.
For the reasons explained yesterday, I'm leaning more towards optimism, as the squeeze on real incomes now appears to be abating in the UK. Although I imagine for luxury interior furnishings, the customer is affluent, and probably not really affected by small changes in average incomes. The UK softness is probably more linked to the slowdown in the London property market, is my guess.
It's tempting to top-up my existing position here. However, as with Topps Tiles (LON:TPT) yesterday, the question is, what's the rush? The newsflow is still negative, and nobody likes buying shares which are trending down, opening up an instant loss. There again, the muted 5% share price drop today suggests to me that the bad news is mostly in the price already - and the news wasn't actually particularly bad anyway.
Somebody might come along and bid for it, at this valuation. So I'm happy to keep this as a small position in my portfolio for now, but might top up later this year. I'll probably wait to see what the next trading update says.
Having had a major flood, and a fire, I imagine WGB's insurance broker must be under heavy sedation by now. What will the next RNS be? Stampeding wildebeest have destroyed new season's production? A swarm of locusts have eaten their inventories?
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
For those requesting Paul's view on Castleton Technology (LON:CTP) he didn't like the balance sheet in November.
Jon
Quote:
Balance sheet - this is where it all goes wrong for me.
NTAV is negative, at -£16.0m. That's a lot for such a small company.
Current ratio looks very weak, at only 0.47. As with Ideagen above, the business is being funded by up-front payments from its customers. Deferred income is £6.3m.
Note that non-current liabilities are also substantial for the size of business, at £11.0m. This includes £2.8m in borrowings, £2.4m in convertible loan notes, and other items.
i ran this test on a few of the struggling names out there (manual work, unable to create a screener for this)
only takes a couple of minutes to check each name
mrosbiston - It might be just my screen, but I can only see 6 1/2 of the companies you reviewed - any chance of reposting the graphic?
Anyway it will be interesting to see how these companies pan out on the basis of these tests, and whether there is in fact any relevance at all in the rations considered.
To be honest, my initial view of the walbrockresearch article was that it was a flimsy piece of rear-view mirror analysis. Certainly all of the items mentioned can be construed as "poor" (although some of them were subjective) but there was no evidence provided as to whether statistically they lead to companies going bust or on the other hand whether they cause the market to take an unjustifiably negative view and therefore actually provide a contrarian buy signal.
It's certainly something worth tracking, but given the lack of evidence provided it would imho be impossible to call it instructive.
I was tracking 3 of the 6.5 companies anyway, 2 with an expectation to buy if and when there is clear evidence that the wheels haven't come off, so it adds a little to me here.
last company was RTN - only 1/4. It does appear to have the strongest balance sheet of the seven, positive NTAV, could be a possible candidate for a turnaround rather than permanent decline (would need to look into it in greater detail than my cursory look).
i agree there is a fair amount of 'rear view mirror' analysis, we can say that with pretty much every bankruptcy (Enron, Worldcom, Globo etc - take your pick). If we are investing in turnarounds or anything contrarian, then you are going to be picking the odd disaster here and there and we accept the risk. Agreed it is very difficult to objectively analyse.
With regard to Watkin Jones there seems to be a number of companies getting in on the idea of building student properties, Empiric Student Properties among others. There must be some sort of limit to the number of blocks of apartments that are needed for students. Is it perhaps just a temporary demand that is being filled?
Watkin Jones Watkin Jones (LON:WJG) isn't just about "building" (and onward selling) student properties, but attached to that business is the happy side effect of a cashflow receipt from managing those properties once completed and occupied. Even if the growth in new projects is encumbered with reaching a "limit", the underlying property management business cashflow is to be considered.
Hi Paul , interested in your views on Treatt. Good quality business historically beginning a big expansionary capex cycle . If not sure if this is something to be afraid of for future ROCE, or welcomed for EPS growth ?
Paul,
Re: Conviviality (LON:CVR) - you mentioned yesterday "When I've got time, I'll revisit the numbers, and see if there were any warning signs in the previous figures."
Only had a very brief glance at this, so can't comment on the quality, but may save you some (or a lot of) time
https://walbrockresearch.com/the-conviviality-guide-of-spotting-red-flags-and-saving-your-money/
thanks very much for this link - great reading.
some of these are difficult to spot without a deep-dive. however, there are some simple ones we could all apply.
Red Flag one: Falling operating cash flow
The obvious sign of distress is when Operating Cash Flow fell from £7.3m to £528k
Red flag seven: Lack of cash in the company’s balance sheet
A business with higher credit sales in proportion to cash sales should hold more cash on the balance sheet. That led to cash as % of total assets falling from 10% to 1.5%.
Red flag nine: No Assets and lots of goodwill
When you have increased net debt, it’s wise to have sufficient levels of REAL and LIQUID assets to prepare for periods of lower profitability. With less than £3m in freehold assets and over £200m in goodwill
Red flag ten: Paying dividends with external borrowings
You know management cares about appreciating their share price when they’re paying increasing amounts of dividends. Who is actually paying the dividend to who? Since 2013, it paid a total of £34.9m, at the same time it asked £200m in shareholders cash.
Thanks to Walter Hin for highlighting these red flags
Inline trading statement from Watkin Jones (LON:WJG) today. Student accommodation looks strong with marketing now taking place for 2019/20 and 2020/21 academic years. Build to rent also seeing a lot of activity with a ramping up in the number of development sites. Steady as she goes.
Walker Greenbank (LON:WGB), keen on any thoughts:
full year results to 31 January 2018 looks good to me, but caveat is the year ahead may not match the prior years' growth.
· Sales up 17.7% to £108.8 million (2017: £92.4 million)
· Total statutory profit from operations up 78.6% to £14.0 million (2017: £7.9 million) due to a full year's earnings contribution from Clarke & Clarke
· Adjusted underlying profit before tax* up 20.2% at £12.5 million (2017: £10.4 million)
· Licensing income up 21.6% in constant currency at £3.1 million as a result of range extensions into new product categories
· Underlying profit from operations** up 25.8% to £12.4 million (2017: £9.8 million)
· Adjusted earnings per share* up 6.2% at 14.52p per share (2017: 13.67p per share)
· Final dividend up 20.3% to 3.68p per share (2017: 3.06p per share), giving a total dividend up 21.1% at 4.37p per share (2017: 3.61p per share)
· Direct business model launched in Moscow in February 2018, including a new showroom, with Germany to follow in H1 2018
All sounds great, but ends with a cautious look-ahead statement:
In the first nine weeks of the current financial year, Brand sales were down 8.3 per cent in the UK and down 3.8 per cent overseas in constant currency, down 6.1 per cent in reportable currency.
trading to date in the current financial year makes us cautious about the outlook; as a consequence, the Board expects that profits for the full year will be ahead of last year's but below current Board expectations. We will provide a further update on trading at our annual general meeting in June 2018."
Walker Greenbank (LON:WGB) final results today show large increase in profits and dividend in part due to a full year contribution from Clark and Clark but outlook statement is unsettling and talks about a difficult market and falling revenues in first nine weeks of current year. SP down about 4% in early trading
Paul, I believe you were a holder back in January so your views would be appreciated.
Paul,
A request for Castleton Technology (LON:CTP) which I hold. The company came to my attention via a PI World presentation and in the boring world of providing IT services to housing associations, councils and the PRS sector I think could be a strong growth story. The company has been around for 20 years but the two guys at the helm have only been there a couple of years and are making rapid progress with a very large market relative to the size of the company. I think around 90% of their clients only use one of the six services they provide and so the potential for cross selling is enormous. I always found it was easier to get business off an existing client rather than chase prospets.
Dave
I second Castleton Technology (LON:CTP), to me it's the share of most interest out there today.
Trading Update is basically in-line and optimistic for future growth.
Hi Paul. You’ve a small typo. You’ve put in a link to Headlam rather than James Halsted by mistake.
Hi Graham,
Hi Paul. You’ve a small typo. You’ve put in a link to Headlam rather than James Halsted by mistake.
Thanks, I've just corrected that, as a friend emailed me . Sorry, not enough coffee yet! ;-)
Regards, Paul.
Paul,
Would be pleased if you covered Adept Telecom (LON:ADT) following their positive YE trading update.
Please note in what could be described as a reverse Ronseal moment it is not a telecom company albeit the market appears to continue to rate it as such. The vast majority of it's business is in managed IT services and a few months ago it applied to drop Telecom from it's name and presumably is still awaiting formal appproval from the powers that be. It has already dropped Telecom on it's website.
As a capital light company growing rapidly through acquisitions using it's strong cash flow and relatively low net debt it does tend to always refer to underlying EBITDA rather than a speific net profit range which is somewhat annoying.
Clients include Oxford, Cambridge and many more Universities , over 4000 schools, 100 Council's, The Houses of Parliament and they servicice over 1M Office 365 users.
I hold.
Thanks Dave.
My morning smallcap tweet:
Adept Telecom (LON:ADT), Airea (LON:AIEA), Fastjet (LON:FJET)
Adept Telecom (ADT) guides slight FY beat in underlying EBITDA and rev.
Airea (AIEA) James Halstead considering making an offer.
Fastjet (FJET) Underlying FY trading broadly in line with expectations. Also buys three ATRs with shareholder loan of $12m at higher of LIBOR + 6.45% 8% until 30 June 2019 then higher of LIBOR + 8.45% or 10%. And this is for a secured loan!
Hi Paul, Wey Education (LON:WEY) has released a company update providing some positive details on its recent acquisition which seems to be integrating well and trading ahead of last year. I know it's a company you were interested in a while back and wondered what your thoughts are now with the recent share price self-off?
Wey Education (LON:WEY)
probably not enough information in the update for any real insight - certainly positive noises about the A21 acquisition integration and the new FD seems a safe pair of hands.
Think we will have to wait until interims on 8th May for any real insight.
This seems to be what has got the share price moving. although on only 9,000 shares so not taking too much from it. My view on the decline is that it has been post good news drift - and moderation of over exuberance in the valuation. You can see there has been hardly any buying volume since November 2017, some modest selling volume but nothing major - the crux has been there has not been enough buying to support the share price - so not enough interest at this valuation. That could change with some stellar results in May, i will hold until those results.
(disclosure - i hold)