Small Cap Value Report (Thu 6 Apr 2017) - FREE, MTC, MYSL

Good morning! It's Paul here.
First day of the new tax year. I've already seen some Tweets from sensible private investors that I follow, saying that they're about to deploy their freshly invested cash in ISAs and SIPPs. So perhaps that might provide some support for small caps? (the amounts are probably too small to make any difference to larger caps).
I'm hearing that AIM IHT fund managers are seeing good cash inflows from clients too. So that's also a positive for decent AIM shares, because they'll generally keep buying more of their existing holdings in the market.
Today I shall definitely be reporting on: FreeAgent Holdings (LON:FREE) , Mothercare (LON:MTC) and MySale (LON:MYSL) .
Time-permitting, I also hope to cover some or all of these: Epwin (LON:EPWN) , Motorpoint (LON:MOTR) , Findel (LON:FDL)
FreeAgent Holdings (LON:FREE)
Share price: 121.5p (up 4.3% today, at 09:26)
No. shares: 40.7m
Market cap: £49.5m
(at the time of writing, I hold a long position in this share)
Trading update - for the year ended 31 Mar 2017
This is a recent float, with the shares listing on AIM in Nov 2016.
The company provides cloud-based bookkeeping software, specifically designed for micro businesses. It's important to grasp that this software is very user-friendly, and easy for non-accountants to use. Hence it's ideal for the smallest businesses - often one person bands, like consultants, or self-employed tradespeople.
The closest competitor is probably QuickBooks, which is advertising a similar product on TV at the moment.
Other cloud-based software products like Xero, are not really direct competitors, as they are much more feature-rich, and less user-friendly (I use both Xero & FreeAgent personally, for small businesses that I'm involved with).
As part of researching the share, I took a free trial of FreeAgent. After playing with it for an hour or two, I liked it so much that I transferred my limited company accounts onto it permanently. It drastically simplified my tax year-end. So I'm a very happy, paying subscriber. It's a terrific product, which is remarkably easy to set up and use.
I've also asked several firms of accountants what they think of it. The answers were that Xero is best for small businesses, and FreeAgent is best for micro businesses. They really like both products, and find it very efficient to have the clients doing the basic bookkeeping, then the accountant logs in via the cloud, and finishes off the year end, and tax stuff.
So cloud-based software is definitely the way forward for small businesses.
Anyway, back to today's trading update, which says;
For the full year ended 31 March 2017, the Board expects to report both revenue and Annualised Committed Monthly Recurring Revenue ("ACMRR") at the period end in line with market expectations at £8.0 million and £8.6 million respectively.
Both the adjusted EBITDA loss and period end net cash are expected to be comfortably better than current market expectations. The Group's gross profit margin remained above 80%.
A few comments from me, on the above;
The company has failed to specify what current market expectations actually are. This is a mistake. Other companies are increasingly putting in a footnote to specify precisely what market expectations are. Otherwise the announcement is largely meaningless for the (probably bulk of) investors who don't happen to have market forecasts to hand.
I don't have any forecasts available at the moment, so can't therefore comment any further on the forecast figures. Really annoying. I've put in a request for the latest forecast figures, so will come back & edit this section if anything is forthcoming.
The company is still loss-making, but with very sticky revenues, and strong organic growth, it's clearly on the right trajectory towards profitability. That's why the market cap is nearly £50m - because the market is anticipating a future move into profit.
Recurring revenues - a key feature here is high gross margins, and very sticky revenues. It's true that a lot of small businesses go bust. However, as FreeAgent is targeting micro businesses, then even if those businesses do go bust, the same person will usually resume trading straight away via a new limited company, or as a sole trader, and will probably use the same accounting software in the new company.
Cash - good to hear that it's ahead of forecast. Although at the most recent accounts (interims) the balance sheet looked weak, with some borrowings. However, this was fixed at the IPO, with fresh money raised, leaving a £5m net cash balance at IPO. This will have fallen somewhat since though, due to ongoing losses.
Marketing - the trouble with this type of company, is that to acquire new customers costs money, on marketing. This is a major expense. However, bear in mind that FreeAgent recruits customers via firms of accountants, and more recently a deal with RBS, whereby its software is distributed free with new small business bank accounts. That strikes me as an excellent way to recruit new customers. Even if they give away the software in year 1, there is then a lucrative stream of future years' subscriptions to look forward to.
My opinion - I rarely invest in loss-making companies. The only circumstances where I will, is if there are all the following factors in existence;
- strong organic growth
- high gross margins (giving plenty of operational gearing)
- mostly recurring revenues
- adequate cash resource to reach breakeven
- credible forecasts demonstrating a clear path to profitability inside 2 years
I've formed that checklist from my previous mistakes! (e.g. Synety, now CloudCall, which repeatedly ran out of money, despite the other factors being good)
In my view, FreeAgent ticks all 5 boxes above, therefore I am prepared to hold a few shares (it's not a big conviction position for me, more an entry level, see how it goes, type of position).
Also, I think the valuation might be a bit rich for now, so I don't see any particular immediate upside. There again, we're in a bull market, so anything could happen.
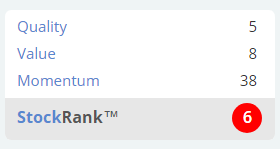
Stockopedia doesn't like it! I always check the StockRank, and am wary of companies with a StockRank this low - it's the algorithms warning me that I might be buying expensive junk. So it certainly pays to stop & think again, before pressing the buy button on anything with a very low StockRank.
Mothercare (LON:MTC)
Share price: 117.5p (up 2.8% today, at 10:50)
No. shares: 170.9m
Market cap: £200.8m
Trading statement - this covers Q4, and hence the full financial year to end Mar 2017.
This business is split between UK (problematic, and loss-making at the last interims), and International (which is decently profitable).
To quickly get up to speed with the company, I Iast reported here on 12 Jan 2017, when Mothercare issued an in line Q3 trading update.
Also, I reported here on 24 Nov 2016, on Mothercare's interim results.
I've just re-read both sections, to refresh my memory. The story here is whether the turnaround strategy is working or not.
UK performance - today's update points to a decent uplift in UK LFL sales - which rose an impressive +4.5% in Q4, taking the year's total LFL sales uplift to +1.1% - whether that's enough to recoup cost increases, is not clear.
Online UK sales - it irks me that the company says 41% of UK sales are now online. I don't think that's true, because previously the company has stated that it categorises orders placed in store, via a tablet provided by the company, as online sales. That's ludicrous! If the customer is actually in the store at the time of placing their order, then it's clearly not an online sale. It undermines my confidence in everything else, when companies try to be too clever with this type of thing.
Margin (presumably net?) in the UK is said to be "within our guidance for the full year", whatever that is. I can't see any footnote to indicate what guidance is. So this appears to be yet another trading update which has mainly been written for city brokers to update their models, rather than for private shareholders to better understand the business & its performance.
Overall UK performance sounds moderately encouraging, although it's important to remember that this business has seen heavy investment in store refits. Therefore, it really should be generating tons of profit, but isn't. I therefore see the UK business as being marginal, at best.
International - this is the important bit, as it makes the profit.
The announcement today doesn't seem to give LFL sales figures. The most meaningful figures to me are the quarterly % change in sales, in local currency. These show a tough period of trading, but with an improving trend, as follows;
- Q4 last year: -9.7%
- Q1 this year: +3.9%
- Q2 this year: -5.6%
- Q3 this year: -5.9%
- Q4 this year: -1.7%
Total this year: -2.4% (for the 52 weeks to 25 Mar 2017)
Overall then, a rather erratic performance, and generally negative (apart from Q1). Q4 performance was still negative, despite having a very soft prior year comparison. So not great, but not disastrous either.
However, note there is a very favourable forex tailwind, so these lacklustre local currency figures translate into much stronger sterling, +10.3% for the year.
Overall profitability - the Directorspeak says this;
"Following a solid final quarter, our overall Group performance remains broadly in line with market expectations for the year.
I can't quite fathom why they're only broadly in line, if Q4 was solid. This suggests that maybe forecasts were too high previously, perhaps?
Valuation - I've just been emailed some info on forecasts, and it seems that the current range for FY17 is between about £18 to 21m. That's probably adjusted profits.
Stockopedia shows an EPS consensus forecast of 9.27p for this year, so if we assume it might be a bit below that, say 9.0p to be prudent, then I make that a PER of about 13.
Note that there's a fairly hefty pension deficit here, to factor into the valuation too.
My opinion - there are some encouraging signs here, of a potential turnaround happening, maybe? There's also interesting narrative about 10 new international websites being launched in the last year, with 21 countries now trading online.
The upside case here is whether the company can demonstrate a geared recovery. At the moment, it's only generating a very small net profit margin. However, if growth can be achieved, then the benefit to the bottom line could be considerable.
There are no divis whilst we wait to see if the turnaround is working though.
The turnaround might work, it might not, I don't know. On balance, I don't think it's clear enough what the future holds, to tempt me into this one.
MySale (LON:MYSL)
Share price: 109p (up 1.9% today, at 12:16)
No. shares: 151.3m
Market cap: £164.9m
(at the time of writing, I hold a long position in this share)
Acquisition - this is an insignificant acquisition in terms of money paid, less than 3m Aussie dollars, or about £1.8m.
The acquisition is called;
Identity Direct, a leading international retailer of personalised products.
The reason I mention it, is that we're starting to see consolidation amongst eCommerce companies. If you recall, Boohoo.Com (LON:BOO) recently bought the brand, and customers list of Nasty Gal, a US online fashion company which went bust.
MySale is also active with acquisitions. It has experienced management. I met the Chairman & FD recently, and they outlined their longer term ambitions for MySale - seeing it as becoming a portal for many different brands. Originally MySale was a "flash sales" fashion website - i.e. a clearance site for out of season, or slow-selling stock. They are reduced heavily for a short period, until sold out. This works very well, as MySale doesn't have to actually buy the inventory.
MySale is basically providing a portal for increasing numbers of brands to shift their end of season summer stock in Europe, into Australian & other Far Eastern markets, when summer is just beginning. Also, it's developing other business lines.
The Chairman made a remark which very much stuck in my mind, he said;
There are no barriers to entry in online fashion, but there are huge barriers to achieving scale.
That very much ties in with my thinking - lots of people have tried to copy what Asos and BooHoo are doing, but very few have managed to achieve any significant scale. MissGuided, and one or two others have, but not many. The big problem is the enormous marketing spend that is needed to achieve scale.
So I think we're likely to see lots of smaller online fashion companies eventually go bust, when investors tire of their insatiable thirst for marketing spending. Then the successful players, like Boo, and to a lesser extent MySale, are likely to pick up the IP on the cheap, and bolt it onto their existing operations. Which is likely to further boost the winners.
There is more detail given in today's update, on how Identity Direct not only has a valuable customer database which can be cross-sold into, but also how MySale can improve its performance by cost efficiencies (e.g. on shipping costs).
My opinion - this acquisition looks good, and is cheap. I imagine there are likely to be more such deals in future. This all helps drive growth.
Like most online fashion companies, MYSL is very difficult to value. PER doesn't work with valuing growth companies, because it's a measure that's more designed for mature, stable companies. Hence you can get ridiculous results if you try to value online fashion companies by PER - Stockopedia shows it as being a PER of 258 for this company!
The likelihood is that in a few years' time, MYSL should have grown into the valuation, and also increased its margins - since marketing spend can be reduced once this type of company has achieved enough scale, and has enough customers that it can talk to directly. In the meantime though, all these companies look very expensive. It's not as crazy as it looks though, once you understand where this type of company could be in 5 years' time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
For me, gold comes into it's own when there are black swan events and forex volatility. However, rather than buy gold ETFs, I have a couple of gold miners who are a) profitable at a much lower gold price and b) pay a dividend. I have also been working on identifying equities to use as cash proxies (low volatility and/or defensive), again dividend paying. If/when markets get more toppy, I'll add to these holdings. The primary aim being to have a segment of my portfolio that can earn a decent divi while providing funds to buy other holdings at lower prices if there is a big market fall.
The motivation for this is that I spent 5 months of last year holding 40% cash (Brexit/Trump etc.) and I have really been feeling the loss of divi income as a result. The market can stay irrational longer than expected, so I am looking for an alternative strategy to benefit from this bull run while having a decent hedge in place that is less of a drag on the portfolio than either holding cash or shorting the index.
FWIW, according to Digital Look, the expectations for FreeAgent Holdings (LON:FREE) are Revenue - £7.62m for y/e 3/17, £10.25m for 3/18 and £13.21m for 3/19. PBT - (£1.89m) for 3/17, (£0.27m) for 3/18 and £1.5m for 3/19. EPS - (4.39p) for 3/17, (0.62p) for 3/18 and 3.48p for 3/19. Revenue for 3/17 of £8m looks to be a few percent ahead of the estimate. PBT margin on incremental revenue looks to be 61% for 3/18 and 59% for 3/19 so a lot of additional revenue is expected to drop through to PBT. Don't know enough about the company to know how they treat development expenditure.
I took near term to be in the future rather than the present or recent past. Either way, one would expect to begin to see a clear return on this investment as 2017 results unfold. Time will tell if that is so.
Triad (LON:TRD) (which I hold) put out a bullish update today at 2pm! SP rose 17%
Seadoc
But we've already had the final results for 2016. Capital investment (tangible and intangible) was up 90.6% from £10m to £19.1m - that's what I was referring to.
http://www.stockopedia.com/share-prices/iqe-LON:IQ...
"Capital investment increased to £19.1m to address near term growth opportunities"
Sorry crazycops,
Thank you, I thought I had seen the results, it is the AR that will be available in May. Mind you the initial results are even more perplexing:
Profit is another 19,440,000 but cash up but 4,957,000 (from 4,644,000). Cash used on investing is well up, £30m from £10m but this includes capitalised development of £6.3m up from £4.9m and even more worrying deferred payment to Koplin of £11.25m. I thought this was already included in the accounts of three years ago? Not sure I can find new capex of £19.1m anywhere in that. Indeed £19.1m from £10m less £11.25 less £(6.3-4.9)m is actually significantly less capex?
".... to address near term growth opportunities"
Yes it was near term but recent near term and not actually in the future?
Regards,
Seadoc
The £19.1m capex is broken down as £6.3m development expenditure, £1.8m intangibles and £11m of property, plant and equipment.
On the deferred consideration for Kopin, I think you are confusing cash and accounting transactions. The deferred cash was paid in January 2016 which is why it appears in the cash flow statement for this period, but the acquisition itself took place in January 2013 so the whole cost of the investment was recorded in the books at that time with the deferred payment being carried in the books as a liability until it was settled last year.
Seadoc, re: IQE (LON:IQE) in 2016 there was a significant increase in capex which was focused on ramping up production capacity. My hunch is that is connected to the new smartphone releases this year but the company are constrained by NDAs so for now, it is all speculation. This said, the trading volumes are very large at the moment and almost certainly a result of increased institutional activity. IQE (LON:IQE) is probably my riskiest holding at the moment but things could get very interesting in H2.
crazycoops,
"in 2016 there was a significant increase in capex ...."
Cash flows from investing activities: 2015 2014
Capitalised development expenditure (4,979) (4,957)
Investment in other intangible fixed assets (1,198) (1,291)
Purchase of property, plant and equipment (3,825) (3,178)
Net cash used in investing activities (10,002) (9,426)
I assume you mean that in May 17 we will learn that the cash flows from investing in Capex will show an increase in 2016 compared to the figures above?
".....which was focused on ramping up production capacity."
But they already have surplus capacity, and a bit, at the moment. Yes could be a change of plant rather than more of the same but I have a horrible feeling that the "spend" will be related to donations to the new centre at Cardiff University.
"...is probably my riskiest holding at the moment but things could get very interesting in H2."
Voted you up for that! Just my view,
Seadoc
I think gold is a pretty good hedge at the moment, I can see things getting worse in the next 2-3 years, how long has the bull market lasted? when was the last recession? Elections in Europe, Brexit, Trump, North Korea, Syria, the world is getting a more volatile place. Yes it's a short term investment, it's not long term.
I agree re gold/silver investment but truly wouldn't touch anything that uses rand as a currency. Zuma has all the hallmarks of a Mugabe and things could get a lot worse before they get better. His latest idea of getting his ex wife to stand in order to get around his own exemption of two terms is typical of uneducated leaders who have embezzled so randomly and freely that they just cannot afford to lose power. Also the reason I have never backed Norcros which as Paul has stated several times appears undervalued.
Camtab,
"Zuma has all the hallmarks of a Mugabe and things could get a lot worse before they get better."
Voted up for that but:
"Also the reason I have never backed Norcros which as Paul has stated several times appears undervalued."
Mrs Zuma does not like her new bathrooms?
Seadoc, holding a few Norcros (LON:NXR)
Paul, you mention that you do not have access to company estimates. I remember that you were trying Research Tree, have you discontinued, if so perhaps you would be able to share your experience.
Thanks
Hi xxx,
Re broker estimates - I can usually get hold of them, but it's a bit of a ball ache. When I'm writing the first few sections of these reports, sometimes I've already been emailed the latest broker notes, and sometimes haven't. When there's very little broker coverage, it can sometimes be just down to waiting for one broker.
I find Research Tree very useful, and continue to subscribe, and will do for the foreseeable future. (I'm a paid up member, and didn't try to blag a free login or anything - am happy to support what is a terrific service).
Obviously, RT doesn't cover all brokers, but there's enough good stuff on there to make it worthwhile, in my view. So say today for example, I put the MYSL ticker into RT, and up popped a Zeus update re the acquisition announced today, which was useful.
I just wish all companies would clearly state in their updates what the broker consensus is, and then whether they reckon they'll be ahead, in line, or below. It's not rocket science, why do they have to make it all so complicated for us?
Regards, Paul.
Agreed.
It is a manifestation of the unequal status of private shareholders.
You might consider standing for parliament.In too many areas, when the review bus of legislation comes around, the changes are limited to a few areas, with a view to the headlines and PR, rather than a careful, one off enshrinement of sensible practice based on a principle, in this case equality.
Management pay is another area.
Be careful with FreeAgent Holdings (LON:FREE).
Most of the users will be one-man band contractors. The only reason they want a Ltd company is because it means they can pay less tax by paying themselves a low salary and making up the rest in divis.
There will be no point in doing this soon. When the IR35 changes, that have just come in to force for public sector workers, come into the private sector too then this will drive people away from Ltd companies and into umbrella companies.
It's a great product and I use it myself but the pool of potential customers is about to be drastically reduced.
Hi Philip,
That's a good point re tax changes making a ltd company less appealing to operate through.
Although remember that limited liability is the other big benefit of operating through a company, as opposed to a sole trader, if there was some unforeseen catastrophe then the ltd company would usually ring-fence any potentially disastrous liabilities.
I'll ask my tax adviser about the issue of rule changes.
Regards, Paul.
P.S. Ah, I've just realised - FreeAgent isn't just for limited company accounts, it's also for sole traders! In fact, you can do your personal taxa return on it. Therefore the tax changes you allude to shouldn't make any difference - micro businesses will still need to use a program like FreeAgent, irrespective of whether they're trading through a ltd company, or as a sole trader. So panic over, I think!
It's still a problem.
Operating as a sole trader isn't an option for contractors (end clients want to deal with a limited company, not an individual).
If they don't have their own Ltd. company, contractors instead operate through umbrella companies such as Parasol. See http://www.parasolgroup.co.uk/umbrella/ They do all the tax and N.I. so you don't need to do your own accounts.
If they abandon operating through their own limited companies - and many will - then they won't need FreeAgent.
The extra kicker is the changes to the VAT flat rate scheme which makes contracting through your own Ltd. company even more pointless - http://www.contractoruk.com/vat/it_contractors_flat_rate_vat_guide_april_2017.html
Hi Phillip
I agree with all your points.
A lot has changed in the last few years as the government clamps down on one-person limited companies (though I didn't realise the IR35 changes affecting public sector workers are being pushed (have been pushed?) into the private sector as well.)
I can't remember the details, but I thought that the IR35 changes were mainly going to impact higher earners, so maybe those on lower rates operating through Ltds will be happy to continue using, or start using, a company like FreeAgent?
2 other points come to mind:
- I believe the government is also coming down on companies such as Parasol, so maybe people will be less inclined to shut down their ltd companies?
- If a recession is coming, I believe there's usually a boost in people setting up shop for themselves, either as sole traders or though limited companies, so that could be a boost, albeit a short-term one, for the likes of companies like FreeAgent.
For reference I do not hold.
I work as an I.T. contractor so I'm fairly up on this stuff.
The new changes may well mean that a lot (most?) contractors will now be deemed to be inside IR35. That's because the end client or agency now has to make the decision instead of the worker (contractor) about whether or not the worker is inside IR35 or not.
At the moment, this only applies in the public sector. See http://www.contractoruk.com/ir35/public_sector_contracting_april_2017_ir35_changes_explained.html
There are credible reports on LinkedIn, etc. that people are working on software to enable the same changes to be brought into the private sector too. That would seem to be common sense, why keep it just to public sector contractors?
There is no crackdown on companies like Parasol. You might be confusing them with dodgy offshore "loan" schemes, etc. ? It's not like that. Using Parasol means that the contractors are an employee for tax purposes and pay "normal" amounts of tax which is what the government wants.
AFAIK, it makes no difference how much you earn although there's a point at which running a Ltd company isn't worth doing if your rate is too low.
It's quite possible that FreeAgent Holdings (LON:FREE) can increase revenue from sources other than contractors. However, I imagine that contractors are a big chunk of their revenue. Maybe I just think that because I am one?
But, if I were to start contracting now, there is no way I would bother going down the Ltd. co route because there's no point financially anymore really.
Hi Philip.
Interesting. I suppose the key question is what percentage of FreeAgent's clients are actually contractors? It may only be a small minority, who knows? It's probably something we need to find out.
There are millions of small businesses which are bona fide, and not operated for any tax benefits.
Regards, Paul.
Yep, true.
I would guess a fair chunk of them are contractors. But they probably have loads of freelancers like photographers, web designers, etc. So I don't know.
It's great software, I use it myself. They don't seem to have great competition either.
I wouldn't be surprised to see it be bought out by Sage.
Paul,
Agreed with on Mothercare and especially regarding online sales. This abuse has got to stop, which is why I don't pay attention to online sales growth, but look at overall growth. At the same time paying close attention to margins improvement.
But I give Mothercare some credit for sticking around. Thought the business would have packed up shop by now.
I used to be excited by MySale (LON:MYSL) but I sold out last week as I think there's limited upside on the share price for a number of factors including:
- Too much competition with MySale (LON:MYSL) at risk of being the loser. I see Brand Alley being well marketed. I do not see Cocosa (£MYSL) being well marketed. BrandAlley UK has 250k likes on Facebook; Cocosa UK has 130k likes - albeit I recognise MySale (LON:MYSL) is still fairly new in the UK although BrandAlley isn't that well established either. I asked the 20somethings in my office what they use and they mentioned other discount sale websites and had never heard of Cocosa. Surely this will suppress margins as clothing brands will just go to the website with most reach and/or that offers them the best deal? Especially if consumers use multiple sites not just stick to one. I don't know how well funded the other competitors are but BrandAlley has a large French parent company that looked well funded. BrandAlley operates throughout Europe already so MySale (LON:MYSL) is losing out there although ahead in Aus/NZ
- But slowing growth in Aus/NZ which might turn negative if these other competitors expand down under.
- A failed attempt to produce its own clothing brand
- Margins aren't improving as quickly as previously indicated
- Broker targets have been downgraded. Before recent downgrades the house broker expected 1.9p EPS in 2019 which makes it look more expensive than a lot of other higher margin growth shares I would argue.
On the plus side it's Cocosa website has had increasingly better stock and brands over the last few months so its offer to customers in the UK is definitely improving. It also has a lot of cash to potentially make good acquisitions.
I'm keeping a relatively open mind but just nervous that the low margins and strong competition mean there's limited upside on the current SP. Unlike Purplebricks (LON:PURP) Boohoo.Com (LON:BOO) and BrandAlley etc I don't see it executing on its marketing very well but maybe I am looking in the wrong places.
Anyone considering buying this share should sign up to cocosa.co.uk - it's v easy to research!
Hi paraic84,
Cocosa is so small, that it's almost insignificant to MySale. So that should be seen as a startup almost. But it's growing fast in % terms, albeit from a low starting point.
The main business is in Aus/NZ.
I don't see MYSL as madly exciting, but you need to factor in that management is very ambitious, and experienced. Plus they have Philip Green & Mike Ashley as major shareholders, who are also now supplying Arcadia Group & Sports Direct stock for expansion.
When I met management recently, they seemed pretty excited about future growth. It's not a business that's standing still by any means. So I'm hoping that we might see an acceleration of growth in the coming few years.
Broker note out today from Zeus (available on Research Tree) does a sector comparison, and reckons MYSL is worth about 184p if you compare it with a basket of peers on an EV/Sales basis.
Personally I see MYSL as a steady riser over next few years, with potential for big upside, if growth & margins really start moving up strongly, which they may, or may not.
Regards, Paul.
One favorite of mine is Begbies Traynor (BEG) which administers insolvencies and more recently property auctions. That makes it counter cyclical to some extent, and also IHT relief is an attraction.
As for gold I have fun money in Humming Bird (HUM), but much more in European Metal Holdings (EMH) which is an Australian outfit quoted also on AIM having (reputedly) large lithium and tin resources in the Czech Republic not far from German car plants. Hope no widows or orphans reading this.
Pan African Resources (LON:PAF) suggestion as a hedge, not a whole fund strategy. Pays a dividend. Been up to 21p this year -now down to 15pish. Just a thought.
I have put £20,000 into my ISA but it was a Bed and ISA, all I'm doing is moving high dividend shares into my ISA shelter, so yes my ISA has gone up by £20k but not my share investments. Dividend and capital gains tax has become a right pain.
Simoan
Maybe if you don't already you should perhaps look at a good Gold stock as a hedge. What's good is moot of course!
I am in at Pan African Resources (LON:PAF).The downside with this stock is perhaps Rand currency movements. However, arguably undervalued at the moment?
I use ETFS PHYSICAL GOLD ETC (LON:PHGP) for gold exposure and ISHRS INDX LINKED GILTS GBP DIST ETF (LON:INXG) for index-linking.
Gold? I'm with Warren Buffet on Gold:
"Gold is a way of going long on fear, and it has been a pretty good way of going long on fear from time to time. But you really have to hope people become more afraid in a year or two years than they are now. And if they become more afraid you make money, if they become less afraid you lose money, but the gold itself doesn't produce anything."
"I will say this about gold. If you took all the gold in the world, it would roughly make a cube 67 feet on a side…Now for that same cube of gold, it would be worth at today's market prices about $7 trillion – that's probably about a third of the value of all the stocks in the United States…For $7 trillion…you could have all the farmland in the United States, you could have about seven Exxon Mobils (NYSE:XOM) and you could have a trillion dollars of walking-around money…And if you offered me the choice of looking at some 67 foot cube of gold and looking at it all day, and you know me touching it and fondling it occasionally…Call me crazy, but I'll take the farmland and the Exxon Mobils."
All the best, Si
Much as I admire Buffett’s quotability, it should be borne in mind that he is talking as a long term buy and hold owner of a portfolio of businesses whose success is directly correlated with the health of the global economy over the long term.
People buy gold as a hedge. If like Buffett you’re happy to hold through the down cycle in anticipation of recovery on the other side, then using gold as a hedge makes no sense.
Absent any Armageddon scenario, he is almost certainly correct in the longer term, but for anyone with an investing horizon shorter than 'forever', which includes anyone who is looking at the markets today and thinking they are more tempted to sell than to buy (I don't think you are alone in that regard), I would suggest that the Buffett view is not necessarily the best way to frame the question as to whether gold is an attractive investment right now.
Much as I admire Buffett’s quotability, it should be borne in mind that he is talking as a long term buy and hold owner of a portfolio of businesses whose success is directly correlated with the health of the global economy over the long term.
Yes, I agree and that's pretty much my approach too. I could live for another 35 years and will need to use my investments as income in future, because by the time I get to retire the government are not going to give me anything, so I am taking a long term view of being in equities.
People buy gold as a hedge. If like Buffett you’re happy to hold through the down cycle in anticipation of recovery on the other side, then using gold as a hedge makes no sense.
IMHO it's a very crude hedge for a portfolio of UK Small Caps as we normally discuss here, so I don't really understand why people mentioned it. I am nearly 40% cash in my SIPP and can't for the life of me see why I should use new money to hedge by buying a Gold ETF. What does that achieve? Yes, I have some holdings which are looking expensive, but that's a long way from expecting the world to end, so why not sell and buy something cheaper or hold cash - why go long Gold? I have never understood the attraction and the thought of wearing it makes me shudder :) If I ever buy gold it will be just before I buy the tinned food, ammunition and disappear into a secure bunker... I had this discussion with someone that works in financial services in 2010 and he was stuffing Gold in his and his wifes ISA's instead of equities....where has that got him?
All the best, Si
If shares crash then gold will almost certainly go up. Small companies are more likely to go down more than large caps. Is your portfolio anything like Warren's Buffett's? Most of his holding are US large caps. Cash is not earning anything. So what is your cash doing?
Being 40% in cash is itself a hedge of sorts and I suspect people might not have suggested gold if they had known you were a cashed up Buffet-style investor.
That being the case, I wouldn't worry so much about your stocks looking expensive. Chances are you could sell and they continue to get more expensive, or if they are long term compounders they will grow into their high rating over time, or you sell and end up buying stocks of lower quality stocks which look cheaper.
If you haven't already read that Lindsell Train case study on Unilever (LON:ULVR) from a couple of months ago, I can recommend it - it was basically showing how if a company can compound its earnings over the long term, movements in its PE ratio are rendered pretty much irrelevant, i.e. don't worry if a quality stock looks expensive now if you intend to hold it for the long term.
I'd say that's even more true of small caps on the basis of the 'elephants don't gallop' theory. It's difficult to know what individual stocks to suggest without knowing what you currently have in your portfolio but if you are holding your existing stocks with conviction on their quality if not their value, I'd suggest just topping up on those in light of the Lindsell Train evidence.
By the way if your friend was selling his gold in 2011 or 2012, he could have made a tidy profit. From the perspective of 2010 I can sort of see the rationale for buying gold as a hedge against inflation, given the then prevailing view was that masses of QE would inexorably lead to masses of inflation. That may still happen of course.
Hi bestace,
Being 40% in cash is itself a hedge of sorts and I suspect people might not have suggested gold if they had known you were a cashed up Buffet-style investor.
That being the case, I wouldn't worry so much about your stocks looking expensive. Chances are you could sell and they continue to get more expensive, or if they are long term compounders they will grow into their high rating over time, or you sell and end up buying stocks of lower quality stocks which look cheaper.
Thanks for your thoughts as ever, which I always find worth reading. Yes, I can see cash could be used as a hedge but I don't feel the need to be hedged currently and it's not something I have bothered with in the past.
As a bit of background I am not retired or a full-time investor with essentially a fixed size pot to protect and I am lucky enough to have very good personal cashflow to almost constantly invest. At work I am seeing anything but a world that's about to come to an end, quite the opposite in fact. I work in technology and my company has just had it's busiest quarter ever (and Q1 is normally the quietest) so there is a lot of new product development taking place or about to start and the general mood and outlook across a number of industry sectors related to technology is currently very buoyant.
If you haven't already read that Lindsell Train case study on Unilever (LON:ULVR) from a couple of months ago, I can recommend it - it was basically showing how if a company can compound its earnings over the long term, movements in its PE ratio are rendered pretty much irrelevant, i.e. don't worry if a quality stock looks expensive now if you intend to hold it for the long term.
Thanks, I wasn't aware of that case study and will take a look, although it sounds like the same approach used by Terry Smith and I already have a large holding in Fundsmith.
I'd say that's even more true of small caps on the basis of the 'elephants don't gallop' theory. It's difficult to know what individual stocks to suggest without knowing what you currently have in your portfolio but if you are holding your existing stocks with conviction on their quality if not their value, I'd suggest just topping up on those in light of the Lindsell Train evidence.
This was pretty much the conclusion I had come to. I'm happy to do this for some of my holdings but not all; things like Boohoo.Com (LON:BOO), Trifast (LON:TRI), Treatt (LON:TET), IG Design (LON:IGR), Tristel (LON:TSTL) are all looking pretty expensive on any conventional measure, and realise I have transmogrified into a Momentum investor :)
All the best, Si
Interesting to hear that people are happy to deploy their full new ISA allowance on day one. As it happens, my company paid a very large bonus into my SIPP recently and in addition to the new £20K ISA allowance I'm really struggling to find homes for new money. I will put some into my best few ideas and top-up some current positions but most of my current holdings are starting to look expensive and I am more tempted to sell than buy more.
In particular, many of them have benefited greatly from sterling depreciation in the past 9 months but this effect is going to drop out soon and maybe even reverse later this year (if you believe the currency experts). So I am a little hesitant to chase these companies higher and have started looking to build up positions in companies that will benefit from a bounce back in sterling.
Obviously, it's a nice problem to have and I'd appreciate any ideas for further research from the locals hereabouts as I'm not finding much of interest coming out of the Stocko screens! But then I don't normally use screens and so maybe I'm just crap at using them :)
All the best, Si
Si,
I have money from tender for shares of Avingtrans (LON:AVG) to maximum of CGT allowance, about £20,000 in a standard account, I have asked to put it into the linked ISA today. Like you I may struggle to find a home for it but I have put most of what was left end last year into Hayward Tyler (LON:HAYT) as I like and I would like to top up Avingtrans (LON:AVG) and I think there may be a mostly share issue to fund purchase, all assuming the offer goes ahead. Have you read Gervais Williams, Retreat of Globalisation? Very strong view that the next three years will not be the same as the last 30.
Regards,
Seadoc
Semi-conductor stocks have been attracting me recently. Both chip makers and the people who supply the equipment to them.
In the UK I have IQE which is rumoured to be about to benefit from the iPhone 8 having 3D sensing. They have many other promising uses and customers for their technology so not another Imagination situation in the making IMO.
In the US I have Advanced Applied Materials (AMAT) which supplies chip making kit and is in an up cycle.
Chip makers to look at include Broadcom (AVGO), Skyworks (SWKS), and Microchip (MCHP).
Alternatively the SOXX ETF offers broad semiconductor exposure.
I also have Apple which is benefiting from expectations of a bumper iPhone 8 upgrade cycle.
But all this is of course in the context that the US market is even more overheated than ours and Trump may never get a tax reform passed so staying in cash may well be a wise move.
Hi John, I think you mean Applied Materials, yes it's on my watchlist just have not pushed the buy button yet.
Hi Herbie,
Yes, you are right. I got mixed up with Advanced Energy (AEIS) which I also hold but with less conviction.
John,
I would agree that semi-conductors have a future. But IQE (LON:IQE) accounts give me a headache:
Year Profit Cash at yr End, all £'000
2015 20140 4644
2014 1996 5504
2013 6126 3258
2012 6631 2773
2011 3233
So from end 2011 profits of over £34m and cash up by £1.4m. Where go the cash? Certainly not dividends.
You clearly have a better understanding than I of finance. I have sold out.
Regards,
Seadoc