Small Cap Value Report (Thu 6 Jul 2017) - Quiz, BLTG, ENTU,

Good morning, it's Paul here.
Quiz
As promised, I'm coming back to you about my meeting yesterday with QUIZ. This company is a Glasgow-based omni-channel clothing retailer, which is due to float later this month. The RNS giving some details about the company is here.
It was almost like looking back in time for me, as the company's business model is so similar to my old employer "Pilot" - where I was Head of Finance from 1993 to 2002. Quiz operates from around 67 UK stores, plus about 140 concessions in department stores such as Debenhams. It also has growing overseas, and online sales. It sells about 60% of online sales through its own website & apps, and the balance through third parties, such as Debenhams.com
Its product is fairly cheap, and slightly niche - in that the company focuses on "dressy" items - i.e. special occasion wear for women, e.g. party dresses, evening wear, weddings, etc. So the company doesn't try to compete on basics, but targets higher margin special occasion wear. I noticed from the company's app that everything I looked at was 100% polyester. So what one of my friends refers to as, "all fur coat, and no knickers!"
I went in to the meeting feeling rather sceptical, but at the end of it was impressed. Management & shareholders are a British Asian family, which is usually best for the clothing sector in my experience. They're self-made people who know the sector inside-out, so a tick in the box there for management.
I also found their presentation well put together, with lots of positive facts & figures - e.g. decent profitability & growth. Although I struggled to hear the softly-spoken CEO - he definitely needs amplification to be heard over the noisy aircon at Panmure's offices. The meeting was full, with analysts and brokers, plus me & my broker. Sandwiches were placed in the middle of a large board room table, which most people couldn't easily reach, so few were consumed.
You can tell a lot from the way management answer questions. The first question was from a fund manager friend of mine, who asked management to elaborate on the company's insolvency in 2009. A tricky question, but management gave a clear & honest answer, saying that their rents were too high, which combined with the recession, meant they had to restructure. Since then, they've learned the lessons, and now operate a much lower risk model. So they only take on 5 year leases, are therefore not exposed to upward-only rent reviews. Also, payback times from capex have to be 2 years or less. Concessions can pay back in just 6 months (£25k capex, typical profit contribution of £50k p.a.). That's impressive stuff.
Overall, my impression of management is that they come across as open & honest, trustworthy, experienced, and capable.
Quiz operates using the flexible test & repeat model, also used by newer challengers in the sector, such as BooHoo. Having a chain of physical stores gives Quiz additional flexibility. So they can trial something on the website, and if it works then place a repeat order, knowing that the item should sell well in the shops. On the other hand, if something in the shops isn't selling well, then they can transfer the items back to head office, and clear them at a discount online. This frees up store space for higher margin sales. The test & repeat business model gives much higher gross margins than the conventional fashion retail model of ordering stock with long lead times. Test & repeat, with short lead times (much production is now UK-made) is a terrific business model, although there's nothing to stop many other fashion retailers doing the same thing.
A short video was shown of the company's newly (a year ago) revamped distribution centre. They spent £3m on that, and new IT systems. It was disclosed that the family own the distribution centre, and the fittings, and rent them to the company on terms agreed by the FD & NEDs as being arms-length. That type of thing is quite common at private companies, and is not necessarily a problem, if fully disclosed, as in this case.
There has been strong growth in revenues & profitability in recent years. The company makes a decent profit margin, both gross and net. Online growth is particularly strong at the moment (about 120% Y-on-Y growth), but coming from a low base of only about £12m online sales last year. Although it should be noted that the current strong LFLs could be flattered by weak comparatives (as there were teething problems with the new warehouse systems this time last year).
My main reservation about this company is that this IPO is being touted as akin to BooHoo or Missguided, in terms of online, and test & repeat business model. However, Quiz's online operations are very small, both in absolute terms, and as a percentage of its overall business. As a friend quipped, "It's more ShoeZone than BooHoo!", and I think there's a lot of truth in that. This is mainly a nimble, entrepreneurial conventional retailer, which also happens to have a website, as do almost all other physical retailers. It's far from unique in that regard.
Also, I am concerned at the high level of customer returns - at 35% this is well above the industry average of 30%. What bothered me, is that management are labouring under the misapprehension that 35% returns rate is good, which is worrying. It isn't good, it's bad. BooHoo returns rate is 20% for example. That said, the gross margin achieved by Quiz is excellent, so the company seems to be able to cope with a high returns rate. Part of it might be that customers sometimes order 2 of the same style, in different sizes, and keep the one that fits best, returning the other. This is a longstanding problem with mail order & e-Commerce clothing sales.
I'm also concerned that there is only £10m fresh money being raised. It is encouraging that the company has self-funded its growth to date. The marketing budget is to be increased by about £1m p.a., to drive online sales growth. Interestingly, the company said that its online marketing spend also seems to boost sales in the physical stores too - an additional, and unexpected benefit. It makes me wonder how long it will be for companies like BooHoo to realise that there are considerable benefits from having a physical store network, as well as online.
The bulk of the £100m float is the founder family selling down 40-50% of the company. So if they think this is the right time & price to cash out half their stake, why would I want to buy the shares from them? There again, you could say the same about BooHoo, where the founders sold a similar amount on floating. Despite BooHoo warning on profits not long after floating, it has subsequently recovered, and is now over 4 times the original 50p float price. So founders selling down is not necessarily a bad thing.
My opinion - In conclusion, I've decided that on balance, I reckon this is likely to be a successful float. I do have some reservations though, as noted above. Despite this, I'll probably apply for some stock in the placing. I think the IPO is arguably somewhat opportunistic - with a valuation that looks toppy, based on associating the company with BooHoo's business model, when in reality they're not really particularly similar, and Quiz's online operation is tiny compared with BooHoo. However, there's such strong market demand for online growth companies, that the over-valuation might be justified maybe? I'd much rather invest in something profitable, and run by experienced rag traders, than some loss-making, cash burning pile of junk like Koovs for example.
I had a 5 minute chat with the FD afterwards, who strikes me as a safe pair of hands. "Every company should have a Scottish FD!" as my broker quipped to me. There's obviously mutual respect between him & the founder + son management team.
I mentioned Stockopedia to the FD, and gave him my Stockopedia business card. I also emphasised how important it is for newly floated companies to nurture a private shareholder following, to boost liquidity & narrow the spread. The trouble with new floats is that they're usually done via a placing of large blocks of shares to institutions, hence immediately run into illiquidity problems.
Overall though, a cautious thumbs up from me, for Quiz.
On to today's news. I'll be updating this article at a leisurely pace throughout the afternoon, so please refresh this page later for more sections.
Firstly I'll look at what look like profit warnings from Blancco Technology (LON:BLTG) and £ENTU
Blancco Technology (LON:BLTG)
Share price: 123.25p (down 18.1% today)
No. shares: 64.0m
Market cap: £78.9m
Trading statement (profit warning) - this company used to be called Regenersis, but then sold off its original business, to concentrate on an acquisition of Blannco - a data deletion specialist.
As you can see from the 1-year chart below, the wheels have really come off this year;
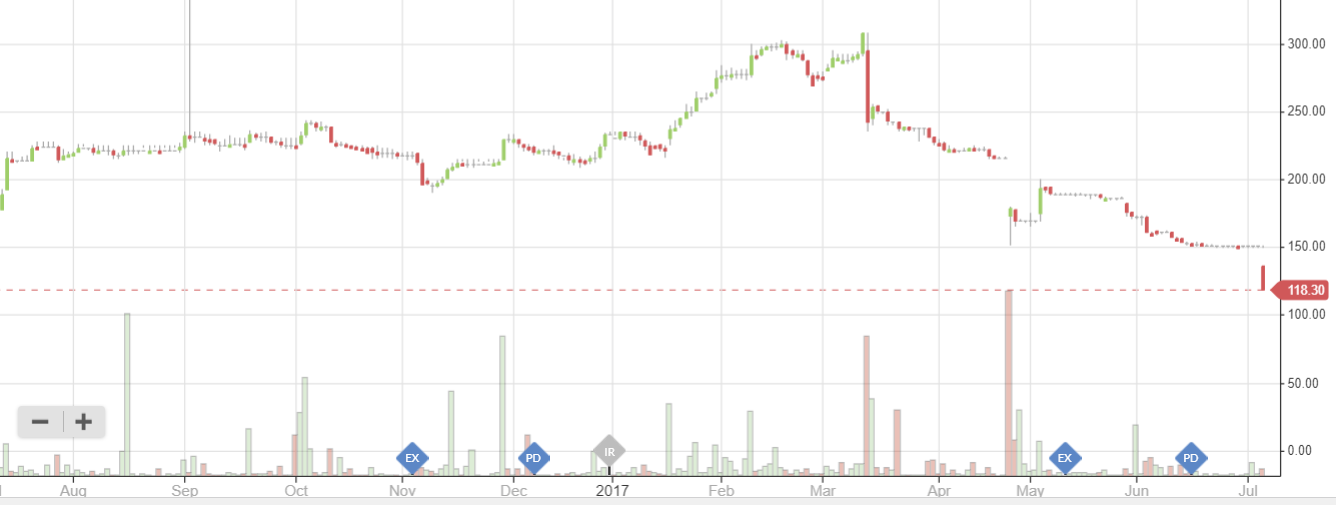
Our Graham wrote a terrific, insightful criticism of the company here, after it dropped 22% to 240p on publication of interim results in Mar 2017. He was right to be sceptical, as the share price has halved in just over 3 months since then.
I further stuck the boot in, here on 30 May 2017, with the share price at 175p, where i predicted more bad news to come, due to the many red flags (e.g. unexpected Director resignations, complicated & questionable adjustments to the accounts, weak balance sheet, etc).
Furthermore, the Stockopedia StockRank is diabolical, at just 7, and it's rated as a "Sucker Stock". Overall then, Stockopedia readers had plenty of warnings about this horrible share, from the computers, and the SCVR team.
The update today is for the year ended 30 Jun 2017. Key points;
Revenues up strongly. Up 30% in constant currency, or 40% in reporting terms (gaining from forex movements). This is in line with market expectations.
However, the company has been hit with a £3.5m non-payment by a customer;
...However, cash flow and net cash are below market expectations due to the non-payment of £3.5m of receivables, the majority undertaken in the prior year.
It's not entirely clear, but reading between the lines, I'm assuming that the customer refused to pay for work invoiced, rather than the customer going bust. This impression is reinforced by a tacit admission that the company has previously been too aggressive in its revenue recognition;
...This reflects the Group's intention to apply a more prudent approach to revenue and income recognition on this type of contract in the future.
The overall hit to profits looks significant;
Taking a prudent approach to these receivables we have decided to provide against them by taking a charge of £2.2m, resulting in Adjusted Operating Profits of not less than £5.5m and Adjusted EBITDA of not less than £7.0m (subject to fully closing the accounts and audit).
My opinion - I don't like this company at all. Today is yet more bad news, from a very accident-prone company. The red flags have been obvious for some time, so it would have made a good short.
Previous management were dreadful in my opinion, so the hope was that new management would be better, but there's not much sign of that so far. I think problems are often left behind by outgoing poor management, not least in terms of company culture (e.g. aggressive accounting, etc). So it's usually best to wait for new management to kitchen sink the numbers.
The company bolstered its balance sheet with a placing at 169p in May 2017, raising £9.45m after fees. With the share price now 27% down on that fundraising just 2 months ago, I imagine there must be some very miffed shareholders here. There could be grounds for legal action there, perhaps? (for possible misrepresentation).
It's possible that there might be a decent company here, struggling to get out. For me though, with a long track record of dodgy accounting, and weak management, I can't see any reason to get involved here. Why take the risk? It doesn't even look particularly cheap, after the big share price falls.
Entu (UK) (LON:ENTU)
Share price: 11.5p (down 25% today)
No. shares: 65.6m
Market cap: £7.5m
Strategic review - an ominous title for an RNS, at a company with known problems. This company sells double-glazing & similar products. It outsources production to a previous sister company called Epwin (LON:EPWN) .
This is what the company says today;
The Group has a detailed plan to reduce costs, improve operational efficiency, leverage its supply chain, improve cash collection and strengthen controls and is making progress on each of these fronts.
As part of the strategic review, the Directors are exploring options for new long term financing, and to strengthen the balance sheet, in order to support the Group's action plan.
KPMG have been engaged to assist with this process which, alongside debt or debt and equity refinancing, will include establishing interest in certain parts of the Group.
Yuck, that sounds grim to me. It looks as if the company is not far away from potentially diluting existing holders badly. Given its lousy track record, who would want to put fresh money into this awful company?
It sounds as if the group is putting itself, or at least parts of the group, up for sale.
My opinion - this company is a hopeless case, in my view. Also, I've heard from a former employee that its sales techniques (hidden charges, etc) are unethical, in his opinion.
There's another double-glazing company, Safestyle UK (LON:SFE) which is highly profitable. So why does ENTU perform so badly in comparison? I think the answer is that the profit is probably hived off into Epwin (LON:EPWN) - which makes the profit margin on manufacturing the windows, which Entu sells.
Floating the 2 companies simultaneously seems to have possibly been a trick to increase the overall proceeds from the floats, than if they had been floated as a single group. A fund manager friend warned me that was the case at the time, but I got suckered into Entu (long since sold) by the prospective high dividend yield (dividends which have of course since disappeared).
Lessons to be learned? Firstly, a high prospective dividend yield can be a trick, used to float lousy companies. So I think investors should be highly sceptical about IPOs which look rubbish, but have a high dividend yield.
Secondly, I think the incestuous relationship between Entu & Epwin was a huge red flag, which personally I glossed over, due to being fixated with Entu's high dividend yield. So from now on, I think dodgy-looking incestuous relationships between companies should be considered a massive red flag.
Thirdly, the weird transactions done by Entu's shareholders prior to it floating (lending/donating vast amounts of money to a rugby club) can be seen as a red flag. Some readers did flag that at the time, and again I glossed over it. So I was wrong, and the readers were right. Lesson learned - if there's anything puzzling in an admission document, then it's probably best avoided. It's amazing what dirt you can find at the back of admission documents, so it's vital to read things carefully, as that will often be the one & only time that such matters are disclosed (because they have to be).
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Re QUIZ
In case you missed this yesterday, there was an RNS giving details of this IPO.
First dealing date is expected to be 28 July
The admission document is now available on the company's website. Here is the link
Great post
My first post - thanks for the column - much enjoy the quality writing.
A while ago - in 23 May 2017 - you were quite positive about Entu (UK) (LON:ENTU) connected company Epwin (LON:EPWN), who make the money on making the windows that Entu sell. With Entu smelling funny, what's your thought about Epwin? If Entu is in trouble, surely Epwin will struggle. I've the sold my Epwin, feeling a little nervous. Any thoughts anyone?
Which country is Quiz registered in? There are no registration details on it's website and I can't find it on the Companies House website. Quiz Limited seems to be a private defence company from Bristol.
The company appears to be Shoar holdings limited after a quick Google ,if that's it I'd value it about £15m on a pe of 10, not sure if that is the IPO price...
Not enough turnover, but Shoar could be a subsidiary. I expect the full admission document will provide all the details.
Interestingly, Quiz Clothing Ltd and Quiz Limited were registered in Jersy in Feb and March 2017
Shoar is the main holding company according to their latest confirmation statement on Companies House.
The T&Cs on the retail website reference a company called 'Tarak International Limited' which is registered in Scotland and is consolidated into Shoar (Holdings) Limited along with a couple of other companies, Kast Retail Limited and Tarak Manufacturing Limited.
As you say, the group accounts for Shoar don't tally with the figures declared in the RNS so maybe there are some other trading companies out there not consolidated into the Shoar group accounts?
Re Entu, I have learned the same lessons as Paul with an additional one. In the early day, I tried and tried to make contact with the CEO and other mgt. I called, emailed, wrote etc. and was repeatedly fobbed off, at one point actually overhearing somebody (don't know who it was) in the background saying "Tell him I'm away from my desk and that I'll call him back" which he never did.
I had emailed my questions in advance and they were very benign and reasonable, it wasn't an inquisition. So, I figured that there was something fishy and sold out. Luckily for me I lost nothing and after I had sold received a chunk of that unsustainable divi!
With regards high dividend paying floats, hasn't an expensive yacht painting company just "floated" with a divi north of 6.5%? If I were allowed (work compliance prevents it) I'd be as short as a short thing on that!
Regarding incestuous relations, does Accrol Group (LON:ACRL) have some form of arrangement where it manufactures but an intermediary sells? If so, this may be another barge pole. (Is there such a thing as a 'yacht pole'?)
Re: (Is there such a thing as a 'yacht pole'?)
Experts call it a "mast"
Beginner,
"(Is there such a thing as a 'yacht pole'?)"
Bit OT but yacht poles? YES. Google Twistle or twizzle rig. One pole good, two poles better.
Sea(bit of a clue)doc
Edit and PS: FREng, umm masts? yup, need at least one of them as well! Have sailed with up to three, but not on my Tupperware
Paul,
Is incestuous a prerogative term, financially speaking? You (or was it Graham) flagged up float of DP Eurasia NV (LON:DPEU) at 200p. Thank you, it made interesting (as in "may you live in interesting times") reading but it got a 10/10 bargepole rating from me, 90% cash to previous holders, most of remaining10% new cash to be spent in Russia. But any traders who bought in at 160p on day one of trading could have made 20% in a week. And it will go on my watch list at 20p.
Regards,
Seadoc
I'm struck by the similarity of the related party transactions at Entu (UK) (LON:ENTU) rightly being viewed as a big red flag yet Quiz has a big related party conflict with the vendors remaining the owners of the new distribution centre. I bet that's not on a 5 year lease...
I've no knowledge of the detail but if it's as described above that alone would rule it for me
yes I find that highly dubious, why wouldn't that distribution centre be part of the business if it's owned by the same people ? with a correction in valuation to allow of course. It may not be material but it does introduce a conflict of interest, where by it's in the interests of the founders to pay too much for that property. Now I don't know that they will, but I do know that they've left themselves the temptation to. Now if the answer is that it's a temporary arrangement while another facility is built or something, then it makes sense, but if it's a long term arrangement, how does it make sense ? other than to benefit the founders , and leave some assets outside the company in case it fails ? Does not seem right to me.
"... although there's about a 50% chance that might be derailed by me stopping off at the pub".
I will happily offer evens to anyone that wants to bet against Paul stopping off at the pub!
It's Thursday..
It's bloomin' hot...
I'd want much better odds than that, far too much risk given the above macro
Cheese I reckon
Good analysis of why entu suckered a lot of investors, including me.
Reinforces my experience that it's best to give conflicts of interest the cold-shoulder.
I think your "polyester" impression of Quiz is an accurate one. My 19 year old daughter described it as tacky and wouldn't shop there (not snobbery as purchases plenty from Primark and Boohoo). Not one for me...
It's interesting to see that Novae (LON:NVA) got taken out today by an American company. With Sterling remaining low, I think it's safe to say there will be lots more UK companies being bought out.
"That type of thing is quite common at private companies" yes and if that is their practice it should stay private.
Punt pole from me
Hi Paul
This may seem like a silly question to the more experienced investor but can how can a low level individual investor like me get involved in a placing? I do my trading online via Internaxx (Formerly TD International) and can't see anything related to IPO's on the platform. I'd be interested in investing in Quiz but would rather not wait until the first day of trading as I'm sure it's likely to open significantly above the IPO price.
Thanks
Ben
Quiz. What is "omni-channel"?
Hi skyvan,
Quiz. What is "omni-channel"?
It means selling via all available means, i.e.
Physical shops, Concessions (shops within a shop - usually in a Dept Store), own website, via third party websites, mobile - via Apps.
Quiz presented this as if it were something new, but in reality many other retailers are omni-channel these days.
Regards, Paul.
"Our Graham" - That got a laugh from me - I guess you have to be 40+ to get it!
"Our Graham" - That got a laugh from me - I guess you have to be 40+ to get it!
Absolutely! I've been waiting for our Graham to give us a quick reminder about something!
P. :-)
Blancco Technology (LON:BLTG) was much debated around the March bombshell: in addition to yours and Graham's analyses there is another thread or two on stocko. Link to the main one here.
I looked at it at the time but decided it was too problematic. in hindsight a short was probably the best conclusion though its lack of liquidity put me off trading it in either direction. Even today's sell-off is relatively anaemic in volume terms but then many of the sellers may have done their thing by now. Fairly large institutional holdings which appear to be staying put ..for now.
Price action looks awful with very little support: I'd expect it to drift to the 100p and may well reach 80p before finding meaningful support.
One of those "glad I don't own it" scenarios - either lance the boil or nurse the wound and hope it doesn't go gangrenous.
Hi, can I ask where you source the Major Shareholders and dealing chart you post? Thank you
James,
http://images.stockopedia.co.uk/user/595e302ec737ebltg.JPG
Hope the link works,
Seadoc
from SharePad which I get as part of a subscription to Sharescope .
Sharepad.co.uk
Think you can take a free trial
Hi Paul,
Thanks as usual for the great report.
If I was interested (after reading all the materials of course!) where would one apply for the IPO for Quiz?
Jon.
Hi jklindsey,
If I was interested (after reading all the materials of course!) where would one apply for the IPO for Quiz?
I'm not sure. In my case, I'm applying through my conventional broker. So I imagine that any broker which has a relationship with Panmure Gordon should be able to let you into the placing, if you ask.
I'm classified as a professional, or "sophisticated" investor, which I have a feeling is necessary to be given access to placings, but am not 100% sure about that.
Best thing is just to enquire with your broker if you can get into Quiz. Or alternatively, just buy in the aftermarket, once it has listed.
Regards, Paul.
The high return rate on Quiz I would have thought has a very simple explanation. If it's special occasion wear, consumers will order it, wear it once (very carefully) for a special occasion and send it back.
It's all part of the alarmingly scammy-state-of-mind that now seems to have infected large sections of the public. In my view, this is largely the fault of contingency-fee based lawyer legislation and the dreadful compensation culture it has engendered. I note that the latest scam is the food-poisoning-on-holiday trick, actively encouraged by "lawyers" to the extent they have people outside hotels in the big Spanish resorts touting for business. I was concerned to read this as a holder of DTG, because, there is little defence for the hoteliers. Cheaper to pay up than fight it.
Well possibly, but a simpler explanation still might be evidenced by the way my daughters and their friends use online fashion retailers: buy 10 items at once of which 7 don't fit very well and they don't like 2 of them, so 9 get returned. This level of returns has to be built into the online model - some companies tend to do it very well, those from a more traditional bricks and mortar background seem to do it less well.
I don't see any of these kids infected by a scammy state of mind but if there are repeat offenders then any decently managed company would detect this and blacklist such people anyway. Same with holiday companies if they have any sense.
timarr
Return rate is likely to grow as online sales grow. I would also add from experience of over 30 yrs in the trade , a high returns rate can be a result of weak quality control systems in place. The trial and repeat model will also not help QC, many corners are cut to get the fabric and garment manufactured to those tight lead times.
Paul,
Not sure if you are planning to look at the Microgen Trading statement today - Sales look very positive, but we are left guessing about profitability unless some type of extrapolation is possible? Someone must think EPS is going to be good because the price is up 16% since the open. - Timing just crossed with Herbie's!
Microgen (LON:MCGN) also issued a positive trading update "The Group has made excellent progress in the first half of 2017 resulting in a financial performance ahead of the Board's original expectations for the period whilst maintaining margins consistent with the prior year."
Once again a very positive update from EKF for those interested:
....trading in the second quarter of the year has continued the favourable trends experienced in the first quarter. In particular, June sales were notably strong. This is entirely due to organic growth with no major tenders won during the period.
As a consequence, the Company expects adjusted EBITDA for 2017 will be comfortably ahead of current market forecasts.
Finally, despite the cancellation of the stock option scheme at a cost of £1.5m cash generation has been very strong with net cash at 30 June of approximately £4.0m.