Small Cap Value Report (Thu 7 Jan 2021) - GRG, WAND, GHT, AUTO, MAB, JOUL, MPAC, JDG

Good morning, it’s Paul here with the SCVR for Thursday.
Timing - Today's report is now finished.
Agenda -
Firstly, here are some brief comments on a few company news items from yesterday.
Greggs (LON:GRG) - trading update
Wandisco (LON:WAND) - more jam tomorrow!
Gresham Technologies (LON:GHT) - 2020 trading update
Auto Trader (LON:AUTO) - trading update - possible read across for small cap car dealer shares?
Mitchells & Butlers (LON:MAB) - exploring a fundraising & trading update
Joules (LON:JOUL) (I hold) - Xmas trading update
Mpac (LON:MPAC) (I hold) - 2020 year end trading update
Judges Scientific (LON:JDG) - 2020 year end trading update
.
Greggs (LON:GRG)
1920p (up 8% yesterday) - mkt cap £1.95bn
This is an update for FY 12/2020.
Greggs is a leading UK food-on-the-go retailer, with more than 2,000 retail outlets throughout the country
- FY 12/2020 revenues down 31% to £811m
- Year-end net cash of £37m
- £100m 3-year bank facility available, so liquidity sounds OK
- Repaid Govt CCFF loan - reinforcing that liquidity is OK
- Modest full year loss of £15m - not bad considering the covid/lockdown chaos in 2020
- Successfully developed takeaway & delivery alternatives (5.5% of store sales)
- New sites accessed by cars “performing particularly well”
- Q4 shop LFL sales were down 19% - to be expected given changing restrictions, and reduced number of people in city/town centres
- 820 staff redundancies
- Plan to open 100 new stores in 2021, net of closures
- Diary date - preliminary results due on 16 March 2021
Outlook - not great -
Looking ahead, the significant uncertainty over the duration of social restrictions, along with the impact of higher unemployment levels, makes it difficult to predict performance.
However, we do not expect that profits will return to pre-COVID levels until 2022 at the earliest.
Valuation - these figures look a lot better than the consensus broker forecasts shown on the StockReport, which is good.
Greggs made c.100p EPS in 2019, by the sounds of it we’re looking at possibly getting back to that level in 2022, so 2 years’ time. The share price is 19.2 times that target. That doesn’t strike me as very good value - recovery looks fully priced-in, so why would I want to buy now?
It’s a terrific business, no doubts about that, but I’m worried footfall may not return to pre-covid levels, ever, because many people have probably got used to shopping online, and working from home. What happens when business rates kick back in too?
It would have made a super purchase over the summer/autumn lows, but it’s since rallied too much in my view, hence doesn’t interest me on valuation grounds now - good business, but too expensive for me.
.

.
Wandisco (LON:WAND)
520p (up 8% yesterday) - mkt cap £283m
This company is always promising jam tomorrow, and claiming to have unique, ground-breaking software.
Paltry revenues for FY 12/2020 at least $10.5m - some (not given figure) sales deferred into 2021
This time last year, FY 12/2020 revenues were forecast at $32.3m - so the outturn is just under a third of the original forecast - pathetic I would say. Yet the share price now of 520p, is actually up on the 438p a year earlier. How does that make sense?
Year end cash of $21m
Outlook - reckons it has a “building pipeline of opportunities” for 2021, and guides for revenue of $35m in 2021 - more than tripling 2020 revenues - a very punchy forecast, and not credible based on past performance, in my view. I’m happy to be proven wrong though.
It says higher forecast sales are due to moving to the cloud, AWS and Azure, allowing fast implementations of new clients. 11 customers signed, but no indication of deal sizes given in this update.
My opinion - I’ve got no way of judging whether it is likely to achieve the huge forecast increase in sales or not. Historic performance has been very poor, so not something I want to gamble on. Good luck to holders.
The company has been listed since 2012, with revenues going nowhere ($10-20m and back down again to $10.5m a.) and racking up huge cumulative losses. Therefore it takes a big leap of faith to think it will suddenly achieve commercial viability. Maybe it will, I don’t know, but would need a lot of convincing evidence before wanting to take the plunge here myself.
That said, the technology has always sounded very impressive, so who knows, maybe it might eventually take off, or one of the big tech companies might buy the company?
I do recall that a few years ago, we managed to catch a big move up in this shares, and made a few bob, but that was just a lucky trade really, not an investment.
One for tech experts only, I reckon.
.
Gresham Technologies (LON:GHT)
148p - mkt cap £104m
Trading Update
This software company reports on performance in FY 12/2020.
Not very impressive is my conclusion. It says EBITDA of “at least” £4.4m achieved, but that reduces to zero once development spend is taken into account.
Cash of £8.8m
Overall trading for the year in line with recently upgraded market expectations
The Group's sales pipeline strengthened steadily during H2 2020 and the Company continues to see positive demand for its intelligent automation and connectivity solutions in financial markets despite challenging macro-economic factors.
In the second half of the year, we increased investment in sales and marketing, as well as completing our strategic investment into the regulatory and STP markets with our acquisition of Inforalgo. These excellent foundations have set us up well for another exciting year ahead."
My opinion - the market cap is just over £100m, and I’m finding it difficult to see why that makes any sense, given that it’s not making any cash profits.
This is another company that has been listed for a very long time, and doesn’t seem to live up to ambitious expectations.
.
Auto Trader (LON:AUTO)
610p - mkt cap £5.9bn
Current trading
Interesting for read-across to the general health of the market for secondhand cars.
Oct-Dec 2020 visits to its website were up 20% vs LY (NB not the same as revenues)
Expecting sales volumes to be impacted in Jan & Feb 2021.
Offering free advertising packages in Dec 2020 & Feb 2021, causing anticipated losses of £5-7m in each month
Drawings of £45m on £400m facility
Substantially within bank covenants
Latest lockdown has forced car dealers to close their showrooms again
My opinion - I don’t think there is enough clarity to know how car dealers might trade in these turbulent times.
AUTO is staggeringly profitable, with amazingly high profit margins. Whilst that’s good, I’d be worried about one of the internet giants destroying its lucrative near-monopoly. A bit like Rightmove.
.
Mitchells & Butlers (LON:MAB)
212p (down 10.5% at 08:11) - mkt cap £913m
I'm trying to cover as many trading updates as possible, even from mid to larger caps, at the moment. This is because reaction to lockdown 3 is very important, and has read-across to small caps. Plus, being locked down in Bournemouth in foul weather, I don't have a lot else to do right now!
As Phuntt helpfully points out in the comments section, this update is indeed stark.
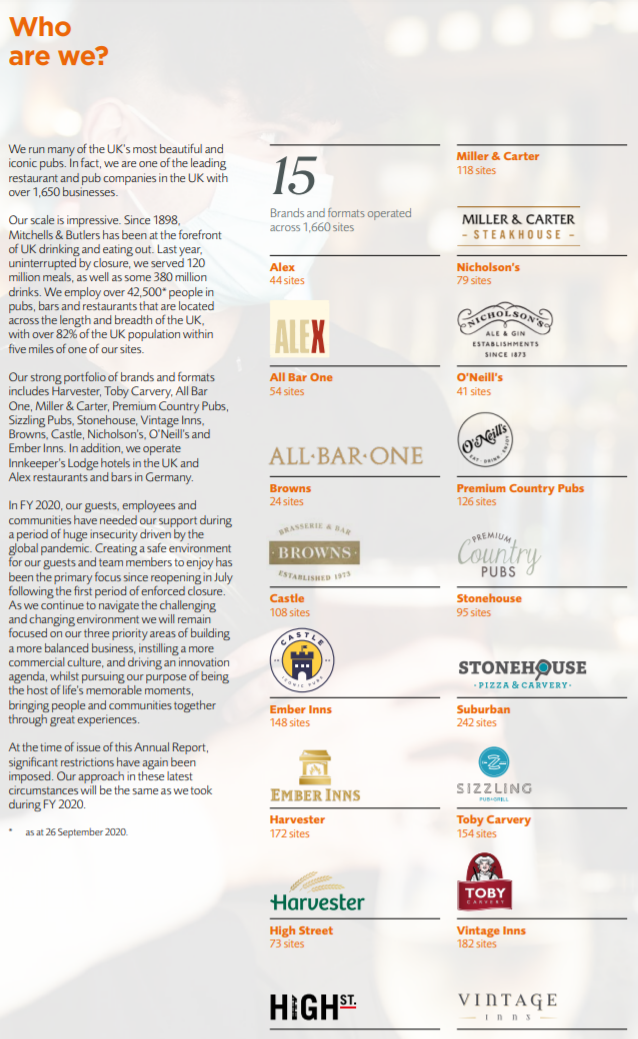
MAB is a sprawling pubs group, with no less than 15 brands;
.
Trading statement covering the 14 weeks ended 2 January 2021.
My summary & comments -
- Enforced site closures meant reduced sales activity over the important festive season.
- All sites now closed (since 30 Dec 2020)
- Q1 (Oct, Nov, Dec 2020) sales down 67.1% on LY - ouch
- LFL sales (i.e. only when sites open) down 30.1% on LY
- Minimising costs & capex
- Cash currently £125m, all borrowing facilities maxed out
- Cash burn in lockdown is now £35-40m per month (before debt servicing costs)
- Debt repayments are £50m per quarter, as the group has a lot of borrowings, but backed up by large freehold property assets
- Put those last 3 items together, and we can see that the group is likely to run out of cash by end March
- Exploring an equity capital raise - no decisions yet made on timing, size, or terms
My opinion - it looks as if MAB management have misjudged the cash requirement. A new lockdown with little to no sales until Easter is nothing new - other hospitality companies have been planning on that basis as the most likely, or at least possible, scenario.
Checking back to MAB's results for FY 09/2020, the balance sheet looks out of balance, in that there's clearly inadequate working capital: current assets of £239m, and current liabilities of £(701)m.
Overall the balance sheet looks OK, because there are £4.3bn of fixed assets, which includes £3.79bn of freehold property (source: 2020 Annual Report)
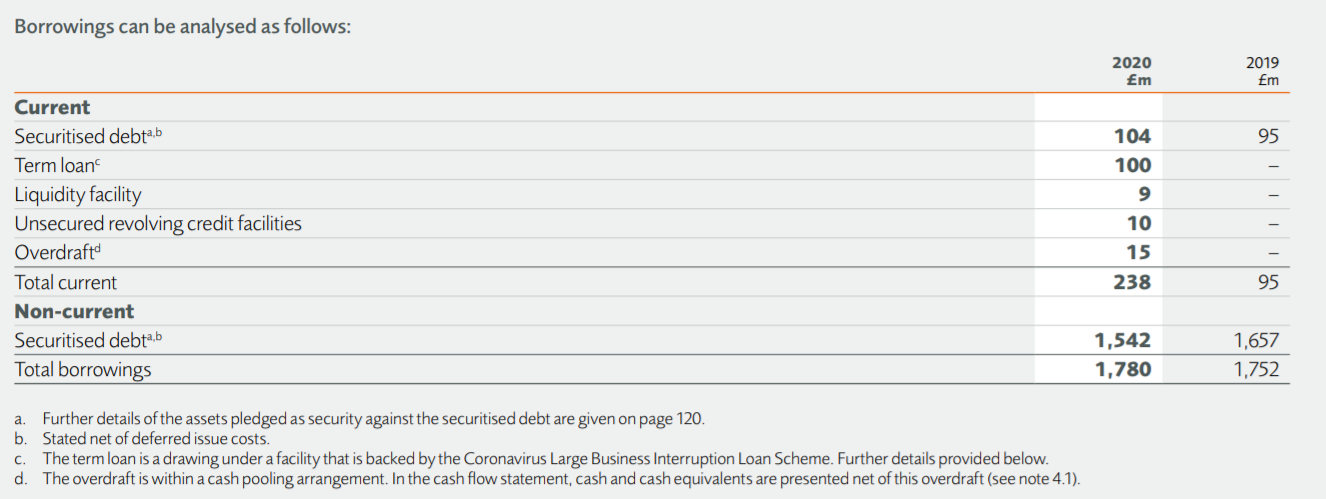
Material uncertainty re going concern was flagged by the auditors in the last Annual Report. The business seems to potentially rely on the leniency of holders of bonds which provides most of the funding. Long term borrowings were £1.54bn at at 26 Sept 2020. See note 4.2 of Annual Report, including this breakdown of net debt -
.
Even if we halve the value of the freehold property, it's still enough to cover the debt. Therefore I don't see this as a distressed situation.
Therefore it should be possible to refinance the group again, with fresh equity, perhaps as part of a package to include resetting terms of debt, and covenants.
It could get messy if bondholders decide to play hardball.
Personally I'm not tempted to get involved, at least until the equity fundraising has been done. I'm sure institutional shareholders will support an equity raise, but we don't know the price - it could be at a significant discount, who knows. Therefore why take the risk of getting involved in this share now, with that uncertainty hanging over it?
The sector read-across is that investors need to do the sums to ensure other hospitality companies have adequate funding. I've crunched the numbers for Revolution Bars (LON:RBG) (I hold) and am happy that it can survive until Easter with zero revenues. Although RBG did confirm in its last update that the covenants are tight at end March 2021. That said, with re-openings likely to have happened, or be imminent by then, it shouldn't be a problem if a small amount of bridging finance is needed.
With vulnerable people hopefully vaccinated by Easter, then restrictions on trading are only likely to last c.3 months, based on current facts. Therefore shareholders are likely to support any fundamentally sound hospitality companies. That's not necessarily true of privately owned companies, so I think we're likely to see carnage in this sector, with potentially thousands of privately owned bars going bust between now and Easter. More market share for the bigger operators of course, once they're allowed to re-open.
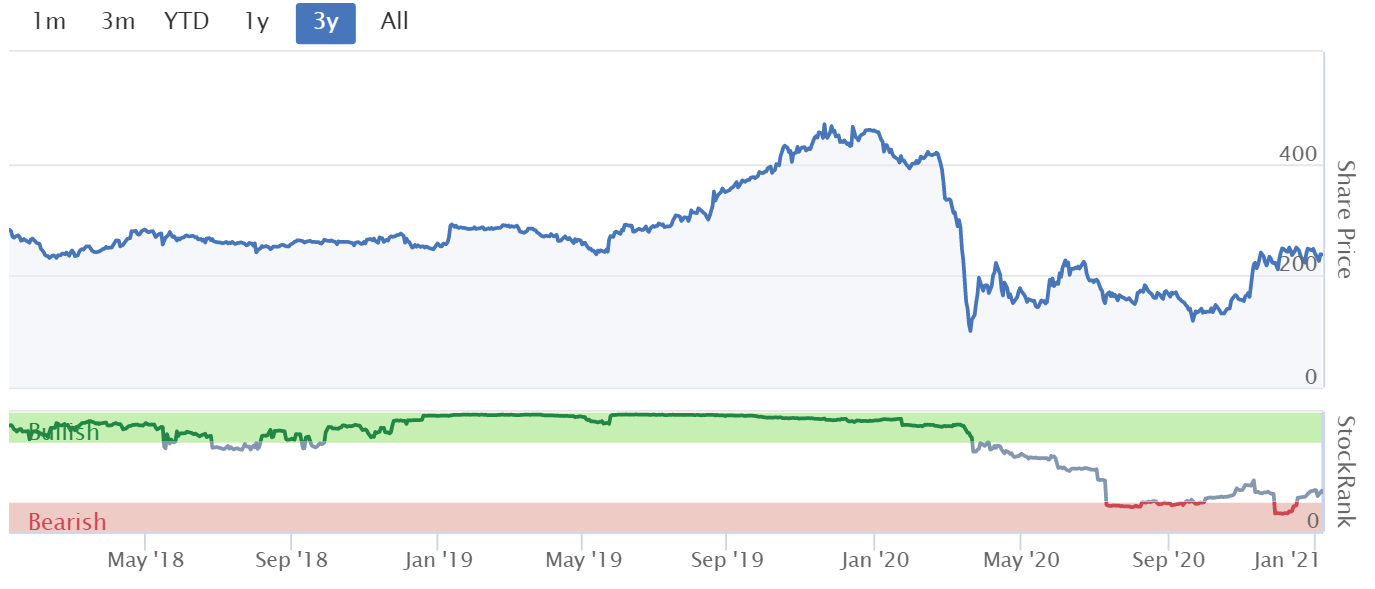
Looking at this chart, I'm surprised MAB shares have held up so well. I came to a similar conclusion when looking at J D Wetherspoon (LON:JDW) shares recently - too much recovery is already priced-in for my liking. Hence risk:reward doesn't look attractive at this point in time.
.
.
Joules (LON:JOUL)
171p (down 5% at 10:18) - mkt cap £186m
(I hold)
This is a distinctive UK fashion brand. It sells wholesale, retails from its own shops, and has a strikingly high percentage of total sales online - which makes it interesting to me. As regulars here might know, I’m usually only interested in retailers that are nailing it online, and reducing their exposure to physical stores.
By this stage, fashion brands really should have got half their sales online, and be rapidly reducing lease liabilities. Otherwise they’re in danger of following Arcadia down the pan. I’m not convinced by Superdry (LON:SDRY) or Ted Baker (LON:TED) as examples which are trying to sort themselves out, but have not yet convincingly demonstrated a turnaround. Although I’m keeping an eye on both, because if they do pull off a turnaround, then there could be decent upside. Both possibly a bit old hat, in terms of brands?
Back to JOUL, an up & coming brand. A little while ago I decided to bank my profits on Marks And Spencer (LON:MKS) (not often you can say those words! It was a lucky purchase at the lows), and put the money into a starter size position in JOUL, at about 150p per share. I was worried that I might have overpaid, but am taking a long-term view with JOUL now, hence the exact purchase price doesn’t really matter to me. The strength of online sales, and my review of the 8 Dec 2020 trading update, convinced me to dip my toe in with a modest initial purchase just before Xmas.
Today’s update - it’s a Xmas trading update, usually peak trading, but obviously disrupted this time by covid;
Joules, the premium British lifestyle brand, is pleased to provide a trading update for the Group's retail channels during the seven-week period to 3 January 2021 (the "Period").
The most important bit is buried in the middle of the announcement, which sounds very encouraging to me;
Total retail revenue through Joules' own-branded retail channels(2) during the Period was up by 0.3% against the prior year, with the growth in Joules e-commerce sales more than offsetting the decline from stores.
(2 )Excludes third-party retail platforms that Joules sells through
eCommerce sales have been very strong. This is important because (although we’re not given the figures unfortunately), Joules is making the majority of its sales online these days;
Total retail sales through Joules' websites, including sales through the Friends of Joules digital marketplace, increased 66% year on year1
1 Gross sales, including Joules own e-commerce and Friends of Joules, prior to returns, calculated consistently in each period
Store closures due to lockdown restrictions has obviously hit store sales hard -
Total store sales declined by 58% during the Period, reflecting the enforced closures of non-essential stores and reduced footfall as and when stores were able to remain open.
(5 )Stores were closed (on average) for approximately half of the seven-week period
LFL sales when stores could open, was better, at 23% lower - not bad in the circumstances, in my view.
Good brand metrics, including an impressive 1.5m active customers.
(4 )An active customer is a customer registered on the Joules database who has transacted in the last 12 months
Net cash of £13m at 3 Jan 2021, and £63m total liquidity headroom - sounds ample, so no solvency worries here.
Outlook -
All stores now closed in lockdown 3
Estimated loss of sales will be £14-18m, assuming re-opening on 1 April 2021, and includes lost wholesale & country shows revenues. Useful information.
Mitigation from;
- Better than expected trading in first 7 months of FY 05/2021
- Strong online performance
- Cost reductions, including HO costs & lease renegotiations.
Diary date - interim results (6m to 11/2020) due out on 28 Jan 2021.
Broker update - many thanks to Liberum, for making their update note available today on Research Tree. This is tremendously helpful to PIs, and helps generate buying interest in the shares & improve liquidity. I wish more brokers would follow suit with many more companies.
Forecast for FY 05/2021 PBT has been cut today by £1.4m, to £3.7m, reflecting impact of lockdown 3. I'm relaxed about that, as it's a factor outside the company's control, and pent-up demand often returns afterwards, or shifts online.
Valuation - forecast EPS for FY 05/2021 is now 2.6p, which at a 171p share price gives a current year PER of almost 66 ! Eeek that’s expensive. However, it’s a highly disrupted year, so shouldn’t be typical of future performance once we’re past covid.
Earnings clearly need to grow strongly in future years, to justify the current valuation. 6.8p is forecast for FY 05/2022, a forward PER of 25 times, which I think can be justified given the unique brand, and very strong online performance.
My opinion - the current valuation does look a bit aggressive, but I’m prepared to look beyond the current financial year. If future profits don't bounce back strongly, then there could be downside risk. Things have gone wrong in the past, so it's not risk-free by any means.
However, it seems to me that there is something special with this brand, and having demonstrated that it can shift to successfully selling online when shops are forced to close, that greatly de-risks the business model. The "friends of joules" marketplace is an interesting development. Could this be an early-stage fashion portal for yummy mummies?! It's possible. Fashion doesn't really work on Amazon.
I don’t want to chase the share price any higher, as it looks fully valued for now. However, I’ll be looking to buy any market dips in 2021, to slowly build up a bigger position size in Joules. After several years following, and appraising it, I’m now satisfied that this should be a good long-term investment (5+ years timescale for me). Hence I want to build up my holding on the dips, in 2021. As usual, I have no idea (or view) on what the short term share price is likely to do.
Note that the founder still holds a large stake, often a good thing, in my view. Although there's a risk that private equity could tempt him to take it private, if things start doing really well. Although I'm told the small print can be horrible with PE deals, so probably best to stay listed on AIM. We need more decent companies like Joules coming to join AIM. Too much junk gets floated.
.
.
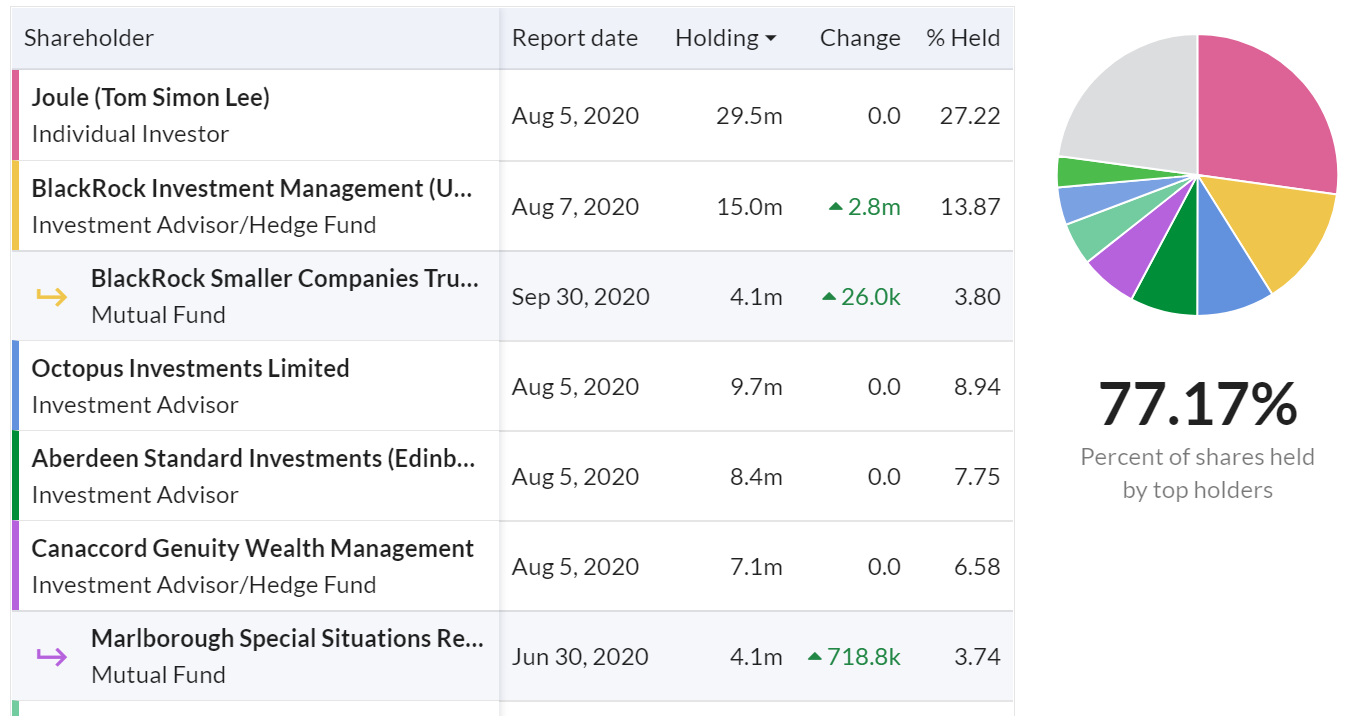
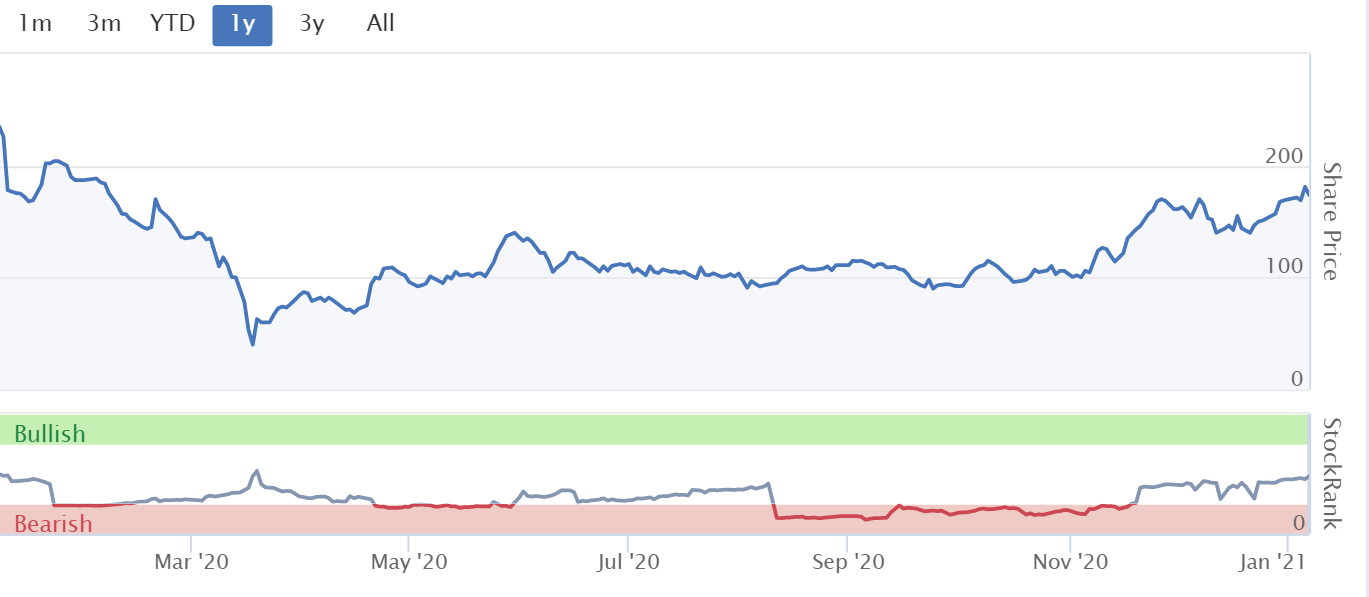
Quite a lot of recovery has already been priced-in
.
Mpac (LON:MPAC)
455p (up 8% at 12:32) - mkt cap £90m
(I hold)
This is a very interesting group of companies, making packaging & automation machinery.
Here is my review of the recent interim results, published on 3 Sept 2020, to quickly get up to speed on the background. Profit was down 45% on H1 LY, due to project deferrals caused by covid.
Jack reviewed MPAC here - flagging the enormous pension scheme liabilities, which does worry me, because small changes in assumptions can trigger big moves in surplus/deficits. Especially as interest rates could even turn negative at some point.
Trading update today -
Mpac Group plc, a global leader in high-speed packaging and automation solutions, provides a pre-close trading update (unaudited) for the year ended 31 December 2020.
The summary says -
Resilient FY20 trading performance, ahead of market expectations and encouraging outlook for FY21
The Board is pleased to announce that the Group expects to report underlying profit before tax for the full year 2020 above market expectations, primarily as a result of better than expected margins in Q4 driven by sector mix.
Trading continues to be resilient, as Mpac serves essential healthcare, food, and beverage markets, deploying digital technology to mitigate travel restrictions despite the continued headwinds from the pandemic.
That sounds good.
Acquisition of Switchback Group Inc - announced in Sept 2020. Going well, it is trading ahead of expectations, with synergies secured.
Order book was £45.4m as at 3 Sept 2020, is now up to £55.5m. No orders cancelled due to covid.
Diary date - FY 12/2020 results are due out w/c 1 Mar 2021
Outlook - is upbeat;
Our pipeline of qualified opportunities and our closing order book give confidence for 2021. The acquisition of Switchback has further enhanced our presence in the Americas and the integration into the wider Group has been successful.
I am confident that we will be able to report a robust financial performance for 2020 and a positive outlook for 2021 which is testament to the fundamental strengths of the Group."
Research update - Paul Hill of Equity Development is an excellent analyst, very thorough. He’s published an update today here. There’s also a 10-minute results video out today, here:
.
H1 produced adj PBT of £2.5m. Paul Hill forecasts £3.5m in H2, giving £6.0m for FY 12/2020, which equates to 25.7p EPS.
That’s a PER of 17.7 (based on 455p share price), which sounds about right to me.
My opinion - I’m sitting tight on my small position in MPAC. Looking back, am wishing I’d bought more, but it was terribly illiquid when I was trying to buy at about 280p. Clearly I should have just paid up, not faffed around worrying about a few pence!
The pension schemes are the key issue that need carefully checking out, so people should check the last Annual Report for more detail on that. I’m wary of pension schemes, given how ultra-low interest rates seem to be causing considerable risk of cash outflows needed to prop them up.
Other than that, MPAC seems to be a decent quality business, operating in a nice growth area. Acquisitions are sprinkling a bit of fizz on top too.
Note below that the StockRank system is super-positive on MPAC, a reassuring indicator.
.

.
Judges Scientific (LON:JDG)
6350p (up <1% at 14:02) - mkt cap £400m
Trading Statement
The Board of Judges Scientific plc, a group focused on acquiring and developing companies in the scientific instrument sector, provides the following update on the Group's trading performance for the financial year ended 31 December 2020.
This seems a pleasing update, the key part saying;
… the Group's performance has remained resilient with the second half of the financial year showing a gradual improvement in our trading environment. As a result, the Board anticipates that Adjusted(3) Earnings Per Share for the full year ended 31 December 2020 will be ahead of market expectations(4)....
3. Adjusted earnings figures are stated before adjusting items relating to hedging of risks materialising after the end of the period, amortisation of acquired intangible assets, share based payments and acquisition-related costs.
4. Market consensus Adjusted Earnings Per Share of 151.8p.
Hooray for footnote 4, thank you to the company & its advisers, that saves investors so much time & avoided confusion! Why can't all companies help us in this way?
Unfortunately we’re not given any idea on how much ahead of expectations, so all I can really say is that at 6350p per share, the PER is lower than 42 times, but we don’t know how much lower! These high PERs can’t keep rising forever, and the risk is that they might revert to the mean, or at least reduce somewhat, in future.
My opinion - it wasn’t long ago that we could buy this on about 13 times earnings, so there has been a massive expansion of the PER by the looks of it. That applies to lots of shares.
The price is too rich for me, but good luck to holders.
.
That's it for today! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

131 comments
I wish I could filter out all posts that contain the word “bitcoin”. :-)
A late post for IGotPoesJacket
I sold Solid State (LON:SOLI) today, so missed the peak but banked the profits.
I also sold Dx (group) (LON:DX.) to on the same vain
So on my Patented "Buy High, Sell Low, Buy Back Even Higher" strategy both these are total failures as I made a profit!!! That is a Big Yay as they were both a successful part of the recovery strategy for this year.
My selling was driven buy having been there several times this year with companies such as Begbies Traynor (LON:BEG) Ig Group (LON:IGG) and Premier Foods (LON:PFD) seeing them reach a high, thinking that I should "run the winners" and then seeing them return from a high to a lower value than my original purchase, this time I just pressed the button.
So Solid State (LON:SOLI) and Dx (group) (LON:DX.) will probably do what Volex (LON:VLX) did and storm onwards and upwards from when I sold, but I can sleep at night and hopefully not get anchored should I need to buy back in again.
Though sometimes I wonder if my selling should be seen as a clear buy signal?
Tommy
You don’t get broke selling at a profit :)
Or just take your money off the table and run the rest ?
I get why people think Bitcoin is a bubble and I get why people think it isn't. Personally I have a small holding in it but nothing that I'm going to spend any time worrying about if it crashes. Conversely It's unlikely to make me mega rich either alas :)
What people do seem to be missing in recent events is this
1) the JPM note recently suggested it may go to $146,000 (yes, you heard that right). Need to find a copy of that note so I can check it (yes JPM has the same CEO who originally said that anyone buying Bitcoin in his firm shouldn't be there - so a bit of a reversal then!)
2) A lot of wealthy / well regarded hedge fund managers have been advocating moving 1% of personal wealth into digital currency
3) A large corporate was talking just a couple of days ago about Bitcoin being part of the Treasury function of major corporates going forward, including their own
Now this tells me Bitcoin et al are going mainstream and I suspect it is that realisation that is driving current prices. The market cap of digital assets has now hit $1trillion so it is no longer a poor cousin.
It clearly isn't a Dutch Tulip type bubble scenario. It has already crashed, stabilised around $6,000 then meandered between $10k and $6k and now broken out again. That suggest longevity not a fad.
I'm no Bitcoin evangelist but I do think we should be careful in our dismissal of it.
What is the geopolitical position of bitcoin. People may think gold is a nonsense but the most powerful financial institutions in the world 'covet' it (ie Central Banks).
Bitcoin is a grand nonsense...that is not to say it wont be worth something or even more than now. But it purely a game of tag...
https://mojomogoz.medium.com/b...
nice article mojo
Are there any more pointless campanula news alerts than these from Boohoo (LON:BOO) ?
Tuesday, Morgan Stanley announce holdings moving from 7.03% to 7.07%.
Today Morgan Stanley announce their holdings have moved from 7.07% to 7.03%....riveting stuff!
Judges Scientific (LON:JDG) - if I were ever to fall in love with a bloke, David Cicurel would be pretty high on the list!! He has the qualities and attributes that I find most attractive in a businessman and the company that he runs.
My problem - it's not him, it's me... is that I never seem to know when to fall out of love with a share... And SELL!
Judges has been very good to me over many years, originally buying some at £7.something. I only wish that I had more love to give in those early heady days
I agree that the price can't continue to move upwards at the same rate but who would have thought we would see this level. Also, my 'love' isn't getting any younger and at some time may want to put his feet on someone else's coffee table - his own perhaps.
If I am to part company after so long together, I really hope that it is to some shining knight with big pockets rather than me giving him the push.
Distinctly tongue in cheek! ;-)
Judges Scientific (LON:JDG)
Hello Paul,
Would probably add unreasonably to your prodigious work load but I for one would appreciate as a routine a commentary re where these companies sit relative to their peers. I guess with £JDG that that would include Oxford Instruments (LON:OXIG) (I hold) and Spectris (LON:SXS) for example. I wouldn't sell Oxford Instruments (LON:OXIG) to buy £JDG but if I was looking for one in this sector....
What do you think?
Sdi (LON:SDI) (I hold) is operating in a similar sector and is about 30% of the market cap of Judges Scientific (LON:JDG), despite being on a strong run recently. Lots of room of acquisitions to make meaningful impact on their business yet. DYOR
Guys, I know it's a bit late today but could we possibly have a little note on the crazy movement of Argo Blockchain (LON:ARB)? I genuinely am clueless what to make of it and wonder whether I should just jump on for the ride.
If you think Bitcoin price is going to go up: Buy Argo Blockchain (LON:ARB)
If you think Bitcoin price is going to go down: Don't buy Argo Blockchain (LON:ARB)
Argo Blockchain (LON:ARB)
Before anyone goes long (or short)...check out the directors of the company for a laugh...clearly not a bunch of people that should be regarded as stewards of one's capital....perhaps they can be viewed as capital bar stewards though...
Not sure how Computacenter (LON:CCC) became a topic today but I'm optimistic about its prospects (I hold).
Lovely Stock rank of 96 (including 99 for quality); institutions have added more in the last 12 months; modest PE 21, and most importantly, an upgrade in forecasts in December (since their September 2020 upward revised forecast when the directors sales took place).
Earning momentum is clearly on their side and if I had any cash left, I would be adding to my holding at todays prices.
I'm looking forward to their trading update 21st January
cheers
Francis
Some extraordinary moves today in stocks. Is the rumored bid for Foxtons (LON:FOXT) getting closer? The market seems to think it might be if the rally in the shares today is to be believed.
Meanwhile bitcoin is currently at 38,352.36 dollars. Cryptocurrency is now worth one trillion dollars in total. Some analysts are now suggesting 100K or higher is likely for bitcoin this year. It is very volatile of course. Argo Blockchain (LON:ARB) is now up 40 fold from its March lows. Is this all a bubble? So tough to know.
Bitcoin & the others are a very obvious, and massive bubble.
Only a matter of time until it crashes again. But these things can go to unthinkable heights before they crash.
I know you’re not currently on Twitter, but in my feed there were loads of “My Stimmy” memes of what people were going to spend their $600 US govt supplied windfalls on. BTC and TSLA seemed to be the main two options.
It’s all going to end in tears, not the investors tears, it was $600 they didn’t need, but at some point this all printing money has to come to an end. Markets are horrendously distorted, no longer functional as efficient allocators of capital and just making incredibly rich people even richer.
Interesting. Maybe a market crash (or at least in the frothiest areas) is the mechanism we need to scrub off excess money supply created by QE?
I couldn't believe it when a subscriber here said yesterday that they were worried about fiat currencies being devalued, so had hedged by buying Bitcoin!
Of course, during the manic up phase, punters feel like they're geniuses, despite taking massive risk.
I've just downloaded the audiobook of Kindelberger's "Manias, Panics & Crashes". But disappointed to see I seem to have accidentally downloaded a shortened analysis of it, rather than the book itself. I wondered why it was cheap!
The US markets are overvalued, there is little question about that. But the UK markets have been pretty subdued while investors waited for the outcome of the Brexit negotiations. I think there is a reasonable chance that the UK will be a good place to invest now the Brexit uncertainty has been removed.
If the US markets crash so will the UK's.
I do wonder if there is much sanity in any market ATM'. I sold £MAB early this week after a nice profit and a TU due today with another lockdown upon us with no end in sight it was a risk i was not willing to take. Read the TU and ask yourself how on earth is the sp only down 5% !!! If it had dropped 50% i would not have been surprised.
To be fair, it was obvious from the Mitchells & Butlers (LON:MAB) results published late last year, that it needed more working capital. Hence announcement today just confirming what investors would have generally already known, if they had been paying attention.
Agreed Paul, but with with no end in sight for Lockdown 3 the situation is not as rosy looking as it was in November for Mitchells & Butlers (LON:MAB) . I thought that TU would have spooked the sp especially as there was no detail for the proposed equity raise.
But there is an end in sight.
Government have published their vaccine rollout timelines.
Early Q2 to lift lockdown if you're optimistic. Mid to Late Q2 if you're moderate. Q3 if you're pessimistic.
Provided we dont have to muck around with tweaking of vaccines for mutations which will lead to big delays in the economy opening up.
Recent events in USA may trigger a rotation from US stocks to other regions. UK would be an obvious beneficiary having lagged global indices and with much brexit uncertainty now removed.
"Bitcoin & the others are a very obvious, and massive bubble"
Not sure about that. You said before that you thought there was an argument for gold because of the amount of new money being created while supply of gold was constrained. If there is any truth to that argument then it applies, probably more so, to bitcoin.
There are gold fans around here (like Jack I believe). So if bitcoin is an abvious and massive bubble, why isn't gold?
I own no bitcoin, but note that a lot of the recent buying has come from hedge funds and even the likes of Ruffer Investment (LON:RICA) . It's not a fringe investment any more.
How much has gold gone up? About 50% in 5 years.
I think Bitcoin has gone up considerable more but I don't follow the price.
For there to be bubble form, prices need to go up considerably not just 50% in 5 years.
Problem with Bitcoin is most mining is in China, it uses a lot of electricity, it is not secure and who wants to us it as a form of payment?
Just because somethng goes up in price a lot doesn't make it a bubble. Boohoo has gone up about 1000% in 5 years. Is that an obvious bubble?
For an asset to truly be in a bubble, there has to be an obvious disconnect between price and value.
You can't compare the two things. One is a company with revenues, growth potential and EPS which drives the share price. Bitcoin's current function is to act a store of wealth so it's price is driven by that only - it doesn't have any intrinsic value, only what we place on it.
I'm not sure where I stand on Bitcoin (own a small amount and recently sold out original stake at $29k leaving me with a free stake only) but consider:
Gold went from 1561 last Jan to 1914 today - a 23% increase
Bitcoin went from 7279 last Jan to 39108 today - a 437% increase
ANYTHING that increases on that rate is BUBBLING even if there is very good reasons for it to do so...
Gold and Bitcoin are not interchangeable hedges on inflation. Gold has been around for 1000s of years and is THE universally acceptable store of wealth across the globe. Bitcoin could be something or nothing, we just don't know yet and right now, it is simple speculation. That doesn't mean it won't turn into something special but we are still very far away from that.
I did just check bitcoin prices, in the last 5 years it has gone up over 100 times, gold as I said is up around 50%.
There are gold fans around here (like Jack I believe). So if bitcoin is an abvious and massive bubble, why isn't gold?
In extremis gold can be and often has been used as a medium of exchange / unit of account - i.e. physical gold can be used to actually buy things. Gold has retained its value over time and has proven to be a reliable store of value.
On the other hand, by historical standards, gold does look overvalued. This tends to happen when there's a lot of uncertainty around such as where there's a risk of fiat currency being debased or when the President starts inciting rioters to tear down the US constitution in order to overturn an election result.
It's hard to see how Bitcoin can be practically used as a medium of exchange - there's simply not enough of it and the transaction speed is lousy compared to any alternative electronic payment method. In practical terms you can't use it to buy a newspaper or speed through a transit gate, for instance.
It may turn out to be a reliable store of value but the extreme fluctuations in price currently suggest that's not the case. Bitcoin's price acceleration certainly looks like a speculative bubble.
If Bitcoin actually started to threaten the currency areas that concern central banks and regulators - financial stability, the ability to control money issuance, etc - then it would be regulated. It's not hard to do that, since to spend it you need to take it out of the Bitcoin world back into fiat. Regulators would tighten KYC rules on wallet use and AML rules on cashing in or out. Some are already doing this.
It's an odd situation really. The vast run-up in Bitcoin actually makes it less of a threat to fiat currency:
Waits 10 minutes ...
Happy days on the Bitcoin blockchain though ...
timarr
At the risk of turning in to a champion of bitcoin (which I'm not), I have to say I can't buy your argument (even with a bitcoin). Obviously bitcoin does have it's limitations as a medium of exchange, but it's still a better one than gold! Have you tried buying that pizza with a lump of bullion?! At least people have bought fast food with bitcoin. I seem to remember someone working out in retrospect that
he had bought a burger with bicoin now worth $130,000.
Bitcoin is no threat to fiat currencies or any of the other associated wingnut nonsense. But what it may well turn out to be is a store of value, similar to gold. Why not? And if someone is claiming that it is now overvalued, then please let me in on what it's value is because I don't have a clue.
Have you tried buying that pizza with a lump of bullion?!
Gold can be exchanged in relatively small denominations (and very quickly if both parties accept it). I don't say it's immensely practical, but it's been done throughout history and, in extremis, could be done again. The pizza anecdote relates to the first ever Bitcoin transaction. It would be even more valuable now and not in the slightest bit practical.
Bitcoin may indeed turn out to be a long term store of value but it's only ten years old and has seen extraordinary inflation and volatility in its price. Gold, in contrast, has been performing that function for hundreds, probably thousands of years, and has been relatively stable in purchasing power over that period.
For an asset to be useful as a store of value that value needs to be relatively stable over time. At the moment that ain't what Bitcoin is. That may change in future but at the moment it's best thought of as a speculative trading instrument.
timarr
I can't buy that either! Gold has only been "relatively stable over time" because you're measuring it's stability against currency which was the same thing as gold - the currency was defined in gold terms. Gold has only separated from currency since the end of the Bretton Woods agreement. I challenge you to say that it has been stable in dollar or sterling terms since then.
I would agree that bitcoin has been more volatile than gold over its, so far, brief existence but who can say that will continue once it attains broad acceptance? Even if it did, volatility does not disqualify it from being a store of value. Just look at gold, or silver, or land or ...
”once if gains broad acceptance”
I think you mean “if” it gains broad acceptance. It’s meant to be a currency - it is a complete failure as a currency.
I challenge you to say that it has been stable in dollar or sterling terms since then.
I'm not even sure why I'm having this debate since I mainly agree with you :-)
But in terms of purchasing power gold has been relatively stable over history. The rule of thumb is that an ounce of gold buys a good man's suit. Frankly that's a better suit than I've ever owned, but it's not so far from the truth.
In the end anything is only worth what people are prepared to pay for it. Gold has no more intrinsic value than Bitcoin, it's just less ephermal.
timarr
I listened to this on a freezing bike ride yesterday https://www.economist.com/podc...
Instructive 10 mins. It seems that institutional interest is what has finally spurred BTC on.
Gutted is me! I sold out of my last Argo Blockchain (LON:ARB) in the spring at around 5p and never re-entered. There's a lesson somewhere..........
It has actually seen massive deflation, not inflation. Sorry to be a pedant :)
Sorry to be a pedant :)
From one pedant to another, that's just fine ;-)
timarr
Timarr....but you can now buy, sell and hold bitcoin and fractions of bitcoin via Paypal. No need to worry about the banks etc. Paypal does the lot for you.
but you can now buy, sell and hold bitcoin and fractions of bitcoin via Paypal. No need to worry about the banks etc. Paypal does the lot for you.
True actually, I'd forgotten that. We've been wondering what Paypal is up to.
But it's not really fractions of a Bitcoin. Basically there's a Bitcoin on the ledger (aka the Bitcoin blockchain) and the ownership of it doesn't change or move, it's just turned into fractional units in Paypal's system which are then distributed within the Paypal ecosystem. You can't spend those fractions elsewhere, although you can trade them within the system.
It's unlikely this is Paypal's endgame, but as a shareholder I'm happy to sit back and see what happens.
timarr
Generally speaking Bitcoin is a subject of total indifference from me.
However, re Paypal allowing fractional Bitcoin transactions (of which I was vaguely aware, but still disinterested).
So what is the transactional chain here?
I'm guessing you have to deposit an actual bitcoin (if there is such a thing) with paypal.
Presumably they then create an effective ledger for you of how many bitcoins (or fractions thereof) that they owe you. Presumably payplan strictly speaking own the Bitcoin (at least as far as the blockchain is concerned).
So presumably if you "buy something with bitcoin" they convert the real cash value of the transaction in to fractional bitcoins and deduct this from your ledger?
Or can you only buy things with bitcoin that are priced in bitcoin?
Probably rambling at bit now, but there are a couple of thoughts :
1. Is the separation of risk legally enforceable?
What if the Bitcoin "Bubble" bursts and it goes to zero?
Under the model I hypothesise above, I think :
What about transactions in progress (ie ordered but not yet shipped) - where does the liability sit if the seller decides not to ship the order?
Are Paypal on the hook for potential "mis-selling" claims? Allowing people to effectively trade bitcoin without understanding the risk?
2. Is Paypal now a bitcoin exchange?
I maybe should have put this one first.
The given that the FCA has put controls on trading bitcoin in UK accounts (might be a mis-description, but again I don't care enough to research) is paypal the one place you can still trade bitcoin?
Can I sell something on E-bay but only accept bitcoin? Eg sell a £20 note for £19 bitcoin equivalents - I could even potentially sell it to myself.
I don't think I have ever been the first person to find a loop-hole, so maybe this just doesn't work, but if it does then; (a) Anyone that still wants to trade bitcoin should look to paypal and (b) the FCA & paypal ought to prepare to spend a lot of time with each other (virtually of course)
I'm guessing you have to deposit an actual bitcoin (if there is such a thing) with paypal.
Hi Gromley
I'd guess not, although I haven't looked at it. I doubt most of the people using this can afford a Bitcoin, but fractionalising this allows for lots of people to buy beneficial ownership of a part of one.
You can't deposit a Bitcoin on Paypal, Bitcoins live on the Bitcoin blockchain which is a ledger recording "ownership" (I use the term loosely, Bitcoin is anonymous by design, but you possess the keys that unlock the Bitcoin you own - don't lose them). Basically Bitcoins don't leave the Bitcoin ecosystem.
Hypothesising, Paypal will purchase a Bitcoin and then record ownership of it on the Paypal ledger. Bob now decides he wants to buy a tenth of a Bitcoin, Paypal calculates the value of a tenth of a Bitcoin and Bob pays them that value (presumably plus a transaction fee). Nine of Bob's mates do the same same. The Paypal Bitcoin ledger now identifies Bob & co as being the beneficial owners of the real Bitcoin.
Now Bob & co have proxy ownership of a tenth of a Bitcoin each which (presumably) they can then sell back to Paypal at whatever the prevailing price is (plus a transaction fee). The actual Bitcoin doesn't move.
If I own a Bitcoin I can exchange it with other people - usually selling it to someone else for cash who wants it more than me, rather than exchanging it for goods - and that transaction takes place on the Bitcoin blockchain. The Bitcoin blockchain records the transaction and the proof of work mechanism that underpins the blockchain ensures I can't sell the same Bitcoin to two people at the same time (although you'd be foolish to give me any cash or goods until the transaction is committed to the ledger).
If I own a fractional Bitcoin via Paypal I can't exchange it with other people other than via Paypal as a Paypal transaction (yawn, transaction fee) but I can use it to buy goods from other people on Paypal who accept fractional Bitcoin. Nothing moves on the Bitcoin blockchain - the actual "owner" of the Bitcoin remains Paypal.
Some of the detail here may be wrong, I haven't looked at it, but splitting ownership of Bitcoins up in this way makes them eminently accessible for people who couldn't afford to buy a whole one but is probably part of the reason for the recent bounce in Bitcoin as it's now accessible to people who previously couldn't afford to play.
timarr
Thanks timarr,
Accepting that neither us are that directly interested, your understanding is most probably better than mine.
So from what you say it does look,to me, like paypal have effectively become an (unregulated?) bitcoin exchange.
All too scary for me!
So from what you say it does look,to me, like paypal have effectively become an (unregulated?) bitcoin exchange.
New York has granted Paypal a "Bitlicense". I've no idea what the scope of that is but I think we can be pretty sure Paypal won't do anything that puts them in the crosshairs of regulators.
It isn't really a Bitcoin exchange as I understand it but that's splitting hairs - it allows the same sort of thing.
The best analogy I can think of was the attempt to create a unit trust that fractionalised Berkshire Hathaway shares. The trust (say) owned 1 Berkshire Share itself but fractionalised it into 1,000 units each. So I could then buy 1/1000 th of a Berkshire Share and could trade those as units. The price of the units would vary with the price of the real share but as a unit holder I wouldn't have any of the benefits of being an actual shareholder.
That analogy would be even better if the exchange that real Berkshire shares were traded on and the exchange that the units were traded on were completely different.
(Buffett stopped this by unitising his own shares to create 'B' shares).
Very happy with my Paypal holding but absolutely no interest in cryptocurrencies.
timarr
That’s interesting but is subject to PayPal’s rates of exchange which are generally poor, I always avoid them if I buy anything in a foreign currency.
Indeed. Soaring today to nearly $40K. Argo Blockchain (LON:ARB) and others associated with bitcoin near the top of the leaderboard every day. JP Morgan are suggesting £146,000 is possible. I remember reading about what a single tulip bulb was worth at the height of the bubble.
" In 1633, a single bulb of Semper Augustus was already worth an astonishing 5,500 guilders. By the first month of 1637, this had almost doubled, to 10,000 guilders. “It was enough to feed, clothe and house a whole Dutch family for half a lifetime, or sufficient to purchase one of the grandest homes on the most fashionable canal in Amsterdam for cash, complete with a coach house and an 80-ft (25-m) garden – and this at a time when homes in that city were as expensive as property anywhere in the world.”
A lot of people currently believe that Bitcoin is in a bubble. I'm no expert in bitcoin but it raises the question: How can you invest in something that is intangible, is it really classed as a gamble rather than an investment??
When there was a frenzy for shares in the railway companies over a century ago when the railways were being built across the UK, the bubble burst but at least investors were left with tangible assets which the railways had bought, ie, they had the land, buildings and the steel rails to show for their money. When the bubble burst in the housing market over a decade ago, at least people still had bricks and mortar to show for their money. Likewise, when the price of gold dropped, at least people still had the tangible asset of gold to show for their money which can be used to make jewelry and used in the world of electronics. However, Bitcoin is just a series of 1's and 0's in a certain order. How can you invest in intangible 1's and 0's?? When the bubble does burst, what have you got to show for your money, just some overhyped computer 1's and 0's on a server on the other side of the world??
I'll probably upset some people but in my opinion Bitcoin is not an investment but a gamble. However, it will get the debate under way.
If Bitcoin is only a series of 1's and 0's then so are Facebook, Netflix and so on. To a certain degree now, and more so in future, it's the 1's and 0's that are the most valuable assets.
Again CM, that’s not correct. You can’t compare Bitcoin to a company which owns tangible and intangible assets (IP for example). Bitcoin is different - I am very comfortable comparing it to gold but not any yield producing asset.
Read the posts. I'm not comparing it to the companies, I'm comparing it to the assets that would be left behind if the company folded, as described in the post I was replying to. Digital assets are not companies and assets such as these are not yield producing unless you form a company around them.
His question was how can you invest in intangible assets. Well bitcoin isn't the only intangible asset of high value. Some of the highest value assets in the world are intangible.
Maybe you are right but if I were investing in a tech company I might look at price to book to give me confidence in the security of my money but the decision to invest would be based on EPS and PE - in other words the yield I think the asset will produce. Gold, currencies, commodities or Bitcoin don’t produce a yield on their own. They are a separate asset class - still investable but different.
I don’t invest because of the IP that Facebook has developed but for the cash that IP produces now or I think it will produce in the future. Bitcoin won’t produce a yield on its own - it’s a different thing.
Mostly agree but if, as you say, you are looking at price to book to give you confidence in a tech company "for the security of your money" then you are looking in the wrong place.
Yeah true lol - I wrote that too fast with three kids shouting at me about their dinner - doh
Facebook does have intangible driven Intellectual Property in its code.
By comparison bitcoin has non-tangible driven sentimental props in its vibe.
Nevertheless...bitcoin go zoom...at the moment anyway, and perhaps for a lot more...just best to be aware you are gambling not insuring your future.
mojovision out
The simple difference between a company like Facebook and BTC is that Facebook performs a useful (for many, not me) function that people are willing to pay for, and it thereby generates an income for its owners.
All BTC does is consume energy at a phenomenal rate (now equivalent to the entire consumption of Denmark) to produce absolutely nothing of any value other than as an instrument for gambling and money-laundering.
People buy Facebook.
Facebook is intangible. Just computer code, like Bitcoin. Sure, there's a company behind it. And maybe some tangible assets now like cash, property, machinery, etc. But the core valuation of Facebook is buying an Intangible asset. It's a money printing asset though!
I would disagree that Facebook's value is 'just computer code'.
I would contend that Facebook's value is not anything to do with their code (from an ex-developer, their 'code' as you see as a customer/user might view it is mostly sucky and wouldn't hold any significant value for other companies):
Their database of personal details which they hold for 2.7 billion active users (Q2 2020), I think is more interesting - including messages, pictures and all sorts of datamining-friendly attributes such as political leanings, gullibility quotients etc - actionable information which does have a very material value, even if it is similarly intangible in a true digital sense.
Bitcoin is in my eyes is just a legalised ponzi scheme, allowing speculation to feed a frenzy - up/down/up/down/up [in the order of 0%-50%-10%-30%-15%-100% of today's price when viewed over the last 5 years].
If you watch the Martin Lewis Money Show broadcasted on Thursday 7th January (yesterday) a lady asked Martin Lewis for his thoughts on BTC because she was thinking of buying some. In effect he told her that he is a MoneySavingExpert and he believed that BTC is a gamble.
I also view BTC as a ponzi scheme. Also, my understanding is that BTC is not regulated by the FCA, which means your money / first £85,000 of you money is not protected should your digit wallet get hacked and your BTCs are stolen or if the company which stores your BTCs in its digital vault gets hacked.
Eco Animal Health (LON:EAH) is an interesting one. Current suspended due to accounting irregularities, awaiting audited accounts for FY Mar 2020...!
Their bread and butter are antibiotics for poultry and pig farms.
They're trying to diversify into vaccines for poultry and pigs. But I'm struggling to find out exactly their development pipeline. Also, today's announcement sounds like their vaccine development is not solely in-house, but jointly with partners? Trying to untangle whether they're leading development, or their partners are and they're just doing sales and marketing, etc.
Anyone have any good insight into Eco Animal Health (LON:EAH) or can point to a good analysis, investment presentation, or broker note online?
I’ve been adding to my holding in Eco Animal Health (LON:EAH) since March. I think the fault for the suspension lies with their previous auditor. The new one hasn’t been able to get the books together in time to satisfy AIM due to the operations being spread globally, compounded by COVID-19 restrictions and delays.
Their core product is an antibiotic currently licensed for pigs and poultry for various infective diseases. It is superior to legacy alternatives in improving meat yield per animal and Eco Animal Health (LON:EAH) is able to charge more for it as pork and poultry prices rise. I believe it is off patent but it is difficult to manufacture and the branded proprietary preparations are licensed on a per country basis. The regulation is onerous and competition from generics is not anticipated. The company continues to gain licenses for this antibiotic in more countries or for more indications (different animal or infection) in existing countries, so the market for it is growing. There is a risk that newer better antibiotics may be developed by competitors of course but there are considerable hurdles to this.
Sales of antibiotic have suffered from collapse in pig herds due to a global African swine fever pandemic. Herds have been recovering (especially in China) due to improved infection control measures and a continuing desire by humans to eat pork.
The plan is to diversify their product offering by developing and marketing livestock vaccines and there is a collaboration with a world class animal health institute in Pirbright. Recent news would suggest they are making positive progress on this front, with a vaccine product awarded a license for use in Brazilian pigs.
Other positives for me are: conservative balance sheet, profitable, undemanding valuation relative to other agri-businesses, significant stake held by founder, Soros’ fund added to its holding in late 2019, HQ in New Malden so local bias for me. Could become an acquisition target for a larger agri-business firm but I would rather it continued to grow organically and resume dividends.
Thank you for taking the time to write a detailed reply to my comment! I found it interesting and useful. Going to mull over Eco Animal Health (LON:EAH) while
"Is it just me, sat on my own working from home or.."
No, the rest of us are busy keeping the Auto Trader (LON:AUTO) website visit numbers up.
Ha, I’ve been eBaying for my jalopy :)
I like Cazoo.co.uk as well. Still private but worth watching as it's founded by Alex Chesterman who founded Zoopla and was co-founder of Lovefilm.
"Best funded private company in Europe" apparently, according to Alex recently.
He seems a smart cookie.
The likes of Draper Esprit and the usual VCs have stakes and it seems likely to IPO this year and they will make a good ROI.
Could be an interesting investment but I noticed a couple of others have started up like Cinch and HeyCar - although HeyCar is a middle-man for dealers so not a direct competitor of the online DTC business model but there is a large overlap.
Hi Paul
I've been buying JOUL since the dip after thee last trading update a month ago. Worth comparing the online sales growth at the last trading update:
Dec 8th: e-commerce sales up by 35% in the Period and revenue from Joules' own e-commerce channels1 up by 45%. E-commerce represented more than 70% of the Group's retail revenue during the Period.
Jan 7th: Total retail sales through Joules' websites, including
sales through the Friends of Joules digital marketplace, increased 66%
year on year
Seems to be strong online growth momentum imo. They also have the new £20m warehouse/fulfilment centre which should be making a lot of difference to the business having retail and ecommerce performance together.
Friends of Joules looks a great addition to the website. It seems to be turning over around £2m and as Joules do nothing but take a commission on any sales and let the other businesses fulfil the orders the margins should be very high.
I don't know if you picked up on it but the new CEO is Nick Jones, former Asda/George and gets very good references online and credit for online sales the. Drapers Online have a good interview with him. He seems a very capable guy as far as online goes so I'm not surprised Joules sales online are soaring.
A very interesting retail play if you can look through the next few months imo.
Fantastic additional info on Joules (LON:JOUL) - many thanks Richard! :-)
Is it just me, sat on my own working from home or..
Is the UK collectively really subdued today? Market volumes seem low, barely anyone has commented here or the other boards I look at.
I notice a few good companies price just dribbling away. A serious problem, good time to trade or am I just looking for something to do to whilst bored?
Is it just me, sat on my own working from home or..
Is the UK collectively really subdued today? Market volumes seem low, barely anyone has commented here or the other boards I look at.
I notice a few good companies price just dribbling away. Or a serious problem, good time to trade or am I just looking for something to do to whilst bored?
I think people are probably waiting for some market direction, which means all the Dec FY trading updates over the next couple of weeks here, and in the US, this months quarterly reporting season. If you've not been taking part in the "dash for trash" then IMHO there is not much incentive to do anything other than sit on your hands currently - quality shares still look a bit expensive tbh, and the crap still looks crappy!
I'm all ears as to which good companies you feel are dribbling away though? ;)
All the best, Si
Volex (LON:VLX) , Solid State (LON:SOLI) , Computacenter (LON:CCC)
Volex (LON:VLX) , Solid State (LON:SOLI) , Computacenter (LON:CCC)
I think you're idea of "dribbling" is different to mine. All three are treading water at around their 5 year highs. Just like Covid never happened...
All the best, Si
Between 5 and 10% down.
Like I said, probably bored and looking for something to do rather than be patient.
Between 5 and 10% down.
Like I said, probably bored and looking for something to do rather than be patient.
A pretty dangerous set of circumstances. Sometimes you just have to sit on your hands and wait for prices to come back before you move, rather than buy something just because you can and you're bored. They're all good companies you listed, but hell will freeze over before I pay up for something at a 5 year high on a PER of 15-20 with margins of 5% or less...
Risk wise I think they're probably fairly priced, but I don't want to pay a fair price. If it helps, I read the last Howard Marks missive again the other day to keep myself in check. Cash is not the worst asset to have currently IMHO.
All the best, Si
Other way around for me, I hold and wondering if I should taking profits, same problem though :)
No harm in taking profits but when I do the shares usually shoot up.
I'm holding onto Volex (LON:VLX). Computacenter (LON:CCC) I don't hold, margins are too low. Solid State (LON:SOLI) I don't hold.
Plenty of shares are still going up though.
Computacenter (LON:CCC) the margins aren’t what they appear.
They have two elements to the business.
They have a pretty lucrative and decent margin consulting and outsourcing business that is very successful and (I work in the industry for a competitor) pretty well regarded.
Then, they have a low margin supply business that provides the kit the consulting business sets to work, this drags down the perceived margin and apparent quality of the business IMO.
Just my opinion, you’re, obviously, free to make your own mind up :)
OK thanks, I'm only going by the Stocko figures, which is why I never bought Computacenter (LON:CCC) in the past.
I see some large directors sales recently.
I see some large directors sales recently.
I wouldn't get too hung up by this. If I had a large holding, or options vesting, I'd be selling whilst the current CGT regime is available. I think you'd probably be right to assume that CGT allowances are not going to be quite so generous in future.
All the best, Si
Computacenter (LON:CCC) had a substantial one-off boost last year providing laptops to schoolchildren who were being educated at home. It may well be time to sell now.
They also had a massive boost as businesses needed to get their unified comms strategy right and business solutions securely accessible across the internet. This trend is likely to stay as interim solutions will need to be replaced with properly engineered ones.
Cash is not the worst asset to have currently IMHO.
To be contrarian ... what about banks?
timarr
Cash is not the worst asset to have currently IMHO.
To be contrarian ... what about banks?
Errr. I don't see a smiley so I guess you're being serious! :) I assume you mean UK banks rather than Goldman Sachs? What about them? If you assume interest rates are going to stay near zero for a good while and loan impairments will increase at some point, I can't see the attraction. I know they are all trading well below book value but we all know what happens to the book value of a bank when the merde and ventilateur are in close proximity...
I admit I have no idea how to value banks and don't normally invest in any company that needs 3 or 4 parts for it's results announcements.
All the best, Si
Errr. I don't see a smiley so I guess you're being serious! :)
Only half serious :-)
Casting around looking for value in the market. Can't see a lot, tbh.
timarr
Casting around looking for value in the market. Can't see a lot, tbh.
Me neither. I thought you were maybe scraping at the bottom of an empty barrel when you suggested UK banks :-) I understand that risk has been repriced due to the risk-free rate being practically zero, but just about everything is priced to offer very low future returns too.
Look at Next (LON:NXT) (which I hold) which is now at a 5 year high. A decent update this week, under the circumstances, but even the 2022 numbers are a pale imitation of past years results. It seems to me we are presently being asked to pay up for a lot of future good news and I'm afraid no-one has binoculars powerful enough to see that far... Is that light at the end of the tunnel or an oncoming train?
All the best, Si
Beg to differ on that - Just bought Augean (LON:AUG) at 197 - not bad value I thought , £EQLS still bargain, Personal Group (LON:PGH) - is rock bottom , Saga (LON:SAGA) still bargain , Rbg Holdings (LON:RBGP) - rock bottom , £POLX - price fall
This might come across as incredibly smug / arrogant / know it all. I hope not but I will post my view anyway. The antidote to trading out of boredom and impatience and the resulting losses is to develop a strategy and then a process, keep following it and improving it. I am fortunate enough to have the time to do this and I do understand that many do not have the time or motivation required.
Not exactly UK small cap but I'm buying US banks..
Three potential drivers.
1. The regulators made them aggressively provide for Covid related bad loans and they will be able to release some when things get back to normal.
2. Interest rates heading up, albeit only at pandemic highs.
3. From John Auther's newsletter today - they've had their decade on the naughty step, survived a couple of shocks, and may be due to be rehabilitated. He applies this to all banks, not just US.
Hi Paul
Thank you for the commentary on Gresham Technologies (LON:GHT) (I hold, probably unwisely) - I agree it is overvalued - esp with capex as large as edbitda. But I no longer understand software company valuations. Looking at PER across a few - Gresham Technologies (LON:GHT) at 45, Kainos (LON:KNOS) at 40, dotDigital (LON:DOTD) at 43, Oxford Metrics (LON:OMG) at 40.5. I believe the last three of these are good companies (and some bull points can be found for Gresham Technologies (LON:GHT) for that matter), but surely a lot of future is being built into these price levels. Can I really bring myself to sell some of my successful investments, on PERs of 40+, and put the money into the "recovery" stocks like Revolution Bars (LON:RBG) and Loungers (LON:LGRS). My track record on picking "recovery" stocks is rubbish.
This is probably much too big a company for this board, but I've added to my TCAP holding today, on the basis of the announced rights issue.
Two reasons; TCAP turns from being a useful supplier to quite an important plumbing supplier to global financial markets Also the company was groaning about how tough it was, and then announced relatively unchanged revenues.
Note that the divi is being reduced post rights issue.
I must thank you Paul for all your thoughts over the last year. The events in America in the last few hours are not mentioned yet but your link to John Authers is worth a read today. After watching our own news casters it is useful to listen to what an american thinks of the the situation in the U.S.A. There is bound to be a reaction on the markets but it was reassuring to read such a balanced and intelligent summary.
micke
Hi mickemmanuel,
I did consider mentioning here the events in Washington last night, but decided against it because;
I can't avoid the main topics of the day, covid, and Brexit, because they have a massive impact on the markets. But I try to keep the focus on how those things might affect share prices. Broader discussion of those topics is best left elsewhere on social media, not here. But it's interesting and relevant to discuss how they affect the markets.
Regards, Paul.
Hi Paul,
Apologies, I was one of those posting about politics yesterday. I soon realised that this is not the place and won't be doing it again, unless its something directly relevant to this blog.
Hi Breakout Trader,
Terrific, thank you!
Best wishes, Paul.
This extract from the Cambria Automobiles (LON:CAMB) AGM statement is interesting.
"Notwithstanding the Lockdown impact, the Group's trading performance for the first three months of the current financial year to 31 August 2021 has been ahead of the corresponding period in 2020".
This covers September to November 2020, so includes most of the second lockdown, with the comparison against a period entirely unaffected by COVID. Revenues are down significantly so margins must be up materially. Perhaps this is a new paradigm for car dealerships?
My son-in-law works in sales for a Mercedes main dealer - although the front door is locked he is still in the office selling cars & demand is high just as it was during the first lockdown. Assume other dealers are doing the same..................people replacing cars rather than booking holidays.......
Interesting.
My screens, which are based on companies with big QonQ sales / EPS increases are showing up some auto businesses (US based)... Ford, GM, Penske Automotive, and one or two others.
They've got good upwards momentum, which would also validate your statement.
Interesting to read that. My son-in-law works for a main Jaguar/LR dealer in the Midlands and was saying November was a record (new sales) month for them. Same scenario with regards to closed doors, but still busy
Personally I think Auto Trader (LON:AUTO) monopoly is unbeatable by any potential competitors. I know Pistonheads tried a while ago with a big advertising campaign but I doubt it bothered autotrader. Unlike estate agents where the fees and possible savings are substantial. The fees associated with selling a car are so small, that it makes any potential saving for going with a different, less mainstream brand, not with the risk or effort.
I’m doing a Crumball Rally later in the year - the competition to Autotrader I’ve found so far is eBay and Gumtree and, frankly, they’re both pretty poor. They’re ok for generic items but for cars the filters aren’t good enough to be able to do a meaningful search.
Plus with the auctions on eBay, you get loads of posts of “relisted due to time waster”. What probably actually happened was someone won two or three cars but only needs one.
I frequently browse for cars, and find Ebay tons better than Autotrader - much bigger pictures, more extensive descriptions, and better laid out, on Ebay I feel. Although I agree with you that the filters on Ebay are rubbish!
At the bottom end, eBay is better as the listing fees are cheaper so there’s more of the kind of car I need for the Crumball, but I’ve had to give myself plenty of time so that I can make sure I’m only winning one auction at a time, which is frustrating.
imo www.themarket.co.uk and www.collectingcars.com auction sites are way more interesting for unusual cars. Often 200+ photos, some of the bottom. Fees are not that cheap though, eg 6% capped at £6k. I was stuck in a traffic jam once with a friend when The Market called to take details of his car - they went to an impressive level of detail.
Thanks for the links, very interesting but not much there for the £200 Crumball recommend (I think I’m going to spend around £400 - seen some PT Cruisers for that money which I think will make a good Crumball car) :)
Ahhh - hadn't appreciated that limit. PH Shed of the Week is always a good read. The limit is now £1,500 sadly, but occasionally they'll go as low as £500 and there's always scope to haggle. Here's their best of 2020 https://www.pistonheads.com/ne...
fwiw, my Integrale Evo 2 owned a decade ago bore the rear window sticker ''My other car's a Skoda'' And that was a Rapide for those with long memories. Over its short life I spent more on gungum than a new exhaust would have cost!
Apologies for going so off-piste.
Hi iain1234,
The fees associated with selling a car are so small, that it makes any potential saving for going with a different, less mainstream brand, not with the risk or effort.
That's a very good point, that I didn't think about. Thanks for pointing it out. Although whilst that might apply to selling individual cars, it may not be the case for dealers listing dozens or even hundreds of vehicles for sale?
Regards, Paul.
RE: Auto Trader (LON:AUTO)
The fees associated with selling a car are so small, that it makes any potential saving for going with a different, less mainstream brand, not with the risk or effort ... it may not be the case for dealers listing dozens or even hundreds of vehicles for sale?
I don't know precisely but I have a done a small project in this area and the fees for the dealers were small as well. They were pretty slow to pay too, so there's liquidity risk. It's very much a volume business.
There's a subsidiary issue that marketplaces that "own" both seller and buyer now have to be regulated as payment institutions, which adds a whole new layer of regulation and costs, and further discriminates in favour of the bigger platforms.
I suspect the biggest risk here is someone like cars.com deciding they want to take a piece of the market. But why wouldn't they just buy Auto Trader (LON:AUTO) if that's what they want?
timarr
Facebook Marketplace is quite a threat to any other marketplace: it charges no fees unless you run an ad, gets incredible reach and has stronger trust between buyers and sellers than any other platform.
Iain1234 Auto trader £AUTO your comments regarding fees associated with selling cars are so small ,talk to any motor dealer and they will tell you Auto Traders fee's are far from small Trader's are always looking for a cheaper option ,yes Auto Trader are the biggest and probably the most widely used but in terms of return on costs they fall well short.
I agree on Greggs (LON:GRG) and I sold mine recently. Where I work most people want to maintain working from home for at least 2-3 days per week permanently and I can imagine this being the case at most offices around the country - I don't think footfall will ever be the same.
I agree that footfall is unlikely to be the same for some time, I guess the unknown in relation to hospitality related business is how many competitors will fall by the wayside?
Yes good point, as weaker businesses fall it may very well compensate for it. In the end I knew I would kick myself if I did not get out when I started doubting the outlook, whereas, hopefully (!) I can live with missing out on a gain providing I had good reasoning at the time.
This is true of so many sectors now - the disruption caused by CV19 to personal habits is the largest we will see in our lifetimes and the truth is no-one has any idea how it will shake out. It really needs to be factored into any share purchase where there are physical real world stores because things are not going to go back to the way they were - in 2022 are office workers still going to work/ will they still commute the same way, how are universities going to teach - more online?, is the tourist industry coming back/ will tourists do the same things?, will shoppers go to town centres anymore etc. etc. etc.
I'm not being all doom and gloom here - I think UK shares will have an excellent year and I think the new normal will see a lot of winners. But the changes to working and shopping patterns will be felt long after the pandemic is in the rearview mirror. And those businesses that have physical spaces will have at least relocate (and probably totally reformat) to avoid being left behind.
Paul has long talked about the fashion industry and the importance of online sales and the huge drag of legacy stores on balance sheets. Companies like Greggs (LON:GRG) have built a huge trading estate based on 2019 footfall levels - I'm clear that this will be significantly different in 2022 but they can't even start changing the business yet to react because we have no template as to what those patterns are going to be and online isn't really an option for them.
I certainly agree with this. Pre CV19 my work was strongly against remote working but now the option of 2-3 days per week will be available to all and I can only see this increasing. In time I could see a lot of people would prefer to move out of congested city life and move to more rural areas if they can still work remotely but that will be a long way off.
On a related note I notice on Greggs (LON:GRG) page it is still showing a long term estimated growth rate of 10.2% - is there any way to see when this was last updated?
The broker equity development put out a quick note on Mpac (LON:MPAC) before market open this morning which was very helpful. Following the 'above market expectations' update put out by the company, the broker now has adjusted EPS at 25.7p for 2020 and 31.4p for what is now the current year.
After the rise this morning that's a p/e of around 15. I can't quite decide if that's a price worth buying at or not. In the past revenues have sometimes been a bit lumpy + big pension, and I am particularly wary of paying too much for companies with lumpy revenues. But offset against that Mpac (LON:MPAC) also on the hunt for acquisitions and the group does seem to have turned a corner, plus the pandemic has put a spotlight on the need to improve security of supply in supply chains so that might boost demand for closer-to-home manufacturing facilities.
I am sitting on the fence for now but will monitor for any pullback especially as I think the market is looking toppy at a time we still don't know much about the new UK and South African variants. Thoughts?!
Mpac (LON:MPAC)
Agreed. I managed to overlook this one on my watchlist - frustrating. Must do better.
At first glance it appears to be delivering. And perhaps moving into a more consistent growth phase with the US acquisition helping to smooth out the growth.
I like the sector, it has a 'picks-and-shovels' appeal but am wary of over-paying in advance.
I detect a slight whiff of spin in the announcement, reading as well as it does at first. On re-reading the underlying proft will be ahead - which may be marginal, not significant or it would say so?
Order book has not grown, it's trading on 16x FY19 reported earnings and upwards of 20 for trailling 12 momths.
I will join you on the fence for now - but I remain intrigued and may well regret not having bought earlier,
cheers
Mark
I've followed Mpac (LON:MPAC) for a long time and have owned from the 200p mark I think so decent profits but not tempted to part company with the shares just at the moment. Good company and well run in my opinion with plenty of scope for growth in a number of areas, including remote servicing. It is the latter that should smooth any lumpiness in machine sales. There was a presentation done by management a few months ago that I imagine is on their website and worth checking out as you can see where growth comes from.
Agree it is broadly fair value right now though there is the matter of 75p approx worth of cash so if you strip this out then on around 11-12 times cash adjusted earnings you can argue it's still pretty good value. There is also hidden land value that may/may not be unlocked through planning and I seem to remember that was quite material (ie 100p or so).
Management not particularly prone to spin in their announcements so I read into this that the business/strategy is performing well and better than they had anticipated. For me that only adds to case for me continuing to hold.
The stock is held back by the size of the pension. I am pretty sanguine about it personally and they are on track to pay down deficits early (next 3 years I think) which will increase annual free cashflow by quite a bit. But nonetheless and irrespective of my own comfort with the pension others take a different view and this aspect does hold the share back a bit
I hold and my take is that given COVID the annual performance is good. I am also encouraged that the switchback acquisition which was expected to be earnings enhancing is performing ahead of expectations. Next fy it will make a full years contribution.
It seems to be in the right sectors and I shall continue to hold
Very curious that the Equity Development note upgrades the Revenue and EPS for MPAC to £95m and 31.4p when these are already given as £101m and 37.4p on Stockopedia. Unless there is/are an/other significantly more optimistic broker forecast(s), the numbers here look more than a little strange.
The stock report says it’s covered by 4 analysts. As far as I know, the forecasts are taken from a third party supplier and represent the consensus.
But Mpac (LON:MPAC) pay Equity Development, so are probably comfortable with their forecasts.
You asked why the Stocko report had a different number. You’re free to use the one you’re most comfortable with :)
Yes it irritates me that, as a paid-for service, Stocko choose to quote only consensus analyst figures, especially when we're still in an era of significant numbers of out-of-date forecasts due to covid impact. Even the free FT market data at least gives High, Low, Consensus if you hover your mouse over the bar charts. Eg https://markets.ft.com/data/equities/tearsheet/forecasts?s=FXPO:LSE#:~:text=Share%20price%20forecast,the%20last%20price%20of%20281.60.
Hit the green smiley bottom right and send them a message. They always reply and are incredibly courteous, understanding and genuinely want to make the product better. They will appreciate the feedback.
The Mitchells & Butlers (LON:MAB) RNS this morning is stark. Pub shares are going to dive today I think
Only pub shares with weak balance sheets and poor future forecasting of their requirements.
Lol Dah, I run a small group of pubs and let me tell you future forecasting of requirements is pretty tough right now. I think it’s safe to say no-one has been right to date...
My morning smallcap tweet:
ECO Animal Health (LON:EAH) Avacta (LON:AVCT) Mattioli Woods (LON:MTW) MPAC (LON:MPAC) Joules (LON:JOUL) Judges Scientific (LON:JDG) Cambria Automobiles (LON:CAMB) Creo Medical (LON:CREO)
Eco Animal Health (EAH) get Brazil marketing authorisation for for Circo/MycoGard, a vaccine for swine. "This first vaccine marketing authorisation in Brazil marks a significant milestone as we build our capability with vaccines and broaden our product portfolio." [SP=255 Cap=167m]
Avacta (AVCT) license agreement with POINT Biopharma to provide access to Avacta's pre|CISION technology for the development of tumour-activated radiopharmaceuticals. "Upfront fee and development milestones for the first radiopharmaceutical prodrug totalling $9.5m. Avacta will also receive milestone payments for subsequent radiopharmaceutical prodrugs of up to $8m each, a royalty on sales of FAP-activated radiopharmaceuticals by POINT and a percentage of any sublicensing income received by POINT. [SP=132 Cap=334m]
Mattioli Woods (MTW) H1(Nov): total client assets and its associate over £10bn. Guides FY profit in line. [SP=758 Cap=213m]
Mpac (MPAC) guides FY(Dec) U/L pretax above market expectations mainly due to better than expected margins in Q4 driven by sector mix. FY21 order book flat. [SP=416.18 Cap=84m]
Joules (JOUL) recent 7 weeks retail rev up 0.3% despite store rev down 58%. Estimates lockdown rev hit £14-18m (c. 8% of FY rev) if continues to Apr 1. [SP=181 Cap=196m]
Judges Scientific (JDG) guides FY(Dec) adj EPS ahead of market expectations of 151.8p. Organic order book 14 weeks of budgeted sales (13.2 weeks). Strong bookings by the recent acquisitions brings the total order book to 15.5 weeks. [SP=6300 Cap=397m]
Cambria Automobiles (CAMB) Q1 rev up YoY. Co traded well in Sep & Oct but Nov hit by lockdown. Guidance still suspended. [SP=56 Cap=56m]
Creo Medical (CREO) gets FDA clearance for tissue ablation device MicroBlate Flex. "We expect to see further first clinical use of our products in various markets..." [SP=194 Cap=306m]
Thank you for this helpful commentary Paul. I notice that as I get older I have become far less interested in company commentaries unless they are very clearly backed up with facts/numbers.
Good luck on the campaign for more company updates to have clearly laid out tables.