Small Cap Value Report (Thu 7 May 2020) - BOTB, VTU, SDRY, FLTA, HYVE, COST, RCH, WRKS

Good morning, it's Paul here with the SCVR for Thursday. In a rare turn of events, I'm up early today & feeling quite perky, so today's report should be earlier than usual & there's stuff left over from yesterday to catch up on too.
Please see the article header for the list of company updates which have caught my eye today.
Estimated timings - most of the article will definitely be up by 1pm today. But I'll probably continue adding sections after that, in order to catch up from yesterday.
Best Of The Best (LON:BOTB)
Share price: 435p (pre-open, likely to go up)
No. shares: 9.38m
Market cap: £40.8m
(I have a long position in this share)
Best of the Best PLC, (LSE: BOTB) the online organiser of weekly competitions to win cars and other lifestyle prizes, is pleased to provide the following trading update for the 12 months ended 30 April 2020 (the "Period").
Once again, BOTB has out-performed against forecast. This is becoming a pleasing habit!
The Company's financial performance throughout the Period, and particularly the second half, continued to be strong.
As a result, the Board now expects to report full year revenue and profit ahead of current market expectations.
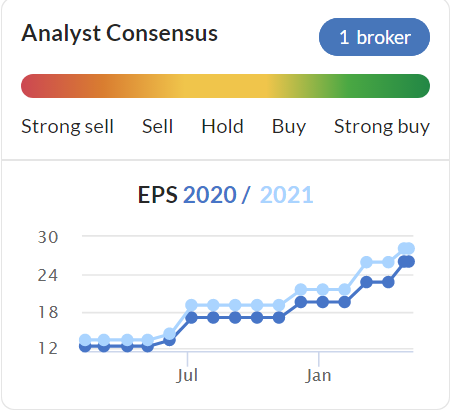
Note this comes on top of repeated increases in forecasts previously;
.
Another point to consider, is that these big increases in profitability have been achieved despite the headwind of adverse changes in taxation (remote gaming duty, and VAT).
Forecast - house broker FinnCap is excellent in getting its research out to investors, via both Research Tree, and its own research portal. A brief update today shows a big increase in forecast for FY 04/2020 - EPS is up to 33.2p now, up nearly 91% on last year!
Forecast PBT has gone up 27% on the previous forecast, to £3.8m.
My opinion - this share should fly today, it's way too cheap, in my opinion. It's rated at only 13.1 times newly raised FY 04/2020 forecast. The share price should be double the current level, in my view, since a PER of 26 would be perfectly reasonable for a share that's growing earnings so strongly.
I just emailed the CEO to congratulate him with a simple message, "You guys are on fire!"
This company should be benefiting from more people staying at home, and not being able to spend money on socialising, etc. We all know what most men do when stuck at home - watch football, and try to win a supercar online! ;-)
Vertu Motors (LON:VTU)
Share price: 24.9p (up 2% today)
No. shares: 369.2m
Market cap: 91.9m
(I have a long position in this share)
This is a chain of car dealerships.
The quick version is that it has plenty of liquidity, modest gearing, and loads of freehold property.
I'll fill in the detail here later. Today's update overall sounds reassuring.
Superdry (LON:SDRY)
Share price: 125p (up 6% today)
No. shares: 82.0m
Market cap: £102.5m
Branded fashion retailer & wholesaler.
Trading performance impacted in Q4 by Covid-19; focus on cash preservation
I last looked at this share here on 10 Jan 2020 - pre-covid of course. It was a profit warning, indicating that the business was trading around breakeven. I dread to think what the figures are going to look like now, once the impact of store closures is factored in. It has an end April 2020 year end.
Key points;
Ecommerce revenues nearly doubling in the last 4 weeks to approximately £3.7m per week vs the average prior to complete lockdown, offsetting approximately one third of the lost store sales.
Net cash of £39.8m as at 5 May 2020 - not bad. I looked at the last reported balance sheet, and it's fairly strong, so I think SDRY is not at immediate risk of insolvency.
Furloughed 88% of all staff, as you would expect
Board taken 25% temporary pay cut, and bonuses stopped
Suppliers - better terms agreed, and reduced intake quantities by 20%
Landlords - most have agreed to 3 month rent deferral, worth over £20m. Good to see landlords being pragmatic. Many SDRY sites are expensive, flagship-type stores, that would be empty if SDRY goes bust. Rent negotiation programme underway for longer term. £16m benefit from business rates relief
Discretionary spending & capex reduced, as many companies are doing
Tax - deferring VAT, payroll taxes, etc, benefit of £5m to cashflow. Corp Tax recovery of £8.5m - it's really good that SDRY is giving specific figures, to help investors/analysts model the numbers more accurately
Dividends - no final divi for FY 04/2020 - no surprise there. I doubt any divis are likely for several years, if ever
Bank - waived April 2020 covenant test - suggests bank is taking a cautious approach, just loosening the immediate covenant test, but not any future ones presumably, as yet?
Funding - it needs more, and sounds like existing banks might be reluctant to lend more (I don't blame them!);
The Company continues constructive discussions with its existing lenders and with potential new financing providers as it explores the need for the necessary flexibility and additional liquidity going forward. This includes exploring its potential eligibility for government backed borrowing facilities through the recently launched CLBILS programme.
Performance figures - are irrelevant, given lockdown & stores now being closed.
My opinion - I was negative on this share pre-covid, and really cannot see why anyone would want to buy it now either.
On the upside, its current net cash position gives it a few months maybe to put together a refinancing. If that is not achieved, then the autumn is a likely crunch point, when cashflow turns negative to fund the autumn/winter stock build. Plus all the deferred costs will have to be paid at some point.
Stores should re-open soon, but at what level of reduced revenues? They might end up losing more money open, than closed., that's unknown at this stage. The shop leases are the big problem here. The last balance sheet showed £73.8m rents in current liabilities. If my understanding is right, this should be the annual rent cost, which is just way too high for this business to be viable now, in my view. The £265.9m over 12 month lease liability, suggests the pain continuing for another c.4 years. Leases are fine if the sites are trading profitably. They're a millstone when operating at a loss, and often pull down the whole company. That's a big risk here, in my view.
Rising online sales is a positive, but not enough to offset the problem stores.
It seems to me that SDRY is an obvious candidate for a CVA - to ditch all those high rented stores. A slimmed down retail estate, combined with a focus on mainly online sales, looks to be the way forward here. Where that leaves the share price? Who knows. It depends entirely on if & how new funding is secured.
Therefore, at the moment, this is high risk & uninvestable, in my view.
Filta Group (LON:FLTA)
Share price: 112.5p (up 57% today)
No. shares: 29.1m
Market cap: 32.7m
Launch of specialist COVID-19 sanitising service
Filta Group Holdings PLC (AIM: FLTA), a provider of fryer management and other services to commercial kitchens...
This franchise company issued an update on 23 March 2020, saying that it has been impacted by covid, as you would expect, given its activities cleaning commercial kitchens, most of which must be shut down since late March.
Management has obviously been thinking of ways to drum up more business, and they've come up with this;
... pleased to announce the UK launch of FiltaShield, a new sanitising service to help businesses combat and prevent the spread of Coronavirus (COVID-19).
Working closely with industry experts and specialist chemical suppliers, Filta is extending its range of environmental services and deploying an approved, laboratory-tested Coronavirus sanitising solution, which is effective against all enveloped viruses, killing them within minutes. The anti-viral solution, which has been developed for use in restaurants, bars, shops, offices as well as healthcare facilities, is applied to a surface by spraying or fogging, leaving behind a mono-molecular layer that bonds to the surface and protects surfaces for up to 30 days.
It's also offering temperature screening equipment, to check if customers have a high temperature & hence may be ill with covid.
My opinion - these look sensible new services to offer its existing customer base.
Neither service appears to offer anything proprietary, or unique. Therefore, whilst it might generate some extra revenues, I wonder how many restaurants could afford to get someone in to do this? Surely better to just buy the fluids & spray them on yourself?
"Up to 30 days" is a nice catch-all claim. After all, 5 minutes is less than 30 days, so would fit that definition!
My opinion - business is likely to be dire for FLTA and its franchisees. We already know that restaurants are likely to be one of the later stage sectors to see lockdown eased.As a longer term proposition, FLTA looks OK, and the US growth could be interesting. Hygiene in kitchens is likely to be more important going forwards, due to ongoing virus threats. I think that shops are likely to be allowed to open imminently. After that, the stock market is likely to start anticipating the subsequent re-opening of bars & restaurants. Therefore, bombed out stocks in this area could have decent recovery potential, providing there is no setback with a large increase in covid cases from the early stage easing of lockdown.
Today's 57% jump in share price looks barmy to me, so provides an excellent selling opportunity, for anyone who was not sure whether to continue holding or not.
Hyve (LON:HYVE)
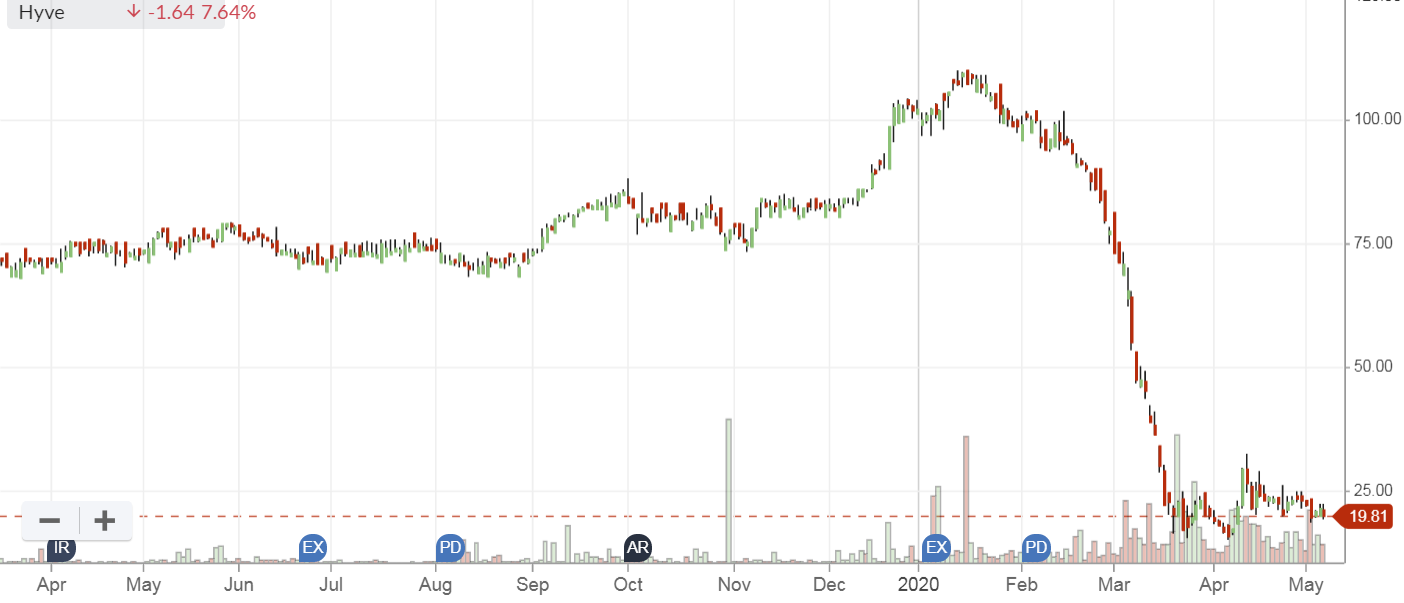
Share price: 19.9p (down 7% today)
No. shares: 815.8m
Market cap: 162.3m
There are 2 announcements today - interim results & a rights issue.
Hyve Group plc is a next generation global events business whose purpose is to create unmissable events, where customers from all corners of the globe share extraordinary moments and shape industry innovation. Hyve Group plc was announced as the new brand name of ITE Group plc in September 2019...
Interim results - to 31 Mar 2020 are now largely irrelevant. The only thing that interests me is the balance sheet, which is very weak, something I warned readers about here on 5 Mar 2020.
Net debt is £157.2m - up 44% on prior year due to unluckily timed acquisitions.
Balance sheet -a train wreck, laden with intangibles & debt.
NAV: £198.6m, but take off £147.6m intangibles, and £280.9m other intangibles, and NTAV is negative, at £(230m). Even the proposed rights issue still won't put this right, in my view. Post-covid, I don't think any company should be operating with negative NTAV, as we now know that doing so is a lot more risky than previously thought.
We might well ask, how come shareholders, management, and the bank thought it was sensible to agree to such a weak balance sheet? I think the answer must be that they thought the shows/exhibitions were valuable assets, which up until covid, they were. The trouble is now, everything has changed. We don't know what resale value, if any, the rights to these exhibitions might be in future.
Going concern statement - worth reading for anyone considering buying or holding this share, as it reminds us of the risks. Concludes that the rights issue, combined with relaxing of bank covenants & loan repayments, leaves the business "well placed" & gives it adequate resources for the foreseeable future.
Rights Issue & Agreement with Lenders - key points of this fundraising;
Underwritten, hence it's definitely happening (at a cost, underwriting fees will be substantial)
Raising £127m
Linked to bank waiving covenants & deferring £35m term loan repayments - perfectly reasonable for bank to require shareholders stump up fresh equity, in return for lenience from the bank (who are horribly exposed to this)
Share consolidation of 10:1, so share count drops by 90%, and share price simultaneously goes up 900%, thus market cap remains the same
Huge price discount of 67.8% for Rights shares, at 6.9p in old money, 69p in new money (post consolidation). This is reduced to a 39% discount on the theoretical ex-rights share price. I haven't got time to work through all the maths on this. The upshot is that existing holders are heavily diluted if they don't take up or sell their rights.
Big dilution - it's 9 new shares for every 4 existing (on a like-for-like basis)
My opinion - this is a great example of an overly-indebted group, which has run into something unforeseen, and being too weak financially to weather the storm. Hence the share price has collapsed, and new equity has to be issued at a deep discount.
If things were to return to normal quickly, then I could see the logic in buying into this. The trouble is, we don't know if, or how soon, exhibitions are likely to resume, nor how successful they will be. Do people really want to congregate at events like this? Maybe some will, with social distancing and masks, but I wonder if these events would be as profitable as before? That's impossible to know at this stage.
Plus there's all the disruption of re-scheduling events, etc, which is bound to lead to some exceptional costs.
It looks far too messy to me at this stage, but could become more attractive if covid subsides & does not return.
This is really a geared play on covid. Even after the fundraising, the balance sheet would still be weak, and I imagine divis are probably a thing of the past.
Overall then I see this as unattractive for now.
.
Lunch time now, I'll be back later.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Update on BOTB post seeing just how easy it was to find online.
According to their 'about' page, BOTB went totally online at some point, they do not operate out of airports or shopping centres anymore. They were also top of the shop with its advert for what looks like good old fashioned spot the ball.
This is clearly a much better state than suggested by my post below which was an honest comment based on this page's info.
In my opinion one factor overlooked going forward is how many tickets they manage to sell from deserted airport terminals and shopping centres. When passengers or shoppers are present the challenge of achieving a socially distant lottery ticket transaction should not be ignored. It could be an avoidable hassle. Add to this whether you have never stumbled across their super-car lottery ads whilst on the internet; I haven't and hopefully this is the area they have managed to expand rapidly. Is there not a risk that the business model has collapsed post Covid and it could take time to recover sales. (I have no financial interest in these shares).
worth reading previous trading update. There are no retail sites left, now 100% online with social media growing exponentially
The government's plan to avert cope with Cocid is to spend vast amounts of money. Does the government have a plan in the event of a bond market collapse ?
Why would the bond market collapse, when there is a guaranteed buyer for all Gilts, to an infinite size - the Bank of England?
Why do you think interest rates are zero? It's bizarre, but that's the truth.
Another posting of biblical size. Keep it up Paul.
I wish that one day I could read about a boring, safe, reliable, dividend paying, environment caring, UK smaller company, which has not been impacted by Covid.
I found one and dithered too long, then kicked myself when the price rocketed (Wynnstay).
Does another exist?
GreyInvestor, does Bioventix (LON:BVXP) fit the bill for a boring, safe, reliable, dividend paying, environment caring, UK smaller company?
Shameless plug:
https://soundcloud.com/thenakedtrader/radio-show-4
Brand new podcast inc a look at loads of shares, mainly potential virus hit company comebacks, experienced traders tips for beginners, fat finger disasters, how not to trade like Corporal Jones, and £100 numbers competition.. and (hopefully) lots of silliness.
Treat as entertainment!
And.. just to say... incredible there is at least one forum left that isn't full
of crazed loons.
Thanks Robbie, I'll check out your podcasts this weekend! Best wishes, Paul.
P.S. Is it on Apple's purple podcast app? I can't see it there. Would be great if you could publish it on there, then everything is in one place. I don't use SoundCloud any more.
"And.. just to say... incredible there is at least one forum left that isn't full
of crazed loons."
Let's hope it stays that way!
The Momentum master is in the house always a welcome addition.
Robbie - it would be great if you could get this on another platform as well as soundcloud - maybe Apple podcasts or even Spotify!
Many people find them much easier to work with.
Listened last night, absolutely brilliant!
Listened this morning Great Music lots of fun . It was like Radio 2 Jeremy Vine with pearls of wisdom, examples of good and bad decisions, lessons learnt and a few stock reviews too. Very enjoyable. thanks Robbie.
Vpc Specialty Lending Investments (LON:VSL) - has anyone ever looked at this company. It is quoted in the UK but trades in the US. I have held it in the past for dividends but got out when it started to fall. It makes asset backed loans to small companies. The dividend is now in the teens which would suggest a reduction or a further fall in price. However today's RNS's indicate the dividend to be maintained with little so far in the way of defaults.
Hi double. Like you I also held this formerly for the dividend, and it served that purpose well. However they invest in debt, and default levels will now have to rise. NAV is now 89p. The letter published today says a lot of optimistic things, and stresses that most interest payments for March were collected, but notes "delinquency" rates will increase. There is little cash reserve, so dividends must be halved at least. I have similar debt vehicles still, and will wait and see what happens. I do not think now is the time to add.
So Filta Group (LON:FLTA) up 70%, this has to be algo trading & a market maker 'having a laugh' shirley, call me anything you want in this market!
So last week I raised the question over Games Workshop (LON:GAW), so today priced at same as January 2020, so must have been unbelievably undervalued in January, right??
And today Filta Group (LON:FLTA) - January average price about 150p, and its now 123p (and actually +73% so another 3% since I started writing this, tis madness).
So today it's worth 18% less than January where it currently has very little income, no forecast, highly likely a permanent loss of value but it can clean your work surfaces for you - wow. As pointed out here thats (1) - already announced, (2) hardly unique, (3) still a lot less business to go after (or maybe they will try for all businesses & not just restaurants) but to me there is no way on earth I'd be buying this now, so who is, tiny volume I suspect. Maybe if it was option money but this is now 18% less than a pretty bubbly market in January.
Purpleski - hold your nerve, this aint over yet, how can it be, the outlook for the UK is staggeringly bad & a government showing no signs of understanding just how bad, what a farce.
john652 - I concur with your puzzlement on today's rise in Filta Group (LON:FLTA) and it appears that the company does as well - it has issued a second RNS to point to no material change https://www.stockopedia.com/share-prices/filta-group-LON:FLTA/news/filta-group-holdings-further-re-specialist-covid-19-sanitising-service-urn:newsml:reuters.com:20200507:nRSG2931Ma/ It must have been the use of the words "specialist COVID-19 sanitising service" in the title. It reminds me of a few years ago when any small cap mentioned the word 'blockchain' it doubled in price.
Hi Sharw,
I think you are correct that the mention of Covid in a positive light, leads to automatic's buying & then a load of momentum & a ratchet up of the price by the MM.
can someone please help me, on a day when the bank are suggesting we could be about to see the biggest recession ever, why are so many share prices flying? Perhaps I’ve missed something? It’s no wonder so many people stay away from investing when there’s so little rationale (again, unless of course I’m missing something quite obvious).
Pure optimism is what I think. The gov is talking about easing restrictions next week, the question I'm pondering is is this the beginning of the end or the end of the beginning? At the moment I am leaning towards the latter.
Thanks Jeff, appreciate your thoughts
I think it's the sheer scale (unprecedented in size & scope) and speed of Govt intervention in USA, UK, and some others. I'm coming round to the view that this is unlike any previous recession, and at least a partial V- shaped recovery is looking more likely. Running a Govt spending deficit of 14% of GDP (OBR estimate) is unprecedented, and basically cannot fail to make the economy recover, providing we don't get a severe second wave of covid.
Shops are about to re-open it seems, with restrictions. If that works OK, then people will want cafes/bars/restaurants to re-open also. The market seems to be pricing-in this recovery, at least partially in some sectors.
There's also a tech share boom going on, which inflates the indices.
Not saying I agree with all the above, but that's what seems to be happening.
Thanks for this Paul, really helpful and gives me some hope to be honest! I wish I had more balls to buy different shares but just long in one at the moment which is probably enough for me.
Hi Paul,
Running a Govt spending deficit of 14% of GDP (OBR estimate) is unprecedented, and basically cannot fail to make the economy recover.
I'm not so sure about this as I wonder how much of this debt is just to keep things ticking along & stopping whole sectors from disappearing & half the companies in the uk going bust. They are bailing out pretty much everyone & putting 1/4 of UK workforce on 80% wages.
A lot of these people are likely to loose their jobs (the companies will not keep a 100% workforce when demand is down), millions already have lost jobs, and those left are not going to spend like it's Christmas.
Now if they had plowed 14% of additional stimulus into the market, sure, massive impact, but how much of this is just keeping things ticking along. In 3 months time huge sums will have been spent, demand will be down, with lots out of work, so is this stimulus the size it initially looks, or in fact much much smaller?
If we imagine none of the furlowed workers loose their jobs (very unlikely), in 3 or four months time we would still have a nervous public, many redundant, massively indebted companies & a huge deficit, but how much actual stimulus? What ever it is , is it enough to sustain the markets, because we have massive debts everywhere & less demand, so I don't see how that won't be a drag on the economy, and resulting downward pressure on share prices.
No doubt the gov intervention is driving the market (some tech is justified) but for how long is my question (and on this I am pretty sure my crystal ball is accurate, until more is needed of course! - madness!!)
can someone please help me, on a day when the bank are suggesting we could be about to see the biggest recession ever, why are so many share prices flying? Perhaps I’ve missed something? It’s no wonder so many people stay away from investing when there’s so little rationale (again, unless of course I’m missing something quite obvious).
Hi Jamie,
All I would say is to ignore the market and concentrate on building and holding a portfolio of quality companies with solid balance sheets instead. As we have already seen with many comments here over the past month or so, pretty much everyone trying predict it has called the market wrongly. Unfortunately, some people will likely have sold up very close to the bottom and now will be gnashing their teeth. You have to assume you do not know what the market will do when investing, because it's true, you don't! Invest on that basis.
In over 20 years of investing I have lost count of the number of times I thought I knew where the market was headed and called it wrong. This costs real money (opportunity cost) over time and once I realised you don't have to be 100% cash and gold, or 100% invested in equities it made things feel much easier. Once you admit to yourself you have no idea what the market will do it is actually quite liberating. It allows you to concentrate more on finding and holding good companies.
That's all I would suggest. I know it won't go down well here because we have so many far cleverer people than me. Things are very uncertain right now, that's for sure, you just need to decide how defensive or aggressive you want to be. I am tending to the latter and I'm 32% cash and buying selectively but that's been the wrong approach so far. Howard Marks has written some great memos on this subject, including his latest: https://www.oaktreecapital.com/docs/default-source/memos/knowledge-of-the-future.pdf
All the best, Si
Things are very uncertain right now, that's for sure, you just need to decide how defensive or aggressive you want to be. I am tending to the latter and I'm 32% cash and buying selectively but that's been the wrong approach so far.
As Charlie Munger says:
“Nobody in America's ever seen anything else like this. This thing is different. Everybody talks as if they know what's going to happen, and nobody knows what's going to happen"
Nothing wrong with cash in uncertain markets, it provides optionality.
timarr
Absolutely. He is wisest who knows what he does not know.
Thank you Si, so many great posters on here! Really appreciate your thoughts!
Great post Si, one of your best.
cheers
Francis
Hi Simon.
Ignore the market and try and understand you will never get your timing right ..and be happy with any decision you make because if you do not have confidence in your own opinion , you will end up chasing your tail.
I have listened to many of the shareholder videos for Fundsmith Equity, where I have a large portion of my Sipp invested.
Terry Smith will tell you, no one can tell what the market is going to do and he just buys great companies with high ROCE.
Leave those great companies to do what they do best and use a small portion of your cash to play with small companies....here and elsewhere.
As we have seen in the last 5 or 6 weeks, prices are nuts but if you are like me , being careful....so what...you might miss some big gains but once we are back in the real post CV , what do you think our new world is going to be like?......
Personally, I am waiting with 35% cash totally convinced that post CV we will see some life changing opportunities ..we cannot spot them right now but they will come as sure as eggs are eggs....they will be the winners for our new future.
Wishing you the best
As we have already seen with many comments here over the past month or so, pretty much everyone trying to predict it has called the market wrongly.
Please see my post on the 20 March called CALLING THE BOTTOM. https://www.stockopedia.com/co...
Just saying - not everybody called it wrongly.
Please see my post on the 20 March called CALLING THE BOTTOM. https://www.stockopedia.com/co...
Just saying - not everybody called it wrongly.
What does this prove? If you have 1,000 chimpanzees throwing darts at a dartboard, one of them will hit the bullseye, eventually.
Si
Mr. Simoan
Are you calling me a monkey..... LOL
Are you calling me a monkey..... LOL
No. Why do you think my post was about you? The point I was making was that predicting future market movements is a mugs game, and the market makes monkeys of us all on a regular basis if we try. You clearly didn't read the Howard Marks memo which quoted a section from https://psmag.com/social-justice/confident-idiots-92793
"An ignorant mind is precisely not a spotless, empty vessel, but one that’s filled with the clutter of irrelevant or misleading life experiences, theories, facts, intuitions, strategies, algorithms, heuristics, metaphors, and hunches that regrettably have the look and feel of useful and accurate knowledge. This clutter is an unfortunate by-product of one of our greatest strengths as a species. We are unbridled pattern recognizers and profligate theorizers. Often, our theories are good enough to get us through the day, or at least to an age when we can procreate. But our genius for creative storytelling, combined with our inability to detect our own ignorance, can sometimes lead to situations that are embarrassing, unfortunate, or downright dangerous—especially in a technologically advanced, complex democratic society that occasionally invests mistaken popular beliefs with immense destructive power."
All the best, Si
I recommend 'Thinking Fast and Slow' by Daniel Kahneman
Essentially posits that human access quick decision making processes innate in their systems. These have a usefulness in a % of situations, but present bear traps for problem solving, or making choices etc.
Fear of loss is one of factors which affects people he argues more than making a gain.
I find this aspect of his observation to be painfully true!
Yes, I read it years ago and am aware of loss aversion although it's very difficult to fight against it. With regard to investment no-one should be using System 1 as it doesn't really seem appropriate. It's not the easiest book to read and as far as investing is concerned I think there are probably more appropriate books to read e.g. Richard Thaler - Misbehaving, Dan Ariely - Irrational series etc. Anyway, you should be asking timarr about this subject, not me :)
All the best, Si
"can someone please help me, on a day when the bank are suggesting we could be about to see the biggest recession ever, why are so many share prices flying?"
Usual suspects doing the rounds are
1. incremental jobless claims in the USA have peaked, market corrections historically bottomed 'somewhere' around this point
2. virus lessening in Europe, restrictions lifting
3. MASSIVE government stimulus, very quickly administrated
4. random talk of vaccine
5. hedge funds raised cash last month to buy dips
6. this recession is event driven, without a structural problem to solve which takes time, like sub-prime mortgages in 2009-2010, so the rebound is (should be) quicker
7. The tech Nasdaq has nearly fully recovered, but energy, airlines, financials, still dead - so the bounce has been selective - e.g. in the UK compare Boohoo (LON:BOO) with Easyjet (LON:EZJ) i.e. a high-flying on-line company versus an airline
Superdry ; Why didn't I listen to my teenage daughter 2 years ago when she said her peers/friends stopped buying this brand ?- the Japanese logo's and designs were so dated
A great short opportunity passed me by ."Only fat old men like you shop there " was her comment as she prodded my stomach as I tried in vain to model one of their lovely orange polo shirts in one of their stores full of middle aged men !?!? No sign of any of the 'kids' who previously had propelled this brand - she was right.
Sometimes the most obvious long and short opportunities are right there in front of you with the minimum of research !
Yes around the same time, a much younger friend, said to her husband when he was admiring a pair of “on sale” joggers and she said “no way, every middle aged man in Britain is wearing them (Superdry)”. I doubt I would have bought the stock as was and am v bearish on “High Street” retail but this definitely put me off.
I snuck back the next day and bought them at 50% off and I love them. I don’t wear them in public though!!
......and now after reading your post Purpleski, I've got tears rolling down my face! Superb entertainment!
I have just heard an online interview between Zeus and Mr Forrester from Vertu Motors. I found it very good watching and listening. I look forward to your comments Paul on Vertu......
I've heard this argument before, for years, with Superdry (LON:SDRY)
Just to play devil's advocate, does it matter if a brand appeals to pot-bellied middle-aged men like us? After all, we've got more money than youngsters have, so it sounds like it could be good business to me.
Although I've probably disproved my own argument by explaining in the main article how SDRY probably isn't a viable business any more LOL!
Superdry (LON:SDRY)
One thing to remember reference the naff reputation the brand has in the uk is that the uk sales are the minority of the sales the business has. in 2019 only £302 mill of £871 mill of sales is uk derived. I had reasonably high hopies that with the maroity of the sales outside the uk - they had booming wholesale a couple of years back and fast growing e-commerce side they would be fine depsite the naff brand - i am slightly perplexed how they managed to do such a bad job of the basics over the last couple of years - i suspect this stems from clueless corporate type bods thinking they could do a better job than the founder owner who as least had a decent vision - having said that they have brought the chosen one back now and his results since returning whilst not being those of a very naughty boy certainly aren't messiah like.
I agree the only Superdry outlet near me is their discount outlet and the last time I went to this village it was empty. I think ( see my previous posts on that other Uber Dog Ted Baker ) this is a brand that relied on being ‘ current’ and when the buyers are middle aged men only, death is imminent. So no USP was
Hi SaarfLondon,
I just had to have a chuckle at your post and those comments by your daughter, "Only fat old men like you shop there" and your follow-up comments. Maybe it struck a chord with me, although I don't shop in Superdry. I may resemble some of it though! I also agree with your final comment regarding long and short ometimes staring at you in the face.
On a side note, keep up the great reports Paul and Graham. Superb and inciteful reading.......
Any views on AA. results today? Nearly doubled in a month since I bought it. Others on here thought it just had too much debt.....which it has.....tempted to sell half today. This caught my eye in the RNS: " no pay rises and a suspension of our normal bonus scheme, a general hiring freeze, a 15% reduction in pay for all Board members for three months, and tight cost control across the business". I guess this will be standard. Not going to be easy for those soon looking for a job as the furlough scheme ends; especially school leavers and those with limited experience. The government has a real problem here.
What's unusual about the Filta Group (LON:FLTA) announcement (which I held until Feb when things kicked off) is that they had already published that they had started a disinfection service (I might have seen it on Twitter).
This is not new news.
I would have preferred more information on their liquidity and that of their franchisees (who I imagine are struggling right now), which as far as I can see has still not been published, despite the company stating they would do so by the end of April.
A
Best Of The Best (LON:BOTB) (I hold)
I agree with the ever increasing consensus that this looks cheap even after today's rise.
Here are my notes for any interested:
Project that forward 1 year and assuming +10% top line growth, a modest increase in OPEX, similar increases in marketing expenditure, flat COS --> should produce net profits of c £4.0m.
A +30% top line growth would equate to net profit of c£5.6m.
The current market cap @557p = £52m, so just looking 1 year out, or possibly 2 in case my assumptions are out, this certainly looks cheap for a fast growing, cash generative company with a seemingly endless customer base.
Happy holder for now.
A
Re £BOTB - I hold and am obviously happy at today's rise. But 2 points of caution:
1. At some point, the increasing 'Excess Profit' and growing scale of this business will attract some heavyweight competitor to copy its model and apply a much larger marketing budget/customer list. Is £BOTB branding/moat strong enough to defend itself. There is nothing in the software that would be hard to replicate and 'spot the ball' is a old and generic idea. There are already several small, weak competitors offering the same concept. Obviously, a big competitor could buy but as the value of the company rises the attraction of doing this vs developing in house declines and......
2. We are hostages to the owner manager and related parties(own >70% share). So far this has worked out very well but will his timings/needs always align with me? For my sins, I own French Connection (LON:FCCN) where the owner's desire to hang on even when dealing with declared interested buyers has cost me dear.
We always talk about what to buy. Is this an opportunity to sell well and recycle the money into something (larger) that could reasonably double in a couple of years if things normalise/ businesses find a way of coping with the new normal eg £Gym which I also own.
(I will probably miss out on further rises but if I am honest, I could also do with booking a win after my post Brexit consumer facing bets have tanked. Behavioural problems bedevil investing! )
Re 'moat' - I think you make a fair challenge but Best Of The Best (LON:BOTB) has quite a big selection of prizes - a competitor would need significant early capital to reach a similar level - so I think that acts as a slight barrier to competition. The only other similar competitor I've seen are more expensive with fewer prizes.
Plus the website is very user-friendly.
My bigger worry is regulatory risk, lack of expansion ambition, and how tightly controlled the shares are. But for now I am a happy holder! Every extra bit of revenue feeds almost entirely through to profit given the fairly fixed cost base.
Any chance you can comment on £COST - should have sold ages ago but what now...?
Hi Paul, appreciate your insights as usual. Any chance of casting an eye over todays updates from £AA and Hyve (LON:HYVE)?
Regards
Hi Paul - please could you cast a cynical eye over the announcement by Filta Group (LON:FLTA) that it has a disinfectant spray effective against coronavirus that lasts for 30 days! The scant detail is available here https://www.gofilta.com/services/covid-19-coronavirus-sanitizing
The key sentence appears to me to be as follows:
The FiltaShield service uses the most effective EPA registered disinfectants which are the most environmentally friendly and safe to those within the environment.
This suggests to me that this is not a proprietary formulation but uses existing disinfectants. Clearly, a clever announcement and potential to generate business from small companies desperate to get back to business but that 30-day protection claim worries me.
Yes, I also view announcements from companies trying to jump on the covid bandwagon with considerable cynicism. Still I suppose it's good business for companies, and helps pump the share price up in case they want to do a placing! That's a general point, as I haven't looked at the Filta Group (LON:FLTA) announcement yet. I'll cover it if there's time once all the other trading updates are covered.
Superdry (LON:SDRY)
I have some of this ultra runt in my portfolio , they werent going great guns pre covid and the main news today is that there is mention of looking at the dreaded finance options - so anyone inveted/investing now will likely own materilaly less of that company soon - on this basis i think its impossible to value properly until there is news ref financing - or they confirm they have sufficient funds to see them through - they were almost trending to breakeven pre covid anyway (slight exageration) so not a strong starting position. I am semi positive though on the company ignoring covid for underr £100 mill market Cap its a big brand name and they have good wholesale and international sales - most of their pre covid namkes were of their own making not haveing been as well run as companeis like Next (LON:NXT). In some respects superdy at present are akin to the numpty who bet on no penalty in the first minute of the champions league final at odds of 1/1000 - comedy farce of the highest order.
In the context of the current business disruption, the Company continues to review its financing arrangements. The Company's existing lenders (HSBC and BNPP) continue to be supportive of Superdry's current and future financial requirements and as part of this process have agreed to waive its April 2020 fixed charge covenant test. The Company continues constructive discussions with its existing lenders and with potential new financing providers as it explores the need for the necessary flexibility and additional liquidity going forward.
Paul - I hope that your wise words to come on Costain (LON:COST) also result in a prompt 20% rise as for Best Of The Best (LON:BOTB)
Best Of The Best (LON:BOTB) is rising because Finncap has raised its profit forecast by 27% today.
I just flag the news, it's not my stuff moving share prices, as they move a lot typically on results & trading updates anyway.
Ref Covid
Nice to see that Pfizer / BioNTech have started human vaccine trials in the US and Gernamy and have advised that if they hit lucky they could be up and running in a similar timeframe to the Oxford group - mention of september for emergency use a best possible outcome if ts works. I am not convinced that this vaccine has anything like the chances of working as the Oxford group - but hey ho the more the merrier in this regard (moving into real human trials) and these two companies are presumably some of the bigger hitters in this field.
Crimson Tide (LON:TIDE) Great results - any chance of taking a look please. Profitable with excellent margins
Rojo, I agree FY19 results (revs up 22%) are very strong at Crimson Tide (LON:TIDE) particularly given the insipid first half (revs up 5%). This shows that MPRO5 made good progress in H2 and the stock is justifiably marked up this morning. Given that 81% of these revenues are “recurring” then, we should be able to look forward to strong momentum in 2020. (I have a very small position.)
But I do find the company very frustrating in terms of getting information. Although we are now in May, there is as good as no commentary in the results on trading in 2020 and no mention of Covid. I think this is unacceptable. This is despite one of the company’s expanding verticals being UK rail, where passengers numbers have recently tumbled (admittedly also growing in NHS and supermarkets). True, the company did come up with a coronavirus “update” at the end of March but this mostly consisted of waffle, apart from disclosing that cash at end-March was up slightly from end-Dec.
Also, one third of this year’s profit comes from “other income” - all in H2 and, unless I have missed it, there is no explanation at all of what is this other income.
I think the MPRO5 is a potentially exciting product in an area (mobile working) which both pre and post Covid you could imagine is set for growth. Checkit (LON:CKT) is in a similar area, but I believe mostly different verticals, with a more aggressive strategy (that is prepared to run losses to fund growth), compared to Crimson Tide (LON:TIDE) which has tried to fund growth from internal cash-flow.
NOMAD change to FinnCapp from Arden in March might (or might not) be significant.
With a market cap of only £10m or so, it might well be too small for Paul to comment on.
Thanks, sounds interesting, I'll take a look if time permits. Crimson Tide (LON:TIDE) is a stock I've held in the past, seems quite a nice albeit tiny company. Very illiquid unfortunately, so I'm wary of getting stuck in things like this, as no escape route if e.g. a second wave of covid strikes.
re Crimson Tide (LON:TIDE) - as you say, these are good although I think more or less in line with their earlier guidance, even if the market doesn't seem to have priced it in.
Their earlier statement on COVID was "Crimson Tide has experienced negligible disruption to normal business patterns thus far and the Board is comfortable that, even on the basis of sensitised forecasts, the Company will remain well funded and operational for the rest of this year and beyond." Presumably the Board is under an obligation to update again if that statement has changed. As a purely software company selling largely on a SAS basis rather than one-off licenses, you would expect the short-term impact to be modest at worst. A deep recession might be another matter.
Free cash flow is still negative - down to spend on fixed assets. They haven't made clear how much of this is one-off. However, the main point of the company is that revenues need to keep growing to justify even the modest 10 million cap.
I hold.
Best Of The Best (LON:BOTB) nice to see a positive trading update, for a change. Thanks for the write-up Paul, I know you've been a long term holder. Leon Boros did flag it in his recent piworld webinar, here.
Do join the piworld Thursday webinar, 1pm today, with Keith Ashworth-Lord, CIO, The Sanford Deland Buffettology Fund, to hear his CV19 survival strategy. Or catch-up via piworld afterwards with the video or podcast (same content different format). Register for the webinar via this link.
Costain (LON:COST) announces details of placing and open offer @ 60p (close 75.1p yesterday)
Open offer 4 for 13 - 20% of new shares. Those not taking up diluted 60.6%, those taking up basic entitlement diluted 48.5%
UAE construction company ASGC taking 25%
Sorry Im new to this but can someone explain what this actually means and how this would translate to a holding of 10k shares as an example. Thanks if anyone can shed some light.
Oliver
Costain (LON:COST) are raising money today in two ways. Hopefully this table helps:
For a private shareholder with 10,000 shares, the Open Offer entitles you to buy 3,846 new shares at 60p (10,000 * 4 / 13).
The key issue for private shareholders is the size of the institutional placing, which in itself is a similar size to yesterday's total shares in issue. This dilutes the interest in the company of current shareholders.
Aahh great thanks. This investing is not so completed afterall once the jargon has been removed.
Morning Paul any chance of a ramble on Reach (LON:RCH) formally Trinity Mirror which from memory you nailed a few years back. Was a great trade from back end of last year to Feb this year then obviously obliterated along with anything non tech or biotech.
Usual stuff in the update cancelling divi, cost cutting and sits on net cash of £33 mil not off much this morning so seems a lot of the bad news factored in.
Probably to early to get involved with until signs of recovery but maybe one for the watchlist ?
As a final note incredible that things like Scottish Mortgage and Polar Cap Tech Investment Trusts near rolling 12 month highs.
Thanks
As a final note incredible that things like Scottish Mortgage and Polar Cap Tech Investment Trusts near rolling 12 month highs.
Not really - look at the performance of the underlying holdings, mainly in tech and some healthcare. Most - although not all - are insulated from the worst impacts of the crisis and many are benefiting. Across the board companies with online distribution models are reporting stable or rapidly rising earnings.
This reminds me of dotcom - only this time the promises are all coming to fruition as online companies reap the benefits of seeing competition effectively shuttered, much of it forever. The whole crisis is compressing the move to remote distribution models for both retail and home working from years into weeks.
At some point, obviously, people will get overexcited and push valuations of these companies to unsustainable highs, but it's not clear that's happened yet. Who will want to go impulse shopping in socially distanced stores surrounded by people in masks and gloves?
Even better, the types of company tend to be capital light, so ideal for coping with any rises in inflation due to monetary policy. For some it's a perfect storm, for others it's a following wind.
timarr
HI Timarr
Don't disagree with anything you say it just goes to show how important it is to try and spot the right sectors of the market to be invested in at any given time.
I think its more the fact that even with this once in a generation event that after an initial lurch down there not even off 5-10% to allow a bit of downside lee-way.
From memory Scottish Mortgage hold a lot of Tesla which is a marmite stock and I think they also hold Zoom which has had a lot of airtime over last few weeks in the press and main media.
Regards
Andy
Now where have I lately seen a capital light company with a remote distribution model?
Oh, I know... Best Of The Best (LON:BOTB) ! Today's star share!
Oh, I know... Best Of The Best (LON:BOTB) ! Today's star share!
Correct. What's odd is the market is only reacting to results and not predicting them since it's bleeding obvious. The bounce in Loopup (LON:LOOP) in the last week is head scratching, they were guaranteed to outperform. Unlike dotcom the market isn't pricing the valuations of these at extreme levels apart from the obvious stuff like Netflix and Zoom.
The world is changing very rapidly: Martin Sorrell, in the S4 Capital (LON:SFOR) update today flagged the future:
Lastly, we have already started to examine our office lease patterns in various cities and terminate and consolidate office premises where possible and faster than we originally planned. Many of our people are indicating a current preference to continue to work from home, if possible. Undoubtedly, our office footprints will change.
timarr
I couldn't agree more. Actually I am livid. Best Of The Best (LON:BOTB) was on my list to invest a few days ago, precisely because it ticked the boxes as a potential post COVID winner. Well, I'll just have to wait for a pullback to buy.
Martin Sorrell is dead right. Commuting to work will only be necessary where the work requires face-to-face communication. I am concentration on identifying companies that offer tools that will enable remote working, such as online team meetings, remote medical diagnostics, remote G.P. sessions, and so on. We had a few false dawns in the past, but I think this time, these changes will stick.
I am concentration on identifying companies that offer tools that will enable remote working, such as online team meetings, remote medical diagnostics, remote G.P. sessions, and so on. We had a few false dawns in the past, but I think this time, these changes will stick.
Some will stick, some won't but the approach is right. There's plenty of opportunity in stocks with good liquidity. I particularly like those in impacted sectors that are using the situation to support their customer base with free access to services while the crisis is ongoing. It's not entirely altrusitic of course - many will switch to paying afterwards.
Pearson (LON:PSON) (online education), Auto Trader (LON:AUTO) (car sales) or Emis (LON:EMIS) (remote VP and pharmacy sessions) are all in that mode. Or even Purplebricks (LON:PURP) - maybe their time is about to come? Or look at logistics companies - Londonmetric Property (LON:LMP) are focused on distribution assets (i.e warehouses and distribution hubs) and have just done a placing because they want to go out and buy distressed assets.
I've never seen a more bifurcated market, split between those with predictable futures and those with uncertain ones. The latter will provide the biggest gains on the upturn but you've got pick 'em right and I don't know how you do that right now.
timarr
I've never seen a more bifurcated market, split between those with predictable futures and those with uncertain ones.
I did an analysis a few weeks back of all LSE stocks that have shot up after 23/3/20, the lowest recent point of FTSE100. I filtered out the healthcare sector because it was distorting the sample. These are stocks such as NCYT, ODX, etc - more like lottery tickets.
My premise was that the leading 50 stocks would throw up the online / asset light / debt free/ cash rich companies. The result? Not at all. There was no pattern at all!
I did an analysis a few weeks back of all LSE stocks that have shot up after 23/3/20, the lowest recent point of FTSE100.
I'd look at it from Jan 1st instead. A lot of the worst impacted companies were in distressed sectors and the panic pushed their prices down to unsustainable lows - essentially pricing them as options. The recovery has seen many of those go from 90% certain to go bust to 50% (or something like that, you get the idea). So looking at the prices since 23/3 will show a distorted picture, taking it from the beginning of the year would a better baseline, I would guess. Be interesting to see what that threw up.
But anything that survives in sectors that can't be competed with online - leisure, bars, etc - will do fantastically well in a recovery. It's just picking the survivors that's the challenge - the BoE forecast today is grim.
timarr
I'd look at it from Jan 1st instead.
OK. Shouldn't take me long to do this. I'll get back.
Do that exercise on US-listed stocks and the results are dramatically different. The strong are getting stronger and instead of pulling back on spending, they are accelerating it to dominate their market. Funnily enough, they would be branded negatively by most UK stock talking heads as jam tomorrow stocks since quite a few aren't currently profitable.
I liked your post timarr.... so much that I just bought some£PSON!. Shares almost at all time low plus loads of cash post various disposals. Have been engaged with on-line learning for daughter these past few weeks so maybe online is set to have a bigger share of the education pie in future!
Fairplay, I got the tech rally to even more stretched valuations completely wrong! ... although I do remember feeling vindicated in Sept 2000 as tech rallied strongly over the summer. All my older colleagues were dumping their TMT ...alas they got the next two years very right. The situation now feels very similar.
I wonder how long it is before the Donald decides a windfall tax of the Jeff would help the US Covid response.
Scottish Mortgage Investment Trust (LON:SMT) have positions in Amazon, Netflix and Zoom (as well as Tesla) which are doing very well in the world lockdown; I hold a few, it seems a good way to get exposure to the stronger US market stocks if you don't want to do so directly.
Scottish Mortgage Investment Trust (LON:SMT) have positions in Amazon, Netflix and Zoom (as well as Tesla) which are doing very well in the world lockdown; I hold a few, it seems a good way to get exposure to the stronger US market stocks if you don't want to do so directly.
I hold Scottish Mortgage Investment Trust (LON:SMT) and their full portfolio is eyecandy for the technophile:
https://www.bailliegifford.com...
Apart from the headline names it's chock full of companies that must be doing great - Delivery Hero, HelloFresh, Slack, Shopify, Spotify, TransferWise as well as some that are presumably having a lousy time - Lyft for instance. Lot of pharma / biotech stocks too.
The whole Baillie Gifford philosophy is interesting, their Trust magazine is well worth subscribing to. I always regarded it as an interesting bit of diversification, but it's rapidly looking like it's going mainstream. Who wants bricks and mortar any more? :-)
timarr
These comments are very curiously written - sounds like a description of some rare species, not LSE's highest-cap Investment Trust, trading on a Premium twice the 3-yr average ! So what deoes Timarr think is 'going mainstream' ? - SMT ?? obviously ! - Baillie Gifford value philosophy ?? If only !!
Hi clarea,
Yes, Reach (LON:RCH) is in the article header, which means I'm hoping to write something about it later today.
Regards, Paul.
My morning smallcap tweet:
Vertu Motors (LON:VTU) Reach (LON:RCH) Superdry (LON:SDRY) Hansard Global (LON:HSD) £R4E Microsaic Systems (LON:MSYS) Origo Partners (LON:OPP) Best Of The Best (LON:BOTB) Works co uk (LON:WRKS)
Vertu Motors (VTU) sales showrooms will open when restrictions are lifted with a phased return. Adj net debt, excluding used vehicle stocking loans, £2.8m. Freehold land and buildings have a book value of £186m. Additional credit approved by banks. I hold.
Reach (RCH) Jan-Apr rev down 13% with a covid impact from mid-March. April rev down 30%. Cash at hand £58.2m of which £25m is debt.
Superdry (SDRY) Q4 rev down 37%. Online rev doubled in last 4 weeks. £39.8m net cash. Passing div.
Hansard Global (HSD) New business for Q3 up 13% but this is unlikely to be maintained in Q4. YTD up 9%. AuM down 12% in Q3.
Reach4Entertainment Enterprises (R4E) reduced cash outflow by 76% to £0.5m pcm. Running costs halved. Net cash £10.3m (excluding a deferred consideration). "This should enable the Group to continue to meet its working capital requirements whilst it explores additional funding options."
Microsaic Systems (MSYS) distribution and OEM channels have been unable to operate normally but "continues to make progress with existing and prospective partners through remote communication channels." Cost cutting has effectively offset the effects of covid on the cash runway in 2020.
Origo Partners (OPP) covid: co has been unable to conclude its strategy of disposing of the Company's remaining assets and placing the Company in liquidation.
Best Of The Best (BOTB) guides FY rev and profit ahead of current market expectations.
Theworks (WRKS) guides FY(Apr) rev up 3.5%. LFL up 0.7% up to lockdown. Online sales up 3x since lockdown driven by home schooling. Net debt £7.9m. £25m revolving credit facility. Co able to operate within its existing banking facilities in modelled scenarios. Talks with bank re forecast covenant breaches under these scenarios.