Small Cap Value Report (Thur 23 Jan 2020) - CMCX, G4M, KETL, ECSC, MTC, ANCR

Morning folks!
There's a huge quantity of updates out today.
Final list:
- CMC Markets (LON:CMCX)
- Gear4Music (LON:G4M)
- Strix (LON:KETL)
- ECSC (LON:ECSC)
- Mothercare (LON:MTC)
Timings: finished at 4.30pm.
CMC Markets (LON:CMCX)
- Share price: 160.6p (unch.)
- No. of shares: 289 million
- Market cap: £464 million
I'm experiencing some regret this morning, when I see that that the share price for CFD provider CMC has nearly doubled since I sold out of it last August.
At least CMC was only ever a tiny shareholding. I've maintained a larger position (currently 8% of the portfolio) in the lower-risk IG Group (LON:IGG), which has also been performing well - although not nearly as well as CMC, in recent months.
CMC issued a blow-out interim report in November - net revenue increased from £63 million to £85 million. Thanks to operational leverage, this translates to a big percentage increase in the bottom line!
Digging into the presentation slides for that report, we learned that the company was using technology "to make better informed hedging decisions".
It admitted that it was hedging less frequently, and I was left with a question mark hanging over whether CMC was as safe as it was before, or whether it was moving into risky territory (the sort of territory which Plus500 (LON:PLUS) inhabits).
It would be surprising if CMC has started to act irresponsibly - in their next annual report, I'd like to see a clear statement regarding how much market risk they are exposed to, i.e. what percentage of total client trades is hedged (internally or externally), and what is the percentage of residual exposure.
Update
Today's update implies that hedging costs and hedging losses continue to reduce in Q3, having already reduced dramatically in H1:
Net operating income continued to outperform expectations in Q3 2020. The strong performance was driven by higher retention of client income in comparison to H1 2020.
Also worth noting:
This resulted in higher revenue per active client despite lower client income due to the weaker market conditions throughout much of the quarter.
Checking the chart for the Volatility Index (VIX), I note that it was indeed depressed for much of the Q3 period (October - December).
Spread betting companies thrive in times of volatility - i.e. when market movements are making headlines, and lots of people are trading.
In contrast, periods such as the October to December period which we just witnessed can be challenging. Well done to CMC for outperforming expectations, despite the quietness.
Outlook is good:
Q4 2020 has started well and in conjunction with the Q3 2020 performance, the Board remains confident in the ongoing strong revenue performance for the full year, with net operating income expected to be ahead of the upper end of the current range of analyst forecasts1.
And another big well done to CMC for putting the analyst forecasts at the bottom of this RNS. All good companies should do this.
The range of forecasts for net operating income (as compiled by CMC) are £184.1 - £189.3 million.
The range of forecasts for pre-tax profit are £38.6 - £45.5 million.
My view
In my November analysis, I suggested that CMC might earn operating profit of c. £40 million this year. Instead, it looks headed for c. £48 million.
Since the official forecasts are wrong, the numbers on the StockReport will need to be updated. The true P/E multiple is in the region of 12x.
Therefore, despite doubling in price, these shares might still not be expensive - and they could have a lot more to run.
You also have to factor in the risks:
- regulators have demonstrated a strong willingness to clamp down on retail trading activity, and gambling-related activity in general (this applies to all operators, not just CMC).
- I think it's fair to wonder what exactly CMC has done to its hedging strategy, that has allowed it to dramatically reduce hedging costs and hedging losses. Internalising more risk, leaving more positions unhedged and relying on correlations between instruments (for example) could mean that the company is more vulnerable to swings in market-related P&L. This needs to be cleared up, in my view.
On balance, I am more comfortable not owning shares in CMC at present. But there's a lot to admire here. Worth keeping an eye on!
Gear4Music (LON:G4M)
- Share price: 272.23p (+12%)
- No. of shares: 21 million
- Market cap: £57 million
This online retailer of musical equipment has issued a decent update for November/December.
Obviously Christmas is a key period in the calendar, so it's good to see that it went well:
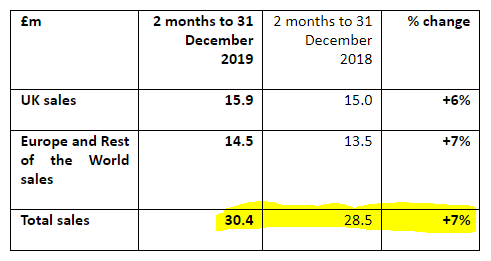
Sales is vanity, so how about profitability:
- gross margin +260bps to 26.5%
- gross profit +18%, growing from £6.8 million to £8.0 million
FY March 2020 profits to be at least in line with expectations.
There is a long CEO comment talking about how the company's infrastructure is working well, Black Friday was a big success, and the existing three distribution centres are big enough for G4M to keep growing, without needing new investments.
My view
A new sell-side research note has been published this morning (commissioned by the company). It gives an EPS forecast of 9.3p for FY March 2021. This is slightly higher than what you'll find on Stockopedia's StockReport.
Since EPS of 9.3p would still leave us with a racey P/E multiple, the market is clearly pricing in further growth in FY March 2022 and beyond. This is not unreasonable, on the basis that the company is adamant that its medium-term plans can be achieved without significant capex.
You might remember that G4M revealed a shift of emphasis in strategy last year, when it decided to prioritise profitability over market share growth.
Thanks to that shift, I do consider G4M to be much more investable than it was before. I've never been comfortable with growth for the sake of growth - I want to see good margins and a positive bottom line!
Anyway, the strategy has been executed - top line growth rates are more modest (7%), but we do get a few pennies in EPS.
And hopefully we will get continued profitable growth in FY 2021. CEO comment:
We remain confident in the medium to long term growth opportunity, whilst continuing our focus on improving gross margins and sustainable profitability.
Overall, G4M strikes me as being of medium-quality, as far as distributors go:
- It sells gear under its own brand, even if this brand would not be considered prestigious.
- Gross margins are not impressive, but have improved over the past 12 months
In the final analysis, it doesn't pass enough of my quality characteristics for me to get involved, and I do think that the current share price is quite optimistic about the company's ability to hit EPS forecasts over the next two years.
The sell-side analyst has put a price target of 450p on G4M, on the basis of its EV/Sales ratio being cheaper than ASOS (LON:ASC), Boohoo (LON:BOO) and Ocado (LON:OCDO). It's a reasonable perspective but the obvious counterarguments are that 1) these other companies might be overvalued, too; and 2) chasing sales is not a very robust investment strategy.
Strix (LON:KETL)
- Share price: 194.93p (+4%)
- No. of shares: 190 million
- Market cap: £370 million
Strix Group Plc (AIM: KETL), the AIM listed global leader in the design, manufacture and supply of kettle safety controls and other complementary water products used in temperature control, steam management and water filtration, is pleased to announce the following trading update for the year ended 31 December 2019.
It's unusual that an AIM company is a real global leader in its field.
That appears to be the case at Strix, which says that it has a 38% global share of the kettle control market. This is the power of owning valuable patents.
Full-year update
Today's update is in line with expectations.
Business is broken down between "Regulated markets" (where intellectual property is a thing), "Less regulated markets" and "China". Very diplomatic!
Key highlights of the RNS:
- market share being maintained in regulated markets
- market share also being maintained in China. KETL's Share in China is growing for "healthy eating appliances", which are replacing traditional kettles.
- the construction of new manufacturing operations in China is on schedule, and costs are in line with expectations.
Dividend for the full year is 7.7p (versus 7p last year).
My view
This continues to look like a really smart company, doing what it says it is going to do and generating plenty of cash.
And while I'm wary of M&A, I'm a big fan of what KETL did last year in the water filtration category: it bought certain assets from AIM-listed Halosource (HALO), when that company ran out of money.
It was only a small deal, but I like the opportunism of buying assets from a distressed seller, rather than rushing to pay a big premium for them. KETL confirms today that the Halosource products have been assisting in the growth of its water division.
KETL's primary water brand is Aqua Optima - you can check out related products on Amazon.
Overall, I continue to have a positive impression of this stock. I can't invest in it for the simple reason that I don't know how long until the expiry of its most valuable patents. If I was reassured on this point (i.e. that they will be around for decades to come), then I would be interested.
(PS: thanks to the Strix PR team for clearing up a misunderstanding I had about the RNS.)
ECSC (LON:ECSC)
- Share price: 120p (-9%)
- No. of shares: 9 million
- Market cap: £11 million
This provides outsourced cyber security services - here is its website. So it's a small support services company in a growing niche.
Profits have been hard to come by, but revenues are at an all-time high (£5.9 million) and the company says that it was cash-generative in H2.
CEO comment:
"We are very pleased that the record trading in H2 resulted in double digit organic annual revenue growth, and a return to adjusted EBITDA profitability. Growth in recurring revenue of over 25% shows the effectiveness of our strategy of winning consulting clients and converting them into long-term managed services clients. The acceleration of new client acquisitions in 2019 should help to build a solid foundation for future growth."
My view
I don't doubt the importance of the work done by ECSC, and the shares may be of interest to readers. Personally, I can't shake off the impression that the business must be very labour-intensive (similar to an IT managed services provider). It is therefore outside my investable universe.
Quantatively, it fails to impress Stocko on Quality or Value metrics, and is classified as a Momentum Trap.
Mothercare (LON:MTC)
- Share price: 15.5p (-7%)
- No. of shares: 171 million
- Market cap: £26 million
An interesting situation: "we remain of the view that we need no more than £25m of additional financing capacity in order to refinance our residual financial debt and future working capital requirements".
That additional £25 million could be in the form of equity or debt. The company says it wants to have "the minimum possible further dilution for shareholders", but I guess the decision is not entirely up to the company - it depends on the terms on which debt might offered.
Looking ahead, it wants to be an international franchisor, instead of the retailer it was before. Very sensible.
It's a special situation. It might turn out to be cheap at these levels, but I would want to wait until funding is resolved before doing anything with it. Until then, the risk of severe dilution can't be discounted.
Out of time for today - thanks everyone.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Thanks for the update, does raise the question re Strix (LON:KETL) as to how us mere mortals would be able to establish, through research or investigation, durations of patents etc that clearly influence intrinsic underlying value of an entity.
ps, not sure the £ticker action seems to work from my android phone...
Bit silly to finish the review of Gear4Music worrying about it chasing sales over profits when today’s update demonstrated the opposite?
Tombholliday,
I think Graham is referring to the Analyst’s valuation method which is based on sales rather than profit. He’s already acknowledged that the focus on margins is a move in the right direction.
I've not looked at ECSC (LON:ECSC) business model at all, but I don't see why this would necessarily need to be people intensive, certainly no more than any other IT outsourcer.
You buy and configure the anti-malware platform of your choice, then you set up an operations centre monitoring for signs of infection and deal with them - the anti-malware platform should do all the hard work for you. You just provide specialists to clean up anything that gets through. Modern anti-malware should block anything that looks funky at first sight (if configured properly). Employing dedicated security professionals is expensive for small organisations and local government - makes sense to pool resources.
Modern cloud based platforms let you authenticate across domains so you can have limited dashboards monitoring a lot of devices.
Disclosure: I would go into more details but I work for one of the providers and don't want to appear to be pushing our product. No position :)
Strix (LON:KETL)
If you want to look up patents the best place is the Espacenet website.
Searching for 'STRIX' https://worldwide.espacenet.co... brings up 317 entries. The most recent in August 2019 (gesture-controlled heating apparatus...I usually just shout at my kettle to get it to boil faster). All the patents can be viewed for those that feel inclined.
A patent usually lasts for 20 years from filing date.
STRIX - I looked on the IPO website for news on Patents and gave up ! The Strix website has comments re Patents, cut & paste of some follow;
Successful Patent and IP Protection
May 2018
Strix has a portfolio of intellectual property protecting a variety of product features across its product range. The portfolio includes over 150 patents and Strix relies on these and, where they have expired, other IP and unfair competition law to take legal action, both to defend the Company's commercial position and ensure consumer safety. Examples of action taken in the last six months in China and Europe include:
Mark Bartlett, Chief Executive Officer, commented:
"We take protecting our innovative technology and superior products very seriously, ensuring that customers can continue to trust and rely on products using Strix technology.
"We continually monitor appliances in the market to prevent the sale of products that do not meet international standards or that infringe our IP. We will continue to take further action, as appropriate, reinforcing our market leading brand and ensuring that consumers can benefit from safe, high quality products."
IP News
August 2016
On April 29, 2016, Strix filed an action against a U.S. based supplier of electric kettles fitted with connectors made in China and branded ‘Liang Ji’ in the United States District Court for the Central District of California. In its complaint, Strix accused the supplier of infringing one or more claims of U.S. Patent No. 5,971,810 (“’810 patent”). Strix and the supplier have resolved their respective claims and defenses with a settlement agreement, the terms of which are confidential. Under this agreement, the supplier has paid Strix a settlement fee and promised to cease sale of cordless electric water kettles through expiration of the ‘810 patent.
How long the Patents last I didn't find out but at least they pursue breaches.
Another vote for Craneware (LON:CRW) if you can Graham please
Hotel Choc was looking for the Xmas update on sales and this looks OK, Not sure the blip on supply chain is too much of an issue but at a PE of nearly 45 they cannot afford a miss of any description. I have this one at the top of my watch list so maybe tempted in soon if
the price drifts back a little on this news .Anyone else have any thoughts?
I bought into Hotel Choc before Xmas. During Xmas with family - everybody who have bought chocolates as presents had chosen HC, rather than Thorntons or M&S. The universal view was that their chocolates were delicious! Their Vetvetiser subscription service looks like it is also a real winner.
I agree about the supply issues - but they do need to sort out.
I also like their website
I'm probably in a minority (along with my close circle) in that we don't particularly like Hotel Chocolat (LON:HOTC) chocolate. The branding and packaging is outstanding, as well as some of the "added flavours", but the chocolate itself is a bit tasteless and plastic. It's still much better than modern-day Throntons or palm-oil filled Cadbury, but I would much rather someone bought be some Lindt, Godiva or M&S chocolate!
I looked at Hotel Chocolat a couple of years ago, but was put off by the level of poor reviews on Trustpilot etc, especially regarding their internet offering.
Just looked at Trustpilot again and there are plenty of v recent reviews bemoaning how poor their ordering process is - rather bizarrely, there are several replies from HC saying "We completely understand and wholeheartedly agree"! Checking, this now seems to be a fairly standard response - a little bit further back, a standard response seemed to be "I have passed this on to our web team who work very hard at making the site more user-friendly".
An e-commerce website ain't rocket science and for a company like HC the fact that they can't master this over several years make them uninvestable for me.
At some point, with a bit more global warming they might even be true to their slogan "British Cacao Grower". What would we know about growing cacao anyway? Now potatoes and oats, absolutely! Sorry but I cannot invest with such flagrant misrepresentation, even if this only fools, fools. Website OK, but agree it just needs to work.
Hi Graham, Ilika (IKA) reported today, have you got any thoughts ?
Hi apjacko,
I know nothing about battery technology, so I don't think I can add any value on IKA, sorry.
Graham
Hi Graham - thanks for the coverage of CMC Markets (LON:CMCX) . I wonder if the market is under-pricing a further beat in Q4 because of the inherent unpredictability of spread-betting income?
Avingtrans (LON:AVG) "has continued to perform well in the first half of the financial year and is trading in line with market expectations. The order and prospect pipeline remains robust.
The recent acquisitions of Booth and Energy Steel (both completed in June 2019) are responding to their Avingtrans recovery programmes well and are integrating as anticipated, with strong order books already secured and healthy prospect pipelines. With the support and guidance of the Group, these two businesses have been experiencing steadily improving performance trends, as they recuperate from previously constrained positions"
I guess the market was wanting more, as share price currently down 3.5%.
Is this something you could cover please Graham... or views anyone else?
re Avingtrans (LON:AVG), in-line results, but still encouraging. I imagine the share price fall is the combination of general market weakness, and the valuation being a bit racy for a "metal-basher". There was some discussion yesterday of Somero Enterprises Inc (LON:SOM) being cyclical, the same must go for Avingtrans (LON:AVG). I have held for some time, largely on the strength of management reputation, the acquisition of Hayward Tyler has proved well-judged, and they have continued to do what they said they would do. So I will continue to hold.
Graham
Don't have regrets about a sell decision where you took a profit. As my ex boss used to say "You'll never go broke taking a profit". Just assess whether your decision was right at the time, learn any lesson from that and move on.
Keep up the good work.
Hi Graham,
I am interested in looking into any UK small/medium cap tech companies who may be getting into the whole 5G space-any thoughts?
Mark - you could "look" at IQE (LON:IQE) . Serial disappointer but they may come good one day.
Mark - UK listed (but Israel based) small cap Ethernity Networks (LON:ENET) is involved in the 5G space. I hold.
£mte
Mti Wireless Edge (LON:MWE) say they will benefit
Good morning Paul,
Please comment on massive share price drop of Sosandar. What does management say about it?
Hi Pavel
You can always contact Sosandar yourself with any questions you may have.
My take is that management are there to execute the strategy, and Sosandar are doing what they said they would do: aggressive marketing to build a customer base. The revenue increase shows it's working as any amount of marketing would never sell tatty rags, so to speak.
I sold my position this week but hope to buy back in. With investors concerned about the possibility of another small placing then maybe they are anchoring to the 15p of the previous one.
But then what do I know?!
Jon
Pavel - you will find a large part of Monday's SCVR taken by Sosandar (LON:SOS) together with many posts discussing it.
The reason for the share price fall in Sosandar (LON:SOS) is: that's the nature of the beast. It's a tiny, loss making, cash consuming, highly speculative business, extremely dependent on 2 key personnel and issuing new shares like they're going out of fashion(!)
It's extremely rare for such a share to go up in a straight line. That's not going to happen. It will be all over the place. The only thing you can bank on is volatility. It will go up and down for no discernible reason because it's a punter's share. It's based on jam tomorrow, not profits in the here and now, so one online comment can set off a wave of buying or selling. I dont mean this rudely, but the reality with this type of share is: get comfortable with that, or get out.
Personally, I would be prepared to back Paul Scott's judgement on this one for the long term because, it's a judgement I respect. But I would recognise that it's his judgement, not mine, and his record of success is largely based on speculative, volatile shares. I suspect he has a higher risk tolerance than most people, including me.
actually on Sosandar (LON:SOS) I think it's more around liquidity. Usually about £80k worth of stock changes hands a day. Doesn't take many sellers to move the needle, or buyers for that matter. Often with smaller stocks people buy in on anticipated news flow gradually over a few weeks but sell out in a cluster for a few days after. The Market makers are the main winners out of that but the volumes are small. This is a £30m company and the selling has all been done on 5m of shares traded = £1.3m of value. so a 3% share turnover moves the value of the business by 30%. Classic illiquidity.
It's a hard stock to value as it remains loss making so it also isn't anchored anywhere. The UK market is rubbish in comparison to the US at understanding and valuing these type of fast growth, unprofitable businesses. More often its done as a price to sales. At an expect £20m revenue for the coming year a 1.5* revenue multiple. I suspect a private equity house would value at double or treble that or poss even more but therein lies the problem. Private investors in the UK want access to these big potential growth stocks BUT they want to value them on a growth/value perspective and the two don't compute! The US doesn't have that problem. A PE or VC house would invest in the business to accelerate growth as much as possible, raising funds at higher valuations. The small UK listed market runs a mile at the first sniff of that strategy. Placing = discount = reason to sell = share price fall.
Sosandar (LON:SOS) has only really put one foot wrong in its trajectory so far in my opinion and that was not raising enough at the outset and more aggressively growing subscribers........but that's in hindsight. Now they are moving ahead with that strategy, having tested the impact and seeing a direct correlation between their advertising and recruiting new but repeat customers. As a consequence Mr Mainwaring is currently busy panicking that they might decide to raise money to grow and is selling out fast. Looking at the house broker research seems to suggest that b/e on the higher spend is achieved this year and the company remains in net cash, so no placing needed. That doesn't mean there won't be one of course and that uncertainty alone causes downward pressure.
I go back to my first point : we want these companies to be listed so we can participate in their success and not just give all the gains to the PE houses but only if they can do it on a shoestring, whilst being consistently profitable and presumably tap dancing to the tune of Dads Army....................
Excellent summary on Sosandar (LON:SOS) David, spot on.
I'm heavily invested in a 7 year old tech startup that is now VC backed and has raised over £60m so far and never made a profit. The CEO is actively seeking more US investors for the simple reason that they understand the big, long-term picture far better than UK/European VC's or Angels. I do expect to exit at some point in the next 5 years but until then, I'm happy to hold and watch them grow sales at mouthwatering margins and continue to raise money at higher and higher valuations. And the good news is the CEO doesn't have speculators playing havoc with his share price. Which is the problem Sosandar (LON:SOS) currently have...
cheers
Francis
Really informative analysis David. Thank you.
Clearly this not an everyman investment - a Paul Scott investment but not a Graham Neary investment. Stocko's computers rightly dislike it because there is no history of profits or positive cashflow. So those of us who want to be in on the ground floor on a (hopefully) successful startup need to evaluate the qualitative information - the quality of the management, the quality of the product, the strategy and how well they are executing it. These are not factors which Stocko's computers can evaluate. Most loss making startups fail, losing money for investors in the process. One completely valid investment style is to ignore startups completely and focus on investing in sound businesses with a track record of profits, cashflow and good returns on equity. Or we can try to sift the gold from the chaff and buy into good management and good business models that have a decent chance of making it through to strong profitability.
We will need to watch Sosandar (LON:SOS) over a few years (not a few days) to find out if this company is going to be one of those
Thanks - yes, it is like most things, a balance. The benefit a VC or PE house has is that they will have a portfolio of unlisted companies, access to management, accounts, sales statistics and possibly a board seat. Certainly they can influence direction. Private investors do not. Even then the VC/PE does not expect every investment to pay off. They expect maybe 10% to blow the lights out, 40% to do ok, 30% to lose a bit and 20% to go bust. The 10% pays for everything else and beyond. Therefore investing in a single stock of this type for a PI is inevitably more risky as there is little by way of portfolio effect. These are not stocks in my opinion that we should lump in with our main portfolios as they don't behave the same and are not valued the same, but there can be room in a well constructed portfolio for them. The bigger problem for me is that AIM feels like the wrong place for them as everyone is persistently scared of raising money, which is ironic.
Other than list in the US I don't know what the answer is but that in this instance it is unlikely to work for a UK online retailer anyway given the demographic.
see Stockos “highly speculative” stock description. Adjust risk accordingly.
Good morning Graham
If you have time I’d appreciate your thoughts on the Craneware (LON:CRW) trading update. On the plus side there is lots of good news about catching up with a sales backlog and about sales growth returning. They are also positive about adjusted EBITDA (yuk!). The bad news is that they lost a major client. And they talk about this loss as if it had already been announced though I can’t find it in their previous RNS releases. And they are still priced as a growth stock (p/e - 45).
I stuck with them after the last profits warning but have already sold today.
Many thanks to you and Paul for your deep insights and thorough analysis
Re Craneware (LON:CRW) . the 10% growth in adjusted EBIT for H1 compares with Stocko's consensus forecasts for a 20% increase in full-year PAT. So I read this as a (minor) profit warning.
Graham.
If you have time, would appreciate your comments on the update from Craneware (LON:CRW) . I read this as a steadying of the ship with good visibility on future (improved) income.
Some big (institutional ?) sales on the back of this update and a fall in the price (c. 9%) but looking longer term I feel quite positive.
Would appreciate your thoughts.
Richard.
Hi Graham, would appreciate it if you could look at the interim results from £NCC. It's a cyber security business with £600m capitalisation. It's done quite well in the last year, focussing on improving operating margins and cash conversion. It tends to be a bit "accident prone" every few years but things seem on track at present.
Hi Graham
Hope the house purchase is going smoothly!?
Don’t normally do requests but would love to hear your views on Burberry in light of the update yesterday and the flu issue in the Far East.
I do not hold - yet!
michael.
Hi Michael, thanks for the request - I might cover Burberry (LON:BRBY) elsewhere due to its size!
Graham
Ok understood. Will keep an eye out over at Cube.
.
Would love to hear your thoughts on Medica. Only a short update today but seems positive
Medica (LON:MGP)
I am interested in a little firm called Avacta, which has discovered an alternative to antibodies in research. They have been on the go since the CEO took the initial research out of Leeds University. To date like all these small companies burnt a lot of money but announcement today suggests may be making progress. Signed some good research contracts with major pharma companies which they seem happy to pay for. Clear there are cash issues. They had a raising last year and limited by share price. So I don't know really interested in your thoughts Graham and anyone else who has a view. Could be a big winner but could just run out of cash (although the institutions seem supportive) so could just need another raising early 2021.
Hi Graham
£g4m brief update suggests that planned changes are working. Be keen to hear your thoughts if you have time. I hold.
Hi Jon, yes I plan to take a look at G4M as it's one we regularly cover. G
£G4M - looking forward to your thoughts Graham as I hold.
Finally some apparently good news but having been disappointed before am I reading too much into the fact they've chosen to update only on what must be their two busiest months (Black Friday, Cyber Monday and Christmas)?
Why not an update for the three months to December 31st? The Interims covered the period to September 30th - could including the October numbers have affected the overall picture quite so much?
Hi Laughton, G4M is covered now. Looking forward to your feedback! G
Thanks for your Gear4music Holdings (LON:G4M) analysis Graham, very useful.
Strix (LON:KETL)
Always thought this was a nice earning business but couldn't figure out when key patents will expire.
Closest I got was this one, which expires 2022. "Thermally sensitive control for a liquid heating vessel"
https://patents.google.com/patent/EP1233649A1/pt
They have many patents, their web site states over 150. I don't know what the true patent cover is. Difficult for me to invest without knowing the runway on this.
Strix (LON:KETL) answered the question about patent expiry in the results video they released with last year's results. They protect IP even when patents expire,
using copyright and (in the regulated market) safety testing of devices
that don't use their controls and liaison with local regulators. I was reassured and impressed (and invested).
Re £STRIX Just a note to say that copyright does not protect the same things that patents do! Patents protect technical inventions (like kettle controls) and don't require the owner to prove that the invention was copied when enforcing.
Copyright (as far as it is relevant to Strix) only protects literary works (which includes source code) and design documents, but requires proof of copying. Different regimes in different countries, but currently in the UK, even if you could prove copying, making a controller to a copyrighted design document would not be an infringement of the copyright in the design document.
That is not to say that Strix's copyright can't be useful, but it's certainly not as valuable as their patents. However, Strix are regularly releasing new products and maintain a sizeable patent portfolio. The risk of a "key" patent expiring is real, but with continuing innovation and a PE of 12, it's not my main concern.
(I hold).
My morning tweet: 18 smallcaps. Smartspace falls on its face.
Smartspace Software (LON:SMRT) £G4M Avacta (LON:AVCT) accesso Technology (LON:ACSO) CMC Markets (LON:CMCX) Gfinity (LON:GFIN) Hotel Chocolat (LON:HOTC) Ilika (LON:IKA) React (LON:REAT) Mothercare (LON:MTC) CPL Resources (LON:CPS), Jtc (LON:JTC), Strix (LON:KETL), ECSC (LON:ECSC), Avingtrans (LON:AVG), Animalcare (LON:ANCR), Epwin (LON:EPWN)
Smartspace Software (SMRT) warns FY rev flat "with an equivalent impact of this revenue shortfall on EBITDA." Blames a supplier being late delivering key product so co unable to conclude negotiations on a number of material enterprise prospects. I hold.
Gear4music (G4M) guides last 2 months rev up 7%, FY profit at least in line with Board expectations. I hold.
Avacta Group (AVCT) sees FY rev and cash ahead of market expectations. Profit?
Accesso Technology (ACSO) no acceptable offers for co. Sees FY rev at or marginally below lower end of previous guidance ($117-118m). Adj EBITDA at least $27m. Reviewing goodwill and intangibles. CEO scarpers, replaced with original accesso CEO. I hold.
CMC Markets (CMCX) guides FY net op income above the top of analyst forecasts of £184.1m to £189.3m. Pretax F/C £38.6m to £45.5m.
Gfinity (GFIN) H1 rev down 20%, only broadly in line with management's expectations due to primarily due to the transition away from low margin Elite Series. Co will "not to progress a material opportunity for a new contract with a customer... [to] enable Gfinity to pursue the strong pipeline of new opportunities which the Board firmly believes will yield stronger company benefits for the financial year 2021 and beyond." So guides FY rev broadly in line with FY19 but with significantly improved margins compared with current market expectations.
Hotel Chocolat (HOTC) guides recent rev in line but costs modestly higher due to inefficiencies in the supply chain which are being addressed in 2020.
Ilika (IKA) H1 rev up 50% to £1.5m, EPS -1 (-1). Anodyne commentary. Still surviving on grants.
React Group (REAT) wins £0.5m 'material' contracct
Mothercare (MTC) Transformation Plan Update: despite poor return from Mothercare UK administration the co's financing requirements are well within the overall guidance set out on 5 November. Remains of the view that co needs no more than £25m of additional financing. CEO steps down but remains an exec.
CPL Resources (CPS) H1 rev up 5%, gudes FY profit ahead of market expectations.
In line: Jtc (LON:JTC) Strix (LON:KETL) ECSC (LON:ECSC) Avingtrans (LON:AVG) Animalcare (LON:ANCR) Epwin (LON:EPWN)
Mr Contrarian - you are really knocking the lights out with these morning updates. I'm sure it's not just me that find these summaries really useful. Thanks very much!
Thanks very much.
Hi Graham
Please could you look at the Q3 TU from £CMCX? Although net operating income is ahead of expectations, I don't quite understand the following comment:
This resulted in higher revenue per active client despite lower client income due to the weaker market conditions throughout much of the quarter.
It seems to be saying that while Q3 income was ahead of expectations it was still behind Q3 2019. Is that your interpretation?
Thanks
Mark
Strix (LON:KETL) seems to be simmering along nicely on all fronts with its pre close trading update today...