Small Cap Value Report (Thur 29 Aug 2019) - CHH, GYM, WTG, Brickability, DUKE, MCLS

Good morning,
We have a few new updates worth discussing today, and I'm also interested to look at yesterday's backlog if there's a chance.
- Churchill China (LON:CHH)
- GYM (LON:GYM)
- Watchstone (LON:WTG)
- Brickability Group
- Duke Royalty (LON:DUKE)
- McColl's Retail (LON:MCLS)
As a reminder, the backlog from yesterday includes Loungers (LON:LGRS), Headlam (LON:HEAD), Wey Education (LON:WEY) and Proactis Holdings (LON:PHD).
Churchill China (LON:CHH)
- Share price: 1610p (+1.6%)
- No. of shares: 11 million
- Market cap: £177 million
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce its interim results for the six months ended 30 June 2019.
I have read through this entire thing and can't find anything particularly controversial in it.
This reflects well on a company which has grown over the years and hasn't really put a foot wrong. It's the good companies which also tend to be the most "boring", on a superficial level, because they just keep on pumping out solid results!
Note the strong like-for-like growth rate of 25% in operating profit, before taking into account the effects of a small acquisition.
The increased stake in Furlong Mills bumps up Churchill's growth rate to 30%.
Note also the very clean accounting: H1 PBT before exceptional items is £4.2 million, while H1 PBT after exceptional items is £4.3 million! The company made an exceptional gain of £0.1 million during its acquisition.
Last year, there were no exceptional items in H1 at all.
Strategically, the company says it has exited activities where it did not have a competitive advantage over the past five years. Despite this, revenues have grown every year. The latest H1 period continues the trend with 10% growth on an underlying basis (my own calculations, excluding the acquisition).
One thing I would bring your attention to is the higher level of cash that left the business in H1, as Churchill expanded manufacturing capacity and bought the Dudson brand. The good news is that these projects are likely to spur future growth, and the overall investment spend in H1 (£3.2 million) is affordable compared to the company's likely annual cash generation.
Outlook
Trading is in line with expectations:
We have reported a strong performance in first half year and once again this has been achieved as a result of long term investment in line with our strategic targets. We have continued to benefit from growth in export revenues and have increased our margins as a result of the sale of further added value products. Our market position remains strong and we believe we have further opportunity, both organically and from our recent acquisitions, to continue to make further progress.
Note the reference to export revenues. This company is tied to Europe and so it has made significant Brexit preparations:
In February 2019 we began to supply orders to Europe from inventory established in a third party run warehouse in Rotterdam. We now hold over £0.5m of inventory in Europe and plan to increase this in the second half of 2019.
The company says it has made "sensible plans to mitigate the effect of disruption on our business where possible".
My view
At the great risk of repeating myself, I maintain a positive view of this business and regret that I don't yet own any of it. However, the shareholder base (including the Roper family) has held firm and the stock has never really gone on sale. December 2018 was the sweet spot in terms of a recent entry point.
This remains on my watchlist, as it does for many of my peers, who would be interested to get it at lower levels.
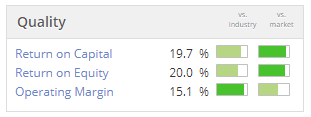
Check the high quality metrics:
GYM (LON:GYM)
- Share price: 244.5p (+2.5%)
- No. of shares: 138 million
- Market cap: £338 million
This is a rollout that I've been monitoring for some time.
We already knew that these results were going to be nice, thanks to the trading update in July.
Adjusted PBT increases to £7.1 million for the period. The adjustments include £600k of amortisation and £900k of impairments associated with shutting down an underperforming store.
Reading the small print
I've looked up last year's annual report to remind myself what is being amortised, and I think the main item is acquired customer lists, which are assumed to decay over a three-year period.
I'm relaxed about adding this back in as a £600k adjustment, but I would be a bit more cautious of the £900k impairment.
The reason is that shutting down underperforming sites might be needed from time to time, on an ongoing basis. For example, two more sites are earmarked for closure before the end of the year. Even though the company doesn't predict any more closures for the foreseeable future, I wouldn't rule them out.
This type of thing also happens with pub and restaurant shares, where in my experience the adjustments can be a lot worse! Investors are asked to focus on the profits at the good sites, while ignoring the expenses associated with shutting down the bad ones.
Anyway, the profit adjustments at GYM are nothing out of the ordinary but I would personally reduce the £7.1 million PBT figure down to £6.2 million, to include the cost of impairing the site which didn't work out.
Second-half weighting
Important to note that the roll-out is weighted toward the end of the current year. 8 new sites were opened in H1, versus full-year guidance of 15-20.
I think there is a risk the company will wind up at the lower end of its guidance, if a few of the new sites fail to open on time.
Another way of looking at it is that people are most interested to join a gym around the New Year, so the company will be strategically opening stores during the season when it is easiest to make sales!
Outlook
Trading in H2 is in line with expectations and the company confirms its view that it is on track to achieve plans for the full year.
My view
I still consider myself a fan of this company and share. It is forecast to make nearly 14p in EPS next year, followed by 15.5p in 2021.
Worthy of a place on our watchlists, in my view.
Watchstone (LON:WTG)
- Share price: 73p (+3%)
- No. of shares: 46 million
- Market cap: £34 million
Counterclaim against Slater & Gordon (UK)
The famous deal between Quindell (now called "Watchstone") and the Australian law firm S&G continues to attract controversy.
It's primarily of historical interest, so perhaps we shouldn't dwell on it. But I was short Quindell around the time of the deal, which ruined S&G and which I believe prevented Quindell from going bust. So it will be fun to see what the courts eventually make of it.
Today, Watchstone announces that it wants £63 million from S&G's UK business to remedy "breach of confidence, inducing breach of contract, and unlawful means conspiracy".
Watchstone claims that S&G's investment bank obtained confidential information from PwC, enabling it to pay less for Quindell's assets than it would otherwise have had to.
The context for this is a £637 million claim by S&G, against Watchstone, for breach of warranty and/or fraudulent misrepresentation.
My view - I don't know if this case has any merit, so there is no point in speculating. I have little sympathy for either party: Watchstone should have gone bust, and S&G should not have paid hundreds of millions of pounds for businesses that were virtually worthless, and which many observers from the outside could see were probably worthless!
As for the value of Watchstone (LON:WTG) today, I doubt that it is worth much more than the current market cap.
The residual operating businesses look like junk (heavy losses at an underlying EBITDA level last year), so the only attractions are the £50 million cash balance and the lawsuit against Rob Terry.
I'd only be interested in this one at a huge discount to the cash balance.
Brickability Group (BRCK)
The City isn't happy right now about the lack of IPO activity. Brokers and advisors are competing for very limited amounts of new business.
Here is something new: Brickability Group.
Its specialities are:
- Bricks & Building Materials
- Roofing
- Heating, Plumbing & Joinery
Company description:
The Brickability Group plc consists of 19 companies, all of which are able to bring together specialist products and services to meet the needs of the greatbuilding and construction market. ...by coming together they will be able to grow sales in new areas and winning new customers by utilising the wonderful contacts earned by the group over the years.
The market cap is £150 million at the Placing Price, putting it firmly in small-cap territory.
Cenkos Securities (LON:CNKS) is the Nomad/Broker - maybe this deal will give it a boost?
My view
This is a medium-sized business, with 25 sites and 225 employees, according to the Admission Document.
Operating profit came in at £14 million in FY March 2019. Leverage looks a bit high on the historic balance sheets, but the company says the £54 million in IPO proceeds will be used to deleverage - sounds good.
This might be worth investigating further.
Duke Royalty (LON:DUKE)
- Share price: 47.45p (-0.3%)
- No. of shares: 200 million
- Market cap: £95 million
Follow-on contribution and restructuring
(Please note that I do not have a position in DUKE.)
This RNS concerns one of Duke's smaller investments.
You might think, therefore, that it should not have triggered me to exit this company. Yet it has.
Last time I covered DUKE, I summarised my thoughts as follows:
"An adventurous financial stock carrying significant risks, but I'm optimistic about this one."
Unfortunately, it has now strayed too far into risky territory for my liking. Even if the size of this deal is small relative to the size of the entire portfolio, the sum total of the risks is now too great for me.
It's difficult to put my calculations into words. Let me put it this way.
1. Duke has restructured a deal from its Capital Step acquisition, suggesting that the initial structure of the deal was not secure enough.
The Capital Step deals did look a bit riskier, compared to Duke's model. While I can see the rationale for the Capital Step deal, to accelerate diversification, I am always biased in favour of organic development rather than "buy-and-fix"-type acquisitions.
2. The investee mentioned today is going to use the follow-on investment from Duke to build a restaurant and entertainment venue in Dublin. While I love going to restaurants in Dublin, lending to them is not an activity which I want to be involved in.
3. The investee mentioned today has recently restructured its debt. While I don't doubt that the investee is currently on a sound financial footing, I am not convinced about its financial track record.
4. A transaction some years ago valued the main operating business mentioned today at £5.1 million. The size of Duke's investment in its parent is €2.75 million. How much equity value can be left?
5. The cash yield for this deal is 18%. As with other deals, the high yield makes me question how much the equity can be worth.
6. Some other investees since mid-2018 make me uneasy, e.g. an Irish recruitment company. The original investees looked risky too, e.g. a Dutch river cruise operator.
7. As mentioned previously, I have been uneasy about the recent development which saw Duke taking equity stakes in its investees, even if Duke considers them to be a "sweetener" that aren't explicitly paid for by Duke.
Putting it all together, there are two main reasons for me to exit my position in this company.
Firstly, the likely risks associated with Duke's deals and the quality of the investees haven't matched up with my original expectations. I could be proven totally wrong on this front - no investee has defaulted yet.
Secondly (and this is not Duke's fault), due to my tax situation, I have no tax relief on dividends. Therefore, rather than paying high marginal rates on Duke's 7% yield, I am better off owning something which doesn't pay a dividend.
There has always been a conflict between my tax situation and Duke's policy of paying large dividends (in accordance with the wishes of its institutional shareholder base). Rather than sticking around in a situation which is less-than-ideal, I prefer to make a clean exit.
McColl's Retail (LON:MCLS)
- Share price: 45.75p (-5.5%)
- No. of shares: 115 million
- Market cap: £53 million
A poor update from this chain of convenience stores, with like-for-like sales down 2.2% and total revenue down 3.6%.
I was discussing this with an investor friend today, who sees a lot of value in the shares. He sees scope for the company's operating margin to improve (from the current 1%) which would make these shares very cheap at current levels.
However, I think these shares are cheap for the right reason. The risks are clear - it's a highly leveraged, low-margin retailer that is currently in reverse gear. It could work out, but it's obviously in a high-risk category of business. Suitable only for brave value hunters and those who think the brand has some value.
Stocko rates it as a Value Trap, which sounds about right.
Apologies for the slow production of today's report - many other tasks getting in the way. Will try harder tomorrow to stay on track!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
DUKE - actually I think the RNS was positive.
Duke has restructured its investment, which now totals £2.75 million, by moving the entire Royalty Agreement from the Pearl & Dean Group, a UK and Irish cinema advertising business, to its parent company, Step Investments Limited ("SIL"). So increases the security of the investment.
The £2.75M is a small part of the £50M+ in the DUKE portfolio, so a small partner.
Incidentally, was in Dublin last week and it is a vibrant place...lots of restaurants of course but lots of full restaurants.
Looking forward to the results which DUKE advised in recent TU: "will show a significant uplift in the financial results over the prior year, with revenue and cashflow from operations in line with market expectations"
Not convinced shifting an agreement to a parent increases security. Parent gets into difficulties, sells the successful subsidiary as its most marketable asset and security is reduced. Everything depends on the terms of the agreement. I have no knowledge of Duke or this agreement, simply commenting on a general principle.
£DUKE, the restaurant in Dublin has pretty good reviews on facebook and trip advisor. The website for it is horrific though.
I note that on 14th August P&D were being congratulated in an RNS by the company, with no mention of the RESTRUCTURING that had been completed in July. I am even more certain that the restructuring was forced on £DUKE.
I wonder if the terms of the existing agreement contained terms that stopped P&D from refinancing elsewhere and that it was cheaper (!) for them to pay the 18%, after all the whole point of a restructure is to consolidate debts and the ongoing servicing fees.
Would be interested to hear your views on McColl's - the share price has been really weak recently, following a heartening run up earlier in 2019 - so where next? As a recovery stock in an unloved sector, I get the feeling shareholders will have to wait many years to see a decent return - is that your view? The failure of Palmer & Harvey holed McColl's below the waterline, so even the acquisition of circa 300 Coop convenience stores hasn't moved the needle.
MCLS - not a business I know a great deal about but as a convenience store I would expect its customers to be less price sensitive (preferring the convenience for odd items) than mainstream supermarkets. It will have a high depreciation charge and hence, probably, reasonably strong cash flow. It pays a whopping dividend – 8% – so, provided the dividend is not at risk, it ought to give a reasonable long-term return from here.Pity the poor souls who bought at 300p however!
Paul,
Did the MACF report ever get written?
Empresaria (LON:EMR) reported H1 19 results last week. Here's a presentation given to investors, last week, by the new CEO & the CFO. (40 mins).
This gives a sense of the new CEO, and her strategy, with a focus on sales and costs. The CFO gives a comprehensive picture on the financials.
(If you want something shorter, the piece to camera which went out with results is here.)
Duke Royalty (LON:DUKE)
In today's RNS I noted that there had been small increases in the investments of Temarca and Trimite without an associated RNS. Having contacted the company and obtained a speedy reply it was explained that because Duke investors were never told about the original deals regarding the Capital Step portfolio companies they issued today's RNS even though it was a small investment increase. (Capital Step was bought out by Duke a few months ago)
For deals prior to the Capital Step portfolio there was full disclosure at the time of investment, and no requirement to issue RNS's for small additional investments in those companies (i.e. Temarca and Trimite)
Looking at Companies House information for Pearl and Dean the last financials (https://beta.companieshouse.gov.uk/company/00614063/filing-history/MzIyNTczMTUwNGFkaXF6a2N4/document?format=pdf&download=0) were filed for year ending December 2017. The company does not look healthy at all to me.
Saw a nice Twitter message regarding Duke today "Hi Duke, we can’t pay”
#Duke - “No prob, we’ll restructure the deal, get some better security and you can waste some more money on an investment in the booming restaurant industry”
P&D - “great, the finance industry are relocating to Ireland, we’ll open it there.”
Overall its a reminder that Duke Investments can carry an awful lot of risk and interest payments reflect that..18%
With Duke Royalty (LON:DUKE), a key consideration is the quality of the security held. In the P&D case it is fixed and floating charge against the holding company (as I read it). Clearly it has tangible assets and one hopes that Duke Royalty (LON:DUKE) is savvy about the group cross
guarantees. It is held as the senior debt.
As far as the 18% rate is concerned, this does clearly reflect usual interest risk but it also reflects the quasi equity risk in these (potentially) very long term loans but without the recipient incurring equity dilution, either current or future.
Whether targeting the hospitality industry at this stage in the cycle is wise position to take is open to discussion !
Long Duke Royalty (LON:DUKE)
Duke Royalty (LON:DUKE) - borrowing money in any shape or form where it costs me 18% is alien to me. Surely if the borrowers are sound and they have any sort of security they could borrow at a fraction of that rate.
Well said. If it looks too good to be true, then it usually is. These kind of rates shout 'distressed borrower' to me and I wouldn't want a company owning a portfolio of these heading in to an economic downturn.
Big fan of the GYM (LON:GYM), although I am hoping a better price comes. Will be interested to see how their smaller format performs. 5000 sqft sounds pretty small for a gym. I don't know if this area is the whole unit or just the area set aside for the gym, as I'd imagine changing rooms and communal areas might make up 2000sqft of that.
But I do suppose an advantage with this type of gym is that staffing costs could be real low, perhaps only one or two members of staff on duty and a cleaner. With monitoring centralised this is a big advantage over small independent gyms.
One thing I wanted to query is the capitalisation of IT costs which are fairly material to profit: £3.5-4.0m this year. As the segment matures I think the driver of innovation is going to be technology-based. For instance, the means exist for a member to know how many users are currently in a gym at this moment (because of the keypad entry).
I would expect large spends most years as new features become available.
Nevertheless this kind of figure sounds quite high to me and it builds up the intangibles balance. I do think that if we do get maturity in this segment then a third-party may offer a better solution for the back-end.
McColls strikes me as being in structural decline and with an unsupportable level of debt. Any strong views out there?
McColl's Retail (LON:MCLS)
"McColls strikes me as being in structural decline and with an unsupportable level of debt. Any strong views out there?"
I would tend to agree with you Jaknife but there are others who post here who are positive about this companies prospects. The main problem i would have other than general trading is the very poor balance sheet that is loaded up with loads of liabilities that need paying - in any sort of cash crunch or reduction in trade activity and i fail to see how shareholders would come out with a penny. Why invest here when other similar companies at least have some positive NTAV as a backup plan.
I am guessing holders are well aware of the shareholder wipeout possibility - presumably on the flip side if they could get profits back up to 15-20 mill a yearish and up the dividend then things would probably be much rosier shareprice wise at that level - so potential 100% upside as well as 100% downside too - i deffo don't like the risk reward here though personally.
McColl's Retail (LON:MCLS)
I'm not sure about your use of the plural, but to mis-quote the late Derek Jameson; "do you mean me? You surely do!"
Personally I am actually quite pleased with today's update , as it vindicates my decision not to buy when we last looked at this in February . It was frustrating to see the share-price rise by 40% in the following month, but I put that down to premature hope of a takeover by WM Morrison Supermarkets (LON:MRW) . With the share-price now c. 15% below the level in February that looks a decent call, although it was emotionally challenging to retain the view that that was not "the turn". (it would have been nice to ride that wave, but I have no allusions that I am a good trader)
The fact that the share price has scarcely moved today, suggests that the market was wise to the likely poor performance (there were plenty of clues in the industry data, Kantar for example.)
I think we are all quite jaded about companies "blaming the weather" but it seems to me that there is a significant "beer & barbies" effect that treats supermarkets, and particularly convenience, when the sun shines. I think investors in this sector would do well to assume indifferent weather and treat sunshine as a bonus, if supermarkets etc. could produce a view of underlying poor weather performance that would be great.
Whilst I do accept that the weak balance sheet and high level of debt are significant risks I cannot really see any evidence for Jaknife's view that they are in "structural decline", neither given the impressive cash-flow do I consider the level of debt to be unacceptable - I think it would take a "black swan" far worse than they suffered last year to cause any crisis.
I note that the company "anticipate results in line with expectations for the full year." I find that easier to believe than the statement by Fulham Shore yesterday. To achieve flat revenues from a position of -1.2% YTD Q3 and -3.6% in Q3 is challenging, but even if they miss slightly on revenues I suspect they can achieve the profit number.
I am still sitting on the sidelines for now as I think there is every chance that poor sentiment will weigh down the share price in the near term, however I remain of the view that I am likely to be a buyer in the not too distant future. The Q4/FY trading update around the beginning of December, would probably be my next decision point, barring anything dramatic in the meantime.
The market cap of a FTSE company (expressed in any non-sterling currency) changes with the exchange rate of that currency against sterling - but the real worth of the company is only affected slowly by exchange rate movements. That's one reason why UK companies look cheap to overseas buyers today.
I have just done a rough calculation to see the performance of the FTSE in Euro terms over the past few years.
At the end of April 2015, the FTSE stood at 6946 and the pound was at 1 .388 Euros. Today the FTSE is at 7185 and the pound in 1.1 Euros.
7185 * 1.1 / 1.388 = 5696, which might be a usefully different way to think about the "bull market" and the relative performance of UK and EU equities.
FREng
I think it was in The Times yesterday that said much of the supposed attraction of UK stocks based on currency movements was less true than the undervalue of earnings in particular stocks i.e that they represented to some extent a 'bargain' opportunity when bidders approach.
To apply this rather than a currency model, for the FTSE would seem to require the overall P/E ratio to be a more important factor.
Not saying I have a view, just thought it was another dimension to add.
Re £GYM - Personally, I think it will be surprisingly resilient in any downturn. Ave rev is only £15/month . Those going to gyms care about their health/looks and this is a long term thing they will want to protect.
Relatively, it is also a CHEAP trip out the home: even if you only visit 1 time/wk this is still only £4/activity - compare that cost to a meal out (£15/hd) cinema (£5-7/hd), coffee +bun ( £4).
A recession WILL really hurt/shake out weaker mid-price independents and smaller chains (plus maybe publically funded ones), especially those requiring a full year's fee paid upfront vs a monthly subscription model. You easily can drop the pool & sauna if cash is tight and trade down. Low cost cost gyms will thus gain market share, offsetting any loss in market size.
GYM has a leading brand, scale is benefitting from LT trends in society on both the demand side (investment in wellbeing, older people doing gyms) and supply side (fall in cost of leases, low borrowing costs at time of rapid expansion).
I hold and will buy more on any Brexit induced spike down with a 3-5 year horizon.
M&S is about to be relegated out of the FTSE 100, doesnt really need discussing, I just though it was interesting and a sign of the times. I bet most of you have owned it at one time or another
I saw that Costco had to shut their Shanghai store early on the opening day due to overcrowding. It reminds me of the famous quote by one of the Costco founders when Jeff Bezos asked for advice in the early days of Amazon.
“There are two types of retailers, those that spend their time figuring out how to charge their customers more, and those that spend their time working out how to charge their customers less.”
I would put M&S in a third category - they spend their time figuring out how to charge their customers more for less. Which puts them on the wrong side of history.
Any chance of a circle back over Headlam (LON:HEAD) Graham, looks ex growth but maybe a decent income stock and balance sheet appears bullet proof possibly one to start accumulating on any big down days.
Hello Graham. GYM (LON:GYM) may be an interesting one to look at today. Interims show expansion is continuing on track based on roll out of new sites and acquisition of two competitors. The question in some ways is, when the expansion slows and capex and expansion costs moderate and the estate matures will this turn out to be a highly profitable business or just mediocre? I think it is a good time for this type of business to be expanding as they should be able to acquire new sites at good prices as retailers and restaurants go bust. On the other hand, gym membership is discretionary expenditure that people may cut back on if there is a recession.
I hold.
Hi both Grahams
I was just taking a look at GYM (LON:GYM) myself.
I remain a huge fan of the concept and overall the results look good. The #1 thing that puts me off investing right now is the debt which continues to increase. The company drew down an additional £2m from its £60m facility, of which it has now drawn down £50m.
I understand the reasons for the draw down but it won't be possible to continue its current expansion pace and bring debt down quickly at the same time, which is the scenario I would be hoping for.
As an aside I am also slightly put off by the 3 site closures mentioned in today's report. The group says that they don't anticipate any more, but then of course they would say that. It would also explain the odd fact that End of Year members (796k) was lower than Average members (797k).
No position for now, but a keen observer.
A
My daughter joined one of the London gyms temporarily, she was impressed with it and suited her shift work - GYM (LON:GYM)
Impressive how the Company makes a profit on a net membership fee under £12 per month (on roughly 760K members used average). Must be a tight run ship.
Up sell looks seems low at roughly £1-£4 per member per month (depending if you use historic or forecast) on top (which seems very low). Presumably the gym crew are supplementing income with PT to make up wages and the gym is taking a cut, which keeps wages in a manageable range and crew if they are making enough.
At some point saturation point on population density to gym will be hit, though doesn't mean it wont sit with steady profits for a while, looks interesting, PE is a little high for me though.
Hi Abtan,
With regards the three site closures, I took a different view. I saw it as strong management prepared to make tough decisions to ensure the portfolio of sites is strong and profitable.
Long term holder.
Andy
Hi abtan, good points on GYM (LON:GYM). I've also been weighing up the site closures. No position but this is worth keeping an eye on IMHO. G
My morning smallcap tweet:
PZ Cussons (LON:PZC), Frontier Smart Technologies (LON:FST), Watchstone (LON:WTG)
PZ Cussons (PZC) sells Greek ops Minerva for £41m, 12.4x EBITDA. Will cut group pretax but 1.8m. Also sells Polish personal care brand, Luksja. No figure for that one. Why? Cap £881m.
Frontier Smart Technologies (FST) Science Group has now re-started discussions with Frontier to effect a statutory merger. Science Group has 70% of Frontier.
Watchstone Group (WTG) files counter-claim against Slater & Gordon. Usual court battle knockabout stuff.