Small Cap Value Report (Thur 9 August 2018) - ARB, EKT, CARD, AA.

Good morning!
We are expecting news in the next day or so from House of Fraser, where Sky News reports that PwC has been negotiating on behalf of its lenders and bondholders, trying to arrange a buyout.
In the absence of a deal, the company is likely to fall into administration and threaten 17,500 jobs. A reminder of how tough things are out there!
Talk soon
Graham
Today I have been looking at:
- Argo Blockchain (LON:ARB) - agreement to expand mining capacity
- Elektron Technology (LON:EKT) - trading statement
- Card Factory (LON:CARD) - trading statement
- AA (LON:AA.) - trading update
Argo Blockchain (LON:ARB)
- Share price: 12p (+1%)
- No. of shares: 294 million
- Market cap: £35 million
Agreement to Expand Mining Capacity
This report normally talks about "good" companies but I feel compelled to mention this £25 million IPO, another symptom of the mass mis-allocation of capital associated with cryptocurrency.
It's shocking to me that some blue-chip institutions were coaxed into backing it.
Let's suppose this was a venture designed to mine a few altcoins (non-bitcoin cryptos). That would be risky enough.
Firstly, crypto miners have to compete with other miners, all of the time. Most of the biggest mining pools are in China, where hardware and electricity are extremely cheap. Every coin they mine is a coin not available to any other miner.
Argo today announces that it has secured energy at 3 US cents per kilo-watt hour, which is at least a good start.
Secondly, you have to accept wildly fluctuating crypto prices. The same as a physical gold mine, your asset will become unprofitable as soon as the market price drops below the cost to mine.
So right off the bat we have a leveraged play on the price of cryptos and on our ability to assemble enough cheap hardware and electricity. It's far riskier than simply buying a few altcoins and hoping for the best.
But even that proposition wasn't risky enough for Argo Blockchain. It has gone one step further and created the new concept of "Mining as a Service", invoking the bubble hysteria associated with today's NASDAQ market and Software-as-a-Service.
The idea is that Argo Blockchain, for a fee, will mine these altcoins on behalf of amateurs who want to get involved in crypto, rather than mining the coins on its own behalf.
So we have another layer of complexity and risk. To make money, Argo will have to find a sufficient quantity of amateurs who want to hire its mining equipment, in order to cover the costs of assembling this equipment and make a profit.
Which makes more sense:
1) to own a gold mine and to mine it for yourself, if it is profitable; or
2) to own a gold mine and to offer amateur investors the chance to own pieces of gold, if they pay you a fee to extract it?
Argo Blockchain is choosing the latter route.
As for the alt coins themselves, Argo offers investors a choice of four: Ethereum, Ethereum Classic, Bitcoin Gold and Zcash.
None of these are doing especially well right now. Bitcoin Gold in particular looks like it is headed for the garbage heap of history.
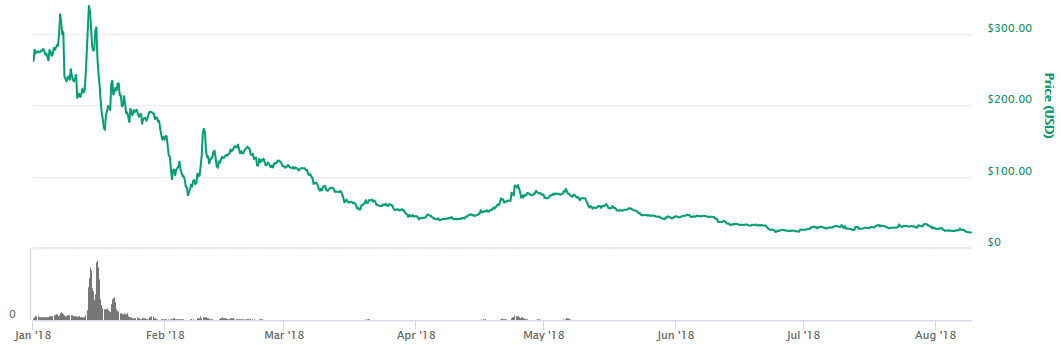
There are already hundreds of dead alt-coins, who failed to achieve mass adoption and can barely even be given away now, making Charlie Munger's description of crypto coins as "turds" look pretty accurate.
I assume that very few people have gambled a significant portion of their life savings on this stock. If there are any, I think it's fair to ask them: aren't there more entertaining ways to risk going broke than this?
Elektron Technology (LON:EKT)
- Share price: 44p (+6.5%)
- No. of shares: 186 million
- Market cap: £82 million
I restarted coverage of this group in February.
Subsidiaries are as follows:
- Bulgin - designs and manufactures sealed connectors and electronic components, for use in harsh/outdoor environments.
- Checkit - software and devices to help small and large businesses track performance and trends.
- Elektron Eye Technology - screening devices for eye care.
Today's H1 update is ahead of expectations.
Sales from continuing operations:
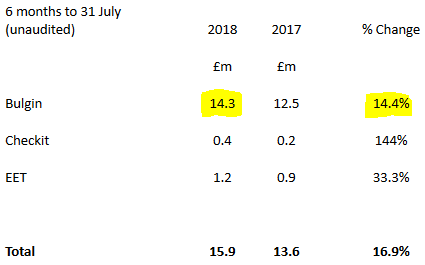
I've highlighted the numbers at Bulgin in yellow as it's responsible for the lion's share of revenues.
All divisions are reportedly doing very well, and the company has net cash of £6.8 million.
The encouraging level of growth and strong balance sheet go some way towards explaining the high rating attached to the shares:
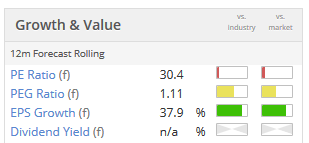
As has been mentioned in the comments, it does look a bit strange to have three such different companies, operating in such different markets, under the same corporate umbrella. It looks to me as if their customers are completely different and the devices they produce have little in common. So I can't imagine what the synergies might be.
That said, the three underlying businesses sound like they are doing well, with Checkit and EET looking quite early-stage while Bulgin is the more established of the three.
So it could be worth looking into in a bit more detail.
Card Factory (LON:CARD)
- Share price: 190p (-10%)
- No. of shares: 341.5 million
- Market cap: £649 million
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, announces the following trading update for the six months ended 31 July 2018.
This is the worst performer in the FTSE 250 today after the following announcement:
- like-for-like store sales -0.7%, "due to weak consumer environment and extreme weather conditions", impacting high street footfall.
- underlying FY 2019 EBTIDA in a range of £89 - £91 million, depending on Q4 performance (FY 2018 underlying EBITDA was £94 million, converting to £73 million of PBT).
On the positive side:
- on track to open c. 50 new stores for the full year.
- remains "highly cash generative". net debt is approximately unchanged compared to six months ago at £160 million.
- Return of 5p-10p per share surplus cash forecast for the end of the financial year.
My view
Another contrarian play, it's worth mentioning that Card Factory is different to other card retailers as it designs and prints its own products.
Its cards don't have the prestige of Hallmark but they do offer good value instead.
And making its own supply means that it earns consistently high margins. It's not merely the distributor of someone else's gear.
So there's a lot more to talk about with this one than you might initially think.
When I covered it in September 2017, with the share price at 315p, I said:
If the shares were on an ex-growth earnings multiple, I could possibly be tempted to hold them for a while.
We are now arguably at that level, with the shares having fallen by 40% since I wrote that, but earnings not having dipped by all that much.
It would never be a high-conviction long-term hold for me, because I don't think this has the quality of a brand like Hallmark.
But it has proven to be a powerful cash machine, generating free cash flow to the firm of between £60 million and £70 million for the past several years.
While the growth outlook is pretty poor in the short-term, I think it is still much too soon to say that the wheels are coming off.
So I'm tempted to open a small, starter position in this.
AA (LON:AA.)
- Share price: 116.6p (+2%)
- No. of shares: 612 million
- Market cap: £714 million
AA plc, today publishes a trading update for the six-month period ended 31 July 2018. Despite the extreme weather conditions we remain on-track to deliver our previously announced guidance of Trading EBITDA of between £335m to £345m for FY19.
An unusual situation. We have a super high-quality and universally recognised brand, serving a wide and mostly loyal customer base, that is loaded with an inordinate amount of debt.
It is one of the most heavily shorted names in London. 8.5% of shares are sold short by seven funds.
Despite net debt of £2.7 billion (January 2018), it hasn't panicked and has even been paying modest dividends to shareholders in recent years.
Today's update is mostly reassuring.
The membership base at the Roadside division is down marginally, impacted by competition and pricing pressure.
At the Insurance division, motor policies are up 7%.
Cash conversion remains "strong and predictable" - music to the ears of both bondholders and shareholders, I'm sure. The next debt maturity event will in January 2022.
There's been useful analysis of this share by "lavinit" on this website.
He has wondered how the debt issue might ultimately be resolved.
I reckon that this will roll on its current form for the foreseeable future, for reasons he outlines.
Late 2021 and 2022, being the next round of refinancing, is when it will get interesting again.
If business remains steady, and there is not much difficulty refinancing it again, and especially if the debt multiples can start to reduce, then I believe the equity will be a multi-bagger.
This has a place on my watchlist and I'd like to buy it when I have a firmer belief that it's going to pull through. I'm merely collecting the evidence at this stage.
We shouldn't ignore the presence of short-sellers, either - they're likely to have some good reasons for their positioning. So in some way this requires even more careful analysis, to prove that they're being overly pessimistic in this case.
The StockRanks love it, except for Momentum:
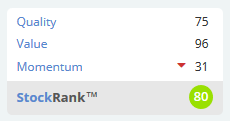
I'm not seeing much else worthy of comment, so I'll leave it there.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
I recently discovered a further use for crypto-currencies in addition to money laundering, tax evasion, drug dealing, etc,
A friend showed me a blackmail threat. Payment was demanded in bitcoin. The threat was ignored.
Richard
In the spirit of “every dog having its day”, I was pleasantly surprised to log in and find that Ascent Resources (LON:AST) , one of my mad money O&G penny share punts was up about 130% on the day. I took a small punt on this Slovenian gas explorer a few months ago when a discounted placement was offered via Primarybid (nice idea this platform, but so many of their offerings appear to have hit the buffers). Seems the company may finally be close to resolving their licence application with the local authorities (although that has been promised before) and the shares have perked up accordingly.
https://www.investegate.co.uk/ascent-resources-plc--ast-/rns/permitting-update/201808091101093484X/
Same magnitude of rise again tomorrow and I might just about be back to break even ....!
Gus.
Graham,
Just checking, you describe Argo Blockchain (LON:ARB) as
"Another symptom of the mass mis-allocation of capital associated with cryptocurrency."
"It's shocking to me that some blue-chip institutions were coaxed into backing it."
"a leveraged play on the price of cryptos"
You use Charlie Mungers quote about Cryto coins as "turds" and you end with this...
"I assume that very few people have gambled a significant portion of their life savings on this stock. If there are any, I think it's fair to ask them: aren't there more entertaining ways to risk going broke than this?"
So............You're saying it's a screaming buy and I should invest all my life savings, re-mortgage the house, and spend my evenings on street corners to earn a few extra Pounds (actually more likely to be 'Pennies') to invest in it as well!? ;-)
+ve. I was personally quite surprised (on the upside) by the modest LFL declines a Card Factory (LON:CARD). When stacked up against other retailers this seems like relative outperformance. I believe people will continue to buy physical cards, so that their recipients can decorate their mantlepieces
+ve. it seems that the board is quite happy paying more dividends (80m) than FCF to equity (60m), and therefore levering up a bit each year. This can't go on for ever, but doing this whilst rolling out 50 more stores (5% annual growth in outlets this year) means that it's a fairly scalable model with room for further coverage, so CFO should catch up in due course
-ve. Shame that it can't seem to deliver performance online. I am much less worried about the digital threat to greeting cards, but it would be additive if CARD upped it's game in this channel.
I am a holder. And will top up more today.
Re Card Factory (LON:CARD)
Thanks Graham for another great review. I put CARD on my watchlist after your last review and have been watching for a good entry point. Now charts are just one tool I use (not always successfully I might add) to decide when to dip my toe in and with CARD I would caution against doing so yet. Today's price of 190 has taken it well below the three remaining resistance points that underpin its price of 210, 203.4 and 203. Until it bottoms out and shows sign of moving up, I would not buy.
By contrast, GAME Digital (LON:GMD) has been sliding relentlessly over the past few months and looks like it has not only bottomed out, but at today's price of 28.6, has broken out of its lower 27.8 resistance band. This suggests an upward trend which will signal an even stronger confirmation if/when it crosses 32.95.
cheers
Francis
People have been offering "mining as a service" since the days of GLBSE (the "Global Bitcoin Stock Exchange" which was needless to say not a regulated stock exchange) - and indeed they have been failing to turn a profit doing it since then too! The problem is that there are only a fixed number of bitcoins to be mined every ten minutes. If people create ever more powerful miners the system adjusts automatically so that the same number of coins still get mined. You are running to stand still. In effect mining always becomes sufficiently expensive that it is no longer profitable.
However the really bizarre tail-wag-dog aspect of bitcoin seems to be that as mining gets more expensive, the price of a bitcoin increases to "justify" the mining costs. If ever there was "a coin for providing a great advantage, but nobody to know what it is" (to paraphrase the South Sea Company) it has to be bitcoin.
Re ARB (and can someone remind me how to enter a stock name and ticker in a post - I keep forgetting and I can't find it defined)!
To make money, Argo will have to find a sufficient quantity of amateurs who want to hire its mining equipment, in order to cover the costs of assembling this equipment and make a profit.
Isn't this a potential risk reduction? Not a company I'd go near with a very long bargepole, but if you are going to get into crypto mining perhaps this is way to go. It's the old line about the people who made money from the Alsakan gold rush were the one who sold the shovels!
Peter
The shovel-seller equivalents are those who sell the computer hardware to Argo. Argo is equivalent to the guy who owns the mine. G
And the data centres who are leasing their servers to Argo - they are also equivalent to the shovel sellers. Argo is the entity which has to put all of this server capacity to good use on behalf of its customers, or it will be left holding the bag. G
and can someone remind me how to enter a stock name and ticker in a post - I keep forgetting and I can't find it defined
I too spent ages searching for a help/how to on this before finding it bottom right of the text entry box for a comment. It's a £ sign before the ticker. Think the ticker needs to be upper case and followed by a space. Ones with numbers don't work.
cheers
Graham, In case of interest this company floated recently BigDish (LON:DISH). On face value it does't look very attractive to me. So might be worth just ignoring. Alternatively, it might be highlighted as a risky IPO and want to be wary of for now. Someone seems to be hyping up the company on lots of bulletin boards which is not a good sign IMO.
House of Fraser - Thanks for pointing that out. I think it is an interesting case of asking: what is risk? Value investors might have gone for established retailers as their P/E's were low. Amazon looked expensive and the shares were very volatile. However, Amazon's business risk was much lower than high street retailers. This is because it was able to undercut established retailers on price.
Is the issue for Card Factory (LON:CARD) that we just don’t send cards so much any more? Their low cost model is attractive but they are in a market in secular decline due to smart phones.
I think JohnEustace that regarding Card Factory (LON:CARD) that is an issue that has been kicked around many times before, but is never resolved. Perhaps the real question is whether the mechanism for the products Card Factory (LON:CARD) sells of retails stores etc, is the most economic.
At the moment because of their structure, they have bricks and mortar retail exposure, retail staff costs, subject to wage minimum regulations, and pound/dollar headwinds, as well as customer appetite questions.
They are still very profitable , just less so, with a healthy dividend (albeit financed through borrowing as much as by healthy cash generation). Unfortunately, it is not easy to say whether they are really positioned for long term decline businesswise, but arguably their from the share price perspective, investor seem to be taking a gloomier view, and at some point, that may signal value in the short to medium term.
The other issue for Card Factory (LON:CARD) that I have seen mentioned elsewhere is that the supermarkets and discounters are increasingly competing with them by offering equivalent ranges.
Slight clarification Card Factory (LON:CARD) cited 'extreme weather conditions' as well as consumer weakness for lower profit guidance. So it could have meant cold snap as well hot phase.
Card Factory (LON:CARD) factory issued an update showing that the extreme weather had an impact on footfall. I am not totally surprised by this, and would expect to this more widely touted in the retail sphere.
Whilst its nice to go out in sunshine, it was so hot, I think a lot more people decided to stay at home, and keep the curtains drawn.
I fully expect Revolution Bars (LON:RBG) to replicate elements of their earlier trading statements about some of their estate i.e bars without gardens, being less popular in the very hot weather.
Elektron Technology (LON:EKT) The figures quoted on Stockopedia financial summary seem to be all wrong i.e 2018 revenue £29.8m should be £41.6m.
EDIT was looking at wrong company.
EKF Diagnostics Holdings (LON:EKF) Trading update. Looking at the forecasts on Sharepad the forecast for revenue growth is 4% but forecast growth for EBIT is 70% and 100% for EPS. Is that likely?
Caledonia Mining (LON:CMCL) - marked increase in debtors and another worker dead. Not sure there's enough to look at for a full report, but any insights would be welcome. Zimbabwean election could have gone better.
10% down today and the price of gold at a recent low, ouch
My morning smallcap tweet: MIRA MIRA on the wall, who is the most bullish of all?
Mirada (LON:MIRA), Elektron Technology (LON:EKT), North Midland Construction (LON:NMD)
Mirada (MIRA) conversion of loan to equity at 1.12p (a 53% premium) taking the concert party to 66% holding. Guides FY rev up slightly. Outlook - bullish, as always.
Elektron Technology (EKT) H1 trading. Rev up 17%. Guides FY ahead of market expectations.
North Midland Cnstrn (NMD) H1 EPS 20p up 104%. Div doubled to 6p. No F/C available. "Our focus on margin enhancement (104% ahead of last year) and cash generation (138% ahead of last year) is beginning to show returns and is anticipated to continue going forward." Recovering well from disastrous 'legacy' projects.
Elektron Technology (LON:EKT) an Adventurous, Small Cap, High Flyer provided an update on trading for the six months ended 31 July 2018. "Strong double digit sales growth during the first half of the year is representative of the multi-year transformation of our business. As a result of strong trading in the first half, and current visibility, we now expect our performance for the full year to be ahead of market expectations." Quality and Momentum seems evident here. I'd be interested in constructive thoughts. I hold.
I would second that. Thanks
Hello mercury61. I'd not looked at Elektron Technology (LON:EKT) before but I took a glance at today's update and their website this morning and what struck me was that Bulgin represents almost 90% of the business (£14.3m of the total £15.9m sales) for the 6 months trading update. So for a basic manufacturer of commoditised electrical connectors, the valuation seems a little racy. I'm not clear what a connector manufacturer has to do with medical testing devices for glaucoma and other eye disorders (Elektron Eye Technology) and what that has to do with Real-Time M&C (check-it). These seem like 3 very disparate endeavours and without knowing the history of the company, I'm not clear how they ended up here but what is clear, is that the boring connector business is doing all the heavy lifting. I wonder if the sexier IoT aspects of check-it are what gives it the racier valuation despite its minimal contribution to revenues (400k). Obviously this is not the result of any in-depth analysis, just a bit of devil's advocacy from a skim of their website but maybe the basis for a discussion. Good luck.
I looked at Elektron Technology (LON:EKT) H1 for the 1st time too, but came to a different conclusion to.... for a basic manufacturer of commoditised electrical connectors, the valuation seems a little racy.
I don't have 1st hand knowledge of the Bulgin product range, but the Quality metrics indicate a widening Moat, and the company has announced it will beat market expectations for the full year. Perhaps others know of the Bulgin product line and can comment? Ian
I’m not so sure the Bulgin products are commoditised. They look to me like the sort of niche products where quality and reputation will come first for a lot of people. No point penny pinching on a connector that’s going in a harsh environment that you don’t want to have to send someone back to.
It’s the sort of thing where a design engineer in days past would just have pulled their catalogue down from the shelf and would have taken some persuasion to look anywhere else. These days that may be internet based but the thinking will be the same.
If I may offer some insight in to Bulgin products. The last company I worked for was a small supplier of specialised communications equipment, and used Bulgin connectors on some of the equipment and connecting cables.
They are good quality but not by any means the only connectors than can be used in harsh environments, nor are they necessarily the best for all environments or applications. We didn't use them everywhere on our products. There are better and more expensive connectors, and there are cheaper ones too. I would regard them as commodity items rather than specialised. They are middle of the road in terms of performance (assuming some degree of ruggedisation is necessary), and price.
I suppose I should caveat the above with saying that I wouldn't necessary claim to be an expert on all their entire range. So I can only speak for the types we used.
Hope that is helpful.
I'm having a look, cheers Mercury. G