Small Cap Value Report (Tue 1 Nov 2022) - MADE, FUL, MCON, ECK, VTU, VINO

Good morning! It's Paul & Graham here, with our usual daily review of small cap trading updates & results statements.
Agenda
Paul's Section:
Made.Com (LON:MADE) - as expected, its shares have been suspended this morning, and Price Waterhouse Coopers are being lined up to become administrators of MDL (the operating subsidiary company). Proposals were received during the formal sale process to buy trade, assets, and brand out of administration. So the next step is that the administrator will sell off whatever they can, which usually happens quickly, and the proceeds are then used to pay creditors in the order stipulated by the law. Since it will owe customers, and trade creditors, then I would say the likelihood of any return for shareholders from the administration of MDL is probably zero, because shareholders rank behind all creditors in an insolvency. It says that, "in due course" the listing of MADE shares will be cancelled, and "any residual value will be distributed to the Company's shareholders". I've mentioned this before, that it looks as if the topco is not going into administration, and may have a little remaining cash possibly? Although there is a bank guarantee over leased properties that might consume that cash, and other costs, who knows? Anyway, it's a sorry tale from listing in June 2021, to insolvency in November 2022. What went wrong? Supply chain problems, and incompetent management I would say. Also, the arrogance of a "disruptor", thinking people would buy furniture online, when in reality most people like to see, and sit on furniture. Plus extrapolating out the pandemic boom in sales, and thinking it was structural growth. Then losing money hand over fist, and burning rapidly through a large cash pile. It was very clear earlier this year that MADE was heading for disaster, so nobody should have been holding this share who reads this column. I wonder who will buy it? The brand, and operations could be snapped up by DFS or SCS, possibly? Although maybe both would be happy to see it disappear without trace, leaving them more market share? Who knows.
Fulham Shore (LON:FUL) - an H1 trading update, with robust trading continuing, and in line with expectations. Rapid expansion of new sites is underway, and the company remains in a net cash position. Valuation would look attractive (forward PER of 13.2) in normal conditions, but the trouble is we're probably heading into a recession. Therefore it's difficult to see any reason to rush into buying shares that are so dependent on consumer spending right now. On company fundamentals though, FUL looks good. Its value for money customer offering is proving resilient so far.
Virgin Wines UK (LON:VINO) - I've had a good rummage through its FY 6/2022 accounts, and think this looks a resilient business, with sound finances, and an undemanding valuation. So, as a value share, and thinking long term, it gets a thumbs up from me. In the meantime, there's an obvious risk that customer cancellations of subscriptions might rise in the current environment.
Osirium Technologies (LON:OSI) - see the reader comments here, where Snazzytime gives a nice summary of this nano-cap. It's only £2m mkt cap, so too small for me to cover. The main problem I can see (having had a quick look at it after hours), is that it clearly needs to raise more funding, and already has a stretched balance sheet. Could be worth a flutter, once it's done another fundraise though, purely as a punt.
Graham's Section:
Mincon (LON:MCON) (£192m) - a pleasing update from this manufacturer and distributor of drilling equipment. Sales to construction are up strongly but the mining industry, its largest customer, has also grown at double digits. Overall sales in the first nine months of the year are up 25%, although this is boosted by acquisitions and by currency tailwinds. Margins look set to hopefully recover, although there is a lag between input cost increases and Mincon’s sale price increases. The long-awaited Greenhammer system is now being used for commercial drilling in Western Australia. I remain a fan of this company and its shares don’t look overly expensive to me.
Eckoh (LON:ECK) (£125m) - trading is in line with expectations at this company that provides online customer service solutions to corporate customers. Headline revenue growth is excellent but again the organic growth at constant exchange rates is unclear. I find the valuation here to be stretching. Even if a price to sales multiple of about 4x is average or cheap in an industry context, I find it difficult to get comfortable with it. The Stockopedia computers agree, awarding it a ValueRank of only 12.
Vertu Motors (LON:VTU) (£164m) (+3%) [no section below] - a small (£4m) acquisition by this automotive retailer. It has picked up two BMW Motorrad outlets from a family-run business in Yorkshire, with plans to rebrand them and operate them within the Vertu motorcycle division. The price paid is nine times last year’s operating profit and freehold property worth nearly £2m is included in the deal.
Vertu will then have six motorcycle outlets, three of which are BMW Motorrad dealerships, and will be “the largest partner in the UK for BMW Motorrad”. I’ve never given any thought to the merits of motorcycle dealerships versus car dealerships but it can’t be a bad thing for Vertu to increase its presence in this sector for such a modest price. I note that the company completed a £3m buyback programme in July and announced a new one in October. With perceived low-quality companies trading so cheaply at present, there is in my view a huge opportunity for them to deliver shareholder value through buybacks, where genuine cash flow generation can support such a move. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Fulham Shore (LON:FUL)
9.9p
Market cap £63m
The story so far - this restaurant chain (Franco Manca pizzas, and “The Real Greek”) was trading robustly this year, with an in line trading update that I reported on here, end August 2022. It also reported rapid expansion into new sites (10 new restaurants this year, taking the total to 90 by end August, up to 95 now), with favourable deals available from landlords.
Here’s today’s news -
Business Development & Trading Update
This covers H1 to end Sept 2022, for FY 3/2023.
Reassuring news -
First half trading in line with management expectations
Trading - in line, despite challenging backdrop.
... both our established and new restaurants performed well during the first half of the Group's financial year.
Value for money products.
Revenues are up 35% vs pre-pandemic 2019, and 25% up on 2021, but that doesn’t seem to be like-for-like, so some of the growth will be for new site openings. Therefore we can’t really judge how good the performance is, unless we do a spreadsheet to estimate the effect of new sites. The only meaningful revenue comparisons are for like-for-like sites, so there’s a gap in the reporting here.
Net cash - was £2.6m at the end of H1 (26 Sept 2022). Undrawn bank facilities of £16.9m gives it plenty of headroom. It’s used £2.1m of cash since the last update of £4.7m at end Aug 2022, which doesn’t seem a concern, seeing as payments would be required to pay for the capex at new sites. Also quarterly rent payments are paid near end Sept, so this reduction in cash looks reasonable, not a concern.
Supermarkets deal - Franco Manca pizzas are now to be sold in supermarkets (500 initially, from this week), for cooking at home. Similar to what Pizza Express have been doing for years. This is being implemented via a licensing partner, Rondanini.
The reason given is to drive brand awareness, especially in areas where there are no Frano Manca restaurants.
New sites - 6 more have been opened in just the last 2 months, so this expansion is really quite rapid now.
Interim results will be announced in December, with another trading update.
Outlook - the well-known macro issues are mentioned -.
... trading conditions that are more unstable and unpredictable than at any time in recent memory. ..
My opinion - let’s find out which supermarkets are stocking the Franco Manca pizzas, and mystery shop them! I see possible damage to the brand, if this new venture is not executed well, and the product disappoints. Personally I’ve never bought branded pizzas in supermarkets, because they’re a rip-off. Although I am particularly careful with my supermarket purchases, as a former neighbour quipped (after I’d suffered some huge loss on the stock market, but quibbled over the price of broccoli), “You’re penny-wise, but pound-foolish, Paul!” It’s difficult to argue with that.
Anyway, are FUL shares good value yet? I would say, yes it’s going that way. We now know that (at least so far) its customer offering is proving resilient, and does indeed offer value for money, which is essential in these difficult times. Lots of competition (especially independents) are leaving this sector, which provides more market share for the strong companies which survive.
There’s an obvious risk that consumer conditions worsen, and FUL issues a profit warning, so it’s difficult to see any pressing reason to buy it now. I’d be inclined to put this on my watch list, and just wait. If there is a downturn in trading, then that might provide a better buying opportunity. If not, then that’s fine, it’s difficult to see much upside any time soon on the current share price.
In more normal times, a forward PER of 13.2, for a rapid roll-out, would be attractive. But we’re not in normal times.
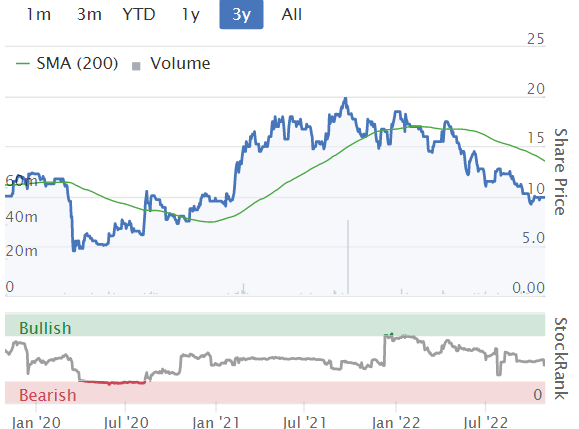
It's striking that, despite a series of reassuring trading updates this year, FUL shares have still halved in price from last autumn's peak - showing just how negative sentiment has turned - which is what provides future opportunities for investors to make profits, of course. It's just the timing that's the tricky bit.
.
Virgin Wines UK (LON:VINO)
51p
Market cap £28m
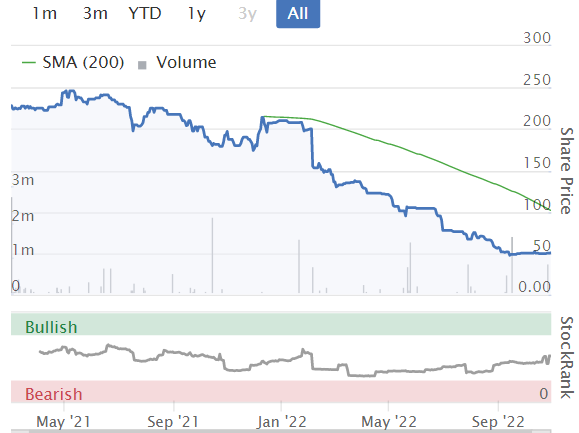
I hope the wine for 2021 turns out to be better quality than the distinctly corked IPOs of last year! This one is down about 80% from its peak in May 2021.
I briefly reviewed its FY 6/2022 trading update here, and came away with a mildly positive view.
Last week it reported results -
Virgin Wines UK plc (AIM: VINO), one of the UK's largest direct-to-consumer online wine retailers, today announces its audited Annual Results for the period ended 1 July 2022 ("FY22").
I’ll call that FY 6/2022.
I’ve reviewed the numbers, here are my notes -
Profitability is very similar to the previous trading update, so no surprises.
Revenues of £69.2m - down 6% on the pandemic-boosted prior year.
WineBank (monthly subscriptions) is key, generating 56% of all revenues, £38.5m
Adj EBITDA £6.2m (down 11% on LY)
EBITDA margin of 9.0%, it says is sector-leading.
PBT £5.1m (down slightly on £5.2m LY)
These numbers look quite respectable to me, so far.
EPS of 7.8p, which is helped by a lowish 14% corp tax charge. Although bear in mind that EPS is expected to fall to about 6.0p this year & next.
PER is only 6.5, which looks cheap, but of course would rise if earnings fall this year.
Gross margin is low at 31.4%, slightly below LY. I don't think wine retailing is a particularly good sector, look at the mess Naked Wines (LON:WINE) got itself into. VINO looks a much more sensible & less risky investment to me. EDIT: I note from the recent webinar that gross margin includes the costs of packaging & dispatch to customers, so the product margin alone would be higher than this. End of edit.
Unusual fall in administration costs (before exceptionals, e.g. LY listing costs), from £5.4m LY, to £4.4m this time. That strikes me as odd, so maybe some one-offs either this year, or last year? The commentary says the business benefits from a flexible cost base.
Finance costs have greatly reduced, as the pre-IPO funding structure (debt) disappeared. Maybe this year could benefit from interest received on customer & company cash deposits?
Staffing - it says 200 in total, of which 164 are in sales! Where are the warehouse staff then? I wonder if distribution might be outsourced, although a bit googling suggests not. There were distribution problems near the end of 2021, with staffing trouble & Omicron.
Cost of customer acquisition (CAC) looks reasonable, at £13.22 (LY: £13.49), but I can’t see any information on customer lifetime estimates. Although the reported figures on customer attrition sound low, but that depends how they’re calculated, so it seems a little opaque to me.
Strong recruitment of new customers in Q4 (Apr-Jun 2022), so that provided a tailwind into FY 6/2023.
Interesting B2B partnerships, with railway operators, Moonpig, and Saga [I hold], and strong pipeline of partnerships - this looks an appealing strategy, and an effective way to recruit new customers. Corporate gifts also did well, up 16%.
Current trading - Aug good, Sept softer (but reined in marketing spending around Queen’s death).
Guidance - flat revenues for FY 6/2023. Expecting EBITDA margin to fall from 9.0% to 8.0%, as not able to offset all cost increases.
Balance sheet is fine, about £11.0m NTAV (as expected). This includes very little fixed assets, it’s mainly working capital, which is favourable because customers pay up-front through subscriptions. Conservative accounting, with customer cash ring-fenced. Total cash was £15.1m, or £7.7m once customer WineBank deposits are removed. That’s a healthy position.
Cashflow statement - note that good operating cashflow is almost all absorbed into increased working capital, which happened last year too. Not necessarily a problem, but I would want to make sure it starts generating genuine free cashflow in future years.
Dividends - none. The prior year divis looks to have been part of the old finance structure, pre-IPO, with preference shares. VINO really should be concentrating on paying divis in future, so I’d like to hear more about their future intentions in this regard. Since revenues aren’t growing, then the company needs to focus on cash, and divis, I think.
Overall, these numbers look clean to me, with hardly any adjustments, and the accounting policies seem sensible, so I’m comfortable with the numbers, and how they’re presented.
My opinion - I quite like this! The numbers seem solid - with profit only down slightly on the pandemic-boosted prior year, although I am curious as to how administrative costs were reduced by £1.0m, that’s a good point to query if they do a webinar. Ah drat, I just realised I missed it, there was an InvestorMeetCompany webinar on 28 Oct, so I’ll watch the recording instead.
It seems to me that the share price has been unfairly clobbered, probably on general negative investor sentiment, but also possibly on worries that cash-strapped consumers might cancel subscriptions. There again, as VINO says in its commentary, eating/drinking out has become so expensive, that having nice wines delivered to your home could be something that people might prioritise as an “affordable treat”, instead of eating out, and paying an inflated price for usually really poor wine (is it just me, or do bars & restaurants in the UK generally serve revolting, cheap nasty wine, but expect us to pay £25+ per bottle!). I can see the advantage to doing a bit of pre-loading with nicer Virgin Wines, and turning up half-cut at the restaurant, and drink tap water instead.
Joking apart, overall I think VINO shares look attractively valued now, at c.50p, so it gets a thumbs up from me. It probably won’t blow out the lights, but in a bull market I think this share could double from the current level, with a bit of patience. In the meantime, the downside risk looks protected with a sound balance sheet, and comfortable cash position.
.
Graham’s Section:
Mincon (LON:MCON)
Share price: 98.5p (+5%)
Market cap: £192m
This is an Irish engineering group. As I’ve noted before, it has shown excellent long-term progress in revenues and profitability:
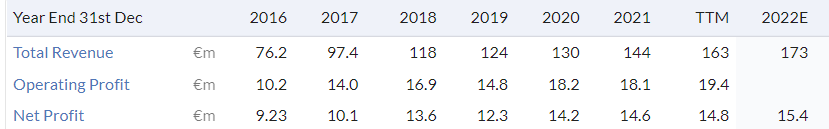
Calling itself “the driller’s choice”, it specialises in drilling equipment: drill rigs, hammers and drill bits. It mostly sells products that it has manufactured itself, and it mostly sells to the mining industry.
At the interim results in August, I noted that the strong dollar had boosted its revenues, but cost increases had held back margins. To meet customer orders as swiftly as possibly, it had switched to expensive air freight.
Let’s take a look at this Q3 update. Key points:
- Revenues year-to-date (9 months) are up 25% year-on-year
- Growth is “mostly organic”, with currency tailwinds. It would be helpful if the company published like-for-like growth at constant exchange rates.
Industries: construction is growing fastest, but mining is also growing at double digits.
Margins
During the past quarter we made significant progress in reducing our order backlog. This will facilitate production and logistics planning, and in particular enable us to significantly reduce air freight from our factories to our customer centres in the final quarter.
The use of air freight has been a major hit to margins - but it has not been the only cause of difficulty:
We introduced price increases in H1 2022 across all markets and regions of the Group. While the effect of these in the past quarter has improved margins compared to the first half of 2022, they have been offset to some extent by higher energy prices in our factories and energy related surcharges on raw materials. Nevertheless, we remain positive about achieving an improved margin percentage for the second half of this year.
For gross margin, Mincon achieved 31.8% in H1 this year, which was down from 34.2% the prior year.
Greenhammer
This mysterious project has been in the works for a long time, and some investors have rightly been sceptical of whether it would lead to anything. The CEO has said that Greenhammer “can have a significant impact on both Mincon and hard rock surface mining more generally”.
Thankfully, there has at last been a commercial contract signed for Greenhammer (announced in September). The contract is with “ a blue-chip mining contractor operating on a major gold mine in Western Australia”, and has “the potential to be a multi-million-euro contract”. Commercial drilling started in October.
More importantly, there are hopes that all going well, Greenhammer “will be taken up quickly by the wider hard rock mining community”.
I usually try not to emphasise projects and plans that appear to be “blue sky” in nature. But in this case, we have a credible company and a credible management team who are making the ambitious claims. So I think it’s worth bearing that in mind.
My view
I see little reason to change my view on this company that I expressed in August. At 95p, I thought the shares looked promising: not too expensive versus current earnings, and with the potential for margins to recover and for Greenhammer to start making a contribution.
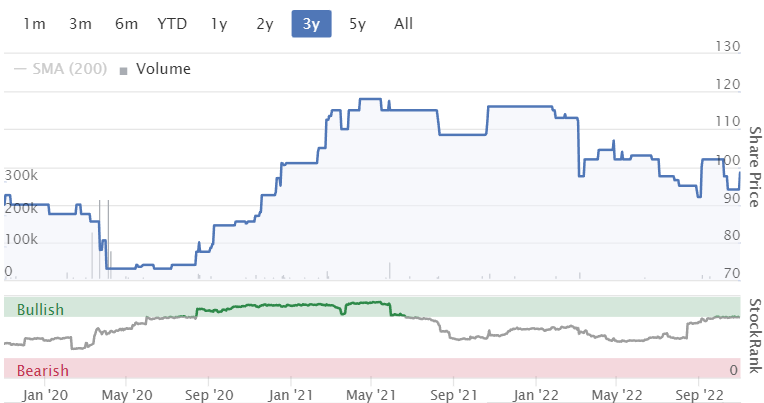
The share price has drifted within a range for the past few months. I maintain my positive view.
.
Eckoh (LON:ECK)
Share price: 43p (+2%)
Market cap: £125m
This is a “global provider of Customer Engagement Security Solutions”, with an H1 trading update for the period ending September 2022.
Trading is in line with expectations.
H1 revenues are up 33% to £19.6m but this includes the impact of an acquisition. US revenue is now 44% of the total.
Similarly, operating profit is up 50% (last year’s adjusted operating profit was £2.5m) but this includes both currency tailwinds and the acquisition’s contribution.
Annualised recurring revenues are now £27.8m.
Product development - Eckoh is developing new products for remote workers. They are already serving this segment, but the new products will include upgraded features and functionality.
Outlook
Despite the ongoing macro-economic uncertainty, the Board expect revenue and profit for FY23 to be significantly higher than FY22. The Group is trading in line with consensus market expectations , supported by long-term structural growth drivers, increasing Cloud adoption and Eckoh's strengthening product offering.
Company-compiled estimates are for revenue of £40.25m and adjusted operating profit of £7.45m.
My view
I haven’t found much to criticise at this company, but I’ve also found little to excite. Underlying organic growth remains unclear and the valuation is punchy:
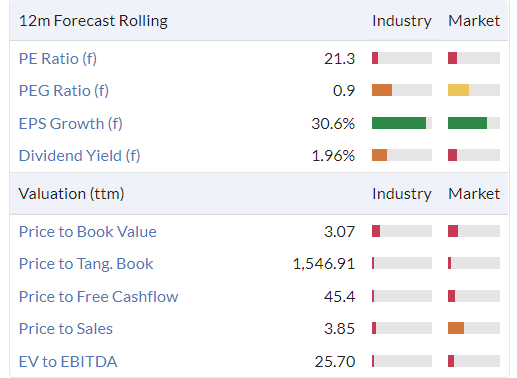
Note that the ValueRank is only 12.
It’s a sector that investors are often willing to pay up for - online tech, with elements of fintech and cybersecurity - and the price to sales multiple is around 4x (I use the enterprise value to ARR multiple, which comes out at 4.4x).
That’s not really an expensive multiple in an industry context, but I still find it uncomfortably high. Judging by the ValueRank, the Stockopedia computers agree.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Re Vertu Motors (LON:VTU) buying 2 BMW motorbike franchises for +/- £4mn. This looks from the outside like a very good deal, both financially and strategically.
My only surprise is that at 3 outlets they are now said to be the biggest dealer in the UK. I looked on the Motoraad website and found outlets in all the random cities I tried. This suggests very fragmented franchise/ distributor base. I am not a petrolhead ( £30 bike and a 9yr old Ford Focus does for me on principle) but motorbikes seem like a very adjacent diversification and easy to add to more existing showrooms.
There is always the big picture risk of car dealers becoming obsolete but recognising that risk, all else seems to be set fair at Vertu right now even if 2nd hand sales prices fall back. High chance it will be involved in consolidation either eating or being eaten but as long as the property values hold up then is looks a good bet either way. Stockop now has price:tangible book at 0.68 so a fair safety margin.
(Disc - i re-read my notes this pm and discovered they said I had bought VTU at 24p but my ISA reports say I did not. Apologies if I have misled in the past! Sadly, clearly a slip between cup and lip in buying!)
There’s a lot of evidence that show that buybacks often don’t deliver shareholder value. Vertu Motors (LON:VTU) shares look stunning value anyway and using spare cash wisely, as hopefully proves to be the case with their acquisition today, is arguably a much better way of rewarding shareholders than spending it on buybacks. Too often buybacks reward those who want to sell as there’s a willing buyer and not those that the supposed buyback reward is intended for!
Buybacks that don't work are those that are (unofficially) intended to soak up supply of an overpriced share or which are not funded from operating cash flow.
For a share that is priced below NTAV and is generating material free cash flow, like Vertu Motors (LON:VTU), buybacks definitively do create value for continuing shareholders. That is surely inarguable?
As to whether that increased value is immediately reflected in a higher share price, that is a different matter.
Agree, buybacks must ultimately add value. If a company buys back 10% of its shares then shareholders would own 10% more of the company than they did before. It may not be immediately reflected in the share price, but if earnings per share increases by 10% (assuming all else equal) then this will eventually feed through to share price.
Thanks for the replies. Re “it (the buybacks) …….will eventually feed through to the share price.” Will it?
Abrdn (LON:ABDN) have been buying back for several years. They started at £5 and the share price is now £1.65! There are so many similar and worse examples unfortunately. The buyback theory is convincing, but so often buybacks reward sellers and not those staying invested.
If shares are bought back at prices that are below intrinsic value, then that is a good deployment of capital - otherwise it isn't. It's up to shareholders to determine what is intrinsic value and from that you can determine if management is making the correct decision regarding capital allocation. This doesn't reward traders, but is great for business buyers, the long term shareholders.
I would like to add that I love share buy backs in the following scenario - the market share price is below intrinsic value, the company cannot re-invest the money into the business to get better returns and the business has very little or no debt. I like to see excess capital paid out in the order of money into the business to produce better returns if debt costs are less than forecasted returns, then if that is not available, reduction of debt if debt is above a well defined ceiling level which is dependent on interest rates and always less than 5 years of operational cash flow, then buy company shares to reverse dilution if the market price is less than the intrinsic value of the company and lastly dividends. Not everyone will agree with my take on capital allocation for a wide variety of reasons - but these are my preferences.
Does anybody have any idea what's with the £:CINE rocket today?
Likely the RNS released at around 5pm yesterday! Cineworld (LON:CINE)
Except that there was no RNS from Cineworld (LON:CINE) - it was a Reuters item. Often you then get an item at open "the company notes press comment and confirms/denies etc.' but zilch. That in itself is not a good way to treat your shareholders.
Back on 9th Sept. there was an RNS that provided this link https://cases.ra.kroll.com/cin... showing the next hearing was yesterday.
I note that they say that "The company cited difficult conditions for movie theaters, as well as high debt stemming from its $3.6 billion purchase of Regal as reasons for its bankruptcy filing". I can't help a little schadenfreude here. I once read in an investment book* that you should always write down why you bought or sold a share and I have followed this. In January 2018 I wrote that I thought the purchase of Regal and the debt it would bring was a disaster and reason for selling at an average of 489p (equivalent of 223p post the rights issue). Phew!
*Edit - just checked - Peter Lynch - One Up On Wall St.
Anyone any insights on why UK retail is up double digits today?
I'm not complaining, but Boohoo (LON:BOO) is up nearly 15% on the day
Wonder if it's interest rate expectations being lowered due to fiscal policy looking more restrictive?
As you say general IR rise expectations lowered plus dollar index DXY falling and rumours of China giving up on its Zero Covid policy .
Chinese Foreign minister already denied this, but who knows maybe no smoke without fire …
Also, the Dollar Index is still within the support range of its parabolic move, until and if that breaks, it’s just a consolidation - recent double top does look interesting though!
I’m actually looking at PM stocks again, they are dirt cheap and charts look bottomy. As people gradually accept the reality of financial repression, these must surely move higher in a mean reversion at the very least.
Hi Forsby,
Any particular PM stocks which might be worth looking at?
At current prices , I like (and hold) Serabi Gold (LON:SRB) , Shanta Gold (LON:SHG) , $GBX , $FNV
GDX & GDXJ ETF’s also well worth considering.
Basically, look for producers not explorers in current market conditions imo.
I would add Pan African Resources (LON:PAF) and Caledonia Mining (LON:CMCL) to that list (I hold both).
Shanta Gold (LON:SHG) is being courted by 3 suitors. Pure Gold Mining (LON:PUR) is wasted, I hold both. This scene isn't for widows and orphans.
Of course, stock picking is key in the sector. The two you’ve mentioned highlight well why company debt is a significant factor before any final decision making. AISC must also be considered alongside jurisdictional risk.
Shanta Gold (LON:SHG) , no debt, profitable - good production (increasing), new mine coming into operation imminently, (reduced operational risk), jurisdictional risk decent due to Tanzanian govt promoting growth.
Pure Gold Mining (LON:PUR) , highly indebted and mine shutdown….. so research and monitoring is essential.
PUR is a complete waste of time.
That should read $ABX above, Barrick Gold - not GBX
Almos Gold, Wesdome Gold Mines, i-80 ...all NYSE.
hi Paul / Graham
Could you please have a look at Osirium Technologies (LON:OSI)
Shares up 65% today on Q3 trading update.
Hi Snazzytime,
Osirium Technologies (LON:OSI) is not one I'm familiar with, and even after today's rise, the mkt cap is only £2m. We normally don't go below £10m mkt cap, because there's not usually any liquidity below that level, so even if we find something good (very rare at that size!) readers probably wouldn't be able to buy the shares.
But by all means feel free to post something yourself here, as to why you think OSI is good, I'm happy to look at tiny things if they are particularly interesting.
Thanks, Paul.
hi Paul
Thanks for your reply re Osirium Technologies (LON:OSI)
I don't see this as a good investment at all. On the contrary I see it as purely for gamblers.
Since flotation in 2016 it has been a jam tomorrow share with regular fund raises needed and consequent heavy shareholder dilution. Share price has crashed from an early high of nearly 200p down to recent low of 2.75p. It has doubled today to 5.5p as I write on a Q3 trading update released this morning.
The latest fundraise earlier this year was at 6p at which time it was signalled that a further fundraise would be required later this year. They have yet to make a profit (today's update merely announces increased sales) and have been burning cash with currently £320k remaining in the bank.
The company is involved in cyber security with a niche 'protected password' product. Hard to assess the potential (outside my pay grade I'm afraid).
Bottom line is that they are still someway from turning a profit with more cash needed soon. Continued jam tomorrow story although it's possible the product has legs and may be attractive as a takeover target.
I thought this might be another share which has so many red flags you might wish to share the danger signs with readers as you have so clearly and effectively done recently with Made.Com (LON:MADE) and Parsley Box (LON:MEAL)
More an educational post than anything.
Snazzy
Hi Snazzytime,
Thanks for that, you've saved me a job! I'll add a tag (making this report searchable) for OSI, and give you a hat tip in the report, so we can find your post if anyone else searches for OSI in future.
Much appreciated!
Best wishes, Paul.
Paul is he expert but, in my view, the bankruptcy risk for this stock makes it, currently, a gamble rather than a considered investment.
Snazzytime, when I first began investing all my savings in the stockmarket, around 2012, I took no heed of capitalisations and am still trying to shake off the dogs that I collected. Paul has warned time and again to stay above the limit he believes in, so stay safe, don't expect any old dog to transform into a multi-bagger. Luckily, the power of reinvested dividends from large capitalised companies is covering my regrets. I'm not a day trader and therefore not envious when I see a tiddler spike for a day or two.
Silver
Interesting and sensible acquisition by Vertu Motors (LON:VTU) of two BMW Motorrad outlets (Motorrad being German for motorcycle). The acquisitions will become part of the Vertu Motorcycles division, which will operate six motorcycle outlets across Motorrad and Honda.
I hold
"For the year ended 29 September 2021, the business achieved revenue of £20.5m and an operating profit of £463,000. Total consideration is estimated at £4.2m, subject to finalisation of completion accounts. The consideration includes a freehold property value of £1.85m and a payment in respect of goodwill of £0.5m. This consideration will be paid from the Group's existing cash resources. Due to the seasonality of motorcycle sales, the Business is expected to contribute a small loss for the remaining four months of the financial year and is expected to be earnings enhancing in its first full year of ownership."
BMW Motorrad is the motorcycles brand of BMW Group. In the full year 2021, it was the UK market leader in the 'big bikes' category with a 16.6% market share. Vertu currently operates one Motorrad outlet in Sunderland which it acquired in 2020; adding the acquired two further outlets will make Vertu the largest partner in the UK for BMW Motorrad."
Paul - I’m working my way through the CEO interview podcasts and finding them a great way to get on top of more companies. There will be a lot of noise as we drift into recession. I can’t explain why listening to the interview is more productive than reading the results or listening to a webcast…but it’s valuable enough for institutions to pay for. In the long run the hard yards companies put in here are rewarded. For them I’m sure it’s better to spend 30 minutes with someone prepared than turning the pages of a well worn presentation to a smaller group of half interested fund managers along for a free lunch.
Hi RDHOWARTH,
Thanks! Maybe I've misunderstood what you said, but just to clarify, I don't charge companies anything to interview their CEOs. Everyone else does charge of course (and fair enough if they have professional costs of production, etc), but they're less independent than me, but they're still good, so it's not a criticism, I just wanted to be clear that my stuff is totally independent and is not commercial. I just interview companies that I think look good.
Also I think the questions that are asked on webinars are often very insightful, showing that as you say interested PIs can be much more insightful than a bored broker who's at a meeting for the wine and the food!
Regards, Paul.
I understand your point, that you aren’t being paid to promote the companies. I was making the point that since MIFID institutions have been forced to recognise that they pay to meet companies - so it is clearly of great value to them. Of course these meetings aren’t public.
Really? Are you sure about that? I've never heard of institutions having to pay to meet companies.
Yep … basically what happened was institutions had to explain what they paid commission to banks for. Inadvertently through the voting process they identified company meetings as a service that brokers arranged - and therefore was paid for. Post mifid this had to split out - and excluded from execution comm. it was a mess for a while but basically if a broker organises something - say a conference - then the fund manager needs an invoice and needs to prove they paid to attend to avoid the implication that commission was used to pay. Soft comm disappeared.
Sorry - reply in wrong "box". See below re SUK2.
What is the best way to hedge a fall in FTSE100? I expect a lot more downside in the next few months. Are there any suitable ETFs or other instruments that I can use in a SIPP? TIA
3UKS or SUK2 but make SURE you know exactly what they do.
Thanks but these are not for me as they are leveraged and useful for short timeframe only. I simply want to follow the FTSE100 for say 6 months
Dicktrade has beaten me to it but I've used SUK2 before. Be careful though it can be a volatile ride!
Spreadbet short or put options (also available in spreadbet account) would be better for longer term positions than the ones listed above imo.
Whilst it's not your SIPP.... Spreadbet accounts are also 'tax-free' wrappers.
Be very careful using products such as SUK2, particularly when they are leveraged. They are only really suitable (if ever) for short term positions, ideally closing your position daily. For example, over the last year the FTSE 100 is down -2.9%. Simplistically, therefore, you would expect a holding in SUK2 to be up 5.8% over the last year, whilst, in fact, it is down -11.32%.
I feel the DAX is a great shorting chance ATM (I'm short). The DAX is not stuffed with commodity companies and I can't help thinking that Germany is really going to struggle as the ECB try to apply interest rate rises across so many different economies to tackle inflation again across so many different countries, and when it gets cold in Europe, energy prices are going to become a real problem.
I see Europe is in a very difficult situation this next six months IMHO, with Legarde saying just this morning that ECB must keep rising rates even if recession risk.
I wouldn't disagree that the FTSE 100 should come down but its a very stubborn index in these times.
https://t.co/X36m4HSUS7
Fundamentally I would agree, but the DAX has just broken out of a descending wedge on the weekly TF, I see more upside in the technicals in the short term. Of course with FOMC tomorrow things could change quickly. But I’d not be comfortable holding a weak short just now. Best of luck with it though, hope you’ve got your stops set!
Thanks Forbsy.
'I see more upside in the technicals in the short term'
If ever there was a better statement to validate looking at a shorting strategy! And yes I do agree with your analysis, as you say in the short term. There could well be a big bounce up depending on the words used by the FED and BOE this week,
Another 400 points would see the Dax at where it was pre-Covid crash. Is the current economic state of Europe worthy of such a level....I think not.
But I tend to be wrong more than am right, hence shorting with caution.
I would say that a DAX hedge against a portfolio of UK small and mid caps is my preference over a FTSE100 short (hence my reply to the original post) which has frankly left the 250 and AIM for dead, due to its weighting favouring the Ukraine situation.
With any luck my longs will soon be doing so well I can back out of my shorts. ;D
Time will Tell
I use similar strategies myself as I tend to remain cash light in stock accounts so completely get where you are coming from.
The Daily 200EMA is being tested just now (DAX40), SP500 also testing the daily 100MA….
So potential for low risk entry, I might have a small pop at it myself, thanks for mentioning it.
Nice to see some traders commenting here too.
Fwiw I agree the indices look very tempting as a short. Keep rising though! Never go against the trend...
Totally agree with you JohnDoe2378, for me I time it as a simple hedge against my longs. I have better things to do than blow my brains out with Indices betting, however in a bear market shorting is the only way to make money.
I hate shorting indices, as you need to spend so much more time watching.
Hopefully the bear will soon be over, however I fear not.
Yes, I hate having to watch screens, especially when I'm working!
But you're right, in a bear market you need to go short. There are a few shares on my short list that are rising at the moment, doubt it will continue but pure conjecture on my part!
Wise words
several major indices are approaching significant resistance such as 200dMA. With RSI at a high point which shows that It would take amazing good news for a break through (such as a universal pivot by all the CBs).
Unless there is a big pivot then the recent rally looks to be based on Hope over any real change in economic conditions and likely to fail.
I’m short on Dax and NASDAQ at present and going to increase as they get close to the resistance.
Stop loss set for a close above the 200dMA.