Small Cap Value Report (Tue 1 Oct 2019) - TND, ALT, HAT, RBG

Good evening/morning, it's Paul here.
I'll start (this bit written late Monday evening) with some catching up from stuff I was too tired to write about earlier, to get you started on Tuesday morning.
Tandem (LON:TND)
Share price: 190p (up 3% at market close)
No. shares: 5.0m
Market cap: £9.5m
(I do not currently hold this share, but have done in the past)
This group sells bicycles, mobility & leisure equipment, and toys.
The shares looked interesting earlier this year, after it reported a bumper H2 in 2018, of about £2.4m profit. Some investors thought this might be a new, higher run, rate, implying maybe £4-5m future annual profit.
That's not turned out to be the case, as H1 in 2019 reported £509k pre-exceptional profit, not the £2m+ that some imagined might be the case. Still, it's a good improvement on the -£298k loss reported in H1 of 2018.
Revenues also seem somewhat unpredictable (hence why profit goes up & down), eg.
H1 2018: £12.7m
H2 2018: £19.8m
H1 2019: £16.0m
Hence it's looking as if the bumper H2 last year might have been a bit of a one-off bumper period?
Outlook comments are quite detailed, talking about each product category. The overall picture is this;
The potential threats on the horizon that we previously alluded to remain in place. Whilst we shouldn't seek to 'blame' Brexit, we remain cautious as to the impact that it will have, should it materialise soon, with potentially uncertain future import duty rates and with regards to consumer spending which is discretionary for the type of products that we supply.
Weak sterling, and therefore a correspondingly stronger US dollar, is also likely to effect the cost of future imports.
We previously stated that the longevity and success of most licences is limited and transient. Whilst we continue to seek new, exciting and profitable properties there is no guarantee of this.
[Paul: note that Peppa Pig is mentioned, which has recently been bought out by Hasbro - how much impact could this have on Tandem?]
Despite these threats we look forward to the rest of the year with some confidence and expect to deliver a satisfactory result to our stakeholders for the full year.
Who knows what a satisfactory result would be? There doesn't seem to be any broker forecasts out there.
Tax charge - strikes me as unusually high in percentage terms. The company says;
There was a tax charge of £215,000 during the period compared to £8,000 in the prior period. This reflected the increased level of business undertaken from our Far East operations.
Investor presentation - helpfully, the company has provided this 44 page slide deck on its website today. It only took me about 10 minutes to whizz through, as most of it is pictorial, showing products.
Balance sheet - looks OK.
Net assets: £12.4m
Net tangible assets: £6.9m (after removing £5.6m of intangible assets)
Current ratio: 1.47 - looks OK
Current assets contains cash of £3.74m, up strongly from a year earlier;
Cash and cash equivalents were £3,740,000 at 30 June 2019 which compared to £957,000 at 30 June 2018. The timing of creditor payments, utilisation of invoice finance facilities and ongoing careful management of inventories helped to improve this position.
However, the narrative then refers to overall net debt, despite there apparently not being any bank debt on the balance sheet;
There was a 43% reduction in net debt from £3,508,000 at 30 June 2018 to £2,006,000 at 30 June 2019.
Therefore, I make that a £5,746k liability included within net debt. Let's try to work out what that is! Right, I've worked it out - this figure must be the total of two lines, both called "other liabilities", of £4,736k in current liabilities, plus £1,010 in non-current liabilities.
Curiosity got the better of me, so I've looked up what this debt is, in the 2018 Annual Report (note 14). It's mainly invoice discount financing, plus a mortgage on a freehold (which itself is in the books at £3.12m asset - based on a Jan 2018 external valuers report).
Investors could easily miss the debt, hence it's important to remember that the cash figure of £3.74m is only part of the picture. The company doesn't have net cash, it has net debt, of £2.0m, but I would also take into account the freehold property of £3.1m.
I feel that the company should clearly mark interest-bearing debt as being such, on the face of the balance sheet. Not just call it "other liabilities", which is not the correct description of what it actually is, and could lead to some investors missing the debt altogether. It looks as if Thomson Reuters haven't picked up on this debt, since it shows a substantially good net cash figure, which is not correct in my view. I've raised a green ticket, to have this issue looked into by the team at Stockopedia HQ & to query it with TR.
Pension deficit - also needs to be factored into valuing this share, at £2.67m.
Overall therefore, the balance sheet is not as strong as I thought it was originally, but it's perfectly adequate.
My opinion - given its tiny market cap, and balance sheet not being as strong as it initially looks, on top of profitability (with a high tax charge) that is significantly down on the last half year sequentially, I'm struggling to get excited about this.
The dividend yield is nothing to write home about either. Plus there's often a wide bid-offer spread, and the share is very illiquid. I recall it took me several attempts to sell, and had to do it piecemeal, for a smallish speculative holding that I picked up a while ago & then got bored with.
On the upside, outlook comments suggest that H2 should be OK.
In these cautious & uncertain times, I don't think it's worth getting involved again here, so I'll stay watching from the sidelines.
Altitude (LON:ALT)
Share price: 56p (up 22% at market close)
No. shares: 68.8m
Market cap: £38.5m
Altitude Group plc (AIM: ALT), the operator of a leading marketplace for personalised products, announces its unaudited results for the six months ended 30 June 2019.
This is a bit of a punter's favourite - a lot of people got clobbered by the recent profit warning.
The 5-year chart below neatly shows how the legacy business was virtually worthless, then all the excitement started in 2016 about it branching out into developing a US-based internet platform to link up end customers with promotional products companies. The idea being that there are numerous mom & pop companies in the promotional products sector, with a big gap in the market for a tech platform that enables them to easily create personalised websites for their clients.
As you can see from the chart, the jam tomorrow bubble burst recently. Although I'm taking a look today, because there's been a 22% rebound upwards today in the share price, so maybe people are starting to get interested again?

The financial highlights show some progress, although bear in mind it made an acquisition in Jan 2019, which will have fed into most of this 6 months P&L numbers;
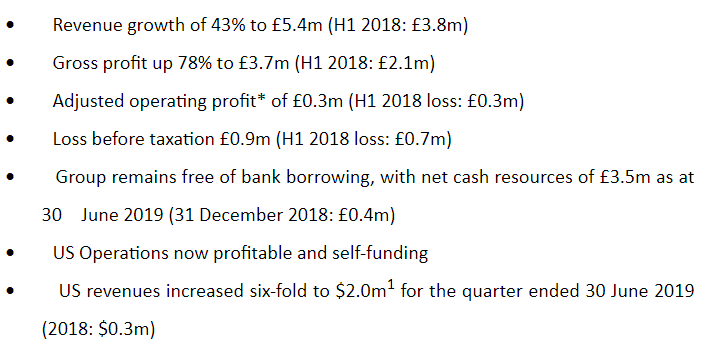
I like the comment about being self-funding, which reduces the risk of further dilution.
High gross margin, and breaking into a small operating profit, also look reassuring.
Balance sheet - looks sound.
There's £3.5m of cash, and no debt.
Cashflow statement - it funded the acquisition of AI Mastermind LLC, and other outflows, with a £9.1m placing. This also left enough left over to boost the cash position (very sensible).
Outlook - management remains very excited about the potential, whilst admitting that growth to date hasn't been as fast as originally expected.
My opinion - I can't really take it any further than that, because the valuation rests entirely on future growth actually happening, and fast enough to get everyone excited again.
Given that, so far, results have disappointed, and broker forecasts have been wildly too optimistic, then there is a bit of a credibility problem.
On the upside, it's completely normal for rapid growth companies to over-egg the pudding early on. Growth companies nearly always take longer & cost more money, to achieve success - often years later than originally planned (look at CloudCall, for goodness sake!)
Therefore investors have to work out whether they think Altitude is a dud, or whether this year's profit warning was just a bump in a road which could still take them to sunny uplands? I've got absolutely no idea what the outcome is likely to be.
Having said that, I'd be much happier taking a punt on this at the current c.£40m valuation, than when it was approaching £100m market cap not long ago (which on reflection was crazy, given that it had only just started to generate revenues from the new activity).
I wouldn't rule this out as something I'd be prepared to take a punt on, now that the share price has come down to a more realistic level, given the early stage nature of what it's trying to do.
H & T (LON:HAT)
See the comments section below (no.2) for my thoughts on the positive RNS from this pawnbroker (increasingly looking like the last man standing) re current trading, and acquiring pledge books from a bust competitor.
Good, that's Monday's backlog sorted out.
Tuesday is set to be dominated by results/outlook from Revolution Bars (LON:RBG) (in which I have a personal holding), and a meeting with management in the afternoon. So I need to be really well prepared for that, so apologies in advance if it pushes other things onto the back-burner. I'm writing all of this week's reports, so I can always catch up on other stuff later in the week, and in the evenings, etc.
Revolution Bars (LON:RBG)
Share price: 67.4p (down c. 3% today, at 13:13)
No. shares: 50.0m
Market cap: £33.7m
(at the time of writing, I hold a long position in this share)
Revolution Bars Group plc ("the Group"), a leading UK operator of 77 premium bars, trading under the Revolution and Revolución de Cuba brands, today announces its results for the 52 weeks ended 29 June 2019.
I read the RNS first thing, between 7-8 am, and thought it looks encouraging. We already knew that the results for FY 06/2019 would be in line with market expectations, because the company would have had to put out a profit warning if that had not been the case (as it did in June 2017).
Therefore, the key issue to affect the share price, is the current trading & outlook sections.
I had a range of scenarios in my mind;
- Upside case - LFL sales turning significantly positive in current trading
- Middle case - continuation of last year's slightly negative LFL sales
- Downside case - a further deterioration in LFL sales
As things turned out, we're somewhere between the upside & the middle case, which I find moderately encouraging, for a turnaround situation, on a completely bombed out share price. The actions being taken by management are working, but not yet enough to put out any bunting.
Here are the main points the way I see things;
Improving sales trend - absolutely key. LFLs have improved from -4.0% in H1, to -1.8% by Q4, and now in the new year, Q1 was positive, at +1.2% (the most relevant figure, which strips out the impact of days when refurbishments were being carried out). This should have triggered a bounce in the share price, but so far it hasn't, as so few shares have actually traded (only 110k today so far, at the time of writing).
What went wrong? The main reasons for RBG's under-performance last year are these below, and I've added in brackets what management is doing to fix things;
- Older sites had become tired, and were suffering because they looked tatty. Previous management had concentrated on new site openings, neglecting to keep older sites up to standard, causing them to see sales declines & staff departures for smarter competitors. [Remedy - sites are now being rapidly refurbished, which costs c.£200k per site. New site openings have stopped for now, to allow a focus on improving performance of existing sites]
- Brain drain - key staff (e.g. area managers, accounts, and some top site managers) were poached by competitors, causing a deterioration in trading in some sites. [Remedy - recruiting, training & retaining good staff]
- Takeover activity - dragged on for a long time, resulting in a recommended cash bid at 203p (which with hindsight shareholders should have accepted), thus putting further strain on the previous management, affecting day-to-day operations. [The Stonegate bid fell through, so new management has been able to focus on running the business]
- Own goals with the food menu - a (since departed) Food Director made a complete hash of things, ditching best sellers for a fancy new menu that flopped. [New menu brought back the old best sellers]
I won't regurgitate all the detail from the commentary in today's RNS, but it strikes me that management is making reasonable progress, and doing the right things to fix the business. An example;
Refurbishments - this is the number one priority, and a virtually guaranteed way to improve performance of struggling, tired, sites. They cost an average of about £200k, which is a lot cheaper than initial fit outs for new sites, which are c.£1m.
Therefore with no new sites opening in this financial year, just refurbs, we should see the capex figure drop significantly. Hence free cashflow should improve considerably in FY 06/2020, enabling debt reduction (which is not high anyway).
Net debt at period end was £14.9 million (2018: £11.5 million) after capital investments of £11.6 million
Adjusted EBITDA was in line with expectations, at £11.1m. Therefore net debt/adj EBITDA is only 1.3 - this is not a problem level at all. Banks are usually happy up to about 2.5 to 3 times, sometimes more.
The going concern note 1(b) just looks like a formality, and is not a worry to me - it outlines the bank facility, concluding that there is ample headroom. We often see such going concern notes - it's only a problem if there is something worrying in there, which there is not here. Such a strongly cash generative business should have no problem at all renewing its bank facilities in due course, at a lower level. It also confirms actual & expected compliance with bank covenants.
... The Group continues to be very cash generative pre expansionary capital expenditure, has ample headroom on its facility to cover working capital and seasonal cash flow needs and can potentially cover a significant reduction in trading performance relative to the current sales trend.
The Directors have reviewed the Group's trading forecast, which demonstrate that the Group has adequate financial resources to continue in operational existence for at least 12 months from the date of approval of the financial statements and to remain compliant with the terms of the revolving credit facility and the financial covenants (tested quarterly) attached to it. For this reason, the Directors continue to adopt the going concern basis in preparing the consolidated financial information.
Site EBITDA - this is a very revealing table;
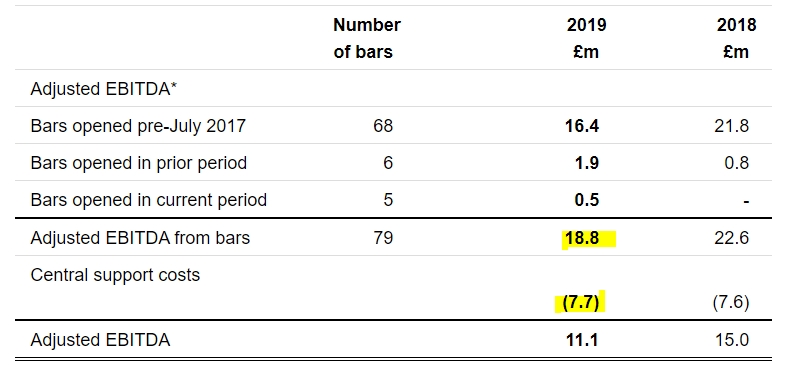
These are the figures that an acquirer would focus on, when putting together a bid. The bars are generating positive EBITDA of £18.8m - this is a remarkable figure, for a business valued at only £33.7m - in other words, the stock market is only valuing RBG at 1.8 times the annual cash profit made by its bars.
We need to adjust for maintenance capex, but even then the multiple would still be less than 3 times. That's astonishingly cheap, and I think it only a matter of time before RBG once again attracts bid interest.
Look at it another way - how long, and how much money would it cost, to build a similar business from scratch? Typical capex per site is £1m, hence for 79 bars, you would be talking several years to do it, at a cost of about £79m or 158p per share.
Sites make an average of £238k p.a. positive EBITDA - and bear in mind that figure will be suppressed by the problem sites - there seem to be 11 of them, looking at note 3 on onerous leases.
Central costs look far too high, at £7.7m - an acquirer would look to strip out a lot of that, hence why site EBITDA is the key number to a potential acquirer of RBG.
IFRS 16 - this new accounting standard is playing havoc with accounts, and I find it extremely unhelpful. It adds nothing to my understanding of accounts, just confuses things. The core issue is that if a site is trading profitably, then the lease commitments don't matter! It's only loss making sites which are a problem. Indeed, I would prefer RBG to have longer lease terms on its most profitable sites, which bizarrely would lead to larger liabilities on the balance sheet.
As noted in the narrative today, IFRS 16 is expected to have a big impact on the balance sheet. This has no operational effect at all, of course, so I suspect investors are just likely to ignore it, pending IFRS 16 hopefully being repealed in the not too distant future, for the nonsense that it is;
For the lease commitments, the Group expects to recognise right-of-use assets of approximately £85.5 million on 30 June 2019, and lease liabilities of £122.7 million (after adjustments for prepayments and accrued lease payments recognised as at 29 June 2019). Overall, the net assets will be approximately £23.5 million lower, and net current assets will be approximately £7.3 million lower due to the presentation of a portion of the liability as a current liability.
My opinion - I'm encouraged by this update. Signs of the turnaround beginning to work are clear, in improved LFL sales in Q1 of +1.2%. Once more sites are refurbished, that figure should rise. Forward bookings for Xmas are strong, and the outlook comments are good.
I'm not saying this is the best business on the market. What I'm specifically saying, is that the shares are obviously under-priced. Therefore it's the type of investment where I'll happily hold, as the turnaround is now visibly working. Sooner or later that is likely to either attract another takeover bid, or a re-rating of the shares. It's just a question of being patient.
I'm meeting RBG management at 4pm today, so have to prepare some intelligent questions for that meeting now. So I'll sign off here for now, and will put any further thoughts into tomorrow's placeholder, and will catch up on other company announcements tonight/tomorrow.
Here is the slide deck from RBG's website that mgt will be presenting to me & another investor today, plus of course no doubt they have lots of other meetings lined up with institutions.
Slide 4 is particularly revealing, showing a very good improvement in monthly LFL sales performance, versus wet-led pubs sector;
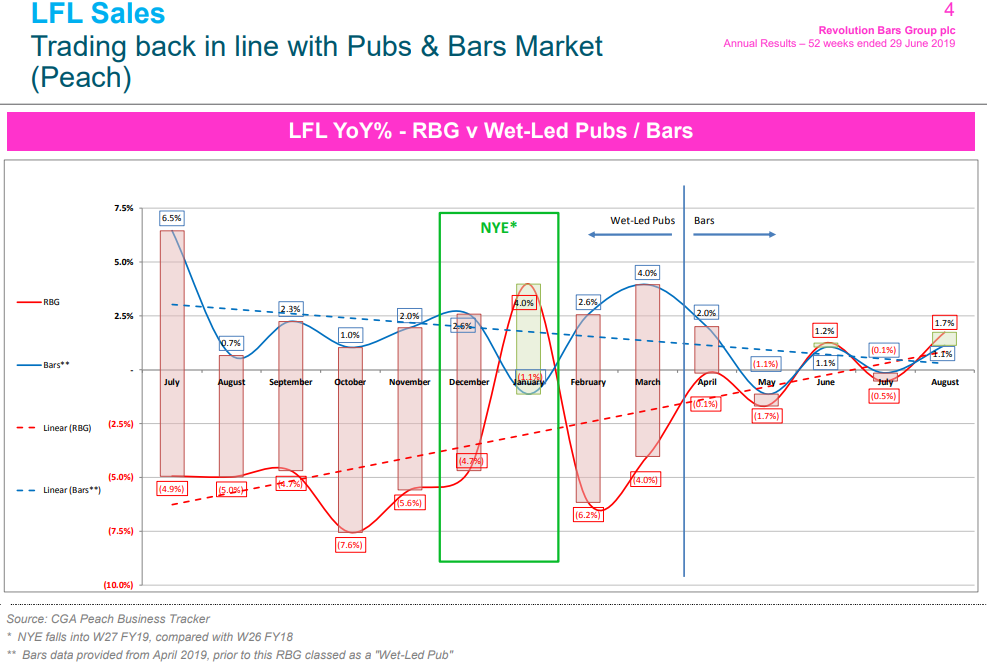
It's not the easiest chart to understand, but it's worth taking a little while to work it out.
Also, slides 18 & 19 look very good - giving detailed information on the refurb programme, and operational improvements.
I have to stop here for today, to get into the City for my RBG meeting.
I'll put further thoughts into tomorrow's placeholder article this evening.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Whilst only now a former Revolution Bars (LON:RBG) holder, have just read all the comments/commentary on it. I feel compelled to say what high quality all the input is and has certainly helped me, without actually having to read the RNS, to know the sidelines is the right place for me to be.
The only contribution I can make to the debate is a small piece of scuttlebutt. As I understand it from the cool kids I know, the bars are no longer fashionable to visit as there are generally better/more hip alternatives. This seems a very big hurdle to overcome in the long run for a destination led estate. Nevertheless, good luck to all holders.
Cheers,
Paul
Paul,
I went through the analyst deck you referenced this pm & saw this (slide 24 in Appendix):
"The average lease length is 27.0 years, with 14.2 years remaining at FY19 period-end"
Did mgt give any insight into whether this includes any of the 11 'impaired' bars. Presumably, (I hope) these are mostly older, smaller bars from the earlier days.
Does this also mean the big new bars are being taken on leases of 30 years! Any comment on this given the volatile nature of the high street/property these days. Would such leases be inflation linked or with exit breaks after XX years?
Gromley,
Thanks for the H & T (LON:HAT) loan book info.
Looks to be a -40% purchase to book, which sounds good. Would be interesting to know how much the £14M A & B loan book was as a % of the current H & T (LON:HAT) loan book, to give an idea the relevance of the H & T purchase?
H&T's Pawnbroking pledge book was roughly £50m I think, so it is relatively material.
One thing to bear in mind in terms of the discount to value is that as I read it H&T are taking on the cost of redistributing all of the pledged items back to local branches (or direct to customer). I cannot imagine that they have an existing logistics operation to ship valuable items around the country as they normally stay put. I have no way to guess what the cost may be.
If H&T is anything like Ramsdens they already have a logistics operation which maintains retail stock for sale in branch from centrally sorted and stored quality jewllery made up of pawned items not collected/paid up, sent in from the branches. So in effect albeit the branch pawn book is operated at branch level the retail operation is managed centrally.
Thanks Laney, you might be right, but I had presumed that pledged items stay in the 'home store'.
Anyway, whatever the practicalities, I would be uncomfortable to assume that the gap between the book value of the loan book and the price paid is pure gain. I cannot believe H&T were the only offerers to take over the book, so there must have been at least some degree of proper 'price discovery'.
For those who follow the Stockranks system there is an interesting point that can be observed today in the ranking of Crimson Tide (LON:TIDE)
The category of "Falling Star" is given when the comparison is "vs European peers", but on the comparison "vs Global Peers" it rises to be a "High Flier". These categories are so diametrically different that it endorses my view that these rankings need to be treated with considerable caution.
Paul commented on the Albermarle & Bond 118 pledge book purchase by H & T (LON:HAT), calculating the pledge books to have cost £71K each. This seems very cheap, but does anyone with industry knowledge or broker info know what a typical pledge book might be worth?
Of course there is also the aspect of the acquisition of thousands of ex A & B customers who will tend to migrate to H and T going forward?
I presume that would depend on the size and catchment area of each store Ian?
However from companies house (speedloan finance) that as of March this the customer loan book was £14m. I guess the number could be seasonal, but that is probably a decent benchmark of what H & T (LON:HAT) bought for £8m.
Although I note they bought 113 pledge books, but other reports suggest that A&B had 116 stores - so I'm not sure what happened to the others.
Revolution Bars (LON:RBG)
I have checked the annual report and the receivables total includes prepayments - and this is the vast majority of the total - being £8.2 million per last years annual report. I am guessing this is mostly prepaid rent.
For completeness other stuff in receivables will include supplier rebates due - i am guessing with regard to card sales - i am guessing its likely to be approximately 2-3 days sales not banked and therefore added to receivables
Note with regard to rent/other prepayments , its not easy/possible to turn this into cash without shutting up shop , so on a cash crunch worst case scenario that's not really going to provide any liquidity help if they need to pimp their assets and find some extra cash.
One of the things I dislike about Revolution Bars (LON:RBG) is the level of uncertainty over what is actually going on.
First there are the openings and closures.
Then the impairments/capitalised refurbishments.
Then knowing exactly how good their estate is looking.
And the prepayments and lease terms.
Not forgetting the question in my mind now about how exactly card payments are processed. Cash too I suppose.
I've never seen any reason to simply trust the management. I suppose I'd really like to see the income/expenditure per branch on a daily basis from signing the lease to termination or now. I'd like to believe their management accounts would allow them to do this, but somehow I doubt it. It's only when you have absorbed the typical patterns from such details that you know how to watch for risks or significant change in trends.
Revolution Bars (LON:RBG) - this is a share I exited nearer 200p but have watched subsequently. I noticed a bit of activity in recent days and was ready to re-enter on good results and perhaps a rise to 80p, This is not to be. There is a loss of £5.6M (10.4p per share) after impairment charges of £7.1M. Ignoring EBITDA, etc the figure I look at is the £5.6M loss because I can see either impairment charges or capitalised refurbishments being an annual figure even if not of this amount.. It is the nature of this business that bars have to be upgraded on a regular basis to prevent trade being lost to the latest "in" venue and the company eventually needs profits adequate to cover such costs.
What puzzles me is the trade receivables. As already mentioned by rmillaree in his excellent summary they are £12M being equivalent to 76 days sales. Does anyone have any idea how a chain of bars can have this sort of figure due to them?
Bear in mind this figure includes prepayments and accrued income, not just physical cash owed to them at year end.
If you look at the last annual report the vast majority of the receivables (around two thirds) related to "prepayments relating to property rent and rates". Most of the rest relates to uncleared credit and debit card transactions.
The Revolution Bars (LON:RBG) Trade receivables are £12.2m and Sales are £151.4m
So (12.2 * 365) / 151.4 = 29 days
By way of comparison, the J D Wetherspoon (LON:JDW) Trade receivables are £21.9m and Sales are £1818.8m
So (21.9 * 365) / 1818.8 = 4 days
Clearly an anomaly - maybe J D Wetherspoon (LON:JDW) customers mostly pay with cash, Revolution Bars (LON:RBG) maybe pay mostly with plastic?
"maybe J D Wetherspoon (LON:JDW) customers mostly pay with cash, Revolution Bars (LON:RBG) maybe pay mostly with plastic?"
Don't believe it. J D Wetherspoon (LON:JDW) cash proportion may be higher, but there will be a lot of card payments too. Many people don't ever carry much cash.
Revolution Bars (LON:RBG) - yes, you are right with the sales. Not sure where I got my figure from. Must be going cross-eyed.
When my son had a business taking credit cards the money landed in his account right away so I am not sure much of the debtors would relate to this. However, Bestace mentions prepayments and I can imagine rents paid in advance could take up a tidy sum. In that event while it is obviously an important figure to bring into the accounts it is not something that will become available to pay the creditors.
£RBG - Ship is turning but far more slowly than I would wish. LFL turned positive in Q1 (presumably why this report was later than last year!) but this is vs a very soft base; I had hoped for more of a LFL rebound vs alleged perfect storm of weather/World Cup etc.
More positively, Mgt seem much more in control of detail than before (monitoring energy consumption, effective staff costs cut by scheduling ie wages/costs by venue up by more than wage bill. Operational improvements like refurbs and lower prices/better value drinks and esp. food take time to be noticed. Good also that 2 weak bars closed post reporting period whilst the new bars are doing OK.
But probably the most critical part of 'stabilisation' was commentary around the more 'settled' operational team (at bar level) as this remains key. Fortunately, CEO recognises this. In the Outlook section, he says (my emphasis)
Our key priorities for the year ahead are to;
· Invest in our team
· Invest in our brand & guest experience
· Invest in our estate
As Stocko readers, we probably all love our numbers. However, Pitcher is right, especially in hospitality, it is people who drive results. Happy, locally well-led bars become magnets, get repeat custom and make money (if operated within a well managed financial frame).
As a non-trader, from here I am happy to hold for the medium term but expect only modest share price recovery in the short term in a very tough ("No deal" ?!) environment and thus no dividends . Opportunity cost of holding is probably my biggest concern.
Re Revolution Bars (LON:RBG) the LfL definition is going to exclude a large chunk of the estate ...
**Like-for-like (LFL) sales are defined as total retail sales from bars that have traded throughout both the current and prior reporting periods.
Revolution Bars (LON:RBG)
Very mixed bag - good news that profit on sites opened previous period picking up nicely and trend in sales is in the right direction albeit only modestly positive due to poor prior trend being so weak. The bad bit is probably historical in that the balance sheet has continued to materially weaken - that should not be a surprise.
Ok lets cut to the chase and look at the business solvency - this is a loss making company with material debt and material other liabilities.
operating Cashflow of £8 mill this is the figure before they pimp it up with working capital changes. Lets knock off £0.5 mill for future taxes if they will deliver long term profit £7.5 mill
This is before interest paid of £0.75 mill and spending on property plant & equip - whats the average the need to spend on average per unit per year to have a maintained estate - strewth tricky question. I would say £60k a year would seem probably bottom dollar if you include kitouts of the odd new location to replace venues that close
With 79 venues thats £4.75 mill
Leaving £2 mill per year safety net - so enough to keep their heads above water. If you up capital costs to £90k per year per outlet then the £2 mill is gone.
Note cashflow this year is much worse than the above calcs as they spent £11.6 mill on capital items - with no/less new openings hopefully cashflow will be now in the right direction. also no dividends due.
Good news on quality is that the newcastle Revolution De Cuba Newcastle appears to be number one on trip advisor in its sector - so top marks there.
Balance sheet is all about the payables - it just takes one line in the payables section to want their money back now for things to get twitchy.
Note trade and other receivables is high at £12 mill - strange.
add on 2.6 mill cash and that's potentially £14.6 mill on the plus side - although i ma guessing they can't get their hands on the payables amount sooner?
owed out £24.9 mill trade and other current payables (up 2 mill)
add £17.5 mill of debt non current.
Thats £42.4 mill owed out !!!
there is other stuff too that i will handily ignore (3 mill of rent free creditor presumably being non cash item - it may be generous ignoring this line item?)
Note if we wind the clock back to 2017
trade receivables and cash was £13.6 mill
payables and loan totals (incl tax at that time) was only £29.1 mill - so in two years they have increased what they owe by £13 mill whilst profits have vanished
As they owe out £40 mill + to bods who will want paying - i would not be entirely comfortable owning shares at present with this level of liabilities and the current level of cash it is producing. For me to want to re-invest i would want to see the cashflow generation above £5 per year so they can ensure the balance sheet gets back to its former solid base.
Hopefully the sound formats they have of Revolution and De Cuba will allow them to get back on track, i don't see anything wrong in the bars themselves - the opposite actually these should be cash making machines based on the venues i have visited
The thing that saved me from getting involved with RBG in the first place was reading their Tripadvisor reviews and deciding that many were not genuine customer reviews but were posted by friends or family of staff etc.
Reading the Newcastle reviews you mention I see many 5 star reviews for the cocktail masterclasses from users with no previous posting history. So I would take a pinch of salt from the margaritas with that.
Revolution Bars (LON:RBG)
I see many 5 star reviews for the cocktail masterclasses from users with no previous posting history.
Good point John
also a few of them liked it so much they left 2 reviews saying much the same thing. Perhaps it was so good they reviewed as soon as they got home - woke up remembered it was so good but forgot they did the review and then did the review again.
I would say with freshers perhaps we shouldn't expect that they have a large posting history.
Perhaps i need to get myself to the next masterclass to investigate further?
Thanks for your thoughts on Revolution Bars (LON:RBG)
As a holder I thought I would throw in a few more (biased?) comments:
First, some assumptions:
Now onto cash flow AFTER maintenance CAPEX = c£7m
(best highlighted in today's presentation)
Average spend on refurbishing the 8 sites in 2018/19 was c£175k (£1,4m in total)
15 sites are planned for refurbishment in 2019/20, so an additional £1.2m expenditure expected, which effectively cancels out the £1m annualised savings the company says it will make this coming year.
In other words Cash generation should, at the very least, be maintained at around £7m per year
For a more conservative estimate, to account for working capital movements, let's assume that this figure might fall to c£6m per year.
Finally there are 2 things I would consider when assessing whether the shares are worth buying:
I was hoping for more today, but will continue to hold with a medium term view in mind as I think the company is moving in the right direction and continues to look good value.
Cheers
A
Revolution Bars (LON:RBG)
abtan
Thanks for adding the figures from the presentation this adds some useful extra detail.
I think one adjustment you need to your calcs is for the finance costs which i think are an after the line adjustment so that will reduce the free cash ledt by approx 0.75 mill?
i would be wary about cost savings resulting in matched higher profits - can't remember the last time a company said following year profits were up £1 mill and that was all due to previously announced cost savings. It is a fact wage inflation at present may be an ongoing issue - even the current bods in charge all of a sudden want to please the millenial workers by offering higher wages £10.50 an hour mentioned in the last 24 hours - the current bods will end up left of "new" labour (blair) if they aren't careful (or there already)
I guess?? the remainder of the difference in our figures is probably down to my figures not specifically adjusting out for p&l related opening costs that may not repeat when openings cease- so cash flow may very well be closer to your estimate than mine happy days :) -so many different measurements my head is done in - lets have a look in 6-12 months and see how this pans out. Perhaps some broker updates will hopefully confirm the debt reduction plans / cashflow estimates.
Solid but uninspiring results from James Halstead (LON:JHD) this morning.
I feel they're doing a creditable job in the face of low confidence and sluggish economies. Hopefully there's some pent up demand that will unleash some proper growth at some point.
SCS (LON:SCS)
Small improvements in Sales, Revenue and EBITDA, Underlying operating profit up 4.6% and underlying EPS up 13.1%.
Cash up from £48.2m to £57.7m, no debt, (MCap is £95m).
All looks solid, but FY20 hasn't started so well:
Whilst it is still very early in the new financial year, the Group has had a more challenging start to FY20, with like-for-like order intake falling 7.6% for the period from 28 July 2019 to 29 September 2019. On a two year basis, like-for-like order intake was down 3.0%. The period has been impacted by the record temperatures seen over the key August bank holiday weekend and the increased political and economic uncertainty that the UK is currently facing.
Re SCS - started writing a response to you (WillBarraclough) and then it long so made it a post....
https://www.stockopedia.com/content/scs-waiting-for-godot-la-z-boy-edit-518151/
My morning smallcap tweet: Dull day.
Crimson Tide (LON:TIDE), Fulcrum Utility Services (LON:FCRM), Manolete Partners (LON:MANO), Revolution Bars (LON:RBG)
Crimson Tide (TIDE) wins 'significant' £1.4m contract over 3 years for mpro5.
Fulcrum Utility Services (FCRM) CEO scarpers. He is thanked.
Manolete Partners (MANO) CFO leaving end Dec. He is thanked.
Revolution Bars (RBG) FY in line. Q1 trading: LFL turns positive at +0.7% cf Q4 -1.8%. Welcome news for a serial disappointer but the whole sector is doing better.
With thanks and credit to jonno for his post late(ish) on Monday :-
After the market closed H & T (LON:HAT) announced the acquisition of 113 pledge books from Albemarle and Bond (Speedloan Fiance Ltd) for £8m funded from cash and existing bank facilities. The acquisition is scheduled to complete on 7th October.
I hold £HAT (and it pays 4.7p divi on Friday - that should cover Mrs Willwilb's Bombay Saphire for a month or two!)
Would appreciate your thoughts.
Hi willwilb,
Thanks for the prompt. I've taken a quick look at the trading update & pledge book acquisition by H & T (LON:HAT) , and it sounds good. Hence expect a strong price rise in the share price on Tuesday (as this was announced after hours);
The acquisition for £8m of 113 pledge books from (bust) Albermarle & Bond shops, works out at about £71k per site. I don't know how that compares with the usual level?
The key information which is not given in the RNS, is what discount to book value the acquisition has been priced at? Given that it moved fast, and could even have been the only credible buyer, then HAT should have been able to negotiate a deep discount to par on this pledge book.
Overall, for me, this whole sector is too grubby. I wouldn't want to hold shares in any company that takes advantage (with extortionate priced debt) of desperate, poor people, and pays out the profits to affluent people.
Regards, Paul.
Many thanks. I fancy we both need some sleep!