Small Cap Value Report (Tue 10 Apr 2018) - D4T4, TMMG

Good morning, it's Paul here!
Let's hope the technical gremlins at LSE have been fixed, and that we get our 7am announcements on time today, instead of nearly 1.5 hours late yesterday. I don't understand why the market opened, given that the news feed was not working properly. They should have suspended market trading until full information had been released (and given us an hour to read the news).
Let's hope small caps continue perking up - there have been some good rebounds already in oversold small caps, which is pleasing. I'm certainly rummaging around for bargains at the moment. In a way I enjoy market sell-offs, as the good shares tend to be thrown out with the bad, thus creating some buying opportunities in stocks that I'd like to hold, but declined to pay the lofty prices being demanded late last year.
I'm wondering if some selling might have been tax year end related? After all, if a share is showing a hefty loss, then ditching it before the tax year end reduces our tax charge on other, profitable disposals during the year.
Mello Derby, 26-27 April
Not long to go now, for this terrific event - organised by investors (David Stredder & his team), for investors. There are no spivvy junior resource stocks at this event, just good quality small caps that want to meet investors. Plus, an outstanding line-up of speakers.
I can't stress enough what a great community feel that David's Mello events have. Being smaller than the London conferences, they attract serious investors, who are prepared to pay a modest entry fee. This gives excellent access to companies & management, and will also greatly broaden your social network of sensible investors, if you hang out in the bar after hours especially!
Anyway, do come along if you can, it's going to be brilliant. Graham & I will be there, and are really looking forward to meeting more readers & comments contributors from here.
D4T4
Share price: 132.5p (up 23.8% today, at 12:31)
No. shares: 38.0m
Market cap: £50.4m
Trading update & contract wins
D4t4 Solutions Plc (AIM: D4T4), the AIM-listed data solutions provider...
The company is today updating us on performance for the year ended 31 Mar 2018.
To refresh our memories, here is my review on 22 Feb 2018. The key issue then was that the company's performance in H1 was poor, hence the full year forecasts looked a very tall order. So there seemed to be a high risk of a full year profit warning. The share price fell back a considerable amount, to factor in these worries.
As you can see from the sharp rebound in share price today, the market is relieved at what sounds like a reassuring update. However, I'm not entirely happy with the wording of this key sentence, as it side-steps reporting on trading versus market expectations, which is they key information. Instead, the company says it will beat prior year comparatives, which of course is not the same as beating market expectations.
The Company is in the process of its year end close and intends to provide a more detailed update on financial performance on 23 April 2018, in advance of this, the Directors are confident that the revenue and adjusted* profit before tax will be ahead of the comparatives for the year ended 31 March 2017.
This is annoying, because it now wastes everyone's time, by forcing us to look up prior year results, and compare them with current year forecasts.
Last year's adjusted PBT was £4.22m, with adjusted EPS of 9.97p.
Stockopedia is showing broker forecast of 10.1p EPS (which is usually calculated on an adjusted basis). So, it seems to be the case that the company has likely achieved market expectations. So why didn't they just say so?
As there is limited broker information now, post MiFID II, I usually check broker forecasts to other sources. Reuters own website shows consensus of 9.6p, which is strange as Thomson Reuters provide the data to Stockopedia, hence why their figures are usually the same as the ones here.
A house broker note issued today seems to imply that the 10.1p EPS forecast has been achieved, and has a positive tone. So the very strong H2 which management promised, does seem to have been delivered. Kudos to management, as that doesn't often happen - a very toppy H2 forecast is usually followed by a profit warning, but not in this case.
Recent contract wins saved the day, in terms of the year just ended, but also sounds like they provide a good start to the new financial year;
... delighted to announce that having secured a number of high quality contracts in the last quarter of its financial year ended 31 March 2018 (further details of which are set out below) it expects to report a very strong trading performance for the second half of the year alongside a record level of bookings, which underpins the Board's confidence for financial performance in the current financial year ending 31 March 2019.
That's all great, but to my mind it also highlights the problems when investing in small software companies - they're so dependent on high margin contract wins, that financial performance is almost impossible to predict with any degree of confidence. Therefore, profit warnings, and volatile share prices, seem a higher risk. You can't really sleep easily when holding this type of share.
My opinion - given that the year just ended turned out OK, this share might be worth a closer look perhaps? The PER seems reasonable (about 12-13), the balance sheet is satisfactory, and there's a dividend too.
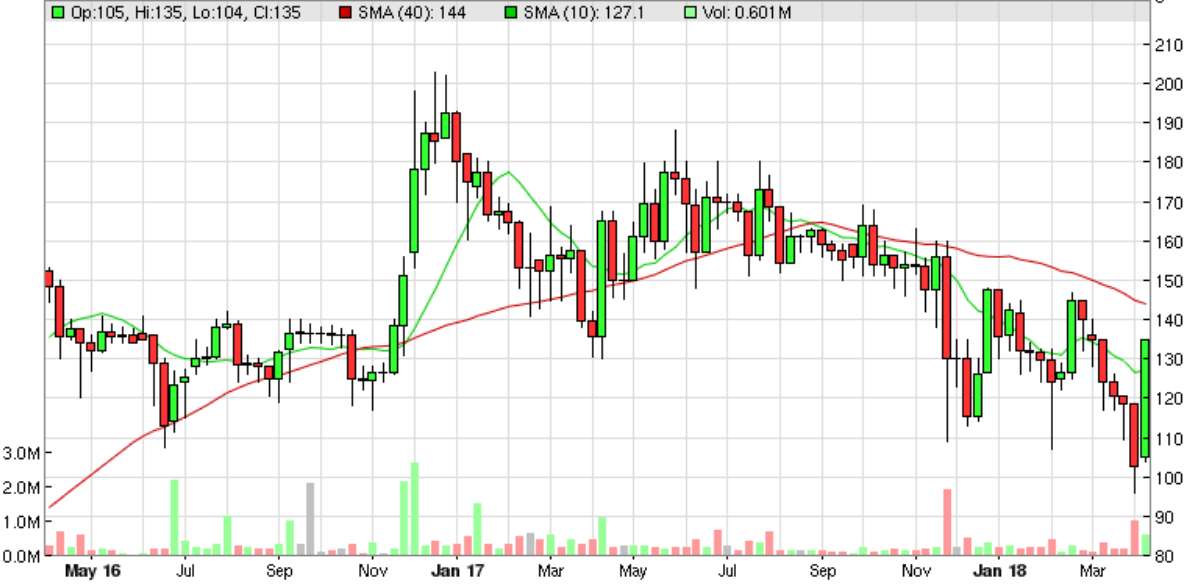
The inherent unpredictability about performance worries me too much to want to buy any shares in it. Also, without having done any detailed research on its product, or competitors, I don't know how to assess it. Note also that the share price hasn't really gone anywhere overall in the last 2 years;
Mission Marketing (LON:TMMG)
Share price: 48.5p (up 6.6% today, at 13:18)
No. shares: 84.1m
Market cap: £40.8m
(for the avoidance of doubt, I no longer hold any position in this share)
... the technology-embraced marketing communications and advertising group...
Acquisition - of a London-based creative agency, called Krow. The initial consideration is only £2.75m, which looks a great deal at first sight, for a business with an impressive client list, which made an underlying profit of £1.0m for y/e 31 Dec 2017.
However, there's a sting in the tail - contingent consideration, based on performance targets, of up to an additional £11.75m. That strikes me as very high, relative to the size of the group. There's a risk that could backfire, in the event that Krow performs brilliantly, triggers a big payout, then the economy goes into recession. So I think shareholders probably need to think carefully about acquisition-related potential liabilities, and whether the group might be over-stretching itself, and building up potential future problems again?
Audited results - for the year ended 31 Dec 2017.
The headlines look good. Although it's not clear how much growth is organic, and how much from acquisitions? Actually, scrub that, I've just found the figures buried in the narrative;
Within our primary activity of Advertising & Digital Marketing, revenue growth was 8%, representing like-for-like growth of 5.4% and a first contribution from RJW.
Also note that the adjustments make quite a big difference to headline, and reported profits - you always get this type of thing with PR companies - they seemingly can't resist the temptation to buff up their own results, as well as their clients'!
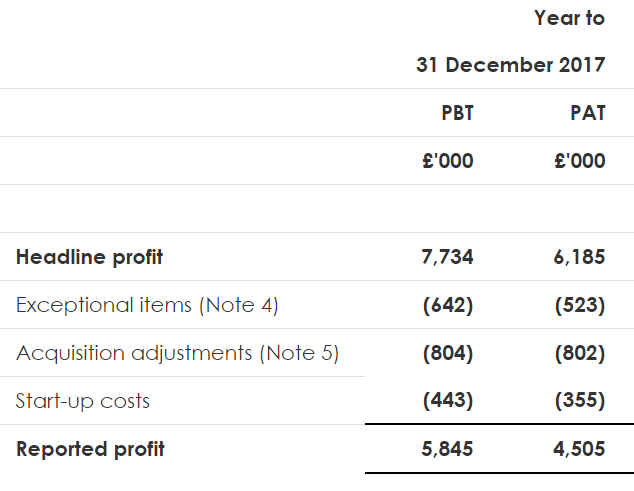
I'm not convinced that the £642k exceptional items really are exceptional. This type of group is always restructuring in some way, so this type of cost seems to recur every year;
Exceptional costs in 2017 comprised settlement costs to former Director Chris Goodwin and also amounts payable for loss of office and other costs incurred relating to the restructuring of certain operations in order to streamline activities and underpin the Board's growth expectations.
The £804k acquisition adjustments shown above relate mainly to amortisation, so I'm happy with the group's treatment of that.
Client retention - this stands out as impressive;
... almost 20% of our revenue again being generated from Clients that have been with us for 20 years or more. As we have mentioned before, the Board believes this Client retention statistic is second to none in the marketing services sector.
PR is notorious for having high customer churn, so it looks as if TMMG is doing something right, to retain some clients for that long.
Outlook - sounds good;
Trading in the first quarter of 2018 was ahead of last year and current indications are that prospects for organic growth are good despite the backdrop of economic uncertainty.
Added to that, we will benefit from the contribution of newly-acquired Krow Communications, announced today, and we also expect to see an improvement in margins as our various initiatives kick in.
All in all, we expect 2018 to be a year of strong growth.
Valuation - it looks cheap on a PER basis, but always has done - this seems a permanently lowly rated share. I'm not entirely sure why, but there we are.
Headline diluted EPS was 7.12p, which came in ahead of broker consensus shown on Stockopedia of 7.0p, and equates to a PER of 6.8.
Dividends - up 13% to 1.7p for the full year, a yield of 3.5%.
Balance sheet - here are my usual quick checks;
NAV: £80.15m - the balance sheet is extremely top-heavy, with acquisition-related intangibles of £87.95m.
NTAV: negative, at -£7.8m - I don't usually invest in companies with negative NTAV.
Cash of £5.9m , less bank debt of £13.1m, gives net debt of £7.2m. We should also include another £7.2m of acquisition-related obligations within debt, which would take the total net debt to £14.4m. That's a bit too high for comfort, in my view. There will also be potentially considerably more acquisition earn-outs, if Krow performs well.
Overall then, to my mind, this balance sheet is looking stretched. That may not matter when trading is going well. However, marketing budgets are the first thing to be slashed in an economic downturn. So the risk is that, when the next recession kicks in, this group could end up in a precarious position, with reduced earnings, and rather too much debt.
My opinion - the sun is shining, in terms of current trading, so everything looks fine, and the shares look cheap on a PER basis.
However, if I were the Chairman here (unlikely, we can all agree!), I'd be telling management to cool it on the acquisitions, and let the balance sheet strengthen into a positive net tangible asset position, so that the group is in a stronger position to weather the next economic downturn, whenever that comes along.
PR/marketing companies can be horribly cyclical, hence balance sheet protection is probably more important here than in other sectors. Hence, on balance, I'd say that the modest PER here is probably a sensible assessment of the risks by the stock market.
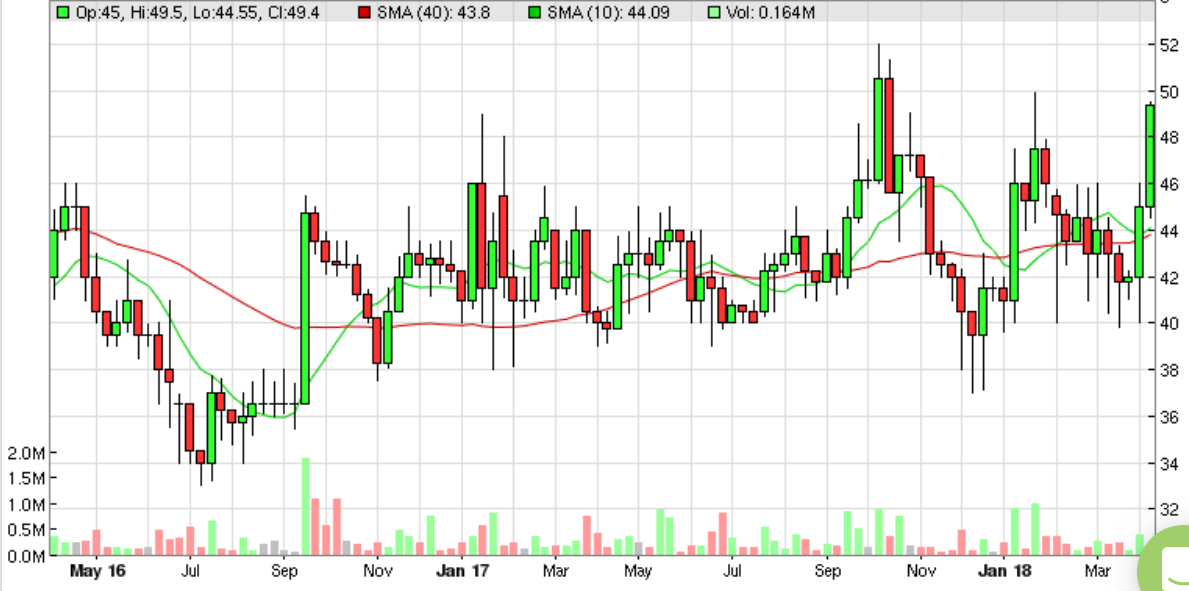
Another aspect to consider, is that, like many small caps, this is a very illiquid share. Therefore, whenever there is any buying interest from new investors, it tends to be readily supplied by existing investors who are high & dry. This leads to repeated snuffing-out of share price rises by sellers, as you can see from the chart.
It was this frustration which led me to recently sell my TMMG shares, with rather poor timing, before today's nice rise. The big question though, is whether today's share price rise will hold, or whether sellers will once again erode the gains in the coming weeks?
Arguably, a takeover bid can often be the only chance of a decent capital gain, with this type of share. Otherwise it might just remain in the perpetually cheap section of the market, with a revolving door for shareholders.
I'll add sections on Belvoir Lettings (LON:BLV) and Card Factory (LON:CARD) to tomorrow's report.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Re Filta Group (LON:FLTA)
As a recent Minervini reader, I wonder if others have noticed that the SP seems to have crossed above its 50 100, 200 day MA today on no news at all. I've had them on my watchlist for a while but have failed to grasp the nettle. Am I right to think they are in the process of re-rating?
cheers
Francis
Filta Group (LON:FLTA)
a true Minervini setup would probably look for a VCP around the pivot at 220-225p
agreed it is one to watch.
SCISYS (LON:SSY) had a VCP breakout today, i am also watching £JDG
How about EKF Diagnostics Holdings (LON:EKF) that has broken out?
£K3C and Everyman Media (LON:EMAN) also.
I have been watching Judges Scientific (LON:JDG)
Hi Herbie (& mrobistan & fwyburb)
Continuing to evolve my appreciation of Minervini's strategies.
I bought into EKF Diagnostics Holdings (LON:EKF) and £K3C a few days ago. Topped up on £K3C again today.
Will look closely at Judges Scientific (LON:JDG) and SCISYS (LON:SSY).
For what its worth, if you were interested these are on my current Minervini screen (which I'm sure differs to some extent from yours). Also, options can enter and fall off the screens daily depending on price changes, so this is simply today's listing.
Large UK caps - Coca Cola HBC AG (LON:CCH), Dechra Pharmaceuticals (LON:DPH), Fevertree Drinks (LON:FEVR), NEX (LON:NXG) - I hold Dechra Pharmaceuticals (LON:DPH) & Fevertree Drinks (LON:FEVR). NEX (LON:NXG) is a bid situation so I ignore (as bid distorts MAs). I'm looking at Coca Cola HBC AG (LON:CCH) a bit longer.
Mid caps - Avon Rubber (LON:AVON), Fenner (LON:FENR) (bid so ignore), Ibstock (LON:IBST), Keywords Studios (LON:KWS), On The Beach (LON:OTB), Plus500 (LON:PLUS), Robert Walters (LON:RWA), YouGov (LON:YOU). I already hold Avon Rubber (LON:AVON), On The Beach (LON:OTB), Plus500 (LON:PLUS), Robert Walters (LON:RWA). Will be looking at others.
Small caps - Dewhurst (LON:DWHT) (liquidity might be a constraint here), EKF Diagnostics Holdings (LON:EKF), LoopUp (LON:LOOP), Mortgage Advice Bureau (can't use the £sign as it inserts wrong stock) - I already hold EKF Diagnostics Holdings (LON:EKF), LoopUp (LON:LOOP). Will look more into others.
Micro caps - Instem (LON:INS), Symphony Environmental Technologies (LON:SYM) - I hold both.
I know you read and comment on the CAN-SLIM thread and thought these might interest you in contrast to your own lists.
Regards
Howard
Howard, thanks for that info. It maybe best to continue this on the Camslip thread I don't want to derail the Small Cap Value report.
Herbie
Ok.
I'll pick it up when next set of postings emerge on that thread.
Regards
Howard
Thanks Howard. Where do I find the Can-Slim thread? (I sense there's a joke response to this but it's too early in the morning)
cheers
Francis
Hi Francis
This is the CAN-SLIM thread
https://www.stockopedia.com/content/can-i-can-slim-16-no-subtitle-this-week-350853/?comment=5#5
Regards
Howard
Many thanks Howard
yeah agreed with all those...
i do hold £K3C , unfortunately i talked myself out of Everyman Media (LON:EMAN) and £EFK - definitely seems like the market is buying the names that held up
thanks for the SCISYS (LON:SSY) update.
I often think that for the benefit of further education and understanding, we MM fans should get together online.
Well spotted. SCISYS (LON:SSY) is a textbook VCP breakout (higher lows in the base and multiple days of increasing volume).
Hi Francis
Filta Group (LON:FLTA) an Interesting spot.
Their 07/02/17 TU RNS states .... 'The Group expects to report its 2017 results on 17 April 2018.'
The TU was upbeat
https://www.investegate.co.uk/filta-group-holdings--flta-/rns/pre-close-trading-update/201802070700029776D/
Looking at >3% shareholders though, insiders hold 71.1% of shares. Then three institutions hold a further 18.5%. Suggesting that only about 10% are in the market.
https://filtaplc.com/investor-relations/securities-information/
Based on Hargreaves Lansdown buy/sell the spread is 5%.
This looks like it could be a bit illiquid, which might be a consideration.
Graham quite liked it in September SCVR.
If liquidity is not too concerning it looks interesting.
Regards
Howard
I agree that Filta Group (LON:FLTA) meets the Trend Template. I'm a Minervini trader and it's on my watchlist too. It also meets Minervini's criteria for revenue and earnings per share growth.
I'm going to wait for the results next Tuesday (17th) and I'll be looking for a positive reaction from the market. I don't like to hold through earnings unless I have a profit cushion. As Minervini says, you always trust a bit to luck holding through results.
Hi Paul
Thanks for today's report.
RE: Mission Marketing (LON:TMMG)
A few thoughts and a correction
Firstly, the correction. This group is not in the PR business. Whilst all marketing & communication disciplines (Branding, Advertising, PR, Digital, Direct Marketing, Sales Promotion, Sponsorship etc) fall under the category of "Promotion" (one of the Marketing P's), the agencies who perform these roles operate differently. As a consequence, the nature of their client relationships are different as are their earnings and vulnerability to economic cycles.
TMMG is new to me but they seem to own 15 individually branded agencies (16 including Krow) in different disciplines spanning the marketing services spectrum including two PR agencies. There seems little sector focus across these businesses. With 1000 staff and revenues of £70m, the agencies average 65 people each and have average turnover of £4.5m. So each agency is a relatively small, independent businesses operating in different markets with differing exposures to a downturn based on what they do and the client sectors they operate in.
This is also a weakness as they don't have a unified brand, culture or sectoral focus so cross selling opportunities across the agencies will be limited (and anyway, agency people all want to own the client relationship and aren't good at sharing!).
I think the PER is relatively low at TMMG because of these factors despite TMMG clients being unusually loyal. The broad rule of thumb is that smaller agencies are valued at around 5 X PBT which happens to be close to TMMG's market cap.
And yes, I think groups of agencies like this can become a takeover target especially if they can build a global group. However the lack of integration between the agencies may make TMMG less attractive.
cheers
Francis
Re: TMMG,
As mentioned above, everytime it does well the management take a chunk of options.
A previous SCVR laid out the options to be paid once the share price reached a certain level, 60 or 70pence, from memory.
The cynic in me thinks that the ‘unusual’ way of structuring the recent acquisition is a way of boosting the metrics that will trigger a rise in TMMG’s share price before the market realises that the giant share of what the business owners are expecting, is actually going to what Paul calls “very high” performance targets and dilution through management options.
But I’m not a cynic, so I would never say the spread is horrible, liquidity sucks, and upside is absolutely limited - to the greedy enrichment of management.
For those following the ITM Power (LON:ITM) story, this morning they won a fuel contract with the Metropolitan Police to provide hydrogen fuel for a new fleet of fuel cell electric vehicles. In addition to this, I found an alleged company with $8 billion in hydrogen HGV truck preorders. I know there were some hydrogen bears out there, but the industry really seems to be gaining traction. My worst case scenario here is Royal Dutch Shell (LON:RDSA) buy up the refuelling/distribution technology on the cheap. (I hold).
I also noticed some large buys going through for Revolution Bars (LON:RBG) over past few days. A BB member pointed out that the time limit has lapsed for bid offers exceeding 210p, so I wonder if this was opportunist buying or potentially someone building a position ahead of an offer. (I hold)
Joe
Over 60m shares just traded in GAME Digital (LON:GMD).
I appear to be alone in taking an interest in Boku Inc (LON:BOKU) today. As a blue sky/jam tomorrow stock I recognise that Paul has sworn off it but for those of us keeping a few wild outsiders in the portfolio the results today appear to confirm everything that you need to see in a company that has to grow towards profitability.
The revenue growth, reduced loss (disguised by flotation costs), increased engagement with key partners, presence in a growing market and, especially ,the control of costs suggest that they are on track. A target of cash positive results after 2019 is what we have to keep an eye on, probably no need to hurry in now but worth keeping on a watch list.
To me, on Air Partner (LON:AIR) it seems as if the market has latched on to the fact that the RNS explicitly states that the "investigation continues", leading to the fear that further bad news will follow, including likely the departures of certain execs. Perhaps insiders know something, but I have no evidence or real view on this.
Its obviously imperative to make your own investment decisions, but I would caution trying to catch the knife here. If it were me, I would rather miss the bottom (even if by 10-20%) and wait for hopefully positive news to come from the company, than get wiped out by a rights issue or something worse. Just my two cents. I have no position, but would reconsider depending on the next update. All the best!
Edit: forgot to click reply, sorry. That was in response to Jasper's post.
Paul, I know you dealt with (LON:AIR) just the other day, but things seem to be going from bad to worse, and not a peep from the company. Against a t/o of ~£50m and operating margin of ~12% a 'non-cash' error of £3.3m, while bad, should not lead to a share price drop of 55%. Do you get the impression that the finances have been badly mismanaged and that the bad news is not yet over?
Thanks.
Sorry Paul.
Another request for me today if possible, a small letting agency stock you looked at briefly last year.
Asagi brought Belvoir Lettings (LON:BLV) to my attention and my comment is this,..
Not a sector I typically invest in but looks interesting enough - Quite tempting, I like to see the EPS has broken the 5 year (perhaps all time) high whereas price is way off the 5 year high - Plus the yield - Interesting enough...
Presumably the share price remains depressed due to the letting fees ban. Do you happen to know if Belvoir Lettings (LON:BLV) have spelt out the expected impact on them? https://www.gov.uk/government/news/government-action-to-end-letting-agent-fees
Presumably yes re: Belvoir Lettings (LON:BLV) as the market doesn't seem too keen at present. In answer to your question, that's a no and I cannot find any broker coverage other than small notes (sadly).
Property Franchise (LON:TPFG) who also reported results today have included the following in their results announcement:
"Tenant Fee Ban
The Government has provided a degree of clarity on its intention to ban tenant fees in England & Wales. A ban in Scotland has been in existence since 2012.
The intention appears to be an outright ban, rather than a cap, on landlords and their letting agents charging any type of pre-tenancy fee. It's not clear whether certain in-tenancy fees will be allowed.
The timing of the implementation of the ban appears to be Q1 2019 which means that the Group's trading for 2018 would be unaffected by the ban. The Group is already taking action to mitigate the effects of the ban which is expected to put at risk 16% of our franchisees' lettings revenue, and at a Group level 9% of total revenue, if annualised*. Mitigation factors include; through organic means and by acquisition, accelerating the size of the tenanted managed portfolio, developing income from financial services & conveyancing referrals. The Group will continue to closely monitor any developments associated with the Tenant Fee Ban and the associated potential impact."
*Both percentages quoted based on 2017 trading
Some thoughts on AIR:LN would be welcome. The price seems to be discounting another CVR-type episode.
Hi Grumpy5, have you seen Paul's thoughts on #AIR on April 3rd?
Yes.
Re Air Partner (LON:AIR) ,as the price has fallen on reasonably large volume,that means there have been both large buyers and sellers since the 3 April announcement. So there intuitively appears to be a large holder who has bailed out/is bailing out. I would expect to see disclosures shortly. A large institutional holder on seeing the announcement would, I imagine, have been straight on the phone to the CFO to find out more background. Presumably they did not like the answers they got back. To me the 2 most pressing questions to ask would be 1) how “preliminary” has the investigation been so far (ie how likely are more problems to be uncovered?) and 2) how was this misreporting discovered (ie how good are current financial controls)?
I would also be interested in £D4T4 . I bought in after the big director buys a few months ago but then got put of and sold out as the share price kept drifting lower. Today’s trading update seems to be telling us why the directors were buying but a clearer forecast would have been helpful. On the plus side, trading sounds good, orders are coming in and their products seem to be selling well. On the downside, it’s a bit worrying that their accounts team don’t seem to have (or be willing to share) a clearer picture of the results. I don’t hold. Like David (post 14) I would be tempted if the share price drifted back a bit over the next few days.
Plus maybe Graham can give us his thoughts on the Impax Asset Management (LON:IPX) assets under management figures issues today (not your bag, I understand Paul)
We know Graham is much more interested than Paul in analyzing or investing in finance companies. Also Graham has (or had) a large position in H & T (LON:HAT), who operate in much the same space. So whilst I would be interested in an analysis of the Ramsdens Holdings (LON:RFX) TS, I would be happy to wait until Graham's report on Friday for this, unless he would like to do it earlier. :-)
I always enjoy your macro thoughts Paul and find them an interesting overview on investing. When you have some spare time, I would appreciate your wisdom on how to approach political events. For example yesterday was a large sell off of anything Russian due to Trump's words over the weekend. Should such a sell off be seen as short term fixable, so therefore a buying opportunity or seen as the start of a long term problem so a selling signal. Your wisdom on such event would be appreciated.
I'm also keen for your thoughts on the Mission Mission Marketing (LON:TMMG) - confident sounding Chairman. Ends the trading statement with "our long-term growth will be inevitable". I had to look up the word "gongoozeler" https://en.wikipedia.org/wiki/Gongoozler
The Mission Marketing (LON:TMMG) Chairman brilliantly used the words gongoozelers & bafflegab in his statement!
bafflegab means: incomprehensible or pretentious verbiage, especially bureaucratic jargon. (this could be used to describe many company statements!)
Thoughts on Mission Marketing (LON:TMMG) would be appreciated.
For what it's worth, the Balance Sheet of Mission Marketing (LON:TMMG) has a very high level of intangibles - £88m. Excluding these results in negative NTAV £(8m).
The company has grown through acquisition, but there is mention about organic growth coming through which is positive. However, there is mention of economic uncertainty which perhaps makes it difficult to forecast.
A third reason for scepticism here is that every time the company seems to be going somewhere the management award themselves a huge chunk of options. Looking at their social media Mission Marketing (LON:TMMG) seems to be a jolly nice place run for the benefit of all the jolly nice chaps, chapesses and chaplettes. I write as a frustrated former holder.
Decent trading update from Robert Walters (LON:RWA) this morning. Looks like net fee income is up in all regions worldwide with Europe being a stand-out performer. Compared to how badly some other recruiters are faring this seems to be a textbook example of how to run one effectively with substantial global diversification.
Hi snoo, grout123 - ignore the petty down votes, but I don't think Paul will be interested in looking at Griffin Mining (LON:GFM), as its a gold miner in China; I don't believe he looks at that sector. I unfortunately have no insight or view on the stock, but others may well do. I think there is some discussion in Matalyda's thread today so you may have better luck in that thread. All the best.
It could be that the down votes are because grout123 isn't using the £ sign before the epic code...?
Anyway, I reversed one of them, I'm also interested in Griffin Mining (LON:GFM) although as per comments on matylda's thread the muted response is probably down to the further delay in obtaining the license for Zone II and the absence of any dividend despite all of the cash they are churning out.
Thoughts on Ramsdens Holdings (LON:RFX) if you have time please Paul. A very brief trading update....'slightly ahead of expectations', so EPS closer to 17 than 16 perhaps. From memory this is without any store expansion so a creditable result. Although perhaps not everyone's cup of tea; the business is as much an evolving currency trader and retailer as it is a pawnbroker/lender, from my point of view. The stock is not expensive especially on a cash adjusted basis. Market cap of about £56m with enterprise value of around £43m.
Look forward to meeting you and the Stockopedia gang at Mello.
All the best
It would be appreciated if you could comment on Griffin Mining (GFM)
Cracking results today
Paul doesn't cover resource companies. Looks like they've done well over the last year so congratulations if you've held during the period!
Thank you. Leopards and spots etc with Chinese firms but I am now feeling uneasy as the numbers are so stellar today but market reaction muted.
Griffin Mining (LON:GFM)
I also think the muted response revolves around no news on a dividend and the zone II licence.
However, currently, I cannot see anything to stop them duplicating their H2 performance in 2018 which would result in revenues of $148, PBT of $77m and PAT of $55m giving a forward PER of less than 7. The relevant metal prices are currently above their averages for H2 2017 as far as I'm aware.
I was disappointed there was no discussion of future dividends in the release, but I think they do need to conserve cash at the moment. Apart from the proposed development of zone II, if you look at the balance sheet they have current liabilities of $52m compared to current assets (including cash) of $37m giving a current ratio of only 0.7 which is on the low side. Although it would be easy to raise debt it would be a "u-turn" after their no debt announcement. Cash generation in the first 6 months will significantly improve the position and I suspect lead the way to a maiden dividend.
Phil
Parity (LON:PTY) reported today (I hold). It looks as though the turnaround is going well - five half-years of improving results since they went back to their core business, and the higher margin professional services division is growing well. With the Value Rank already 95, strong momentum, the QR set to improve, good ROCE and decent FCF, PTY feels undervalued to me. I'd welcome others' views.
Griffin Mining (LON:GFM) if you have time?
Looks like record results - could be a 100 stockrank soon. Market doesn't seem to like it that much, had early gains but sold off.
BTW Paul - In case you missed it - You may be interested, there's quite a bearish (Whitman Howard - never heard of them) note on Research Tree regarding Next (LON:NXT).
Morning Paul,
I think Mission Marketing (LON:TMMG) is the pick of the bunch for me today and would appreciate your view as always (I believe you hold or at least used to).
Results For The 12 Months To End December 2017 – Revenue up 6% to £70.0m (2016: £65.9m), PBTup 10% to £7.7m (2016: £7.0m), Diluted EPS up by 11% to 7.12p (2016: 6.41p), FY Dividend up by 13% to 1.7p (2016: 1.5p). Net Debt is now down even further to, a much more manageable £7.2m. 2018 has started well and is expected to be a year of strong growth. Also announced an immediately earnings enhancing acquisition (Cash £2.75m) this morning.
Seems cheap to me for a company growing at circa 10% - But the Spread is a killer!
See you at Mello (and the bar)!
Morning Paul & gang, if you are looking for things to cover, Impax Asset Management (LON:IPX) please? Grahame has been covering it...
£D4T4 warrants some comment, it has been something of a conundrum since their shocker of a half year update: today's RNS on a beats full-year seems to put that to rest: there should be a fairly significant rally to re-rate
I know many readers here are Minervini advocates but in low liquidity shares, many of his SEPA rules are difficult to apply.
Worth a kick-around as axiomatically applying trading rules in low liquidity small caps is not a great idea in my view: they simply don't have the physics ( volume, momentum, float) to behave well technically. However, when the data is not there to support fundamentally, there is a decision void. Heuristics then ?
yes, £D4T4 grabbed my attention too . Had a bit of a re-rating already this morning - up 20% but if statement is to be believed I expect in excess of 10p EPS and net cash back around the £5m mark.
With a strong order book for y/e 19 feels as though this is trading on a cash adjusted PE for next year of around 8 or 9, which appears cheap.
Wonder if 1st half woes are avoidable in future with bigger order book? Am inclined to buy some if if drifts back slightly from todays highs. Got up to 170p before the 1st half and they are in a good market sector.
Agreed though I suspect the momentum will remain to the upside; d4t4 was sold-off to reflect the half year and not full year results so I doubt many will sell on the expectation of the full-year results on 23 April which can only be better than the interims and are already signalled to be better than forecast. It is not unreasonable to expect to see the 170p+ level depending on how good the beat is (mgmt quote "record" revenue and profit figures in H2)
UK tech stocks were off over 30% ytd as of last week and martech particularly was clobbered on fears of regulation and the Facebook negative halo effect.
The result was a perfect storm for d4t4 hence the massive discount.
Perversely, regulation and the impact of GDPR is positive for d4t4 as they are already badged as compliant but I suspect it will take some time for the market to digest and internalise this. There is a real paucity of analyst coverage which is unhelpful.
I am very bullish on d4t4 based on the Celebrus technology and the growing order pipeline. Results on 23 April should give insight into the relative growth of recurring revenues and licensing which should help smooth revenue streams and hopefully reduce the impact of project lumpiness .
Today's announcement was a binary catalyst that the market needed, I'd be surprised if there is much of a pullback: the relatively high volume of buying on today's news supports this.
as an addendum, this is from FinnCap this am who are the house-brokers and forecast a 200p target. They are the only analyst covering d4t4
D4T4 Solutions (D4T4): Corp
Deals deliver a strong H2 performance
It is a relief to hear that the data collection and management solutions provider has closed a number of major H2 deals to help deliver demanding FY 2017 earnings expectations and relieve pressure on the share price. The board remained confident on the FY numbers despite a slow H1 but the shares have been somewhat depressed since the YE, on investor nervousness. It now seems that management confidence was justified and H2 was a record six months for revenue and profit, on the back of a number of new contract wins from a strong pipeline of potential business. More detail should be available in the usual post YE trading update towards the end of the month, once the books have been closed. At this point, we retain our forecasts and we expect a share price recovery to around or above the 150p level on the back of relief and the exciting prospects such a strong second half performance suggests.
Thanks. that's very helpful. I bought a few at 130p. hopefully they can surpass the highs leading up to results in a couple of weeks. do look cheap as long as their next H1 number isn't expected to be lumpy again. Market does hate H2 weighted stocks.
My morning smallcap tweet:
Omega Diagnostics (LON:ODX), Tricorn (LON:TCN), Hvivo (LON:HVO), Elektron Technology (LON:EKT), £D4T4, Ramsdens Holdings (LON:RFX)
Omega Diagnostics Gp (ODX) trading: warns FY rev down 5%, adj pretax -£0.7m . Will close 2 sites to cut losses at cash cost of £0.6m max.
Tricorn Group (TCN) guides FY adj pretax beat. Rev up 20%.
hVIVO plc (HVO) notes the 'sudden and extreme fall' in its share price and confirms that it knows of no reason for such a fall. The 90% fall in 3 years has been more measured and no doubt deserved.
Elektron Technology (EKT) Contracted annual recurring revenue for Checkit now over £1m, which is ahead of management expectations.
D4T4 Solutions (D4T4) has secured a number of high quality contracts in Q4 so expects to report a very strong trading performance in H2. Expect revenue and adjusted pretax ahead YoY. House broker F/C guides adj EPS up 1% but is 10 months old!
Ramsdens Holdings (RFX) guides FY slightly ahead of expectations.
RNSs seem to be up and running :)
Out of interest, results from Card Factory (LON:CARD) show cost pressures are increasing and these being sustained in 2018. These are being mitigated through other cost reductions rather than price increases. Also of interest is the level of dividend which is being distributed and has partly been funded though an increase in debt levels. I wonder if his payout is sustainable?
Boku Inc (LON:BOKU) results also out today. Whilst it is still loss making, growth has been significant and the outlook is positive. It IPO'd recently and sits in an interesting space: growth is scalable in different geographies. Does anyone have any insights?
Ramsdens Holdings (LON:RFX) trading update states results will be ahead of market expectations - although it is no mentioned what these are.
Hi Paul, would be grateful if you could cover TMMG:
Headline profit before tax up 10% to £7.7m (2016: £7.0m)
· Headline diluted EPS up by 11% to 7.12 pence (2016: 6.41 pence)
o Free cash flow up 70% to £9.1m (2016: £5.3m)
o Bank debt leverage ratio reduced to x0.8 (2016: x1.3)
· Full year dividend up by 13% to 1.7p (2016: 1.5p)
· 2018 started well and is expected to be a year of strong growth
Another for TMMG please Paul