Small Cap Value Report (Tue 10 Sept 2024) - RNO, HVO, LUCE, MPAC

Good morning, it's Roland here kicking off today's report.
There are a lot of companies reporting today, so I'll focus on the most viewed list, reader requests, and quick summaries.
Update 11am: I'm happy to report I've now been joined by Paul, who'll be adding some further sections.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies reporting
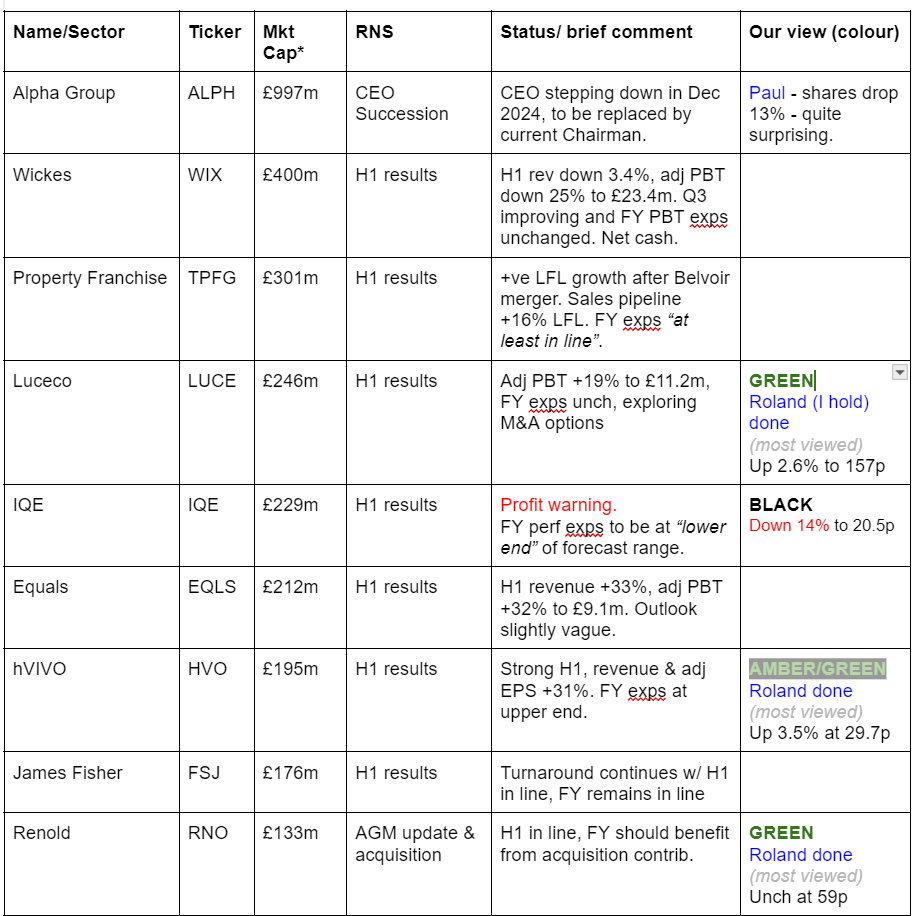
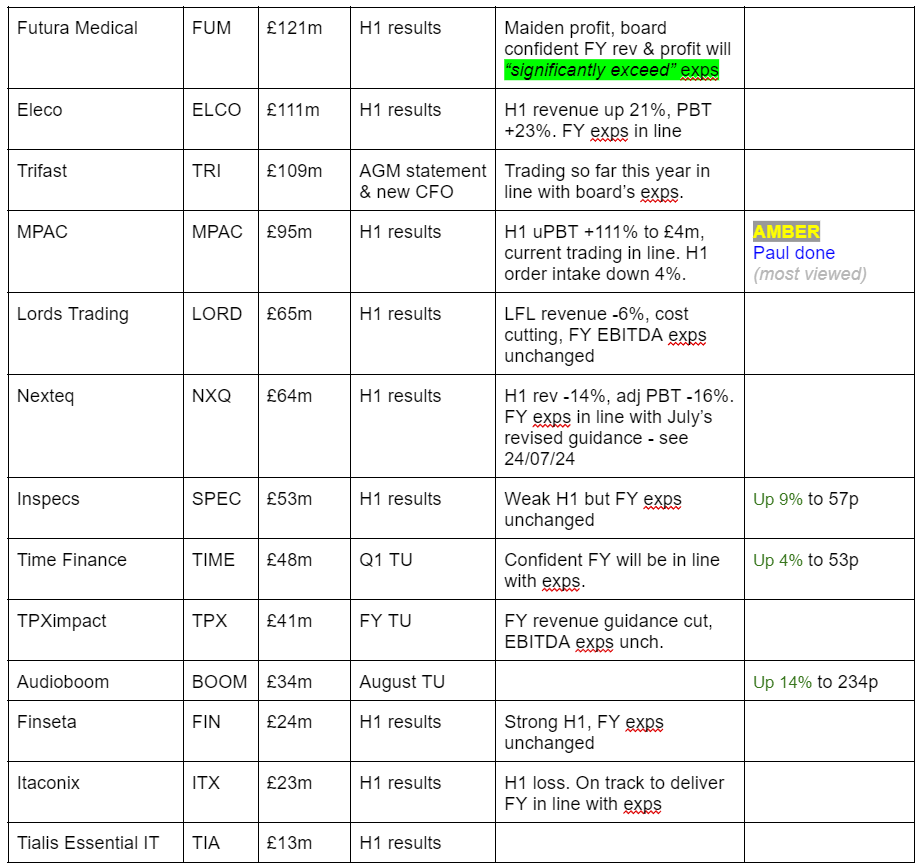
*Market caps at last night's close
Summaries
Renold (LON:RNO) - Unch at 59p (£133m) - AGM TU & Acquisition of MAC Chain - Roland - GREEN
Today’s trading update confirms performance has been in line with expectations so far this year. Renold also announced an acquisition which should improve group profit margins further. My view remains positive, despite a couple of minor niggles.
hVIVO (LON:HVO) - +3.5% at 29.7p (£204m) - Interim results - Roland - AMBER/GREEN
A strong set of half-year results, although tempered (slightly) for me by expectations for a weaker H2 and a shrinking order book. I suspect this is only short-term and believe that growth prospects could remain strong. But with updated FY24 eps forecasts suggesting a flat result this year, I’ve adopted a slightly more cautious stance.
Luceco (LON:LUCE) - +2.6% at 157p (£251m) - interim results - Roland (I hold) - GREEN
A solid set of half-year results from this electrical products specialist despite market headwinds in the UK construction sector. The outlook for the next 18 months seems positive and I’m comfortable with the fundamentals and valuation here. However, I do have some longer-term concerns about the acquisition-led growth strategy.
MPAC (LON:MPAC) - unch 465p (£95m) - H1 Results - Paul - AMBER
H1 profits are nicely up against weak comparatives, and in line with expectations. Good visibility means FY 12/2024 is also tracking in line. I have issues with the excessive receivables on its balance sheet, and poor H1 cashflow. Lumpy orders, erratic historical performance, and no divis since 2016, mean that I’m struggling to get above AMBER, but the PER does look modest.
Paul's section
MPAC (LON:MPAC)
Unch 465p (£95m) - H1 Results - Paul - AMBER
MPAC (LON:MPAC) , the global packaging and automation solutions Group, today announces its unaudited financial results for the six months to 30 June 2024 (the "Period").
Positive headlines and key numbers -
“Significant revenue, margin and profit growth
Strong order intake and healthy prospects pipeline; confident in the full year and beyond”
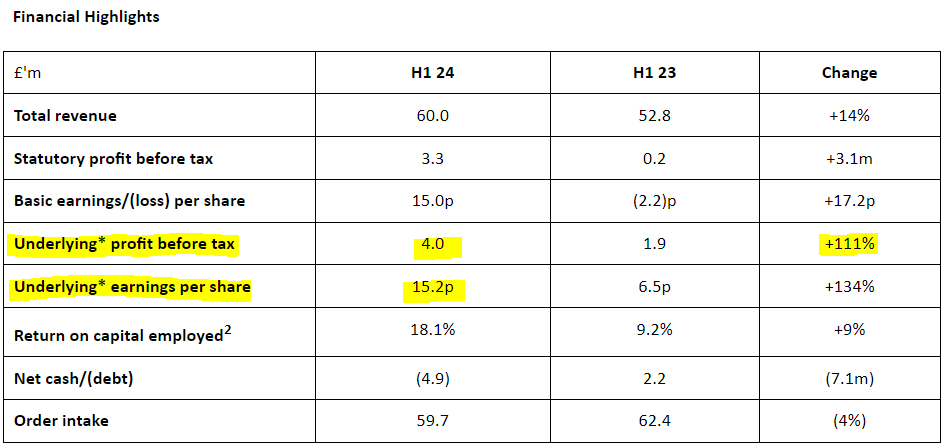
Very good “underlying” PBT and EPS growth, albeit coming from a low base last year.
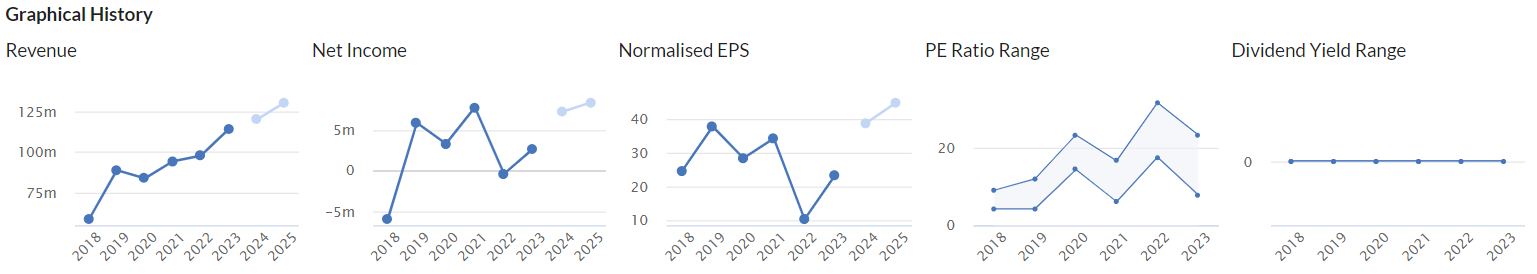
Performance has been quite erratic, with profit collapsing in 2012, but rebuilding since, which has been reflected in a roller coaster share price.
No divis paid since 2016, which is a definite question mark - this doesn’t look a very cash generative business over the long-term.
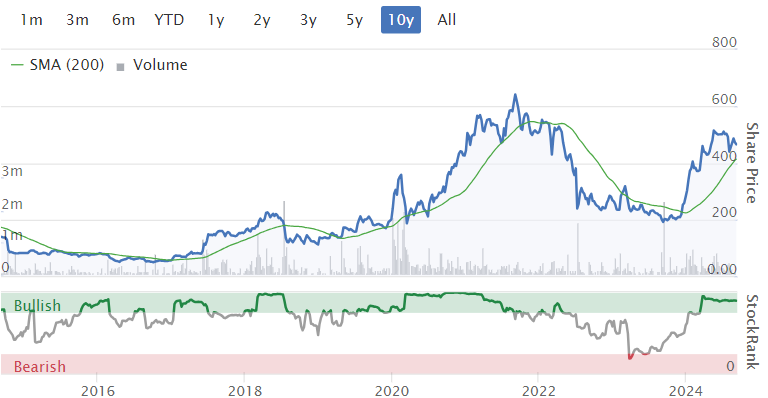
Outlook - there are some nice points in the “operational & strategic highlights” section, saying that H1 was in line with expectations. New customers won. Underlying operating margin up strongly from 4.2% to 7.5%, operational efficiencies, new products launched.
“Order book broadly unchanged from FY 2023”
Current trading also in line with the Board’s expectations.
H2 weighting, but gives reasons for why it thinks that can be achieved -
“Confident in relation to the full year end and, with continued improvement in project margins, in achieving the H2 underlying profit weighting which was announced earlier in the year”
Build up of working capital in H1 expected to unwind in H2.
Acquisitions - sounds like more are in the pipeline. Do these add value though? I’m not sure.
Balance sheet - NAV is £68.5m. That includes intangible assets of £23.3m, and a £33.0m pension asset, so both of those need to come off, and I’ll also deduct deferred tax liabilities of £8.3m and a pension deficit of £1.6m, giving NTAV the way I calculate it of £22.1m, which looks OK for the size and type of business.
One item that stands out like a sore thumb is “Trade and other receivables” of £52.6m. That’s way too high, and is almost all of H1 revenues of £60m. I think we had this issue once before, but it needs to be queried with management. Receivables should be something like £20m (a third of H1 revenues), not £53m. So there’s a problem here I think, in that MPAC seems to be accumulating work done, but not being paid for it yet. That introduces obvious risk of something going wrong. I would want to see them receiving stage payments from customers, rather than running up a large amount owed by customers - who might then dispute amounts owed possibly. It’s not right anyway, whatever the explanation we’re likely to receive telling us that it’s OK!
Cashflow statement - was poor in H1, with working capital sucking in cash, to produce an overall negative cashflow. They say this should reverse in H2, but it does worry me a bit, as this didn’t happen last year - cashflow was positive in both H1 and H2 in 2023.
The pension scheme is still cash hungry, consuming £1.2m of cash in H1.
Since there is now a large accounting surplus, that probably means the actuarial deficit might reduce in future maybe? I’ve not looked into the detail, this is just to flag that it’s an issue which you’ll need to check carefully before buying the shares.
Broker updates - both Shore and ED update us.
ED has 38.4p adj EPS for FY 12/2024, and 44.0p for next year.
At 465p per share, this is a PER of 12.1x and 10.6x, which looks pretty good value to me. There’s no net debt to worry about either, with a smallish net cash position. Hopefully they can do a better job of collecting in the mountain of receivables, and move into a much stronger net cash position in future.
Paul’s opinion - I’ve only been AMBER in the past, and my concerns over excessive receivables and lumpiness of orders (plus no order book growth) are holding me back from going up a notch to amber/green. So it’s another AMBER from me today - which is fairly good, as ambers tend to perform well overall, and only a little behind amber/greens.
I can see why bulls like the lowish PER, but how reliable are profits? Arguably the erratic historical figures deserve a lowish PER.
Roland's section
Renold (LON:RNO)
Unch. at 59p (£133m) - AGM Trading Update & Acquisition of MAC Chain - Roland - GREEN
the Group's financial performance in the first five months of the new financial year was in line with its expectations
Industrial chains and gearboxes group Renold is one of Paul’s top 20 shares for 2024. The stock has performed well so far this year, driven by a strong improvement in profitability.
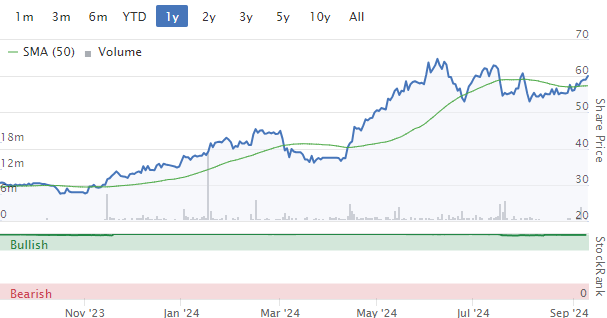
Today’s update doesn’t appear to have moved the needle with investors but reads fairly positively, in my view. There’s also news of an acquisition that is expected to make a positive contribution to trading for the remainder of the year.
Checking back in our archive, Paul covered Renold’s 2023/24 results here in July. He then took a look at the company’s share buybacks for director stock options awards here.
AGM Trading update: Renold confirms that trading during the first five months of its financial year has been in line with expectations.
Group revenue for the period fell to £102.3m (FY24: £104.7m), which was a 0.9% reduction at constant exchange rates.
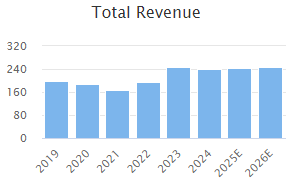
This extends the company’s run of flat revenue – I see that prior to today’s acquisition, analysts had expected this flat trend to continue:
Order intake has risen by 15.5% (constant rates) to £105.5m so far this year (FY24: £92.6m), although this benefited from a single large contract award with the Canadian Navy in May. Excluding this, underlying order intake was 4% higher at constant rates.
The order book was flat at £85.5m at the end of August (August 2023: £85.4m). The company describes this as “close to a record high level”.
Net debt was £24.5m (0.6x EBITDA) at the end of September, ahead of today’s acquisition. This looks comfortable to me.
Outlook: the company sounds positive about trading and the outlook for the remainder of the year:
Trading and profitability for the first half is in line with the Board's expectations, whilst the full year will now also include six months contribution from the MAC Chain acquisition.
Research Tree has an updated note from house broker Cavendish (many thanks) upgrading FY25 earnings forecasts by 5.7% to 7.5p per share.
Cavendish’s analysts have upgraded FY26 forecasts by 15.9% to 8.6p per share.
Stockopedia already had a consensus figure of 7.5p per share for the current year, so this leaves the stock on an unchanged forward P/E of 7.9 for FY25.
Acquisition: The company has also announced the acquisition of MAC Chain Company Limited today, for $31.4m in cash.
MAC Chain appears to be a Canadian company with operations in Canada and the Pacific Northwest of the USA. It’s a “manufacturer and distributor of high quality conveyor chain and ancillary products”, primarily serving forestry and broader industrial markets.
This acquisition is expected to “immediately enhance” adjusted earnings per share, but also be accretive to Renold’s group operating margin.
The information provided in the RNS tells us that MAC generated sales of $25.8m for the year ended June 2024, with a pre-tax profit of $3.5m. This implies a pre-tax margin of 13.6%, which is indeed ahead of Renold’s FY24 operating margin of 12.6%.
Cost savings are expected to reduce the purchase multiple to 6.9x EBITDA and Renold’s management expects leverage to peak at 1.2x EBITDA following the deal.
Roland’s view
Although Renold’s appears to have struggled to deliver much top-line growth in recent years, the group’s profitability has improved significantly:
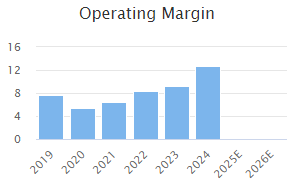
Today’s acquisition looks fairly priced to me and I’m pleased that it should improve the quality of the business, if we view this in terms of profitability.
Given the group’s improving margins and double-digit returns on capital employed, Renold shares don’t look expensive to me.
I’d like to understand a little more about the group’s recent lack of revenue growth. Is this cyclical, or structural?
Personally, I would also prefer to see Renold pay a slightly more generous dividend.
However, these are only minor niggles for me, at this valuation. The outlook still seems positive and I would guess there could also be some cyclical upside potential (e.g. in mining).
I am quite happy to maintain Paul’s previous GREEN view on this stock.
hVIVO (LON:HVO)
+3.5% at 29.7p (£204m) - Interim results - Roland - AMBER-GREEN
hVIVO describes itself as a “specialist contract research organisation and world leader in testing infectious and respiratory disease products”. From what I understand, this company is well-known for its ability to run human challenge trials, where volunteers are infected with a mild dose of a disease so researchers can study how it progresses and consider possible treatments.
I don’t look at healthcare stocks very often and I must admit hVIVO is a new company to me.
Checking back in our notes I see Paul covered the firm’s H1 trading update positively in July.
Share price performance has certainly been strong over the last year, with the shares up c.50% over the last 12 months.
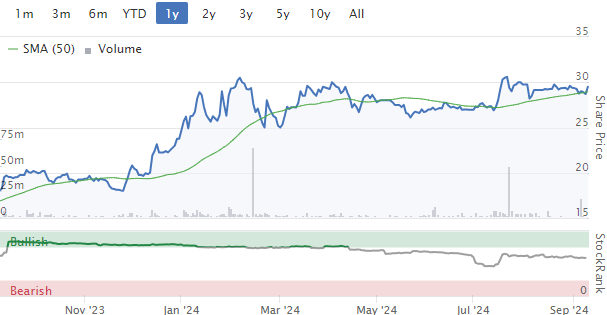
Today’s half-year results appear to reiterate the positive guidance issued in July:
"We are pleased to reaffirm our full-year revenue guidance of £62 million and expect EBITDA margins to be at the upper end of market expectations”
hVIVO helpfully informs us that consensus market expectations for FY24 EBITDA margins are 22.7%, within a range of 22-24%. Given this, I’d expect this year’s EBITDA margin to be 23%-24%.
H1 results summary: today’s figures cover the six months to 30 June 2024 and show strong half-year earnings growth and improved profitability for this business.
Here’s a summary of the main figures:
Revenue up 30.6% to £35.6m
EBITDA +67.6% to £8.7m
EBITDA margin of 24.5% (H1 23: 19.1%)
Adjusted earnings up 30.6% to 0.81p per share
Cash of £37.1m (H1 23: £31.3m)
Order book of £71m at 30 June 2024 (H1 23: £78m)
The company flags various operational highlights including the opening of its new facility at Canary Wharf and “a record number of volunteers inoculated” across various trial programmes.
Performance seems to have been improved by “expedited delivery of projects”. This is apparently the reason why the order book at the end of June was lower than one year ago – hVIVO is completing contracts more quickly than it was previously.
Among the contracts signed in H1 were a £6.3m Human Rhinovirus (HRV, or common cold) trial and a £2.5m Omicron (Covid-19) “characterisation study” with a mid-sized pharmaceutical company.
The company also reported progress manufacturing various “challenge agents”. I believe these are required to infect the human volunteers participating in trials.
Outlook: the company has reiterated its full-year revenue guidance of £62m and says that 100% of this guidance is now fully contracted.
This highlights the expected H1 weighting this year – H1 revenue of £35.6m represents 57% of the expected FY figure, so H2 is expected to deliver just £26.4m of revenue.
Assuming a full-year EBITDA margin of 23.5% (upper end of 22%-24% range) gives an EBITDA figure of £14.6m.
Today’s results show adj EBITDA of £8.7m converting into £5.3m of after-tax profit.
Assuming a similar conversion for the full year suggests hVIVO could generate £8.8m of profit this year. With the market cap at c.£200m after this morning’s rise, that prices the shares on c.23 times FY24 forecast earnings.
My estimate is broadly in line with updated guidance from Cavendish today. After upgrading its forecasts in July, Cavendish analysts have now trimmed FY24 earnings estimates to 1.3p per share (previously 1.4p) due to expected higher lease costs.
Forecast earnings of 1.3p price the shares on a P/E of 23.
Roland’s view
I don’t know much about the medical and operational side of hVIVO’s business. But the company’s accounts do tell a positive story, in my opinion.
Free cash flow now appears to have turned positive and the group’s net cash of £37m suggests to me that hVIVO’s financial position is now fairly secure, barring unforeseen developments.
Revenue growth also appears to be delivering positive operating leverage – in other words, profits are rising faster than revenue, as fixed costs are more thinly across increased activity.
The group’s operating margin rose to 18% last year and I calculate this improved to 20.7% over the 12-months to 30 June 2024. Those are decent figures, in my view.
The stock's forecast P/E of 23 seems reasonable to me for a high-margin growth stock, but one possible caveat to this is that hVIVO’s earnings are now expected to be flat this year.
FY23 adjusted earnings were 1.3p per share, while today’s updated forecast from Cavendish is also for a 2024 result of 1.3p per share.
Admittedly, consensus estimates suggest profits could rise by a further 20% in 2025:
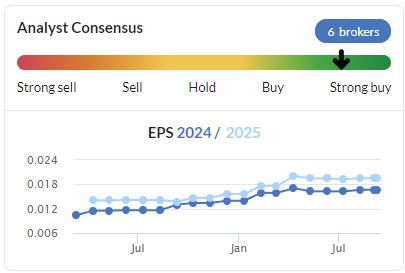
Even so, I’d like to see evidence of order intake improving again to help justify the stock’s current valuation.
On balance I think there’s still a lot to like here and I believe the business could have further growth potential. But I’m inclined to take an AMBER-GREEN view at this stage, to reflect the weaker H2 and shrinking order backlog.
Luceco (LON:LUCE)
+2.6% at 157p (£251m) - interim results - Roland (I hold) - GREEN
This is a supplier of wiring accessories, EV chargers and other electrical products, with a focus on the residential and RMI (repair, maintenance and improvement) markets.
I hold the shares personally as Luceco is currently a constituent of my rules-based Stock in Focus model portfolio.
Checking back in our notes, we last looked at Luceco in July, when I reviewed the company’s half-year trading update and said “I remain positive ahead of the half-year results”.
Has anything changed since then? Let’s take a look.
H1 results summary: today’s accounts show revenue up by 8.4% to £109.6m during the first half of the year. Of this, 3.6% is said to be organic, with the remainder from acquisitions.
The company says it’s encouraged by sales growth of nearly 10% in its Residential RMI divisions, which make up nearly two-thirds of group sales.
However, revenue from infrastructure customers has fallen 13%, offsetting these gains somewhat.
The overall impact on profit appears to be positive, whichever measure you prefer to use:
Adjusted pre-tax profit up 19.1% to £11.2m
Statutory pre-tax profit up 40.3% to £8.7m
Adjusted operating margin 11.5% (H1 23: 10.7%)
Net debt rose modestly to £39.4m (H1 23: £37.6m), representing leverage of 1.1x EBITDA.
This increase in borrowing is due to the acquisition of cable management specialist D-Line for up to £12.4m in February. This seems fine to me, assuming D-Line delivers as hoped.
Looking across the business, two of Luceco’s three reporting segments achieved sales growth during the half year.
Wiring accessories: revenue up 19% to £48.9m, op profit +32.4% to £9.4m
LED Lighting: revenue down 4% to £36.3m, op profit down 63.2% to £0.7m
Portable Power: revenue up 9.9% to £24.4m, op profit up 38.9% to £2.5m
This doesn’t seem a bad result to me, given the headwinds facing the UK construction sector at the moment.
However, the LED Lighting division has clearly performed poorly. Management says this is due to a drop-off in sales in infrastructure markets, which is expected to be temporary.
Outlook: trading is said to be in line with full-year expectations. Updated broker estimates today from Longspur and Panmure Liberum (with thanks) appear largely unchanged, with Longspur forecasting FY24 earnings of 11.8p and Panmure estimating 11.4p per share.
Those figures are broadly in line with the Stockopedia consensus figure of 11.8p per share, pricing the stock on 13 times earnings. There’s also a useful 3.1% dividend yield.
Roland’s view
My general view on this business is that the core wiring accessories business is probably the highest quality part of the business, with the strongest competitive advantages.
These results don’t change that view – wiring accessories generated a 19% operating margin, versus 1.9% in LED lighting and 10.2% in portable power.
On a long-term view, my main concern is whether the group’s pursuit of acquisitive growth is diluting the overall returns on capital that might be generated by the wiring accessories division alone.
Luceco shares have performed risen by 80% over the last couple of years, but remain more than 65% below their pandemic peak:
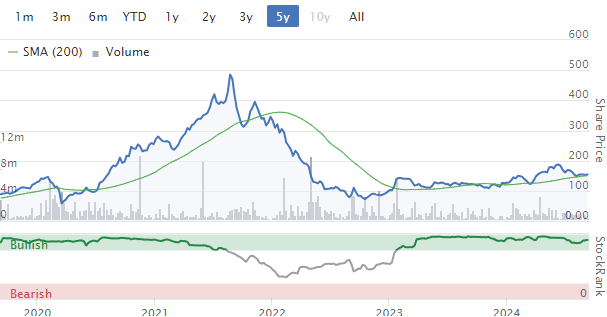
It’s not clear to me whether Luceco has the quality and scalability needed to regain those former highs.
However, as things stand today, I think this is a reasonably good business at a reasonable price.
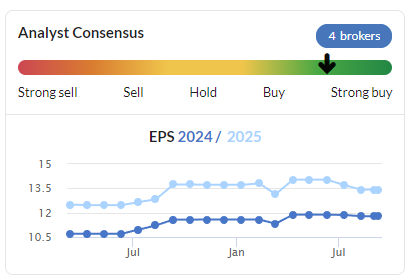
Given the prospect of improving market conditions next year and expectations of stronger earnings, I think I can justify maintaining the GREEN view I took in July.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
MPAC (LON:MPAC) - Investor Presentation video recording now available
?si=Iru5fbwSW5aqRb-fAdam Holland (CEO) and Will Wilkins (Group Finance Director) of Mpac presented to investors following publication of their Half Year results for the six months to 30 June 2024. Management discussed the half-year performance, the progress made against their 5-year strategy to double revenue, and the outlook for the Group. The team also answered a range of questions submitted by viewers
MPAC (LON:MPAC)
Paul writes "The pension scheme is still cash hungry, consuming £1.2m of cash in H1.
Since there is now a large accounting surplus, that probably means the actuarial deficit might reduce in future maybe? I’ve not looked into the detail, this is just to flag that it’s an issue which you’ll need to check carefully before buying the shares".
I have just watched the discussion by management (link in my post near the beginning of comments). 16 mins. in the CFO says current payment results from the June 21 triennial review. The result of the June 24 review is a work in progress that should be announced before the end of the year and he sounds confident that it will be a much better outcome. The policy of the company is to 'decouple' the pension scheme at the earliest opportunity.
Very good results reported by Finseta (LON:FIN) today and outlook very positive. Large percentage swings in share price recently. Surely worth more than the current price. Any other holder views out there? "Looking ahead, the strong trading momentum that was experienced during the first six months of 2024 has been sustained into the second half and we are on track to report significant growth for full year 2024, in line with the Board's expectations. At the same time, with the excellent progress made in executing on our strategic priorities, we have strengthened our operations and the foundations to deliver long-term, sustainable growth. As a result, the Board continues to look to the future with great confidence."
Mortgage Advice Bureau (Holdings) (LON:MAB1) - near 9% fall here today with constant automated selling. Seems harsh given the reasonably positive comments for H2 and the likelihood that interest rate cuts will start to happen in the next six months. The reduction in agents in H1 has started to reverse in H2 . They have to do revenue of £145m in H2 compared to H1 to hit target but they do have a traditional H2 weighting to business. One of Graham’s picks for 2024 and a quality company with the founder owning 18%.
The selling seems a bit harsh so I have been buying today. Anybody aware of anything I’m missing?
Looks a bit more severe than a fall to-day- been dropping since mid August from around £8.30
IQE semi-conductor wafer maker disappoints yet again, I see. Quelle surprise. "Apple supplier IQE tumbles after profit warning".
"Company expects annual profit to be at lower end of analysts' estimates". Of course it does. The last time it made a profit was in 2018, but that was less than £1m.
Shares down 16%. Seriously, just what is the point of this company? It's not a viable business.
Shares down 16%. Seriously, just what is the point of this company? It's not a viable business.
Never has been viable. I remember warning as much when there was all that excitement several years ago. It’s a joke company, frankly, and a typical example of a story stock that got pumped up by bulletin boards because of a weak association with Apple. I worked in semiconductors for 30 years and these compound technologies have never been anything other than an unprofitable niche for as long I can remember.
Alpha International (LON:ALPH) - had a nasty reaction to the news of the existing CEO leaving, his successor has bought 50k shares today: https://newsfile.refinitiv.com...
It is a shame to see Morgan Tillbrook stepping down as CEO. I wasn't expecting that. He has done amazing things with this company since the IPO in 2017 (the market cap at the IPO was £64.2m). Nice to see the buying from Clive Kahn.
Any views on Inspecs (LON:SPEC)
Strange sudden move down yesterday before gap up today on results
Hard to value depending on preferred measured of true p/e (as tax charge looks very high), ebitda, cash flow or p/s etc The debt reduction looks good given the capex on the new facility also. Guidance overall unchanged but orders stronger than last year.
I think it may be a late summer. The price of VP (LON:VP.) seems to be bouncing around a bit.
Looking at the chart I see...
... almost no volume - unless something is happening in the background - I see no RNSs.
VP (LON:VP.)
That’s just the spread playing out. Shares have been oscillating around 670 for months.
VP (LON:VP.) Yes the spread is awful - I was actually going to buy some yesterday but with the current spread it would have amounted to a 7% upfront payment - no thanks. Not aware of any other stocks this size that have such a wide spread, but it basically makes it un-investable for me, which is a shame.
Paul’ s Podcast episode 36. It’s the first podcast i have listened ( shame on me) and I absolutely enjoyed it. How entertaining! I was actually I have pub relaxing and listening. It’s very handy to flick back quickly to look at a share missed as the week is reviewed. Keep up the great work.
There’s also a transcript given by the podcast provider if you want to reread after the pod to refresh memory
Centaur media
Just a quick note following on from discussion last week.
Downing are (were?) closing down their position causing overhang on price .
Someone commented that there were other sellers as could be seen in reductions in holdings shown on stockopedia eg Aberforth dropping from 15 to 14%.
Devil is in the detail this drop is not the result of selling but issuance of shares under incentive plan .
When a company owning over 3% moves up or down a % they have to notify market.
Wonder if there is any way stockopedia could colour code these changes on holdings
- red sales
- green buys
- blue is when change is caused by other factors
Just a thought , probably bigger fish to fry .
When a company owning over 3% moves up or down a % they have to notify market.
Wonder if there is any way stockopedia could colour code these changes on holdings
- red sales
- blue buys
Interestingly planetx, Investor Meet Company has just started doing this with their RNS service (you don’t even have to open the RNS). Also they provide an AI summary at the beginning of each RNS which is pretty neat.
Interesting to see that Cyanconnode Holdings (LON:CYAN) got an ‘over subscribed placing’ away at a premium to the recent share price. Good to see directors participating in buying quite a large amount. According to the RNS
“The net proceeds of the Fundraising will be used to provide ongoing working capital for growth, to further strengthen the Company's balance sheet and to fund the setup of a hardware product design lab in India, which will enable a ramp up of operations.”
This follows on from a major new contract win for 6.5 million omnimesh modules announced at the end of last month. Gervais Williams is a fan and I note from today’s RNS that Permier Miton participated buying 5,555,555 via the placing.
Good morning. Can you do a review on SLP.L ? Full year results today don't look too rosy but I still think its a great business. Interesting to hear your thoughts?
Hi Derbarian
It look to me that cash is around 55% of the market cap. Although the PE is around 24 times. The outflow in cash is essentially the dividend payments.
Direct costs have increased 10%.
Sales have fallen by 35%+ and they have still made 10% net profit.
In my view, it is all around the basket price. If you think whether or not it will increase again in the future.
I hold.
Please Roland, Can I add my voice to Derbarian to have a look at Sylvania Platinum (LON:SLP) . Many thanks in advance.
Mo Shaker - they don't cover mining or biotechnology
Paul please have a look at Sylvania Platinum (LON:SLP) and I promise I'll donate to ZANE =D
Mo Shaker what are your views on Sylvania Platinum (LON:SLP) ?
My take is it is no longer a good high paying divi share as down to 3p including a special this year. Forecast seems to be around 4.5% yield. And unless China and or the auto industry pick up over the next 6 months they are not going to be a dynamic growth share either. I'm not counting on either of those things happening.
Yield is still decent if patient and plenty of cash but where is the catalyst for a rebate? Add in the joys of being based in South Africa with political and power problems and for me it's on the watchlist for when it turns up again.
Care to share? As other posters have mentioned it is highly unlikely you'll get a comment from the writers here as commodities are not covered. They have to draw the line somewhere.
I’m curious to hear any opinions on Serica Energy (LON:SQZ) results today. I understand sentiment is negative due to the current low oil and gas price and onerous tax rate for UK producers as well as the potential reduction of Capex allowances in the forthcoming budget but nonetheless, this still looks like an enormous cash machine with a dividend yield approaching 20% for goodness sake!
This caught my eye: “Following the share buyback of £15 million ($19 million), interim dividend of 9p declared today, unchanged on 2023. This reflects the Company's confidence in its medium-term robust cash generation outlook, with the expectation of generating over half a billion dollars of cash flow after currently committed investments over the coming three years at current commodity prices, after factoring in the expected tax regime.”
That’s half a billion dollars without factoring in any rise in oil and gas prices which must surely be an upside risk given events in Ukraine and the Middle East.
The effect of the brought forward tax losses which they acquired with the Tailwind acquisition is above my pay grade to understand but they claim an Effective tax rate of just 26% by utilising these assets and the balance sheet shows a net deferred tax asset of $75.1 million at 30 June 2024. The deferred tax asset amount of $559.4 million “..are expected to be recovered through utilisation against deferred tax liabilities… and through future taxable profits.” So unless I’m mistaken, they have a bit of a shield against the onerous energy levy taxation for some time to come?
The accounting for the tax losses is a little confusing as they state elsewhere in today’s report that “..the tax losses acquired with Tailwind, the balance of which remained at over $1 billion at 30 June”. I’m not clear what this figure actually refers to but I suspect that the net figure of $75.1 million is the pertinent one.
Overall, to my untrained eye, the downside risk here looks well covered by the dividend and on a mid term basis, any recovery in the share price (this traded at 4x the current price just two summers ago) makes this an attractive proposition. Value trap or unloved opportunity anybody?
Serica Energy (LON:SQZ) : Roland has commented on this previously so it would be interesting to hear his views after todays results.
I have held in the past but got fed up with the continuous decline and with labour coming into power that created too much uncertainty for me and sold out. I think they announced that if the uk government won’t approve new fields they will go to Norway - global warming strategies seem to be country specific which is daft. The financials looked great when I bought them but the uncertainty drove the price down and I personally think this uncertainty still hangs over the sector in the UK which is unfortunate. Relying on shipped imports rather than a potential pipeline to the uk is a bad strategy if we have another crisis.
Serica Energy (LON:SQZ) , worth noting the current price of Brent has very recently dropped below the threshold level for the Energy Profits Levy ($71.4). Of course it needs to remain so for a 6-month period (Avg) for this to take effect. It is somewhat counter intuitive that a low oil price environment would be more bullish for Serica and appears to be an interesting possible catalyst which could drive the hoped for turnaround in sentiment. No position currently but watching closely!
Simply put, Serica Energy (LON:SQZ) doesn't like paying tax. I hold.
That got my curiosity. Does anyone, any company actually like paying tax? I find it a necessity but I don't like it and I also don't hate it - I just try to be as efficient as possible.
Serica publicly said just that in a report.
Gamma Communications (LON:GAMA) results look very positive today and above expectations. Any chance of a look at those? Thanks Neil
GAMA Nice little cracker of a company, although not small-cap. Thought I'd add my 2c whilst we wait for the pros to weigh in.
Revenues up 10.3%, and statutory operaitng profit up 8.3%. Market liked the results, sending the share price up 8% to 1620p as I write. It was up 10% in earlier trading. Net cash is up 17%. All good stuff.
GAMA is a "leading provider of technology-based communication services across Europe", operating in B2B (business-to-business).
"Following a strong first half performance, growth is expected to continue across the second half and Adjusted EBITDA is now anticipated to be in the top half and Adjusted EPS at the top of the range of market expectations."
There a YT vid of a consultant that worked for GAMA and he had nothing but praise for the company and the way it was run.
Average ROCE for the company is 23%. Over 5 years, revenues have been growing at 13%pa, operating profits at 14%pa, reported EPS by 14% pa. And it has net cash. Nothing to dislike there.
Stockopedia gives it a quality score of 98. I'm not surprised by its high score.
In terms of valuation, Stockopedia gives it a P/FCF (TTM) of 16.9. I'd be prepared to go up to 20 for such a quality company. Fwd PE is 17.5 - not cheap - but acceptable for such a business.
It was a new ISA position for me, where I got in at 1338p. So I'm happy.
Equals (LON:EQLS)
Given the great growth and the fact that Q3 appears to have accelerated I really don’t get this apparent acceptance of an offer at 135p particularly given the £20m+ of net cash. Adj eps should be hitting 10p either this half or next so really this is a business growing at 30%+ proposed to be taken out at around 10* after factoring in cash?
WTAF are the board doing - doesn’t feel like they are maximising returns for shareholders to me?
Worse still - if they hadn’t done this ridiculously extended PUSU my guess is the shares would now trade considerably higher - probably around the 140-150p mark (17-18*) but because everyone is expecting a slam dunk takeover at 135p no one is prepared to pay much more than 115p as everyone wants a premium to any purchase price. I think the board have made a large error of judgement in the case of shareholders. It may well work out well for them as we don’t get to see the terms of any sweetheart management deals in the new entity, so we can’t make a call on motivation.
We know the consortium think they are getting a fantastic deal as they are also willing to allow Equals (LON:EQLS) to pay dividends that don’t come out of the purchase price. That tells me they are throwing shareholders a bone to try and avoid a problem. They’ve basically bought themselves a free option - take a year to agree the deal and then more time to finance it whilst all the time making sure the business has more than grown into the valuation you were prepared to pay for before you had 20/20 hindsight…… great for the consortium……bl**dy rubbish for shareholders.
I hope shareholders vote against any deal - I think I will. I want at least another 15p and more like another 30p. I doubt my vote will make any diff but hey ho. Not happy - think I will email the CEO.
I see Equals (LON:EQLS) results rather differently. The transactions have increased by an impressive £3.5bn (56%) to £9.3bn, but giving only a 33% increase in revenue to £60mm. This then gives a fairly underwhelming £300k increase in Profit after tax of £5.2 mm. Basically EQLS gets only minimal net profit from the growth in transactions. I can see why this might lead to a lot of prolonged and difficult discussions over future value.
Not really though Aislabie
The difference in the statutory number is the increase in tax
Adjusted profit after tax is up 26% and adjusted EPS is up 22%
So not really true that Equals (LON:EQLS) only gets minimal net profit from the growth in transactions, and of course that growth is after the additional investment in the business and advisor fees on the prolonged transaction.
MPAC (LON:MPAC) results look positive. Presentation not until Friday (08 30 eek!) but in the meanwhile there is a 25 min interview with Paul H on Vox :
MPAC (LON:MPAC) Doing all the right things - margins heading up towards that magic 10%. Customer diversification ongoing, continuing to innovate and nothing in price for potential clean energy. On a fwd PER of not much more than 10* which just seems too harsh to me.
Once you add in all the pension payments it looks a lot less cheap!
But you are assuming those pension payments go on forever Tortoise, which they clearly don’t.
If you factor in the pension payments and timeframes to the EV it makes minimal difference to overall valuation metrics.
hVIVO (LON:HVO) half year results. Outlook confirms full year at upper end of expectations.
Also a CEO interview on the results on the Vox Market Podcast this morning for anyone interested
Interview with CEO Mo Khan, of hVIVO - YouTube
Busy day ahead by look of things and I have just seen Centamin (LON:CEY) has received a bid from Ashani so another to be taken over from USA. Any thoughts please (I hold)
I think the offer is not generous with respect to expected growth in revenue/profitability. I would like a higher offer or will vote against the takeover.
Having taken a bit of a knock yesterday with Hostmore (LON:MORE) in its death throes Anglogold Ashanti (NYQ:AU) has come along today and righted the boat. Centamin (LON:CEY) is our largest holding bohemie and I look forward to the dividedend payment on the 27th this month but I'm not over-happy about the takeover as I was reckoning the share price would have exceeded 200 pence in due course, what with the newly-established price level of physical gold. Ashanti's action is pretty aggressive methinks, a top-slice when the dust settles perhaps? ANG by the way is the Johannesbury Stock Exchange ticker.
Agree with Kam31572 I dont feel its valuing Centamin fairly. Gold price increase still to be refectled in forthcoming results. Its a dominate player within that region which counts for alot.
CEY should be worth more considering gold price I hold tempted to buy more
Thanks to all for input on Centamin (LON:CEY) - What I find frustrating is that it seems to be a done deal though I won't be crying to sell out - having held this share for years we are being offered not cash but an exchange worth no more than the SP of years ago.
There we go then, happens all too often in equities.
It seems to happen with gold miners where small shareholders dont believe that they are getting a fair deal.
I seem to recall similiar concerns with Highland and more recently with Shanta.
Could happen to Serabi Gold (LON:SRB) or Hummingbird Resources (LON:HUM) as well. I hold both.
I wonder what the Egyptian goverment thinks of the changing ownership, to South Africa from Jersey.
I wonder what the Egyptian goverment thinks of the changing ownership of Centamin (LON:CEY) , to South Africa from Jersey.
Great to have you here today Roland. Busy day with 21 companies on your list. Did you draw the short straw?
I hope Paul’s absence isn’t caused by illness or injury.
Hi FREng,
I lost my house keys when in London, so when I got back to Bmth last night, couldn't get in & no locksmiths were available. So I had to spend the night at a local hotel, joining a coach party of pensioners, listening to a 60's music tribute band in the hotel bar LOL!
Just got access to my flat a moment ago, so I'll be helping Roland out now. As Brucie used to say, "Didn't he do well!" getting up a comprehensive list & summaries for loads of companies.
Not had to show any ID or documents, the locksmith just let me in. Makes you wonder why burglars go to all the trouble of breaking in, when you could just wait for people to go on holiday, then call a locksmith to get you access to nick all their valuables.
Regards, Paul.
Saga (LON:SAGA) I don't hold
So I had to spend the night at a local hotel, joining a coach party of pensioners, listening to a 60's music tribute band in the hotel bar LOL!
Good man, always thinking of the readership - now mystery shopping Saga holidays!!
Can we also know what medications they were on for the Pharmaceutical sector investors.
MPAC (LON:MPAC) webinar on Friday - sign up here! https://www.equitydevelopment....
Mpac, a global packaging and automation solutions group, will conduct an Investor presentation covering their Interim Results results for the six months ended 30th June 2024. The online presentation will be hosted by Adam Holland (CEO) and Will Wilkins (Group Finance Director).
This event will take place at 8.30am on Friday 13th September.
The webinar is open to all existing and potential shareholders, and registration is free. Questions can be submitted during the presentation to be addressed at the end.
MPAC (LON:MPAC) - H1’24 results: positive momentum delivers strong results - link to new research report: https://www.equitydevelopment....
For the six months to 30 June 2024, Mpac Group reported significant revenue, margin and profit growth.
Revenue of £60.0m was +14%YoY, (adj.) EBIT of £4.5m, +105%YoY, operating margin 7.5% vs 4.2% H1 23, and EPS of 15.0p compared to (2.2p) a year earlier.
Year-to-date order intake remained strong at £59.7m, +6% on H2 23 (H1 23 of £62.4m was distorted by pent-up demand unwinding), with a closing order book of £71.4m providing extensive coverage over forecast revenues for the remainder of 2024. We expect the customary H2 weighting, with forecast EBIT at c.38% above the H1 level.
These strong results build on the sound foundations and momentum already established. With a clear vision for growth over the coming five years, we retain our fair value of 530p/ share, indicative of a FY25 EV/EBITDA of 7.0x vs the market cap weighted average of a group of peers of 10.6x.
Paul. Any chance of you looking at trx.results today? Thank you.